Small Cap Value Report (9 Oct) - VNET, THT, ZYT, QPP, OPTS, ACM

Good morning! Vianet (LON:VNET) has issued a trading update this morning, and it will be interesting to see how the market reacts to this. Technically, it's a mild profit warning, since they indicate that pre-exceptional operating profit will be c.£3m, about 10% down on last year, for the current year ending 31 Mar 2014. However, in the circumstances, with a major threat to their core business from the Government's proposed Statutory Code, that's actually not a bad result in my opinion. We already knew this was likely to be a poor year, with all the extra costs associated with defending the company against this legal threat, and disruption from management time being diverted from the business, plus the inevitable standstill on making new sales of the beer flow monitoring equipment until this issue was resolved. So anyone expecting a good year this year just hadn't done their research!
Pub closures has meant that the installed base has fallen to 17,000 Pubs, where it was expected to stay at 17,500, so that's disappointing, if not altogether unsurprising in the circumstances. The group's other divisions have improved, with the vending division now profitable, the USA making "positive progress", and fuel division is now close to breakeven.
The bit I like best is that the recurring revenues are emphasised (mostly on five year contracts), which has allowed continued strong cashflow, and the interim & final dividends are being maintained, which is excellent news. That means the 7.6% dividend yield is safe, for the time being. Now all they need is for the regulatory threat to fall away, as it's very likely to in due course, and in my view we'll be heading back to a quid a share, and maybe more once some decent vending contracts come through.
I am expecting the shares to open down modestly today, and if they continue dropping, I will be using that as a buying opportunity. The valuation here is pretty attractive if you think, as I do, that the regulatory threat is not likely to have any teeth. Anyway, let's see what happens!
There's a solid trading statement from Thorntons (LON:THT) this morning, for their Q1, being the 14 weeks to 5 Oct 2013. I'm not quite sure why they measure a quarter as 14 weeks, when it's actually 13 weeks? Total sales were up 2.1%, although this masks an excellent +11.0% performance from their commercial division (called FMCG by them). The retail division saw sales down by 5.7%, although that's not as bad as it looks, as this was mainly driven by store closures. Like-for-like sales in retail was only down 0.4% (this measure strips out the impact of store closures).
In terms of outlook, the key bits are these;
We have an exciting Christmas offer across the business and are encouraged by the strong order book within our FMCG division. This puts us in a good position ahead of the key Christmas trading period.
Our current outlook for the financial year remains in line with market expectations.
So that looks pretty sound. In terms of valuation numbers, Stockopedia shows the broker forecast consensus as being for 7.8p EPS this year, so at 91.5p per share at the time of writing, that makes a current year PER of 11.7, which looks about right. However, that's not taking into account the substantial net debt, and pension deficit, which I last calculated as 40p per share, and 36p per share respectively.
So if you ignore the Balance Sheet altogether, then the shares look reasonably priced. However, if you factor in the weak Balance Sheet, and lack of dividend (although it looks like divis are being resumed this year, at a low level), then the shares don't look cheap at all.
It's also a low margin operation overall, so I remain of the view that shareholders had a very lucky escape here thanks to a friendly Bank Manager that supported the business when it was teetering on the edge a while back. Yes it's recovering now, but I think shareholders were very lucky rather than skilful here. You only have to look at Albemarle & Bond Holdings (LON:ABM) to see what can happen at highly geared companies.
This is the final call for Mello Central tonight - the excellent quarterly investor evening held in London at FinnCap's offices in 60 New Broad Street. There are three interesting companies doing presentations, and a record attendance of about 70 investors (a mixture of PIs, HNWs, and City folk) is expected. See you there! Start time is 5pm for arrival/drinks, and 5:30pm presentations begin. Then drinks, food & networking afterwards.
I know it is frustrating for people who live outside London, to keep hearing about all these London events, but the information shared with attendees then tends to ripple out onto bulletin boards after the event, so indirectly you also get to hear about it too.

I like the trading update from Zytronic (LON:ZYT) today. This is a small UK company that designs & manufactures specialised touch screens for things like vending machines, cashpoints, etc. So they make bespoke designs, and in relatively small batches, therefore it's not competing with the high volume commoditised end of the market.
They had an absolutely superb track record of steadily rising sales & profits (see historic graphs below) until May of this year, when a nasty profit warning halved the share price, which had already been drifting down to around 300p, to bottom out in July at around 144p. This was a narrow escape for me, as I liked the company and management, following a meeting in late 2012, but decided that it was fully priced at over 300p, with not enough upside to make risk/reward attractive enough for me to invest.
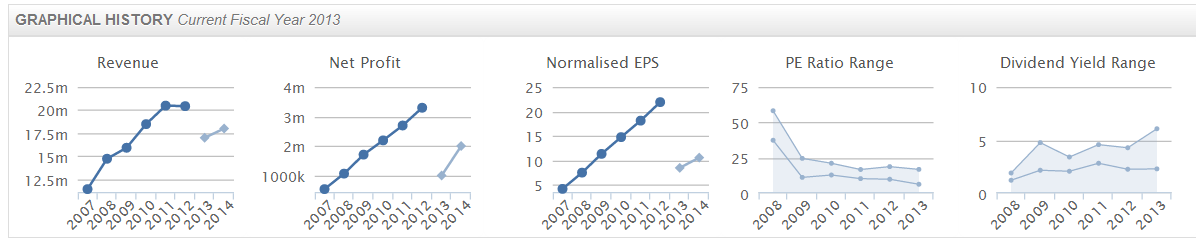
So I've been looking for an opportunity to get back into Zytronic, as I believed management's assurances that the difficulties they experienced in early 2013 were not a symptom of decline, but were due to gaps in the order books. However, I also wanted some firm evidence in terms of an improved trading update, and this morning we got it.
They say that H2 for the year ended 30 Sep 2013 saw "an improved trading performance", and that results for the year should be ahead of market expectations. Pre-audit estimates are for £17.2m turnover, and £1.9m profit before tax. That's well ahead of arguably ultra-cautious broker estimates for £1.0m profit on £17.0m turnover.
As you would expect, the shares have bounced nicely this morning, up 21p to 184p at the time of writing. My assessment is that this now lifts a cloud from the company, and should mean that investors can stop worrying about the downside, and concentrate more on the upside - which is interesting, as they have some innovative very large touch screens, including curved ones, in the pipeline.
EPS should drop out around 10p for the year just finished, so the shares are not cheap against those figures, at a PER of 18.4, but as you know it's all about looking forwards, not backwards in valuing shares. So with a bad year behind them, we should be able to look for say 12-15p EPS this year, so the PER is probably somewhere in the 12-15 range, which looks reasonably good value to me, for a tech company with interesting technology.
The dividend yield and strong Balance Sheet have definitely helped support the share price, and with a 9.1p payout expected for this year, the divi yield is very good, at almost 5%. Although it should be noted that the dividend cover is only just over 1 time - i.e. the company will be paying out almost all its earnings in divis for the year just gone. That's only OK as long as they expect EPS to rise strongly from here.
Overall then I'm encouraged by this statement, and think the shares could return to being an interesting growth company, but they can't afford to slip up again, or the rating will get trashed.
Risk/Reward & Profit Warnings
As a general aside, you've always got to consider what the impact of a profit warning would be, as any company can hit a bump in the road. Especially smaller companies, which tend to be more reliant on a small number of key products and clients. So that means there is typically 20-50% downside risk to the share price on a profits warning (depending on its severity), therefore one has to see much more upside from the current price in a good scenario, to make the reward outweigh the risk.
Also clearly one has to consider the probability of each outcome. So if the downside risk looks very slight (e.g. if a company has recurring revenues on long term contracts), then I would be prepared to invest if I could see say 50% upside on the current share price. Because in that case, a 50% gain is the likely outcome (the reward), and a profit warning (risk) is very low.
However, in a business that does project-based sales, and has high fixed costs, then the risk of a profits warning is very high, so I would want substantially more upside on the share price (100% or more) to make the shares look attractive on a risk/reward basis.
Therefore I often like buying shares after they have warned on profits, but only if it's a fundamentally sound business that has just hit a temporary bump in the road. May Gurney was a good example of that last year, where I bought near the bottom at about 130p, and the shares recovered to about 300p in a year (I sold far too early sadly, but still made a good profit on them).
As Anthony Bolton said, the best buy decisions with shares are often the most uncomfortable - i.e. when sentiment is extremely negative on a company, because they have performed badly in the short term.
On the other hand, catching falling knives can be a diastrous strategy, if you are not able to sort the what from the chaff, in terms of finding decent companies that have just had a temporary setback. I find it's usually best to wait for at least a few weeks after a profit warning for the dust to settle, but the timing depends on what type of market you're in. In a bull market the recovery time can start quite soon, in a bear market it can be 6 months+.
I think that in the current bull market, many investors are over-paying for growth, and are intoxicated with the strong momentum in their favourite stocks, imagining that they will keep going up forever. This is a recipe for disaster in my opinion. The higher the rating, the harder & faster it will fall, if & when the company disappoints in any way. So a PER of say 20 leaves absolutely no room for results that are not up to scratch. Good is not good enough, results have to be sparkling to justify that sort of price.
Whereas with value stocks, they tend to largely shrug off mild profits warnings, as Vianet (LON:VNET) did this morning. A brief blip down, as a few nervous nellies run for cover, then the value buyers come in & it's now only down 2p on the day. That's because sentiment is already so bombed out, that more bad news doesn't really do that much damage. So risk/reward is actually positive, despite (or because of!) sentiment around the share being so bad.
Back to individual companies. Quindell Portfolio (LON:QPP) has issued a positive-sounding update, trumpeting "organic growth of £300m+ per annum". Must admit, I am getting slightly tempted to buy some, as it does seem to have some remarkable momentum behind it in terms of contract wins. Although as has been set out many times before here, the figures don't convince me at all, nor the sustainability of the business model. Given that the market cap is now over £600m, so it's more of a mid-cap, it's not really within the remit of this report any more, so I'll probably drop coverage of it. Although I will report on their published results only from now on, just as follow-up from previous comments, but I won't report on any other sundry statements from them.
This is turning into "War & Peace", so I'll wrap things up fairly soon.
Newriver Retail (LON:NRR) has issued a positive-sounding portfolio update. I like the company & management, and think it's an excellent long term property & dividend play. However, I sold my own shares a little while ago, as they were in my shorter term portfolio, and I wanted the money for something else that seemed to have more immediate percentage upside. I might look at picking up some more NRR if a buying opportunity arises in future, for my long-term portfolio.
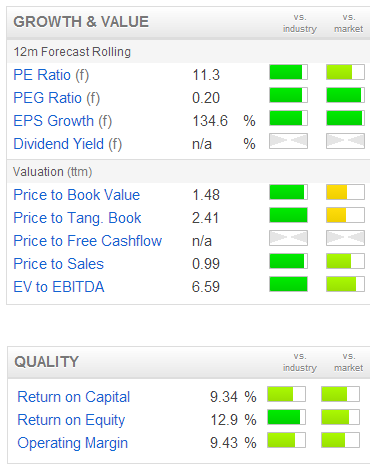
A trading update from Optos (LON:OPTS) looks quite interesting - talking of "excellent progress" and reduced net debt. Might be worth a look, as the valuation graphics on Stockopedia show a lot of green (i.e. good!)
Similarly with Accumuli (LON:ACM) - it has issued an in line with expectations trading update today, and the Stockopedia graphics are nice and green, which is a good green light to do some more research, which is one of the ways this site makes researching many companies so quick & efficient - you can rapidly eliminate things that don't fit your basic criteria, freeing up more time to home in on the good ideas with deeper research.
Hopefully my reports here also help people with limited time home in on some of the better ideas from the morning's announcements. That's the idea anyway, although it's always important to remember, these reports are just one person's opinion, written "on the fly", so always essential to Do Your Own Research ("DYOR")!
Signing off for the day, and see many of you at Mello Central tonight.
Best Wishes, Paul.
(of the companies mentioned today, Paul has a long position in VNET.
A Small Caps Fund to which Paul provides research services has a long position in ZYT)
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

21 comments
Ref pensions deficits - had a quick look at Norcross and Thorntons
Thorntons made £3.7 mill post tax profit last year and the pension deficit appears to be £25 mill range with obligations of £90 mill.
If this is the case then this firms puts Thorntons in the basket case sitaution when it comes to investing unless there is some certainty that there another out (NTAV?) or increase in profits on the way (can they ditch shops and make more money if they do wholesale?). It will take well over 5 years entire profits at this rate to clear the deficit.
Norcross - their deficit is £30 mill but post tax profits are much higher at 9.1 mill - their scheme liabilities though are £420 mill.
Hmmm - i would be much more comfortable with Norcross on the basis than an extra £3 mill to them per year still leaves £6 mill profit - compared to Thorntons who be left with £0.7 mill.
Unfortunately the size of the scheme liabilities for Norcross is £420 mill ins much higher than Thorntons - so if pension deficits increase again this seems a much more risky than the chocolateers. I have no idea though if a LFL deficit comparison should ever be done with regard to pensions so it may be larger is necessarily worse if it has more conservative assumptions or more knowns than unknowns.
On these numbers neither is really company i would want to invest in at present with the figures as shown per the last accounts.
Re pension deficits the main issue at present is the artifically low interest rates. Once they move to a realistic rate the deficits will reduce significantly. I am taking little notice of them at present. Bank debt is of course a different issue.
If you believe interest rates will move in a major way, why invest in stocks at all? The market is not pricing major interest rate moves any time soon, so if you're really convinced the market is wrong here, you can make easy millions with interest rate or bond derivatives.
Paul - your comments on VNET are spot on. The yield will be highly supportive; there will be clarity in the next couple of months re the Government review and they are still making profits this year with the upside from a) US b) vending and c) breakeven at Fuel to help them. Debt is low at less than 1 x PBT. Yield is 7.5% and PE on the revised forecasts is around 7 x.
Thanks Paul. Helpful advice as always. I'll ask you to recommend such a broker this evening. As you deplete the supplies of white, I shall be depleting the supplies of red.
Positive RNS from Newriver Retail (LON:NRR) this morning although not much market reaction.
Steve
http://www.investegate.co.uk/newriver-retail-ltd--nrr-/rns/portfolio-update/201310090700130412Q/
Does seem encouraging, is it me, or is it a little odd that they would rns the rates paid by individual retailers ?? Seems to me that would be competition sensitive and you wouldn't want other retailers to know what you are charging your current tenant ?
All seems positive to me, I'm sure Paul knows much more about this,
cheers K
Hi Kenobi,
I was coming on to Newriver Retail (LON:NRR) later!
"is it a little odd that they would rns the rates paid by individual retailers ?"
As far as I can recall from my days as a retailing FD, rents were publicly published by a body like the Valuation Office, or some other property body, as they are needed for rental evidence purposes when challenging rateable values for Business Rates, and when negotiating rent reviews every 5-years.
I remember my old CEO hitting the roof when he heard that a competitor had taken on a new lease across the road at a much higher rent, as that would impact on our forthcoming rent review, by establishing local current rental evidence!
Cheers, Paul.
Regarding VNET, when is the final Statutory Code decision likely?
Morning Paul,
I'm tempted to get back into Vianet (LON:VNET) for the reasons you outline but it's another one where I am put off by the bid/offer spread - 64p - 68p at the time of typing, or around 6%. Ouch!
Steve
PS See you at Mello Central this evening if you are going.
Hi Gostevie, why not try and place a trade in Vianet and see what price you get quoted? Advertised LSE spread now 68p - 70p.
Asagi (no position)
Morning Steve,
Yes indeed, I shall be at Mello Central tonight, depleting their supplies of wine, so see you there!
You know the answer to wide bid/offer spreads - a proper telephone broker! They are more expensive, but a good strategy is to have a cheap online broking account to use for trades where the spread is narrow, then also have a secondary account with a telephone broker to use on small caps when the spread is very wide and/or where you need to get some size.
It's not worth using a telephone broker unless your trades are £5k+ in my opinion, as the minimum commission (typically £50) then outweighs the benefit of tighter spreads. But on £10k+ deals in small caps, a telephone broker is essential in my view.
Cheers, Paul.
It's always worth checking what price quote you get even with discount brokers, the RSP spread is often significantly smaller (half?) that of the LSE spread. Once I even was offered to buy at the LSE bid(!), all for the regular bargain basement commission and executed online.
Hi Paul
So with NXR we should largely ignore the pension deficit but with THT it should be fundamental to valuing the company?
Cheers, Martin
Hi Martin,
"So with NXR we should largely ignore the pension deficit but with THT it should be fundamental to valuing the company?"
I'm more worried about the Bank debt at Thorntons (LON:THT) than their pension deficit.
However, on the subject of pension deficits, you do have to look at each one individually, and assess its significance. In the case of Norcros (LON:NXR), their fund is very big, but only has a deficit which is small (something like 5-10%) of the total fund. Therefore one would expect that to melt away as interest rates normalise.
Also, the annual overpayments required to be paid by NXR are only about 10% of their EBITDA, which strikes me as modest, and so I just tend to regard its pension deficit as justifying a discount of say 1-2 points on their PER. So I'm not ignoring it.
As regards Thorntons, I can't remember the details on their pension deficit, but as I say, I'm more concerned about the excessive bank debt at Thorntons, which has to be taken into account in the valuation, you can't just ignore bank debt. It also greatly increases the risk. What would happen if the bank suddenly get a missive from regional office, telling them to drastically reduce their exposure to Thorntons? You would have an emergency Rights Issue/Placing at a big discount. I'm not saying that is going to happen, or even likely, but it's a risk. This is why I avoid highly geared companies. Everything might be fine now, but what happens if some big external shock occurs, e.g. the Euro blowing up, then all of a sudden Banks want to call in loans again & you're back on the critical list.
Cheers, Paul.
Morning Paul, I understand what you say about the balance sheet at Thorntons but I think overall you may be being a little harsh. Management seem to be following a sensible strategy which is yielding results in operational terms. As it reduces its reliance on stores (and gets out of the incumbent leases) cash flow should improve.
You are probably right to say they had a lucky escape but they do now seem to be on the front foot.
I wish one of my other retail holdings, French Connection (LON:FCCN), which admittedly has a much, much better balance sheet, would show some sales and profits growth!
PS well done on the half marathon - will go to the site and donate now.
Hi John,
Re. Thorntons (LON:THT)
"Management seem to be following a sensible strategy which is yielding results in operational terms. As it reduces its reliance on stores (and gets out of the incumbent leases) cash flow should improve."
That's true. Maybe the figures would stack up better once you strip out the remaining loss-making stores, but I don't have those numbers?
I agree that their strategy is good, and is working. The only thing I am challenging is that the valuation is too high, once you factor in the net debt & the pension deficit. To my mind, a sensible price for THT shares, in their current position, would be about 50p per share, so I think the shares are significantly overvalued at 91p. That's the only reason I'm bearish on them, not that I dislike the company, but that I dislike the share price!
Cheers, Paul.
Paul,
THT at 50p would be on a prospective PE of 6 whilst growing EPS this year at about 30%. I accept the debt levels are not what you would want but that price is unrealistically low. I think you might usefully compare someone like Lindt where you will see THT are on a lower PE, presumably allowing for the debt levels. At the current price I think THT is cheap. It is only the debt levels that are stopping me adding more.
VNET otoh has massively over promised for years and years (I recently happened on a broker tip for them from 2008 (I really must get rid of all this paper) - they were trialling in the US then, the price was much higher etc.....). On top of that it has acquired regulatory issues. I wouldn't touch it.
Hi Paul
But VNET do have an obligation to state if they consider broker expectations to be unrealistic?
Cheeers, Martin
Martin,
"But VNET do have an obligation to state if they consider broker expectations to be unrealistic?"
True, which is what they have done today.
But really it's down to us as investors to consider whether broker forecasts are sensible (which in this case it obviously wasn't), not take them as gospel.
I cannot understand why anyone would have imagined that they would see profits rise, in a year where selling their core product has been brought to a virtual standstill by a regulatory threat from the Govt? But judging by today's 12% drop in share price, it appears that's exactly what some people have done! Still, it's only 34k shares traded so far, so all pretty irrelevant really. Just makes the divi yield even juicier for anyone buying at these levels, especially as we have bang up-to-date confirmation that it's going to be maintained, due to strong recurring cashflows.
This seems to me a situation where one has to completely ignore negative market sentiment, and keep focussed on the figures & the likely reaction when the regulatory threat goes away. Remember that the regulatory threat only mentioned beer flow monitoring equipment as an aside, it's not in any way a core issue.
Cheers, Paul.
Paul
Consensus broker forecast for VNET is a PBT of £4m, so how is this a mild profit warning? VNET don't even give a clue as to what PBT will be, as they don't give any guidance on likely exceptionals.
What is your expectation on PBT?
Cheers, Martin
Hi Martin,
The broker forecast for Vianet (LON:VNET) this year was complete nonsense, so I've always disregarded it.
Given the disruption to the business this year, people should have been expecting pretty dreadful figures from them, so to come in 10% below last year isn't bad, in my opinion.
It was blindingly obvious that the regulatory threat would put a hold on any new contracts, and probably delay renewals too. So I would be amazed if anyone was expecting profit growth this year - if they were, they just hadn't done their research properly!
Cheers, Paul.