Small Cap Value Report (Fri 1 July 2022) - UBG, MYSL, REAT, XPF

Good evening/morning, it's just Paul here for Friday (Graham does Mon-Thu). Today's report is now finished. Enjoy the weekend everyone!
Congratulations to Simon Thompson for winning Journalist of the Year at the Small Cap Awards last night (run by Master Investor). He normally wins it most years. Still, it was nice that I was included as one of the 5 nominees.
I had a good chat with Unbound (LON:UBG) (I hold) yesterday afternoon, and have typed up the key points below.
Agenda -
From yesterday - my notes from a call with the Unbound (LON:UBG) (I hold), to clarify some reader questions & misunderstandings.
UPDATE at 11:22 - There wasn't anything interesting on the RNS today, so I've had a lazy morning, and will now look back at React (LON:REAT) ad XP Factory (LON:XPF) updates from earlier this week. Sections should be up by 3pm.
Mysale (LON:MYSL) [No section below] - this has come up on the top % risers today, up almost 200% (from a very low base of 1.25p). The excitement seems to be due to Mike Ashley's Frasers (LON:FRAS) emerging with a new 28.5% stake. He must have taken several of the major shareholders, maybe including Philip Green's 16.3% stake? Or if it's someone else, then Green, Ashley, and Schroders would together hold a controlling 59.7%. We saw what happened at Studio Retail when Ashley & Schroders teamed up - they bought it for a quid, and other shareholders got wiped out. For that reason, I wouldn't touch MYSL. It's a rubbish business too, which never lived up to the promises, and is now in decline & loss-making. I wouldn't bank on the founding Jackson brothers being able to hold off the vultures. Still, if it all goes wrong for them, the Jacksons could just blame it on the boogie! ;-)
React (LON:REAT) - Interims look uninspiring (around breakeven), but a recent acquisition should transform future results, as it's a high margin window-cleaning business. I was expecting to dismiss this share again, but on closer inspection there might be some potential here, if more good acquisitions can be made. The problem is that equity is on a low rating, so each acquisition is likely to require considerable further dilution - so EPS could remain depressed.
XP Factory (LON:XPF) - an interesting concept, which looks tons better since the acquisition of Boom Battle Bars. The share price is coming down nicely, and starting to look interesting as a long-term buy & hold. Sites are being rolled out quickly now, some owned, some franchised. I think this share looks interesting, but there's probably no rush to buy just yet.
Unbound (LON:UBG)
Q&A with the company, yesterday
How does this marketplace concept work, and what is it?
It’s a new website, UnboundGroup.com and we’ll drive traffic there from Hotter Shoes database.
It’s a way to leverage more products to our existing database of 4.6m consumers.
Will not use a single penny of working capital - it’s a drop ship model, as you correctly said.
Products & services will be curated, specific for our target audience - e.g. if a customer buys walking boots from Hotter, then we’ll target outdoor clothing to her, from partner Rohan, which has a strong store presence, but wants to grow their online sales.
Other existing sales channels include 17 standalone stores, and 8 garden centre concessions.
I asked to discuss the garden centres more - low cost to set up, they do have to be staffed. CFO has previously said on a webinar that all 8 sites are profitable.
Looking to roll out more garden centre concessions. How many? Not saying at the moment, as scoping out an expansion plan. Payback time is quick from new sites.
Garden centres are perfect demographic for Hotter, and many customers will know the brand already, as lapsed customers of shops since closed. Use 3D scanners to get exact size & shape of customers feet, reduces returns. Have full range, but not necessarily every size option, so some orders despatched from the distribution centre.
Returns rate is low compared with online fashion, in the low 20%’s. Combined with high gross margin of 68%, this is good business.
How about posting out traditional catalogues? Yes we do this, about 800k per month sent out. Can add third-party products into catalogues very easily, for minimal extra spend - a couple more pages in a brochure that’s already being sent out, is very little extra cost.
Very sophisticated marketing analysis is done in house.
The whole strategy can be summed up as “leverage” - little extra cost, to leverage existing marketing spend to drive extra sales, from curated third party products/services.
Hotter Shoes factory has 3x capacity, was doing £100m revenues before shops were closed in restructuring during pandemic. Hence want to recover those lost customers through online, concessions, etc. So have the capacity to scale up.
Everything being done is low risk, and low cost.
Results for FY 1/2022 showed £52m revenues, and £5.6m EBITDA, so current share price is 2x EBITDA. I pushed back against this, saying many private investors don’t like EBITDA (that’s useful feedback they replied), especially after IFRS 16 has made the numbers nonsense. CFO clarified EBITDA was £3.8m pre-IFRS 16. Also that doesn’t take into account net debt. But I think we agreed the shares are cheap for a profitable, growing company.
How many of 4.6m people on database are active customers? We’ve not disclosed that, but over 1m respond, and have bought something in the past. Some dormant customers might not want to switch to digital channels, so that’s where garden centre expansion could unlock those customers - cheap, and profitable way to do a low risk retail roll out.
We’ve taken on board feedback from your readers today, and have learned that we need to be clearer in future RNSs. We should have said specifically that we’re using a drop ship model, with little to no costs or working capital.
My opinion - it seems obvious to me that, being a new listing, the company has not yet got its message, business model, strategy out there to the private investor community. At £11m market cap, we are the buyers of the shares, instis are not going to be interested in something this small. Hence the change of brokers is a good move, that was an obvious mismatch, inherited from Electra.
I think the reader comments in yesterday's SCVR reinforced that UBG has just not explained its business model to the investing community. So I urge people to take a look at existing webinar recordings out there - on InvestorMeetCompany from 3 Dec 2021, and a Capital Markets Day webinar from 15 Sept 2021 on Unbound's own website. Maybe it would be better to check out this information before condemning the business model on your own invented, alternative facts?!! There again, as the company accepts, it should have explained everything more clearly in the RNS, and not just assumed that we all understood the business model.
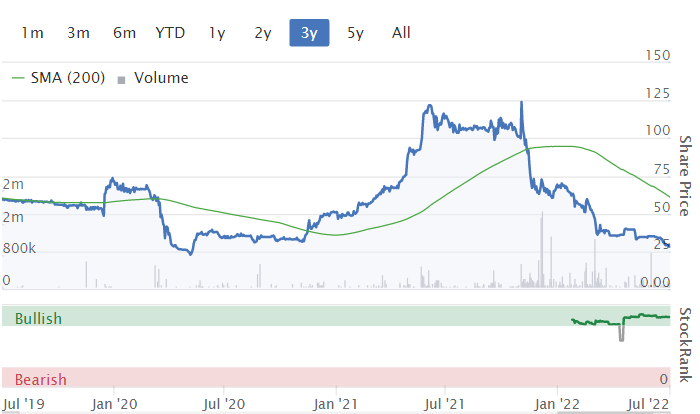
Overall, I think UBG shares look cheap at £11m market cap. It's a good brand, with a high gross margin, profitable, and growing. In a bull market, this would possibly be valued at 2-3 times the current price, in my opinion.
Downside risk? I don't like the bank debt, so there's a possibility of dilution, if the economy really craters. There again, as with Saga (LON:SAGA) (I hold), supplying niche product/services to affluent pensioners, is probably one of the best places to be currently.
Would I want to hold if the market cap was £30m+? No. But it's £11m, and that's too cheap, I reckon.
The marketplace platform is a sound idea I think, and involves little to no risk.
Some reader comments yesterday were inaccurate, so I hope its been useful clarifying the facts here.
.
React (LON:REAT)
1.0p
Market cap £11m
Very small, but I know some readers like it, so I glanced through the interims last night.
It’s an acquisition vehicle for specialist cleaning companies. Which just doesn’t interest me at all, as these companies are two a penny, usually run privately (owner-managed), and being so competitive, margins are thin. So why would you want to focus on building a sector consolidator, in this sector? I don’t see the logic for that at all. What are the scope for synergies? I don’t see any, maybe discounts for bulk-buying cleaning fluids? Although my view does change somewhat further down, so keep reading!
Here are my notes -
H1 Revenue doubled to £5.1m
Big drop in gross margin, from 41% H1 last year (LY), to 23% H1 this year (TY)
Trading around breakeven.
Big fundraise, about half the market cap, in April 2022, raising £5.5m
Bought Laddersfree post period end, for up to £8.5m - highly material to the company’s future, given that the group market cap is £11m. Laddersfree is a commercial window cleaning business.
Balance sheet - nothing, once intangibles are eliminated.
Current trading in line.
Laddersfree - is said to have revenues of £3.0m (flat vs LY) in FY 11/2021, and a very high profit before tax of £1.4m. Normalised adj EBITDA was £1.2m (these figures are from the acquisition announcement of 12 May 2022).
I’ve looked at Laddersfree’s accounts at companies house, and it does indeed look a highly profitable & cash generative little business. Who knew that window cleaning could be so lucrative? Maybe I’ve missed my calling in life! Where did I put that bucket…
Another thing to bear in mind, is that Directors of private companies often pay themselves a low salary, instead being paid mainly with divis, as that reduces NIC charges. This inflates profit numbers. So when consolidated into a listed company, the Directors have to be paid proper salaries, which can reduce profits a lot. It’s not clear if that has been done in the “normalised” figure given above.
My opinion - the Laddersfree acquisition does look transformative, in that REAT should now start making meaningful profits. Funds were last raised at 1.2p (a deep discount at the time, which upset existing holders), causing a lot of dilution. REAT will clearly have to keep raising more fresh equity, to do more acquisitions. The last acquisition almost doubled the share count, to over a billion. It needs to do a 100:1 consolidation I think, to stop the share price looking mickey mouse, at just 1p. My worry is that the Directors have shown they are happy to issue lots of new shares, at a deep discount, in order to get deals done. Directors don't seem to hold much skin in the game themselves, which again is a worry.
On broker consensus, the forward PER is about 6.5, which looks reasonable.
This share is a straightforward punt on Mark Braund’s acquisition skills. He’s got to buy good businesses on very cheap earnings multiples, since his own paper is on a very low multiple. The trick with successful acquisition vehicles, is to get your own paper highly rated, say a PER of >20, then make acquisitions on a PER of something like 6 or 7, maybe half funded with debt. That allows EPS to rise rapidly, and creates shareholder value, which is the strategy executed so brilliantly by David Cicurel of Judges Scientific (LON:JDG) . He identified a sector where many small, highly profitable companies could be consolidated, e.g. when owner-managers of specialist scientific instruments companies wanted to retire. I remain to be convinced that there’s such a good opportunity in the contract cleaning sector, but who knows - the numbers from Laddersfree do look impressive, and there’s also the chance of organic growth, to expand it nationally.
Overall then, with a fresh look today, this is actually looking better than my preconception. It could be an interesting punt, but likely to be plagued with continuous dilution, to fund more acquisitions, which could prevent the share price from achieving take off velocity. It’s difficult to see now how a low-multiple share, is a good method to consolidate a cheap sector. So I expect to see management constantly doing the rounds, trying to generate buying interest so that this share re-rates to a higher margin, with shareholders then being clobbered with more dilution for each new acquisition. It’s possible that might work, so I’ll keep an eye on it.
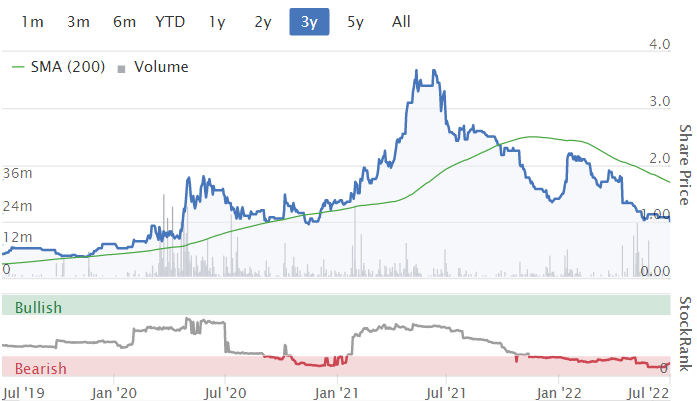
I think this share got a bit rampy around the time of the pandemic, with people chasing it too high. Although the valuation now looks a lot more sensible -
.
XP Factory (LON:XPF)
17p
Market cap £26m
I last covered this escape rooms/bars group here in May, and was starting to warm to the concept, although high valuation was the deal-breaker for me at 26p per share (£39m mkt cap, for an essentially unproven business model).The escape rooms don’t really interest me as a concept, but the acquisition of Boom Battle Bars looks a lot more significant - competitive socialising, a very popular concept for bars these days.
Revolution Bars (LON:RBG) (I hold) have successfully trialled a similar concept, so expect to hear more of these gaming themed bars coming to a High Street near you! Landlords like them too - RBG’s CEO recently said in a webinar that they had lost out on a couple of good new sites, to a competitor whose gaming format was preferred by the landlord, to a conventional cocktail bar format from RBG.
Stockopedia subscriber, Fiddlesticks posted an excellent comment here, which helpfully provided the financial model for the roll-out via franchisees of the Boom Battle sites. It looks a cracking set up, with XPD receiving a 10% revenue share. That’s so good actually, that I suspect franchisees are likely to become disillusioned, once they realise that most or even all of the profit is going to be siphoned off by XPF - possible risk there?
Anyway, with the shares now down from 26p to just 17p, (mkt cap £26m) is it cheap enough to get me interested now? Let’s have a look at the latest
AGM Statement - from 2 days ago, 29 June 2022.
XP Factory (AIM: XPF.), a group of leading UK experiential leisure businesses operating under the Escape Hunt™ and Boom Battle Bar™ ("Boom") brands, is pleased to provide an update on trading …
This builds on the update in May, so it’s only really 1 month (June) additional info.
2 new Boom sites have opened. Total is now 17 (4 operated by the company, 13 franchised)
6 new sites being built (3 company, 3 franchised)
Pipeline is for a further 20 sites, of which 8 are at an advanced stage - so this is quite a rapid roll-out underway - interesting.
On track to have 27 Boom sites open by end Dec 2022.
Confident that site dynamics previously forecast will be achieved.
Franchised sites performing in line with expectations. Although it’s strange this was not specifically stated above for the company managed sites.
Inflationary pressures on fit out costs, but return on capital “remains highly attractive”. This is badly worded & confusing -
The return on capital expected from Boom owner operated sites remains highly attractive, notwithstanding inflationary pressures to fit out costs, with target cash on cash returns in excess of 50% still achievable taking account of landlord contributions and rent-free periods
Escape Hunt sites - performing well, ahead of expectations in Q1, in line in Q2 (for company operated sites).
More sites being opened.
Cash of £6.8m at end May 2022 (why not give the end June, current figure?)
Some site openings delayed a few months, which I don’t think matters really.
My opinion - do check out my notes on the FY 12/2021 results here, as there are some important points, e.g. potential dilution from contingent consideration relating to the Boom acquisition.
Today's announcement reads as a bit vague, and over-PR'd in places. Which arouses suspicion, more than glossing over potential negatives.
As we know, hospitality is a really tough area right now, with consumer incomes squeezed by inflation, and high gross margins in the sector meaning that there’s a leveraged impact on profit when demand softens.
That said, the best operators do fine, even in recessions.
XPF has a novel format in the Boom bars, being rolled out rapidly, partly funded by franchisees, in a property market where very attractive deals are available.
I’m increasingly drawn to this share, and think it could make a decent long-term purchase, once the economy/stock market are on a firmer footing.
I don’t think there’s any solvency risk, helped by some sites being franchised, a nice mixture actually.
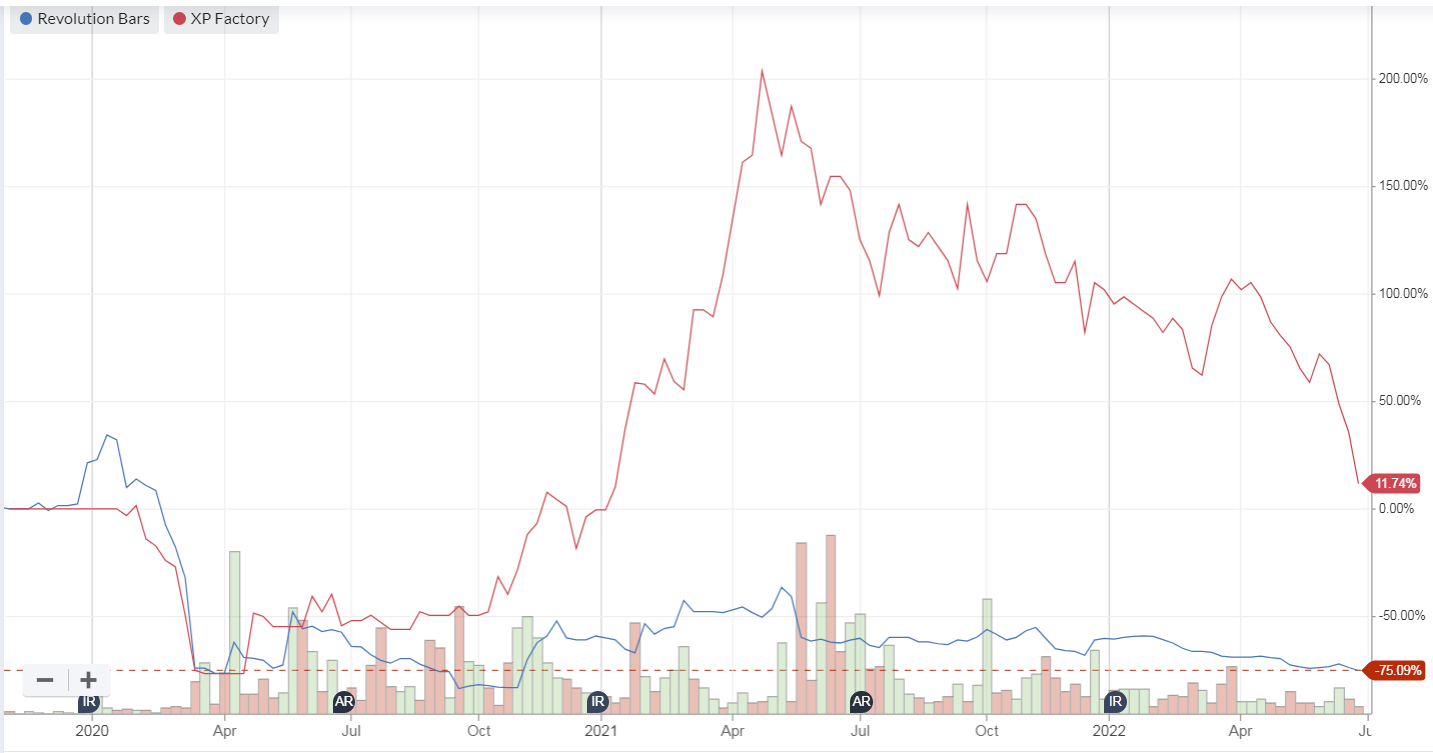
It’s interesting to compare the charts of RBG (I hold) and XPF. It depends where you set the starting point, but I’ve based the below on just before the pandemic started. As you can see, the higher line is XP Factory, which had a big boom, starting in Oct 2020 (when a major stock market rally started on the vaccines being launched). XPF then got way ahead of events, in the summer of 2021, and it’s been downhill ever since.
This chart suggests there might still be some newness premium in XPF shares, compared with the (unjustified) staleness in RBG shares, despite RBG trading well, and refurbishing its stores, and with 2 new formats ready to roll out.
So for me, RBG remains far better value, but at some point, I could be tempted to supplement that with a small starter position in XPF. I’d want it cheaper than the current price though - why pay up, when markets are throwing bargains at us every day?
.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

68 comments
Saw this today and thought some may benefit from seeing it. New technologies help recreate UK shoe manufacturing industry (themanufacturer.com)
Great find Camtab, thank you.
Podcast trial - I've revived the idea of a weekly SCVR summary in a podcast. This is just a trial version, about 30 minutes, which I've put on my occasional use personal website.
If you think it's any good, then I'll do them regularly, pls indicate approval by liking this message, or disapproval/indifference by not liking this post!!
Pls feel welcome to spread the word & link on Twitter too.
http://qualitysmallcaps.co.uk/...
I thought Mysale (LON:MYSL) had planned to delist from the LSE and transfer to the ASX? What happened to that?
I note that some very large buys have gone through Team17 (LON:TM17) late on in the session, circa 1,000,000 shares total.
Not sure what's going on their, if anyone can shed any light, perhaps changing hands with large share holders.
Update: I had a flick through the history and large volume trades are not that unusual. Must attract some wealthy folks!
Im guessing many shareholders have lost confidence in the company and founder long ago with appalling staff relations and more recently the owner taking more free shares to dilute existing shareholders. But share price at a shocking low for what should be an attractive sector could well be attracting gamblers.
Quick question
Has anyone had their dividend payment from Diversified Energy (LON:DEC) yet?
Thanks
Tommy
Hi
Yes, in ii - normally a day late as in USD.
Dear All
I know there is no wow this is amazing and here is all the detailed analysis guaranteed winner winner chicken dinner, just a lunchtime coffee note whilst a CPD lecture plays in the background.
I too can say that I am down across the 6 family investment pots, this year and even more since last summer.
There are significant holdings in cash in three, mine mums and sisters accounts (IWeb mostly ISA).
My wife and girls remain fully invested but they are ISA/JISA respectively through Fundsmith. The girls continue to have a monthly drip feed. The JISAs have >10 years before they can be accessed.
I continue to pay in monthly to Fundsmith, Vanguard and my company pension (Blackrock Funds via Aviva).
My Fidelity Pension Pot (previous company) is mostly cash.
I have slowly been starting to buy back into the markets through the IWeb Accounts, though showing a lot of red obviously but basically looking at companies I feel will continue to trade even through a recession/downturn, that I feel are unlikely to go bankrupt and taking opening small positions (up to 1%).
Part of this is the debate for mum (just turned 80) so is invested for income rather than growth (other than income from ISA only has state pension). Though I have changed now to more smaller holdings, with a reasonable spread of industries and slowly building these positions back, is about 30% invested, much better yield than previous, capital showing down but accept that for now. The debate over the coming months is basically the when to buy more in existing holdings (take to 2-5% holdings), so things like Twentyfour Select Monthly Income Fund (LON:SMIF) British American Tobacco (LON:BATS) Real Estate Credit Investments (LON:RECI) Legal & General (LON:LGEN)
I still have the internal debate to whether to follow my manual stop loss, so hence have sold things like Headlam (LON:HEAD) and Saga (LON:SAGA) purely on a it has dropped X%. Most are showing down since I sold so feeling a genius (not). But knowing my normal technique I will buy them back at a higher price in a few months time, but I can sleep at night and not have this ouch ouch ouch ouch every day, too many other issues in life right now.
I think that the important part for me is I have not exploded, fallen to bits or lost everything on a casino spin or silly punt. I still have a plan, even if it has changed and will need to be changed further.
There is always a debate on "cash" versus "inflation" but right now I am working and do not need to touch my investments, and I cannot touch my pension for >10 years. For mum it is slightly harder do I want a 5% yield, and accept a 10% capital draw down, or do I say if you need 5% we can take the cash at year end and hope that markets do not rocket up, no simple answer. It is about what is right for me, being able to sleep at night, and not worry too much.
I need to learn more about charts so when are things starting to bottom out, what is a bump versus a break out.
I concur there have been some very sensible comments about holding your nerve and staying in, or staying out, and avoiding doing the hokey cokey. Otherwise what I used to do, Buy High, Sell Low, Buy again EVEN Higher, Sell again EVEN Lower. So far nerve holding kind of...
Longer than I thought, but a lecture on SCL linings on Thames Tunnels can do that to the best of people!
Sorry a generalised Friday waffle but a better post later on when I have had some thinking time.
Tommy
ps. To finish a question I was taught by a very very good manager I had earlier in my career, and yes it is construction. "Is anyone dead?" "Is anyone seriously injured?" "Is there anyone hurt?" " Then it is only money!"
Hi Tommy,
I do enjoy your posts, please keep them coming. I imagine they are cathartic for you, they provide a similar service to me.
Cheers
Chris
P.s. I'm well down for the year, even more so down since May 2021. I don't monitor the %s, and I haven't checked my shares' prices in weeks/months now, which I think helps me keep my nerve. I'm not intending to sell anything, unless and until the company-specific story changes in an RNS.
In today's Small Caps Life email there's positive commentary on yesterday's Capital (LON:CAPD) contract awards RNS. They end by saying:
More details will follow later this month with their Q2/H1 trading update:
We are not sure we will see any revenue range upgrades at this point but with them on a P/E of 5 and experiencing very strong markets and agreeing highly profitable long-term contracts out to at least 2025, then you don’t need any upgrades here to make a very strong investment case.
(I hold). Edited to include a link to Small Caps Life substack.
Thanks FREng, I also took a position last week in £CAPD as they seemed to have been dragged into the general mine stock sell down in the last few weeks.
They had an exceptional 2021 profit of 70.2 million, which according to Stocko will not be beaten 2022/23?, which is my only concern reference SP, but they are heavily investing in drilling rigs as follows
Dec 2021 - 109 total
Q1 2022 - 110
Q2 2022 - 115
Y/E 2022 - 120
Also 28% of the revenue in Q1 2022 came from non drilling activities i.e. Mining services and MSALABS (laboratory services) up 7% from Q1 2021, which could be a game changer and future additional revenue driver.
My hope is strong Gold prices will drive further contract wins. Yesterday's RNS appeared very bullish ref the 19th July RNS.
The SP saw decent gains yesterday, my gut is it will fall back a bit which could be a good entry point/top up.
Piles of cash and a growing profit margin over time, am fairly bullish about this one.
Time will tell.
Many commodity prices have fallen significantly recently as fear of recession grows. Lithium being an exception.
Sorry Acorn I have adjusted my post, they are mainly in Gold (9 mines) and 1 copper.
Historically growth at £capd has been cash consuming rather than cash generating. MSA Labs and the investment portfolio may make some difference this time round but....
I don't think the $70m Profit after tax you mention for Capital (LON:CAPD) in 2021 is that meaningful. Capital runs a significant portfolio of junior miners, where gains/ losses in their value run through the P/L. In 2021, $34m of "profit" came from marking up the value of holdings (particularly, PDI and Firefinch). So that I calculate real underlying profit after tax at $36m in 2021 ($12m in H1 and $24m in H2). It will be interesting to see if Capital can keep up with H2's underlying profit level - given the still strong market for rigs despite maybe slightly weakening ARPOR.
Looking at the share prices of Firefinch (particularly after the spin off of Leo Lithium) and of PDI (as well as some of the smaller holdings) I would fully expect the investment portfolio to show a substantial loss in H1 2022 - so I am assuming that actual profit after tax (inc investments), will be well down on 2021 levels. When you look at the brokers' forecasts, you need to understand if their profit forecast is pre or post the investment line. (For example, I think Tamesis generally strip out the investment income).
The MSALABS growth story has been impressive, despite it not having any exclusivity to Chrysos's PhotonAssay units, which seem key to its growth. Capital own 75% of MSALABS - so the minority interest needs to be taken into account in valuing this business.
Despite the above which temper the upside at below 80p, I agree the shares offer value.
Braemar Shipping Services (LON:BMS)
Anyone have any thoughts on this?
Good sector at the moment and management positive about how they are doing currently.
Uncertainty is around the publication of the final accounts which are being delayed to allow the auditors to do more work on the non-core disposal of Cory Vertom . They first mentioned this on 20/5 and delayed the results to the second half of June (the 2020 acc. were published 3rd June). Then on 28/6 they promised the accounts on 4/7. Today they say that's not going to happen and we'll let you know - reiterating positive trading currently but now referring to "number of corporate transactions" delaying the audit. They've said nothing to rule out a can of worms in 2021. Perhaps I'm too cynical.
Phil
(Don't hold)
I don't think they would have said "TRADING CONTINUES TO BE VERY STRONG AND AHEAD OF MANAGEMENT EXPECTATIONS" if they knew of anything ugly in the offing.
Hope I'm right - I hold LON:BMS.
My point was they can say that, and they are not saying anything false if there is a skeleton in 2021 - they are only referring to 2022.
Anyway, time will tell.
I've held Braemar Shipping Services (LON:BMS) since 2015 and struggled with it ever since, keep seeing a glimmer of light on the horizon. I think the current Board is trying harder and could be wrong in my everlasting impression that it is a dog.
As one of the inaccurate responders yesterday thankyou for the clarification. The really good news is the Management seem prepared to listen which is a key investment plus for me. I remain a holder.
Thanks Paul for your thoughts on Unbound (Unbound (LON:UBG)). It does seem interesting, given the current share price and the demographic of the customer. I reviewed the information on Edison Research. The things that put me off are the management focus on EBITDA, which in my experience tends to lead to a focus within the company which ignores all the costs that exist below EBITDA and the importance of maintenance capex. Like you, I spent my career working as a CFO in retail/digital businesses and I would have liked to have heard the management talking about the desire to make at least 10% operating profit on their core business of selling Hotter shoes. This is hard work and not very glamorous. It's much more interesting to talk to new brands about future revenue streams. For example, it may well be that the garden centres sites are making a profit, but does that that take into account a decent recharge for HO management cost and attention. Without that core making a decent profit, which conveys competitive advantage, my fear would be that the company is going to bounced around by market forces. Given the debt, I would like to have seen more cashflow, but the Edison research showed some substantial non-cash movements to reduce net debt without any explanation. Given the current uncertainty, I think I'll pass for the moment.
Thank you to all of you who posted so much valuable information to my post yesterday. Clearly, a certain type of comment brings you guys out to reach. I replied to timarr, and as I wrote yesterday, I am down over 30% overall, but I am still in here. One interesting point I think, is I thought my being down over 30% was bad enough; I am somewhat relieved to discover I am not alone, so clearly, this bear market is everywhere across the board. Of course, the market is illogical at present but I am in the process of flogging off some of my investment properties, as I want cash to deep dive into the bargains in equities out there now and into the future..Interestingly, whilst my equity investments are bombing out, my property portfolio is doing the complete opposite and I know from experience when cash buyers ask you if you want to sell your houses, it is a sign the market is approaching The Winners Curse.
Whilst, I am no expert in anything, I am able to make money, and in 2003, I bought 2 houses within 100 yards of one another; one for £9000 cash and the other for £11000 cash. Yesterday I was offered £280,000 from a cash buyer and that was his opening offer. Of course, I have improved the properties since I acquired them, and have rented them out and I have small mortgages on them...I used the remortgage money to buy more similar-priced properties. However, when I was with my very prosperous solicitor, he asked me 'why do you want to buy such cheap unloved properties in those working-class areas of the city..My reply was simple' If you cannot understand why I am buying these ridiculous low properties, then neither can my competitors like you, who are prosperous.. Accordingly, you do not need me to tell you, that with residential properties right now, we are approaching The Winners Curse stage of the property market...Get out and do not buy anymore, as it is too dangerous unless you are in for the long haul..Of course, I am not flogging off all of my property portfolios but enough to ensure my retirement is cash richer..Interestingly, I own several properties in a Welsh seaside and University town and I normally do not rent to students. However, I have increased the rents by 25% and one 2 bed flat had 61 serious enquiries and a 1 bed flat had over 80 enquiries..The property market is nuts right now but I want to cash out as equities are also nuts right now but for the complete opposite reasons...Cash is king but I want to slowly deploy it with some bargain, income-yielding beauties in the stock market..So guys thanks again, I particularly enjoy the long posts of our man Paul, as he is King. Best to you all
"Of course, the market is illogical at present ..."
Of course, of course. Well, I've been reading comments like that on this blog for about 6 months now. All of them say something like: "how can the market be falling? How can it not see how wonderful my shares are?" It's the same, in reverse, as when the market was rallying from the lows in 2020 and there were plenty of comments saying the market was so illogical for rallying so strongly and that it had to fall again.
Hmm, well the "illogical" market seems to have been pretty clued up in 2020 and it seems to have been right about where we're heading in 2022/3 as well.
In advance of a likely recession, the market is offering high returns to those prepared to take the high risks associated with that environment and are willing to hold for the 5 years it may take to see any gains. Higher rewards are on offer for those willing to hold micro caps that, as a breed, are higher risk and can't be sold, in any size, during hard times. As the probability of persistent inflation, leading to higher interest rates and ultimately recession, has increased, so has the market fallen. It all seems pretty logical to me.
The sharp fall of the markets , in general ,has nothing to do with inflation or the rise of interest rates.
In the 1970s inflation rose over 150% ( yes 150% ) but the market doubled.
In the 1980s inflation rose over 65% but the FTSE 100 was 400% up.
The markets have fallen because valuations were very very high , and liquidity ( as markets are falling ) dries up. Obviously, as markets and share prices were so high , profit warnings started to emerge as management expectations were way too high and thus the collapse of so many small caps.
However, in my opinion, I believe that there is limited downside at these levels for a lot of small caps.
Have all a nice weekend.
Regards
Yiannos
"The sharp fall of the markets , in general ,has nothing to do with inflation or the rise of interest rates."
Yikes!!!??! Yiannos, sorry but you're just wrong here. You're not going to believe me so I'd suggest either doing the analysis yourself (using short term e.g. monthly or quarterly, not decadal returns!) or look at some of the research e.g. this relatively readable paper from the IMF which summarises the evidence and includes some discussion of the difference between the short and long term impact:
https://www.imf.org/-/media/Fi...
Quote: "Equity shares ... do not prove to be a good hedge against inflation risk as researchers find a negative correlation between real stock return and inflation in the short run in developed countries."
As far as your theory that it's all down to valuation, again sorry, but valuation is irrelevant to short term stock market performance There is no correlation whatsoever between valuation and short term returns. When the market is highly valued sometimes you have a great year and sometimes you don't: other factors determine that. Only if you look at returns over periods of 5-10 years+ does value start to predict returns. Again, do the analysis yourself or look at some research. There are probably better papers out there but here is one based on the popular CAPE valuation methodology:
https://www.brandes.com/docs/d...
Quote: "it’s impossible to predict the stock market return over the next 12 months based on valuation factors."
yep
Completely wrong about the 1970s - that was an utterly disastrous period for stock markets. In real terms most stock markets lost more than half of their value, with the UK market being particularly woeful. Don't have the precise figures in front of me, but it was certainly the worst period for stocks since the war. That said, there were pockets of the market that did quite well - Buffett unsurprisingly made some very good gains on deep value names.
Sorry but I beg to differ. The 1970s were horrendous for investors. As your numbers show end1979 FTSE stood at 488 (up 56% on its level of 313.16 at the start of the decade). There would have been dividends on top of this. But inflation was much higher. The RPI index (the only real measure of inflation at the time) increased by 340% in the 1970s (annual compound inflation of 13%).
https://www.swanlowpark.co.uk/...
On top of this, if you did manage to make any money in the 1970s tax rates were extremely high (incredibly at 98% being the top rate on investment income from 1974 onwards).
Numbers are there for everyone to see and make their own assumptions and judgements , but most importantly , investment decisions.
Your assumption and explanation is completely misleading for investing purposes. We do not compare the market returns directly to inflation , but I understand that people sometimes try to explain the unexplained.
I have £100000 and I made 30% return , then I made £30000. I do not then go and deduct the inflation rate.
I have written and shown to the forum here that inflation and high interest rates do not necessarily mean collapse of share prices. Perhaps in the very near short term , but , however, this has already happened.
I think you should do some research about the FTSE 100 in the 1970s and 1980s
Hi Paul, any chance of looking at Kingswood Holdings (LON:KWG) (I hold). Seems to be growing fast with good (in line?) results out yesterday. Though US division may have had one-off benefit from bull market? Thanks
Morning Paul,
If you're by any chance bored and slightly interested, Shore issued a note on £GLAN yesterday (results were published a month ago, it's fallen from ~£40m Mkt Cap on IPO to ~£20m now).
Looks a little interesting but the Debt side of things is a little off putting, they intend to recapitalise (a raise at a higher price than here?).
Some of my notes...
Accounts Payable SaaS - Directors(>50%) - Shore EPS in EUR (8.7c/10.5c/12.9c) - IPO'd May-21 to support Buy & Build - Aspirations to sell at 5x Rev. (23E £19.3m) - Rev./EPS f/c to grow 15%+/20%+ p.a. - 400+ customers (100+ Tier 1) - Win/Win model - 80%+ Recurring revenues
There's also a FY Results (end May) presentation on IMC https://www.investormeetcompan...
If you get a chance, welcome your views and either way, have a great weekend.
Vertu Motors (LON:VTU) have done an acquisition of 3.5m into an online car sales company, should be earnings enhancing this year.
Only time will tell but I feel they have really used the excess profits of the last couple of years so nicely between buy back, dividends and acquisitions. Very happy to continue holding and see how they continue to add value for shareholders
Small, but interesting and earnings accretive acquisition by Vertu Motors (LON:VTU) of Wiper Blades Limited that specialises in the on-line sale of wiper blades and other automotive accessories. #VTU is paying £3.5m, including goodwill for current revenue of £3.2m and £0.5m PBT. Wiper Blades will increase its on-line presence in automotive accessories that currently comprises Powerbulbs and Aceparts. Good use of funds as #VTU is awash with cash.
Also a brief upbeat announcement from MJ GLEESON (LON:GLE) confirming that it has reached its medium term strategic target of 2000 house sales. A full trading update is scheduled for 11July.
I hold both
Terrible month/qtr/year really and I find myself down about 21.5% so far but I remain upbeat when I see I am not far from the rest of the market and most of my investment companies are doing well.
Like others I am trying to figure out when to deploy excess cash into these depressed prices but after putting in some straight after the russian invasion (which are down about 10%) I am holding for now. One thing I wanted to ask other peoples thoughts is I have a few shares which have held up very well from this and either come down low single digits or in the case of BAE Systems (LON:BA.) even gone up.
Part of me is considering at some point ditching these and moving the money into harder hit shares that I assume will come back stronger. I am not interested in the pumped up Nasdaq as some of those have clearly still a long way to go, particularly the heavily loss making SAAS companies but more some of the ones we discuss on here which have been bombed out but are profitable growing and now trading sub 10 P/E.
Obviously I so my own research and make my own decisions but just throwing out for Friday if others are having the same thoughts?
I remain fully invested in UK small caps, the one exception being £ITV. The portfolio of 27 shares is held within my ISA, which means that I have to sell to buy. This provides an element of enforced discipline. I use dividends to add to holdings. With few exceptions the companies I own have cash with little or no debt. My overall approach is to do nothing and try to better understand the companies I own. I try to act on facts and ignore those who think they can predict the future, whether that is inflation, interest rates, oil prices etc.
However that hasn't saved the portfolio which is down 17% or so YTD. At some point the market will have priced in Armageddon and prices will turn. As to when I have no idea.
Good luck in whatever you decide
A poor 1st half, at -17% decline YTD. Still, I am happy holding my portfolio and console myself with dividends paid I can reinvest, cash on standby for a crash, and valuations that are still holding up well with each trading update.
All the best to everyone here.
BSV
Brookeda, on current status I'm somewhere between yourself and jonno not to be exact but yesterday I did a full recount for the family 6 portfolios. Half in Isa's, half out, it doesn't take into account long-lost cash in companies through bankruptcies and damaging take-overs though.... The portfolio covers some large caps, mid caps, small caps and AIM too. I'm quite catholic, yesterday I sold one holding in BAE Systems (LON:BA.) and reinvested the proceeds by adding to Ariana Resources (LON:AAU) hoping to improve my lot. My downfall has been not listening to stop losses that were set.
As of today (closing figures from June), my YTD stats are:
ISA (Mainly Long term holds): -6.4%
ISA Cash: 28%
IG Spreadbetting account: +20.4% on closed positions, with the caveat that I have some heavy and ongoing paper losses from legacy 'buy-and-hold' (no stop loss) positions in Boohoo, Volex, Block and Rio Tinto. I plan to let these run and *hopefully* they get back to B/E one day.
I don't plan on looking to pick up bargains (dangerous word) until I see evidence of bottoms forming on individual stocks, and constructive patterns starting to shape up. I'm very cautious about buying at the moment as I think this bear market probably has a few more months to run, at least.
Paul
Good feedback on unbound .
Private equity do love using Ebitda, Charlie Monger legendary investor summed it up the best
“Every time you hear 'EBITDA' substitute it with 'bull**** earnings''
I’m not sure I was so far wide of the mark yesterday
- building an online platform, marketing it , to generate profit from third party brands is what hundreds of other companies are doing not to mention the whiz kids in their bedrooms who are going to create the next generation.
My opinion is it’s just not going to work and it is not going to be as “no risk” as mentioned, If you have ever built an online platform and managed it day to day it is definitely not necessarily a low cost option .
- sounds a bit of a dodge on active purchasers, how many customers have purchased in the last year is an acid test question that any inward investor looking to buy that business would be all over.
I can see the mail order catalogs that’s their bread and butter, I can see the garden centres but these peripheral “low cost” options I can’t .
Anyway I am clearly not a fan even at these numbers, I ask myself what would Warren Buffet and Charlie Munger would say .
The bottom line is brutal .
The Private Equity guys at Electra could not unload either Hotter or TGI. Fridays to any trade buyers so they floated it on the stock market at the peak of the bull market . Timed it to perfection and got away with a big pot of cash .
We all got swept along with the “special situation” at the peak of a raging bull market and thought we would make a few quid .
Instead of chasing Unbound and Hostmore further I now see it as a Private equity company unloading their dross for a huge price and timing it brilliantly .
Well done Electra .
Key for us here is to learn the lesson, take the medicine.
This is actually not quite true because Electra issued Hostmore (LON:MORE) shares to shareholders and then renamed Electra - £UBG ....so instead of holding Electra shares where the two underlying investments were TGI and Hotter .... shareholders received the actual companies - listed separately. Electra didn't run off with any pot of cash - it was wound up. Encouragingly for all current shareholders is the fact S Welker/Sherborne remain decent shareholders of both businesses. They put current management teams in place and won't be happy with how the demergers have gone.... Unbound (LON:UBG) has panned out pretty much as forecast (earnings wise) but was a small part of the process and an easy position to cast away rather than add to.
As an aside, and worth being aware of.... many years back Sherborne did their first UK turnaround - pre credit crisis - a business some of you may now know 4imprint - at the time this was an unfashionable office consumable business which they moved online....for the last 15 years or so its been a steady grower in unfashionable areas and the stock passed my expectations many times over. I do see similarities here and I don't doubt its difficult but never-the-less you are paying nothing for it. If you have spent any time with Sherborne you would know they won't put idiots in charge of the business - especially when they retain equity. So despite the share price performance I wouldn't be so quick to write it off....and as it can't be too big a position for anyone its definitely worth holding. The institutions will be dropping tiny holdings in programme trades and that's why the shares have been so poor.... this creates the opportunity in my view.
I think you will find if it was ever made available that all the stakeholders, Directors, advisors , management . and all involved with the Electra unwind “special situation” did extremely well out if it .
A fee festival of noses in the trough of a raging bull market .
What we’re those advisory fees again I vaguely recall Paul saying 11 million ? (Could be wrong )
There are thousands of listed companies with great proven management that can talk plainly and concisely and give clarity just don’t understand the attraction here .
As I say I am totally not a fan and there is form here so it’s plain to see.
I’m not going to post anymore on Unbound instead I’m going to do sone work and best go create a low cost platform and go make sone easy money with no cash down and no set up costs .
Can’t be hard , I will report back at lunchtime on the EBITDA forward run rate forecasts and open it up for investors .
Whilst your point re fees was relevant at the point of demerger - Im not sure why its relevant today.... it doesn't affect the forward looking prospects.
The point is very relevant , it is about the mindset of management .
If these guys come from private equity with its 3-5 year timescales and self serving entitlement to high salaries and options etc we need to be really aware of it.
Again I defer to Warren Buffet and Charlie Monger who have covered this - it is worth reading up on and understanding .
Anyway , no more posts on inbound I’ve nearly finished my platform and will be giving you guys the chance to invest this afternoon .
Sep 24, 2021
Paul , sorry enjoy the sun of course .
I agree with Yiannos1 on NSCI , reminds me a bit of ELTA situation where sun of the parts is clearly currently way in excess of market cap .
Looks like you felt differently when the shares were higher. The rear view mirror is a bad guide to the future. Its Munger btw ....:-)
planetx I'm on the same page as you but I should appologise to Paul S here as I probably expressed the same sentiments to him over a chat and I pissed him off.
I don't think Paul is saying that any of this is not true but its £11m m/c now and a load of debt. It does trade profitably and so if it can grow without excessive dilution then its can easily multi-bag from here.
The key for me is that they don't dilute at this point in a poor market to chase rainbows. I'm not sure they'll be able to resist but who knows. It's small beer now anyway.
Something must be putting PI's off Unbound (LON:UBG) I don't suppose it's anything to do with the huge Spread? I don't hold and am looking at a multitude of alternative choices.
I'm enjoying the debate.
Hi JASVFS.
I agree there seems to be an irrational / emotive element to the debate on £UBG Strange for such a small company. It can hardly be the bedrock of anyone’s portfolio.
It would be better if posts were constructive. Hard if you’ve been burned in the past but it shows a strong mindset.
Re Electra, Outbound and Hostmore - a good rule of thumb is never buy what private equity is selling.
RichardK,
Re Electra, Outbound and Hostmore - a good rule of thumb is never buy what private equity is selling.
Electra didn't sell Unbound & Hostmore. They separated the companies, and swapped Electra shares for the individual shares in both companies.
So whilst I agree with your general comment about private equity, it's not actually relevant here.
Regards, Paul.
Hi Paul
Thanks for providing clarity on Unbound (LON:UBG) (I hold). I was starting to think I’d misunderstood their business model. I haven’t and believe they are undervalued if they meet their targets. I wonder what are the margins on the partner brands? Significantly lower than their own product I expect. They must therefore be careful to make sure the shoe sales come first and then add on the extras.
Concessions in garden centres can work well. Most of them now appear to be retail/leisure destinations (for retired folk) that also sell plants!
What I have found off putting is, when you put a buy order in, there are other charges besides the broker trade fee and these seem, if I have read it correctly, to be a yearly charge. I have never seen this before. I looked at buying the other day, and instead of my usual £5 trade fee I would of been charged nearly £18. And then another charge in a years time. It stopped me from buying. I’ve never seen this before and honestly don’t understand it, so I just didn’t bother as there are plenty of other shares about that quite frankly seem less risky.
Hi gmtrader
If you are talking about extra charges when buying Unbound (LON:UBG) then I wold ask your broker why the extra charge. I only pay my standard charge with AJB.
I’ll have to check this out further as I have never seen this before in many years of trading. I’ve just photo’s a dummy buy and it lists the charges. This is just for a £500 purchase using IWeb. Has anyone else seen this?
Hi gmtrader
Looks like Unbound (LON:UBG) is an investment trust (IT) and those are the annual charges for investing in the IT.
I have never looked at Unbound (LON:UBG) before, but looking on Hargreaves, they provide a Premium/(Discount) to the NAV and list charges so it looks like its an IT to me. Also, being formally Electra Private Equity, PE listing are often ITs.
I have no idea if this is simply a hang-over with these platforms or whether Unbound (LON:UBG) is still structured as an IT. You might want to check this out.
Regards
Howard
Ok cheers Howard. I looked at UBG a while back while it was in the process of unwinding from Electra and thought those charges were as you said. But still giving those charges now. I’ll contact them and see what they say. I presumed all brokers were charging this and therefore thought this would put off many investor as it did myself.
Very strange. Definitely not the case at AJBell.
Unbound (LON:UBG) I just tried a dummy buy and get the same. iWeb is treating this as a Fund investment, not a share buy, the extra costs are fund management charges.I would contact them and tell them they have it listed wrong it's a share not a fund.
I eventually got through on the phone to Iweb, only to be disconnected after they put me on hold! So I contacted then again via web chat and this is a comment they made to me!!!
"Yes so the colleague did check this with our dealing team and they are aware of this. There's a name change happening today so a log would be put through for this to rectify"
A name change happening to UBG today, maybe they decided that Unbound was a terrible name and they liked Hot Hotter Hottest better!
Interesting you mention Saga (LON:SAGA) Paul, I've thought for a while that their target customer can't be very different to that of Unbound (LON:UBG) , and therefore there might be some opportunity in cross-over marketing - maybe they do already, but Hotter could be featuring in Saga's magazine, SAGA claim there to be 150,000+ paid subscribers. Likewise, Saga's services would perhaps be a decent fit for Unbound's new multi-brand approach. It's hard to believe they won't already be talking with one another but if not someone they'll listen to might want to suggest it.
As an aside, the new platform won't seriously be called 'unboundgroup' will it? What marketing genius conjured up that catchy little ditty? https://www.unboundgroup.co.uk...
I'd have gone for hothotterhottest.com or something a bit more fun...
As an aside, the new platform won't seriously be called 'unboundgroup' will it? What marketing genius conjured up that catchy little ditty?
Sadly - the answer is yes! I have just registered on the website to be advised when it opens. Surely, the name originated as weak internal joke by PE types to reflect the new 'freedom' the independent business unit would get (like assetco or bidco from the less creative). Even unbound.com would be better (if available) as the adding in 'group' sounds so boring and corporate. Who wants to type or click on that when you are looking for shoes that let you 'do more of what you love'.
The success of the business, any consumer business, depends on being able to get inside the mind of your prospective customer and deliver value to them. I think the business has potential - but I have doubts about the entrepreneurial growth skills (vs financial re-engineering/strategic skills) of the CEO.
Since Unbound (LON:UBG) representatives will almost certainly be reading this column today, can I add that an action like hiding the true active customer number - bought in P12M, a standard report metric for consumer goods companies - is another own goal and reflection of PE not Public company mentality. For the CEO, the share price is a key metric and the customers for that for a minnow on AIM are private investors.
Fobbing us off with less-than-transparent data and less insight than we can get for alternate uses of our money and which they would ask for themselves in a meeting is not a good look.
I hold (because I think the business is now very cheap with a lot of potential but....)