Small Cap Value Report (Fri 1 June 2018) - CDM, DTY, PCF, HYNS

Morning folks,
There is a lot of trivial news today, but sorting through it, I think I can find a few interesting stories. Let's see!
Cheers,
Graham
Codemasters Holding (LON:CDM)
- Share price: 200p (placing price)
- No. of shares: 140 million
- Market cap: £280 million
Admission to AIM and First Day of Dealings
Codemasters is a video game developer and publisher, specialising in racing games. The company announced it would float today in a placing announcement earlier this week.
It has been around for 30 years and has 500 full-time employees across 3 UK locations and an art production facility in Kuala Lumpur. Its main franchises are "DiRT", "GRID" and "F1". It owns the rights for DiRT and GRID, while Formula 1 is owned by Liberty Media.
Most of the IPO proceeds are going to its majority shareholder, an Indian conglomerate, through that conglomerate's Singaporean subsidiary. The selling shareholder is selling 60% of the company to raise £170 million (gross), more than ten times the IPO proceeds to be received by the company itself.
As mentioned recently, I tend to prefer IPOs which are more focused on raising money for the company than on letting the existing shareholders exit. But that's just a general rule, and we can always look into the specifics of any situation.
Admission Document
I've pulled out the Codemasters admission document from its website - the key information source for any new stock.
According to this, the company has been producing Micro Machines for many years. This is a fun racing game I played when I was a bit younger - it was an extremely good title.
The document also reveals that GRID and DiRT are successors of Toca Touring Cars and Colin McRae Rally - while I didn't play them so much, I do remember that they were huge titles at the times. I haven't owned a games console in something like ten years, so it's no surprise that I don't recognise their names any more.
Anyway, the admission document has 145 pages, so in a situation like this where I am under some time pressure, I need some shortcuts.
I want to understand the relationship with Liberty Media a bit better. Using the search function, I find:
the loss of the F1 licence could materially adversely affect the business of the Group and its trading performance
- this is no big surprise, but is helpful to see it in black and white.
We also have confirmation that performance is reliant on its three big brands, including F1:
The Group’s ‘‘DiRT’’, ‘‘GRID’’ and ‘‘F1’’ franchises contribute a significant proportion of the Group’st otal revenue and any downturn in the popularity and subsequent sales of one of these franchises may adversely affect the Group’s financial condition.
Scrolling down to the historic financial performance of the group, and the Going Concern statement, I see that it has been reorganised prior to IPO:
As set out in Note 34 (Post reporting date events), the Group undertook a group reorganisation and debt restructuring whereby all but US$5 million of the principal of the loans payable to Reliance were converted to equity and the accrued interest on the loans was waived.
That's great - it looks to me like the balance sheet should be back to normal now, rather than drowning in shareholder loans, as it was before.
The company has suffered huge outflows in interest over the past couple of years. Leaving that to one side, the performance looks quite good:
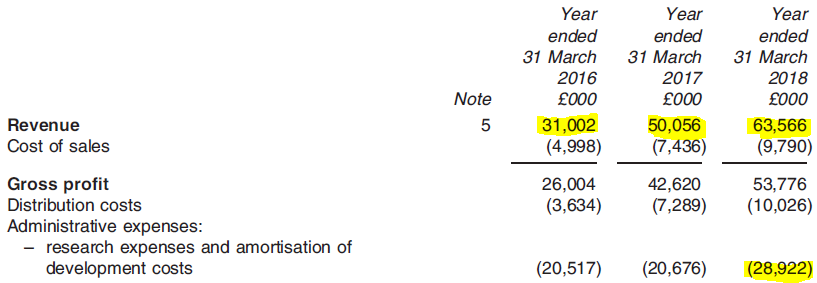
Revenues have risen very well over the past few years and gross margins are excellent, as you would hope to see from a video games publisher. Most of the expense is in research and the amortisation of development spending, e.g. £29 million in FY 2018.
Operating profit was £8.1 million in FY 2018 (FY 2017: £14.3 million). The fall in operating profit in FY 2018 was largely due to the increase in research and development costs that you can see in the table above.
I'd be interested to know:
- the breakdown of revenue between DiRT, GRID and F1.
- to what extent the revenues are a function of specific games titles being released each year, i.e. vulnerability to future years which might be quiet in terms of the release cycle.
Dignity (LON:DTY)
- Share price: 1048p (-14%)
- No. of shares: 50 million
- Market cap: £524 million
CMA Investigates Funerals Sector
The Competition and Markets Authority announces an investigation into the £2 billion funerals market.
Dignity has revenues of c. £300 million from providing funeral services so, naturally enough, this sounds like bad news.
The Competition and Markets Authority's (CMA) market study will examine whether the information provided by funeral directors on prices and services is clear enough for people to be able to choose the best option for them.
It will also look at how prices have changed over time and the factors that affect them.
Recall what happened last year - Dignity's share price collapsed after it admitted that its pricing was unsustainable:
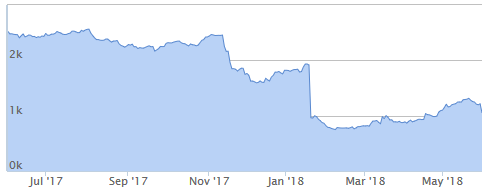
This was as predicted by a short-seller who operates a funeral price comparison site and posted his thoughts here on Stockopedia (link).
According to the bear, Dignity had increased its prices by 81% from 2005-2016, squeezing its customers as much as possible, and this had been the main driver of its financial returns.
In January it announced price freezes for traditional funerals and 25% cuts in simple funerals, to stem its losses in market share.
What will the CMA think? They mention today that low-income individuals might spend up to one third of their annual income on a funeral.
It's a sensitive issue. Personally, I would have thought that this was the sort of thing that the welfare system (or life insurance, for those who can afford it) was supposed to deal with. After all, there aren't really any barriers to entry to being an undertaker, are there?
HM Treasury is also getting involved in the issue of pre-paid funerals:
In parallel to the CMA's market study, HM Treasury is launching a separate Call for Evidence on regulation in the pre-paid funerals sector. The CMA therefore does not intend to examine the pre-paid sector within its market study.
Personally, I wouldn't have marked down Dignity shares by much on this news. In my own view, regulation tends to help, not to hurt, the competitive position of an industry's largest companies (because of their economies of scale - it's harder for smaller companies to pay the fixed costs of dealing with regulation).
The company responds favourably to the announcement:
As one of the UK's largest providers of funeral and crematoria services, Dignity has led calls for greater regulation of both at need and pre-paid funeral sectors while continuing to set the standard for what constitutes best practice in the industry.
So if I was already thinking about buying some Dignity shares, I would be strongly considering doing so today.
I think this could be a decent investment at the current level, but personally I would wait for cheaper entry, considering that it has £565 million in debt outstanding in mortgage-type debt instruments (to be repaid by 2049). So it's not really as cheap as it appears at first glance.
The Stocko algorithms aren't overly excited by it either. They do give it an above-average quality rank:
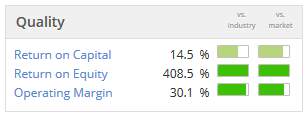
One warning about this is that you do need to watch out when you see a massive Return on Equity (ROE), compared to Return on Capital. This implies a lot of debt capital is being used. Return on capital is a safer metric in that sense, and is a moderate 14.5% in the case of Dignity.
PCF (LON:PCF)
- Share price: 42.5p (-1%)
- No. of shares: 212 million
- Market cap: £90 million
(Please note that I currently own shares in PCF.)
Reader requests have prodded me into saying a few words about this online bank and vehicle finance provider.
Those of you who attended Mello in Derby will have had the opportunity to meet Scott Maybury (CEO) and David Bull (FD), and to listen to a detailed presentation they made, explaining the business. I'm hoping to do an interview with Scott in the next little while, which will hopefully give us all even more insights into the company's long-term plans.
I bought into PCF last December at 27.5p, eagerly anticipating that the company's return on equity would start to climb again towards 12.5%. I don't expect turbo-charged returns from financial stocks like lenders and insurance companies: I expect to earn something similar to their return on equity, adjusted for any dividends they might pay.
What really excited me about PCF was that it had already done all of the hard work in terms of building the infrastructure to operate as a bank. Looking ahead, the plan was simple: build retail deposits, gradually replace the wholesale funding sources, and grow the lending portfolio responsibly.
As things turned out, I got a much faster return than I expected, gaining over 50% in six months. What has happened, I think, is that others have cottoned on to the fact that PCF's lending portfolio is probably going to grow very fast, that it is set to become a much bigger company, and management have continued to execute very well.
I do expect a few bumps on the road but if that all-important ROE number can continue to grow, with impairments remaining under control, then I think investors will do well.
H1 Highlights
PBT climbed 20% in H1 to £2.1 million, but this number matters very little to me, to be honest. The point about building a banking infrastructure is that you build something which can handle much larger payloads. It's very similar to a fund management business. You build a platform which can handle many multiples of its existing assets. That is what PCF is setting out to do.
So even though the 20% increase in net income is to be welcomed, what I really want to see is an increase in ROE: this means that profitability is improving relative to the equity capital deployed by the company.
We don't have much evidence that this is happening yet. H1 return on equity (for the period ending March 2018) is 8.7% - not bad, but much lower than the long-term target. There are growing pains as the company develops into its new business model, i.e. the initial set-up costs and the increased overhead to manage banking infrastructure.
Consider how the overall structure has changed: it has £108 million in new customer deposits as a bank, but it had new business originations of just £69 million. It could be absolutely going for broke with its lending portfolio, but it's not. Unsurprisingly, therefore, the portfolio "continues to perform well and in line with our expectations".
One of the ways in which the company is being conservative with its portfolio is that it's improving the average credit profile of its customers. The CEO was very specific in correcting me when I referred to the existing portfolio as "sub-prime" - he refers to is a "near-prime", and is keen to compete for the lower-yielding but very safe prime segment of the marketplace, now that it can afford to (you need to have cheap funding to be able to lend to the lowest-risk customers profitably).
Big Picture
The big question mark for me is not so much about the 2020 targets, which I am optimistic that the company will achieve (it doesn't matter to me if it doesn't meet them exactly on time).
Instead, the big question mark for me is about what happens between 2020 and 2022, when the company's strategic objective is to shoot for a £750 million portfolio. Some sort of acquisition plan will be required, and great care will be needed to ensure that it is executed properly.
If it goes well, then with the benefit of operational leverage through the banking model, the company will be targeting a significant further increase in ROE, to 17.5%.
Of course, others may also have economic concerns in relation to general conditions in the credit and consumers markets - I am willing to accept these risks, on the basis that PCF is well-capitalised, has a great track record in impairments, and is serving an increasingly strong set of customers. When you're investing in equities, there is often no alternative but to accept that you are taking some economic risk!
Valuation
Net assets finished H1 at £40 million, so the shares are now clearly on the expensive side in terms of price/book value (about 2.25x).
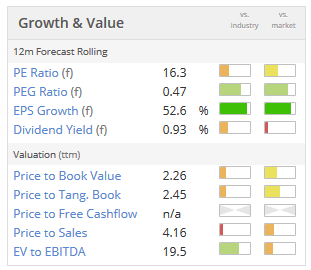
The Stocko value metrics sum it up. The shares are:
- expensive relative to earnings
- cheap relative to earnings growth
- expensive relative to dividend yield (I don't care about this, I want the company to reinvest earnings for growth)
- expensive relative to book value
- expensive relative to sales (irrelevant since it doesn't have "sales" in the conventional sense - it's a bank)
In the end, for me it comes down to two simple questions:
- How much conviction do we have that ROE will improve? (I could be wrong, but I am willing to bet that it will improve toward management targets)
- How many multiples of book value are we willing to pay for a company which will hopefully achieve ROE of 12.5% in the next few years, and perhaps as much as 17.5% in the long run?
These are complicated questions. For what it's worth, I'm happy to hold on to my PCF shares at the current level.
Haynes Publishing (LON:HYNS)
- Share price: 241p (+4%)
- No. of shares: 15.1 million
- Market cap: £36 million
A quick word on this publisher of technical manuals. It has been a great little turnaround story over the past couple of years (and I'm embarrassed to admit that I've been watching it, off and on, all the way up!)
(Be careful - there are two share classes, which can cause havoc with some software programs. I think the Stockopedia calculation is correct.)
This is the opposite of a profit warning:
The Group on target to report adjusted profit before tax (excluding adjusting items and acquired intangible amortisation) up c. 10% from the prior year and ahead of current market forecasts by c. 7% for the year ended 31 May 2018.
I can see a consensus forecast for 2018 PBT of £2.7 million (although I don't know to what extent this estimate has been adjusted for intangibles, etc). Perhaps we can now assume it will be 7% higher, at £2.9 million?
Well done to those who have been staying with this for the last few years. What looked like a very old-fashioned company has found a new lease of life with new management and a fresh approach.
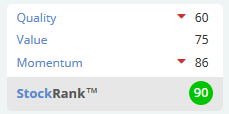
The Stocko algorithms reckon there is still plenty to shoot for: it's classified as a Super Stock.
Ok, I'm out of time for today as I need to attend a couple of weddings. Have a fine weekend!
Graham
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

45 comments
I'm a relatively recent investor and would regard myself as still a beginner. I hold about 30 individual stocks, give or take, with a UK bias but with substantial international exposure. This accounts for 80% of my investment. The balance of my holding is in ETFs and closed end funds. I have selected the funds and trackers with the aim of giving me exposure to advanced overseas economies (US and Germany), to tech. stocks, to China and Asian markets and other emerging/frontier markets, to small turnaround situations, and to start-up businesses.
The investment in funds and trackers gives a bit of ballast and diversity to my portfolio and also gives me exposure to sectors/markets that I would not feel confident investing in directly ... although the diversification means that I am clearly not going to benefit much from multi-baggers and the like.
I run a small notional trading fund alongside my main investment portfolio, with a strict limit on cash committed to it. Good job ... I haven't enjoyed a lot of success in trading so far.
I don't really hold any cash in my investment account. I have free cash available that I could afford to invest amounting to about 50% of my current investment. That is powder that I am keeping dry for the moment, in part pending the next major bear market, although it seems a bit too much and I will probably reduce it as I move from beginner to intermediate status as an investor. My margin account gives me headroom to increase my holdings by about 25% at any time without having to hold cash with my broker. That's more than enough flexibility, I believe.
I am not expert or experienced enough to argue a strong case for my approach. I feel comfortable with it, however, and am achieving reasonable returns. Of course, I'd do a lot better if only I'd prune my portfolio down to just the 'winners' ;-)
Interesting discussion on cash holdings and market timing. After a happy year in 2017 investing in high QVM shares and chasing a bit of momentum I am gradually switching my portfolio into good quality shares with a long divi track records and reinvesting divis using the approach popularised by Jeremy Seigel and others. In this way if the market falls, the divis buy more shares at lower prices and you dont have to worry about timing the market. Of course the real risk of this buy and hold approach is that some of your portfolio cut divis so I diversify across industries. The other uncomfortable characteristic is that the shares you invest in may not always have great value particularly the more defensive ones. I also accept that my potential outperformance of the market will be less and that you need a longer time frame for this strategy to work. Whilst this does mean I am more at the mid - large cap end of the market there are some smaller names in my portfolio e.g. Bloomsbury Publishing (LON:BMY). This should suggest that I should always be fully invested but I haven't been brave enough during this current bull run and am currently around 18% cash! Ill drip this in over the next 5 years or use it all if there is a major correction.
What would be really interesting is if Stocko could do an annual survey of cash holdings amongst its subscribers (I know that a similar thing is done in the fund management business) incorporating any hedging.
My view of dignity is that prepaid funeral plans will be the next equitable life scandal.
Although held separately from the companies funds the amount of money lost in commission and other costs is considerable, So the plan will fall short of the cost of the funeral. Fine if there is no guarantee, but some of these plans guarantee that it will buy a funeral, and it won’t. Watch this space, if the regulator gets this right it will get very messy.
Your warning on Alfa Financial Software Holdings (LON:ALFA) from June last year finally played out this afternoon. Well done again, Graham.
I actually just read that whole report from 1st June 17 and my goodness, all the company reviews Graham wrote were spot on!
I think the reason that Dignity (LON:DTY) has been marked down so much is because they're frightened about what funeral price transparency might mean for their profits.
Dignity (LON:DTY) makes it very difficult for people to calculate (and hence compare) the overall price for a funeral up-front with a complicated pricing model make up a many separate costs for different things.
If they were forced to offer a simple overall cost (which is where I think the CMA is going with this) then it would be obvious that Dignity (LON:DTY) is more expensive than it's competitors by a considerable margin.
I held Dignity (LON:DTY) for several years and luckily got out at £25 but I wouldn't be investing in them at this point.
To add to the discussion, and also one suggestion.
My portfolio summary is :
<2% in cash (worried that I'm nowhere near those previously mentioned!)
26 holdings (too many for me really, but a few are remnants from mis-investing!)
Largest holding accounts for 20%
Top 6 for 60% and top 12 for 85% - So you can now work out the dregs as mentioned, plus a few speculative punts = 14 stocks for the remaining 15%.
I split my holdings into 3 size categories - >5%, 2.5%-5% and <2.5% which accounts for the 6, 6 and 14 above.
I think my main downfalls are not doing enough DYOR, catching falling knives, and top-slicing too soon - All of which, as I'm aware of them, I'm trying to improve/curtail.
Now to my suggestion - There's been a lot of general discussion on SCVR, not related to an individual stock, but extremely interesting to read, learn from, ponder and obviously discuss. Would it be an idea to have a weekend SCVR to discuss (at a more leisurely pace) one of these topics, ideally proposed by Paul/Graham - Italy, Retailers, CVAs, Pension deficits etc. as some examples that come to mind recently.
Lovely commentary on PCF (LON:PCF) and well done Graham. I bought in on the back of your conviction in December and have done very well as a consequence. Great to have two such compelling writes on this site who cover very different sectors and with two such different styles. Your technical analysis of financial shares is first rate and has taught me a lot.
Hi Graham,
Thanks for the report, as always. Whilst we're talking about gaming, I can't be help mention Frontier Developments (LON:FDEV) - you'll recall you kindly covered them a while back, and the shares have increased in value by over a third since then. I have read today that Jurassic World: Evolution has 'gone gold' & copies have been received by reviewers (but are under strict NDAs).
There will be a live game play reveal at E3 on Sunday 10th before release Tuesday 12th.
Remember this is a multi-platform (PC, PS4 & Xbox) global release. Tencent have approx 9% of Frontier Developments (LON:FDEV) and a man on the BoD. As such, they will be pushing this heavily in controlled territories where their distribution platform 'WeGame' is dominant (China, particularly).
Thanks,
IG
NB - I hold a long position in Frontier Developments (LON:FDEV) and topped up today @ £17.99
Using $1.30 translation my back of the envelope ATVI vs FDEV relative valuation still has FDEV as comparatively cheap despite rising 37% (vs ATVI +12%) since Graham's update last September. ATVI has current EV of around $55bn and FDEV is $775m, so that's a x71 uplift, yet the PBT uplift based on FDEV's 2019 and ATVI last FY is only x45 (1.2bn vs 26m). Judging by the unheralded pre-release demand for JWE as evidenced by Steam, not difficult to imagine that broker estimates (only 3 of them of them) are way too conservative. Perhaps a better read across for FDEV is KWS ($1.4bn EV), FWIW i consider FDEV as a more valuable business than KWS. The latter being too reliant on acquisitions for my liking. DYOR
Hello Graham,
As you are thinking of buying Dignity shares it might be worth checking their liabilities from the large number of pre-paid funeral plans that they have sold. This is what put me off the company a couple of years ago. It seems to me that there is a risk that the safety first type of investments in which this money is invested may not keep pace with the rising cost (as opposed to prices) of funerals they are committed to providing. On the other hand, I would guess that some of these liabilities may never be realised if relatives of the deceased do not come across the paperwork relating to the pre-paid funeral plan and pay another provider.
I'm inclined to be cynical about all of these pre-paid funeral plans and will be entirely unsurprised if the Treasury investigation finds some serious issues and decides to place them within the remit of the FCA. It will surely be better for most of us to build up some savings in our own account.
However Dignity do say that "The money required for your funeral is held securely in the independent National Funeral Trust where it is carefully looked after until it is needed." which makes me think that it isn't sitting on their balance sheet.
Hi all,
Good discussion re: cash and timing the market.
I'm just under 10% cash. My portfolio is all UK small/microcaps which is "risky" - or maybe volatile - in itself. I've been investing now for just under 2 years, but all with money I don't plan to use in the near or medium term, and not something I'm relying on, so the aim is simply compound and build with a long term view.
To mitigate risk (or what I think is mitigating somewhat) the small caps are almost all debt free or minimal debt, profitable and growing - all definitely stronger in growth and momentum ranks than value. The risk I have then is with potentially more expensive valuations they are now more prone to sudden/extreme drops should things turn in the market or with the stocks themselves.
Having spent much of the past 2 years trying to read and learn as much as I can, most of the common themes I have come across definitely support staying in the market over the long term opposed to timing, which is something I feel more comfortable with anyway.
Cheers
On Video Games Companies it is ALWAYS worth checking how much R&D they have capitalised in the balance sheet. Secondly , always worth trying to find out of the revenues are on a sale / return basis or a little more solid. When I used to work at a games company we would provide WHS ( thats how old I am !! ) with a large volume on sale/return only to issue a rather large credit note after the reporting end if that product bombed. Codemasters have good solid products , but nevertheless , the business factors may apply. I hold no shares in Code.
Thanks for flagging Codemasters Holding (LON:CDM) Graham. It operates in an interesting space and worthy of further research. One general issue that I do have with the current way IPOs operate is the availability of information. The Admission Document which was published earlier this week but was not available until after 8am this morning. In addition, the initial share price jumped from the 200p IPO price available to institutions to over 250p at the opening.
It puts private investors at a distinct disadvantage purely in relation to the information available. I don't see why the Admission Document could not have been made available prior to today.
I am 25% cash on the basis that a 10 year bull market, the second longest in 200 years, has to end maybe not in the summer but probably during the next 18 months.
An important consideration is that recessions can be classified as either local/regional or worldwide. During this decade long bull Russia, Greece, Spain, Italy, Argentina etc have all had a recession. We cannot exclude the UK from this prospect which is why I have 25% of my portfolio in USA/dollar denominated equities.
At this stage of the cycle it may be unwise to have 100% of a portfolio in UK small caps?
Graham,
Another recent IPO of a games company to look at if you want to buy into the sector is £TM17 who are best known for the Worms series.
Hi Graham - suggest some comments on Haynes Publishing (LON:HYNS) trading statement. A great turnaround story over the last 2 yrs and now a very different business to the one most people are familiar with. Thanks !
re: Haynes Publishing (LON:HYNS).
Nice tip Dr. Vodka. Done!
Timing the market is always going to be difficult. It really depends upon your investment horizon and generally speaking - cash loses its value over time, shares increase their value over time.
I have held a pretty defensive portfolio for the last 18 months - on the basis that this bull market can't possibly go on much longer. As a result I've missed out on profits by selling out too soon and by not buying stocks that looked overpriced. I still think that my underlying assessment of the market is correct but each time a potentially serious problem emerges (Trump tariffs, Italy,,,,whatever) the market dips for 24 hours then shrugs its shoulders and carries on upwards. So my question is.....is anyone else here currently trimming their portfolios and building up cash?
I've been around 20% cash for a while. For me, it's good to have something spare, in case there is a crash, but also good to mostly be invested, in case there isn't. What sort of cash % are you working with?
Thanks Graham. I'm on about 15% cash at the moment. I usually aim for 10% so I'm a bit up at the moment partly because I can't see much that looks cheap enough. Interested to know what others are doing.
Now down to 55% cash. Still waiting!
Yes. I hold about 20% in cash and have a very odd portfolio of an number of small starter positions in penny shares with potential, residual free carry shares where I have taken out the original capital to preserve it and swing trading shares where there may be a short term catalyst for a price rise eg FLO this morning. I would prefer to have a buy and forget portfolio of FTSE 250 companies paying a growing dividend but can't bring myself to buy and hold out of similar concerns to you when I might be able to buy in lower in the near to medium term.
Hi, this is exactly the question I have been pondering and I was going to post a similar question this morning. Before I say anything I have been investing for a while so I do understand market timing is a waste of time. That said if you think the market is too high it doesn't make sense to sit and watch equities sell down. Obvious I know but I don't really agree any longer with this buy and hold strategy. My experience is it just doesn't work any longer. I had an example this week where I bought Pressure Tech at 1.4, they hit £2 and now they are back at £1.4. This keeps happening time and again. I think it simply reflects the degree of risk in the markets driven by low interest rates and relatively low volatility. But this artificial environment was put in place in 2008, and you could make a case that interest rates would be expected to go up from 2012 onwards if central banks let things move more naturally.In short I agree with your position but where do you put your cash to get any sort of return, if this goes on for another 5 years?
Hi Camtab,
Buy and hold should always work if you invest in companies that are well managed, growing and reasonably priced. Price action follows the performance of the business so if earnings and dividends are growing the share price (usually) keeps up to pace as long as the rating is not excessive. Your example of Pressure technologies is not a great one imho. It took a tumble from 2 to 1.4 on Wednesday after a poor T/U. Paul Scott didn't seem to have a particularly great view of it and management felt it was going to under perform market expectations. If there is any sort of doubt about the future prospects of a company why invest? There are loads out there with great prospects! Unless you are a talented short term trader with the time to do so then buy and holding good businesses that compound earnings and divis over time is the only way imho!
The very best of luck.
Hi
Ref cash holding.
I hold 30% at present but was higher in the early part of this year (over 40%). I do prefer to be as fully invested as possible though.
To that end I've been screening UK, US & Europe with a Minervini inspired screen.
Very few UK stocks are now meeting the tests (there were more earlier in the year). A few European stocks are, but by far the numbers from the US are dominating screenings.
This is surprising to me as the narrative is that US is overvalued, yet my screen which is quite harsh on earnings, sales and margin growths still returns 20 to 25 US stocks.
As a consequence I am increasingly buying US stocks (for example £HFC and £DECK), recognising the high index valuations, but seeing through the quants that earnings which drive share prices/growth are in fact clearly present in the US.
I've no idea if this will work out and I am prepared to reduce/exit rapidly but my US buys are up significantly more in contrast to my UK holdings (also, to date, the US share price growth rates more than compensate for FX charges).
Regards
Howard
Yes a survey is a nice idea but I suspect for many PIs 'cash holding' is a vague number - surely most hold quite a lot outside their main portfolios in bank accounts that could be deployed in extremis but is typically there for possible major expenses eg house move/ refurb, car purchase, buffer of several years' living expenses etc? In my case I'd typically want 20-25% of my main portfolio value as available cash.
Other things perhaps worth surveying are:
1. Trading frequency. Even though I spend perhaps 1-2 hrs/day on investment matters I manage to make barely 1 trade a month, maybe 2 at best! Perhaps my natural indecisiveness?
2. Portfolio concentration and diversification. I sense that many Stockopedians are way more concentrated than most investment 'professionals' would recommend. One thing I found staggering about this article https://www.telegraph.co.uk/pe... was the quote "The major concern for our panel was the spread of the investments. A portfolio of that size would typically be divided between at least 20 funds – not just two, said Jon Treharne, of IFA Shore Financial Planning." So for a £1/2m portfolio the experts recommend over 20 funds, each of which will have perhaps 30-60 holdings, ie getting on for 1,000 individual holdings, presumably with appreciable overlap. OK I know we're not talking entirely UK equities here as there will no doubt be a lot of overseas stuff, bonds, commodities etc in a balanced portfolio, but I am genuinely concerned that the 'conventional wisdom' is to run such huge diversification.
Millen point taken on cash holdings but what I was thinking was more along the lines of how much PI's cash %holdings have changed over the last month, year etc. Cash holdings will also reflect liquidity of portfolio and trading style - I would have expected that those with lots of illiquid small caps would see bigger shifts in cash holding % so the important data is how much their cash changes over time.
Re trading frequency - sometimes I don't do anything for 4 or 5 weeks. It depends on your investment approach. If you are buy and hold you are going to be trading less than say a technical trader. All other things being equal I think fewer trades better but you might have more activity in the early days as you are finessing your investment approach
I agree the Telegraph comment is nonsense. Somebody with a portfolio of 20 diversified funds is going to end up with a very expensive tracker. This was clearly written with investment fund managers / advisors interests in mind!
I have never understood the logic of holding multitudinous funds either. I can though see a case for holding a internationally diversified selection of low cost ETFs, especially if you don't have the time or inclination to study the market. It was Warren Buffett that once famously said: “Wide diversification is only required when investors do not understand what they are doing“.
About 20 companies appears to be an optimal holding between individual stock risk and market risk. This should be conventional portfolio wisdom, not the piffle espoused by most financial managers.
P.S. I hold around 30, just to be sure!
Hi iwright7.
I tend to be sceptical of most claims about “this is how the market works” wherever they come from, preferring to assimilate the various theories, distil an approach and then trial it to see what works. (I trained as an economist and found most abstract theories fell apart on first contact with the real world!). When it doesn’t work I’ll adapt and try and find something better.
I had reason a couple of years ago to take on a reasonably large sock of cash for long term investment (I pulled together several occupational pension schemes and AVC’s into a single SIPP) and was faced with the interesting challenge of where, when and how to invest it. On the principle that “diversification is the only free lunch in investing” (not everyone agrees with Buffett’s concentration ideas and given the large FUM he controls even he/B. Hathaway has a surprisingly disparate range on investments), I set about looking for a framework for investment that would have a reasonable chance of protecting capital while offering a decent (not necessarily market beating) return.
For various reasons I’ve kept this separate from my active investment portfolio of individual shares and limited my portfolio to the universe of collective investments (i.e. passive and active funds and ETF’s). Likewise, rather than take on the market timing risk of investing the entire lump sum at the outset, I’ve been dripping it in monthly over the past 18 months to a point that it is now just about fully invested and the only cash is coming from accrued income and dividends.
Still early days, but I’ve learned a few things. Firstly, by breaking the global investment market up into sectors by geography (Nth Am, Europe, UK, Asia, Emerging Markets etc.), asset type (fixed income, equity, commodity, property etc.), investment focus (sector, market, asset type, etc.) and investment structure (active managed, passive index, ETF etc.). you quickly end up with a very big matrix of potential areas for investment. On top of all of this, there is the added complexity of Foreign Exchange translation added to the mix. Secondly, there are a huge number of investment funds of wildly varying historic performance and fee structures to choose from, all claiming to be the “best” in their respective fields. Thirdly, trying to predict future events and their consequences on the markets seems pretty fruitless. Even if you call the event correctly, the market often seems to move in an entirely counter intuitive way (think Brexit referendum and the rise in UK markets, Trump election and the bull acceleration in the US). So far as I can tell, I’ve yet to find a single investment that (realistically) claims to be a tracker of “the global investment universe”, so I’m stuck with trying to build a proxy to deliver this from scratch.
Accordingly, rather than try and second guess what will happen, I’ve looked to construct a “portfolio for all seasons” that will hold value, earn a decent return and contain checks and balances with gains offsetting losses. As a result, the number of holdings is quite large, about 50 separate investments, and even at this level there are areas that are ignored/under invested. (For example, there’s very little fixed income as I find it hard to make a case for buying bonds at the moment in a world of high debt/potential for credit default and rising interest rates/reduced bond prices). Even so, I’m still not happy with the mix and think I need to do more to protect against systemic risk from a global downturn (I don’t necessarily think it’s about to happen, but the investment objective is to try and take market direction prediction out of the equation).
Early days, but results so far are OK. Casual observation is that the ETF’s have (surprisingly) significantly under performed the basket of funds, the managed funds have done better than the indexed funds (even allowing for the generally higher fees) and the Investment Trusts (with the benefit of some leverage) have done best of all. Oil linked funds have done well, gold linked funds have been poor, small caps have beaten mid and large caps and Japan and Asia have been the best geographic markets. None of this is very scientific, other than to observe that in the general chaos of the global market, it’s very difficult to prescribe a priori what will give the best outcome in the future. With this in mind, I’m quite comfortable to take a wider level of diversification than theory might suggest and try and back all of the horses rather than pick the winner.
Gus.
Gus,
The good thing is that there are lots of ways to systematically invest in the stockmarket.
I am normally an individual stock picker, rather than a sector pricker and am happy to avoid too much diversification. More particularly I adopt a high QM selection approach so am relatively active - If a company loses momentum for too long it wont stay in the portfolio and will be sold to make way for something else.
Each month I cross check my results against UK market indices. For the12 months to end May there was a disparity between large and small caps gains: My end May notes: FT100 higher @ 7700 (+3%) vs. 7530. AIM100 @ 5650 vs. 5000 (+13%). AIM has done very well over the last 18 months, so its a pity that there is no AIM 100 ETF/fund available.
Hello anothersaxman58
Definitely an interesting question. I think it was John Maynard Keynes who said "the markets can stay irrational longer than you can stay solvent." The efficient market hypothesis says exactly the opposite - that markets (on the whole) are good at balancing all the information currently available. But how can the market synthesise profit trends, debt levels, interest rates, Trumps ego-mania, Putin's attempts to destabilise the West.... to get to a sensible composite position. Even more difficult is that some of these factors are so binary: trade war - on or off, Brexit deal - on or off...
So I have been doing something a bit like you over the last two years - taking money out of the market. I am now about 25% cash. Where I think I may have been doing it differently is that I am trying to focus on holding high quality businesses with good barriers to entry and no debt, good ROE / ROCE and good free cashflow. These companies are usually (often very) expensive but their businesses are less likely to suffer even if their share prices might crash. And (I think Graham recommended this recently) I am putting together my plan for how to react when the recession / bear market / crash comes along - so that I know what to do even while my panic reaction leaves me like a bear in the headlights.
Hi, I've been hearing that this so called bull market can't last for a few years now but it still keeps going despite the occasional hick up! As a result I stopped reinvesting but didn't trim or sell out. I'm glad I didn't because my picks have kept on rising ( despite the occasional hick up ). So as I am absolutely terrible at timing the market I intend to reinvest slowly and choose strong well run companies ( Hopefully ). What's the rush? I would rather take my time and get it right. I tend to buy and hold for a long time and this has always worked for me although I sympathise with those who say this is a bad strategy as they watch their high flying shares return to normal original pricing! I know that Black Swans can come out of nowhere but the market shrugs them off over time. I believe I read on one of Paul's comments that Banks could fail if things go seriously belly up in Europe so I'm wondering where everyone keeps their cash that they are not investing? Isn't a bank account just as risky as the stockmarket?
System1 (SYS1) results today tell a sorry tale, though they seem to have taken strong action and to remain profitable and cash rich. This looks like a good entry point if you trust the management. I'm neutral and hoping that TechMarketView covers SYS1.
EDIT: TMV didn't cover it - SYS1 isn't in their universe of interest. So I hope Graham is willing to look at SYS1
Paul's battered holding Image Scan Holdings (LON:IGE) announces new portable x-ray machine channel partnership in Brazil, market doesn't seem to care though!
Perhaps the market thinks, if they can't sell them here why expect someone else to be able to sell them there - Perhaps!
£HOLCO
Morning Graham
Given the quiet UK small cap world today I wondered whether you might consider looking at a Dutch small cap. Holland Colours reported their FY results after hours last night.
Revenue growth continues though there was a significant increase in some raw material costs (20-100% up in some cases) hitting the bottom line. Dividend increased. Stockpiling of inventories hit cash flow.
Results published in English on their website
Cheers
http://www.bbc.co.uk/news/business-44327899
Investigation into funeral prices - might be worth a deeper dive for those who hold Dignity (LON:DTY)
re: Dignity (LON:DTY). Thanks for flagging that - will mention it in the report. G
My morning smallcap tweet:
Haynes Publishing (LON:HYNS), STM (LON:STM), Sprue Aegis (LON:SPRP), Abbey (LON:ABBY)
Haynes Publishing (HYNS) Guides FY adj pretax up c. 10%, ahead of market forecasts by c. 7%. "As reported at the interim results in January, the changes to the US federal tax rate will reduce the US net deferred tax assets and liabilities by c. £0.8 million. Therefore, Group profit after tax and adjusting items will be c. 5% lower than the prior year."
STM Group (STM) Deloitte expected to finalise its Gibraltar regulated entities Skilled Person Review in the coming days, on receipt of the respective management responses from the various Gibraltar businesses.
Sprue Aegis (SPRP) finds new FD, starts Dec. Executive Chairman to step down to NED when a replacement non-exce chmn found.
Abbey (ABBY) FY trading. Rev similar to last year but "somewhat lower" margins mean operating profit down.
Seems quite a quiet morning for small cap news - presumably market today will be driven by the bigger “macro” issues (Italy govt agreed for the time being, US steel and aluminium tariffs, Spain PM facing vote of confidence on corruption allegations, N Korea nuclear talks off/on depending on which news thread you read, the “B” word etc.). Also US non farm payrolls this afternoon that usually generate a bit of activity on the USD and knock on to the equity markets. Is it just me, or are we stuck in a three ring circus at the moment with a higher than usual quota of clowns? Hard for the PI to know quite where to look at the moment.
On the company news side, I did see that OFGEM has announced an enquiry into Telecom Plus (LON:TEP) (trading as Utility Warehouse brand) debt management arrangements.
https://www.investegate.co.uk/ofgem/rns/ofgem-investigates-utility-warehouse-on-debt/201806010708489721P/
Not a small cap at the moment (about £800m market cap) but might be by lunchtime .....
Gus.
Graham, could you comment on the PCF results ? They seem to be have been passed by last week
re: PCF (LON:PCF). You have many likes for that request - so ok! G