Small Cap Value Report (Fri 1 May 2020) - BDEV, CRPR, KMK

Good morning, it's Paul here with the SCVR for Friday.
It's a quiet day for news. Remember that I only cover results & trading updates for some sectors. I'm not going to comment on other stuff, like speculative drug companies jumping on the Covid-19 bandwagon! Because I have no insights on anything like that.
Here is the link to yesterday's report - in case you missed it, I added new sections on Up Global Sourcing Holdings (LON:UPGS) and Cenkos Securities (LON:CNKS) in the afternoon/evening.
Today's report is now finished.
Barratt Developments (LON:BDEV)
Share price: 515.8p (down 0.6% today, at 09:13)
No. shares: 1018.3m
Market cap: £5,252.4m
(I currently hold a long position)
This update from the UK's largest housebuilder is very similar to recent updates from other housebuilders.
Key points;
- Phased re-opening of sites, from 11 May (not re-opening in Scotland - no reason given)
- Social distancing marshals on each site will enforce compliance with new procedures
- Reduced level of customer interest - this seems at odds with other housebuilders, who sounded more upbeat about demand
- Limited number of additional completions this FY 06/2020
- 11,776 completions YTD, very similar to LY (11,723)
- Forward sales of 12,271 houses, £2.85bn
- Taking same cash conservation measures as others
- Cash - £430m, plus undrawn £700m RCF, plus Govt CCFF scheme funds if needed - sounds strong, no issues with solvency, as with other housebuilders - the whole sector is vastly more financially secure than in previous recessions
- Outlook - guidance was withdrawn on 25 March. No update given. This is no good, they should have a very clear idea of the outturn for FY 06/2020, given that few further completions are anticipated.
My opinion - my view remains positive on this sector. With interest rates at historic lows, I don't see any likelihood of house prices falling a lot. Hence with building work resuming, this sector could continue recovering. I imagine the Govt is likely to want to stimulate activity, hence a drop in Stamp Duty seems likely, in my view.
Balance sheets are a joy to behold in this sector, they're amazingly strong. Other sectors could learn from this. Corporate financial strength needs to be increased across the board in Western economies. Hence, as indicated by Shoe Zone (LON:SHOE) for example, dividends may be withheld until companies have strengthened balance sheets, which could take several years. Given that housebuilders have such strong balance sheets, then I expect they should continue to be good dividend payers.
James Cropper (LON:CRPR)
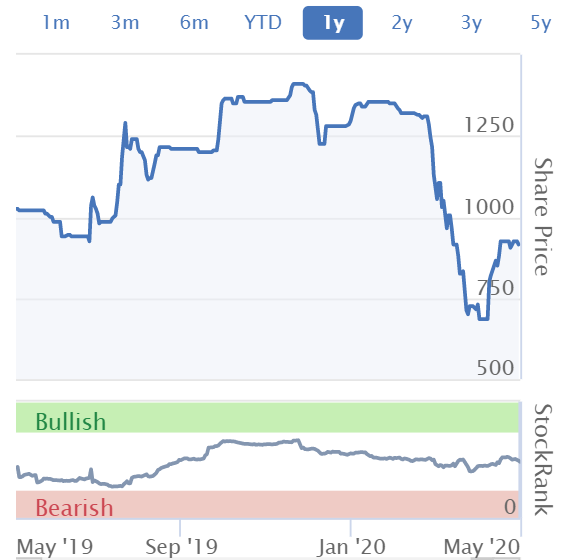
Share price: 900p (down 1.6% today, at 09:58)
No. shares: 9.55m
Market cap: 86.0m
Further to its announcement of 24th March, James Cropper is pleased to provide an update on the expected outturn for the year to 28th March 2020 just ended and on our expectations for trading during the current year.
It's helpful when announcements start with a brief description of the company's activities. Investors & commentators look at hundreds of companies, and it's not easy to remember what activities they all do. Cropper doesn't provide that information today. As an alternative, each company's StockReport here on Stockopedia provides a Profile Summary near the bottom. In this case it starts with;
James Cropper PLC is engaged in the manufacture of specialist paper and advanced materials...
Performance for FY 03/2020 looks strong. Although this would only have had a slight negative impact from COVID-19, right at the end of the year;
Year ended 28 March 2020
As a result of delivering on the growth strategies within each division, the Group produced a strong performance last year with positive growth in both revenue and profits. Market penetration and expansion has been achieved across the divisions.
Adjusted pre-tax profits (excluding IAS 19 impact) are expected to be well ahead of market expectations for that period and in excess of £6m.
COVID-19 impact - the above is a really good starting point, but as I would expect, performance has since deteriorated -
Whilst the Company was on track to continue growing, the impact from COVID 19 will have a negative effect on product demand in each of our divisions...
See the RNS for more details of divisional performance.
Outlook - for the new financial year ending 03/2021 is quite detailed, which is good - we need this kind of information from companies, rather than guidance being completely withdrawn;
...we are expecting that the course of the financial year will be as follows:
the first quarter to June 2020 to incur a large negative impact and it will be loss making. During this period, the Company is making use of the Government's Coronavirus Job Retention Scheme to furlough more than 50% of staff in the UK operations.
In the next two quarters, to December 2020, we expect still to see a negative effect and to continue to be loss-making, albeit with some recovery evident.
For the final quarter to March 2021, we expect progressive recovery towards a more normalised situation and the Company anticipates being back into profitability.
That's useful information, but it doesn't provide any actual figures. So I'm still largely in the dark, or at least experiencing twilight.
The business is now, we believe, in an 18-24 month recovery period. The Company expects a hit to cash during 2020-2021over the period of the COVID-19 pandemic and as we return to more normal trading conditions...
That's interesting, and it chimes with what a lot of CEOs in America are saying (I've been glued to CNBC in recent weeks - it's very good for intelligent views & commentary, at least whenever that clown Jim Cramer is not participating). This all adds weight to the idea that a V-shaped recovery seems fanciful - something I've been saying here recently. This makes the stock market's massive rebound in April seem premature.
Cash/liquidity - key point;
- Cost-cutting done
- No final dividend
- £12m available headroom on cash/bank borrowings - "sufficient to weather storm"
- Looking into borrowing for future capex
Balance sheet - I've reviewed the last one, as at 28 Sept 2019. Overall, it looks OK, so I don't see any issues here re solvency. Although that depends on how bad the losses are this year, which the company doesn't provide any guidance on.
A couple of cautionary points;
Receivables - could need a doubtful/bad debt provision, if customers are unable to pay CRPR's invoices.
Fixed assets quite high, so this is a fairly capital-intensive business.
Big pension deficit - I'm very wary about these right now, because ultra-low interest rates drives up the liabilities, and the stock market correction may have pushed down asset values in the fund. This is a key point to research, for anyone considering a purchase here.
My opinion - it looks an OK business, nothing special. Therefore I would only be interested in buying its shares if it became dirt cheap, which is not the case now.
The pension scheme is a major negative. No dividends for now. Losses this year, but they don't say much - must be significant given that 50% of staff have been furloughed.
Overall then, I don't see any reason to want to buy this share. Another consideration is the ludicrous bid/offer spread of 850p to 950p. If you pay full ask, you've therefore incurred an immediate 10.5% loss - which is absurd. Out of curiosity, I checked the real prices with my broker - it's 860.5p bid (2,500 shares), and 940p offer (1,500 shares). That would still equate to an 8.5% instant loss - which nullifies any logic for buying this share.
Analyst forecasts have not yet been reduced, so the forward valuation metrics are currently meaningless.
.
.
Kromek (LON:KMK)
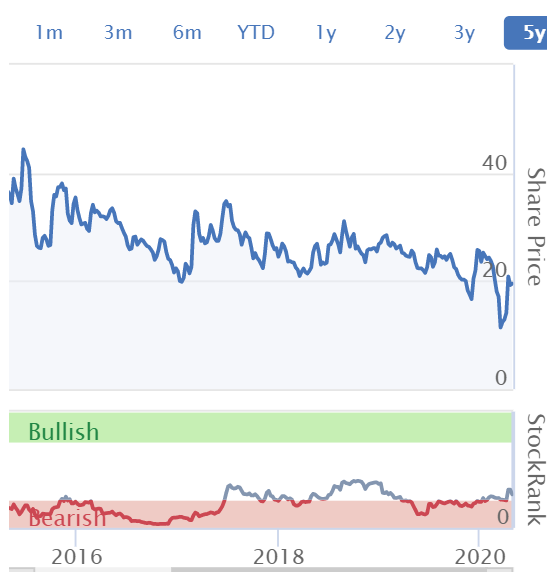
Share price: 17.5p (down 13% today, at 11:20)
No. shares: 344.6m
Market cap: £60.3m
Full year trading update & COVID-19
Kromek (AIM: KMK), a worldwide supplier of detection technology focusing on the medical, security screening and nuclear markets, provides an update on trading for the 12-month period ended 30 April 2020 and its business response to COVID-19.
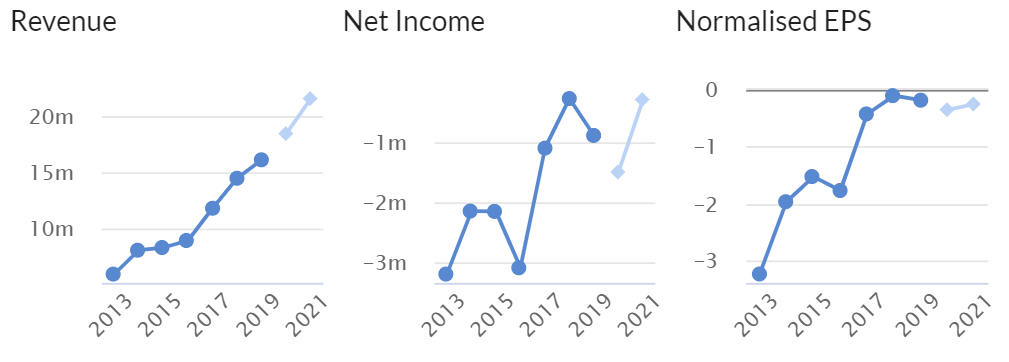
This story has been around for a long time. As you can see below, it is making progress, but 7 years of losses, and a tripling of the share count over that period, must be trying the patience of even the most optimistic shareholder.
.
.
Profit warning -
- Kromek was doing OK until end Feb 2020
- Mar & April saw impact from COVID-19
- 2 key contracts delayed into FY 04/2021
- FY 04/2020 revenue £14.5m (well below £18.5m forecast)
- Adj EBITDA breakeven - but this translates into adj LBT of -£4.6m, which looks pretty grim to me
- Multi-year contracts, which it reckons gives good visibility
- Making ventilators - no indication of profitability of this sideline
- Cash of £10m, debt of £5m, hence net cash of £5m
Cash preservation measures look significant -
...ceasing all discretionary capital expenditure; curtailing all travel and non-essential spend; and, securing a short-term rent concession on the Group's leased properties. These measures, along with others in the pipeline, are expected to reduce monthly running costs and cash outflow, generating annualised savings of approximately £3m.
Outlook - too uncertain to give guidance. Board confident it can withstand the current situation.
My opinion - I'm surprised that the market cap is as high as £60m, given the poor track record - being unable to break into profit, after a long time trying. Maybe it could succeed in future, but I have no way to assess the likelihood of that happening. Therefore, for me it would only be a punt, not an investment. Hence it's not of interest to me. It's probably only going to appeal to punters, or experts in the sector who are able to determine if the products are any good or not. The 58% gross profit margin suggests its products must be pretty decent, to have some pricing power.
.
.
That's me done for the day, and the week.
Many thanks for your comments, very useful points often.
Best wishes, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

50 comments
might be a long time before house purchases get back to anything like normal and mortgages will be more hard to get.I think the market will remain depressed for years
Barrats have done very well over the past three years due to their really good land bank sites, I do think going forward they don't have a lot of particularly good sites compared to competitors.
I went to view their site on the old Upton Park ground, it is their current huge flagship site and it is awful, the flats themselves are really nice but I cannot see why anyone would pay 500k+ to live there. Area, transport, amenities... everything are just awful.
Compared to Taylor Wimpey who have several really attractive sites in the nice areas of Hackney/Ebbsfleet/Surrey. I favour £TW going forward.
CNBC is on 24hours as combines America Asia and Europe on a cycle.The London part is on 6 or 7.am to 10 am.The starting time seems to vary since the lockdown.Prior to the lockdown the London show largely depended on the guests on it.The 2 male English presenters have been doing the show for over 15 years as have their American counterparts and have lots of contacts.They get long interviews with the likes of Warren Buffett.
The male presenters tend to be very opionionated though and interrupt guests too much The female presenters tend to be very good.When you look at the deadbeat females currently in politics you wonder why some of the ambitious CNBC female presenters have not gone into politics?
The CNBC soundbites that go alongside the adverts have become full of dishonest virtue signallingly.
One senses that the people who produce CNBC as with most of the mainstream media are basically careerist virtue signallers.
A rather good, and despite the title, not so gloomy article covering the current state of affairs in UK housing in todays Times. Sounds like base case is -5%...which as Paul says isn't too much of a problem for new house builders...
Re affordability. As a result of the GFC, interest only 100% LTV mortgages and worse ( teaser rates etc) are a much smaller as percent of lending, which is great for health of mortgage market. It only really protects the lender from the impact of higher rates though, which we all agree are some way off.
What this does mean is for a normal borrower, a repayment mortgage on a £300,000 house with an 80% mortgage is £1300 a month ...not £400 as someone suggested. This is manageable but a decent chunk of disposable income, for a dual income of say £60,000.
What you can see in the Times piece is that even in a -5% price scenario mortgage lenders will pull back on the 80% plus mortgage availability which reduces transaction numbers. Fears of worse could accentuate this trend.
As the analyst from Peel Hunt and Paul highlight, balance sheets are materially better than 08 which is positive. But it is still a house builder.. and the business model will consume that balance sheet pretty quickly if cancellation rates rise and transactions fall. Ofcourse we haven't seen this yet, because we are in lockdown. I think Id probably wriggle out of deal if it was me... and forego the holding deposit.
What does consume your balance sheet mean? It means book value or NAV falls because cash disappears, you have unsold stock to write down and land bank needs to be written down.....this isn't a solvency issue as Paul says ... unless they draw down the RCF.... but it will impact share prices.
Barratt Developments (LON:BDEV) tangible book is £4bn ...c400p a share.. compared to the current share price of 530. If the cash is consumed, they take a 20% haircut on WIP and a 15% cut to land ( -5% house price scenario) this would be a £1bn (25%) hit to tangible book... reducing it to 300. I think this illustrates the sensitivity of the model to changing trends.
Uk builders
I've bought and sold a few central London properties on an small basis since 2000. One left today. My view is the current situation is somewhat 'stable' as when I do the math on my current property the mortgage payments based on 20% deposit 1.5% prime rate and 25 years term are about the same as the rent. And that's a repayment mortgage not interest only. When the market is too far ahead the mortgage payments normally rise above the rent, when the market's depressed the reverse happens.
Interest rates globally are on the floor and will stay there for many years because (a) they are suffocated by a sea of govt bond issuance aka QE (b) no govt would raise rates and destroy their economy
Understand the inflation bogy forcing rates up, but because of (b) above I see govts ignoring asset inflation, like they did after GFC, for now.
Help to Buy - I scuttlebutted around local new-builds and yes, HTB is a big factor here, along with Asians who are still buying will cash. No idea where HTB will go other than Tory governments usually pump property.
I own Berkeley Group (LON:BKG) (£1 billion in cash) and Countryside Properties (LON:CSP) (lovely capital light model)
Bought both cheap recently and I hold for a gradual rebound over the next 18 months or so. No plan to hold for the longer term.
In my lifetime of 50 years, house prices have only fallen when interest rates shot up, and made monthly mortgage repayments too expensive. Right now, the situation is as far as possible to imagine from that trigger.
Hi Paul
Over time that's true but when we get big shocks and sudden drops in interest rates it's usually because of some major economic event, which triggers a rise in unemployment. The last time that happened - in 2008 - the drop in interest rates was accompanied by a 20% fall in house prices which didn't recover for over five years.
We know unemployment will rise quite rapidly but we don't know what will happen after - the limited evidence from other pandemics is that the following recessions tend to be U shaped. But given how much the government has spent going into this it's hard to believe they won't spend coming out of it and housebuilders will probably get a fair chunk of that. Hopefully unemployment will drop rapidly.
There will also be a lot of permanently vacated retail and commercial properties. Rather than turning town centres into ghost towns I'd hope the government would encourage redevelopment and reuse with a lot of spacious low-cost homes and local amenities (creches, convenience stores, outdoor exercise areas). Builders prefer greenfield to brownfield sites because the former are more profitable but a well-thought through policy should target the latter.
Most housebuilders will be fine but their land banks may be worth a lot less than they're currently valued at. Personally I prefer the heavily cashed up ones - Persimmon (LON:PSN) and Berkeley Group (LON:BKG) - but many have their attractions right now.
timarr
Equity values built up in homes are in a far better position than in 2008 with mortgage terms being much more strict since.
I don't see there being any forced sellers of homes while banks are giving mortgage holidays and the government are paying for furloughing. So I don't see a lot of pressure in the secondary market.
In the primary market there may be less demand but in a deflationary, low interest environment, it makes more sense for house builders to sit asking for the same house price than try to sell quick by reducing the price and have the cash.
They also hold the bulk of the buildable land in the country.
I don't see there being any forced sellers of homes while banks are giving mortgage holidays and the government are paying for furloughing. So I don't see a lot of pressure in the secondary market.
That's not going to last forever. Furloughing will end relatively soon, although I imagine it'll be tapered - but the job losses from BA are a foreshadowing of what's to come in some industries where demand will be reduced for a significant period of time. A fairly sharp rise in unemployment looks inevitable and the best estimates are second quarter next year for a return to growth - assuming we've got Covid-19 under control.
The worst case downside is that (1) unemployment rises sharply, (2) people can't afford to pay the mortgage and (3) everyone's too scared to buy = house price drop. Of those (1) looks like a certainty, (2) ought to be limited due to mortgage holidays for a while and (3) is quite likely, so the most probable outcome is a smallish decline unless it takes longer to get the pandemic under control than anticipated.
The immediate issue for housebuilders is cashflow if sales dry up, the secondary one is a flood of brownfield sites with prioritised planning permission undermining their existing landbanks. Fortunately most of them are pumped up with government cash due to Help to Buy so unlike 2008 there's not much solvency risk. Of course, if we're still managing Covid-19 and practicing social distancing in a year's time anything could happen.
timarr
Interesting to read your views on CNBC and Jim Cramer, Paul. When I first saw Cramer about 15 years ago I couldn't stand him either but have really warmed to him. Now, whenever I'm in the US (quite often) I try to get back to the hotel to see his 6pm Mad Money show (only broadcast in the US). He is extremely knowledgeable about a heck of a lot of US stocks, even though he can sometimes call them wrong. He has an interesting background (https://www.cnbc.com/jim-cramer/) and I've read a few of his books which are a good read.
For many years now when in the US I stopped watching Squawk Box, their pre-market open show. The presenters are really annoying, none more so than Joe Kernan (https://www.cnbc.com/joe-kernen/) who really is stealing a wage. He is so arrogant and stubborn and wrong about so many basic things. He knows very little outside his limited range of specialism. A few years ago there was a cringe worthy video going around social media with the CNBC Squawk Box presenters arguing with a Republic of Ireland (Eire) politician. The CNBC presenters were adamant that the Rep Ireland had the British pound as their currency and kept challenging the Irish politician when he tried to explain that they had the Euro as their currency. You'd think it was a joke but seriously this is how inept I find the coverage on Squawk Box.
If anyone else travels to the US in the future, the CNBC evening show of Shark Tank (Dragon's Den) is a good watch, though valuations are ridiculously high compared to UK standards, especially for unestablished businesses.
Re CNBC - I agree about Joe Kernan - he's obnoxious, nauseating & incredibly stupid. Clueless.
Jim Cramer - yes, knowledgeable about lots of stocks, but his whole ranting clown act ruins it. Also, such a thick accent, and numerous pointless sporting references, that even his interviewees often have to ask him to repeat the question. Ass-licking to CEOs is also cringe-worthy.
But, have to say, I've had a much better feel for the market (and made money) from having CNBC on in the background, and jotting down the occasional insight from interviewees.
I often watch the US closing bell programme on CNBC at 9pm UK time. Can be eye opening sometimes (e.g their idea of a cheap her!) especially some of the analyst comment. Most of the commentators seem bullish about their markets most of the time.
wild shot
CNBC is also on Freesat. Do you know what time it is on here in UK please?
Hi Ken,
I don't have Freesat so good to hear you can access it there. CNBC is a 24 hour broadcaster so should always be broadcasting. If you are asking for a specific show I'm not sure which show you are enquiring about? CNBC has regional broadcasts so Mad Money and Shark Tank are only broadcast in the US, not the UK. However you'll be able to see Squawk Box and Squawk on the Street which Paul watches in the UK from mid-morning UK time and the US CNBC broadcasts right through the US trading day times.
I remember in mid-March Cramer talking about "buy buy buy" there is no risk from here etc.
I have also seen him doing interviews of how he used to manipulate the market when he worked for a hedge fund.
For that reason I am very sceptical of him and people like Ron Barron who was saying Tesla was going to be bankrupt at 180 (looking at the balance sheet I knew it wasnt right) and then he pumped it up and said it could hit 5,000.
So I'm just really quite contrarian to most of what is said on CNBC and these channels.
I had the opportunity to invest in Kromek pre-IPO, but did not take it. My understanding is that their primary technology has no significant competitor, but then Concord does not fly any more. I am happy to have missed it!
The reason why Barratt - and all non-absolutely-essential - construction operations haven't re-started is because the Scottish Government has made it illegal to do so, despite it being an opportune time. For instance:
- on civil engineering sites to improve live assets such as road, there will be a hell of a lot less disruption to the road user due to reduced use and greater access = reduced cost, less time needed to do the work.
- on schools, wouldn't it be good to just be allowed to go while the kids aren't in school, even just surveys?
Instead, they are is willing to send companies and people's livelihoods to the graveyard in order to ... save lives/be one up on Westminster (delete as appropriate).
I don’t agree with you here. I do work on Taylor Wimpey, Countryside and various other sites and the reason they haven’t ‘gone back’ is because they are all very hesitant to be the ‘first’ to do so thus ruining brand image. Sites such as Bellways and McAleer & Rush are returning next week on sites near to completion.
I don't see any likelihood of house prices falling a lot.
Bold given we are supposed to be in the middle of a 30s style depression.
Bold given we are supposed to be in the middle of a 30s style depression.
Is it actually being bold saying one expects things to stay where they are in that regard , i would have thought the bold person is one who can predict a 20-30% drop 6-12 months before that drop happens. With ultra low interest rates / minimum wage increases and an ever increasing population (increasing faster than new houses are being built i presume.) I don't personally see the need to presume the worst will deffo happen, for most of the country for a say 300k valued house on 80% mortgage with 2% interest rate one only needs to find £92 a week to cover the interest payments on that nice house - thats very affordable compared to what it costs to rent. All a bit oversimplistic i know as one needs to pay for the house evertually - but i simply see a high % of people defaulting as long as the lenders aren't over aggressive in that regard.
Not bold at all. Mortgage payments are incredibly cheap right now, if you can come up with a deposit. A 5-year fix at a very low rate, is extremely attractive to younger people who are paying far more expensive rents. Do the sums.
In my view, new house prices are only likely to fall significantly if interest rates rise a lot. Monthly mortgage payments are incredibly cheap. Plenty of people (eg. public sector staff) have secure incomes.
Help to Buy could take off maybe 5-10%, at a guess.
In my lifetime of 50 years, house prices have only fallen when interest rates shot up, and made monthly mortgage repayments too expensive. Right now, the situation is as far as possible to imagine from that trigger.
Apol... it was the statement, I don't see any likelihood I was ribbing! Whenever someone says something like that Im reminded of the Mark Twain quote, "Its not what you know that will get you into trouble, Its what you know for sure just aint so" ...... but you are right about new build prices, its just difficult to transact if the wider market is weak.
re Barratt Developments (LON:BDEV) I would observe like Taylor Wimpey (LON:TW.) they have suspended land buying. The land creditor consumes the cash on the balance sheet and so they need to shift the £1.6bn work in progress to bring cash back in to support future build and land committments in 2021. Barratt Developments (LON:BDEV) have a shorter land bank which will be an advantage if land prices fall. I would suggest transaction levels are crucial to overall health of the market and changing jobs tends to be a positive driver whereas losing your job isn't.
Whilst the builders maybe restarting building .... this doesn't mean they can sell their stock.
The forward sales are about a year's revenues. As long as interest rates are this low, I don't think the housebuilders are likely to have any trouble at all selling new homes. If people can come up with the deposit, then monthly mortgage repayments are modest. Nobody knows of course, I'm only offering my personal opinion, which might be right or wrong.
On 1 May....is it time to sell in May? Time to bank cash after some extraordinary recent gains in some stocks? Maybe. The markets look like they could be falling away again as reality sinks in. The decision by Shell and others to cut or reduce dividends seems to have unnerved the media a bit. The dividend is the main reason to hold many of these stocks it seems to me; some of whom were higher in price ten years ago but the chunky dividends have made up for that. No income, all the risk of equity.
"More than 60% would be uncomfortable returning to bars and restaurants".....that's the danger even if the Government allows business to reopen.
One commentator noted that a lot of the rally in the USA is based on Amazon but they came out with mixed results.... "profit declined and the company said Thursday that it might lose money in the current period. The jump in expenses will come from spending “hundreds of millions of dollars” developing testing capabilities for all of its employees for COVID-19, starting with front-line workers; personal protective equipment for the company’s hundreds of thousands of employees; “enhanced cleaning” of its facilities; and “higher wages for hourly teams.”
I wonder if the markets are taking into account all the likely legal action against some major companies? The legal bills and costs involved could be huge. This story about a waitress on a cruise ship who caught Covid even before the ship left port:
"She is one of more than 100 Celebrity Cruises crew members who have joined a class-action suit filed against the company on 14 April, alleging it failed to take timely action to protect workers, despite having weeks of notice that coronavirus was spreading worldwide. Upwards of 100,000 crew members remain trapped on their ships". That is a lot of people when income is zero!
I take the point on Amazon, and similar comments have recently been made in Tescos and Sainsburys RNS updates. Just wonder, though, if part of their slightly downbeat take on incurring extra running costs might be news management. It would look pretty bad to be seen to be doing well during a world catastrophe.
Something to bear in mind for companies that have seen a revenue windfall from Covid-19, such as AMZN. Any half sensitive management team will not want to be seen to be making excess prrofits from the pandemic. Hence they will be tucking away provisions like mad, and saving profits for a rainy day. It is, or certainly was in the UK, very easy to find little corners to tuck away such items.
There is a slightly implausible commanality between the recent comments from both Tesco (LON:TSCO) and then J Sainsbury (LON:SBRY) that, Yes our sales have been fantastic, but it cost us an awful lot to supply those sales. Having worked at the latter, and followed the retail sector for decades, I believe it is (always) appropriate to have one's max cynical hat on.
The upside for investors of course is that such companies will be reporting better profits than would otherwise have been the case when times become tough for them. Although in the case of AMZN it is difficult to see when that might be!
Given that all grocers are having trouble trying to find a way to make home delivery profitable, I would have thought that increasing home delivery dramatically would only contribute marginally to the bottom line. I think there is too much marginal cost involved to get a positive volume effect. Problem is that the margin on groceries is slim but nonfood is better yet in this crisis the mix is against them That is before any though of the extra costs of cleaning and kitting up etc. So I would not be surprised to see very little increase profit for the extra volume
Greggs (LON:GRG)
Greggs have had to delay the previously announced re opening of some of their stores - they are scared they will be overun with rabid customers wanting stotties and steak bakes. Having spent enough time in the greggs queue i think that is a highly likely scenario - so from a staff safety point of view this backtrack makes sense. They do need a backup plan though whether that is deliveries or giant japanese type vending machines i need my fixxxxxxxx. Nowt like a greggs stottie for ones crisp sandwich is there? (i go fancy and add tomato whats your topping tipple?) Plenty of taxi drivers in my neck of the woods don't have many paying customers at present - provide a greggs option with every paid for trip and problem sorted.
Games Workshop (LON:GAW)
I don't see what the big deal with the games workshop price fluctuation is. The shareprice is down 15% from the pre covid peak - thats a loss of over £300 mill in company value. I can't imagine the company is going to lose anything like £300 mill of profit from covid - so it all seems reasonaly consistent with pre covid to me or at a minimum not inconsistent. Surely the demand from preople who want their stuff isn't going to evaporate long term due to covid is it? as shipoffrogs has higlighted their customers are probably the original self isolaters so business as normal for them - now if some evil villain managed to clone Big Daddy Nagash in real life then .......
Didn't they close their stores?
Hey folks – it’s been a wild couple of weeks and we wanted to give you a bit of an update on what’s going on here at Games Workshop, specifically on the subject of new releases. Well, as you know, Games Workshop is carefully following guidance from governments both here in the UK and throughout the world to keep all its staff safe and healthy, closing all its sites until an initial date of the 14th of April. This includes the factory and distribution centres in the UK, USA and Australia, etc.
Online is open*, I just ordered a bunch of stuff.
*which is what matters, seen as I can't go to the store anyway.
Kromek (LON:KMK) Hi Paul, would be good to get your take on Kromek if you have time. Thanks
Yes, Kromek (LON:KMK) is in the article header, which means I'm intending to look at it!
I would think that Smiths (LON:SMIN) may well have been running their slide rule over Kromek. I'm a long term holder of Smiths and I rate them highly. KMK would seem to be a good fit with their existing product line, and with the support of a company like Smiths behind them they would be in a much better position to develop and market their products.
And at a market cap of around £60m it would be virtually a petty cash buy for Smiths.
Games Workshop (LON:GAW) is a good example of todays market. It is trading at its January 2020 price, nearly all its shops are closed, impact of social distancing & recession unknown & it has agreed £25m overdraft which if used, is debt to repay.
A brilliant share for any long term owners but if todays price is fair, then the January price was hugely undervalued. Games Workshop (LON:GAW) seems a proxy for half the market at the moment.
I am near completing an analysis focusing on the top LSE stocks in each sector relative to the FTSE100, and at each point: past 12 months, YTD, from 18/2/20 (last market plunge) and 23/3/20 (last bottom).
Games Workshop (LON:GAW) is the only stock in its sector to rank in the top 5, at each of these points.
A remarkable company, one that I have totally underestimated from the very beginning, much to my regret.
Games Workshop (LON:GAW) is the only stock in its sector to rank in the top 5, at each of these points.
A remarkable company, one that I have totally underestimated from the very beginning, much to my regret.
As I noted on a different thread today, it looks like Games Workshop (LON:GAW) will lose between £10m and £15m in their final quarter, based on the recent trading update. It's a great company but highly operationally geared. The current price seems to be factoring in a very strong bounceback.
timarr
As I noted on a different thread today...,
I had a good look at your reply in the other thread, and I do not disagree with your rationale. However I am assessing GAW in relation to its peers in its sector.
In addition to having a moat, GAW has some amazing metrics. ROA = 51.5%, ROCE = 82%, normalised operating margin = 32%, operating profit/ capital employed = 75%. I can think of many CEOs who would kill for this. GAW can afford to lose some of this fat and still be an outstanding stock, in its sector or in the full market.
So the question is, will GAW still be in the top 5 in its sector, say in 6 months time? Well, in the current climate, nobody in his right mind will hazard to say one way or another. Personally, it is in my shortlist to buy "at the right time", whenever that may be!
I can think of many CEOs who would kill for this. GAW can afford to lose some of this fat and still be an outstanding stock, in its sector or in the full market.
Fair enough, but remember operational gearing works both ways. It turbocharges returns on the way up and decimates them on the way down. The point being that they may not have as much fat to lose as it appears.
At the right price, it's an outstanding company but like so much else right now there's a lot of guesswork involved in figuring out what that price should be.
timarr
"A remarkable company, one that I have totally underestimated from the very beginning, much to my regret" You're not alone Ramridge!
As the FT observed - customers of Games Workshop (LON:GAW) are very experienced at social distancing.
Careful! Paul had to apologise for expressing similar sentiments a year or so ago....
;-)
Games Workshop (LON:GAW) was one of the few sales I got right (I sold most of my holdings March 19th). Buying at £25 in Jan and selling at £68/£71 in February 20.
I will be buying back in but not at this level. I would expect it to be able to justify a price of £68/£71 in two to three years time, not this year.
Pretty impressive, buying GAW at £25 in Jan, PS! Perhaps you could tell us how you did it. Or did you mean Jan 2018?
Frontier Developments (LON:FDEV)
Looks like frontier is gaining some seriously good mementum going now, i never had the confidence to pull the trigger previously as they weren't at the stage where i was confident they were at the 1 decent licenced game per year stage - it looks like they are now at that lefte if not beyond. I would also say Games workshop and F1 seem very decent franchises (IMHO from non exepert) - this should help their push towards signing more big names if they deliver decent numbers for their partners.
Would i add now ? i don't know they are at 37 * 2019 EPS - so price looks about right - will be intereasting to see what the first estimates are eps wise for 2022 and 2023 onwards. Note eps estimates for 2020 and 2021 are lower than 2019 , this does kind of highlight the need they had to get the deals over the line that they have done. Now all they still have to do is execute - i guess the skys the limit if they have ability to take or more franchises and ramp up the output materially again from tis new higher level - one would imagine economies of scale come itno play nicely when you are churning out 5 big games a year compared to 1.
Here's David Buik's Macro Market Commentary, from yesterday's piworld webinar. Highly recommended, for a punchy, not too heavy, overview of some of the key macro economic issues the market faces. David's been through many bear markets, interesting to hear how this one compares, in his view.
For next week's piworld Thursday webinar, 7th May, 1pm, we are delighted to be joined by Keith Ashworth Lord, from the Buffettology Fund, giving his CV19 survival strategy. No doubt he'll talk about his top holding Games Workshop (LON:GAW), and their licencing deals, including with Frontier Developments (LON:FDEV) today, and many other nuggets. As always, there will be the opportunity to ask your question. Pre-register through this link.
My morning smallcap tweet:
Shield Therapeutics (LON:STX) Kromek (LON:KMK) Arden Partners (LON:ARDN) £James Quadrise Fuels International (LON:QFI) Avacta (LON:AVCT) Spaceandpeople (LON:SAL) LSL Property Services (LON:LSL) Immedia (LON:IME) Gulf Marine Services (LON:GMS)
Shield Therapeutics (STX) guides FY(Dec) rev only £0.7m due to AEGIS-H2H study fail and the agreement to repay Norgine €2.5m. Has cash to Q1 2021.
Kromek (KMK) guides FY(Apr) flat due to contract delays and lockdown. Co "good visibility over future revenues, and it has a healthy pipeline of projects." Cash at hand £10m. No guidance.
Arden Partners (ARDN) H1 trading: "materially higher corporate finance revenues, higher retainer levels but lower equity commissions. The equity trading operation suffered material losses." Guides loss but down YoY. Has cash well in excess of its regulatory requirements. Continues to sign up quality clients.
Cropper(James) (CRPR) guides FY(March) adj pretax well ahead of market expectations at over £6m. Guidance: Q1 large negative impact and loss making. Q2-3 continues to be loss-making, albeit with some recovery evident. Q4 being back into profitability.
Quadrise Fuels (QFI) cost cuts means has cash to mid Q2 2021. Equipment and MSAR fuel for the first phase pilot plant trial in Morocco now on site, awaiting end of site lockdown.
Avacta Group (AVCT) collaboration with Adeptrix to develop a high throughput COVID-19 antigen test using Adeptrix's tech. Aims for clinical validation, regulatory approval and manufacturing in June. "We believe that the BAMS test will be hugely attractive as an adjunct to PCR testing because it uses laboratory equipment that is already in hospital labs."
SpaceandPeople (SAL) gets £1m covid loan, will allow the Group to trade through the current period of venue closures.
LSL Property Services (LSL) new CEO, old one thanked.
Immedia Group (IME) CEO scarpers. He is thanked.
Gulf Marine Services (GMS) FY rev down 13%, adj loss $20m ($5.1m). Q1 adj EBITDA slightly better than plan. Needs new loan signed by end June or it's lights out. What a crock.
Nice of you to mention Avacta. Ive been watching/holding for a few years and it now gets its time to shine.
Grout
Do you think Avacta £Avct will soar like £Ncty Novacyt once the Cytiva collaboration news comes through ?
I don’t normally bother with pharma but with so many covid plays doing well (timing Being crucial) I’ve decided to take a small punt on a few
Frontier Developments (LON:FDEV) TS and collaboration with Games Workshop (LON:GAW) on a 22/23 video game a gleam of light on a fairly quiet day for RNSes