Small Cap Value Report (Fri 10 Mar 2023) - AFRN, VRS, MORE

Good morning from Paul.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Aferian (LON:AFRN)
38.5p (down 36%)
Market cap £33m
Trading Update, FY22 Results Delay & Board Update (profit warning)
Aferian plc (LSE AIM: AFRN), the B2B video streaming solutions company, today provides an update on current trading and its impact on the outlook for the financial year ending 30 November 2023.
24i business is trading in line with expectations.
Amino business has seen reduced demand -
…device sales in the first half have been materially lower than anticipated.
Recovery is not expected until later in the year, as a result it warns on profit -
… management now expect Amino's outturn for the full year ending 30 November 2023 to be substantially lower than originally anticipated.
Cost savings of $5m (annualised) have already been implemented (cost efficiencies, and R&D teams)
Outlook -
… the Board now expects Group revenue and adjusted EBITDA for the year ending 30 November 2023 to be substantially below its original expectations. Whilst device revenues continue to be negatively impacted by the current market environment, the Board has confidence in the growth drivers of the video streaming market as well as Aferian's ability to address that market. Notwithstanding the difficult trading conditions of the Amino business in the first half of the year, the Company is still expected to generate a positive material adjusted EBITDA for the full year.
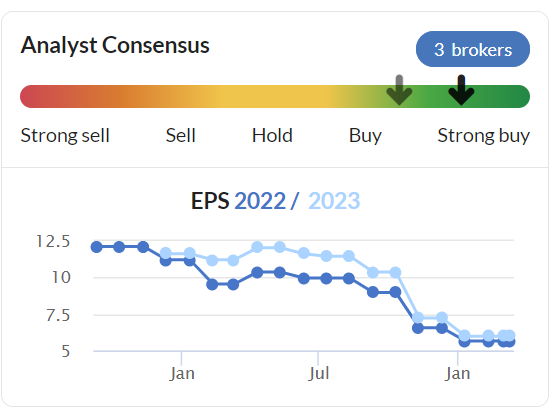
Note that broker forecasts have been falling considerably even before today’s profit warning, so not a happy situation -
Delay to FY 11/2022 results - no change to expectations provided on 8 Dec 2022, which said -
For the year ended 30 November 2022 the Group expects to report adjusted operating profit1 within the $7.8m-$8.8m guidance range.
But there’s a problem with bank covenants which is delaying the accounts sign off (which sounds going concern related) -
The Company is in compliance with its banking covenants and is in discussions with its banks to ensure future covenant compliance. This will delay the announcement of the full year audited results for the year ended 30 November 2022. A further announcement will be made as and when practicable.
Clearly that increases risk that a discounted placing might be required. It might turn out to be fine, but I always get nervous when bank covenants are mentioned.
It had net cash of $4m when last reported. On 8 Dec 2022. I would have expected it to update today on the current cash/debt position, but that information is missing.
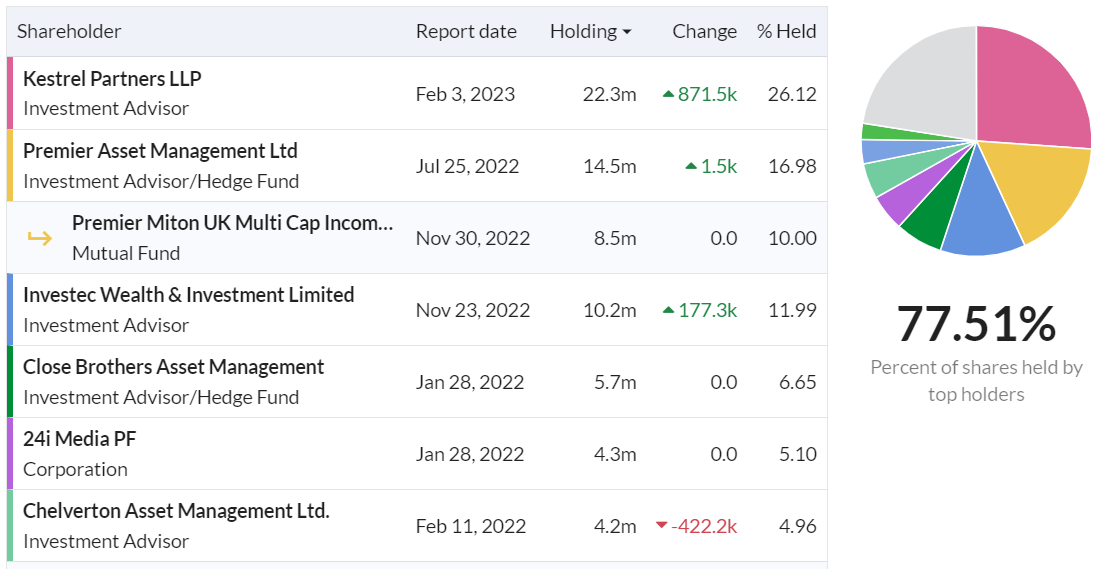
NED appointment - May Royde of Kestrel Partners is set to become a NED. Kestrel is the largest shareholder, with 26%. The shareholdings are quite concentrated, so I wonder if the top holders might decide to take it private? Or he might just be joining the Board to kick ass?
Broker updates - nothing available.
Balance Sheet - I’ve checked the last one, at 31 May 2022, and it’s almost all intangible assets. Remove those, and NTAV is slightly negative at £(1.0)m. There’s almost nothing in fixed assets, so the other main items are just working capital, which is balanced, with current assets and current liabilities both around £30m. So neither strong nor weak overall, I’d say. It probably needs the bank facility to cover day-to-day swings in working capital, depending on the timing of customer payments.
Therefore it seems to me that the bank facility should be manageable, and it doesn’t look a dangerously high geared situation.
My opinion - I’ve always found Aferian difficult to analyse, as it’s not clear to me what drives the business, who it’s competing against, and if it has any competitive advantage. Historically it makes profits every year, but variable amounts. Set-top boxes might be old hat these days perhaps?
It used to pay large divis, and it has also made acquisitions, which have clearly not been very good, and performance has been in decline for several years now.
Hence I don’t know whether the company’s prospects are good, or not.
So my view is neutral. What do readers think? If you have any insights, then please do add a comment below.
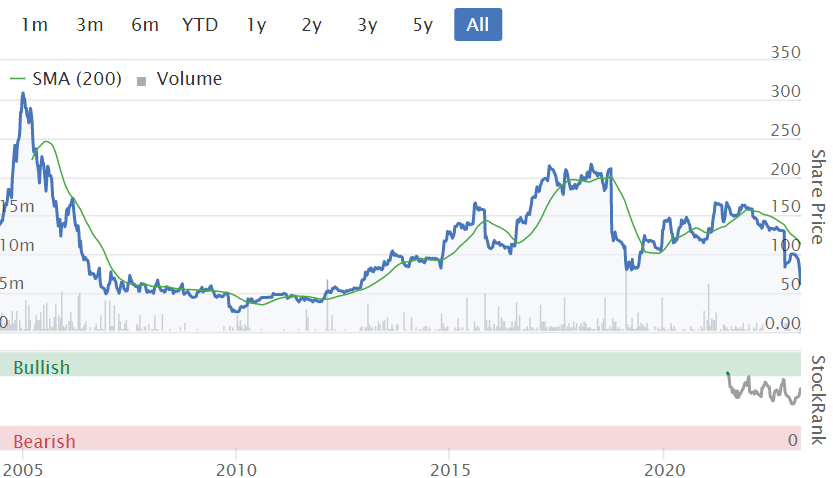
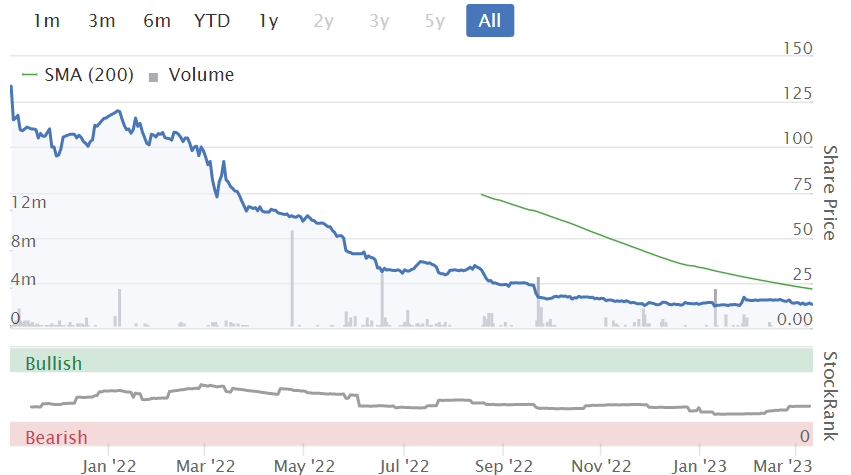
The share price has fallen all the way back down to where it was c.10 years ago -
Hostmore (LON:MORE)
13.4p (down 3%)
Market cap £17m
Trading Update & Delayed Accounts
Preamble - This is the TGI Fridays casual dining/bar chain, which has been a complete disaster since it demerged from Electra Private Equity. This was one of my heaviest losses in 2022, and it’s now a share I’m wary of, given poor trading, lacklustre/overpriced menus, and worrisome bank debt.
Restaurants/bars are one of the worst sectors at the moment as we already know, being squeezed between reduced demand (and high operational gearing), and multiple inflationary costs - especially wages, energy, and food/drink ingredients. There’s also continuing over-capacity in the sector, with many independent operators likely to go bust.
The potential upside is worth considering though, and could include - possible reductions in energy prices, food inflation reducing, consumer demand returning at some point. Hence geared upside possibly, as well as geared downside. Those that survive these brutal conditions will have less competition and hence more market share. It will be fascinating to see how things pan out. And as always, recessions are when future stars are born through innovation and supplanting the stale old formats. Is TGIs a stale old format? Lots of people seem to think so, it’s frequently mentioned here in the reader comments.
Anyway, on to today’s update from MORE -
FY 12/2022 accounts were due to be published on 16 March.
Delayed due to negotiations with bank over its borrowing facilities -
The Group is currently in discussions with its lending banks to amend its existing facilities.
This process is progressing well and the Company now expects it to conclude in the first half of April. A further announcement confirming the new date of the Preliminary Results will be made in due course whilst an update on the Group's amended banking facilities will also be provided as part of the Preliminary Results announcement.
We already knew that high bank debt was a problem at MORE, so that’s why the share price has hardly budged today.
The risk is obviously that the bank force MORE into doing a dilutive equity raise, which from a position of weakness could be ruinous to existing holders. That’s the downside risk. Or it could work out fine, if the bank co-operates and agrees revised facilities. We just don’t know how this is going to pan out, and it’s a major uncertainty which could propel the shares into a big move down, or up, depending on what happens.
Current trading - we’re reassured that there has been no further deterioration -
The above matter is unrelated to recent trading, with the Company generating VAT adjusted revenues (note 1) for the first nine weeks of the 2023 fiscal year that are similar to 2022's comparable revenues. Related EBITDA and cash flows are in line with current market expectations for the full year.
As you can see below, the broker forecasts have been plummeting, and are only now around breakeven. I thought even that looked too ambitious when I last scrutinised a broker note, hence I remain of the view that another profit warning is possible. That could then trigger a covenant breach, and an emergency discounted placing, or worse.
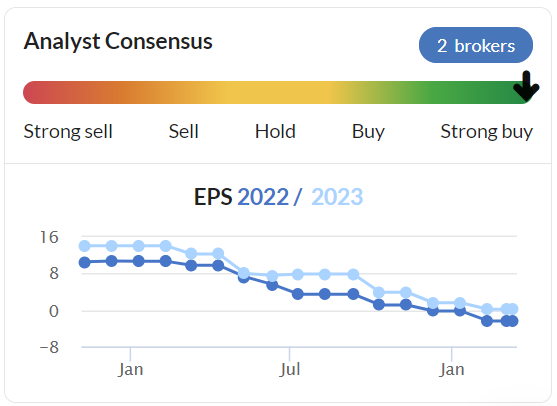
My opinion - this share is high risk, potential high reward. If the economy begins recovering, and consumers spend more freely again, then the broker forecasts could start recovering again, and if it gets back to say 10p+ EPS, then the share price could be 5-10 bagger from the current level.
Anyone holding this share should do so with their eyes open - there’s a big risk of a heavy loss, even 100% loss in the worst case scenario, if the banks pull out and investors refuse to back an equity fundraise.
However, if it survives intact, with bank support, no dilution, and trading begins to improve, then there could be a geared recovery, giving investors a multibagger potentially.
What’s my view? I think it’s too risky right now. I’d rather pay more, once it’s sorted out the finances, than run the risk of a wipeout now. Due to tthe high risk, I've got no choice than to mark it as red.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

81 comments
I am just catching up with yesterdays horrendous news about Wandisco (I do not hold) - my sympathy with holders.
In terms of the post mortem, I am thinking what lessons can be learned or what warning signs were present. I think that there is one interesting thought process that has not been discussed (apologies if it has).
Whenever there is a small cap company with extraordinary claims, I think we should all be sceptical. The smaller the company and the bigger the claims - the more sceptical one should be. I think this is only true of certain industries - especially imo healthcare / pharma and Tech. The reason for this is the amount of acquisition and staking activity that takes place in these sectors. And also the amount of ramping that goes on. If Wandisco's tech was so powerful and so important then why had no other businesses tried to either get a stake in the company or try a takeover. I am thinking that most of the big tech companies would have had a keen interest - if indeed what they were saying was true.
I have had a similar situation with Shield Therapeutics (no fraud - just fell for the story) - they told a great story! It sounded as though they had an amazing drug (which has had approval) with huge demand. However the demand side has failed to materialise (at least within a reasonable time frame) and the stocks market cap makes no sense for an approved drug with so much 'potential' (similar successful assets are often worth in the billions to pharma companies). The only lesson I could take from my bad experience was that if what they were saying was true - then big pharma would have bought them out long ago (given the valuation the market had on the business - versus the potential if what they said was credible). If the ones with all the knowledge in the industry have no interest - then my mistake was believing I knew better than the experts. Therefore my conclusion was that the drug had very little potential - as there had been no interest from big pharma - I don't know why they weren't interested - but the fact they weren't should be a red flag. I sold on this basis (basically concluding the company was a pr machine spouting BS). I took a huge loss but the stock did drop another 80%! And still no interest from the pharma world - this says a lot imo about the quality of their product or its marketability / or ability to monetise - not sure what - but the warning is there.
So to conclude, I am not sure if this would have been a red flag for people or not. But nowadays I am wary of any small cap that makes very big claims - in an industry where if what they say is true - would surely attract huge acquisition interest from other companies. If the road they have travelled is silent - the silence should be deafening!
Franchise Brands (LON:FRAN) reported full year results yesterday, here is the presentation they gave to analysts at the LSE video & podcast. Executive Chairman, Stephen Hemsley (ex Dominos Pizza) and Peter Molloy, Managing Director, B2B Division gave a very comprehensive presentation. The figures are strong with a big contribution from the 2022 acquisition of Filta, which was previously AIM listed.
They run through each of the brands and go into detail on Filta. They plan to sell the B2C division; to grow the B2B division through cross-sell and upsell; to use technology to drive efficiency and continue to look for further earnings-enhancing acquisitions. Stocko is showing an upgrade to forecasts, yesterday.
Surprised no comments on Hostmore (LON:MORE) following Paul’s review of latest news. There was much discussion on Stockopedia that this share and Unbound (LON:UBG), originally held in the private equity vehicle Electra Private Equity were significantly undervalued and when demerged and listed would be sound investments. This proved to be a fiction either due to misleading statements from the Private Equity group or inadequate analysis from potential investors including myself! Like Paul these two ‘dogs’ are my worst performing holdings - down over 90%. It is fortunate that my original investment was a small % of my overall portfolio as I fully expect both companies to go to zero!
Simple case of private equity getting rid of their dogs at the peak of a bull market .
They did very well
Investors bought into it a bought PE dross at inflated prices .
Warren Buffer and Charlie Munger are scathing on PE mentality .
Buffett wrote that “private equity” is a “name that turns facts upside-down: A purchase of a business by these firms almost invariably results in dramatic reductions in the equity portion of the acquiree’s capital structure compared to that previously existing.”
Simply a well executed coup by PE just be sure to learn from this and steer clear of PE listings that are only ever dumped on investors.
I’ve had some dealings with PE and luckily I Had the strength of mind to tell them where to go.
Spirent Communications (LON:SPT)
Three directors obviously think that this week's fall in Spirent's SP is overdone .
Not huge purchases but £40-£50K worth each, all reported this week.
I took a small position after the fall following the Calnex Solutions (LON:CLX) trading update on Tuesday.
Investegate |Spirent Comm PLC Announcements | Spirent Comm PLC: Director/PDMR Shareholding
And another one today too !
A day like today is best to pick up from your short list rather than looking at what is reported today.
Among my short list is CCC and SPT but it is really the big shots like Legal and General and some financials I am after today.
Good article in the FT'S Alphaville section titled 'Diagnosing London's Listing Miasma' by Craig Cobden
https://www.ft.com/content/6ce...
Re Trident
No point giving us the link cos they want our money before they give us a peep.
Ta ever so, anyway.
No money required for FT Alphaville
Says I need to subscribe, when I click on that link.
You can register for a Free FT account, but you can only read a certain number of articles per month
I compiled a list of UK stocks that have loan facilities with Silicon Valley Bank just FYI if anyone else knows of others would be good to add:
https://twitter.com/MGinvestor...
Hi MGinvestor
Many thanks for your Tweets, explains why Molten Ventures (LON:GROW) is down over 15% (as I type), was down over 18% earlier. I hold but luckily sliced right back to very small position just a few days ago ... phew Luckily I do not hold any others
For those not on Twitter her are the Tweets
Regards
Howard
Wise (LON:WISE) SVB Financial (NSQ:SIVB)
WISE uses SVB. https://businesscloud.co.uk/news/wise-secures-300m-debt-facility-led-by-svb-uk/
[Wise customers are not covered by the FSCS.]
SVB Financial (NSQ:SIVB) Molten Ventures (LON:GROW) Trustpilot (LON:TRST) Cazoo (NYQ:CZOO) Unbound (LON:UBG)
Molten Ventures has connections with Freetrade, Cazoo, Trustpilot, Unbound, Primary Bid, etc.
https://www.moltenventures.com/portfolio
This could be relevant if follow-on funding is needed or if stakes need to be sold.
I know I'm becoming a bore regarding Somero Enterprises (LON:SOM) and feeling that it has a short term gloomy outlook due to macro factors (as it clearly is a super company) but I noticed today that the yield has risen above the PE. See here;
This is a shorthand and not necessarily reliable indicator that the market thinks that the dividends are going to be cut.
Maybe but @FXPO are still paying dividends.
Why does @ not work for me when it works for everyone else!
Ferrexpo (LON:FXPO) - you don’t just type, an additional step is required to click on the security when it appears in the drop down (like when you are searching for a stock and type in the ticker), as per the screenshot below.
No drop down appears when using the phone. (Pixel 6 android)
hi Smudge
Sounds like there may be an issue when using a mobile (or perhaps only certain types of mobile). Have you raised it with Stocko via the green blob? If not, suggest you do and share the response on here.
If it is a system problem then it needs resolving.
I always use my laptop so I never have a problem.
Snazzy
Hi Snazzy,
Well, I thought I'd take up your suggestion. Just tried again with both the laptop and the phone and they both work as they should. Happy days.
Didn't work on Monday, the evidence is there in Monday's SCVR. Had to type it in by hand.
One little bit of good news on a rough and tumble Friday. Have a good weekend all!
Same for me when I use the phone. Ok on the laptop.
I wouldn’t panic about Somero .
It’s a great company with great products with plenty of cash and makes cash ideal takeover candidate too .
As a shareholder you own part of a great business
As a share trader you may want to jump
Agreed. The question are whether US construction will suffer a contraction and the extent this impacts revenue/earnings. Its a well-managed company with a strong record and the dividend is fairly-well covered. IMHO investing in an unproven company with no consistent record nor dividends and you take significantly more risk in the next year compared with buying Somero Enterprises (LON:SOM) at its current valuation and holding 5 years and collecting the dividend over that time. Others may disagree?
hi planetx
Somero Enterprises (LON:SOM)
Agree with your views.
By the way it would be helpful if when you post comments you could enter the stock in question using the correct link (i.e. please enter @SOM and click on the stock in the pop up box). Readers would find this helpful - much appreciated.
Snazzy
I've heard before when PE=Yield that a share is known as a "square share" and is a powerful value indicator.
I've heard before when PE=Yield that a share is known as a "square share" and is a powerful value indicator.
Like most of these types of things, as an indicator it's probably no better a sign of "value" than flipping a coin. My experience tell me lots of "square shares" also end up in the dunny. For example, RBS was a "square share" in 2007.
On Somero Enterprises (LON:SOM) specifically though, I don't know what all the fuss is about? You're either a trader or an investor. I don't fool myself I can do the former so have to rely on the latter as my investment approach. I know I can't see into the future and I know others on here don't know either, so I have to invest on that basis. If anyone else can show me a company with the same strong balance sheet, strong profitability and cheap fundamentals of Somero with sound, prudent, straightforward and conservative management, I'm all over it.
All the best, Si
Stockopedia | Somero Enterprises Share Price - SOM Share Price Quotes, Charts, RNS & Stock Market News
It has just declared the final and extra dividend and goes Ex on 6/04/23.
Happy day! Mr Pork-barrel Neill Ricketts, Versarien (LON:VRS) boss, has resigned. He is not thanked. I should think not.
You mean this Neill Ricketts, whose LinkedIn profile says: "Manufacturing Genius 2015 EMI, GoldStartup Giants (OFEX:SUG) games 2012,HP startup of the year 2013,Nice guy". Hilarious!
Aferian (LON:AFRN) Max Royde is going to be busy (too busy to give sufficient attention?) as apart from his day job as a Kestrel Partners Managing Partner he now has four NED roles: "I currently hold board positions at CentralNIC plc, IQGeo plc and Trailight Ltd" source: https://kestrelpartners.com/te...
Equals
Don’t you love the market .
Happy to buy from me at a ludicrous 77 p
But won’t sell me any stock.
Guess the market wants to take this opportunity to shake out some stock at a bargain price only to sell it back later .
Can’t buy a single share at the moment .
no but you can take a spread bet (which i did)...
I’m not sharp enough for spread betting , makes my head hurt .
haha yes you do have to get out early if goes the wrong way...
Yes l have found that on a few stocks, I go to buy recently, can only buy very small amounts such as £20 worth, or the price is above the spread.
Hill & Smith (LON:HILS) reported Full Year 2022 results earlier this week. It's benefiting in the US from the Infrastructure Bill and the reshoring. One asks when the UK is going to encourage investment!
Here's the results presentation by Exec Chair & CFO. Video & Podcast.
+14% Organic constant currency rev & profit
15% op margin
US bus 64% group profit
Spent £66m on 4 acquisitions; Proceeds of £62m from disposal
ROIC 19.2%
80% cash conversion
Total FY22 dividend 35p: +13%
Robert Walters (LON:RWA) (I hold) down this morning to 480 briefly. Two RNSs - The founder is retiring, almost immediately. Internal succession appointment. I have no way of knowing whether the successor will succeed or not. Second RNS is FY22 - all numbers look good. If one assumes that performance will remain steady then no reason to sell.... except that if I study the chart I am pretty sure that the only thing that has held up the price since Christmas has been the buybacks. The chart suggests the market might price this share at 450p... or less if it wasn't for the buybacks.
'In 2022, the Group purchased 2m shares at an average price of £6.25 per share through the Group's Employee Benefit Trust. A further 2m shares were purchased at an average price of £4.93 for £10.0m and cancelled. The Board is authorised to re-purchase up to 10% of the Group's issued share capital and will be seeking approval for the renewal of this authority at the Group's Annual General Meeting on 27 April 2023.'
I would welcome other views.
Robert Walters (LON:RWA) is one of the very few stocks in the green today - as I type. Low valuation, great dividend, plus buybacks, long history of profitability, only 15% UK focus and strong Asia exposure. Sorry to see Robert retire but the successor has been running much of the operating business - highly comparable to the succession of Timo Lehne at SThree (LON:STEM) . What’s not to like?
Share might go lower short term but long term I’m convinced it’s a winner. Not selling today and if it falls substantially I’ll add.
Yes, it has bounced back. But I saw a red bar and 480 mid price on my HL account when I was typing - and that is below recent support. I completely agree about the fundamentals but usually when I like something and the market doesn't it's the market that wins.
Robert Walters (LON:RWA)
Well the market was wavering at 08:05 and more positive at 09:00. Do institutions buy at market open or after the SP has settled down? The market appears to be on owners’ side.
But I’d ignore all the above and look forward to the time when markets recover.
Robert Walters (LON:RWA) The chart suggests the market might price this share at 450p
Are you feeling happier now after the 2% drop that spooked you turned into a 10% rise on a huge down day for the general market? I really think you just need to be patient and not worry about how low it could go. Instead, think about how high it should end up once current macro passes. If it drops, buy more.
Yes, and I didn't sell.
Yes, and I didn't sell.
Good start to the weekend then
Today's horror is Aferian (LON:AFRN). Results were due a month ago and it lost a third of its SP from then until yesterday on no news as people interpreted the delay as bad news. Today the SP halved at open on news that customer destocking on the Amino side has continued for longer than expected and will have a material impact on the current year. 26% holder Kestrel gets a seat on the board. Let's hope they can improve things as this was one of my largest holdings.
Come on Paul cheer us up what a miserable week its been and today no better.
Looking through the 199 posts of yesterday I found many moans about the sort of fraud at WANdisco (LON:WAND) generally just getting a slap on the wrist.
Occasionally, however, justice is done. In 2016 I bought shares in Redcentric (LON:RCN) and then a fraud was discovered where the amount of cash in the a/cs had been falsified (something I always thought would have been obvious to auditors checking against bank statements). The SP halved when this was announced but the company was not suspended as it remained a going concern.
Justice? - in this case yes- the Finance Director pleaded guilty and was sentenced to a total of 3 years’ imprisonment, and was ordered to pay £120,346.70 following confiscation proceedings.
The CFO was tried and found guilty at Southwark Crown Court and sentenced to seven and a half years. In sentencing, HHJ Beddoe remarked:'Your offending was persistent, significant and substantial, abusing an exceptional degree of trust. Your actions have damaged Redcentric plc and also public confidence in the City. 'A CFO of a public company – of any company – is expected to demonstrate the highest standards of integrity. It is the bedrock upon which a company, its directors and its shareholders are entirely dependent. When people such as you are found to have failed seriously they must expect severe punishment.'
In the same 14 week trial the jury unanimously acquitted the CEO of all charges . He had faced four counts of misleading the market pursuant to s.89 Financial Services Act 2012, in the first ever prosecution brought under this statutory provision.
The FRC fined auditors PwC £6.5m (cf Grant Thornton £2.3m for Patisserie Valerie) and two of its partners £200k each.
The company and the FCA also agreed a restitution scheme, of which I was a beneficiary, for shareholders who had bought between the publication of the results that turned out to be false and the announcement that they were.
As for WANdisco (LON:WAND) I would have less hope - the company is registered in Jersey. I don't know who is to blame but, for example, Chris Pemberton VP of Marketing lives in California, as does Tony Velcich Senior Director of Product Marketing whereas Frank Moser CRO / SVP Global Sales lives in Zurich, leaving Nimish Shah Strategic Account Director in the UK. Where would any litigation begin? While looking at that I found loads more fancy titles such as Vice President of Global Field Operations (Guildford), Senior Vice President of Customer Success & Engineering (San Francisco), VP Solutions Engineering (The Netherlands) and Vice President of Global Field Operations (Bromley). Just how many people in WANdisco (LON:WAND) had a Senior Vice President or Vice President title?
wow - good research. and this isn't a company doing $bns of turnover where such roles could exist, this is a tiny company doing £9m of revenue! It was well on the short-list but with the pumped up sales talks, the "100% margin" (that i commented on here is just fanciful at best) and nasdaq listing it was just too risky / didn't have any spare capital to lose on it. People only do this digging after the event.
Great share, Sharw! It's always encouraging to hear about justice being served, especially in cases of fraud that can have such a negative impact on both companies and public trust in the financial sector. It's impressive that the CFO of Redcentric received such a substantial sentence for his actions, and it's heartening to know that auditors and other parties involved in the fraud were also held accountable. It's unfortunate that the situation with WANdisco (LON:WAND) seems more complicated, but hopefully, steps will be taken to ensure that those responsible are brought to justice. Thanks for sharing your insights!
Great post and really thought provoking. I suppose as investors we need to question why a company would have so many VP roles. Leading on to:
1) Is it intentional? When this eventually gets to legal proceedings, will they try to use the argument of diffusion of responsibility; the bystander effect. "I didn't know it was my job to ensure X,Y and Z". Much like with Sam Bankman-Fried who has tried to scapegoat all of FTX's wrongdoings on Alameda Research company.
2) Is it a genuine case of a top heavy management who haven't been given a clear and defined left and right of arc of their responsibilities? Which has ultimately led to somebody being able to carry out fraud unnoticed.
As painful as it is, the important thing is to try and find the red flags of this and apply them to our investing going forward.
Wasn't the Redcentric CFO found guilty of making false and misleading statements to the market and false accounting, rather than fraud?
I see that at Wandisco, not only was the CEO also the Chair, but the NEDs were all city boys, with no techie backgrounds, which hardly seemed fitting for a business like Wandisco.
Funny job titles? It's currently seeking a "Scrum Master".
I know it sounds like rugby terminology, but I can assure you that "Scrum Master" is a real IT role.
https://www.simplilearn.com/sc....
Yes small companies with highly / over paid execs with fancy titles = massive red flag.
Just announced they have appointed FRP Advisory to conduct investigation....well, thats a start. Wonder if a shining knight will appear soon to the rescue if indeed the cloud service they offer is so appealing.
I also suffered as an shareholder of RCN. Great to see some justice was done. Thanks for sharing!
Be good to hear a similar story about the Patisserie Valerie fraud but I won’t hold my breath!
People do get punished. I remember one of our partners, Julian Pilkington at Spicer and Oppenheimin in the early 1990s, lost his practising certificate over our incompetent audit of Barlow Clowes. Sad end to a career really.
Sadly I lost out (lost my entire holding) on Redcentric (LON:RCN) because I bought prior to publishing of the mis-stated accounts.
I held after mis-stated accounts were issued though I would not have done had properly-representative accounts been issued instead.
I can't be the only one. The restitution scheme didn't cover this.
Arcontech (LON:ARC)
Looking at recent interim's alarm bells went off looking at their trade receivables which were stated at 1,468,165 in Dec 31st 2022 up from £209,800 Dec 31st 2021 (they have June 30th year end) , despite revenue decreasing by 6.6% to £1,357,041. So trade receivables went from 14% of revenue in H1 2021 to 108% of revenue in H1 2022.
After contacting their Nomad, finnCap, they came back with the following, which may allay concerns somewhat - ‘ all debtors are current. There has been a change in the company’s annual billing cycles for a few larger customers as they renegotiated contracts. They secured longer term agreements for these customers but the effect was that invoices were raised later than in past years while negotiations concluded.
In previous years the invoices for these customers would have been raised and paid prior to 31 December. As the invoices were raised later this year, they were debtors at reporting date and have subsequently been paid in full. They also had one client who increased payment terms to all of their suppliers including Arcontech. As a result they raised their invoice in December whereas in the past they would have raised it in January. This is to ensure there was no difference to the timing of receipt of cash for Arcontech. None of this will affect the annual revenue run-rate, it is simply a case of invoicing and payment timings.’
Apologies for posting here relating to pensions and SSAS providers, I’m sure this must affect others and there so much knowledge and expertise in this group…
We have recently been advised by ii (interactive investor) that they will no longer handle SSAS accounts (small self administered schemes) so we’re going to have to move again. (I knew ABRDN would spoil ii when they bought them!) We only moved to ii when Barclays stopped supporting SSAS’s. Funds were locked up for 2 or 3 months during the process!
To my point, does anyone have experience of other providers such as AJ Bell for this specific purpose. Not looking for recommendations obviously -just opinions on SSAS compatible trading platforms that are not too onerous on trustees and enable simple, self selection of investments and independent determination! Opinions gratefully received!
I use Jarvis and have for years. It work well but is basic. I called in the other day for some help and got good support. The type of account you need is called "Share Deal Active".
AJB have a good reputation for service and we've never had an issue with them after dealing for 25 years!
Jim
works...
Our SSAS is with Stocktrade (part of Embark/Lloyds Group). The platform works with very little downtime. Telephone support is very good. The downside is that trading is (relatively) expensive - 0.3% ( up to £75) per trade so trading a few times a month can become costly.
My sympathies neils. I too have been caught by ii's latest changes. I have a Curtis Banks SIPP (it was formerly a Hotbed Sipp provided by Alliance Trust that was very sympathetic to holding unquoted investments), but that changed when Curtis Banks took it over, they became hostile and bureaucratic and just didn't want unquoted stuff). This time I am simply transferring the quoted portfolio directly to ii (as opposed to it being a "PTA"). So far the transfer procees is going ok, but it's not completed yet. I've been quite happy with ii since they took over from Selftrade (bar one stock specific issue), but all this churn amongst providers is a right pain!
ii who for me took over from TDW both excellent and simple, all you need fitting on one page and they went right back through various others to DHL some 20 years ago. ii now Aberdeen = all change...
Since the disemvowelled company took over ii, there have been many changes, many upgrades, none of which have made things better, indeed the opposite with the recent website upgrade. Now they want to get rid of us troublesome people with pension trading accounts completely. It will be a nuisance but, in a way, I will be glad to part company. Our pension trustees have proposed AJ Bell and my initial contact with them has been positive. It is exclusively a GBX account i.e. you can't hold foreign currencies in the account. This was one of the best points of ii and meant you didn't have forex charges after the initial non-UK share purchase. The main problem is the stock transfer takes 6-12 weeks, so you can't trade your stocks during this period. If you are a buy-and-holder, this will be fine but if you like to trade, it's really an issue and I am currently wondering whether to cash out completely and buy back in again within AJ Bell, dealing charges and stamp duty notwithstanding.
Seatbelts on today. Could be a rough ride
Yep, bear market still here, contrary to some opinions. Actually thinking this year could be worse than last year, judging by the amount of profit warnings lately. That's my fear side talking, hope I'm wrong!
The news overnight on the Silicon Valley Bank looks grim. When companies lose trust in their bank it usually only ends in one way. I believe they are the 18th largest bank in the US with a lot of interests in the UK. This could be another Lehman Bros situation and we know what impact that had on the markets.
For me I am rounding up whatever Cash I have around in case there's a major correction in the next few weeks. I am selling nothing I have today though which I may live to regret.
Hi Brookeda,
It's tough out there isn't it?!
I'm keeping my largest conviction holdings, still around 60% in cash currently. Really need to short in these times.
Yes I don't short as I don't know enough about it and I don't do things I don't understand. I just try and ride it out and invest additional when I feel there's upside opportunity.
Can be mentally tough through seeing your valuations coming down
I'm adding to shorts today (and buying VIX). Most of my positions are in non-financial smaller cap stocks and often not ones with large debts which in theory should be less impacted but in reality we know small caps can get sold off very quickly as well a la October last year and maybe in mid-2020 as well then the market realises how cheap they have become and then they bounce strongly.
I really don’t get why problems at SVB Financial (NSQ:SIVB) should have such a negative knock on effect on the UK market today or for that matter on the shares of the major US banks, SVB Financial (NSQ:SIVB) operated in the high risk venture capital space funding technology and healthcare start ups. In addition it shouldn’t be any surprise to the market that bond portfolios have suffered losses given the rapid increases in interest rates over the last year. John Authers comments on the subject worth a read this morning but the UK market reaction seems a huge overreaction.
I am no expert but there are a number of things. SVB Financial (NSQ:SIVB) aren't alone in having used Bonds as a way of keeping "safe" reserves in their system. Apparently US banks have $630bn of paper losses in bonds at the moment which are off their balance sheets. So the major concern is a domino effect which then dries up capital in the market.
Clearly the US govmt will need to step in and step in quickly to avoid a meltdown here in confidence.
https://www.bbc.co.uk/news
I am sanguine about SVB. I don't think there is contagion, based on three things:
If anyone has a recommendation for an ETF that has the big financial institutions, either USA or UK/EU, let me know. I'm going to be researching them to buy in if the markets keep dragging all banking shares down, as I don't see this as a systematic risk yet.
And it has played out like that this morning... SVB not seen as too big to fail, and allowed to collapse. Small enough for the usual FDIC process to take place for failed banks.
Now the question comes whether this sparks larger contagion... mass withdrawals in cash by retail customers. Corporates taking money out of smaller, regional (more vulnerable) banks.
I would be very surprised if the banking system couldn't survive this. All the tighter regulations post-2008 was gamed on scenarios like this, to prevent this type of contagion happening.
This is worth a watch and I think it supports the bear case.
https://www.bridgewater.com/re...
If the employment data from the US comes out significantly worse than expected later today we could see a real bloodbath this afternoon. 0.5% rate rise now seen as more likely than 0.25% according to https://www.cmegroup.com/marke...