Small Cap Value Report (Fri 10 Nov 2017) - CGS, VLX, IQE

Good morning!
This is the placeholder article, published the night before, to enable early comments and suggestions from readers.
Best,
Graham
Paul has interviewed the CEO and CFO of Tracsis (LON:TRCS) on his personal website. following the publication of their 2017 results. It's available at this link.
Castings (LON:CGS)
- Share price: 435p (-5.4%)
- No. of shares: 43.6 million
- Market cap: £190 million
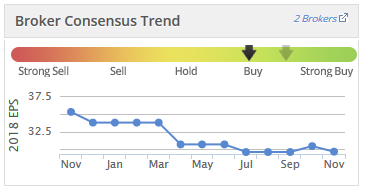
Checking my notes on this industrial group, I've generally made positive noises on it over the past year, while the market cap has been c. £200 million. Sadly, the outlook has been gradually deteriorating - see how the consensus 2018 EPS forecast has reduced from 35p to less than 30p:
The group has two parts - casting and machining. The machining plant came to the conclusion of a large contract about a year ago, resulting in a lot of excess capacity which needed to be filled again.
This part of the business has failed to recover yet, as today it reports a loss of £1 million (compared to a profit of £0.8 million in the previous year).
If I've interpreted this correctly, it would have achieved breakeven were it not for some one-off costs which have been included in the result:
Following a detailed review of the operation, additional short-term costs have been identified and included in the result for the period. The main areas impacted are stock obsolescence and the recoverability of tooling costs which, when taken with the director severance cost, have reduced group profits by £1.0 million.
The company is straightforward enough not to use any adjusted or underlying measures in these results (something I like about it). That said, perhaps we should bear in mind that stock obsolescence, etc. are somewhat unusual and that without those costs, it would have been approximately breakeven in this side of the business? The lack of an MD remains a serious concern, however.
The foundry part of the business performed fine, revenues up 8% and profit up 10.5% to £6.9 million.
Outlook
I'm a little disappointed with this, as they could have explicitly said that the outlook is now lower than prior expectations. Instead, it is implied:
Demand from our commercial vehicle customer base remains steady and therefore the full year result for the foundry operations is anticipated to be in line with market expectations..
The previously reported replacement work for CNC Speedwell has been reassessed in response to the issues experienced during the period. As a result of this review, the decision has been taken to exit certain non-core projects. Whilst this will most likely delay the revenue growth of the group, the directors believe there are sufficient opportunities available within the core customer base to replace this in the medium term.
So the bottom line is that sufficiently attractive replacement work arising from the end of the major contract at the machining plant has failed to materialise.
This is the world of B2B contracts and industrial companies - business comes in large chunky blocks and it can be really hard to replace good clients. It's why the likes of Terry Smith prefer investing in companies whose sales come in the form of small, easily predictable transactions.
My opinion
I still have a high overall opinion of Castings. it has barely diluted its shareholders in over 20 years. It's also paid out a gradually rising dividend for over twenty years, and even paid out a special dividend last year.
Where it fails to excite me is with its quality scores:

I'd describe these numbers as "acceptable", but would hope for more in the stocks which I personally invested in, especially when they are in their mature phase.
It remains a low-risk play from the financial point of view. The balance sheet is still bullet-proof showing entirely tangible net assets of £124 million, of which property, plant and equipment is £75 million. The perfect example of a big, heavy industrial company.
Volex (LON:VLX)
- Share price: 76.5p (+5.5%)
- No. of shares: 90.3 million
- Market cap: £69 million
This is a power cord supplier which is apparently on the turnaround track after a couple of years in the doldrums.
The share price has doubled from its low earlier this year, resulting in a mammoth momentum score and an excellent StockRank:

Momentum is proven to "work" (i.e. there are trends which persist in share price movements) so I can fully understand why people incorporate it into their investment strategies.
But even the worst companies can have superb momentum sometimes, so let's see what's going on here:
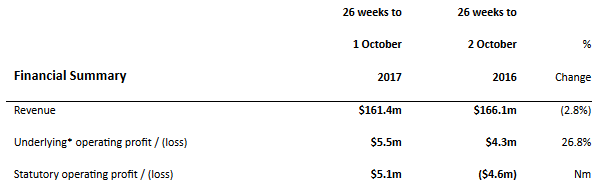
The operating margin of 3.4% (underlying) is very weak, but this is the best result achieved by the company in some time:
A statutory operating profit of $5.1 million is the best result in the past 5 years, reflecting an improved underlying operating performance and an absence of one-off restructuring costs.
Group revenue is down by $4.6 million on the prior period primarily as a result of a further $11.0 million decline in our largest Power customer's revenues.
Not entirely dissimilar to Castings, then - vulnerable to the one-off hit from large/profitable customers withdrawing. Is it true that the largest customer is still Apple?
I've just opened up the 2017 Annual Report. At the time, the Chairman said the company believed that sales to its largest customer "have now stabilised". Interestingly, he said "over investment in production capacity for our largest customer had resulted in excess capacity [at the Shenzhen facility] for a number of years."
The report also said that Volex "for the past five years has focussed on six long-standing key customers, failing to generate any new significant markets or accounts". Fairly damning stuff! The top ten customers accounted for 64% of revenue, and the largest one was 18%.
In today's report, the Chairman uses exactly the same phrase - "has now stabilised" - in relation to sales to the largest customer from Volex's Power Division, which fell another 25%. I'm not sure how reliable that claim is, since sales to that customer were supposed to have stabilised at year-end?
Digging further into the report, I see that gross margin in the Power Division is really weak, at just 15.5%, resulting in an underlying operating margin of only 3%.
There is a strategy to turn things around, but it sounds far from easy:
With Volex's traditional PC and peripherals markets set to continue their decline, competition here will only intensify. Therefore it is vitally important, if the Power Cords division is to turnaround its recent performance, for it to seek out new end markets that value Volex's expert knowledge in the manufacture of high power distribution cables and its reputation for quality and safety.
It might be safer to assume that the Power Division is not going to improve from here.
The Cable Assemblies Division is a bit more interesting, with gross margin of 21% and underlying operating margin of 7.4%. Sales are on the increase here, too. And it gives the impression of being a lot more diversified. With operating income of $5.2 million here in H1, I'd attribute most of Volex's value to this division.
Move to AIM: The company is getting off the main market and moving to AIM, citing the increased flexibility with which it will be able to make acquisitions, etc. It also mentions its current market cap. Makes sense to move to AIM, I think.
Outlook is in line with expectations.
My opinion
The Cable Assemblies Division looks interesting with some slightly more interesting, value-add activities which might prove to be a more sustainable source of profitability than the Power Division.
Given the very high StockRank, I'm inclined to think the outlook here is better than average, with a few caveats. Customer concentration risk is still a huge issue - that's the sort of risk which I manually and deliberately avoided when I was managing a Greenblatt Magic Formula-oriented portfolio.
The balance sheet isn't the prettiest I've ever seen. Receivables and inventory both appear to be on the high side, although the company has some stated reasons for this.
Conclusion: I wouldn't hold it long-term. But it looks like it will continue to re-rate in the short-term.
IQE (LON:IQE)
- Share price: 162.25p (+16%)
- No. of shares: 687 million (before placing)
- Market cap: £1,115 million (excluding value of placing shares)
Proposed Placing of up to 67 million new shares
Placing of new shares raising £95 million
Readers have prodded me into commenting on this widely-followed manufacturer of wafers for the semiconductor industry.
I first commented on it here nearly a year ago, when I said the rating it was on seemed a bit cheap. The share price was c. 38p!
With the share price now elevated, it has elected to raise money - intuitively, that makes perfect sense to me. Companies should sell shares when the shares are expensive, and buy them back when they are cheap. That's good for the company itself and it's good for long-term holders.
Of course, many existing holders do not think that the shares are currently expensive, as they expect it to grow into this valuation over time.
Certainly, it has a fantastic track record of growing sales and profits. Today's placing is justified in a number of different ways - not just to increase capacity to meet growing demand for existing products, but also to develop new products and technology and to de-gear the balance sheet. Debt and defcon had grown to £42 million by June 2017, versus H1 adj. operating profit of £10.6 million.
That level of debt doesn't seem onerous to me, but again, if I was running a business and felt that the share price was sufficiently generous, that is the point at which I would sell some shares to reduce borrowings and incur minimal dilution. The new shares will represent just less than 10% of the current share count.
You might wonder why the company is in debt at all, given its track record of profitability for the past ten years. The answer is that it has made very significant investments:
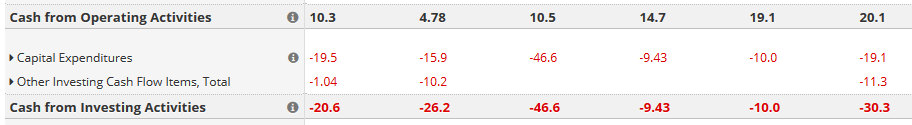
If you can read the numbers in the above graphic, you'll see that capex and other investments have been significant and have generally surpassed the cash inflow from operating activities (the above data are for 2011-2016).
It's another capital-intensive business, though it does apparently have a unique offering in terms of the mix of compounds used in its wafers. This has created for it #1 and #2 positions in the growing markets in which it operates.
At some point, the investing activities need to generate free cash flow in order to justify them (i.e. at some point, cash from operations needs to surpass cash from investing activities). Free cash flow generation is the only way that dividends can ever be paid, and IQE has never paid a dividend.
For now, investing activities will probably remain significant. The rationale for the placing includes the following:
IQE is seeking funding to enable it to scale the business to capture multiple high growth mass market opportunities.
This placing will allow IQE to expand its capital expenditure programme in its new foundry, with the purchase of up to 40-60 new MOCVD machines over the next three to five years.
(GN Note: MOCVD machines are used in "Epitaxy", the process which IQE uses to deposit thin films of material on its wafers.)
According to the January 2016 talk at Mello Beckenham, capacity utilisation at IQE was about 55-60%.
Wafer revenue in H1 2017 was 17% higher than H1 2016, so that should still have left a comfortable amount of spare capacity, but with the company talking about "multiple high growth mass market opportunities", it's understandable that they'd want to increase capacity. At some point, hopefully, the increased scale and prior investments made will lead to FCF generation.
According to shorttracker.co.uk, at least 6.5% of IQE shares have been sold short (not including short positions of less than 0.5% of the company, as they aren't published by the FCA).
A decent-sized short campaign is a red flag, for obvious reasons. I'm guessing that the funds involved are thinking about 1) the high valuation against conventional metrics, 2), the lack of free cash flow, and 3) the reliance on a small number of customers.
Loss of a share with a significant customer and customer concentration risk are listed as key business risks in IQE's 2016 Annual Report. Checking the footnotes, I see that two customers together accounted for 45% of IQE's sales (24% and 21%, respectively). Of course, there is no sign of overall demand slacking in the short-term.

I'm not going to draw any hard-and-fast conclusion here. If I was absolutely forced to take sides, I'd probably go short, for the above named three reasons.
The only difficulty with this position is that fighting against momentum is usually a mistake, and IQE currently enjoys a very high Momentum Rank of 83.
That's all I've got time for today. My favourite company mentioned today was certainly Castings (LON:CGS), but they were all interesting in their own way.
Have a great weekend and see you next week!
Graham
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
70 comments
"If I had a pound for every time some great new technology never took off, I'd now be sitting on my super yacht in Monaco..."
Well, if you'd bought IQE's shares a year ago at 30 pence and sold them at today's closing price of 170 pence, you might not be sitting on a yacht in Monaco, but you would have done much better than the vast majority of investors over the past year!
Stockopedia covered First Derivatives First Derivatives (LON:FDP) in 2010 - It has been in the news and is an interesting company but there are some strange anomalies such as poor ROCE and a very low operating margin for a software company. If anyone feels like covering it others might be interested.
I'm more than a little confused, I can see and understand Graham's reasons for thinking a short position on IQE might be the best bet. It does seem to be a very volatile stock. Paul seems to be dumping it from his BMUS fund but still holds some. I would'nt mind hearing his comments on the stock. My opinion is that it's probably one for the brave. If all the glue holds up it could be a flyer.
Regards, Mick C
paul wrote one of the first replies on this comment section, saying a little about iqe
I was pleased with the Castings(LON:CGS) Interim results.
It appears that demand for trucks is still holding up.
The expected new business on Machining has not been achieved and that side of business is being
streamlined. New experienced management are taking action.
Balance Sheet still strong £19mill cash.
Dividend maintained.
Look forward to sound Company getting over bump in road.
Hi Graham,
You wrote about IQE: "You might wonder why the company is in debt at all, given its track record of profitability for the past ten years. The answer is that it has made very significant investments. If you can read the numbers in the above graphic, you'll see that capex and other investments have been significant and have generally surpassed the cash inflow from operating activities (the above data are for 2011-2016). It's another capital-intensive business, though it does apparently have a unique offering in terms of the mix of compounds used in its wafers. This has created for it #1 and #2 positions in the growing markets in which it operates."
However, I think you might have overlooked or been unaware of some of the following points:
(1) The main reason IQE has borrowed money over the last few years was to buy wafer manufacturing facilities for compound semiconductors and intellectual property from its competitors. This long-term strategy has enabled IQE to achieve its present dominant positions in the outsourced manufacture of wafers for compound semiconductos.
(2) The Welsh and UK governments have recently invested about £300 million to set up a centre of excellence for the research and development of compound semiconductors in south Wales, which IQE is part of and will benefit from at very little cost to itself.
(3) IQE's business has high operational gearing, so if there is close to full utilisation of its equipment above its previous approximately 55% utilisation, that should feed through to profits and cash generation.
(4) The profit margins on wafers for VCSELs is significantly higher than for IQE's other products.
(5) Once IQE's existing facilities are close to full utilisation, IQE can expand into an electronics facility at Newport that had originally been purpose-built for LG but which had never been used, which the Welsh government is providing to IQE rent free for 3 years. In order to expand its production capanbilities, all IQE has to do is to buy some new machines (which was the reason for yesterday's placing).
To top slice or not to top slice IQE that is the Question? At leas a top slice locks some profits in.
I like Castings (LON:CGS) but today I sold for a small loss after 2 years. Probably a small profit after dividends.
I would certainly buy again at a lower price or better newsflow, but newsflow has been slightly negative since I bought. They are reliant on too few customers and I worry they may suffer more than most by leaving the eu.
What I'm annoyed about though is that there was a clue a while ago. When a MD leaves suddenly and the CEO takes over it should have rung an alarm bell. I could have sold at 460p.
On another topic entirely, I got my Annual report from Bioventix (LON:BVXP) today. You just have to love a successful company who's report is just a black and white print out on A4 stapled together. A+ for not wasting money and no ego trip.
Hello Doug, I'm not invested with Castings (LON:CGS) but it's been on my watchlist, last year I did not find the right price to buy in but this year I noticed the EPS broker forecasts were down, which put me off. It's something I always check now before buying, I want them to be going up. I agree it's a good company but I also have doubts over Brexit. Actually I was expecting the shares to down around 10%.
I sold my Bioventix (LON:BVXP), which I really regret now, looking to buy back if the prices drops a bit.
I sold my Bioventix at 2825p think if they go down below 2200 worth a look again.Had such a great run it was a good time to cash in.
Hi Herbie47
I would be careful of the “...buy back if the prices drops a bit.” Strategy.
David Gardner the founder of Motley Fool tells the story of how he said to himself when Yahoo was at $29 he would buy in when the price dropped to $25; trouble is it never dropped to $25 and split adjusted reached $1,000.
See http://investorfieldguide.com/gardner/ for the full podcast.
Interesting he does not have a sell strategy because he doesn’t sell!!
Best wishes
Michael
Hi Michael,
My reply got lost, so briefly, yes you can miss out but I have picked quite a few shares on dips that have done very well. Bioventix (LON:BVXP) was one actually when it fell to 960p. Tristel (LON:TSTL) was another. I'm sure David Gardner bought something else like Amazon with his money. I do get their Canadian emails but may stop because they are quite annoying. I do have a few of their tips.
Thanks for your write up on IQE (LON:IQE), Graham.
Forgive me, as I asked this question a few months ago, but I'm really struggling to value the company.
As I understand it, they had £133m turnover in 2016 and made £20m pretax so £16m post tax. This is a net margin of 12% of turnover.
When ARM was acquired they got 24.4 times revenue/56.8 times post tax profits but enjoyed a much healthier net margin of 44% of turnover.
If one applied these same multiples to IQE for the fun of it one would get a valuation of between £908m to £3.2bn on 2016 numbers. Now clearly this is a growth stock which means it is harder to value based on historic numbers but what multiples would you apply to reflect their much lower margins than ARM?
(I've been long but have been sitting on the sides since, alarmed by their low margins and the short positions which increased again two days ago, now standing at 6.65% + those with positions below the declarable %).
I'd like to thank everyone who has commented on IQE (LON:IQE). On balance I decided to top-slice my holding mainly due to the inherent capital-intensiveness of the business, risk of misjudging future demand and the relatively high valuation.
Thanks for a great report Graham. For someone like me who doesn’t know much about IQE that’s really helpful and points out some factors to think about. Best regards, Andrew
Hi Graham - re. IQE (LON:IQE) A very balanced review and opinion, which cuts through the hyperventilating comments I have read today, here and on other BBs.
FWIW at the current price of just above160p, I think the shares are priced almost to perfection. So I sold all my shares @160.5 . I am still looking at these shares to trade in and out. Yes, the longer term investment opportunity is still positive, but on a risk/ reward basis, I am happy to take the £profit today, and think about the longer term entry point over the next weeks/ months.
IQE (LON:IQE) - I sold half of mine. They just look a bit over valued at the moment compared to some of their peers. Yes high price but not much profit. I will keep a small stake and see where it goes from here. Other semiconductor cos are making large profits and paying out good dividends, even though they have doubled this year they still look reasonable value.
I'm inclined to agree and have done the same. Like you I think there will be an opportunity to buy back in below today's peaks. A bird in the hand etc.
Also grateful to Graham for the balanced review. For me, I am still in having bought a few more early on today and probably looking to add a final slug in December as the strength of the "story" I think will really start to open up. Whilst there is room for some volatility in the short term, I don't really think there is too much "risk" at the moment.
Anyway one particular thing I wanted to thank Graham for was the mention that they were running at 55-60% utilisation in Jan-16. I'm pretty sure that there are figures out there for how many 'tools' (machines) they have had (I'll have to hunt that out), so it must be possible to get at least some idea of what scale these 40-60 new ones would given them.
For what it's worth Ramridge - I agree and took similar action on Friday morning.
I note that RBG revolution bars is now struggling in the 160's level.....after shareholders turned down £2 bid recently. Not a holder having sold out when the bid went above 205. 150p soon with 130p possible I think. One to watch but I would not buy yet.
I’m not concerned that IQE (LON:IQE) are going to be too dependent on Apple. Just reading their interim results presentation shows that they have plenty of other irons in the fire.
Equally in their share placing statement they said “This placing should also enable IQE to accelerate the development of new products and technology; whilst protecting and enhancing its current positioning in a fast-moving marketplace”
Previous management statements have shown they are well aware of the need not to be overly dependent on a single sector (so by inference they would feel the same way about being too dependent on a single customer).
Furthermore, Himax have stated they are ramping up for 3D in Android phones. That doesn’t necessarily involve IQE at this stage but it demonstrates that 3D is not something that only Apple will incorporate in their phones. It is unlikely in my view the none of the Android OEMs will use chips for this that use IQE wafers.
While we may all have an opinion about the attractiveness of face recognition versus other unlocking technologies, it doesn’t matter what we personally think as the marketplace has already shown that there are a very substantial number of customers that want an iPhone X. Furthermore face recognition is only one application of the technology, others include things like being able to change the background of a picture. I may think that is trivial, but the popularity of playing with photo filters suggests that there are plenty of people who like this stuff.
I have no problem with capital investment like this placing when it is clearly supporting a high level of profitable growth.
I am convinced that IQE have many end customers, not just Apple - (even if this was the case, we would never know). It seems to me that this is a company right at the cutting edge of semiconductor development, and as such I remain a very happy holder, even Buyer at these levels
It seems to me that this is a company right at the cutting edge of semiconductor development,
It's really, genuinely, not at the leading edge of "semiconductor development". Look at the market cap and then compare it to the market cap of TSMC, for instance. If it was in any way leading edge do you not think it would not be a much larger company? This is a niche compound semiconductor play (not the same thing at all as silicon based semiconductors). I suggest you do more research about IQE and its products to make sure you understand what it is that you are investing in.
Please don't take this the wrong way, from the things I have read in the last 6 months on BBs it is clear that you are not alone - there are clearly a few people who have done their research but there are many more who are just riding on their coat tails.
All the best, Si
I think there is an issue here of what exactly "semiconductor" means. Most people including me use the word to describe semiconductor chips i.e. the finished article that consists of zillions of transistors, diodes etc that is used in so many applications. More accurately however it is the term used for the material that forms the wafer or substrate upon which all the electronics is layered in microscopic detail. IQE is at the cutting edge of semiconductor development if you apply the rigorous definition of the word. Semiconductor development has moved on from the use of silicon to much more advanced "compound" materials" where IQE is undoubtedly a world leader, particularly in the breadth of product it can supply.
I think there is an issue here of what exactly "semiconductor" means. Most people including me use the word to describe semiconductor chips
I agree that terms are much mis-used but the word semiconductor relates to the material science behind the technology. As someone that works in the industry, I always use it in this context and when asked what I do, I tell people I design chips (not semiconductors!) Boy, does that kill a conversation quick! The only reason to use the term "semiconductor chip" is to avoid confusion with a "potato chip" :)
IQE is at the cutting edge of semiconductor development if you apply the rigorous definition of the word. Semiconductor development has moved on from the use of silicon to much more advanced "compound" materials" where IQE is undoubtedly a world leader, particularly in the breadth of product it can supply.
We'll have to beg to differ on this. The compound semiconductor materials IQE (LON:IQE) produce have been around for decades. They have always been niche and never gained wide acceptance or shipped in anything like the production volumes that silicon based semiconductors have.
The excitement now is that there are finally volume applications for compound semiconductors (in particular VCSELs) that are going to change this, and the omens look pretty good, although not as good as the most hyped-up commentators would have you believe. I really want to see them succeed in this but at the same time I don't want to be invested in it :)
All the best, Si
Si,
I’m a bit confused.
If IQE is not at the cutting edge of epitaxy for compound semi-conductors, who is?
My understanding is that the product life cycle for silicon wafer based semi conductors is coming gradually to an end for some applications as the need for higher speeds and lower power consumption etc. for high end applications increases - e.g. 5G. And that compound semis will become prevalent for that. Is that not the case?
https://5g.co.uk/guides/what-are-compound-semiconductors/
Si,
I’m a bit confused.
If IQE is not at the cutting edge of epitaxy for compound semi-conductors, who is?
To be fair, where did I say they were not at the cutting edge of epitaxy for compound semiconductors? I think that's why you're confused. My response was to an assertion that did not differentiate between compound semiconductors and silicon based semiconductors. There is a world of difference between the two. Compound semiconductors are not at the cutting edge of "semiconductor development" so how can IQE be at the cutting edge?
My understanding is that the product life cycle for silicon wafer based semi conductors is coming gradually to an end for some applications as the need for higher speeds and lower power consumption etc. for high end applications increases - e.g. 5G. And that compound semis will become prevalent for that. Is that not the case?
People have been making noises like this for as long as I can remember and yet Moore's Law has relentlessly churned out silicon feature scaling that has got smaller and smaller. If you are invested based on this thesis then you will be waiting a long time and it doesn't seem to be a great reason to hold IQE (LON:IQE). There are problems with compound semiconductors that do not make them a great replacement for silicon. If they did, do you not think Intel, Samsung and TSMC would be throwing vast amounts of money at developing compound semiconductor processes rather than the current small-scale R&D they are performing? And if they did, where would that leave a tiny company in South Wales?
All the best, Si
"There are problems with compound semiconductors that do not make them a great replacement for silicon."
Compound semiconductors do not need to replace silicon for there to be growing demand for the former. My understanding is that there are many applications for which silicon semiconductors do not perform as well as compound semiconductors, particularly those applications that involve converting electric signals to electromagnetic radiation or vice versa. For example, are there many VCSELs (vertical cavity surface emitting lasers) or LED light bulbs that do not use compound semiconductors? Demand for both VCSELs and LEDs is growing rapidly at present.
My understanding is that there are many applications for which silicon semiconductors do not perform as well as compound semiconductors, particularly those applications that involve converting electric signals to electromagnetic radiation or vice versa.
Yes, this is correct, but these applications are few and far between, and assume that silicon processes will not improve further. Certainly there will be huge cost advantages to using silicon rather than more expensive compound semiconductors, and so chip makers and equipment vendors will move heaven and earth to use the existing silicon based technology.
For example, are there many VCSELs (vertical cavity surface emitting lasers) or LED light bulbs that do not use compound semiconductors? Demand for both VCSELs and LEDs is growing rapidly at present.
No and they never have - LED's are obviously very old technology and have always been manufactured using III/V compound substrates. VCSELs are clearly a growth area but the point I'm making is that that is about it. If the demand from Apple went away in the next 12 months what would happen? I have a large holding in Apple but I wouldn't want to hold shares in one of their small technology suppliers any more than I'd want to hold shares in a company supplying product to the UK supermarkets.
All the best, Si
Hi Simoan, you wrote: "LED's are obviously very old technology and have always been manufactured using III/V compound substrates. VCSELs are clearly a growth area but the point I'm making is that that is about it. If the demand from Apple went away in the next 12 months what would happen?"
I'm afraid that you're very mistaken about this.
LEDs are not very old technology, in the sense that it is only in the last couple of years that the light-conversion efficiency of LED bulbs has improved tothe extent that they are now being widely used for lighting in homes and offices, with an enormous increase in demand.
The demand from Apple for VCSELs won't go away in the next 12 months. It is likely to remain high for years, because all their future models of iPhones and iPads will probably use VCSELs for face recognition and Augmented Reality applications. Demand from other mobile manufacturers such as Samsung for VCSELs is also likely to increase for years. VCSELs will also be used in self-driving cars. VCSELs and other types of lasers that are manufactured from compound semiconductors are used in optical fibres, for which demand is increasing exponentially at present due to their use in the huge data centres that are required to provide services for 'cloud' computing.
Some other applications for compound semiconductors that are growing rapidly at present are for wireless base stations for the next generation of mobile phones, and for efficient power conversion from high to low voltages.
Obviously the market for silicon-based semiconductors is enormous and will continue to be so for the forseeable future. However, the demand for compound semiconductors is growing much more rapidly and from a much lower base.
“Compound semiconductors are not at the cutting edge of "semiconductor development" so how can IQE be at the cutting edge?”
Well there is plenty of commentary out there that describe the specific areas where compound semis have superior physical properties to silicon semis. If you want play semantics about the phrase “cutting edge” so be it.
“There are problems with compound semiconductors that do not make them a great replacement for silicon. If they did, do you not think Intel, Samsung and TSMC would be throwing vast amounts of money at developing compound semiconductor processes rather than the current small-scale R&D they are performing? And if they did, where would that leave a tiny company in South Wales?”
No one said they are replacing all silicon semi conductors. They are a niche for specific applications where their properties justify the cost. As new opportunities to use those properties arise and the cost comes down, larger diameter wafers for example, the use of these technologies will grow.
As for the last part of that paragraph, I think you are aware large companies often leave niche applications under served, which provides opportunities for smaller more nimble competitors, who then grow into much larger operations over time.
Well there is plenty of commentary out there that describe the specific areas where compound semis have superior physical properties to silicon semis. If you want play semantics about the phrase “cutting edge” so be it.
But it's not semantics. the reality is that cutting edge silicon technology is miles ahead of compound semiconductors, just the lithography technology itself required to create 3-dimensional features at 10nm wide is quite amazing, and Intel earlier this year announced Fab42 in Arizona for 7nm silicon in a few years time. Compound semiconductor technology is miles behind this.
No one said they are replacing all silicon semi conductors. They are a niche for specific applications where their properties justify the cost. As new opportunities to use those properties arise and the cost comes down, larger diameter wafers for example, the use of these technologies will grow.
But this has been the case for over 20 years and I don't see this changing in my investment lifetime, let alone working lifetime. Yes, it's niche, it's always been niche and it will always be niche.
As for the last part of that paragraph, I think you are aware large companies often leave niche applications under served, which provides opportunities for smaller more nimble competitors, who then grow into much larger operations over time.
Absolutely. And my own company profits from this. But it is a bloody difficult world to live in, particularly if you are a supplier to very large organisations. As someone else mentioned, Apple will be very unhappy with having a single source of VCSEL technology, they will push back hard on price all the way down the procurement chain, and you can bet your life they are actively encouraging competition to create an alternative supply chain.
All the best, Si
It is great to have your input on this and am glad that you have clarified that IQE are (probably?) at the leading edge of development re the epitaxy process for compound semis. I am however interested in developing understanding of your comment that compound semis are not at the cutting edge of semiconductor development. If that is the case what and who is currently at the leading edge of semi development in your opinion? Clearly one of the major risks for IQE is that their IP will be superseded by new technologies so any light you can throw on such threats would be appreciated.
Clearly one of the major risks for IQE is that their IP will be superseded by new technologies so any light you can throw on such threats would be appreciated.
I wouldn't worry about being the IP being superseded if they have strong patent protection. And it will need to be strong because patent litigation in the semiconductor industry is rife!
I think Graham has brilliantly highlighted the main problem with IQE as an investment in the main article above i.e. cash flow will be constantly eaten up by Capex. IQE operate in an industry which requires constant expenditure to stay in front and so they can't just turn Capex on and off like a tap to release free cash flow. They also seem to have very low historic operating margins for a world leader in technology, particular operating in niche markets - niche normally means high margins to me!
All the best, Si
Si
I think you’ll see their margins improve dramatically as the capacity of their production facilities becomes fully utilised and then expanded.
While it is tempting to use their past performance as a guide to the future I think it is a mistake as there is now a much bigger market for their products appearing.
But I’m interested in your view that VCSELs are just about it. Industry commentators are saying that compound semis will be needed for 5G communications. Are they wrong?
But I’m interested in your view that VCSELs are just about it. Industry commentators are saying that compound semis will be needed for 5G communications. Are they wrong?
I don't know, but experience would tell me with 99.9% accuracy that they are wrong. I never listen to "market commentators" because they are normally talking their own book and have a vested interest in building up and "selling" certain technologies, so you have to be very careful. Many of them are academics who have no practical background in semiconductors or business.The bottom line is that in 35 years working in the chip industry (just as with most other industries) I have found 99.9% of predictions by market experts turn out to be completely and utterly wrong.
If I had a pound for every time some great new technology never took off, I'd now be sitting on my super yacht in Monaco...
All the best, Si
Yes. I agree in terms of investors.
I was referring to industry commentators in the sense of those who write articles for industry journals and so on rather that investment community commentators. Well, I suppose we won’t have to wait very long to find out.
I was referring to industry commentators in the sense of those who write articles for industry journals and so on rather that investment community commentators. Well, I suppose we won’t have to wait very long to find out.
I was talking about industry commentators too. it always amazes me how many people predict things with such certainty amidst so many "known unknowns". I guess the big hope for IQE is the 5G base stations will need to use compound semi devices for power amps as I believe the radios may need to move to using millimeter wave techniques normally only used by the military. However, even then we are not talking massive volume, certainly not iPhone volume, but every little helps!
All the best, Si
I haven't read all of the IQE posts on all bulletin boards but from what I have read it looks like the excitement is all about VCSEL. IQE claim to be the market leader in VCSELs but I would guess that Lumentum and Finisar would disagree. Finisar (or at least a part of Honeywell at the time that Finisar acquired) invented VCSEL back in 93 and have shipped over 150 million VCSELs and have a turnover of about 1.4Bn USD. Their VCSEL website is here: http://myvcsel.com/
Maybe it is a co-incidence that Volex (previously a big supplier to Apple) reported today but worth looking at Paul's comments on them and questioning if the same comments will be made about IQE in the future. Can't blame them for raising a load of money now with all of the hype about and a p/e of 40 for the year ending Dec 2019.
IQE make wafers for VCSELs, which it supplies to Lumentum who manufacture VCSELs from IQE's wafers, and Lumentum then supplies those VCSELs to Apple.
very interesting news today by oxford pharma OXP. Assets to be transferred to a new private company leaving a new cash shell with a stonking 19 million in cash. If you like buying shares with a huge discount to cash in the bank plus a bonus holding in a pharma company this is worth a good look as a special situation.
So why are they doing it? Does it make sense?
The current OXP business has not worked well in the public area. Pharma is always under pressure to deliver when really it is a long term business. So that's going private with a couple of million quid and shareholders will get shares with the new private company.
Its the aim cash shell "cash resources of approximately £19.3 million as at 31 October 2017 into other opportunities" that is of real interest. The interest on that pile will cover all costs and maybe a reverse into a serious business...who knows? I don't know of any other aim shells with 19.3 million in the bank!
Hi guys, I will cover IQE (LON:IQE) next.
HA,
I am absolutely livid with Aeorema Communications (LON:AEO) : Releasing final results at 11:15am. No excuse for this sort of behavior whatsoever, so dumped holding.
I also sold my entire position in IQE (LON:IQE) yesterday for 140p, so if you think you're having a bad day today, remember, there's always someone worse off :)
Have a great weekend everyone.
IG
Herbie47
I agree with the face recognition issues about discretion. I think the fingerprint recognition has gone, but I think (half memory only) that the numeric password has been retained as a second line option. Please shoot me down if this wrong!
I think it the potential of augmented reality that appears to also excite, and apparently a number of suppliers will be going this route also, so demand for VSEL wafer semiconductors will have to rise to meet this new demand.
There will be at some point an explosion of augmented reality apps. Basically the Google glasses concept repackaged for a mobile phone. Data/images will be overlaid over potential real life situations. Not sure what plusses will arise from this apart from people staring more at their phones than they already do, but for it is to some extent a fashion item, and so demand will increase at the supplier level for the underlying technology, until it moves onto something else, I guess.
I would agree that the 3D augmented reality is what could really prove a winner. I saw a show with a mechanic using a prototype application where he pointed the phone to the engine bay and an augmented reality of how to remove a part was overlayed the actual engine. Wow I thought I' d use that. Such applications to real life are endless.
Some of the questions raised by previous posters about IQE are answered by this post on the iii board:
http://www.iii.co.uk/investment/detail/?display=discussion&code=cotn:IQE.L&it=le&action=detail&id=12225945
Hi Paul - re Tracsis (LON:TRCS) I listened to yesterday's audiocast and it simply reinforced my view of a solid well-grounded management. I particularly liked John McArthur's reply to lack of M&A activity over the past FY. He has set the criteria bar high and will not move it if no suitable target can be found.
Although the past FY's performance was pedestrian, I detect enough signs of potential double digit (top line and bottom line) growth over the current FY.
Took a long position this morning.
leoleo73 - re IQE (LON:IQE) Sorry, but I can't agree with your thoughts (or most of them)
I'm sure you're right about the share price falling because the word was out in the past few days about the placing. I'm sure no-one really believes that those bookrunners took on the task without checking in advance that there was institutional demand to carry off the placing. The time it took to complete surely proves that.
However - I don't believe that Apple are their only customer. IQE make the wafers that chip makers need to then supply Apple but I don't believe that other smartfone, computer and tablet makers are going to be sitting on their hands - they're all going to want to include 3D in their products going forward and for that they or their chip suppliers are going to need IQE. I don't believe that Apple are their only customer.
As for the need to raise money - my take is that IQE need to increase capacity in a big way to meet the demand that is already there and which they know is increasing dramatically.
As for a "single product" manufacturer. IQE have a lot of irons in the fire. Their products are going to be increasingly needed for such things as 5G, Infra Red, the internet of things etc. etc.
I'm biased, this is a big big holding for me (and today I'm a very happy camper) but always interested to hear opposing views.
Similar thoughts to others did occur to me (but to be clear moaning about rigged markets, just genuinely curious how these things pay out.
So at 4:38pm yesterday IQE (LON:IQE) announced the placing and by 7am this morning they had found buyers for £95m worth of shares.
Do corporate financiers really work that quickly?
(I suspect not but maybe those with experience can tell me otherwise).
Presuming the answer to be no, then the buyers must have been tapped up in the days previous to this. In such circumstances I presume the potential buyers have to sign up to non-disclosure and non-trading before they can be told anything. (Although it would niave to assume that no whispers EVER leak out).
But even if that is perfectly leak proof, does it not potentially cause a "false market" for a few days anyway?
If you are an insti accumulating these shares and then sign up to a non-trading clause, then demand is taken away from the market and the price falls. No?
Going back only a few days, the share price was trading at around 150p and whilst "consolidation" was quite predicatable, but it seemed to me that going down to 140 (and even to the low 130s intraday) was a bigger pull back than might have been expected.
Could that be the effect of the placing to come?
It doesn't "bother" me too much as I can't think of a better way for things to bne handled and it is a fact of life that a fund raising is going to cost you in one way or another, but whilst we think of this as a placing at no discount to the market price of 140p , isn't it possible that it was actaully at a small discount to the "true" market price of around 150p?
Still a good deal IMHO, but just interested if any of the industry folk have any observations on my musings?
Hi Gromley.
It may have changed since my day (most things have) but in essence, when a Placement is being contemplated the broker will circle with prospective investors several days before an offer to test appetite for new shares with regards to volume and pricing. As part of this process, the broker takes the investor "over the compliance wall" at which point they're deemed to have received inside information and are precluded from buying or selling the shares in the company until released (usually the point at which the information becomes public). The broker is usually required to record who is over the wall which in theory would allow the authorities to look into any suspicious activity if they were of a mind to.
In practice the process is potentially leaky either directly or more usually indirectly (friends of friends, lunchtime gossip etc.) - the days of self regulating my word is my bond are long since past (if they ever existed!).
Gus.
Yes, of course I know IQE (LON:IQE) have a wide variety of products / customers, indeed that is why I bought the shares. But the recent share price history suggests that the (indirect) Apple contract is now responsible for 125p of the share price and everything else 40p. And there is a risk that 40p part may be being neglected right now.
Whether there are or will be other end-customers for the same 3D technology is very much in doubt. Not only is mobile consumer 3D not obviously required (face-recognition can manage without it, the only other use is currently animated emojis), there are other ways of doing 3D (e.g. two cameras, or even one camera moved around).
I will feel a lot more comfortable if/when Samsung is known to be an end-customer or other areas have grown more.
I should say that despite my concerns a prospective PE of 36 is hardly demanding and I continue to hold.
My apologies then leoleo73 - I misread your post as saying that Apple were the only customer IQE (LON:IQE) have.
Thanks Laughton and Leoleo73. Very interesting and adds to the sum of my knowledge about IQE (LON:IQE).
IQE (LON:IQE): Including an open offer would have sent a more welcoming message to small shareholders, but given that we could buy at the placing price yesterday we can hardly complain on this occasion. Although given the shenanigans that are allowed to go on elsewhere in AIM, there is always going to be the lingering doubt that the fall in price over the past few days was due to word of the placing leaking out.
I have a moderate-large position, but this is partly due to fear of missing out rather than much conviction. Much of the current valuation due to a single contract for a single product, which would be bad enough, but that customer being Apple takes it to a different level. Apple hate being reliant on a single supplier (which is why they put off using proper (Samsung OLED) screens for so long) and exercise enormous negotiating power. Previous suppliers have arguably got distracted serving Apple and certainly suffered when their contracts are terminated or curtailed. (UK ones include Volex and Imagination).
I'm also always concerned when a company needs to raise money (and dilute shareholders) to grow. Of course the purpose of a stock market is supposed to be to allow equity to be raised, and this money is going to create a variety of jobs in one of the few areas of the UK with people looking for work. But as an investor my ideal share is not capital intensive but is self funding and just keeps growing and/or churning out cash with no effort or further investment on my part. (I've always thought there was a conflict there)
In this case it could be argued that Apple are using IQE's high rating to raise money to buy cheap manufacturing plant for themselves but avoiding any ownership risk. As Apple are the only customer and so powerful they effectively control the plant, can screw down their margins (alternative is to leave plant idle) and cancel at any time. Of course, the theory is that Apple need IQE, but Apple won't let such a situation to persist for long (would IQE really be able to fight Apple in a legal battle over IP? Look what happened to Imagination). And there might be contacts in place, but I doubt they are for long given the uncertainties of the market.
The conclusion I'm coming to is that: IQE urgently need more customers (e.g. Samsung), may be worth more as part of a bigger / more powerful group, and the current situation is very fragile.
As always, I post these assertions in the hope that someone will contradict them and I will learn something!
IQE (LON:IQE) has many customers but I don't think Apple are one of them. They supply their wafers to LITE who use them in their products to supply Apple. I think they are doing the right thing to raise money cheaply to expand when demand is growing as long as they don't over extend themselves. Yes I have concerns over this large contract may end or maybe this face recognition may have problems, I know some users don't like it so much, before you could just start it by touching the phone with your finger, so a lot discrete, situations I can think of are in the street and in a meeting etc., now you have to lift it and hold at a certain distance from your face, in some lighting situations users have had problems.
I've seen reports that the next iPhone will have both Touch ID and Face ID. They certainly haven't given up on trying to get Touch ID working through the screen. They launched the X before it was really ready for reasons of the anniversary and trying to show they could live up to the Jobs legacy. Ironically, I think that's not something that he would have done, but there we are, their shares are doing well.
The thing stopping me buying one is the all glass construction that breaks if dropped from three feet. So it may look lovely but you'll have to hide it in a case.
Bloomberg report that Apple are working to launch an iPad with Face ID next year.
https://www.bloomberg.com/news/articles/2017-11-08/apple-is-said-to-plan-2018-ipad-redesign-with-facial-recognition
It's good to know that touchID maybe an option. I'm not an iphone user myself, too expensive for me. I think faceID is a real issue, these are expensive items, I read about people being attacked for them, some have even been killed, here is one case: http://www.independent.co.uk/news/uk/home-news/abdul-samad-stabbed-death-iphone-moped-west-london-little-venice-charity-worker-a8006321.html. So having to hold it up in the street is maybe not the best way, especially at night, also it will flag up it's iphoneX even more expensive. I have an ipad, I would rather not have faceID on it, number or touchID I would prefer.
Volex (LON:VLX) results look OK. Also its balance sheet is pretty good these days. Not a very exciting company though - making electrical flexes, at low margins. The big, lucrative Apple contract is long gone, so it's just a commodity supplier these days.
P.
I second IQE
My morning smallcap tweet:
Marechale Capital (MAC) Last night: "Due to delays in relation to a number of the transactions it is involved in, it expects to report an operating loss for this period of between £250,000 - 300,000. " Also £100k write-down.Oxford Pharmascience (LON:OXP), React (LON:REAT), Marechale Capital (LON:MAC)
Oxford Pharmascience (OXP) to demerge operating business, become cash shell for acquisitions. Holders to get shares in demerged private business.
React Group (REAT) FY trading "very disappointing, with revenue of around £2.65m and a pre-tax loss of around £400,000." H2 has started to show signs of improvement. How refreshing to read the honest appraisal of failure which come with new mgmt. It never lasts.
Castings CGS (LON:CGS) released their 6 month report today and showed significant reduction in profits blamed with not passing on material increases at the same time as they came in and some issues on one of there profit lines. A steady well run company that looks long term but I guess the stock will take an hit today
Hi Brookeda, I've covered Castings (LON:CGS). Cheers
Yup it's the 10th! Anyway, can I request some thoughts on IQE (LON:IQE) 's bang-on-the-current-price fundraising & positive kind-of trading statement? I see Paul has been reducing in his BMUS fund recently... will he regret this?
Hi runthejoules,
Yes I do regret reducing my holding in IQE (LON:IQE) ! (but it was over-sized, so was making me fret, hence why I trimmed it back to a normal size). I can always buy back & enlarge the position again.
The big fundraising announced last night, and completed this morning (to clear debt & fund capex) looks a big vote of confidence by Instis. Also being at zero discount, it shows there was plenty of demand, and it doesn't disadvantage private investors who don't have access to book builds usually.
Overall, pretty bullish I would say.
Regards, Paul.
wow, what's the logic for the jump in iqe price today ? perhaps institutions couldn't get enough shares in the fundraising and have chased the price up this morning ? I am seeing up 24p as I type.
Does seem like perhaps instos knew their was a fund raising coming and that explains the weakness up until now. It's hard, how do you set the price/size without knowing the market appetite ? How do you judge this without speaking to institutions ? I guess they'd be crazy to buy in advance if they knew a issue was around the corner.
K
Isn't it the 10th tomorrow?
You were right, I originally said 9th! Thanks.
G