Small Cap Value Report (Fri 11 Nov 2022) - WRKS, VINO, NXR

Good morning from Paul!
There are some amazing rallies going on at the moment, in many sectors. The trigger seems to be reduced expectations for inflation, and hence interest rates. As discussed in my recent interview with UP Global Sourcing Holdings (LON:UPGS) factory gate prices in China are easing, as orders from the West have dried up. Also there's been a plunge in shipping container costs, which is a positive tailwind for margins. Plus the dollar has partially weakened, which again is good for us, as it reduces inflationary pressures over time.
All of that looks encouraging. However, my worry is that we're possibly only at the start of an earnings recession. So if we buy shares now, we could get clobbered with profit warnings. Powerful rallies are normal in bear markets, so this could be another bear market rally. Personally I like to buy the dips, not buy the rallies, so am trying to avoid becoming over-excited by surging share prices right now. Will they hold, and continue rising, or fall back again? Maybe it would be a good idea to trim some positions, to give some firepower for if/when markets roll over again?
Agenda
Works co uk (LON:WRKS) - H1 trading update looks in line. Although it's not clear what actual profit will be (it only mentions EBITDA). Broker consensus is for only slightly above breakeven this year. Shares look very cheap, but it's not a very good business, so it should be cheap.
Today I'll be mostly focused on doing 2 CEO interviews, being -
Virgin Wines UK (LON:VINO) at 11:00 - this is now published (audio) here, and on my podcast channel. I'll type up the transcript (just for Stockopedia subscribers) over the weekend. I thought this went well, and it looks an interesting company, on a reasonable valuation. As always, please DYOR, it's not a recommendation, just my personal opinion.
Norcros (LON:NXR) at 16:00 - this audio interview is also now published here. Transcript to follow over the weekend, hopefully.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Works co uk (LON:WRKS)
30.5p (down 11% at 10:11)
Market cap £19m
H1 Update (26 weeks to 30 Oct 2022)
“Increasingly challenging consumer environment”
H1 LFL sales up 0.6% (split +3.5% LFL in stores, and -16.9% online [but still +50% vs pre-covid])
May 2022 saw an impact from cyber attack.
Recovered from June onwards, and summer was good.
Last 6 weeks trading has softened (against strong LY comps)
Online sales - rate of decline has slowed.
Net cash position of £11.0m, but £5.0m cash payments went out the next day, so it’s really £6.0m net cash - good of them to disclose this.
Outlook for FY 4/2023 unchanged.
For reference, the Company compiled estimate of the market's expectation for the FY23 Adjusted EBITDA result is approximately £9.0m.
Interim results due on 20 Jan 2023.
My opinion - I wish they wouldn’t quote EBITDA, as it’s not real profit. Also it’s not clear whether the £9.0m H1 EBITDA is pre, or post IFRS 16, which makes a big difference. Last full year, pre-IFRS 16 adj EBITDA was £16.6m, which translated into £10.2m PBT. That was heavily boosted by business rates relief, since ended.
I can’t find any broker notes, but the StockReport shows consensus of a wafer thin profit after tax of £1.4m, or 6.4p EPS. So I have to assume the company must be trading in line with that. PERs don't make a lot of sense when companies are this close to breakeven.
The market cap is very cheap at only £19m, but it doesn’t look a very good business, and might struggle to make profits at all in future, as consumers retrench. There again, the products are value-orientated, so maybe demand could hold up? Who knows? I don’t see anything much to attract me to this share, other than cheapness. It’s likely to be squeezed by higher costs, and potentially reduced demand. That could eradicate profitability altogether.
It could be a beneficiary from much cheaper sea freight costs, and easing input cost inflation maybe?
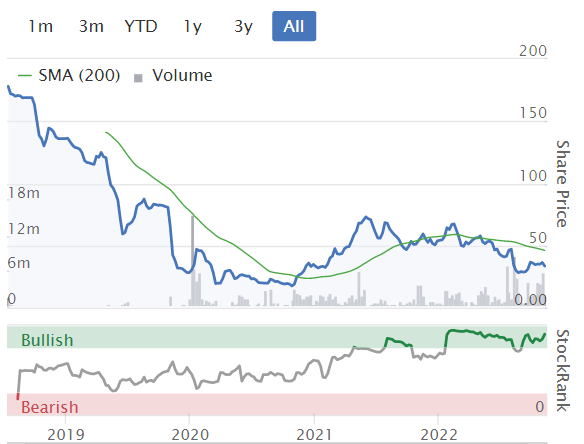
Note that performance was poor, before the pandemic.
The StockRank seems surprisingly high.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

46 comments
so. You think money is crypto. The big problem is , people are greedy. They take risk and money is backed by governments. Crypto is backed by people. People are selfish. Government is for the majority. Individuals are selfish and that's why this goes to zero. No one, steps in when there is a bank run. The government always steps in to save the currency of the currency. I have tulips for sale,
absolutely beautiful how people are so convinced that value exists just because other people buy it. And then no one buys any more because it doesn't create goods or services. The emporer has no clothes.
how about buying companies that produce goods and services are actually used and useful. Trying to game this system means you think you have an advantage and or you compromise your ethics. You don't have to. Just buy good companies and hold them like you own them, because you do. Listen to your managers, they work for you. This platform is dominated by traders, sadly many say they are owners of the business they trade
the market is not where I make money. The companies I own make me money. I go to the market when I want to buy or sell, which is seldom.
Wise words Paul
"Personally I like to buy the dips, not buy the rallies, so am trying to avoid becoming over-excited by surging share prices right now."
The NASDAQ100 up 7%+ yesterday. Crazy! The type of price change you expect from Bitcoin. Total over reaction by markets. Best wait.
If the window of opportunity to buy great companies at low valuations is closing, this makes my job harder. It makes my current net worth better, great if I want to sell, but shit if I want to build my investments. Obviously, I want to buy. I have never wanted to sell. I want to own more, not less. I want to own more of the Companies I think I understand. Please stop buying. Please sell. Of course if you are not buying the market, I will have a proper conversation when we exchange our holdings for fair price. I have 3 companies that are fairly priced and 8 that I believe are cheap. I have no intention of selling the companies that are fairly priced because they, in my opinion, are great businesses that have a very long future. The others are priced in my favor. I would happily encourage traders to sell them down.
just to clarify, the businesses that I consider cheap are, in my opinion, have a very long term future.
Hi Graham Neary,
Further to your report on the 8th of Nov about Argo Blockchain plc I just wanted to add that the 2026 bonds (8.75%) are trading at around $1.5 (having been issued at $25).
The company has clearly gone bust and its shares trading still at 8p is a joke. The shares value should be a big zero.
Thanks
Good spot, thanks yiannos1 :-)
Thanks for the update yiannos. G
Just a reminder that we are hosting Mello London next week in Chiswick and all are welcome. Ed Croft and Graham Neary are doing presentations and there will be 35 companies also presenting and lots of very good speakers. https://melloevents.com/mello-...
Interesting thing about these sudden rallies is that there's always a few beaten up shares (usually under the radar small caps) they get left behind, even though their peers have all shot up. Secure Trust Bank (LON:STB) still not really budged even though other banks have, and the same with Augmentum Fintech (LON:AUGM) in the venture capital space. Both quality companies and good trading opportunites in my view. I'm sure there are many others out there, but these are the 2 on my watchlist.
Been a very long time since Paul and co ran a slide rule over Secure Trust Bank (LON:STB) - would be great if they could. It’s really taken a battering
Another few that have passed this rally by are Renold (LON:RNO) ME International (LON:MEGP) Facilities by ADF (LON:ADF) and Argentex (LON:AGFX), and also Foresight group (LON:FSG) not sure why that's bolted to the floor, also GB (LON:GBG) as a slightly risky outsider but was up strongly yesterday.
Yes good spot on Foresight group (LON:FSG) an alternative asset manager who are very much in the sweet spot (sustainable assets and infrastructure with good recurring revenues) - rarely gets mentioned here or anywhere else, but looks really interesting and sold off quite a bit, despite consistently strong updates and AUM growth.
Hee hee...I'm not trolling or harassing you...
Foresight group (LON:FSG) interesting and much superior to say Molten Ventures (LON:GROW) that's been mentioned in here (wouldn't touch Molten at deep discount...who knows where writedowns and dying funded businesses go for them!). However, I believe Mercia Asset Management (LON:MERC) is a much higher quality play but more complex to unpick
https://www.stockopedia.com/co...
Why do you say that about Molton ...???? Or are you just stirring ?
Not stirring...of course I can be wrong. Molten are in 'club' deals for fashionable tech that's either looking to Nasdaq or has listed. The cos they invest in are much larger valuations and realistically their exits are to IPO (Foresight and to greater degree Mercia can exit to industrial buyers). Valuations of what Mercia hold much more modest than Molten too (can't say for Foresight). Molten don't generate significant revenues from 3rd party funds business relative to the scale of direct investments they have...so to support their companies through further rounds (and so avoid dilution etc) they will probably need to tap markets for a raise as they have in the past (unless they get nice cash exits...tough environment...and as exit is to IPO they can be locked into holding).
Its a risk return argument. I'm not saying that Molten will be terrible just that it has more downside risks and IMO it weighs to the downside
Thank you, I appreciate your well considered response / points.
In the larger company space, defence companies aren't doing well - e,g, BAE Systems (LON:BA.) Qinetiq (LON:QQ.) and Babcock International (LON:BAB)
Does the market really think the success around Kherson means less defence spending?
FTSE 100 I guess has held up well this year really, FTSE 250 and AIM saw the bulk of the gains yesterday/today.
I think new money maybe moving into bombed out small and mid cap space, well that's how it appears...I could be wrong, but hope not for us year long suffering small cap followers.
FTSE 100 - 0.4%
FTSE 250 +1.5%
FTSE AIM +1.2%
Its an interesting situation we are at right now.
So from now on in you could imagine a steady News flow of decent sentiment. Perhaps UK Inflation peaked, European Inflation peaked, China reduce COVID regulations, maybe talks between Ukraine and Russia, all these have a slow and steady positive effect on the markets countering some of the bad news, recession, poor profits, a hole in UK finances etc. So I have been wracking my brains as what to do from now, because as of yesterday lunchtime my tactics need to change.
If you like me have been net buying the last 3 months in good quality small and mid caps, my gut feeling is what you paid then is pretty safe and if it drops below that then all bets are off. So today I have been protecting against losses by setting stops just above my buy prices, as below that we will be heading into pretty dangerous territory again. Not possible on all shares but as they rise I will get a protection stop loss on. So technically I wont be any worse off than I was mid day yesterday if this is a dead cat bounce.
From there just keep nudging up my stop losses, keeping far enough away not to stop out. Anything that's hitting a target I will sell half and set a trailing stop. Some will go but going for profit will do. It might be worth selling half a stake in something before a news day, can always buy back in if it does fall (VLX a classic example this week)..just taking some profits. I am cutting anything that's already down for me and starts falling.
Will be using some cash for a little more exposure to mining, but TBH I think for me all the pain of buying over the last few months, the self doubt is over for now (thank God), and am going to sit this phase out and keep some cash on the side lines.
Thanks for every ones help and advice over this last few months, some real gems have been discussed.
Paul S keep the podcasts coming, I love them!
Good luck to you all, I hope like me you are going to have a few beers this weekend!
Paul
Talking about portfolio execution tactics, as Paul has been, I reckon that's good advice for me to take profits along the way. However, I'm also mindful of Nicolas Darvas's mantra that there's no need to sell a rising share price and no need to hold a falling share price. What if this really is a 'lockout' rally that no sensible investor will ever believe until it's too late to buy? My solution is to let the stock prices dictate my actions, while investing using fundamentals as a guide and with a long-term, contrarian mindset. The biggest danger now, as I see it, is the possibility I'll let my sensible and rational self choke off what could prove to be enduring gains.
Incomprehensible to me that Frp Advisory (LON:FRP) implicitly seen as a better biz (higher rated) than K3 Capital (LON:K3C) when K3C run a much superior durable model than the classic advisory one employed by FRP...
Who's taking the other side and why?
These are different businesses though - FRP offer pure exposure to insolvencies which might be attractive in the current climate. For K3 this makes up a fairly small part of their overall business (by profits, although it makes up a decent chunk by revenues) - the rest of the business is fairly cyclical I would imagine, so overall earnings could take a hit in a recession.
I agree I'm comparing espresso cups to teapots to a degree. Insolvency is nearly 55% of K3 Capital (LON:K3C) revenue (£37.5m of £70.7m) on c.18% (ebitda) margin...add in some shared central costs and its close to the 16.5% Frp Advisory (LON:FRP) applying some handwaving.
Giving the K3C bit of the biz you implicitly rate (insolvency) a (historic) price to sales rating like FRP gets £163m market cap for K3C before tax and corporate finance -> that means that only £42m of market cap to the £33.2m of revenue from corporate finance (£21.6m) and R&D tax advisory (£11.6m). These businesses operate at c.40% and 50% ebitda margin (corporate finance reported as 50% this past year...partly good year and partly that central costs now borne by group not corporate finance alone...so approx 40-45% margin year prior to acquiring/developing tax and insolvency). Note ebitda margin is relatively clean and good measure for K3C except for earn out cost of acquisitions (I'm 'normalising' that out).
K3C's insolvency has been growing generally >20% organically over several years (pre and post acquisition by K3C) and investment in growth has deflated margins which should come in at 20% and over. Corporate finance deserves some cyclicality thinking but so far their SME focus and process (v systematic and sales driven focused on small end of SME and doing large volumes cost effectively) has avoided simple cyclicality. Tax is much less cyclical and securing a client leads to a repeat revenue profile over c.5yrs. Given 50% margin in tax on a revenue they have shown they can grow at a decent clip (could be >20%) plugging it into their systematic sales engine what value is appropriate on that £11.6m revenue? Is £100m too much? I think not and on the low side...but we are in more sceptical times I acknowledged.
That leaves corporate finance...its been growing organically at a high clip for years and hitting margins up to 50% in good years and c.40% is a reasonable and 'conservative' assumed base case. At £21.6m revenue and even assuming a cyclical slow down its got a few turns of value for market cap.
And the above is before we give them a lot of credit for growth potential. IMO high.
Some very solid movements on shares. Glad held onto most of them as only 3 weeks ago it was pretty bleak out there . At the time we have to tell ourselves the sentiment can change extremely quickly and who knew just how quickly! From oversold to overbought perhaps. Looking at all the layoffs by tech companies , hiring freezes by others and interest rate rises still coming through I'm trimming some positions into this rally.
There are still a few recent stocko ones that haven't caught up like Angling Direct (LON:ANG) Beeks Financial Cloud (LON:BKS) £ASTO. Others have had very impressive rallies from their lows of 30-50% in just a couple of weeks (Luceco (LON:LUCE) , THG (LON:THG), JD Sports Fashion (LON:JD.), Saga (LON:SAGA), Inspecs (LON:SPEC), S4 Capital (LON:SFOR), Smiths News (LON:SNWS),Boohoo (LON:BOO), - but don't hold that). Let's see where we go next!
And whilst crypto falls as well! :) Microstrategy short is a great way to play this
Wa worried there may be some contagion from FTX and a 25% fall in BTC but seemingly not or maybe just in meme stonks
Luceco (LON:LUCE) has hardly gone up and is still 78% below 52 week high. Im not sure what you mean by Stocko ones? They are all on Stocopedia.
Im up 35% on Luceco (LON:LUCE) since it was last mentioned on scvr
Well done on that
I am sure you will have a TopTurkey for your Christmas lunch.
Everything feels a little calmer this morning. Unless you are short Boohoo (LON:BOO) or similar that is. Im sure there have been similar days back in 08 maybe or 01 but I can't remember one quite like it. It was coming...the CTAs had made way too much money so everything had been pushed to the limit... Of course nothing really changed but ....
I would argue the easy beta short returns, lazy shorts riding the negative sentiment are done for now. Nothing is ever over but we are a year down the road... and starting to think seriously about 2023 and beyond. Its clear some industries look a lot better than others.... and a lot of stocks offer great value. There will be a real mix of cr@ppy performance institutionally.... these guys can get caught in the headlights just like anyone else. Next year is a clean slate though. At the start of the year..even a whiff of disappointment and they will kick the shares out....for fear of a repeat of 2022. This may throw up more good opportunities....time will tell. It will be volatile.... but more about stock picking. Whilst we will be in recession - recessions aren't so bad for the stock market. My view remains its a good investment backdrop... more about strong expected returns than strong prices...
One thing I would add is that next week I would be doing a quick 10% placing if I needed some money to get me through H1 23....now I know we don't have many of these companies ...but don't be surprised to see a few placings. Its a no brainer corporate wise and the smallest of windows to get it done. Id be making the calls.... be interesting to see what we get.
My reading for the weekend is industrials... and my bet is this has legs...but then its stop start for a while as we ride the data rollercoaster.... enjoy the rally and good luck always.
Interesting stuff RDH, good to read other people's take on the investment outlook.
R
An incredible day it was yesterday. It proved the difficulty with timing the market and staying away either in cash or wealth preserving assets. Unloved Gold also had a shining day.
Are we still in a bear market rally or it is the beginning of reversing the bear market?
I think it is the latter. A big jump up like yesterday is a significant signal.
we may have some give back but the trend is already set!
I said it first but being without cash I'm just waiting for the Market to catch up with my investments.
Silver
The SP500, my preferred indicator of risk sentiment, is in a well defined descending channel on the weekly TF. Until it breaks out of that to the upside, it’s a bear market rally.
My gut feeling is that this is a bear market rally … interest rates have not peaked and many western countries are about to enter into a recession … all which will impact company results.
I agree. we are in recession but it will be confirmed in early 2023. The market for some shares have already discounted that for good measures. The housebuilders are a good example. The house prices are due, quite rightly, for a 25% drop over the next two years. good news for a large number of young buyers. The housebuilders shares however, may not drop further.
Predicting the big economic picture is very self satisfying and clever but it is so annoying when the market does not react as you expect. That's why there are lots of poor economists around!
Of course you've heard the term "climbing the wall of worry". Tops of bull markets are often seen when share prices go up despite bad news and Troughs of bear markets are often found when share prices go down despite relatively good news. The latter has been occurring recently - you only need to read comments on here to get the sense of that.
My guess is we will now enter the wall of worry phase. Ignore the frothy initial jump yesterday but I suspect that despite seemingly still relatively poor news flow the market will start to unwind some of the losses in advance of better news in 6 months time. That doesn't mean a straight line, nothing ever is, but somehow the bottom feels like it is in. That can all change with another black swan event of course.
Croma
Not bad results .
They’ve got sone nice technology just released sone intelligent locking systems .
Cash pile down a bit but they’ve bought asset backed bolt ons this year .
1.59 profit on circa 9 million valuation with over 2 million cash and plenty of assets looks ok .
It is illiquid but they seem to be doing the right things and the management seem to be building a nice platform for steady future growth .
Not one for traders and there are probably better places for your pennies but I’m happy to hold , especially as it’s a very easy business to understand .
I could do with a detailed balance sheet as I suspect the freehold and inventories almost cover market cap which sort of makes it a no brainer hold .
Hi planetx,
Full report and accounts are available on the website:
https://www.cssgplc.com/invest...
Property plus inventory is some way short of market cap, although if you add in cash as well, you are starting to get closer. Mind you, if the price action today continues as it has started, we might be there by 16:30!
Croma Security Solutions (LON:CSSG) results. All sounds very positive until you get to this:
Gross profit
6,396
5,385
Administrative expenses
(6,237)
(4,898)
Other operating income
86
764
Operating profit
245
1,251
EPS down from 6.56p to 0.42p
Hargreaves at 09:28 Sell:50.00p Buy:57.00p (12% spread) down 13.50p (21.26%)
Add back the £627k goodwill impairment, and it looks a bit better.
Good point. The goodwill impairment is for Weighted Average Cost of Capital and I confess I haven't a clue how to treat that. But here is a possible re-statement of the results. Does it make sense to look at it like this?
Hi Michael,
I would agree that your adjusted comparison for Croma Security Solutions (LON:CSSG) is a better basis for comparing this year with last year.
I ignore the goodwill write-off because it essentially means that they paid too much for something in the past (ignoring the fact that this is a hindsight view largely driven by recent interest rate increases), and that 'wasted' cash is long gone from the balance sheet.