Small Cap Value Report (Fri 11 Sept 2020) - DC., DTG, HFD, MIRI

Good morning, it's Paul here, with Friday's SCVR.
Today's report is now finished. Sorry, I've dropped MCB from the list, as it doesn't interest me at all, and a friend has just invited me for lunch, and the sun has come out. Thank you for your indulgence!
Here's the link for yesterday's full SCVR, which I finished off in the evening, and now covers Epwin, Speedy Hire, and Anpario, as well as earlier sections on Victoria, Saga, and Dunelm. Some interesting companies there. I've been very encouraged by quite a few interesting situations which are emerging at the moment.
Broker forecasts - opportunity
There's a really good opportunity at the moment, to work out which companies have badly wrong broker forecasts out on them. Some brokers are too optimistic (or forecasts are old & out-of-date), and some are ignoring strong current trading, hence issuing woefully pessimistic forecasts. If we spot the right ones, then there's good money to be made in some shares, I reckon. Hence it's more important than ever to closely scrutinise trading updates & outlook comments.
Lack of guidance - not acceptable
It's a really poor show that some companies are still refusing to give full year guidance, given that we're most of the way through 2020, and it's pretty clear that a gradual economic recovery is gaining traction.
Companies don't have to give precise profit or revenue forecasts, but they could give guidance on this basis:
- Base case (i.e. management's reasonable forecast, which they will all already have internally), then an
- Upside case, and a
- Downside case (renewed lockdowns, etc).
Why can't they tell us (the owners of the companies!) this basic information? Failure to provide guidance at this stage is, I think, unacceptable, and investors need to start putting pressure on companies to give proper guidance - a range of possible scenarios to the market. I note that they do this when they want to raise money! And sometimes the auditors force them to reveal stress testing in audit reports (very useful). We need proper disclosure of future guidance, not the feeble excuse that it's too uncertain. They all have forecasts internally, so we need to see them too. It's wrong to keep the owners of the company in the dark.
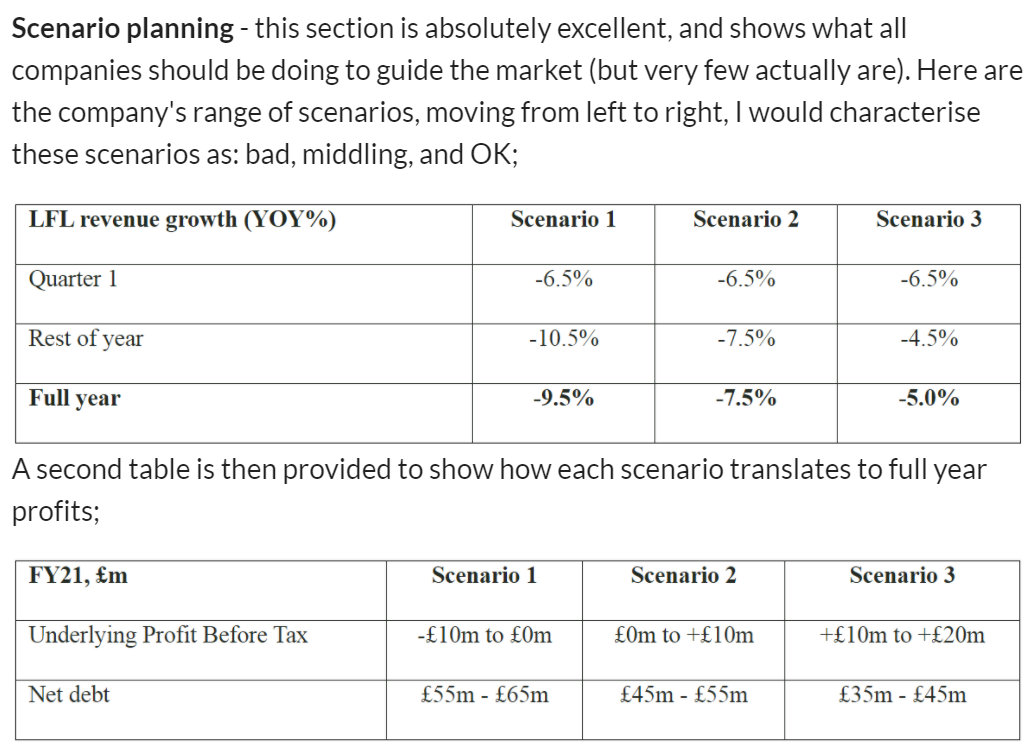
Halfords is a great example (below) of best practice. This is an excerpt from the SCVR for 7 July 2020, where I highlighted the brilliant scenario examples given by Halfords. We should have this information provided by all companies. Absolute transparency. Why ever not?:
.
.
.
Today's agenda
There's nothing of interest in the small caps area, so I've gone through my notepad and picked up a few announcements that I intended to look at, but didn't have time earlier this week. Not all of these are small caps, but I'm looking into them for wider macro read-across, and because they're on my watchlist as possible purchases for my personal portfolio (I'm happy to buy mid or large caps, if they look appealing).
Dixons Carphone (LON:DC.) - a reader request, which sounds potentially interesting, trading update yesterday
Dart (LON:DTG) - I'm toying with the idea of buying back into this airline/travel group at some stage, but it might be too early - AGM statement a few days ago
Halfords (LON:HFD) - trading update earlier this week
Mirriad Advertising (LON:MIRI) - flagged up by PR firm Yellowstone Advisory, in the comments here earlier this week
Mcbride (LON:MCB) - final results from earlier this week
.
Dixons Carphone (LON:DC.)
Share price: 88p
No. shares: 1,166.5m
Market cap: £1,026.5m
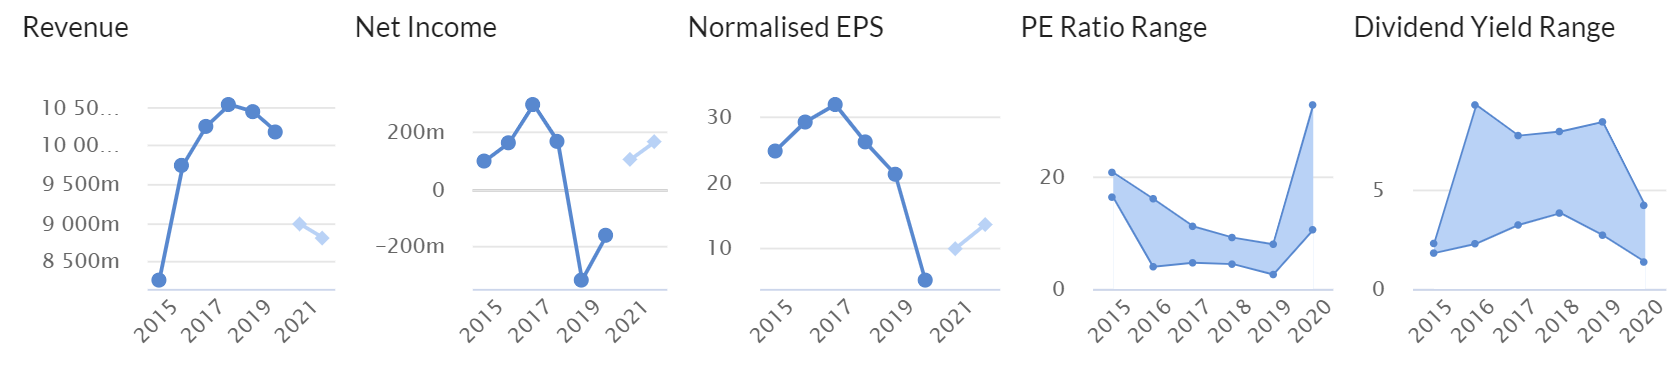
This is a reader request. I've not looked at this share for years, because I assumed it was just another old-style retailer, doomed to eventual failure due to increasing internet competition and uneconomic shop leases. The Stockopedia graphs below reinforce that impression, with declining revenues and profits. The lighter blobs are forecasts, which don't look realistic to me (why would profit go up now?), on first impressions;
.
.
Results for 52 weeks to 2 May 2020 - I've reviewed these, as background before I look at the latest trading update. Key points;
- Adj pre-tax profit fell 47% to £194m (LY: £363m)
- Most concerning issue is the UK & Ireland Mobile division moved heavily into losses of £(104m) - this looks a serious problem
- Nordics region is very profitable, so shouldn't be seen as just a UK business
- £284m net debt doesn't sound to bad, but the rest of the balance sheet is a car crash: NTAV negative, at £(990m) - which includes a large pension deficit (annual cost £46m), plus large lease liabilities
- Margin pressure (I suppose this is inevitable, with generic products, lots of competitors, people comparing prices online)
- Online sales are 35% of total UK & Ireland electrical division sales - impressive
This is starting to look like something I'd be more likely to short, than to go long.
Latest trading update from yesterday, 10 Sept 2020. This covers the 17 weeks ended 29 August 2020, so that's the new financial year to date FY 04/2021, i.e. May, June, July and August 2020.
Strong sales in all markets with outstanding online performance
UK & I Electricals - LFL sales up 12%, impressive.
Online is strong. I'm impressed that the growth rate post-lockdown is still excellent;
Online sales more than tripled year-on-year while stores were closed, and have continued at more than double last year's sales since stores reopened. Online market share gains every month and overall share gains since stores reopened
Dixons Travel stores down 90%, which is a 5% hit to total electricals sales.
Gross margin down, but not quantified
Cash - this appears impressive, but we're not told whether or not creditors have been stretched, so I'd want to see the full numbers before drawing any conclusions from this;
The Group is in a net cash position - which is a substantial improvement on this time last year - and has continued access to over £1.3bn of available committed debt facilities
Outlook -
We've started the year well, but nobody knows what the future holds and, like many, we remain cautious in our outlook.
We're also in the early stages of exploring the option of listing a minority stake of our Nordics business next year. This would shine a light on the value of the Nordics business whilst retaining it as part of the Group."
That's an interesting possibility. The Nordics business is very profitable, and there might be some shareholder value to be extracted by listing it separately, a part-disposal to generate some cash, is the way I see that.
My opinion - viewed in isolation, this trading update reads well. However, it glosses over the reality that this is a low margin sector, with lots of competition, and whilst the business is doing well online, it is also saddled with all the historic baggage of expensive shop leases, and a pension deficit. Hence I reckon slowly disposing of its shops as leases expire, and servicing the pension deficit, could end up swallowing most, or even all future cashflows & profit. Therefore I would treat the dividends as not likely to last much longer. There could also come a point where suppliers may not be able to get credit insurance, hence the massive £2.0bn trade creditors which essentially funds the business, may not be sustainable in the long-term.
Short term, it sounds like things are going OK. Longer term, I wouldn't be surprised to see this share go down the pan, along with so many other traditional retailers. The online business is strong, but lower margin. I'd like to see the split of profits between physical & online, and then compare the valuation with competitor Ao World (LON:AO.) which of course doesn't have the historic problems of a retail store portfolio, nor pension deficit.
Overall, I definitely wouldn't go long of DC. and it's something that might make a good short at some point, possibly.
As we've seen with Gear4music Holdings (LON:G4M) - there's very little money to be made selling large quantities of generic, low margin products. The money is from chasing higher margin products, and developing own brands at higher margins. I can't see much chance of that happening here, as electricals are so easy to buy from anywhere. We tend to have our favourite brands (e.g. I always buy entry-level Bosch appliances, because they're such good quality, never go wrong, and last forever, without being particularly expensive). It doesn't matter to me who the retailer is, I just want a specific product at the lowest price, and with quick delivery. Hence it's always going to be a race to the bottom in terms of price & margins. Hence a deeply unattractive sector.
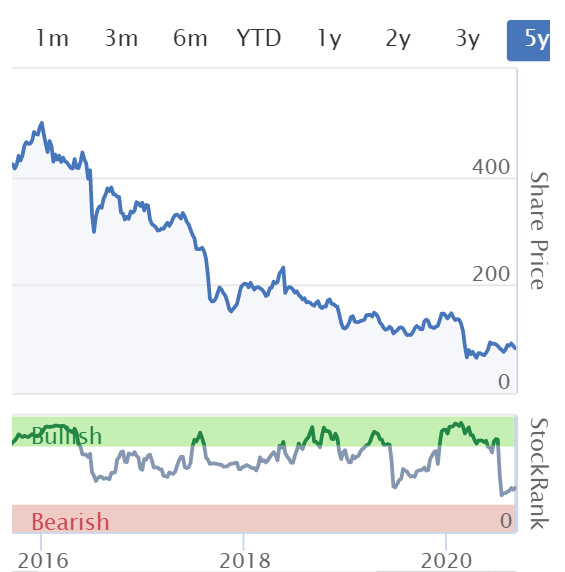
The 5 year chart below is a bucket of cold water over anyone feeling positive about this share! It just looks like a structurally declining business from that chart. What is going to change any time soon? Online sales possibly, but that then leaves billions of historic problems to deal with - i.e. lease liabilities, pension deficit, principally.
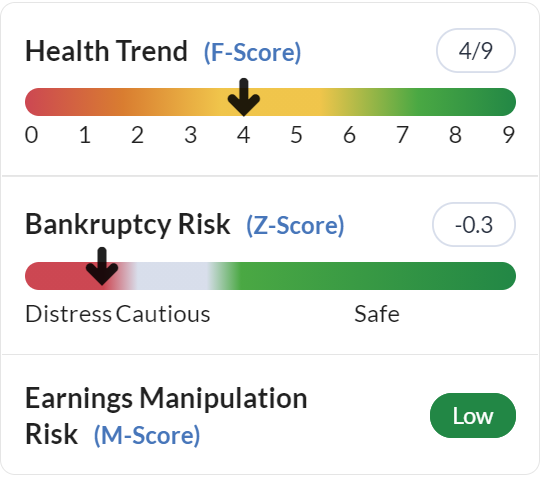
Note that the Altman Z-score is flashing red, confirming my view that this business is financially distressed on a balance sheet basis.
.
.
.
The reader who asked me to look at this, is probably regretting that request now!
Dart (LON:DTG)
Share price: 711p
No. shares: 178.7m
Market cap: £1,270.6m
Annual General Meeting Statement and Proposed Name Change
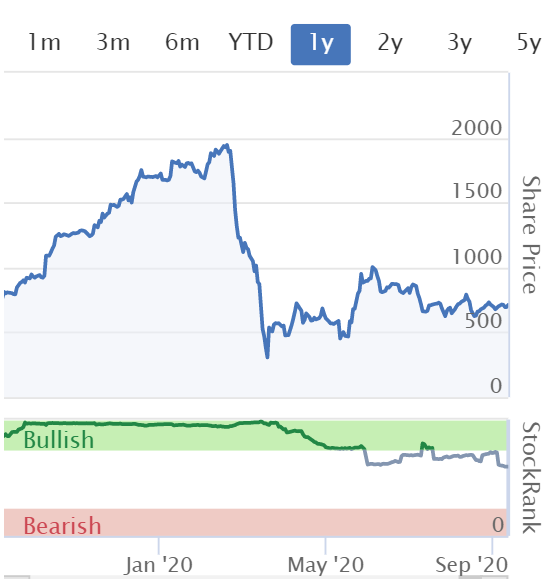
Dart is an airline Jet2.com and package holidays group, focused on value for money, so not dependent on the previously lucrative business travel market. It has a financial year end of 31 March 2021. Therefore, FY 03/2021 figures are likely to look awful, including the whole covid period (hopefully). It's potential strong recovery in FY 03/2022 which makes this share potentially interesting, together with its superb track record over the pre-covid years.
This announcement came out on 3 Sept 2020.
"After grounding our aircraft fleet in mid-March, we were pleased to resume operations on 15 July, gradually ramping up Summer 2020 flying to approximately 40% of our planned destinations for August, ensuring we could provide as many of our customers as possible with their well-deserved and eagerly anticipated summer holidays....
I notice that says 40% of planned destinations, which strikes me as ambiguous. That could be completely different from 40% of flights, or 40% of passengers. Also, what about the costs of keeping the rest of the planes grounded? That must be costing a bob or two.
This next bit reassures somewhat, as crucially the load factors sound OK (but no figures given);
Whilst there have been setbacks, such as the imposition of quarantines and evolving guidance from the UK Government, we have been satisfied with the average load factors and financial contribution achieved to date and will continue to add further capacity, as appropriate, for the remainder of Summer 2020, supported by our quick to market, flexible operating model.
Winter 20/21 bookings - are behind available seats, and pricing needs to be competitive - not so encouraging.
Summer 2021 - much more encouraging news here. It strikes me that, having been denied a summer holiday in 2020, many people must be looking forward to 2021, and booking up in advance. Since airlines need the cash up-front, that's very helpful;
For Summer 2021, we plan to fly to all our popular leisure destinations with an appropriate, tailored level of service, which we anticipate will be close to Summer 2019 seat capacity levels.
Bookings to date are encouraging, with average load factors ahead of the same point last year and package holiday customer numbers as a proportion of total departing customers showing a material increase.
This augurs very well for the future, but it relies heavily on covid being at least under control, or eliminated, by summer 2021.
Liquidity - sounds good, but it's not clear if this is net cash, or gross cash?
As at 28 August, our Total Cash balance was £1,064m, with an 'Own Cash' balance (excluding customer deposits) of £629m (at 31 March 2020: £1,387m and £520m respectively).
Additionally, the Bank of England Covid Corporate Financing Facility of up to £300m of funding is currently unutilised.
Name change - to Jet2 plc, to reflect the focus now that Fowler Welch has been sold.
My opinion - we've only got partial information in this update. It says nothing about profitability, so we're flying blind in terms of how to value this share.
It's clearly not in any solvency risk, with plenty of liquidity. Also I'm encouraged that a fair bit of flying has resumed, and they're happy with load factor (i.e. bums on seats) and financial performance. Nothing is said about air freight, and I wonder if there could be upside from re-purposing some planes for that, on a temporary basis?
This share is a straightforward bet on covid being defeated in the spring of 2021, with enough treatments, testing & maybe vaccines, to allow air travel to get back to normal. If that happens, then I think you would see a substantial re-rating of airline shares, and Dart is the pick of the bunch for me.
In that scenario, I reckon Dart shares could double, or even more. In addition, as it's securely financed, then even if the scenario next year is less rosy, Dart should probably still be solvent, whilst weaker competitors might go under. Although flag carrier airlines are usually seen as too prestigious for Govts to allow them to go bust. Are they direct competitors to Dart though? Probably not, in most cases.
The downside risk here is that, since covid has not been eradicated this summer, the autumn/winter is looking increasingly likely to see a second wave. That's bound to cause negative investor sentiment, and it's difficult to see UK investors being prepared to take a sanguine view - collectively we seem far less prepared to look through covid than, e.g. US investors.
Overall, I'm tempted, but on balance have decided not to be brave, and instead I'll watch from the sidelines for a more attractive entry price. If I miss a big re-rating, then so be it.
.
.
Halfords (LON:HFD)
Share price: 192p
No. shares: 199.1m
Market cap: £382.3m
Halfords has an end March year end, so this update covers April-August 2020. That includes the lockdown period, although most Halfords sites continued trading, being classed as essential services - a key advantage, and reassuring if you fear a second wave of covid.
LFL sales up 5.0% over the 20 weeks, fuelled by trend for cycling & staycations (some of which is likely to be a one-off, I imagine)
Online sales, and gross margins, both strong
Clear guidance is given for H1, but not H2;
Assuming expected demand levels in September and stability in the relative value of the US dollar, underlying H1 FY21 PBT1 is expected to be in the range of £35-40m.
Significant uncertainty remains for H2 FY21 . Given the natural fall-off in the relative strength of cycling and staycation products during winter months, alongside a difficult economic outlook, H2 FY21
PBT could be significantly lower than H1 FY21.
Online - it's vital that businesses adapt to the internet, or die, with only a few exceptions (Primark springs to mind). Halfords seems to be doing well here;
In the last 12 months we have tripled our investment in the ongoing development of our web platform to enable a dramatic shift to online ordering, with sales up +160% year-on-year and representing 54% of total revenue in the period.
That will include booking MoTs, etc, at its service centres, as well as selling products. I've used Halfords for an MoT, and to buy a stereo, and was happy with both.
There's a lot more information in the RNS, including a superb table of revenues & LFLs in good granularity, by month, and by division. This shows how strongly the business bounced back from weak trading in April & May, and has since recouped lost sales.
My opinion - I started off with a fairly negative impression, but working through this update, became more positive. I particularly like the resilience throughout covid/lockdown, and the strong move towards online. The shop leases could be a problem in future, although large sheds are better than town centre sites, as we've seen from e.g. Dunelm and ScS (I hold), customers seem happier to visit retail parks than town centres.
Is it worth £382m though? I honestly don't know. It's difficult to value because the future is uncertain. Therefore I'm neutral.
.
Mirriad Advertising (LON:MIRI)
26p - mkt cap £55m
PR outfit Yellowstone Advisory flagged this up for me to look at, but I don't think they'll be very happy with my response here!
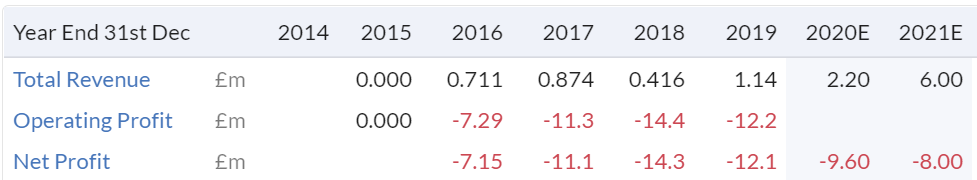
Looking at the track record, it's a blue sky stock so far - negligible revenues, and huge losses to date. So to be valued at £55m, it must have a great story!
.
.
H1 results for 6 months to 30 June 2020 look dire. Only £897k revenues. That's up 109% on H1 LY, but it's still tiny. Sequentially, it's only up 26% on H2 LY.
H1 operating loss of £4.9m
H1 cash burn reduced to £4.5m
Cash - it had £14.4m at end June 2020, reduced to £13.3m end August. That's enough to take it well into 2021, but unless there's a massive rise in revenues, then it will need more cash later next year.
Outlook - cautiously optimistic. That's nowhere near bullish enough to justify the valuation. There needs to be a massive step change upwards in revenues to get anywhere near breakeven, which doesn't fit well with "cautiously optimistic".
My opinion - good luck with it, but this type of thing is of zero interest to me. The reason is because, over the last 20 years, I've seen so many speculative blue sky things float on the stock market (usually AIM), and hardly any of them succeed. Even if they do, it's usually a lot later, and many fundraises along the way. Why take this risk, when the odds are stacked to heavily against investors?
This could be the next big thing, who knows? But there's nothing in the figures or outlook to suggest to me that the upside is worth over £50m. Risk:reward looks absolutely terrible. If you like searching for needles in haystacks, then this type of thing might appeal. Very rarely, something like this does succeed. Very, very rarely! So you never know. I'm happy to sit on the sidelines, and wait to see some decent commercial progress. Then it might be worth revisiting.
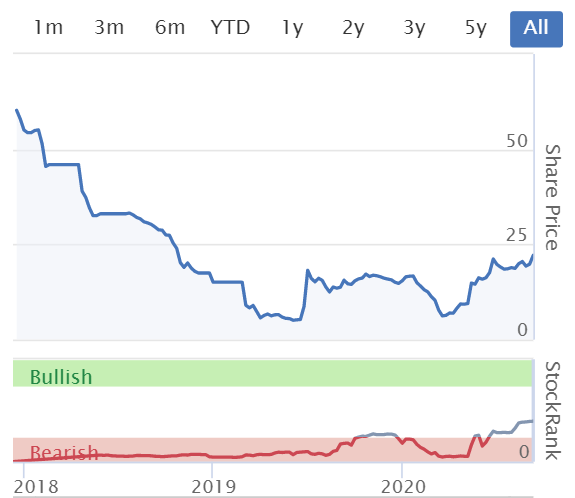
It floated in Dec 2017, and has burned through a lot of cash since then, with very little to show for it, in revenues.
.
.
I'll leave it there for today, and the week.
Thank you for all the excellent reader comments this week. They can sometimes be a chore to plough through when people are ill-tempered, but it's been an absolute pleasure this week, with lots of interesting & courteous discussion! Thanks and well done to everyone who gets involved. The internet is full of angry & rude people, so it's great to have a little enclave here where we can be pleasant & helpful towards each other.
Enjoy the weekend!
Best wishes, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

75 comments
It puzzles me that they still call the listed entity Dixons as that seems to be the brand that they have pretty much totally dropped. (Although I believe there is a Dixons travel at Gatwick.)
In terms of digital reinvention I think there are pretty much there although as an omni-channel offering that I personally think works well.
I can't comment much on the "consumer electronics" side (TVs,Hifi and cameras, which I associate with the old Dixons brand. If I want TV or audio, I would almost always go to the excellent Richer Sounds and back when cameras were a thing, I would have gone to Jessops.
I have quite a lot of experience with the other streams though.
White Goods (Currys), I personally think there are excellent - they always come at around the best price when looking on the internet and I like the choice to be able to go to one of their big sheds and see the product up close and personal and still get the same price.
Computers (PC World), I'm slightly less keen - for desktops I tend to build my own and customise (My current one is about 10 years old and I'm sure it must still have some original parts other than the case!) But I have used them more recently for laptops. Again, good on price and buying via their website is a pleasant experience, buying in-store less so. [Warning grumpy old man rage coming] They insist on employing spotty yoofs, who assume that if you are old enough to shave, then you must be an IT idiot and that they can sell you lots on unnecessarily expensive add-ons and then treat you with disdain if you are stupid enough to put yourself at risk by declining their advice. To be fair that's probably about sales incentives and where the margins are. So I think I will stick to online for this category!
Mobiles (Carphone Warehouse). I valued their stores very highly, with very helpful and knowledgeable staff you genuinely give the impression of being on your side. I suspect it is a very clever customer satisfaction ploy, but they always seem to find an extra discount to give you even if you are not wavering about paying the quoted price. However this part of the business has been badly hit by the slowdown in the Handset upgrade cycle and they are retrenching from their presence on the high street.
I recently had to do an early upgrade on my other half's phone and was crestfallen that our local branch had been permanently closed down during lockdown. The website was okay, but the fact that I would have to contact their call centre to finalise the deal really put me off (maybe their call centre is excellent, I don't know, but I have yet to encounter a call centre that comes close to satisfaction). Instead I chose to travel to their nearest big-shed to do the deal in person - excellent service as ever, however, the extra hassle might put me off in future.
From my perspective, they seem to get most things right; so from an investment point of view I would be cautious if you think they need a big turnaround to look attractive as I'm not sure it is there to be had. (I'll confess to having not looked at their reports recently, so just commenting on the gist of the comments above.)
Having said that though, if you trust trustpilot (I generally don't) then it looks as though they do have a lot to do. It is very polarised : 20% excellent , 67% bad (the worst possible score on the 5 point scale). That skew suggests to me, that they may need a different approach to Trustpilot - i have never been invited to encouraged to score them on trustpilot. Unprompted I would be highly unlikely to post a review unless I was really upset!
Not sure if that is helpful or not; but just a different perspective.
Investoree
The Open Offer is at 12p so you will be able to buy at 12p.
@Whitbourne et al - in answer to the portfolio valuation charts issues,
we've actually scheduled some great improvements for this in the coming weeks.
We will be adding a time-weighted-return chart that normalises for the capital inflows/outflows onto the portfolio chart quite soon. So you'll be able to see the time weighted return or the portfolio valuation by default as per your preference.
Before then we are in the midst of moving our infrastructure to AWS, but then we'll be cracking on portfolio improvements. It may take a couple of months, but we'll have it delivered soon enough.
Thanks Ed, it’s great to know that this is on the cards. Thank you also for acting so promptly following the server problems earlier, it’s a worry you could do without and I’m sure moving to the cloud is the right decision.
Hi Paul, I’ve always enjoyed reading your commentary even when I don’t agree with it so don’t mind your contrary views at all. As you’ve mentioned before you don’t get everything right and have missed a few great companies in the past and subsequently kicked yourself for not getting involved, GamesWorkshop springs to mind as a multi bagger that got away.
New technology can take time for adoption and that’s certainly the case here but momentum is building. I think the TenCent client example is a good one. They signed a contract with a minimum value of £1m in year1 and a minimum value of £2m in year 2. The company said that China is performing ahead of expectations so those numbers are likely to grow. The US ad market is a substantially bigger than the Chinese market and they are in discussions with 6 out of the top 7 streaming platforms and expect to sign at least 1 by the end of the year. Given the relative size of the markets it is likely to be a quantum bigger than the Tencent deal. The reason these deals are being signed is that brands and ad agencies now understand the clear benefits and higher ROI that Mirriad delivers to their marketing. This progress doesn’t suggest a blue sky stock to me. Rather one that has developed a world leading product that is delivering superior results to brands and is getting traction across the globe.
I know that you are a pragmatist and prepared to revise your opinions as the facts change. I’m glad the stock is now on your radar and look forward to your future comments.
How interesting, thanks.
I just work from the numbers, there are no emotions involved whatsoever. Those contracts do sound interesting, and as you say, interest from big clients could get exciting in future.
If the numbers dramatically improve, then of course I'll revise my opinion! :-)
If you like Mirriad you'll probably love Blackbird (LON:BIRD)
Thank you for your thoughts on £DTG.
Coincidentally I popped over to www.valueinvestorclub.com this morning and started to watch the latest interview in the excellent PIWorld series with Castleford Tiger at
I am an ex holder of £DTG having bought twice: firstly at 154p in Feb 2013 and thought I was very clever to sell 476p 31/2 yrs later for a 24% CARG.
I then regretted my sale and bought that November at 453p and sold 9 months later at 510.
My interest has been re-ignited by Castleford Tiger and a post by Avalon216 on Value Investors Club from May 2020 (I am not a full member so what I can view is delayed by 45 days) which can be found at:
https://www.valueinvestorsclub...
With the demise of Thomas Cook DTG's main competitor is now Tui Ag (LON:TUI), which, to use Avalons words, "if it can survive" may mean DTG can come back even stronger. Avalon believes, if it can survive, that DTG is worth many multiples of where it is today.
Dart was priced at 470p when the post was written and now stands at 718p.
I will study some more over the weekend and then if my thoughts are confirmed I will open a starter position on Monday with a view to building on that with a three to four year view.
I hold Avacta (LON:AVCT) on the basis of its LFT being successful and being rolled out in quantity. If it is successful, the impact on air travel will be significant. So if I invest in AVCT then an investment in DTG is logical. I think?
Have a good weekend.
Regards
Michael
Dart (LON:DTG)
Paul - great commentary on DTG. Based on the way the Mar 2020 accounts are presented the own cash figure of £629m is gross I think. (i.e cash and money market deposits of £1064m less customer payments in advance (derived) of £435m).
Of the major players this is in my view the best managed by a long way and I'm looking for a suitable entry point. I am however waiting for another update on the bookings position for Summer 21 as whilst load factors are ahead of last year, the proportion of the Summer 21 programme sold at this point is usually quite low and the post Christmas booking period will provide a firmer handle on how good/bad things are.
"The reader who asked me to look at this, is probably regretting that request now!"
On the contrary, whoever they are they just got an excellent sell signal. Preventing a loss is better than making a profit sometimes...
£FDEV Anybody know the reason for the huge number of share transactions today - currently 1.69m (daily average 66k) - I hold.
If you look at the trades there are two at 10 43 totaling over 800k.
Morning Paul
I’m not trying to upset the Stockopedia working model, but have just noticed that YTD stocks with a ranking of 0-10 massively outperform all others!
Interesting - if you dig a bit deeper you’ll see that it is influenced by very small cap (sub 50m). It could be a few tinies that have benefited vastly from Covid news. In fact it appears to be the sub 10m market cap that are skewing the results. It’s not an area that I would necessarily look to invest
I had a look but even >50m 0-10 outperforms the 90-100 rank this year. The 90-100 had a massive fall and has not fully recovered.
This was discussed in a bit of detail in the thread linked below. It is curious and somewhat counterintuitive, but it won't get me buying any <10 stockranks any time soon!
https://www.stockopedia.com/co...
Paul
an important admin point on the Saga open offer. The record date is 9 September as you stated yesterday. The ex entitlement date is 11 September. This means that holders on 10 September are eligible for the open offer. I bought shares yesterday after reading your comments (and some of my own research). My broker has credited my account with open offer entitlements. Even more important given it was placed at 12p, a decent discount to market of about 15p.
HB
Oh that's great news HornBlower, thanks for clarifying. I always seem to cause confusion on entitlement dates, so probably best if I don't comment on them in future fundraisings, and just tell people to query with their own brokers.
Hornblower or Paul can you please give any further information on this open offer as I am not getting any sensible information from IG Index and would like to ensure that I am able to take up my open offer. I would clearly like to buy my entitlement at 12p not 15p if at all possible. Many Thanks Martin.
Hi Investoree,
You need to talk to your broker.
Regards, Paul.
Hi Paul, As it is quiet today could i have your views on yesterday's announcement by TT electronics re a covid test in seconds. It sounds like a game changer but the shares are down 5% today . Am i missing something ?
micke
TT electronics (LON:TTG) were up 40% yesterday, so it is probably some profit taking.
Hi mickemmanuel,
Thanks for the prompt. I've just had a look, and the announcement from Tt Electronics (LON:TTG) yesterday does indeed look interesting - which is reflected in its share price shooting up about 40% yesterday.
I've got no expertise to judge whether this is a game-changer or not, and of course it hasn't yet got regulatory approval.
That said, I like TTG to being with - it's a serious, sensible company, that has a good track record of profitability - i.e. it's not some rampy start-up, or blue sky junk that's just trying to jump on the covid bandwagon in order to get a placing away at an inflated price!
For that reason, I've decided to have a small punt on this. Worst case scenario, the stock goes back to the starting point, and we have a maybe 30% loss from the current price. Upside case? Who knows, if the product does get approved & sells well, then there could be a nice boost to results for maybe a year or two? Sounds like TTG is only the manufacturer, and doesn't own the IP.
Bottom line, I've no expertise in this area, so it would only ever be a complete punt for me.
Regards, Paul.
re TT electronics (LON:TTG), I see that this contract is new work for the Hartlepool site, which was acquired when they bought Stadium a couple of years back. I thought at the time that Stadium was being sold much too cheaply, and this announcement indicates why. That said, the fact that they have been making such a success of Stadium says something for the quality of TT electronics (LON:TTG) management. (I don't hold.)
I whole-heartedly agree with this. It is unprecedented for me to consider using the word unprecedented, but I will. I certainly cannot remember a time when broker forecasts have been so far from the reality.
Surely though the problem is that if everyone knows this, then no-one will be using the forecasts for valuation purposes?
Of course those that use valuation tools, screens or methods that include broker forecasts are going to struggle I think. Certainly I see that the metrics of increasing or decreasing broker sentiment and throwing out more wrong flags than they are correct ones.
It is a time to pay attention and form your own judgement based on the detail of what management are saying imho. (Maybe it is always that time, but more so now than ever.)
Just published Inspired Energy (LON:INSE) half year results, in a presentation to analysts 9.9.20 by Mark Dickinson, CEO & Paul Connor, CFO.
Video or podcast
Dixons Carphone (LON:DC.)
Not regretting making the request at all Paul, That's very useful and highlights the limitations of my own research!
Thanks for taking the time to look into it.
DYOR of course, but there is a bull case to be made on Dixons when one gets beyond the snapshot financials and into the nitty gritty of the business - long term, could be the dominant player in UK and Nordic electricals. Meanwhile they have plenty of liquidity, and more importantly they have closed Carphone Warehouse which is posting big losses - the large receivables book being unwound with a potential cash release of £100-£200m. This will deleverage the balance sheet and allow for some investment into the electricals business. While that business may not be the most exciting in the world, their relative market position could strengthen as competition struggle / drop away. So under normal conditions, you get a retailer with an improving balance sheet and market position on a mid single digit multiple, even when including interest / pension contributions.
Thanks daz!
I'm not saying right or wrong, just shared my thoughts on the fundamentals, as I see them.
Market sentiment can often go crazy, and we're bang on a period like that now, where there are large pockets of market mania, for growth companies. It's a bubble, and only a matter of time until the bubble bursts. With zero interest rates, that could take years.
On the upside, traditional companies which are re-inventing themselves for the digital world, are rare, but potentially lucrative. Maybe Dixons is one of them? I doubt it. It could be interesting if it does a pre-pack admin, to get rid of all the shop leases & pension fund. Otherwise, why get involved?
Regards, Paul.
Blancco Technology (LON:BLTG)
Up 18% today and i cant find any news, any ideas ?
Hi John,
I believe it was due to a tip from Frontier Tech yesterday
Thanks Marcus,
Must have been a good tip from Frontier Tech Investor.
Concise, precise and cuts through the jargon-keep it up Paul.
Does anyone know why the ANP spread is quite so wide. Since it is surprisingly volatile I like to dip in and out but the opportunities to do this are obviously far fewer given the c.5% spread.
I agree. It is a little illiquid at times. This tends to happen with AIM stock. Not many shares and quite a substantial institutional shareholding. They did try to address this problem with a 1 for 10 consolidation a few years back. Doesn't seem to have worked. SPE is nearly as bad. Buy for 9.05 sell for 8.70. I suppose it rather depends on volume, as the spreads do narrow at times. What I don't understand is how an institution buys £1000000 worth of shares in ANP and the sp doesn't budge unless its some kind of transfer deal. Anyway I am a big fan of Anpario (as is master investor Lord Lee)having followed and invested since Kiotech days. In all honesty I would not buy more at todays price but there again I have a few and with it being particularly treacherous out there this is not a bad deal for a near 2% div and very solid. More question of not wanting it to overbalance my portfolio, which I may regret
CentralNic (LON:CNIC)
I missed this yesterday & the book build completed today at 75p for 20% of new shares, is that a 20% dilution to holders?
CentralNic Group plc
("CentralNic" or the "Company" or the "Group")
Conditional acquisition of Zeropark and Voluum for USD 36 million
Proposed Accelerated Bookbuild to raise approximate gross proceeds of £30 million (approximately USD 39m)
I am looking forward to Holland Smith retuning...there is much psychology on loss even when something temporary is taken away, i feel it with HS, 10 trillion of temporary stimulus anyone?
While clearly the extra shares do reduce your percentage holding of the company, it is also true that raising the cash by £30miliion (at very little discount to market price) means that the company has £30million additional value and (with luck) more than that as they use the money to acquire earning enhancing assets.
It is very unfortunate that PI s get sidetracked in the raising, other companies leave at least some part of the raise for the private investor to contribute later. Clearly it is not easy to raise money for a takeover which, understandably must be kept highly confidential.
For these instances, where there is very little discount involved in a takeover fund raise I am prepared to cut the company a bit of slack. If you want to maintain your percentage in the company, an open market purchase would not have been unduly disadvantaged
Here's the piworld interview from yesterday: An Hour with Castleford Tiger. CT outlines why he might invest in a company, and gives examples of those he likes, where he see significant upside. Great wisdom from someone who's been successfully at it a long time. Video and podcast.
CT mentions: Mpac (LON:MPAC), Tandem (LON:TND), Lpa (LON:LPA), Manx Financial (LON:MFX) £HSP.
The next piworld interview is with Cockney Rebel, who has a name for making money in small caps, with a knack of perfect timing. We'll learn more about how he does it. Join us on Thursday 24th September at 1pm, register here.
Morning Tamzin, Another great little package from you. Had waited a while for this one so disappointed I couldn't make the live version yesterday - but have just listened to the podcast - You can't beat a straight forward honest speaking Yorkshireman for telling it how it is. Very entertaining and enlightening
Hello Whitbourne, yes I had the same problem, but if you add any new monies to your beginning stake it comes out right. Hope that helps.
Ah yes - so backdate all contributions to when the portfolio was first created? Good thinking. I could then reverse out the existing entries by making 'withdrawals' on the relevant dates.
Thanks, LGI
Hi Paul
In the interest of something a bit different to look into, for you or anyone else who has some spare time, may I suggest Hellofresh, the meal delivery company.
It's Germany/US listed, so not the usual company discussed here. And for the avoidance of doubt the last update was a few weeks ago and I do hold a position.
You mentioned a few days ago that you were looking for a company with pricing power, cash generation and a low valuation. I've been thinking about whether this company fulfils these criteria.
As it's not UK listed + I hold I was hesitant to write this, but I think there is money to be made, and as I've done so well through community suggestions here, I figured that I may as well share some of my own too.
Apologies in advance for "ramping up" one of my holdings:
That's a maximum EV/FCF multiple of x22 for FY20 (I would hope closer to x17), which in my opinion is not demanding for a cash rich company growing so fast.
One more point to add is that the US operated at 100% capacity during Q2 so the company had to stop marketing/on-boarding new customers. New capacity is set to go live by the end of this quarter. The USA Q2 114% year-on-year revenue increase was therefore driven purely by current customers - very impressive.
I watched a few youtube reviews on the company and they were surprisingly positive too. Does anyone here have any experience with the company?
Again, I hope people don't mind me discussing one of my holdings here. Hopefully others may have looked into it too, so thoughts as always appreciated.
A
I signed up to a few of these companies a few years ago (hellofresh, gusto and mindfulchef). I seem to remember there were some issues with HelloFresh' produce being less than fresh. I've just checked trustpilot and the issue is obviously still there: https://uk.trustpilot.com/review/hellofresh.co.uk
I'm still with MindfulChef and participated in a fund raise which worked out very well, details here: https://www.seedrs.com/businesses/mindful-chef
Hi Andy
Thanks very much for sharing your experience with HelloFresh.
I must admit that I don't really look too much at trustpilot for investing, and I prefer to let the numbers do the talking.
Out of curiosity, do you still get emails from HFG asking for you to try their service again?
Cheers
A
Hi abtan. I can't comment on the shares but I love HelloFresh's products. I started getting them during the pandemic - I work for the NHS which meant I was rather busy earlier in the pandemic and wanted someone to sort out the food and recipes while eating heathily during the week. It saves me a lot of time and the meal prices aren't too bad (about £5 per person per meal). Since early April I have never had the same meal twice so I love being able to cook fresh food from scratch. I've only ever had a problem with one vegetable during that time so I think some of the critical reviews may just be unlucky rather than endemic.
I haven't looked at the financials of the company but some things I'd think about as an investor are:
- There are a number of competitors offering similar services. Personally I have looked at a couple of the others but I am not interested to try them as either their menus look too basic (e.g. Gousto) or would leave me hungry still (e.g. Mindful Chef - good luck andyd!).
- I wonder if the company might benefit from the working from home culture? I never tried it before the pandemic because I couldn't count on being at home enough evenings a week to cook anything.
- It doesn't really work for single people or large families, only say 2-4 people.
- While now I think £30 per week for 3 meals for 2 people is a reasonable price to pay, especially to avoid hassle of spending more time shopping and thinking about what to cook, at first I thought it was expensive. That'll narrow the market. It's basically a middle-class family product.
- All these companies spend a lot of money on marketing and deals to lure customers in. Bizarrely HelloFresh recently told me they'd give me 10% off for the rest of the year. I have no idea why they did that. Obviously I'm delighted as it saves me more money but that seems like a terrible business decision given I'm now a locked-in customer! Maybe something in their algorithm suggests people quit the service at start of September so they offer an incentive perhaps (back to school maybe??)?
- I can definitely see where they try and save money on the costs of the food. E.g. the vegetables always seem smaller than usual, there's a lot of minced meat, and chicken thighs rather than chicken breast. However, I've found 95% of the portion sizes to be perfect. There was only one meal where I felt I was cheated out of a decent sized portion!
- I would assume the margins are low due to competition, transportation costs, and given groceries are generally low margin.
I hope that's helpful
Re. Hellofresh
Thanks for your sharing your experience.
In response to some of your points:
For reference the contribution margin is c.27%, admin costs take up another 2%, capex currently uses 8%, and I'm happy for the rest to be taken up by marketing if it means the company is able to capitalise on its growth and grab market share in what is a relatively nascent market.
I'm obviously very biased in my thinking, though I find very little fault when interrogating the numbers. And I was a huge sceptic until recently.
It will be interesting to see how things work out.
Thanks again for your thoughts.
A
A chart "correlation" I picked up on listening to macro voices which I show as a bit of fun on a Friday. It goes to show that fundamentals are only ever a piece of the jigsaw and ultimately we never really know what motivates buyers and sellers.
Paul, would be interested in your view on #BLV, Jack reported on them on Monday. Looked strong set of results, held up well despite lockdown. But today founder reported to be selling 2m shares at no less than 150p. I am thinking it could be chance to get on board, I don’t hold
£BLV
Andy, I think this is a good opportunity to get a discount which will quickly be snapped up. 4market makers on the bid at 150 and only one on the offer at 155, the rest at 160/5
What's a good website to get all the latest broker forecasts?
I used to get it from "Money" but they say the company supplying them with the info went out of business and they can't find another.
Keep up the good work Paul et al!
I wanted to express my gratitude to Paul & Jack for their recent work.
The combination of macro comment & company analysis is invaluable & fascinating to read.
Thank-you so much for your efforts.
My pleasure, thanks stephen! Jack is turning out to be an excellent replacement for Graham! (who gave us sterling service for a good length of time, and was a pleasure to work with, I hasten to add!)
Quick question to the community, as it’s a quiet day. The default portfolio view on the new site has a useful comparison with the FTSE All-share (you can probably change the benchmark, I haven’t tried). I like being able to change the time interval for this and look at periods where I have under- or over-performed and why.
This feature is made much less useful by the lack of any distinction between increases in valuation because of share price appreciation or dividends, and increases arising from new contributions to the portfolio. I can’t see a check-box that says “this is new capital so ignore this transaction for performance purposes.” Instead, the stated performance is flattered by new contributions and I have to adjust these out manually.
What am I missing?
I've also noticed this and was quite disappointed - I don't think you're missing anything here, I think this is simply a bad software design unfortunately.
my workaround (which doesn't really help if you want to see pro-rated performance of your portfolio) is to backdate any new contributions to the same 'original start date' to get an apples and apples compare.
what other portfolio tools do others use? stocko's does seem to be fairly weak if I'm honest.
I too have noticed this shortcoming, and have the same workaround, ie backdate new capital to Day 1, but this is inherently unsatisfactory as it dilutes performance for the period until the new capital actually goes in.
I have so far rejected the idea of a separate portfolio tool as I like being able to analyse portfolio and stock performance altogether on Stocko, but it is far from perfect.
Another imperfection is that in the real world, as well as all my stocks, I also hold a couple of funds and these are not covered by Stocko, so my portfolio totals are incomplete, and I cannot compare my stocks' performance against the funds I hold. Funds are of course not companies so don't have the usual metrics, but Stocko does cover ITs which, although they are companies, and some even have Stock Ranks, are not susceptible to the same analysis as trading companies.
A further item on my wish list for my Stocko portfolio is multi-currency recording. I hold dollar and euro stocks and cash balances and find I have to convert every transaction to sterling at the relevant time (useful for tax purposes, but a pain otherwise). I am constantly adjusting the 'FX difference' deposit/withdrawal in respect of the currency cash balances to reconcile the Stocko portfolio total to the platform total, surely a waste of time.
I echo your request - what tools/methods do others use?
I have been looking at SharePad as this does seem to solve many of the above issues (https://www.sharescope.co.uk/s...), though it is quite pricey vs Stockopedia so I've not taken the plunge as yet myself - paying for both would be a sizable commitment for me.
I've seen some great features on the 'todo' list here at Stockopedia, but not really much in terms of comms on progress towards them (even after some years of waiting).
non-essentials such as 'referral program' seem to have jumped to the front of the queue on the backlog (https://portal.productboard.co...); I don't see items such as this as adding any compelling reason to favour the 'value' product vs what seems to be a more fully featured alternative.
I have requested this a number of times and also the addition of total return indices to compare against. Each request acknowledged but so far no build :-(
i do it in a spreadsheet instead but rarely as a consequence.
Ed: if you are reading this, it can't be that hard to do! I'll have a go at the algorithm if you want!
If I've understood this correctly, you can get around increases arising from adding new shares by adding a single cash transaction greater than the value of the PF. If your PF creeps over the initial cash transaction, you can go back and edit to increase.
I have noticed that dividend values don't transfer into the graphs, which I find a shame for my income PF
Hi Whitbourne. I queried this with Stocko HQ and they are aware and it's coming in the next feature updates. If you click on LEARN in the left column and then look at PRODUCT ROADMAP, you'll see that Folio Performance Reporting is coming next. I'm really looking forward to that update as I also find the current performance tracking quite limited. I really do want to tip my hat to Ed and the team at Stocko for the monumental efforts that have been made in developing the new site and the incremental upgrades that continue to make this an incredibly outstanding value and such a wonderful resource. I cannot begin to imagine the complexity involved in getting all of this so right across mobile and desktop platforms. There are of course imperfections but when you compare to the appalling level of persistent bugs that reside in OSX for example in spite of the massive resources available to Apple, I think it's an enormous credit to the passion and dedication of Ed and his team.
Thanks johnsmith and Antehelion, I will do the backdating for now as a workaround and it's great to know that this is on the 'to do' list. Completely agree about the continuing improvements to the site, it hasn't all been plain sailing for the Stocko team and I'm very impressed with what has been achieved to date.
Hi Whitbourne
I have experienced similar issues, e.g. putting money into my ISA on 06 April each year, and have done the work around below of backdating to an artificial historical date, though I had not done that with reinvested dividends.
I would note that I deleted the whole portfolio this week as it just went array for some unknown reason (probably my fat fingered typing) and have a project to rebuild once more when I have a couple of hours and a glass of wine after the kids are in bed.
I would note personally this is more a comparison tool for me here, so a good to know where I am doing well or not and how I can do better in terms of the overall portfolio charts My main tool for tracking is an Excel spreadsheet, as I have needed to do this for tax returns etcetera for the various family investments, so that has annual summaries on both income and investment returns, including "not realized" on 05 April every year. This also helps because the different family members have different plans, so mum is retired and only has state pension so this is an income target to fund her lifestyle whilst protecting capital, my sister and myself is grow capital for future income/lifestyle. Then this also allows stress testing against various targets e.g. beat the best Cash ISA, 5% return, better than the "Index".
I have just thought does the "Index" tracking function purely do the valuation or does it also include dividend reinvestment along the way too?
Please please please raise the comments straight to the team via the green button at the bottom right, the more of us that ask for changes the more likely they are for them to happen - Ed et al do respond really well to feedback as noted below, but if you do not ask or say they do not know!
Thanks
Tommy
Folio valuations on the new site don't work for me, these are based on shares held, so if you sell a share for a large profit then that does not show in the valuation. It will work if you don't buy and sell shares in your portfolio. Why is not cash shown in the valuation? My USA one went from +80% to -60% to +100% all in the space of about 2 months this year.
I don't use the new site, one reason being the portfolios.
also if you happen to buy and sell both on the same day (without entering a hrs/mins time) the gain is not shown on the "Today's Gain" result..
I've not tried being accurate over the exact time of the purchase/sale so maybe its me at fault here, but seems odd that 'today' doesn't include transactions dated/closed on that date...
Thanks I did not know that about same day trading, not that I do many of those transactions. But I don't understand why your profit or loss, if a share is sold in not reflected in the portfolio unless you reinvest it.
If you combine your portfolios with a watchlist, which I do with some of them, then they are mess on the new site, you can't switch off empty shares unlike the old site.
I don't use any online portfolio system. For the last 20 years I've tracked my portfolio on Excel, and used a valuation system based on the idea of it being a cost free unit trust.
Any cash in or out buys or sells "shares" based on the current valuation of shares (total divided by number of shares), these can be part shares, there doesn't have to be an integer number of shares.
Not a small-cap of course, but news out this morning that the CEO of Rio Tinto (LON:RIO) and two others are resigning as a consequence of the destruction of ancient Aboriginal sites to make way for an iron ore mine. An illustration I think of the importance of company culture. You can’t possibly control a sprawling empire like Rio Tinto from the top, seeking to know everything. You have to appoint good people and trust them to get their priorities right, including understanding the wider impact of their actions.
Rio Tinto chairman Simon Thompson said: "What happened at Juukan was wrong and we are determined to ensure that the destruction of a heritage site of such exceptional archaeological and cultural significance never occurs again at a Rio Tinto operation. We are also determined to regain the trust of the Puutu Kunti Kurrama and Pinikura people and other Traditional Owners. We have listened to our stakeholders' concerns that a lack of individual accountability undermines the Group's ability to rebuild that trust and to move forward to implement the changes identified in the Board Review.
This is a long-term holding for me. I do think it’s a well-run and responsible company, this was a serious failing and it’s right that the CEO has taken responsibility.
It did get regulatory approval and the agreement was signed by the Aborigine tribes involved. Rather strange.
UK output up 6%, although still below pandemic levels. Might just give the ftse a lift.
Paul, if you have time could you cover the trading statement from DC. yesterday?
Online sales growth was impressive however there is no mention of profits.but the 'strong' trading and a forward p/e of 6.5, could mean it's a stock that's been overlooked.
Hi daz123,
Dixons isn't a small cap, and it reported yesterday, but seeing as I don't have anything of interest in today's RNS from small caps, then I'll check it out for you & report back. Give me an hour or two then the section will be up.
Regards, Paul.
Thanks Paul
My morning smallcap tweet: Super quiet
Tungsten (LON:TUNG) Belvoir (LON:BLV)
Tungsten (TUNG) CFO resigns with immediate effect, for personal reasons. He is thanked. [SP=39.44 Cap=50m]
Belvoir (BLV) founder to place up to 5.7% of co at 150p min. [SP=163.8 Cap=57m]
Monster effort yesterday, Paul! Amazes me how you can get through so much detailed analysis and writing in a day! Much appreciated.
Thanks Kieran! It helps when companies are interesting to look at, and where there is potential to make some money! :-)
Special thanks, Paul, for pulling the night shift to cover Anpario (LON:ANP) which I am glad you like. (And yes, their recent growth is all organic).