Small Cap Value Report (Fri 12 Oct 2018) - CAKE, CAR

Good morning!
Markets have stabilised today, with the FTSE back up 50 points.
Monday is historically the day when we get stock market crashes, so perhaps we are being set up for more weakness at the start of next week!
Patisserie Holdings (LON:CAKE)
- Share price: 429.5p (suspended)
- No. of shares: 104 million
- Market cap: £446 million
Overall, it's a quiet news day on the RNS feed. But not for CAKE.
The Serious Fraud Office has confirmed that it has opened "a criminal investigation into an individual", in response to the RNS by Patisserie Holdings (LON:CAKE) that its currently-suspended Finance Director has been arrested and released on bail.
The Press Association reported yesterday that the company could go into administration as soon as this morning, without an immediate cash injection. So we should get an update very soon. Needless to say, the outlook is bleak. The possibility of a pre-pack administration has been mentioned.
I was curious to learn about the Finance Director's history. This is his bio on the Patisserie Holdings website:
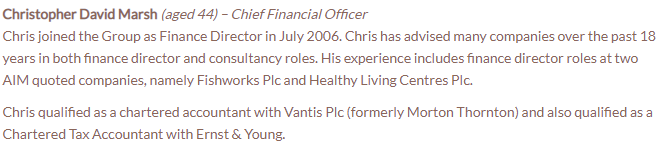
Ok, so he has been involved with the company for 12 years. Is that a bad thing? I wouldn't say so. Although it could be argued that it's unusually long.
But the two other AIM-listed companies he worked for ended badly for his investors.
The seafood restaurant chain Fishworks Plc went into administration, while the loss-making gym chain Healthy Living Centres delisted with its share price close to zero.
There is also a link with Gary Ashworth, who was involved in forcing Interquest off the stock market and into private hands. Paul Scott nominated Interquest as "the small company which seems to worst treat its outside shareholders" and described management as "incompetent, and not to be trusted".
Some links between all of the characters:
- Luke Johnson was the Chairman of Healthy Living Centres with Chris Marsh as FD.
- Gary Ashworth was the Chairman of Interquest.
- Luke Johnson was an investor and a director of Interquest.
- Gary Ashworth was the Chairman of Fishworks while Chris Marsh was FD and Luke Johnson was an investor.
The ties are clearly very deep between all three men.
What does it all mean? Could investors have avoided Patisserie Holdings (LON:CAKE) on the basis of its connections with Interquest and other businesses which ended badly for the private investor?
I don't think so. It's all a bit circumstantial so far.
This quote at the end of Burn After Reading sums up my feeling, and perhaps the feeling of many Patisserie Holdings (LON:CAKE) shareholders who have been burned:
CIA Supervisor: What did we learn, Palmer?
Palmer: I don't know sir.
Carclo (LON:CAR)
- Share price: 81.9p (-5%)
- No. of shares: 73 million
- Market cap: £60 million
This is "a global supplier of technical plastics products". It's quite a lot bigger than Plastics Capital (LON:PLA).
H1 trading was below the Board's expectations. Customer delays are to blame but the planned production had started by the end of the period.
The Board's expectations for the year ending 31 March 2019 remain unchanged, with results weighted towards the second half of the year, as expected.
It seems fair enough to treat this as a "mini" profit warning, as the expected H2 weightings frequently fail to materialise when H1 has been disappointing.
Checking our previous coverage of this share, the company has had a lot of bad news already this year, after a major profit warning in January.
Pulling out the most recent annual report, I'm reminded that customer delays were to blame for a weak H2 last year.
And now customer delays are responsible for more weakness in H1 this year. Perhaps the company needs to start expecting customers to be slow as a matter of routine, rather than being surprised?
I have also noted a lot of customer concentration at Carclo. The 2018 figures were as follows:
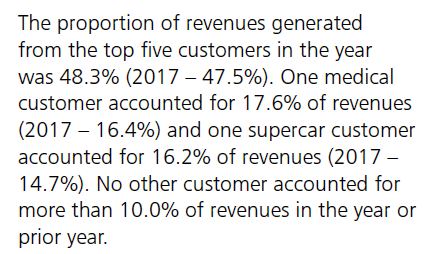
Because of this concentration, it doesn't interest me as a potential investment.
It's trading at a cheap multiple, which I suspect is justified:
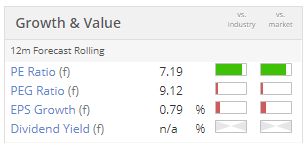
There is nothing else of interest to me today, so I will call it a day. Get your crash helmets ready for Monday!
Graham
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

109 comments
The idea that the FD carries the rap for everything seems a bit far fetched.
The Head of Grant Thornton has also gone.
Hi all,
There's also the small matter of a charge that Patisserie Holdings had for around £5.6 m, created July 2007, in favour of Risk Capital Partners (Johnson and Scalzo as Noteholders) and which was satisfied last week, on 11th Oct 2018...
Risk Capital is LJ investment vehicle...
https://riskcapitalpartners.co.uk/
See
https://beta.companieshouse.gov.uk/company/06070007/charges/srCdbKdtR0JbgbzGAltpgzBKmqg
The coincidence of timing seems unhelpful, on the face of it.
ATB
Bonitbeach
Thanks for the link. There are some interesting articles there. For example:
https://riskcapitalpartners.co.uk/2018/08/26/luke-johnson-my-bad-bets-on-a-junkie-a-drunk-a-serial-liar-and-a-fraudster/
But I'm just saying i don't really think any hats off are due. This is not about altruism.
Absolutely, I didn't mean to imply it was! This is capitalism and he's trying to protect his own interests and in so doing protecting those of others as a by-product. Don't get me wrong, I'm not a big fan of Luke Johnson, and being something of an iconoclast not a big fan of "celebrity" investors full stop. He's been shown to be every bit as infallible as the rest of us and possibly even more so given he should have had full inside information. Maybe just the kind of cold shower he needed...
All the best, Si
infallible?
All we know is that he's admitted he probably took his eye off the ball,
Bit of an understatement!
As others have said, he's also trying to save many jobs in the process. I'm not sure what more he could have done, under the circumstances.
I don't disagree with any of that, and it's certainly a good thing for all concerned that his able to do so. But I'm just saying i don't really think any hats off are due. This is not about altruism.
Peter
Re Patisserie Holdings (LON:CAKE)
Whether LJ's rescue was motivated by trying to minimise the damage to his own fortunes or for
other reasons such as saving his reputation, I applaud the consequences of saving by all accounts, some 3000 jobs.
I have to say hats of to Luke Johnson for sticking in there and digging deep into his own pockets to attempt to save the company.
The cynics will say, well he can afford it, or he must have known something, but I very much doubt the latter.
I sincerely hope he succeeds and he can turn the business around. If he manages to keep it afloat, it will be down to pure determination. After this, who knows, it could go from strength to strength.
I think Johnson's motivation will not be as altruistic as you suggest. As owner of 37% of the company, if he can at least keep the show on the road for £20m, some of which he should get back soon, he almost certainly comes out ajeat - possibly well ahead - of where he would be had CAKE gone to the wall.
I think Johnson's motivation will not be as altruistic as you suggest. As owner of 37% of the company,
I'm not sure this is fair - you can't possibly know his motivation. All we know is that he's admitted he probably took his eye off the ball, he's made a substantial interest free loan and is not taking part in the equity raise, so will be diluted down from 37% to 29%. As others have said, he's also trying to save many jobs in the process. I'm not sure what more he could have done, under the circumstances.
All the best, Si
Giving a short term loan (secured was suggested over the weekend though not confirmed, anyone know?) and letting others put up risk capital in an attempt to stop your largest investment going to £0 from c£165m doesn't sound much like altruism.
Which is not to be expected in any event - he was no friend of small shareholders with Interquest. He appears to be a hard nosed investor trying to salvage his biggest investment and reputation at least cost to himself. As most people in his position would.
Re Patisserie...
An investigation last week found that £9.7m had been spent on two overdrafts set up with HSBC and Barclays which executive chairman Luke Johnson and the board did not know about, Mr Johnson told the Sunday Times.
https://www.hl.co.uk/news/2018/10/15/patisserie-valerie-uncovers-10m-secret-overdrafts-after-nightmare-week?cid=halDM43920&bid=189679726&e_cti=294237&e_ct=T&utm_source=AdobeCampaign&utm_medium=email&utm_campaign=EONRM_Daily_newsroom_15.10&theSource=EONRM&Override=1
So it is blatant fraud and the CFO likely the culprit.
Few notes re Patisserie Holdings (LON:CAKE) - apologies if they've been covered already, but I've been reading a lot from various sites ! ... and I'd be grateful for any corrections :o)
1) The link to Stonebeach at Companies House:
https://beta.companieshouse.gov.uk/company/04396961/filing-history
Patisserie Holdings Plc (which some of us (still) have shares in !)
owns
Patisserie Valerie Holding Ltd - a holding company
which owns
Stonebeach Ltd - which is the main trading company (i.e. the shops) - Two Directors, Chris Marsh and Paul May.
According to the last Annual Report, within the group are 3 holding, 4 trading and 4 dormant companies, all under the Plc umbrella.
2) I thought Directors private addresses were no longer accessible on Companies House, but from the link above, it tells us that CM's addresss is the same as the registered office* when appointed as Secretary in 2014, but gives a residential address when appointed a Director in 2007. A quick search and it seem this residential address was last sold in 2006, so it's feasible he still lives there.
* I've read elsewhere that the Reg'd Office address of Sarehole Road, can quite easily be 'anagrammed' into something else ! lol
3) How easy would it be for an FD to set up another bank account with an overdraft facility, without anyone else being involved, or would it take at least one other Director? Now, if only we had an Ex-FD who we could ask ! lol
I presume, IF this is possible, then all post would be given direct to CM (unopened?), and therefore unknown to other Directors and the auditors. You can't expect auditors to audit bank accounts they know nothing about, and how can this ever be stopped from happening again.
4) I have read a comment elsewhere about the shares resuming trading on Thursday, but can't find any confirmation of this - although I recognise the poster, and doubt he'd post a blatant guess/lie.
Hopefully a Non-Brexit, Non-Cake, uneventful week ahead - How boring would that be ! lol
Patisserie Holdings (LON:CAKE)
Sunday Times reports undisclosed overdrafts of £10m and no cash - LJ unaware - what to believe?
Need what happened here in the public domain ASAP - this can't be something that is sat on for 4 years.
Phil
Would be interested to hear Graham’s views on the article in the FT dated 10th October 2018 called ‘HMRC Files petition to wind up Patissere Valerie’ and in particular the associate company Stonebeach Limited (company number 04396961), which generated 90% of the parent company’s revenue and profits. Also why it needs approx 8 number associated companies to run its organisation. My main interest is to find out what signs we need to look for and where to find them. Thankfully, I was not a shareholder.
Graham mentioned Luke Johnson was involved at interquest. If he has 37% and the institutions just picked up 20-25% more at 50p is there a chance he can buy the company with a low offer?
Despite the short-term cashflow for Johnson I can't see him doing too badly out of this
Absolutely. CAKE had an mcap of £450m or so prior to last week, of which Johnson owned 37%, or £160m+. It's a no brainer, if he has the readies, to pump in £20m or so if he thinks that can keep CAKE afloat, which seems possible, as far as we can tell. Yes, post suspension mcap will be a lot less than £450m, but it's still a far better deal than letting it fold. And if he picks up a few shares at 50p,, and manages to keep the show on road, no doubt getting his loan back, he will have come out of this, financially at least, relatively intact - possible even better off if things go well. Clearly there is a risk that they won't, but he must (or at least should!) know better than anyone what the issues and chances are, so I'd doubt he stands much chance of losing out from the loan.
Absolutely right Peter. This is one very clear example of how the market can be rigged against the smaller private investor.
Indeed.
Despite the short-term cashflow for Johnson I can't see him doing too badly out of this, that's if the underlying business is good, as the share price will inevitably recover, perhaps not to previous levels, there will be a negative premium attached for some time.
The big question is what these secret overdrafts were used for. That makes for something like a near £40m swing (from £29m positive to £10m negative). It could well be that the business is just not viable at all. But in this case, he is still at the front of the queue for money.
The next financial years trading will surely be poor. The other services they provide (catering, custom cakes) will take a hit, and there must be big damage to supplier relationships, and capex will have to take a back seat while everything is ironed out.
The best outcome here would have been that the problem was theft - a one-off, fixable problem. But it looks like fraud, with working capital overstated by c£30m and presumably historic profits by a similar amount.
Re; Patisserie Holdings (LON:CAKE), FWIW, I used to be a restructuring banker at a large bank and I think that Cake have handled this just about as well as they could. Obviously the board didn't have appropriate controls in place but since this has been announced they have put a plan in place and actually raised capital pretty quick. I reckon it all hinged on Luke Johnson being willing to put his hand in his pocket - without that I doubt a fundraising would have been viable. Will be interested to see how it plays out. I have a small holding, having sold down in the summer.
It's not obvious to me in whose pocket Luke Johnson's hand is located. The loan is "will be secured in due course" which sounds a bit too open, he can later devise the security to his advantage... Of course this is justified by the emergency...
I would have thought it obvious that he would want security and that would be on assets of the company.
Burn After Reading! Perfect reference Graham. This is one of those undeniable s*** shows that has come out of no where.
So looks like the company has been saved.....for now....as the placing has raised £15.7m plus the LJ loan of £10m:
https://www.investegate.co.uk/patisserie-hldgs-plc/cake/result-of-placing/201810121718319599D/?fe=1&utm_source=FE%20Investegate%20Alerts&utm_medium=Email&utm_content=Announcement%20Alert%20Mail&utm_campaign=Patisserie%20Hldgs%20PLC%20Alert
Now all we need to do is make sure we are not investing in any instis that supported the placing.
Think holders will be looking at an 85% loss at best. Roughly 29m in EBITDA @ 15x to get to EV - a multiple that was incidentally understated!
If we take that down to 12m as per announcement and us same multiple, we are at EV of 150m, market cap at 140m, and call me crazy, but for some reason, I think if they can get and EBITDA multiple resembling £reach , they will be lucky!
As someone who did manage to spot Globo having been a holder, I am disappointed with the analysis especially in light of some comments above.
Personally, I think more scepticism on too good to be true (on the business operation) as opposed to valuation (a la Globo) maybe one of the many lessons that need to be learned.
PS would appreciate if my analysis wasn't obliterated, or if it is, it is done politely. Perhaps I should not be doing this on my phone at wethetspoons - seriously busy - might be one to consider for those that are forgiving of high debt businesses
I suspect the share price will be extremely volatile when the suspension is lifted. The institutions are likely to hold their position but I suspect private investors may head for the exit to salvage something out of this.
I’ve noted with recent placings the share price falls subsequently. Two recent examples are Burford Capital (LON:BUR) & Sosandar (LON:SOS). Perhaps some of it is market sentiment related but based on the events at Cake, I can’t imagine the 50p will be a floor.
As a holder, if 50p is the floor I would be ecstatic! I'm a buyer at EV below 24m, which is based on 2019 EBITDA of 6m.
They can't continue - this is all over the news - brand damaged - kings road store has been taken by landlord (and seen a few others), their roll out is shot to pieces (which landlord will take on this business without a ridiculous upfront requirement).
Without wanting to be emotional, I say this enters bargepole territory.
Without wanting to be unfair on auditors, iomart has been taken off since they have same auditors, recent listing and again seem to be doing much better than the crowd.
Not sure GT can be trusted - report in FT about a partner leaking the chief executive officer's year end appraisal - downright nasty and disloyal I think (to a company you own, not work for). https://www.thetimes.co.uk/art... And that partner I am sure has if in audit signed off on accounts or some repayment plan or some document with a signature that means nothing!
"They can't continue - this is all over the news - brand damaged - kings road store has been taken by landlord"
Damaged brand?
They've never had so much publicity as per the past few days!
In what way does this publicity damage the brand?! After all they sell coffee, not Banking Services!
As for the Kings Road store disappearing who knows, maybe it was loss-making. If not, they have 205 other stores.
Disclosure: not currently a shareholder
I agree re Patisserie Holdings (LON:CAKE) - the consumer damage will be very limited, especially if the stores stay open. There has been no problem with the product, no one poisoned with dodgy cake or burned with scalding coffee. Outside the financial bubble (which by definition includes all SCVR readers) it will be forgotten in weeks. The Chairman and Board have been complacent to this point but have acted fast to solve the crisis. Be interesting who takes the poor supervision rap - normally, I'd expect the Chairman to go but he owns a third of the business
Luckily, I sold out on price grounds 6 months ago but will happily buy in again if the price is right. But at what price, who knows until a deeper investigation is completed
It's the King Street Hammersmith branch of Patisserie Holdings (LON:CAKE) where the landlord has taken possession of the premises. I expect it's a profitable site - it's been busy when I have walked past. They said they were "forced to" as the tenant was in breach. Presumably the existence of a winding up order triggers a clause in the lease.
It seems other landlords are managing to hold off for now, but it shows the urgency of dealing with the winding up order.
The sad irony is that Luke Johnson, who has a regular column in the Sunday Times business section, had an article in that paper on 9th September entitled "A business beginner’s guide to tried and tested swindles". The article began: "Here is an aide-memoire for those looking to spot the next fraud — or indeed for aspirant swindlers who want to learn the basics of their trade. Surprisingly, very little changes — many of the same tricks were played 50 or even 100 years ago."
To be fair to LJ, he is putting (much of) his c***k on the block with the loan announced just now - it being unsecured in the short-term. Overall you don't get more binary investment opportunities than this open offer, and I will be turning it down, thank you very much. Quite, quite extraordinary.
I will be following closely what Oliver Shah (Sunday Times Bus Editor) and Mark Kleinmann (Sky ditto) have to say on the subject because they are both remarkably well connected in this (murky) field.
Patisserie Holdings (LON:CAKE) - Hi Grumpy5. Unfortunately, from what's been announced so far, you won't be given an opportunity to decline an Open Offer...............
I'm impressed that Luke Johnson appears to have accepted a degree of responsibility - making a £10m, 3Y, interest free loan is much better than could have been. I'm curious as to what "secured" at the end of the para refers to - getting the loan, or getting security over an asset?
I think there is a typo in the placing statement. Surely the profit forecast of £120m turnover and £12m EBITDA based on current run rate must refer to y/e 30/9/18 not 30/9/19? How could they possibly extrapolate a forecast for the next 12 months based on current run rate? Suppliers may require much more onerous terms for one thing until they are out of the wood.
After being up all day looks like the FTSE is flirting with being in the red and the 7000 level again.
A week to forget.
I'm no technician but market opening high, weak close near the days bottom, as I understand is not a good sign for the next day.
Graham's comment re crashes on Monday could be especially pertinent!
On a brighter note, at least one of my holdings is flat this week because their shares got suspended! No cake for those that guess the holding correctly! To think, it was top of the list for adding!
Am very disappointed that the announcement does not detail that this audit is being tendered and forensic analysis of what might be doctored bank statements, hidden creditors and what seems likely, some of those prepayments going to a bank account of an employee, perhaps via a supplier.
As for auditors, having been a financial and internal auditor for way too long, I can assure you audit reports are not worth the paper they are written on. Partners (forget everyone else) are timid especially if you have a personality on the board, basic requirements like bank confirmations (indpendent confirmation of allcounts held and balances are not important enough to delay sign off) and obviously this would not be a required procedure if it is not a statutory audit.
Grant Thornton are not alone in this sham of a profession that holds integrity and ethical standards dear (bigger and smaller are guilty) that exists to deliver tax and advisory work (less independence issues in the small cap world).
I would pay more attention to your own analysis (Graham / Paul / other analysts). If an audit report identified something is wrong, then I can assure you the share price and good analysts will have told you first!
They are trying to save @Patisserie Holdings. Placing and loans from Luke Johnson: https://uk.advfn.com/stock-market/london/CAKE/share-news/Patisserie-Holdings-PLC-Trading-update-and-propose/78454184?xref=newsalert
Better news than expected. Have to wait and see if works
In June 2003, Luke Johnson sold Pizza Express too cheaply. I, and perhaps many former shareholders, have not forgiven him. If he has lost money in this debacle we will not weep for him, only for his fellow shareholders.
I avoided CAKE because he was involved. If he now gets the assets in an advantageous administration deal it will be a clear warning for all investors to buy a longer barge pole!
Judging by experience the board in general will not meet the bank, and the auditors may seek some signed piece of paper but will arrange no meetings with the bank officials. I guess fraudsters will always have a way to stall such interventions, but the fact that they never happen, just makes for one less barrier for the FD or another to be the sole rep of the company with the banks.
I understand the Board collectively might not meet with the Bank, but the CEO and a 38% shareholding Executive Chairman of a plc would normally meet with the Bank from time to time, sometimes socially as well. The Bank would not pass on the opportunity to stay close to a serial entrepreneur with an investment company and a stable of businesses.
Agree entirely though, that if fraud is the motive then 'normal' goes out of the window. Too soon to say, but it all sounds fishy!
Further developments for Patisserie Holdings (LON:CAKE) including a proposed placing:
https://www.investegate.co.uk/patisserie-hldgs-plc--cake-/rns/trading-update-and-proposed-placing/201810121544169469D/
“Historical statements on the cash position of the Company were mis-stated and subject to fraudulent activity and accounting irregularities as set out in the announcement of the Company on 10 October 2018. This activity and the irregularities are, in the Directors view, also likely to have affected the historical financial statements of the Company. The Directors estimate that based on current run rate information available, annual revenue and EBITDA, before exceptional one off costs, for the year ending 30 September 2019 could be approximately £120 million and £12 million, respectively.”
There is a proposal to re-audit the financial statements. So what exactly did Grant Thornton audit considering this is a material error and fraud?
There is a placing to take place at 50p to raise £15m.
Patisserie Holdings (LON:CAKE) - it would be nice to think that existing shareholders being given the chance to "help" via an Open Offer at the same price, or a later Rights issue.....
Goodness, that RNS is an absolute rout.
Why would anyone subscribe to a placing even at that reduced level? It seems that the business case was based on lies.
Patisserie Holdings (LON:CAKE):
so it was historic mis-statement of cash - auditors should be hammered over this.
Patisserie Holdings (LON:CAKE) :
Interesting that their Investor Relations website and accounts have no photos (mugshots) of the directors.
Nice work Graham. Fascinating mystery from an accounting / business perspective, but devastating for the stakeholders. It will all become clear in due course, but I do wonder what part the Bank also plays in this. People are rightly challenging the Board and the Auditor, but to go from £28m cash to Nil as suggested would surely raise questions between the Bank and the Board as well... or did they never meet? I know it's different when the Company is indebted to the Bank, but surely they reviewed the facilities from time to time - with someone other than just the FD.
Nicely written article Graham, given the volume of contributions on Patisserie Holdings (LON:CAKE) there should at least be a whole separate thread on it: in aggregate there is enough data and viewpoints to write a great case study. Somewhere to concentrate these would make sense. I watch vicariously though I have had my fair share of delistings over the years.
Your "6 degrees of separation" approach to the management is hugely relevant and something that quants and factor investing can't model: the people. Buffett does bang on a lot about management and the old adage of a bad company and good management, albeit in reverse, comes to mind.
Maybe we need a rogues gallery of barge-pole management : the litigation one would be wonderful
A barge pole list is an excellent idea, for companies, directors, auditors etc.
For way too long shareholders have been shafted, defrauded, and interests placed secondary behind and by greedy boards, who either have cozy personal service contracts with their own companies, are purely incompetent, commit fraud, have ridiculous performance incentive plans etc etc. or where there are so many red flags, like being registered overseas and not having meetings in the UK etc.
Of course, it would have to be built around being someone’s point of view and nothing liable on it. But I’m sure many of us have dabbled in stocks, where for example, a rather portly antipodiean is on the board and significant alleged ramping occurs etc. Or, personally, I held shares in Silverdell, where all’s well one day and the company is suspended the next and then bust. In fact I seem to remember that they were unraveled in a similar manner to Patisserie Holdings (LON:CAKE) with a court order against a subsidiary...
If he was responsible for taking the cash out of the business, I very much doubt he would've been released on bail. He'd be on the first plane to Brazil, as jonesj suggested above!
I guess either current assets have been overstated, or current liabilities, understated. What the precise nature of the misstatement is anyone's guess, but has clearly happened "off balance sheet".
A future accountancy exam case study in he making...
If (hypothetically) anyone was to suddenly just help himself to all of the companies cash, shouldn't he also have the good sense to move to Brazil, or wherever does not have a suitable extradition treaty these days ?
There was some issue where money was mysteriously moved off shore at a Japanese camera maker. The directors fired the whistle blower & remained as directors. No doubt a somewhat different case, but I would like to think it couldn't happen here.
Two cases I was previously close to where a large sum of money “disappeared” in very short order due misappropriation/misbehaviour by a single person in a company.
One was due to a senior business manager being blackmailed and taking funds out (via sale of company assets at an undervalue to his own private business) to cover a substantial gambling debt (and avoid a concrete overcoat from alleged links to the mob). The other was a Group Treasurer who played fast and loose with some FX derivatives contracts and blew up the company’s apparently healthy cash position when he took the view that a hedging should be a profit centre (and lost, big time). In both cases the cash was irrecoverable and ended badly for shareholders (although in the former case it was not terminal).
That the individuals could act without the system halting their activities was a result of poor oversight/internal controls but not necessarily the fault of the auditors given the rapid escalation of both “frauds” as the perpetrators panicked and took the view that a white collar crime punishment was preferable to the alternatives. In both cases, the individuals were very self assured and domineering of colleagues etc., but perhaps not quite as smart as they thought they were. Time will tell, but it may not simply be planned embezzlement for long term personal gain as the chances of getting away with the loot permanently and without getting caught are remote.
Gus.
Re 'Burn after reading' - a little earlier in the dialogue
'it's a clusterf**k'.
Thanks Graham. I keep learning something new and have been investing since 1986. Thanks to your excellent detective work we now know another thing to check before investing. For small company and AIM shares, check out the previous record of the finance director!
Luckily I don't hold CAKE, but have held in the past and follow events. Sympathies to those who hold CAKE. . It's different to stubbornly sticking with a Company where there were plenty of warning signs and which over bullish investors chose to ignore. CAKE news came out of the blue.
Bandits everywhere..........................especially in the boardroom....................reminds me of when i worked for a profitable £100M turnover UK company that was bought by an American fund & went bust in less than 3 years...........i seem to remember they brought in a new FD & just a few months later we went from always having cash to never having cash..............but it wasn't his fault of course..................
CAKE is clearly a similar case to Globo, also audited by Grant Thornton and where the cash claimed on the balance sheet had disappeared. Regulatory authorities still pursuing that case I understand. Auditors should always independently verify the claimed bank deposits but there is at least one example I remember where they were given fake information. I would be very surprised if the alleged cash disappeared since the half year, or even the previous year end.
According to the BBC: 'it is also understood that Mr Johnson is not in a position to personally provide the cash needed immediately'.
Could it be that this is much worse than expected? Or somehow Johnson is unable to for another reason? Would have thought only working capital was needed as supposedly the business is profitable.
Given Johnson's involvement in the screwing over of Interquest shareholders, in my view he is unlikely to come to shareholders rescue here. Much more likely, I think, that he let's it go bust and then picks up the assets in a pre-pack.
If Luke Johnson is allowed to pick up the company's assets cheaply in a pre-pack administration arrangement then that would be a huge injustice. Rewarded for his own lack of oversight.
If Luke Johnson is allowed to pick up the company's assets cheaply in a pre-pack administration arrangement then that would be a huge injustice. Rewarded for his own lack of oversight.
Yes, I totally agree, but who is going to stop him? It's going to look like a very easy arrangement to the administrators - he's already there and he presumably has enough cash, (or more likely ability to borrow against the assets he's buying!) to settle a deal quickly. Easy in and out and fees earned. Everyone goes home happy apart from shareholders, and probably a lot of creditors.
Paul has suggested on Twitter that the current liabilities are very small for a company this size and especially when compared with the current assets. Could he just of been pushing the costs and ever increasing levels in the future periods and so whilst the cash was there the liabilities where even greater?
Precisely. Liabilities would have been understated and now they have come to light there is insufficient cash to pay them. Much more likely than the CFO having stolen £20M plus.
Patisserie Holdings (LON:CAKE)
SFP Probes Unnamed Patisserie Valerie Individual
LONDON (Alliance News) - The UK Serious Fraud Office said Friday it has launched a criminal investigation into an individual related to Patisserie Holdings PLC.
The government agency, which did not provide any specific details on its probe, said the decision to investigate came after an earlier announcement by the company stating the arrest and subsequent bail of its suspended Finance Director Chris Marsh.
Marsh was suspended from his role, after the the cafe chain discovered "significant and potentially fraudulent" accounting irregularities. The company, however, has not yet accused Marsh of any wrongdoing.
The company, which owns the Patisserie Valerie brand, in a statement on Wednesday said the irregularities "may lead to a material change in its overall financial position". It also revealed a winding up petition for its principal trading unit Stonebeach Ltd for GBP1.1 million owed to the UK tax department.
The company subsequently warned that it would be unable to trade without "immediate" funding.
"Without an immediate injection of capital, the directors are of the view that there is no scope for the business to continue trading in its current form," Patisserie said on Thursday.
Shares in the company are currently suspended.
Or I wonder if he was covering up a cyber attack which drained the accounts.
Patisserie Holdings (LON:CAKE) - I have witnessed a case where because of mental issues a senior person who was well qualified and previously doing a good job started to pretend that various matters had been dealt with when they had not. He did not benefit in any way himself. Without knowing any details it is perhaps too early to suggest that the CFO has taken any money for his own benefit. Could be just a cover up for poor trading or his own incompetence.
@Edinburgh Investor #21
"Re Patisserie Holdings (LON:CAKE) Are companies usually insured against this type of fraud? "
As far as I'm aware, if you can insure against 'fraud', then it doesn't include people like Directors. Something to do with them being the Insurance holders/beneficiaries and also the perpetrators.
Re Patisserie Holdings (LON:CAKE) Are companies usually insured against this type of fraud?
Interesting question as there's a possibility of liability and even charges for the other directors if the CFO has taken straight cash himself as there is a lack of control on a public company. They escape liability/charge if the CFO has used some chicanery away from their immediate oversight.
However, whatever he did its seems highly unlikely it is possible to steal a large sum without collaboration somewhere.
Also, very odd are the reports that it all happened recently. Usually this sort of theft is slow. If its all been done suddenly then I wonder if there will be reports of mental health probs or even something like a form of blackmail/coercion on CFO?
All 100% speculation plus never looked at Patisserie Holdings (LON:CAKE) seriously
Sorry to disagree with the comments here on the subject of Patisserie Holdings (LON:CAKE), but surely the most likely explanation is the money was never there in the first place? It is possible the finances have been misrepresented for years and eventually the cold hard reality of cash makes that untenable. Just on Bayesian principles this is much more compelling than a large sum of money having been purloined in a few months.
I disagree with your conclusion. Cash balances tends to be harder to manipulate than paper profits. If your assumptions are correct, Grant Thornton would have had to screw up auditing for years.
The cash theft theory, however, only requires a sudden transfer of cash which, I would wager, would be easier to get past the auditors. The entire situation seems bizarre because neither myself, or many other investors including Graham and Paul, spotted anything dodgy in the accounting and again, I'd expect some sort of red flag if this was caused by long-term manipulation.
This evidence leads me to believe a cash theft is the most likely cause. We'll know within a few days either way so I guess this is all academic, especially with the shares being suspended.
Grant Thornton screwing up audits for years would be business as usual.
In terms of cash verification, Grant Thornton should have verified balances directly with the bank. This is standard procedure. However, this would only verfiy the balance at the half year and year end point. This would be independent corroboration. If cash was taken out after the period end, then that would not have been detected. Also, if the cash was taken out prior to the period end and recorded as a “legitimate” expense then it would imply collusion between two or more people as an override of controls would have to have taken place.
One thing to note is the winding up petition that was placed in the Gazette by HMRC. The liability would have related to a prior period and unlikely to have occurred in recent months as it takes time for things to go through the system. The amount concerned would be material in the context of an audit. Grant Thornton should have flagged this if it occurred prior to 30/9/17. There may not have been a full audit at the half year stage.
Nevertheless, the whole audit model is flawed: the audit fee is fixed upfront and the trainees will be on-site doing the grunt work. With a fixed fee, where is the incentive to dig deeper and investigate any potential issues?
"Nevertheless, the whole audit model is flawed: the audit fee is fixed upfront and the trainees will be on-site doing the grunt work. With a fixed fee, where is the incentive to dig deeper and investigate any potential issues?"
This has been mentioned a couple of times, and is nonsense. The company should obtain a quote for the annual audit, and this quote will be based on an audit that does not identify issues requiring further work. It will be understood by both parties that should the audit uncover anything requiring additional verification etc - that the audit fee will rise to accommodate this.
I appreciate that while there is a fixed fee that is quoted and there is scope to alter this based on work performed, it’s very rare an auditor will increase the fee based on suspected fraud. The whole premise is based on allocating time to sections of the Balance Sheet predominantly and detailed analytical review of the income statement. If there is excessive time being spent on a particular section it needs to be explained. Therefore, at the audit planning meeting the expectation is set about time constraints.
It may we’ll be different at Grant Thornton, but the business model dictates that in order to make money, the audit requires to be performed within timescales. And by allocating either graduates or 2nd year trainees to do the bulk of the grunt work, then management within an organisation can convince an auditor that all is above board.
This is a good point. It seems like a viable explanation considering that you'd need to do these payments around the year end - perhaps this was how the whole thing was uncovered? Either that or there are subsidiaries not consolidated into the Group accounts that have massive overdraft balances.
Either way, Grant Thornton would be well at fault, this is standard stuff you'd need to look for in any audit. All that will happen to Grant Thornton is a slap on the wrist, no doubt. You'll hear about them getting a fine of something daft like £160,000 in the year 2023, it's usually the way these things go.
Fined?
Here's the result of an "audit" they did earlier: Globo
Perhaps what we should all be more worried about is the regulation of accountants by accountants; it appears unfit for purpose. The complete lack of contrition by any of these firms or the individuals directly implicated is shocking. They just roll with the powder puff blows and carry on as before.
If it is going to cost a bit more for auditors to do a proper job using appropriately trained and experienced staff then it is a price, as shareholders, we should be willing to pay.
They take these things more seriously in the US. Arthur Anderson & Enron
Bonitabeach
CAKE - It seems as if the CFO must have stolen some cash to be arrested or done something criminal that is now blatantly obvious. Directors normally don't get themselves arrested without considerable investigation.
I find it hard to believe that anyone could steal over £20M cash and be sat in their office hoping no one finds out. Perhaps it is the result of a losing speculation. Although they mentioned having less cash than they thought I would have expected this was mainly due to liabilities having been hidden which have now come to light the payment of which would wipe out the cash balances.
Patisserie Holdings (LON:CAKE) - I agree - would be interesting to hear the FDs side of this story. To steal £20m - in whatever form - from a relatively small company with £20m in cash and hope to get away with it? What was his expected outcome? Beggars belief. Hopefully they get a solution sorted that saves the business and minimises the impact on shareholders and employees.
Anyway, their cakes are nice but a bit fancy for me. Prefer a Belgian bun or coconut finger from Greggs!
Only speculating as there are no details and I'm wearing my poker player's hat here, but what would be the jail time for a £28m theft, assuming he was clever enough to hide it away somewhere... Bitcoin perhaps? His actions might make sense on a risk reward basis. 28 divide by 7yrs? = £4m a year. Not a bad return.
EssexPete
Where there is evidence in a case before the Crown Court that the offender has benefited financially from his or her offending, the court must consider whether to make a confiscation order i.e. any assets stolen will likely have to be returned.
In addition, fraud indictment carries a maximum penalty of 10 years in custody.
Fair point Howard, but seizing assets by court order will only work if they can be found. Likely to be some horse trading with length of sentence and return of some of the funds. Agree with Andy, it is more likely to be misrepresentation that's got out of hand over a period of time.
Last post, as this is quite distressing.
I sold my shares in PV recently as they were looking expensive; my thoughts on the debacle are
Lee Ginsberg the NED in charge of the Audit at Patisserie Valerie (CAKE) has been NED in charge of Audit at Mothercare, Softcat, Trinity Mirror and On The Beach – surely anyone would say he is “overboarded”. How can he cope with all these roles especially if all reporting at same time of the year? It looks like he has taken his eye off his responsibilities at PV – has he been providing the challenge to the Executive that a good Non Exec should?
PV’s Board has not been refreshed since Lee Ginsberg joined in 2014 so the Board have probably been rather cosy and perhaps Group Think set in. This certainly can lead to complacency and in a rapidly growing coming this can be dangerous. They have no diversity, no women on the Board which is strange since a high proportion of their customers are women.
The PV Board was fit-for-purpose when they had a market cap of £40m and they have certainly proven a model AIM company in terms of growth, profits and share performance. However, I suggest their Board has not been fit-for-purpose when they were expanding to a market cap of £448m.
Some pressing questions:
• Should a company like PV not have an Independent Chairman rather than an Executive Chairman who owns 38% of the company? He also has lots of other business interests so has he taken too much for granted with the company’s controls?
• Has the Board suffered from “Group Think” since they have not refreshed it since 2014?
• Why do they have no diversity on their Board?
• They haven’t carried out annual Board Reviews (as per the Governance Codes) – would this have helped identify the now apparent problems?
• Have their two Non Execs been too busy with their other interests to keep their eye on the ball and challenge the Executive?
The PV Board clearly needs a shake-up although one could conclude that the horse has at least partially bolted.
Fraud stories are usually more tragic then a simple 'expecting to get away with it' as they usually involve some sort of financial distress - gambling, leveraging, making up for bets or investments that have gone wrong, for yourself or for family, there are many possibilities!
When you read about these stories, its usually a matter of someone trying to cover things up for as long as they can, rather than thinking they will genuinely get away with it.
Purely speculating but if its a cash grab situation, I'm sure there's more to the story here and it will be tragic to read about.
According to the FT, the Patisserie Holdings (LON:CAKE) CFO "had been arrested on suspicion of fraud by false representation and released under investigation, without charge"
Interesting.
Is it business as usual at their shops?
I assume that the online business (cake ordering/catering) must have come to a standstill.
Re. Patisserie Holdings (LON:CAKE) , apparently they’re doing a new line in porridge ..... I’ll get my coat.
Gus.
Gus, porridge with a drop of whiskey perhaps, to improve palatability or steady the nerves? :)
If I was a https://www.stockopedia.com/share-prices/patisserie-holdings-LON:CAKE/ supplier I would be very nervous about continuing to supply them ... with (relatively) short shelf life of raw materials it strikes me as the sort of manufacturing and supply chain business that could easily grind to a halt ...
Worrying times for all ... not least those innocents at the sharp end of the business
Interesting developments: the CFO appears to have committed a significant fraud and potentially siphoned all the cash since the interim results. Was he acting alone or were others involved? It also suggests that he was not managed and/or he was portraying a different picture to the Board.
Here’s an extract from today’s Times: “It is understood that earlier estimates of a £20 million black hole understate the position, with experts now suggesting that the entire £28.8 million net cash balance declared at its interim results in May may have disappeared. The deficit raises difficult questions for Grant Thornton, which was paid £230,000 for auditing the company in 2016 and last year.” There was also mention of a rights issue: would shareholders consider stumping up more money since its become apparent how ineffective the Board have been?
More details will come out in due course. But as investors we need to learn the lessons of what went wrong. In addition, without hindsight was there anything that appeared as a red flag? Also, although the likelihood is slim, but can we be sure that this could not happen in other companies regardless of whether they are listed on AIM or the main market?
Sometimes you can't have your CAKE and eat it LOL
I liked their business, but never invested because it was too expensive.
The only red flags were that perhaps their story was too good to be true, and how the cash kept rising since 2015 despite dividends and new stores.
Although having been in a few of their shops I would have thought they were doing well. Revenue of £114m equates to something like £500k p/a per shop across its brands, and that is feasible enough.
Latest RNS from Patisserie Holdings (LON:CAKE)
The Company has been made aware that Chris Marsh, who is currently suspended from his role as Company Finance Director, was arrested by the police last night and has been released on bail.
This goes from bad to worse. I was tempted to invest at one point but never did because I tried out a couple of branches and didn't enjoy the cakes as much as I expected to. Lucky escape! My commiserations to anyone who holds these, it came completely out of the blue.
I don't suppose you could please cover Pagegroup (LON:PAGE) (after the recent update) as it's a quiet Friday...?
Hi andrea... thanks for the request this morning but I'm afraid I try to avoid recruitment companies these days. All the best. G
Produce Investment - announced final results today. Looks like a mixed bag with plenty of adjustments. Dividend pending buyout offer.
My morning smallcap tweet: Middle East Symphony dissonance.
Symphony Environmental Technologies (LON:SYM), Carclo (LON:CAR), Veltyco (LON:VLTY)
Symphony Environment (SYM) warns FY rev only 6% up, broadly in line with market expectations. Guides FY earnings (pretax?) only £0.1m. F/C £0.5m. Blames timing of orders placed by distributors in the Middle East for d2w oxo-biodegradable plastic. It expects (hopes?) "an improvement in government enforcement actions and this, combined with an increase in the direct sales force of our Middle East distributors, is expected to generate a substantial increase in sales volumes."
Carclo (CAR) guides FY in line with board's expectations despite H1 underperformance at Technical Plastics. H2 willbe great due to "the full effect of the new programmes, expected customer timings on projects and the anticipated improvement in margins at Wipac in addition to cost saving initiatives, ramp up in production volumes and expected higher design and tooling profits in Technical Plastics." Lots of fingers crossed there.
Veltyco Group (VLTY) CEO leaves after only 6 months. She is thanked!
More volatility overnight. FTSE 100 futures hit a low of 6921 at one point but currently back up at about 7042 (36 points up on last night’s close). Dow has currently recovered about 400 points of yesterday’s 500 point fall and Asian indices seem to be nudging into positive territory. Whether it’s a dead cat bounce or the October market funk finally working its way out of the system remains to be seen.
Gus.
The CNN Fear & Greed Index hit an 'extreme fear' level of 5 yesterday:
In the past 10 years, this level has been reached only 12 times:
The S&P500 bounced strongly on 11 of the 12 occasions after the CNN Fear & Greed Index reached its current level of 5.
https://money.cnn.com/data/fea...
I track that daily, when it is this low it is typically a good buy signal......typically
dscollard
As you can see from the back-test engine, the past 10 years experience has been quite favourable.
It's been like tossing a coin 12 times & the coin being in your favour 11 times with an average 9.7% return, & a 2.8% loss just once
(I looked forward 10 weeks on each of the 12 occasions the CNN Indicatior hit the 'extreme fear' level of 5)
nice expected value on that: what platform do you use for back-testing?
Dscollard
The data provider is SentimenTrader.
Their database allows backtesting for Equities, indicies, sectors, bonds & commodities across a large array of risk/sentiment indicators.
Their tagline is 'analysis over emotion'.
Highly recommended.
https://sentimentrader.com
Thanks Howard, very useful and much appreciated. I have reservations on back-testing unless one is wholly systematic and almost algorithmic in execution: the psychology of skin in the game can't really be modelled. Though by the tag line I am guessing that is kind of the point of it .... I'm a student of Mark Douglas' stuff though being a practitioner is always a challenge.
Dscollard
I wouldnt be surprised to learn that Mark Douglas was a subscriber to SentimenTrader
He does after all stress consistency & tilting the odds in one's favour
@ Howard, sadly and prematurely he died earlier this year, believe his final book is being finished by his assistant Paula Webb. The Disciplined Trader and Trading in the Zone are two perennial re-reads of mine.
Howard
Thank you for sharing the Fear & Greed Index with us. I think it will be very useful & have incorporated it into my processes.