Small Cap Value Report (Fri 13 August 2021) - BOTB, MCLS, VLG

Morning all, it's just Paul here, with the SCVR for Friday.
Today's report is now finished.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to cover trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Agenda -
Paul's Section:
Best Of The Best (LON:BOTB) (I hold) - Brutal profit warning, with profit guidance for FY 04/2022 lowered by 62% to c.53p. Expect a big fall in the share price today.
Mccoll's Retail (LON:MCLS) (I will hold - applied for placing) - equity fundraising at 20p announced last night, with interim results. This is a special situation - financially distressed and high risk. However, I like the turnaround plan, to re-brand stores as Morrisons Daily, which has worked well in early trials.
Venture Life (LON:VLG) - profit warning, and broker forecasts reduced. Chinese distribution deal sounds like it could be dead in the water. Too much uncertainty & too many moving parts for my liking.
Paul’s Section
Best Of The Best (LON:BOTB)
(I hold)
1525p (pre market open) - market cap £146m
I’ll rush to get this out before 8am, as this share is widely held by readers (and by me!)
Background - briefly is that this supercars competition company went entirely online (it started in UK airports), and started delivering stellar growth. The shares were a big multibagger. However, more recently the gloss came off BOTB shares when management sold about £60m of shares in a secondary placing at £24 per share, after a lengthy period when the company was up for sale. About 2 months later, a disappointing trading update hit the share price, which had settled around £15.
Trading Update (profit warning) - today
Best of the Best PLC (LSE: BOTB), the online organiser of weekly competitions to win cars and other lifestyle prizes, provides the following trading update for the 15 weeks ended 8 August 2021.
This is the start of FY 04/ 2022.
The company had previously (on 16 June 2021) said that trading had softened, since lockdown ended on 12 April 2021.
Guidance slashed - a lengthy explanation is given, but the key point, and it’s horrible, is that profit for FY 04/2022 is now expected to be 57% down on FY 04/2021.
Actual EPS last year (FY 04/2021) - 122.5p
New guidance for this year (FY 04/2022) - 52.7p
Finncap’s last note was forecasting 142.4p EPS for this year. The RNS says new guidance is 62% below market forecasts (there’s only one forecast, I think), which arrives at 54.1p, very close to the 52.7p figure above.
EDIT: revised forecasts have just come through from Finncap, as follows;
This year 53.3p
Next year 64.1p
Its revised target price is 1400p - which is certainly not realistic in the short term, but could come about if trading recovers in due course, who knows? It seems that BOTB is a lot more unpredictable than we realised.
What PER to use? I'm leaning towards 15-20, implying a valuation of 800-1066p, that's what I think it's now worth for the time being. Longer term, who knows, that depends on whether trading recovers or not.
PatrickL makes a very good point in the comments below, that revenue is forecast to only drop from £45.7m to £40.0m (still more than double pre-covid level), but it's the operational gearing that's the killer here. that leads to a forecast 57% drop in profitability.
End of edit.
Cash balances - over £6m at 12 August 2021, so no issues with solvency or liquidity.
What’s gone wrong? A lengthy explanation is given, but it boils down to reduced customer demand (people spending money on other things since lockdown ended), and higher marketing rates resulting in lower marketing activity.
My opinion - this is a stinker, much worse than I was expecting.
Unfortunately, I think the share price probably halves today, to £7-8 (am writing this at 07:38). I've already decided there's no point in trying to sell, because there won't be any buyers until it's found a level much lower, this share tends to be very illiquid.
Assume the brace position.
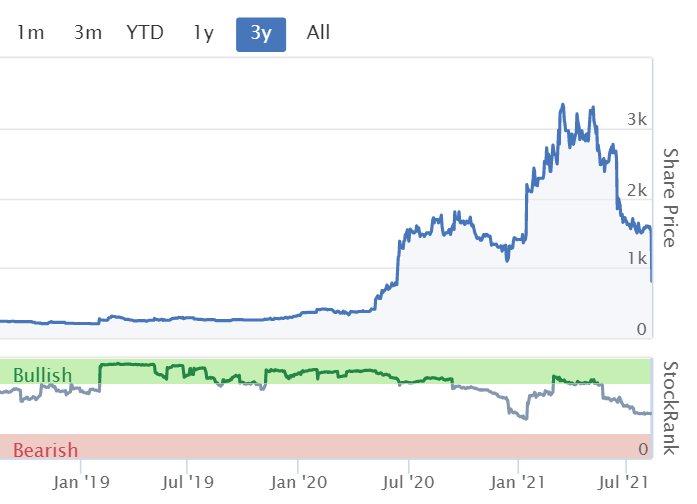
What a grim chart. I'm astonished that it has unravelled so quickly. All the numbers looked so good just a few months ago.
.
Mccoll's Retail (LON:MCLS)
(I’ve applied for a small amount in the placing)
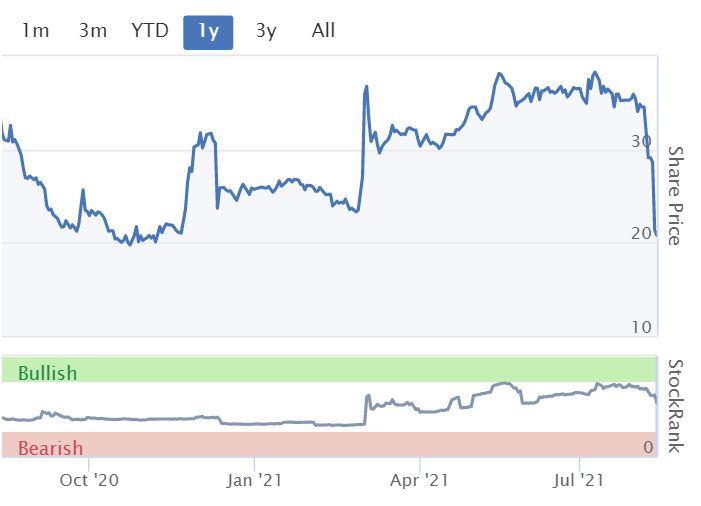
Share price: 20.75p
No. shares: 115.3m now, 290.3m after placing/open offer (assuming full take up)
Market cap: £24m before, £60m after fundraise
Fundraising - many thanks to my friend William who flagged up this fundraising to me last night, which was announced at 15:50. So after winding down for the day, I cranked back up again and spent yesterday evening going through the numbers.
Here are my notes -
- Placing to raise £30m, 150m new shares - book build successful, announced this morning.
- Priced at 20p - a deep discount to the share price of c.35p before news leaked
- Open Offer for up to 25m new shares to existing holders
- Share count will rise by 152% to 290.m - so a highly dilutive fundraise
- Purpose - reduce gearing, and fund rollout of site re-branding to Morrisons Daily
- CEO putting in £3m, a serious amount of money, which I like a lot
Interim results - not good, the balance sheet looks really weak, hideous actually, with negative NTAV of £(144)m. Although supermarkets do have favourable working capital - i.e. receiving customers cash before having to pay the suppliers. This £35m fundraise will only eliminate about a quarter of the balance sheet NTAV deficit, so further balance sheet repair is needed. Net debt is £111m (excl. leases) which is too high. Covenants are tight. So this fundraise is from a position of financial distress.
Like for like sales are positive +1.0% for H1, on top of +8.3% in the prior year, so some signs of life there.
Supply chain disruption sounds like a growing problem, shortage of drivers, could derail H2 trading, the company says.
Margins fell, but have since partially recovered.
Morrisons deal - this is the interesting bit. It’s a very odd situation, but McColl’s has started re-branding some of its sites to Morrisons Daily, and it’s working well. This is what makes this share potentially interesting. Each rebranded site costs about £60k + £30k for more fridges, which enables the format to move away from newsagent/booze& fags led, and become fresh food-led, with prices not much more than supermarket. These are local, convenience stores, which are being turned into mini Morrisons. What’s the betting then, that Morrisons might buy MCLS at some point? That seems the logical end game.
Wholesale supply agreement with Morrisons runs until Jan 2027.
Rebranded sites are generating a good uplift in sales & profits, with a fairly good 2-3 year payback - so this strategy looks worth pursuing.
My opinion - this probably won’t be the last fundraising - MCLS says more funds will be needed, and the balance sheet looks awful to me.
I went through the interim results, also published last night, and they’re not good. EBITDA gets swallowed up by heavy finance charges, and £1.8m p.a. pension deficit recovery payments. Plus of course business rates will be kicking back in again, which saved £5.8m just in H1, a material additional cost coming back in. So the company is facing cost headwinds.
I see this as a high risk, special situation. However, the upside from converting stores to Morrisons Daily is fairly clear. The banks have relaxed a bit, as part of this deal, so potential insolvency looks less of a risk.
In my view, there’s potential upside here to maybe 40-60p if the bull case plays out, that’s my target, based on analyst forecast of profitability once the sites are refitted to become Morrisons Daily. The strategy looks sensible to me, with proven uplifts in performance from converted shops. The CEO putting in £3m personally is another big sign of confidence in the strategy (mgt already owns 10.5% before the fundraise).
Overall, I like the occasional punt, where there’s a logical turnaround plan. Hence I rather impulsively rang my broker last night after the market had closed, asking him to see if he could get me into the 20p placing, not really expecting anything to come of it. Anyway, this morning I got a message to say I’d received 70% of my order. So in a couple of weeks, I’ll end up being a MCLS shareholder - hence why that needs to be disclosed here, even though I don’t technically actually own any yet.
Quite an interesting special situation, but now its funding position is somewhat improved, and the share price has plunged, I think it’s a more attractive investment idea than before. Definitely not for widows and orphans though.
As we saw with Revolution Bars (LON:RBG) (I hold), small caps that need to raise cash from a position of weakness, can result in brutal dilution & losses for existing holders. Hence why it’s usually best to avoid these type of stressed situations until after the new funds have been raised and hence risk reduced.
There are lots more companies out there which obviously have overly indebted balance sheets and need to raise fresh funding. They’re very high risk, and people need to wake up to how risky some of the shares in your portfolios might be. It only takes a previously co-operative bank manager to have a fit, and demand an immediate fundraise, and before you know it, the share price goes into freefall.
Institutions don’t seem as willing to support fundraises now, and if it’s a challenging situation like this one, then they demand a deep discount as the price for their support. Existing holders then have a permanent loss, unlikely to be recouped, unless you greatly increase your position size at the new lows, which you may not want to. These things are very tricky, but can be easily avoided by just focusing on the balance sheet position, and avoiding companies with a funding need.
.
.
Venture Life (LON:VLG)
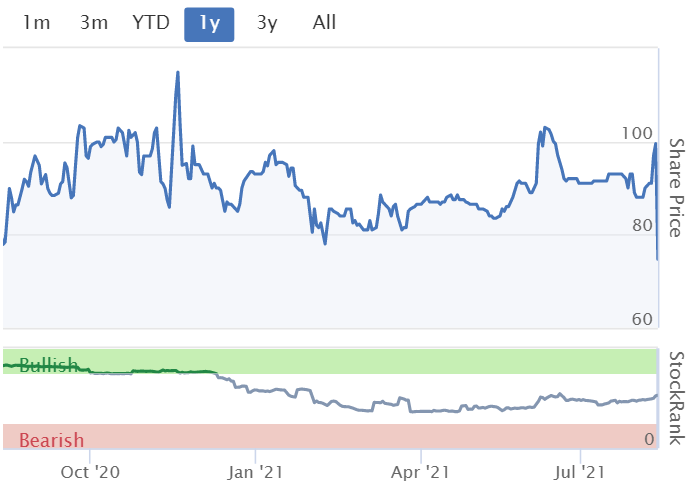
74.7p (down 25%, at 10:44) - mkt cap £94m
Trading Update and Progress on Recent Acquisitions (profit warning)
Oh crumbs, another profit warning, bad luck to holders here. You can’t avoid all profit warnings, because the future is inherently unpredictable, so there’s no point in getting emotional about it. Accept this as part of the process - some investments do well, others disappoint. We have to take it all in our stride, and crucially learn from each mistake, and try to spot similar things in advance in future. Easier said than done, I know!
Venture Life (AIM: VLG), a leader in developing, manufacturing and commercialising products for the self-care market, provides an update on trading and the acquisitions of BBI Healthcare Limited ("BBI") announced on 7 June 2021 and the Helsinn Integrative Care Portfolio ("HICP") announced on 6 August 2021.
H1 revenues (Jan-June 2021) expected to be £13.8m, down 18% on H1 2020
Reasons? “Much lower sales of hand sanitising gel”, and reduced sales to Chinese partner
Everything else showed overall growth of +9%
Covid had an impact in H1, but “encouraging signs” of recovery, esp in UK retail
Acquisition of BBI added £1.1m to H1 sales, despite only being c.1 month from acquisition - sounds like this will be material to full year results then, if we annualise it to c.£13m revenues. This was a big acquisition, costing up to £36m, so should materially boost future performance I imagine. VLG says the acquisition is “progressing well”, cost synergies extended.
HSG - sales dropped to almost nothing in H1, and “unlikely to be anywhere near the 2020 levels in the future”
Dentyl sales to Chinese partner also negligible, at just £0.2m in H1 (see below)
There’s more detail in the trading update, which I won’t get into, because I've already lost interest in this share.
Chinese partner - this sounds pretty bad to me - it might be wise to remove any contribution from this sales channel from forecasts, to be on the safe side -
In addition, whilst we have also seen some sales to our partner for Dentyl in China during the first half of 2021 (£0.2 million vs £2.3 million in H1 2020) as well as the continued paying down of a significant part of their debtor balance, sales out to this partner so far this year have not picked up as we had expected. The partner is still suffering from the effects of the Covid impact in 2020, and is not yet taking new product at the rate anticipated when the agreement with them was signed in 2020 or indeed in line with their communication earlier in 2021, which has likely been exacerbated by the significantly increased shipping cost to China now being seen.
Whilst we expect more sales to this partner in 2021, and are hopeful that sales this year can at least match the full year 2020 revenues to this partner, we are exploring all options to maximise the value of these assets in China, where demand for the product has been good historically.
Order book -
The order book for the business (excluding any orders for the China partner and the acquired BBI business) is higher than at the same time last year, indicating good growth in the core business during another extended period of lockdown across many markets.
Outlook -
The second half will have a more meaningful contribution from the new acquisitions and the business is well placed to benefit from the confidence that can be seen as the UK and global economies recover from the impact of Covid. The Board is excited by the growth opportunities available to the Group and looks forward to reporting further delivery on its strategy…
The two recent acquisitions meaningfully increase our expected profitability and cash generation in 2021, where we will receive the benefit of the two new acquisitions in the second half year. 2022 will see us receive the full year benefit of the new acquisitions and, along with the continued growth of our existing business, enables us to look forward to significant growth in revenues and profitability next year. At the same time, we have the resources to pursue additional earnings enhancing acquisitions to accelerate this growth and the Board looks forward to the future with confidence."
My opinion - too many moving parts here, for me to be able to form a view. The recent acquisitions are very material to the overall size of the group, so a lot hinges on how they perform.
As mentioned before, I didn’t like management disposing of about £7m-worth of shares at 90p, at the same time as raising fresh capital in Dec 2020.
Historically VLG has made very little profit, and the one year it did (2020) seems to have been boosted by some one-offs, e.g. hand gel. Therefore the valuation now rests largely on the recent acquisitions, and broker forecasts, which have been reduced today a fair bit. 2021 fc EPS comes down from 4.5p to 2.5p, then a big jump to 4.6p in 2022 - how likely is that to be achieved? No idea!
Overall then, I’m neutral, because there's too much guesswork involved in predicting future profitability.
Overall the shares have gone sideways for the last year, so not a disaster by any means.
.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

171 comments
Best Of The Best (LON:BOTB)
I wrote my thoughts up on it on my blog - writing is helpful.
Anyway - I wanted to say that this discussion board was a big help in dealing with any "whatever" - appreciate it!
All the best,
Vivek
Best Of The Best (LON:BOTB) Directors screwed over shareholders whilst pocketing £60 million & setting themselves & their families up for life.
I don’t care about being sued- I have told them- Rupert Garton & their PR guy Toto Berger from Buchanan what I believe they have done. They only said on 13th May that they were trading in line with market expectations.
Moaning won’t change a thing. Like Paul, I will get out if these rebound. Management have proven themselves to be untrustworthy with zero credibility.
Seems one of the NEDs bought £500K worth of stock @ £24 during the issue from the other directors. Could be an interesting board meeting when he is sitting on a paper loss of 70%....
Why did you change everything? Having great problems trying to navigate.
As someone who also holds Best Of The Best (LON:BOTB) and therefore share others' pain last Friday, I am very grateful for the many contributions made on this board.
I have rarely seen so many constructive posts in my years on Stockopedia and it is very gratifying to see how this community came together to help each other.
The comments below have certainly helped me examine my own decision making which (hopefully) will mean I avoid making mistakes about position sizing, entry points, exit points and cutting losses in the future.
Thank you all
Cheers
Francis
Commiserations to all holders of Best Of The Best (LON:BOTB) , not one I've been involved in but i think this is a useful learning example to others as to why: “Investors need to be well versed in both fundamental analysis as well as technical analysis.”
Quote from 'Rich Dad, Poor Dad'.
Having previously ignored technical analysis completely and being burned in a similar fashion many years back, whilst I am still learning both crafts I have found a deeper understanding of SP movements by trying to marry the two approaches...
On review of the technical perspective, there were clear sell signals in May as the MACD turned down after the fibonacci extension target at the 1.618 level had been fulfilled around the peak SP. The weekly candles, which give the most reliable information, also printed '3 black crows' suggesting downside risk was significant.
Hope this is of interest and that readers can look at this objectively (right click and open in new tab to see more clearly).
Forbsy.
Nice post Forsby!
Investors/traders please take into account at least some technical data (what the market is telling you). This is particularly relevant to well promoted names on forums where recommendations/constant positive chatter may lower your research guard. I personally let the chart tell/indicate the direction of a price and buy and sell accordingly.
Good luck
hi Forsby nice post on BoB... I am also trying to apply a techno fundementalist approach (a la Minervini) to small caps, which is what you refer to here. But I am interested to hear what you think of and how you apply stops...? Given liquidity constraints around small and micro caps. Its much easier to hit and run in large caps obviously.
Hi Antwainer,
Thanks for the compliment re post above. Though not sure who Forsby is lol.
My name is Forbsy!
For the record, I don’t use set stops on small/microcaps. I analyse the chart patterns alongside the candles in respect to volume and make decisions based on my interpretations. For small/micro caps I accept the greater volatility that comes with it before entering a position. I don’t use Minervini tactics as the stops are too tight for small/micro caps as you have alluded to. I also like the following indicators to add context to price movements EMA’s, MACD, RS, RSI, ATR. I don’t use them all at the same time but some help with entries and some with exits. If price falls through a significant pivot point I look to exit and take my loss. I tend to reduce position sizing when a stock rises to >10% of portfolio, I often sell into strength after a strong breakout and add again on pullbacks to pivot points for small cap holdings that I still like.
I trade and invest across spread betting account, ISA & SIPP so utilise different styles in each, with higher conviction holdings I will add more on pullbacks as per the styles outlined in the ‘Art of the Execution’. Don’t be a rabbit!
Hope it helps,
Forbsy.
Commiserations to all holders of Best Of The Best (LON:BOTB) , I’ve been fortunate enough not to be caught out with this one and have never held it. But I do have other rather unsuccessful holdings. I’ve mentioned before that I’ve taken a bit of a bath at IQE (LON:IQE) for example.
We all know the lessons but have trouble sticking to them.
Never buy small, illiquid companies - if it blows up you can’t get out without a very painful hit.
Avoid companies with few competitors in markets with few barriers to entry - when the competition does arrive they will be in big trouble not having been battle hardened by significant competition over the years and have no IP etc to protect them.
Avoid companies where the business model could easily be rendered completely unworkable by just a small change in the regulations - this isn’t what has brought BOTB down but they operate “on the edge” of what constitutes a game of skill as opposed to a lottery and a small regulatory change could hole them below the water line.
Have I stuck to these rules myself? Of course not! My most successful holding of late is an illiquid mid-cap that was an illiquid small cap. Hmmm! Stick or twist?
Just wanted to say thanks to everyone for all the comments today on Best Of The Best (LON:BOTB) which have been thought provoking and educational (and for putting up with some of mine which have been some what less so) it is what makes Stockopedia worth the sub.
My hope is that today will be the worse day of the year (decade?) but also that I can some how learn from it.
Bonne nuit
Michael
Best Of The Best (LON:BOTB)
Spot the Ball is as good as doing the Lottery i.e. lucky punt.
Great marketing online (who does not want to own an Aston Martin Vantage with £50k in the boot) but how many small bets will you lose before you get bored (using your own money of course).
Ok if management trustworthy but dragged out the takeover business way over its sell by date IMHO so the G is not very good - the E and S were never good either so as some old Greek sage said - we are where we are.
I hold System1 (LON:SYS1) but a bit of a hockey stick growth has just been announced today in their AGM Trading Statement.
They've developed a new proposition called Test Your Ad. Its a huge database of TV ads over decades, and the knowledge of what is effective and what isn't in a TV ad. Advertisers can subscribe to the database, and also run their ad concepts through it, to get a "score" of their ad effectiveness. If its low, they can then change the ads while still in creative production till they get the recipe right. Data product effectively, akin to Bloomberg, but for marketing ads. High fixed costs, but huge operational leverage to profits.
Anyways, Data Products were:
However, for me the missing piece of the puzzle is... whether the rest of their revenues (typical agency / consultancy stuff in marketing) has collapsed, and therefore of course the Data revenue mix would be higher? Nothing mentioned of the rest of the business in the TU today. However, it seems like the revenues have held up OK (maybe a slight decline?) judging by the Q1 revenues revealed. It is difficult as TV advertising is a bit of a seasonal business.
System1 (LON:SYS1) (no position)
Hi Boon
I've finally found some time to catch up on this company, prompted by yourself and the Maynard Paton/jonkingston interview.
I can see why you are all so bullish on it now.
Indeed, the Test Your Ad product looks very interesting; a fast growing top line, presumably much of which is recurring, and a high gross margin.
You mentioned a high fixed cost base. I don't recall seeing that but I will keep an eye out for it now. If in fact most development costs have already been incurred and opex costs are relatively quite low here, then this could be the foundation for a future star.
No position yet, but it's on the watch list now. Thank you for taking the time to post your comment.
Cheers
A
Hi
It seems to me that both BOTB and VLG are today victims of a Covid over-rating?
Possibly companies which have had huge covid-related boosts could have their positions reduced in a portfolio.
Conversely, will companies which were hammered due to Covid be re-rated upwards?
Of course any new variant which is resistant to current vaccines would change this.
Good w/end all! I'm glad Fri 13th is almost over! !
Regards,
Ben
Venture Life (LON:VLG) issued a lab report on their mouthwash kills covid, plus their toothpaste. I went out next day and bought six months supply as thought brilliant. Next day a fund raise/dilution. It was on special offer at Boots so seems they were more astute than me.
Newby small investors will be taking notes so warnings to the clown managements out there.
I also bought 3 or 4 bottles of Dentyl last November. The in vitro study was by Cardiff University, not the company: "In their published in-vitro[2] study, scientists at Cardiff University concluded that Venture Life's two CPC based mouthwashes eradicated the SARS-CoV-2 (COVID-19) virus completely (>5log reduction, equivalent to 99.999%) within a 30 second exposure." I use it when needed, but still have some left. [The mint flavour, which makes me gag! Clove is much better :) ] The Chinese may well have overbought as I did - they are in general far, far, more careful about their health than we are - and many have mouth issues due to poor upbringing.
In yesterday's update they state, "The clinical study at Cardiff University on our mouthwashes completed in April 2021 and the results have been submitted for peer review in key journals. We are hopeful to see the publication of these results very soon."
Were those in vivo results to be good it could do very very well indeed.
Immediately so, since it's a product already on sale and in use. And what a market in China.
According to an LSE BB poster I respect, "Cenkos have now raised their forecasts to 4.53p adjusted EPS this year, rising to 6.21p EPS next year. That's a P/E of 16.2 falling to just 11.8, now incorporating the acquisitions which weren't previously included..... Singer have also issued an update today, with a 130p fair valuation "using a peer-based 15x EV/EBITDA multiple"."
Risk/reward looks good to me at this level, even without the vast potential if the in vivo study comes through. I can't see why the in vitro results should not be replicated in vivo. If it kills the bug it should do so just as well on one surface as on another.
Given the core business is still solid - growing - and they are financially solid with finance to make more acquisitions (which they seem to be successful at) I'm happy with it, and topped up yesterday.
Re the sad comedy known as Venture Life (LON:VLG)
https://www.stockopedia.com/co...
Best Of The Best (LON:BOTB) Yes you are right and the signs were there in the Stockranks and I should have paid heed.
I have been lashing out here in the comments today (and not shown much maturity) when in fact it is my process that is at fault and particularly my selling and position sizing discipline.
Hopefully I can learn from this and move on.
Have a good weekend everyone.
Regards
Michael
A lot of us have been bitten today and I'm avoiding tallying up my weekly numbers till I've had a few glasses of wine.
Its probably cost me about 2.5% of my PF today but over the last 4 years of holding this and taking some out over that time I can't complain really. Will decide in the next few weeks whether to just close the rest out and move on.
As a previous poster on here about Best Of The Best (LON:BOTB) and as someone who has shared in both the previous euphoria and today's disappointment, I have analysed the factors that motivated me to take the action that I did to try and learn from both and, possibly, help others in the process.
I originally invested in BOTB at £2.80 and subsequently bought more at £4.50 and at £8.30. At a point (prior to the top), my holding in Best Of The Best (LON:BOTB) was worth more than 50% of my combined portfolios. I sold our entire holding at £29 and watched, miserably, as the price went up to £34. I don't claim any kind of skill or foresight in selling at £29 - my reason for selling was purely that I didn't want to see the profits that I had made evaporate as it was so significant (greater than my entire profits over the previous five years). When the placing occurred, instead of taking this as a warning sign, I bought in and eventually ended up with around 20% of my original holding. Some of these I managed to sell after the trading update in May but I continued to hold around 10% of my initial holding up to today despite some (on reflection) obvious warning signs and increasing unease. I thought that the price could go either way - up if the lack of engagement earlier in the year had just been a blip but, of course, down if that had continued. As we discovered today, the blip has turned into a trend or, at least, a bigger blip.
These are the warning signs that I managed to reassure myself about and ignore and which, I think, were as clear as they could have been to me and other investors
1. Inability to find a buyer / agree a price
2. Poor communication to shareholders during a suspiciously extended sale process
3. Talk of private equity getting involved in the discussions - but not in a good way
4. Following ending of sale period – quickly moved to do a placing at a price that was low enough for people to comment on
5. FinnCap 2021 eps forecast was much lower than people had anticipated and their forecast for 2022 showed growth abruptly ending
6. Continual selling in the market
7. Difficult to believe that such a simple business could really be worth £300m at one point – several people saying that the market cap was much higher than it would take to replicate the business
6. Previous share buy-back a few years ago at a price that was significantly in excess of the market price - indicated an aspiration to artificially push the price higher. Dilution explanation at time not entirely convincing
7. Too good to be true, unlimited growth potential. I did a calculation of revenue per social media user and it seemed to be growing exponentially which seemed strange
8. Illiquidity after the placing – wide spread and little trading within the spread
9. Paul’s initial support and classification as a ‘hold forever stock’ but subsequent sale
It does surprise me that Mark Slater reassured himself about all these warning signs and whatever is said about him being a long-term holder, I would imagine that he must be, in some measure, regretting his purchase today.
Against these warning signs, I constructed arguments for each one to reassure myself based upon the following positives about the company and the management:
1. Management have always seemed understated and not seeking to ramp the share price (with exception of the unusual buyback mentioned above). William always responded courteously and quickly to questions that I sent him
2. The accounts are simple to understand and the business is equally simple. The company has always been cash generative with genuine profits and no income recognition issues. It's a capital-light, people-light (only 28 employees) business
3. Management continued to retain a significant amount of skin in the game and were not greedy in terms of remuneration and options
4. Leon Boros claimed at a Mello Monday to have spoken to William Hindmarch in March and that he had confirmed then to him that engagement was as strong as ever despite lockdown restrictions easing
5. Mark Slater took a significant stake
6. Paul bought back in after having sold
I am not blaming anyone else for my decisions, merely explaining all of the factors that I took into consideration in buying back in, in a limited way.
I am retaining a very small holding that, even if the price goes to zero, will still leave me comfortably in profit on this one. But I need to acknowledge the big mistakes that I have made and may be continuing to make by retaining any holding.
Looking at the positives, revenue is significantly higher than it was two years ago and the eps is also much higher. The market has never really seemed to me to believe the growth story about Best Of The Best (LON:BOTB) in the past - usually ascribing a p/e of about 15-17 last year during the period of exceptional growth - except when it seemed that growth would materially exceed forecasts when it touched, by some calculations, 22 times. Given today's shock, it's difficult to see how, in the short-term it will trade at much more than 15 times earnings going forwards. What happens to the price will depend on what happens to sales because of the operational gearing.
Did William know that growth would stall? I very much doubt it. Did he suspect that it would? Certainly, otherwise he wouldn't have been in such a hurry to sell down his stake. Once again, we are reminded that, if a Director's significant sale seems to signify something then we should listen to what our intuition is telling us and be doubly sure that we aren't falling prey to confirmation bias.
I have no idea what will happen to the share price but suspect that it will remain under pressure in the short -term as some investors will cut their losses and move on. Re-establishing trust will take a while, I should think. Like timarr I don't think that anybody has been mugged here. Except those, like me, who were a little naive about the warning signs.
This has been an incredible learning experience for me and there have been many twists and turns over the last year and a half. I wouldn't rule out a return to growth. It's just that, for me, I am more fearful of being caught out twice in the same share than I am at missing out on another great ride.
Why assume Leon Boros, Mark Slater or anyone else is good AND(!!) have done their work?
I'm amazed that PIs put their capital at risk in this way. Its been okay for a long time as BULL MARKET whoop whoop and every bear plunge was a buy....but when the environment changes how often will you need to be kicked in the head to get the message?
Here's why I still consider other people's views even though experience has taught me that, really, 'nobody knows' is, probably, the best mantra.
On the one hand, I find it incredibly hard to assess the future growth prospects of many (most?) listed companies. I am a middle-aged, ex Group FC / FD who can tell you in the greatest detail what a set of accounts mean. That’s my rather slight comparative advantage. But I rarely shop for anything, don't go on cruises and my working life was spent, largely, in manufacturing not service companies. I am painfully aware of what I don't know. And that is a hell of a lot. I haven't the first clue about which companies are likely to turn out to be compunders and whose share price will take a bottom left to top right trajectory ad infinitum. Am I so different to most other men of my age? Should I give it all up and hand my assets over to a 'professional'? I don't think so.
Instead of trying to work out by myself whether, for example, the re-opening trade will lead to Saga (LON:SAGA) getting back to its ATH, I have chosen to read the opinions of others. As many opinions, both positive and negative about a stock, as I can. I then, sub-consciously, ascribe a weighting to the various views and decide which version of the future seems, on balance, more probable. I am continually amazed by people that are able to do this entirely by themselves. But I know that I am not one of them. As Hayek noted, the real world is just too incredibly complicated for me to assess the outcome from so many disparate sources of information. My observation from my working career is that, even in the best companies, nobody has the first clue about what their future growth rate will be, Having constructed hundreds of forecasts over the years, it's clear to me that if insiders don't have the foggiest, it would be a brave investor who believed that they did.
The point of my ramble about Best Of The Best (LON:BOTB) was that so much is down to good luck. And timing. On Best Of The Best (LON:BOTB), I got somewhat lucky with my timing. Until I got unlucky. Mostly, we delude ourselves when things turn out exactly as we expected that we have incredible foresight. When, in reality, if we were to have access to the information that a company’s Finance Director or Sales Director have, we would be horrified at how lucky we had, in fact, been. However sophisticated investors think they are being with their research – and here I refer to both private and institutional investors – we should remind ourselves that they have a fraction of the information that insiders have. And, as I say, my experience is that insiders still haven’t a clue as to what the future holds. There was an interesting article by Howard Marks in the last couple of weeks about the poverty of forecasting.
I will continue to work on the basis that, ultimately, I just need to make more decisions that turn out to be right than turn out to be wrong and that, to make really out-sized returns I will sometimes have to take out-sized risks. And I will continue to sub-contract the opinion-forming to others who actually buy stuff, who go on cruises and who work in service industries with some cynical overlay from me.
Umm…lots of likes…people obvs like to sheeple ;)
I agree that things are not perfectly knowable. So why crowd in where people use their sheeple instinct to chase the higher priced nice but uncertain story. Why not go for the less comfortable but uncertain story that doesn’t have that sheeple fatness in the expectation?
Unless of course you like to trade the trend and liquidity flow at micro and macro level…which tbc is not ‘fundamental’ investing .
So I find your response to lack logic despite its smartness.
Maybe you just learned to do different but haven’t processed yet…
(Note, Mark Slater isn’t a classic consumer of botb, or vlg or boo etc…he buys the Bentley, gets top dollar private medical health and his daughters shop Bond St…so what’s he teaching you on product…like you he’s following the trend and the momentum…unlike you he charges people a large fee …and hopefully unlike you he’s mediocre at it)
At a point (prior to the top), my holding in Best Of The Best (LON:BOTB) was worth more than 50% of my combined portfolios.
I'm not quite sure how to interpret this comment. Does this really mean that 50% of your total wealth (excluding your house?) was invested in BOTB or is your share portfolio just a small proportion of your overall portfolio?
The former. The vast majority of my purchases were at £2.80 and £4.50 and, for reasons that aren't entirely clear to me now, I put around 20% of our assets into Best Of The Best (LON:BOTB). With hindsight, I realise that this was very risky. At the time I made the initial purchases, this was the biggest conviction trade that I had had in about ten years. Which only goes to show how badly wrong you can be even when you are convinced that you are right!
RE: Best Of The Best (LON:BOTB)
Like timarr I don't think that anybody has been mugged here. Except those, like me, who were a little naive about the warning signs.
Err, I don't think I said that, although I think it's correct.
I do think there's a lot of confirmation bias around, and not just in terms of BOTB. As humans we're all predisposed to look for reasons to confirm our decisions but when we hold a stock we should do the exact opposite - we should look for reasons to sell.
In the case of BOTB:
There are doubtless others we could pick out in retrospect.
As I've said before, diversification is the best way of protecting us from our own mistakes - holding a concentrated portfolio is usually a sign of overconfidence unless you're very, very good at analysing stocks. I know that I'm not good enough to run a small portfolio, which helps protect me from the worst consequences of my own stupidity.
timarr
Hi Tim
How positions do you hold and how many positions make up say 80% of your pf?
Do you ever let your position size run beyond a certain %age of pf or are you rigorous in trimming back on a monthly basis?
My problem is I struggle to keep track of 15 stocks, let alone 20 or 30. If I am going to hold 20, 30, 40, 50 stocks I don’t see what edge (assuming I have any) I would have (to ge honest I really can’t imagine finding that many stocks to invest with enough conviction) and I might as well give the money to Smith, Blue Whale and Buffett.
Thx
Regards
Michael
Moving Averages - 10, 20, 50 (the most important one), 100, 200. Tells you all you want to know. I'm coming to the view that if falls 10% I've not caught momentum and dump - selling is the hardest thing to do. Two portfolios - the Trader and the SIPP/Coffee/whatever. At this time I'm struggling to put into the SIPP/Coffee but it won't be Best Of The Best (LON:BOTB) or small cap miners (lol) for sure.
Moving Averages - 10, 20, 50 (the most important one), 100, 200.
GarryC can you clarify your use of Moving Averages. Which is the most important MA and do you sell after SP falls below 10% below this?
I shall pose this question on a new thread as well.
Hi Michael
How positions do you hold and how many positions make up say 80% of your pf?
Roughly 100 positions, 40% of those make up about 80% of the portfolio. Long only, I don't short or hedge, I don't think I've ever had anything get to the point of trimming, but that would be at 8%. Everything is held in tax shelters, which has saved me a six figure sum over the years.
I benchmark against the FTSE All Share. Even adjusting for dividends the portfolio has outperformed in 17 of the last 21 years and in 2 of those I was effectively out of the market for various reasons.
I'm ruthless in cutting anything where the business model changes or fails in a way I don't like or I become suspicious of management's behaviour - related party deals, dodgy share options, repeatedly lucky share sales and general disregard of shareholders are immediate sell signals for me. Keeping track mainly means checking major year-on-year changes in the accounts and skimming trading announcements.
Most of my larger holdings have grown to be so - once settled in the portfolio I have an average holding time of 8 years (and rising). Most of the larger holdings have seen drawdowns of between 30% and 50% while I've held them - but obviously diversification means no single company can seriously impact my returns.
Once someone can read a set of accounts and has figured out the core set of financial metrics that they're comfortable with most investing, in my view, is about managing one's own mental state. I'm tempermentally unsuited to running a concentrated portfolio and this works for me.
All this means that when something like BOTB falls over it means I can view it with an unbiased eye. I think it's still too pricey to top up given the uncertainties, but not so broken I'd consider selling.
timarr
Thank you Timarr for sharing this, it is very interesting and useful to see how other people manage their portfolios.
Marcus
Timarr,
Roughly 100 positions, 40% of those make up about 80% of the portfolio.
Can you give us an idea about what your time management look like? I struggle to give 15-20 the time they deserve, keeping up with the news flow, updating my valuations, thinking about risk management etc... I can't imagine managing a portfolio of 100 positions.
I've often been tempted by botb, but always felt that I'd missed the boat,
Obviously this cost me a lot in potential profits, interested to hear that one issue was that competition entered the market. I'm not at all surprised by this, once they'd given up the airport thing, and were purely on line, where's the moat ? I'm surprised that a group of people working there didn't leave and start up on their own. At the end of the day what's involved ? search engine exposure and advertising/ social media presence, and funding to pay for the prizes (though you should have the money for the prizes before you give it away. I'm not saying it's easy and any tom dick and harry could do it, that's obviously not the case, but anyone with the search engine / social media skills could have a reasonable stab at this, one thing's for sure, the sort of people who will buy these tickets are probably interested in new competitions and angles on it, so if new competition appears that have products that seem different and interesting, what's stopping them buying tickets in something else they've stumbled across ?
Still no reason it can't be a great business, but can it be a high margin business and keep growing at a fast rate regardless of competition ? I suspect not, but that's not to say it won't do well in the future, maybe it'll be them that comes up with lots of new ideas that inspire people to bet more ? They do have the advantage of the contacts of people who have bought from them before ?
For me this is the sort of share that's a bit of a whim product, other opinions exist, and since I'm not the sort of person to buy this product, other opinions are probably more insightful,
K
Things not looking good at Venture Life (LON:VLG) - interestingly this was heavily tipped by Simon Thompson at IC just a couple of days ago. I certainly wouldn't criticise anyone for making the wrong call but his summary did state that 'a forthcoming pre-close trading statement is set to prompt earnings upgrades' - that sounds rather odd, as if he was almost certain there was going to be good news coming. ST is good but clearly fallible, and slightly irritated the way anything he tips immediately shoots up 10%.
Bouden54 my problem with ST is he seems to tip 2 or 3 companies a week plus “Bargain Shares” portfolio each year which is surely going to lead to some winners?
As an employee of IC as I understand it he is not allowed to invest directly in stocks but if he as good as some of fans think he is, why is he still writing for the IC?
I find some of what ST writes pretty good and I've had some nice winners courteousy of his research. That said I never take anything as gospel and do my own research as well before I ever take a trade and I decided not to play on Venture Life (LON:VLG) particularly, as similar to
Mojo, I just haven't ever quite got comfortable with management and I am inherently suspicious of supposedly large Chinese deals. I haven't seen many end well for the western party!
To be fair to ST he doesn't tend to tip 2-3 companies a week, most of his articles are update commentary on existing tips. He basically does a bargain shares list once a year of maybe 10 companies and then I'd say half a dozen or so other new tips. Overall I'd say his performance is pretty good so I use him for ideas.
My issue in this case is not with ST expecting upgrades but with Venture Life (LON:VLG) management not steering the market to this issue earlier. They clearly hadn't updated analyst expectations so we are expected to believe this warning basically happened yesterday.....hmm ! People like ST and other analysts were expecting a base case much higher with potential from the new acquisitions to increase this baseline.
good question
Commiserations to all holders of Best Of The Best (LON:BOTB) (and the rest – what a day for it)
I was out already, but my average was £30.66 and I sold the lot on the negative forward looking statement at £19.50 for a 5% reduction in my total portfolio value. On the day the statement was released I skimmed it and really didn’t give it enough credence as a profit warning until the market stepped in and helped me interpret it. I’ve read the Stockopedia profit warnings guide many times over, and that – along with the fact that there had been a recent placing of management’s shares caused me to exit the entire position.
There’s no way to know why the sale process didn’t go through nor how much management knew when conducting the placing. Whilst I don’t suspect anything sinister, nor do I expect them to be able to predict the future, I still feel that ultimately these are the people that are best placed to know the current operations and the outlook for the company, which contributed to my decision.
An issue unrelated to the company is that, on reflection, my entire position in Best Of The Best (LON:BOTB) was externally influenced and reinforced .I didn’t come across it using my normal stock screening /picking process, or research it in my normal way (actually I did like MGMT skin in the game and institutional buy in but anyway) I thought about how many times I’d seen the company mentioned on Twitter etc. So on the same day that I sold my stake I also deleted my Twitter account. I understand with all financial writing and commentary that there is an inherent informational asymmetry that must be considered – this only seems to be magnified on Twitter. It may be the case that more experienced stock pickers can tread this line more carefully but I decided that it was a negative influence on my process at this time. Most importantly I asked the question – Did being on Twitter make me any money? The answer:- No. (By the way when I discuss external influence I'm not referring to any writings on SCVR which are an essential part of my research and always flag up things that I'd completely overlooked)
I do believe that the outlook of a company must be regularly reassessed – which suggests that, as appealing as the coffee can approach is, it’s probably not for me. There’s some discussion on here about the Quality Rank of Best Of The Best (LON:BOTB) but there’s more to quality than just that number. Stephen English did a brilliant talk on Melo (21st June 2021 I think) with some commentary on this topic. I am however a huge fan of the StockRanks and as herbie47 & timarr noted its about selecting from a pool, or having a diversified basket of high ranking stocks – No single high ranking stock can necessarily be relied upon.
Are we potentially seeing a tipping point, where the profit warnings are going to come in thick and fast over the next few weeks?
After 6 months of the re-opening tide lifting all ships, and where every company was seeing rising revenues and profits and "performing better than management expectations", are we now going to see the weakest companies struggle to keep performing and profit warn?
As the saying always goes, when the tide starts to go out, that's when you see who isn't wearing any pants.
I see that Avon Protection (LON:AVON) also dropped a lot today, on disappointing Trading Update. Heavily rated share on a high PE compared to historic, which got inflated over the last 12 months.
Hi dahoko,
That's exactly what I'm worried about too.
So many companies are now flagging supply chain problems, and raw materials shortages & price hikes, that it's bound to cause some profit warnings. Plus all the UK freight (driver shortages) issues seem to be getting worse.
Combine that with broker forecasts that have often been raised from ludicrously low (hence very easy to beat), to maybe more ambitious, then it seems we're being set up for a period where profit warnings could become quite a problem.
I'm thinking in terms of reducing my gearing a bit actually, as profit warnings on geared positions are a lot more serious.
Regards, Paul.
Commiserations to holders of Best Of The Best (LON:BOTB) . I've held things before which have crashed like this. It's not nice. But to me this is a good example of why the "coffee can" approach to investment is doomed to failure.
The key issue with Best Of The Best (LON:BOTB) is probably the rapid escalation in the cost of customer acquisition which has blown their business model out of the water. Suddenly their ability to grow rapidly with high margins has evaporated. They hope that this situation will "normalise" in their favour, but why would it? They have no moat, so what's to stop other virtual businesses moving in on those high returns on capital?
The only moat available to most businesses in today's world is rapid innovation. I think Best Of The Best (LON:BOTB) stopped innovating and others have moved in on their turf, particularly their advertising turf. Trouble is, if you DO achieve rapid innovation, that means your business changes really quickly. Investors will find that what they put in their coffee can 5 years ago has mutated into something else. When they open up their coffee can, they might get a nasty surprise. It seems to me there is no real alternative to constant reassessment of your investments.
The coffee can from 100 baggers approach means that even a brutal drawdown needs to be taken on the chin. One example in the book is Monster that went down 40% in a month a few occasions before it was a 100 bagger.
I don't think I've that much patience nor the intestinal fortitude (a phrase my american boss uncorks from time to time) for it myself but the research is clear. One analysis showed the best investors in one fund managers analysis were ones that had either died or forgotten they had the investment.
"the research is clear"
What research is that exactly? I'm aware of the idea, I just disagree with it. The data that I've seen quoted in support of this approach suffers from survivorship bias and other selection issues. Nice example with Monster, but how many counter-examples are given where the stock goes down another 40%, or maybe 100%? What about all the portfolios that didn't contain a 100 bagger; or the portfolios covering different time frames e.g. ending in 1932 (not starting there as Phelps' original book does) or 1982 for that matter; or the portfolios from other countries e.g. Japan?
Best Of The Best (LON:BOTB) met Mayer's criteria set out in "100 baggers" including market cap, margins, ROE, growth, big player in a small field to give it a moat etc, so presumably some people hold this as a potential 100 bagger. If they believe in the philosophy then yes, they should continue to hold, or maybe buy more, but I question the whole approach.
In particular, in today's world companies have to change rapidly to survive. They will quickly become different companies to the one originally bought, with different management, markets, products, competition etc. For each new version of the company to be a success is extremely unlikely and shouldn't be taken as an article of faith just because an investor bought the version of the company that existed 10 years ago.
Quite!
Amazon the quintessential 100 bagger was a low margin retail business until 2012.
Bill Miller, Jeff Bezos & a few other shrewd people noticed scale economies returned to customer & AWS
Of course in 2014, it was obvious to the market that it would go from 300 to 3000, then I dare say it would not have traded anywhere near 300 at the time.
As for Google, that other one, which does irritate me more because I asked my Dad to buy (post his .com burn) saying it had turned into a verb. With hindsight, when the word Apple became fruit or company, it was probably a buy signal too.
Anyway, the reason I bring up Google is that a partner at a VC fund that prob million bagged (conservatively) on Google said that back in the day (long time before it listed), if we could have sold our stake in Google, we would have.
FYI, You are going to have to take my word for the exchange with the VC partner.
We are comparing Amazon, Facebook et al with ... er Best Of The Best (LON:BOTB)
If you had a coffee can, a pension fund in boring terms, would you put it in it? Angle (LON:AGL) potential huge benefit to mankind - yes but only when its SR gets some where sustainable 50+
Hi cmpeckham,
. But to me this is a good example of why the "coffee can" approach to investment is doomed to failure.
Really good points you make there. I've been pondering this since the BOTB profit warning on Friday, and am also cooling on the "coffee can" investing concept. It sounds so persuasive in the 100 Baggers book, but in reality, in the digital age, business models can be disrupted, competition emerges, etc.
Regards, Paul.
am also cooling on the "coffee can" investing concept. It sounds so persuasive in the 100 Baggers book, but in reality, in the digital age, business models can be disrupted, competition emerges, etc.
As Nick Train has pointed out there are 12 companies in the FTSE 350 that have 100 bagged at some point, another 12 that have gone up between 50 and 100 times. By definition anything that grows from small to reach the 350 will have multi-bagged. That will carry on happening.
https://www.lindselltrain.com/...
The 100 bagger concept is sound but the question, as it always has been, even in a digital age is how do you identify them in advance?
Like Loopup (LON:LOOP) and Novacyt Sa (LON:NCYT) (which I also held at one point) Best Of The Best (LON:BOTB) got a huge one-off boost which some us - including me - interpreted as a permanent increase in earnings. Well, we were wrong and the tide is going out. We can see this with financial stocks as well - both Cmc Markets (LON:CMCX) and Hargreaves Lansdown (LON:HL.) have reported reduced earnings but on higher customer numbers.
However, for companies that have seen an increase in customers during the pandemic I expect that there will be a genuine and sticky increase in earnings if you smooth out what happened in 2020. After all, the BOTB share price sits, even now, at double what it was in March 2020. CMC is three times the price, NCYT is up 15 times. When looked at in a decade, through the other end of the telescope, who knows where they will be?
timarr
"By definition anything that grows from small to reach the 350 will have multi-bagged."
Correct. That is why Nick Train is committing a classic error of data selection. He starts with a list of the most historically successful companies and counts how many of them have been ultra-successful. What a pointless exercise! No meaningful conclusions can be drawn from that, particularly as he biases the data further by only looking at "trough to peak gains". All he does is create a misleading and dangerous impression (e.g. see another comment here today about a portfolio of 100 stocks, of which 1 is a 100 bagger).
But let's work with his conclusions for a minute. He identifies 12 companies, representing the cream of the cream of multi-baggers. Let's look at what has subsequently happened to 3 of them:
Cairn: -87%
Capita: -97%
Tullow: - 99%
Now according to this philosophy, investors are supposed to ride out the downtrends in successful companies and what shares could be more deserving of this attention than ones that have proven themselves by 100 bagging? Just ride out that 99% loss because all will be well in the end(!?!).
From your other comments I interpret that you don't actually implement this philosophy. I just feel sorry for the people that do.
From your other comments I interpret that you don't actually implement this philosophy. I just feel sorry for the people that do.
I don't think anyone would implement a 100 bagger approach - Meyer's book is about as clear an example of the Texas Sharpshooter Effect as you could ever wish to find. It makes for an entertaining read but it's unlikely that any serious investor would take it, well ... seriously. So, no, I don't implement this philosophy.
Nonetheless the idea of actively seeking multibaggers is a valid approach. It was at the core of Peter Lynch's success, as he described in One Up on Wall Street. Providing you don't buy during one of the market's periodic manic phases there are always decent quality small cap stocks around with reliable management who will grow their businesses steadily. As I noted earlier, my average holding time is around 8 years (and rising) and for stocks like James Latham (LON:LTHM), James Halstead (LON:JHD), Xp Power (LON:XPP), Jarvis Securities (LON:JIM) and many more that's been a nicely profitable and rather stress free exercise. Often these types of companies end up getting taken over, so the prospect of 100 bagging rarely arises.
As for Nick Train - well, I'd agree the article is rather seeking to explain the Lindsell Train buy and hold forever strategy and, as such, is a bit contrived. But a 100 bagger is only such at a given point in time. No great company has ever remained great forever - Coats Viyella was once the largest company in the world, that's never happening again regardless of how much regression to the mean they achieve.
Underlying this, however, is an important point - buy and hold is a great strategy but it isn't zero effort. Companies with apparently unbreachable moats can be upended by innovation - newspapers, retailers, music publishers, etc have all been undermined by the internet in recent years. It's reasonable to assume fossil fuel companies will also go the way of fossils, although probably not as quickly as people expect.
Of course, if this stuff was as easy as the writers of investment books made out then they'd be doing it themselves rather than writing investment books.
timarr
I remember reading One Up On Wall Street and deciding I didn't have the time to follow that approach (he held even more stocks than you do!). I agree that actively seeking multi-baggers is a valid approach, but I think it should be for a select few. I'm happy to believe that you are among that number. Most investors don't belong in that group.
The problem is the rough patches. No one can know if they are temporary. The better approach for most investors is something along the lines of the Stocko investment club. They have sell rules based on the purchase price which is illogical, the purchase price should be irrelevant in the sell decision, but at least they cut their losers.
As you say the world changes and it is doing so even more rapidly than in Peter Lynch's time. I just looked up his biggest winners, which were: "Fannie Mae, Ford, Philip Morris, MCI, Volvo, General Electric, General Public Utilities, Student Loan Marketing, Kemper, and Lowe's." Hmm. Is that really a buy and hold forever portfolio? Should he still have his portfolio concentrated on those stocks today? If not, how do you know the right time to sell?
Future investors will look back at today's winning portfolios containing the likes of Apple, Facebook and Amazon and think: "How quaint! Did they really think they would hold those tired old things for ever? They should have sold in 20xx when xyz happened." As we know, recognising that point in real time is rather tricky.
Well, Peter Lynch didn't run a buy and hold portfolio. He made his money then moved on.
The challenge, as you rightly point out, is when to sell. And, of course, you're also right that the pace of disruption is higher now than it ever has been. But every decision, be it buy or sell, comes trailing clouds of uncertainty and is indicative of the habitual overconfidence of human beings.
Personally, by and large, I'm happy to run holdings as long as the fundamental business model doesn't appear to be broken as evidenced by the numbers - primarily cashflow, in my case, although there are other factors that may be relevant. As far as I'm concrnered share price, by and large, is irrelevant to the holding decision, or even the selling one. But it is relevant to buying - as Rob Arnott showed, investors are great at identfying the stocks that will grow fastest, but then overpay for them.FWIW, I think I'm agreeing with you, albeit I always prefer to err on the side of management while I have confidence in them, even if the company is struggling. Selling is the hardest discipline and avoiding emotional attachment to stocks is very important. That's, perhaps, the most important principle for private investors.
timarr
Is the coffee can investment method a failure if one or two investments do badly?
If you invest an equal amount in 100 companies - one of them 100 bags - the other 99 fail and go bankrupt eventually - the chance are you will break even - equalising out dividends vs costs.
The chances are most of the 99 will have value - if you invest sensibly, dividends over the long term will outstrip costs.
FWIW. I have 2 local McColls. Both shops look terrible and the Manager of one is not shy of venting his fustration at the company and the lack of cash to make even basic repairs. Never heard someone so rude about his employer! Balance sheet and the above puts it on my bargepole list.
thanks for this info. that's very helpful
Well, they've now raised the cash to make repairs and capex investments to those Mccoll's Retail (LON:MCLS) shops! With a plan to rebrand them too as Morrisons Daily.
Time to re-evaluate your view, when the facts change?
Re: Best Of The Best (LON:BOTB) (No position)
Now watch as Hindmarch & co. hoover up the shares when the price has hit the deck.
I sold out of VLG this morning following bad TU which was realitevely easy to do at quote with IG immediately after markets opened for a small loss. I lost patience with management's funny business.
My question is why would Paul not try the same approach with BOTB? Is this decision based on how bad the TU is? Maybe some of the stock could be sold at least?!
Also has anyone had experience of placing an opposite bet with Spreadex in this situation to hedge the position to counter the liquidity? Or does this approach face same problems?
i have a number of shares that have low liquidity and wanted ideas on the best approach if they issue negative TU's in future. Maybe only way is to "soak it up" in diversified portfolio?
Hi gus,
My question is why would Paul not try the same approach with BOTB? Is this decision based on how bad the TU is? Maybe some of the stock could be sold at least?!
Re Best Of The Best (LON:BOTB) - just to clarify on that point, what I meant was that I would sell at 1500p if that price was available today, but clearly it wasn't going to be available!
I worked out (pre market open) that the price would probably drop vertically to £7-8 (pretty accurate as it turns out), and at that price I'm happy to hold, because I worked out my own valuation as being 800-1066p, as explained in the article above.
In the past management have been very good to external shareholders, drawing modest remuneration, and paying out generous divis & special divis which all shareholders benefit from.
Although I agree that their reputations are now trashed in the eyes of some, having sold £60m of stock at £24, then reporting a more than halving of profitability today. Although for people who didn't like the massive Director selling, there was ample opportunity to sell out at a higher price (which I personally did for most of my original position).
Unfortunately, I got it into my head that £15 looked like a floor, and recently added to my position, so that's a mistake as it turns out. Still overall, I've made way more money from BOTB in the past than this recent loss, unpleasant though it is.
It's still a good business, but it's now become clear (which I didn't see coming) that well-funded competitors seem to be driving up the cost of digital marketing, and that seems to be squeezing BOTB's margins.
That said, management have proven to be resourceful & adaptable over the years, and still hold huge personal stakes, so are motivated to rectify things. They do other forms of advertising too, like TV ads, which are pretty effective (Sosandar (LON:SOS) (I hold) do the same, and say TV ads can be targeted quite well to particular regions, and around relevant shows, at quite reasonable cost).
On balance, after getting the emotions out of my system in the first 5 minutes or so, I've spent the morning soaking up views here and from my wider network of shrewd investors, and some have decided to sell up, whereas personally I think there could be a better time & price to sell at. So for the time being, I'm happy to hold (but not buy any more). It's not a particularly big position (well definitely not after today's move!) and is now only about 0.7% of my portfolio, so I'm just happy to park it there and forget about it for a while, and see what happens next.
Now that the weaknesses in the business model have been shown in very suddenly & brutally, it's not a stock that will ever become a large position of mine again, and I think an exit around say £15 would satisfy me, if it gets to that level again?
The market cap is only currently £75m, which is cheap in my view.
I fully respect different opinions, this one is quite finely balanced, and am just airing my current view (which may change at any point), not trying to persaude anyone else either way. It's interesting to discuss it & I've read & digested all the opinions here, thank you for posting them.
It just shows doesn't it, that all the stats and wonderful historical numbers, over quite a few years, can suddenly go wrong. That said, if you treat last year as a one-off bumper year, and ignore it, then there's still a good, and growing business here. It's highly solvent too, so no chance of any issues there re solvency or dilution, as costs can be cut easily if needed. There's actually quite a lot still to like, looking beyond today's bad news.
Bear in mind the share price has crashed by almost three-quarters from the peak, that's the crucial point - so the bad news looks priced-in to me.
Oh I should as always apologise to anyone who has lost money on this share, and was influenced by my opinions on it. Although to be fair, I have publicly said previously that I'd sold most of my shares, e.g. in the most recent interview with Tamzin. Obviously I look a complete chump from saying how well the company had done, etc, but I was basing that opinion on the facts as they stood on that date. The facts have now changed for the worse, and therefore I'm a lot less keen on the business than previously. But valuation adjusts for that. When it was popular & riding high, it was over £30/share. Now it's disappointed, it's £8/share. That all needs to be taken into account. It's a lower quality business now, but it's much cheaper to reflect that.
Regards, Paul.
Dear Paul
Great follow up comment on Best Of The Best (LON:BOTB) Thank you.
On:
“Although I agree that their reputations are now trashed in the eyes of some, having sold £60m of stock at £24, then reporting a more than halving of profitability today. Although for people who didn't like the massive Director selling, there was ample opportunity to sell out at a higher price”
On the first sentence that is my view and the company is uninvestible and I will be out within the next month so.
On the selling the reason they gave, if I recall correctly, was ”to satisfy market demand” but appears they were unloading stock which they knew was grossly over valued and that is unforgivable. As my 15 year old son suggested to me this morning was it a bit like Jeremy Irons’ actions (to sell everything, outgoing only today) and yes I think this was.
Yes they still have a large holding but are now, because of the sale, independently wealthy and even if Best Of The Best (LON:BOTB) goes to zero they will never have to work again and so their interests and ours (other owners) are in fact only partially aligned.
Regards
Michael
After a read of a stockopedia ebook (forget the title) I changed my investment approach to ditch stocks automatically with bad news TU's as soon as market opens. The ebook suggested that most stocks don't finish their decline on the 1st day but often do a pullback (just to get your hopes up) but then continue with a slower decline for 6 months to a year or so. When I implemented this approach on Avon Protection after they announced a delay in a big contract then the stock played out exactly as the ebook indicated.
I wish I had read this ebook before #VLG management sold out their big stakes at same time as the fund raise as I would have sold out then instead of tying up my capital with that one for all of this time but there were a few tipsters vouching for VLG.
I sold out of BoB after the directors sold a chunk of their holdings. I am sure they knew even then that the signs that trading was slowing down for I do not believe in coincidences. Who is the NOMAD?
(LON:BOTB) Ouch. Managed to dump my position for a very healthy loss.
What have I learned from it? Well now I know its absolutely time to re-review my portfolio; any share which has had bumper revenue/profits due to the pandemic is going to be looked at through a very sceptical lense.
Its taken me too long to get round to doing this... work, family, procrastination - such is life. Definately the kick up the backside I needed to give my head a wobble and re-review!
I see Avon Protection and Venture Life have also put out profit warnings. Hopefully everyone holding also held (LON:STCK) to mitigate some of this loss!
Indeed Andy. I think this is the lesson and I need to put in some serious work over the weekend.
Regards
Michael
Please can someone help me out? (re. Best Of The Best (LON:BOTB))
What calculation is being made to get to an implied valuation of 800-1066. Is it PER X EPS?
"What PER to use? I'm leaning towards 15-20, implying a valuation of 800-1066p, that's what I think it's now worth for the time being. Longer term, who knows, that depends on whether trading recovers or not."
Hi Kev,
It's the actual EPS of 53.3p multiplied by the assumed PER of 15-20. Hence 800 - 1066p. Regards, Mark
Thanks for the reply
I have had bad luck this week with management hyping up the prospects of a particular company, only to be disappointed. Feel for those at Best Of The Best (LON:BOTB) as I know once trust has gone in management, its gone forever.
Stay strong peeps, money will be made and lost for years to come.
Best Of The Best (LON:BOTB) Absolutely concur. Management beyond pale and make Best Of The Best (LON:BOTB) uninvestible for me going forward.
I also hope that Stocko revisits its Algo - it has Best Of The Best (LON:BOTB) with a quality rank of 99 rolling laughing emoji.
I think DYOR more than ever. I will certainly take stocks ranks with a pinch of salt going forward. They might point you in the right direction for a basket of companies but on an individual level I am beginning to question there relevance.
Regards
Michael.
Top comment.
Thank you.
Regards
Michael
Stockranks are backward looking, when the figures are updated then they will be adjusted.
There is some evidence that the higher ranks out perform lower ones in the UK.
Best Of The Best (LON:BOTB) only has a SR of 44!
Yes that is point as a group, they out out-perform but a high rank on an individual basis I think can only confirm biases and lead to lazy investing behaviour which it has done in my case.
It reminds of a quote from Patrick O’Shaunessy that the best performing shares come from the group known as micro-caps but as a group micro-caps are the worst performing group.
Regards
Michael
Hi Michael, I get what you are saying about micro-caps but I don't think that is the same as Stockopedia ranks. Micro-caps you may find a few gems. Stockopedia is about picking from a pool that will out perform, yes you will get bad stocks within that pool but the chances are less than other lower ranked pools. In NAPS there is usually 1-2 duffers, several that don't do anything, then many that do quite well and then around 4-5 that do very well. Looking at this years NAPS, 6 are already over 50% gains with 1 of those around +180%. Only one is below -20% and 1 is -6%. So out of 20 stocks, 6 have done very well. The next 8 are between +10-40%. So you had a 70% chance of having picked a winner, only around 10% chance of picking a loser. A 70% success rate is rather high and that is over 10% gain not just win or lose. If win or lose then it is 85% winners, although 1 of those is about break even. So Stockopedia is the opposite from your micro-cap example.
Seems you have focused on Quality rather than other ranks, maybe there is such a thing as Quality trap?
I think DYOR more than ever. I will certainly take stocks ranks with a pinch of salt going forward. They might point you in the right direction for a basket of companies but on an individual level I am beginning to question there relevance.
Stockranks don't work predictively at the individual stock level. Never have, never will.
In essence a Stockrank is a backward looking mash-up of various factors that have been shown to be indicative of outperformance. Most of the time a basket of high rank stocks will outperform a basket of low rank stocks - although as Stockopedia has only really been operating in a raging bull market we don't know how it would perform in different conditions.
To quote Stocko on high Stockranks:
"Portfolios of these stocks have, on average, over the long term, tended to outperform the market. But individually there is zero guarantee of outperformance"
https://www.stockopedia.com/le...
I'd commiserate with Best Of The Best (LON:BOTB) holders, only I am one. Sometimes stuff happens, diversification is the investor's best friend in these circumstances.
timarr
Hi Michael,
I'm not sure that's entirely fair to the StockRanks. The overall rank for Best Of The Best (LON:BOTB) was 44 yesterday and the company was considered a "Falling Star". There is an alternative argument where we would've been much better off had we sold when the StockRank dropped through 70. If only! :)
I'm almost thinking the other direction to you and might make more use of the StockRanks to limit cognitive bias. The NAPs results speak for themselves and they've certainly got me thinking.
Cheers,
Kieran
I'd also back Kierans point on Stockranks - the overall rank had dropped well below 70 BEFORE the first bad news in June so in fairness anyone following stockranks closely would have sold out long before the last two warnings. I use stockranks as a rough guide but actually following it this time could have saved people a lot of money. Might have to look at my portfolio against stock ranks over the last few months now. Applying some outside logic isn't a bad thing to do and may actually help me trim my portfolio back a bit as we are starting to see some more volatility.
ok sounds like you are right and I take it back. An early emotional reaction to a truly awful morning. Best Of The Best (LON:BOTB) and £AVON.
The NAP's results seem to support mechanical approach using algo only although the portfolio did have 1 year of underperformance. I think you always need momentum on your side.
I use algo for screening and then DMOR to buy into the story which helps with decision making.
Agree with your point about the limitations of the Stocko Algo. Like humans it does appear to suffer from "recency bias" such that a short period of strong numbers will move the score very quickly and vice versa. I think it needs to be used with caution in certain stocks like "lockdown winners" and mining stocks where the revenue and profit can reverse very quickly.
At the end of the day what did they do, produce, make. Nothing. Gave away expensive cars to gamblers. At least Venture Life (LON:VLG) sold expensive toothpaste.
How do I find the BooHoo thread please?
With any company, go to its page, then click on the "discussions" tab.
thanks
Or click on the Discuss icon on the left hand side and just scroll down until you find it, normally fairly near the top anyway...
There’s also a list of the company specific threads with embedded links that can be found here.
https://www.stockopedia.com/co...
Boohoo (LON:BOO) is one of them.
Gus.
It can be found at:
https://www.stockopedia.com/co...
Regards Michael
A sobering day - that the Mkt can so savagely hit 3 shares today already widely commented on . Interesting to note that even the pundit Mark Slater (who I believe is somehow associated with Stocko?) is heavily into both Best Of The Best (LON:BOTB) and Venture Life (LON:VLG) - Yes, we all make mistakes!
"Mark Slater (who I believe is somehow associated with Stocko?)"
Is he?
There is a Jim Slater Guru screen.
No - but just found this press release from 2019 which shows my confusion
https://citywire.co.uk/funds-i...
Sounds like Mark Slater bought Company Refs but Stockopedia bought the subscriber list.
There was a webinar by Ed this week that suggested Stockopedia had partnered with Mark Slater in order to buy Company Refs, a company originally set up by his father, the late Jim Slater. As far as I am aware, that is the only connection that has ever been made public.
I have adopted a position where I only invest in businesses I would like to own and that I understand.
I sold out of tobacco and gambling as it felt a bit grotty. Just a personal opinion.
For me Best Of The Best (LON:BOTB) was a similar decision. I just didn't like the business and whenever I have been approached in shopping centres or the airport it feels a but smutty.
To be fair I kept looking at the updates on Best Of The Best (LON:BOTB) and felt I was missing out. I was very tempted.
In a way I feel like I made the right decision to stay out of it although my reason for not investing was not that I feared a drop in profits.
Another share I have avoided although often tempted by is Sylvania Platinum (LON:SLP) I choose not to invest as there are too many macro factors that can influence the business that I don't understand.
Rather than gloating I guess I am trying to say that I invest within my own limited capabilities and understanding. I am becoming more disciplined in this.
I am leaning towards buy and build models - Sdi (LON:SDI) and Marlowe
I hold Volex (LON:VLX) and £Saga
I like large defined markets, a clear strategy and good management.
I completely agree with this idea and I still sucker myself into riskier, unknown stocks (like SLP). I am trying to stick to the program now though with your last line being the mantra.
Wise words Camraid. Only invest in businesses that you can understand. I have been tempted by mining stocks in particular and have occasionally invested, fortunately without too much grief to date, but I have no knowledge of geology and geophysics and find myself bamboozled by various up dates.
Note to self
Stick to what you understand!
All the best
Jonno
I largely agree with you that it is best to stick to what we understand. But I think it is natural human instinct to say, in hindsight, after something goes wrong to say that it was because I did not understand it properly and, on the flip side of the coin, that the investment that goes well was one I was fully on top of.
I have not invested in any of these three companies, but it would seem to me that Best Of The Best (LON:BOTB) and Sylvania Platinum (LON:SLP) are comparatively simple business models that are comparatively easy to understand. Saga (LON:SAGA) which is mentioned in CamRaid's original post - a mix of insurance and how travel will revert post Covid - is arguably much more complex.
My former boss always insisted that we put a "confidence rating" from 0 to 10 on all our ideas. If we were only "7", what did we need to understand better to increase our confidence to a "9"? Could we find that extra bit of information? But interestingly, in practice, I don't think our very high confidence ideas (as measured beforehand) actually outperformed our medium confidence ideas, for whatever reason. Maybe when we have too much confidence we are not attuned as well to warning signs.
I think it is a good exercise, however, and I do from time to time go through my portfolio and give my confidence levels on each investment and to write down my "known unknowns" about each of them and as many bear arguments as I can.
Hi Wimbledonsprinter
Your are right in that we can all have 20:20 vision with hindsight. In my younger days I recollect investing in a business that was nailed on. What can go wrong. I thought? Needless to say it went bust.
All the best
I got lucky sold and out most of my Best Of The Best (LON:BOTB) shares at £32. Still hold a few, but the damage could have been much worse. Just wondering if there is more bad news from other companies that might have benefited from lockdown at the time. I am a big holder of Gear4music Holdings (LON:G4M) . Does anyone have any thoughts?
Gear4music Holdings (LON:G4M) bear in mind that analyst forecasts are already set based on a big lockdown benefit unwind this year. In managements last trading statement they said that the perceived unwind is not as big as anticipated so analysts are actually upgrading rather than downgrading. Also remember that live music sales dropped off a cliff in lockdown and should now be returning thus Gear4music Holdings (LON:G4M) had both a positive and negative lockdown effect.
I'm not sure you can do too much read across between Best Of The Best (LON:BOTB) and Gear4music Holdings (LON:G4M) as they are very different businesses. Remember Gear4music Holdings (LON:G4M) is also rapidly rolling out its distribution across Europe. In its case it also has a moat, that being scale - the market is littered with very small players and is highly fragmented.
Lefty
The biggest difference between Best Of The Best (LON:BOTB) and Gear4music Holdings (LON:G4M) is that the former had a 20% increase in EPS predicted for 2022, whilst the latter has a 50% reduction in EPS predicted!
I’ve always been a fan of the approach of ‘under promise and over deliver’…I am hopeful G4M falls into that category.
Musing on Best Of The Best (LON:BOTB) , wondering at what price this becomes a candidate for an MBI? It’s already quite closely held by a few key stakeholders. Shares were sold in a placement at £24 creating a healthy war chest for the principals. They recently looked at the possibility of selling the company in its entirety but this came to nothing. Why not have back the whole cake, especially if it’s cheap enough? A cynic might even suggest there’s a fair bit of kitchen sinking already going on with today‘s announcements.
Gus,
They say that profit warning comes in threes. With the lack of airport physical presence to make up for the drop in online traffic, it seems like the business will continue to be under pressure. There is also very little in terms of innovation in this business and eventually might be competed away from the new waves of 'lottery like' businesses built on NFTs. Whilst the costs have reduced as the business have transitioned mostly online, online marketing cost will eventually catch up.
Watch the directors' actions - they might give it away if they choose to offload more shares given the sharp price decline. Perhaps a more conservative way is to adjust the net income over a cycle (say 10 years average net income) which comes out to GBP2.36Mn. That would put it on PE 60x roughly.
I don't have any positions, long or short in the company. I thought I would share my thoughts as I do enjoy the daily write ups here.
Yes I personally always stayed away from this as couldn't see anything particularly unique about the business (must be hundreds of companies doing online competitions) and last year's spike felt like it might be a one-off craze before people move onto something else.
Painful day for me, I run two portfolios, one for my brother and one for myself. I sold Best Of The Best (LON:BOTB) for my brother in June after the trading update with the infamous sentence (I had bought near the lows in 2020 for him and he got a return of circa 300%). For this portfolio as it is not my money, I follow a fairly strict rules based sell discipline - heavily influenced by the profit warning guide produced by Stocko.
I continued to hold in my portfolio as I had only bought in a lot later, and the profits I had made been wiped out. I had felt that the new valuation compensated for the risks. This is a good example of a number of biases no doubt - I also continually sort out confirmation to continue to hold and ignored those who sold. Thankfully I run a fairly well diversified portfolio and I am only down 1.3% today. I think this a lesson to me to be stricter with my own cash and not take punts when the story changes.
if the competition are willing to pay more per click for customers then there won't be a return to the lower costs that BOTB are hoping for. Surely this speaks to the challenges of an online only model rather than the differentiation they had when they had physical space at airports to show the prizes.
the only winners here are Facebook and Google
Yes and Alphabet and Facebook are what I should have been buying since June last year (when I first bought Best Of The Best (LON:BOTB) ) rather than buying £BOTB.
It is rather unfortunate to remember that it was Jim Slater who coined the phrase “Elephants can run) and yet that is precisely what Alphabet, FB, MSFT, Apple, and others have done over the past 12 months.
Can I learn the lessons? I hope so.
Regards
Michael.
Yes and Alphabet and Facebook are what I should have been buying since June last year (when I first bought Best Of The Best (LON:BOTB) ) rather than buying £BOTB.
Alphabet, Apple, Facebook and Paypal are the biggest gainers in my portfolio over the past decade. However, I'd be very careful about what conclusions to draw from that. Jim Slater was basically right that elephants don't gallop - but it so happens that these companies have gained effective monopolies online, as they've been faster to adapt than the regulators. Realistically their growth rates must slow, otherwise they'll be earning more than the Earth's GDP.
More typically the next set of multi-baggers that I own are all small companies - all less than £250 million when I bought them. The challenge is to hold on to the good companies while selling the failures. I'm always looking for smaller companies at a reasonable price with good quality metrics and trustworthy management. Once I become comfortable with the business model and the management I'll hold through downturns unless the business model changes (a big, diversifying acquistion for instance). No stock ever goes up in a straight line forever.
The one golden rule, though, is don't invest in anything where the management are at all compromised. I want managements that underpromise and overdeliver and who set an example for their staff.
And no story stocks. Cashflow is king.
timarr
Yes, as Jim Slater said when referring to the growth of large and small companies....
Elephants don't gallop but a flea can jump 200 times it's own body length, however, the trick is picking the right flea!!!
Reading the various comments left today by subscribers, it would appear that quite a few of them will be looking at their Portfolios over the weekend and thinking what they could have done differently so as to have avoided such heavy losses today, such at Venture Life (LON:VLG) , Best Of The Best (LON:BOTB) , etc. One of my Sell Rules which I have adopted over the decades, having learnt the hard way from experience in the early days, is to sell all my shares in a company when the management sell all or a substantial amount of their holding. As an example, I sold all my Venture Life (LON:VLG) shares when I learnt that management had sold between £6-7million worth of shares and simultaneously did a fund raising exercise. I wasn't happy with this news and so I got out.
Thanks Tim and I agree. I am not contemplating buying them now with the possible exception of FB and the majority of my pf is in companies with market caps below £700m (Games Workshop (LON:GAW) Boohoo (LON:BOO) Reach (LON:RCH) Tremor International (LON:TRMR) being the exceptions, I also have three US stocks 1% positions above this size) of which Best Of The Best (LON:BOTB) is now the smallest!!).
But over the past 10 years I have bought BRK, BVXP, Buffettlogy fund, Fundsmith, JPM, LVMH, NFLX, PYPL, TRMR, VUSA and DIS for my 15 year old son's JISA/SIPP (and made only one sale of Ford) and while it may or may not have out performed my portfolio, the ride has been a lot less gut wrenching and the returns acceptable.
Regards
Michael
That's the big downside to me,buying into high multiple growth stocks like BOTB, a safer & less stressful way is Quality imo, Hope a lot on here have managed to diversify enough to have not suffered to much.
Consiton, the quality score of Best Of The Best (LON:BOTB) on Stocko is 98
Is it the date or do profit warnings come in groups of three, Best Of The Best (LON:BOTB), Venture Life (LON:VLG) and £AVON. We all get it wrong from time to time so commiserations to holders.
Fortunately I do not hold, although once held Venture Life (LON:VLG) and £AVON. I sold Venture Life (LON:VLG) earlier this year for the reasons stated in my post of 4th February, which in large part have come to pass in today's announcement. It is not often I get it that right! As for Avon Protection (LON:AVON) I naively sold this for around £15 for a reasonable profit, not so clever as despite this morning's announcement it is still trading at £20 plus.
Excuse my musings and hopefully all three will recover, although my pick for the longer term would be £AVON.
Looks like £VLG story is that Hand Sanitiser Gel sales have dropped now we all have it on our shelves. BUT, it seems to me that the world will be using a lot more hsg over time. This allied to the recent acquisitions makes this a good (albeit risky) entry point for me
But I've heard warehouses are full up with hand sanitiser, prices in shops have also fallen, so I would not pin your hopes on sales picking up and margins will be squeezed.
I sold out of Venture Life (LON:VLG) some time ago, I lost faith in the management.
Boots were giving away hand sanitiser free with purchases last week when I was in there so must have a lot to clear off their shelves.
The fomite transmission of Covid - which hand & surface sanitisers are designed to prevent - has been found to be infinitesimal, e.g. here
"A real-life situation is better represented in the work of Dowell and colleagues7 in which no viable virus was found on fomites.
In my opinion, the chance of transmission through inanimate surfaces is very small" in the paper: https://www.ncbi.nlm.nih.gov/p...
So I think the promotion of hand sanitisers was (reasonably understandably) hyped by governments at the outset of Covid, but are now products largely bought by the over-neurotic.
I started selling Venture Life (LON:VLG) in early Feb, and ditched my residual position this morning. Looks expensive even on house broker's real EPS numbers
Hi Jonno - I do not hold Venture Life (LON:VLG) but reading your comment and being a bit of a novice investor (one year now) I trolled back through the SCVR reports to find your note from the 4th Feb to see if I could learn something from it. There is no doubt your assessment of Venture Life was spot on at that time so well done. This does go to show that you really do need to do your own research and make valued judgements based on that research.
I hope you don't mind but I decided to post your assessment again as I am sure other readers may be interested in reading it and hopefully get something from it that will lead to us all improving our investing skills.
Regards, Stephen
jonnoFeb 4, 2021
Venture Life (LON:VLG), somewhat of a conundrum. Having revisited last September's interim report and re-read the recent trading update, I have become a little more circumspect.
As mentioned in an earlier post, the use of EBITDA, rather than pre-tax profits does make me a little uncomfortable. Also reading through last September's interims it appears that the company benefited considerably from the sale of 'Disinplus' hand sanitising gel as the pandemic took hold, generating revenues of £3.2m, which represents 34% of the total revenue of Venture Life brands of £9.2m during the period. I recall watching Creighton's presentation of its interim results on PI World, last December when Pippa Clarke, the marketing director said that the market for hand gels had become saturated. In fairness Venture Life (LON:VLG) have said that it does not expect to replicate similar revenues from hand sanitising gel in the second half, although it does expect demand to continue. Nonetheless I prefer to take my lead from the management at Creightons.
I also remain a little wary of the contract to supply oral care products to China. Historically Chinese companies have not always been paragons of good corporate governance. Finally I note the large increase in 'Trade and other receivables' contained in current assets in the unaudited accounts to the interims. This is shown as just over £10m versus £6.3m for the prior year. At present I have not found an explanation for the significant increase. It is possible that I have missed something, which wouldn't be a surprise.
The upshot of the above is that I have decided to exit my investment in Venture Life (LON:VLG) at a modest profit. The company is in rude health financially and may well make some successful acquisitions. It may well be that I have thrown the baby out with the bath water.
However I personally feel more comfortable investing in companies where I believe I have a better understanding of the business and its finances and which update the market with greater clarity.
These are just my views and I wish those who continue to hold and invest in Venture Life (LON:VLG) the best of luck
Flagging for holders: Zeus Capital has published a new note on Boohoo (LON:BOO) vaunting its big 5 yr investment plans.....and it is a great note regarding how Boohoo (LON:BOO) looks value wise v its competitors.
As per the etiquette I will continue any discussion on Boohoo (LON:BOO) thread. Will take a bit of time to read too........
Zeus says, 'At last night’s closing share price boohoo trades on an FY22E PER of 23.9x falling to 18.4x in FY23E. Excluding the market fall out from COVID-19 in March 2020, this is the lowest PE rating the Group has traded on in c.6 years'.
'We believe this represents an unjustified discount to its identified peers given its consistent track record of profitable growth, the flexibility and agility offered by its operating model and its proven ability to act as a sector consolidator'.
Zeus is house broker and NOMAD
Hi Tinner
Could you link to where you continue your thread on Boohoo (LON:BOO)
Thx.
Michael
sympathies to all holders of Best Of The Best (LON:BOTB) - very painful and frustrating to endure a drop like this. Hope nobody takes too much damage to their overall capital.
Another angle on Best Of The Best (LON:BOTB) (I hold) as I think about the numbers.
it's quite interesting to ignore FY 04/2021 as a one-off year, and instead look at the years either side, as follows:
FY 04/2020 (little covid impact): revs £17.8m, EPS 37.4p
FY 04/2022 (new guidance): revs £40.0m, EPS 53.3p
Revenue is more than double pre-pandemic level, but profit up a lot less. Which implies there might be a fair bit of cost that could be stripped out, if he wants to run it for profit rather than growth?
Also, if FY 04/2021 hadn't happened (the bumper profits year) then we would probably look at the above numbers, put it on a PER of 20+ and see it as a strong growth company.
Clearly lockdowns had a lot more effect than was realised, but even so a more than doubling of revenues (ignoring the bumper year from lockdowns) is still very impressive. Or looking at it another way, could guidance be reduced again in future?
Hi Paul
On Best Of The Best (LON:BOTB) it would be nice to be optimistic from here but what is your view on management who they sold in to the market at £25 will have had the data that would have indicated to them the direction of travel of sales and suckered holders and new investors (Slater) in to buying over priced stock off them?
I am afraid that regardless of where the company goes from here I don't want to be invested alongside management like this, they have lost my trist, and I will be selling down over the coming weeks.
As Buffett said I can make my money back elsewhere.
Regards
Michael
Michael
The Directors made a secondary placing of stock on 31 March 2021 at £24.
Seven weeks later on 23 May they issued an update in which revealed that they continued to enjoy healthy trading:
"The Board is pleased to confirm that revenues and profits before tax delivered in the Period are expected to be in line with market expectations, which were most recently increased in March 2021"
Not sure why you are assuming they were aware of a slowdown at the time of the March placing?
Apologies Jesse - repeated your comment but still wondering what if any evidence there is regarding supposedly unethical management
Hi Michael - the £BOTB placing was announced at the end of March and there was a trading update in mid May. The TU was in line with expectations. Not therefore sure what evidence there is that they knew of the more recent fall in sales at the time of the placing.
Having experienced many profit warnings and several 100% wipeouts I know that one of the biggest pitfalls for any investor is their own emotions. The only sound basis for reacting to any news flow is objectively and unemotionally.
For me looking at the overall picture I will hold. The Hindmarches by my calculations still own over 20% and are strongly incentivised and experienced. I’m not sure that Mark Slater got ‘suckered’ as you claim - I doubt that he is suckerable!
The only real issue here is profitability going forward and at the moment I am willing to hold.
where is the evidence that management have somehow behaved unethically - no management anywhere has the ability to precisely see the future.
Best Of The Best (LON:BOTB)
OK accepted I am allowing to much emotion to creep in here and I withdraw my comment but a business where management have little or no visibility of revenues three to five months out and don’t feel that they can make a reasonable predictions of same is not a business I should be invested in. That is one of the many lessons I need to take away from here.
My apologies for my out of turn comments.
Michael.
My worry on Best Of The Best (LON:BOTB) is the EPS number (42% 2 year growth) relative to the revenue increase (125%). They state in the RNS that they have a primarily fixed cost base so how much cost can really come out? This provides the operational gearing on the way up but is obviously brutal on the way down? Also, most marketing costs are variable but clearly at +60% price increases this has made new customer acquisition non economic (else they would be spending on marketing irrespective of the increase).
Then you have new competition also spending heavily which suggests that marketing rates may normalise but perhaps at a higher base given the competition. So room to grow maybe but at even lower margins?
This business feels to me now like it has almost no moat. Whilst it was under the radar making relatively insignificant profits there was no competition. But as profitability has risen competitors like Omaze have come to the fore and it appears that margins have eroded quickly. It would be interesting to see how loyal players are in the face of competition. I'm not sure we got any sense of that in the announcement and I would now be fearful of some churn.
Thus I'd be reticent to view it as a growth stock anymore. The prospective bidders are probably breathing a sigh of relief but I do wonder if they might come back given the reduced valuation.
I agree, the issue here is that it's non economic to get more customers via the methods they have been, (presumably advertising, google ads, facebook ads etc), the challenge is will they manage to find other routes to get people to buy that are cheaper ?
I completely agree though that they have no moat now, and they're in a battle with competitors who may have new ideas, and be hungrier than the current company is,
K
It's interesting Best Of The Best (LON:BOTB) do not mention competition at all, because Omaze have been advertising on TV and also heavily spending on online ads - I would think this is the reason that the marketing costs are up as keyword targeting is done by bid.
Will costs normalise? That seems to me to be reliant on whether Omaze works or not. As only net profits are passed on to charity, it makes sense for them to advertise as long as it brings in the money. It still could be that their competitions make a loss, in which case they simply exit the market.
A new competitor (Yiannimize) also has come on, playing 'spot the coin'; this also is competing for the same keywords. This is backed by a Youtuber of the same name, would presume he has some money to finance losses.
However, it seems to me that there are other platforms who offer competitions, who simply use a competition to sell a car for a higher price than on the free market. The types of cars they offer are starting to converge (at BOTB's lower end).
From a customer-facing point of view these are much fairer - someone actually wins the car they enter for, maximum tickets are capped, your chances cannot be diluted by someone paying a lower ticket price - none of these factors apply to BOTB.
In my view the reduced customer demand is a result of alternative platforms grabbing market share. All the car comps (and to a lesser extent, Omaze) are competiting for the same target market, which is a relatively thin one.
Anecdotal evidence to support Snoo's analysis on £BOTB
On Facebook, I see a lot of ads that meet this pattern: answer a skills-based question, pay £X for a ticket, win this vehicle. I have been tempted because the prizes are something I would actually drive - VW campervan, Land Rover Defender, motorbike. I have no use for a Lamborghini... The barrier to entry is quite low for these companies and it makes it harder for BOTB to stand out and takes sales off them. I don't remember seeing any of these ads before lockdown, it's a new phenomenon and the number of new entrants to the market is unsustainable, in my view.
Here's a run down of my FB page ads this morning:
Ford Transit Trail AWD £1.45 - BOTB
1976 Suzuki GT1100 £1.99 - Aspire Competitions
2-tonne Mini Excavator £12.99 - Agri Giveaways
BMW F700 GS £3.97 - The Giveaway Guys
Triumph Scrambler XC1200 £8.57 - Rev Comps (whose skills-based question is: what is the capital of England?)
2016 Kubota mini digger £24.97 - Lucky Day Competitions
In case you are wondering, yes I did once buy a mini digger on Facebook marketplace and I will clearly never be allowed to forget it...
Yes, I see it in exactly the same way. The fact they either don't acknowledge this or, worse, aren't aware of it, is concerning.
I can see how rising ad costs is impacting them. They probably did loads of FB advertising. Last year, FB rates dropped as advertisers pulled budgets. Which was also when BOTB saw huge revenue and profits. But the FB ad rates have risen very strongly YoY. So I can see how their "cost per acquisition" (CPA) has tipped to become unprofitable in the last 6 months, and therefore they've had to pull back on the ad activity.... which means less players acquired.
So it turned out that Best Of The Best (LON:BOTB) was heavily dependent on ads bringing in players, and maybe too dependent on a few ad platforms like FB. It looks like there is no "base" of loyal customers playing week in week out, that all sales had to be "bought".
Wonder if there's any other companies, especially those heavily dependent on FB ads, about to issue their own profit warnings due to rising ad costs?
There's a similar ad cost inflation on Google PPC too (see their latest quarterly results). So businesses that get alot of traffic like On The Beach (LON:OTB) and Moneysupermarket.com (LON:MONY) might also be suffering heavily.
Best Of The Best (LON:BOTB) (I hold)
Hi Dahokolomoki
You said "FB ad rates have risen very strongly YoY."
I can't find information on FB Costs per Impression (CPI) in their latest earnings release, but assuming this is correct, do you know what the reason is?
I imagine it's due to either:
If it's 2, I would hope this would revert to more normal levels in time.
If it's 1, won't Best Of The Best (LON:BOTB), or indeed any online advertiser, constantly need to factor in rising CPI rates and therefore just pay up for more expensive new users?
----
For reference I can see that Google's Cost per Impression is up +63% for April-June (and last year it was down -23% YOY) = +25% for 2021 vs 2019.
But I imagine that most Best Of The Best (LON:BOTB) customers don't come through Google anyway (who googles "win a car" or "best of the best"?), so presumably this doesn't really matter.
Any thoughts would be appreciated.
A
FB ad rates: can't remember exactly where I saw it, but a quick Google search brings up some articles, like this ZDNet one that states "Advertising revenue growth in the second quarter of 2021 was driven by a 47 percent year-over-year increase in the average price per ad"
I also work in Digital Marketing, buying large sums of FB ads, and the sources of data I have seen (direct, from agencies, from FB, from marketing media outlets) have been consistent on their reporting of increasing online ad rates in Q1 and Q2. There has been a plateau-ing and slight moderation in Q3 IMO though, so ad cost inflation might be "transitory".
Best Of The Best (LON:BOTB) (I hold)
Thanks Dahokolomoki
Yes, I've seen the higher Ad revenues reported by the social media companies, though I wasn't sure if this was purely to do with:
It's been quite hard to find any information on historical CPM rates, but I did find the below chart, which confirms the rapid rise, especially on iOS devices at the end of Q2, which is linked to Apple's IDFA changes (the system that allows advertisers to track users.)
The source article is here.
https://www.consumeracquisitio...
Does anyone know where we can track CPM information on a regular basis?
---
FB itself doesn't report this metric, though it did make this comment in their latest results:
"The impact of the pandemic on user growth and engagement, the demand for and pricing of our advertising services, as well as on our overall results of operations, remains highly uncertain for the foreseeable future.
In addition, we expect that future advertising revenue growth will continue to be adversely affected by limitations on our ad targeting and measurement tools arising from changes to the regulatory environment and third-party mobile operating systems and browsers."
It's almost as if BOTB's success is dependent on Facebook's algorithms working properly.
And not just BOTB.
Some digging revealed a few other companies impacted by Apple's Tracking change, including the latest results from Zynga (a gaming company), where the share price dropped 17% on the day of the announcement, albeit with a glimmer of hope announced at the end:
https://venturebeat.com/2021/0...
"“At the same time, Apple rolled out their IDFA [change] and the market got kind of choppy as well. We decided to pull back our user acquisition spending to see how it settled. We saw a reduction in audience from from the great reopening. We were also not aggressively acquiring new players because we didn’t think it was the right thing to do at that time.
So that put a little bit of a softening on our revenue run rates for the second half....
...Now, the good news is that we’re starting starting to see the recovery and the core business is strong. We’re seeing good early returns on user acquisition trends.””"
The above almost exactly mimics the latest commentary from Best Of The Best (LON:BOTB) .
I've read many comments here on recent poor performance being down to incompetent or deceitful management, and increased competition...but what if BOTB's success has luttle to do with any of those factors and is instead completely subject to systems above them working efficiently?
And if that's true, then why hold BOTB at all?
It doesn't matter if it has a moat if it can't control the drawbridge
As a holder it's certainly an interesting question for me personally.
As an aside, I think the above, at least for me, shows how hard it is to have conviction in anything given all the unknowns we don't even know we should be keeping an eye on.
A
Hi abtan
I think your suggestion - that the increase in advertising costs is due to Facebook and Google's algorithms malfunctioning in the face of the changes to tracking made by Apple - is the most likely explanation for the most recent issues at Best Of The Best (LON:BOTB) . It certainly makes more sense than some of the other suggestions.
Which leads us to your question:
what if BOTB's success has luttle to do with any of those factors and isinstead completely subject to systems above them working efficiently?
My answer to that, roughly, is that it's no different to most companies who rely on third-parties for parts of their supply chain, operational systems or key components. All companies are, to some extent, dependent on things outside of their control. This is why, in the short term, even the best companies can hit unexpected roadbumps.
However, Facebook and Google depend on companies like BOTB using advertising to promote legal activities - they have no reason to deliberately undermine their customers. I'd be more concerned where companies tend to stretch the limits of what regulators regard as acceptable. BOTB doesn't seem to fit that profile as far as I can tell.
If this is the major current problem for BOTM I'd expect it to normalise over the next few months. If it is though, why wouldn't the management have pointed this out - it's hardly something they could be blamed for?
But maybe, therefore, the current price is an opportunity? Maybe.
timarr
Hi Abtan
Good posts on Best Of The Best (LON:BOTB).
TBH I think calling Omaze illegal is going too far. Similar restrictions apply in the US (lotteries are not permitted without licencing). It is obvious it is a paid prize draw, but perhaps the more compliant way to describe it is a free draw with optional paid entry (you can enter by post).
But it does illustrate the grey area in which these firms exist. The terms could simply be reworded in future, banning these competitions. The charity aspect, IMO is an 'investment' - it is a selling point and also potential protection from any other action. But the structure to my mind is not good value for either customer or charity.
But let's not think BOTB are immune from this either. If I ran a competition where you had to guess where I think the FTSE will end to 2 decimal places today is that skill or luck? Note that when you 'spot the ball' at BOTB you are not spotting where the ball actually was, but where the ball was according to their panel. There are other aspects that I think are tenuous as well. I don't think most players are actually aware that if they spend £5 on one ticket their chances can be diluted out by others playing at £0.45 going for a different prize.
Its interesting that you capture the average prize giveaway, it does show that recently at least the average value of prizes are declining. Looking at the maximum prize available they are some way off what has been given away earlier in the year- this is much more pronounced in the midweek.
One metric you may like to consider is customer value, which is not affected by variance. Today's competition shows a £4.80 competition for a Porsche Turbo S (cash alternative £128,000). Going on a cached page, in January, a chance to win for the same car (cash alternative £125,000) was £2.30. All the other prizes follow the same pattern (cash alternative/ticket price is lower). Even allowing for the fact that overall entries could be down 20% or so, someone playing today is getting much worse value.
The new competition I think is a bit of a gimmick but has its uses for the company. The prize variance is very large at the moment from smallest to largest (over a factor of 10 for the weekend). But the prizes here have very low variance - £40k seems a good guess as the liability no matter what combination is picked. So if £80k a week could be shaved off the average giveaway by virtue of lower prizes, they could run this special competition permanently and still be better off.
So at this point we are seeing overall average price values reducing as well as the effective cost to entry increasing - customers paying more for less. We can see businesses with high monoply effects (Rightmove) or big barriers to entry/switching costs (electricity) do this, but BOTB doesn't have any of these features.
Going down a path of trying to restore profits by increasing ticket prices while reducing their prizes paid out is not likely to work long-term. They go on about engagement, but I actually think this is pretty poor - basically one-way videos showing winners. Their Youtube channel has 63k subscribers and has very little in engaging content. By contrast the new competitor Yiannimize is pushing 2m subscribers, is much more watched (305m total views vs 15m), and has genuine content. In terms of fostering community among customers this is way more likely to succeed.
One thing I noticed about the figures is that the massive increase in revenues to 2020 was done without employing any more staff; it's basically turning the advertising dials up and down. Yet the next years forecasts (profit £6m) indicates that they have already been paying higher costs. One could argue that if 50% of the business was done by old customers, why bother advertising at all? Iam inferring that even the old cohort of customers still requires much advertising to.
It is right that there are unknowns. On the current valuation, this could be a bargain if sales come back and advertising rates go back to normal. Even if not fully recouped it could still imply £10m a year - a very low multiple if you believe that growth can resume.
However, these factors will be visible to the insiders way before any investor can deduce it. And lack of money is not an excuse, seeing as they cashed out very recently. So big directors purchases/share buybacks I think is going to be the biggest clue here.
£botb (I hold)
Hi snoo
If you follow the links in my original post omaze definitely looks to be operating illegally.
You cannot run a paid prize draw competition in the UK, even with a free entry option, unless you are a lottery, which must be a registered charity.
Omaze is not a registered charity.
Zero skill is involved when buying a ticket. It's just a raffle.
I'm happy to be corrected if I've missed anything, I'm just not sure what it is.
I will respond to some of your other points later on.
Cheers
£BOTB
Sorry, I can't edit my post, but it's worth adding that US legislation/regulation, whatever they are, are not applicable to omaze UK.
Re: BOTB and the US: sure, I realise that laws are not applicable - the point is that the company must have some experience at navigating a grey area to make their competitions legal.
For instance, in the UK, Omaze are registered with the Fundraising Regulator which repeats the laws for running draws. Maybe it's worth a complaint to them? It would be a massive coup if you are right, seeing as Omaze have been operating here for over a year here. (I think Omaze is a bit of a rip-off for reasons given before). My suspicion is there is some technical explanation which defeats the wording. They are not alone: Raffle Houseis also a prize draw but they also have a page explaining their compliance. It would be a huge regulatory oversight if these things were in breach.
I should have added IMO, Yiannimize increases the regulation risk. Their competitions run exactly the same as BOTB; multiple competitions open with one draw, whoever gets closest gets the prize. On some weeks someone might win a supercar, landing them with a loss. But on a lot of other weeks someone might end up winning a low value prize: Louis Vuitton bags, a golf or kitchen bundle might be £1.5k tops, 20% of the prizes are maybe £5k or less. Entry to the lower prizes are much cheaper, thus they can be overweighted in the draw, and each entry has an equal chance.
Personally I think this is rather sharp practice, many customers will be ignorant. The scale of this is much worse than BOTB (where at least customers win a car). But the regulatory action if it comes down would affect the companies massively.
Best Of The Best (LON:BOTB)
Hi Snoo
Thanks for sharing the Raffle House compliance page, that's really interesting.
I didn't click their links (so I assume that they are indeed pointing to the correct regulation) but this comment did catch my eye:
"Raffle House has NOT joined the growing list of prize competitions that have been shut down by the Gambling Commission,"
Which competitions have been shut down by the GC? And more importantly, why?
----
On a separate note, being on the Fundraising Regulator (FR) Directory doesn't really say much about Omaze, except that they are:
It's probably worth adding that the FR is funded by companies and charities that want to be in its Directory, such as Omaze.
---
In any case, I think we're moving away from the issue of investing so I think I'll leave my Omaze analysis there.
Thanks again for sending those links through.
A
Best Of The Best (LON:BOTB) (I hold)
Hello again Snoo
"If I ran a competition where you had to guess where I think the FTSE will end to 2 decimal places today is that skill or luck?"
I think the more pertinent question is:
"If I ran a competition where you had to guess where the same x10 Stockopedia subscribers think the FTSE will end to 2 decimal places every day is that skill or luck?"
Not sure I want to get into the skill or luck debate though.
---
"Its interesting that you capture the average prize giveaway"
I've forecasted Revenue for a while now by doing this.
As you can see below, GP has been around the 60% range for a while now so if I could estimate COS, I could estimate revenues reasonably accurately.
Having said that, this H1 looks different, and I am expecting a gross profit closer to 51%, or at least that's what I'm tracking.
For clarity I don't generally look at research notes so I don't even know what the broker is forecasting.
---
Thanks for sharing that cached page - very interesting.
I knew that BOTB dropped prices in 2020 (I could see) but it's certainly interesting seeing it in the digital flesh.
I'm not sure the ticket price increase is universal though.
For reference I see that BMV M5 (cash alternative £82k) tickets are currently £2.75, much lower than back in 2019 = c£4.80 (5.65EUR.).
I did consider setting up a crawler to track ticket prices, but to be honest I wasn't really sure what it would tell me unless I could track user numbers as well (which the company doesn't divulge.)
---
To reinforce what I've said previously I still think the future of the Best Of The Best (LON:BOTB) - and the other raffle/gaming websites - is dependent on the changes made by Apple + IDFA.
I read of another company this morning - Poshmark (US-based) - claiming in their recent earnings release that they were forced to spend more on marketing to get the same number of users to their app due to a poorer ability to target users due to the Apple changes.
As a result their expected profitability % was lower than expected.
I don't know why this situation would change in the future - perhaps more money being targeted to Android users - but I am coming around to the belief that future growth is simply going to be more expensive...and hopefully BOTB will take advantage of their cash resources to pay up and get things going again.
A
Best Of The Best (LON:BOTB) (I hold)
I still don't understand why Omaze are considered a competitor in the UK.
They have 2 houses on raffle on their UK website only and what looks like a sporadic car draw (is it monthly?) which can only be entered if a user buys a ticket for 1 of the house raffles.
And from what I can make out it's operating illegally. Here's my post from last week.
The tickets are more expensive too.
So 2 genuine questions:
My personal albeit subconsciously biased response to both questions is 'No' especially question 2, which I can only imagine being impacted by macro market forces.
Any counter thoughts would be most appreciated.
A
Avon Protection (LON:AVON) also stick out a profit warning today and down 20% - seems more due to logistics/fulfillment delays rather than lack of orders but enough to knock this and next years revenue. I guess delays could lead to cancelled contracts though.
I hold both Best Of The Best (LON:BOTB) (small) and Avon Protection (LON:AVON) (one of my larger holdings as I originally bought in under £10/share) so not a great day in the Gus 1065 household but hey ho. Personally, while I think the Best Of The Best (LON:BOTB) profit warning is a stinker I’m a lot more sanguine about Avon Protection (LON:AVON) . The reasons given for the various Avon Protection (LON:AVON) revenue delays seem to be market wide macro issues (labour market tightness, procurement and shipping) rather than company specific and appear to be of a short term nature. I think it’s good that the company is on the case and prudent in managing the market‘s expectations. I see today’s 20%+ correction as an over reaction and am using it as an opportunity to top up my holding. FWIW I also think it makes Avon Protection (LON:AVON) an even more attractive bid prospect at this reduced price level.
Gus.
Warning bells were ringing when Best Of The Best (LON:BOTB) directors were selling at £24. I got sucked in to the story and bought at £27. Sold out this morning for a reasonable loss. Good lesson for the future!
sold then april 1st today friday 13th...
Best Of The Best (LON:BOTB)
Kieran
Yes indeed but also assumed (makes an ass out of u and me) that Mark Slater investing was a sign of a good company.
Basically the management screwed the share holders and have lost all credibility. I will keep to myself what I really think of them because I don’t want to get sued. But I will say that the data they had when the sold down their holdings will have told them the direction of travel of the business. What a dreadful company and dreadful management. It is still shocking what goes on in the world of AIM.
Stokcopedia should have definitley picked Best Of The Best (LON:BOTB) up as a "Sucker Stock".
I should have followed the Stocko profit warnings guide and sold out but at the moment sitting on a massive loss.
Will be selling down, starting today, over the coming weeks and am not interested what happens while run by current management, this is now on the barge pole list for me.
Been a dreadful morning as I also hold Avon Protection (LON:AVON).
Regards
Michael.
Best Of The Best (LON:BOTB)
MichaelFBS
Basically the management screwed the share holders and have lost all credibility. I will keep to myself what I really think of them because I don’t want to get sued. But I will say that the data they had when the sold down their holdings will have told them the direction of travel of the business. What a dreadful company and dreadful management. It is still shocking what goes on in the world of AIM.
I wouldn't presume this is the case. I would agree the timing looks sketchy but crapola like that happens sometimes - the directors had a ridiculously high % holding for a listed company (76% i think) . The facts off the matter here is the directors flagged up exactly what they were doing and shareholders had a decent chance to exit at the same time as director selling at prices 20% above what the directors cashed in for.
What was the alternative here ? they didn't sell - carried on as normal and the shareprice would have been at this place anyway - same end result. IMHO the directors did some bods a favour by selling and flagging up that potentially the price may be toppy - i would guess quite a few shareholders took note of what directors did and dowsized their holdings accordingly?
yes you’re right, Directors crewed over shareholders whilst pocketing £60 million & setting themselves & their families up for life.
I don’t care about being sued- I have told them- Rupert Garton & their PR guy Toto Berger from Buchanan what I believe they have done. They only said on 13th May that they were trading in line with market expectations.
Moaning won’t change a thing. Like Paul, I will get out if these rebound. Management have proven themselves to be untrustworthy with zero credibility.
Michael,
I feel your pain as Best Of The Best (LON:BOTB) was my largest holding until today - very poor execution on my part.
However, you may want to look into your own decision making process.
Maybe mgt, stockranks, Slater screwed me and others over, but I can say with some certainty that I am responsible for a large part of any screwing.
Good luck with it & hope you can find a good place to recover any losses.
Vivek
Pretty good estimate, Paul. 820-1000 bid to offer at start.
Very poor updates from Venture Life (LON:VLG) and Best of the Best (LON:BOTB) this morning. Luckily I took the decision to sell both but Slater bought into both raises:
#VLG @ 90p for 15% stake
#BOTB @ 2400 for 9% stake
Wonder what their thoughts are?
Good luck to all holders.
So, you promoted both without really doing work, particularly Venture Life (LON:VLG) , and now you gloat that you got out at a higher price whilst some people are left holding the bag?
Classy! But hey, don’t let it stop you from promoting other stocks…
While adopting the brace position for Best Of The Best (LON:BOTB) , thought I’d copy across from Monday’s SCVR another Friday 13th ray of sunshine with details of the Mccoll's Retail (LON:MCLS) placing that came out late yesterday afternoon. Might be a good day to hide under the duvet?
——————-
Anticipated Mccoll's Retail (LON:MCLS) fundraising duly pushed out into a seemingly reluctant market at 20p share to raise up to £35 million (£30 million/£5 million under an Open Offer). Up to 175 million shares represents between 52% to 60% dilution for any existing shareholders not taking up their rights in a partial Open Offer. At 20p a share this is a 43% discount to the 35p share price when Paul posted his write up on Monday.
https://www.investegate.co.uk/...
CEO Jonathan Miller has indeed put his hand in his pocket to the tune of £3m/15 million shares. Other directors have added their support too. Significant sticking plaster but I fear this canine still has too many fleas ….
Gus.
Mmm. Mccoll's Retail (LON:MCLS) very deep discount for a very large chunk of sales. Good management take up, and interesting growth in expansion programme. This segment of smaller convenience stores must be growing fast, and they offer a really good service, all IMHO.
McColl's Retail (LON:MCLS)
" Significant sticking plaster but I fear this canine still has too many fleas …."
Yep - this really is a bit of a basket case.
Per latest results
borrowings £110 mill (i have ignored lease liabilities of £180 mill on top !!)
and "trade and other payables" £186 mill
£35 mill will certainly help but definately sticking plaster type fix when really when a lorry load of gorilla tape probably wouln't be enough to make this company comfortable ref paying what they owe if it ever had to be paid "on demand"
I have to agree here. Not done any deep research but spent the last hour looking. For me, there are three things making me bargepole Mccoll's Retail (LON:MCLS) for now:
If they had done a CVA or completely restructured their store estate plus rent reductions during COVID, it would maybe be an interesting story as structurally they would have reset their cost base and also store portfolio. But...
This is a hard profit warning from Best Of The Best (LON:BOTB) but the precise clarification is pretty helpful and a key point for me is 'The Company's revenue is c.2.5 times higher than the corresponding period in FY 2020, the pre-Covid comparative year.' I wish they had put more focus on how their business is growing compared to pre-COVID to understand how this is performing for 'normal times'. FinnCap have just published a free note which says 53.3p for FY22 and 64.1p for FY23. If this falls to £7-8 as Paul suggests, or worse, then that might represent quite a good buying level.
If you look at the Finncap note they are only predicting a fall in revenues of 12.4% for FY22 and a small rise of 5% revenue in FY23 (too low??) so this does seem to be primarily about higher marketing costs which Best Of The Best (LON:BOTB) may be able to tackle given this is a variable cost and they may find more effective marketing channels.
This may have read-across for other internet focused businesses as presumably the higher costs of acquiring new customers will translate to others. It'll be interesting to see if Asos (LON:ASC) Boohoo (LON:BOO) etc comment on that or whether actually the issues Best Of The Best (LON:BOTB) are encountering are more to do with how they execute their marketing spend.
I was very excited to hit an all time high last night on my portfolio but given Best Of The Best (LON:BOTB) are still my largest holding I guess this is short lived experience. Having been 20% of my portfolio at the start of the year its shrunk to 5.4% before trading today so looks like still quite an hair cut but not has bad as it could have been. This has obviously been partly due to the already significant drop in the price but also I have been pruning 250 these to reduce my exposure since the first warning (wish I'd have done more now!)
Will see if I can offload a few more this morning but has Paul says looks like we have to hold now and hope for the recovery. As someone who bought in at 250 over 4 years ago I have already taken out far more than I put in but until the company can stabilize it's difficult to find many buyers.
To be a fly in Slaters office would be very interesting this morning
Patrick
Re Best Of The Best (LON:BOTB) vs £ASOS or Boohoo (LON:BOO) - I guess the key issue is not the cost of acquiring customers, but rather that out of Lockdown people have so many more options to spend their money. Whatever the ins and outs of customer acquisition and other rising costs, the fundamental point is that people continue to need and want to buy clothes, probably more as life normalises, and in the case of Boohoo (LON:BOO) now, also beauty products, etc., whilst playing an online game / gambling to distract oneself from boredom, etc (remember it’s origins were killing time at airports and shopping centres) has little relevance now.
The company does specifically say the cost of even reaching potential customers (not just the acquisition cost) is a problem: "the cost per thousand impressions (CPM) on social media platforms - which account for two-thirds of BOTB's marketing spend, increasing by up to 60% compared to previous levels".
Best Of The Best (LON:BOTB) (I hold)
Hi Patrick
You said:
"I wish they had put more focus on how their business is growing compared to pre-COVID to understand how this is performing for 'normal times'."
I couldn't agree with you more.
I thought today's update was actually quite poor, and I don't mean the change the forecasts.
A slowdown post-lockdown was inevitable so giving us vague % details on the 15 weeks pre- and post- April 12th or April 30th (I kept getting confused which one they were referring to), without supplying any actual numbers doesn't help form any sort of opinion on the future direction of the company or help us compare to "normal times."
Some further observations of my own:
The current year is forecast to drop 13% - as a long term holder I will happily take that trend.
Many of my holdings are reporting a slowdown or reversal after a bumper year.
If this is the base from which the +30% growth re-starts then I'll be a happy person.
To be honest I'll be happy if growth returns to +20%.
This seems like a remarkably safe base from which to grow the business.
I was expecting churn to be much higher, so again, some of this seems like it will be in addition to the safe base I noted in 3.
Here's a snippet for any interested:
---
In conclusion I'll probably continue to hold for now. I'm yet to see anything that would convince me that growth will not return in the future and even if it doesn't the current price seems fairly valued so I would hope further downside is limited.
Good luck to all holders.
A
Hi abtan (and others) for your thoughtful posts on £BOTB.
Clearly plenty of raw feelings - something of a „lover scorned“ emotion about this one for many. FWIW, I took the opportunity to double my (small) holding yesterday at about 825p/share. Fools and their money and all that but for me at this price level the risk/reward doesn’t seem too bad.
Why? At risk of betraying a confirmation bias, I agree (albeit without the detailed analysis to back it up) with abtan‘s appraisal that stripping out the Covid effect, £BOTB‘s core user base seems pretty sound underpinning much of the revised eps of about 52p share. Trying to extrapolate crazily high Covid growth rates of >100% pa were never realistic but this is what boosted the shares to £35 or so on PE‘s in the 30‘s which with hindsight was never really on for a commoditised, low barriers to entry aspirational lottery (sorry, game of skill and judgement - personally I still think spot the ball is just a „poll tax on the stupid“).
At 800p a share, however, it becomes more of a cash cow proposition than a high growth glamour stock still with the possibility of decent rather than exponential growth to boost the core earnings base and the background possibility of either the management taking it private and/or one of the potential suitors identified in the abortive sale process of a few months back coming back in now that it could probably be acquired for a fraction of its previous valuation. Also, I took a look at the Stocko report from June 2020 when the share price was last at about 800p, just as the shares were taking off like a scalded cat.
At this time, estimated eps for 2020/21 was about 33/28p and the PE was 28.1, compared to yesterday‘s „market melt down“ figure of 52p/PE of 15x. Essentially it’s still the same company, same business, same market albeit with a bit more competition (which doesnˋt appear to be eroding the core punters base) and a now entirely online operation with a significantly higher level of core earnings. Clearly private investor sentiment has cooled with many PIs thinking they’ve been legged over by the management playing „pump and dump“ at £24 a share just before a profit warning but the Contrarian in me thinks it’s now got more upside than downside from here.
As I say, a fool and his money ….
Gus.
My morning smallcap tweet: Best Of The Best holders will need an ambulance, not a supercar, after this crash.
Best Of The Best (LON:BOTB) Venture Life (LON:VLG) SysGroup (LON:SYS)1 Morses Club (LON:MCL) Sportech (LON:SPO) Braveheart Investment (LON:BRH) Zegona Communications (LON:ZEG), Westminster (LON:WSG)
Best Of The Best (BOTB) guides FY22 earnings c.62% below mkt exp due to drop in new customer rev and much higher ad costs. Has spent less than budget on new customer acquisition due to poor value. "We are hopeful that the cost of acquiring new players will normalise before too long." [SP=1460.06 Cap=137m]
Venture Life (VLG) guides H1(June) rev down 18% despite £1.1m sales from the acquisition of BBI in early June. Blames lower sanitiser and Dentyl sales. Outlook "H2 will have a more meaningful contribution from the new acquisitions and the business is well placed to benefit from the confidence that can be seen as the UK and global economies..." [SP=99.89 Cap=126m]
System1 (SYS1) guides Q ending June broadly in line with prev Q. Expects double-digit year-on-year sales growth in H1 overall, [SP=320 Cap=41m]
Morses Club (MCL) trading in line. Will reorganise into new holding co U Money, to replace MCL in Oct. Claims it's necessary for "realignment of the Group's structure to allow it to better facilitate the ongoing development of the Group's digital strategy." How odd. Is there another reason? [SP=82.6 Cap=109m]
Sportech (SPO) mitigates failure to get Connecticut sports betting licence with an exclusive 10-year commercial arrangement with the Connecticut Lottery Corp. [SP=35.7 Cap=67m]
Braveheart Investment (BRH) £2.5m placing at 18p, a 21% discount, to accelerate the development of Paraytec's Covid testing instrument by taking direct control of the final design and engineering packages. [SP=22.51 Cap=9m]
Zegona Communications (ZEG) as expected, tender offer for 98% of shares at 153.5p. [SP=149.95 Cap=328m]. I hold.
In line: Westminster (LON:WSG)
Someone asked yesterday what is my source for these summaries. It's https://www.londonstockexchange.com/news?tab=news-explorer&headlinetypes=2&sources=RNS&period=daily&page=2&headlines=11,23,185,170,74,16,19,3,18,25,153,57,83,186,192,68,77,72,21,20,59,45,151,33,32,37,36,35,34,161,29,164,189,190,26,28,27,58,129,15,14,155,154,53,30,54,55,56,187,46,139,70,39
Indeed - Best Of The Best (LON:BOTB) on my mind too, A poorly timed investment for me, and I can't imagine that today will be a sensible day to get out. The question is, what is a fair price for it now?
£botb trading update today. Ouch! This looks dreadful. Given the thin liquidity here, I’m expecting a rout.
£botb profit warning