Small Cap Value Report (Fri 13 Nov 2020) - self help books, CGS, GFRD, FRP, RBG, BYOT

This part written by Paul
Good morning, I suppose I'd better write something about shares! (the self help books stuff below was written last night)
Agenda - these news items have caught my eye;
Galliford Try Holdings (LON:GFRD) - AGM statement (big share price rise today, so must be interesting, hence it is top of the list)
Frp Advisory (LON:FRP) - Half year trading update
Revolution Bars (LON:RBG) - CVA approved
Byotrol (LON:BYOT) - AGM Statement
After that, I'm going to write up my recent buys, for discussion purposes, and my current thinking about the market in general.
Timing - I'll be working all afternoon, so let's estimate 6pm.
We're conscious that some reader comments seem to indicate that people are getting confused about which sections of the SCVR are written by me (Paul), and which by Jack. I thought we'd made it clear, but seemingly not clear enough!
Therefore, let's try to simplify things by separating the SCVRs into 2 parts, clearly marked as being written by Paul or Jack. We'll both write within our individual parts of the report. Hopefully this might clear the fog a bit! We're just trying out different ideas, and we'll run with whatever works best for readers :-)
.
Self help book recommendations
Jack and I both discussed the idea of posting about which particular shares we've personally been buying this week. So here are mine (Edit: sorry, I rambled off the point). Usual disclaimers, these are NOT RECOMMENDATIONS. The whole ethos of Stockopedia, and me personally, is to encourage discussions, education (in both directions - I learn a lot from you, and want to never stop learning), and to take responsibility for our own portfolios.
On that subject, recently I got a hideously nasty email from a former friend, that I invested a lot of time & energy into, blaming me for his terrible stock market losses back in c.2012-14. I foolishly agreed to manage a trivial amount of money from him, agreed to when we were down the pub, and it was nothing but trouble. I got nothing out of it (I didn't want anything out of it, I just wanted to help him), and after things went badly, he pulled out his money for a c.20% loss, and then disappeared without trace, for years.
As it happened, I still had the spreadsheet within GoogleDocs of our holdings, and out of curiosity, I checked it out recently. We had 40% of his portfolio in BooHoo! When it was c.25p. So I emailed him along the lines of, how are you mate, hope you're well, as things panned out, if you'd stuck with me, you would have made a fortune! Never mind, such is life, etc. Let's meet up for a beer if you're free?
Some time later, I received a poisonous, obviously drunken email from him, describing me as a liar & a cheat. I couldn't believe it! It was all nonsense. He chose to cash out at the worst possible time, not me. He accused me of lying to him about using daily spread bets instead of quarterly spread bets. What nonsense! I have, and still do, use daily spread bets, for about 15 years, as they're easier to keep track of, for a marginally higher cost.
Then I related it to my favourite book - the timeless classic, which I re-read every year, to remind me that people are not rational;
.
.
I want to feel angry about the injustices, and lies that my former friend has wrongly accused me of.
Then I realised, he's just angry with himself, and wants someone else to blame for his failings. Instead of manning up, and taking responsibility for his own mistakes. When I told him that, he accused me of "lacking empathy". Give me strength!
Another amazing book by Dale Carnegie helped me come to this conclusion, and made these lockdown times easier. If you are finding times tough at the moment, or you constantly worry, then please read this following book now - it could make your life better, I've given it to 2 loved ones, and they both thanked me profusely, finding it very helpful;
.
.
To make it a hat-trick, this book literally saved my lungs, so if you smoke, just read it! It works.
.
.
Anyway, we'll come back to investments tomorrow! The above are all books which I found incredibly helpful. I hope you do too.
.
Galliford Try Holdings (LON:GFRD)
Share price: 100p (up 22%, at 12:15)
No. shares: 111.1m
Market cap: £111.1m
This is a UK construction group. The market clearly likes today’s update, as the share price has risen 22%, part of a big rebound in recent days, along with lots of other cyclical companies, triggered by the positive Pfizer vaccine news on Monday.
The chart seems to be saying that the market isn’t sure how to value this company;

.
Today’s update reads well, but I lost some of my enthusiasm when I read the most recent accounts, and saw that the balance sheet is not particularly strong, despite having a ton of cash on it.
Anyway, this is what it says today;
Operations are almost normal, not affected by second lockdown
Cash-rich, more than the market cap;
The Group is performing well, in line with the Board's expectations, with an excellent first half year average month end cash position towards the upper end of previous guidance of £125m-£145m.
However, to see the full picture, you need to look at the whole balance sheet. As at 30 June 2020, NAV was £120.5m, but that included £81.0m intangibles, so deducting those we get to only £39.5m NTAV - adequate, but not particularly strong, given the large revenues.
Looking at working capital;
Current assets £467.8m (including £197.2m cash)
Current liabilities £482.2m (including £458.8m trade payables)
As you can see, that means a deficit of £14.4m on working capital.
How come it’s sitting on such a large cash pile then? It’s timing differences - i.e. GFRD receives cash from customers, before it pays its suppliers. To my mind, that isn’t really surplus cash. It’s a nice business model, but essentially all the cash is spoken for. Or to put it another way, if the business were to wind down, and cease trading, then there would be no cash left, once all the suppliers had been paid.
That’s one way of looking at it. A more bullish view is to say that, if GFRD can keep the plates spinning, and collects in money faster than it pays it out, and that can continue indefinitely, then the company has a big pile of cash that it can use to make acquisitions, pay divis, etc. Although that carries more risk, because things might change - e.g. if customers demand more time to pay, or suppliers push for faster payments (which could be driven by prompt payment regulations).
Return to profitability is on the cards (it lost £59.7m before tax & exceptionals, in the FY 06/2020) -
The Board expects the Group to return to profitability in the first half of this financial year and a resumption of dividend with the interim results.
Good news for shareholders, about resuming divis.
Outlook comments are upbeat -
Our strategy and sector focus mean that the Group is positioned to emerge strongly from the pandemic, supporting the Government's planned investment in infrastructure and economic recovery…
We are encouraged by the pipeline of new opportunities across our key sectors…
The Group's strategy is focused on robust risk management, sustainable growth, careful cash management and margin progression. The Group is well capitalised with no debt, no pension liability, a portfolio of PPP assets, and a strong order book and is making good progress on its strategic priorities and the financial targets set out in September 2020, including expected reinstatement of dividend.
It lists some recent contract wins, of considerable size.
My opinion - this is a good update, no doubt about that. I wouldn't be surprised to see this share going higher still.
Personally, I don’t want to invest in infrastructure builders, as so many of them run into trouble and go bust, when large, complex, low margin projects go wrong.
.
Frp Advisory (LON:FRP)
Share price: 109p (up 5% at 13:33)
No. shares: 239.6m
Market cap: £261.2m
It’s worth revisiting my notes here in Aug 2020, where I looked in detail at the structure of this insolvency practitioner business. The most important point is that 25% of the profits are paid out to partners in a profit sharing scheme. So we need to make sure we take that into account when looking at valuation. Do forecasts include the profit share charge? They need to, as it’s a material to the valuation.
There’s a lot of restructuring going on at the moment, especially CVAs in the retail, leisure & hospitality sectors. I often see FRP’s name crop up as advisor to companies doing CVAs. So I expect there’s plenty of business at the moment, and for 2021 likely as well.
FRP Advisory Group plc, a leading UK professional services firm specialising in advisory services, today announces a trading update for the half year ended 31 October 2020.
The Group delivered another strong performance during the first half, continuing to grow and win larger and more complex mandates. This includes a recent high-profile appointment in the Group's Restructuring division on the administration of Edinburgh Woollen Mill.
This growth was achieved despite the significant reduction in the number of formal insolvency appointments within the marketplace compared with the prior year, as a result of the support measures made available by the UK Government in response to the COVID-19 pandemic.
As a result, the Group expects to report revenues for the half year to 31 October 2020 of £35.9m, up 14% on the prior year (H1 2019: £31.4m), and underlying adjusted EBITDA* of £9.7m, up 7% on the prior year (H1 2019: £9.1m), in line with the Board's expectations.
I would want to check whether this EBITDA figure has accounted for the 25% partner profit share, it’s not clear from today’s announcement. I’ve sent an email to the analyst at Cenkos. If I get a reply, then I’ll add an edit here.
Liquidity sounds fine;
The Group's balance sheet remains strong with an unaudited cash balance as at 31 October 2020 of £15.2m and an undrawn revolving credit facility of £5m.
Headcount is rising, and 3 acquisitions have been made.
My opinion - neutral. I can see the upside case, in that business should be buoyant for some time, due to companies restructuring, and some eventually failing altogether in 2021 and beyond.
However, I’m not very happy with the structure whereby partners have 5 layers of remuneration, and hence there’s a conflict of interest with regard to outside shareholders. Although the partners do still own 50% of the equity, so you could view that as interests being aligned maybe, at least partially?
On balance, I think this share is probably more likely to go up, than down, in the current environment. So it might be worth considering.
As we've got up-to-date confirmation that it's trading in line, then we can rely on the numbers below, which look reasonable to me - the stock is probably OK value at this level;
.
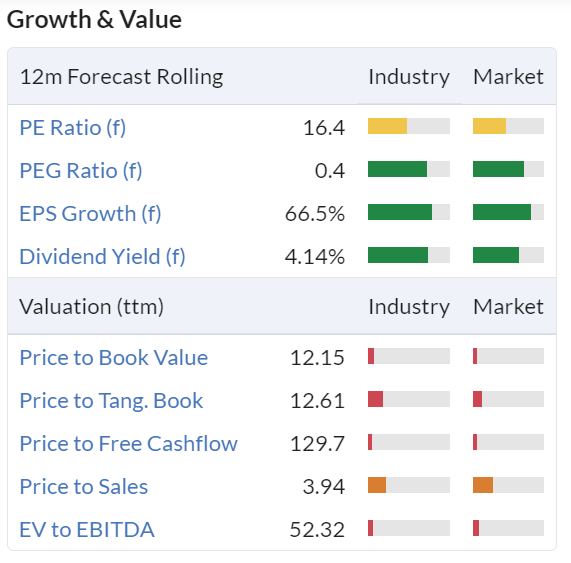
.
** Breaking News! **
Revolution Bars (LON:RBG)
Share price: 17.0p (up 3%, at 15:22)
No. shares: 125.0m
Market cap: £21.3m
Good news for long-suffering shareholders at this bars group.
The necessary percentages of creditor votes were achieved to pass the CVA process today. It’s subject to possible legal challenge for 28 days.
6 sites are being offloaded: Sunderland, America Square London, Birmingham, Solihull, Bath, and Clapham High Street.
Another 7 sites are moving on to turnover rents for 2 years: Clapham Junction, Putney, Richmond, Bristol, Reading, Cheltenham and Stafford.
There’s a useful benefit from doing this CVA;
The Group estimates that its cash flows (before one-off costs of implementing the CVA of approximately £1.1m) will improve over the two-year period of the CVA by approximately £4.0m.
Liquidity - this is very helpful information;
Net bank debt is currently £13.5m compared to current committed bank debt facilities of £37.2m, which reduces to £29.3m at the end of March 2021 and to £28.1m at the end of June 2021. Under the terms of the CVA, £1.3m of rent and service charge arrears will be paid on 20 November 2020. The Group's cash burn rate, if all the Group's bars are subjected to an enforced closure and assuming the continuation of the current CJRS and other government reliefs, is estimated at approximately £0.4m per week.
This enables us to estimate how things might look when the furlough scheme finishes at end March 2021. That seems to me also a seemingly realistic time when restrictions might be lifted, and the bars might be able to trade normally, as hopefully the vulnerable will have been vaccinated, so they young & healthy can get on with their lives normally. We hope.
That would entail another 20 weeks of cash burn at £0.4m per week, hence £8.0m additional debt, plus the £1.3m rent arrears mentioned above, so £9.3m extra debt, added to the existing £13.5m net debt, reaching £22.8m - which is well within the reduced facilities noted above, as at 31 March 2021.
This is most encouraging. It means that RBG should be able to get to 31 Mar 2021 in a reasonable position, with manageable debt. Once it re-opens, assuming no restrictions, then it should have a trading bonanza, with annual EBITDA being £15-20m in my opinion. That would allow it to repay debt quite quickly, and resume site refurbishments, which were delivering strong paybacks before covid.
The CFO is retiring at the Dec 2020 AGM, in a planned handover to a new CFO who joined in July 2020. Hence this doesn’t appear to be a cause for alarm.
My opinion - I welcome the additional information provided today, re debt/cash burn. This significantly lowers risk, and the shares still look too cheap to me, even after they’ve already doubled from the recent low.
There’s clearly much more reason for optimism now. Once the sites are trading normally again, then I think this share would be worth 40-50p. It won’t get back to old levels, due to the substantial dilution from the 20p equity fundraise.
I’ve lost a packet on this one, but more recently it was the right decision to sit tight, because my sums indicated it would get through this crisis still solvent. Today’s news reinforces that.
Having been stopped from partying for so long, I think the customer base is likely to go bonkers when things get back to normal. Not just in bars, but also restaurants, holidays, etc. Hence why I am bullish on the economy for next year. The doom has been very much overdone, in my view. I think many people will want to live for today, spend freely, run up debt, etc., after this shared horrible experience of covid restricting our lives in so many ways in 2020.
I’m hoping to speak with the CEO at some point, to ask a few questions about the CVA, and what happens next, so if that happens I’ll do an update next week.
.
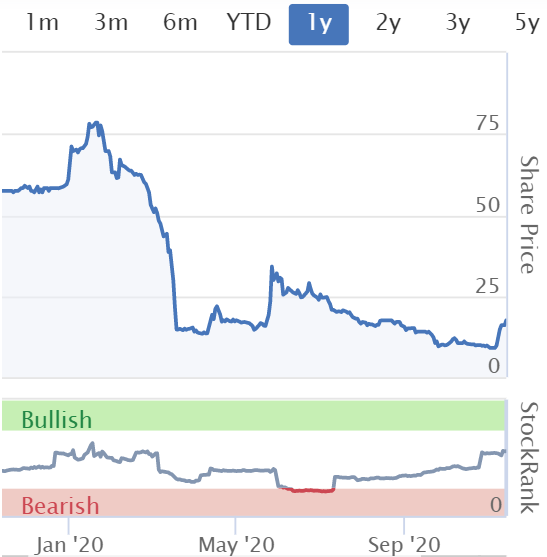
.
This part written by Jack
Castings (LON:CGS)
Share price: 333p (+0.6%)
Shares in issue: 43,632,068
Market cap: £145.3m
Castings (LON:CGS) is a UK iron casting and machining group with a solid track record of investing in the new technologies and manufacturing processes and a reassuringly prudent approach to its balance sheet. It makes a point of not taking on any debt.
As an equity investor, I see that debt has its role in the grand scheme of things but we are very much business owners and this prudent approach does catch my eye. It implies a sense of stewardship sadly lacking in certain other listed companies.
Stockopedia sees it too, with a Quality Rank of 90. For all that Quality, though, the valuation appears quite modest.

This is likely due to a lack of meaningful profitable growth over the past few years - see the negative CAGRs (compound annual growth rates) in the Financial Summary. So you can buy quality at a reasonable price, but growth is the concern.
Director buying has been strong, the community has also been picking up shares, and the Major Owners tab looks very respectable - so, an interesting backdrop against which we can set today’s update.
Sales for the six months ended 30 September 2020 were down 43% to £41.7m and Castings has swung to a loss before tax of £0.63m (2019 - profit of £7.34m).
Clearly normal operations have been impacted by the pandemic. By the end of September, monthly demand levels had recovered to approximately 85% of pre-COVID levels.
The group splits its operations in two: Foundry and Machining.
Foundry output was down 43% at 14,350 tonnes and external sales revenue fell by 42% to £40.5m (97% of revenue for the period).
The profit from the foundry segment was £0.8m, down 89% ‘However, assuming demand remains buoyant, productivity gains are due to be realised during the second half of the financial year and into 2021/22’.
Machining generated external revenue of £1.2m (3% of revenue), down 60% with a reported loss of £2.1m compared to a profit of £0.1m in the previous period.
These are not pretty results but are hopefully as bad as it gets - and Castings has used this time to strengthen its operations and financial health, with:
- £0.8m of capital investment focusing on automation and productivity improvements in Machining,
- £1.6m spent on a production line upgrade and the introduction of a new in-house treatment plant in Foundry, and
- The disposal of its Fradley site for a gross £1.95m, resulting in a profit of £0.66m.
Flicking over to the Balance Sheet (which looks spotless), we see net PPE of around £70m after depreciation. That’s nearly half the current market cap. I wonder if the group has any more undervalued assets hiding in that line?
Castings is also confident enough to declare an interim dividend of 3.57p, which is a 2.6% improvement on last year’s interim payment to shareholders.
Conclusion
COVID has hit business hard but there are clear signs of longer term quality at a reasonable price here.
The outlook section shows hints of activity returning to pre-COVID levels, with the usual caveats of ‘ongoing uncertainty’. Additional supply chain disruption is a possibility and Brexit remains a risk, with over 70% of group revenues coming from the European Union.
The group has been successful in obtaining a number of new projects with its European truck customers for 2021/22 and 2022/23. In addition to replacement work, these projects include additional platform volumes and also more value-add product solutions.
In the meantime Castings has strengthened its operations and continues to pay a dividend.
The group maintains a strong balance sheet with cash levels of £35.2m; an increase of £1.8m during the period after the dividend payment of £5.0m.
There’s a lot that is good here, but Castings has underperformed the market as an investment for a long time:

Revenue and profit have been falling over the years so my big question is: where does the growth come from?
That said, Castings does provide a positive outlook with scope for margin expansion.
I like the company. The valuation is modest, so there could be something here for the patient, quality-focused investor - but I’d want to know more about how management expects to meaningfully grow earnings over the long term before investing.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

158 comments
Not quite the same sort of book as Paul's self help suggestions but David Spiegelhalter's The Art of Statistics is on sale in the Kindle Daily Deal today. He's an outstanding writer on what, for most of us, is a tricky topic.
No formulas, just really well written explanations.
timarr
Wonderful stuff. In a world fraught with virus, lockdowns, burnouts, professional/personal pressures, never ending quest to make more money and general heightened anxiety, it's fantastic to get a daily dose of SCVR. Paul/Jack (and all the other writers) as well as those making regular comments, keep it up! Talking of books, my aunt sent me the most refreshing book I've read for a long time - the boy, the mole, the fox and the horse. Simple. Kind. Perspective.
There was a late news update from Naked Wines (LON:WINE) They had anticipated a bumper Christmas based on their increased number of subscribers. As such they increased their website traffic handling capabilities. They launched their Christmas hamper and the site crashed due to unbelievable demand. They sold 40,000 hampers at £185 each. That is £7.4m in a day.
I bought in at 218p. They are subscription based with excellent customer retention. C19 has only accelerated what they were doing and they are taking the US by storm. In the US the direct to consumer wine market is huge.
There is a long way to go on this share. I am still surprised there is not more noise and discussion about it.
Him CamRaid,
We've looked at Naked Wines (LON:WINE) here loads of times. It's just so difficult to value. I think it's one of those shares, where you have to take a leap of faith - you either believe in it, and value it on growth metrics, or you don't! Up to you. I cannot add value either way, from looking at the figures.
Regards, Paul.
I have done a fair amount of research and monitoring of this. This is a summary from another write up. Naked Wines was in a position where they had just invested a lot of money building the infrastructure in the US and just sold their retail business to get a big net cash balance sheet. Great timing going into Covid. They had high fixed expenses, a good business model and capital ready to invest. The market maybe underestimates the long-term trend a lot here.
Covid has changed things structurally for the better for WINE. The market is still perceiving WINE as a company that will get a short-term boost and then revenue growth will get back to 10-20 % a year (that in itself is good numbers).
But there is a situation here where WINE can grow the topline 25-50 % a year now for the next 3-5 years because of this Covid boost.
WINE experienced an insane number of new customer growth in April and May at +256 % YoY.
Even more important this happened with only 115 % higher investments. i.e. WINE acquired the many new customers at less than half the 'Customer Acquisition Cost' they had the year before. This was due both to short term impacts (lower Facebook ads etc.) but also generally better conversion rates across acquisition channels.
What does this growth mean to Naked’s ability to achieve scale on variable and fixed expenses?
The fixed expenses compared to revenue in the US was 2,6 % lower in April and May. For a company with a long-term EBIT target of 8-12 % a 2,6 % reduction is a lot. At the same time the company lowered the variable expenses per order by 18 % due to scale in logistics etc. This came because of early investments in growth where they now achieve scale economics.
These scale economics effect the long-term growth outlook. When WINE achieve better unit economics because of scale they can afford to invest a lot more in CAC at higher CAC rates and still deliver good LTV/CAC ratios. Everyone that has bought ads at Facebook can tell you how much more ad space you can buy if you can raise prices 10-20 % per ad.
There is real long term potential here and it could double or triple in the next 2 - 3 years.
That's interesting, thank you Camraid
You are welcome. The return they target is 4 X CAC. The underlying profit is best viewed by removing the marketing costs.
Evening Paul...After such a rollercoaster of a week in markets, I ,like many others are really looking forward to your view of the market after your buying frenzy this week...Wishing you a great weekend break after such a lot of effort by you and jack this week.Tony
Thanks Tony!
I've written up my buying frenzy article, so will publish it on Monday :-)
As always, thanks for your support, Jack and I really appreciate it. It's smashing to have such an engaged & supportive readership here.
Best wishes, Paul.
Great and reassuring update on Revolution Bars Paul. Many thanks.
This is the third low-ball offer I've been involved in recently - I can frustratingly understand Highland Gold Mining (LON:HGM) and Kaz Minerals (LON:KAZ) due to oligarchs and concentrated shareholdings - none of this apples to Codemasters Group (LON:CDM) !!
Anyway, rant over, but it is VERY frustrating when you find a share which is a LTH and then the BOD capitulate at a bargain price.
I agree Edward John Canham. I also hold CODEMASTERS and held KAZ. Frustrating.
Hi Paul, thanks for you efforts and opinions as always. Are you still planning to write up about your recent stock purchases and market thoughts? I believe you are bullish on the market in general but it would be really interesting to get your thoughts on the market and what stocks you have been buying.
Looking forward to it, but suspect Mondays SCVR early bird special is already being written
Yup, I'm writing it up now! :-)
Yup, I've written it up this weekend, so will publish on Monday, or maybe Sunday night.
P.
A great intro Paul, it seems like you are back to your old self again (hopefully the books you suggested helped you). It's really interesting to read when you give the intro a personal/human touch. It's great to see it again, long may it continue!
Thanks Casino_Winner,
We went through a bit of a bad patch here a few months ago, but now everything is much better.
All growing pains really. I've been writing these reports for years now, like a personal blog back then, but due to the huge growth of Stockopedia, it now has to be a bit more disciplined, and focused more closely on shares, and a much broader audience.
I totally get that. So I need to rein in my more flippant comments, in case someone somewhere misinterprets them.
Anyway, all good! Onwards & upwards :-)
Best wishes, Paul.
Revolution Bars (LON:RBG) CVA approved
Revolution Bars (LON:RBG) statement today included "However, whilst we welcome the support Government has given, the hospitality sector has been severely affected by their often illogical, inappropriate and disproportionate response to the coronavirus pandemic".
Must admit I agree. My local cafe has seats set well apart, screens everywhere, every possible Covid restriction, they disinfect and clean constantly and this is a low infection area. Closed on second lockdown and now gone permanently.
Revolution Bars (LON:RBG) Feel once the lockdown ends, whenever that may be and the government allow Revs to open and trade, they will fly, there is a lot of pent up demand from 18 – 24 year olds who want to go out and have fun. Next years trading for Revs I think will be very strong. + the CVA will have allowed them to make structural changes to their property portfolio so, onwards and upwards........hopefully.
Problem is that they are not all like that. Some establishments take infection seriously, plenty haven't
In defence of Virolens rather than TTG. My Pia is routed through Melbourne for some unknown reason which led me to a company called Keyoptions, based in Melbourne. They have bought the rights to distribute Virolens through Austalia, Asia and Latin America. They emailed me back when I asked them about the Ft article and about their role with Iabra, which I probably won't post here, but suffice to say they did strongly disagree with it.
Clearly I accept that TTG have been either naive, or ignorant of the city wire post in Miami on the same day (september 10th) as TTG RNS re their selection to manufacture Virolens for Iabra, which clearly states subject to government approval:
Lord Global Corporation, soon to be 27Health Holdings Corp, joins with KeyOptions to market Virulent®, 20-second COVID-19 testing product for areas outside of North America and Europe
Lord Global CorporationGlobeNewswireSeptember 10, 2020
This is the first AI driven mobile laboratory that can, in its first iteration, diagnose with 99.8% accuracy the presence of the live COVID-19 virus in saliva samples.
Upon the various governmental regulatory body approvals, which is expected in the near term, the market for this product will be very significant.
MIAMI, Sept. 10, 2020 (GLOBE NEWSWIRE) -- KeyOptions, has secured the rights to bring the Virolens® testing units to Australia, Latin America, South East Asia, Turkey and a number of other geographies in conjunction with other partners.
Whoops sorry about the big print. O well what the heck.
Any way it appears there are four different interests here which seems to have added to some confusion, not to mention Heathrow, the FT, Boris and The Daily Pain. It does seem to me there has been some journalistic endeavour to unfairly belittle firstly Iabra and the qualifications of its founders. and secondly some previous history with Lord Global Corporation, which they wish to distance themselves from and are openly seeking a name change. Which only leaves me to wonder who is marketing Virolens in America and Europe. Maybe IAbra are doing it themselves? I think its says something that they have organised themselves globally and the product within 3 months starting with 4 people! Well done guys. (provisor) if it works!
Black Rock have increased their holdings TTG by 4.5% recently and Keyoptions seem pretty sure it will be ready to roll in weeks with approval. I wont go into how IWEb messed me about at the beginning of the week with this. but they cost me plenty too.
I have bought a few more more today
The Galliford Try price rise today is probably as much due to their appointment as main contractor for the Stonehenge A303 tunnel project announced yesterday as anything else.....but the update is good.
Galliford Try Holdings (LON:GFRD) A303 contract:
The most expensive and destructive way to widen a road that is surround by fields. Can you see that going smoothly with all the finds they are going to make and burials they could come across? If they just put a hedge up blocking the view of Stonehenge at the near point the road would run better. Also the £20 rip off entry fee causing people to do slow drive by.
I despair at this crazy planning. I can’t see this contract going smoothly, Swampy Druid is going to be out quite rightly, alongside the archaeologists demanding to go at paintbrushing speed. It all then goes back to single lane in the next village. How is this plan so out of touch with any reality?
I worked for DFS some 25 years ago and Graham Kirkham ( Now Lord) regularly quote Dale Carnegie, great books.
Allen Carr's books have extended my life as well as improving it's quality. Would also highly recommend Easy Way to Control Alcohol. There seems to be various updates of the books, the originals always seemed best to me. If his style doesn't suit various authors have taken the same messages and presented them in other books.
Byotrol (LON:BYOT) added to the blog below.
Multibaggers with 10 Bagger Potential - Byotrol (BYOT, G4M, VEC, CRL, CMCX, CAR, DLAR) https://www.stockopedia.com/co...
BSV
Hi Paul, thanks for the book recommendations, The Sage of Omaha always references Dale Carnegie’s book as a huge influence on his early life and development.
Hi Paul & Jack. As a way out of the "who's writing what" confusion (which I don't find a problem btw) perhaps you could come up with a joint name - e.g. PACK and then merge it with the somewhat cumbersome SCVR and give this invaluable daily briefing one snappy name "The SMAC PACK". Of course you may end up with all under 18s being blocked from the site but it will at least reduce one area of ambiguity.
Galliford Try Holdings (LON:GFRD) agm statement today. No debt, no pension worries, cash roughly £140 million. Cash still way above mkt cap at current price of 95p. Business valued at less than nothing. Most important thing perhaps....dividends to restart so the income funds will now start to buy again in anticipation I guess. Dividends have been generous in the past according to longer term holders. We don't know how much of the cash pile is deferred taxation but I doubt it is too much.
Nothing much has changed here...we all knew about this big cash pile and the big contracts on the way down to an all time low of 70p. It fell day after day. Just shows that sometimes you have to grit your teeth and add on the way down if you see a bargain. I don't like the construction sector at all (as against housebuilders) myself. Low margin and too many disasters for me. But I thought this stock was always an exception because of the balance sheet strength. One of my biggest holdings and I am not tempted to sell below cash levels I must say with infrastructure contracts high on Government agenda .
Galliford Try Holdings (LON:GFRD)
No debt, no pension worries, cash roughly £140 million.
I think we do have some more clarity now that the June 2020 finals have been issuued and the balance sheet picture is somewhat clearer.
Would you agree that the majority of the cash is possibly somewhat necessary to hold onto if the business wants to prove that it can be solvent looking at liquid assets only?
If we ignore the intangibles it appears the cash is necessary so the buisness has sufficient funds to be able to pay down its £450 million of trade and other payables. The receivables balamces of £250 mill is well short of covering that liability.
Ok this business might be able to subsist without the cash if it never needs to pay the payables - but without the cash they would presumably be at the mercy of the companies they deal with that appear to be happy to give them plenty of credit "as things stand" For most of these construction companies that have failed the payables situation is what normally pushes them out of business if they don't have the liquid resources to cope with being able to service these liabilities.
Having said all of the above the low market cap does make this a somewhat appealing proposition - somewhat diminishing with the recent bounce. Sharebuyback would have been a really good plan here if they are comfortable they could allocate say £10-20 mill or so in taht direction , perhaps that wouldn't be prudent in the current climate though.
"The Board expects the Group to return to profitability in the first half of this financial year and a resumption of dividend with the interim results". £900 million approx in new contracts announced today.
My view is if you are going to buy in this sector, Galliford Try Holdings (LON:GFRD) looks the cheapest and safest bet. I see plenty of upside in an area that is very much out of favour and very lowly rated. Strong and growing profits as the Government throws in billions and a generous dividend may change views. Never going to be on a racy price; with no debt more of a comfortable tortoise. An agreed takeover would not surprise though; they sold the housebuilding arm and it would not be a shock if a much bigger company was thinking about an offer.
Not being a trader but a long investor Galliford Try Holdings (LON:GFRD) has been a continual disappointment since 2015. For myself it is the complete opposite of a ten-bagger. Re-combine it with its offspring BVS - cum - Vistry (LON:VTY) and it doesn't get any better. A pound to a penny the A303 project will run over-budget, are there any takers?
Silver
It's already taken over 30 years, so I doubt you'll get any takers.
See Hofstatder's law.
Not a small cap, but this beahaviour by Tui Ag (LON:TUI) is scandalous. I am glad I don't own it. The sort of behaviour that gives capitalism a bad name.
Tui under fire as delayed payments put businesses at risk
https://www.ft.com/content/f13...
£CDM A lot of shareholders here seem to be assuming that the institutional holders have been sounded out about the TakeTwo deal and will vote it through.
Well maybe so - but there have been none of the "xxx has given irrevocable acceptance" sort of announcements yet. We all get a vote on this deal and I shall be voting against the sale.
I'd be looking for at least 25%-30% above the current shareprice for mine...but I'd much prefer CDM to carry on doing what they do as an independant company.
Yes but maybe with new management as the current lot have shown they do NOT have shareholders best interests at heart
Seeing as its a flat Friday I thought I would recommend the new series of Billions. All great fun as usual - even better than the Sopranos (though Tony Soprano on Management still essential reading). You may know that Andrew Ross Sorkin - the leftie on Squawk on the Street (I'm a Joe Kernan man myself) - is the writer / producer and probably devises the outrageous Hedge Fund strategies.
Paul, I've read all three of those books and I agree - life changers!!! (Especially Allan Carr, the genius of that book is still underrated despite it being a best seller).
Sounds like your friend has a lot of issues, fair play to you for extending an olive branch despite the way they have acted!
It has always been clear which items were written by Jack and which by Paul. An inability to work this out might suggest an inability to be involved in shares.
That's exactly what i thought when i read the intro, but i couldn't have put it so eloquently as you!!
Nice comments Paul. Its not all about making money. Nice to hear the human side
Hi Paul
I read this and was really looking forward to seeing what they are:
——-
Jack and I both discussed the idea of posting about which particular shares we've personally been buying this week. So here are mine
———
Noted on not being recommendations of any kind, but I can’t see the list?
Would be great to read every week, to see where your personal conviction is as well as your "opinion".
When a reader makes a comment on one of Paul and Jack's excellent contributions, is there any way of tracking what comments the same subscriber might have made on other stocks not mentioned that day? It is possible on lesser quality chat rooms like ADFVN. Is it possible on Stockopedia?
You can just click on their profile name, it shows all their posts.
For a fuller list you need to go into their profile.
That particular Stockopedia feature isn't as good as the equivalent on the ADVN and LSE sites (I hate to say ADVFN has any advantage over Stockopedia however small).
Macro musing about the departure of Cummings.
It seems that the dominance of the old Vote Leave team inside No 10 is ending. I wonder whether this will mean that a compromise is imminent on the Internal Market Bill and the trade negotiations with the EU. If so, what might this mean for Sterling exchange rates (and therefore for inflation - and for FTSE profits since most of these are not in Sterling)?
I guess the market view will show up first in the bond markets, probably today, but I can't interpret those, so I'd welcome any insights from those who can!.
Yes, The Conversation (daily articles by minor academics) suggests Biden win leads to pressure for some UK-EU agreement
https://theconversation.com/wh...
I did wonder if the Biden win was anything to do with Cummings going (boom boom). Maybe some pressure from the US along the lines of 'don't be populist if you want a trade deal'. It made me wonder about Borris's position also, but who knows how that would play out. Guess it depends how much BJ still wants it.
Once Brexit is sorted I can's see Boris sticking around, he'll have achieved his objective, reckon it will be all change in the spring.
What?
Boris has wanted to be Prime MInister for a very long time. Way before Brexit and whilst he was still moderately pro-EU. He stood for London Mayor as part of a long term plan to be PM. Saying he'll leave because "mission accomplished" just doesn't make sense in my view.
I agree after the 2 current major issues are sorted he will want to stay with less pressure and will then want to prove his worth in more normal times, I still think he will do a great job and I think people read too much into his demeanour.
I get the impression that Boris has always wanted to be 'former Prime Minister' and yuck it up at the club, rather than actually do the hard work of being 'current Prime Minister'.
Wonder what his pension rights will be as ex-PM?
1. Boris wanted to be Prime minister...check
2. Boris wanted to get the UK out of the EU at any price...check
3. Boris wants to put in the long arduous work of offsetting the damage of 1 and 2....are you kidding?
Gone by Autumn 2021
1. Simplistic analysis by someone who hasn't investigated Boris, his long term goals or motivations....check
You're right. I refuse to believe that the Brexit negotiations and woeful preparations are the result of total incompetence. The majority voted to get out but Parliament said NO! and has done everything it can to make the process fail. The only reason Bozo went for it was because he saw an opportunity to become PM. The whole house is full of underqualified fools.
Thanks for the bull case IGPJ - I just think loosing Cummings will leave him floundering more than he is at the moment.
If he recognises he can't cope without his advisers, then why not get out while he can spin a great Brexit tale. It also avoids having to cope with the fallout when reality hits home. It makes sense to me ;-)
Quite. Boris is becoming increasingly isolated - he would never have been chosen as party leader if it had been up to the parliamentary party. They already knew what he is like.
I expect that the respective parliamentary parties would have not chosen Mr Johnson or Corbyn, as their preference would be for someone safe, competent and electable.
Whilst members electing party leaders looks at first sight like a better form of democracy, in practice it is achieving bad results.
Competent would seem to narrow the field considerably in all parties. But presumably the tory MP's thought May was competent. I can't see politics settling down again soon, so interesting times will remain for the markets
I voted for Boris last time and will vote for him next time. I already knew he was deeply flawed and he has unfortunately not disappointed in that respect. Never underestimate how relatable he is to many, many equally flawed people up and down the country. Would I vote for Hunt or the rest of them, never in a million years. If the parliamentary party don't want re-electing that is their prerogative.
Gone before then lots of family and money issues. My guess is gone in January
My opinion of you Paul, is you have saved me a small fortune, just by me learning a little of how you analyse stocks. We all have to follow our own paths in trading, but it does help if you or Jack, opens the gate for us. Pippa.
Agree 100% with that Pippa
That's great to hear, thanks Pippa! :-)
Morning all,
Based on previous posts, it appears there are quite a few Codemasters Group (LON:CDM) holders on this forum. I'd be interested to hear how you've approached the recent takeover situation? Any other feedback or previous experiences with takeovers would also be interesting to hear. I sold my shares in Codemasters Group (LON:CDM) this morning as I figured it's better to avoid any risk.
For example:
On the 10th of November, there was an RNS with the headline: "Take-Two Interactive - Offer by Take-Two Interactive Software Inc". In this, the terms of the acquisition value for each Codemasters share is stated as 464p. Today, the share price is 475p. If the Codemasters board recommends the takeover, why are people still buying/selling above the proposed price? There is clearly speculation that the bid would be rejected but surely this is quite a risky approach?
Based on your previous experiences, how do you think this could play out?
Thanks,
Kieran
I sold all my (LON:CDM) earlier in the week as I have to admit I lost a little faith in the management and wasn’t interested in owning Take Two shares. I am very disappointed with the offer and it being accepted by the BOD, I just had an uneasy feeling and sometimes I have to listen to my gut. Good luck to all those who are still invested.
IMHO the rise is now due to reports (from sketchy sources like the Mail) that the institutions are gearing up to reject the bid. Buyers could be thinking two things: 1) bid fails, Codemasters continues to grow as eSports and next-gen consoles bed in, or 2) the board have signalled a willingness to deal and a higher offer could be incoming after Christmas.
My working hypothesis is 1, and I continue to hold, but I have been very tempted to cut and run. I do not want to own shares in Take Two.
I sold my £CDM shares at 480 on 9/11. I was disappointed at the bid, and lost faith in the management for accepting such a low bid. My assumption at the time (maybe wrongly) was that they would have talked to the institutions (who owned 50% I think) and all had agreed it worthwhile. I did look into Take Two - didn't realise they make Grand Theft Auto that my boys love. Codemasters Group (LON:CDM) probably fits their portfolio of games nicely, and they gain developers with experience of building great driving games, plus access to F1 and World Rally Champs. So good buy for them at what looks like a good price.
Good luck to all holders, I will watch from the sidelines.
Codemasters Group (LON:CDM) Yes I agree it is a good price for Take Two, I would say a very good price. If I was to name my selling price it would around 600p cash, even that I feel is modest with the future growth prospects.
I'm disappointed with the management recommending such a lower offer.
Codemasters Group (LON:CDM) I'm holding onto mine, the takeover premium is so low over the pre takeover price, I would rather not sell. Usually there is a premium of around 30% about the current price which would have been around 570p which would in my opinion be reasonable. I'm not interest in Take Two shares. Many shareholders seem unhappy with the bid price and are likely to reject it.
Being in two minds, I have sold half my holding! Might sell the rest if it looks like the current offer will proceed.
one perspective to reinforce the hold and wait 'n see strategy is that in a recent Slater interview he did mention Codemasters Group (LON:CDM) and that when they buy for the fund they look for at least 50% upside in ~3 years. The current price i think delivers his target. However there is still future growth from eSports, growing digital sales, the huge pile of cash they could be sat on post xmas, £100m + of amortised dev costs and zero debt. I'm relying on institutional rejection BUT the major investors would i expect have been consulted before the board announced the potential offer and their recommendation. One board's gain is another fund's loss
I'm holding on to Codemasters Group (LON:CDM) in the expectation that someone like EA will come in for them and we'll hopefully get a bidding war pushing them up above £5.50.
I'm also happy to continue holding Codemasters long term if the shareholders reject this deal and there isn't an alternative offer.
If the deal gets finalised then I'll sell - I have no interest in holding Take Two shares, even if that means taking a small hit. The cost of trading a foreign share and then taking the currency hit converting that back into my ISA cash balance means it'll probably work out about equal. If my ISA let me hold $ I would probably be happier to hold Take Two though they are on a crazy multiple like most US tech stocks.
I am still holding onto my Codemasters Group (LON:CDM) shares. They are in my SIPP so I cannot hold Take2 shares in there anyway so will hold for at least a couple more weeks until I see whether the bid is going through or not.....if it is I will sell then.
Codemasters Group (LON:CDM) - you and IGotPoesJacket are worried about holding NASDAQ: TTWO
In the RNS on the offer it says: "Take-Two intends prior to completion of the Acquisition to establish a depositary interest dealing facility for the benefit of Codemasters Shareholders so as to facilitate the trading of Take-Two Shares from outside the United States of America".
Dealing with US shares can be a nightmare if dealing with a US based broker or bank, I have some shares I acquired when I worked for a US company. I would only want foreign shares inside an ISA or SIPP.
If this deal is accepted then I will be selling before its completed.
I have a SIPP with A J. Bell (I noted the negative comments here earlier this week!) and can hold overseas shares no problem (Canada, USA, Belgium & Denmark in my case). Provided you have completed a W-8BEN for the USA and a NR301 for Canada the withholding tax on dividends is also reduced due to a reciprocal tax treaty arrangement. Unfortunately the same doesn’t apply to the European shares and most platforms won’t countenance the process of trying to claim back some of the withholding tax which is apparently possible, but complex, in most cases.
I sold out at 480. The change in price over the last few days is due to the fluctuating value of Take-Twos share price on the US market. I doubt investor sentiment has much to do with it. If it was an all cash deal the CDM price would be more stable and nearer the offer price of 485p. It could still fail to go through. I hope it does fail as CDM seems undervalued at 485p p/s. The major institutions hold 50%. A few people have commented that they may have been informed prior to the RNS but I can’t see how that’s the case as that would be insider info. I have turned my attention to the other UK based names - Sumo and T17.
There is a Times article: ‘’Takeover is game on after Codemasters accepts lower offer’’. Not sure what ‘lower offer’ refers to.
Apologies for shouty big letters.
Codemasters Group (LON:CDM) The value is 485 per share I believe.
Codemasters Group (LON:CDM) As it's based partly on shares, I think the current bid offer is lower than 485p now, it was only about 462p the other day.
I haven't sold any of my Codemasters Group (LON:CDM) shares and don't intend to. I will also be voting against the current Take-Two offer and I have a feeling that quite a few institutions will do the same. As someone else noticed there haven't been any announcements recently of institutions signing up to the deal and I expect that they see it for the low-ball offer that it is.
As for management I can see their perspective. All of their options will immediately vest, they'll carry on working in exactly the same way and they'll receive a new set of options in Take-Two. Win-win for them and they can argue that shareholders aren't getting shafted because they can just hold the Take-Two shares. It's even possible that Codemasters Group (LON:CDM) will do better as part of a bigger group.
However that still leaves the fact that this is an opportunistic bid looking to grab all of the near-term profit growth out of our hands. I believe that either the offer will be rejected or Take-Two will have to up their price or a competitor will make an offer and we'll get a bidding war. I'm happy with all of these three outcomes.
Codemasters Group (LON:CDM)
Have to admit at the moment I haven't done anything with my shares as I'm frankly stunned by the BOD and by implication their advisors.
If this goes ahead they will be taken out at a forward PER of 26 (including any - not sure if there is any - bid premium)
Forward premiums on their peer group (not including any bid premium) :-
40 £TM17
43 Frontier Developments (LON:FDEV)
31 Sumo (LON:SUMO)
You've really have to wonder at the BOD of Codemasters Group (LON:CDM) - who are they really looking after?
Morning all. I have a quick update on where we are value/growth wise. First two charts.....
This is the US 30 year bond yield ... although it has risen from the bottom it says deflation.
This is the spread of 30 year bond yields over 5 year yields and hints at the possibility of inflation. A clear trend maybe present but the market has been very willing to ignore this until this week. The announcement of the vaccine test results caused what has been described as the largest shift from growth to value in a single day since the ending of the tech boom in 2001.
As a bit of fun back in July I started watching how Tesla faired relative to a random equally weighted benchmark of 5 UK out of favour value plays. Those stocks were BP, BT, Rio, IMB and Barclays. From the 16 July this basket is down 2% mainly because of 24% fall in BP. The All share index is up 3%. Tesla is up 30%. Tesla had famously risen nearly 40% the week before this started.
Now of course we get into all sorts of problems if we start to try and argue this random equal weighted group tells us anything. However, of the group only Barclays and BT outpaced the All Share Index over this short period. Clearly headline rate levels are hardly supportive of a wholesale shift into value stocks yet. Despite the magnitude of shift this week, I would argue it reflects the extreme of positioning beforehand, and clearly, leaves plenty of scope for much better performance from value stocks.
This final chart plots Amazon Vs JPMorgan as an illustration of the trend. From the peak in 2000 Amazon failed to move past JPM until the 2008 and the GFC. Even after the GFC it again suffered a period of 2 years underperformance. This neatly summarises why the move was so extreme this week. As we move into next year its difficult not to imagine a period of things getting better and therefore a lot of scope for a new trend to emerge. This will have ramifications for all stocks in all markets.
A couple of graphs on value vs growth, including 2020 and C-19. 10-yr and 5-yr returns.
The current period of value under performance is the most extreme both in terms of duration and magnitude. Mean reversion argues that this trend will soon shift back to favour value. Time will tell.
Mean reversion argues that this trend will soon shift back to favour value. Time will tell
Hmmmmm it depends i would guess - if we say alot of the undeperformance here is due to now obsolete or over indebted companies losing most of their value - i don't see that underformance reversing itself anytime ever. Will the other subset compensate perhaps but i wouldn't. I would guess if the value sector has contained alot of s*** stocks looking back with hindsight over the last 5 years i don't see that there will necessarily be any outperformace to catch up for what has been lost - if those companeis have been massively diluted or gone pope or become walking zombies (Centrica and AA.?). i would agree that value won't underperform forever but these numbers are so stark they suggest that this periods mean is different to other periords mean end of and the two datasets should not be mixed. Does anyone know if mean reversion is even relevant if one is trying to use periods with different means? which is what i am probably trying to ask. Perhaps the mean reversion disciples/experts will say i am talking nincompoop and they may be right.
Narrative always triumphs over reality...in the short term.
If we can find no mean reversion, at a meta societal-economic level as well as in dull factor land, then large cap momentum growth will be one of the great short opportunities of all time. I don't know when to call it obvs.
If there is no life in value then make your plans to hold types of assets in types of jurisdictions that cannot be confiscated. Betting on the continuation of momentum growth is playing short volatility ahead of the end of democratic capitalism as we know it.
I'm not a value investors but even more keenly I'm not a momentum growth investor.
There are structural macro reasons mainly around monetary and financial market conditions that have made it so great for momentum growth. Very few of these companies are very 'constructively' innovative...I'm fans of their work but they are to a great extent diversions of capital resources when it comes to the continuation of the human race (as in the race to progress and support humanity).
Many of the 'value' activities are more societally critical even if they do not currently have macro favour (back to structural macro and political).
Comments above are not a moral judgement by me but my opinion of what bounds our possible futures. Big stresses and events usually herald changes we need to make...and for the unfortunate societal failure.
The great strength and durability of value as a factor is simplicity and lack of hubris. Picking the few winners is an activity loaded with hubris and self-delusion whereas buying a diverse basket of the unloved for sure captures some failures but also accesses the greatest power in economics and financial markets...the mysterious capital cycle. Just think how hard many of those 'crap' companies are working not to be crap...when do they catch a break?
Dimensional Fund Advisors are one of the best asset management franchises ever in my opinion for what they give investors access to...diversified semi-passive portfolios of 'crap' https://www.dimensional.com/
Of course, this time may be different...and if it is then it will be as something big and political occurs...perhaps US deciding that Microsoft etc are part of the war against China...but know what you bet on
I don’t think I understood any of that. Are you saying (inter alia) that now is not the time to invest in Scottish Mortgage IT?
That’s a much more succinct summary ;)
I think Baillie Gifford are a great firm and I know them well historically. Generally, having your money with them long term is a better than average choice...but I wouldn’t give anything with Scottish Mortgage’s performance new money. That said maybe we are living a paradigm shift...this will be at least my 4th active observation of such claimed event in equity and the other 3 were wondrous and powerful but fell over
"Then I realised, he's just angry with himself, and wants someone else to blame for his failings."
It's a lot easier to blame someone else. Unfortunately for him, the people who make money in stocks are mature enough to take responsibility for their own decisions.
The harshest criticism comes from those with the least at risk.
Hi Michael, I do agree with you however we must never feel so empowered as to discount the tremendous impact of both good luck and bad luck on the outcomes of our decisions. It's all about managing risk and luck, isn't it?
Very zen Michael. Personally I think all my stocks are total bar stewards...and then I grow to hate some of them.
As for self-help reading. This is my favourite in the genre:
The Wee Book of Calvin: Air-Kissing in the North-east
https://www.amazon.co.uk/Wee-B...
hee hee
Paul, great choice of books by DC. I particularly like the Frank Crane "Just for Today" section in the Stop Worrying and Start Living book . My adult children have all read both his books and hold each in high reverence.
"Just for Today, I will Adjust myself to what Is, and not try to Adjust everything to my own desires. I will take my family, my business, and my luck as they come, and fit myself to them."
Very apt for me when the market doesn't fit my expectations.
You can please some of the people all of the time, all of the people some of the time, but you cannot please all of the people all of the time.
Given it is your own money and strongly recommended by the page that you do your own research, isn't it enough to have the reasoned argument? Why does it matter if it is Paul or Jack. We know the team. If the team changes then we want it to be clearly stated. Its not that I don't value Paul or Jack, its just that I value the team more.
Hi Camtab, I agree with the sentiment. I think the issue is simply that readers like to reply with a comment and it's more polite/friendly to acknowledge the author. So people feel bad when they say "great analysis by Paul!" and it was actually Jack or vice-versa.
For that reason, I would like to know who wrote which section. I don't mind how it is done, I thought it was clear before and it's equally clear now so that's great.
While I am writing, I agree with all Jack says on Castings (LON:CGS) and the quality of its management. I came across the company years ago and it is an exemplar of the best of UK manufacturing, investing consistently in technology and skills, not taking financial risks, a reliable high-quality supplier with a good reputation across Europe. I wouldn't invest in Castings (LON:CGS) myself because (a) this is exactly the type of company that Brexit will hit hardest and (b) while there are some cast suspension components, the majority of castings go into internal combustion engines and that is a dying technology.
The best analogy I can use is with a supplier of harnesses for horse-drawn carriages in the early years of the 20th century. Their market is about to disappear, through no fault of their own, and however well-run and respected the business may be that is no protection.
Fair dooos Whitbourne,
Hi Jack
Whilst I appreciate it is not an easy thing to say or talk about, I just wanted to say thank you for your honesty in your note about your purchase and subsequent sale of Tt Electronics (LON:TTG) yesterday on the spike a few weeks back, and unfortunately you were on the wrong side of the trade on this occasion.
I would like to ask a follow up question, was Tt Electronics (LON:TTG) on your watchlist and a fully assessed and a rational purchase on that day or was part of it seeing the "apparently" very positive news and feeling you had to be part of it or a bit of both?
As I can say honestly I am still in recovery mode 8 months after the spring crash and I am still down on the year (>10%). Though on the positive side I still have (>80% ) most of my mum's, sister and my capital so we have not lost everything.
I am asking as I think over the last four months I have made a lot fewer mistakes through trying to apply better a decision matrix and ensuring all trades both buys and sells go through that BEFORE I press the button. Though I can still point to some horrendous decisions both buy and sells, which include not pressing the button.
Thank you
Tommy
SCVR is essential reading for me every morning and we are incredibly lucky to have Paul and Jack adding outstanding value in a clear and entertaining way, when I guess they could be living simpler lives solely making their pile from investing. I actually don't care who wrote what as both are excellent and it is content not contributor which really matters. However, looking at yesterdays SCVR surely it is already abundantly clear from the opening agenda who is writing what?
One simple aspect of their different writing styles helps me easily distinguish between Paul and Jack.
At the end of each company write up there is a brief comment. As many do I usually skip to this before I read the full details.
Paul heads his - 'My opinion'
Jack heads his - 'In conclusion'
As one who is easily confused this helps me a lot :-)
Smart! I hadn't even noticed the difference...
Morning IronPyrites,
Good point! I deliberately format my sections differently to how Jack formats his, and we both have a fairly distinct writing style of our own, so once readers become familiar with the SCVRs, I'm sure they can immediately see who is writing each bit. But I think splitting the reports into two parts, is a good development, so think we'll run with that for now.
Best wishes, Paul.
Codemasters Group (LON:CDM)
So according to the (gutter) press the large investment houses are not happy with the proposed takeover of Codemasters - hopefully lead to a higher offer or a new suitor?
https://www.dailymail.co.uk/money/markets/article-8939649/Codemasters-faces-investor-backlash-726m-deal.html
It's hard to see why the institutions would be happy with the Codemasters Group (LON:CDM) offer - I'm not either, and also surprised/annoyed that it was recommended. I think the best outcome for me now would be an improved offer because my faith in management has been dented.
I've just finished reading 'How to stop worrying and start living', its a great read and I've taken many points from the book.
I always like to read so I would like to know if you have any more recommendations. Maybe recommend a book a week/month as part of this report.
There are a couple of book related podcasts I follow. The Knowledge project often does really in depth interviews with authors (one to two hours each) and can be enough to capture their thinking without reading the books themselves and the investors field guide has a good book club which recommends articles and books from the previous month.
Not enough hours in the day though....., and can lead to an expensive book habit.
Thank you for the recommendations, I have just subscribed to both podcasts.
The Book Prescription Scheme was introduced by Professor Neil Frude who is a clinical psychologist in South Wales. He was thinking about ways to reduce his large waiting list and approached colleagues for book recommendations and the Book Prescription Scheme was born.
All of the books listed are stocked in every Welsh library and GP's can prescribe a book or individuals can borrow them or just buy them if they choose.
The scheme was subsequently rolled out to other parts of the UK.
Here's a version of the list but there might be a more up to date version but the website is down at the moment ... https://111.wales.nhs.uk/pdfs/...
Hope that helps
Phil
Great idea! I also like the idea of readers sharing your best books/podcasts, etc, here. I "read" a lot via audiobooks, as my eyes are too tired to read physical books, from staring at a screen all day. Audiobooks also mean that otherwise wasted time (shopping, in the bath, exercising, etc) can be put to use. I've "read" about 60 audiobooks in the last year.
A fascinating conventional book, that I couldn't put down, it's a riveting read, called: Cecil Rhodes, flawed colossus. Obviously a major historical figure, that divides opinion, so I wanted to find out for myself what he was like. On balance, despite his amazing achievements in a relatively short life, I think he was a nasty bit of work, who did a lot of damage, and had little to no concern for human life. But standards of the time were different to what they are now, so huge numbers of historical figures fall into that bracket.
I quite understand why students at Oxford would like his statue taken down. Although perhaps it could be moved to a less prominent position, because the Rhodes scholarships to this day are a great benefit to people from all around the world.
Anyway, the book is very well written - and it touches on the likelihood that he was almost certainly gay. Hiding in plain sight. It amuses me how his admirers gloss over that!
Regards, Paul.
For what its worth, as a newish subscriber/reader, I have the highest respect for both of your views/writings. I don't have to agree with either of you all of the time, but I enjoy listening to well thought out reasoning even if I have a different view.
Both of you have a great understanding of balance sheets and company workings, but as we all know the market works in mysterious ways. Therefore I see the whole of the SCVR and many other sections of the site as simply a portal for people to discuss in a grown up and polite way their thoughts on companies and the market a as whole.
I don't take any of it as advice, simply an opportunity for people to highlight good and bad.
The level of debate and knowledge from all subscribers is top rate.
I have enjoyed the clear authorship acknowledgement over the last few days and can clearly see who has written what, so its working for me.
Keep up the great work - your input into a recent MelloMonday Paul and the BASH was equally impressive (was catching up last night on an old MM).
Hi KevinS1,
Great, thanks for the feedback, it's much appreciated!
The way you read SCVRs is absolutely what we want - i.e. we're flagging up things we find in the accounts, and then giving our personal opinions, but readers need to just see our work as part of the puzzle, and make up your own minds, which may be different to what we think.
A lot of it is educated guesswork, and the market is mostly sentiment-driven, so logic frequently goes out of the window in terms of share prices! That's one of the things that makes it so interesting & exciting being in the market. I just love that feeling I get, when I research a company, and find something that is really obviously under-priced. I've found quite a lot of those recently, and am feeling super bullish about a number of my large positions.
Best wishes, Paul.
Some of these books are only 19p on Amazon if you download onto a Kindle!
I read "how to win friends" in my first job and found it instrumental in forming my approach in sales.
Did that just now..........How To Stop Worrying and Start Living by Dale Carnegie, 19 pence. Will help enormously when I can't sleep at night.
Silver
Paul
If you have time to look at Silence Therapeutics (AIM) I would be grateful. I watched a presentation the other night on this Company which would indicate they are on the cusp of greatness. (Innovations in isRNA to treat heart disease and other genetic diseases) However I like other readers are probably fed up with great stories and no substance or results, that said they are funded by some pretty big players like Astra Zeneca.
One thing I cannot get my head around is the disparity between the Nasdaq listing and the AIM listing. The price difference is huge between the two listings for basically the same stock why would this be?
the ADR represents 3 shares. The US price should trade at the UK price x 3 x GBPUSD (currently 1.32). Then account for liquidity, bid/offer spread and trading volumes.
Hi Portcall909,
I've had a quick look at the StockReport for Silence Therapeutics (LON:SLN) - it's not the kind of thing I can possibly add any value to. It has negligible revenue, huge losses, and is valued at £377m! So there's nothing for me to analyse. The valuation is clearly based on investor expectations for products in development. I have no knowledge or expertise in that type of thing.
Sorry about that.
Regards, Paul.
My morning smallcap tweet: GUN shoots two barrels at corp governance
Frp Advisory (LON:FRP) Gunsynd (LON:GUN) Iconic Labs (LON:ICON), Byotrol (LON:BYOT), Nakama (LON:NAK), Galliford Try Holdings (LON:GFRD)
FRP Advisory (FRP) guides H1(Oct) rev up 14%, U/L adj EBITDA up 7%, in line with mgmt exp. [SP=105.96 Cap=254m]
Gunsynd (GUN) £1.1m placing at 1p, a 5% discount. Placing will occur in two tranches as co "does not have sufficient shareholder authority to issue the shares in full." So two fingers to shareholder rights. How does the NOMAD think this is OK? [SP=1.08 Cap=3m]
Iconic Labs (ICON) £747k placing at 0.012p, a 20% discount. to replace European High Growth Opportunities Securitization Fund funding (a death spiral?) with normal debt. This "will remove the overhang of continuous conversion of convertible instruments into Ordinary Shares". Did they mention this downside when co took the funding? Of course not. [SP=0.02 Cap=5m]
In line: Byotrol (LON:BYOT) Nakama (LON:NAK) Galliford Try Holdings (LON:GFRD)
People were always addressing Graham as Paul on Graham only days, does it really matter, some folk just get it wrong from time to time?
It only matters when we disagree on shares. We don't have a "house view" on any shares, just our own personal opinions, which may differ. So if I'm bullish on a stock, and Jack writes something negative about it (which is absolutely fine, we want a diversity of views), then it could really confuse readers, who might think I've changed my mind & turned bearish on the share.
Regards, Paul.
Read the easy way to stop smoking over a decade ago and I still remember it. It definitely worked for me
Seemed obvious to me who was writing what.
On a quiet Friday i think the HY IMS update from Castings (LON:CGS) looks pretty interesting. This is a foundry business making large metal parts mainly for the commercial truck market. Lockdown was v difficult for them when demand fell off a cliff but over the coming months it has gradually recovered to 85% of precovid levels and the schedule suggests getting back to match covid levels. They have made productivity improvements during lockdown so potentially margins will pick up going forward.
There is £25m of net cash on the BS, equivalent to 25% of the market cap and their confidence is reflected in a raised, yes raised, interim dividend.
Management have a decent stake in the company and this is reflected in how carefully the business in run.
Thank you, Yellowstone Advisory. I have known Castings (LON:CGS) for many years (disclosure: I hold) and I have always admired their financial management, which is exceptionally prudent. They have a rock solid balance sheet and a business which is agile thanks to steady and well directed capex. Brian Cooke, the former CEO and now Chairman, runs a very tight ship but, as far as I know, has never gone out of his way to court the City hence it usually flies below the radar. Mr Cooke has been steadily buying stock over the last couple of months (3,300 @ 338p on 28/9; 3,000 @ 328p on 28/9 and 3,000 @ 323.5p on 13/10) to add to his stake of circa 2m shares in the company or 4.5% of the equity. It trades on a historic yield of 4.48% and periodically pays special dividends to its shareholders - last one was 15p paid on 15/07/19. A classic long term investment.
I agree YA - my only concern is the lack of historic growth. Any counters to this point are welcome as it looks like a very well-run company otherwise.
Best,
Jack
Hi Jack, You make a good point on growth. In todays statement management say
"The group has been successful in obtaining a number of new projects with our European truck customers that will commence production in 2021/22 and 2022/23. In addition to replacement work, these projects include additional platform volumes and also more value-add product solutions."
This may translate into revenue growth and hopefully management will be able to elaborate on this and update on progress as we go through the year.
Best, Alex
I think we are lucky to have two excellent writers that I do not care who wrote which section.
More power to your pens.
totally agree. Feel the joint Paul and Jack reporting has taken this up a level, there is now so much content to read through, keep up the great work guys.
Does it really matter if sometimes readers get confused about who wrote which part of the SCVR? No matter what you do it will still happen from time to time. Also remember having 2 authors is new so readers have to get used to it.
I vote for not having a single report, but 10 variants for all wants and needs.
1) Colour coded
2) Labelled at the bottom
3) Labelled at the top
4) Labelled at the bottom and top
5) A Paul or Jack watermark
6) A Paul or Jack background
7) One in bold the other in italics
8) Side by side, left and right
9) A toggle feature
10) A voiceover audio button at the start of each company so we can actually listen to Jack or Paul while we are reading (I’d pay extra for that).
James,
Thank you for your indulgence, but you might be over-thinking things, and in need of a mild sedative, due to an over-active brain. I recommend Horlicks! ;-)
Best wishes, Paul.
P.S. Oh dear, just realised the joke might be on me ! 10 versions sounds marvellous, let's do 20 versions LOL!
Hi JamesHolmes, LOL.
You missed out that Paul & Jack should also have their names highlighted in reverse flashing video! ;-)
These suggestions are all based on us actually reading the original piece before commenting.
That’s completely unrealistic.
So I wouldn’t worry about it too much. The comments worth reading tend to be made by people who get the authors name correct because they have read the article and thought about it. I find that a useful way of weighting the comments.
Why have 3 blades when you can have 4. Go for 30, mach30!
how about every day we choose a red or blue pill? Up for grabs as to you or Jack handles which colour
Haha - I guess it must be some kind of comment on market mood (I know not what) that the commentary thus far is about stylistics and presentation.
I have myself been confused on a couple of occasions over the last few days whether Paul or Jack have written a particular section - but in all honesty it is largely irrelevant. I respect both Paul & Jack, but if I disagree with either it makes no odds who wrote the section.
To be honest if the cleaner (and this is not meant to be a sniffy comment about cleaners) chipped in with a section before either Jack or Paul arrived in the office (yes I know - being in the office was so 2019) I would not care - I'd take it on its merits either way.
But whilst we are on things that I don't think matter too much - I have to just point out to Paul - this is the report for Friday the 13th.
{Cue slightly spooky dramatic music - followed by the Eastenders' drum beat - good night all!}
Hi Gromley!
As always thanks for your marvellous comments.
But whilst we are on things that I don't think matter too much - I have to just point out to Paul - this is the report for Friday the 13th.
Ah yes! I'm a bit like Captain Mainwaring, trying to cope with the 24 hr clock, and getting it constantly wrong. I've now corrected the typo, thanks for pointing it out :-)
Best wishes, Paul.
I can’t fathom why readers can’t see who has written each piece when it clearly says at the start “written by Paul” or “written by Jack.” So why not just continue doing it as you do now?
yeah agreed - you cant please everyone so no matter what you do someone will be frustrated.
Agree 100% ... it's so simple
As it is late Thursday looking back / forward I must say that the highlight of today was the Volex (LON:VLX) presentation on investormeetcompany.com when the (potentially a red flag) departure of the CFO was cleared up in the Q&A (although the company should have announced what was to happen a long time ago). Long may such online events continue so I have booked for the Intercede (LON:IGP) Interim results presentation on Thursday, 26 November 2020 at 4.15 p.m. (Paul has probably beaten me to the head of the queue).
The problem with two sections is that I (and I'm sure many others) come back to the page several times throughout the day. If its in two sections then the reader has to scroll up or down through stuff they've already read to check if there's something new in the other section.
My vote, for what it's worth is just to have the name of the writer after the details of the company, so Thursday's would look like:
(LON:ZOO)
Share price: 53.5p (down 3.6%, at market close)
No. shares: 74.6m
Market cap: £39.9m
Written by Paul
(LON:MKS)
Share price: 120p
No. shares: 1,953.4m
Market cap: £2,344m
Written by Paul
(LON:RCDO)
Share price: 340p (-7.4%)
Shares in issue: 53,406,250
Market cap: £181.6m
Written by Jack
Nice idea, but it will still confuse the crap out of some people lol! :-)
I can't see how a simple 'written by Paul' or 'Written by Jack' can possibly be confusing. Could it just be that some people have to get used to looking for it. I thought it was just habit, and inattention to detail that caused some people to assume when commenting that it was written by Paul without checking to see it it actually was.
Why not just literally split them up so the Title is '#### Small Cap Value Report'. That way they are 2 different blogs and its easy to track or look back (as I do ALOT) to re-read over bits. It seems that you both specialize in different sectors so they are unlikely to cross over. Just an opinion so I am sure there are a multitude of reasons why that may not be possible :-)
Graham and I tried 2 separate SCVRs each day, a few years ago, and the readers hated it!
We'll keep trying until we find a format that people are happy with :-)
Cant win :-)
could perhaps use a colour-coded background per section to differentiate? (might need new site features to support this however)
thanks though for trying different ideas out, cheers both.
Yes, I like the idea of colour coding too, but we have to remember that some readers are challenged with colours. I'm sure we'll find a compromise that everyone can work with!
Just coming back to KGBs question on Reach plc Reach (LON:RCH) purported readership not being the in even the top 50 visited sites. BTW Jack has done a better job than me than setting out the investment case here : https://www.stockopedia.com/co...
It’s not one title which is 5th - it’s the amalgamation of all their titles which puts them in 5th place.
Put simply if you add up all these - you get 5th place in audience in UK... simples
National newspaper
Local and regional newspaper
(Macclesfield Express / Wilmslow Express / The Sentinel (Staffordshire))
Scottish and Universal Newspapers)
Digital online Brands
Reach has launched websites under the Live brand:
Yes, my son looks at his local "newspaper" online every day. He has never bought a hard copy. The websites could be improved but it is infinitely better to have a crap website (not saying that Reach's are all crap) with millions of people logging on to them than brilliantly constructed websites with no viewers. It is all about the volume of online activity. This is of such value that I cannot see longer term why it matters if anyone actually buys a paper!
Paul and Jack - Why don’t you just put your initials after your section PS and JB ?
Because people wouldn't notice it!
maybe two halves then as you seem to suggest with a heading for each
Paul’s Section
Lipso orio pro potario etcetera
Jack’s Section
Lipso orio pro potario etcetera