Small Cap Value Report (Fri 13 Sep 2019) - CCT, JDW, GAN, TM17

Good afternoon, Graham here.
Paul and I appear to have got our wires crossed about who was doing today's report.
I'm going to do a late version of the report now, with the help of Jack Brumby.
Sorry for the lack of communication and lateness! We are on it now.
Today's report covers:
- Character (LON:CCT)
- J D Wetherspoon (LON:JDW)
- GAN (LON:GAN)
- TM17 (LON:TM17)
By Jack:
Character (LON:CCT)
- Share price: 355p (-4%)
- No. of shares: 21.4 million
- Market cap: £76 million
Profit warning.
‘Through a combination of these factors, the profit before tax for the Group for the year ended 31 August 2019 is likely to be in the range of £11.0m - £11.5m., slightly under the lower end of current market expectations.’
This toy company is one of the more popular stocks on the site - and recently, as many of you know, the share price has unravelled as a result of Hasbro bidding for Peppa Pig IP owner Entertainment One. It’s been quite a dramatic decline.
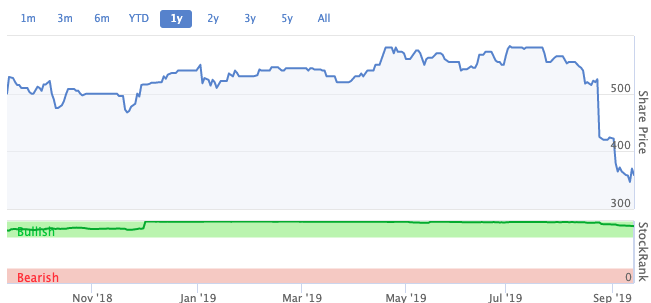
That’s a drop of about 38% over the past couple of months. Alas, when it rains it pours.
The company says:
‘The second half of the financial year just ended has seen several factors negatively impacting our business. The most significant factor has been the failure of the retail market in Scandinavia to fully absorb the sales vacuum caused by the liquidation in January this year of Top Toy, OVG-Proxy ApS's ("Proxy") largest customer until its demise.’
Add to this Sterling weakness (with the $/£ proving particularly painful for the group) and the fact that Character’s recent purchase of Proxy needs a bit more TLC than was originally anticipated… It’s clear that conditions are tricky for management right now. When it rains it pours.
As for Peppa Pig, Character says:
To date, there has been no dialogue between the Company and Hasbro as to its future intentions for Peppa Pig and, although it is unlikely that a definitive position in that regard will be known for some time, discussions have taken place with eOne and it has been agreed that the Group's current Peppa Pig licence (due to expire on 31 December 2020) will be extended for an additional six months to expire on 30 June 2021.
Quality, cash flow, capital allocation
There’s a lot to like about Character save for its obvious weakness of being quite dependent on the remarkable popularity of Peppa Pig (and its own lack of intellectual property). Supplier or customer concentration is a fact of life for many small cap companies, unfortunately. This risk has crystallised somewhat in recent weeks for Character.
That aside, Character Group is a cash-generating machine. The group chucked off 41p free cash flow per share in FY18, giving its shares a free cash flow yield of 11.4%. What’s more, Character’s management has historically been quite shareholder-minded when it comes to deploying this cash.
Over the past five years, the group has brought back about £11m of shares, it has paid out nearly £15m in dividends, and it has gone from net debt of -£4m to net cash of £20m. This performance may have been turbo-charged by Peppa Pig sales, but at least shareholders have benefitted from the plunder.
You can see its Quality credentials for yourself:
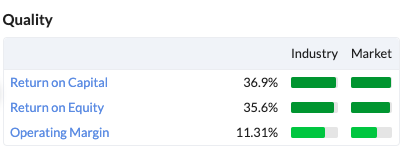
In fact, the group has a Quality Rank of 99. Here’s how Stockopedia comes to that conclusion:
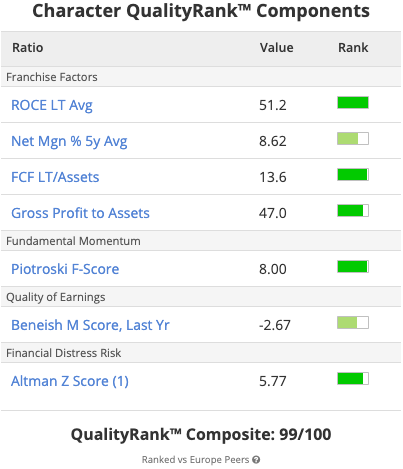
Unfortunately, these quality metrics can’t completely spare Character from external shocks. No company operates in a vacuum and problems have piled up.
Balance sheet - is fine. Strong, in fact, with net cash of c£20m and a current ratio of more than 2x.
My view
Character Group operates in a highly profitable, but fragile, niche. It has no real barriers to entry that I can see save for its reputation and existing relationships. That said, management owns shares and the group has demonstrated a track record of redistributing cash to shareholders.
If you take a long-term view and back the management, then these levels could be a buying opportunity. My hunch is that in the short term, lower conviction holders will have been rattled by recent developments and more selling pressure is to come. This could be wrong, of course, but some of the issues CCT has pointed to could take a long time to work their way through the system. Brexit disruption could be a dominant market dynamic for years to come. Top Toy is also unlikely to be the last toy retailer to go into liquidation.
That said, Character has a clean balance sheet, strong cash generation, and high returns on capital. Management is experienced and has skin in the game. Assuming the company can navigate these trickier markets and continue its habit of returning cash to shareholders, then this could be a contrarian buy. I just think risks have increased, and I wouldn’t expect momentum to improve anytime soon.
Also by Jack:
JD Wetherspoon
- Share price: 1546p (-0.3%)
- No. of shares: 105 million
- Market cap: £1.63 billion
Who would’ve thought JD Wetherspoon would become so… politicised.
Chairman and founder Tim Martin has become one of the most vocal proponents of Brexit and his Chairman’s Statements have become go-to reading for people on either side of the debate.
Regardless of where you stand on politics, you can’t deny that the man knows how to run pubs. JDW is probably the only modern pub chain that has elevated itself to ‘brand’ status - this should not be underestimated. Everybody knows what they are going to get at a Wetherspoon’s: an affordable and diverse selection of high-quality beers, well-maintained toilets, boat loads of coffee refills, and a cheap fry up - often in a stunning freehold property.
Trading
Like-for-like sales are up 6.8% in the year making for total sales of £1.8bn (+7.4%) and profit before tax is down slightly at £102.5m, although the group has invested a substantial sum of money into its estate (£167.6m in the period, vs. £110.1m in FY18). Of this sum, £35.2m was invested in new pubs and pub extensions (2018: £35.9m), £55.2m in existing pubs and IT (2018: £64.7m) and £77.2m in freehold reversions, where Wetherspoon was already a tenant (2018: £9.5m).
This leaves free cash flow per share of 92p, by the company’s own calculations, vs. its current share price of 1,541p.
The last two weeks of the year were better than the year as a whole, which bodes well as the chain heads into the new financial year.
Margin is down and debt is up but, with JDW, this is usually a sign that it is investing wisely and further establishing its competitive moat (of low prices, high quality, little debt, and lots of freehold property). Indeed, debt has gone up this year as a result of the pub group buying its properties.
View
There are few companies that are genuinely run as if they aim to be around forever. It is far more common to see companies run in a short-termist, EPS-targeting, option-vesting manner. When you do encounter those companies run for the long-term, you can usually tell from the accounts and management commentary.
Games Workshop is one of them, and Goodwin also comes to mind. I think JD Wetherspoon is another. I urge you to check the group’s statement if you have time. In it is a table that is literally too long to post on here, showing Wetherspoon’s sales, profits, and cash flows from 1984 through to 2019. Not many companies provide investors with that kind of perspective because not many companies genuinely think in terms of decades.
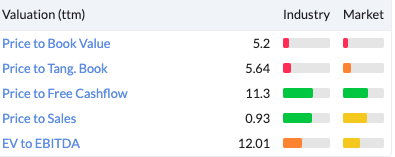
That said, the group’s shares are quite expensive right now. With 900 pubs around the UK, there is probably scope for more growth, but I suspect you can probably get better returns elsewhere. It’s a quality operator though, probably the best pub company in the UK.
By Graham:
GAN (LON:GAN)
- Share price: 86.5p (+19%)
- No. of shares: 85 million
- Market cap: £74 million
Trading update and conclusion of strategic review
August 2019 Internet Gambling Growth for NJ
This is a B2B provider of software to the gambling industry.
I've written about it a few times before - see the archives.
The bull thesis is that it's going to exploit new opportunities in the US, and become a much, much bigger business. Historically, it hasn't been profitable.
H1 results
Today's results show revenue increasing by 145% (not a typo) to £11.3 million.
- the company moves into profit (£0.7 million).
- cash balance bounces higher to £9.1 million, no debt.
- US is responsible for 78% of turnover (the rest from Italy).
Of the revenue in the period, £3 million was attributable to a patent which GAN licensed to a US company.
This patent is to do with linking a casino reward card/reward points with online gambling accounts.
While the £3 million license is not recurring in nature, there could be more deals like this to come:
The Patent was awarded to GAN in September 2014, successfully defended in H1 2017 and has now been licensed for substantial consideration setting a precedent for additional Patent licensing agreements.
Discussions with more land-based casino operators are underway.
Looking at other revenue sources for GAN, £4.3 million was from "real money gaming operations recurring revenue". This revenue source has more than doubled, compared to the prior year.
Other major developments in the period include legal online betting for the first time on the Super Bowl in New Jersey (GAN's platform was used) and six more US states enabling online gambling (Rhode Island, Montana, Indiana, Iowa, Tennessee and Illinois).
Outlook
The CEO is positive on the company's prospects, to say the least:
We have an incredibly positive outlook for the remainder of 2019, as the recent launch of Internet sports betting and casino gaming in Pennsylvania, the Company's current sales pipeline and existing contracted clients are projected to significantly enhance GAN's revenue and EBITDA prospects.
H2 will benefit from "the seasonally strong Winter period" and the new NFL season from September. More specifically, GAN will be involved in Fanduel for Flutter Entertainment (LON:FLTR) in Pennsylvania and the real money online casino for Parx in New Jersey.
Strategic Review
Instead of accepting a bid to go private, GAN has decided that a US stock market listing will be in the best interests of its shareholders.
Can't argue with that: the US markets tend to give companies the highest valuations. And with GAN now being a US-centric company, US investors are likely to be friendly to it.
I note the company says it "received multiple bids from multiple parties during the FSP". So maybe there is still scope for a takeover bid at a future date?
My view
There is a lot of information to digest - sorry for all the detail, but nearly all of it seems important! There is a lot more in GAN's RNS announcements today. They have even published an RNS specifically outlining the huge growth of the online gambling industry in New Jersey.
As for whether I would invest in these shares, I am tempted to have a "flutter" but that's all it would be - I don't really know how to value GAN's patent and software.
I am much more comfortable investing in a B2C brand like 888 whose market positioning I have some ability to analyse and to judge (and I do have a long position in 888).
What I find particularly interesting about GAN is that its growth helps to confirm the explosion in online gambling activity in the United States. 888, Flutter Entertainment and others could potentially benefit in a huge way from these developments.
GAN's enterprise value of £65 million might well turn out to be too cheap, given that revenues doubling again before too long does not seem out of the question. For example, a few more patent licensing deals with casinos would result in more large cash flows straight to the company, probably without needing to spend very much at all (except maybe on lawyers, to defend the IP).
The recurring revenue side of the business is also very strong, doubling in a year. What's to stop it from continuing to grow along with the US onling gambling industry?
So in summary, I do think that this is an intriguing share and might be worthy of additional research. For those of us who can't achieve a deeper understanding of the B2B gambling landscape, there are probably safer ways to access the growth of the gambling industry in the US.
Team17 (LON:TM17)
- Share price: 295p (-1%)
- No. of shares: 129 million
- Market cap: £381 million
Taking a look at this in response to reader requests.
Team17 has been listed for little more than a year.
The name will ring a bell for those of you who have ever played Worms (I must admit that I played it quite a bit).
The company says that it is still making "significant revenues" from its back catalogue of games, including Worms.
I note that it develops its own IP in-house while also supporting "indie" (independent) games from external developers (in exchange for revenue share). It says:
Digital distribution... has significantly reduced barriers to entry for developers looking to bring games to market. Through our Games Label, we can support independent developers of all sizes (wherever they are located in the world) to launch their titles and maximise their commercial value.
As we know, digital distribution was a key issue for investors in Game Digital (GMD), now owned by Sports Direct.
H1 Results & Outlook
The growth rates in this half-year report are terrific. As with Frontier Developments (LON:FDEV), it's important to bear in mind that game developers have a production and release cycle which creates spikes and troughs in their sales figures.
Indeed, Team17 wastes no time in reminding investors of this, and that the "revenue profile across FY19" is "more H1 weighted than previous years due to release schedule."
The Board is "comfortable with full year expectations", implying that the strong H1 was already baked into the plans for the year.
The full-year revenue forecast is c. £51 million, versus £30.4 million in H1. So the revenue split is approximately 60:40.
My view
I'm impressed! It looks like this company is well-diversified among many different titles. Also, given the emphasis being placed on its back-catalogue, Team17 creates the impression that it doesn't have to reinvent the wheel every six months - it will always get at least some revenue from the existing titles.
The diversification and back-catalogue should serve to take a lot of the risk out of the stock.
The market seems to be equally impressed as I am, awarding the company a very high rating:
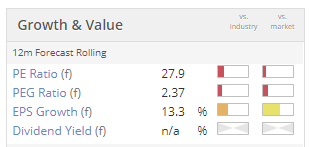
Is it worth this rating? I don't know, but I like what I've seen so far and look forward to keeping an eye on this one in future.
That's it for this week, have a good weekend everyone.
Cheers
Graham
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

62 comments
Nice work Graham and Jack
Hi Graham,
I posted a comment about Xaar (LON:XAR) yesterday regarding Xaar 3D shareholding sale. As you have commented on Xaar (LON:XAR) in recent past wondered what you think about the proposed deal?
I haven't looked at that news from Xaar (LON:XAR) yet ACounsell, sorry. Maybe on Monday! G
Hi Graham
Interested to get your thoughts on £888 from reporting earlier in week.
Cheers
re: 888
Hi EI, I covered that in detail in the Midcap Report (you can get to it by clicking on my face above!)
Market cap nearly £600 million so it's better suited for midcap reporting.
Thanks
Graham
Hey Graham, where do I find the 888 write up?
Kev231072
Grahams mid cap report can be found at https://cube.investments/categ...
Some other familiar writers also contribute...
thank you
............
Graham
Character (LON:CCT) has more barriers to competition than you give it credit for and also owns its own IPR as well as licensing and distributing. It's an important point not to overlook with this share, though seems to be a fairly common misconception. Wouldn't surprise me if a bid comes in given the fall.
Hi David,
In Graham's defence, I wrote the CCT piece! I do see appeal in the shares, but I see risk as well. What do you think are CCT's barriers (beyond experienced management, distribution network, and licensing)? As far as I'm aware, CCT doesn't actually own any IP? Not in the same way that GAW does, for example.
Character says in their latest report that
"Our current portfolio is derived from our own-developed, inhouse ranges, including those that we produce ‘under licence’, and those of third-party manufacturers, which we distribute in our territories on an exclusive basis"
So while they don't own the Peppa Pig character the toys are developed by them and I assume that means they have some IP in the designs. The same applies to the Stretch figures they sell with Hasbro branding.
So although they aren't vertically integrated like GAW they are more than a simple distributor. I don't think Hasbro can just say thank you in two years and start making all the current Peppa Pig toys themselves without reaching an agreement with CCT.
I see, thanks for the quote and comment John. I wonder how much value you might ascribe to CCT's inhouse design and development function. I couldn't find any mention of IP in the accounts - happy to stand corrected - but I would've thought management would explicitly reference this aspect of their business? I see intangible assets of £803k for product development in the FY18 accounts. This figure could be understated.
To be clear, I can see a lot of good plus points re. CCT - the returns on capital, the cash generation and distribution (divis & buybacks), the owner-founder management with substantial shareholdings, and (esp. now) the valuation. I believe forecast divi yield is above f'cast PE ratio. But I also think short-term risks have increased. For those willing to accept the risk, it strikes me as a profitable, well-run company that could be a good medium-term investment.
Hi Jack
Yes, my answer is similar to Johns post above.
They develop some of their own toy products in-house, some of which relate to licences and others that are their own creation. If a licence expires the company taking back the licence won't get the toy designs, unless they agree to pay something for that IP.
This is also why licences tend to be for a long window. We are very focused on Peppa Pig as it is pertinent to the Character (LON:CCT) will have had it for 17 years! Successful designers and distributors have sticky clients. The two things combined provide what I would call a mini-moat!
Since Character (LON:CCT) only tends to trade at a maximum of 10-12* cash adjusted earnings licences that last 17 years plus are fine. If they were perpetual the share price would command higher multiples.
You obviously need to be able to replace and diversify successfully in case an event such as a takeover happens and that's what management seem very good at.
Then you have the fact that product design coupled with very strong distribution is far from easy to replace. New entrants find it really hard to break into this market. Why would brand owners, or toy designers give exclusivity to un-tested new entrants when Character (LON:CCT) have proven so adept at understanding and tapping the market and creating value consistently over time? People seem to be under the impression that this is an easy market to break into and it really isn't. This acts as another mini-moat. It helps of course that Character (LON:CCT) is so good it recently won supplier of the year at the industry annual awards.
My point previously was really that there's been an over-reaction partly created by uncertainty and partly by a lack of understanding around the nature of the business model. At the current price the market has more than discounted in a complete removal of the Peppa licence and attributed nothing back for the next 2 years which are secure at the very least.
It has assumed, despite good historic performance suggesting the contrary, that management will not replace any lost revenues with new licences and products. The current multiples suggest that the market thinks the average licence duration is 5 years, when really it is 2-4 times that for the good products.
Hence for me risk/reward now looks pretty good. You'll get all the benefit of the next two years Peppa revenues and any licence extension (in whatever form) for free. If the
Probably not of interest to most, but the announcements from £EDGE are interesting......if only to illustrate the type of stock that everyone should steer clear of IMHO.
Value destruction on a grand scale and clear evidence in non independent directors!
Jobs for the boys at its worst.
Appalling behaviour or the remaining director at EDGE - reappointing directors who had been removed at the AGM vote. That last time I saw this happen was at Victoria - but that soon got overturned and all of them removed! That should happen here if shareholders had any sense.
Does anyone have any in-depth view on GAN (LON:GAN) ? I see todays announcement revealed a massive uptick in revenues of 145%, profitability and net cash on b/s of £9m. Termination of sales process given multiple bids that did not attribute sufficient value for shareholders.
I do not have any position but nominally looks interesting. Anyone looked at this, is there a catch?
David, I've started having a look at £GAN I think it potentially has a lot of runway ahead as more states are allowing sports betting, and the consensus is that more will likely follow. This is from an article last year, citing research that up to 32 states would allow it within 5 years. Interestingly, the major sports associations (NFL, NBA etc) aren't supportive as they feel it impacts the integrity of their games.
There's £9m of cash and no debt, it appears now cash generative as you say so this helps derisk and the tone of the update today extremely bullish in outlook. Also looking at a listing on major US exchange.
I guess there is always the risk regulation could go the other way but that doesn't seem to be the path they're on.
I know this is probably controversial but I no longer pay much attention to P&Ls or Balance Sheets (or whatever they are called this morning) because I no longer trust auditors to find out and tell the truth. I put a comment about this on AcccountingWeb and nobody disagreed with me - the accountants themselves seem to feel that the audit profession needs to change.
Therefore what I look at now is the same metric I studied closely when I was running my own business - cash flow.
It doesn't tell the whole story about a business and it can mislead in a fraud (eg: Patisserie Holdings) but I trust it enough to use it when choosing investments.
Here's my question. Does anyone have experience of using the Stockopedia 'Price to Free Cashflow' metric and if so have you found it to be accurate and reliable?
Thanks in advance for any help.
I have always regarded cash flow as the most important metric. Stocko numbers are a place to start, but you do really need to go through it in detail yourself looking carefully for any discrepancies or unexplained items. Wouldn't be enough to avoid the Patisserie Holdings (LON:CAKE) type fraud, but that type of risk is one of the reasons for having a more diversified portfolio.
My view is that recent accounting standards have made it all much harder to analyse. Items which are essentially risks or paper adjustments are making their way on to the main accounts. Those numbers are important but would, in my view, be better handled as potential modifiers in footnotes.
I would say be careful of the headline figures reported by stocko. I just picked out Direct Line Insurance (LON:DLG) at random as a stock with high cashflow. Today the stock report says price 298.5 (up 1.4), FCF ps 44.3 and Price to free cashflow 6.64 instead of 6.71. Not an enormous difference but enough to show the numbers come from different sources/calculations. I mention this because in the past I have seen enormous differences in these two numbers.
On the wider point I agree with the importance of looking at free cashflow, but it is only one perspective and if you focus on it exclusively you limit your potential universe of stocks, potentially excluding many high growth stocks. That may be the right thing for you, given what you are comfortable with, but it is something to be aware of.
When evaluating a listed company, the accounts are really useful but they do not represent the full picture. Staff turnover, customer churn, levels of repeat business, reputation – all of these plus a whole lot of other quantitative and qualitative factors are incredibly important. But it's very difficult for investors to ascertain this type of information. Possibly accepting that no matter what research you do, there will be missing pieces of the jigsaw may be a way forward. My approach is not to be over-exposed to any one company. And investing no more than I can comfortably afford to lose on any single stock – there are simply too many unknowns.
Not trusting the accounts is very much what I just said in my new book entitled "Business Perspective Investing" (subtitled "Why financial numbers are not important when picking shares"). Even cash flow figures can be misleading if there is downright fraud, which is quite common - Patisserie is just one example.
You need to look at many other facets of a company not just the financial numbers.
Book plug *cough cough*
I know this is not really a small cap at all, but if possible and worthwhile, a short comment on John Lewis reporting a 25m loss and the forward looking comments they made on a no deal brexit's impact on JL's trading.
This must have a read-across to the rest of the high st and possibly online retailers as all that stuff needs to be imported and online retailers (I am guessing) carry less stock than shops.
With the text editor links to numeric tickers can be emulated ... Team17 (LON:TM17)
Property Franchise (LON:TPFG) H1 results presentation by CEO & CFO, given on day of results.
A very comprehensive overview of this franchise, outlining how their growing, the opportunities, including their hopes for financial services, and the threats of the legislative landscape. Open honest management, and a good divi.
Further, if you haven't seen it yet, take a look at Stephen Yiu's interview from Blue Whale. It's always enlightening to see how the pros do it - especially when he's achieving an annualised return of over 20%.
A very good overview of Property Franchise (LON:TPFG)
Thanks for providing this service
Can't access presentation video for Property Franchise group. Comes back with error code 404 oops! Anything you can advise. I have tried via both their site and piworld.
Ted, Have you tried here -
https://cube.investments/cube-podcast-19-property-franchise-generating-annuities-for-shareholders/
You might need to scroll down the page a little then click on the "play" arrow in the black box.
Never held J D Wetherspoon (LON:JDW) but, in my experience, their venues are often rammed despite the surrounding streets being otherwise largely empty. Food very average but beer unbelievably well priced.
J D Wetherspoon (LON:JDW)
I think there is room in the world for the odd eccentric - no one is forced to buy the companies shares and mr Martin has done a great job for shareholders like me over the years.
I can’t see any downward spiral with regard to profits or any of the numbers to be honest - the last 3 years have been record breaking and eps has gone from sub 50p prior to those years up to an average of 75p for the last 30 years. 50% increase in that time is fine by me.
Profit after exceptionals is up - operating profit is down less than 0.5% - that’s not a downward spiral when we factor in last years numbers were their best ever. If you are looking at the £5 mill reduction in profit before tax this looks to be solely down to the extra finance presumably associated with them fixing the interest rate for 10 years on 770 mill of their debt. Debt hasn’t gone up materially so if future finance costs are also higher I see that as being outside the control of the company. It makes sense for them to have a known fixed rate if that is available at a reasonable price.
J D Wetherspoon (LON:JDW) I often go into a Spoons with a couple of friends who are near fanboys of pub not Martin - one's an anti Brexit European national the other very pro Brexit Brit entrepreneur. I've never researched the company. Metrics looks frothy on p/e basis but underlying cash generation over time v strong. Financially looks like a well run company and the question is what sort of growth it has.
Operationally it seems a really well run business. The pubs are usually pretty busy. On first take you'd perhaps expect it to be a middle age to old age blokey sort of place but usually got a younger crowd too...plus high proportion of women as well. Tend to have decent flow of punters during the day as well as at night. Prices lower helps obvs but there's something else to the formula IMO.
Martin should probably pull back on the political punditry and there's got to be some danger he's got himself too emotionally entangled in it. I find it hilarious in our time of endlessly streaming hypermedia Brexshit that people dislike the chain on political grounds.
third vote for £TM17 please
Paul, I would be interested in your views on Character (LON:CCT) ( I hold).
Negative trading update today. But the main news around Character is Hasbros recommended bid for Entertainment One (LON:ETO) announced on 23 Aug. Since then Character (LON:CCT) has fallen from 525p to 370p (yesterday). This is because Hasbro is likely to take in-house ETO’s toy production. Indeed this is explicit in Hasbro’s announcement of the bid:
“Hasbro expects to realize in-sourcing and other global annual run rate synergies of approximately US$130 million by 2022, driven by integration benefits, substantial savings from moving a significant portion of eOne's toy business in-house and enhancing the profitability of eOne's licensing and merchandising activities.”
Around a quarter of CCT’s revenue comes from toys licensed from ETO - principally Peppa Pig. The Peppa Pig licence was due for renewal in Dec 2020 - but today’s trading update says that ETO has agreed to extend this to June 2021. This gives CCT at least 21 months breathing space. Also it is intriguing why ETO would have agreed to the extension (particularly as this presumably has got the nod from Hasbro).
There are two other mitigating factors supporting the Character (LON:CCT) share price.
1) ETO trades above the 560p offer price, indicating that the market believes a third party could counter-bid. (For this to be useful to CCT, this would require this to be a third party not looking to take toy manufacture in-house. A media group?)
2). CCT has a strong cash balance, meaning it is likely to survive (if not thrive) whatever happens.
Yes, £CCT please.
On a side note, as a newbie to Stocko can anyone tell me how to create web-links to stocks in my discussion posts?
I notice everyone posts a stock code and its always linked to the stock report, how is that done?
Hi Kennzo,
Use the £ sign in front of a ticker, this works on most shares but not those that have numbers in the ticker (such as D4T4).
If you ever forget, there is a note at the bottom right of the text editor window - Use the £ sign in front of a ticker to turn Vodafone (LON:VOD) into Vodafone PLC.
Kennzo
Put the £ sign before the ticker for the stock. E.g. write “£VOD” for Vodafone (LON:VOD)
A couple of qualifications: 1). Does not work if the ticker has a numeral in it; and 2) leave a space after the ticker (don’t put a comma, full-stop, or apostrophe afterwards).
If you make an error, you have a hour after you have posted to edit your post.
Thank you investors, very helpful!
I also hold Character (LON:CCT) and made a mental note to buy more if the price dipped below 300p this morning on any over-reaction. I then went for a shower and came back at 8:05am having missed the opportunity down at 265p....damn!!
Peppa licence holds for the next 2 years and is 21% of revenues currently. You can see by commentary in todays report that they are already focused on further diversification of revenues. Management have a strong track record over many years both using in-house and licenced toys. They are highly respected in the industry and I would expect them to have the nous to replace capacity "if" the Peppa licence is taken in-house by Hasbro "and" the bid does actually win out. It's an unwelcome distraction granted, but I have felt for a while that the price fall is an over-reaction.
I read a comment on here that the market had cottoned on to the idea that Character (LON:CCT) have no moat but that's just a red herring, presumably from someone that doesn't actually know the business very well. The share has never traded at a "moat" multiple. It has always traded at a maximum of circa 10* cash adjusted earnings. It generally does have a number of small moats though including their own brands, strong reputable distribution that is not easy to replicate and strong industry relationships. Generally their product licences are quite long as well.
Hasbro have an existing relationship with Character (LON:CCT) over the Stretch licence, so it's not a given that the whole revenue stream from Peppa disappears. Hasbro could, for example, change the terms of exclusivity so that Character (LON:CCT) made toys co-exist with new Hasbro toys or they could give the licence on distribution back to Character (LON:CCT). The market also thinks a higher bid is coming so Hasbro may not get the franchise anyway. Therefore given that the immediate loss of Peppa is now more than built in to the share price the risk/reward looks skewed favourably.
As to todays announcement they are tracking towards a 45p EPS. Hardly a disaster. Clearly this has come from a specific event in the Scandi region and they expect the Proxy business to turn profitable again in the coming year so it seems management are comfortable the relevant actions have been taken.
Also bear in mind that 30% of their market cap is cash with no debt so balance sheet is very strong. That may not go up this year given the support given to Proxy, but nonetheless if you strip cash out from the share price it is now trading on 5.5* earnings and an 8% yield. I think that remains pretty attractive medium term.
Hi davidjhill,
Do you know what the volume was at 265p for Character (LON:CCT), that’s a crazy price and can’t have been much volume? Seems more likely one of those situations with tiny volumes and resting orders ?
hi John
Yep - small. Character (LON:CCT) opened at 250p/280p bid offer and actually only circa 3000 shares were traded before they were back above 300p, so probably wouldn't have got much, if any. Interesting to see they stabilised just a few pence down by close of play.
Hi Davidjhill,
Thanks for that info, where do you find that information, ie opening prices & traded volume?
Another vote for £TM17 from earlier in the week please.
Hi Paul, not too sure how busy the RNS is today for you, but if you have a chance could I persuade you to circle back to look at £TM17 interim results from earlier this week? Performance looks very good and they seem well set against the FY expectation. There is also a strong cash pile building. I do not currently hold but am considering...but the valuation is challenging!
Thanks!
Tom
another one for £tm17 please - I haven't had a look but the maker of Worms is certainly on my radar
Not a fan of Tim Martin, nor his establishments, but the results statement of J D Wetherspoon (LON:JDW) must be worth commenting on. Of the 19 paragraphs by Tim Martin before detailed commentary, 16 of those are devoted to brexit rather than the results of the company he chairs.
Not a shareholder, but if I was I’d be more focused on the downward spiral of profits rather than using his podium to talk politics. Wondering what the guy is paid for?
Niether a fan nor a detractor but the general trend of profits under him has been upward, not a trend downward:
2013-2019
Net profit -millions
'13 76.943
'14 79.362
'15 77.798
'16' 80.610
'17 102.830
'18 107.249
'19 102.459
talking of Brexit just copied and pasted this from barclays
Barclays has now decisively moved to ‘no deal’ as a base case. In their opinion much of the bad news is priced in, but not all of it,
downside risk scenario (below).
Impact of ‘no deal’
Interesting - I just read that the £ is up today as the market thinks a no deal is becoming less likely.
When a market commentator says the £ rose/fell for X reason they don't really know what they are talking about as they can't read minds. If you bought £ today, only you would know why wouldn't you.
Yet nearly half the population is in hysterics- including those who should know better- over such relatively small changes?!
Relatively small? They certainly weren't spelled out three years ago. And a £20bn to £40bn fiscal impact has ramifications for the wider economy.
Out of an annual UK government budget of circa £800bn, £20-£40bn impact is not exactly catastrophic. I’m sure most on here have seen their portfolios move more than (%) this in a day Besides, I can think of where 30 odd billion of that can come from...
Not sure JDW would eb worth Paul's time. It looks over-priced to me (PE 20, PEG 8), paltry dividend and large debt:net profits. Would I buy that business? No. Perhaps the buying pressure is in the hope that it will be the next GNK...
Actually, I found it after pressing the 'Discuss Tab' rather than the 'small cap value report' tab. But yes, not quite as straight forward.
Apologies for my comment at the top of todays report which I made on Wednesday whilst flailing around bleary eyed looking for that day's report! I think I've figured out how the placeholder system is now working.
My morning smallcap tweet:
GAN (LON:GAN), Character (LON:CCT)
GAN (GAN) rejects all offers received in strategic review. Trading is significantly ahead of the Board's expectations.
Character Group (CCT) guides pretax £11-11.5m, slightly under the lower end of current market expectations. Blames closure of largest Scandinavian customer and the weak £.
Looks like its my turn to bump this up to the top ready for the morning.
I've noticed that the last couple of days, the SCVR is quite hard to find (I got to it by looking at Paul's activity feed). Under the discussion links to it and on the home page, the links are all pointing to yesterday's report and earlier. I think this may be why there are so few comments.