Small Cap Value Report (Fri 14 Feb 2020) - TRI, INDV,

Good morning, it's Paul here with Friday's SCVR.
It's quiet for results/TUs today, so I'll circle back to a couple of stragglers that I didn't have time to look at earlier this week.
Estimated time of completion is 1pm
Edit at 12:26 - today's report is now finished.
I'm pleased to see that Elon Musk has followed up on my suggestion, to take advantage of the crazy rise in share price at $TSLA to do a fundraising of c.$2bn. Apparently this is a fortnight after he had confirmed that there wasn't going to be a fundraising. He gets away with murder, doesn't he! Anyway, it's most pleasing to note that he obviously reads the SCVR ;-)
This is a point worth emphasising actually, about fundraisings in times of share price strength. Any company that has a soaring share price, and a stretched valuation, should take advantage of that to do a top-up fundraising. Bull markets present a golden opportunity to fix balance sheets, pay off debt, and protect a business in advance of the next recession.
Yet hardly any management teams seem to anticipate the economic cycle. This is very strange. Why is it, that in the sphere of finance/economics, humans keep making the same mistakes without learning from them? Despite events following very clear cycles - both in terms of the stock market, and the economy as a whole.
Conditions now are looking increasingly similar to the boom conditions in 1998-99, and 2006-7. In both those times, I remember stock market valuations becoming very high, especially for growth companies. Optimism seemed boundless, people who warned about trouble ahead were ignored (because they had been consistently wrong for at least 5 years, so people stopped listening - even though we all knew that we were in a bubble!). Corporates and individuals were borrowing too much, leading to inflated asset prices, over-investment, and over-consumption.
Then something happens to prick the bubble, and economies slide into recession, stock markets tumble, and lenders start withdrawing credit.
I can't help feeling that we're nearing the end of this current bull cycle. Maybe another year or two before it all blows up? It feels like that to me.
Trifast (LON:TRI)
Share price: 166p (down 4%, at 08:36)
No. shares: 123.9m
Market cap: 205.7m
Trading update (mild profit warning)
International specialist in the design, engineering, manufacture and distribution of high quality industrial and Category 'C' fastenings principally to major global assembly industries.
The Board of Trifast provides the following unaudited trading update covering the Q3 financial period and up to the date of this announcement.
Trifast has a 30 March 2020 year end. Therefore this TU covers Oct-Dec, but also current trading in Q4 to date.
It's a profit warning I'm afraid -
In our Half-year results for the six months ended 30 September 2019, we commented that in the current financial year we expected trading to be weighted towards the second half in line with our normal trading pattern. However, since our announcement in November 2019 market conditions have become more challenging than had been anticipated, reflecting greater volatility of results in Q3, and a slower than forecast start to Q4 (the latter being historically our strongest quarter in the financial year).
The financial impact doesn't sound too bad at all - lower end of analysts' forecasts is OK, given that the forward PER isn't high;
The impact of this weakness has continued to constrain revenue growth across a number of our sectors. With a corresponding reduction in gross and operating margins against a semi-fixed cost base being further impacted by deferred start of production dates.
As a result, following a review of our year-to-date results and an update to our Q4 forecasts, the Board has concluded that the Group's underlying profit before tax in FY2020 is now expected to be at the lower end of analysts' forecasts.
I think shareholders should be quite relieved about that, I was expecting far worse, given the previous comments.
Coronavirus - doesn't sound like it's a major threat -
To date the impact of the Coronavirus epidemic has been restricted to the extended closure of our Chinese sites and a corresponding reduction in locally generated revenues. It is not possible at this time to assess how extensive any longer term impacts will be, but we are already working closely with our customers and supplier base, only c.10% of which originates in mainland China, to minimise these risks as far as possible.
I do wonder though, if there might be a knock-on effect? i.e. other suppliers outside China might rely on Chinese raw materials perhaps?
Outlook - "Project Atlas" sounds interesting - to drive efficiency, with "at least a 25% return on investment", which sounds good. Shorter term benefits are said to be slower than originally anticipated. I read that as meaning that profit forecasts will need to be trimmed a little in the short term.
Upbeat commentary about the medium-term future, hence not so great in the short-term;
Notwithstanding the current high levels of uncertainty, we are pleased to report that our pipeline of new wins is strong and activity levels around the Group continue to be encouraging. This means despite a challenging FY2020 the business remains well positioned in its markets and we are optimistic regarding prospects for revenue growth in FY2021 and beyond.
We are encouraged and supported by the fact that we have lost neither business nor customers over this difficult period and continue to hold preferred supplier status at a wide range of large manufacturers across the globe. The strong long-term fundamentals of our business model and strategy are unchanged and the Board continues to be optimistic for the medium-term future.
Updated forecasts - nothing available as yet. I will update this section if/when updated forecasts come through.
My opinion - a key omission from this update was a footnote showing what the range of analyst expectations are. This wastes time for everyone reading the announcement, as we now have to look it up. Please include this information in all trading updates, people who write & review RNSs (Peel Hunt and TooleyStreet Comms in this case). In all other respects, this announcement is clear, and well presented.
Nothing is said about the problems in the automotive sector, which must be affecting Trifast, as factories are slowing down production in some cases. Germany in particular is already struggling economically, and will be hit very hard by reduced demand from China, its main export market.
A niggling doubt I have, is that the financial impact of the above seems too mild. I wonder if the FD might have released some provisions, to soften the impact?
Let's see what the analysts do to forecasts. I'll update above later, if I get the info I need.
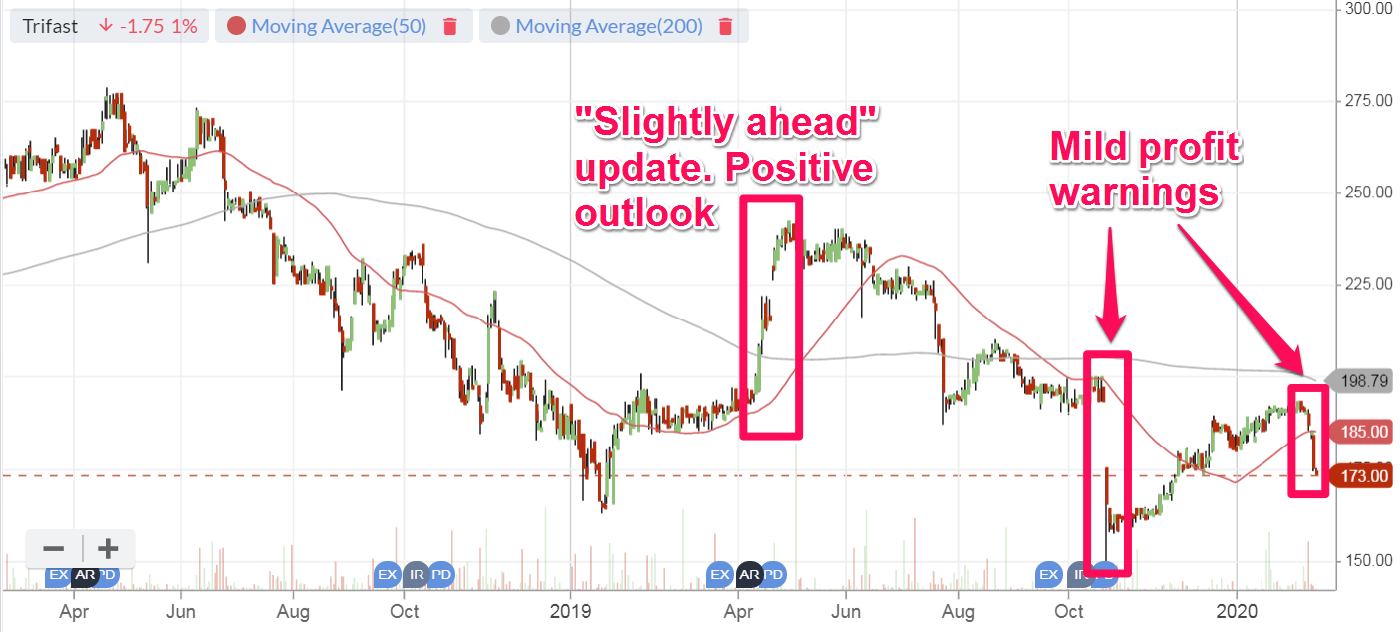
As things stand, I note that TRI shares had already fallen in recent days, presumably anticipating coronavirus fears & softer trading?
.
.
Macro factors must surely be mounting on Trifast. Therefore, I can't see any reason to get involved here for the time being.
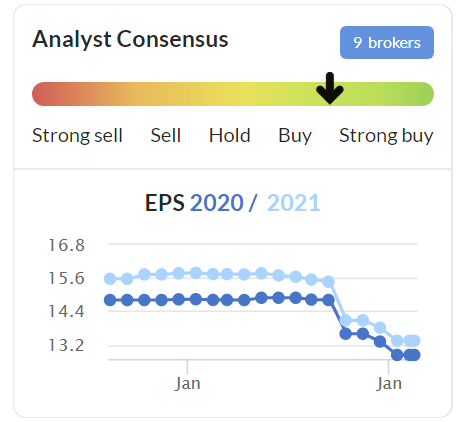
Note that broker forecasts have been steadily falling, and I'd expect more downgrades given the company news today, and disruption to global supply chains.
Note too that the Stockopedia tech team have fixed the y-axis on my favourite graph below! Please could Haynes shareholders return my bunting from yesterday, as I want to celebrate this (one of many improvements to the new site here, coming thick & fast!). I'm happy that the new site is now better than the old site, so I've switched permanently to the new Stocko site.
Indivior (LON:INDV)
Share price: 39p (down c.20% yesterday)
No. shares: 731.7m
Market cap: £285.4m
This is a speciality pharmaceuticals company, that I've never looked at before. It used to be worth several billion, so something has clearly gone disastrously wrong, for it to now be a small cap. Graham wrote a very interesting piece about it here in July 2018, pointing out that the fall to 270p per share was due to a generic alternative to INDV's key drug, Suboxone.
With the price now a fraction of that, and Stockopedia showing that its cash pile is more than the market cap, curiosity got the better of me last night, so I did a bit more digging. What could the catch possibly be?
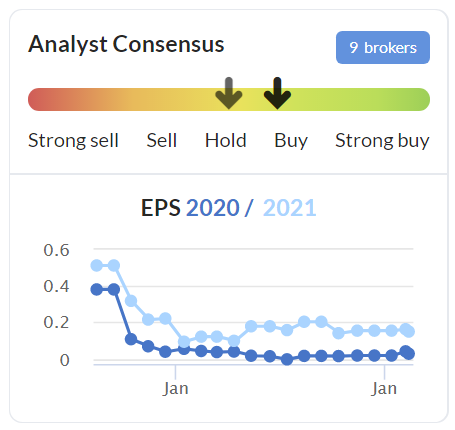
My favourite chart (now with a y-axis!!) gives a good clue - earnings are collapsing;
.
.
Also, the FY 12/2019 numbers have clearly disappointed the market, with a poor, loss-making Q4.
Legal claim - however, the main reason this share looks so cheap, has to be this;
On April 9, 2019, a federal grand jury in the Western District of Virginia indicted Indivior PLC and Indivior Inc. on charges of health care fraud, wire fraud, mail fraud, and conspiracy, in connection with the marketing and promotion practices, pediatric safety claims, and overprescribing of SUBOXONE® Film and/or SUBOXONE® Tablet by certain physicians. DOJ is seeking to recover $3 billion in monetary forfeitures and all
My opinion - the legal claim makes this share uninvestable for me.
It's so huge, that to value the share correctly, you would need to become an expert in its legal problem. Nothing much else even matters, given the size of the claim. There also seem to be other legal things going on. Note 12 to the accounts gives chapter & verse.
Because of these massive legal claims, I can't take this investment idea any further, other than to say I won't be revisiting it!
Unfortunately, I can't find anything else of interest, either today, or in my notes from earlier this week.
Therefore, I'm going to sign off the the day, and the week. Have a terrific weekend!
Best wishes, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

38 comments
There is an interesting discussion of INDV (Individor) here:
https://www.stockopedia.com/content/what-are-your-golden-rules-552576?order=createdAt&sort=desc&mode=threaded
but as this is the forum with the most reads let us try to shake out some comment from the 'heavy hitters' about anchoring.
The author ends with: It is also poor logic to wait for a share to recover back to the price you paid for it. That price is only significant to one person (you) and is the classic psychological mistake of “anchoring”. This is worthy of a whole post in itself.
For the same of argument I suggest anchoring can be useful for buying and selling relative to the price you previously paid.
In 2019 I Sold INDV ,517 having Bot at ,45. In 2018 at ,97 having Bot at ,84 and earlier that year Sold 2,18 Bot 1,76. So at the present price it looks interesting. Respected poster Cisk makes the point cash-debt=mrkt cap.
However reading Note 12, as suggested by Paul, prevents me purchasing until the lowest recent prices recur, below 30p.
Another share in the news AIR (Air Partner) has just rejoined my portfolio at 74p.
2019 Sold ,97 Bot ,83.
Sure News changes but Prices have Memory.
Discuss.
Thanks for the shoutout aflash - unfortunately I broke one of my rules and duly bought some £INVD - then to sell a few days later on a thumping % loss! Thankfully I only put in a tiny amount...
Should have researched further of course and not bought on instinct - when does one ever make money from that?!
If the legal case is won / settled then I’m sure the shares will rocket, but as Paul says, it’s a huge cloud to be operating under. My guess is that they will settle - but at what price?
One strategy I’ve been using more of recently is to buy back stock I’ve held in the past, whose price has bombed out (and in many cases I lost money on previously). After all, if you’ve already done the research and still like the company, why not, if the fundamental reasons you bought in the first place remain the same?
Animalcare (LON:ANCR) and Avacta (LON:AVCT) fall into that category for me. I’ve not bet the farm on either, as both are high risk, but they seem to be turning the corner, although with Avacta (LON:AVCT) there’s more hot air which has yet to be turned into movement...
I think thats a great strategy cisk, I personally do something similar myself. my watch list consists of about 50-60 stocks all of which I "try" to take notes on and build up a clear picture over time until a buying opportunity presents itself.
Yes another 'mistake' is not to double up when you a really good idea. I have money in around 4 places...would make sense to use cash in each place to buy stock in these top naps.
As an aside I have gone into an area quite aggressively for just about the first time..pharma/life science. Stock ranks is great but less useful in this space so it doesn't rea/ly bother me say that Avacta (LON:AVCT) is described as a sucker stock. It's really all about the future/potential. My interest was piqued by some of the fall from the Woodford debacle and one thing led to another. Biggest winner probably E-Therapeutics (LON:ETX).
what happened to Air Partner its share price fell from 95p to 74p,
Thats proper laziness, I should probably go and find out for myself
Errr Ambrosia, if you look at the company news on Air Partner (LON:AIR), you will see the profit warning issued on Jan 22... The trigger for the share price fall. Ed
Hi Paul
Thank you for the comment on Trifast (LON:TRI), which I persist in thinking is a well-run, undervalued company. (Though I sold last year.) Makes and sells nuts and bolts - what could be more boring. Although international, it is heavily weighted towards the continent - I agree it looks like it faces headwinds at the moment.
I have just joined Stockopedia with no finance background.Your comment regarding the bubble scares a beginner.All growth companies have inflated prices.The political turmoil of the past two years have taken a toll on the job market especially the financial institutions.Quantitative easing maybe holding the markets but raised asset prices ,inflation and weak growth will effect everyone in the country this includes businesses too.
Is there a way of identifying those companies that are not in the bubble or should we join everyone and invest anyway.
Yes you have to use Stockopedia to find the hidden Gems that are either still good value or have a strong competitive advantage.
So as a starting point I would recommend you find out/read about
You can use the Screens under the Browse tab to screen for various criteria
I also like low / no debt and growing dividends (not necessarily a high dividend rate, but growing).
Sadiayusuf, you’re right to be cautious - don’t know how long you’ve been investing but I remember the dot com boom well enough, and there are certainly parallels between then and now.
Personally I wouldn’t be buying amazon, apple and the like but who knows how far momentum will take them. Tesla is another story and imho is crazily overvalued, but hey, that’s never stopped a stock from advancing!
Luckily the UK seems cheaper compared to US, but of course will still plummet if the Dow does.
As long as you don’t need the money in a hurry you can afford to ride out the inevitable storms and focus on good quality companies at decent prices - and this is a great place to look for them!
Meanwhile, what is going on at Malvern International (LON:MLVN) ? Very high volumes yesterday and today which given their appalling record of managing sensitive information (their announcement of the sale of the Malaysian business in early January was preceded by a massive spike in buying) suggests news is on its way. I have a very small position which is getting smaller by the day.
Cheers
Francis
As Paul reminded me yesterday in my schoolboy error post, the low share price means even a volume of 5 million (as of 1pm today) is actually still only about £25,000.
ps. although I think this could be a nice turnaround story, I am a little worried in the immediate term that they might be hit by Coronavirus in terms of overseas students/learners needing to travel to the UK.
Hi Patrick,
I agree that the value of trades is low but my point was that the volume of shares traded is disproportionately high over the last two days, relative to other days.
cheers
Francis
I don't see how Malvern International (LON:MLVN) can go much lower. Its EV is about a quarter of that of Wey Education (LON:WEY) but with higher revenues. One of the two is incorrect!
The trouble for me is the loan they have taken out.... very expensive. Does anyone know the terms and conditions they alluded to in the last trading statement?
It seems a given that there may be a profit warning for this year due to a reduction of travelling students from South East Asia.
With the size of the loan relative to the market cap, it could be a case that existing shareholders could be squeezed out if things went bad.
Hi Snoo
Where did you get that information about a reduction in travelling students from SE Asia? Thanks
Nothing official....just a guess. It's pretty difficult to get a flight from China to here for the foreseeable future. British Airways have gone down to one flight a day from HK, because of bad load factors.
I don't mean the official student type at university (whom might have been back already), more those that might come over for vocational courses that Malvern offer.
Maybe it might not be too bad? I don't think Malvern give a breakdown but their recent acquisition Communicate English do, average age 27, Chinese only make up 2%.
yes sales dropped through the floor as one of their drugs expired its exclusive license
Your comment re Tesla that “Any company that has a soaring share price, and a stretched valuation, should take advantage of that to do a top-up fundraising. Bull markets present a golden opportunity to fix balance sheets, pay off debt, and protect a business in advance of the next recession” reminds me of the craze closer to home for hydrogen energy-related stocks - Itm Power (LON:ITM) Power and Ceres Power Holdings (LON:CWR) Power - or are their price rallies just too bubbly to support a share issue?
Add £phe to that list too
On learning from history:
There are some similarities between previous cycle peaks and current circumstances. But one thing history teaches is that: "bull markets don't die of old age". In other words it takes an initiating event, something beyond the ordinary market jitters to actually change mode from bull to bear, regardless of how long the bull market has been running. The UK market, in overall direction, is driven by the US market and that is usually only thrown off course by a recession. There have been very few bear markets that have not been triggered by an oncoming US recession. A US recession looks unlikely this year.
A related history lesson is that the last year of the presidential cycle (2020) is only bettered by the 3rd year for average stock market returns. There is a good reason for this: no president wants to face re-election during a downturn, so policy is engineered to give a boost.
Overall, history suggests that the market should grind upwards this year, regardless of valuation, and it would take something very significant to change that picture. Regrettably - in all respects - Covid-19 might be the thing that changes the picture, but we can only wait and see what happens with that.
People don't die of old age either...but it is ageing that heralds death and when very old is highly predictive.
Markets are always a riot of narrative fallacies. All is clear ex post. But just like with people, bull market age is a good probabilistic indicator the older it gets and the energy of price outruns the vitality of profits.
My guess is that hopes for a continued global bull market now rest on a weakening dollar (and its been strengthening) and a shift in this chart (for Asia too):
If these two things happen then the stale ageing US bull market where valuations are clearly stretched relative to profit vitality can allow other to lead. Here's an age related US chart:
Now, I do think the bull will run due to fiscal policy and debt monetisation....but there will be a very choppy interlude before that happens.
Re: Good Energy (LON:GOOD)
From what I can gather, Ecotricity have not filed their accounts yet with the intimation that their auditor Grant Thornton have a problem. That and the price cap perhaps?
cheers
Francis
Paul, could you have a look at GOOD if you have time, in the NAPS, big fall yesterday and today, thanks
£Good Could I second this - or at least ask if anyone knows why it has fallen so precipitously? Thanks
I've been puzzling over Good Energy (LON:GOOD) too (I hold). But so far there is no news so there is nothing for Paul to work on. My guess is that a big investor is pulling out and I'm wondering whether I dare buy at what I hope is the bottom. The fall has been 13% yesterday and 8% early today.
I don't know much about Good Energy (LON:GOOD) at all. The only general advice I can offer is that if the share price is falling so fast then maybe the market knows something that you don't, and that maybe it would be best to wait for news to come out and, hopefully, the upside to resume before committing any more funds.
Re: Good Energy (LON:GOOD)
I didn't either until I started looking at it today. At the £1.88 sp today it gives it a market cap of £30m with debt of nearly £40m and a book value per share of £1.22. Not sure what I'm missing but it looks extremely over valued to me. Whilst I'm very interested in renewable energy, I am concerned about investing in those with high premiums to NAV especially as there is talk of renewable energy revenues coming down against high fixed costs.
cheers
Francis
I'm as confused about the sudden drop as I was about the recent surge. As recently as late November, Good Energy (LON:GOOD) were around £1.50 per share. I couldn't work out what had prompted the price to rise to around £2.40. The current price compared with November's doesn't look quite so bad...
Hi andyd,
I only cover trading updates & results here, plus other interesting announcements such as takeover bids.
There's nothing from Good Energy (LON:GOOD) - the last trading information was on 10 Sept 2019, when it issued interim results.
Incidentally, as I've just changed a friend's electricity onto a renewables contract, I got a quote from GOOD. It's very expensive - about 30% more expensive than renewable energy from ScottishPower, which was the cheapest green provider on both uSwitch, and with the meerkat mob.
For my own home, I recently switched to Pure Planet, a 100% renewables company, which was actually cheaper than my previous supplier (non-green). Here is a referral link for Pure Planet (part owned & losses funded by British Gas) - we both get a £50 Amazon voucher each for everyone who signs up using this link
I'm happy to look at the next set of published accounts for you, when GOOD publish them.
Regards, Paul.
No problem, thanks for the reply
One problem Paul. They do not supply Northern Ireland. Ah well!!
Thanks for the nudge for me to check on what I am paying for electricity however I found Good Energy to be nearly £100 per year more expensive than my current provider and having now used one of the comparison sites I have found another provider that is over £200 per year cheaper than Good Energy.
No, they're not backed by British Gas but they do claim to supply Green Electricity so I'm happy.
"Why is it, that in the sphere of finance/economics, humans keep making the same mistakes without learning from them?"
Probably because loading up on debt when the market is offering it enhances EPS and the bonus payouts for those in charge....and of course a lowly geared company preparing for the inevitable downturn in the econoimic cycle gets asset stripped by PE funds and the directors removed from their jobs.
Hence equity buybacks and debt finance. Great for all while the party is in full swing, but leaves a far worse hangover the morning after when the cycle turns.
Not much 'appening this am. One thing I noticed was 4 Ergomed Directors have bought approx £40k of share each. Interesting business I have been watching for a while but not bought into yet. I am a little restrained on buying as since the Tories victory there has been quite a recovery. As Warren Buffett points out all boats rise on a tide. Seems to me investing is about trying to read these beta moments so one of the skills is not getting shaken out of the share in bad times, which like most of life seems to require confidence. The challenge is getting the right shares for the beta moments, which of course where you come in Paul (I know I know dyor, ) but I suspect many peoples' confidence isn't that strong and your approval/disapproval therefore takes on Achillean momentum to many decisions taken. Just saying......no criticism intended at all. I think you do a great job!!
'As Warren Buffett points out all boats rise on a tide.'
Only half the time.
In my experience boats do NOT rise on an ebb tide, only on an incoming tide.
"A rising tide floats all boats….. only when the tide goes out do you discover who’s been swimming naked."
Warren Buffett
My morning smallcap tweet: Trifast tries slow instead
Chamberlin (LON:CMH) Trifast (LON:TRI) Hydrodec (LON:HYR) Brickability (LON:BRCK) Mobeus Income & Growth 2 VCT (LON:MIG) Air Partner (LON:AIR)
Chamberlin (CMH) [last night] warns H2 was subdued with rev only slightly up on H1. H2 op loss broadly the same as H1 which was £1.01m.
Trifast (TRI) curse of H2 weighting - weak market means FY U/L pretax at the lower end of analysts' forecasts. Coronavirus - only 10% of supplies originates in mainland China, working closely with customers and suppliers to mitigate risk. Outlook - Project Atlas investment benefit realisation is likely to be slower than was originally anticipated. Order book is good.
HydroDec (HYR) terrible FY trading for this cash strapped tinpot. Rev off 22%, adj EBITDA -$3.2m (-$1.2m). Wins 3-year contract with Duke Energy, a major US utility, to process its used transformer oil. Nevertheless guides FY20 materially lower than previous market expectations due to ongoing working capital constraints.
Brickability (BRCK) buys a roofing products importer and distributor for £2.75m. The acquiree made FY19 pretax £0.7m on rev £8.2m
Mobeus Income & Growth 2 VCT (MIG) realisations of three investments bumps NAV 4.49p. Last ffig was 89.85p in Sept. Similarly for some other Mobeus Income & Growth VCTs.
Air Partner (AIR) has arranged flights for coronvirus evacuation. Hindered by China govt officials sticking to normal working hours.