Small Cap Value Report (Fri 15 Sep 2023) - PRV, WIX

Good morning from Paul! I'm off to a slow start today, with it being Friday. Hardly any fresh news today, so I'll focus on looking at interesting companies on the backlog list.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Summaries
Porvair (LON:PRV) 598p (£277m) - Nine Month Trading Update - Paul- GREEN
A Q3 YTD trading update from Tuesday this week is rather light on specifics, but I reckon it could be heading for a forecast busting 40p EPS in FY 11/2023 - half has already been achieved in H1, so broker consensus of 33p seems too low. Nice quality company, growing (helped by acquisitions), strong balance sheet, highly regarded management, and finally a valuation that I find appealing (after years of being over-priced in my view). So I think this could be a good entry point for a quality company. Could be a bid target, it looks the type of thing that private equity would find attractive at a 30% premium.
Wickes (LON:WIX) - 147p (£378m) - Interim Results - Paul - AMBER
H1 profit is down, but FY 12/2023 guidance is maintained. A thin profit margin of only 3%, and a lack of revenue growth (but rising costs) doesn't leave much room for any potential macro downturn. On the upside, Wickes is paying generous divis of 7.4%, and buybacks on top. Healthy balance sheet, although cash is a seasonal spike due to a build up of trade creditors. After a good run recently, I think the price is probably up with events for now.
Paul’s Section:
Porvair (LON:PRV)
598p (£277m) - Nine Month Trading Update - Paul- GREEN
Checking our previous reports, we consistently say the same thing about this specialist filters business - that the business is good, but shares look expensive. You can see that from graph 4 below, where the PER is usually above 20, with the PER of 17.1, being relatively speaking the cheapest it’s been over the 6-year range shown below -

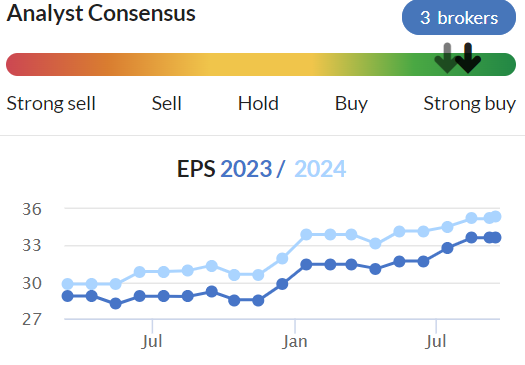
It’s good news on the trend for broker earnings estimates too, which have been rising - impressive in a tough macro environment -
Here’s the latest news -
Trading Update for the 9 months to 31 August 2023, for the FY 11/2023.
- Q3 trading “satisfactory”
- Full year guidance - “full year earnings to be above those for 2022.”
Looking up last year’s results they were good -
Revenue £172.6m (up 13% at CC)
Adj PBT £19.4m (up 31%) - note the decent profit margin of 11.2%, demonstrating pricing power.
Adj basic EPS 33.2p (up 32%).
Adjustments historically were only small, and look valid to me, being acquisition-related.
It’s a pity they didn’t say on Tuesday’s latest update how much they think FY 11/2022 results will be beaten by. So very vague guidance, albeit reassuring that this year is another year of profit growth.
The latest broker consensus for FY 11/2023 is 33.7p, only slightly up on last year, so it seems to me there’s more likelihood of results beating expectations, than missing them.
H1 profit was up 20% vs H1 LY, so unless it had a poor H2, then I’d guess that something nearer 40p EPS might be on the cards for this year (it did 20.1p aEPS in H1).
Nothing is said about cash, or the balance sheet in the latest update. I’ve checked it, and it’s very good, with net cash, and a strong overall NTAV position. Small pension deficit would need checking.
Paul’s opinion - if I’m right, and a forecast-busting 40p EPS is possible, then at 598p the PER is 15x.
For a high quality, growing business, I think that’s a decent entry price, so I’ll shift from AMBER to GREEN.
There might also be potential upside from a takeover bid - this strikes me as the sort of growth company that might attract private equity, or an overseas trade buyer.
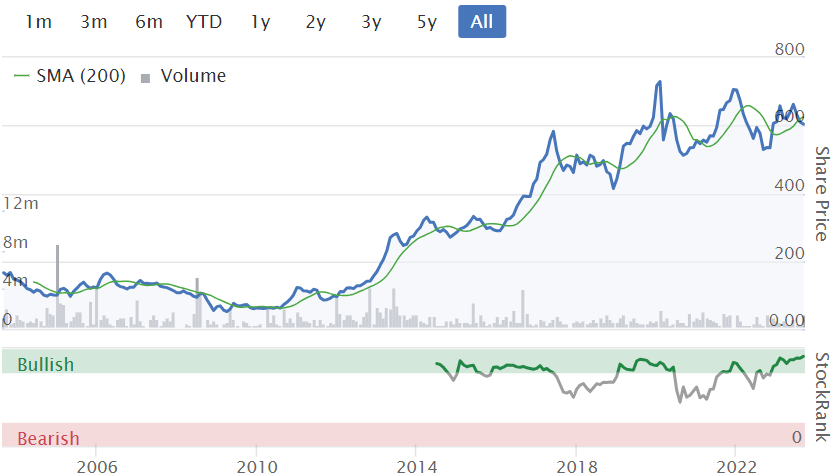
Multibagger in the long-term, although nothing much has happened in the last 4 years. Divis are modest, so not an income stock, as cashflows are spent on acquisitions.
£WIX
147p (£378m) - Interim Results - Paul - AMBER
for the 26 week period to 1 July 2023
Strategy continues to deliver, with positive first half LFL sales; full year expectations maintained
H1 revenue only up slightly 0.7% to £828m
Adj PBT £31.1m, down 25% on H1 LY
It presents another profit measure, adjusting out SaaS IT costs, but I’m not interested in this measure, so am ignoring it.
Share buybacks happening every day at the moment.
Adj EPS in H1 was 9.4p (down 29%)
Interim divi 3.6p - held flat vs LY.
Outlook - very detailed guidance is provided, which is impressive I think -
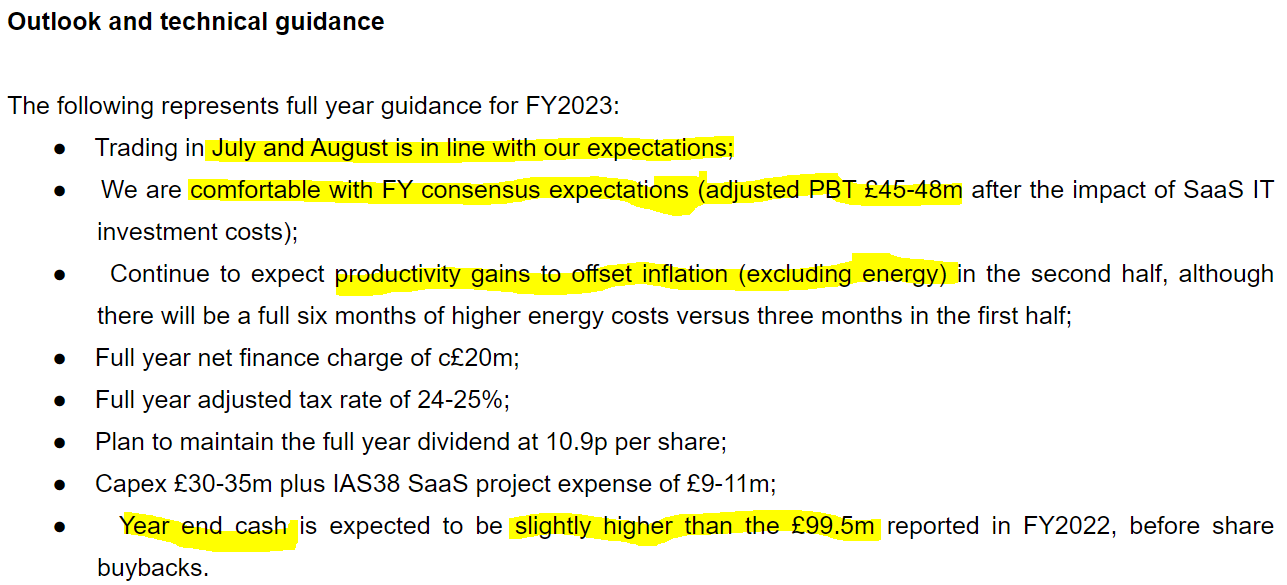
It’s worth pointing out that £45-48m aPBT is a thin profit margin on forecast revenues of almost £1.6bn, only about 3% at best. Worth bearing in mind, as the company would suffer if the economy goes into a full blown recession (I’m not sure that’s likely, but who knows?). Since home improvements are I imagine mostly done by homeowners, then higher mortgage costs could squeeze Wickes’ main customers as time goes on and more peoples’ fixed rates expire, leading to a loss of disposable income.
Forecasts - I can’t find any broker notes, but have manually worked out EPS for FY 12/2023 at 13.5p.
(Workings: aPBT £46.5m, 25% tax = PAT £34.9m, divided by 259.2m shares).
This gives a PER of 10.9, which is probably high enough for now, given macro headwinds.
The PER on the StockReport doesn’t look right to me, so I’ve just flagged it through the green blob, for checking with the data provider. It looks like the 1 Jan year end might have confused the data provider possibly?
Dividends & buybacks - a stand out feature of this share. It’s strong finances enable it to be generous with divis. As stated above, Wickes is planning on maintaining total divis of 10.9p for FY 12/2023. Giving a yield of a healthy 7.4%, but with cover of only 1.4x, so that yield could come under pressure to be reduced if 2024 profits continue falling.
A share buyback totalling £12.5m was announced on 28 July 2023, with transactions happening daily, as you can see from the RNS.
Balance sheet - looks pretty good. NAV is £164m, including £23m intangible assets, resulting in NTAV of £141m.
Lease liabilities are heavy, at £670m, with less on the debit side with Right of Use Assets of £529m, giving a leases deficit of £(141)m. If we eliminate all lease entries, then the balance sheet NTAV doubles to £282m.
The cash of £190m looks a seasonal high, and I can see that year end balances are about half this. Note that trade creditors seem unusually high at June period ends.
Paul’s view - the main attraction is income from a 7.4% divi yield, plus buybacks help enhance per share figures.
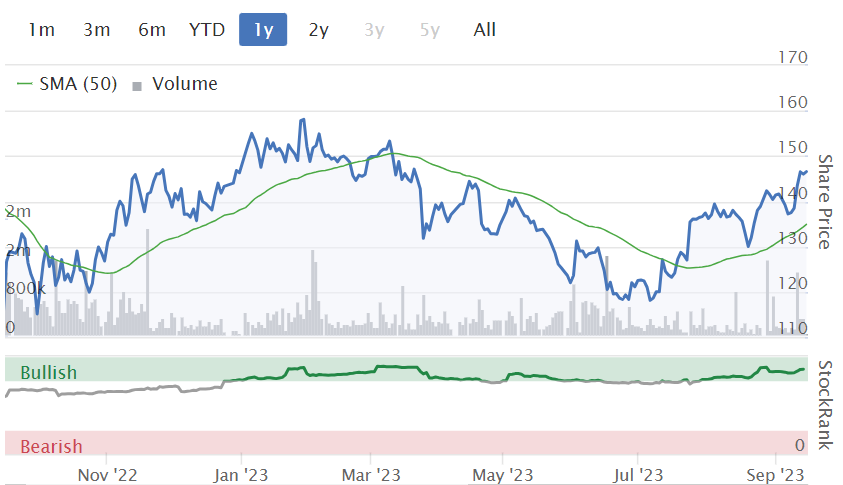
Shares have a had a nice run recently, and I’d say on fundamentals, in a period of tough macro conditions, the price is probably up with events for now. Hence I’ll go AMBER here.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

53 comments
Hi Paul
Wickes (LON:WIX) Sharepad shows an EPS of 14.2 for this year followed by 15.9 for 2024, which seems to be in the right ballpark.
I've sent several messages over several months regarding this and several other companies whose year end is 1/1/2023. None of them have been updated with the latest year end results and the forecasts are showing dates of 2022 and 2023 - utter nonsense - but nothing has been done to correct the situation.
Is there a special situation developing in Starwood European Real Estate Finance (LON:SWEF) ?
If I read it correctly they are winding down the company and returning capital over the next 2 years.
NAV is 103p and share price is 87p
Dividend is 6p and covered so NAV should go up slightly between now and maturity.
So with 16p of capital and 12p dividends a holder should get paid 28p over 2 years. That’s a 15/16% compound rate of return over 2 years.
Loans are heavily collateralised with low LTV so doesn’t feel like any major risk to capital.
Have I missed something?
David. Thanks for pointing out Starwood European Real Estate Finance (LON:SWEF) - it is not something I have looked at before. I think these sort of situations can,in principle, be interesting and often aeem priced to low by the market. SWEF seems to have been in wind down since the EGM in January 2023 - and it has started to make capital returns.
I am invested in 3 somewhat similar situations and I think the 15-16% annualised returns that you mention for SWEF (if NAV is reliable) is about where the market values these credit wind ups. Obviously, theae apparent returns have to be seen in the light that if NAV is materially wrong, it will be on the downside.
I hold SLF Realisation Fund (LON:SLFX) - which is now nearing completion, with most capital returned (generally through returns of capital); NB Global Monthly Income Fund (LON:NBMI) - which has already returned about 2/3 of it starting NAVs through mandatory acquisitions of shares (similar methodology to SWEF) and VPC Specialty Lending Investments (LON:VSL) - which has only just approved the windup at EGM and is yet to return capital but is still paying a double digit div yield. This last Victory Park wind-up is I believe offering a higher IRR to wind-up, although I think there are valid doubts about the speed (and incentives) the manager will do the wind up.
And Crystal Amber Fund (LON:CRS) which I hold is in a similar boat
Yes - although Crystal Amber Fund (LON:CRS) (I also hold) owns equity stakes. The "advantage" with a credit fund liquidating is that they just have to wait for the loans to be repaid - if the maturity is short enough. But for an equity fund, either they have to sell or engineer a corporate action to get an exit. Crystal Amber's listed stakes (De La Rue (LON:DLAR) and Sutton Harbour (LON:SUH) are quite chunky so selling in the market is quite difficult and some are already delisted (like Allied Minds or the contingent value in Hurricane).
The only thing I can think of is that dividends will presumably tend to zero as the assets are wound down (assuming they return cash as they go).
Reference Gulf Keystone Petroleum (LON:GKP) I agree peterg I should have used the word "rumour" and not "news" just in case it is "fake news".
HSS Hire (LON:HSS) on a forward PE of 5 and Yield of 4.3% looks cheap, but so do VP (LON:VP.) on 6.2 PE and 7.9% yield, and Speedy Hire (LON:SDY) on 6.4 PE and 7.9% yield. Stock ranks 94, 77 and 96 respectively . In my opinion they are all cheap for a reason - they are going nowhere.
Compare them with the 800lb gorilla in the rentals market Ashtead (LON:AHT), on the UK market at least, with a forward PE of 14, yield of 1.7% but 50% growth in revenue since the pandemic slump. None of the others have shown any growth of any significance since 2020. And the UK arm of Ashtead is its weakest link - no growth in latest FY v 20% growth in revenue in the US. Similarly profit margins in the UK business are only 28% v 48% and growth guidance has been lowered for the UK to 6-9% this year v 13 - 16% (unchanged) for US at the end of their Q1.
If you like yield why not look at VP (LON:VP.) or Speedy Hire (LON:SDY) . If you like quality, look at the difference in margins for Operating profit, ROCE and ROE, at Ashtead (LON:AHT) . What do HSS Hire (LON:HSS) offer of particular appeal, particularly at this point in the cycle? Is there a turnaround in the pipeline?
I suspect the big (Ashtead (LON:AHT) and United Rentals (NYQ:URI) ) will get bigger and the small will need to carve out niches to compete. Is it Competition authorities stopping Ashtead taking a bigger slug in the UK or is there just more opportunity in North America?
Excellent post sevencc, 100% agree with you and it is with that in mind that I invested in Ashtead Technology Holdings (LON:AT.) hoping they carve out that niche you refer to, I think HSS Hire (LON:HSS) and Speedy Hire (LON:SDY) are value traps.
Big jump this morning in Gulf Keystone Petroleum (LON:GKP) on news that Pipeline may be re opening soon. Not confirmed but SP up 25% on opening price of 85p. I hold having bought 4 days before pipeline closed!
Gulf Keystone Petroleum (LON:GKP) . Perhaps more accurate to say on "rumour" of pipeline reopening, rather than "news"? It's not the first time! It will happen, but until it's formally declared I would assume nothing.
Gulf Keystone Petroleum (LON:GKP) Genel Energy (LON:GENL)
This helped me to understand the risks faced by oil companies in Kurdistan : https://moram.eu/oil-companies...
Great article
I'm attracted to Gulf Keystone Petroleum (LON:GKP) because it's so cheap but I read a recent article that said that Russia effectively controls what happens at the Kurdish oil fields because they've historically been the main champions of the Kurdish cause and they have a strong influence in Kurdish domestic affairs. I can put up with most risks but anywhere where the Russians are heavily involved is too much for me. Having said that, everything is relative, and if pipeline reopens soon then this could well double in no time.
Gulf Keystone Petroleum (LON:GKP) ...the share that launched a thousand divorces
Myself likewise. OPEC is determined to keep produced reduced to as low a level as possible which does not bode well for GKP or my investment there.
You were going to go back to Eleco and Anpario Paul, you've dealt with long lists since but a quick comment on either would be much appreciated if you have time. We hold and added to Eleco and are looking to add to Anpario at around the current price.
On the question of when to start buying housebuilders, Paul's weekend podcast, Directors in MJ GLEESON (LON:GLE) - I hold - now starting to buy........
https://www.stockopedia.com/sh...
Market big move, 14 September
Housebuilders , Banks, Real Estate joined the party on the inflection day yesterday. I believe it is going to be the beginning of a steady rise over the next few months.
I looked at the directors buy and sell list at the Investorschronicle today: 17 buy and 1 sell.
Difficult time for investors with lots of cash, wait or join the party. Fear of missing out force them to join and the party continues!
I'm not so sure about there being investors with plenty of cash. They may rally round once a strong recovery is certain but I wouldn't mind betting the cash available has been put to good use elsewhere.
Wondered if anybody had any thoughts regarding the positive Ingenta (LON:ING) update on Monday - Graham took a look last year and it seems to be gaining a bit of momentum after some recent restructuring.
I just noticed this section at the very bottom of the stocko reports;
I used to scroll through the RNS's to see when the next trading statement was due - but no need anymore! Is it a new feature?
Although I've never managed it I don have a feeling that investors loose interest in between trading statements and that can be a good time to pick up stock at a better price.
Jim
It's always been there, although be aware that the dates are sometimes estimates until the company announces confirming the date.
In the old version of the stocko website there was a useful feature that showed a calendar of upcoming dates, including ex-dividends, agms etc. for your portfolio. That never made it onto the new version of the site.
"In the old version of the stocko website there was a useful feature that showed a calendar of upcoming dates, including ex-dividends, agms etc. for your portfolio. That never made it onto the new version of the site."
Well said RichTea. I really valued this calendar feature in the Folio section and it was a main driver of my resistance to move away from the old site to the new one. I was given assurances from the Stocko team that this feature will be added. Whenever I make periodic enquiries as to why it is not there yet, now maybe 2 years + on since the change I get feedback that there is little demand for it.
I found it extremely valuable and it was all in one place. Now if I want such information it requires a lot of effort on my part searching round various websites or manually pulling information from RNSs (which I don't have time to do). This is my big gripe with Stockopedia, they forced me onto a different version of the site (without this feature - a broken promise?) and their subscription prices have been rising notably. I'm still a subscriber for now, however I'm not entirely a happy camper. (Before anyone suggests it then yes I have communicated via the green contact us button on the bottom right before to flag this, numerous times.)
As its Friday let me throw this out there. Markets looking a little bit more positive in the last week or so. Wondering what everyones thoughts are and what they are doing if anything. I have invested some surplus cash in a few ETF's and new stocks in the last few weeks. I still have other money on the sidelines which I would like to put to use if the market falls at some point. I would love to put more into US ETFs but a combination of the strong USD and the gulf in P/E's between US and Europe for now stops me from doing that.
Still think there's a lot of crazily undervalued stuff out there and still seeing positive results meaning the stock doesn't fall and the slightest miss getting whacked.
Markets are scenting the top of the current interest rate cycle. Once there's talk of cuts (subject to the POO etc, of course) we might be off to the races. All this could occur just as we go into recession - but the markets look ahead 6-18 months.
Its nice to see some companies reporting profit growth amongst all the gloom.
BTW, the US market is always expensive - for good reason.
Jim
I've looked at markets versus interest rates historically. I might be missing something, but everyone keeps saying that when interest rates peak, stock markets will go up. I am confused. Historically, this doesn't seem to have happened as markets get fixated with recession instead and earnings estimates come down. The yield curve (i.e. cheaper to borrow long duration than short) is still 0.7% inverted and we are 14 months into the inversion. We are only at the start of a recession at this point, if its started at all and the yield curve is screaming beware!
Here are my thoughts if you have a graph of interest rates and share prices which is pretty easy to do if you google it - I have used the S&P500 and US rates as they are always the dominant force:
GFC - shares bottomed in March 2009 at least 15 months into the recession and as interest rates hit a low.
2002 - shares bottomed as interest rates bottomed-out and then rallied as rates were increased again.
1990 - shares moved up after 6-12m of recession and interest rates bottomed.
1980s - again shares only rallied as interest rates had troughed.
I think share prices might reduce as interest rates are cut from high levels. If rates are cut quickly, the reason will most likely be that recession has arrived. This is unless you believe that central bankers will perfectly time their actions to reduce inflation to 2% without any negative consequences (despite the fact they don't ever appear to have achieved this before and after an unprecedented 15+ years of bubbles, money printing and zero cost money).
The market seems to think this time is different and there will be no recession. That has almost never happened on a yield curve inversion and particularly for one of this size and duration.
What am I missing as its keeping me from deploying cash at this point?
I think it’s a difficult one Topvest I agree there are some contradictory indicators out there.
What I would say is that US indicies are skewed to very large tech that have been thriving on the AI boom and I suspect that gives a false picture. Ie many stocks in US are already priced for recession, it’s just that the index isn’t showing it. So as we hit peak rates those stocks should also move off the bottom irrespective of recession, which seems to be happening.
In the UK I think liquidity has been the killer and this has been much more pronounced than previous downturns or recessions. LSE volumes have more than halved! That coupled with redemptions causing the drip drip effect has sat UK equities on the floor.
What I think is happening is that the market is now starting to price in both peak interest rates but also lower volatility in interest rates. So people are beginning to pick up long term bargains and because of the liquidity effect this is causing a more pronounced move.
The market seems to think this time is different and there will be no recession.
What am I missing as its keeping me from deploying cash at this point?
History doesnt always repeat. In some respects the present high inflation seems a bit of a con. I know its real and is playing havoc with some stuff - but it all seems to be a particularly random chain of events that have lead to high inflation now . I thought this blip would subsided super fast and come back down before interest rate rises would cause havoc. That certainly aint happened "here" for one reason or another but if we look at the US - the trend there seems to clearly be back towards low inflation - presuming we do the same ( stupidity of our government being main obstacle - its clear to me that high interest rates at present are more likely to fuel inflation than tame it!) - i can see stuff getting back to normal rfef inflation within 12 months and no reason for inteerts rates not to follow suit.
IMHO whether we technically have a recession or not isnt so important as long as any decline is not severe and long lasting. I think what happened through brexit and covid does kinda prove the economy can quickly bounce back.
What is without doubt completely different from prior recessions is teh complete lack of unemployment - to me i see real recessions directly resulting in peeps not being able to get a job and keep a roof over there head. I see a complete lack of any signs that theer wont be enough jobs to go around - so i dont predict a severe long lasting recession of teh type we used to have. What people love to do in this county is bi tch about everything when most peeps dont have it too bad. Even a couple earning the minimum wage working 40 hours per week each should be pulling in £700 per week cash in their poicket with no benefits. There isa decent incentive too for peps to get out there and better themselves - i think its kinda healthy at present that peeps if they are not getting fully rewarded can do something else and hopefullyn get their worth.
to me the main danger here is that high interest rates last - cause havoc with homeowners and the jobs dry up. Hopefully if rates start dropping within 6 months then the worst of that damage can be avoided - good news just in time for an election (albeit too late for the hopeless powers that be now)
Thanks for the post Topvest. A good dose of common sense here to keep everyone's feet on the ground. I guess given the performance of the AIM over the last two years people believe it can't get much worse. I only really remember well the GFC when it seemed the whole system of capitalization would crumble. Who knows if it will become the same in another year? Perhaps we could be looking at 400 again for the AIM but hopefully not.
Its very complicated.
FWIW
Interest rates last September 1.75%, FTSE 7,300
Interest rates this September 5.25%, FTSE 7,700
Looks like the market is due a fall.
FTSE 100 is all commodity and international revenues. Interest rates in UK almost no bearing on FTSE100
Look at FTSE 250 and small cap charts - looks rather different
I note from Bloomberg today that Bank of America estimate that UK equity inflows topped $260m for last week the most in a year….almost all of it going into FTSe250.
That rather backs up the thesis around inflows chasing longer term bargains in an illiquid environment.
US interest rates from 1962 - 1980
S&P during same period
Rates peaked 1980. S&P started a huge secular bull market to present day, 2 serious bear markets 2000 and 2008. I think we're still in secular bull, wouldnt call what happened in 2022 in the US a proper bear market, was just a very large pullback to the trend after unprecedented free money was thrown like confetti during covid.
2022 pullback to the long term 50 month trend trend line. Im bullish as long as this holds, but open to the idea that if rapid rate rises break something next year or Taiwan is invaded by China then with the amount of debt around the globe a 2008 style crash could potentially happen. Right now everything looks fine.
Bonds might be a better trade than stocks for the next 12 months if interest rates do start to come down, I'm musing that with short dated corperate bonds you might be able to make 8-10% over twelve months if rates come down slightly and the yield stays around 6/7%.
Anyone any thoughts ?
Only that I have been thinking something similar
No idea on bonds Phoenix, but thank you for the tv recommendation last week. Very good.
There's a lot of crazily overvalued stuff in the USA too. That market is one fumes while the UK one is in tatters. What will happen if the USA markets come again under pressure?
Your first sentence does not need the word “too”
?
Not a small cap but widely followed Games Workshop (LON:GAW) just knocked it out of the park yet again. This business truly is the gift that just keeps giving. I'm scratching my head as to how they just relentlessly keep on growing in the face of so much negative macro news.
"Trading for the three months to 27 August 2023 was ahead of the Board's expectations for the quarter with core revenue of c.£121 million (2022/23: £106 million) and licensing revenue of c.£6 million (2022/23: £3 million). Profit before tax is estimated at c.£57 million (2022/23: £39 million)."
"This has been driven by healthy growth across all channels." (my bold). Remarkable!
I'm a long term holder but gutted that I top sliced in August at the heady highs of £114 per share. I'm expecting the price reaction to exceed that number now.
Yes. An amazing company. I am also a long term holder. Hopefully there will be some update on the proposed Amazon tie-up soon, which should bring it to an even wider audience.
Happy holder for the dividend but the growth is beyond expectations and very welcome!
As well as Amazon, there was an announcement via YouTube of a link up with Weta Workshop, the NZ studio for a new range of larger models, sounds interesting in terms of developing opportunities to expand the product range, even if not deemed RNS worthy.
I also have held since 2016 and top sliced a few times. This was indeed welcome news today as the last year has by their standards been poor, most of my profit was gained in the years before, but it does look on the rise again now
Seems like a quiet day. I’ll risk going off topic.
Does anyone hold or have thoughts on Eenergy (LON:EAAS)
Thanks for all the Nuclear feedback yesterday... most helpful.
Any thoughts out there as to why HSS Hire (LON:HSS) are going south bound at an alarming rate on no RNS news, no director sells and no major movement in large holders ??????
Peeps concerned about the upcoming recession no doubt
Not a holder but I imagine the share price here reflects on how the housebuilders and material suppliers are performing. they all appear to have had a slow down due to the macro
I've had a quick look at HSS Hire (LON:HSS) for you. Graham looked at it on 2 March this year, at 12.2p, concluding AMBER, saying it could be good value. 2022 results look quite good, also helped by a tax credit giving EPS a boost. There was an in line with exps update on 21 June 2023.
I have always previously flagged HSS as having dangerously high debt. However, the last balance sheet shows a much better position, with debt looking OK, not excessive any more. It seems to have refinanced in 2022, as the share count more than tripled.
The shares have been in a relentless downtrend since a big spike in early 2021.
As others have said, maybe the market is worried about a recession, and that possibly triggering HSS to get into trouble over its debt? Or it might just be fund managers selling to fund redemptions, a big problem at the moment with small caps.
I'll keep an eye on it, and prioritise reporting on the next trading update.
Regards, Paul.
hi Paul
Is Argentex (LON:AGFX) on your backlog list?
Shares fell over 10% on Wednesday when H1 results were in line but some softness in H2 to date the main cause of negative market reaction.
Results were disappointing in comparision to Equals (LON:EQLS) who announced results the previous day and reported on by Graham..
Would welcome an update please.
regards
Snazzy
Hi Mike
You need to understand who their main clients are for HSS Hire (LON:HSS) .
Obviously there is the likes of you and me doing a larger DIY job and wanting something that is not worth buying, smaller percentage of the business and just a tick over activity.
Smaller builders, either bringing in equipment for a specific job or something they own has broken, or they need two of something they have one of type stuff.
Then the main income from Medium-Larger builders, basically as a plant supply, so cheaper to hire than to hold on books get what you need, know it works and is serviced and certificated, delivered to site and taken away when you want it to be.
They key one is the medium to larger builders, so people are anticipating what is the housing market doing which is appears to be slowing down given and what is the main construction market doing...
I don't invest in my own industry but my thoughts are people are looking at the leverage, what is the overall utilization levels, what have they dropped to, what might they drop to and what does that do to the profit, basically reverse operational gearing coming into effect. You still own everything, you are still depreciating it, paying loans on it, but it is all sat in a yard gathering dust whilst going rusty...
Good luck
Tommy