Small Cap Value Report (Fri 16 August) - RGD, EQLS, CNS, QRT

Good morning folks,
The market has crawled higher this morning, giving frazzled investors a little bit of relief after a tricky week.
There is supposed to be a Weekend Effect, with stocks doing worse on Monday compared to Friday. Is it really true? I have no idea! As discussed in yesterday's report, investors are jittery at the moment, so perhaps we can have another big sell-off on Monday.
There are updates today from:
- Real Good Food (LON:RGD)
- Equals (LON:EQLS)
- Corero Network Security (LON:CNS)
- Quarto Inc (LON:QRT)
I'm likely to run out of content after discussing these shares. So if any of you are still here this afternoon, you can read my review of Once Upon a Time in Hollywood.
Real Good Food (LON:RGD)
- Share price: 6.5p (-10%)
- No. of shares: 100 million
- Market cap: £6.5 million
Real Good Food plc, (AIM: RGD) the diversified food business, today announces its final results for the year ended 31 March 2019.
This company has been causing headaches for investors for quite a while.
The long-term performance helps to tell the story:
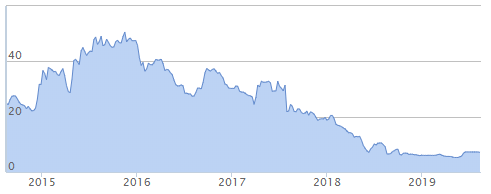
Background
In May, it was fined and censured by the London Stock Exchange for "multiple and serious breaches of the AIM rules and a pattern of unacceptable conduct by the Board". The disciplinary notice can be downloadedhere (PDF file).
The Directors responsible for those breaches are gone, and we have a new Board.
It has completed four disposals, leaving it with two core divisions. So hopefully a much simpler story from now on:
- Cake Decoration (comprising Renshaw and Rainbow Dust)
- Ingredients (Brighter Foods)
Results
Today's results pertain to FY March 2019 - doesn't it seem quite late to publish them?
- Revenue at the continuing businesses falls by 3.4%
- Huge goodwill impairment (£18.7 million)
- The two divisions are said to be profitable, before impairment
Good improvement in Adjusted EBITDA is reported, but I doubt that this is a relevant metric for investor since depreciation will be a real and significant cost at the underlying businesses.
Indeed, the adjusted EBITDA comes out at £1.9 million for the year, but the depreciation charge is nearly £1.6 million. So you if include depreciation in the result, you are left with something only a few hundred thousand pounds over breakeven.
And that's before including huge financial charges. There is an acknowledgement in today's statement that "the Group's level of debt outstanding remains higher than a business such as Real Good Food should have, given its business model".
Net debt was £35.7 million, dwarfing even the adjusted EBITDA figure.
Outlook
Trading is "in line with our modest expectations for the year". The company is focused on reducing debt, which sounds appropriate.
My view
As a general rule, food manufacturing businesses don't interest me too much.
And this company's potted history and above all its high debt load are enough to turn me off this stock completely.
StockRanks correctly identify it as a Value Trap. It's very cheap against net assets, and the company points this out in its commentary today.
Let's consider this in more detail. The company says:
the Group's balance sheet retains a significant tangible asset base, goodwill that has been written down to realistic levels, and has net assets significantly in excess of the Group's current stock market capitalisation. This is an important measure in establishing the Group's financial worth in the future.
Unfortunately, I can't accept this statement at face value. Net assets are £26.6 million, yes, but that includes £52 million of intangible assets. There is still a huge amount of goodwill on the balance sheet, even after the writedowns which have already taken place.
In other words, if you strip out the intangibles, the company has significant negative net tangible assets.
The company also looks cheap against sales, but it's not a very high-margin business and so it probably should be cheap against sales.
Overall, I see this share as one to strongly avoid. I could be wrong, but I just think that equity value looks very slim when you take the debt load into account.
Equals (LON:EQLS)
- Share price: 108.5p (-1.4%)
- No. of shares: 165 million
- Market cap: £179 million
Placing and Open Offer to raise up to £16 million
This was flagged on Wednesday.
Equals confirms a £14 million placing and £2 million open offer.
The purpose: "accelerate corporate offering, facilitate market consolidation through bolt-on acquisitions and provide growth working capital."
The reference to "growth working capital" implies that the company hasn't used up all of its reserves, but that it merely has no more cash with which to carry on any more growth of the business. That might well be true, but as I discussed on Wednesday, it did look as if cash at this company has been heading for zero.
In this regard, the company says:
Equals would benefit from more collateral to fund both the expansion of its corporate international payments business and also its card-based businesses.
If you're happy with its product development and growth opportunities, the cash burn won't be a concern. On the positive side:
In FY 2018 the Company doubled its year-on-year transaction volume to £2.4 billion, and reported a seven-fold increase in adjusted EBITDA to £7.5 million. The Group now serves more than 1 million customers with over 30,000 business customers, including Netflix and KFC.
Trading update - trading has remained strong and in line with expectations.
My view - there is a lot happening at this company and the decision to raise funds with modest dilution to shareholders appears to make a lot of sense. I still think that this one is worthy of more detailed research.
Corero Network Security (LON:CNS)
- Share price: 3.55p (-44%)
- No. of shares: 402 million
- Market cap: £14 million
Commiserations to anyone who held this one last night.
This company's H1 EBITDA loss is set to increase to $2 million (from $1.4 million) as sales in the pipeline failed to materialise as expected.
The pipeline is said to have grown strongly, with high hopes for H2, but it's reasonable for investors to feel jaded when they read commentary like this.
Outlook
Things get worse in the outlook statement.
Management expect revenue for the full year ending 31 December 2019 to be approximately 20% higher than revenue for the prior year (2018: $10.0 million) and anticipate an increased EBITDA loss for the full year (2018: EBITDA* loss $2.1 million), as a result of the additional Corero direct sales investment in the second half of 2019 of approximately $1.0 million.
There could be "a requirement for additional working capital prior to being cash generative". The Chairman has indicated that he would support this.
My view
It seems unwise to get involved in a company which could run out of cash and need an injection of funds from the Chairman, at a price that can't be predicted. I can only agree with Stocko that this has the hallmarks of a Sucker Stock - a stock that is statistically unlikely to generate an attractive return.
Quarto Inc (LON:QRT)
- Share price: 66.5p (-1.5%)
- No. of shares: 20 million
- Market cap: £14 million
This is another debt-laden micro-cap which has been in the wars.
The CEO describes these results as "encouraging" and they are in line with expectations, but the company really needs a good H2, which is the seasonally stronger half.
The main bright point today is that net debt has been reduced by $8 million, compared to a year ago. It is now $65 million (£53 million, nearly four times the company's market cap).
Selling books is currently difficult, and likely to remain so:
The book trade market remains soft, while in the co-edition market, further consolidation is impacting both English and foreign language sales, especially on the Adult segment. As a result, the Group expects the trading environment in the second half to be more challenging than in prior years.
H2 tends to be much stronger, but this outlook statement suggests we don't have all that much to look forward to.
My view - worth keeping an eye on this one, but I suspect that the market is right to keep the market cap at low levels for as long as its debt levels are elevated and profitabilty is elusive.
Once Upon a Time in Hollywood
It's a quiet Friday, and I promised you a review, so here are my thoughts on Once Upon a Time in Hollywood. I will not include any spoilers.
Firstly, I think that Tarantino fans will not be disappointed. It has all the things we like about his work: multiple storylines, a large cast, unique camera angles, and a surprise ending.
Secondly, those who hate Tarantino's work will also not be disappointed. They will have to deal with a narrative that doesn't seem to go anywhere for periods of time, dialogue that exists purely for its own sake, excessive bloody violence, and a few main characters who fulfil stereotypes rather than giving us the chance to witness something more real.
The keys to enjoying this film are:
- Relax, it's a comedy (sort of). The same could be said about Pulp Fiction and Jackie Brown. Tarantino isn't trying to tell us something important about the world or about ethics. He is offering us a few hours of entertainment and escapism, that's it.
- Don't expect it all to make sense on the first viewing. As is sometimes the case with Tarantino movies, there are too many details to take them all in, the first time you see it. If you don't understand something, you can always watch it again. Just enjoy the things that you do understand.
- Go with the flow. There are elements of truth and fiction, and you might not always know which is which. It's just an attempt to tell a story in an interesting way, nothing more. Treat it like you would treat a friend who is telling you an amusing anecdote.
Is it a good film? Well, I enjoyed it very much and I would watch it again. So for me at least, it achieved its aims. Some great actors, great acting and a great director. Hard to go wrong!
Well that was a fun way to round out an exciting and eventful week.
Have a good weekend! Paul is back on Monday.
Best wishes
Graham
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

21 comments
The scene at the end had us holding our hands over our eyes. He doesn't hold back. But lots of gentle moments in between. I saw it at a Cineworld (I am a so far disappointed shareholder). Price of a small popcorn and a bag of wine gums? £7.46. Price of a ticket for an old man? About the same.
I see the FT film critic gave Once Upon a Time in Hollywood five stars while two comments that followed rubbished it. Perhaps they took it too seriously - contra Graham's advice.
I see FT Alphaville have referenced your analysis of Burford Capital (LON:BUR)
A nice hat tip
Real Good Food (LON:RGD) When an AIM company is censured, you know it must be bad.
Mark; how true!
Real Good Food (LON:RGD)
The previous directors are all gone (I think) so at least it has that in its favour. Still looks like a bargepole job on the basis of the debt, sadly.
Hi Graham, like you, Real Good Food is not the sort of company I would normally invest in. However, I took a punt on the Downing Strategic Micro-cap IT which is heavily committed to Real Good Food - think I might be leaving this one to my grand-children!
Thanks for your good work.
Phil
Phil,
Real Good Food (LON:RGD) is Downing Strategic Micro-Cap Investment Trust (LON:DSM) 's largest position, but almost all of it is in the form of loan notes. I'm not too keen on Real Good Food's equity either, but I think the debt looks pretty secure, especially given that it ranks ahead of the pension fund.
Incidentally, Downing Strategic's second largest holding is Volex (LON:VLX) , a company that I am very keen on at the moment, and most of their other holdings look pretty solid now that FireAngel's share price has fallen back and Redhall has gone.
I cover RGD, VLX and FA. on my blog.
Out of left field, but a question for those that may be kind enough to assist -
how would one go about getting exposure to inflation linked bonds, ideally globally
Many thanks and have a great weekend.
£IGIL iShares Global Inflation Linked Govt Bond UCITS ETF
Hi
I think you have to first ask what volume/value am I looking to invest, then look at the broker to see if you can deal online, and at what prices and volumes, although most brokers will tell you its better to deal over the phone when spreads are high. Good place to start might be
http://www.fixedincomeinvestor.co.uk/x/default.html
Which has a lot of good info and I used this to educate myself when investing in corporate bonds via LSE order book for retail bonds (ORB). I used iDealing
Good luck
Sharmvr
I use £INXG
FREng
Graham.
Not related to today but have you any thoughts on Rock Rose Energy as I see the share price has come back somewhat from the highs post the return from suspension. Not sure how much there’s is in the balance sheet for de commissioning costs from some of the fields bought with the Marathon purchase and do you see this as adequate?
Thanks
martin
RockRose Energy (LON:RRE)
Martin - I'm afraid I've stuck to my rule and stayed away from that, as it's beyond my sector coverage. Well done to those who've profited from it.
Hi Graham,
Looking forward to your review of Once Upon a Time in Hollywood. Hopefully it may work some magic on the Cineworld (LON:CINE) share price.
Best wishes,
Imran.
Dear ELI5,
Everything is normal from 9.40.
Any limit or good-'til-cancelled orders have vanished on FTSE 350 stocks. Your broker may be re-instating them now, but it might be a good idea to check.
There is no what-went-wrong explanation.
This is educated guesswork. I won't be offended if people wish to correct the above.
On Reddit, when people have no clue what something means, they use the abbreviation ELI5, which is short for 'explain it like I'm five'. If possible can someone ELI5 this, please?
I've been able to work out that something is up with FTSE100 & 250 ( partitions 1&2). Everything else is normal?
Edit: To be fair 'trading issue' is pretty vague as an explanation so probably no one outside the LSE knows!
LSE technical updates: https://liveservice.lseg.com/node/143
From Exchange:
All GTD orders on partition 1 and 2 have been expired.
Instruments on partition 1 and 2 (FTSE 350) will resume in an opening auction call at 09:20 and will uncross at 09:40. EDSP auction for FTSE100 securities will commence as per today’s standard schedule at 10:10. Users that receive rejection messages, are advised to log out their trading sessions and log back on to the relevant gateways again.
If you're trying to get your young relatives into investing, perhaps they'll be inspired by Ryan? He started investing at 11 yrs, with £1,000 capital generated from car boot sales. Six years later he's generated an average return of 100% pa. Currently studying for 'A' Levels, he will have less time for trading, instead will keep his interest, with his recently launched investing research website, and a daily podcast covering latest company announcements.
Weekend watching: piworld interview: The Perspective of a teenage investor
Just 30 minutes, but well worth a watch.
In the same theme, next week we'll have interview with Lord Lee, who has just published his second investing book, a primer for newbie investors, primarily aimed at teenagers: Yummi Yoghurt: A first taste of stock market investment. In the interview, we discuss the book, and his investing caveats, which led him to becoming the first ISA millionaire in 2003. Today, he earns an annual dividend income from his ISA, which is equal to the total invested capital.
FTSE 100/250 opening delayed. Some technical glitch.
My morning smallcap tweet:
Corero Network Security (LON:CNS), Real Good Food (LON:RGD), Equals (LON:EQLS)
Corero Network Security (CNS) H1 trading: rev only $4.2m, down 16%, due to weak Juniper sales. Guides FY rev up 20% but increased EBITDA loss due to additional Corero direct sales investment of $1m. May need modest fund raise.
Real Good Food (RGD) FY rev down 3%, loss £32m (£27.5m) due to more write downs. "Current trading is in line with the Board's modest expectations." They've a lot to be modest about.
Equals Group (EQLS) £14m placing and £2m OO at 110p, a nil discount. Funds to accelerate corporate offering, facilitate market consolidation through bolt-on acquisitions and provide growth working capital. Trading is in line.