Small Cap Value Report (Fri 16 July 2021) - RNO, EVE, LUCE, RBGP

Good morning, it's Paul & Jack here with the SCVR for Friday. Welcome back Jack!
Timing - today's report is now finished. Time to enjoy some sunshine!
Disclaimer -
A quick reminder that we don’t recommend any stocks. We aim to cover trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research) - don't blame us if you buy something that doesn't work out. Reader comments are welcomed - please be civil, rational, and include the company name/ticker.
.
Agenda -
Paul's Section:
Renold (LON:RNO) (I hold) - delayed results are in line with expectations. Strong closing order book, and positive trends throughout the year, markets recovering well. Management seem upbeat on analyst call, and now looking at acquisitions. Dramatic drop in net debt, due to very strong cashflow. This could be quite good long term, maybe priced about right for now, taking into account the big pension deficit?
Eve Sleep (LON:EVE) (I hold) - in line with expectations update is not enough to please the market. Super-low market cap, and cash pile, are the main interesting aspects of this company. I'm not convinced this will turn out well, and am not inspired by management/strategy either.
Jack's Section:
Luceco (LON:LUCE) - excellent results and an upgrade in FY guidance from a stock that has performed strongly over the past year. In truth, it has been growing well for a while now and this could be a well managed company with a bright future. The valuation is becoming a little rich, but some companies deserve their premium. Luceco might be one of them.
Rbg Holdings (LON:RBGP) - growing, acquisitive professional services group comes out with an in line statement. Perhaps the market is unimpressed with a setback in a large litigation financing case, but the valuation looks undemanding once Memery is fully integrated, and the longer term growth opportunity remains intact in my view
Paul’s Section
Renold (LON:RNO)
(I hold)
22.7p (down c.1% at 10:01) - mkt cap £52m
Apologies for this section taking a while to gestate. I’ve had one of those mornings when it’s been really busy, but so far my productive output has been nil!
Holding this share has been a bit stressful this year, because it twice delayed publication of results for FY 03/2021. As it turns out, the reason given (auditors slow) does appear to have been genuine, although I fully understand why people (including myself) got anxious that there might have been some unfolding horror show imminent.
In overview, the figures are in line with guidance previously provided, few key numbers -
Revenue £165.3m, down 12% on prior year, due to pandemic impact - the signs are that this shortfall could be recovered in future years, so I think there’s upside looking very likely from these new, soft comparatives.
Adjusted operating profit is highlighted, at £11.2m, down 16% on prior year (I’m using the actual exchange rate table, not the constant exchange rate table). This is a decent outcome actually, because a 12% revenue drop would normally be amplified considerably at the profit level, due to oeprational gearing (i.e. falling gross profit meets fixed overheads). However in this case, there’s been the benefit of last year’s cost-cutting through restructuring (now complete). Hence a resilient performance, and in line with expectations (previous guidance).
I’m not keen on operating profit these days, because IFRS 16 has shifted some rental costs into finance charges. Note 3 shows the breakdown of heavy financing costs of £4.6m, which includes £2.2m relating to the pension schemes, an ongoing cost, so I wouldn’t want to strip that out. Profit before tax of £5.9m is the more meaningful profit measure in my view, which is actually up 20% on LY, due to last year’s £2.4m restructuring costs (nil this year).
Adjusted EPS is 2.0p, in line with broker consensus. That’s down 31% on LY. I think it’s realistic to assume that, on the new lower cost base, future trading should recover to 3.0p per share, so I’m happy to value the business on say 10 times that, so 30p per share - decent enough upside on the current price, in due course.
Balance sheet - the stand-out issue, which we’ve discussed here before, is the large pension deficit. This is on the balance sheet at £102.4m. The best way to view this, is a long-term liability, that has a long-term funding plan in place, costing about £5.5m p.a. in cash contributions. That’s a lot, but Renold has successfully shouldered this burden, without needing to raise fresh equity. But it does explain why there aren’t any dividends for now.
Other than that, the rest of the balance sheet looks fine to me, and this year has seen a dramatic reduction in net bank debt, down by about half to only £18.4m - so the company should not be seen as financially distressed any more, it’s pretty solid now.
Cashflow statement - is very impressive. Tighter management of working capital (e.g. reduced inventories), combined with reducing capex to maintenance level only, has resulted in a whacking great cash inflow, allowing it to reduce bank borrowings by £17.1m.
Analyst briefing
We’ll be here all day if I keep going through the RNS, so instead I’ll share my notes from this morning’s analyst call. As usual these notes don’t cover everything, I tend to just jot down the most important points.
Excellent cash generation - big reduction in net debt
Gradual improvement as the year progressed, eg. Q4 revenues down 5.4%
Increasingly flexible cost base
Chinese factory doing well & scope to expand & increase profitability
Major restructuring complete - lower cost base
Net debt down from £36.6m to £18.4m in the year
Head office costs absorbed £1.0m cost of environmental provision in France (old Calais site)
Capex reduced to just £2.9m (maintenance level) - major capex now done over last 9 years factories have been modernised
Pension cash outflow has averaged £5.5m over long term, expect it to remain at that level, stable, for 17 more years
Bank covenants were amended, but complied with original covenants anyway
Order intake signficantly increasing
Customer & sector diversity protects Renold from sector-specific problems
Supply chain - still a problem, but varies, daily problems to be navigated. Containers very expensive, and don’t see this resolving itself any time soon - important point, as numerous companies are saying the same thing at the moment. Does it matter long-term though, I’d say not, as this is clearly a fixable issue.
Markets now extremely buoyant - we could be selling more if we didn’t have supply constraints & delays
Cost increases - are being passed on to customers quickly
Torque transmission division (smaller than chains) is a later cycle recovery, but now winning some nice orders, like RNS recently said. Also long gestation, but have won order for escalators on Budapest underground system
Using Indian & Chinese factories interchangeably, to get round issues like tariffs, lockdowns, etc, becoming a more global, integrated business
Acquisitions - much more of an area of focus now that reduced debt gives scope to make £10-20m acquisition. Very fragmented market, lots of opportunities.
My opinion - this looks fine to me. Nothing unexpected, and the outlook is clearly very much better than at the interim stage. I think the share is probably priced about right for now, but I see good upside to 30p+ with a bit of patience, due to the stronger order book, and ability to pass on cost increases to customers.
I like the focus on acquisitions, as that should dilute the pension deficit over time - i.e. if the size of the group were to say double over time, then £5m p.a. going out for the pension scheme wouldn’t really matter that much. Management seem very grounded, and they know the sector inside out, so know which businesses to acquire in complementary areas, in a fragmented market with small, specialist producers of chains in particular industry niches. So a good opportunity to be a sector consolidator, if handled well.
There's also the wild card that someone else might decide to bid for Renold, that wouldn't surprise me.
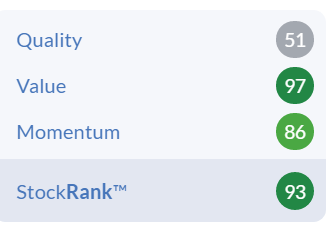
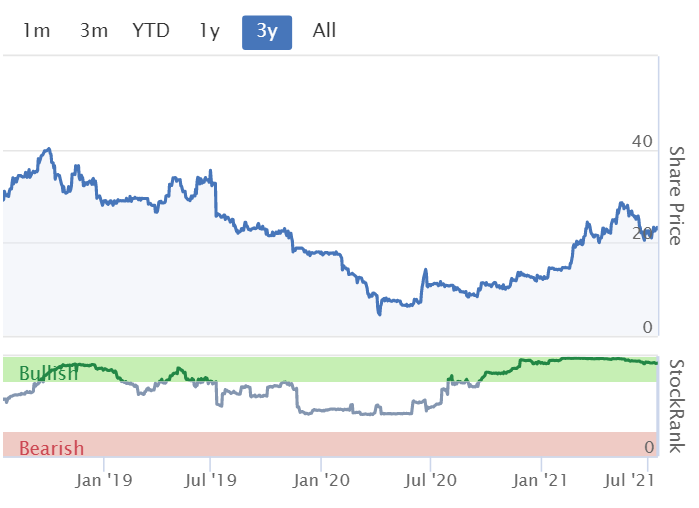
Stockopedia likes it too -
.
.
Eve Sleep (LON:EVE)
(I hold)
3.95p (down 14% at 12:28) - mkt cap £11m
eve Sleep ("eve", the "Company), the direct to consumer sleep wellness brand operating in the UK, Ireland (together "UK&I") and France announces a trading update for the six months ended 30 June 2021.
It’s an in line with expectations update today, but clearly traders were hoping for better. I say traders because you can see from bulletin boards that this share has attracted speculative money, hoping for another spike up in share price.
I picked up some at 4.8p, attracted by the big cash pile relative to the market cap, and that it is actually generating reasonable, and modestly growing revenues.
The thing that put me off, on a recent company webinar, was that the CEO commented: we’re up against several very well-funded competitors. E.g. possibly Emma, Simba, I’ve seen TV ads from them on quite a lot. Eve went down the high cash burn, heavy advertising route a while ago, and failed to reach critical mass. That said, TV ads are often remembered by people for many years, so I think there could be brand value in Eve above the current market cap.
I wasn’t convinced by the strategy to broaden the product range into sleep wellness either. Although it does say in today’s update that some new products are selling well.
Management didn’t really fit my personal preference for dynamic founder/entrepreneurs, and I have no real conviction that their strategy is likely to work. Let's hope they can [pull something out of the hat.
H1 sales rose 13% to £13.9m, so that’s maybe £30m annual run rate, not too shabby for a £11m market cap company, and memory foam mattresses are high gross margin products, with Eve selling a lot online. Marketing is a big chunk of overheads, so completely variable, giving flexibility.
Net cash is down, to £5.2m, but that's almost half the market cap, and cash burn is much lower than in previous years.
Supply chain problems - interestingly Eve says these are abating somewhat, and it has increased stock levels to cope. That got me thinking, how much of the current international supply problems are being caused by companies increasing stock levels? That’s the natural response to any supply problems - hoard supplies. But that in turn makes supply problems worse, if everyone does it!
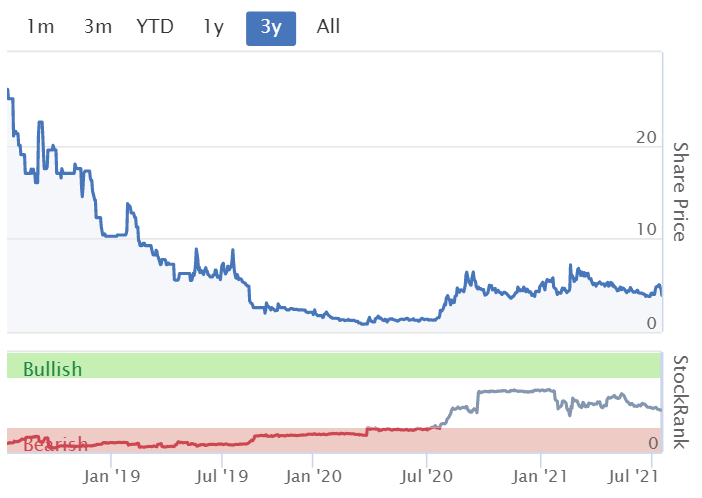
My opinion - there are signs of life here. It’s not a good business, but at £11m market cap, with plenty of cash remaining, and meaningful revenues, I wonder if someone might bid for it?
My feeling is that Eve is in an impossible middle ground - too small to be able to grow aggressively without a lot more funding, but costs that are too high to operate profitably on a shoestring as a small market participant.
This share is a bit of a special situation. Am wishing I hadn’t bought them now actually, but never mind. It’s too cheap to sell at 4p.
.
.
Jack’s section
Luceco (LON:LUCE)
Share price: 396.78p (+4.14%)
Shares in issue: 160,800,000
Market cap: £638m
Luceco is a manufacturer and distributor of high quality and innovative wiring accessories, LED lighting and portable power products for a global customer base. It’s been on a storming run for quite some time now, with a one-year relative strength reading of +163%.
The initial Covid slide already looks like a small bump in the rear view mirror.

The group supplies trade distributors, retailers, wholesalers and project developers with a wide range of products which broadly fall into the following brands:
- British General ("BG"): wiring accessories including switches and sockets, circuit protection, and cable management products;
- Luceco and Kingfisher Lighting: energy efficient LED lighting products and associated accessories; and
- Masterplug: cable reels, extension leads, EV chargers, surge protection, timers and adaptor products.
Full year guidance that is ahead of current market expectations… We now expect to report H1 2021 revenue of £108m and Adjusted Operating Profit of £19m, versus previous guidance of £105m and £18m respectively.
Highlights:
- Revenue of £108m is +51% on H1 2020 and +31% on H1 2019, with ongoing market share gains ‘particularly during Covid’,
- Retail revenue +27% on H1 2019; Hybrid +70%; Professional Wholesale +34%; Professional Projects -8%,
- Residential demand continues to be strong with continuing high levels of home improvement activity,
- Commercial and institutional demand is improving,
- Gross margin up by 10bps to 38.5%, ‘protected from significant industry-wide cost inflation to date’,
- Adjusted Operating Profit more than doubles year-on-year to £19m, with Adjusted Operating Margin of 17.6%.
The strong performance comes from a mix of high sales growth, protected gross margin, and controlled overheads. Conditions have improved throughout the second quarter and ‘demand has been stronger and broader than expected’.
Luceco has a strong order book and H2 revenue is generally higher than H1, so there’s every chance of sustained good news.
Inflationary pressures are increasing, however. Luceco estimates the annualised cost impact has increased from £15m to £20m and these headwinds will increase in the second half. The group has so far protected its margins against inflation on raw material and freight prices - an encouraging sign that suggests a degree of pricing power - and it expects to be able to continue to do so.
Full year 2021 outlook:
- Revenue of at least £220m, 25% higher than 2020 and 28% higher than 2019,
- Adjusted Operating Profit of at least £39m, 30% higher than 2020 and more than double 2019,
- Adjusted Operating Margin of 18%, 1 percentage point higher than 2020 despite inflationary pressures,
- Net debt is expected to be approximately 0.25x LTM Adjusted EBITDA at year-end (before any M&A activity),
- Cash conversion is expected to improve in H2, as extra inventory held in H1 to compensate for supply chain disruption is progressively released.
Conclusion
When times get tough, that’s when quality operators can really shine and take market share. This looks to have been the case at Luceco:
Superior and improving product availability in a tight market, as a result of our vertically integrated manufacturing model, has accelerated our market share gains toward the end of the half
Clearly, here’s a company with the wind in its sails. It’s growing strongly.

How sustainable are these growth rates? Luceco appears to have wobbled in 2018, but apart from that it has actually strung together a consistent record of net income growth.

Shares in issue have held steady over that time at around 161m, so a good amount of this progression is flowing through to shareholders.
If I assume another £3m of costs comes off after the forecast adjusted operating profit of £39m (as has roughly been the case in previous years) and apply a 20% tax rate, that would give a net income estimate of £28.8m or 17.9p of earnings per share. That’s pretty much right in line with the Stocko forecast of 18p and gives a forecast 2021 PE ratio of just around 22x.
The financial data and management commentary here suggest a stock worth investigating but with a market cap of more than £600m on forecast 2021 revenue of £208m and at the current valuation, is there limited scope for a further rerating or can Luceco continue to outperform? It’s probably a fair price given the track record and trading prospects, with upside potential should the company continue to impress organically or identify a promising acquisition.
That’s what I would want to look at: Can it become a materially larger company via organic and acquisitive growth? And does it have a clear runway for that growth?
It looks like a fine company in a sweet spot that is taking market share. The confidence in being able to protect against further inflation is reassuring.
Rbg Holdings (LON:RBGP)
Share price: 131.49p (-11.16%)
Shares in issue: 95,331,236
Market cap: £125.4m
RBG Holdings is a professional services group. Recently more of these companies have come to the fore on the back of changing regulations paving the way for easier acquisitions in this space. It looks to have triggered a wave of consolidation and ‘roll-up’ strategies.
RBG has the following divisions:
Rosenblatt - a pioneering UK law firm leading in dispute resolution, with a growing international footprint advising on complex cross-jurisdictional disputes.
Memery Crystal - specialist international law firm offering legal services across corporate, real estate, commercial, IP & technology (CIPT), banking & finance, tax & wealth structuring, employment, and dispute resolution. ‘One of the leading firms in the UK to advise the emerging cannabis sector on a wide range of business issues’.
Together, these two form RBG’s Legal Services Division (RBGLS).
LionFish Litigation Finance - finances litigation matters being run by other solicitors in return for a significant return on the outcome of those cases. RBG has two types of litigation assets - Rosenblatt's own client matters, and litigation matters run by third-party solicitors.
Convex Capital - specialist sell-side corporate finance boutique based in Manchester focussed on helping smaller owner-managed companies realise sales to large corporates.
The stock’s done very well since January but the shares have been marked down somewhat this morning.

It’s an in line statement today for the six months ending 30 June 2021. More details will be released in the interims on the 15th September 2021.
RBGLS - Rosenblatt and Memery Crystal have performed well. Memery was acquired on the 28th May of this year and integration is ongoing. RBG says the two brands are highly complementary and will be combined into one legal services business.
Opportunities should arise for the two firms from the combined client base, and RBG also aims to realise synergies by combining support functions and technology platforms. Further details on the integration plans will be provided with the Group's interim results in September.
Litigation finance - The current litigation assets include three large cases project named Neptune, Shango, and Mercury. In the case of Project Neptune, the Court of Appeal recently found that because there was a 19-month delay in the judge providing a judgment, this judgment is not safe. Therefore, a full re-trial has been ordered with the date not yet set.
That’s a long time! I’m curious to know why there was a nineteen month delay. Perhaps this is in part down to Covid, or perhaps not - either way it sounds like a bit of a set back.
LionFish is actively invested in 10 cases in total however, with a total cash investment of £3.2m across and a total capital commitment of £8m if all cases go to trial.
Convex Capital - ‘After a challenging 2020, where deals were postponed or delayed due to Covid, the Convex Capital team worked to pivot its sector focus to rebuild its transaction pipeline.’
That suggests an interesting contrast between the public and private markets over Covid. We’ve just covered Numis (here), which is reporting bumper conditions amid equity placings and stock market IPOs. FinnCap too. And yet here we have Convex Capital further down the size chain reporting disruption. The group talks about ‘pivoting its sector focus’, so perhaps this is an issue more specific to Convex and its positioning, rather than the private market as a whole.
Following the change in direction, Convex Capital has completed eight deals generating revenue of £5.0m since the 1st of January this year and has a strong pipeline of 25 deals with several currently at various stages of completion.
Conclusion
Full year expectations are for FY21E (from Singer at least) are £45.5m of revenue, and adjusted EBITDA of £12.6m. Forecast EPS is expected to be down on 2020 and more or less back to 2019 levels at 7.92p per share, for a forecast PE ratio of 16.6x falling to 13.9x in FY22.
That’s quite modest if you expect RBG to continue growing at its historic double digit compound annual rates. Truthfully I’m not sure why the shares are down so much - probably a combination of profit-taking and the delays to the Neptune case.
Litigation financing is a tricky business to anticipate. There could be big wins here down the line but it’s hard to say when they might materialise. The Neptune delay is a case in point.
One thing to look for in these fast-moving acquisitive companies is just how adjusted ‘adjusted EBITDA’ is. In the past, cash flows per share have not tracked earnings per share all that well, so the extra detail provided in the upcoming interims will be enlightening.
With such an asset light people business, the balance sheet is also quite small so debt levels must be managed carefully. Interest cover is well in hand so this is not an issue for now but could change quickly depending on the nature of future acquisitions.
Apart from that, the growth strategy appears to be intact so I’d say this latest share price fall is an opportunity to dust off some notes and reassess the potential here.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

65 comments
Just to mention that RBGP will be discussed in the MelloBASH (Buy, avoid, sell or hold) session on the Mello Monday show tomorrow evening
https://www.stockopedia.com/content/mello-monday-and-a-halfway-review-of-the-2021-stockopedia-stockpicker-competition-838384/
A small update from UK_Investor_8888
I received my new house at the end of June. Unfortunately, its been nothing but problems with over 50 snags and appalling delivery.
I've completely taken my eye off investing in the past 2 months doing nothing but with 4 Dividends rolling in.
The portfolio is at -10% of peak value with just two problems or holdings at less than +40%.
Tharisa (LON:THS) -10% and Sylvania Platinum (LON:SLP) -15%.
I am not really sure what's going on there, but suspect its just summer seasonal weakness and don't feel any concern.
We have spare cash too, and given I've sunk half my wealth into "The White Elephant", is a pretty good problem to have.
Not in a massive hurry to make my next investment but will as soon as the paint dries... literally.
Looking forward to when I have the time to just read Stocko, economics and financial articles instead of trivial domestic nonsense.
I notice Smiths News (LON:SNWS) have II upping their holdings.....Aberforth Partners LLP by 1% to 14%......
I received an email this morning about a new FT/IC award -
"Investors' Chronicle and the Financial Times are pleased to introduce the Celebration of Investment Awards.
New for 2021, these awards celebrate those organisations that have made a positive contribution to the UK investment industry over the last 12 months - whether that be strong performance, good ethical practice or excellent customer service.
And we want to hear from you. As the investors at the heart of the industry, we want to know which companies, funds, platforms, brokers, advisers and PRs have impressed you this year.
Your feedback will help us recognise the companies whose acts and attributes are making a positive impact, and will culminate in our Readers' Choice Award. So take 2-3 minutes to tell us about who has given you great service this year".
My response was:
"There has been a most welcome sea change in the last 12 months of the number of companies engaging with private investors and providing them with presentations with Q+A that previously had been limited to analysts. A number of organisations have led this including InvestorMeetCompany.com, Yellowstone Advisory, Walbrook PR and finnCap. They are all worthy of a nomination but mine goes to PIWorld for the good quality sound and video and for the equally informative interviews by host Tamzin - often of high profile fund managers such as Keith Ashworth-Lord".
You will have your own views and can make your nominations here: https://survey.ft.com/jfe/form...
This week's PIWORLD interview: John Rosier's Portfolio update. John is an ex Fund Manager, who now runs John's Investment Chronicle, a subscription site where he details trades or his views on news releases as they happen. This year, John's done very well with Sigmaroc (LON:SRC) (although we were speaking before the Nordakalk reverse takeover announcement, so no comments on this!) Looking forward, he still likes the stocks that have done well this year: K3 Capital (LON:K3C), Sdi (LON:SDI) and Sylvania Platinum (LON:SLP), and he is particularly bullish about Swedish listed Lundin Energy, Serica Energy (LON:SQZ) and Supreme (LON:SUP). Hear what he has to say about stocks and markets here: video & podcast.
Yesterday, we released the Wh Ireland (LON:WHI) full-year results overview with CEO and head of Wealth Management. They have delivered profits for the first time in five years. The turnaround plan is starting to pay off, they tell us more here: video & podcast.
Topically, for the chat today, we have rearranged the Vertu Motors (LON:VTU) webinar with Robert Forrester, CEO & Karen Anderson, CFO for Tuesday 17th August, 4.30pm. You can put your questions on their car washing policy or anything else, to them then. I hope you can join us, this has taken a lot of patience to arrange! Register here.
Other webinars that might be of interest:
Sosandar (LON:SOS) full-year results presentation: Wednesday 21st July, 11.30am Register here.
Tekmar (LON:TGP) Capital Markets Day: Thursday 22nd July, 4.30pm Register here.
Stockopedia/PIWORLD StockSlam Wednesday 8th September, 6pm Register here.
We hope you can join us for some or all of these webinars.
Any chance someone might take a look at the Sigmaroc deal? Sigmaroc (LON:SRC) I hold. This looks to be transformative if they can pull it off and the market seems to like it, with the shares up above last night's close and the placing price.
re £SRC some really odd numbers in the business being acquired, Nordkalk. Rev decline 4% in each last 2 years, whereas ebitda-as presented- growing 15% CAGR> without explanation from co these are hard to gauge. Hopefully co at some point will explain these trends.
Hi mepfish.
Re. the Sigmaroc (LON:SRC) numbers, I agree it looks a bit odd that the Nordkalk revenues are down 4% pa yet the Ebitda/Ebit are growing at something like 15% pa. Corollary of this is that Ebitda margin is up from c.17% to 24% in the same period. It states elsewhere in the release that limestone prices have been stable over the past few years which suggests that something else explains the improved margins. One possible explanation could be that given transport costs are quite a large part of the total sale price of bulk commodities the significant fall in fuel prices over the period (which have now reverted to previous levels) might be a significant factor in this margin improvement. If so, it’s likely that the current margins being achieved might come under pressure. Hopefully we’ll get guidance on this from the company in due course.
Gus.
Learning Technologies Group (LON:LTG) is probably too large for you to cover with a current market cap of £1.5bn. But yesterday's M&A announcement and small fund raising may be worth a comment. Rather like the other Andrew Brode company (LON:RWS), LTG is growing rapidly through acquisition. Take a look at 10 year charts of both LTG and RWS. Both these companies are no longer "small" now but were "small" not so long ago.
I'm looking forward to Paul's write-up of £RNO. I don't hold but have been monitoring this share since Paul flagged it.
From a quick skim so far my Qs/comments are:
I think I'd be more interested below 21p but would welcome others' views!
Hi Patrick L, I bought Renold (LON:RNO) mid-May at 26.78p, since when it's headed down. I was hoping that the share price would lift on the news that the delay in reporting was benign and the outlook seems ok, but it seems to have sunk a bit and then flat-lined today. I obviously don't share your wish that it goes below 21p but I wish you good luck if it does! I will continue to hold unless it clips my soft stop-loss of 20p. I can always go back in later.
Re: Renold (LON:RNO) I hold - Hi Indie, looks like very unfortunate timing really as the multiple accounting delays couldn't have been foreseen and have really knocked the momentum out of this stock. At a time when a lot of things are cooling from recent/all time highs its hard to see an in-line results providing much of an uplift. I've bought at 15.79p and 26.74p and my average is around 20p. Continuing to hold also as not much has changed since my original purchase but I really do like momentum.
Rbg Holdings (LON:RBGP) trading update today - in line with expectations, but having seen them present at Mello I was expecting something a bit more exciting - possibly still early days. One of their huge legal cases, which would produce major cash if it went in their favour, will have to be retried because the judge took 19 months to think about it if I read this correctly!
The Rbg Holdings (LON:RBGP) case appears to be this one. https://www.mishcon.com/news/j...
“By the time the trial is reheard, they will be giving testimony on events which occurred over 12 years ago.”
Rbg Holdings (LON:RBGP) the original judgment in the case is here https://www.bailii.org/ew/case...
The judge's last comment was "I should, in conclusion, pay tribute to the highly efficient manner in which this case was prepared and presented. In contrast, I must sincerely apologise for my subsequent delay in production of this judgment"
Further hearing re monies awarded (may shed some light on potential sums RBGP could recover from the case) https://www.bailii.org/ew/case...
And latest Court of Appeal hearing https://www.bailii.org/cgi-bin...
I'm no expert on £RBGP but it strikes me that a litigation funding operation with only 10 cases will be particularly volatile. Look at the volatility in much bigger and more diversified operations like Burford Capital (LON:BUR) the exception at present is really Manolete Partners (LON:MANO) which has lots of small, fast cases and therefore attracts a higher rating.
Litigation finance is only one part of the business, and a fairly small part, so a small number of cases shouldn't be too much of an issue in this case.
A bit like buses I don't comment on anything for ages and then twice in two days - Jarvis Jarvis Securities (LON:JIM) yesterday (I hold ) and Luceco Luceco (LON:LUCE) today (I hold ) . Bless them Luceco have issued that wonderful statement "Full year guidance ahead of market expectations " . They are now expecting full year revenue of at least £220m and Adjusted operating profit of at least £39 million giving 2020 EPS of at least 24.3 pps which is 35.2% ahead of forecast. In the past you have been more of a Volex man in this sector but Stocko now has Luceco as the winner when you use their comparison tool - got to be worth a look .
The consensus estimates in Stocko are :
(£)
(p)
(p)
(£)
(p)
(p)
Unlocking restrictions and letting Covid rip through the public, is leading to workers being pinged and companies being unable to operate. Are heading towards a UK-specific stock market crash?
It seems as though to have a good economy covid under control is needed.
BSV
People are starting to delete the apps or ignore them. None of our family have them.
My nearly two year old granddaughter has been banished from nursery to "self isolation" (difficult at her age) for ten days because someone in her bubble there tested positive. If it happened next week she would be able to continue, but there must be doubt as to whether the nursery will have enough staff left to stay open anyway.
@Doublelutz
I just want to echo this. I received the notification and completed 10 days isolation as required. I then got another notification for isolation 2 days later even though I had not left the house, just used my back garden. I immediately deleted the app.
I'm sorry, but we can't live like that.
I remember around Christmas time people were getting isolation notices all over the place - I suspect they were legitimate as a lot of people (I know) were also ill around this time. From a workers point of view when I got pinged to isolate back then I didn't get paid by my company and was unable to claim the government allowance. So the equation for me was any single day of work I did could cause me to have to isolate for up to 10 days. You couldn't pay me a single days wages to stay in my house for 10 days so I just stopped working (that is amongst other concerns and certainly not an option for most people).
Got to have doubts about validity of Covid numbers when I hear from a teacher that there are currently 340 kids in his school out of 1450 - and that you can get a false positive to avoid going to school with a simple use of Fruitshoots! Thought this was fake news at first but apparently true.
The narrative in the UK is fascinating; cases rise as do hospitalisations (although clearly at levels way below previous waves), and the gov is pitching a plan to let COVID run amok as 'freedom day'. What kind of story will be sold when they inevitably backtrack as the Netherlands did mere weeks ago when the R number hit 6.0? It's all our fault for not exercising personal responsibility? It's like saying it's our personal responsibility to ensure we have safe drinking water.
I think the idea of a 'Roaring Twenties' style reopening in the UK is looking unlikely, but if you are thinking stock market crash then I'd look further afield: the US has ten states where vaccination rates are below 40% (all deep red obvs), and another 21 where vacc rates are below 50%. Meanwhile the Delta variant is on an absolute tear.
We could be at this for a couple more years, which is unutterably depressing to even contemplate. I'm at 29% cash and slowly edging higher. Bleh.
I'm over 60% cash and intend to stay there!
We could be at this for a couple more years, which is unutterably depressing to even contemplate. I'm at 29% cash and slowly edging higher. Bleh.
While agreeing with you I don't understand what's happening in the Netherlands. They reopened before the vaccination program was complete (like us) and CV-19 has run amok (as it will here). That's surely exactly as everyone would expect?
Furthermore the Netherlands only has very low levels of hospitalisations (as you'd hope). So why re-introduce restrictions? Is anything happening that anyone with rudimentary secondary school maths couldn't have predicted?
Letting CV-19 run has significant risks, but if you decide to do surely the only reason to backtrack is if hospitals are at danger of being overwhelmed?timarr
Politicians blinked? The hospitalisation rate in the Netherlands is very low (2.7 per 1m as of 4th July). What doesn't bode well for the UK plan is that as of 4th July the hospitalisation rate in UK was 14.5 times higher than Netherlands before our reopening.
Also the reality is for healthy, younger people catching it and recovering is the best possible outcome as this give much stronger immunisation than vaccines (the data shows this)
Also the reality is for healthy, younger people catching it and recovering is the best possible outcome as this give much stronger immunisation than vaccines (the data shows this)
What reality? What data?
In general for most diseases vaccine delivered immunity is safer than natural immunity. With the former you don't end up seriously ill with CV-19, with the latter you may. Vaccines are delivered directly into muscle and provide a pretty consistent immune response. Natural infection enters from the respiratory tract and gives an inconsistent immune reaction - at one extreme it can kill you, at the other it may provide minimal protection.
Moreover the evidence so far is that people can be repeatedly infected, even at the same time, with different CV-19 variants. Vaccines provide some protection from all variants (so far).
Even young and healthy people should opt for a vaccine if possible. Yes, side effects do happen but they're rare and the side effects of natural infection - Long Covid - are definitely to be avoided.
https://www.immunology.org/sit...
timarr
The evidence that's available says that's not true. There are various takes on it, here's one that puts it bluntly:
https://www.contagionlive.com/view/immune-response-from-mrna-covid-19-vaccines-is-more-robust-than-natural-infection
In addition, there appear (form what's currently understood) to be 2 ways in which vaccines are more effective - they are likely to provide longer lasting immunity - and they are better at protecting against new variants.
One discussion of this is available here:
https://newatlas.com/health-wellbeing/vaccine-immunity-stronger-than-natural-infection-covid/
In addition, there are small risks to the vaccine, while long covid affects 10%(?) of those who catch the virus, including the young - plus those who have the vaccine do not risk spreading the virus or requiring others to self isolate.
Lee,
This strikes me as extremely important. Can you give a source for the supporting data?
I'd recommend the latest edition of 'The Briefing Room' on BBC Sounds which is asking the same questions but gives no straightforward answers.
The alternative is we stay in a mild lockdown for years/ever. We are just a few days away from the majority of new cases being in vaccinated people and as no vaccine will ever be 100% effective what can you do? Wait a month and its winter - better to relax things now while the kids are off.
The government have capitulated to their own back benchers and left it to our collective responsibility and common sense, that will end well. @farraway1 on twitter: "I NEVER use my headlights when I drive at night. It's my choice so what's it got to do with you? If your headlights are so effective then why do I need to use mine? Why would I need to use my headlights? Driving a car has a 99.98% survival rate"
There will be buying opportunities, if we live to see them.
I think a reversal of government policy is inevitable in the UK, and the price we pay is people get long covid and people dying. Why are we doing this, is to appease some backbencher and meat to sections of the voting public?
This looks bad for business also, as the restricted opening for some businesses is better than a complete opening and closing of activity.
I hope this won't happen, but it longs serious enough for me to expect a mini-crash.
BSV
I actually hope the Gvt will stick to the policy of "cautious but irreversible" lifting of restrictions. once the majority is double jabbed, people wont need to isolate unless they test positive and companies will be able to continue production and operations with minimal impact. So i dont think we will see a UK stock market crash (but who knows?)
On a serious note, we cannot continue to live as if we are in some dystopian zombie apocalypse. The real problem is the obesity epidemic across the world, and covid has highlighted this. I suspect a deluge of mental health problems following the impact of prolonged restrictions (which is why i hold LON:KOO Kooth) but i suppose that discussion is not for this paltform.
Well you could be right as the flu has disappeared, everything now gets labelled covid and as we have been unable to eradicate viruses this will go on forever or until we have all starved to death or been killed due to not being able to get treatments for illnesses other than covid.
I don't suppose anyone really cares what I think but........I am pretty sure that relaxing all restrictions in one go will lead to a big rebound in cases and hospitalisations and to a smaller (hopefully) rebound in deaths (because of the vaccine effects). Our utterly useless PM will try and tough it out until things start to look bad for his ratings, will then flip flop, re-impose some kind of lockdown and markets will fall.
The market has very little idea how to price in the effects of covid19 as no-one really knows what they will be. So we saw an over reaction to the initial pandemic followed by a wildly optimistic recovery, with smaller ups and downs in response to changes in covid statistics and government actions. Personally I think the markets are currently irrationally optimistic and prices will fall. I guess things will settle down eventually and that are will be buying opportunities (leisure, travel) for the very patient.
But we have been INCREDIBLY LUCKY that covid-19 has been such a (relatively) mild disease. We may not get away with it next time.
“ I don't suppose anyone really cares what I think but........I am pretty sure that relaxing all restrictions in one go will lead to a big rebound in cases and hospitalisations and to a smaller (hopefully) rebound in deaths (because of the vaccine effects).”
I think that we should care what each other think because we do need to try and all get behind whatever strategy we follow as a country regardless of whether we think it is rather risky.
I don’t buy the narrative that we are relaxing all restrictions at once. Seems to be some sort of Starmer sound bite. We’ve had gradual return to schools, to using pubs and restaurants, to meeting others outdoors and indoors. So, it’s certainly not removing restrictions all at once.
Seems to me that we cannot stay restricted in our movements forever just because there will always be vaccine refusniks. And my understanding is that the risk to someone under 18 who is unvaccinated is still less than the risk to a double jabbed person over 50 years old.
A possible alternative might be to legally enforce vaccination for the whole population, except medically exempt, but there’s no appetite for that so far.
On the investment front, being in cash hasn’t paid off so far during the pandemic so I don’t see a good argument for holding a large proportion of cash right now. I’m holding a bit for buying opportunities but, with negative real interest rates, cash seems especially unattractive right now.
I don’t buy the narrative that we are relaxing all restrictions at once. Seems to be some sort of Starmer sound bite. We’ve had gradual return to schools, to using pubs and restaurants, to meeting others outdoors and indoors. So, it’s certainly not removing restrictions all at once.
Do you live on another planet?
It is government policy to remove all restrictions, and it's a free for all, for anyone to do whatever they like with the protection of the law.
A possible alternative might be to legally enforce vaccination for the whole population, except medically exempt, but there’s no appetite for that so far.
What Orwellian world are you suggesting be created?BSV
“ Do you live on another planet?
It is government policy to remove all restrictions, and it's a free for all, for anyone to do whatever they like with the protection of the law.”
Very disingenuous BSV. You know exactly what I mean because I explained it. Some major restrictions have already been removed.
“ What Orwellian world are you suggesting be created?”
Now you’re just being alarmist and resorting to hyperbole. Compulsory vaccination has been done before with small pox. Before COVID-19, locking down the whole country was unthinkable, but we ended up having to do it. So, what was unthinkable became a necessity. If the only way out of perpetual lock downs turns out to be compulsory vaccination then, distasteful as compulsion is, we may have to consider it.
Very disingenuous BSV. You know exactly what I mean because I explained it. Some major restrictions have already been removed.
People can only assume you mean what you write. I suggest it disingenuous to write one thing and expect readers to understand the meaning as something else.
Compulsory vaccination has been done before with small pox
Compulsory vaccination did not work so well. Only 2/3 of the infants were vaccinated 5 years after the Act was introduced. Not sure Governments should introduce failed policies of the past.
BSV
"A possible alternative might be to legally enforce vaccination for the whole population, except medically exempt, but there’s no appetite for that so far"
Lets just bin this idea right now. There would be riots en masse; you cannot force people to take a medicine which is completely unproven in the long term.
this would more likely cause a UK market crash than covid itself.
"A possible alternative might be to legally enforce vaccination for the whole population, except medically exempt, but there’s no appetite for that so far"
Natural Selection - let God sort'em out.
“ Lets just bin this idea right now. There would be riots en masse; you cannot force people to take a medicine which is completely unproven in the long term.
this would more likely cause a UK market crash than covid itself.”
And, if the only alternative is to have never ending lockdown restrictions, are we not going to riot too?
Lockdown was unthinkable but we ended up accepting it. Perhaps, if we want to avoid more and more lockdowns, we may in due course have to go down the compulsory vaccination route. And can we really wait several years living the way we are now to see what long term data may show?
Morning all,
I've been on the verge of buying into Vertu Motors (LON:VTU) this week after some good insight from Paul and other subscribers on the SCVR. Vertu has a good margin of safety with extensive free-hold property and interesting prospects. However, I've been cautious due to a couple of risks:
1. New vehicle supply challenges - the impact is hard to gauge
2. Stellantis intention to terminate their current contract with Vertu in June 2023. Vertu currently operate 27 sales and aftersales outlets (out of 149 total) with Stellantis franchises which include Peugeot, Vauxhall, Citroen, DS Automobiles and Jeep. It's likely an agency model will be negotiated and everything will continue fine in future; however, it's still a risk as there is some uncertainty for now.
So... to figure out my next steps, last night, I went down to my local Bristol Street Motors to experience what it's like as a customer. This was the first, and main car on the street corner:
For a company that is focused on selling cars, I couldn't believe it. Most of the cars in the yard were also dirty. I then went to another outlet to check whether the first one was an outlier. Again, those cars were quite dirty. This surely can't be normal?
Personally, my experience put me off buying VTU shares for now and I'm going to sit and continue watching from the sidelines.
Cheers!
Vertu Motors (LON:VTU) That picture! Lookers must have a trained pigeon force sent to dive bomb its rivals.
put it this way, no one is paying 23k for a car in that state for sure, but I'm sure they polish the cars regularly
£Vtu - the chicken poo is extra: the price would be £22,000 without it!
That looks a pretty customer offputting display. In a previous life I ran some small car dealerships and it was standard procedure to have a car washer go over the cars every morning - starting early as there's not much point in washing the cars when the customers have all gone home. As we ran a fairly tight staff situation in the event of sickness I have done the job myself. Quite interestingly it gives you a chance to chat to the customers. A car in that state would not have been allowed on display.
Might be interesting to forward your photo and comments to Head Office
Following on from your first point, I recently bought a second hand car (about 18 months old - JLR) and the salesman told me that the factory was concentrated on making orders for customers. As a result, the franchise did not have to buy the usual number of new cars from the manufacturer. That meant that there were not the usual number of nearly new cars in the system, which was one of the features pushing up prices.
Obviously anecdotal, but if extrapolated across the sector, how that all feeds through into the financial of the retailers is difficult to understand. On the one hand, they are going to get the one-off increased margins from existing inventory, but this effect will will reduce as they refresh it, plus reduced discounting on new cars, but presumably at some point the reduced volume coming through will have an impact. Good difficult for me to work out, so I have decided not to buy into motor retailers at this stage of the cycle.
Kieranj077 - what dealer was this exactly? i.e. where was it? Thanks
Hi gwilli68,
This was at Bristol Street Motors Hyundai Exeter.
Cheers,
Vertu Motors (LON:VTU) - looks like you do have pigs that fly in Exeter.
Vertu Motors (LON:VTU) I hold - talking to a car salesman recently. He tells me huge problem in industry is short supply of cars to sell. Few new cars available due to parts shortages and that's a knock on effect on 2nd hand market.
Looks cleaner here. https://www.bristolstreet.co.uk/used-car/2690201/volvo-xc60-d4-190-se-lux-nav-5dr-awd-geartronic-diesel-estate/
My morning smallcap tweet:
Feedback (LON:FDBK) eve Sleep (LON:EVE) Sigmaroc (LON:SRC) Luceco (LON:LUCE) Renold (LON:RNO) Learning Technologies (LON:LTG), Bonhill (LON:BONH), RBG Holdings (LON:RBGP), Amte Power (LON:AMTE)
Feedback (FDBK) first private business win for Bleepa for 20 of CVS's sites. "CVS have evidenced a real commitment to empower their vets..." Ugh. [SP=0.81 Cap=9m]
eve Sleep (EVE) guides H1(June) rev up 13%. "Marketing contribution [huh?] and EBITDA losses in line with management's expectations." Expects H2 rev in line. [SP=4.6 Cap=13m]
SigmaRoc (SRC) completes huge placing at 85p, a 5% discount, to fund acquisition of Nordkalk Oy Ab. [SP=89.5 Cap=250m]
Luceco (LUCE) hike FY(Dec) rev guidance to at least £220m (up 25%) and adj op profit at least £39m, ahead of current market expectations. H1 rev was 3% ahead of guidance. [SP=380 Cap=611m]
Renold (RNO) FY(Mar) rev in line. "Order books have continued to grow in the early part of the new financial year. Whilst there remains considerable Covid-19-related challenges in some parts of the world, with supply chain issues and rising costs, we are well placed to deal with these and our performance over the last 12 months gives me confidence that we will return to growth this FY." [SP=23 Cap=52m]
Learning Technologies (LTG) [last night] £82m placing at 192p, a 3% discount, to help fund acquisition of GP Strategies, a leading US listed provider of learning services and workforce transformation. [SP=198.2 Cap=1471m]
In line: Bonhill (LON:BONH) RBG Holdings (LON:RBGP) Amte Power (LON:AMTE)
Any view on Sigmaroc (LON:SRC) this morning, raised some money to settle yet another acquisition, which seemingly each one getting larger in size.
Sigmaroc (LON:SRC) - received an email from PrimaryBid giving me 35 minutes to make a decision?. At 5% discount thought no especially as the SP will match the offer price the next day so could just buy in the market once see the reaction.
Not sure where Nordkalk Oy Ab sits in strategy of buying family run businesses (presumably smallish). Stocko great though for a quick research under pressure.
Strategy stymied by 4% bounce on the opening!
Hi GaryC.
I disagree - I think the Sigmaroc (LON:SRC) acquisition is exactly aligned with their strategy. In the past they’ve been limited to buying Mom and Pop operators due to lack of firepower to go after bigger Game. In this case they’ve really extended themselves with an ambitious deal maximising their access to credit lines and new equity issuance but seem to have pulled it off.
The acquisition itself seems a very good complement to their existing U.K. and European operations giving them a whole new territory in Eastern Europe and the Nordic region. They’re paying roughly 7x EBITDA funded using their own PE of 17.9x so it’s earnings enhancing right out of the box even before they bring synergies and their better management expertise to bear. Lots of detailed information in the footnotes of last nights RNS, of which this is a summary:-
„Nordkalk was established in 1898 as a limestone developer in Finland and has since expanded across Northern Europe to become the leading limestone company in the region. Nordkalk develops limestone- based solutions for agricultural, construction and chemical industries and its main products are crushed limestone, limestone powder, quicklime and hydrated lime. Nordkalk delivers raw materials to numerous industries, and its solutions contribute to clean air and water, as well as the productivity of agricultural land. Nordkalk is a self-sustaining profitable business, with a long-term track record, operating in stable and developed jurisdictions such as Finland, Sweden, and Poland. Nordkalk generated €67 million underlying EBITDA and €61 million net operating cash flow for the year ended 31 December 2020 and has achieved EBITDA margins in excess of 15 per cent. for the last 15 years, with an underlying FY2020 EBITDA margin of 24.2 per cent.“
https://sigmaroc.com/wp-conten...
Not without execution risk but a lot to like here IMO. I hold.
Gus.