Small Cap Value Report (Fri 16 Mar 2018) - JDW, CVR, BUR, TECH, SimplyBiz, HAT

Good morning!
The list for today is going to be something like this:
- J D Wetherspoon (LON:JDW)
- Conviviality (LON:CVR)
- Burford Capital (LON:BUR)
- TechFinancials Inc (LON:TECH)
- SimplyBiz
- H & T (LON:HAT)
J D Wetherspoon (LON:JDW)
Wetherspoon shares are marginally lower after beating H1 forecasts but expressing caution on H2.
LfL sales were up 6.1% in H1, but slower growth and higher costs are anticipated in H2, so the full-year forecasts are unchanged. Here's the half-year report. Relevant for a wide range of companies in the sector.
Conviviality (LON:CVR) (suspended)
Conviviality has confirmed that it is working on "the possibility" of an equity fundraising, to fund its VAT payment.
Given that its existing lenders were already maxed out, and probably unimpressed by the company's ability to make cash flow projections, this has seemed the most likely outcome.
To its credit, it did succeed in cancelling today's dividend payment, saving £8 million. That relieves some of the pressure - I was penciling in a 50p placing price, but that is looking a bit pessimistic now.
Of course, this is purely speculation on my part: it all depends on the hunger of existing shareholders, and the demand for new shares. It's impossible to tell where the demand for more shares will find equilibrium against forthcoming supply (incidentally, this is why dilution is so risky for existing shareholders - you have no idea how bad the dilution is going to be). Funding could happen at almost any level.
The irony is that Conviviality paid out nearly £20 million in dividends last year, and is now scrambling to find £22 million from somewhere.
Even before this VAT débâcle, I thought Conviviality's dividend payments were questionable. Over the last three financial years, including this one, it has raised over £190 million (gross) from shareholders to fund acquisitions, paying significant fees. At the same time, it has distributed £27 million in dividends, triggering tax liabilities for shareholders. Given all the frictional costs involved, why raise funds and return funds at the same time?
Not paying a dividend this week was the right thing to do, but not paying a dividend for the previous two years would also have been sensible, in my opinion.
Hopefully, trading will continue as normal with suppliers and customers, and the problems will not become any more serious. As the company itself said regarding this year's forecasts:
To the extent that the current situation creates operational difficulties, this may negatively impact the adjusted EBITDA range.
If and when the shares resume trading, I would remain very cautious about getting involved. I've been a sceptic for quite some time not just on Conviviality's valuation but also on its strategy. The former is likely to be reset at a more realistic level, but we still don't have any evidence that a more prudent strategy will be pursued in future.
Burford Capital (LON:BUR)
- Share price: 1402p (+2%)
- No. of shares: 208 million
- Market cap: 2,918 million ($4,085 million)
I'm a little bit reluctant to write about this one, because 1) the market cap is well beyond our limits at the SCVR, and 2) it's much more difficult to analyse than the average company. But I'm happy to say a few words, since so many readers are interested in it.
Firstly what is it - it's a law firm, specifically focused on litigation finance. This means taking large stakes in legal claims, using its own capital and also now using the capital of others.
It has been a spectacularly successful investment:
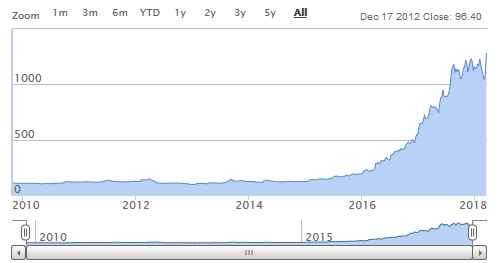
According to the latest figures, its balance sheet equity has soared to $800 million, of which $351 million is money invested by shareholders ("share capital"), and $423 million is retained earnings ("revenue reserve"). It has also paid out around $65 million in total dividends, according to a quick calculation by me.
The entire asset base is now $1.5 billion, with the main entry being the all-important "investments" - i.e. stakes in legal cases. These investments are now worth some $1,075 million.
Investments are written up as their value increases, but Burford argues that it does this conservatively, not writing up the value of its claims to their full value in the secondary market:
The reality is that we all live in a world of market valuations of assets. Fund managers mark their entire portfolios to market all the time. We operate much more cautiously, given that the secondary market for litigation risk is less developed, but fair value accounting is a fact of life and our marks have historically been shown to be reliable.
My opinion
I do find it difficult to have a strong view on Burford. I suppose I could simply congratulate the company and its investors for their success, and leave it at that. But I can say a little more.
One objective fact is that it is an innovator in its field, and has had tremendous profitability and growth so far.
As a financial stock, this is another case where I would be using the book value as my anchor number, thinking in terms of what multiple of book value makes sense.
The number currently attached to Burford is 5x book value ($4 billion market cap, $800 million net assets). If we assume that investments are worth an additional $200 million due to conservative accounting, we get 4x book value.
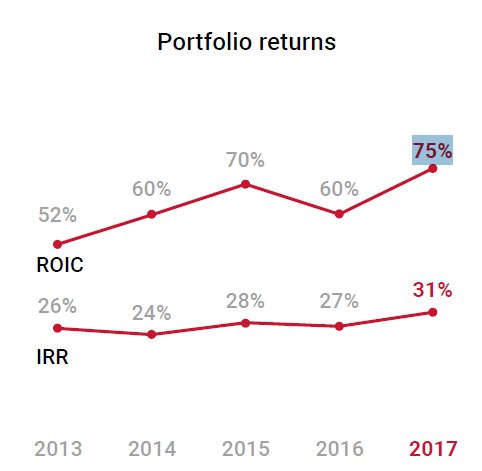
This says that investors are expecting very serious returns in the future. Based on the track record, it looks reasonable to expect above-average returns:
The main risks I would say are probably a) concentration risk in investments, and b) defending the company's competitive position, as more capital is likely to flow into the sector.
Concentration risk has declined as the company's portfolio has grown. This is a good thing, although it may perhaps be difficult to maintain a 31% IRR over a much larger portfolio.
The table below summarises the company's track record in its lifetime: it has committed $516 million, invested $443 million and recovered $773 million so far from 61 investments, generating the return statistics shown in the previous chart. There are a further 82 cases where it has invested $629 million, and not yet made any recoveries.

Arguably, we could mark the ongoing cases up by a lot more than $200 million to produce a bigger book value and a lower effective price/book value multiple.
While previous successes have been concentrated (e.g. the Peterson case, which is probably still undervalued on Burford's balance sheet), future successes are likely to be far less concentrated.
Moving on to think about competitive prospects, it must surely be inevitable that more capital will be attracted into this space.
Last year, Burford made what I thought was an unconvincing argument as to why new entrants would not be able to compete with it:
Second, the litigation finance market is still relatively nascent and new entrants need to raise capital to compete. The providers of that capital can see Burford’s publicly disclosed returns, and sensibly demand comparable returns from new entrants. Thus, discounting to achieve volume will result in immediate underperformance by the new entrant, which will in turn lead to investor unhappiness and the refusal to advance incremental capital.
I don't see the sense in this, because Burford's returns have been huge. Even if a competitor were to underperform Burford by a few percentage points, they would still beat average equity market returns and virtually all traditional investment markets.
That was the second point in a three-pronged argument as to why competition would remain muted in the short-term. I do think that competition will heat up eventually, but it looks like the company is right that competition remains weak for now.
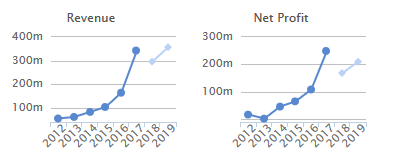
On balance, I'm neutral toward the stock. It's an interesting and unusual one. There are some significant risks attached to it, and an adventurous valuation, but it keeps doing really well. And there is not much point in making forecasts for next year, because anything could happen:
TechFinancials Inc (LON:TECH)
- Share price: 24p (+11%)
- No. of shares: 72.5 million
- Market cap: £17 million
Notification of CEDEX Token Pre-Sale Event
I'm mentioning this as a measure of the ongoing crypto-mania. This is an RNS announcing the scheduled launch of a new coin related to diamonds.
Working within the Ethereum (ETH) eco-system, the new coin will be assisted by a proprietary algorithm which will estimate the value of the underlying assets.
Every diamond is unique, and this is why exchanges for diamonds don't exist in the same way as you have exchanges for gold, silver, copper, etc. Previous attempts to create liquid markets in diamonds have failed.
When you read the prospectus for a new equity issue, it can be alarming to realise how few rights you have as an ordinary shareholder, and the extent of the risks to which you are exposed.
New crypto-currencies, however, are on another level completely.
Consider these risk warnings from the whitepaper for the CEDEX Coin (CEDEX means "Certified Blockchain Based Diamond Exchange). The emphasised points are mine:
CEDEX tokens hold no rights and confer no interests in the equity of CEDEX. CEDEX tokens are sold with an intended future use on CEDEX platform and all proceeds received during the token sale may be spent freely by CEDEX on the development of its business and the underlying technological infrastructure.
CEDEX tokens should not be acquired for speculative or investment purposes with the expectation of making an investment return.
The Tokens are designed and intended to perform as a functional utility for use only on the Company’s business platform that is yet to be developed.
Because CEDEX Tokens confer no governance rights of any kind with respect to the Network or Company or its corporate afliates, all decisions involving the Network or Company will be made by Company at its sole and absolute discretion, including, but not limited to, decisions to discontinue the Network, to create and sell more CEDEX Tokens for use in the Network, or to sell or liquidate the Company.
At least when you buy an equity, you have some rights - the right to vote at meetings and get a dividend. When you buy a coin, you have no rights at all.
The SimplyBiz Group Plc
Another new float worth mentioning, SimplyBiz is another service provider to financial advisers. It has that in common with IntegraFin Holdings (LON:IHP), whose flotation I also covered recently.
SimplyBiz claims to be "the UK's largest support services compliance provider for intermediaries (by revenue)". It is headquartered in Huddersfield.
The Placing will raise £30 million for SimplyBiz (to pay down debt) and £34.6 million for selling shareholders.
An opening market cap of £130 million is anticipated, versus historic numbers (2015 to 2017) as follows:
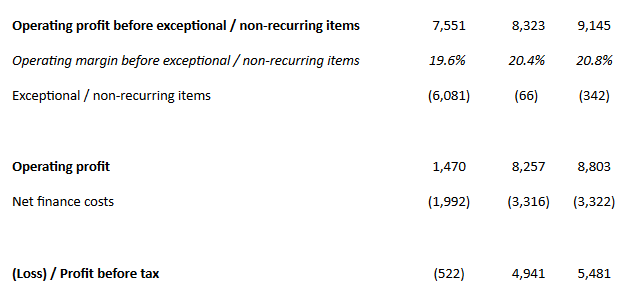
If exceptional costs remain controlled and if finance costs are much lower after the fundraising, then the valuation against 2018 earnings might turn out to be quite reasonable.
H & T (LON:HAT)
- Share price: 347p (+4%)
- No. of shares: 37.4 million
- Market cap: £130 million
(Please note that I own shares in H&T)
This pawnbroking group remains an important share for me, despite having more than halved my position in it. If I hadn't sold a chunk, it would have ended up being more than 25% of the portfolio. But I still have a healthy holding in it.
The financial highlights from these results (published on Tuesday) are excellent and speak for themselves.
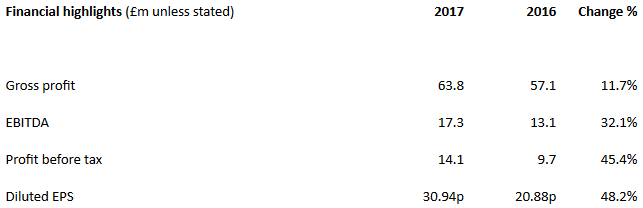
If you drill into the segment information in footnote 2, there was a £4.7 million increase in gross profit, after taking into account impairments on personal loans. (The above gross profit numbers do not take these impairments into account.)
When you include the effect of impairments, H&T's increase in profitability was surprisingly broad-based, despite the stunning growth in personal loans.
There was little or no improvement in profits from gold purchasing, pawnbroking scrap and "other services" (FX, electronic buyback, cheque cashing and Western Union).
The core pawnbroking operation, on the other hand, delivered a respectable 4.5% improvement, with profits up by £1.3 million. Its pledge book finished the year up by 11.6%, so hopefully there will be some momentum for it through 2018 as well.
Retail did even better, helped by the company's est1897 jewellery brand and the successful roll-out of the est1897 website. This segment result was up by £1.6 million, as higher volumes offset lower margins.
Finally, personal loans were the biggest contributor to growth, as expected. This segment produced an extra £2.2 million in profits (after impairments) as the personal loan book almost doubled to £18 million.
Some shareholders have been wondering why the share price has seemed a bit subdued, on a trailing PE ratio of 11x, despite excellent results. The most plausible explanation I can give is that buyers are held back by the ongoing threat of further FCA action.
Half of H&T's personal loans fall under the FCA's definition of high-cost short-term credit. In the latest update on its review of high-cost short-term credit (link), the FCA said:
There is an emerging picture of a case for possible intervention in a number of markets but also a recognition of the limits of what can be achieved through traditional regulatory interventions alone.
Among the potential solutions mentioned in the update is the idea that government should subsidise losses or give tax breaks to non-profit lenders and credit unions. This would be a negative for everybody else in the industry.
Ultimately, it appears unlikely that the FCA will do serious damage to the pawnbroking and personal loan business model, especially in the case of H&T whose services are well understood by customers and highly competitive against existing alternatives. But I think that this is probably the main concern which overhangs the share price for now.
The outlook is fine, and trading is in line with expectations:
The Group has enhanced its ability to serve a wider customer base, both in store and online, with growth in its well-established core products and the newer unsecured lending offering. This diversified approach to growth reduces the risks inherent in any individual objective and positions the Group to capture share in this exciting market.
The balance sheet shows net tangible assets of about £90 million, and total balance sheet size of £142 million. Bank borrowings reached £22 million, from a facility which now allows maximum borrowing of £35 million. I am comfortable with all of these numbers.
I might finish by noting that H&T currently enjoys a near-perfect StockRank of 98.
That's enough for today. Thanks for dropping by and enjoy the weekend.
Graham
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

76 comments
re Burford Capital (LON:BUR)
i bought in 2015 at 170 - simply because they were tipped by simon thompson (IC) AND because neil woodford held them.
otherwise i had - and still dont have , any idea of the pro's and con's - quite beyond me ..
i wonder if mr buffett has looked at them.
| Report | Link | Share Reply
Thx for builds - my 'expertise/experience' is in marketing/sales not finance. I see products which are good and welI suited to an underserved market so I am confident they can get the topline growth. But I accept short term funding risk is there. I believe if they get a couple more years of good growth away then I think the risk will drop as they retain more cash and at worst could sell a slug of themselves to strengthen equity base via a rights issue if required. Key signals for exit for me would be if impairments start to rise (instead of current falling).
However, I think this is an industry where simple technological improvement (real time Mgt Info from ipads and Apps to reset rates) has given a very big and under appreciated boost to mgt control. Combined with face to face contact I'd hope they (we!) would see trouble coming soon enough. Famous last words ! (In contrast I think some online lenders will get into trouble and provide further profitable acquisitions.
But question - Is the fact that the loan is spread amongst 6 players and fronted by a company I have never heard of a concern (ie they are stretching cant find funding easily). Or does it look like a typical deal.
I thought (hoped?) the 6 year deal was actually a conservative move by an experienced Chairman for a maxi min result ie ensuring a good but not best possible outcome in the same way keeping the staff coverage high fwas (mgrs per agent, mgrs per area mgr high).
Hi Zipmanpeter.
There’s a bit more information about the Non-Standard Finance (LON:NSF) loan facility on the company website. It was arranged by Alcentra, a specialist middle market offshoot of Bank of New York/Mellon. Not really a household name in the UK but a pretty well known large US commercial bank. I don’t think their involvement should be taken as a sign NSF where struggling to get funding elsewhere. It looks as though RBS also provide a bilateral facility on top of this and presumably do most of their clearing and payments business.
I agree it’s encouraging that it’s a committed 6 year facility, but suspect there are various conditions to funds being drawn down and covenants and other triggers that might accelerate repayment. Likewise, however good the relationship with the bank and wider funding group there’s still a dependency on their goodwill if issues arise which remains a potential risk compared to being funded out of retained earnings or a deposit base. All good while the sun shines - the leaks only tend to appear when it rains.
Good luck.
Gus.
Burford Capital (LON:BUR) is competition a worry? This is what BUR say in the AR
"Another common question we are asked by investors is about competition: Won’t your returns attract competition, and won’t that competition inevitably drive down returns?
In fact, we operate in what has always been a competitive marketplace. Burford has grown by
besting its competition. We were not the first mover in this market and we have always faced robust competition. That competition is not very visible to investors given that Burford is the only listed player of scale in this industry and our largest competitors are structured as private investment funds. Indeed, there are at least 11 firms competing directly with us, each of which has at least $100 million in capital and has been operating for at least four years, with many of them having longevity similar to Burford’s.
So, we have in fact been producing our historical returns in the face of substantial competition. Furthermore, a number of factors insulate our business from naked price competition, which should provide some level of confidence in our ability to continue to produce desirable returns:
■ Law in general is not a price-sensitive commodity: Particularly at the high end of the corporate market, where Burford focuses, law is not generally a commodity product, and lawyers and clients put value on relationships, reputation, pedigree and other factors that weigh in Burford’s favour.
■ The extensive diligence process is inconsistent with auction-style processes: Setting a price in a litigation finance matter requires substantial diligence, including extensive (often unpaid) work from the client’s lawyers, and thus the market does not regularly have auction-style competition for investments as neither litigation finance providers nor lawyers are generally willing to spend the uncompensated time necessary to facilitate such a process. Moreover, lawyers' confidential work product (which is important to the diligence process) cannot be widely disseminated without putting its protection at risk.
■ Contingency fee pricing is a useful reference: The relatively high pricing offered by contingency fee law firms operating in an adjacent but related space can create
a benchmark or expectancy divorced from conventional capital market expectations and has remained relatively constant over time.
■ Scale matters: Our size and expertise are unmatched which gives us a unique ability
to serve our clients. While there are other
large pools of capital out there, none has our expertise when it comes to litigation evaluation and management, and our competitors with litigation expertise lack anything approaching our capital and scale."</i>
There's more which addresses the subject quite comprehensively and is best read directly from the AR.
Re Burford Capital (LON:BUR) & potential competition - re BUR's comments: some degree of a competitive 'moat' then but specifically in relation to:
"Scale matters: Our size and expertise are unmatched which gives us a unique ability
to serve our clients. While there are other
large pools of capital out there, none has our expertise when it comes to litigation evaluation and management, and our competitors with litigation expertise lack anything approaching our capital and scale.""
- It can't be that hard to put the two together, surely, and there might be more incentive to cut out Burford Capital (LON:BUR) and keep all the margin for oneself once creeping competition starts to erode profit margins. Not the most moaty of moats, is all I'm saying. And as I said earlier, there can be plenty of profit left on the table long after competitors show up and start nabbing market share, especially in a growing market.
(No position. Any views on balance sheet asset valuations still most welcome please.)
They've got a moat.
They are the number 1 player in this field by size and expertise.
If you want to litigate and scare the other side you want someone big standing at your shoulder.
Re Burford Capital (LON:BUR) agreed, they have a competitive moat and a good name. Barriers to market entry are not as large as for some industries, but they have a moat.
Do you have any insights into the net realisable value of their litigation-finance assets please? (I'm hoping it's at least five times higher than the carrying value of those assets on the balance sheet, to justify the current market value of the Company.) If it is then I'm in, cause I get the valuable intangible stuff I wouldn't even begin to know how to place a value on as a freebie (including know-how, good name, contacts and relationships with customers and financiers).
I've tried to value it Ed and have given up. I don't think anyone else can arrive at a robust valuation either.
It's the market leader in a nascent business segment and both Burford and the business segment are growing at a hell of a lick.
I suspect that there's a good chance that the difficulty in valuing the business may still mean it's being mis-priced.
One of the key issues is that the Income (and the profits) are largely a made up figure - the directors are having to estimate the value of cases in progress.
But if you look at some key metrics - invested capital, commitments, realised and unrealised gains and cash thrown off you'll see that they've been roughly doubling over the last three years.
If they've allocated their capital in the last two years as wisely as in the past then we could see these metrics continue growing in a similar vein for another couple of years before we start to see some plateauing. This suggests the price could still double/treble from here over the next 2/3 years.
Personally, I think you'd do better by considering the downside risks and if you get comfortable with those then let the upside (unknown) look after itself.
If your feared competition comes in it's probably a good indicator that the business segment is still in a strong growth phase, and I suspect Burford will be benefiting the most.
The world is getting more complicated and more regulated but human nature and behaviour will remain fairly constant, that's some tailwind for more litigation.
Thanks for taking the time to reply regarding valuing Burford Capital (LON:BUR) ,Ship, and my somewhat flippant comment on tangible book value aside, I agree with what you have said, and I'd be prepared to pay a significant premium to the tangible asset value of revenue-earning assets here - clearly there is some canny legal nous at play. Though my exploration of value has been clouded by the necessity to neck a bottle of wine on account of it being Friday night, I have reached the perhaps premature conclusion that this might be the most highly-valued under-valued investment I have yet encountered in about ten years' of share investing. At times like these I tend to ask myself, "what would Janebolacha do?", but I think we know the answer. (No position - but ask me again once the hangover has cleared.)
@ed,
There’s a link on the home page of the Burford Capital (LON:BUR) site to a recording of the earnings call and the slide pack is on the Investors page. It would be a worthwhile use of an hour to listen to the recording.
From memory (I’ve had a glass of wine too) they are conservative in their valuations in that they hold the investment at their sunk cost until there is an actual legal event such as a ruling in their favour. Even then they will apply a discount until they actually collect payment. As others have said, winning a case is just part of the journey, collection is the next phase and is an area that they specialise in.
They do not write up the values on sentiment or feelings such as “the judge seemed receptive to our case”. They are actively trying to promote a secondary market in legal investments so that there are market assessments of value that they can use, e.g. the partial sale of their Petersen interest and the Teinver sale. They have only ever written back down the value of two investments that they had previously written up.
Thanks John, I shall be following your suggestion re Burford Capital (LON:BUR) today and looking at this in more detail.
One interesting angle on Burford Capital (LON:BUR) and other litigation finance competitors from a cursory reading of Burford Capital (LON:BUR) 2017 annual report relates to cases involving expropriation of certain company assets by national governments (Argentina in this case). Foreign shareholders (Spanish) in these companies (airlines and an oil/gas business) suffered major business losses - even bankruptcy and are pursing the government through the courts supported by finance from Burford Capital (LON:BUR). If we get a Labour government, sooner or later, and John McDonnell as Chancellor implements his veiled threats to expropriate assets as part of the Labour's nationalisation programme then there could be plenty of business opportunities for the likes of Burford Capital (LON:BUR) given the foreign involvement in many of our utilities and railway franchises. Perhaps despite the 7 x share price increase since the start of 2016 Burford Capital (LON:BUR) might be an excellent hedge vs. Labour's proposed nationalisation programme.. I am not currently a holder but perhaps I should be!
Building Graham's article on on H & T (LON:HAT) that "Half of H&T's personal loans fall under the FCA's definition of high-cost short-term credit.", I note that less of £NSF's loan book does (since most branch and all guarantor lending are much lower) and that Home Credit is currently well beneath the price cap AND 'community based' with face to face to face interview - likely to be better received than online lending.
If online lending at very high rates were to be restricted in a future FCA review this could be very good for Non-Standard Finance (LON:NSF) !
Wish we knew whether the £30m bill on Conviviality (LON:CVR) was for vat or a tax bill, it might help. There is also no statement as to whether it is just a timing issue so can only assume it isn't
In which way would it make a difference? (VAT vs TAX).
The Guardian is already talking about "at least" £50m capital increase:
https://www.theguardian.com/business/2018/mar/16/conviviality-uk-drinks-retailer-seeks-rights-issue-after-catastrophic-financial-errors
What I can say is that it is very difficult to raise funds for litigation financing vehicles because until you have critical mass - which I think BUR's annual report suggests is around the $300m mark, you are limited to funding individual claims, rather than portfolios, and can always be effectively destroyed by one or two adverse claims. I believe this is what happened to Juridica Investments (LON:JIL). Raising that sort of money is difficult for a first venture into this field. You really need some big hitting litigators to give the structure credibility, and lawyers at the top of their game tend not to be entrepreneurial.
Re Burford Capital (LON:BUR) : Small fry sums for a global asset management company to set up a competitor with relative ease? Regardless, there can be plenty of profit to be had for years after increasing competition starts eating one's extravagant lunch.
No, What clever global asset managers do is ask Burford or Therium to accept capital in their funds.
Using all of their hard to develop networks and taking a big slice of the upside for no cost.
Based on Bulletin Board chatter isn't Burford Capital (LON:BUR) now a screaming short!
Only in jest, thanks for all the updates Graham and a good weekend all - Well done to those holding.
Burford Capital (LON:BUR) I fully understand why investors may be sceptical. What sounds too good to be true generally is. Fortunately, there are always exceptions to that adage. I hold BUR from an initial investment at £1.50 in 2015. At the time it was a small stake among a number of disparate investments and somewhat unremarkable. The speed with which BUR has grown, particularly with the acquisition of GKC has surprised me and given the increase in value, I have thought long and hard about whether I should cash in my chips or stay on for the ride.
Whilst I too find it impossible to accurately quantify the future earnings of the company, I am convinced that further significant growth is definitely likely. Even today I have topped up and am happy to do so despite the recent sharp increase in the SP. The reason for the sharp increase is simply down to results that exceeded the limited expectations of investors.
For anyone who has serious questions about how the company makes its money and whether or not it will continue to be able to grow, I recommend reading the Annual Report
http://www.burfordcapital.com/wp-content/uploads/2018/03/BUR-28711-AR2017-AW-web.pdf
and the associated presentation
http://www.burfordcapital.com/wp-content/uploads/2018/03/Burford-March-2017-Investor-Presentation-FINALpdf.pdf
I echo what John Eustace said. It is highly informative, detailed and clearly written despite this being a complex business. I get the sense that BUR are on top of their game, know what their strengths are and how to innovate to provide what their clients want but ultimately to benefit their shareholders and investors.
My rationale for staying invested and for committing extra funds is down to my faith in management to continue to build on their track record given supporting underlying factors. These include, falling expense ratio, availability of additional capital, growing demand for and acceptance of litigation finance into the mainstream. Moreover, whilst competition is inevitable, BUR has the scale and the reputation to hold its own. talking of reputation, BUR currently works with 70% of the largest law firms in the USA and refers to the importance of building relationships with its clients in the AR.
Large individual cases make headlines for obvious reasons but they are not the norm, the bread and butter of this company's workload. Look beyond the these occasional "big ones" and disputes that involve governments and think about the more mundane pursuit of financial remedies for corporate wrongdoing, such as one in which BUR acted for an oilfield services company whose client didn't pay their bill. Systematically refining over 1500 enquiries into 50 or so cases where they felt investment was appropriate tells me there is plenty of work left for the competition as well as giving BUR the "choice cuts"
The investor in my assessment, is faced with two simple questions, can BUR continue to raise the finance necessary to invest in more cases? Can BUR management exercise enough control over their processes to ensure that the return on investment is maintained at a high level? My opinion on both is "yes"
Re questions for investors in contemplating investment in Burford Capital (LON:BUR) I'd argue that Graham posed a third and even more important question (I'm glad he did since it has been putting me off investing in Burford Capital (LON:BUR) ): Does BUR's balance sheet massively under-value its litigation-finance assets and if so what is a reasonable, conservative estimate of their likely realisable value and therefore P/NTAV? (If their carried value is anywhere close to accurate then current market price for Burford Capital (LON:BUR) is close to six times (six times!) the tangible assets from which it earns its income. - I need to get digging but there is no point reinventing the wheel so if anyone who already knows the answer wishes to share with the good readers here and give us a head start then many of us will be very interested.)
(No position.)
There is now a trade body http://associationoflitigationfunders.com/about-us/
The other issue for Burford Capital (LON:BUR) is that it's success is beginning to push up the quantity of litigation and the threat of regulation is just beginning to be heard. https://www.cdr-news.com/litigation-funders-respond-to-us-calls-for-increased-regulation
There are a few other competitors. Therium is one, and I know of at least one private family office and two funds seeking initial funding at the moment. The problem for competitors is that the US is the main market for litigation and you need very deep pockets. The fact that Burford are funding your litigation shows 1) that it has been reviewed by people with proven judgment, and they like the odds; and 2) that you can afford to litigate to the end. That gives a competitive advantage straight away: after all, most people prefer to settle and get on with their business rather than spend 3 or 4 years gearing up for court.
I was once on the board of a litigation fund which was never launched. It is one thing to see the opportunity, it is another to work out how to exploit it. And while big margins should bring competition, the law is remarkably insensitive to price competition. People want the best quality service and the best chance to win, and Burford Capital (LON:BUR) has found that territory and is constructing a fearsome moat. In their annual report, which is remarkably well written and readable, they refer to the size of the opportunity by mentioning the iphone in 2007: everyone ended up being a potential customer, but nobody knew it at the time. That is where Burford feel they are now.
Like one of the posters above, I looked at Burford Capital (LON:BUR) long ago, hesitated and ended up buying in a year ago. The boat is definitely still in the dock.
Re Burford Capital (LON:BUR) & competitors providing litigation finance: Thank you for your views and insights, Donald, and I draw readers' attention to Comment 11: by my reading handybrownone seems to be saying there are at least five competitors in the UK (and growing) and many more in the US (by far the largest litigation market and Burford's main market). Which of the two of you is right I couldn't say since I have no relevant knowledge and you have both had some professional involvement, but interested readers should be aware of both views. Perhaps your views converge around effectively few competitors given the need for deep pockets, and it does seem that BUR has taken a strong first-mover advantage and run with it. It also seems clear that the high returns available to competent players and modest barriers to market entry will inevitably attract large amounts of competing finance such that returns seem bound to reduce in future, whether or not well-heeled litigation financiers approve.
(I have no position in Burford Capital (LON:BUR) though that might change in future if I can convince myself that BUR's method of valuing its litigation-finance assets on the balance sheet massively understates their likely realisable value - on the face of it this seems a tall order given the apparent Company valuation currently in excess of six times tangible-asset value, but I should dig a little deeper.)
Graham: Thank you for your analysis on Burford Capital (LON:BUR) - I particularly like your comments on basing a valuation on book value. I hadn’t considered that previously even though I knew it is a financial stock. You also make some other very insightful points for further consideration.
re Burford Capital (LON:BUR)
Thanks, Graham - for going where others fear to tread and giving us a fine insight on this unusual but fascinating stock.
Richard.
Thanks for the comments on Burford. Much appreciated.
re: Burford Capital (LON:BUR). You're welcome! G
Hi Graham.
Thanks for the considered view on Burford Capital (LON:BUR) . Sometimes difficult to maintain perspective when the news and numbers are so consistently good and the chorus of voices from many of the (respected) Stock board contributors is so positive.
While I’m wary of the vicissitudes of “crowd think”, I’m also a happy holder of several years who has regularly topped up on the occasional dips. With the benefit of hindsight, one of the big recent drivers was the merger with Gerchen Keller announced in Dec 2016 which in one fell swoop doubled the size of the franchise and put the global #1 and #2 players in litigation finance under the same roof with dominance in the US and European markets and the resources to develop the market in Asia. Hard to think of a parallel sector where such a dominant position was allowed to go through by the regulators on the nod. This scale, reach and expertise gives them a huge moat and most likely first look/refusal at pretty much every significant litigation case and presumably the reputation to intimidate the opposition in the cases that they take on into settling early. The following is an extract from the Dec 2016 release at the time of the merger:-
“By combining the complementary operations of the two largest litigation finance firms, the enlarged business expects to capture benefits of scale. In litigation finance, scale is important for portfolio diversification, market coverage and a deep bench. The scale and resources of the combined firm are expected to provide expanded geographic coverage in the US and globally, resulting in increased capital deployment for both public and private investors.
Burford expects the enlarged group to benefit from increased revenue diversification through the contribution of recurring private capital manager fees alongside investment income. The addition of GKC's substantial business immediately launches Burford as a significant manager of private capital, with significant ongoing management and performance fee revenue, while also allowing Burford to continue to grow its lucrative on-balance sheet investing activity.
Burford's integrated global platform offering public and private capital solutions will permit new innovation in the fast evolving industry of finance for law. The ability to access private capital will permit Burford to continue to innovate and expand its products and solidify its client relationships while also managing balance sheet risk, including offering new financial solutions with varying risk and return profiles such as the monetisation of post-settlement receivables (as GKC does today).”
Two years on, it looks like so far the merger has delivered what was promised in spades.
Gus.
re: Burford Capital (LON:BUR)
Thanks for the input Gus, much appreciated. I would expect Gerchen Keller benefits to flow from the current year onwards, on the basis of this comment from the Annual Report:
"Virtually none of our 2017 income came from investments made in 2017, and thus we are not seeing today the income potentially associated with the higher volume of new investments made this year."
Graham,
Gerchen Keller was well established before it was taken over and has been contributing income already.
The comment about 2017 investments means fresh investments in new legal cases or portfolios of cases made by Burford directly and using investors funds. I do not take it to refer to the acquisition of Gerchen Keller.
RE H & T (LON:HAT) interesting to see their business is diversifying rapidly from gold/pawnbroking with their personal loans up +95% to over £18Mn (with impairment down). However, in this area are fishing in the same sea as NSF's rapidly expanding chain of retail stores for lending called Every Day Loans (This had 34 stores at acquisition in 2015, is now at 53 stores and with 12 more to come in H1 2018). But this area of unsecured lending is growing fast and there may be room for both to also squeeze the smaller operators and establish retail store brands here that become very valuable. HAT have 181 branches already so the footprint is already paid for/established whereas NSF are taking out new leases when the high street is hurting should get great deals in higher profile sites (next to the charity shops!). The big banks have withdrawn focus from unsecured lending and face to face will retain an appeal for unsophisticated and/or non-standard creditors of whom their are many - not least many of the 15% self employed.
Personally, I think the pawnbroking legacy will limit HAT and I don't like gold so I hold Non-Standard Finance (LON:NSF) as a purer play on sub prime lending with a better set of internally generated leads from its home credit and guarantor lending leads.
FCA warned on consumer debt levels and put lenders who's business model is lending to people who will not be able to repay on watch and general concerns around consumer credit might be impacting prices.
From a regulatory perspective, I would suggest pawn broking is lower risk (regulatory), since it is effectively a sale and leaseback, giving the borrower full ability to not repay (if problem) or back out if collateral value drops from time of pledge.
Personally, I like the company - should have bought late 17 when there was unexplained price fall down to sub 300 (hindsight is a fantastic investment!).
I hold Ramsdens Holdings (LON:RFX) and some serious consideration as to whether to switch to H & T (LON:HAT) on grounds of valuation, although I expect Ramsdens Holdings (LON:RFX) is worthy of a slightly higher valuation given growth outlook
Very much looking forward to Graham's view here and many thanks for covering the company.
Sharmvr, Thanks for response. Below is and article from FCA which seeks to specify who exactly is taking out the extra personal credit and its no 1 insight is " Insight 1: Credit growth has not been driven by subprime borrowers" (EDIT to show end of QUOTE) but better credit scoring people taking out more on credit cards and as carloans. So H&T, NSF and similar are all reporting good lending conditions to top of the bottom as employment is high and min wages increases etc have exceeded inflation in recent years. Full document in FCA authored document at
www.fca.org.uk/insight/whos-dr...
and in a more corporate friendly way in the latest (to me compelling) NSF results
http://www.nonstandardfinance.com/~/media/Files/N/Non-Standard-Finance-V3/reports-and-presentations/nsf-results-presentation-fy2017.pdf
FCA probably also favours face to face formats since these increase the chance under new more onerous requirements that interviews discover whether lender can/will repay - hence separate teatment of home credit vs on line Wonga loans. That said increasing regulation helps ALL the big boys including H&T who can afford to organise to meet requirements
Re Pawnbroking being a lower risk 'sale-and lease back' sort of model I am not so sure. Will probably endure and H&T are now largely unopposed in it as last man standing but feels a bit old fashioned (although moves into pawning electrical items etc may give it a bit of a boost.
Anyway, I think nearly ALL the specialist sub prime lenders are good value at present as the memory of the crash still haunts the financial elite. In truth, well managed businesses in this space have always made good money but are currently unloved. Here's hoping!
Hi Zipmanpeter,
Likewise thanks for the response and the report - I just saw the headline not had a chance to see in detail.
Insight 1 makes sense - I borrowed to buy a car and a watch - hopefully not stupid as needed both - but would have bought 2nd hand had new not been offered on 0% finance, which I assume requires a good credit rating (pat myself on back and thank Mum, Dad and God!) and I am not a big fan of borrowing (made a dent in the mortgage though from this, which does have a cost! - sorry trying to justify my borrowing with this)
NSF results - solid based on my read through - which was I imagine far less diligent than yours - I am weary of Morses Club (LON:MCL) and Non-Standard Finance (LON:NSF) - because of losses on Provident Financial (LON:PFG) - which announced the profit warning the day after my limit was hit!
Given that PFG has been around for however long, it cannot be that unethical and one could argue, lending to people that need it at higher cost is more ethical than the other way around, where it is effectively financial engineering for the most well off with little value to society (but I am not one to judge lenders or borrowers).
As you say, all specialist sub prime lenders are good value and have been keeping an eye on the sector (including Non-Standard Finance (LON:NSF) and £HAT).
Do you have any thoughts on Morses Club (LON:MCL) vs Non-Standard Finance (LON:NSF) - I could argue that Morses is the safer bet (valuation and debt/equity)
Pawnbroking lower risk - I speak purely from a regulatory risk perspective - I work in risk consulting (Banks) and our reg advisory guys consider pawnbroking as having less reg risk because the customer can walk away.
Using the Stockopedia tools to compare H & T (LON:HAT) and Non-Standard Finance (LON:NSF) leaves me wondering why the well-informed investors here believe NSF is the better investment, when the computers rank HAT better on almost every heading and NSF has high and growing debt and recent broker forecast downgrades.
I'd welcome enlightenment, as I have no position in either of them.
Re Non-Standard Finance (LON:NSF)
Site emphasis is DYOR which I have done for myself .....and this is now very clearly my most divergent position from Stockopedia alogrithms as well one of my largest! However, this is probably where most money is to be made if I am right. But I would really, really welcome company specific concerns since this is such a large position for me now.
My personal view is that Non-Standard Finance (LON:NSF) is lowly rated because still new (IPO n 2015) in unpopular area (sub prime) and growing fast. (Stockopedia rightly highly values historic data but not the future) . This works except when there is reason to believe the past is not a true reflection of the future. Like with a relatively new company. H&T chairman I think said he wished his debt was increasing faster as this would mean they had good places to lend. I think NSF has found those growth markets. So losses are occurring AND CURRENTLY GROWING on a statutory basis due to big investments now that should repay in about 1-2 years. Crucially, all of these investments appear to be working out well for now.
Non-Standard Finance (LON:NSF) have 3 niche face to face sub rime lending businesses. All of them are now growing at an organic rate of >20%
i) Branch lending (Every Day loans 24-299%) - Already clear no 1 with rapid retail roll out of proven face to face concept. Other banks retreating. Online does not work well for non standard customers who include the self employed, those with county court judgments as well as those with financial problems. (For instance I am an Managing Director recently returned from abroad with a lot of assets but am struggling to be 'seen' in UK as my wife had been paying all domestic bills!). Each branch is said to lose about $175K over first 18months in set up costs before delivering $300 pa per annum. Took on 34 branches in 2015, now at 53 with 12 more in H1. So big upfront loss visible now for jam tomorrow. Highly credible roll out plan with internal promotions of Asst Branch Mgrs freeing BMs to open new sites, best practice supervised by Area Mgrs - old school but effective
Business 2: Home Credit (interest 164-733%. Now clear no 3 (+/- 9% share) in market consolidating to big players under FCA pressure and ever more regulation. Behind only Provident (50%) and Morses Club (20%). Paid £82.5Mn for a Home Credit business in July 15 but gifted a business about 40% of this size for a total one off investment £5-7Mn in 2017 when Provident decided to ditch agents and go for fully employed collectors. Chm was Providents Chm until 2013 !! Agents who came across brought all their best customers so impairments are down and lending 53% up in 2017. Simple technology support improving management info now all agents have ipads instead of paper. Short term losses from paying temporary commissions and new low cost offices until rounds up to speed and then very profitable. Provident just announced it does not intend to take back customers/agents as focusing on lower ROA Vanquis bank.
Business 3: Guarantor loans under TrustTwo and George Banco (since Aug 17) for brokers (interest 37-62%). Now clear no 2 with twice the scale of 3rd place and in position to be the alternative to Amigo (est 80% share). George Banco bought when P2P funding had to stop so another stressed seller. Again short term investments (acquisition costs, integration costs) but then very rapid returns.
Funding to support all this growth has been obtained via £260Mn guaranteed loan for 6 years at LIBOR plus 7.5% so no chance of running out of funds before the growth comes. Rate seems high but borrowing at 9-10% and lending at 40 to 200% is a great business as long as you can control impairment. Mgt info now very good and short term loan length means action to raise rates can be taken quickly. Few loans are >2yrs, most are 1 yr or less so can be adjusted quickly.
Management are experienced and incentivised with (relatively) low salaries but big bonuses - especially those with founder shares which only have a big value if the share price exceeds 1.10
Why are analyst estimates low. Firstly they are not so low at 80 & 90s /share vs current 67p/share). This (along with a rapidly rising dividend, already a bit under 4% including buybacks) would be great by me even over 2 years!
Why declining - 12 month forecast has got worse as management has ACCELERATED investment in 2017 and 2018 to take advantage of opportunities ......it is 2019 and especially 2020 that the benefit will come through. Since I am an 'owner' not a trader this is OK by me.
I also think that non-standard (new polite term for sub prime) lending has got a bad reputation. Leaving aside the ethics of investing in such companies, I think they are difficult to sell to the public and be on analyst buy lists. But as ever, what matters is the specific company. I think NSF have a winning strategy and are executing well. Their customer scores are high and FCA regulation helps not hinders them (Branch and Guarantor loans are fine, home credit regulations will help the big guys and long term shut many of the smaller competitors.
Long answer - did not intend such but full yr results out this week and just bought some more so argument well rehearsed in my head!
You forgot to mention 90.46% owned by Institutional Investors. Never seen a figure that high before.
Non shareholder. MM doesn't strike until he sees the supply drying up.
Hi Zipmanpeter.
Thanks for your detailed write up on Non-Standard Finance (LON:NSF) . Not a company I’ve looked at too closely in the past although I am a holder of H & T (LON:HAT) and spent quite a bit of my career arranging wholesale finance through the bank and capital markets for sub prime lenders. A quick comparison of the two companies at this link:-
https://www.stockopedia.com/compare/?tickers=LON%3ANSF%2C+LON%3AHAT%2C+
Comparing the two businesses, I can see a lot of attraction in the Non-Standard Finance (LON:NSF) business, especially with regard to product offering and growth. My main concern would be with regards to the combination of aggressive growth when others are pulling back (opportunity and imprudent lending are two sides of the same coin), especially where management and possibly sales employees are incentivised for top line growth rather than ultimate repayment/ profitability (easy to lend in this sector, not always so easy to get the money back) and the nature of their funding.
They seem to be reliant on external funding (rather than their own capital/ retained earnings or some form of deposit base) which is great while the sun is shining but can unravel very quickly if there’s a problem in the business. Although “guaranteed”, the £260m facility you mention will probably have various termination triggers and “protections” for the lenders and I’ve been on the bank’s side of the table often enough to know that when the credit cycle turns (slowing economy, higher unemployment/less overtime, rising interest rates, higher defaults etc.) rugs tend to get pulled from under the feet pretty quickly. This can show itself in a number of nasty ways - for example I once saw an apparently minor trigger in one loan agreement cross default into a company’s clearing bank arrangements/overdraft facility that effectively saw it shut down within three months. Banks will always be your best friend ... until the credit committees decide otherwise (been there, still wearing the scars).
Personally I see sub prime lending businesses as a good profitable nest to put some of my eggs into, but I’d be wary of putting too many of them into a single highly geared, wholesale funding dependent start up that has yet to go through the shake out of a full blown recession. Even the biggest and best sandcastles (GMAC springs to mind) sometimes get whacked when the tide comes in ....
Gus.
Re Non-Standard Finance (LON:NSF) in this case, I think these companies prey on the misery of millions. The tougher times get, the greater the misery, and generally the bigger the profits of operations such as these. I understand the logic for their existence, but they disgust me, and I will not invest in them, nor will I do the same in tobacco companies. Ethics in investing are a difficult subject. There are few companies out there who you would describe as whiter than white, but there are red lines...and we have to set our own.
This is not targeted at Zipmanpeter but merely makes a statement about this sector in particular. I apologise for any hurt feelings, nor do I look for any response to this posting. As I say we all have to set our red lines.
hi ridavies
Agree with the principle, and everyone has their red lines, but have you ever compared the costs of borrowing from these companies to the equivalent costs of borrowing from a mainstream lender? The results are interesting, to say the least ...
The only way this can realistically be addressed is through government action - commercial lenders have to make a return and that means taking into account default rates, which are huge in the sub-prime market. We can see that the profits aren't extraordinary so we know it's not simply about profiteering.
In the meantime the only alternative these borrowers have is far, far worse.
timarr
Drifting off track perhaps, but someone who works in social housing tells me there's one name that always comes up when tenants get into arrears - they will be buying their household goods on weekly payments from BrightHouse.
Yeah, I think Brighthouse got fined last year by the FCA and categorised as an irresponsible lender. Private Equity owned, you can't imagine that's a sustainable model for a sub-prime lender of any kind.
timarr
Not that I understand Burford in any great depth, but those who do, here are a few musings I have and would value any thoughts/suggestions:
Who are the competitors?
I could only find one other listed competitor (IMF Bentham), which is listed in Australia, and has had nothing like the returns (financial or share price) that Burford enjoys - they talk about strong growth and mention Burford Capital too. Sure there are good reasons that I am not aware off.
There must be some private companies / family offices getting involved in this area no given the uncorrelated returns?
The fact that they sold a case well above their carrying value (Teinver), implies that someone is willing to accept lower returns than Burford on the same case (if I understand correctly, or alternatively the certainty of the case is much greater now compared to before)
It looks like they have also funded the expansion of a law firm (does that mean they get preferential access in the event of competition) - surely the law firm is obligated to act in the best interest of clients, and therefore obtain the lowest possible cost of funding?
I wholly agree with Graham re p/b and struggle to justify valuation on that basis. Also, I can't see the lack of competition (unless they buy up competitors) with those kind of returns - that said, googling litigation finance gives you 20-30% return for funding legal cases with no capital risk (sounds way to good to be true).
Im going to do some proper research into company and litigation finance along with reading Mark Minervini's book, since I find it nigh on impossible to buy on charts that look like Burford (to my own cost on many an occasion!)
How did other holders get comfortable - any useful information sources?
Thanks very much in advance
Also
Ref J D Wetherspoon (LON:JDW)
Wetherspoons shareprice is looking a bit toppy at present bearing in mind how the shareprice of others in the sector are doing (Mars/Greenking - those two do have more debt mind) - they are though delivering to the best of their ability. I probably should sell - but last time i sold out at 370p i had to pay 700p to buy back in (that was several years later mind) - so i guess perhaps this is a proper hold to infinity type share.
If you're able to please comment on XLMedia (LON:XLM) I'd be grateful. I can say something nice about your picture again.... ;-D
Yep, Burford Capital (LON:BUR) still in the boatyard and I am the same - Would buy more, but its already my largest position.
On the note of potential lumpiness do remember that Burford are able (if they wish) to sell on a % of their winnings to crystallize revenue ahead when of the loser pays up, so smoothing out year to year numbers. On top of that there is now greater portfolio diversification and litigation insurance income. A great business.
Thank you
Hello Burford heads!
1) Why does this company have a low to negative FCF?
2) What limits its growth trajectory?
3) Are current op margins (c70%) the norm or a function of its form of high growth?
Thanks
lavinit - you raise a good point and that was one concern I had: negative FCF. But the reason behind it was the reinvestment of the proceeds from investments back into new cases which is also supported by the issuance of a bond. It would appear demand is increasing due to the coverage it is getting and also more acceptance by legal firms and clients to undertake litigation funding. The management are all lawyers and they have provided significant amounts of details in the annual report about the business. They, and the team, are very astute at picking cases that appear to have a good level of success and this is performed during the due diligence that is undertaken.
From what was discussed on the results presentation, the growth appears to be sustainable based on the level of claims that are being put forward.
On your first point about cash flow, it's simply because cash is invested up front and cash returns are generated a couple of years later as the legal cases work their way through the judicial process.
It is something to monitor closely though. They highlight the super cash generation of $362m in 2017, but that's akin to operating cash flow and you need to deduct cash invested into new cases ($570m) to get to a figure which is more akin to free cash flow. After other movements from working capital etc. they get to a cash outflow before financing of over $100m for the year, and since they started trading in 2009 they have now seen cumulative cash outflows before financing of over $400m.
That's why they frequently need to tap the bond markets for financing, despite the nice upwards curve on cash generation they show in the chart ISAallowance posted in post#14.
I am hopeful that at some point, they will reach a 'critical mass' whereby cash generated from past investments will be sufficient to self-fund new investments without having to resort to more debt. However I have no idea when (if ever) they will get to that point, and given they have many years of potential growth ahead of them, it is very possible that this state of affairs could last for years where free cash flow continues to be negative and they finance the growth from more debt.
I would see the limits to growth coming ultimately from 2 main areas:
- limits on the amount of debt they can take on. The existing bond covenants state that net debt must be less than 50% of gross tangible assets. Based on their 2017 numbers that still leaves plenty of headroom to take on more debt for the time being.
- the filtering process for investing in new cases. The investment committee currently gives final sign off to all investments. On one level that is a source of their competitive advantage, as evidenced by their win rate on cases, however it surely presents a bottleneck whereby the committee only has a certain capacity for the number and size of cases they can review. Last year they reviewed 151 cases. Would they be able to review 300 cases a year and still not be spreading themselves too thinly? 500 cases a year? I don't know what the limit is, but surely there is one.
They could of course take on more staff to address that issue, but this is a niche area and would they be able to find individuals of a similar calibre, with a similar level of experience to their existing people? I was hopeful that the GKC principals might have fulfilled that role, but it seems that wasn't to be.
Thank you bestace.
Is 70% a sustainable margin even once growth comes off? Or is their link? I wouldn't think twice about it (in a hunch sort of way) at 30-40%.
May sound dumb, but can they effectively book income before they pay the costs of generating it? I'm not angling at anything untoward here. But it makes me think of investment banking. Very high income and margins but then usually more than the reported margin is swallowed up in staff payments. I'm a little surprised reward like this doesn't come through more with Burford Capital (LON:BUR)...investment banking, high end lawyering...not that far apart. If this were private city practice the senior lawyers leading clients would take 7 figure packages pa and the middle tier pretty hefty salaries.
To answer my own question: Perhaps the thing with Burford is that they are not taking normal high end labour intensive legal fee but upside on a 'tranaction'?
In terms of booking income, I believe Burford Capital (LON:BUR) recognise income either as unrealised or realised. However, a change will only be booked when a concrete event happens eg a judgement, rather than based on sentiment. They indicated on the results call that valuations for on-going cases were conservatively valued.
I think that's what you were referring to in terms of income recognition. Apologies if I am mistaken.
Thanks. Makes sense.
I suppose my questioning is more paranoid....it’s a very high return to achieve. Just lack of competition or first mover sort of thing. Or something odd in the dynamics of quick growth.
My apologies for my questions being rather dumb and simplistic. I should read into it myself obvs!
On margins, yes I don't see why 70% margins couldn't be maintained for the foreseeable future. There is more competition around, but the overall size of the marketplace is also increasing and price is often not the main determinant of winning business.
On salaries, they do have a LTIP in place, and the staff are well paid, but the culture appears to be totally different to that of the investment banking world in that they actually seem to give a s**t about shareholders.
One of the things that put me off when I first looked at Burford Capital (LON:BUR) is that the two main investment principals were remunerated on a hedge fund style "2 and 20" arrangement for investments they made. However that arrangement was unwound 4 or 5 years ago.
Hello Graham,
Any chance of a catch-up with £HAT? I thought the results looked good, but the market reaction has been luke warm. Is it just me or is the market only responding to negatives at the moment?
Hi Andrew, H & T (LON:HAT) is on my list for today. Thanks
Thanks Graham.
On professional matter I have approached a number of these companies and they issue is not the funds but the lack of quality cases. There is a natural growth phase as lawyers and clients start to look at alternative funding. There will be cases that are litigated that previously would not have been but its big cases. I approached them and they were not interested in single case for less than £10m - it was a complex case.... I am slightly kicking myself for not investing. There are lots of other people doing this now. I can name 5 more in the UK. USA there are many many more.However, these are the clear leaders and I think they will start returning cash to investors over the long term.
Graham,
You know who supplies J D Wetherspoon (LON:JDW) - yes it is Conviviality (LON:CVR) . J D Wetherspoon (LON:JDW) may not be in a rush to pay the outstanding invoices and as you point out this applies to many in the sector.
Regards,
Seadoc
Hi Seadoc... indeed.
I can't be the only person here who thinks that he's missed the boat on Burford. Very annoying as I went to a presentation by the company a year or so ago and was very impressed.
On a different tack the version of the Conviviality (LON:CVR) release I'm reading refers to PwC as are when it should be is, and to finding requirements rather than funding. Very poor.
In my opinion, the boat hasn't even entered the port. In fact the boat you're waiting for is still in the construction yard!
Hi Hayashi,
I don't think you've missed the boat on Burford (although obviously DYOR). Exactly a year ago I was in the same situation following the final results - I had heard of Burford but not really looked into it closely until then, and it had something like 3-bagged in the year, I thought I'd missed the boat. After looking into it a lot though I took a high conviction position at £8, and the only reason I'm not buying more now is that it's now my largest position.
There's a quote somewhere I've read that "I've missed the boat" is one of the most expensive phrases in investing.
I'm also glad I read Minervini's book before Burford's results last year - I'm cr%p as a trader, but it's certainly helped me to lose my fear of buying investments at new highs.
I hold £BUR
Re £Burford: I will have a revisit to the story. DYOR is probably an overused acronym..... and particularly in this case. Quite honestly I don't know how you can research this....you simply have to buy into the management or not. Trying to do numbers and therefore find a valuation on that basis is virtually impossible. I'm particularly intrigued by the moat here ...areas with high growth/high margins usually attract would be competitors. I recall now that the presentation was at an outfit called Hardman. One of the companies was in cocoa I think and went bust ..one was Burford..not sure about the others.
Hi Graham, I would be interested in your thoughts on Burford Capital (LON:BUR) which released it annual report for Y/E 31/12/17. It provides litigation finance and has generated significant returns which it has reinvested back into the business. In addition it has also entered the asset management space.
I listened to the results presentation and the CEO talked about committing $1.3bn in new business which is 3x 2016 levels. They also mentioned greater acceptance of litigation finance by lawyers and clients (36% in 2017 compared to 7% in 2013). In 2017 there were 1,500 enquiries and after due diligence was carried, 59 investments were closed. In terms of each investment, it represents up to 2% of the balance sheet.
In terms of growth the majority of business is from US but UK & Europe & Australia were growth areas.
In terms of the investments held on the balance sheet, these are held at cost until a concrete event happens before being revalued and therefore the valuation is said to be conservative.
They do have a good reputation in the sector as they have repeat custom in the industry and also have considerable size which offers some economic moat.
However the share price has had an incredible run and I wonder if there is any upside left? The cash proceeds from the wins was reinvested back into the business along with a new bond issued to raise more funds to invest. There is a element of binary risk: you either win a case or lose it. But based on their track record, the win rate is high and the level of returns generated is good. Some of the binary risk is eliminated by setting up an investment management business.
Any thoughts would be greatly received.
+1 for Burford Capital (LON:BUR). There seems to be a disproportionate amount of commentary on the net given the ridiculously good results published on Wednesday.
I think it's an interesting stock because it's a new industry and a lot of brokers simply don't know how to value it, because Burford cannot provide forecasts due to the uncertain nature of their litigation cases. There is a lot of talk of the returns being lumpy but the way I see it, the more cases they take on, the more diversified their portfolio; it's exactly the same with an equity portfolio - the more you have the more diversified and less volatile (!!) your portfolio.
The question of outcomes and hence returns being lumpy is due for revision, The overwhelming majority of Burford Capital (LON:BUR) investments (95% of those made in 2017) are in multi-claim portfolios with greatly reduced loss rates (only 3%!). We need to remember, in any case, that most cases never even go to court but instead are the subject of negotiated settlement.
These extracts from the AR may be relevant on that point:
"Trend towards reducing binary risk continues
Multi-case portfolio loss rate of 3% vs single
case loss rate of 19%"
"The most effective way to reduce the price of
our capital is to reduce the risk of loss, and clients
are enthusiastic about structures that moderate
that risk in exchange for lower pricing. As a result,
our business has evolved significantly towards
multi-claim portfolios and other complex
structures that are more capital protective in
various ways. As an example of the rate of change
in our business, only around 5% of our new
investment commitments in 2017 were in singlecase
litigation matters. In 2009, that number
would have been 100%, and even last year, in
2016, it was 12%. This change has allowed us
simultaneously to decrease our portfolio risk
(our loss rate using the same methodology as
above for investments other than single cases
is 3%, dramatically lower than for single cases),
deploy considerably more capital than
would have been possible if we had focused
predominantly on single cases given increased
transaction sizes and operating efficiencies,
and still produce desirable returns. Indeed, our
returns (net of losses) on multi-claim portfolios are
presently higher than our returns on single cases."
AR, pages 7 and 8.
http://www.burfordcapital.com/wp-content/uploads/2018/03/BUR-28711-AR2017-AW-web.pdf
(Anyway, I'll shut up now about Burford. Please excuse my banging on about it!)
Hi, the actual execution of successful judgments/awards by Burford Capital (LON:BUR) (i.e. actual collection of monies by Burford) will always be lumpy. In large part because the simple reality is that there is often a huge lag between receiving judgment and actually getting paid. This is particularly the case when a state, or state-owned entities are involved, as is the case for some of their big ticket investments. There is also the difficulty in actually finding assets of the judgment debtor to actually collect upon (either they are insufficient, or they have been put out of reach of the judgment creditor); again a huge issue when states are involved. Settlements also play a very large role, but these will usually be at a substantial discount. Another facet that investors may not realize is that damages claims are often inflated to provide a buffer for when a judge/tribunal scrutinizes the claim and applies a forward looking discount (e.g. the investor may put in a claim of damages for US$1bn, knowing and hoping to actually collect half that).
The net result of all that is that it will almost always be impossible to say precisely when Burford will actually collect back on its investment; industry press is probably the best bet for private investors.
None of this is a criticism of Burford Capital (LON:BUR), indeed I have written positively about it before, just an observation from someone who works in the industry. That is why the market will, I think, always struggle to decide what value to give to the company; though I suspect a long term outlook will be rewarded.
That image from the results presentation is the first thing I look for now - cash receipts are still going up lock-step with income, which implies to me that there is no over-aggresive revenue recognition, and no problems collecting cash.
Like Jane I'm prone to banging on about Burford Capital (LON:BUR) but I'll limit myself to saying that their reports are exceptionally well written, explain their business better than I can, and address most if not all of the concerns being raised here.
http://www.burfordcapital.com/investors/financial-reports-and-presentations/
Jane
any insight on why a multi-case portfolio will have a different win rate than a portfolio of single cases?
No, I don't have an answer on that one. The loss rate on multi-case portfolios is only 3%, meaning a success rate of a rather amazing 97%! The loss rate on single cases is 19%, meaning a success rate of "only" (but still remarkable) 81%. I need to look into that. I wonder whether the multi-case portfolios comprise a number of individually smaller and perhaps "easier" cases or perhaps thus cases more likely to be settled quicker and out of court so as to avoid costly court proceedings. Or it may well be that Burford felt confident enough of their own judgement and ability to invest early on in difficult cases, some of which were bound to fail. I say that because, knowing Argentina and South America quite well, there can't have been many lawyers around who would have taken on the Teinver and the Petersen cases and fought them through, apparently successfully. I have asked lawyer friends in Brazil and they say they would have run a thousand miles from those cases! As you know, investment in single cases is becoming an ever smaller part of their business, comprising only 5% of new investment in 2017.
The way i'm reading that statement is Burford Capital (LON:BUR) win on 97% of the portfolios they invest in, not 97% of the cases within the portfolios.
That does sound reasonable if we have 70% of top 100 US firms, just for arguments sake all 70 have a multi case portfolio with us, so even a 3% failure is 2 firms losing money on their cases, they are using us as insurance.
Oh dear. I wrote most of my reply and lost it before pressing submit. Let's try again. Here are a few more thoughts on Burford Capital (LON:BUR) . Please forgive if a lot of what I write is a bit simple and obvious.
1. It is very difficult to make forecasts for Burford Capital (LON:BUR) because it is so fundamentally different from most of the other companies in which we invest
a) most companies makes sales and incur costs. The difference between the two of these (after the usual accounting shenanigans) is reported as a profit or loss. Our ability to forecast future performance depends on the extent to which sales and costs are predictable
b) BUR is more like a gambler betting on the outcome of court cases. And this depends not only on the court judgement (or out of court settlement) but also on the ability (or not) to recover the amount won or agreed
2. BUR's competitive advantage derives from:
a) the shortage of available litigation funding. Many litigators with potentially winning cases do not have the financial resources to pursue their claims. In effect, they have to accept BUR's funding terms or give up on the claim. This allows BUR to set the odds on its bets. In one recent claim BUR recovered >700% on a litigation that it considered likely to succeed. In horse racing the odds would have been evens at best
b) BUR has plenty of opportunity to assess the likelihood of success of the litigation it funds. It assesses the cases in detail. It legal experts can get a good idea of how likely a case is to succeed. A bit like a punter given access to the training grounds who can see how well the horses are running before the race
And, BUR seems to be good at locking in profits even while a case is in progress. On several occasions it has sold on a %age of its potential winnings locking in big winnings even before a case is settled
My only worries are:
A) what happened to Juridica Investments (LON:JIL) , a similar litigation funding organisation. Juridica Investments (LON:JIL) had one year of super profits and then lapsed into losses. I don't know enough about how this came about.
B) whether BUR's ability to negotiate generous odds (high %age returns on the funds invested) gets eroded if/when the availability of funding matches the availability of good (high probability of success) cases.
Disclosure - I have held for several years and have no current intention of selling
My morning smallcap tweet:
Graphene Nanochem (LON:GRPH), Clear Leisure (LON:CLP)
Graphene NanoChem (GRPH) fails to find new nomad*, listing cancelled on Monday but planning a resurrection via a takeover and new IPO. * After 'mutually agreed resignation of Panmure Gordon'. Nothing fishy to see here, move along.
Clear Leisure (CLP) places £300k at 0.7p, a 25% discount.