Small Cap Value Report (Fri 16 Nov 2018) - TRAK, EYE

Good morning!
Obviously the political situation is taking centre stage at the moment. This has been such a long-running saga, that the stock market seems to have priced-in political uncertainty.
How do I see politics affecting the stock market? The chance of a Corbyn Government (a far bigger risk to company earnings than Brexit, in my opinion) still seems very remote, thanks to the fixed term rules. So a Government apparently no longer has to call a general election, even if it loses a no confidence vote.
Nobody seems to like Mrs May's deal. So what happens next? She seems to have an extraordinary ability to stagger on, regardless of anything that's thrown at her. That would be a great plus, if she were actually competent. Having an incompetent, but extraordinarily stubborn & tenacious PM, is surely the worst of both worlds.
Conspiracy theories, suggesting that we're being manipulated into abandoning Brexit, are looking more credible by the day.
The way I look at it, is that chaos is the new normal. We just have to live with it, and share prices have already discounted the uncertainty.
Trakm8 Holdings (LON:TRAK)
Share price: 22.5p (down 65% today, at 13:45)
No. shares: 36.0m
Market cap: £8.1m
Half year results & trading update
Trakm8 is a UK based technology leader in fleet management, insurance telematics, connected car, and optimisation.
Awful results today, have clobbered the share price. Bad luck to shareholders here.
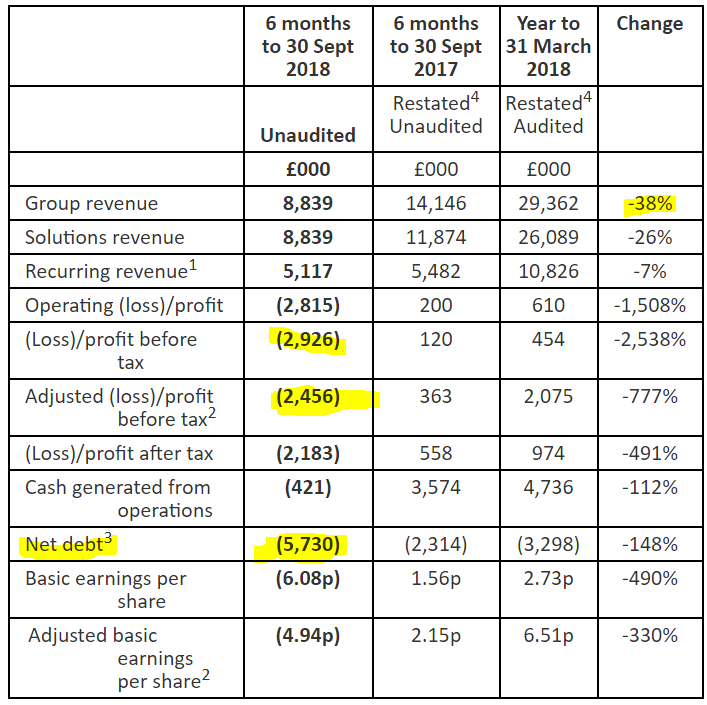
H1 was heavily loss-making, and I think the big issue is now whether the company can survive, given that debt has risen sharply?
I've highlighted the items below which concern me the most;
Various reasons are given for the poor performance - see RNS if you're interested.
Outlook - the dreaded H2 weighting strikes again;
Since the Group's trading update announced in September 2018 it has become clear that the improved H2 financial performance, driven by continued growth in the telematics business, will not materialise as the Group anticipated.
Continuing delays in decisions by customers is preventing the return to the usual levels of success in Fleet and Optimisation, a move to a rental model in the automotive space, and the loss, due to sanctions, of a multi-million-pound contract for the supply of Insurance solutions into Iran, has meant that revenue for the current financial year is now expected to be 20-25% below the FY2018 outcome, and 10-15% below on a like-for-like basis.
The directors expect that while the current year will be loss making, the market for Trakm8's solutions will be robust in the longer term and that the Group's strategy will drive Trakm8's future operational and financial performance; evidenced by contract wins from LexisNexis and an initial two year agreement to supply EE, part of the BT Group, with telematics based services, using its Connectedcare product.
The trouble is, given that the company has previously been over-optimistic in its commentary, that I doubt whether these current assurances will be given much weight by potential investors. It does however give some hope for existing investors to cling onto, should they wish to.
It's a common flaw in many investors, to disregard poor performance, and instead switch to blind faith that things will get better. I've learned the hard way, over the last 20 years, that this is not usually a good position to take. It's usually much better to just ditch any share, if the fundamentals are deteriorating, which is exactly what I did with my TRAK shares, selling in autumn 2016, when performance began to deteriorate.
EDIT: Checking our archive here, I seemed to have briefly bought back into TRAK in autumn 2017, although I can't remember doing that.
Balance sheet - I'm always wary of loss-making companies which have debt. The risk is that banks can withdraw debt facilities, which can result in either a discounted fundraising, or insolvency. The following caught my eye;
- TRAK has £6.5m in long-term borrowings, so investors would definitely need to check out the terms of that debt.
- Recievables of £6.7m looks high, given that H1 revenues were £8.8m.
- NAV is £19.4m, less £20.3m intangibles, gives NTAV of negative -£0.9m - not good, but not disastrous either.
- Development spend of £1.7m was capitalised in H1. Although note that the company receives substantial R&D tax credits. The cashflow notes show that £969k was received in tax, which is clearly good.
- I think there's a heightened risk that the company may need to do an equity fundraising, hence significant dilution could be on the cards for shareholders.
My opinion - based on performance to date, it's become clear that this really isn't a very good business. There seems little visibility, and management assurances are consistently over-optimistic.
In particular, revisiting the trading update here on 12 Sep 2018 , it strikes me as highly misleading in tone, compared with today's awful H1 results. For that reason, I consider this share uninvestable. It's not the first time that management at TRAK has tried to pull the wool over investor eyes - remember the misstated net cash figure in the commentary a couple of years ago? I gave them the benefit of the doubt at the time, but am more sceptical now.
If I wanted to invest in a telematics company, then Quartix Holdings (LON:QTX) (I have no position) is vastly superior to TRAK. It generates pots of cashflow, and pays a 4.8% dividend yield. Whereas TRAK looks financial precarious, and continually disappoints.
Personally I wouldn't touch TRAK unless it sorts out its balance sheet debt, and returns to profitability. Although, having seen the company disappoint so badly to date, it's probably not something I'd want to revisit at all. There just doesn't seem to be any proper visibility, the overheads are too high, management lack credibility now, and the insurance business is rubbish - young drivers want to rip out telematics devices after one years' forced use - nobody wants a spy in the car monitoring how you're driving - that completely removes the enjoyment from driving.
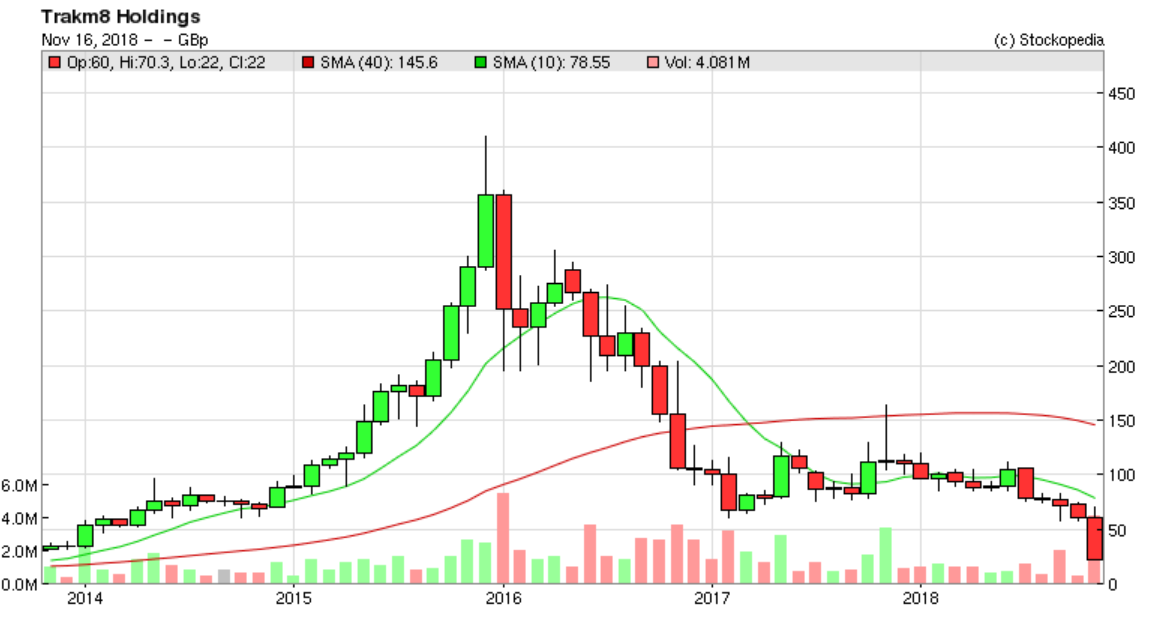
How about this for a 5-year chart;
Eagle Eye Solutions (LON:EYE)
Share price: 128.5p (up 3.6% today, at market close)
No. shares: 25.4m
Market cap: £32.6m
This is an IT company, providing digital vouchers for supermarkets & other retailers to communicate offers to customers.
It's vaguely on my radar, because I like the potential for the business model, and it already has some impressive, big brand clients. Customer churn is low - a key measure for any IT company.
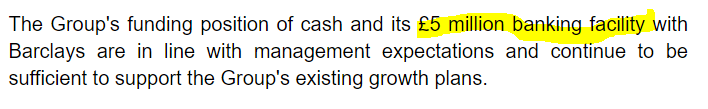
Although I have a concern that EYE does not seem to have adequate cash resources, whilst still loss-making. There is a bank facility, but loss-making companies should not be funding themselves using bank debt.
Today's update sounds generally upbeat, but the conclusion is that it's in line with expectations;
The challenge we have set ourselves this year of running the business 'Better, Simpler, Cheaper' is now well under way and the initial impact of these initiatives, supported by the growth in revenue, have meant that the Group's adjusted EBITDA loss has materially reduced compared to Q1 FY2018.
We remain on track for our move to EBITDA profitability, in line with management expectations.
Expanded markets - it's moving into the fast food sector.
Outlook - upbeat;
The growth in revenues and volumes is expected to continue into Q2 FY2019, from the annualisation of Tier 1 contracts, the impact of new wins and the strong growth of the issuance network in the first quarter.
With our recurring revenue remaining high, at 72% of Group revenue, very low levels of customer churn and an expanding addressable market opportunity, the Board looks to the remainder of the year and beyond with confidence."
My opinion - this company looks potentially interesting.
Most small caps have reduced in price quite a lot in the last few months, and this is no exception. The market cap isn't low enough to tempt me in, but it's getting into more interesting territory, where I could be tempted if the price continues drifting down.
I have to leave it there for today.
Wishing all readers a pleasant weekend!
Best wishes, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

42 comments
There will be pain from this as it is a shock to the system but the projections re permanent damage are bad economics and forecasting. A model that only predicts bad outcomes is a bad model...
I'm sure that's a very comforting thought if you are promoting a hard Brexit, but that doesn't stop it being meaningless rubbish. You are effectively saying no major change can cause permanent damage, since otherwise faced with any hypothetical change no "good" model can predict that any change can lead to a bad outcome!
Hey Peter, you've got me banged to rights...I'm a raving loon...but just since you are here...
I copy and paste the below to illustrate that meaningless rubbish is the topic raised by Peter:
"I'm sure that's a very comforting thought if you are promoting a hard Brexit, but that doesn't stop it being meaningless rubbish."
I now copy and paste an example of meaningless rubbish by Peter as its both jibberish and misrepresenting what I said to assert his superiority...
"You are effectively saying no major change can cause permanent damage, since otherwise faced with any hypothetical change no "good" model can predict that any change can lead to a bad outcome!"
Eh, didn't say that. You too seem to suffer from economic illiteracy and a peculiar lack of appreciation of economic history. I'd explain...but its probably lost on you.
Please specify what in brexit causes systemic permanent damage to UK economic potential. Be specific rather than general and explain how the causal factor extrapolates forever more. There are things that could arise around Brexit to cause this but curious to hear it from you since you are so cuttingly dismissive and confident of your own view.
And, just to keep it factual, I did not promote a hard brexit above or at other times. I voted brexit after reflection and analysis. My starting point was assuming I would vote remain as I have always been a soft EUropean (although how the PIIGS were handled was super stupid and, in the case of Greece, irrational and immoral given they had been accepted into the shared mission).
Give me genuine fiscal integration within a federal European wide structure and I'd quite likely vote to join the euro.
Well, the first post WA draft kerboom is Spanish..."Spain demands Gibraltar Veto in Brexit Deal":
https://www.bbc.co.uk/news/world-europe-46267684
The Irish issue is real. The British may have been negligent in caring about it enough around the referendum but since then the EU with somewhat shortsighted Irish support have played it a bit ugly. it should always been a solution sought in a final deal and never a tool for leverage in pre-deal negotiations and in the WA.
Now the door is open for others to seek leverage and something they want. Spain's first to apply the ratchet.
What if the 27 don't agree to the deal Barnier negotiated? Undoubtedly the Italian govt will play to form and claim that Italian needs should be better considered in some way. And their recent form is that they will not agree unless they get exactly what they want "in the national interest".
The mess is coming...the best thing the UK can do, whether you are remain or leave, is pass this potato back to the EU to see if they drop at this point.
It's a high stakes game and we need to play for the high ground and the leverage it provides. The EU is showing cracks and May is looking stronger. Hopefully May sees this and can stay the course for the moment despite the pressure.
Now the door is open for others to seek leverage and something they want. Spain's first to apply the ratchet.
Not exactly. The UK and Spain have conducted separate talks over Gibraltar throughout the Withdrawal Agreement negotiations. Spain want it to be clear that that status will continue, but the WA is ambiguous.
https://elpais.com/elpais/2018...
The Irish border discussion can't wait for a final deal. The UK wants to close its borders against the EU next March, so the status of an open border with Ireland has to be sorted now. If the UK was willing to tolerate freedom of movement during the transition period then the negotiation could be pushed out.
timarr
BREXIT!!!!
If May gets the withdrawal agreement to parliament it will pass. The last few days have been a great example of what happens when the hot water boils over...everyone has gone a bit off the chain and mental...they could not contain their inner angst and had to give expression to it.
We are now in the cooling down phase. It is irrelevant whether 48 Tories vote for a leadership challenge. It will just be part of the general theatre.
WA passes as when it gets right down to the yes-no decision (with the EU in the background bluffing take it or leave it) party loyalty and whipping goes out the window...it may be that May makes it a free vote as that actually liberates support.
Whether you are remain or Brexit, soft or hard in your disposition, the best thing for UK to do now is pass May's WA. By all means try and adjust the sovereignty interfering backstop if possible before then...and a bit of heat and drama might help it move as the EU has shown some panic at this late stage. Emotionally I think May may have the upper hand at this point as they know the outcome they want is very dependent on her and they must help her stay in the game. Even if the EU wants to win the UK back into the club it knows it cannot risk that play right now. It needs WA signed and then in the implementation period re-marriage can be played for.
Passing WA back then bats it back to the EU. Here's what no-one in UK has got round to thinking about (I suspect maybe apart from the diligent May)...all EU 27 need to agree on it. That is not trivial. There's a high chance of some gamesmanship from Italy, Poland and perhaps the Visegard nations generally. Who's to say that Italy doesn't just link it to their budget and immigration beefs. This is the UK's great hope of actually being able to apply some leverage and from the moral high ground of 'well we held up our end of the deal'.
Personally, I don't like the deal and I voted for Brexit. I would prefer a 'hard' brexit to what is on the table. There will be pain from this as it is a shock to the system but the projections re permanent damage are bad economics and forecasting. A model that only predicts bad outcomes is a bad model...unless we are talking a systemic failure of some sort. If you believe brexit causes isolated UK systemic failure then you've got a lot of explaining to do.
The risk to the UK will be if global capital markets close to it. If they remain open then the UK can finance stress and gaps that come from brexit. It would be akin to an act of war if our neighbours in the EU sought to isolate us as punishment. They will not do this, as its a preposterous position for them to pursue.
mojoword out ;)
Did we give up with the Game Digital report or have I just missed it? T
Unfortunately this thread has to be mainly about politics, as that is the main force driving share prices at the moment. I find the current, unprecedented situation very hard to call, but some things seem clear:
1. There isn't Parliamentary support for May's deal, or for no deal.
2. The EU is set against renegotiation, apart from a little polishing of May's deal/turd perhaps.
3. The Tories really, really don't want a General Election at the moment.
Some possible outcomes after the deal has been rejected
1. Norway style deal
2. a second referendum
3. MPs are so scared by the market reaction to the deal being rejected that they approve it the second time around
Hi dodge
I've just finished reading the damn thing, or at least skimming it ... the big issue for me is the transition period - we end up taking EU laws but not having any say, and paying for the privilege. At the end of the process, if everything works as expected, we do end up with a proper Brexit, but there's all sorts of issues to overcome to get there. And the backstop veto, while understandable, is a threat hanging over any future trade deal.
The only conclusion I can draw is that the government thinks that without such a grace period we don't have the resources or institutions to function as an independent nation. After 50 years of integration with the EU that's probably not entirely surprising, but deeply worrying.
Personally I think the Tories should hold off on a leadership challenge, let the Brexit Bill fail and then depose May. If she wins a leadership vote before that she can't be challenged for a year, and she's stubborn enough to try and ride it out. Although I can't believe I'm saying this, I think the best thing for the country is to put the Brexiteers in charge - at least then, if they fail, there'll be less excuses, although they'd obviously blame everyone but themselves (witness Raab's statement today).
On a personal note my conclusion from this is that Project Fear is probably more real than I'd thought, and I'll be addressing that by adjusting my asset allocations over the next few weeks.
However, the sun is shining and we won the cricket. There are always reasons to be cheerful, whatever the political weather.
timarr
Since it's the weekend ....
On the NI and the Union question, the irony is that the single thing that would most accelerate moves towards the NI leaving the Union would be a hard Irish/NI border. There's no chance of NI voting for Irish unification at present as there are plenty of catholics who are quite happy with things as they are. Undermine the economic links with the republic and inhibit free trade, and that would be likely to change - and quite likely not only amongst catholics. With a hard border NI would be a remote outpost on the fringes of the UK (as it was in the past, pre EU and the Good Friday agreement) with a failing economy.
The DUP represent a minority of a province that voted strongly for remain and the thing that would do most to preserve the Union, both with NI and Scotland would be to stay in the EU.
I must confess that I had never looked at Eagle Eye Solutions (LON:EYE) before, but reading Paul’s write up couldn’t help but think to myself, “this is going to be a sucker stock surely”.
An lo and behold, when I looked , it is.
This is not to automatically demean it as a potential investment some story/sucker stocks do come good, but so few that you really are looking for a needle in a haystack trying to find them.
Purely on the factors Eagle Eye Solutions (LON:EYE) is far from the worst sucker stock you will ever see.
Quality and Momentum are actually not that bad.
The Quality Rank is held up by the high Gross Profits to assets
As a “software company” though it should have virtually no COGS so it is not hard for this ratio not to look positive; especially if the company has very little by way of assets. The rest of the components of the quality factor are pretty poor, to be expected as it has yet to generate profits or cash.
The Momentum Rank again is held up by a single component, this case “scaled earnings surprise”, ie they have overachieved against market expectations in the past. This is potentially more positive in my view, but as they are now only “in line” then that may not be a pervading measure.
Value Rank is poor as we might expect for a company yet to make any profits. However, the Price to Book ratio is also significantly adverse at 5.19x. Bear in mind that I believe this ratio operates off Book value (NAV) rather than Tangible Book Value (TNAV) and that at the last count (June-18) of the NAV of £6.4m, Intangibles were £5.5m.
In reality therefore were are looking at a Price to Tangible book value of an eye-watering 37x. They would surely need a massive moat to justify that and I just don’t see it.
From what (very little to be fair) I have read, it does not sound to me that there offering is especially novel or hard to reproduce.
In fairness though I could say that neither was PayPal’s offering especially clever, but they still achieved massive market strength.
I’m not sure if Paul routinely reads ‘after the event’ comments on the threads, but if you are looking in Paul; I would be really interested to hear what you see that I do not – I know that in the past you have often seen potential that has escaped me, but in this case I’m struggling to see it as anything other than a ‘dog’.
Paul does in fairness highlight whether they have the cash to get through to profitability and questions whether they should be taking on debt at this stage. Looking again at the accounts they burned through £3.3m of cash in the year to June 18 and were therefore left with net cash of £0.4m and headroom including their debt facilities of £5.4m.
The fact that there June numbers feature c. £1.5m of Gross cash and £1.1m of Gross debt suggests to me some complexity in their accounts and that the current “headroom” amounts to little more than a year unless they achieve a material improvement in cash generation.
I love that the SCVR often causes me to take a look at stocks that otherwise might not hit my radar and this has been a fascinating one just to take a high level view of. I will definitely be looking out to see how it does (if I don't add it to my shortfolio first) but if I have missed an obvious attraction here I would always welcome additional input.
I may be in the deep minority here but I am impressed that Ms May has kept her nerve and worked tirelessly to square an impossible circle. We have voted out but that had decision no structure it is ridiculous (nor within our interest) to just leave without an agreement.
Lets take a tiny example; there is a very convenient arrangement currently, which in the event of your illness in Europe, allows your NHS cover to pay for local help. We can reject this or ignore this in which case it fails, or add it to the vast list of things that need to be covered by a new agreement, There is no requirement for Europe to continue this, they might just find it easier to ignore it. But it is in our interest (and not necessarily theirs) to come to an agreement. (I do not know if these is even part of the agreement but I hope you get the example).
Multiply all these tiny areas of agreement and getting a new set of agreements is both hard and necessary and I don't see a flag waving Boris or Jacob R-M putting the work tin o resolve these problems. So my thanks go to Mrs May for the continuing effort
Well said. Love or hate Mrs May (and I've never been keen on her) she has taken on Mission Impossible. Brexit was always going to be a farce because no matter what was agreed, a lot of people would be upset. Remain - had one definition and was clearly understood. Leave - has thousands of personal interpretations which is why no matter what the Brexit deal will be a lot of Leavers will be upset about the deal.
Hi Aislabie.
I appreciate Stocko is not a forum for political comment, but agree with your sentiments. Likewise, I’ve no strong pro or anti Brexit position (I voted to remain but will accept the majority decision to leave) but having started out on the journey feel it has to be in everyone’s interests to get to the end of it.
The post Euro membership referendum role of PM was always going to be a poisoned chalice (why do you think David Cameron exited stage left ASAP?) yet so far Ms May has not succumbed to the Hemlock. Coupled with the failed attempt to get a workable (i.e. non DUP dependent) majority in the Commons in last year’s election, she’s in a pretty near impossible position of trying to build a consensus where none exists. Add to the mix a combination of external political opportunism from the other parties that will benefit from the Tories tearing themselves apart and the internal fractures from the likes of Jacob R-M (perhaps on principle) and Boris J. flip-flopping his position for his own long term leadership ambitions like he’s in some some Oxford Union debate chamber and there’s a sad inevitability about the current mess.
Whatever Faustian pact May has had to enter into with Gove and Fox to keep them in the Cabinet will play out over the coming weeks and months but to date all credit to Ms May for showing more cojones than the rest of the chinless wonders in Westminster put together. I suspect it will cost her her premiership (perhaps as soon as next week) and just hope it doesn’t cost her her health, but of all the players on the stage she seems the only one prepared to roll up her sleeves and try to do what’s required to get the job done.
Gus.
Some kid had a sticker in the back window of their Corsa last night - "I hate this black box more than you hate how slow it's making me drive".
Made me chuckle.
I do know a middle aged guy who, on getting 9 points, chose to have a black box fitted and regularly reads his driving report. Don't know if they can normalise this behaviour, needs a lot of marketing...
Just a note on this from Paul - it's wrong:
If the government loses a motion of no confidence then an explicit vote of confidence must be held and won within the next two weeks or we go to the polls. The two week period is to allow an opportunity to form a new coalition - which is unlikely in this case, as no one else will support the Tories and the DUP hate Corbyn.
Essentially the Tory government depends on DUP support - and if they go off in a huff, as they seem ready to do at the moment - then the only thing stopping a General Election is whether Corbyn actually wants one. He might judge it'll be easier to wait until the Tories infighting sees them collapse completely and we fall out of the EU with no deal. Even assuming a lot of the stories circulating about the chaos no-deal will cause are rubbish there'll obviously be a bit of dislocation, and that point might be the obvious time to strike.
I'd still rate the chance of a Labour government in the next year at no more than 30%, but a year ago I had it near zero.
Interesting times indeed.
timarr
I don't think that's quite right. There is a difference between a party having a vote of no confidence in their leader and the House of Commons having a no confidence vote in the government.
In the former the party is changing its leader and has absolutely no obligation to go back to the electorate. In the case that May lost the confidence vote a leadership election would ensue and the new leader would be PM. Unless the Conservatives decided to then call an election none would take place.
The latter can occur if someone calls for a no confidence vote in the House. That is no confidence in the government, rather than the PM (even if it is implied). In this event an election can occur as you describe. However, as the Conservatives have sufficient seats, even the DUP voting against would not get them over the line. You would need Conservative MPs to also vote no confidence in the government and that won't happen especially as Sinn Fein do not take up their seats or vote. In any case the DUP would not vote against though they might abstain in protest. The last thing they want is a Labour government, irrespective of what they may think of the current PM.
Labour themselves have pretty much said that an election won't take place, which is why they are now calling for a peoples vote on the outcome.
Anyway, all in all a "sh**show", but then that was pretty obvious right from the start, when the only option was "in" or "out"........talk about complacency!!
There is a difference between a party having a vote of no confidence in their leader and the House of Commons having a no confidence vote in the government.
Agreed. Paul's comment, and my response, was on the government losing a no confidence vote, not the PM, which is entirely a matter for the Tories. Also the Conservatives can't call an election unilaterally, they need two thirds of MPs to agree, that was a change made under the Fixed Term Act.
I think you're wrong on the numbers. Note that they don't add up if you look at the standard sites because there are 2 Tory, 5 Labour and one DUP MP's listed as Independent for various reasons. They all vote along party lines most of the time.
There are 650 seats and Sinn Fein don't take up their seats so there are 643 sitting MPs - and, therefore, 322 votes are required to win if all MPs vote. The Tories have 317 seats and would therefore lose.
If the DUP abstain, rather than vote, then there are 633 votes on offer, 317 are required to win and the Tories would therefore win.
Note that the Speaker doesn't vote unless there's a tie when, by convention, he's expected to favour the status quo.
In addition the Tory Craig Mackinlay is on trial for filing false expenditure claims and Labour's Fiona Onasanya is on trial for perverting the course of justice. If either are found guilty they'll have to resign.
At the margins every vote counts and sheer circumstances can cause accidents. The last time a sitting government fell on a vote of confidence was in 1979 when the then Prime Minister, Jim Callaghan, decided he wasn't prepared to allow the gravely ill Labour MP Alfred Broughton to travel from hospital to vote even though he was willing to do so. Broughton died shortly after.
In the event of a no confidence vote expect it to get nasty. The last time voting was really close - on the EU withdrawal bill - the Tory whips broke pairing rules and forced ill and heavily pregnant Labour MPs into the House to vote. It's unlikely to be forgotten if the Tories need a favour next time round.
timarr
There is zero chance the DUP will abstain rather than vote down anything they see makes NI less of a part of the UK, so they will never let the current deal ()that appears to align Ni with Irish/EU regulations more than UK ones) get the slightest chance of success.
PS the Tories didn't break pairing rules, there was only 1 pair available, so Labour MP Cat Smith was given the pairing, the others then had the choice to come in or not - and came in. What was dodgy is that they usually let MPs like that vote without having to come in in person. Its still an example of how hopeless May and her whips are. Don't give a damn about the MPs welfare, or the electorate's decision to leave, or I'd say, anything else that isn't exactly what they want.
This constitutional stuff is getting a bit off topic, but I suppose it's the weekend ...
There is zero chance the DUP will abstain rather than vote down anything they see makes NI less of a part of the UK, so they will never let the current deal ()that appears to align Ni with Irish/EU regulations more than UK ones) get the slightest chance of success.
Agreed. Back in the old days if the Brexit Bill had failed we'd probably (*) have had a General Election, as it would have constituted a vote of no confidence. Now you have to have a separate no confidence vote so the DUP could vote against the government on Brexit but for them on a confidence bill.
On the pairing thing the Tories did break pairing rules. Brandon Lewis was paired with Jo Swinson, didn't vote for most of the day, but then did on the critical amendments.
For what it's worth I don't think the deal is an attempt to undermine Brexit, it's just the best our bunch of hapless politicians and negotiators can produce in the time available. The overwhelming impression is that our leaders aren't really used to managing change and really don't know what they're doing.
Just in the past few weeks we've had Raab discovering that 17% of our imports come through Calais (note, Dominic, more come through Rotterdam), Bradley uncovering the astonishing fact that NI citizens religiously vote along Unionist / Republican lines and Caroline Nokes explaining to a bemused Home Affairs committee that the app to allow EU citizens to apply for permanent residence doesn't work on iPhones (**). Before that David Davis hardly ever visited Brussels, let alone negotiated, and Boris Johnson's main contribution to foreign affairs was to condemn poor Nazanin Zaghari-Ratcliffe to an extended time in an Iranian prison.
Oh, and the arch-Brexiteer MP Andrew Bridgen apparently thinks that all UK citizens automatically qualify for Irish passports (do go find this on the RTE website, it's comedy gold).
timarr
(*) "Probably" because our constitution is actually held together by tradition and sticky-backed plastic. It's malleable, which is one reason it's survived so long.
(**) The official advice is to "borrow a friend's Android phone". Nokes blamed Apple but this is functionality we've wanted Apple to enable for 5 years or more. They haven't for their own business reasons so the likelihood of them changing this globally just for the UK government was always vanishingly small. Heaven knows how much this has cost, they've employed no less than 6 consultancy firms to design the solution. Thank goodness we don't have to rely on technology in other areas to deliver a smooth Brexit.
I'll agree the deal is hapless politicians being even more useless than before. But have you read the Spectator's story about it?
Apart from the usual points on giving up sovereignty for decades, there's 2 interesting extras sneaked in there:
1. No former or current MEP or EU employee will have their salary or pension taxed.
2. No MEP or employee who has criminal charges brought against them can be prosecuted.
https://blogs.spectator.co.uk/2018/11/the-top-40-horrors-lurking-in-the-small-print-of-theresa-mays-brexit-deal/
I'll agree the deal is hapless politicians being even more useless than before. But have you read the Spectator's story about it?
Generally it's a pretty hopeless article - most of the points being made are the kind of errors laypeople make when substituting legal exactitude with commonsense. For instance:
Well duh. Are we going to enshrine UK Law in an EU treaty? Isn't regaining sovereignty the point?
Once we leave we decide what access we give the EU. The article is full of such substitution confusion, along with an array of statements that seem to confuse the transition / implementation period with the final divorce.
On the two specific points about taxation and criminal charges: this is about maintaining the rights accrued to people while we were in the EU. If people earned money and were told at the time they wouldn't be taxed on it or performed services and were told at the time they were immune from prosecution then those rights are protected under the withdrawal agreement. It's a basic tenant of any legal system that people shouldn't be taxed retrospectively or prosecuted on the basis of laws that weren't in force at the time of the offence.
And on this:
Well, firstly this applies for the implementation period only anyway, but second if we arbitrarily withdrew from this every single company in the UK that hosts EU data would have to leave - and that's a lot of companies. And as for useless - frankly, it's the best thing the EU has ever done for us.
Anyway, as with any report, on either side, we need to look at the source. In this case the Spectator is owned by the tax exile Barclay brothers, who also own the Telegraph. And, of course, among its former editors it counts one B. Johnson. Probably not the most unbiased source of data.
But in the end, everyone has to make their own mind up. Rather than reading ideologically inspired op-eds I invite everyone to read the actual text themselves and make up their own minds:
https://ec.europa.eu/commissio...
timarr
Could I second the request to have your views on NXR from yesterday please
Trakm8 Holdings (LON:TRAK) breaks one of my cardinal rules - don't invest in companies with silly names. Investing is a serious business. There are thousands of investment opportunities out there so why on earth would anyone put their money into a firm whose name sounds like something two fourteen year olds would text to each other?
Your cardinal rule of 'not investing in companies with silly names' doesn't seem foolproof, saxman.
The worst three performers in the FTSE All Share in the last year are : Carpetright, Countrywide & Debenhams - all of which appear to have less silly names than the best three performers : Ocado, Evraz & Nanoco ?!
remember GLOBO ?
Paul, I appreciate it is a tricky one but do you have any views on price movement in FCCN since they announced they are putting themselves up for sale? The price has been underwhelming I would have thought. Currently 52p mid. 1) Would we have expected some news several weeks on? How long would something like this take to establish whether there is an interest given they have been in the same industry and therefore are probably fully aware of the co. 2) Looking at bal sheet I can get to an asset value around 38p. Given some goodwill for share price 50p may be a sensible offer? 3) Given the turmoil in share prices this is a good time to buying NOT selling. All in all I am interested to know if your £1 to £2 valuation is moving at all? Best wishes and thanks for the insights you continue to give us all.
Hi Camtab,
I don't want to speculate about French Connection (LON:FCCN) . There hasn't been any news from the company, so the share price is just moving around in a vacuum, driven by low volume, small trades.
As far as I'm concerned, nothing has changed. The company is up for sale, with we are told, 4 interested parties.
As regards timescales, this is what the company said on 19 Oct 2018;
What I like about this situation is that we already know the company's performance is improving, due to strong wholesale division, and gradual closure of loss-making shops. Apparently there are 3 massively loss-making shops due to closure in the next couple of years, which should be transformational for performance. So even if a bid doesn't occur, the fundamentals should strongly improve over time. So a nice each-way bet, in my opinion.
Regards, Paul.
Good to hear from you Paul. It was a fishing question really wasn't really expecting a response from you, but thought one or two of the others may throw something in. I can totally see your argument, my only real nervousness arises from the state of the market and the state of non internet retail at present. Have a great weekend.
Paul,
MYSL?
regards,
Jonathan
Neary's July comment on TRAK was right on target.
"Neary's July comment on TRAK was right on target."
Quite so - I couldn't decide whether to comment on it here or on the original thread, so I have done both!
Trakm8 Holdings (LON:TRAK)
When this article was written (2-July-18 with the share price at 94p) Graham wrote :
Roll on to today 16-Nov-18, the profits warning duly arrived, but with the shareprice down 62% on the day to 22,5p (down 75% from the July price) I think we can safely say that the profit warning was not previously priced in.
Something I have learnt over time is that it is a dangerous game to suppose that the bad news is "all in then price" (I don't mean to suggest that was what Graham meant in this case). Often times the news may be worse than presumed (as was the case here) or that having digested the expected bad news the market will proceed to price in further bad news.
I am losing count of the number of "H2 weighting" predictions that have failed to transpire.
Hi Paul, did you cover LON:NXR trading update yesterday ?
I cant find a link to yesterday's report..if not perhaps your view today.
Overall it was steady as she goes , with Merlyn bedding down and the tile division returning to profitability. I do find it reassuring when the problems which are identified by the ceo are dealt with as proposed. I was surprised by the size of the pension deficit reduction on such an apparently small move in the discount rate, but am unsure of the implications of the Lloyd's pension ruling. [I hold]
Enormous congratulations to ShareSoc who won the Investors Chronicle Editor's Award for services to Private Investors. This is highly deserved, not least for what they achieved for Beaufort Securities clients. The Directors give their considerable time and expertise, voluntarily. We are really lucky to have them
Whilst acknowledging ShareSoc. Here's two presentations from their November London event. (These events both in London and elsewhere are really worth attending).
Pelatro (LON:PTRO): IPO'd at the end of last year. A very confident presentation, which gives a great overview of the investment case. The first they've given to PIs.
https://www.piworld.co.uk/2018/11/15/pelatro-ptro-sharesoc-presentation-november-2018/
Ilika (LON:IKA): cover solid state battery technology. Their products. Their business model. The finances. The Government funding they've received for the Faraday Battery Challenge. Their milestones.
https://www.piworld.co.uk/2018/11/15/pelatro-ptro-sharesoc-presentation-november-2018/
One more presentation to follow is Forbidden Technologies (LON:FBT)
Again, well done ShareSoc!
I broke two of my rules when investing in Hutchison China MediTech (LON:HCM) some years ago:
The first: do not invest in development pharma companies because I really don't know how to value their prospects (and often I am not sure they do). Todays news from HCM of the failure in Phase III of a headline drug, confirms why I should have taken this rule more seriously.
The second: Run your profits - which very fortunately I didn't on this occasion, having top sliced a couple of times. But still a 16% drop today is no victory
HCM still has profitable business, it is not a one trick pony, but failure at Phase III is always expensive.
My education is always expensive!
The Trakm8 Holdings (LON:TRAK) profit warning in the interim results has resulted in over a 60% share price drop. Whilst group revenue has dropped 38% to £8.8m, operating profit last year has turned into a operating loss of £2.8m. Debt has also ballooned from £3.3m to £5.7m. This is approximately the same as the market cap.
The company has £2.0m of cash at 30/9/18 but used £1.5m during the period.
It talks about investing in expanding manufacturing capacity. It does not appear to have taken place in the period and perhaps is an expense to be aware of in the future. It is not apparent how much investment is being planned.
The outlook statement details the deterioration in H1 performance since the September trading update appears to contradict the statement of "strong levels of orders, post period end, from existing and new customers".
I would be interested to know the customer churn; whilst TRAK claim to be winning new clients, they also appear to be losing clients. All this will also have an impact on recurring revenue.
EAGLE EYE AGM Statement today, Q1 Revenue growth of 26% and narrowing EBITDA loss. Paul, you reviewed them in January and saw potential. The share price was 224p then, now it is 130p. Also announces high calibre and relevant experience NED joins today.
I have been watching them and have taken the plunge and bought shares today. Paul I would be interested in your view, you did say you would review again.
Thanks to you and Graham for the great work. I normally read SCVR twice a day.
Here's the recent Eagle Eye Solutions (LON:EYE) results presentation:
https://www.piworld.co.uk/2018/10/10/eagle-eye-eye-results-presentation-october-2018/
You get a good feel of the CEO, CFO, the company and their vision going forward.
Thanks for sharing the PIworld presentation about Eagle Eye Solutions (LON:EYE) tomps3.
And yes, you do indeed get a good idea about the people and the business. Whilst watching, I tried to park my prejudices about the CEO, Tim Mason, who helped Tesco lose a fortune in the US with Fresh n Easy. Yes, he was instrumental in the development of Tesco's hugely successful club card but the hubris he displayed at Fresh n Easy is still clearly evident at EagleEye. Not for me.
cheers
Francis
There is a Rule 8 RNS this morning from Flybe (LON:FLYB) indicating that several directors have between 612,745 and 1,470,588 shares under their performance plan with an exercise of 1p. ONE PENCE!! That seems crazy to me. I wonder what the terms of the performance plan are....
My morning smallcap tweet: TRAK driving with no visibility.
Trakm8 Holdings (LON:TRAK), £AD4, STM (LON:STM)
Trakm8 (TRAK) H1 and huge warning only 2 months after an in-line stmt. H1 re down 38% and adj EPS -4.94p (+2.15p). Guides FY rev down 20-25%.vs F/C +9%. Blames delays in decisions by customers, a move to a rental model in the automotive space, and the loss, due to sanctions, of a multi-million-pound contract for the supply of Insurance solutions into Iran. I thought everyone knew about Iran sanctions. Too busy to read the papers? Doesn't guide loss level.
Adept4 (AD4) guides FY rev flat, Trading Group EBITDA down at ~£0.6m.
STM Group (STM) CEO won't be charged by Gibraltar police in the matter of a client's tax dispute.
Trakm8 Holdings (LON:TRAK) - over the summer the UK Government and EU repeatedly assured businesses that they would be supported in continuing to trade with Iran, in the face of US threats. Those assurances melted away pretty quickly.