Small Cap Value Report (Fri 17 Feb 2023) - PURP, CML, WAND

Good morning from Paul!
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul's Section:
Purplebricks (LON:PURP)
9.9p (pre market open)
Market cap £30m
Trading Update & Launch of Strategic Review
Purplebricks Group plc (AIM: PURP), the UK's leading tech-led estate agency business, provides an update on trading in respect of the financial year ending 30 April 2023 (“FY23”), and announces the commencement of a strategic review.
Key points -
Turnaround plan to focus on best-performing regions underway, but has incurred £1.2m more (one-off) costs than planned.
Q3 (Nov-Jan) sales instructions lower than expected.
Additional cost savings of £4m identified.
Fees to customers increased from 1 Feb 2023.
FY 4/2023 guidance reduced: revenue £60-65m, EBITDA loss of £15-20m.
Still expects to become cashflow positive in early FY 4/2024.
No update provided on the current cash position - a glaring omission. There was £31.3m at end Oct 2022, but that was after hefty cash burn of £12m in H1. So I think we can assume that cash is now likely to be considerably less, maybe somewhere between £20-25m? How much of that will be left once the strategic review process has concluded later this year?
Strategic review - is putting itself up for sale, so a Formal Sales Process under the Takeover Panel rules now starts.
My opinion - we discuss de-listing risk here a lot in the SCVRs, which can come about in a good way, if someone launches a premium-priced takeover bid. Or it can happen in a bad way, with companies returning to being a private company, usually at a bombed out price as forced sellers exit before the shares de-list.
PURP has cash in the bank, so it’s not under any immediate cash pressure.
The shares now are just a punt that someone will come along and buy it, presumably for the brand name (with a lot of advertising pounds having been spent/wasted), together with a loss-making, failed business model. It’s difficult to see that attracting much buying interest, but you never know.
I did have this one my watchlist, but will remove it now, because I don’t want to gamble on the outcome of a formal sale process, for a business that has effectively failed to prove it has a viable business model, after a considerable time of turnaround attempts by various CEOs. Some businesses just can’t be turned around, and I suspect this might be one of those.
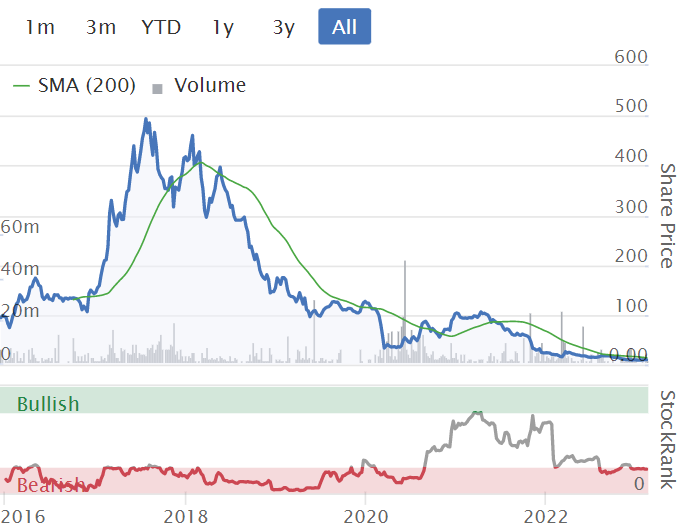
I can remember this one being a very good trade that we caught from 100-500p a few years ago. Although the trick was to sell into the spike, rather than hold on for grim death once the newsflow turned negative. With hindsight, it's interesting how so many "disrupters" have turned into expensive failures, with conventional businesses fighting back. We've seen that in both the estate agents, and car retailing sectors, for example.
CML Microsystems (LON:CML)
582p (up 6% at 08:29)
Market cap £92m
Oval Park is the freehold campus that CML owns, where it has been trying to extract value from land development for many years. I covered it in some detail here in Aug 2022, which was quite fun - using google maps to identify the site, and trying to guess the potential upside value from local press reports of the plans.
This seems to be excellent news -
… pleased to announce that conditional planning approval has been granted at its current 29-acre site located at Oval Park, Maldon….
What are the conditions? I’m no expert on planning applications, but to my untrained eye, this doesn’t sound particularly onerous -
Final approval is subject to the completion of the necessary Section 106 Unilateral Undertakings relating to the payment of a financial contribution towards the County Council's costs of monitoring a Travel Plan. The decision notices granting planning permission should be issued once the Unilateral Undertakings are complete which is expected shortly.
Works are expected to commence Autumn 2023.
My opinion - we’ve reported positively on CML here in the last year. It has several attractive elements to it -
- Core business performing well, and is a high margin niche business.
- Substantial cash pile.
- Further upside from the freehold property - now improved, as planning permission has at long last been granted (it’s been trying for over 10 years!)
I don’t have enough information yet to value the property element, so we need more guidance from brokers on that.
Shares have done very well in recent months, so it’s not such a bargain as last time we looked.
Shore Capital uses EV/EBITDA as a useful valuation measure in its note, and I think there’s a good argument for treating the freehold property like cash too, since it’s a separate asset. That method arrives at a valuation that’s still quite attractive, so I’ll remain green (broadly positive) in my opinion on this share.
WANdisco (LON:WAND) (I hold)
1274p - market cap £883m
Call with CEO yesterday
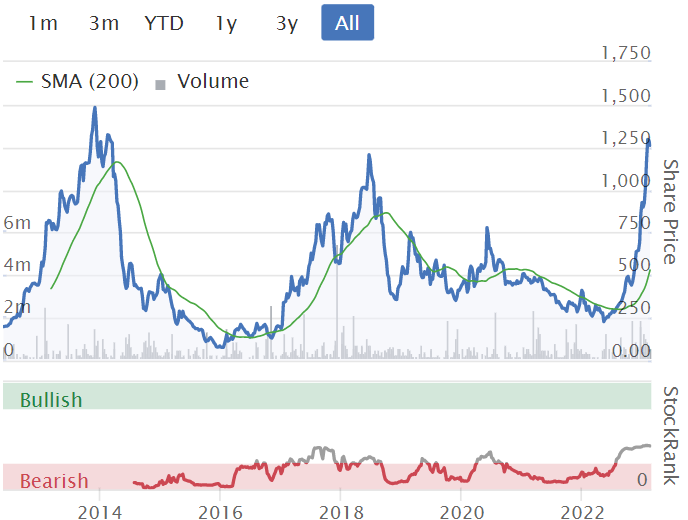
I was pleased to be offered a call with the CEO (and founder, David Richards), as WAND came up repeatedly in the SCVRs from last summer onwards, with a remarkable flurry of big contract wins. This suggested to me that something game-changing appears to be happening. Although my enthusiasm is obviously tempered by the huge market cap, and a historical track record of heavy losses, and several false dawns for growth previously.
I didn’t take detailed notes, but this is the general gist of the Q&A I had with the CEO yesterday -
How come growth fizzled out previously, but you’re now seeing a surge in big contract wins?
It’s all down to 5G - which is just being turned on in USA now. Big companies are now looking for the ability to move data at huge scale. Eg. the automotive industry, each new EV is generating 25MB of data every hour. Monetising that data is what EV makers are looking at for the future. Same with telcos. Data sets at huge scale are arriving, which is what our software is built for. So 5G has created a tipping point for WAND.
Do big contract wins act as references for additional new business?
Absolutely. WAND is proven, and it’s now a question of grabbing market share, we already know who the big customers of the future are likely to be, especially automotive & telcos, but also mining companies.
There were big billings in 2022, but spread over x years? $110m backlog at year end. Can you explain?
Contracts are not set up for x years, they’re “commit to consume”, and half is paid in cash up-front typically.
Has year end receivables of $44m turned into cash? Yes.
Will you need to do another fundraise? No, fully funded, and cashflow positive, due to acceleration in contract wins.
Broker notes only show modest revenue growth in 2023, how come?
Given previous performance, the forecasts are deliberately set low, to be beaten.Don’t want to make the same mistake again of over-promising.
I note from your major shareholder list that there’s a lot of big holders based in USA. Will one of the big tech companies buy WAND?
WAND operates in Silicon Valley, and in the UK - unusual in that regard. Hardly any UK-based growth tech companies, it’s a big problem for the UK. If your gross margin is under 80%, then you’re not a software company. All sorts of companies got floated on AIM that were given a tech rating, but weren’t tech companies! They just have a website, and move stuff around, that’s not a tech company. The City got greedy for fees, and floated anything (I couldn't agree more!)
WAND has 100% gross margins, have resisted the temptation to bolt on lower margin services. It’s a software licensing business, with very high operational gearing.
Not interested in selling the business, we’re building what should become a highly cash generative business, that could make operating margins over 50%. Difficult to think of any other UK company generating the rapid rate of big, 100% gross margin contract wins that WAND is now achieving. That’s what US investors see more than UK investors, but there’s growing interest from UK funds now too.
What about risk? Isn’t there a danger that someone else works out a way of doing this that’s better, and cheaper?
Theoretically that is a risk, but what WAND does is not just desirable, it’s the only way to move around large scale data without problems. Protected by 37 patents, and lots of know-how. It was created by a polymath, so is not something that can be replicated.
My opinion - to say that WAND’s CEO is bullish, is an understatement! That makes it easy for me as an investor - the company has to deliver very strong growth in 2023, in revenues, and profitability, and if it doesn’t, then I’ll sell up and move on. So this is looking binary, with a market cap at almost £900m - which leaves no room for anything to go wrong.
For me, the key point is the long list of recent, big contract wins, with large companies. Are these one-offs? The company says mostly not, and that many of the (smaller) ones that are one-offs are likely to develop into ongoing sales.
Could WAND be a good way to play the explosion of data that is happening now in various sectors? Possibly, I don’t know. There do seem to be some exciting signs though, and the company has never before achieved anything like the latest order backlog contract value. So it does seem to be something game-changing underway here. How to value it? I’ve got no idea, it’s almost impossible to value at this stage.
Note that several large shareholders have recently been adding to their stakes.
I’m tempted to buy more, but whenever I feel excited after talking to a company, I always give myself a 2-3 day cooling off period, before buying any more shares.
As usual, do please post all your opinions below, especially bearish ones, as I probably need some balance after getting hyped up talking to the company!
Just to emphasise again that the above is my imperfect recollection of the broad gist of what was said, so apologies if I got the wrong end of the stick on anything.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

88 comments
WANdisco (LON:WAND)
Paul re your question "Could WAND be a good way to play the explosion of data that is happening now in various sectors? Possibly, I don’t know."
That is my main reason for not "investing" in WAND. There are reasons for trading in it but in my opinion that ship has sailed.
I have posted at length on previous occasions so will keep it brief.
Wandisco's recent contract wins are from existing users with on premises data centres storing large amounts of live changing data. These customers want to follow the trend of outsourcing their data processing to cloud providers like AWS and Google but have huge amounts of data to move. That isn't the same as saying that new data, from possible new and existing customers, using 5G mobile networks to enable that data to get straight to the cloud, needs the services of WAND.
IMHO, a risky bet on what I think is a zero sum game that I will sit out.
Anyone know if the alert system is broken on here? I keep clearing old alerts (in th top right hand corner) on companies I hav'nt owned for ages but they keep coming back?
Seems to working for me but is annoying of getting alerts for buy price which turns out to be sale price. I have reported this but support don't see the problem. Im also getting alerts for prices well below the sell price sometimes.
Needs improvement, along with the share prices on here which are misleading.
Nothing to do with stocks... but this is going to be so funny if its true!...
https://aviationweek.com/defense-space/aircraft-propulsion/hobby-clubs-missing-balloon-feared-shot-down-usaf
$400,000 of missile used to destroy a $12-$120 dollar ballon! Would the military/government ever admit to it?
...or is it a planted cover up? ooooooo conspiracy'o'clock!
ECO Animal Health (LON:EAH) I hold, been noticing that long time major shareholder (and generally value investors) Schroders have been steadily increasing their holding this month, from 9% to 15.1%
ECO Animal Health (LON:EAH) Strange this is not reflected in the volume of shares traded, unless it was spread over several months. The last director buy is missing from Stockopedia, maybe that problem is back again, I did notice it on another stock as well.
Quite a lot of exposure to Chinese pigs, I understand.
c24% of rev is from China.
OK, not as much as I thought.
Indeed, the amount they have bought is about 4 mil shares and according to London Stock Exchange there's been under 3 mil traded since start of year. I suspect the 2 1/4 mil that Daske sold were bough by Schroder off market.
M&C Saatchi (LON:SAA) So just who is doing the buying here then ? up and up she goes
MS International (LON:MSI) are flying today on no news. Does anyone know why - has it been tipped somewhere?
MS International (LON:MSI) David - I - almost - pine for the long boring months at 320p :-) It does seem to be more volatile nowadays.
I've not heard that its been tipped today though I did notice that 22k were traded in 1 hour today and the daily average is only 11k. Immediately after that the price spiked on low volume. I expect the market makers ran out of stock?
The free float is only 45% and in realityis much smaller than that. A lot of investors have held the stock through some thin years and are not in a hurry to sell? It doesn't take much stock being bought or sold to move the price 10% either way at the moment?
cheers
Mark
EKF Diagnostics Holdings (LON:EKF) - just sold £9mn or the shares were bought on the cheap by an II - likely to be the former - but book is looking much better.
Water Intelligence (LON:WATR) - Has anyone got any thoughts to offer on the relentless drift against the general market trend in '23?
Understood that this just happens sometimes for no fundamental reason.
IMO, market sentiment. I was in Water Intelligence (LON:WATR) only recently. Amongst others, similar sell-off has taken place with Best Of The Best (LON:BOTB) , Tristel (LON:TSTL) , Kin and Carta (LON:KCT) , Auction Technology (LON:ATG) . Water Intelligence (LON:WATR) doing pretty good, solid TU, but peeps are nervous.
The last trading update Revenue increased by 31%, but only 3% PBT increase, but that seems to be because of large payment to Salesforce. Brokers forecasts were revised down recently. I do hold some Water Intelligence (LON:WATR). I think it is ok, some costs in a new system, have dented the profits, but these payments will be ending soon.
I listened to an interview with the CEO of Purplebricks (LON:PURP) a while back (available here - https://pca.st/enakvd0y) and one of the things that really stood out for me was that they had appointed a CEO with absolutely zero experience in property and estate agents. Completely put me off any thoughts of investing.
I'd really like to filter for companies where the CEO is actually an expert in the industry or an expert in the technology the company is using - and has either the innate skills needed to be a CEO or has learnt how to be a good one.
Maybe this is less important in larger businesses as it's much more about managing a large team. But it feels in small companies that the CEO's job is a lot closer to the coal face.
Absolutely spot on. It does surprise me that in all these analyses of small listed businesses the emphasis is almost wholly on the metrics and numbers. Very little attention seems to be paid to the quality of the senior management team. Which in my opinion is probably the most important factor in determining the likelihood of success.
Absolutely spot on. It does surprise me that in all these analyses of small listed businesses the emphasis is almost wholly on the metrics and numbers. Very little attention seems to be paid to the quality of the senior management team. Which in my opinion is probably the most important factor in determining the likelihood of success.
I don't understand how you've come to that conclusion. Quality of management is something we think about & discuss a lot here. But its so subjective, that's the problem. Think about all the time "impressive" management turn out to be useless! A few examples - RBGP. Then there was Edi Truell at that software company, who pompously turned up to ramp the shares and made us all feel as if we were honoured to be in his presence.
That's exactly why I like hands-on, down to earth entrepreneurs, with plenty of skin in the game, who just get on with the job. Not fancy city types. We talk about this exact point all the time here!
None of the SCVRs I have ever seen give an appraisal of the capability of the senior executives at the same time as reviewing the numbers .. Unless it is after the event and things have already gone badly wrong. In which case its easy to point the finger.
One way to view the value of a company - is to imagine a scenario - if this company ceased to exist tomorrow, will it cause any pain to the market it is trying to serve?
For example you could look at Apple (NSQ:AAPL) and say yes - their products are loved and in many cases, substitutes will not be as good for their customers that use it.
But when you look at Purplebricks (LON:PURP) there are others that do similar low-cost pricing, and hundreds of other traditional estate agents that sellers can sell their property through. If it disappeared tomorrow, the house sale market will not be impacted one bit at all.
Thanks, Boon. Nice thought, "if this company ceased to exist tomorrow, will it cause any pain to the market it is trying to serve?"
I will try to apply it, as I am wondering whether to increase my holdings in International Personal Finance (LON:IPF) and Civitas Social Housing (LON:CSH) . I suppose little is indispensible, but both appear to have value to a chunk of people.
...And said CEO had been made bankrupt some years prior.
Hi iamflimflam1,
Yes, I agree - I also listened to the CEO interview from PURP on 8 Nov 2022, and thought she was hopeless. I recall mentioning that in one of my podcasts. All she did was talk about process, and didn't seem to have any industry-relevant flair or experience. Just someone with HR experience, talking about her personal career journey - totally irrelevant to what was needed.
Reminds me very much of the CEO interview with Eve Sleep, where she dropped a bombshell which made me avoid the shares, which was, "We're up against some very well-funded competitors". That went bust some time later.
That's part of the reason CEO interviews are so worthwhile. Sometimes you just get a bargepole feeling. Not necessarily because the person is bad, but because they're trying to achieve the impossible, as with EVE and PURP.
So it's absolute codswollop to say (not you) that we ignore factors like this here. Between us, I think the community here is very good at spotting mgt that's out of their depth, and business models that probably won't work.
Mind you, I'm drawn like a moth to a candle by value, which can often be a mistake.
Regards, Paul.
Arrgh ! I wish my magic wand WANdisco (LON:WAND) was working last Nov when I revisited this stock and hovered over button ,I then watched it ping up and jumped on in Jan .This rascal stock goes against all my spidey senses -with scary val and no earnings, but if they can maintain advantage will get taken out. 100% margin is gonna attract some smart copycats .I do Love the CEO s enthusiasm ......but arent they all !
WANdisco (LON:WAND) - ”It was created by a polymath, so is not something that can be replicated”
Except by another clever person, which the US has in spades, and from all over the world - in stark contrast to our backward little island.
I do find the CEO extremely frustrating. Not least because, if he wasn’t so apparently lacking in the wherewithal to run any business too large to run out of a garage, I’d have bought some of these when it was under £4!
Except by another clever person, which the US has in spades, and from all over the world - in stark contrast to our backward little island.
<Rant>
We have no shortage of clever people. We have a huge shortage of capital willing to support them and governments capable of creating an environment they can thrive in, all of which contributes to a culture that fails to reward risk and regards failure as a permanent stigmata, as opposed to a learning experience. Meanwhile our education system seems designed to ensure smart poor people remain poor while rich stupid ones run the country.
</Rant>
Well, it is Friday afternoon ... :-/
timarr
Fair point. And I endorse your "rant". I should have said "well-backed clever person". My point was far more about the bullshit-spouting CEO.
I know its Friday - but I couldn't agree more.
Good rant timarr. And we have a Department for Science technology and innovation whose Minister doesn’t have a science, engineering or technology degree or any equivalent experience.
I previously bought WANdisco (LON:WAND) low and sold high successfully. Almost bought back when I saw momentum building around 350p but didn't so kicking myself on that trade. But at over £900m this is now eye wateringly expensive - it needs to be doing £45m of annual profits to be justifying that sort of tag (£35m if we are being optimistic) and it doesn't feel like it is anywhere near that level even at 50% net operating margins
I'd be tempted closer to 600-700p
Jubilee Metals (LON:JLP) I see 2 directors have bought shares, following the recent share price fall, not large amounts, around £20 odd thousand each, this may help the price recover.
Inland Homes (LON:INL) has made an intra-day announcement that has had a material impact on the share price. It has successfully renegotiated bank covenants see here. It is up 40% at the time of writing.
thanks for mentioning this. I hold from days I was following Simon Thompson.
has been a ten bagger in reverse for me. not worth even selling it!
No question that historical performance has been lamentable, but Stocko now classifies this as Contrarian with a ValueRank of 99 and Quality Rank of 74. Given the near 70% increase on Friday, the market must have been pricing in a large possibility that the covenants would be breached. The question of how to extract value from land held remains, but with price to tangible book and price to sales both below 0.2, if ways to do that can be found, there could be considerable upside. Clearly, not without risk this one, though.
LON:WAND. I've spent my career in tech mostly on the data side, and have been through the dotcom boom. Is this a good company yes, is this a viable product yes, would I be pumped if I was the CEO you bet!. But the stocko scores tell you all IMO. Value 2, Momentum 97. Market cap ~30x sales.
Too many times I've seen the scenario where tech growth has been extrapolated forward into the future to support a story. IMO its a trade not an investment with lots of FOMO. That said if (when) it tumbles it might be worth a punt as someone big will buy it.
Wow £900m market cap now. added to watchlist - as a short! looks like markets 'may' be pulling back as they have moved down a fair bit in the last 24 hours if we don't get more 'buy the dip' action today so am moving more into a long/short strategy as fail to see much upside on shares like this now. Good luck and well done to those who got in at 1/5th of the price a year ago!
Ps can they really have 100% margins? or is that not really true and they are just putting the costs of servicing the software (if if small) and any dev/upgrade cost is being taken to admin expenses or capitalised? But agree these businesses would be high margin so need to be careful on traditional P/S ratios they can trade maybe up to 10x and still not be as ludicrously valued as they first appear. but 30x!? But I know this is not unusual state side
EDIT: Berksbee where did you get 30x sales from. Are the forward bookings of $120m (so £100m) multi-year? otherwise if that's a single year they will be realised in it would 'only' be c9x? still expensive but slightly less so
2023 estimated earnings are ~$30m on Stocko - forward bookings can be multi year especially in the software business. That said the CEO implied they will blow the estimate but I assume not by an order of magnitude. Also there is history of forward bookings being very flaky in the software business - big scandal with Oracle a few years back springs to mind. I am not saying this is the case here but I am always a bit twitchy with the "only way is up" narratives.
WANdisco (LON:WAND) looks overextended to me on the charts. I would avoid this one like the plague. Trade risk first, not profit first. Stockreports shows this stock has never made a net profit. Its hardly the next Apple or Google, where profits were so big, greater than even the GDP of some countries. In fact, Boohoo (LON:BOO) is now, finally, looking interesting, and is techically setting up for a strong move higher. Would much rather put my cash in that then in some binary outcome of a stock.
Agree on both stocks - particularly interested in Boohoo (LON:BOO) change of sentiment it appears -can it stay above 50p ? Will only spreadbet this at moment to protect downside
Talking about share prices rises on no news, does anyone know why OPG Power Ventures (LON:OPG) has shot up over 40% in the last week?
RE OPG
Very interesting.
Is this Classic buy on rumour, sell on news?
OPG Power Ventures (LON:OPG) Not sure, read that it maybe partly due to falling coal prices.
I think Q3 results are imminent, peeps believe that because the coal price has fallen, magically Q3 figures will be good, or the outlook would be bright and rosy. IMO, a bit of FOMO, but what do I know. GLA.
I sold my OPG Power Ventures (LON:OPG) shares today, price was falling and spread is widening, I got some of my money back, still quite a loss but don't to risk losing anymore. 2 institutions bought 40m shares on 18th January.
Purplebricks (LON:PURP) Feeling relieved that I don't hold. Anyone who thinks that lots of directors purchasing shares is a good buy signal should have a look at the Director Dealings here.
RE: CML
No holdings.
Looked at the chart and saw that it had rocketed from its long plateau on Feb 10th, last Friday..
Checked the news. Oh, there was no news that I could find.
On a different subject: why is insider trading a crime?
How do you know it is insider trading, for the share price rise?
Quarto (LON:QRT) has seen a recent rise in share price, there has been no news and I can't find any reason for it. I sold my shares as I expected the shares to fall back but they have not.
Quarto (LON:QRT) - shocking rise after it had fallen back to intraday 116p. I was tempted to add to my position but given how "slow" I had anticipated the sp rise to be up to results day (next month, I believe), I decided against it. Within few days the sp had risen to 145 - 150 bid ask (where I sold out). I put it down to Quarto (LON:QRT) being a laggard but IMO at present price - the sp is spiking a wee early, but then again what do I know again!
There are rumours about the company Quarto (LON:QRT), being taken private, one director holds over 40% of the shares. I sold out at 156p, shares did fall back slightly but now up into the 160s. Apart from this rumour, can't find anything else. The spread is quite wide and I can't buy 400 at the moment. Will watch from the sidelines.
psn, apparently there are two sorts of insider trading. One is criminal and the other isn't, so one should go carefully.
TO Silver Moon and Rusty2.
Insider Trading? I know nothing - nor do I accuse.
Looks like a share tip from a popular tipster could be the reason for CML Microsystems (LON:CML), it is often difficult to find reasons for share price movements.
Insider traders should be prosecuted, a few prison sentences would probably change some insiders dealings.
Silver Moon, I think the term Insider Trading is usually only used when it is illegal, Correct me if I'm wrong. Unfortunately it seems insider trading prosecutions are as rare as hen's teeth.
Roger, Simply Wall St. would disagree with you on this point, but you are right about the prosecution rate. You can also see why I often don't bother to vote at AGMs.
This is the CML Microsystems (LON:CML) ownership breakdown FYI.
Silver
CML Microsystems (LON:CML) was included in Simon Thompson's Bargain Shares 2023 on that day.
Why is insider trading a crime?
1. Because trading with inside knowledge gives those in the know a huge advantage. A good example was the film Wall Street. The Michael Douglas character made a fortune by buying into a company before anyone else knew the results of an important court case.
How easy is it to identify?
1. It is easy to identify insider trading. Just follow the change in share price before an important price sensitive announcement (e.g. a takeover bid). And then look for the large trades that fuelled that share price move. Isn't that interesting. This trade was instigated by the brother of an advisor on the takeover
2. It's not so easy to prove. Without evidence of information being passed we can know that it must have been insider trading but not prove it
Why are there so few cases brought to trial?
1. because the enforcement agencies don't have the skills or the resources? Or maybe they just don't have the motivation (see also the failures to shut down or prosecute the internet based financial scams that promise high interest rate guaranteed returns and then disappear with our money)
2. because some consider insider trading to be a victimless crime and so not important. This is definitely not true. Anyone who sold out of a company on a share price rise just before a takeover bid will know that
3. we were at Harrow or Eton together. Or maybe it was Balliol. It is much easier to jail people from the other side of the tracks
Why don't PIs have access to the same information as institutions and professionals? That is also unfair. They often can't buy shares at a discount either.
Missed a trick yesterday Paul, and sold my last holding in CML Microsystems (LON:CML) having forgotten about the land and planning application, oh dear, it doesn't take much to get ahead of oneself. But never mind, as one door closes another one opens.
Morning Silver Moon,
Oh no, that is such bad luck - selling out of CML Microsystems (LON:CML) yesterday. Never mind, can't win 'em all, and it sounds like you were selling out in stages, into a share price that's done pretty well in the last few years, so looks like it was a winner for you, so I wouldn't fret over missing out on a few % more.
Deciding when to sell is by far the most difficult decision, isn't it?!
We all sometimes forget key information, when looking at so many shares. So I think some very brief notes for each share we hold, on a piece of A4 pinned up on the wall next to our screen, is a good idea, even if only key points in 2 columns for positives & negatives, for each company.
Regards, Paul.
Good day to you Paul, you have such a clear view of things. I'm not overly upset as I'm gradually migrating from pure growth to income-with-growth, my aim being to achieve ISA portfolios, (yes, there is a spouse) of dividend payers so as to then relax and let ii drop tax-free lucre into my current bank account. After all, I'm pushing 79 and hardly starting at the beginning.
Regards,
Silver
I find the notes facility on the Stockreports useful. As you say so much to try and keep track of. Selling is difficult, they often go up after I sell, even if done nothing for a year, is that Murphy's law?
NWGNatwest (LON:NWG) . Not a SC but interested to hear views on todays seemingly excellent figures triggering a 8% fall in SP.
NWG has the highest ranking on Stocko among the banks. I am looking forward to my 10p final dividend. clearly the market did not like today's report for one reason or another.
Natwest (LON:NWG) results were fine and everything in line with expectations. No idea what caused this morning's fall - no doubt some strange algorithm that I would never begin to understand. Would not be surprised to see this recover by end of day. Anyway a good opportunity to add to what is now a very solid name throwing off mountains of cash as rates have risen.
The BreakingNews that follows mat explain the fall in Natwest (LON:NWG) .
(The author is a Reuters Breakingviews columnist. The opinions
expressed are their own. Updates to add graphic and company
code.)
LONDON, Feb 17 (Reuters Breakingviews) - British lenders
have had a great six months. Shares in NatWest NWG.L and
Lloyds Banking Group LLOY.L rose 17% and 16% respectively
between Aug. 16 and Thursday, as fears of a deep recession faded
and investors started anticipating fat bank lending margins due
to higher rates. But NatWest Chief Executive Alison Rose has
brought that excitement to an end. The 28 billion pound
state-owned lender on Friday set a 3.2% target for its 2023 net
interest margin – the key measure of how much lending income
banks make after subtracting the interest paid on deposits. That
compares with 2.85% last year and 2.3% in 2021. But NatWest’s
shares fell by almost a tenth. The problem is that 3.2% is
exactly what it posted in the fourth quarter of 2022; analysts
were penciling in 3.38% for 2023.
It’s surprising that Rose thinks lending margins have maxed
out already. Higher rates take a while to feed into revenue
because so many borrowers have long-term or fixed-rate debt,
which reprices slowly. Adding to the mystery is that Rose’s
expected net interest margin in 2023 is based on a steady 4%
Bank of England base rate, which means it isn’t just down to
expected rate cuts later in the year. One explanation for the
disappointing forecast is that deposit costs are going up on
savings accounts. That would be a cause for celebration among
households and firms with spare cash, but it might bring the
bank share-price party to an end. (By Liam Proud)
The fact is Natwest have no greater insight in to what will happen to interest rates this year than anyone else - I suspect they are just prudently guiding on the basis that rates stay at 4% - but its all just guesswork. There's certainly no new information here that justifies the fall today - I suspect the algorithms just automatically latch on to the guidance being reduced and the share price drops.
Watkin Jones
Very impressive share incentive plan awards today for CEO and CFO
Circa 100k each
The “incentive” and performance criteria are are pretty tough
- to stay in employment for 12 months .
Am I missing something. ?
Must be a horrible place to work if senior management need rewarding with shares to keep working there .
I was quite keen on Watkin Jones but this is just deflating to shareholders and inflating to pocket filling management who seriously need a LTIP to stay in employment .
RE: Watkin Jones (LON:WJG)
Must be a horrible place to work if senior management need rewarding with shares to keep working there
Or maybe it's necessary to prevent excellent management being headhunted?
To be fair, zero performance options are never great, but shareholders approved this at the last AGM, so it's not a surprise, unlike the Boohoo (LON:BOO) awards yesterday.
In fact, I don't have much of a problem with the latter either, given the hurdles to be mounted to achieve them, the problem there is that the same management couldn't achieve the previous awards, so it's a never ending set of rewards for failure. Management need to earn their gravy in all markets, not just when things are going well.
timarr
Re Watkin Jones (LON:WJG)
Are these really 'zero performance' shares or shares previously earned under LTIP criteria (EPS and TSR), that have now vested. I looked at annual report and AGM resolutions and could not see reference in either to zero performance shares.
I assumed that the reference to 1 year was that they needed to be still with the company one year after they 'earned' the shares. I do not currently own shares in WJG, but was looking into purchasing. I would be concerned if they just hand over that number of shares just for showing up.
“Or maybe it's necessary to prevent excellent management being headhunted?”
Don’t think Charlie and Warren Buffet agree with this so nor Shoukd minority shareholders .
The sad fact is shareholders feel powerless and accept it, private equity, institutions tend to turn a blind eye as ultimately they are drinking from the same trough .
It’s not right end of story , and a 100k amount is hardly going to prevent headhunting if the CEO are CFO are world class .
It’s just a bit of pocket filling on the daily stock market gravy train that everyone accepts as “that’s the way it is “
“Show me the incentive, and I will show you the outcome.” – Charlie Munger
In this instance this is clearly just a bonus / part bonus that is being done in equity (for some upside). It should be viewed holistically around total comp of each exec rather than a broad based rant about nil cost options. They could have done it in cash but at least this way if he walks within a year he loses it. A number of industries operate like that. If the total comp of a Director is say £400k they might get £200k salary, £100k as a cash bonus and £100k of restricted equity. If you take that away the comp is £300k at which point that may be comparatively low against competition/industry etc.
I do share your disdain of the gravy train options though - ie %ages of the company given away for nothing along with a nicely loaded cash compensation package.
timarr, firstly it bothers me that PI's mostly don't get any say in voting at AGMs and secondly my account of Watkin Jones (LON:WJG) rests in my Record of Old Stocks spreadsheet because I sold it at 246 pence in November 2021. Whether the price was a post-Covid bounce or what I don't know but the writing was on the wall and I made money out of it just as the current directors will.
We're (my wife is the admin dept) rebuilding a holding in Watkin Jones for the third time Silver Moon, hoping for another successful outcome. BTW, I'm pushing 80 and looking forward to competing in the M80 Masters running category soon. 79/80 is the new 60 :-)
I do wish you well JASVFS, and well you might as Watkin Jones (LON:WJG) is now at an attractive price. Buy low, sell high.
Silver
My morning smallcap tweet: Bricks and slaughter
Purplebricks (LON:PURP) Boohoo (LON:BOO) Harland & Wolff group (LON:HARL) CML Microsystems (LON:CML) Oncimmune Holdings (LON:ONC) EnSilica (LON:ENSI)
◄Purplebricks (PURP)► puts up For Sale board on itself. Cuts FY-Apr guidance - rev £60-65m and adj EBITDA loss £15-20m. Blames disruption from move to focus on profitable areas and those with largest opportunity for market share growth. Plans another £4m cost savings. [SP=10.19 Cap=31m]
◄booHoo (BOO)► my goodness! Having a vote on the 'Growth Plan'. Sounds better than 'Option for Management To Turn Things Round Plan'. I mean, who's against growth? [SP=48.63 Cap=617m]
◄Harland & Wolff (HARL)► negotiates £16m payment from Saipem the terminated contract. "The project has been a helpful learning curve for the business in this environment." [SP=15 Cap=26m]
◄CML Microsystems (CML)► conditional planning approval granted at its current 29-acre site in Maldon. Final approval is subject to the completion of the necessary Section 106 Unilateral Undertakings. [SP=553.5 Cap=88m]. I hold.
◄Oncimmune (ONC)► partners with Siemens to improve malignancy risk assessment of indeterminate pulmonary nodules. [SP=53.55 Cap=40m]
◄EnSilica (ENSI)► wins €5m contract to develop a new chip to address the next generation of mass market satellite broadband user terminals. [SP=95 Cap=71m]
Good morning Paul,
I know that Boohoo (LON:BOO) is not covered by the SCVR anymore but I was wondering what your thoughts were regarding the RNS yesterday?
Regards
Morning oliver,
Well as it's a small cap again (by our criteria here), we can still cover Boohoo (LON:BOO) here without starting uproar in the user base!
I've never been a fan of management incentive plans generally, as I can't see any evidence that they genuinely attract or retain good management. Outcomes often seen random (right place, right time), rather than down to management actions. Also I think the incentives are often negative - encouraging management to take unnecessary risks (e.g. over-gearing, in order to hit growth targets).
Where an intermediate class of shares is created, that strikes me as thinly disguised theft of part of the company.
A redeeming feature of BOO's latest plan for management bonuses, is that it sets fairly challenging targets for the share price, starting to pay out at 95p per share - about double the current level.
The other key measure is total dilution. In BOO's case if the 95p share price target is hit, there's 1.46% dilution. Is that really such a big deal? If I held, I'd be happy to give away 1.46% of the company to management, if they've doubled my money from the starting point.
If the top target is hit, of 395p, then the total dilution for mgt is 6.06%. That would be about an 8-bagger from here, so I'd want to kiss management and treat them all to an all-expenses paid trip to the Seychelles, if they achieved that kind of shareholder return!
So whilst it's usually the case that management incentive schemes are pure greed, in this particular case, I think the rewards look fair, and are aligned with big shareholder returns from here.
But your view will depend on when you bought your BOO shares. Holders from the peak around 400p will not be impressed. But recent buyers will probably think this scheme looks fair.
Regards, Paul.
P.S. So in summary, my key criteria for mgt incentive schemes is that they must -
1) Have stretch targets for the share price, which this does, and
2) Have modest total maximum dilution, which this also does.
Your reply is greatly appreciated. Far more info than I had hoped for and in plain English and no Jargon, I am now attempting to explain this to the dog. Many thanks.
One way to help get Boohoo (LON:BOO) to that starter 95p share price is to consider just one simple reason why returns for all on line retailers are so extraordinarily high. It’s because clothing sizes are not standardised. Variations on womenswear especially are wide. So inevitably online shoppers buy more than one of the same item, and then return the one or more that doesn’t fit.
It’s not rocket science surely to standardise sizes? After all much more complex items like tyres and electronic items including TVs and white goods (and what about Space) are often standardised.
Clothes are returned for other reasons too but I bet the bulk of returns are because of bulk buying because of size uncertainty. Time for the retail sector to address this issue?
Hi ken,
Yes, there are some standardised clothing sizes, but I remember being told back in the 90s that each retailer has their own fit, which builds customer loyalty once customers find a retailer whose products tend to fit them well. That relationship breaks down the cheaper the product gets, as corners are cut, and the fast fashion companies deal with so many factories, it's very difficult to control.
Did you see Dragons Den last night? There was a rather flaky entrepreneur who came up with an interesting concept, which might be copied by the sector, of customer returns going through a customer swap portal, rather than being refunded in cash. If it worked, that might help solve the problem of high cost of dealing with online returns that can be up to c.50%.
Also, BOO and others are now charging an admin fee for returns, which could deter serial returners, who have been spoilt for years with free returns.
Regards, Paul.
With international selling, you have to take into account different sizes for different races/countries. A standard size maybe ok for UK and Europe but probably not be a good fit in the Asian market. There are also differences in age groups. Younger people tend to be a different shape from older people. I have found sizes have got larger over the years and it is difficult now to even find small sizes. Recently I'm finding sleeves are too long for me, most male models seem to be over 6' tall.
Most male models seem to be over 6' tall.
Most 20 year old men are over 6ft tall. My son is 2 inches taller than me at 6'2" despite my wife being very petite. It's just the way of things.
But not everyone is 20. I know a lot of young people, who are much smaller than 6', some only around 5'6".
Re clothing standardisation and £BOO- Google ' Zozo suit in Japan ' . It supplies a free/very cheap and tight-fighting suit covered in polka dots. You take a picture of yourself on a smartphone wearing it and you have an (almost perfect) digital body shape - no lies on waist size possible, women's varied ratios handled. (If this weren't a word-focused blog I'd share the image; they are great for fancy dress parties as well!)
From that, you could link to either "custom made clothes" as per Zozo's claims or more realistically AI selected best fit from a retailers range. Needs either a big player (or govt regulation) to run with it - I see it as a revenue/loyalty driver, an ESG story AND a cost cutter. Returns are a pain to BOTH consumer and retailer even if they had no cost attached to them
One of the things I liked about Unbound (LON:UBG) (dare I mention the share) was its instore digital foot shape measuring to get the 'perfect fit' from its Hotter range. Once you have that, I can believe your claim...and if my foot changes shape (bunions etc), I have to go to your store/ garden centre concession again). If only their Mgt were better/more more honest!
Yes Paul, I did see Dragons Den last night and that investing concept that could be copied across the sector. Deborah Meedon and Paul Jones jumped at that opportunity for, from memory, just 4% each too. I also think that each new series of Dragons Den has been an improvement on the previous one. In contrast the opposite seems to be the case with The Apprentice.
As for just standardising sizes as a simple solution to the bulk of returns, your reply and others show it’s not that simple to do.
And as for admin fees for returns, though it might well deter serial returners, it also deters genuine customers too.
Boohoo (LON:BOO) share price was up 12% just now so market reaction to the Growth Share Plan seems positive. Just a chance we’re on the road to a strong recovery?
Too late to edit typo. . I did know it’s Peter Jones!
I worked for a womenswear retailer a couple of decades ago (in IT). The sizes were deliberately de-standardised. Oh, that size 12 doesn't fit, maybe the size 12 on this rack will fit.