Small Cap Value Report (Fri 17 May 2019) - CRL, FUTR, STAF

Good morning!
Not much to report on from my hotel room this morning, which is just as well since I only have about an hour before I have to leave to speak to the crowd at Mello.
There were excellent presentations yesterday from Impax Asset Management (LON:IPX), Scientific Digital Imaging (LON:SDI) and Judges Scientific (LON:JDG), and probably lots of other companies I missed.
Today I'll look to attend presentations from Water Intelligence (LON:WATR), Sosandar (LON:SOS), Character (LON:CCT) and Avation (LON:AVAP).
In this report I will try to cover:
- Creightons (LON:CRL)
- Future (LON:FUTR)
- Staffline (LON:STAF)
Creightons (LON:CRL)
- Share price: 28p (pre-market)
- No. of shares: 62.5 million
- Market cap: £17.5 million
Final results timetable and trading update
(Please note that I currently have a long position in CRL.)
Not sure how the market might react to this - I don't see any broker forecasts - but it's ok from my perspective.
H2 revenues will be "broadly similar" to H1. For context, the H1 result was £22.3 million (with PBT £1.4 million).
"Broadly" usually means "a little lower", so we might see full-year revenues of c. £44 million, maybe?
Revenues in FY 2018 were £34.8 million, so that would be a 26% increase.
The company has also enjoyed a little bonus:
a one-off benefit from the recovery of R&D expenditure through the government's corporation tax rebate scheme in the region of £350,000 in respect of 2016/17 and 2017/18 and thereafter for the duration of the scheme, the company is likely to receive an annual benefit proportionate to our allowable R&D expenditure.
I presume this means about £180k benefit for each financial year, adding up to £350k in total.
When you have a market cap of less than £20 million, every little helps. I'm happy to continue holding.
Future (LON:FUTR)
- Share price: 914p (+7%)
- No. of shares: 82.5 million
- Market cap: £754 million
I haven't looked at this one in a while, so I've just been reacquainting myself with its media brands, several of which I recognise.
Key points from today's update:
- full year results should be ahead of expectations
- revenue +100% to £109 million, helped by acquisitions. Most revenue is now derived from the US.
- various adjusted profit measurements growing rapidly
- statutory operating profit +163% to £10 million
I want to separate organic growth from growth by acquisition. Future says there was organic media revenue growth of 38% at constant currencies. Media revenue is 70% of the total - the rest is in the Magazine segment.
Later, the statement says there was organic revenue growth in the "core" business of 14%.
My view - I have to cut this short due to time constraints. I don't have a strong view on this share yet. The balance sheet is stuffed full of intangibles and historic losses, so the NCAV (current assets minus total liabilities) is a very large negative number. It has a large debt facility to help it keep growing. If profitability is sustained, it should be fine.
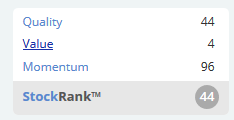
My initial impression of this aligns with the StockRank view that it's a Momentum Trap, possibly overvalued, but I haven't had the time to do as much research as I would need to reach any firm conclusions. So take this with a larger grain of salt than you normally would!
Staffline (LON:STAF)
- Share price: 500p (-40%)
- No. of shares: 28 million
- Market cap: £140 million
Adjusted EBIT forecast reduced to £23 - £28 million, versus prior forecast of £43 million.
There are a lot of excuses given, and problems with publication of the accounts. At the end of the day, this doesn't seem to have been such a good business after all. I no longer study the recruitment sector in any detail, having decided that there are easier ponds in which to fish.
That's it for today, have a great weekend and normal service shall resume next week.
Cheers
Graham
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

14 comments
A late RNS from yesterday from Spectre Holdings (Philip Day) on the subject of Bonmarche Holdings (LON:BON)
As I have posted elsewhere :
Overall, whilst I find the lack of engagement a little disappointing, the continued availability of “the offer” still limits the downside and offers and asymmetric risk vs. reward balance, so I continue to hold.
Staffline (LON:STAF)
‘Tight labour market, transferring contractors to perm’ , this sounds dubious to me, let’s fix our flexible resource cost because of what might happen, not come across this before as a general employer view.. ‘Slowdown in contract market’ I agree with above comments on this, really. I posted earlier in week on Empresaria (LON:EMR) and the possible impact from the new IR35 rules which HMRC have been trying to implement for 20 years, and finally lookro have nailed it putting responsibility on employers, and I think Staffline (LON:STAF) issues might be related to this, maybe not but I think sufficiently worrying that I sold out of Empresaria (LON:EMR) this week,
For those invested in recruitment have a look here:
https://www.gov.uk/guidance/ir35-find-out-if-it-applies
A beneficiary of this should be FDM (Holdings) (LON:FDM) who have a clever model picking up stem graduates who failed to get into the banks/consultancies/lawyers, training them and putting them into firmly ‘relatively’ cheaply, the firm then has an option to buy them off FDM.
Graham,
Yes enjoyed the Mello presentations yesterday, (including your own). I have a starter Scientific Digital Imaging (LON:SDI) holding and it was the 1st time I had heard the CEO present. I was particularly struck by how supportive attendees/shareholders are of their buy and build strategy and the management's and shareholders almost religious commitment to SDI's success. I also caught the end of the Judges Scientific presentation and it stuck me what a great fit buying SDI would be. Both aspects encourage me to hold.
iwright7,
Not a chance of Judges Scientific (LON:JDG) taking over Scientific Digital Imaging (LON:SDI). Both companies buy & build strategies rely on buying private businesses on a price to EBIT of 4-6. Buying on a comparable multiple would be sacrilege to DC.
Yes Creightons (LON:CRL) update confusing - especially as the use of the word 'but' implies the first part of the sentence is bad news. "The Company reports that the sales in the second half of the year to 31 March 2019 are likely to be broadly similar to those for the first half, but there will be a one-off benefit from the recovery of R&D expenditure "
But surely that would be good news as it implies continued growth over the previous H2 - as it would be £22m revenue H2 in 2018/19 vs c.£18m H2 in 2017/18.
Maybe the issue is that the revenue growth has slowed a bit. But Creightons (LON:CRL) is so cheap that even flat revenue growth would be good!!
Remember c.2p EPS for H1 2019 and it closed trading yesterday at 27p.
No worries Camtab, maybe see you today!
Disappointingly could only make Thursday. Enjoyed your beginners course on investment though, very useful.
Morning - yes, am taking a look at FUTR.
Graham sorry I missed you yesterday. I did see you several times in conversation but hard to get a moment with you. I went to Duke presentation which was very interesting and also Beek Financial which is a company I really like. I spoke to the Avation CFO, but some how aircraft leasing just feels the wrong business for me. I am very concerned about the environment and we have to reconsider how we use airplanes. His explanation that the millennials are more interested in experiences than assets and therefore fly more isn't at all unreasonable in the world we live, but unfortunately we have to find ways to reduce the carbon output. The CFO's response was they are up with technology which is fine but.......
FUTR?
Maket missed this one competely and its rise is just getting started.
Any thoughts on FUTR?