Small Cap Value Report (Fri 17 Sep 2021) - STCM, PPS, AXS, ELTA

Good morning, it's Paul & Jack here with Friday's SCVR. Today's report is now finished.
Agenda -
Paul's section:
Proton Motor Power Systems (LON:PPS) - a bizarre share, with a crazy balance sheet. Jam tomorrow - i.e. awful historic (and interim) results, but the big valuation seems to rest on hopes for credible-looking orders received more recently. A complete punt, so wouldn't interest me at all. In a sector that's been in a speculative mania of late (clean energy).
Accsys Technologies (LON:AXS) - a good trading update. This looks an interesting growth company, but I find it difficult to value, and don't see enough upside on the current market cap to make it look compelling to buy. I could be wrong though, as am only using broad brush assumptions.
Electra Private Equity (LON:ELTA) (I hold) - I cover updates on both portfolio companies, Hostmore (which owns TGI Fridays), and Hotter Shoes (to be renamed Unbound). I've just come off a call with management, with things seemingly going OK, as confirmed in recent trading update. Do check out the link to Unbound's recent CMD recording.
Jack's section:
Steppe Cement (LON:STCM) - Good results with revenue up 17% and profit after tax up 52%. This company has had a high StockRank for a few years now but is thinly traded and, having doubled in recent months, is no longer in deep value territory.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to cover trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul's Section
Proton Motor Power Systems (LON:PPS)
40.7p (up 3% at 08:06) - mkt cap £316m
I haven’t looked at this share for over 6 years, and it has got considerably more bizarre over that time. Continuous losses, and very low revenues, combined with a soaring share price.
Note that the largest shareholder, SFN Cleantech Investment Ltd holds 78.6% of the shares.
It’s another set of awful figures, to add to a long list.
Revenues of only £0.9m, and an operating loss of £(3.9)m. Remember this company is valued at £316m!
A large credit to finance income offsets the usual heavy finance cost, which reduces the H1 loss from £(10.3)m last time, to £(1.2)m this H1.
Now we come on to the fun bit, the balance sheet. It looks much as I would expect for a small, loss-making company, until we get to long-term liabilities, which includes £80.0m of borrowings, and a £396m liability called “Embedded derivative on convertible interest”.
Overall net assets are negative at £(474)m! That makes it completely uninvestable to me. The numbers are just ludicrous.
Clearly then, if you are tempted to buy this share, then the key issues to research would be -
- Terms of the large £80m borrowings - when is this repayable, to whom, are there any covenants, etc? It seems to be a loan from shareholders, as it’s difficult to imagine anyone else would be prepared to extend so much debt to a tiny, loss-making company.
- Terms of the convertible loan, and how on earth has such a gigantic liability of £(474)m appeared on the balance sheet, seemingly due to a derivative of some kind?
With these size liabilities on the balance sheet, this share cannot be considered a regular investment, it’s more a special situation, needing careful research from sector experts.
Orders/pipeline - this is the interesting part, and is clearly what has driven a frenzy of excitement around this share. It had a period end order book of £7.3m, and follow-on orders since the period end are mentioned. The value of customer quotes is significant, at 45m Euros.
This suggests to me the company has an interesting product (hydrogen fuel cells), which the market seems to think could become commercially valuable.
My opinion - it’s a jam tomorrow share, which makes it impossible for me to value. The historic figures show that the equity is worth nothing, so the £316m market cap is entirely based on excitement about its future potential, with significant orders now coming in.
Hence I think this share is only for gamblers, or sector experts. You would really need to know your stuff about fuel cells, and the competitive landscape, to be sure that you’ve found a future winner. There must be so many companies around the world trying to produce commercially viable fuel cells, hence for me this would be like trying to find the proverbial needle in the haystack.
Also, the whole renewable energy, or clean energy sector has been in a big speculative boom lately. Valuations are often ridiculously high, based on little of substance. So it’s really an area for speculation rather than sensible investment, in my opinion.
The long-term chart is interesting, below. This share has been listed for a long time, and most of that time it was valued at very little (understandably). However, something happened in early 2019 to start a multi-bagging frenzy, maybe contract wins, or something similar? As you can see more recently, a fair bit of the froth has since blown away, although at £316m market cap, I'd say it could fall considerably more without continued positive news on customer orders. About as far from a value share as it's possible to get!

.
Accsys Technologies (LON:AXS)
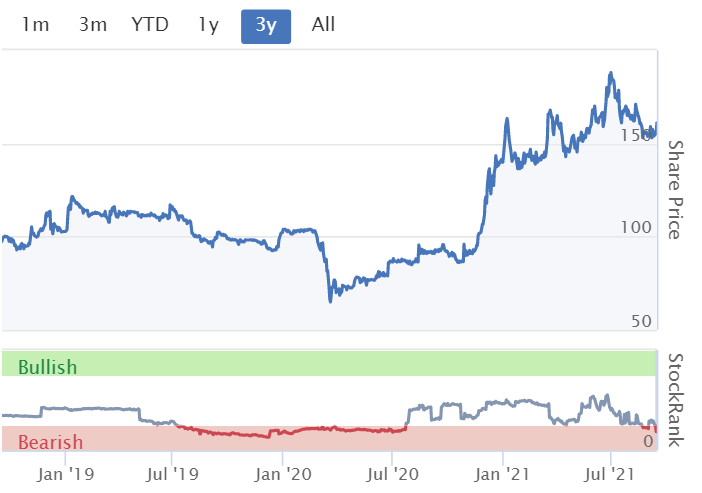
162.5p (up 5% at 10:40) - mkt cap £313m
Accsys, the fast-growing and eco-friendly company that combines chemistry and technology to create high performance, sustainable wood building products, today announces an unaudited trading update for the first five months of the 2022 financial year from 1 April 2021 to 31 August 2021...
There’s a fair bit of detail in today’s update, which comes across well.
However, rather than me rehashing it all, I think the CEO’s summary sums it up very well as follows -
Rob Harris, Accsys CEO, said:
"Accsys has made a strong start to the 2022 financial year. Our established Accoya® business has delivered double digit volume and revenue growth. This reflects continued strong customer demand, our price increases, product mix, and lapping the initial more severe effects of COVID-19 last year.
During the last five months we have continued to make good progress with the construction of a fourth reactor in Arnhem, advanced our US JV with Eastman and whilst we experienced some previously communicated challenges with the construction of our Hull Tricoya® facility, we are working through these and expect to have the plant commercially operational by July 2022.
Looking ahead, we remain confident in delivering on full year expectations and underpinned by the clear market opportunities for our high-performance wood products, we continue to progress towards our ambitious 2025 fivefold increase in production target."
Valuation - this is particularly tricky because AXS is not exactly jam tomorrow, because it already has production underway & is selling product. However, the share is all about scaling up production 5-fold in future, and how that would pan out in terms of profits? It’s all about achieving scale, but that is taking a long time, and of course costs money, in capex and working capital increases.
Broker consensus for FY 03/2022 shown on the StockReport is 108 Euros revenues, and just above breakeven with a net profit of 2.3m Euros. That’s fine at this stage, because new factories won’t have kicked in.
The question is, what would the figures look like once new factories are operating?
If we assume say 500m Euros revenues in 2025 as planned (“ambitious”) and what, maybe a 5-10% profit margin (I’m just guessing there), then this business could be making say 25-50m Euros profit per annum by 2025. Take off 25% tax, convert into sterling at £1 = E1.17, and put it on a PER of say 20, and I get a valuation of £321m - £641m. The current market cap is £313m, so it looks like a lot of upside is already priced-in.
You might want to try out different numbers to my assumptions above, and you could reach a higher (or lower) valuation - e.g. if you think the valuation might go above a PER of 20 (entirely possible for growth shares), and/or that the profit margin could be higher than 5-10% once scale is reached. Plus I haven't factored in anything for downside risk, if the company doesn't achieve its ambitious 5-fold increase in revenues.
My opinion - I’ve always liked the concept here - AXS makes a genuinely good product, that is in demand. Hence scaling up production should enable more to be sold. A 5-fold increase in sales would likely transform the numbers for the better, if achieved.
Valuation is the tricky part, and do I really want to wait 4 years until 2025, for a share that might potentially double in price, by my calcs? Not really.
.
.
Electra Private Equity (LON:ELTA) (I hold)
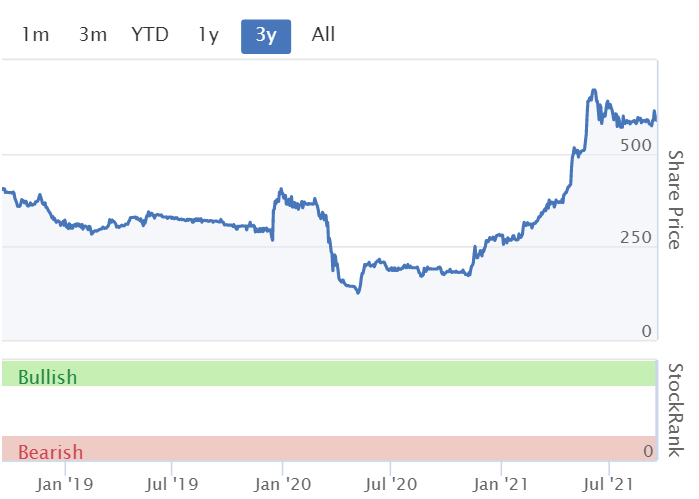
580p - mkt cap £225m
I’ve covered this share a lot this year, and it’s one of my top conviction holds. It’s an investment company which is divesting its main asset, TGI Fridays (casual dining chain). That is due to list imminently, by end October 2021. It will be called Hostmore, and ELTA shareholders will receive free shares in Hostmore.
After that, ELTA will change its name to “Unbound”, and its sole investment will be Hotter Shoes.
Both businesses have been extensively restructured and rejuvenated under decent new management teams put in place by ELTA. The prospects for both businesses look very good, in my opinion.
I reckon ELTA shares look substantially lower than my sum of the parts valuation - which gives good upside, and low risk, to ELTA shares, if the market agrees, once these shares are standalone regular companies.
Hostmore (TGI Fridays) Trading Update
This was issued yesterday.
Electra Private Equity PLC ("Electra") is pleased to issue a trading update for its hospitality brands, Fridays and 63rd+1st, for the 16 week period since 17 May 2021, and to announce the composition of the Board of Directors of Hostmore PLC ("Hostmore"), the parent company for those brands.
Since re-opening, trading has been good - the comparisons are with 2019 pre-pandemic levels -
Averaging +11.8% on 2019.
The rate of increase accelerated within that period, to +15.2% in the most recent 7 weeks.
However, as the company flags up, the reduced 5% rate of VAT on food & soft drinks, a temporary measure, have caused most of that increase. They’ve provided VAT adjusted numbers too, which are flat against 2019, and +2.6% in the most recent 7 weeks.
The company says these numbers are out-performing the market, based on data provided by Coffer CGA Business Tracker. I think Wagamama did even better in a recent update from Restaurant (LON:RTN) .
I’m happy with that. It’s helped by the fact that Hostmore doesn’t have many sites in London, which is where the biggest footfall drops (and the worst staff shortages) have been. Its Covent Garden site has a lease expiry, so won’t be re-opened. That has helped drive more traffic to its expensive Leicester Square flagship site.
63rd+1st - this is a new, more adult-themed cocktail bar, which was trialled in a site in Cobham. The roll-out is now starting -
we are opening our next two 63rd+1st sites - in Glasgow later in September and Harrogate in November - following a successful launch in Cobham earlier this year in May.
Therefore, in Hostmore shares, we are getting 2 hospitality brands to roll out. This is a very good time to be opening new restaurants, as 10-20% of competitors have gone bust, and landlords are offering very attractive terms on new sites. Hostmore is currently focusing entirely on taking over well fitted-out sites, with reduced capex, compared with the shells that it might have typically taken on pre-covid.
If Hostmore attracts a premium, roll-out valuation anything like say Fulham Shore (LON:FUL) then it could turn out to be lucrative for shareholders.
This is what ELTA shareholders will be left with, once Hostmore demerges.
I attended the recent Capital Markets Day (CMD) on a webinar, and thought it very interesting. Hotter Shoes has been turned around, comprehensively restructured, with physical stores reduced from 82, to 17. It’s now a profitable, digitally-led business.
The plans are to expand product ranges into complementary areas, such as gardening (already have concessions in Dobbies), clothing, even holidays. This is all going to be done on a low risk, capital-free model, in partnerships.
Hotter has a close connection & strong brand, with the over 55s women, its main market. There’s an opportunity to expand its menswear (only 10% of sales at present).
I gave feedback that management used a little bit too much MBA-speak, and that they clammed up during Q&A, refusing to answer some questions as too commercially sensitive. It was explained to me that the IPO process has seen them having lawyers & advisers swarming over everything they say, hence why they thought it best not to say anything that might cause problems. They’ll loosen up in future, I’m sure.
The good news is that there’s a recording published today of the Hotter Shoes (Unbound) CMD, do check this out. At the moment, I think some ELTA investors have almost disregarded Hotter Shoes, thinking it’s of little value. Whereas actually, I think it could be a decent investment. There’s also a chance that big holders might dump their shares, creating an overhang, and an attractive entry point for us, once it becomes a separately listed micro cap.
I wouldn’t want to hazard a guess at the market cap of Unbound (Hotter). Oh that’s too boring, I’m going to guess! In my view, I think it could be worth say £50m standalone. But as price discovery occurs, that could fluctuate wildly, from say £30-70m market cap, is my complete guess.
Another recent float targeting the older demographic is Parsley Box (LON:MEAL) . This still valued at £43m, even after almost halving in price since IPO. MEAL is still heavily loss-making, spending money mainly to get its brand known. Whereas Hotter Shoes already has a very widespread brand recognition amongst the over 55s, and is already profitable. So to my mind, Unbound/Hotter should be valued at considerably more than MEAL’s £43m.
A new research note is due out from Edison fairly soon, which I’ll flag if I spot it.
My opinion - I really like this special situation. Not many investors seem to know, or understand the situation here. That’s why this share sits at what could turn out to be a significant under-valuation still.
Both Hostmore and Unbound look excellent companies, that I would be very happy to hold. Hence my plan is to sit on the shares long-term, and hopefully watch them re-rate by maybe 50-100% of the current valuation, is my best guess. Considerable volatility could occur as the market finds a value for both Hostmore and Unbound shares. So I think people need to work out in advance whether you're trying to trade this for a short-term profit, or whether you're looking to the longer term (which is my position).
.
.
Jack’s section
Steppe Cement (LON:STCM)
Share price: 53.04p (+0.08%)
Shares in issue: 219,000,000
Market cap: £116.2m
Steppe Cement is the leading cement manufacturer in Kazakhstan with annual capacity of 2m tonnes.
Its facilities consist of two dry kilns (which use less resources) and four mothballed wet kilns. The group says its competitive advantage comes from being a low-cost producer but in truth there is little coverage on this company - one thing to note though is that it has been consistently flagged by the StockRanks as having good value, momentum, and quality. Today the group has a StockRank of 99.
The screeners out there will no doubt have seen Steppe pop up on various screens over the years.

There is competition risk in the form of overseas producers able to operate at even lower costs, and a lot of supply. There’s probably country risk too, and an unfamiliar major shareholders list sheds little light on the quality of corporate governance. Some known institutions on the register would help, assuming they use their resources to conduct adequate due diligence into the board and management structure.
That said, Steppe’s facility remains well invested and cost some $250-300m to create, compared to today’s market cap at a little over £116m. In that time, Steppe has generated profits and more recently began paying out dividends.
Financial highlights:
- Revenue +17% to $39.5m,
- Profit after tax +52% to $6.2m.
- Earnings per share +47% to 2.8 cents.
Doubling that EPS figure and translating into GBP would equate to around 4p of earnings and a PER of 13.1x. What comes across in these results though is the disproportionately large increase in profits on the back of 17% revenue growth, so perhaps a mere doubling is too cautious, assuming trading dynamics remain constant or cement prices rise further.
Steppe managed to increase cement prices in H1, with the average ex-factory price up from $36 per tonne to $39 per tonne (+11%), leading to a 6% increase in gross margin to 46%.
General and admin costs also increased (up 16% in USD terms), production costs rose 5%, and reported inflation was 7%.
Market update - The Kazakh cement market increased by 28% during the first half of the year and total cement consumption in the country is expected to grow to 11 million tonnes in 2021, an increase of more than 1 million tonnes from 2020. Steppe’s share of that market has fallen by 1.5% to 15% however.
Balance sheet - net cash of $7.4m, up from $6.4m a year ago. Cash of $9.6m set against $3.2m. Nearly $50m of property, plant, and equipment. Net tangible asset value of $63.23m. Cash conversion was strong too, with free cash flow of just under $7m being more that reported profit attributable to shareholders of $6.19m.
Conclusion
Steppe Cement continues to be something of an oddity on the UK stock market. A cement producer operating in Kazakhstan that began life in the 1950s under the Soviet Union and, more than half a century later, finds itself listed on AIM where, judging by the figures, it remains either forgotten or mistrusted.
It could be that this is a high quality asset. More communication with the market would be a plus. I’ve never seen an offer to watch the management present, nor have I seen any broker notes on the company. It makes you wonder why the company is listed at all.
The cement market is huge, but are there any barriers to entry? The company points to its low costs and location near the capital, which is rapidly growing. But then again, in a growing market, it has lost some share.
It looks like a well run cement producer and if commodities go on a run it could still prove to be undervalued. But with the shares having more than doubled recently it is not the clear bargain it once was on, say, an NTAV basis. And that’s realistically the point at which I’d be willing to spend more time on it.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

55 comments
Morning all,
Electra ( LON:ELTA )
This article is in today's Retail Bulletin and demonstrates Hotter further embracing the "on line department store" concept.
"Comfort footwear brand, Hotter Shoes, will next month (October) begin to sell its products via John Lewis online as part of its strategy to reach even more consumers within its core demographic of 55+.
Hotter, which sells 1.3 million pairs of shoes worldwide, has struck up its latest partnership as it expands and responds to changing consumer trends. The brand, which currently reaches 29% of the female population 55+, has heavily focused on digital transformation in the last 18 months and is seeking to underpin further growth by securing strategic partnerships with well-known complementary brands.
A curated selection of women’s and men’s Hotter shoes will be available on John Lewis online as both brands seek to offer wider product sets to customers. Hotter’s product strategy is driven by its unique proposition of customised comfort, precision fit and stability.
The prestigious partnership with retailer John Lewis is the third collaboration for Hotter in the last three months. In July, the business re-launched a selected product range on Debenhams.com, after the retailer was acquired by Boohoo earlier in the year. This month (September), Hotter has launched a partnership with online marketplace Zalando, one of the largest global online marketplaces, focused on European and UK markets."
Re Electra Private Equity (LON:ELTA) and Hotter specifically, I really like this part of the business (the old are rich and still underserved but getting into digital very fast). It claims to have contact details for 3.7Mn or 29% of women over 55 and email addresses for 8%. This is great.
However, in the presentation Paul references above, it includes this at 21.00 mins in
This worries me as it seems to fly completely against privacy concerns and I thought laws! Can anyone explain this? If I browse a site without registering, can they email me legally?
This worries me as it seems to fly completely against privacy concerns and I thought laws! Can anyone explain this? If I browse a site without registering, can they email me legally?
No. I think what "stimulating on-site email capture" means is that they're finding ways of persuading you to provide them with your email address.
The other part of the statement is also legal at the moment - "Technology to identify anonymous site vistors" probably means using a third-party that can triangulate your data (e.g. ip address) to a profile and then let Electra Private Equity (LON:ELTA) know what you're likely to be attracted to without telling them who you are.
You'll see this already when you browse Google for the mistresses' birthday present and then adverts for skimpy lingerie suddenly start popping up in other places when the wife starts looking for gardening implements. It can be very awkward.
The whole area of these digital marketing companies tracking online behaviour is bit murky, frankly. The government intends to reform GDPR which may make this more or less intrusive. If I were guessing I'd say more, but there are lots of caveats to that.
This kind of online tracking isn't so much common as endemic. It's not exactly a USP, just normal online merchant behaviour.
timarr
Re Electra Private Equity (LON:ELTA) (which I hold). My wife is part of Hotter's target demographic and she has bought Hotter shoes previously. She is inundated with email catalogues, mostly for sports shoes that she never buys. She has unsubscribed.
this is just what every up to date ecommerce site does. In English it means they try to show you more of what they think you like in order to get you to sign up for offers or news
The problem is, if I have to put my email in I rarely proceed any further, so they are losing potential sales. I give them my email only if I have to. Some are difficult to unsubscribe from, I got a load I think from some american site. They are wasting their time with me anyway.
Electra Private Equity (LON:ELTA) I agree with Paul here and think that holding ELTA has potential but may be a wild ride when the breakup happens. However I resonate heavily with his comment, having watched the video, I found it dripping with management-speak. I sometimes question if there is a clone school that produces these people with an inbuilt dictionary of semi meaningless phrases. I hope that they continue under the brand name 'Hotter', it's not particularly attractive, assuming a better replacement could be found but is hardly as meaningless as 'Unbound'. I also watched some time ago the presentation from Fridays. Again an awful lot of management-speak from a similar clone school and another meaningless name change proposed to 'Hostmore'. I think and hope that they will continue to badge themselves under the Fridays name as everyone knows who they are and what they do. As for the spin-off at Fridays, something to do with some numbers representing street names in the US, words fail me!
I conclude I am getting too old for this game, rather like Victor Meldrew.
GN
I agree with most of the above but i actually like the 63rd and 1st name , although i wasn't really taken with their website and the menu is different for Chobham and Glasgow , (does that work ?) , but trying to book a table gives the impression that they are pretty busy so that hopefully bodes well.
I think there could be a lot of upside at Hotter/Unbound , why does Womens make up 55% of sales and Mens 10% ? Surely if anything Men over 55 would be more likely to forsake fashion for a comfortable pair of shoes than Ladies of the same age ??
Thank God It’s Friday at 63rd Street and 1st Ave – Secrets of Manhattan (wordpress.com)
Maybe this explains the name.
Richard
Who makes up the other 35% of sales, if men are 10% and women 55%?
I always thought Hotter shoes were for women.
RayStraw, Yes the mens sales they need to work on. My wife has bought Hotter shoes at some time and I actually thought they were all Womens styles. I long ago abandoned looks for comfort so I guess I might become a customer.
I think there is a fair size market, I find most of the chinese or asian made shoes are too narrow for my feet, so I tend to buy shoes now that you can get in wider fittings, such as Clarks and NB. Not bothered about looks.
The consumer facing names will be Fridays and Hotter. The non-names Hostmore and Unbound are the holding companies the PE guys set up (for tax, admin & other reasons) including hoping to instill the belief that more standalone brands/companies can be added.
For instance Hotter is focused on shoes 55+ women. If they launched a new company focused on clothes for 55+ women, cross selling using the same email base but wanting a different name, they could.
Hi Zipmanpeter,
Sorry I only just saw your post, I duplicated it above before I'd seen it! Apologies.
Paul.
Hi GN100,
I think we need to distinguish between the trading names (e.g. Fridays, and Hotter Shoes) and the holding company names on the stock market. They're two different things.
For example, I suppose the Hostmore name was chosen because it sounds like something to do with hospitality, and the group company already owns 2 distinct brands, "Fridays" (they're dropping the TGI bit), and 63rd+1st (cocktail led bar/restaurants, new format, referencing a New York street address).
They're also considering small acquisitions, e.g. of small chains of bar/restaurants that don't have the capital to expand, and/or where owners want to retire, etc. So Hostmore could end up with multiple brands, all being rolled out. This is the perfect time to do it, with so many good, well fitted out sites available from landlords desperate to find a well-financed tenant.
Re the management-speak, I did flag this up to the company, in my feedback on the CMD. I said that a lot of private investors really don't like a lot of trendy buzzwords. I noted down a few from the Unbound CMD, for your pleasure & exasperation -
The Hotter Shoes stores are now being seen as "technology centres". not shops!
"We're re-branding comfort - to an enabling version of comfort"
"Changing gears in the presentation...."
Regards, Paul.
Paul - yes, I cringed at the 'technology centres' bit. That name describes more the McLaren version near Woking. However, I see the logic of different holding Companies. The acid test for us is if they make money and the SP's increase. Fingers crossed, I hold and could consider picking up some more if there are wild swings on the demerging
Retail sales figures were published today for August and they are down 0.9%.
However to quote the ONS web site:
https://www.ons.gov.uk/busines...
While we don’t comment on Boohoo (LON:BOO) here it might have a read across to small caps such as £SOS.
Regards
Michael
I have read somewhere today that "retail sales" are made up largely of Supermarket sales and these have dropped because people are eating out now instead of buying ALL their food at a supermarket . That is the main reason for the drop. Lies, Damn Lies etc.
Richard
Looking at the page I link to above they breakdown by:
Regards
Michael
I had listened to the Electra Private Equity (LON:ELTA) (I hold) recording earlier today and it’s a shame that they had not had the chance to read John Authers column (referenced below) before hand.
Richard
Richard - where is the reference to the John Authers column - I can't see it. A link would be helpful.
GN100
You can sign up for his free weekday newsletter here.
https://www.bloomberg.com/account/newsletters/points-of-return
I find it very useful.
I bought a very small position in Steppe Cement (LON:STCM) a few months ago to do some work on the stock but I sold them out again pretty quickly.
Jack mentions that the 2 operating dry kilns are well invested. This might well be true but was something that I was unable to verify. Hence my decision to sell out as I was completely unsure what was the expected life of the remaining kilns. Cement operation is a significant carbon producer and I had no information on the Kazakh environmental policies. So it just went in the too difficult basket for me.
My understanding was that the shut-down wet kilns dated from the 1960s - the 2 operating plants were first constructed in the 1970s.
My short holding period was over a dividend date and I did receive 100% of the dividend - there were no strange withholdings given its Kazakh/ Malaysian legal structure.
On the question of competition - I would generally think that the cost of transporting a heavy cheap material likely cement means overseas competition is irrelevant for a largely landlocked country such as Kazakhstan. Cement plants have to be close to the end-market.
If anyone has any information on the expected economic life of the remaining operating kilns, I would be interested.
Very pleased that you re going to update on ELTA Paul. I’m not sure what to make of some of the recent recent news. Also wondering whether the switch to AIM is a wise move?
Hi ken,
Hostmore (TGI Fridays) is going to list on the main market.
The rump of ELTA will only contain Hotter Shoes, so ELTA will be renamed Unbound Group, and switched to an AIM listing. Given that Unbound will probably only have a c.£50m market cap (my estimate), the AIM makes complete sense.
It's all going to plan, so there's nothing to worry about.
Regards, Paul.
HI Paul,
I hugely appreciate all of your and Jacks work - you have an amazing work ethic which I know myself and many others both appreciate and have benefited from.
I am not sure if I have missed it, but is there any view on what the mkt cap might be for Hostmore?
Thanks
K
Thanks KevinS1,
I am not sure if I have missed it, but is there any view on what the mkt cap might be for Hostmore?
Edison have published some estimates of valuation in their previous notes, but I'm not alone in thinking they might be too cautious.
Revised numbers are due out from Edison next week I think, so I suggest taking a look at their update note at the time.
Personally when I crunched the figures, I think ELTA could be worth 1000-1200p given some time for the 2 individual shares to settle down. But that depends on what appetite for the individual company shares there is, which is completely unknown at the current time. We'll just have to wait and see what Mr Market thinks in due course!
Regards, Paul.
As tweeted by @InvestinHenry, the best ever Games Workshop (LON:GAW) TS that never was...
https://investor.games-worksho...
And it was posted by Games Workshop (LON:GAW) on the Investor Relations part of their website on the same date as their relatively uninformative real TS.
Proton Motor Power Systems (LON:PPS)
The value of customer quotes is significant, at 45m Euros.
This line makes me think this company will turn up on the next episode of Dragons Den cap in hand - hmmmm is my memory failing or did one listed company actually turn up on dragons den with their cap in hand?
Morning All
re Pci- Pal (LON:PCIP) - an RNS came out yesterday that Semafone are suing PCI for a supposed infringement on their patented product. I followed the art of execution and swiftly sold at a 15% loss as I wouldn't currently invest in a company with that overhang (I will happily buy back in once the issue clears)
but i'm wondering if anyone here has any different views on the matter?
Re Pci- Pal (LON:PCIP), not sure if you saw this comment from Barnakles posted at 10:23 in yesterday’s SCVR:-
“Interestingly, Eckoh and Semaphone settled their dispute over this same patent in 2015. "In consideration of the licence, Eckoh will pay Semafone royalties in respect of the patents."
Haven’t looked further into it but looks like a fishing trip by Semafone to wheedle some cash out of Pci- Pal (LON:PCIP) rather than a company business breaker. I’ve retained my small (now smaller) position as a marker for a possible increase depending on how the issue is resolved.
Gus.
re Pci- Pal (LON:PCIP)
Thanks GUS. Problem is how much will the royalties eat into PCI's margins? Isn't it guess work at this stage?
Also it appears PCI will be fighting Semaphone til the end as they vehemently deny the allegations so they will be going down a different route to Eckoh. Seeing as both parties feel pretty strongly about their case without being a lawyer and fully understanding the tech I felt the best course of action was to sell out and let it play out - which is a shame as i really like the company
As soon as there is a positive development i will be buying back in with a bigger stake (assuming the price is still below ~80p/sh)
I've dug into this a bit further, here's PCI-Pal's patent in question (status: pending)- which actually cites Semafone's one (status: active) which they claim is being infringed. Without any expertise personally, it's a coin-flip which way this will go, but you are correct that the SP will be under a cloud until the uncertainty around it clears (could be a year or more?) so your strategy makes a lot of sense.
Basically though, Semafone are claiming they have the rights to the tech that can mask the touchpad tones (DTMF masking) from the call centre agent when you enter your card number over the phone. In this way they can protect your sensitive information. However, a quick google search shows that this tech is quite widespread and widely implemented - there are at least 5 or 6 providers that utilise this tech for PCI DSS compliance. PCI-Pal even have a page on their own site explaining it, so they must be reasonably confident they aren't breaching anyone's rights by using it.
On balance I am erring on PCI-Pal's side here, and if the SP dropped to the low 70's it would be very tempting to pick up some more. I only have a starter position so I'll just leave it to keep an eye on developments, like Gus. Interested to hear other views, particularly if anyone has experience in patent law.
As an aside, I renewed my car insurance (Aviva) last week, and used this exact tool to pay by phone, and it works like a charm. What makes the experience so smooth is you don't feel like the agent is transferring you anywhere - it is a very seamless handover and handback from the payment processing service. There's no requirement to press hash after entering the information, and at no point does it feel like the agent has left the call, they guide you through each step, and can interject (I presume) if there are any problems. It's a much more satisfying and secure experience than any other phone payment systems I have used, automated or no. It's only a matter of time that this becomes the de facto way card payments are taken over the phone IMHO. Unfortunately the agent didnt know if it was a PCI-Pal system or a competitor's.
However, a quick google search shows that this tech is quite widespread and widely implemented - there are at least 5 or 6 providers that utilise this tech for PCI DSS compliance. PCI-Pal even have a page on their own site explaining it, so they must be reasonably confident they aren't breaching anyone's rights by using it.
You need to be careful about this - not all DTMF masking is equal and not all is PCI compliant:
https://sabiogroup.com/blog/ne...
There are ways of working around DTMF for PCI other than Semafone's but at face value the PCI-PAL solution looks very similar in approach.
As it happens I know the Semafone people, they have an office around the corner from ours. They're not the "fishing trip" kind, so I'd be inclined to take it seriously.
As I have no interest in Pci- Pal (LON:PCIP) then I have no idea if this is material or not, but I'd certainly assume there'll be some costs associated with defending this, the Semafone team are not the sort of people who will back down because someone waves a lawyer at them.
timarr
Some interesting research quoted by John Authers in his article today that confirms superior returns from investing in companies where the CEO can explain the proposition in simple terms.
It uses the Gunning Fog index. Out of interest I pasted in some SCVR articles and it takes 12 years of formal education to read the SCVR - about the level of a school leaver which I think is great considering the subject matter.
Hi JohnEustace,
Out of interest I pasted in some SCVR articles and it takes 12 years of formal education to read the SCVR - about the level of a school leaver which I think is great considering the subject matter.
How interesting, thanks for sharing this.
Ed did something similar a couple of years ago - using an automated tool to assess the various writers on Stockopedia. Pleasingly, I came out with a fairly good score, with relatively short & simple sentences. Plus a vocabulary that is readily understandable by anyone of teenage years or above. That's very much my intention - making a sometimes complicated subject accessible to pretty much anyone interested, which is really important.
Regards, Paul.
Hi Paul Scott /John Eustace,
I have learnt so much since I started reading SVCR. Initially so much was new, some of which I understood easily and other parts not at all. I have developed my understanding substantially and my performance immeasurably.
Thanks to Paul Scott, Graham Neary and more recently Jack Brumby. Also to the many subscribers who contribute here.
Michael.
0O76:LSE AP Moeller - Maersk A/S
Why can't I find this on your site - I think this could be a good share to invest in and want to add it into my portfolio.
For Maersk try https://www.stockopedia.com/sh...
That's the Danish listing and I'm interested in the LSE one.
Morning Owen - Have you tried the Green "conversation button" to ask the Stocko Team direct, rather than a blanket question to the audience?
Normally bottom RH Corner on a desktop - They are usually very pro active in responding
Or type 'Maersk' into the search box.
Yes you can indeed to that and it only shows the Danish listing - but I'm interested in the LSE one.
If you search the LSE site you’ll find they hold no data on Fundamentals or Analysis either – hence none on the UK section of Stockopedia. To get the Stockopedia data you’ll have to subscribe to the European section.
morning fellas thanks for all of your hard work. Would you be able to give some thoughts on Steppe Cement (LON:STCM) this morning please? Thank you, andy
Volvere (LON:VLE) H121 results today (I hold).
Shire results inline Id say... decent growth at 15%, and although they sound a cautious tone on margins perf is good. Still decent op gearing as growth comes through, so as long as it keeps growing, there is potential here esp in H122 numbers. A full year operating profit north of £2m to shoot for...which is a nice return on accounting asset value of £10.54m. I mention this just to highlight the obvious value building relative to NAV.
Indulgence also did well with Revenues doubling to £1.86m and a halving of the loss to £0.36m. Hard to say what revenue will be in the second half...my guesstimate is that they probably need to do about £4m compared to £2.7m 2020....to breakeven for the half...thereby setting the stage for 2022. We will see, clearly early stage and reliant on a return to health of the hospitality sector.
It seems to me in aggregate you have £2m as short term profit benchmark to go for and could get to £3m relatively quickly as operational gearing at Indulgence comes through. So in 12 months maybe revenues of £42 - £43m. Clearly plenty of value...
The real kicker will come through when the cash £23.13m gets deployed and generates some fizz around new investments. Whilst frustrating that there is nothing to talk about yet, its a free option. Also the cash will be a useful buffer should the market wobble. Until deployed I would view the shares very defensive, with little downside. No bad thing.
Re Volvere (LON:VLE) , nice summary. It's been a frustrating holding but I agree there's certainly long term value here and to some extent they've been unlucky with Covid and the government support has clearly depressed further acquisition opportunities.
Today's update sounded some notes of caution around competition for shelf space in the vegan food sector and it's yet another company highlighting increased labour costs, staff shortages, rising input costs, logistics and Brexit / Pandemic issues.
I'll be happier once they finally get to deploy the war chest but I'm certainly going to remain patient for the longer term value to out, especially given the credibility of the management here.
On a broader point following on from some commentary yesterday, I also would like to add my huge gratitude and respect for Paul and Jack's immense dedication and work rate. Even on the days when I all too frequently neglect to add my thumbs up, I cannot overstate how much I appreciate their daily contributions. Sincere thanks.
Does STCM have much more upside? It's still a Kazakh cement co. You can probably go Hong Kong or emerging market exchanges and buy cement cos at 2xPE.
Morning Paul, Jack (and Roland if you're reading), I just want to say thanks for all your hard work over the last few weeks staying on top of all the RNSs. I hope today is an easier day and you get to finish early and enjoy the weekend.
Morning Paul/Jack,
I accept your thoughts on natural resources but some broad general thoughts would be welcomed bearing in mind the current record highs for some of these natural resources and the impact of this on, for example, the move to electric vehicles and need for improved battery life etc etc. Like I say, no need to mention any specific companies....just your thoughts. Natural resources is becoming an increasingly more important (and volatile) sector.
Thanks for your continued knowledgeable and helpful daily comments and thoughts.
As it is broad thoughts you are after, perhaps this is one for a separate discussion thread. I have views and relevant holdings, but it's not really SCVR territory. As Paul says above in the share he examines, Proton Motor Power Systems (LON:PPS), the company's actual current performance diverges so far from the price evolution, that determining a current value requires a lot of crystal-ball gazing. Interestingly, there are economic parallels between some of these new energy shares and actual mining explorers (and drug developers). We may all be happy to have some 'jam tomorrow' equity, but I think you'll find even the brilliant Stockpedia can't give meaningful valuation help, because their hoped-for cashflow and profits are in the future.
Cracking interim results from Steppe Cement!
I hope you mean ‘stunning’ or ‘excellent’ results from Steppe Cement (LON:STCM) EB&B but hopefully not ‘cracking’ Sorry folks just lightening the mood after my volatile week.
Steppe Cement are so low under everyone's radar there might be a danger of them hitting the ground!!! Hopefully a perfect landing!