Small Cap Value Report (Fri 18 Aug 2023) - EMAN

Good morning from Paul!
I'm a bit preoccupied this morning, as I have to accompany a loved one to hospital shortly for a routine operation. So I might have to find a quiet corner there are do some more updating of this article later, so please bear with me. Although looking at the state of the market, everyone's probably hiding under the kitchen table, trying not to look at your computer screens! There's not much news today either.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £1bn. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk.
Everyman Media (LON:EMAN)
Down 2% to 59p (£54m) - Trading Update - Paul - AMBER/RED
I’ve been increasingly negative about this cinema chain, because it has failed to demonstrate that it can make any genuine profits, trumpeting meaningless EBITDA figures instead. The pandemic disruption can be allowed for, but that's over now, so it should be profitable now (but isn't).
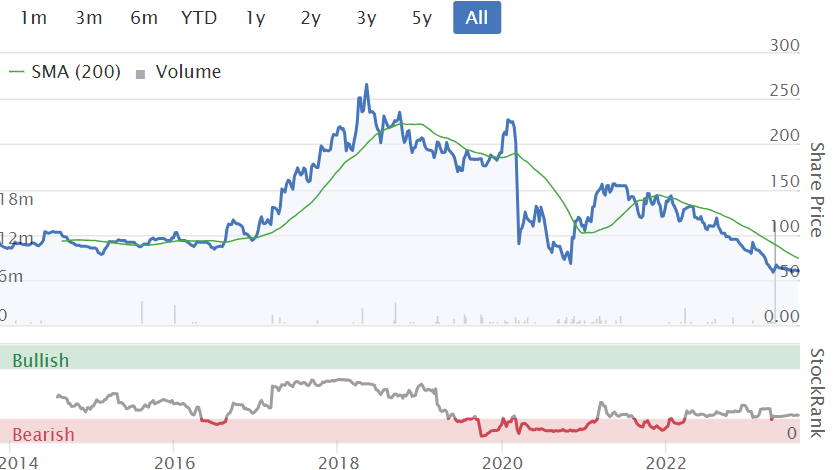
As you can see, since it listed, positive investor sentiment gave way to a hammering in the pandemic, but a failure to regain traction since. It’s just not a very good business model in a nutshell.
New Banking Facilities - maybe I’m missing something, because the banks are happy to lend substantially relative to the market cap -
Everyman Media Group PLC (AIM: EMAN) is pleased to announce that on 17 August 2023 the Group agreed a new three year loan facility of £35m with Barclays Bank Plc and National Westminster Bank Plc, extendable by a further two years subject to lender consent. The facility ensures that the Group is soundly financially structured and well positioned to take advantage of opportunities moving forwards.
The new facility replaces the existing £25m Revolving Credit Facility and £15m Coronavirus Large Business Interruption Loan Scheme ("CLBILS") held with Barclays Bank Plc and Santander UK Plc.
We’re not told anything about the terms though. Debt is getting a lot more expensive these days of course, so I wonder if EMAN is generating a sufficient return on investment to justify rolling out more sites?
Trading Update - for the 26 weeks ending 29 June 2023.
It’s in line with expectations -
Trading continues to be in line with expectations and the Board remains confident that the financial performance of the Company for the full year ending 28 December 2023 will be in line with market expectations1.
1 Current market forecasts for the year ended 28 December 2023 are revenue of £94.4m and Adjusted EBITDA of £17.2m.
As I’ve mentioned before, the trouble is that this is a capital-intensive business - opening new sites is very expensive, and the fit-outs then have to be expensed through the P&L each year with a heavy depreciation charge - which reflects the expected use & life of the capex from eg. wear and tear.
This remains the case, with Canaccord’s spreadsheet (many thanks) translating adj EBITDA of £17.2m into a profit of…. nothing! Actually it’s an adj loss before tax of £(0.9)m.
Paul’s opinion - remains negative. I cannot see the point in rolling out a format that doesn’t make a profit. Remember the above forecast is for the full year, so that takes into account the expected H2 weighting to film releases. Barbie & Oppenheimer have been good in July it says.
The only bull case I can imagine is if there are benefits from increased scale in future. In that case it might make sense to roll out more sites.
This share seems to me a worrying example of how fixated with EBITDA the city, and the banks, have become. It’s not real profit in a capital-intensive company, although you can argue it’s a proxy for cash generation if the business were to stop expanding, and if you ignore things like finance costs and tax (which have to be paid out as cash in the real world, so why ignore them?).
There’s also maintenance capex to take into account. Cinemas get a lot of customer wear and tear, as does any site that has large numbers of people going in and out, spilling drinks and popcorn everywhere, constantly rustling crisp packets and sweet wrappers, and coughing, and lighting up their mobile phones during the film. etc.
It’s useful to be reminded of this famous quote every now and then, which I just looked up on google -
Warren Buffett: "The tooth fairy does not pay for CAPEX. We have to account for it to assess a company's true earnings power." The same point applies to sales and marketing expenses. Both CAC and CAPEX are real cash out the door up front, which is the worst type of expense.
For me, any retail/hospitality type roll-out investment (ie where you’re investing in the upside from growth in site numbers) has to move into proper profits (PBT) by the time it’s got to say 40-50 sites. If it’s not profitable by that size, then it probably isn’t a very good business model. Look at how profitable the bowling companies are, each extra site loads on more profit, they’re cash generation machines. Compared with that, EMAN’s numbers are almost a joke.
I’d be happy with EBITDA if the site fit-outs were modest, and funded by landlord contributions (as for example XP Factory (LON:XPF) [I hold] is doing). But EMAN’s site fit-outs seem very expensive, leading to the need for borrowings, and EBITDA is completely consumed by the depreciation and finance charges.
Another drawback is that the big capex obviously has to be done up-front, before the business knows how a site will actually perform. Front-loaded, heavy expenditure, with uncertain payback - not the best business model. Also once a lease is signed, the tenant is locked in, regardless of how well or badly it performs. So many multi-site businesses collapse because of a small number of really bad leases signed at the top of the market, that they can't get out of, and landlords seem less inclined to agree to CVAs these days, to let tenants off the hook.
Despite all my misgivings, with the banks clearly viewing it positively, and trading in line, I don’t suppose I can justify staying at RED, which we normally reserve for companies where something is badly wrong. But I’ll keep a moderately negative view, at AMBER/RED. It’s a nice format, with a premium seating and food offer, but it doesn’t make a profit!
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

53 comments
This week's podcast went up last night (Saturday). I'm just doing 1 podcast each weekend now, have ditched the macro thing, as it was too repetitive! No mystery shares this week. I comment on market conditions, and investor gloom.
It surprises me how gloomy a lot of the comments are in this thread here. Equities are volatile, and go through bearish patches every now and then, it's completely normal. If you've picked decent quality companies, and they're cheap, soundly financed, and putting out reasonably good trading updates still (as many are), then cheap valuations are a positive thing - giving us the opportunity to load up on the best ones, and lay the groundwork for superb gains in future. I've seen that cycle play out multiple times before. We'll look back in future, and ask ourselves why we weren't loading up on cheap, good quality companies, when the opportunity was there on a plate! They could go down for a bit longer, but I think there are 3 very clear reasons why UK small caps should be at or near the bottom of the cycle now -
Of course we all like to check our portfolios frequently, and get a sugar rush when we have a good day, and feel a bit grumpy when we have a bad day. But unless you're a short term trader, it really doesn't matter what the day-to-day share price is doing. I'm really enjoying not using gearing any more, as I can totally relax owning shares outright, as nothing can happen in the market which would ever make me a forced seller now. That's really liberating actually. I just keep on top of the fundamentals, and carefully read the updates that come through by email for the companies I follow, and then can sit back and relax the rest of the time.
Also looking out for the many new opportunities it interesting & quite exciting. We spotted 3 interesting ideas this week, all of which ended the week up -
Gaming Realms (LON:GMR) (I hold) - continued big Director buying (over £100k each time),
On Beach group (LON:OTB) (I hold) - massive Director buying by the founder (now a NED) of £2.5m, was an open invitation to follow him, in my view. Appears very shrewd, as he sold at a much higher price. So if he's buying now, I want to follow suit (especially as we recently had a discussion here whether several readers where pondering if it was overdue a bounce. The huge Director buy is the catalyst I think, so I like this one now.
Restore (LON:RST) (I hold) - this had come up on my watchlist as a constant faller, and I was worried about the bank debt. So I prioritised it this week, and rushed out a review here by 8am on the morning of its interims, and found an interesting situation where results/outlook reassured. Also I forgot to mention that it had previously received bid approaches (rebuffed) at a much higher price, so bid interest could once again return maybe? The core business seems to be doing OK, and the debt doesn't look ruinous, with even a reduced divi still being paid. So I think we might have been a turning point. It bounced nicely, up c.10% already, even on gloomy Friday rising further. So again, I think this is a nice trade. Not sure I'd want to hold long-term.
We'll keep flagging up trading ideas, as there are lots being thrown at us at the moment.
Even Kin and Carta (LON:KCT) was a significant riser, after putting out a better than expected H2, due to cost cutting, which I also covered here. Although we don't think much of that share, so couldn't bring myself to buy any, even though it was ahead of expectations. It will be interesting to see if the c.20% bounce actually sticks, or if people sell into the rally, which is what I'm seeing happening almost everywhere right now. You can't blame people for warning to snatch a quick profit, given how few shares are sustaining the rallies.
I hope you're enjoying the weekend! I just need to update my SCVR spreadsheet next.
Best wishes, Paul.
Thanks Paul, totally agree re ebitda this should not be a used to measure business especially ones that are capex intensive like cinemas + other hospitality businesses - expect most of these buinsses get bonuses on ebitda targets that can be manipulated to hit said target.
I don’t understand what ‘adjusted ebitda’ means to anyone……so ignoring any capex even for things that mean buiness cannot happen+ exceptional items….. this must be a fudge . I am finding it difficult to work out what to look at since IFRS16 for business with a lot of leased property.
As for Everyman cinema i quite like their offer + think they have a bit of a different offer to other chains + they have the backing of some very experienced investors. But definitely need to show a profit soon!!
Difficult times, especially for UK small cap (including AIM) investors. Still this is when one can lay the groundwork for future profits.
The family portfolios I run are all in ISAs and in the main remain fully invested. They are almost exclusively in small caps with a few FTSE250 shares. The maximum portfolio size is 30.
As for me and my approach. I avoid mining, biotech, banks, oil, gas, munitions and tobacco stocks, either because I don't understand what they do or because I prefer not to invest. However I appreciate that others may take a different view. Each to their own.
My first port of call when assessing a potential investment is the balance sheet, particularly debt. I tend to avoid overly indebted companies. Most of my investments are cash rich or have little debt.
I don't use stop losses. I agree with Peter Lynch that if you buy a stock with a stop-loss of 10%, the only thing you are guaranteeing is that you'll lose 10% on that trade. I think that this is especially true in a bear market. To further paraphrase Peter Lynch I try to concentrate on what is know rather than speculate about inflation, future interest rates etc. I am fairly certain that the Bank of England doesn't know where interest rates or inflation will be at the year end, so what chance have I?
I have recently been buying some REITS, investment trusts and infrastructure funds, e.g. Harbourvest Global Private Equity (LON:HVPE) TR Property Investment Trust (LON:TRY) Palace Capital (LON:PCA) and NextEnergy Solar Fund (LON:NESF) as most of have endured a fairly torrid time and appear to me as offering good value despite the interest rate climate.
Top 5 holdings ARE Volex (LON:VLX) Avingtrans (LON:AVG) Howden Joinery (LON:HWDN) Ten Entertainment (LON:TEG) Bloomsbury Publishing (LON:BMY).
The cycle will change, as that is what they do. When the pendulum swings it is likely to do so rapidly and with little warning.
Just my tuppence worth. I don't have a crystal ball which is just as well because I am not sure it would help!
I wish everyone well.
I hold 4 out of those 5, Volex (LON:VLX) and Bloomsbury Publishing (LON:BMY) are in my top 5 small caps.
Ten Entertainment (LON:TEG) I don't but is on my watchlist, I see it was down over 10%, can't see any news.
Bloomsbury Publishing (LON:BMY) was also down quite a bit.
I'm down 0.9% for this year. Around this time last year I was down for the year by 29% at one point, ended the year down 8%. If I look at a rolling 12 months, then i'm up 8%. It seems to be a game of wack-a-mole at the moment.
Really needed to read this thread today after such a bad few weeks, hell a bad year!
Like most people on this thread I’m down, in my case 6.6% YTD across my portfolio of stocks, REITS, Commodities & Funds.
It’s forced me back to basics and made me tighten back up on my own rules, things like always having a stop loss, where sometimes I had not bothered despite knowing I should.
Having target prices to force me to reconsider rising shares.
It’s tough when you’re doing this alone so this forum and the honesty from people when they are doing well and badly is great inspiration and helps you to realise you’re not alone!
7% down is completely normal. If it is causing stress you need to reduce equity exposure and diversify more. 40% fall is not unusual, I have suffered this many times
Good trading rules today. Makes a lot of sense. I think Mark Minervini is the best subject matter expert on trading and his books are a great read. I'm not really a trader myself but do look at the chart and whether its stage 1 or 2 or a dreaded stage 4 when buying, and sometimes when selling.
Well its been a very poor week - it often happens in August whilst people are on holiday and there is no liquidity and very little buying. One gets the feeling that the market is also starting to think the economy is starting to roll-over. I personally think c6% interest rates will be the top as I can't see the real world taking much more without things breaking big time.
My portfolio is down c2% YTD but my projected dividend and interest income is up 8%. We all hate our portfolio value going down in value, particularly after an ugly 2022. As a dividend investor, when I'm doing rubbish I try and focus on my dividend income which is much more stable - it makes me feel that my approach is still working long-term. This might be of some help to others as two years of market pain is getting a tad depressing, and there is possibly more pain to come if we get a harder landing.
Mark Minervini is a huckster at best
Hi Ben - lol, not seen him that bad before and certainly not the best interview from him, that's for sure! I suppose everyone has a bad day.
We will have to agree to disagree on Mark Minervini though. I'm not a trader, but I learned a great deal from his first book "Trade like a Stock Market Wizard". The original material was from Stan Weinstein, but Mark definitely improved it. I would say that his book is probably one of the best investment books ever written, and I've read a few!
Marks and Spencer (LON:MKS)
https://corporate.marksandspen...
I didnt read anything about this in this weeks trading update but it is on their investor relations section that Marks and Spencer plan to reinstate the dividend in November.
Arbuthnot Banking (LON:ARBB) down 11% on seemingly no news
mr market clowning this morning i see
A tiny 7000 shares traded. MM don’t want stock and just walk the price down on every small sell which panics other holders into selling.
£17m of the market cap wiped off from £70k worth of volume. It’s nuts but it is what it is. August often like this
indeed, the stock is quite illiquid
but even so - complete silliness as you say!
why? well even the most brief look at their recent half yearly report would tell you they absolutely smashed it out the park...
Definitely a day for mystery shopping in Weatherspoons , but not with the Daily Mail
This morning's RNS:
While the Company's prices do vary from location to location, a price survey carried out by the Company's pubs into pricing at their nearest competitors in April 2023 showed that the competitors' drinks prices were, on average, 43% more expensive than Wetherspoon and competitors' food prices were, on average, 33% more expensive than Wetherspoon.
Wetherspoon chairman Tim Martin said:
"Wetherspoon has identified a number of errors in recent Daily Mail articles. It is important for the press to maintain a reputation of providing accurate information for the public."
I started trading IPOs and privatisations back in the '80s before Black Monday took the shine off the market for a bit. Currently clinging on to 3% YTD gain, which helps to soften some of last year's 20% hit.
Took up my current Stocko sub about a year ago and find the rankings, together with the SCVR have helped my decision process, as have the comments from the community, highlighting resources as well as company information.
It's tempting to top slice winners when the market's like this, but probably more useful to just accept that the short term value of some of those "recovery" holdings, nursing 30% losses from poorly timed purchases, is that they have failed to move this week. Realising these losses to fund purchases of winners in the dip makes more sense to me, so sold down Keystone Law (LON:KEYS) to top up Wise (LON:WISE) and open a position in Tracsis (LON:TRCS)
Off to Leicester Square for an all day breakfast and £7 pint of Leffe.
My 2 pennies. I'm looking at companies that announced good results, shares went up but are now retracing. E.g. Bank of Georgia (LON:BGEO), Volex (LON:VLX) , Oxford Metrics (LON:OMG) 4imprint (LON:FOUR) Card Factory (LON:CARD) . If i can get in at the price before the results came out I feel I got a good deal. No idea if this strategy will work!
I hold Bank of Georgia and have done well with them. Hopefully more good times ahead
Volex (LON:VLX) is my largest holding. I suspect markets will bounce early next week so today might be a good buying opportunity for the bold.
A few points Id make on today's discussion coping with falling markets. These are just my thoughts, everyone has there own risk tolerance and style.
1. If it's making you stressed or unwell, stop. Can have all the money in the world, but it's no use if you're unwell or depressed.
2. Ask truthfully if you can beat a global tracker ETF or S&P ETF over the long term. Most fund managers can't, so is it worth the hassle and stress? Maybe better to just drip feed cash into an ETF over 10+ years. No hassle. No profit warnings.
3. Stop buying companies against the trend. You're gambling you know better than the market, many are value traps. If the trend is down, the earnings trend will also be likely be down. Use Stocko EPS forecasts graph, it's invaluable.
4. Buy companies with rising or recovering EPS graph, positive newsflow and positive looking chart. Moving averages rising or starting to turn. Buy strength not weakness.
5. Use a stop loss. Set it at whatever level you like but have a line in the sand. Don't hope, take control of what loss you'll take.
6. Ignore the media, tips or anyone's elses opinion. Stick to your own plan.
7. Have a plan. Go through negative scenarios in your head before buying, decide then what you'd do if the worst case scenario happens. Upside will take care of itself.
8. Protect your money. Don't let it dribble away week after week. If somethings not working stop doing it. Either change what you're doing or sit in cash for a bit. The markets always there, don't have to be all in all the time.
9. Dont be stubborn and think you know best. I'm wrong probably half the time. It's just part of trading, I've had to accept it. I've no problem being wrong, but ignoring my stop losses or being egotistical is idiotic.
10. Ignore what CEOs say outside of RNS releases. Don't fall in love with a company. Ive no interest in becoming a part owner. I've bought some numbers which I think will be higher numbers in 6-12 months when I sell.
11. Pace yourself. This in the longest Test match you'll ever see. You'll have periods of time when you need to be defensive to see off the new ball, then knock it around for singles for long periods and occasionally times when the bowlers tire and you can go all out attack, looking to hit sixes and it's all incredibly easy. Do whatever it takes to stay in the game.
12. Always learn. 2022 forced me to learn shorting properly, I'm nowhere near as comfortable or competent as going long so it's a work in progress. Really investing is a neverending process of gradual improvement so takes many many years to feel comfortable. I've been doing this since 2000, seriously since 2008. I feel maybe 60% to where I'd like to be, so still lots to learn.
Here here, terrific post!!
This is a great set of rules for trading. But it's not investing.
Many thanks for your checklist Wolfie, PI’s will be finding it to be quite pertinent. I have matched it with my actions and am noting a disparity. Today is a new day and just as likely a new direction taken if not already decided upon.
1. I’ve worked where I‘ve been going wrong and confess to having been stressed out and having interrupted sleep at times.
2. Beating any target has proved impossible.
3. As a Contrarian I grew numbers, but they were in a kennel, I’m trying to stop feeding them now (not doubling-down).
4. It just happened that I performed a big new research yesterday and today as a result sold 3 positions and added to two already held. Who knows what the result might be.
5. I never use Stop-Loss’s, things did get out of hand. Still are.
6. Fripperies like Red Hot Rockets and such-like have been given up and I’ve learned to my expense to treat all commentary with utmost caution.
7. My Plan is to beat the Opposition but there is an awful lot of it.
8. Dribbling money away makes me think I’m in my cups if you know what I mean but at least I’ve been consistent.
9. My kind of stop loss ends with the Company in bankruptcy. Someone described me as being a Stoic (I was in hospital), being stubborn helps.
10. It’s noticeable today and every other day by the RNS’s that Company Directors love their Company and keep on buying back its own shares and at 79 yoa I’m not sure this will be of any benefit to this shareholder. But as you say, Wolfie, there’s still lots to learn and strive for.
Wise words and a great post!!
Just wanted to say a big thank you to everyone who took the time out of their day to responded to my earlier message. Hearing the advice, support and personal experiences of the investors here is what makes this community very special. Thanks again. Ben
No problem - to give you some liquidity examples being out of kilter
Arbuthnot Banking (LON:ARBB) has been marked down 6% on just £50k worth of stock - that’s a £10m market cap reduction for 5,000 shares changing hands
Bank of Georgia (LON:BGEO) has been marked down 8.5% or a drop of some £150m+ despite superb results yesterday - number of shares changing hands = 38,000 - so £1m of stock
You can see how prices are currently being driven by tiny volumes because liquidity is on the floor.
I have managed to sell off my overly large holding in Rua Life Sciences (LON:RUA) at a thumping loss. I think it must soon hit the buffers having tried unsuccessfully to raise cash for over a year now.
I wonder whether one reason for the decline of the LSE is that it perhaps has a higher proportion of its available capital in the hands of predators who lend for control rather than income? Rua Life Sciences (LON:RUA) 's potential seems real - I can't believe the money isn't there.
I started investing around about 2000 - dot.com time - dabbled very low sums in individual shares but gradually moved to being 100% unit-trusts.
Around Covid time I started my stocko subscription and had a great 2021 - like many others believing I was the next Buffett.......soon to realise I wasn't Buffett, but a simple Buffoon.
I have slowly been moving back to a more sensible spread of Investment Trusts, ETF's and some Unit-trusts (but very high costs so I only pick a UT if there is a strong reason) with about 40-50% in individual shares (all sm-cos).
My ATH was June 2021 since when I am down about 20% - of which about 6-7% is this YTD.
I cannot see any other option but to top-slice some gainers to hold some cash and await the bounce - I am normally 99% fully invested.....although I might simply leave things alone and not crystallise a loss, but haven't really sat down and analysed my PF for a few weeks.
Like most on here I am now very focussed on cash-rich holdings, paying a decent divided with a good SR, but still haven't learnt to do this effectively all of the time, so am still holding the odd stinker.
I have this morning also closed my SB a/c and given up ever using it again - I was doing OK trading indexes, but as usual took my eye off the ball and missed the recent DAX & FTSE drops creating a margin call. Advice to anyone who needs it - don't use leverage (as I've heard many times and ignored it!!!).
The markets will come back - they always do, but who knows if there is a lot more pain to come first, or will we simply tread water for a lengthy time or will they bounce later this year. Who knows, but you can create long-term wealth by being patient, not betting on jam-tomorrow companies, compounding over time and harvesting some decent dividends I hope to look back on this period in five years time as simply another "blot" on my PF as it was in 2018 & 2022 when I had down years (full records only kept from 2011), albeit a slightly more painful one.
Good luck everyone..........things can only get better (I hope).
Yes, this has been a bad week Ben. But don't worry, there will be plenty of worse weeks to come in your investing career!
As for when things might turn around. Nobody knows, but seasonally this is a weak time of year for stockmarkets. Seasonal trends seem to be very strong in the stockmarket, though the reasons are unclear. Winter and spring are usually the strongest times of year, so perhaps things will pick up soon. Having been outside earlier today, it certainly feels like winter is coming.
What is of more concern to me than the short term weakness is the long term decline of the UK, and indeed the western world generally. The UK stockmarket has been underperforming the USA for decades now, and the UK economy has been doing likewise. We don't discuss politics on these boards any longer, so lets not speculate on the reasons, but as long term investors we cannot ignore these trends.
So for me, while I think this current bear market might end soon (October to April/May is seasonally a strong period) the long term trends are still worrying.
Now that wage growth is outpacing a rapidly falling headline inflation, we are either going to get a strong economic recovery or wage inflation is going to rapidly slow as well.
I would say the latter is much more likely as unemployment is clearly rising and the most forward looking survey data suggests a rapid cooling in the jobs market is already happening :
"For instance, the net balance of recruiters reporting that salaries are rising for new hires fell to a 27-month low in July, and now is below its average in the second half of the 2010s, according to the report on jobs survey.”
The factory gate input measure is another leading indicator that takes some time to feed through into consumer prices and it is also in outright deflation now.
The tech sector is very much in the doldrums in terms of jobs - I've got quite a few friends who have been on the bench for 6 months or so now and there's no sign of things improving. I've definitely noticed a change in recruiters who talk to me. A year ago they would have been trying to get me to move to a new job. Now they are all trying to place candidates.
Since I started investing at the start of 2022 I think this has been the toughest week I've had. About a month ago when inflation fell more than expected I had a real optimism that a turnaround was coming. This optimism has been drained along with the SP of a lot of my shares. I find myself nearly 10% down YTD with Watkin Jones (LON:WJG) and Mobico (LON:MCG) making up around half those losses. I've found myself checking the intraday movements more than usual, just hoping for a green day to stop the bleeding, which I know is both fruitless and detrimental to my mid term strategy. I think in many ways I find big legs down on clear bad news easier to swallow, it's the gradual drops I find harder to stomach. How have others faired this week and what are people's thoughts on the coming weeks and potential events to encourage a reversal?
My current mentality is you’ve got to ‘stay in the game’. De-risk your portfolio and look to tread water or lose a handful of %. The bounce back when it comes will be rapid…we just don’t know when it is. Im 20% cash, 40% fund based, 40% direct equities. Majority of my equities have a stockrank over 90 and positive technicals.
I know how you feel Ben! I started investing at the end of 2018. 2019 was flat. My highest point was in 2021, when I had gained 36% and then its been all down hill from there. My lowest point was Oct last year, where my overall performance from the start had lost 40% of money I had put in (a massive swing!)
Since then, I have been paying more attention to the stock ranks. Not going to company presentations (its far too easy to buy a good story). Looking for stocks that have Net Cash and are not loss making (burning cash). Looking for good dividend payers, to help support the portfolio and looking at the NAPS approach. My portfolio has now bounced to a 28% loss.
I'm also fully invested. I struggle to hold some cash as I fear I'll miss a bounce. Although, when stocks do drop, then I can't act. I still have patients to learn :)
I think its a matter of holding on, accepting your mistakes (trying to learn from them) and also realise we are in a bear market. Its a long journey!
I've been surprised by how many companies are generating good growth in income and profits against a very difficult backdrop (especially in the UK). That doesn't protect though from a general reduction in valuation which we have seen over the last year or so. I invest almost 100% in UK small caps and its been a very challenging period, but I keep buying from fresh contributions to my SIPP to average my position and remain fully invested throughout, not being clever enough to time the markets.
The market has been a challenge for the last couple of years nad picking winners isn't easy. Sometimes it's best to adapt your strategy. Across the portfolios I manage (miner and a family member's) I shifted concentration away from so many AIM stocks and small caps to focus more on FTSE250 mid-caps and divi payers. When those prices are falling those divis provide some solace.
AIM All Share index at a 7 year low excluding the few days after Covid. Sadly it looks like Scotty's optimism (along with a lot of us) was misplaced. But I guess we're stuck now and have to hold for the inevitable (but when) rebound.
How long have you been in the game? If you're only down 10% YTD that's not much. This has been a terrible year so far for UK shares and many are down sharply (>35%)
If it's any consolation Ben Hazzard, you started investing when many quality shares were already good value, like most of us you didn't know they'd keep on getting cheaper. It is indeed very wearing, our portfolio has fared badly, including fairly recent buys when I've had an attack of optimism. The FT had stats recently on UK Funds moving out of UK equities and into Global Funds, I'm afraid until this Government or the next one, introduce positive actions to stimulate share holding only the brave, foolish, or very clever will wring profits from shares. We've moved to a good portion of our holdings to now yielding more than cash deposits but the shares are going nowhere! We are still 40% cash which is now only losing 5%. Good luck, you joined at the toughest time I can remember and I started in 1982. I enjoy being on Stockopedia for Paul's Graham's Roland's and subscribers comments, it helps me to make less mistakes and sometimes find winners!
Tough time for you to start Ben. I started 4 years ago and saw a huge surge with Covid stocks. Some days everything in my Folio went up and I thought I was the bees knees and wanted to talk about shares to anyone I met. Then the decline started and I stayed invested and all the paper profits I made and ploughed back dissipated and I'm now well below water. I think if I'd have started investing in 2022 or 2023 I would have probably given up by now.
Hope it turns round for you and all of us but there is little light at the end of the tunnel at the moment.
GLA
“Fortunes are made in bear markets not bull markets”
Is I think a Warren Buffet quote .
Remember how it felt 18 months(?) ago at the peak of the bull market when everything
was flying and you’d buy a share and two weeks later it was up 20% on the back of a crazy market fuelled by easy money and growth stocks and big valuations .
Most of “us” felt great with our successes and constant green days “up another 1% today”
We had the deluded dopamine hit we were great market analysts and share pickers .
You feel great in a bull market of overpriced companies and poor value because your “up 10% month to date “ etc .
The absolute hardest part of investing is bear market declines where you start to second guess yourself and the lack of dopamine success that you get in the bull runs disappear .
We all get sucked into bear market thinking but for 100% sure this is the time when some good companies are historically cheap simply because everyone has taken their bat and ball home and are sat on the sidelines .
There are some pretty nailed on acquisitions and takeovers and company turnarounds going on so I think it is prime time to switch the focus to “now is the time” and when everyone is fed up it’s actually a great time to be invested .
Spot on planetx,
Talking specifically small caps if you look at the volumes being traded day to day sp's are just being marked down on some very small trades, what usually happens is traders/investors panic and rather than crystalize a loss they take a profit on their best holdings just to stop the pain.
being greedy when others are fearful is very easy to say but actually hard to execute, I have added to a couple of my best conviction holdings this morning.
Out interest, what are your highest conviction holdings? I sold my Zotefoams (LON:ZTF) holding at 400p a few weeks ago and am going to redeploy the money today. I'm tempted to move into Card Factory (LON:CARD) after a 5% drop on retail news, that or top up Seplat Energy (LON:SEPL) or Polar Capital Holdings (LON:POLR) .
Hi Ben,
Not in PF size order,
Marks and Spencer (LON:MKS) Rolls-Royce Holdings (LON:RR.) Yu (LON:YU.) Ashtead Technology Holdings (LON:AT.) Card Factory (LON:CARD) Chapel Down (OFEX:CDGP) Hargreaves Services (LON:HSP) Kitwave (LON:KITW) Equals (LON:EQLS) ME International (LON:MEGP) Jet2 (LON:JET2) Redde Northgate (LON:REDD) Bloomsbury Publishing (LON:BMY) India Capital Growth Fund (LON:IGC) which is a bit of an outlier but I believe India ( plus Vietnam, Indonesia) will eat a lot more of China's lunch because Xi and the CCP have pushed their relationship with the West too far.
Some solid selections there. BMY in particular I've always liked but always waited for a pull back to buy that's never arrived!
Agree Helvellyn re India and Vietnam. I hold VietNam Holding (LON:VNH) and India Capital Growth Fund (LON:IGC) . Not sure China can be totally ignored so hold Fidelity China Special Situations (LON:FCSS) .
Yep. Great time then. I used to highlight stocks that went up by more than 10% in a day and some days that was most of them, Synargen, Novacyt, Greatland Gold, Kistos, Eurasia etc., and even dear old Avacta. All had one thing in common for me - I held on for too long. I'd like to think I've learned my lesson - just need a surge in the markets to find out!
I've been in the game since before 2008 and I can tell you that this year has felt worse than the 2008 crisis. I'm not sure where is the bottom but I'm keeping ample cash to top-up and trying to resist jumping on stocks when they are down on a day.
Very tough year so far for UK equities. This week wasn't good for me either so you're not alone. I'm down 7.62% YTD, following a Momentum Rank strategy. I was hit hard during the bank sell off in Feb/March and haven't really recovered. However, I benchmark myself against the Stockopedia Momentum Rank which has is down -13.74% YTD, so I take some comfort my strategy has given me relative strength.
It will recover, it always does (I've been doing this for six years now). Just hang on tight, and follow your strategy. Also, between October and December, stock market returns are seasonally higher compared to other months (we saw a strong rally last year!), so there is still hope yet.
August can be an awful time for stocks if investors are worrying about anything because liquidity is so low due to holidays. that means traders and fund managers are not at their desks which means they will likely sit on their hands and retail investors are away. Liquidity drains out of the market and so moves are exaggerated.
This year is worse because there was very little liquidity even before we went into holiday season.
So im particularly careful with August when trading in particular. Assess carefully against the investment case rather than panicking on drops or getting carried away with rises, particularly those that are accompanied by very little volume. Can be hard when we’ve had the 18 month investing environment we’ve had but remember liquidity is important for stability of prices - and right now there is none.
Hang in there Ben - you are not alone! In fact, if you are only down 10% this year take heart that you are probably doing better than many here (me included) in that timeframe. With stocks, and especially small caps, you will have to tolerate bigger swings than 10% from time to time, it comes with the territory unfortunately. The psychological grind of seeing everything falling over long periods can be challenging - for what its worth it can help in these sorts of times to: (i) make sure investment amounts / allocations are appropriate and not too aggressive (one can generally sleep better if you know you will still have a roof and everyone will be fed and clothed etc. even if the stock markets went to zero overnight on an apocalypse), (ii) comb through the portfolio and trim any riskier / speculative holdings that you are not 100% committed to in your heart of hearts and may have invested in in more forgiving times (particularly those with high leverage or that may struggle in the current inflationary/interest rate environment or from the China slowdown etc. - but basically anything that makes you nervous every time you look at your holding), (iii) stick firmly to your strategy and investing rules (unless facts change rendering a shift necessary) so that you can feel there is "order" to things even when the markets do their best to make you feel like everything's unstable and uncertain and (iv) open a cold beer and some peanuts and watch the markets and headlines as they unfold around you with a satisfied feeling of serenity and calm.
BIACS
Ben - I echo all the other comments. I’m down 9% YTD and glad its not more. I’m finding this year much tougher than last year when alternative energy & commodities bailed me out so I finished up about -6%.
I think - hope I’ve de-risked as much as possible with a good spread of global IT’s & ETF’s - JGGI, PCGH, GGRG, BRWM, Fundsmith plus some private equity - OCI & HGT that are on a huge discount as well as about 30% & in small & mid caps, with a yield overall of about 4% across the PF. . It’s really hard to sit on your hands when the market is depressed - but as others have said, that’s really the only sensible option IMO. Buying when there is blood on the streets is harder to do than say. I have been drip feeding £ into FSG, TEP, TCAP ,MONY on down days as I see them as sound long term plays that are on sale. I’m more concerned about their price in 5 years than 5 days. Even Berkshire Hathaway had a 23% fall peak to trough in spring 2022. We may go down / sideways for several years yet, but I console myself with the fact that markets have always recovered in the past & the divi’s are still rolling in. If you owned a buy to let, one would be more concerned with the security of the rental income than the capital value. It’s the income that us pensioners need to live on. Despite my handle I try hard not to be a trader (I always seem to lose money overall buying the latest shiny new stock, as some work out well for me, but are outweighed by those that don’t !!). I am rereading Ben Graham’s ‘The Intelligent Investor’ which helps me stay rational.
You always have the option of keeping some cash and just going for stocks which are as close to a sure thing as it gets. Its much easier to swim with the tide and if general direction of travel is not clear then again can stick to the side. Moving averages can show direction of travel.
Also it is probably much easier to find funds or especially ITs that can outperform. Plus the discount/ premium on ITs is a good general indicator.
My morning smallcap tweet: Diving or thriving?
Everyman Media (LON:EMAN) Global Ports Holding (LON:GPH) Plant Health Care (LON:PHC) Trafalgar Property (LON:TRAF)
◄Everyman Media (EMAN)► trading in line. New three year Barclays loan facility of £35m. [SP=59.8 Cap=55m]
◄Global Ports Holding (GPH)► strong Q1. Run rate for FY24 passenger volumes currently ahead of guidance. [SP=236 Cap=160m]
◄Plant Health Care (PHC)► Brazil approves PHC279 for the control of sugar cane and coffee disease. [SP=9.35 Cap=32m]
◄Trafalgar Property (TRAF)► £125k placing at 0.1p, a 13% discount, to keep the lights on. [SP=0.12 Cap=m]