Small Cap Value Report (Fri 18 Nov 2022) - GLE, NAR, LIO

Good morning from Paul & Graham.
Agenda
Paul's Section:
MJ GLEESON (LON:GLE) - it warns that the cancellation rate has shot up recently, which shouldn't come as a surprise to anyone. Being a low price, starter home builder, GLE should be relatively well protected from any downturn, because some buyers are expected to trade down, partially offsetting reduced demand from existing customers. Housebuilders look stunningly cheap to me, with the whole sector trading well below net tangible asset values. Hence I would see any continuing share price weakness as increasing the buying opportunity. They generally don't have any debt, and are sitting on cash piles, as well as owning huge land banks outright. So this time it really is different, even allowing for a housing market downturn.
Graham's Section:
Liontrust Asset Management (LON:LIO) (£727m) - H1 numbers are released at this fund manager, following the detailed H1 update last month. Outflows were large and with sales reportedly remaining difficult, it’s too soon to bet on the trend reversing to inflows at this time. The bounce in asset prices since the end of September has at least produced a recent uptick in AuMA. H1 revenues are slightly higher than a year ago but unadjusted profits are sharply lower as they digest the acquisition of Majedie. There is a huge emphasis these days from many quarters on sustainability, ESG and Net Zero, and Liontrust is very focused on these trends. It’s not my top pick in the sector but I do suspect that Liontrust shares, like most others in the sector, are underpriced.
Northamber (LON:NAR) (£13m) [no section below] - this tiny company has a 63% shareholder and continues to be a case study in bad capital allocation. Net tangible assets are £23m and they remain locked up in a business that is inherently unable to earn an economic return. Perhaps some day, the assets will be released and put to good use, but who knows when that might be? Today’s full-year results (FY June 2022) reveal the company has made a fresh operating loss on £66m of empty revenues. Northamber has not made a meaningful operating profit since 2005: if markets and economies were efficient, a company like this would have released its assets to more productive use a long time ago. [no section below]
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul’s Section:
MJ GLEESON (LON:GLE)
374p (pre market open)
Market cap £215m
MJ Gleeson plc (GLE.L), the low-cost housebuilder and land promoter, is holding its Annual General Meeting (AGM) later today at which Dermot Gleeson, Chairman, will make the following comments…
Several larger housebuilders have recently reported slowing market conditions, as expected given macro conditions. Gleeson is not immune, and today says this -
"In September we announced record revenue and profits for the year to 30 June 2022 and said that we were well-positioned to deliver further profitable growth in the current financial year, notwithstanding the outlook for the broader economy.
Shareholders will be well-aware that since then much has changed. The market volatility and sharp increase in interest rates following the mini budget impacted buyer confidence and caused a significant slowdown in demand.
Gleeson Homes cancellation rates which for the first ten weeks of the year were 20% have, over the past six weeks, increased to 41%.
Net reservation rates have reduced, over the past six weeks, to 0.26 per site per week against 0.42 for the same period last year…
Despite this, they don’t sound particularly concerned -
Whilst it is far too early to call a recovery, we were encouraged by yesterday's Autumn Statement. We would expect to see the re-emergence of buyer confidence as the wider macro volatility subsides. What is more, there are good reasons to hope that an improving outlook for longer term interest rates will result in greater mortgage availability and affordability.
Average selling prices for FY 6/2023 to date are well up on last year -
The average selling price on new reservations since the start of the financial year was £186,500, an underlying 9.0% higher than the same period last year.
This is a key attraction with this share - being at the affordable, bottom end of the market, plus people are trading down -
Despite these higher prices, our homes remain attractive to first time buyers and a couple on the National Living Wage can still afford to buy a Gleeson home on any one of our development sites. Furthermore, we are now seeing interest from customers who might previously have considered a more expensive property built by another developer but who, in the current environment, are attracted by Gleeson's more affordable price points.
Pipeline is multi-year (it sold 2,000 houses last year, for context) -
Land continues to be available at sensible prices and the pipeline remains strong. Gleeson Homes has a land pipeline of 16,484 plots with a gross development value of £3.1 billion, of which 8,607 plots are owned and 7,877 are conditionally purchased.
As with other housebuilders, it complains about the congested planning system.
Range of outcomes for the current year -
For the Group as a whole, the outlook for the current financial year is dependent upon the pace of recovery in the housing market. Having reviewed a number of scenarios, the Board believes that Gleeson Homes could deliver volumes anywhere in the range between 1600 and 2000 units.
Next update will be on 13 Jan 2023.
My opinion - as we discussed at Mello, housebuilders are debt-free, and typically trading at a significant discount to tangible net assets. That means a deep recession in the housing market is already priced-in to shares, and recovery is in for free - very attractive in my view, although there could be some short term pain, on negative sentiment.
For this reason, in my view the whole sector is attractively valued.
Gleeson is my sector pick, because it’s operating at the affordable, bottom end of the market.
Many housebuilders have June year-ends, I don’t know why.
We must have seen peak earnings for 2021/2, so it’s widely expected, and known, that earnings are likely to fall.
There’s an interesting benefit to selecting a smaller housebuilder, in that the new 4% residential property developers tax comes with a £25m exempt profit allowance. Therefore GLE should pay little tax. Whereas larger housebuilders will pay proportionately more.
Long-term, this share, and others in the sector, should do very well I think. In the meantime, being priced well below tangible asset value, risk:reward looks highly favourable, and the cheaper they get, the more I’d be inclined to buy.
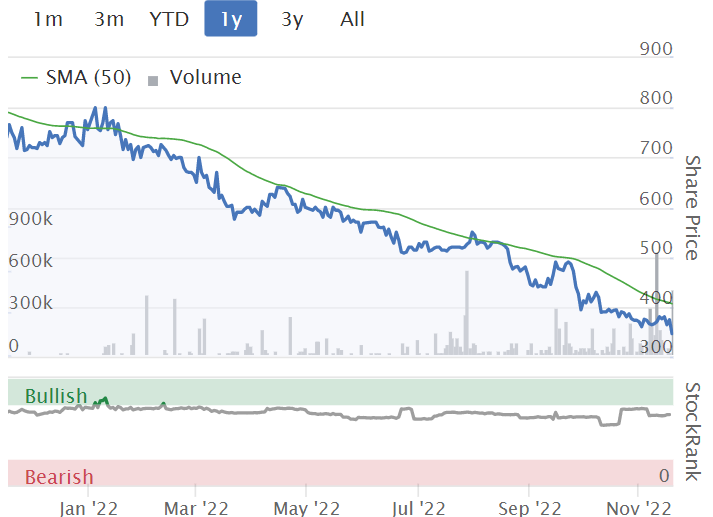
Other housebuilder shares have bounced recently, whereas GLE has hit a new low, so that's another reason to be bullish on this one, in my view, as market conditions are the same for all of them -i.e. getting more difficult in the short term due to macro factors.
.
The market cap is currently £202m (346p per share * 58.3m shares in issue).
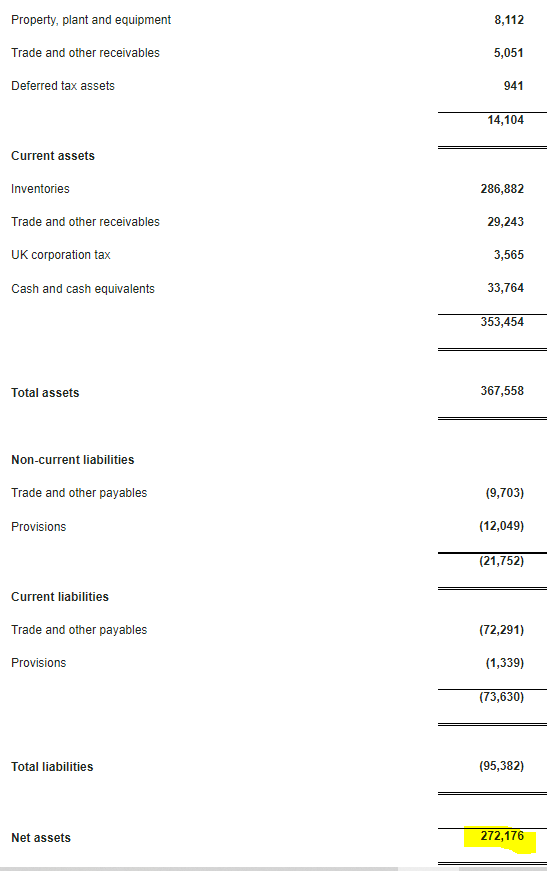
This is what you get for your £202m market cap - £272m of tangible net assets! This is an amazingly strong balance sheet, and remember the inventories are all in at cost, but are worth more than cost. This asset backing should mean very limited downside risk from here, and upside in for free, even if property market conditions are weak for a while.
.
.
Although I should point out that in the severe housing market of 2008-9, Gleeson took a big hit to its balance sheet, which reduced net assets from £159m to £103m, a write-down of about 35%. Currently, the discount to NAV is about 26%, so the stock market is currently pricing in a stepp drop in house prices, of about three-quarters of the severity of 2008, which seems quite extreme to me. In other words, there is considerable housing market downside already priced-in to the share price of 346p.
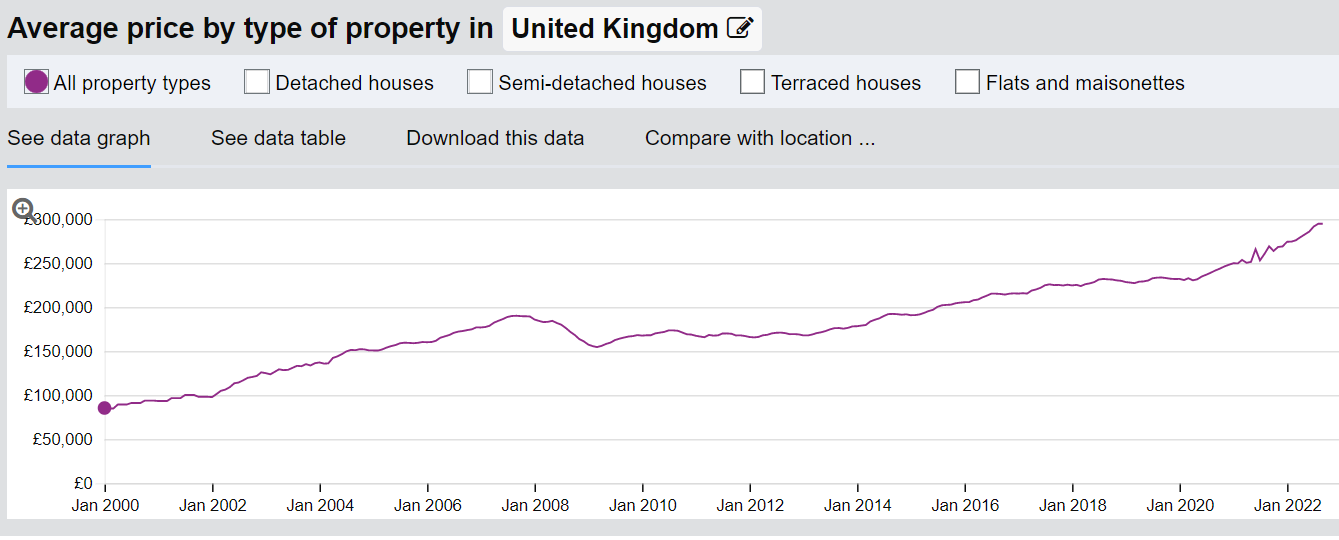
Land Registry data shows that average house prices peaked at £190k in late 2007, and bottomed out at £154k in March 2009, a fall of 19%. It then recovered about half the loss by 2010, then went sideways for 3 years. Then in 2014 the current bull market in residential property began in earnest, as you can see -
Graham’s Section:
Liontrust Asset Management (LON:LIO)
Share price: 1120p (+1.5%)
Market cap: £727m
The fund management space continues to be one of my favourite investment themes in the current environment. Let’s get up to speed with events at Liontrust.
Today the company has published its interim results for the H1 period ending September 2022. Last month, it issued a detailed H1 trading update which I covered here.
Key points:
- Net outflows during the six-month period were £2.2 billion.
- Assets under management and administration fell from £33.5 billion at the start of the period to £31.7 billion, despite adding £5.1 billion in assets from the takeover of Majedie Asset Management.
And the financial results:
- Revenues +1.6% compared to H1 last year.
- Adjusted PBT +9% to £42.9m.
- Actual PBT fell 55% due to the impact of the Majedie acquisition.
The acquisition has at least prevented Liontrust from experiencing a much larger fall in AuMA so far this year. Interestingly, Majedie’s sellers agreed to receive a fixed number of Liontrust shares, a deal format they may have regretted as the value of LIO shares subsequently tumbled! But Liontrust was shielded from any harm caused by that volatility.
This is what the Chair has to say about that deal now:
The acquisition of Majedie Asset Management has been impacted by global events and their effect on investment markets, which we could not foresee at the time of purchase. Buying Majedie was consistent with the strategy of continuing to diversify our investment management and distribution capability. This leads to a more robust and resilient business over the long term as we have proved with Liontrust's other acquisitions over the last decade.
At least the price tag was denominated in shares, rather than cash! That would have been much more painful.
First interim dividend: unchanged at 22p. The yield is 6.5% according to Stockopedia.
Outlook
The company acknowledges that asset management sales are being hurt by macro conditions, and confirms that “the industry trend in the UK has continued in the third quarter of 2022”, i.e. it remains very difficult to convince investors to pour money into funds in this environment.
On the other hand, there has been a pickup in AuMA since the end of September (£31.7 billion): as of mid-November, AuMA has improved to £33.5 billion. That will be due to the recent bounce in asset prices rather than inflows.
Here’s the outlook statement:
Despite the challenging year so far, we are optimistic about the future growth of the Company. The confidence is based on the fact the business is financially strong, we have robust investment processes, we have been diversifying our investment capability and distribution, and the brand profile continues to be positive and strong. This belief is reflected in the Interim dividend payment we have announced.
My view
I’ve just run a back-of-the-envelope calculation, and I think you get c. £46 of AuMA for every £1 invested in Liontrust at the current share price. This should be significantly better value than Liontrust shares have historically offered.
For example, in mid-2019, Liontrust only had £14 billion of AuM. Again, a quick calculation suggests around £30-£35 of AuM for every £1 invested in Liontrust at that time.
If you’re bullish on the “sustainable” investment theme, then these shares might be a useful way to invest around that idea: Liontrust’s focus is very much geared to “sustainability”, ESG and Net Zero.
Personally, I think there are a lot of opportunities in this space currently, so I’m not sure if I’d put Liontrust top of the list. There are some very cheap fund manager shares to be had, and there are some other truly excellent fund managers who are also trading at historically low prices. In no particular order:
- Abrdn (LON:ABDN)
- Schroders (LON:SDR)
- Polar Capital Holdings (LON:POLR)
- Jupiter Fund Management (LON:JUP)
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

49 comments
Good to meet a number of you at Mello Wednesday and Thursday....and cheers for a few beers (I suspect I'm in beer debt to lurker Bill).
Also very good to meet our leaders Paul and Graham...keep it up...and given goings on in the evenings somewhat amazing that the show kept rolling in the morning ;)
Until next time, ciao.
Interesting research from Shore Capital REF: Sureserve (LON:SUR), which is again bouncing off resistance having had a decent rally last week.
Jeremy Hunt yesterday pledged in his Autumn Statement another £6bn to improve energy efficiency in homes and industry from 2025. This is on top of the £6.6bn current ongoing programme. The details are still to be set out, but we see this as a potential major positive for the social housing energy services groups long-term pipeline. Valuation: FY23 PER 7.7x.
• The combined impact of the two programmes are aimed at reducing energy consumption by 15% by 2030 and improving energy security. Full details are expected soon.
• It is not clear whether there will be any changes to the current programme, such as grants to homes, but it extends the commitment.
• We see the group benefiting from protected long-term contracts in protected sectors of gas safety compliance and energy efficiency that is not reflected in the valuation: FY23F (Sep YE) 7.7x, PER; 4.6x EV/EBITDA.
(I Hold)
I'm now down 10% on GLE, oh well. I'm holding for the long term. The profit warning today can't be a surprise, the shares have already come down very sharply.
For the value hunters, I've just bought a decent slug of Secure Trust Bank (LON:STB). Dirt cheap and some serious shareholders on board...but DYOR, I'm an amateur.....
GreyInvestor - I too bought Secure Trust Bank (LON:STB) recently but I am being reminded frequently at the moment that the market knows more than I do most of the time, and the chart is giving me only a very weak buying signal - the price could easily drop 10% from here - so I have been watching like a hawk and wondering when their next reporting date is. There is no financial calendar on their website so I sent an email to the published address for enquiries saying I'm a shareholder and asking that question but they haven't replied. If they don't reply today I'm going to phone the Company Secretary on Monday.
Good idea. Stephen Cohen is no lightweight as an investor….
i'd strongly recommend doing a mystery shop for STB, I tried to create a savings account with them and was horrified at the 1990s experience. I think the numbers look good, but I wonder at what point they will cut themselves out of market share, the lean digital only startups like Atom are on a totally different level in terms of ease of use and appeal to anyone under the age of 70 (imo)
Positive update from Bodycote (LON:BOY) this morning, now above 50 and 200 day MA.
Could be a nice bowl forming, not sure share in this sector though would command a PE of much more than 15, especially in a bear market.
No position.
Regards.
My view on house builders would be you want to be in the most efficient one until clear signs things are improving. I suspect that its still too early and more bad news to come. Why? Well bad news travels slowly,...rates probably not quite peaked yet although they are getting there. MJ GLEESON (LON:GLE) build costs are £40,000 per house lower than say Persimmon (LON:PSN) but they sell at £75,000 lower. Inflation covers a multitude of sins they say....and broadly speaking its good for builders but not if selling prices come under pressure. My guess would be new build holds up a little better due to energy efficiency but never the less ... with a slower market and potentially weaker price .... Id hold off. The price to book values largely reflect differences in return and margins. Clearly the less margin you have the more exposed the P&L is to the tightening jaws of cost and price. Does this impair book value? not on the face of it... but the risk is always that they write down book...(land and WIP) to drive a much improved P&L since the write off goes through as exceptional.
The sector contrasts markedly with say Banks or hybrid banks like Rathbones (LON:RAT) who are making better returns due to higher interest rates and subject to provisions, dividends or total payments will most likely rise here.
I agree about the housebuilders generally and MJ GLEESON (LON:GLE) particularly because although it's a good company, it will not go bust, and it will pay dividends, there is nothing to show that the share price is not a falling knife. As I have been reminded the hard way with PayPoint (LON:PAY) this month, buying a good company which will not go bust and will pay dividends is pointless if one loses multiple dividend payments from a falling share price. I think that what I am saying is that in a market like this timing is crucial. The pundits all say you can't time the market but sometimes I think it's the only way to achieve a decent performance. And the time is not yet right to buy MJ GLEESON (LON:GLE) unless you want to try trading it for a quick 10%.
I think with house builders you need to separate the various components that have caused the falls. This is a cyclical sector and tends to trade at price to book value rather than specific PE ratios so I find it better to look at that for context. The other thing is balance sheet. In previous downturns builders have been leveraged, now they are not. £CREST as an example now has half its value in net cash, Taylor Wimpey (LON:TW.) has circa £650m and so on. That means the usual fear of tapping shareholders at distressed prices appears unlikely this time around.
In my view builders sitting on 0.6 to 0.7 * BV is historically a trough level, whereas 2* is generally peak. At the moment in some cases we are sitting below historic trough levels. I put that down primarily to the Truss mini budget. It created gridlock in mortgages and as such cancellation rates went up and people searching for houses went down. That gridlock has now started to ease again and should continue to do so. The next market pressure is affordability and that needs some time to reset to new interest rate levels but it doesn't change the supply/demand dynamic longer term. If house prices fall in the region of 8-12% that isn't great for house builders but it doesn't justify sub 0.7* book values for businesses in net cash positions. Cost inflation is then the next issue and I believe we are past the peak on that now. look at YoY of Steel -63%, Lumber - 42% etc. Once energy costs roll over too input inflation could look benign.
Combine the above and what I expect to see is pressure on margins and overall revenues, thus lower EPS. This will likely lead to less special dividends but still quite high yields from normal divi's as I expect house builders to stay profitable just with margin contraction.
In my view I see house builders around trough levels. I think the cost inflation, house price falls, interest rate rises, margin contraction and lower divi's are factored in. What wasn't factored in was the mortgage gridlock / withdrawals. As a consequence I see a stepped recovery from here as each issue fades but will clearly take some time.
Persimmon increasing the cladding provision from £75 to 350 million is a bit scary for the balance sheet.
Not a small cap comment so pls pass over if not your cup of tea, but posting here as a follow-on to more extensive discussion that took place in the SCVR comment section on Oct 4th.
Legal & General (LON:LGEN) trading update today well worth a read, especially after all the recent commotion in the LDI/DB pension scheme world.
To quote the last para for those short of time:
Consistent with the guidance provided at HY22, we expect to deliver resilient FY22 operating profit growth in line with the 8% delivered in H1 (£1.16bn vs £1.08bn) and FY22 capital generation of £1.8bn.
Strong statement....most encouraging. Risks around LDI seem to be falling away...
RE: Legal & General (LON:LGEN)
Strong statement....most encouraging. Risks around LDI seem to be falling away...
Not sure there were ever many. L&G had no direct exposure and tons of liquidity anyway. If the bond crisis had persisted the UK would have been bust so it was always going to be a short-term liquidity issue. No doubt there was some arm twisting from the BoE behind the scenes.
The recovery today is in part due to the Solvency II reforms announced by the Chancellor yesterday. These have long been flagged, but will allow insurers to release investment into properly productive assets and increase returns.
I've been happily buying Legal & General (LON:LGEN) and Aviva (LON:AV.) for a while but they still look cheap to me, noting that rising interest rates bolster their income at the same time as recession will see a spike in claims, albeit many of them dubious.
timarr
If we start discussing the finer details of Solvency II here I suspect we will be treated as guests who have outstayed our welcome...
I was never too concerned about Legal & General (LON:LGEN) from an LDI perspective, as I explained back in October for those who wish to revisit.
As has since become clear, combine too much leverage in a pooled fund structure with a one-way gilt market and you get fireworks.
The real fault lies in some LDI managers and pension consultants putting too much reliance on historic market behaviour to model their potential collateral requirements. And no....I am not being "Hindsight Harry" here, it doesn't require a PhD to observe that QE has distorted the UK gilt market and that statistical analysis of previous yield jumps was not fit for this purpose. I don't have much sympathy for the leveraged repo crowd either - we know there are scenarios where the repo market ceases to function as we would wish.
I missed the Legal & General (LON:LGEN) opportunity last month as it did trigger my buy alerts, but I passed because I was too worried of over-exposure to one industry in my portfolio; I hold Phoenix group (LON:PHNX) and they are already my largest holding, more than 10% of my portfolio.
But Phoenix has also risen so I have benefitted, so I can't complain.
On claims spike - I am thinking that we are maybe about to enter a multi-year cycle of increasing car insurance premiums, what with the rise of used car prices now baked in, as well as more claim volumes. This should encourage switching behaviour, as more customers balk at the increases at renewal. Moneysupermarket.Com (LON:MONY) might benefit. Although they will now also see another year of zero-energy-switching due to the extension of govt support after Apr23. Unless gas and elec prices collapse, which could happen in a worldwide recession. Food for thought.
(I hold Phoenix in the Boon Fund)
But Legal & General (LON:LGEN) & Phoenix group (LON:PHNX) don't write motor (or other non-life classes) as far as I'm aware..
At Mello, I talked to Ed and Paul about more comments on Mid and Large caps.
My arguments is we benefit from a collective wisdom of the group as much as the comments by Paul and Graham. I read all the comments and it is very good that so many of the community here take the time to write. Thank you all and please continue!
Paul told me that he is now reviewing companies of up to nearly one billion which is great .
Regarding the windfall oil tax for oil companies operating in the North Sea:
so let me get this right. if Serica or Harbour Energy invested in oil/gas assets abroad profits from those wouldn't be subject to the windfall tax? And why can't the UK government tax overseas oil/tax assets? [if the companies are listed in the UK]
I think it is because bilateral double tax treaties set out the residency rules and the taxing rights of the respective countries based on the location of the entities and the type of income. And treaties override national law, unless you rip up the treaty with all the associated consequences of withholding taxes, tariffs and trade barriers. A bit like mini-Brexits all over the world and making a UK listing long term unattractive for a windfall tax of a few billion.
As I didn't manage to get to Mello unfortunately were there any company presentations that screamed high quality businesses with good management offering value?
Paul Hill posted his presentation at Mello https://www.stockopedia.com/co... - his process/checklist is very interesting, as are the five companies showcased (disclosure - I hold LOAD and AGFX).
Cheers
Simon
Over the nest few sessions, I will put in writing what I heard and learned and gained form the Mello.
The first session was John Lee, who said some interesting points;
He said he is fully invested most of the time unless he receives cash which he expects from the take overs (Appreciate group).
His comment about having too much cash was interesting: it is clever when you sell high but then you worry when to re-enter the market. This becomes a source of anxiety and stress , exactly opposite of what you wanted.
His holdings: In defence sector his preference was Concurrent Technology.
He has added to his holding in Anpario, Christie.
He still likes Treatt, PZC, describing them as good recovery values.
Paul,
If anyone was tempted by your talk at Mello yesterday about Gleeson, should be much happier to buy it at 10% discount today. That is exactly what I am going to do today.
Here's the £STEM first of their investing series given on Tuesday. It highlights why they are very well positioned as the only global STEM specialist with strong growth drivers:
They focus on contract, short to medium-term placements which is what the majority of candidates and clients want.
They focus as much if not more on relationships with candidates than the clients. They are disciplined in their analytics to focus on what placements drive the best returns for them.
They aim to increase market share, currently c2%. Germany and Netherlands they are #1 and #2 in a highly fragmented market, Timo CEO led these two regions historically. They have a strong focus to build in the US.
Top 5 markets US, Germany, Netherlands, Japan and the UK represent 75% of the global STEM market.
The next one will be in January and will focus on their investment in tech and what they expect that to deliver.
Video & Podcast.
Separately, forthcoming events:
DSW Capital (LON:DSW) interim results webinar on Thursday 1st December, 1pm, when James Dow, CEO and Nicole Burstow, CFO will present results and take questions. Register here.
IG Design (LON:IGR) interim results webinar on Wednesday 30th November, 12 noon, when Stewart Gilliland, Interim Exec Chair, Paul Bal, CFO (to be CEO from 1 April 23) and Lance Burn, Interim COO will present results and take questions. Register here.
Sosandar (LON:SOS) interim results webinar on Tuesday 13th December, 11.30am, when Julie Lavington and Ali Hall, Joint CEOs and Steve Dilks, CFO, will present results and take questions. Register here.
VSA Capital Aquis Stock Exchange showcase event. This is happening at the Royal College of Surgeons WC2. A full day event on 29th November, 9am-7pm with free booze and food during the day and drinks in the evening. Lots to entertain. The main show is Britains got Aquis where 20 companies present and Fund Managers Andy Brough and Judith MacKenzie will judge their investment cases alongside Rich Ricci, Panmure Gordon and Jim Armitage, The Sunday Times. In addition, presentations by Sir Robin Saxby, founder of ARM, will discuss the future of tech, James Wood, Winterfloods on the dark art of Market Making and David Buik presenting the macro picture. Register here.
So what's going on at Mulberry up 40% yesterday, results Tuesday
Yes, I wondered that, 1/2 year results are due on the 22nd so must already be signed, set up for printing and embargoed. I suspect someone may have had a sneaky peek. If the results are good enough to justify yesterday's cash splashing then I like to think the FCA might take an interest; Mulberry (LON:MUL) is not the most liquid of shares due to the vast majority- more so than normal- being owned by a few entities, so in theory small investors already face a higher bar to trading in and out, without having to compete with possible insider trading.
Good morning Paul. Unfortunately I could not afford to make the trip across the water to the Mello live event. I noted from somewhere that you were going to be promoting MJ GLEESON (LON:GLE) in your 3 minutes in the Wed bash I think. Unfortunately as I say I wasn't there to hear your proposition. I have always been a supporter of the MJ GLEESON (LON:GLE) proposition being on the side of the small guy - house buyer and house provider - but this morning's trading statement is disappointing though not unexpected. You must have thought along the same lines so do you expect them to recover significantly in the coming year? I felt obliged to sell them some months ago, and would have been well in the red now if I had not done so.
I was also in and out of MJ GLEESON (LON:GLE) but must say at 10% down today, its very cheap and I have opened a position and just going to tuck them away. I will have a few bites at it over the next year and build a position. I know they are cheap houses, but do operate in areas where house prices are lower...but that said I think its a great chance to get a foot in the door, perhaps a little early, but it's already a good company in an unloved market sector well marked down.
Time will Tell
Good luck with Gleeson - decent company and very cheap. Have held this on and off, but just don't see much prospect of a recovery any time soon in current climate. My experience is that while trading deteriorates, so does the share price - no matter how cheap - and am guessing the next couple of trading updates will be poor. Will probably wait 6 months to see what state the housing market is in and reassess the sector then
how does the oil windfall tax update of yesterday impact energy generators like Drax and SSE? What would be the total tax burden they'll carry compared to 'normal' oil companies? I'm asking because I saw the stock prices move up yesterday?
Windfall taxes increasing from 25% to 35% for energy company profits, and a new 45% windfall tax on electricity generators, combined will raise £14bn next year.
Some think the windfall tax had already built itself into the share price previously.
so far , it seems, Centrica is a beneficiary.
94 p this morning.
Not been this high for ages.
By the by on Drax (LON:DRX) I seem to remember in one of Mr Head's portfolio reviews and share buy possibilities that he said that Drax (LON:DRX) had been very kind to him, but that the government subsidy to the company was approximately equivalent to its profit. Not very good value for the taxpayer at first sight. If the Drax (LON:DRX) SP rises in the current circumstances, then it really does question the rationale for this policy. Perhaps it is to maintain some cleaner (than coal?) electricity supply back-up which is not dependent on oil or gas?
From bad memory, reading in the Private Eye, Drax pays loggers in Canada to chop trees down and chip them and ship the wood chips to Drax who then burn them to make electricity.
This is declared as carbon neutral and so attracts govt subsidies.
Personally I take the same views on all that as I did (and do) on Crypto:
"Who do they think they are fooling" and "Someone is making a lot of money out of that, I missed out"
I love that this sort of thing is starting to be said in investment circles. For a rational group of people, who own businesses through their shares to continue to support some of the rubbish things that happen, to carry on I find reprehensible. That said the idea we can move dirty to clean in a few years is naive. The problem is we should have started the process 20 years ago. This year the world is burning coal again.
Re Drax (LON:DRX) - burning wood chips from SE USA to cut carbon emissions is a fraud - and a reminder of why Adam Smith wrote about Political Economy! - and it cannot last.
On the one hand the sceptics will ask if we are to burn stuff, why not cheaper coal. O n the other wing (which I support) people will increasingly ask if the same Govt subsidy money was put into energy efficiency (insulating lofts, subsidising heat pumps) and low cost renewables (on/offshore wind, solar,) and energy mgt (grids-cale batteries to shift & smooth consumption), would this not be a far more effective long term use of funds
The only lobbies to keep the subsidies to Drax going are local MPs to 'save jobs' and, short term 'keep the lights on' and government inertia.
Having been heavily burned by a sudden shift in regulation on other shares, I would steering very wide of Drax from an investment point of view - +ve momentum could change very fast with 1 change of Minister.
Re: Windfall tax on energy generators
N.B. The details have not been finalized. Here is the most recent document: https://assets.publishing.service.gov.uk/government/uploads/system/uploads/attachment_data/file/1118358/Electricity_generator_levy__technical_note__final.pdf
Previous tax rate- 20%
New tax rate- 25% + 45% windfall tax on profits arising from excess profits on (UK) generation (‘Exceptional Generation Receipts’)
Observations- The levy will be applied to groups generating electricity from nuclear, renewable and biomass sources. The levy will not be applied to pumped storage hydroelectricity, battery storage, coal or oil generation.
N.B. The levy is subject to benchmark prices (and an allowance). This makes it less painful than I had assumed.
Also- The windfall tax on oil and gas producers is very different: https://www.legislation.gov.uk/ukpga/2022/40/contents/enacted
Disclosure- I own no electricity generators.
AGM statement from £GLE. Cancellation rate up as one would expect, but at £186k per home still affordable for a couple on NLW which rises to £10.40 next year. They're also indicating interest from customers who previously might have considered buying from a more expensive developer.
Seems like a profit warning to me; reservation rates down, cancellation rates up, land sales going nowhere. I recently acquired a small holding in GLE. I don't expect it to be a good one in the short term.
But..this is a good company with some pretty serious shareholders. It deserves to do well. I approve of it's support for first time buyers, even if those are the hardest hit by events of the last couple of months.
I'm not sure 186K is affordable for many. Just put the NLW into a few bank's mortgage calculators and a couple only offered me around 100k mortgage, others I could make the 190k but that was the upper limit of what I was offered.
Not a reflection on MJ GLEESON (LON:GLE) , I just struggled to get my first home a while ago and like to know how affordable houses actually are for society.
I think they say they are affordable for a couple on the minimum wage (not an individual).
I used the calculator as a couple. i.e. 2 people on the National living wage.
I did the sums yesterday. £167k average purchase price, 85% mortgage, 5.5% to 6% interest rate, 20 year repayment = something like £15,600 per annum to be paid. Average couple earning £44,100 gross. Seems like a stretch to me; a third of their gross pay, or maybe 40-45% of net pay?
Interest rates have a huge impact on affordability.....
Your winnings, sir.
Clearly these company execs are fully paid up members of the Ministry of the Bleeding Obvious.
"Outlook for the current financial year is dependent upon the pace of recovery in the housing market."
"We are shocked by recent events in our industry."
If you didn't recognise the quote:
;t=2sUs old folks got it