Small Cap Value Report (Fri 19 June 2020) - STAF, RCN, WHR, ANIC, TRI, COST

Good morning, it's Paul here with Friday's SCVR.
Sorry I didn't manage to do any more writing yesterday afternoon, I was too tired by the time I got home, and not in the best frame of mind, with the car having failed its MoT for the second time in a week.
Estimated timings - I've started at 7am, so should be done by 1pm.
Edit at 13:07 - today's report is now finished.
.
Staffline (LON:STAF)
Share price: 48.5p (up 52% yesterday) - currently down 17% today, to 40p, at 08:54
No. shares: 68.9m
Market cap: £33.4m
Statement re share price movement
Some kind of speculative frenzy gripped this share yesterday, with it spiking up 52% on no news. Hence the company has needed to put out a statement today. The crux is;
Staffline, the recruitment and training group, notes the recent movement in the Company's share price and confirms it is not aware of any reason for the price movement...
Further points;
Bank facilities - expects to agree & implement revised financing arrangements soon.
Results - for FY 12/2019 should be published soon (they need to get their skates on, as I think the shares would be suspended if not published by end June). Audit work not yet finalised - which will presumably hinge on bank facilities being signed off, in order to publish accounts on a going concern basis. Although this might allow shares to continue trading, possibly? -
The full report and accounts for the year ended 31 December 2019 is now expected to be published and sent to shareholders in July. Accordingly, the Company has applied to AIM Regulation for an extension to the current reporting deadline of 30 June 2020, which has been granted in accordance with the temporary measures put in place due to the impact of COVID-19.
Figures - 2019 results expected to show small underlying EBITA loss, and pre-IFRS16 net debt of £59.5m - that's a lot of debt, but remember that Staffline has a blue chip client base, with a large receivables book. So the bank has quite good security.
Cashflow - benefiting from Govt deferral of VAT & payroll taxes - "significantly improved ... liquidity through the end of 2020". Whilst this is helpful, these liabilities will still have to be paid at a later date, which the bank may not be happy to fund. Therefore, there's still insolvency risk here in my view.
My opinion - too risky for me in the current circumstances, and I don't want to touch this sector anyway.
.
Redcentric (LON:RCN)
Also says it accounts are delayed, but gives a reasonable explanation;
Redcentric plc (AIM: RCN), a leading UK IT managed services provider, announces that it now expects to report its full year results for the year ended 31 March 2020 on 21st July 2020.
The current audit is taking longer than originally expected due to the restrictions of the current lockdown and does not relate to any issues with the audit.
As announced on 3rd April 2020, trading for the year to 31st March 2020 was in line with the Board's expectations and pre IFRS16 net debt at 31st March 2020 was £13.5m.
Taking that at face value, it sounds OK.
.
Warehouse Reit (LON:WHR)
We were discussing Newriver Reit (LON:NRR) yesterday, and I've also mentioned Hammerson (LON:HMSO) before, as potential, but riskier property investments.
Warehouse Reit (LON:WHR) is altogether a safer option, and looks an attractive income share. I've covered it here before, so see the archive for more details. By specialising in buying warehouses, it has focused on an attractive subsector, where rental yields are good (and sustainable), there's increased demand (due to move towards more online shopping), and supply is tight because values can be below build cost.
To reinforce what a good stock this is, it's just announced a large (relative to its mkt cap) fundraising that has gone very well. The fundraising size has been increased from £175m to £200m, and crucially the price discount was negligible, at 110p (versus 111p market price).
My opinion - this is an excellent investment, in my view (not one I hold personally, but is on my watchlist). It provides a high yield of over 5%, which should be inflation-proofed, since rents are likely to rise over time. There's no premium to NAV, so it's good value.
I think this is one of the best shares I've come across for long-term income seekers - e.g. SIPPs in drawdown. It provides a good yield, and over time NAV should also rise. What's not to like? It won't be completely immune from the recession, but if anything is likely to be a beneficiary from the pain that retailers & their landlords are facing, as supply moves online.
The fact that it's just got away a large fundraising, at no discount, with excess demand, demonstrates very clearly that institutions are happy to back this sub-sector. Obviously do your own research as usual, because I might have missed something, but this one gets a thumbs up from me.
.
Agronomics (LON:ANIC)
Possible de-listing & tender offer
I'm not interested in the company - it's a Jim Mellon vehicle for investing in pre-revenue biotech & pharma companies.
This is an interesting announcement though. The company says it will consult shareholders on possibly delisting.
The main reason given could have wider read-across. It's struggling to raise follow-on funding from AIM, and sees better funding opportunities in the private company space;
...the Directors believe that the Company, as a private company, will be able to access substantial equity capital from investors specialising in private market investment
Tender offer - this is an excellent idea. In order to prevent the share price crashing, and to provide an exit route for shareholders that cannot, or don't want to own shares in a private company, an alternative is being offered to buy out shareholders at 6p - similar to the market bid price before this announcement. This is a nice touch, well done to Jim Mellon for providing this fair exit route.
My opinion - it's hardly surprising that AIM is losing its appeal as a place to fundraise for speculative companies, because hardly any of them actually deliver on their promises. Over the last 20 years, I've seen hundreds of rubbish companies listed on AIM, and the speculative ones nearly all go disastrously wrong. Sure, there's a continuous supply of new mug punters, who open broking accounts and get sucked into speculative rubbish, it's a rite of passage for all of us, to lose money on junk shares. And the odd one still slips through the net!
To keep AIM buoyant, brokers need to find decent companies to list, not more speculative junk - which ultimately is killing the golden goose, as investors become more cynical about everything.
I wonder how many more companies might de-list? It's a very real risk for speculative micro caps.
.
Trifast (LON:TRI)
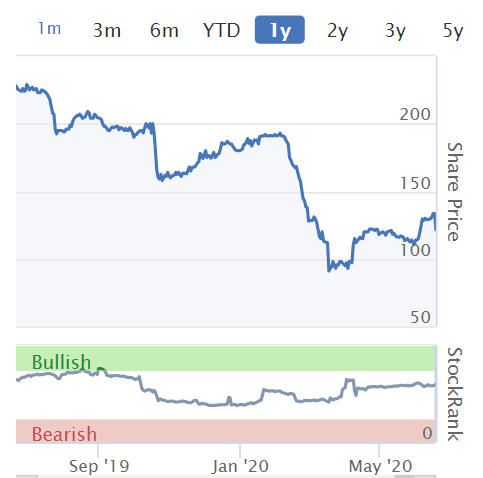
Share price: 121.5p (down 9% today, at 09:00)
No. shares: 122.7m
Market cap: £149.1m
Trading Update & Proposed Placing
Placing - quite small, only about 10% of the market cap, to raise £15m + possible £1m ("broker option").
It's an accelerated book build (ABB) as usual, so we should get more details, including pricing, later.
Liquidity sounds OK -
Cash preservation actions have further reinforced the Group's financial position with good levels of covenant and liquidity headroom to manage through the current period of disruption
Current trading - improving;
Activity levels have shown improvement during May and into June and the Group has the ability to ramp up to full production across the business as conditions improve.
Directorspeak sounds upbeat -
"Despite Covid-19 the next couple of years for Trifast remain a very exciting time for our business. As we look to implement and invest in a number of significant and positive changes in the way that we are structured and operate"
Results FY 03/2020 - expected to be like this;
- Revenues c.£200m, resilient performance. This is in line with £201m shown as broker consensus on Stockopedia.
- Lower gross margins, as previously reported.
- Underlying PBT c.£17m.
- Net debt £16m at 31 Mar 2020. Comfortably within net debt:EBITDA covenant at 0.8x
Impact of covid-19;
- Significant impact in Q1 (Apr-Jun 2020)
- Temporary closure of some facilities. All open by end April, some at reduced capacity
- Trading volumes contract, especially in automotive
- Revenues in April c.50% down Y-on-Y
- Profit "significantly adversely impacted"
- Volumes improved in May
- Pipeline encouraging, further recovery expected in June - NB. returning to underlying profitability
That all sounds sensible to me. As you would expect, the business has taken a one-off hit to profitability, and seems to now be recovering. That shouldn't be a surprise to anyone.
Lots more detail is given, including a "reasonable worse case" scenario, which would see revenues down 27%, and an unquantified hit to profitability. In this scenario it would make additional cost cuts. It says that there's adequate cash headroom, and it would remain within banking covenants, even in this worse case - reassuring. So why do a placing then? They say it's to reduce risk, and provide further headroom. OK, fair enough.
My opinion - this looks a sensible deal, with only modest dilution (I'm guessing that the placing price is likely to be close to the prevailing share price).
TRI seems well managed, judging from its thorough RNSs, and it makes a decent profit margin for the sector.
I suspect results for FY 03/2021 could be worse than the 20% drop in forecast EPS to 8.48p. Broker forecasts often seem to overlook operational gearing, Longer term though, it sounds like TRI is set up quite well.
If you're prepared to look through likely poor results for FY 03/2021, and hold for the long term, then this could be quite a good entry point, c. 120p per share, maybe? I can't get excited about it either way - it's not really value, and it's not growth either. It's probably priced about right at the moment.
.
.
Costain (LON:COST)
Share price: 75.7p (down c.1% today, at 12:27)
No. shares: 274.9m
Market cap: £208.1m
Trading Update (AGM)
Costain, the smart infrastructure solutions company, announces an update on trading including the impact of Covid-19 on the Group's operations...
Use of the word "smart" above made me google it, in case Costain has been involved with the disastrous so-called "smart motorways", which have turned out to be extremely dangerous, and resulted in dozens of deaths, due to the lack of a proper hard shoulder. Investors might need to look into that, to ensure no liabilities could hit Costain.
It raised £100m in fresh equity, very recently, to help shore up the balance sheet, and pay suppliers more promptly as required by the Govt's Prompt Payment Code. I reported on that here, on 11 Mar 2020, am just re-reading my notes now to refresh my memory.
Today's update says the usual thing that everyone is saying - business was interrupted by covid, but is gradually recovering.
The overall level of activity in Q2 has been broadly as anticipated at the commencement of the lockdown in March and where necessary we are working with clients to change resource levels and programmes to meet their revised requirements as a result of Covid-19.
Financial position improved with £100m fundraising, which has helped it win new contracts. It has £110m in net cash - a decent position in a sector where larger groups are often drowning in debt. Undrawn bank facilities also available. This looks good.
Order book is strong at £4.2bn, and various contract wins are listed.
Note there seems to be some contractual disputes - discussions continue. This would need to be clarified before buying any COST shares.
Outlook - covid uncertainty, but "we remain confident in the positive forward outlook..."
My opinion - I really dislike this sector. Infrastructure companies tend to make tiny profit margins, but the contracts are large & complex, and can often end up with costly disputes & over-runs. Shareholders are paid divis in the good years, but then have to stump up more cash to shore up the balance sheet when something goes wrong, as it nearly always does, eventually.
Why on earth would anyone want to invest in a company like this? Still, at least it has sound finances, and isn't likely to go bust due to the decent net cash position. So it's nowhere near as risky as some other troubled sector companies, many of which have gone bust over the last few years.
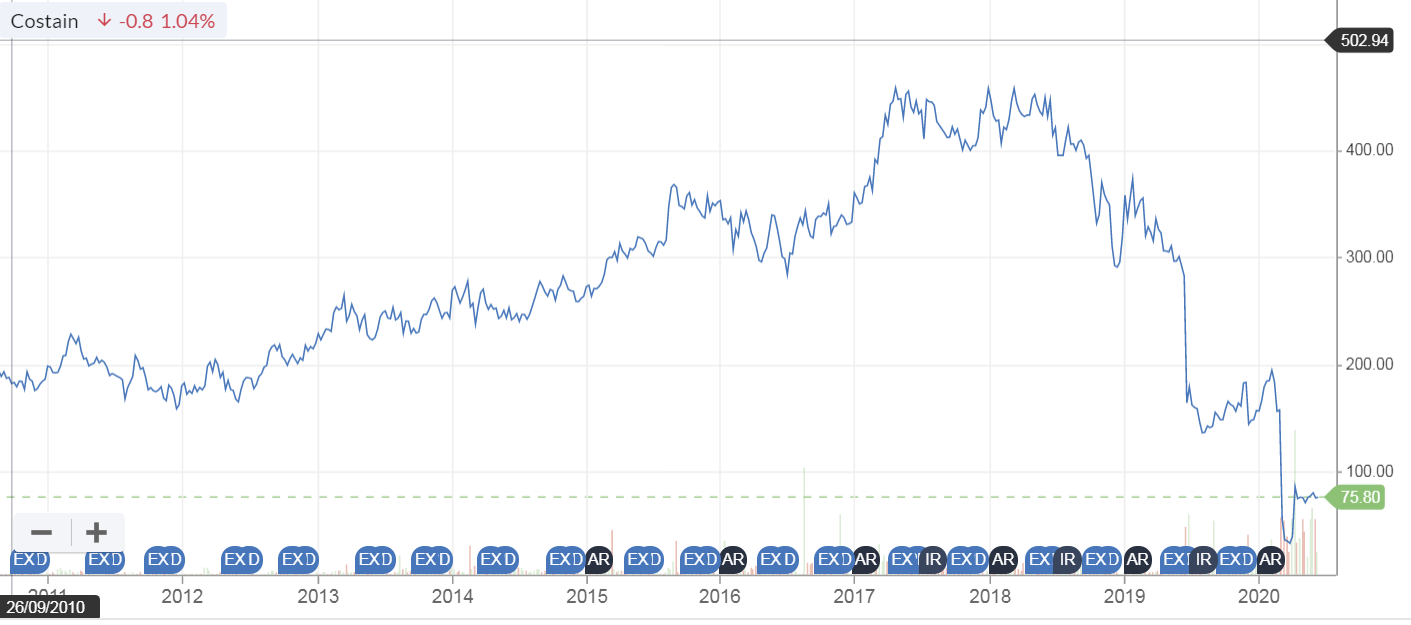
Looking at the 10-year chart below, we can see just how badly things have gone wrong, well before covid. A contrarian might be tempted to think the share could recover. A word of warning though, the share count has almost tripled in the last few fundraisings, which means that the share price is not likely to recover anywhere near previous highs, even if the company does well in future.
.
.
All done for the day, and the week. Have a smashing weekend!
Best wishes, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

110 comments
Apologies if this is off topic here but I wanted to post it somewhere for posterity.
I was on the 94 bus from Lancaster Gate to Oxford Circus early this morning and a very loud and obnoxious Australian (who incidentally felt he was *far* too important to obey current instructions and cover his face on public transport, despite everybody else doing so) was bragging on his mobile to somebody that he had inside information that an obscure and tiny AIM company called Gunsynd (LON:GUN) is going to issue a game changing RNS on Monday.
I have no position and no interest in this company, and the market is closed for the weekend anyway, but let's see if anything happens.
Another company with negative revenues. Seems to be a theme today. In these strange times that must mean it has infinite value.
This one is also an investment company see my post above.
RNS or no RNS the share price will probably get a boost on Monday now anyway by the mere mention here.!
RNS out this morning:
https://www.investegate.co.uk/gunsynd-plc--gun-/rns/strategic-investment---rincon-resources-pty-ltd/202006221013086412Q/
Share price up about 23% at the time of writing. I wish I had bought some now.
Smart motorway, its all in the name of course, and the thinking of all these academics was clearly that having a hard shoulder is so last year, so old fashioned. Was there anyone with an ounce of common sense who didnt think ‘how in reality is that going to work then’. Have all these masters degree academics moved over to SAGE, goodness! Wasn't it the slogan of the US Arms association, ‘guns don't kill people, people do’ , clearly not the poor old motorways fault.
Whenever I hear Government ministers talking about "smart" solutions I immediately think they simply aren't spending the money to do the job properly and are pretending it will all be OK if they paper over the cracks with some technology.
And they'll be in another job before it all goes wrong so someone else can deal with the mess.
Regarding Smart motorways, the A38(M) Aston Expressway tidal flow system from spaghetti junction into Birmingham has some similar aspects - a lane that is only open some of the time with a red x above it to indicate when it is closed.
I used it often back in the 80s and it worked pretty well from what I recall. Admittedly the speed limit is 50 or something like that but it certainly didn’t prove too complicated for the citizens of Birmingham to understand.
I think that if they reduced the speed on smart motorways to 50 when all four lanes are operating and had a publicity campaign to raise awareness of the need to obey the red x for when a lane is out of use and then give it time to bed in it might do the trick.
Anyway, by the time we reach a decision on this vehicles will quite possibly be running in autonomous mode on motorways (even if they are still unable to cope with more complex roads).
Graham, I think it’s a bit different, it’s on the right not the left and it depends on which way most of the traffic is going, and it’s been like that from the beginning. Similar system on Sydney Harbour Bridge I believe,
On Agronomics (LON:ANIC)
Probably showing my ignorance here (though I ran a business and did the bookkeeping for 30 years!!) but how can a company have permanent negative sales?
Thank you.
It is classed as an investment company and therefore its "revenue" is the increase or decrease in the value of its investments.
Your MOT thought you got a 6 month extension under COVID gov rules anyways?
Thanks Ginfred, I was not aware of that,
Would insurance still apply do you know? If a car was not MoT'd?
Paul,
Your MOT extension will no longer apply if you take your vehicle for its MOT and it fails.
Here are the rules: https://www.gov.uk/guidance/coronavirus-covid-19-mots-for-cars-vans-and-motorcycles-due-from-30-march-2020
Not something you really want to test Paul. You know how insurances like to wriggle out. I believe you are allowed to drive to an MOT test station, for a pre booked test, but might depend what it failed on. Most car insurances have a clause 'a vehicle must have valid Mot , road tax and be in a road worthy condition.' Best ring your insurance to double check if in doubt and state the purpose of the journey. If you have AA insurance you could always try and get them to tow it to the garage! Plan B, plead ignorance, which is no legal defence. GL
On a quiet Friday I am looking back in time..to SIG Plc 2005. I had been in the city a few years and this was a glory stock. A top position for prominent mid cap fund managers of the day.
The 2005 report and accounts are very interesting reading, the company has growth drivers, government regulation support increasing use of insulation products, increasing trading sites, housing is booming, they are acquiring smaller competitors and increasing product range. Revenues of £1.6bn generate an operatic profit of £102m, a rise of over 30%. Net debt was £175m.
By 2007, organic growth was harder to come by and so acquisitions made a larger part of the pie. Net debt was rising. In 2008 they fell on their sword and raised £325m beginning a decade of restructuring and failed attempts to improve trading margins.
In todays announcement they confirm the detail of their latest rescue. Before we even look at the detail I would argue the next 24 months will not be easy to rebuild your business.
They have announced a £165m cap raise, £140 net of fees. This is a pretty expensive restructuring by any stretch. Pre-emption has been tossed out of the window in favour of gifting an investor stock at 25p... to get the institutions to back it at 30p.... and a nod to the private investor in an open offer, helping a little to mitigate the massive dilution. The shares trade today with the open offer and go Ex on Monday.
Its interesting that it looks to me like they want to return to the 2005 template... revenues of £1.5bn with a shot at £2bn... group margin of 3% with a shot at 5%... but without the sexy insulation margins anymore, nor the positive market backdrop. The only interesting line I can really find is that of consolidating a broken mess of an industry. This could work. It could help bolster their shrinking market share... and inability to improve profits for 10 years.
The upside here would appear to be 2021 being better than expected...so you hit 2022 a year early and do north of 5p of earnings... of course the 30p entrance looks good.... but for me, I see more difficult times ahead so at the risk of missing another recovery play... Id wait and have a look in the Autumn. By this time you have better colour of 2021 and what you would like to be invested in. Personally Id be surprised if it looks as good as it did in 2005.
I wondered why if any other holders of Wey Education (LON:WEY) have any thoughts as why news of the government grant Wey Education (LON:WEY) has received for a summer virtual school was not released as an RNS. It’s not even on their website as a news item!
This just seems very odd to me and poor investor relations.
The share has risen 25% this week, presumably on this news.
https://www.inavateonthenet.ne...
UK's smart motorways to be reviewed after huge rise in near-misses
https://www.theguardian.com/po...
RNS. I am struggling with the new baffling web site. The old one was easy to use and for my purposes much better. I just want to see price sensitive messages of the day.
Which ever way I configure it I get too many or no messages. I have not found a way of saving a filter which is very inconvenient.
I should perhaps add that I have worked extensively with relational data bases and sql.
Can somebody help please.
Lennart
Afternoon Lennart, I agree entirely I used to get TODAY, ALL except NAV values and it made searching easy. Lately I have been resorting to the Mr Contrarian filter for my 1st pass
Paul please stick to things which you understand your comments about smart motorways are unsubstantiated, my daughter who has a Masters in traffic engineering and 15 years experience on smart motorway design and monitoring tells me that this is due to people not using them properly. A little more education and less group think is called for.
There seems to be wide scale reporting about smart motorways being dangerous for the reason that Paul mentioned. It might well be due to them not being used properly, but that doesn't take away from what's being reported. I can't see the issue with what Paul is saying, but perhaps I'm missing the point?
Possibly, but well designed systems should make it very easy for the user to use them properly. Sounds like something is missing in the design, if they're resulting in traffic accidents.
Tony, the theory of Smart Motorways may be fine but to err is only human. and at 70mph often fatal.
Tony Drew
Paul please stick to things which you understand your comments about smart motorways are unsubstantiated, my daughter who has a Masters in traffic engineering and 15 years experience on smart motorway design and monitoring tells me that this is due to people not using them properly.
Unfortunately people are free to comment and will comment - i would say your argument appears very straw man if the basic facts of Paul's argument are correct that these smart roads are causing more deaths accidents and near misses than non msart alternatives. It's fairly easy to closely monitor / model as approrpiate and predict/risk manage situations like this when implemented. To blame the predicable reaction of hundreds of thousands of users doesn't cut it with me - the modellers and implementers should ensure its not a situation where bods follow predictable human behaviour that just so happens to be against the rules and that that certain rule breaking means the situation is getting worse - or the practical realities of the backup plans aren;t as good as were presumed would be the case. It's fully problem of the implementers here and unfortunately they will be very biased in probably wanting their fancy new system to work or as would be natural for the results to come out as tey hope would be the case.
Note the Highways chief England guy who should know a thing ot two - seems to be suggesting there is an issue here !!
This comes in the wake of a statement from Highways England chief executive Jim O'Sullivan, who told the Transport Select Committee that current dynamic smart motorway systems are "too complicated for people to use".
I actual think its good insight from Paul. It would be easy not to mention the companies association with smart motorways, which up to now hasn't gone as smooth as everyone would have wished and could lead to issues for Costain.
This might indeed be down to a lack of education by the public, which might change with time, but in this moment in time if I do a fact check I can see accidents have increased considerably more than any prediction, which in the world of investment has to be looked at.
Being pragmatic, perhaps Paul should have said accidents have increase 20 times rather than using extremely dangerous, but if someone said 20 times worse I would be thinking of using similar phrases
Totally agree other than where you cannot move yourself (not car) off a smart motorway due to a wall or the likes, these need to be amended. However, the general quality of driving on motorways is atrocious, sitting in the middle lane, lorries having to under take as drivers don’t understand there is a speed limit and how to overtake and pull back in!!
Tony..As a father with 2 daughters I understand where you are coming from..You are no doubt incredibly proud of your daughter and I offer my congratulations to her for her Masters in traffic engineering and 15 years experience on smart motorway design.
However, motorists are like Paul, we are not naturally expert on all things related to smart motorway design and monitoring..moreover as someone who drives in excess of 30 000 miles per year, designers and motorists can lean so much from one another but may I suggest, to you and your daughter , there are no experts in any field...no expert is 100% right all the time and mortals are never right 100% all of the time ...we are all trying our best, just as Paul was doing , so a little bit more humility and understanding on these pages is always welcome.
Have a great weekend Tony
Hello Tony Drew, I think your post highlights the reason why smart motorways are unsafe and this is because people are unable to use them properly. I think that is the reason why so many people believe the programme should be terminated. Motorway design should not require special training/education for drivers in order to enable it to operate safely.
What a ridiculous comment. Try telling the relatives of all the people who've died on smart motorways (due to leaving them exposed to oncoming traffic when broken down), that they're safe.
My comments are based on facts - widely reported. Did you & your daughter see the Panorama expose of this, for example? These smart motorways are fundamentally flawed, and very dangerous, because there are inadequate refuge spaces for broken down vehicles, too far apart.
Also, the camera monitoring is inadequate, and sometimes results in operators failing to spot a broken down vehicle, and hence fail to close off the nearside lane. That is a massive design flaw in the whole thing.
Generally things have to be safe, even if people do something wrong. You cannot possibly justify things only being safe if everyone follows the rules correctly! That's absurd.
Incidentally, whenever anyone starts any comment by telling me to only comment on things I understand, without exception they go on to write utter tripe, as you have done. I check the facts on everything I write.
People who design & build duff projects usually go to their grave protesting that there was nothing wrong with them. That's human nature. An exception was the politician who authorised smart motorways, who conceded in the Panorama interview that they were not safe.
Too true. I spent nearly 15 years as an engineer in safety-critical fields, but anyone with an ounce of common sense could see that such 'smart' motorways were obvious, predictable death-traps. I couldn't believe they were being implemented and it was perfectly obvious that was going to lead to tragic deaths.
My comments are based on facts - widely reported. Did you & your daughter see the Panorama expose of this, for example? These smart motorways are fundamentally flawed, and very dangerous, because there are inadequate refuge spaces for broken down vehicles, too far apart.
As of last year Highways England have shown that the number of deaths on the new stretches of smart motorway had fallen by 28%. It's not over a long period of time but standing back from the press coverage it makes a bit of sense if you consider that people will generally be driving more slowly.
The issue, I think, is that all of the deaths on the smart motorways are caused by the same thing - people stopping or breaking down on the dynamic hard shoulder and then getting out of their cars. That seems preventable while accidents caused by excess speed are accepted.
Personally I hate the things, but the actual evidence is that they reduce congestion and pollution and save lives. Not that that will make any difference of course.
timarr
timarr,
The issue, I think, is that all of the deaths on the smart motorways are caused by the same thing - people stopping or breaking down on the dynamic hard shoulder and then getting out of their cars. That seems preventable while accidents caused by excess speed are accepted.
Personally I hate the things, but the actual evidence is that they reduce congestion and pollution and save lives. Not that that will make any difference of course.
Show the evidence for this please.
A Morris Minor with wet drum brakes, driving at 70mph is incredibly dangerous. A modern car that can stop on a dime with ABS is not.
Motorway accidents are NOT caused by excess speed. They are mostly caused by driver inattention, and drivers being too close to the car in front.
The safest thing you can do, to prevent motorway accidents, is to leave a good long gap between you & the vehicle in front.
I've looked into this stuff all my life, so DO actually know what I'm talking about, unlike the proud but foolish father.
Regards, Paul.
Hi Paul
Personally I hate the things, but the actual evidence is that they reduce congestion and pollution and save lives. Not that that will make any difference of course.
Show the evidence for this please
It comes from the Highways England Smart Motorway All Lane Running Overarching Safety Report published in March this year.: https://www.gov.uk/government/...
It's riddled with jargon but the main findings are a reduction in the overall number of deaths:
Overall, there has been an absolute reduction of 27.9% in the casualty rate, from16.76 to 12.08 per hmvm. When taking into account the national motorway trend of a 12.3% reduction in casualty rate, there has been a statistically significant reduction of 2.62casualties per hmvm, which is a 17.8% improvement. This change was statistically significant.
Naturally the press have ignored the findings. Still we wouldn't take any notice of the press when it comes to public safety, would we?
timarr
I read the executive summary and some of the report. There are 3 types of smart motorway and I believe one of them, the dynamic hard shoulder, has created a lot of the problems and is being knocked on the head. It's introduction was a mistake.
Tim,
I think part of the issue here (at least) is that there are more than one type of "Smart Motorway". Controlled motorway schemes - like the M25 with its dynamic speed limits seem to make a lot of sense, and I have no problem accepting they save lives and improve traffic flow.
But the real issue, and I'd assume that's what Paul is talking about, are the all lane running schemes (no hard shoulder) and the dynamic hard shoulder ones (no hard shoulder in rush hours erc). Those are where the excess deaths have been happening, and it's pretty clear that some of those are inevitable if you don't have a hard shoulder. However, good your CCTV monitoring and however quickly the signs are lit if someone has to stop on the HS then there is a real, and increased, risk of someone running into the back of a vehicle stopped on what has become the inside lane. Add to that normal human issues, drivers and cctv operators not paying 100% attention and the risks get bigger still.
I'd think it's pretty clear, that in contrast to what someone posted earlier, the driving force behind their adoption was not the ideas of academics, but the desire in transport departments to increase the number of effective lanes on some motorways without the considerable costs of building one.
"(Re Smart motorways)..the desire in transport departments to increase the number of effective lanes on some motorways without the considerable costs of building one."
As this site has discussed re Covid, should the calculation not be : risk of death or injury compared to the cost of building vs the opportunity cost of other road safety investments - just as NICE compares the cost of alternative new medical treatments (or at least did until Covid!).
It could be that avoiding the extra motorway cost and fixing 200 traffic light junction/blind bends saves more lives more cost effectively; especially if autonomous motorways are only 10-15 years away. This is the tyranny of the big and obvious - think HST2 vs new suburban platform extensions and track links!! Health & safety is most about choices not eliminating risks.
Disc. - I own no SMART motorways or trainlines (nor have any special expertise in these :)
Hi peterg
The report is on the all lane running schemes - basically the safety aim seems to be to keep death rates at or below the levels seen before they were introduced. Which the report claims is the case.
To be honest, I don't really have a dog in this fight, I was just pointing out that the actual evidence suggests smart motorways aren't any more dangerous than normal ones. Personally I hate the bloody things, but I do feel we should try and weigh the evidence rather than jumping to conclusions based on gut feel and Daily Mail reports.
timarr
So smart motorways are great if humans don't act like humans. That's ok then..
re Smart motorway design. ‘.....due to people not using them properly.’ Then that is down to bad design! Good design foresees and caters to human behaviour, that is why you can’t put an electrical plug in the wrong way. You can’t blame people, you blame the designer for not understanding crowd behaviour!.
These 'smart' motorways are only as smart as the people driving on them. Most drivers will use them sensibly but unfortunately as Paul points out people don't pay attention. I have seen countless amounts of times people in high end cars, just modern ones in fact, driving whilst holding the phone to their face, or texting. Truck drivers fiddling around with 1 of their many Sat Nav devices on their dash. Yet most of these vehicles are fitted with Bluetooth connectivity.
Its a fact cars will always break down, yet one car can cause so much chaos because drivers are not reading the road ahead. More pressure should be put on manufacturers to tackle phone use in cars.
For that reason I am going to avoid Costain (LON:COST)
Paul, you should help the economy and yourself by buying a new electric car! Chris
Hi Chris,
I would buy (or rather, lease) an electric car, if a charging point was available in my block of flats.
It's something I've queried, and likely to be installed at some point in the future, but not imminent.
I justify having a 4.0 petrol car, by the fact that I only do about 1,000 miles p.a. in it, and use trains/bike/walk for everything else :-)
Best wishes, Paul.
Paul,
You might want to consider a car club. I made the switch several years ago and really like the system. One reason being no MOTs to worry about. Its also better than car hire, much more relaxed about scratches etc.
best
Hi Armorduck,
Yup, I'm a member of car clubs, both in Bou'mth and London. They're handy to use e.g. when it;s raining & I don't want my old XJS to get wet & turn into a pile of rust on the garage floor!!
Unfortunately, I think the London one I occasionally used (DriveNow) has folded, which was a pity. They used to hire out Minis convertibles & BMW i3 - both huge fun to drive!
Cheers, Paul.
Raven Property (LON:RAV) - you need to check but I don't think the ordinary shares offer a yield as such. From memory they make a regular, but not guaranteed, tender offer at above the prevailing price which I suppose you could consider a "yield".
They do have preference share alternatives (RAVP) and (RAVC which is shortly to convert into RAVP). These do currently offer very high yileds which should perhaps tell you something of the perceived risks involved.
Disclosure - I own RAVC
I have held the preference shares for many years ,a quarterly dividend of 3p,ie, 12p /annum. In light of risk to all dividends currently,I have no problem with this one. I have sold my REIT's as the future is uncertain ,regarding the dividend,which is why i held them I did top up with a few more at 82p ,a few weeks ago. My average buy price is 131p over many years
Paul, you mention Staffline (LON:STAF) needing to get their results in quick to avoid suspension - is that still the case in light of the FCA announcement as I thought this gave everyone up to an additional two months? Or have I got my wires crossed....
As mentioned in the article, the FCA has given them an extension.
A cheaper Russian version of Warehouse Reit (LON:WHR) might be Raven Property (LON:RAV) , clobbered by Woodford placing/overhang but at a substantial discount to NAV , and like in the UK in Russia there has been a dramatic move to internet shopping over lockdown .
Always good to get some tips on this site. Re Raven (£RAV) it looks very intriguing and would appear to offer a very solid yield. Board looks good too. Obviously being Russia there is a big discount factor.
Agronomics (LON:ANIC) is a nice little case study on things to watch out for when using the Stockopedia Stock Rank system.
It has a negative revenue of -£45K. Clearly that is not good but it causes Stocko to compute an operating margin of 1718% and put it in the very top set of companies by Op Mgn. Similarly it has a P/S of -497 which Stocko also thinks is a top-performing value for P/S.
This inflates the Q and V ranks and could mislead you when building a screen.
Arguably anomalous values for financial ratios should cause them to become N/A for screening or ranking purposes because their value has ceased to tell you anything useful about the company. But in the meantime it is essential to check all of a stock's values for sanity before trusting the ranking system for that stock.
Yes I've seen and previously reported previous issues like this where negative values cause anomalous rankings. It's disappointing that the algorithms still allow these through. It seems like basic error trapping to me. I have to say I have stopped bothering to report them any more.
Hi Paul, Is it your Jag that has failed the MOT - why, what year and model? Hope its sorted soon. Disclosure - I own two Jags!
Are you John Prescott?
no that would be two jabs.
Hi Paul,
Agronomics had raised money 3 times in the last year alone! I was asked to look at it earlier this year and was put off by the constant raises. Secondly, majority of their investments are in the US which is a serious game over there so without being able to follow you'd get diluted regardless. It was interesting as a vehicle to play the alternative meat category but too opaque in addition to the points above.
Agronomics (LON:ANIC) - OK, there's some risk that the proposed tender/buy out offer might all come to nothing but just received a quote to BUY Agronomics (LON:ANIC) at 5.1p - that means a 20% uplift to the proposed 6p buyout. Looks as though they're trying to push the process along rather than drag it out.
SIG (LON:SHI) £105m placing at 11% discount & £60m investment at a 25% discount from CD&R Sunshine.
The co agreed fees of £25m = 15% of total.
The cash to the co is 23.6p/sh, a 30% discount!
CEO grabs a £375k bonus. What, for arranging such a knockout deal?
Uninvestable
RNS: "The Capital Raise is expected to raise £165 million in gross proceeds, and c.£140 million in net proceeds" is a little misleading.
So the fees are 7.2% of gross equity raise and 3.6% of the debt. The shares issued av. 26p net of placing fee, a 22% discount.
Sorry about that. Still looks like a poor deal to warrant a CEO bonus.
Request for Studio Retail (LON:STU) today. Owns fast growing internet business https://www.studio.co.uk/ "Studio has continued to trade strongly and well-ahead of the prior year, with product sales over the first eleven weeks of the new financial year up 55% against the comparative period. This has been driven by particularly strong demand for ranges such as toys, games, electricals, fitness and garden".
I believe there have been companies that transferred from the main index to AIM. Osbourne & Little. Think they might have gone private now or the same way as the editor of the Standard. Is there enough regulation or are they just happy for it to perform as skid track! I remember the CO of Avanti saying he would never have had the opportunity to raise the money without aim to launch 2 satellites carrying their broadband into space. In fact I think I watched the second launch or was I dreaming). )I was quite excited to be invested in that even if it did come back down to earth empty. Seems they just need to start jailing more of the ones who spoil a great opportunity for the genuine ones, and they must be clearly distinguishable. Less clear is who and how efficiently it is regulated.
Last comment, if Agronomics (LON:ANIC) is now 5.01p on the market and there is a Tender offer coming of 6.00p why wouldn't you buy as there is a 20% gain for what seems calculated risk?
Or should this be filed in the not part of the plan and you are going to regret this B1N?
re Agronomics (LON:ANIC)
"...not to accept the Tender Offer, and to consult with other Shareholders on whether they wish to hold shares in Agronomics as a private company, and on the proportion of their shares that they would wish to sell under the Tender Offer. These discussions will be used to assess Shareholder support for the Proposals and, therefore, determine whether to proceed with the De-Listing, and, if so, the size of the Tender Offer."
"The Board believes a significant majority of shareholders will support the Proposals. It is however aware that, if the Proposed De-Listing goes ahead, it needs to consider the best interests of all shareholders, which is why the tender offer is intended to ensure minority shareholders who do not wish to remain as shareholders in a private investment company would have an opportunity to sell some or all of their shares. The announcement today allows the Company to gauge the position of its shareholder base so that, if it proceeds, the tender offer can be structured accordingly."
Quotes above from the RNS, with my bold added. It seems to me that there is no guarantee that you will be able to tender all of your shares even if it does go ahead, and hence this is certainly not a risk free arb, particularly if you don't want to be left with some unlisted shares in it.
The Cyber attack on Australia highlights the need and opportunity for Cyber-security.
I own #IGP and #SWG.
Yes I've got those two. Apparently SWG are also delayed by auditors from being able to release results, and another that spared punters from the £2.40 placing. Now 20% below, but happy to wait nervously!
#SWG not delayed - always said 'in June'.
From the trading update 24th April
"Having successfully built the Company into a profitable business providing a wide range of software and solutions to best protect organisations' data and information, it is an appropriate moment to scale Shearwater. We now have a solid foundation from which we can build, a highly experienced Board with an enviable contact base and a very professional management team capable of executing this expansion.
"Due to the uncertainties created by COVID-19, there are many more opportunities for good businesses to team up with us and become part of an exciting group in the growing market for organisational resilience."
Trading update and outlook
Further to the pre-close statement announced by the Company on 2 April 2020, the Group has had a strong financial performance for the financial year ended 31 March 2020 and has generated unaudited revenue of £33.0 million (FY19: £23.5 million) and unaudited Underlying EBITDA of £3.2 million (FY19: £1.4 million loss). Cash as at 31 March 2020 was £3.3 million but is expected to reduce by approximately £2.3 million during April 2020 due to scheduled payments of amounts owing under prior acquisitions.
During the period, the Group has continued its focus on driving operational improvements through effective organisational design and the execution of cross selling opportunities. Most recently, as a result of the COVID-19 pandemic, the Group has experienced a step up in software sales as the demand for cyber security solutions which enable organisations to facilitate secure remote access to their critical networks, data and information assets has increased, as the trend for home working continues.
In addition, the Group has noted a change in revenue mix from higher revenue/lower margin hardware-based sales to lower revenue/higher margin and high recurring software and subscription-based sales.
As a result of the prevailing market trends, in conjunction with the proposed implementation of the RCF and the Placing, the Directors enter the new financial year with a great deal of confidence around their ability to execute on the considerable growth opportunities that the Group is experiencing.
The price has fallen back substantially and appears to present a decent risk / reward scenario.
DYOR.
I hold.
re Shearwater (LON:SWG), the forward PER stands at over 40. Future growth seems to depend quite a lot on the management's "buy and build" abilities - they seem to be doing quite a decent job so far. But the risk still seems to be on the high side to me, compared with others in the sector.
Shearwater (LON:SWG)
well they really should be doing well in a crisis shouldn't they (aside can we being back commercial union please for the same reason?)
they as they describe themselves as being
"the organisational resilience group"
Thanks for flagging this one up guys - looking at the main company info this looks like the trend in main numbers looks very promising (i like a good trend does i)
Interesting that there are some red flags - so i think i may have a look into this one under the bonnet when i get some time.
Paul - i can't see that this company has been commented on before in the daily reports which seems strange - so if the numbers are as nice as stocky suggests might be woth some comment if you have the time and inclination
Oh extra comment - it looks like they may be adding profits by acquisition - not my preferred method of increasing profits doh!!
There is a Cenkos note if you are interested.
Hi Michael. Re SWG Someone on ADvfn apparently emailed and got a reply saying results would be delayed several weeks due to immobility and shortage of staff at auditors. Waiting for date to be scheduled.
Hi Simon.
I have just sent Phil Higgins (CEO) an email to check.
Regardless, the updates have been very good both in terms of figures and cash generation. Also C19 remote working has been a positive also.
Both CEO and Chairman spent £125,000 each in the recent placing and have significant share-holdings.
The SP was 295p a few weeks ago, the placing was at 240p and now below 200p.
No worries, I bought more myself this morning again. I agree the Director participation has been nothing short of spectacular. They should build on the profit turned now I would hope.
I just wanted to say thank you for the posts and comments on my "am I a Numpty?" post earlier in the week, whilst still hurting it makes me remember that I am a human being doing the same things we all do - agonize over everything and sometimes we feel a genius and sometimes we fell a total numpty. We make the decisions on the information we have at that time, and the emotion we are feeling at that minute and then live with them the rest of the day, week, year, life depending on what that decision was.
So learning from last year where I had a couple of >50% drops e.g. Card Factory (LON:CARD) and thinking that they will bounce back and not selling, and then obviously finally selling at the very bottom to watch them bounce back significantly from the point of sale. I have been more disciplined at using stops to remove the emotion and noting that I am not at able to react immediately most days even with alert emails etcetera.
With most stops triggering during last week and a couple this week, I have then watched the market all go back up again, or in the case of Strix (LON:KETL) an intraday low spike. So using Stockopedia better and having my retrospective "Am I am Numpty or Genius?" shadow portfolio, it hurt and hurts. But it was the right lesson learnt, it was just not executed well. Thank you for the point if it is a long term hold put it in the cupboard and forget about unless there is something fundamental changes about the business that causes you to rethink - I am watching Strix (LON:KETL) and will buy back in again.
So Paul a big thank you for your honesty both in the PI World interview and on your commentary on your decisions on De La Rue (LON:DLAR) and Newriver Reit (LON:NRR) . Just because you chose to sell does not mean you cannot buy back in again, later that day, later that week or even in two years time.
There is still massive FOMO still going on. But I have managed to implement another lesson learnt and sit on the sidelines and focus on the other challenges in life currently and not chase things that were not part of a plan.
Picking up the positives whilst down on all three portfolios (my shares and ISA, and mum's SIPP) by varying %'s whether judged by 1 week, 1 month or 1 year. Me and mum are still in the game and the cash is there when I am ready and it feels right to deploy. Hopefully I can make a few more of right decisions at the right time with some of it, and cut out a couple of the mistakes as looking at this year (since January 2020) literally a handful of decisions would have meant this year would be positive on all three portfolios.
Whilst it feels like a daily imperative of missed opportunities, I didn't follow Paul with Best Of The Best (LON:BOTB) and I did not follow my instinct to buy Boohoo (LON:BOO) ahead of the Q1 results, this is a 20 year timeline not a 3 days, so yes I miss out but as someone rightly pointed out there will be plenty of opportunity to be both a "genius" and a "numpty" in the months and years ahead.
So yes my decision to sell Hammerson (LON:HMSO) at £1.37 after doubling up to almost break even was really good with hindsight, and my decision to exit Fevertree Drinks (LON:FEVR) looks silly, that is just part of life.
Tonight there will be a very appreciated glass of wine once the kids are in bed as my wife got confirmation yesterday she had passed two really important pieces of coursework (four months after submission) as she is currently having to do a day a week at University whilst being frontline NHS and that is what important really means.
One pattern of behaviour I've noticed in myself is unduly weighting my negative performances. For example, I timed the rise of Go Ahead shares from the very bottom of the recent dump-off to the the top of their particular rally. Timed it perfectly. Do I pat myself on the back and allow that stroke of luck to cancel out my Tupperware FOMO?
No I don't. Like an idiot I regard the Go-Ahead success as par, the minimum that a savvy investor should be doing, and the Tupperware debacle is further proof I am not said savvy investor.
A much healthier approach (and one I am working on) is to view the whole thing like Kipling:
"If you can meet with Triumph and Disaster
And treat those two impostors just the same."
You'll be an investor my son!
Just as a post script note, the exit of Hammerson (LON:HMSO) was 08 June, and the exit of Fevertree Drinks (LON:FEVR) at a loss, selling at £16.86 was 13 May.
I like to decouple my buys into two rules:
Do I think it is a solid company (this can also be a moderately expensive one) and I think will keep going over many years to build brand/leverage/competitive advantage etc.
Or do I think it is a company that is being underappreciated but not a ground breaking company (usually cheap).
The reason I do this is because I ignore my instincts to sell or market sentiment on the first one and become emotionless to it, and for the second, I monitor it much more closely and just get out quicker if it seems I got the sentiment wrong and sell sooner if it goes up - maybe just lock in even only 10% upwards.
These are just my rules, and it has worked for a number where the price went down but I knew were ultimately very well placed companies.
Sometimes companies become a bit of a mix of this as environment changes though, I would put £FEVR in that category - I like it and think the long-term brand is great but bars (on-market) being shut has been a huge stumbling block.
My not so classic XF had issues in the Beast from the east snow with a blocked Diesel Particulate Filter (DPF) - Had to get it de gunged by a specialist - it was out of puff as if it had CV-19! At least your classic was before such modern emission friendly solutions, you love it really
re. Staffline and other businesses in this sector.
This is the industry I work in and I wouldn't consider investing in companies right now. Naturally the sector has been badly affected by COVID and the only reason companies can post ok results is because of furlough and rent or tax deferrals. For many of them it will take several months after staff return to work to see revenue coming through and even longer to see cash. I can see mass lay offs in this sector.
Companies with a strong contractor book should be ok, but those relying on more than 50% of their revenue coming from 'permanent' recruitment fees could be in trouble.
As for Staffline, I don't know their business, but 2019 was a good year for my industry. My company and most others made a lot of money, so not sure why they made a loss. As I mentioned, I know nothing about Staffline so maybe there is a reason for their EBITDA loss that I am not aware of.
Re £STAFF, maybe some hoping for a full takeover by the Chinese company with a large shareholding. Quite close to the limit aren't they?
I think that company is from Singapore....really well run business, industry leading RPH, excellent profit margin and yet their shares have halved in recent years, so what do I know??? :)
Wish if the Small Cap Report available for Australian (ASX) market
I have not seen anything to replicate SCVR in Oz, but if you have not used it this site (and its regular neweletter updates) I have found is a useful resource.
https://smallcaps.com.au/
I like the sound of WHR. I am going to look into this further.
Get yourself down to Motorpoint (LON:MOTR) for a bargain.
I hope he's going to Vertu Motors (LON:VTU) for his bargain, and while asking Mr Google if they actually sell any decent cars, I came across this
https://cardealermagazine.co.uk/publish/investor-calls-vertu-motors-buy-troubled-dealer-group-lookers-merge-marshalls/194466
Published earlier this month but I had not seen it before and it mentions the possibility of quite a bit a M&A in this sector.
Another cardealermagazine article shows they are sales are improving (do they own cardealermagainze by any change
https://cardealermagazine.co.uk/publish/robert-forrester-on-you-and-yours/195509
REC divi date 11 August - it was right at the beginning....
My morning smallcap tweet: 16 summaries. Friday used to be quiet.
Global Ports Holding (LON:GPH) Trifast (LON:TRI) Urban Exposure (LON:UEX) IQ-AI (LON:IQAI) APQ Global (LON:APQ) Staffline (LON:STAF) Velocys (LON:VLS) Catenae Innovation (LON:CTEA) Woodbois (LON:WBI) H C Slingsby (LON:SLNG) Costain (LON:COST) Agronomics (LON:ANIC) £SRG TechFinancials Inc (OFEX:TECH) Redcentric (LON:RCN), Learning Technologies (LON:LTG)
Global Ports Holding (GPH) denies press reports that it may delist.
Trifast (TRI) £15m placing via ABB "to continue to invest in long term growth as well as maximising its growth in the short term as markets recover." Trading in line.
Urban Exposure (UEX) Following decision to cease seeking new business, CEO & COO leave, released from share lock-up. Some other dirs leave as well. Won't dispose of Urban Exposure Amco. Guides potential net returns for shareholders 70p to 83p. 80% of proceeds should be returned in 7 to 15 months.
IQ-AI (IQAI) its MRI DSC perfusion technology earns recognition as the national standard for scanning high-grade brain tumors. "It is the only MRI-DSC platform that offers truly quantitative output regardless of scanner platform, field strength, or time point."
APQ Global (APQ) book value 17.49c or 14.15p
Staffline (STAF) not aware of any reason for yesterday's SP surge. Financing talks continue and co expects to agree and implement a revised financing structure ahead of finals(Dec) which will appear in July, a month beyond deadline. Extension granted. Guides small underlying FY EBITA loss. I hold.
Velocys (VLS) FY(Dec) results delyed beyond June. Guides rev £0.3m (£0.7m), adj op loss £9.8m, cash £4.8m (£7.0m) despite £7m raise in July.
Catenae Innovation (CTEA) partner has successfully completed the proof of concept pilot trial of the Company's Cov-ID status verification passport app.
Woodbois (WBI) reached an agreement in principle with the major bondholder for a debt for equity swap. Conditional on placing. Will invest c$3-5m in Gabon factory, which has restarted sawmill ops.
Slingsby (SLNG) rev in Jan to May down 3%. "The trends in Group gross profit margin and overheads experienced in the first quarter of 2020 have continued in Q2 and, as a result, operating profit in the five months to the end of May 2020 has remained higher [YoY]...Orders are concentrated on a limited product range and it is unclear as to the impact that the virus will have on demand." Also possible bad debts.
Costain (COST) activity levels have increased since the beginning of the lockdown and have now stabilised. Has won a number of new contracts and framework awards since the £100m fundraising. Guides order book £4.2bn.
Agronomics (ANIC) plans to delist and make 6p tender offer with sum available TBD. "To fund the Tender Offer, the Company intends to raise funds from parties interested in supporting Agronomics as a private company." SP is 6.75p.
Studio Retail Group (SRG) CMA will refer sale of Findel Education to a Phase 2 review.
Techfinancials (TECH) FY(Dec) has material uncertainty going concern stmt.
Redcentric (RCN) delays FY(Mar) results to 21st July. Not due to any audit issues. FY was in line.
In line: Learning Technologies (LON:LTG)
Thanks for posting these everyday Mr Contrarian. Very appreciated
Paul Hawkin's webinar yesterday: Everything you wanted to know about Corporate Bonds. Video here or Podcast here.
This is an amazing lesson for anyone who wants to understand Corporate Bonds, with the key elements an investor should consider. Paul Hawkins traded in bonds for RBS, Barclays and Santander, before becoming a full time investor. Absolutely priceless education.
Next week, no educational Thursday webinar, instead we have F1 video games company, Codemasters Group (LON:CDM) who will present their results, including an opportunity for questions. Register here.
I remember when Codemasters started in 1986. Before that the Darling brothers developed games for Mastertonics.
STAF now expects to report a small underlying EBITA loss for 2019 and pre-IFRS16 net debt of £59.5m as at 31 December 2019. Any thoughts on that, Paul
Generally flat results out of Record (REC) today. Pretty good in this market. I continue to hold. My only questions are a) will they manage to grow and b) when will the proposed dividend be paid (in my experience companies hide the dividend date to make sure that you read the complete set of accounts). I failed.
The interim dividend of 1.15 pence per share was paid on 27 December 2019, and the final ordinary dividend of 1.15 pence per share will be paid on 11 August 2020 to shareholders on the register at 3 July 2020, subject to shareholders' approval.
I find searching for "dividend" does the trick :)
timarr
Plus the special dividend of 0.41p
Any other companies paying special dividends at this time?
Plus the special dividend of 0.41p
Yep. I keep hoping they'll pull a growth rabbit out of a previously unnoticed hat but in the meantime the income stream has covered most of my initial investment.
As an aside I don't invest for income in general, I prefer companies that invest internally to grow their earnings, but in the last four months my portfoio has been deluged with dividends whereas I imagine most dividend investors are seeing severe drops in income. Partly that's because a lot of UK companies have been overpaying dividends based on their earnings and partly it's opportunistic - a way of cutting dividends under cover of the general market malaise.
The other part, obviously, is the collapse in earnings in swathes of the market. Anyway, hopefully, on the other side dividends will be rebased at more sensible levels allowing more internal investment and better future earnings growth.
timarr
I’ve slept on my NRR stake, and have decided to hold. I’m tempted to add. To my mind they are positioned to capture the new mood of localisation, and the price more than adequately covers the risk. Well done with your usual open thoughts on the subject yesterday.
What did it fail the on Paul? Very rare that a vehicle fails a retest!
Well it’s an XJS.......
Emissions too high, and handbrake needed adjustment. Halfords decided they didn't want to try adjusting the handbrake as they've not been trained in doing that kind of handbrake. Also they put some engine cleaning fluid in the fuel tank & told me to take it for a good long drive. So I burned through half a tank of petrol, in order to improve the emissions lol! Something illogical about that! That didn't work either. So it has to go in to a specialist dealer. Am beginning to doubt my wisdom in selling a 3-year old Merc to buy a 27 year old soft top Jag lol! But it's worth it every time I take it out for a spin on a sunny day :-)
Paul, try this I’m told it works for getting through emissions tests https://www.dipetane.com/
When I had a nice older car I arranged the MOT and annual service at the same time. Much better than just pitching up at these MOT centres and hoping it gets through. It might have needed a couple of things done prior to get through the MOT but it was all sorted out on the day so saved lots of time.
Probably tells us more about Halfords than anything else.
Did they suggest an OEM Catalytic Converter to cure the emission problem?
When you said engine cleaner I thought 'diesel' which would have been understandable but then you said petrol....hmmm. Ok, having worked in the trade I've heard things and would suggest finding yourself a good local independent garage rather than use a big chain.
Hi Paul, Sorry about the Jag. I run a 50 year old Triumph Convertible so I know where you are coming from. My car doesn't need an MOT because of its age, I believe the cut off is 40yrs. Too out of the ordinary for the average test centre and test machines would fail it on emissions because standards have got tighter. Could be your car is spot on for an XJS. I either check it over myself or take it to a back street garage that employs experienced mechanics. Best advice if you don't have the skills and tools is to find a Jaguar owners club, it can help with where to go in your area, sourcing parts etc and you might enjoy the social side too. Edit just read the age of yours is 27. Get an E-type.
You might have been better just getting a 3 year old Merc convertible!
The good long drive is supposed to include thrashing it a bit. Possibly easier said than done with a V12 engine.
I've always looked for an MOT station that does free retests and ONLY does MOTs, so they have no incentive to fail it on marginal items.
Charlie Munger, Vice Chairman of Berkshire Hathaway, once commented “[w]ell I think I’ve been in the top 5% of my age cohort all my life in understanding the power of incentives, and all my life I’ve underestimated it. And never a year passes but I get some surprise that pushes my limit a little farther.” In his famous The Psychology of Human Misjudgment speech, he continues to expound the importance of incentives by talking about how they changed the behavior at Federal Express, and it is worth reproducing in full: One of my favorite cases about the power of incentives is the Federal Express case. The heart and soul of the integrity of the system is that all the packages have to be shifted rapidly in one central location each night. And the system has no integrity if the whole shift can’t be done fast. And Federal Express had one hell of a time getting the thing to work. And they tried moral suasion, they tried everything in the world, and finally somebody got the happy thought that they were paying the night shift by the hour, and that maybe if they paid them by the shift, the system would work better. And lo and behold, that solution worked.
Hi Paul,
I thought that MOT's were extended for 6 months because of covid.
Yes that's right, mine was due to run out but has been extended until November.
Chop it in for a low milage XKR .
smells the same but works