Small Cap Value Report - (Fri 19 May 2023) - OTB, PHC, MIRA, KGH, CCR

Good morning, it's just Paul here today.
Today's report is now finished! Thank you for all the interesting reader comments this week.
Countdown to Mello Chiswick - on Tue & Wed next week. I'll be along in the afternoons (SCVR writing in the mornings as usual) and evenings, so hope to share a drink & a natter with as many Stockopedia subscribers as possible, do say hello to Graham & I if you're there!
** STOP PRESS ** - David at Mello has just been on my WhatsApp, saying that, as a thank you for Graham & I doing some presenting at Mello, he'll let 5 Stockopedia readers have Mello Chiswick tickets for just £10, for the Tuesday next week only - use code: ME23TEN here.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk.
Quiet for news today -
Paul's Section:
First of all, 3 rather dull sections that I prepared last night -
On Beach group (LON:OTB)
105p (£174m) - Interim Results - Paul - AMBER
I had a look at these figures the other day, but ground to a halt, as there’s not enough for me to go on, to form a view.
H1 is the seasonally slow, winter half year, for this beach holidays agent. So it incurs a fair bit of the up-front marketing spend for the peak summer bookings period, but in the seasonally slow half of H1 to March 2023. Therefore, there’s not really anything to be gleaned from its H1 performance, which was around breakeven, the same as last year. The big expenditure is marketing, which can be flexed up or down to suit.
I also find the balance sheet rather tricky to analyse, with very large receivables, client trust account, and trade payables. So it’s difficult to know how these balances would move about on a day-by-day basis.
Paul’s opinion - neutral, as trying to work out how the business is likely to perform in future requires too much guesswork at this stage. Although with the share price having almost halved from a recent spike, I am wondering if it might be a more speculative trade, for a bounce? There's also the question about how much the holiday sector will recover, given the cost of living squeeze?
OTB was achieving about 16p EPS pre-covid, and now has c.27% more shares in issue. So if it matches pre-covid performance, then we could guess that EPS might reach about 12.6p. Put that on a PER of say 10-12, and I get to a rough valuation of 126p-151p. Since the price is currently 105p, that suggests to me that there could be something worth researching further here, if you want to invest in the holidays sector.
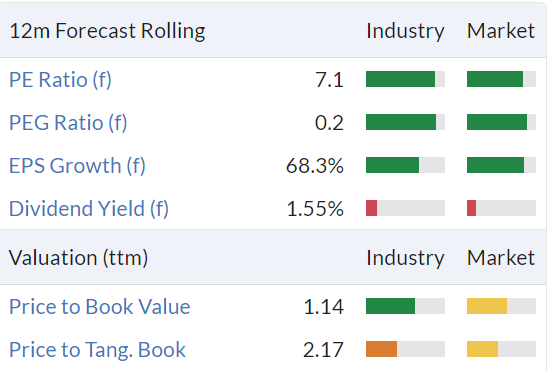
It also looks cheap on broker forecasts, with the StockReport showing a forward PER of only 7.1
Overall then, I'm intrigued, but haven't got enough information, so will say I'm AMBER.
Plant Health Care (LON:PHC)
Up 7% to 10.9p y'day (£34m) - Remaining Listed on AIM - Paul - RED
I mentioned this poorly performing, loss-making company here on 2 May 2023, when it announced it was consulting shareholders on whether to de-list or not. Yesterday it announced vague details of its consultation, which sounds encouraging, with shareholders wanting it to maintain its AIM listing. It sounds like another fundraising is likely at some stage, with at least some sign of shareholder support.
I’ve just had another quick look at its 2022 results, and they’re really bad - another large loss, and cash running out. Why get involved, when there’s currently no sign of this being a viable business?
Mirada (LON:MIRA)
Down 66% to 6.5p (£0.6m) - De-listing - Paul - RED
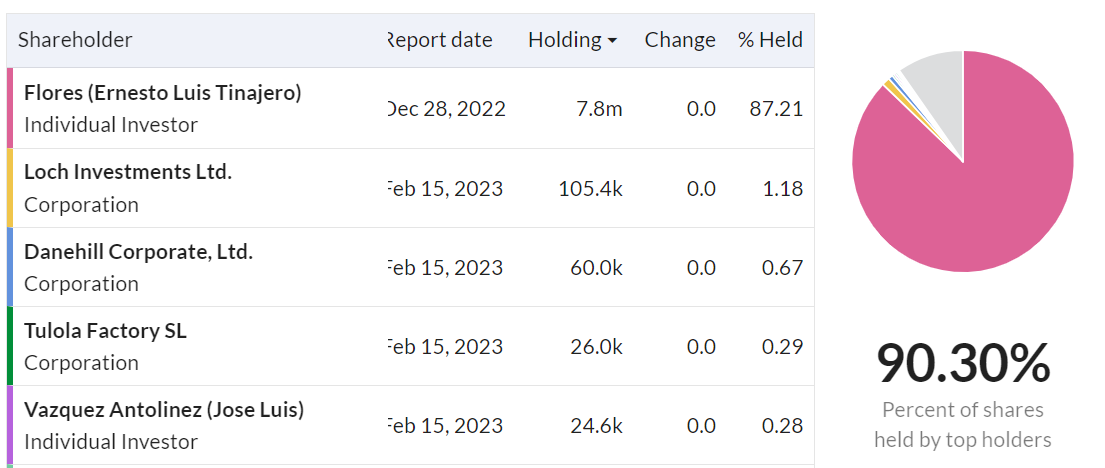
Delisting - announces it will de-list. The usual problems are mentioned - e.g. low & volatile share price, inability to raise fresh equity, lack of liquidity, and costs/hassle of a listing. It also points out that having one major shareholder with 87% of the company is an issue. The share price fell 65% on the delisting news, and the market cap is now only about £0.5m, so clearly it makes no sense to remain listed.
Once again, we need to be carefully checking everything in our portfolios, particularly tiny, loss-making companies like Mirada, for their shareholding structures.
Brokers (and AIM itself) need to stop allowing micro caps to float with absurd shareholder structures like this -
Knights group (LON:KGH)
Up 9% to 93p (at 08:35) (£80m) - FY Trading Update - Paul - GREEN
Knights, a fast-growing legal and professional services business in the UK, today provides a trading update for the year ended 30 April 2023.
We last (briefly) looked at this expanding chain of legal firms here in Nov 2022, when a reader TheFloatingInvestor flagged a £1m Director buy, after a reassuring trading update. I had a quick look, and confirmed that it looked super-cheap.
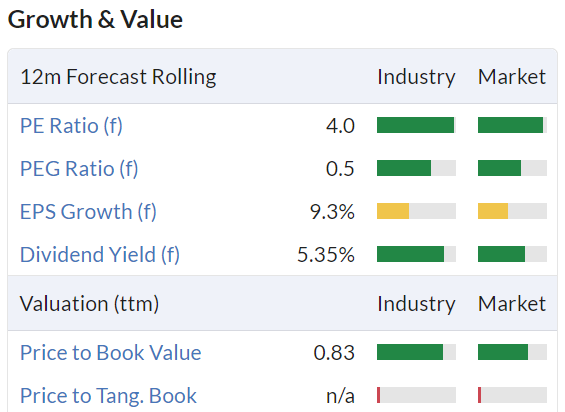
Although I’m not a fan of listed legal/accountancy firms, due to their inherent conflict of interest between fee earners and outside shareholders. Mind you, when something gets down to a forward PER of 4.0, with a healthy dividend yield on top (although no asset backing), value investors are compelled to take a closer look! Here are Knights value stats as of last night -
Today’s update - is for FY 4/2023 - key points -
Revenues £142m (up 13% vs LY) - although this is £4m behind the StockReport’s consensus broker forecast.
Underlying PBT c.£21.5m (up 19% vs LY) - the StockReport figure is not directly comparable, since it is PAT of £17.1m. That implies a corporation tax of around 20.5%, which is in the right ballpark. It’s a pity Knights didn’t specify if the £21.5m adj PBT is in line with expectations or not - that’s the most important piece of information in a trading update, so to omit it is a schoolboy error in my view. I’ve just lodged a complaint with the company’s advisers.
EDIT: I've just had a reply saying my feedback has been passed on to the company, and that the house broker has apparently issued an update note which indicates that yes, this update is in line with their expectations. So maybe it's one of those updates where, by not mentioning it, the implication is that's it's in line with expectations. I much prefer that to be specifically stated, rather than implied. End of edit.
Debtor days - key for lawyers, as it’s capital tied up. This is a reasonable 30 days (i.e. unpaid customer invoices for the last 30 days billings, which is very reasonable actually). Plus a total of 87 days is quoted for “lock up” - which is unpaid invoices, plus unbilled work-in-progress. I haven’t compared this figure with other listed lawyers, but it sounds reasonable, at just under 3 months. This is improved from 98 days lockup at H1 end.
Net debt is £29m, significant given the market cap of £80m. Well within the £60m facility limit. Also well down on the £35.6m reported at end Oct 2022.
Acquisitions - 2 in the year, have gone well. 2 more in the pipeline. So it sounds like the business is on the front foot, making further acquisitions. It seems to be buying up smallish legal firms outside of London. So a key question would be to find out how they manage all the different firms, and what synergies & disciplines are imposed. Often legal firms are quite badly run, and inefficient, so there can be advantages to bringing them into a well managed group. Although how are the big fee earners retained & incentivised, is a key question?
Balance sheet - there’s no asset backing, with the last reported balance sheet showing NTAV of around nil. So bear in mind that the working capital is financed with bank borrowings, which increases risk if something were to go wrong. Plus of course bank borrowings are more expensive now.
Paul’s opinion - I previously thought Knights looked cheap, and today’s update confirms that.
So it’s a GREEN view from me, although I’ve only done a fairly brief review this morning, and would suggest anyone buying the shares needs to do considerably more research, as always, because we cover so many companies here, it’s possible we might have missed something important.
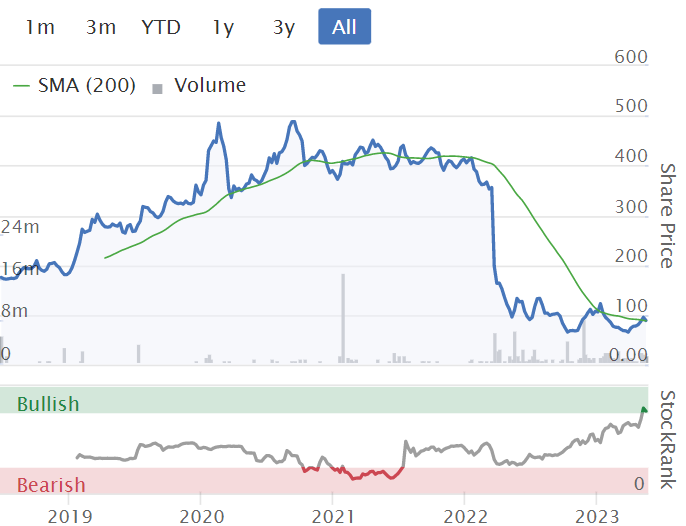
In particular, I can’t remember what went wrong in March 2022, but that was the trigger for the shares massively de-rating, so that would be the first thing on the list to research in more depth.
Maybe there’s an opportunity here, with the business seemingly having recovered, but the share price has not followed suit, still in the doldrums. Note the StockRank has also been rising strongly and is now quite good -
C&C (LON:CCR)
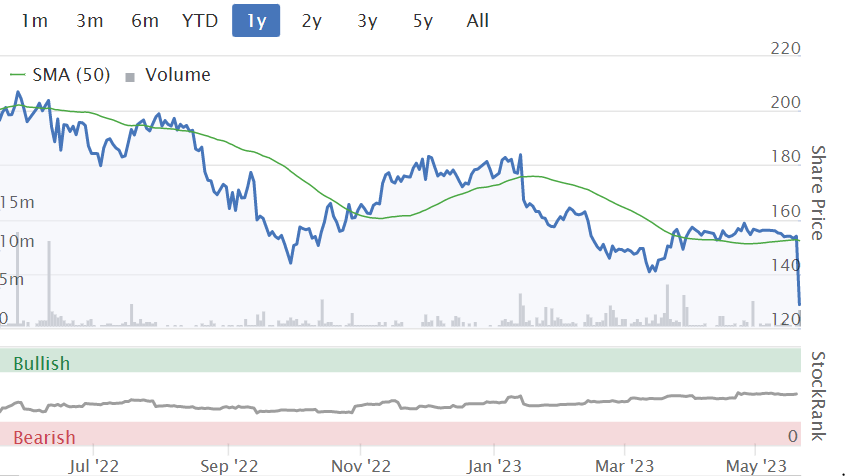
Down 17% to 127p (£502m) - Profit warning - Paul - AMBER
C&C Group plc (‘C&C’ or the 'Group’), a leading, vertically integrated premium drinks company which manufactures, markets and distributes branded beer, cider, wine, spirits and soft drinks across the UK and Ireland…
Graham normally covers this Irish-headquartered group, and did an excellent review here in Oct 2022, which I’ve just read to get me up to speed quickly.
A ERP system upgrade has gone wrong at the businesses (Matthew Clark & Bibendum) bought out cheaply from the collapse of Conviviality in 2018 -
it has encountered significant challenges, in terms of time, cost and customer service…
We’ve had a few companies report similar problems with IT upgrades recently, eg Virgin Wines UK (LON:VINO) - a reminder to see announcements about buying new IT systems at any company as an amber flag maybe?
They thought the issues were under control in March 2023, but deteriorated again in April. May is getting better, but involving heavy additional costs.
What’s the financial impact? Hefty -
C&C currently expects a one-off impact of c.€25 million associated with ERP system disruption in FY2024, reflecting the cost associated with restoring service levels and lost revenue. There is expected to be a consequential increase in working capital in FY2024, however leverage is expected to remain within the Group’s stated range of 1.5x to 2.0x.
The rest of the business is performing in line -
Excluding the impact on MCB, C&C is currently performing in line with management expectations for FY2024 and the Board is confident in the Group’s medium and long-term strategy and prospects.
Guidance - this sounds quite strong actually. I’m assuming that the reiteration of previous guidance is because the one-off impact above will be treated as exceptional, and adjusted out? -
C&C re-affirms the guidance given in its Pre-Close Trading Statement of 23 March 2023. Specifically, the Group expects to report operating profit of €84 million. C&C’s strong free cash flow generation, together with increased balance sheet strength will also enable a re-instatement of dividend payments to shareholders, with respect to FY2023.
Management changes - the CEO has fallen on his sword, or been pushed maybe, as the Chairman and CFO step up, the CFO becomes the new CEO.
Results are due out shortly, so hopefully it’s a day Graham is working, so we can get his more expert view -
The Group will issue FY2023 full year results on Wednesday, 24 May 2023.
Paul’s opinion - it’s dangerous buying after a profit warning, as problems can snowball quickly - I’m sure everyone can remember how fast Conviviality unravelled, with minor initial problems soon becoming massive, insurmountable problems that ended up with the group going bust. Hence it’s bound to unsettle investors in CCR that the same businesses which brought down Conviviality have now dented CCR’s share price by 18% today.
I’ve had a look at CCR’s last balance sheet, and it’s solvent, but not particularly strong, with NTAV of 85m euros, which I don’t see as being a lot, given the size of the business. It’s dependent on bank funding, so the covenants do matter.
If the IT problems get sorted out promptly, then I imagine this issue could just be a bump in the road, providing possibly a good entry point for investors who already like the company.
Or, it could get worse, we don’t know.
Personally, I don’t see anything serious enough to be ringing alarm bells, but can’t get madly excited about the upside either. So it’s a neutral, AMBER view from me at the moment.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

56 comments
All tags gone missing.
I used to own Jet2 JET2, sold much too early but at least missed the covid crash. I have just bought back in having done a swift comparison with OTB and Tui. I wanted to go for a travel company as there seems an insatiable demand for overseas travel for UK consumers, especially short-haul, that is not being much affected by inflation and the squeeze on incomes. Tui and Jet2 are much bigger companies by market valuation and I do think their buying power makes them pretty safe as mass-market providers in terms of competitive pricing. The share count at Jet2 has risen but so has the book value per share. The danger may be the age of the driving force behind the copany but I feel much safer here than in OTB.
Seems they are going to have a good 2023:-
https://www.reuters.com/world/...
Who knows about 2024.
I also have had a little dabble in Jet2 (LON:JET2)
Hi Paul
Thanks for flagging up the MELLO Chiswick ticket offer code for next Tuesday (from David S). I've just grabbed a £10 ticket for the Tues as I can't attend on Wed/Thurs.
I appreciate your STOP PRESS update - great work.
Matt McK
There are still a couple of ten pound tickets left but they are only for the Tuesday. If any of you want both days just use the 50% off code ML23STOCKO50
Re Mello. I'll be there again...sifting through the dirt for any diamonds :) ...I quite enjoy events like this as efficient ways to meet crap companies (or at least ones I have a prejudicial view of).
Was nice to meet some people from here last time. Say hello or give me stick if you prefer...I'm tall, grey hair and usually garish sort of shirt on (well, I think classy but I realise others have different views)...
Even Mr AngryPotato(?)...I'll buy you a beer.
You're unique Mojo! ;-)
Haha. Yes I’m a bit odd …see you there Paul and hopefully for a bit of nonsense chat in evening as well as the <yawn> day job :-)
OTB.
I mentioned the awful experience my wife had with OTB during covid cancelations,wife spent months sending them e mails asking for a reimbursement , my wife was receiving different messages from different departments telling her conflicting & confusing responses.To cut a long story short the plan was to wear my wife down,ithanks to poster Erng who advised us to go to our Bank who duly paid us out.Iwonder how much our bank has charged them ?.So for me my research stops there.
I looked at Trust Pilot and could see a lot of disgruntled customers leaving their negative comments and rating but one thing is clear though a lot of them said their customer communications are terrible as chat and phone lines have nearly two hours waiting time. In their reply they are apologising saying they are extremely busy.. does it suggest they are having a customer bonanza! also i do noticed some very happy customer comments too (I Hold).
A message and question for Simoan particularly, but others feel free too, re semiconductors area:
Views on Sondrel (Holdings) (LON:SND)?
A few questions to aid the response:
1) Is the migration into 'turnkey solutions' a positive? So not just ASIC design but prototyping and production with the latter a long duration low headcount service with the intention being to add scale earning on top of the capital/labour intensive design work.
2) How vulnerable are they to design tool access they are permitted by others?
3) Access to these tools create big working capital/amortising intangibles effects. What to worry about there? Can they scale and reduce the relative impact of this? (There's quite a bit of opacity around this stuff right now that won't get clearer until they report fully)
4) Did they IPO as they were over strained by covid impacts to business...was it effectively a bail out IPO? (partly they got to gift Siemens shares in return for reducing onerous liabilities owed to them)
Re iEnergizer (LON:IBPO)
The company was £800m market cap not that long ago and c.£500m before delist announcement. Some grounds to be cheesed off with such a low valuation given pretty decent performance...but its a bear market time and the ownership structure odd in that Aggarwal owns nearly 90% so its always going to be on a discount to a more normal structure.
Aggarwal collects approx £35m in dividend payments at current payout. Nice.
Clearly he's unhappy with this situation for some reason. We can only guess why.
What is clear that announcing delisting without any mechanism or offer for shares at that moment would always hammer the shares. I've got no great insight on what the price for a share that will no longer be listed and when private is 90% owned by an individual who hasn't exactly respected shareholders in a public setting should be. My guess is that anything above zero is perplexing. I'm no expert on corporate law (I've been significant owner of two unlisted companies...well three but I'm excluding one) but ability for majority owner(s) to change directly or indirectly materially impact minority rights is very high. If the majority owners want to take more economic interest for themselves they can engineer that relatively easily. You may be able to fight some of that if you have the legal stomach and/or wallet (done that before!) but its tough going and can become emotionally painful...you are always a poorly informed outsider and the insider(s) can switch things up on you just to mess with you. It ain't cricket (or whatever...hailing from northern Scotland this game is a mystery to me)
Conclusion: I think you need your heads looked into if you are thinking of committing any significant wealth to iEnergizer. Aggarwal has already shown he's happy to rip your face off. What you do commit is mere lottery style gambling...unless you have some pretty fearsome personal or bought corporate law capabilities.
I'm not sure how a matched bargain facility will operate. I believe there will be entire discretion on 25 May for the buyer(s) to set price....I'd guess that will be Aggarwal and if he's saved 1/3rd of his last dividend cheque he can buy all the remaining shares! If its not Aggarwal then its clearly an absolute mad f%$&...or some hardcore activists/hedge fund with a deep legal team that think they can make a big turn out of their stub.
I forecast the matched prices on 25th will be well below today's price. And that if you hold your shares into private land you will get much less and perhaps zero dividends. But if its money you can lose it may be an interesting experience
I'm still hoping that any of his client companies with ESG policies will bar this company from tendering for services! Procurement depts would find this slam and grab of interest to them in the tender process. Always worried about being collateral or reputational damage.
I do wonder if this Investor relations person and this friendly helpful matched bargain dealing is to put "lipstick on the pig". Sorry I don't mean to offend any pigs!
Fundamentally though this was legal and AIM market sets the conditions to allow / even encourage this sort of behaviour. It will continue, unfortunately. I think you are right on the price - Aggarwal says "I'll give you 1p" and you have the choice to match!
Hi Paul, I do enjoy your write-ups - keep up the good work. Were you going to do a write-up on Kinovo? I thought their figures were excellent and they still look cheap.
Oh yes, I started looking at Kinovo, but got side-tracked by something else. I've noted it down on my pad. Isn't that the one that collapsed, and has recently 5-bagged? Any idea what's behind that?
On a quiet Friday here's a chance for you to give your views on investor relations provided by listed companies and potentially win a case of wine. MHP the financial PR are looking to produce a piece of research that identifies the key information which influences an investor to invest. We all have our gripes and praise about IR so here's an opportunity to give feedback directly to the people who shape the IR we receive. Please take the opportunity to give all your views.
Just for the record, we have no commercial interest in this survey but we passionately believe in the retail investor getting equal access to company information as institutional investors. If this is important to you too, please complete this Investor Influence Tracker here with as much detail as you can. Many thanks, hopefully you win the wine - odds should be pretty good!
Completely separately, a few webinars are coming up:
Today 19th May 2023, 1.15pm Cerillion (LON:CER) CEO & CFO will present interim results. Paul's interview with Louis is brilliant and I look forward to hearing a continuation of the story today, following the interim results, which were released on Monday. Register here.
Next Tuesday, 23rd May, 11am, Eneraqua Technologies (LON:ETP) CEO & CFO will present Full Year 2023 results. They are a relatively recent IPO. Specialists in energy and water efficiency so in a sweet spot. Register here.
And a way off, Tuesday, 20th June, 2pm IG Design (LON:IGR) The Chairman & CEO will present their Full Year 2023 results. There is all new management here, the new CFO moved into the CEO position and a new CFO joins at the beginning of July. They were hit very hard by COVID and the inflationary impact of containers, staff, energy and other commodities. I'm looking forward to hearing how it's all coming together. Register here.
Paul, sorry to keep mentioning this but some of the tags have dropped off, again.
Hi Rusty2
Paul, sorry to keep mentioning this but some of the tags have dropped off, again.
Yes they do this quite often, usually just before lunchtime, so maybe the tags are also going to spend the afternoon in the pub?!!
What I normally do now, is to do a final check of the tags when I sign off here at 13:00 to 14:00 usually, and put the tags back in, if required.
Still, it's helpful when you remind me, if they've departed early for The Rising Sun! ;-)
Regards, Paul.
It's probably something to do with a later entry. You create a tag, and then do something else which causes the tag to drop off. Do other Stocko writers have the same problem or is it an SCVR thing? I'm trying to be helpful which usually blows up in my face!
Looks like all the tags went down the pub and never returned. Seriously Stocko should fix this problem. Otherwise there will be more gaps when searching.
Luceco (LON:LUCE) another director buy today, think that is 4 different director buys this week, all fairly significant amounts, is this suspicious?
Also a director buy at Future (LON:FUTR) following yesterday's fall.
The only suspicious is that you are misleading the community here, unless you haven’t properly studied all these transactions in the last 3-4 years.
For example, W Hill pocketed about 3m on previous sales and a couple of buying transactions is just meaningless.
I don't know if it is me but every company I seem to come across at present is a professional services business!! The UK market has declined significantly in the decade since I left the City. Back in 2001 about 50 to 60% of Pension Fund monies were in equities now according to a recent figure I saw its nearer 20%. IPOs are way down with Cos preferring the US. I remember people who didn't know or didn't care responding to "we will lose the City" with "never". Well the degradation I see is significant and it is an important part of our national income.
By pension do you mean DB? As those will hold gilts, as they are not looking for growth, given most are nearly fully funded. DC will take a while to absorb the DB equities selling, but will continue to need growth, some of which will end up in illiquids
What you say is true. DB were starting to fall away early noughties (thanks to Sir (ha ha ha) Robert Maxwell, that well known socialist. I think by 2005 the largest UK DC scheme was probably over a billion so would have expected to see DC make good progress 17 years later. But yes I am not sure what numbers the 20% were measuring although if DC have gone into these managed lifetime thingy majibs the last of the boomers are approaching retirement so I would expect those to be in bonds (poor devils!)
Tharisa (LON:THS) H1 results to 31st march 2023. $310m mkt cap, Rev $335.3m, profit before tax $72.4m, nett cash $110m, 3 cent dividend. the new Karo mine likely to be fully funded from cash generated. Looks good value at 85p, i would appreciate you checking out the financials. DYOR
The Resolution Foundation has an interesting report out today on food prices which shows they will soon overtake energy as the biggest hit to household spending (see below) - albeit in terms of annual increase in spend which will reflect high comparatives for energy. The last ONS figures showed 19.2% inflation and looking at some of the early Kantar data for April I wouldn't be surprised if the figures next week show this getting even worse. The government is unlikely to do much about food prices so this potentially has quite a bad impact on some households' disposable spend.
Also presumably rising food prices are going to knock out some of the hospitality sector which is probably best stayed clear of right now.
It's actually pretty shocking that households are almost £2000 worse off due to food and energy alone compared to this time last year (and also pretty amazing that the economy is doing as well as it has despite this).
https://www.resolutionfoundati...
Morning ! I thought the trading update for Knights group (LON:KGH) was decent this morning, looks inline with a forward p/e of 4x ? I know you (Paul) don't like the sector but this strikes me as well oversold and too cheap now. Who agrees ?
In theory Knights group (LON:KGH) looks cheap with underlying PBT of 21.5m. However in 22 underlying PBT of 18.1m translated into an actual loss. That's a serious amount of underlying!!
I held last year, but the adjusted number seemed nonsense v the actaul loss as you say, so sold out. It appeared they buy companies and report only the good bits, stripping out anything they don't like. Also if p/e is 4x it needs to buy companies < that to make a decent return. Doesn't make sense to me.
I was tempted to drop the 'under' from underlying but thought better of it! :-)
Just another thought when in researched this company last year, there was underlying yoy growth I.e. all growth was from acquisitions. The model seems to buy professional services that are plodding along and put them together, hoping to create a big plodder.
Thanks for the comments on On Beach group (LON:OTB) Paul. A few other things to note:
I nevertheless hold albeit in part because I haven't had time this week to have a proper dig through the figures yet!! But those are my initial thoughts.
On delistings Paul has commented on another case above and MrContrarian highlights news of iEnergizer (LON:IBPO)'s process for trading of shares after delisting. As a question on iEnergizer (LON:IBPO) and absolutely not recommending as a strategy, but is there a case to buy the shares at this point and level if someone is interested in dividend income? It paid dividends from 2019 through the pandemic and Stocko is showing it having divi yield of over 40%. If the majority shareholder is committed to paying himself dividends, this could pay for itself in less than 3 years. After delisting would shareholders still have the same rights to dividends? Clearly liquidity would be very limited even given today's announcement and this would be high risk for example if the company stops paying dividends or pays them at a lower level. Wondering if I've missed something and what others think about this?
Hi Michael_P
I totally agree, it’s a dilemma. I don’t have enough experience of previous cases to know if the company will carry on paying dividends once it delists. Total market solution ‘s website sums up the dilemma:
https://total-market-solutions...
In the past I have held a number of shares through delisting. Some were dogs that never paid a dividend that I should not have bought and were eventually liquidated. However, two were dividend payers that continued to pay decent dividends. in one case the main division was sold and a return of capital worth a multiple of what I bought the shares for (let alone their post-delisting price) was made. The other the company continued to pay decent dividends and a return of capital through a tender offer occurred again providing a 100% of profit on my original investment let alone any post-declaration price.
So perhaps a viable strategy could be to invest in solid dividend paying companies bought at a post-delisting declaration price and held through to an eventual return of capital. However, one would have to be content not to be able to trade the shares for a realistic return or at all for years and be prepared to take a total loss on those companies that did not trace the happy scenario I experienced in the two instances I mentioned. As my experience was not part of a strategy I can’t even guess at a likely return from such a strategy but can only suggest it is not completely foolish and one only for the very patient and adventurous- two qualities that seldom go together.
Thank you for sharing your personal experiences and fascinating insights. Indeed that is an unusual combination of traits an investor would need to have on this. Agree that trying to quantify expected expected outcomes is not straightforward.
Hi Michael-P,
As a holder of IBPO my dilemma is do I sell now before de-listing or continue to hold.The shares were trading at £5 in October 2022 and now at 56p.My thoughts are that as the company is profitable and was up for sale that this may yet happen after de-listing and possibly at around the £5 level -giving the majority holder a windfall on all the shares purchased at the lowly 50p level.Why would privately owned companies be valued at 10% of listed companies-sure there is a liquidity differential but not 90% discount.The risk is that the majority holder will be able to do what he wants and that may mean paying no dividends.I’m minded to hold and see what happens as how can a company with a previous near one billion market cap be now only worth 100 million because it’s un -listed.Comments welcome please to help me make a final decision.
PS.many thanks to Paul Graham and Roland for their brilliant daily reporting.
I certainly wouldn't want to advise you on this. What I can say is that I hold shares in an unlisted company through part of a remuneration package during a brief stint working at a startup. My expectations for that ever achieving an exit are pretty low and dividends are also a dim and distant prospect at best. The way I think about that investment is totally different to how I think about listed investments. In the case of iEnergizer (LON:IBPO) a lot of it comes down to a qualitative judgment on the CEO himself. He is 64 so he may be gradually starting to think about retirement and in that case, an ongoing source of dividends or an exit if conditions allow may be appealing. For me I'd wouldn't be placing much confidence on an exit, but it might not be unreasonable to think that there could be some dividends. Who knows how long for or at what level. Best of luck with whatever you decide, the delisting process currently is not kind to existing holders.
Thanks Michael-P.
Re-IBPO ….thinking more on this if it was easy and profitable holding this share when it de-lists why haven’t the experienced and knowledgeable Private Equity mopped up the cheap shares.It may be possible for such a large shareholder as a per cent to vote through a resolution to change his shares to dividend paying shares and everyone else converted to non paying dividend shares resulting in those holders effectively holding shares worth nothing apart from equity if sold.Very un ethical and I am no expert but guess it’s a possibility.Also as a private company it maybe more tax efficient to sell it that way than if listed but again this is a guess.
Many thanks for the input on this.
There are a lot of valid questions there and a lot of unknowns. Possibly due to the small float private equity realise that the only way of taking control of the company is negotiating directly with the majority shareholder and he may have made clear that his sale price is more in the ballpark of the pre-delisting price or above. There are 32 million free float shares and the 20d average traded is 2.9 million which is far above the 365d average of 260,000 so there has been very brisk recent trade. Possibly some of that has been institutional buying although likely many funds are forced sellers if they are not permitted to hold unlisted instruments. As I said before though I am certainly not making a recommendation, just trying to think through the mechanics of a particular type of special situation.
Re iEnergizer (LON:IBPO) I am not a holder but was for a while. I sold at a profit so no sour grapes.
We talk a lot on this board about trusting management. The decision to delist is Aggarwal's. He has not had the courtesy to explain either the logic behind the move to delist or what will happen going forwards. He is no stranger to unusual corporate behaviour - with the obvious exception of PE houses, who else loads up a company with a massive debt simply so that they can pay themselves a massive dividend? That is not an ordinary activity in our universe.
So I think talk of massive upside and dividends is inconsistent with the way in which this company has been run in the past and it it is almost certainly reasonable to assume, based on previous experience, that the interests of the majority shareholder are paramount and that the minority shareholders will NOT be treated well here. The market certainly seems to think that - hence the massive gap between the previous price and the current one. Other delisting companies tend to lose 50% of their market value - not the near 90% that initially happened here.
We hold Peel Hotels, a previously listed company with much more straightforward management. We are yet to multi-bag on that one and, because of losses, dividends have ceased.
Apologies, I just re-read that and realise I have rather over-used the word 'massive'. I know we are supposed to ignore our gut feelings but mine is telling me here that this is a company to be avoided at all costs
IBPO - Based on the total lack of regard towards their private shareholders regarding the way they have gone about the de-listing - I personally wouldn't trust them to ever pay a dividend. Once bitten, twice shy! My fear is that they will pay themselves the dividend but that the private holders will never see a penny. Obviously their 'dividend' will be disguised through 'consultancy fees', bonuses for achieving targets etc - if there is a way they can screw you then they probably will (based on their recent actions). Perhaps an eventual sale may see a good return but personally who wants to have their money tied up in something they have no control over - especially when there are so many good opportunities in well run businesses that do have regard for their shareholders.
Not advice, just my opinion.
Hope everyone has a great weekend.
cheers
Matt
Paul, if it's a quiet day, would you kindly look at Alphawave IP (LON:AWE) please? It's been discussed quite a lot by subscribers due to heavy director buying, decent stocko ranking & shareprice momentum, followed by suspension pending a re-audit of accounts. Should be admitted back to trading today or next week as accounts now published.
Alphawave IP (LON:AWE) made 2 large acquisitions last year and this was the reason for missing the deadline for audited accounts. There was no re-audit, it just took longer than expected. Judging by the fairly terse statements around the group CFO departure it strikes me that the founders were perhaps unimpressed with the delay despite the lumpy transactions that complicated the audit process. Certainly listening to the results presentation the CFO gave no indication that he was on his bike so I heavily suspect he was pushed due to the poor timing.
Nonetheless the audited results for me didn’t feel like material changes. Some wrangling over classifications that is fairly normal in these type of circumstances but those are usually not done in public of course. For a company struggling with a perception problem its unhelpful.
Nothing really changes the longer term story though and you either buy it or you don’t.
£awe
If I was a holder I would not be so generous - did they not go out on a limb to say they expected no changes per final audit and yet something like 15% of profits have been removed. Imho current credibility of board here is next to nil from my perspective. They didn’t have to go out on that limb in that regard and yet they did - just made themselves as a board look pretty hopeless here imho. Personally not sure how anyone who is not one of the main insiders could know what is really going on here with all the moving parts in play.
I've taken a quick look through the accounts and nothing is simple.
Huge acquisitions relative to size of company (3 acquisitions for consideration of $439m, and that before a whole bunch of deferred compensation which got bunged into working capital...). Unsurprisingly headcount is up from 149 to 695.
The largest acqusiition for $245m was loss making:
"If we had acquired Banias Labs on 1 January 2022, we estimate that the Group's profit for the year would have been US$12,388,000 lower."
The JV accounting for Wisewave/Verisilicon is very hard to wade through. They are recognising revenues from a discount off the licence fee in the early years. As a reminder:
"At the end of 2022, the Group owned 42.5% of WiseWave, a newly formed company established in China in Q4 2021 to develop and sell silicon products incorporating silicon IP licensed from the Group." And then we find lower down "The value of the cumulative losses incurred by WiseWave exceeds the cumulative value of our investment into the business."
57% of revenue was from China...later they state "We expect a decline in revenue from China over the longer term".
The Going Concern note seems OK...
But then you have "announcement of a large non-binding multi-year agreement with a leading North American hyperscaler." What is the point of an "agreement" that is non-binding? Is that AWE saying to hyperscaler "If we build something really good will you buy it"? Response from Hyperscaler "We agree we will look at it....."??
CFO now gone.
It no longer bears much resemblance to the company that IPOd...you now need to get your head around 4 companies and work out what they all do.
I've filed into the "very difficult" folder, for possible onwards transfer to the "I can't see what is going on" folder where I put IQE many years ago.
Thanks for that Monty Carlo.
Alphawave IP (LON:AWE) sounds way too complicated for me to analyse from scratch on a Friday. I was hoping to rattle through 2-3 simpler companies that I already know, then knock off work around 12:30 to go for a long lunch in Soho with Research Tree!
Regards, Paul.
Paul, if it's a quiet day, would you kindly look at Alphawave IP (LON:AWE) please? It's been discussed quite a lot by subscribers due to heavy director buying, decent stocko ranking & shareprice momentum, followed by suspension pending a re-audit of accounts. Should be admitted back to trading today or next week as accounts now published.
I don't see how Paul can meaningfully comment on Alphawave. It's completely outside his circle of competence. I used to work in the Semiconductor IP industry and have dealt directly with some of the companies associated with Alphawave and it's a complete punt as far as I'm concerned. I can only judge the company based on my experience of dealing with associated companies such as VeriSilicon, and it is not good. My gut told me not to trust them because they were always so vague about what they were doing. And that pretty much matches all of the information I have seen in the public domain about Alphawave.
I can only really judge based on soft issues, such as the CV's of the management team, and they do not impress me at all. These are not the semiconductor industry heavy hitters I would expect to see leading a $4 billion IPO. And the CTO is a bloody academic with no real industry experience! The Executive Chairman has only really worked at Achronix, a tiddly little unprofitable niche FPGA company - not Xilinx or Intel (was Altera). Companies like Achronix used to contact me regularly looking for some kind of association so they could add another "partner" to their website and issue some joke marketing PR. In that regard, I'd completely ignore the Partner page on the website. It's just a piece of marketing puff and at least two of the companies mentioned are competitors!
All the best, Si
Simoan - I share all of your concerns above.
However, in the interest of balance we should also recognise that the company (or at least the board) is not entirely composed of nobodies as you have the Marvell founder in there, to quote something I've scraped off the web to save time:
"Dr. Sehat Sutardja was a co-founder and CEO of Marvell Technology Group.
Sehat led Marvell, since inception, as Chief Executive Officer, and
took the company public in the year 2000 after achieving record-breaking
profitability and scale in a short period of time. Sehat and his wife,
Weili Dai, also a co-founder of Marvell, ran Marvell for over 20 years
and built one of the top semiconductor companies in the world."
Of course I am also aware of the circumstances in which the couple departed from Marvell.
Go and look it up folks, and draw your own conclusions.
Hi simoan,
"I don't see how Paul can meaningfully comment on Alphawave. It's completely outside his circle of competence."
Thanks! (err, I think)
P.
Thanks! (err, I think)
Sorry, yes, my comment was meant in a positive way. I worked in the industry for 20 years and honestly couldn’t give a good assessment of the business outlook of Alphawave IP (LON:AWE) myself, so don’t really see how anyone else hereabouts could either. It’s such an opaque company. There are too many red flags and so not a company worthy of your time IMHO.
And I couldn’t agree more with you.
My morning smallcap tweet: A stake in the heart of the city
Knights group (LON:KGH) Oxford Nanopore Technologies (LON:ONT) Unbound (LON:UBG) iEnergizer (LON:IBPO) Genedrive (LON:GDR)
◄Knights (KGH)► guides FY-Apr rev up 13% and U/L pretax c.£21.5m. In line? [SP=85 Cap=73m]
◄Oxford Nanopore Technologies (ONT)► presented "breakthrough performance data and new platform updates, including direct RNA sequencing to support the emergence of RNA-based therapies". [SP=237.46 Cap=1964m]
◄Unbound (UBG)► could be very short of cash in Sept due to the planned build-up of inventory. Hoists For Sale flag. Temporarily ceased its loss-making direct-to-consumer sales in the US and EU - 11% of rev. [SP=3.5 Cap=2m]. I hold.
◄iEnergizer (IBPO)► JP Jenkins has been appointed to provide a matched bargain facility after deling (24 May). [SP=51 Cap=97m]
◄genedrive (GDR)► NICE draft guidance recommends CYP2C19 genotyping for clopidogrel treatment. "Although CYP2C19 ID test is in development, the NICE Committee included its predicted performance and pricing in its clinical and economic models." [SP=21 Cap=21m]
Thanks MrContrarian - your summaries are much missed when you take a break