Small Cap Value Report (Fri 19 Oct 2018) - REC, SFE, PDG, SSON

Good morning!
There's a lot of Brexit-related news at the moment but it's unlikely to help us find the next great small-cap opportunity, so I'm going to pretend it's not happening.
Today we have:
- Record (LON:REC)
- Safestyle UK (LON:SFE)
- Pendragon (LON:PDG)
- Smithson Investment Trust (LON:SSON)
Record (LON:REC)
- Share price: 31p (-12%)
- No. of shares: 199 million
- Market cap: £62 million
(Please note that I currently hold REC shares.)
Not a great update from Record.
This is a specialist fund manager providing currency services. I own shares in it because of my positive impression of management (conservative and well-aligned), excellent cash generation characteristics, and my belief, at the time I invested at least, that it served an important financial niche.
Unfortunately, it hasn't achieved much in terms of growth in the last few years - but then, this has been reflected in the valuation.
Its share price has also been a victim of the recent general market correction, and then when you add in the effect of today's trading update, it's dropping deeper into what I hope will eventually prove to be "cheap" territory.
When it comes to valuation, we should bear in mind that the company had equity (as or March 2018) of £26.5 million, almost entirely tangible and liquid, including cash and money market instruments worth £22.5 million.
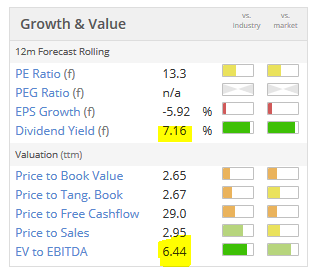
The Stocko valuation chart shows what I'm talking about: forecast dividend yield of 7% and EV/EBITDA ratio of 6.4x (prior to today's sell-off, so it's cheaper now).
Today's update is not too encouraging, sadly. Assets under Management Equivalent (AUME) are up by 1.1% when expressed in GBP, but this was driven by market movements, not by client inflows. There was a small client outflow during the period.
Additionally, 7 clients (out of 66) are leaving, taking $2.5 billion of AUME with them (out of $61.8 billion). They use the Passive Hedging product, which is the cheapest one, so the total loss in terms of fees will probably not be huge. But it's hardly good news.
Fees - "Fee rates for most products were broadly unchanged". Again, this doesn't sound great. The overall trend in fees appears to be negative. No performance fees were earned during the period.
CEO comment:
"We are seeing an encouraging range of new business opportunities across products and geographies, although this has to be balanced against continued competition and fee pressure in passive hedging in particular. With our diversified product suite and our ability to offer tailored solutions to clients and potential clients, we aim to make further progress in the second half of the financial year."
My view - Unfortunately, Record's Passive Hedging product doesn't seem to stand out in the crowd (and charges low fees), while the Dynamic Hedging product, with higher fees, is a very small percentage of overall AUME and is in a negative long-term trend.
That said, due to my sluggish investment style, I have no immediate plans to sell my position.
On the bright side, I think it has the potential to recover some positive momentum in a period of extreme FX volatility, when institutions might be desperate for currency advice and might be willing to try the Dynamic Hedging product again, and I see the balance sheet and management as factors which reduce the risk of staying invested.
Safestyle UK (LON:SFE)
- Share price: 57.5p (+14.5%)
- No. of shares: 83 million
- Market cap: £48 million
Curious news from Safestyle, the windows and doors company which got hammered by aggressive competition, eventually taking its rival SafeGlaze to court. As a result, SafeGlaze is being forced to change its name and its behaviour.
Today's update:
The Board of Safestyle UK plc ("Safestyle") has become aware of certain rumours in the market and confirms that it is not in discussions to acquire NIAMAC Developments Ltd (trading as SafeGlaze UK) ("NIAMAC") nor to acquire its business or assets. The Board of Safestyle is however considering certain other arrangements with key stakeholders in NIAMAC that could benefit Safestyle's business and accelerate its recovery.
Not sure what these arrangements might be, does anyone have any guesses?
This company doesn't pass my quality filters but perhaps it could make for an interesting speculation if the competition is going to cool down and performance will turn upwards again?
Pendragon (LON:PDG)
- Share price: 23.3p (-11.5%)
- No. of shares: 1404 million
- Market cap: £327 million
Another victim of the EU's introduction of WLTP emissions tests, Pendragon's results are going to take a hit from supply disruption to new vehicles.
It's a sector-wide issue and most or perhaps all dealerships need to be marked down as a result.
Additionally, investment in the Used Car business has been accelerated.
And so:
As a result of the combination of these factors our underlying profit before tax for 2018 is expected to be £50m.
It's a pet peeve of mine when companies leave out prior-year comparisons. For the record, underlying PBT last year was £60 million. The year before that, it was £75 million.
My view - a cheap car dealership that has been buying back its own shares, I would be keenly interested in this if I wanted to get involved in this sector. The issues causing today's profit warning are, I think, temporary.
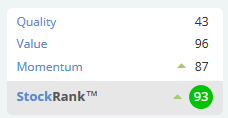
A portfolio based on the StockRanks would also be interested:
Smithson Investment Trust (LON:SSON)
- Share price: 1016.4p (+2%)
- No. of shares: 82 million
- Market cap: £835 million
Terry Smith's new vehicle hits the market: "a quality small and mid-cap global equity fund". I look forward to tracking its progress.
Paul is back next week. Have a great weekend!
Graham
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

21 comments
Re: Record NTAV I won't argue with cash.
But the expression 'money market instruments' always makes me wince.
Was not lehman brothers et al worth billions in 'money market instruments'
Hi Si
Frankly its hard to enough to spot the difference between Conservative politicians and Socialists nowadays.
Its very hard to know what incentives work for management. I tend to the view, hopefully like you, that some people just like doing a good job. But incentives have always been in fashion, though arguably less generous than some of today's outrageous trends.
In my head, I think of a cash pool equivalence to justify or otherwise. The problem with this is that the tax treatment of cash is potentially less generous (for now!) than options. Overall I am not too disturbed at the proposed awards, as they currently stand. There appears to be a lock in period.
I would imagine quite a lot of previous option awards lapsed as a result of CEO's etc leaving, so hopefully the historic dilution position isn't onerous.
Vive la revolution :-)
https://www.youtube.com/watch?v=qypgPszx3Kc&list=PLO_0P86K9BP98JY8acD2M6kuMTa1t9E9D
Does anyone know who Record (LON:REC) are losing customers to? My guess would be Alpha FX (LON:AFX) who look to be doing better, but Stocko has them marked as zero for momentum for some reason which isn't obvious to me.
Re Safestyle UK (LON:SFE)
The thought that immediately popped into my head when reading the announcement this morning was that maybe they were agreeing some kind of region by region non-compete agreement.
An other more bullish guess is that NIAMAC Developments Ltd (trading as SafeGlaze UK) [Actually I thought they had been barred from trading as SafeGlaze] has been so damaged by the legal action that Safestyle UK (LON:SFE) are picking over the corpse.
I strikes me though that unless you are in the business and know something it is impossible to tell whether either of these are the case or whether it is something completely different.
Without further clarification, it is not something I could consider investing in.
“It's a pet peeve of mine when companies leave out prior-year comparisons. For the record, underlying PBT last year was £60 million. The year before that, it was £75 million.”
Could not agree more. As a part owner of 13 odd companies I think that this should not a peeve but a requirement/obligatory. How companies report to the market/owners should be prescribed by the stock exchange. In the same that what goes into published accounts is prescribed.
Just my view.
Michael
The decision by Record (LON:REC) to buy a block of Neil Record's share for 45p doesn't look like such a great decision. The move last year was described as following.
The Tender Offer is intended to provide an efficient way for the Board to reduce the Group's retained capital and return excess capital to shareholders.
Regarding the dividend being covered by earnings, I have my doubts. The business is clearly deteriorating here. Management instituted a fee cut earlier in the year of 10%, so it's alarming that despite that, $2.5b in AUM is about to walk out the door. Not only do you have a reduction in AUM and fees, but costs seem to continue to mount, giving the company the worst of both worlds right now.
Of the £5.3m of ordinary dividends that were paid out last year, this was covered by £6.1m of earnings. With less revenue and greater costs, I cannot see how the dividend is covered by earnings. The real concern here is that even with the cut in fees, AUM has declined in the last few quarters regardless. Perhaps more cuts in fees are require to stem the bleeding?
The key question for any company with AUM is can they generate returns for investors? Otherwise money gets pulled and it is hard to convince new investors to invest.
For Record (LON:REC) the red flag is that they consistently never make any performance fees, which is when their funds generate good returns for investors. So lack of performance fees is almost a leading indicator of more AUM pressure coming.
Slightly off topic but I thought readers might enjoy a videoclip of a regional BBC journalist asking the boss of Persimmon (LON:PSN) about his £75m bonus https://twitter.com/spencerstokestv/status/1052981336288432128
Unusually, the Telegraph and Guardian in agreement on where those whopping bonuses are coming from:
Help to buy has mostly helped housebuilders boost profits
Help to buy is really help for housebuilders
paraic84,
Talking of which the snouts are in the trough at Revolution Bars (LON:RBG). I wondered how long it would take after the poor recent results, and not long was the answer:
https://www.investegate.co.uk/...
Just about the only good thing I can think of that would result from a Labour government would be an end to this kind of behaviour.
All the best, Si
Hi Si
Re: Revolution Bars (LON:RBG)
I can't believe that a Labour Government in current prospect would be the answer to anything much myself that a capitalist would generally believe in. Wait until George Orwell style,under Marxist or radical Socialism (or whatever BS is believed) that some decisions reflect some are more equal than others!
The reality of potential 'upside' for shareholders generally is around the £2.00 mark, so the only way to incentive management, apparently, is to give them a piece of that action, and to deliver a benefit to option holders that requires option pricing at the current level. There might be more underlying complication to the exercise criteria, such as lock in periods etc. but I suspect not.
Only an insider view would know on current Revolution Bars (LON:RBG) trading trends whether that is a truly low bar, or that represents a real achievement for management!? As a pool of money it seems to represent around a net £500,000 gain for all option holders, with the CEO getting at least potentially half that pool. So not the end of the world, assuming no more awards.
Not really worth electing a bunch of Marxists for, is it?
I can't believe that a Labour Government in current prospect would be the answer to anything much myself that a capitalist would generally believe in.
Me neither, which is why I said it's about the only thing I could think of. Please don't start off down the track painting me as a Labour party sympathiser - I'm not, it was just a simple comment.
The reality of potential 'upside' for shareholders generally is around the £2.00 mark, so the only way to incentive management, apparently, is to give them a piece of that action, and to deliver a benefit to option holders that requires option pricing at the current level. There might be more underlying complication to the exercise criteria, such as lock in periods etc. but I suspect not.
It has been well proven that such incentives do not work and only engender the wrong kind of management behaviour. I can't find the performance criteria for the PSP scheme. IMO the vesting criteria should always be clearly stated in the RNS announcing the options. Funny that it never is and it's so bloody difficult to find them. BTW the PSP options are free and not based on the current share price.
Not really worth electing a bunch of Marxists for, is it?
Again, that's not what I said. I regret mentioning it now so let's stop it here and avoid a long boring political debate. I personally have little interest in politics other than how it effects my investments and don't normally vote because of the stupid electoral system we have in this country.
All the best, Si
"I personally have little interest in politics other than how it effects my investments and don't normally vote because of the stupid electoral system we have in this country."
Interesting comment
I presume you're in favour of PR?
We share that in common as well then!!!
Do you know what the performance conditions are that they need to meet?
Do you know what the performance conditions are that they need to meet?
From the annual report it looks like a combination of EPS and TSR (total shareholder return) uplifts. Neither are great - both can be manipulated through share buyback schemes rather than any actual performance improvements.
Ideally there shouldn't be anything linked to share price - that's whatever the market deems appropriate at the time, and not something that managements should be trying to influence directly. Earnings is better, but some component of earnings they can't easily manipulate through friendly accounting is better still.
But broadly, perverse incentives incentive perverse behaviour. And if they didn't work companies wouldn't use them, so they're worth paying attention to.
timarr
Revolution Bars (LON:RBG)
The cult of the leader is alive and well.
A team drives an organisation forward, not one individual.
So why do remuneration committees continually come up with this solution - the CEO gets more than 50% of the bonus pot.
I always find it amusing when one of the broadsheets ask as one of their standard questions "Does money motivate you". I've yet to read a CEO reply that says "yes". So take them at their word !
Phil
Edit: One novel thing about this scheme - the CFO is not included.
Quarterly trading update at Record (LON:REC) seems rather lack lustre. The figures seem largely flat, but there is the warning that AUME will take a hit over the next year with two large clients leaving. There is an unusually high volume of trades going through this morning. Is the dividend here sustainable? If we are due a measure of market instability, this company should prosper.
Is the dividend here sustainable? If we are due a measure of market instability, this company should prosper.
The forecast annual dividend costs around £5m and at the end of the FY in March 2018 the company had £22.7m in cash even after returning £10m in a tender offer last year. So it doesn't seem there is an immediate threat to the dividend.
All the best, Si
Good morning Graham,
I hope you don't mind me mentioning it here but I'm running my Investor Sentiment research again this year and would like to invite your readers to join in. Post is here with the link to the survey
https://www.stockopedia.com/content/market-sentiment-research-october-2018-409914/
Cheers
Francis
Hi Francis - no problem at all! Thanks for sharing. G
My morning smallcap tweet: Yet another CYAN shareholder shakedown.
Cyanconnode Holdings (LON:CYAN), PCI- PAL (LON:PCIP), Webis Holding (LON:WEB), Akers Biosciences Inc (LON:AKR), Futura Medical (LON:FUM)
CyanConnode (CYAN) Yet another big discount placing. £5.1m for instos, £0.5m for hoipolloi. 18% disc at 10p, 99.8% below 2005's IPO.
PCI-PAL (PCIP) wins five-year contract from new Canadian client, worth an initial CAD$280k.
Webis Holdings (WEB) blow as a commercial dispute with US syndicate forces end of service. Guides reduction in gross margin for FY19 $0.8m.
Akers Biosciences (AKR) another skittle falls as interim Non-Executive Chairman scarpers.
Futura Medical (FUM) raised £5.6m via PrimaryBid at 27.5% discount. Open offer at 7p.