Small Cap Value Report (Fri 2 Aug 2019) - STAF, AIEA, GOAL

Good morning, it's Paul here.
Just so you know what today's timings are, I'm on the afternoon shift - so am writing between 11am- expected finish time c. 3:30pm. I've got nothing else on today, so no distractions thankfully. Well, just the market being open, which is a constant distraction of course.
Takeover activity
This is turning into something of a frenzy, with practically every day bringing news of another UK listed company receiving bid interest. I suspect there might be many more to come - because the weak pound makes UK assets attractive to overseas buyers. Takeovers provide us with lots of potential opportunities to make money, so I'm rather excited about this theme.
Also, some markets e.g. USA, look expensive right now, therefore in comparison UK shares look cheap. Therefore, buying in growth through relatively cheap takeovers of UK companies, looks a very sensible strategy for American companies. There's also the potential for a USA-UK trade deal post-Brexit, which could enhance the attractiveness of some UK companies to an American buyer. Language helps too.
Positioning ourselves in companies' shares which look well set up as a potential bid target can be lucrative if there's a decent bid premium. However, sometimes bids can be at a poor premium (e.g. recently Sanderson (LON:SND) only about 10%), or in financially distressed cases, at a discount - who can forget the Flybe bid at just 1p, when shares had been c.16p days beforehand?)
Although it's mostly luck, as nobody really knows which companies might receive bids. It's often very surprising which ones do! (Earthport & PTSG spring to mind). Sometimes bidders can see something good in a company which UK investors might think is not good. And/or, American buyers, particularly VC/PE seem happy to put gigantic, unfathomable, valuations on tech companies. That's fine by me, if they want to buy any of my holdings at greatly inflated prices.
Talking of potential takeover bids, Staffline (in which I hold a long position) has caught my eye this week, not for results, but as a possible takeover target. I wouldn't normally cover this kind of thing, but it looks a good opportunity in my view, and it will be interesting to hear what subscribers think, in the comments section below.
Staffline (LON:STAF)
Share price: 140p (down c.7% today, at 12:01)
No. shares: 68.9m
Market cap: £96.5m
(at the time of writing, I hold a long position in this share)
New Singapore shareholder - in case you hadn't spotted it, a potentially interesting situation is developing with Staffline (LON:STAF) . You might recall that the share price collapsed due to problems emerging with non-compliance re minimum wage regulations. Plus a general profit warning due to clients taking some staff in house, due to a tight labour market. An emergency fundraising was recently completed at just 100p.
Note that the former CEO, Andy Hogarth, had sold his stake in Jan 2018 at just over 10 times the share price of the recent refinancing, banking £10.3m. Very lucky timing it seems. Another example of why it's often best to sell up, if a key Director/founder dumps their entire stake. Problems often seem to emerge in the following year. Funny that.
I picked up some of these in the 100p placing recently, as the figures looked to me like a survivable financial crisis.
On 22 July, there were 3 successive "holding in company" announcements, showing that A Singapore company called HRnet Group had bought 7.39% of Staffline. A bit of googling showed that HRnet is a Singapore listed staffing company. I'm always interested when a buyer in the same sector (UK or overseas) crops up with a disclosable stake, as it can sometimes be a precursor to a takeover bid.
I've never looked at any Singapore companies before, so this was quite interesting to find out how to go about it. HRnet has an investor relations section on its website, and it all looks very similar to UK listed companies.
Purchases at 180p - this is a much more interesting announcement, on 31 July. HRnet itself put out this RNS, rather than it just being a "holding in company" RNS from the company itself (which came later). So clearly HRnet wanted the world to know that it had increased its stake to 25%. Bear in mind that the share price was 115p on the day that HRnet bought some large blocks of shares, paying 180p per share, a massive 56% premium.
There are 2 ways of looking at this;
1) Paying such a large premium suggests to me that HRnet is at least considering bidding for the whole thing, at 180p or more. That seems to be what usually happens in these situations, where a large premium is paid anyway.
2) This could be a blocking stake - i.e. 25%+ blocks anyone else from buying Staffline. Then HRnet can bide its time, and bid at a later date, or not, as it wishes.
Whatever the outcome, HRnet paying 180p certainly confirms that the shares are undervalued at 140p or less. Hence I've been happy to increase my position here.
Note that HRnet has also recently increased its stake in Gattaca (LON:GATC) to 5.53%.
Gattaca has a market cap of £43.1m last night (at 134p), and Staffline has a market cap of £96.5m. HRnet has a very strong balance sheet, last reported as having S$304.5m net cash as at 31 Mar 2019. That is c.£183m in sterling (1 Singapore dollar = 60 pence). Therefore, HRnet has enough cash on hand to buy both Gattaca and Staffline, if it wishes to.
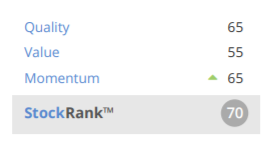
Stockopedia covers international shares too, in the premium subscription packages. Reviewing the StockReport for HRnet, it looks rather good as a potential investment. I'm struck by how high the operating profit margin is at 16.1%. It is also asset backed, with a PTBV of 2.06, with the bulk of the net assets being net cash. It pays a 4.3% dividend.
Here is the StockRank for HRnet (Singapore);
My opinion - I like Staffline shares at this level anyway. Having a potential bidder sniffing around, which has just paid 180p for a blocking stake, confirms to me that the shares look very good value. It doesn't make sense to me that the share price is languishing at 140p, so this looks a good opportunity to me.
Gattaca is probably worth a fresh look too.
I wouldn't normally be interested in this sector right now, due to macro uncertainty. However, when valuations reach bombed out levels, and overseas buyers are taking stakes, then it's worth looking at.
Airea (LON:AIEA)
Share price: 42p (down c.18% today, at 12:54)
No. shares: 41.4m
Market cap: £17.4m
The principal activity of the group is the manufacturing, marketing and distribution of commercial floor coverings.
Today's report covers the 6 months to 30 June 2019.
Unfortunately for shareholders, this seems to be a double dip on disappointing trading. I reported here on 28 June on its profit warning, which hit the share price badly, as you can see from the usual 2-year chart below;
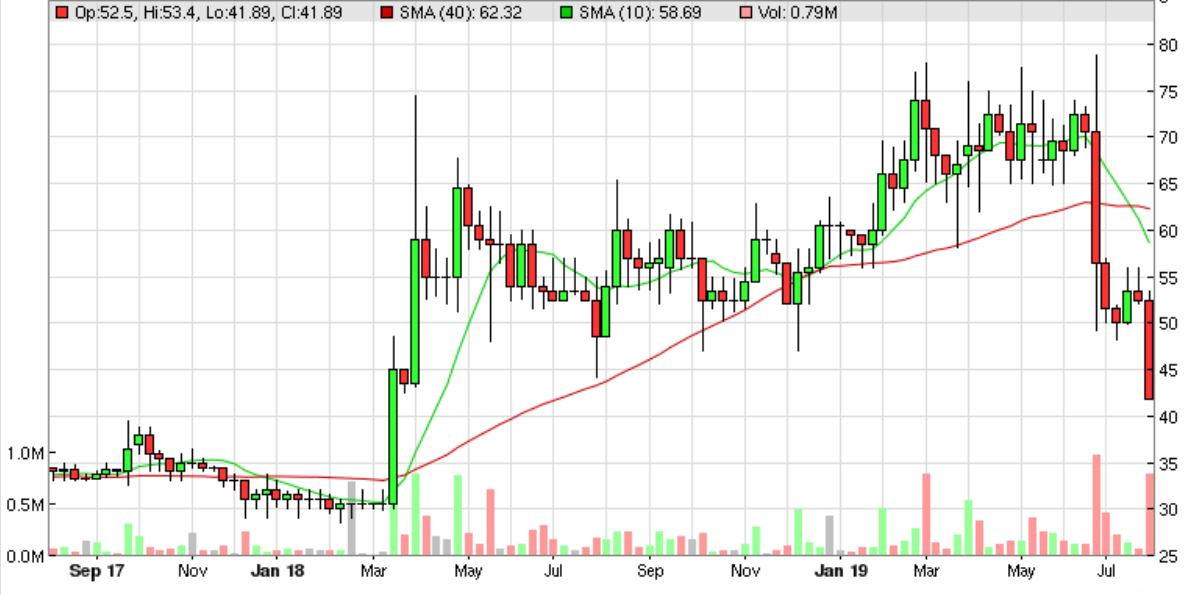
It's surprising how often this happens actually - i.e. a sharp fall on a profit warning, then a second sharp fall when the next set of figures come out. Sometimes these can be buying opportunities, when the price sells of excessively, but as we all know, falling knife catching can be very painful. Even though I should know better, I still find them irresistible sometimes.
This is what the company said on 28 June 2019;
- Very strong order book
- Good Q1, tougher Q2
- H1 revenue slightly down
- Lower operating profit (no indication of how much down)
As I commented at the time, this update was unclear, and with no broker research available, we were left somewhat in the dark.
That's the background covered, so let's have a look at the interim results & outlook.
Interim report - key points;
- Revenue down 2.7% to £8.89m - that's OK, as it ties in with the "slightly down" indicated previously
- Operating profit down 27% to £1.085m - that's a larger drop in profit than I was expecting
- Dividend (interim) cut from 1.75p last year, to 0.8p this year. That might have rattled some investors maybe? Although I note that the last final divi was also cut significantly, from 5p to 2p. I'm not very happy about this - shareholders seem to be paying the price for the decision to gear up to buy out the CEO's shareholding. The balance sheet would otherwise have been strong enough to maintain divis.
Outlook comments - are things improving? Not really by the sounds of it, which is hardly surprising in the current circumstances;
Although disappointed with the sales performance during the last six weeks of the first half we are pleased by the progress made during the period improving the foundations of the Group. Sales growth will continue to be challenging given the uncertainty that remains whilst awaiting the outcome of Brexit negotiations; however, as a UK manufacturer with a strong position in the UK and internationally and an ever increasing product portfolio, we are well placed to moderate these risks and take advantage of growth opportunities as they arise.
Airea should be a beneficiary of the weaker pound, as the value add element of its UK costs (i.e. selling price, less imported raw materials) become cheaper compared with international competitors, both in exports, and strengthening Airea's competitive positive vs imports.
If tariffs come in after 31 Oct 2019, then Airea would of course have to reduce its prices for exports (thus lower profits) to compensate, however would gain from increased market share (and/or profits) from its UK sales, as overseas competitors would themselves face tariffs on goods they bring into the UK. People often forget that tariffs work both ways, on imports and exports. It's anybody's guess how the net position would pan out.
Balance sheet - quick review;
- Investment property of £3.4m - nice to have - roughly offset by;
- Pension deficit (accounting basis) of £2.6m - this is quite material, as the company is paying in £400k p.a. in deficit recovery payments
- NAV: £13.7m - hardly any intangibles, so that's a solid balance sheet
- Big jump in receivables, from £2.87m a year earlier, to £4.6m at 30 June 2019 - needs looking into
- Inventories also quite high in absolute terms, at £7.36m, up a bit due to Brexit stockpiling (makes sense to me)
- Current ratio looks very healthy, at 3.25
- Net cash/(debt) position has deteriorated, due to adverse working capital movements. A new loan of £1,551k has appeared in non-current liabilities, and cash is down by about £1m a year earlier, to £1.4m. Overall it looks fine, but worth noting. The company is soundly financed, but I'd like to see working capital tightened up somewhat. Maybe they just have to keep a lot of items in stock, for customers to draw down? I know that is an issue with floor coverings businesses. Geoff Wilding of Victoria (LON:VCP) mentioned this, saying that he can often strip out a lot of working capital from acquired companies in this sector, which part-funds his acquisitions.
Cashflow statement - interestingly, the company also saw negative working capital movements in H1 last year, which reversed in H2. That reassures me that these could just be normal seasonal movements.
Note in the financing section, that a new loan of £1.7m was drawn down, in order to fund a £2.0m loan granted by the company to its own employee benefit trust. I seem to recall there was some investor unhappiness about this, as I believe the shares purchased were sold by the CEO, before the profit warning.
My opinion - these figures are a bit worse than I expected, so can understand why the share price has sold off again today. It's very illiquid, so price moves can be large, on little volume.
The divis are still quite attractive, when worked out on the lower share price. Although I'm not impressed with the company cutting divis quite so readily. Maybe it would have made more sense to sell the investment property, and maintain better dividends?
It's difficult to see any immediate upside on the share price, unless the company attracts bidding interest, which is possible. After all, European carpet makers (there are a lot in Belgium, I believe) might want a UK manufacturing base, to circumvent future tariffs?
If I held, I wouldn't be selling now that the price has fallen so much. It looks quite good value, if you think trading performance will improve in future. One for long-term shareholders, rather than speculators.
Goals Soccer Centres (LON:GOAL)
Update - looks like game over for shareholders, I'm afraid.
... it has become very recently evident that there has been improper behaviour within the Company.
Recently?!! It was obvious that someone was fiddling the figures.
Shares won't be relisted, so looks like it could be a 100% loss. Sorry for anyone who got caught out on this one.
Having said that, the recent trading performance noted today looks excellent. And the bank is bearing with them, so who knows, there could be a vague possibility that some shareholder value might be salvaged?
Discussions with the debt providers remain positive and they have confirmed to the Company that the existing debt facilities will remain in place post the initial 31 July 2019 review date, albeit that one of its covenant thresholds has been exceeded.
Year-to-date sales across the 45 sites in the UK on a gross like-for-like basis are up +11.5%. The Company's US gross like-for-like sales are up +14.5%.
I have to down tools for now.
Regards, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

36 comments
what are your thoughts on the STAF news today?
Thanks for the reply Phil, most helpful.
I see that the SVS website is still accessible, but obviously not the log-in part of it. Maybe somebody just forgot to take it down!
Not being able to panic sell with all the chaos that is going on at the moment my turn out to be a good thing, who knows, still rather have the choice though.
Like others I too have an account with SVS, and first realised that something was wrong yesterday when I tried to log-in to my account at lunchtime.
As has already been mentioned, what happens if a corporate action occurs, also are dividends still paid into our accounts, even though we cannot access them? If the mess is finally sorted out will we get our equities back or will they have been sold at some future date, and we only receive the cash?
We will have to wait I guess until Monday, when hopefully something will be announced. Hopefully retail investors will at least get back their cash/shares.
SVS is authorised by the FCA so compensation scheme will cover up to £85k.
https://register.fca.org.uk/ShPo_FirmDetailsPage?id=001b000000MfNZkAAN
Had experience with Beaufort Securities - dividends due were received, holdings were not touched so you got your shares and cash at administration date plus later dividends. There were no corporate actions covering my holdings so I don't know on that.
My BS account was an ISA and was transferred into another ISA so no consequenses there.
Phil
Thanks for the info re dividends & holdings, that sounds positive. And was also wondering about the ISA situation, so thanks for that info too!
Thanks from me too, Phil - v useful.
One question on the compensation scheme that I have is -as I hope! - its eligibility for execution-only investment actitivies. I've never heard anyone make a distinction when it's been discussed on forums etc, but digging further now the relevant page talk extensively about a firm having given 'advice' etc - see eg. https://claims.fscs.org.uk/PreScreening/EnterDetails.
On a separate note, I have direct messaged you, Acky, Hicks and Laurie on this generally. Please see your inbox.
I wonder if taking Paul's view of 'cheap' Companies if we could for fun build up a list of Ones to Watch from the perspective of their attractiveness for takeover purposes.
I know generally its a mug's game, but I wonder if there are generally some good investments which are languishing, and which may be vulnerable.
We can shoot them down, as improbable or probables, from Stocko readers viewpoint, and then have an ongoing screen of the collective filtered runners and riders.
Probably a silly idea?
Recognising it is only a mug's game and thus only worth thinking about re companies you already at least half believed in, I have 2 candidates (both of which I am in already):
LOOP - recent (60% in P3M) fall in excess of 20% EBITDA reduction announced with good hopes of recovery in 2020 as i) additional delayed sales pods come on stream and ii) adding video may return net churn to positive. US beachhead already established and hiring to accelerate there. Attractive SAAS model for $ rich tech buyers
CALL - similar to LOOP but already recovered recent fall. N et new user wins/mnth ahead of year end target by end of H1. US business growing and now cash positive and being accelerated. Either a trade buy or a PE deal opportunity
Hi Trident,
Definitely not a silly idea when there are collectively so many hours between us all put into researching different companies.
one recently flagged to me is Proactis PHD.
Lots of stakes being taken by large funds after a massive share price crash after a profit warning.
So what is going on at SVS Securities? Have they gone under or are they simply closing? (No condolences, please, I use many brokers and I am covered by FSCS in the event of a firm's bankruptcy, but I moved shares from Beaufort to SVS....)
Are there any other firms that are on the edge that people can tell me about? I have accounts with everyone, so I would really like to know.
Good question laurie. I just tried to log in to my SVS account this morning only to find the website simply no longer exists! On googling SVS Securities the first article that comes up is one from Value The Markets which reckons that according to 'multiple sources' as of yesterday morning it 'has been shut down', and that 'an Administrator has been appointed and a statement is expected on Monday'. Looks like will be an FSCS job, so sounds like a load of hassle and a big time delay in getting access to cash and shares? What happens if any corporate actions in the meantime? Not been in this situation before and it doesn't sound good...
Laurie
SVS Securities
Where did you get this news from?
All I know is I can't log into my SVS account.
Edit: OK - got it.
https://www.valuethemarkets.com/2019/08/02/svs-securities-another-broker-bites-the-dust-how-much-trouble-is-aim-in/
Re: GOAL it looks like the curse of Mike Ashley has struck again. His somewhat random commercial adventurism is beginning to make him look like a business Jonah.
I remember the early 2000's, when there was a huge disparity between value shares and the rest of the market. Although I didn't own many shares, I do recall that a lot of them were being bought out. One of them was Amstrad, which I had had bought only a few months earlier. It had a big cash pile which was a substantial part of its market value.
Although acquisitions tend to be pro-cyclical, sometimes companies can be actually be rational. At the time, there was deep value, and value shares performances subsequently produced gangbuster returns.
I don't think we're in the same circumstances as then, but Paul's comments seem on-the-money to me. It's a combination of relatively cheap stock market values and attractive exchange rates.
If I had to hazard a guess as to what would make a good takeover target: a company that wasn't too large, in a mundane industry, and have a low EV/EBITDA rating. Low ratings means that there's likely to be low debt, they're relatively cheap, and can be justified on the grounds of "value-enhancing". Banksters lap up all that kind of stuff, making them good candidates to pitch to their corporate clients.
Hi Paul,
I just draw folks attention to an RNS issued yesterday by Spectra Systems re their possible entry as a supplier of coated polymer for production of bank notes, using disruptive technology which I assume has been developed in house.
Hi folks,
Just so you're all aware, Paul's currently busying himself by digging up info on Singapore-based HRnetGroup for today's SCVR, following its acquisition of 11.7m shares in Staffline Group. He's on the case and will appear with his findings in due course!
Thanks Jack.
Hi Paul
Any thoughts on this regarding £SOS
Online fashion retailer Sosandar PLC said that Octopus Investments Nominees Ltd bought 11.12% stake in the company on Wednesday.
Octopus Investments Nominees owns 18.1 million shares in the company.
Sosandar shares closed 7.0% higher at 15.25 pence each.
Airea (LON:AIEA) I started looking at the Airea results and thinking why are they down so much, initially thinking the fall was too much based on the income statement results. I then saw the balance sheet to see a massive rise in trade receivables (debtors) which is not consistent with the movement in revenue. Also there is a notable move on creditors hence a big impact on the working capital of the business. Plus a new loan of £1.5m in non-current liabilities. If people know the reasons for all this with a good business explanation it would be good to know. They are flags for me which I'd want to understand further.
The EBT loan is in the receivables line ...needs to be disregarded
I’m a holder of Airea (LON:AIEA) so feeling bruised but I follow the company as closely as anyone & I’m categorically convinced that the CEO share sale was coincidental ...but I know many are adding 2+2 & getting 4...
I’m as cynical as anyone else but regard this as a temporary setback
The warehousing has a sub 2 yr payback as they utilise external warehousing capacity currently
The new ERP system is a deal they did as the vendor was suffering from a Brexit slowdown & offered terms that made it unarguable given the improvement in management information it offered
I think this is what has clobbered the shares today - I' reading this as the 2nd half continues to be challenging, so not surprised to see the fall.
That said, it is possible that the weal pound will assist them with the non-UK sales going forward.
Be interesting to see how it plays out.......
"Sales growth will continue to be challenging given the uncertainty that remains whilst awaiting the outcome of Brexit negotiations; however, as a UK manufacturer with a strong position in the UK and internationally and an ever increasing product portfolio, we are well placed to moderate these risks and take advantage of growth opportunities as they arise."
Please can you Pets at Home (LON:PETS) please Paul after their trading statement indicating FY profit slightly above expectations
AIEA.N Rylance sale of all his 2,150.630 shares to the Employee Benefit Trust @ 72p on 5th April 2019 was not picked up on the Directors Dealing Section on the Stockopedia profile.
Goals Soccer Centres (LON:GOAL) RNS issued today saying
"...evident that there has been improper behaviour within the Company. This has involved a number of individuals for a period since at least 2010"
This company has been covered several times by SCVR. Perhaps to most damning of which when Paul said "I think this is probably the end for shareholders here. " back in March. Full article here. However back then the shares were already suspended but you could have got out back a few days earlier after reading Pauls' comments here
As with most other UK frauds those responsible will probably get away with it, unlike our American counterparts where those responsible would most likely already be in prison before it got this bad.
Well, minimum should be that he's kicked out, feathered his own nest, ripped off the pensioners and cost the company A LOT of money. Maybe he would like to return some?!
And I see they're building more warehousing - probably to hold all that bloody inventory they're stockpiling because of Brexit...
And investing in systems - another classic. If Travis Perkins had to write off £100m recently on failed IT projects I don't give this lot much of a chance.
I should have learnt my lesson investing in these micro craps (no, that's not a typo). Liquidity so bad.
They should have taken the Halsted offer. Maybe they'll come back and get them on the cheap now...
Hi CISK
I’m not following your point...here the EBT is nothing to do with pensioners...the shares are held to satisfy options that will be issued to current key employees shortly..now they’re out of a close period
With respect the warehousing is replace external warehousing & has a sub 2 yr payback
The ERP system was 150-200k from memory & is designed to improve management information & enable leaner inventories post Brexit
I’m not sure you can blame Airea (LON:AIEA) for Brexit shambles either
Hi Rhomboid,
You’re correct it was a typo on my part, meant to say EBT but for some reason was thinking pensioners!
I admire your glass half full stance on Airea (LON:AIEA) - unfortunately for me there are too many red flags here and plenty of other opportunities around. I certainly don’t blame Airea for Brexit, it’s out of their control. But many companies blame brexit for their current woes...
And back in 2016 when the vote was made to narrowly leave the EU, unfortunately what has happened since was pretty much predictable and forecastable. And those that felt that what was an economy in pretty good shape would continue to be that way, with years of uncertainty, political ridiculousness and wasted billions not having much impact, unfortunately were mistaken. Anyway, enough brexit talk.
What really did it for me was the timing and cost of that share sale to the EBT. That, with other factors, has pretty much wrecked the finances of the company. And throw in a rejected bid from James Halstead - it makes the management at best look questionable and at worst downright rubbish.
If they so desperately needed shares for the EBT, surely a share purchase program, buying shares in the market over time, would have supported the share price and evened out the buying price, rather than buying them from the CEO? So now we’re in the situation where he got almost double the current price for his stock, the company actually borrowed money to do this, cashflow - and trading - has deteriorated and the share price is on the floor.
So I wish you luck with your continued holding - maybe Halstead will come back with a revised offer, but for me, I should have followed my gut and sold when the CEO sold!
A question to ask perhaps is what are the terms of option awards.
The EBT is arguably a hedge against option award requiring shares to be bought in the market at the time of exercise. The alternative would be to issue new shares, which is dilutive.
If there is an exercise price that option holders have to pay, that money goes into the EBT, and is there to repay all or part of the the loan made by the Company to buy the original shares.
The company may have to write off any element of the loan which represents a shortfall of the exercised shares compared to their original value. The auditors will probably detail this to this to the board annually.
Of course buying such a large tranche off a Director who remains CEO is fraught with conflicting interests, and should not be done, unless they are sold at absolute bargain basement prices or can be justified in terms other than the interests of the selling party.
I would take this generally as a barge pole indication
WINE goes naked, how good a price was the sale and what happens now? Interested in your thoughts, Paul
£AIEA Anyone would think the CEO saw this coming.......
Large director sales are always a sign to bail out in my opinion... especially if there is more than one. Sometimes they say it is for "tax planning purposes" but I do wonder sometimes
From the corresponding RNS :
"Our Chief Executive Officer, Neil Rylance, built up his personal shareholding in the Company a number of years ago and, as part of this sale to the EBT, intends to continue to lead the company in this next important phase of its development".
EBT = Airea Employee Benefit Trust and the name of the Non Executive Chairman is Martin Toogood.
jonesj,
Could you tell me please where did you get this information?
The last director dealing information I can see on Stocko is R.Salt a buy on 17/10/2016.
Also how did you do the graph and overlay?
Thank you,
Randval.
Randval
1 I got the directors dealing info off Shareview. On Stockopedia, the directors deal is included in the RNS but not the directors deal page. If actually intending to take a sizeable position I suspect it makes sense to check every RNS to ensure no significant information is missing.
2 The overlay graph is done by overlaying images with Excel and a photo editor (Irfan View).
Jonesjj,
Thanks for info.
I do have a few shares in Airea (LON:AIEA) but thankfully only a starter position, the smallest position in my portfolio even before today.
I will probably hang on for a bit just in case James Halstead (LON:JHD) are interested at this price.
Best wishes,
Randval.
My morning smallcap tweet: Majestic goes fully Naked, boot for GOAL.
Goals Soccer Centres (LON:GOAL), Majestic Wine (LON:WINE), IQGeo (LON:IQG), Autins (LON:AUTG), Pets at Home (LON:PETS), Lamprell (LON:LAM), Appscatter (LON:APPS), Airea (LON:AIEA), Augean (LON:AUG)
Goals Soccer Centres (GOAL) investigation finds "mproper behaviour [which] has involved a number of individuals for a period since at least 2010." Historic accounts can't be relied upon, 2018 audit work suspended. Will likely be booted off AIM end Sept. OTOH UK LFL up 12% & US 15%.
Majestic Wine (WINE) The announced disposal of original business has fetched £95m + £5m for property sale. Returning a paltry £3.8m (5.2p/sh) to holders. Will be fully Naked now.
IQGeo Group (IQG) £13m tender offer at 46p, a 5% premium. Returns a small part of £30m received on sale of RTLS SmartSpace.
Autins Group (AUTG) Placing at least £3.5m at 20p, a 30% discount, via bookbuild.
Pets at Home (PETS) string Q1. Guides FY underlying profit, before IFRS16 impacts, slightly above current market expectations of £85m.
Lamprell (LAM) order delays cuts FY guidance to $275-350m from $250-400m. The $275m is solid though.
appScatter (APPS) delayed FY hit by impact of the acquisition of Priori and proposed acquisition of Airpush, resulting in delaying SaaS subscription revenues. Rev about halved to £950k. Shares will remain suspended due to Airpush RTO.
Airea (AIEA) H1 rev down 3% as "high levels of market uncertainty within the economy resulted in tougher market conditions during the second quarter slowing the Group's financial performance."
Augean (AUG) The expected HMRC tax penalty is £4.6m. Will be issued end Aug and will be challenged.