Small Cap Value Report (Fri 2 August 2024) - WIZZ, JHD, VSVS, CPI

Good morning from Paul! It's an early start today, as I have to stop early for an investor lunch.
Explanatory notes -
A quick reminder that we don’t recommend any shares. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech, investment cos). Although if something is newsworthy and interesting, we'll try to comment on it. Please bear in mind the "list of companies reporting" is precisely that - it's not a to do list. We typically cover c.5 companies per day, with a particular emphasis on under/over expectations updates, and we follow the "most viewed" list of readers, so if you're collectively interested in a company, we'll try to cover it. Obviously with the resources available, we can't cover everything! Add you own comments if you see something interesting, and feel free to discuss anything shares-related in the comments.
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to, if they are using unthreaded viewing of comments.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. And/or it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Others: PINK = takeover approach, BLACK = profit warning, GREY = possible de-listing.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom), Video update of results so far, June 2024.
Frozen SCVR summary spreadsheet for calendar 2023.
New SCVR summary spreadsheet from July 2023 onwards.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Phil Hanson's data analysis measuring performance of our colour-coding system in the SCVRs, from July 2023- Mar 2024 (with live prices). My video explaining/reviewing it.
My other video (June 2024) - How to screen for broker upgrades on Stockopedia.
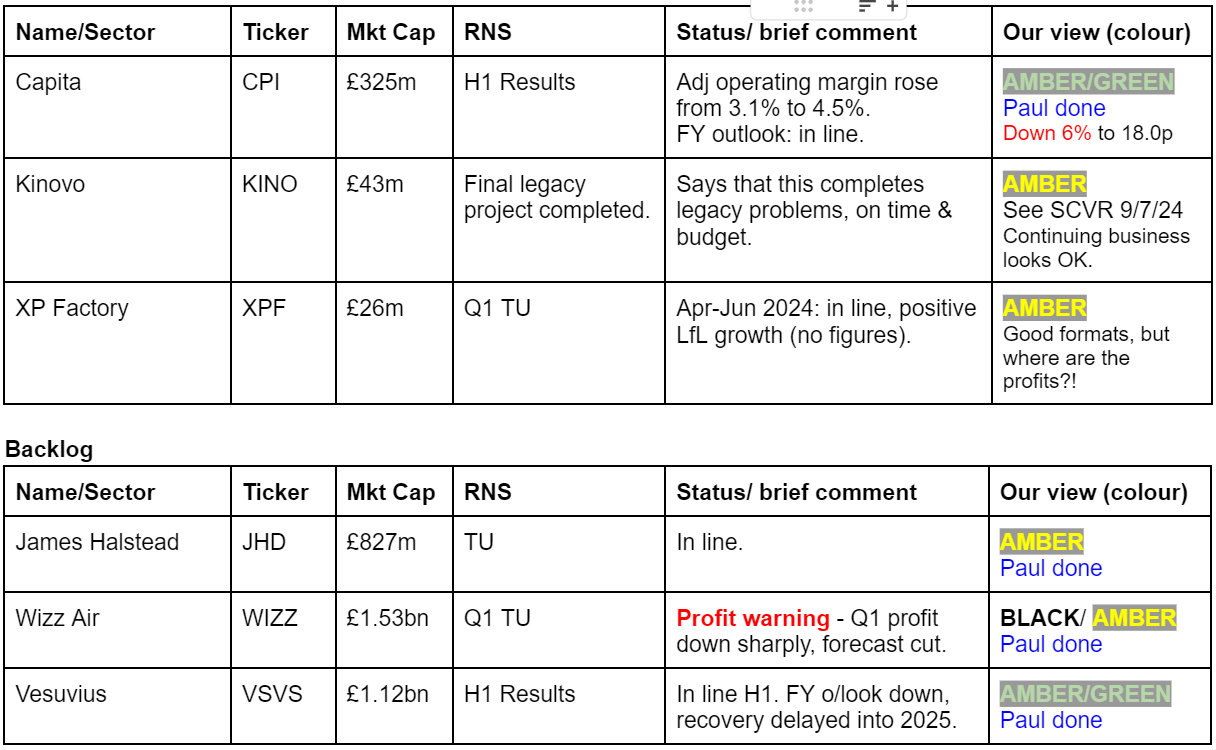
Companies Reporting
Summaries
Wizz Air Holdings (LON:WIZZ) - down 23% to 1,480p y’day (£1.53bn) - Q1 Update - Paul - AMBER
Took a 23% tumble yesterday on a disappointing Q1 update. With Ryanair, Wizz and Easyjet all coming under selling pressure lately, it's looking as if there might be an issue building with over-capacity with budget airlines. Especially with so many new planes on order. I'm avoiding WIZZ as unlike the other listed budget airlines, it doesn't have any balance sheet support, with negligible NTAV, so it's the riskiest pick in this increasingly difficult sector.
James Halstead (LON:JHD) - 191p (£827m) - Trading Update - Paul - AMBER
Reassured investors earlier this week with an in line trading update. It's a good quality business, making big profit margins, and with a strong (net cash) balance sheet. However, shares look pricey given the stagnant growth. To justify a 19x PER, I need to see growth accelerating. Decent divis, as it pays out almost all earnings to shareholders.
Vesuvius (LON:VSVS) - down 12% to 427p y’day (£1.12bn) - H1 Results - Paul - AMBER/GREEN
A sell-off yesterday was caused by wobbly outlook comments saying recovery is deferred into 2025. That said, the business is still highly profitable, and seems modestly valued. So this might be an interesting share for value investors to research further.
Capita (LON:CPI) - down 5% to 18.0p (£309m) - Half Year Results - Paul - AMBER/GREEN
Just a quick skim of these numbers, leaves me with the impression there's a reasonable turnaround underway here. Balance sheet is still weak, but the previously announced disposal should clear all bank debt. However it still relies on substantial up-front cash from the main public sector customers. Could be interesting, if further improvements are made to operating margins.
Paul’s Section:
Capita (LON:CPI) - down 5% to 18.0p (£309m) - Half Year Results - Paul - AMBER/GREEN
Time constraints this morning mean that I can’t properly get into the details today.
We already know the story here - extensive restructuring has been going on for years, to reduce debt and (hopefully) return the remaining businesses to healthier profit margins. That could produce impressive results, given that revenues are large, at c.£2.5bn pa.
The H1 results table shows things moving in the right direction I think, with an improved operating margin, and adj PBT (if you accept the adjustments) up nicely, but still only a modest amount -
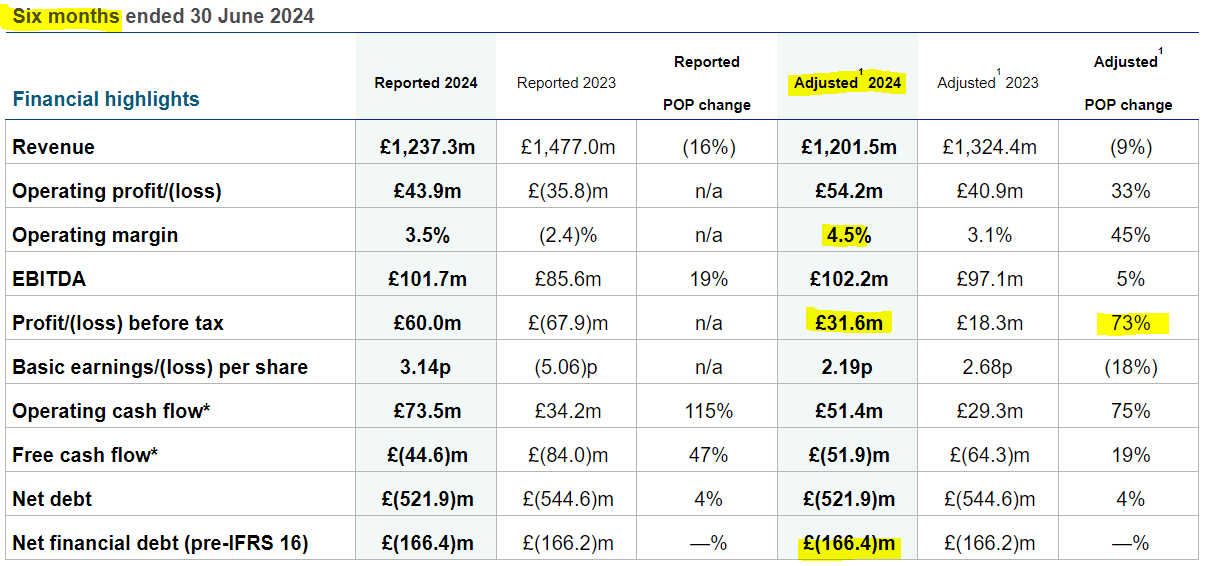
Note that net financial debt (excludes leases, which are large at CPI, it must have lots of expensive offices), unchanged at £166m has since been entirely cleared from a recent software company disposal. So it now effectively has no financial debt - although I imagine would continue dipping in & out of overdraft facilities depending on daily cash movements (payroll, payment runs, customer receipts, etc).
Graham and I seem to differ on this one, unusually. I’ve been amber/green since last autumn, going up to a full GREEN on recent news of the £200m software company disposal. Whereas Graham couldn’t be coaxed above amber when he last looked.
The newswire today says that shares are down 5% due to a lacklustre outlook. Or it could just be that today’s is a general down day, and it’s taken CPI down with it? Who knows!
I find these outlook points a bit too granular, and would have preferred a simple statement saying how they expect to perform vs market expectations -
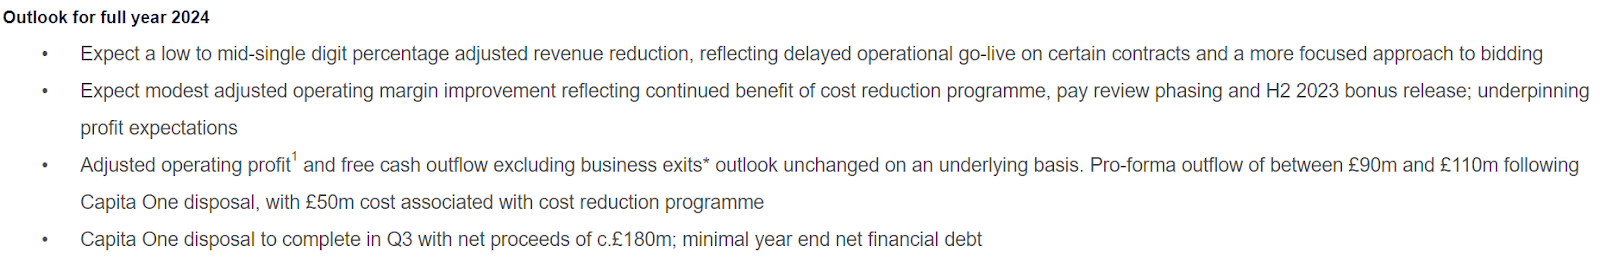
Although the third bullet point above sounds like the outlook is in line with expectations.
Balance sheet - is pretty horrible still. Taking off £520m intangible assets, takes it to negative NTAV of £(350)m. It’s not bust though, because the Govt pays up-front (see the whacking great £515m deferred income creditor. That’s the other side of the double entry for cash in the bank. So without generous up-front payment terms from the Govt, Capita would either be bust, or would need an additional £500m in bank debt.
Still, it gets money up-front, which is very nice. Investors need to hope and pray that doesn’t change!
Paul’s opinion - I’m leaning towards AMBER/GREEN today, as looking at the full numbers has reminded me that the balance sheet is still weak, and that its turnaround is still a work-in-progress.
Although, providing nothing significant goes wrong, there could be an opportunity here for investors.
Vesuvius (LON:VSVS)
Down 12% to 427p y’day (£1.12bn) - H1 Results - Paul - AMBER/GREEN
Vesuvius plc, a global leader in molten metal flow engineering and technology, announces its unaudited results for the six months ended 30 June 2024.
The company reckons H1 was in line with expectations -
Resilient results in line with expectations, despite subdued market conditions
Surprising to see the shares down 12% then, clearly something has displeased the market.
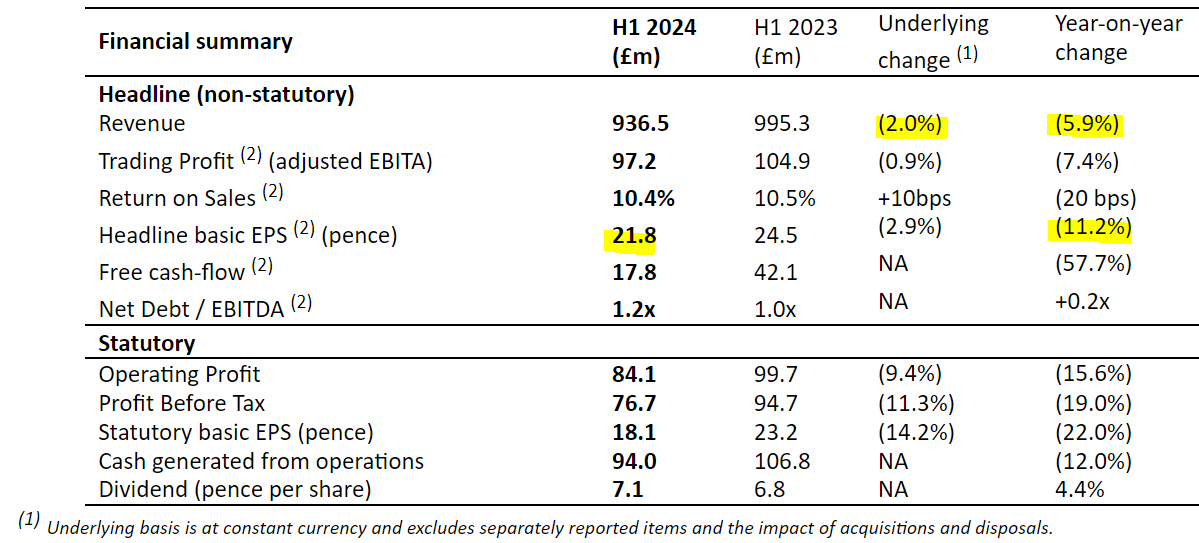
H1 profit down a bit on last year, depending on which measure you use. Adjustments are not huge, and an operating margin just over 10% is pretty decent -
Outlook - I’ve just found the wobbly bit -
“We no longer expect a significant improvement in our end markets in the second half, with most external forecasts predicting end market recovery being postponed to 2025. Accordingly, we now expect our full year headline trading profit for the year to be only slightly ahead of last year on a constant currency basis(*).
(*) FY23 trading profit was £200m reported and is £192m retranslated at H1 2024 FX rates.
Balance sheet - quite capital-intensive, as I would expect from a steel/foundry-type business. NAV is £1,267m, which includes £693m intangible assets. So NTAV of £574m. That’s mostly made up of £464m fixed assets. Working capital is hefty, requiring some debt to finance it, doesn’t look excessive. Pensions are shown, so that would need scrutiny. Also note the minority interests line, so not all operations are 100% owned by VSVS.
Overall it looks OK, nothing to worry about.
Cashflow - I’m not so keen on this. Post tax cash generation in H1 was £69m, but this was mostly spent on £51m capex.
Then it spent £73m on divis & buybacks, fuelled by increasing debt by £100m. This raises the question over whether its generous 5.8% yield is sustainable?
There’s also a hefty £17.1m spent buying shares for the ESOP.
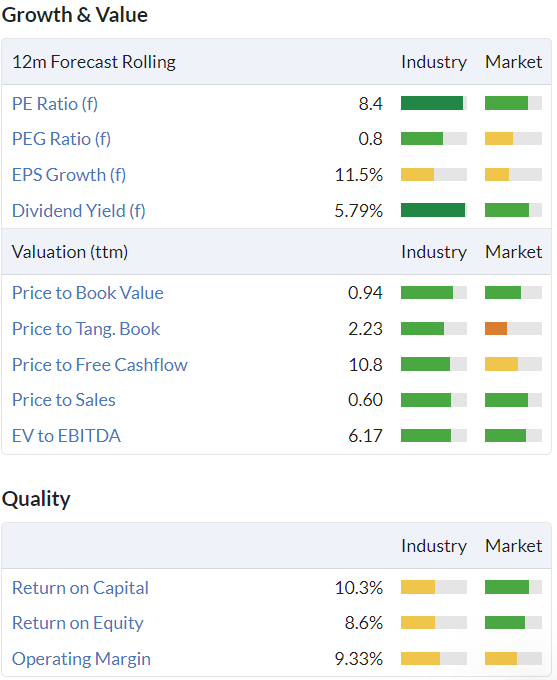
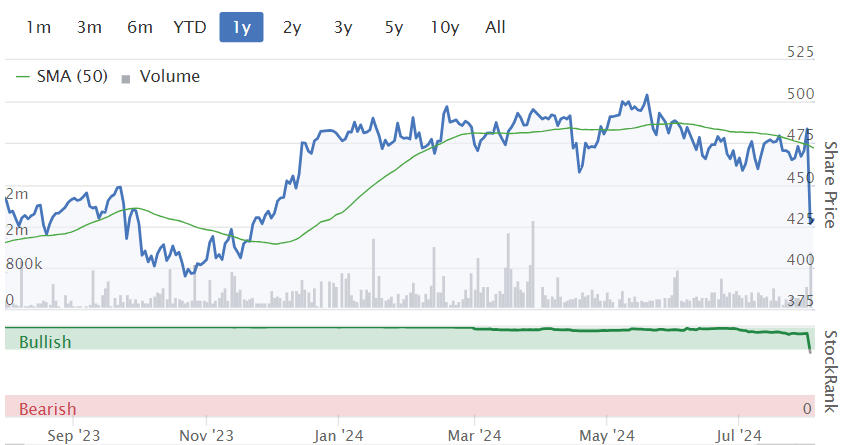
Paul’s opinion - the StockReport shows attractive value metrics, so this might be one for value investors to follow up on with your own more detailed research. It’s quite a lot of business for the money, but not a sector I know anything about, so am not sure I can add any value here really. After peaking in 2018, shares look to be in a long-term downtrend now. I wonder if it might attract a takeover bid given the modest PER?
Wizz Air Holdings (LON:WIZZ)
Down 23% to 1,480p y’day (£1.53bn) - Q1 Update - Paul - AMBER
This budget airline has halved in share price since the recent May 2023 high, and is now back down to a similar range when it first floated in 2015-17. Threat or opportunity? I’ve got to have a quick look.
Similarly, Ryanair shares have taken a big drop recently, from 21E down to 14.6E, Easyjet has not been great of late. Thankfully my sector pick, JET2 seems resilient, after good results which we briefly reviewed here on 11/7/2024. I do feel JET2 is well differentiated, focusing on not just flights but also package holidays, excellent customer service, which was reflected in a recent survey. Whilst WIZZ and Ryanair in particular have recently scored poorly in customer surveys. Or are we just waiting to be hit with a profit warning from JET2, given that it declined to give detailed guidance for the key summer period? Only time will tell, my crystal ball is in for servicing I’m afraid.
Focusing on WIZZ, its problems began in mid-June -
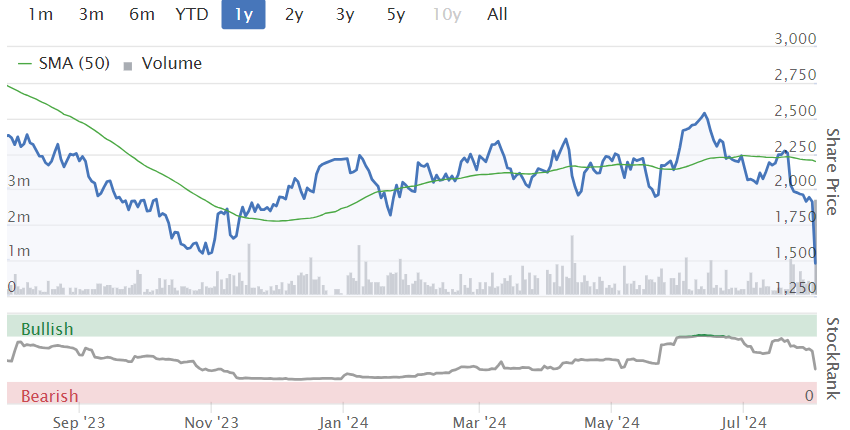
Stockopedia is showing WIZZ on a forward PER of just 4.3x, which looks odd. Bargain, or a sitting duck for further downgrades?
The newswire says that yesterday WIZZ reported that Q1 profit slumped 44%, and forecast was cut.
Q1 Update - covering Apr-Jun 2024, within FY 3/2025.
Accounts are in Euros.
Problem with 47 aircraft being grounded over engine inspections.
Q1 trading was poor, with a statutory loss of E(4.5)m before tax, vs E67.1m last year, on E1.26bn revenues.
Balance sheet - has negligible net assets, and far too much debt, so that rules out this share for me.
Paul’s view - not of interest due to the weak balance sheet. Whereas JET2, EZJ & RYA all have much more balance sheet support, through decent tangible assets. WIZZ is by far the weakest of the 4 listed budget airlines in terms of its balance sheet. If I’m going to invest in a difficult, unpredictable sector like this, then I’d always go for the rock solid balance sheets first.
There seems to be a lot of new capacity in the pipeline, with large order books of new planes, combined with worries in some countries about over-tourism. Which makes me wonder if we might be heading into a glut of budget airlines & holidays, and increasing pushback from the countries being inundated with tourists? So on balance maybe this whole sector is best avoided?
EDIT: WIZZ issues another update today, giving July 2024 traffic stats, and CO2 emissions.
James Halstead (LON:JHD)
191p (£827m) - Trading Update - Paul - AMBER
Readers asked me to circle back to this update from Weds this week.
This specialist commercial flooring company was an impressive share performer until about 2015, but for the last 9 years it’s traded in a range roughly from 200-300p. Although shareholders have received a good flow of divis, so the total shareholder return has been better than the share price alone suggests.
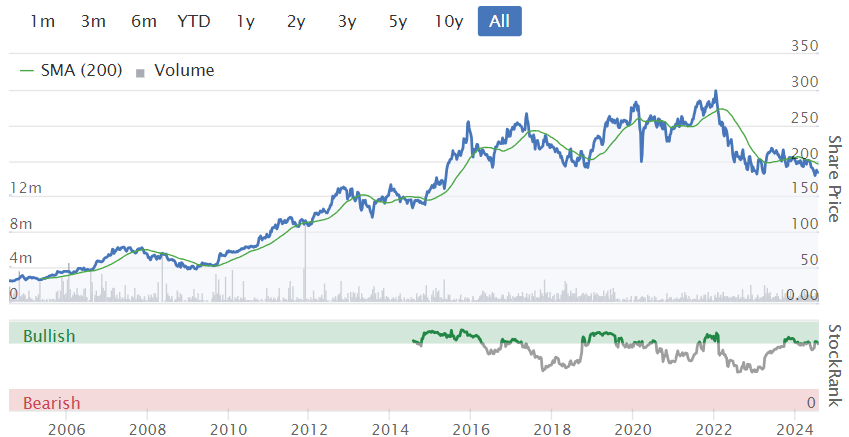
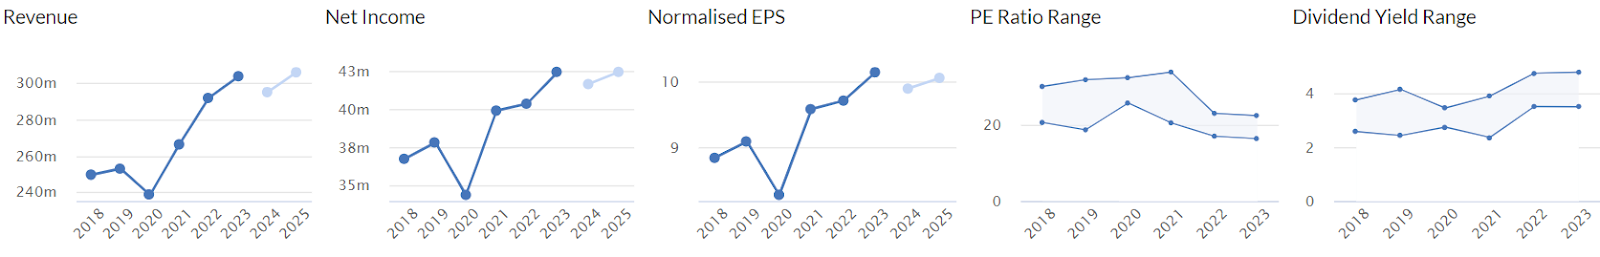
I’ve never really understood why the stock market has generally applied a premium rating to this company, with it frequently trading with a PER of 20x or more. That doesn’t seem justified based on recent years’ performance, with little profit growth since 2021. So we need to see an acceleration of profit growth here, or this share could end up de-rating further (it’s hardly cheap now , on a fwd PER of 19.0x) -
“James Halstead plc, the commercial flooring manufacturer and international distributor, is providing the following trading update ahead of its results for the year ended 30 June 2024.”
Overall - it’s in line, so reassuring rather than spectacular -
“In summary, profit before tax will be at record levels and in line with (upwardly revised) market expectations. “
Expects to improve on last year’s results, for profit, cash, and dividends.
Regions mixed - M.East & Americas good, UK & Europe weaker.
Margins “bolstered” by product mix, cost control, and efficiency.
Costs - lower raw materials prices (but still 50% above 2020 levels), but electricity remains expensive.
Red Sea disruption has caused delays, costs, and increased inventories.
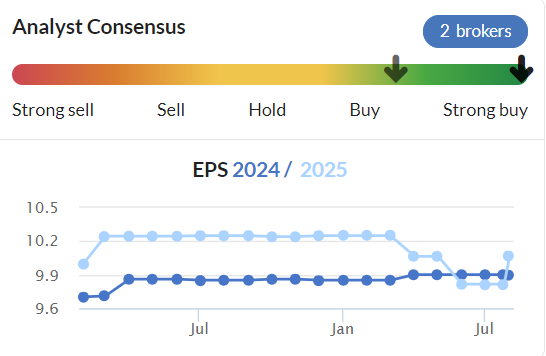
Broker consensus - only shows a very slight increase in FY 6/2024 forecasts back in April 2024 - so nothing to get excited about here either -
Balance sheet - nothing said in this update, but I’ve checked back and it’s smashing, very conservatively financed, with net cash - which we often find at family-run businesses. About £166m NTAV at 31/12/2023, including £62m net cash. Thumbs up here!
Paul’s opinion - this is undoubtedly a decent quality business, evidenced by strong profit margins. But where’s the growth? Brokers are forecasting very little, and with EPS seemingly stuck at around 10p, that means I’m being asked to pay 19x for what looks like an ex-growth business.
So I think to be bullish on this, there needs to be a clearer route towards better profit growth. I can only go on the existing broker forecasts, it’s your job to analyse whether you think these are likely to be beaten or not, through deeper research into products, competition, etc.
Overall, I think it’s a good business, but looks priced about right, based on the information available today.
So it has to be AMBER.
Obviously if business improves, and broker forecasts start rising, then we’d be happy to move up.
This is a nice quality business, for sure. Strong profit margins, strong balance sheet, good reliable divis, so I can see why some people like the company. I just don’t think the share price is attractive given the apparent lack of growth. Could that change as better macro conditions emerge? Quite possibly, we’ll have to wait and see. Big profit margins worry me in a way, as that attracts competition, so I’d be interested to know what other companies supply similar products around the world.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

111 comments
What a coincidence!
Announced in the morning that Buffett sold around $80 Billion worth of stock taking his Berkshire cash balance to $280B. They own now more T-Bills than the FED has on its balance sheet!
All the best
tbf he also sold a fair chunk of Apple stock before a big rise and didn't he buy into Diageo too, so he doesn't always get it right...
update in your opinion on GDR
National World (LON:NWOR)
Paul I thought it was a good example of what averaging down can do and why so many clever traders always warn about avoiding averageing down.
I must remember not to mention prices paid. Sorry I must do better.
Not to worry portugull, if you don't include figures you could be accused of being a journalist.
You have nothing to apologise for IMO.
A choppy end to the week - it's only the 2nd day of August so we could be in for some action over August and September - markets have a tendency to move when you aren't expecting it over the summer. It's all about the US and whether the AI bubble is bursting, caused by a possible US recession as we move into 2025.
Yiannos1 - 75% cash is very bearish. Only 32% myself. I'm still wary of the 25 month inverted yield curve. Its testing my patience, that's for sure!
Hi topvest
My concern is that we are now in a deflationary environment. As an accountant (from your posts I imagine you are) you know very well that all estimates regarding companies earnings for 2025 and 2026 were based on higher revenues but most importantly on higher margins! All these estimates will be missed and this is the reason I am 3/4 cash.
The inverted curve has already started to normalise and has ALWAYS been very bearish for stocks-also the true picture of the US economy will only be clearer after the US elections and further in 2025.
BUT
No doubt the market will recover and go higher when interest rates stabilise but till then………….
All the best
I've found it odd over the last few months that the average forecast EPS growth in the UK indexes are so high, and keep being increased.
FTSE100 is showing as 10.5% EPS growth forecast. FTSE250 is a gobsmacking 14.3%. You would think we're a fast developing emerging market. And AIM100, as usual with all the blue sky, is a ludicrous 21.4% EPS Growth forecast.
(All found easily by looking at the home screen of Stockopedia, for anyone else interested).
Something has to give; either the brokers are right and the economy is in MUCH better shape than anything thought, and there's a combination of healthy sales volume growth as well as margin growth...
OR all those forecasts are way too optimistic, they get slashed massively, and we see some serious correction in share prices.
I'm personally c20% cash at the moment (more details in my latest monthly Boon Fund post on Substack). It has hurt me over the past few months, given the rising market.
However, if I add up "defensive" companies that I hold (ones that should see minimal impact in a recession), that's another 33% of my portfolio, so I'm probably close to 50% total in some sort of protection against a market correction.
Very surprised to see quite a few intelligent investors trying to play the cash vs invested game. We all know that markets go up over time and more importantly, there are compelling statistics that tell you that being out of the market at key upward moments is very damaging to long-term returns. Good luck trying to time your reinvestment but I am staying fully invested.
P.s. if you don't believe me just think back to covid. The market sold off too quickly to get out before the fall and then rallied remarkably when most commentators were still very bearish.
I think it’s a downward moment though!(after the US elections)
The fear of missing out is the worst enemy and the downfall of all investors.
There is nothing better than having cash in your portfolio and doing some useful research for the next multibaggers.
Good luck
Very surprised to see quite a few intelligent investors trying to play the cash vs invested game. We all know that markets go up over time and more importantly, there are compelling statistics that tell you that being out of the market at key upward moments is very damaging to long-term returns. Good luck trying to time your reinvestment but I am staying fully invested.
You need to remember that everyone here is on a different investment journey, is at a different point in that journey, and hence necessarily will have their own tolerance to risk. Some may still be working, others may be retired and living off their investments. Some may say they are 100% invested and yet they have substantial income form a buy to-let portfolio or some other source of income. We just don’t know. And that’s why I just ignore any comments posters make about their portfolio. It tells me nothing in the same way posters mentioning the price of their trades is just irrelevant noise.
This blog is excellent for discussions of individual companies and their valuations, but anything beyond that does not add value, and I include macro economic discussions in that - no-one knows the future and making predictions about that stuff is a quick way to make yourself look an idiot. As such, I totally understand Paul’s frustration, and if I he wants to let off steam every now and again then it doesn’t bother me.
All the best, Si
No one can dictate to others what to write here ; especially if it comes from employees of stockopedia. If you don’t like something move on-if you disagree state your case-say your opinion.
From my early years I have learnt FIRST to value bonds whether issued by governments or companies. I have stated here about Saga (LON:SAGA) when 300p and Petrofac (LON:PFC) when 80p that their bond pricing meant that the companies were in distress mode-and many many other companies.
I am sharing here that the US 30 day federal funds futures for 2024 and 2025 were showing clearly on Friday afternoon that the US will be in recession or that growth will be minimal. If I am wrong then I will adjust my portfolio accordingly. Not exactly idiots (as you have chosen to post) but perhaps investors that are not experienced enough are the ones that do not pay attention to all these signals.
All the best
No one can dictate to others what to write here ; especially if it comes from employees of stockopedia. If you don’t like something move on-if you disagree state your case-say your opinion.
Who’s dictating anything? You should re-read my post with maybe less of an aggressive stance. People can write what they want, I can ignore what I want. I read this blog every day and ignore 90% of comments because they are not relevant to me. I imagine others do the same. Nothing controversial in that. If you think you’re adding anything by discussing macro then fire away. Total waste of time and effort IMO. Unless you’re the one in a million person who has called interest rates right…
You think one in a million call interest rates right? But the futures in the US say where interest rates are going. Is that so difficult to understand? It’s a 100% rate cut in September and 100% another 2 before Christmas. You can visit the CME Group website and see everything.
As for the dictating you can read my post again as well and perhaps stop using these words : aggressive stance-they create a hostile atmosphere and start arguments. You disagree with me fair enough-I accept it-I accept as well that you do not follow the US bond market-I disagree 100% with you as well regarding macros and investing-no issues-move on.
You are defending Paul-my opinion is that he has no right to say who writes what and when. To be honest I do not understand how the management accepts this. If Portugull wants to write and explain his journey regarding National World (LON:NWOR) then he is allowed to do it without anyone interfering. He only tried to say that basically average down is nonsense!
PS-I read all the comments and every single word in them-they are all relevant to me whether I agree or not.
You are defending Paul-my opinion is that he has no right to say who writes what and when. To be honest I do not understand how the management accepts this.
It’s very simple. Without Paul’s input, this place does not exist and those like me that have inhabited the same part of the internet as him for nearly 25 years stop subscribing. I ‘m sure Stockopefia understand that. I have never met Paul but have had sufficient interchanges with him to appreciate he is fundamentally honest. I have never seen a better analyst of small cap companies and he is clearly fully invested in this blog on a daily basis. I don’t know how he does it. No-one is perfect, but unlike you given how much he invests in his own time each day, IMO he has every right to ask posters in this comment section to smarten up their act.
No doubt about Paul’s ability but this is not my issue so I will leave this conversation as you are coming back with different things that have nothing to do with my original post and perhaps implying things that have not been said.
Again no doubt about Paul’s ability to analyse small caps so I make myself VERY clear. On very rare occasions I have disagreed with some of his analysis but 99% I find them correct and 100% HONEST.
You need to wind your neck in Yiannos. Your posts are undoubtedly aggressive, as Simoan says and as suggested by the number of times Stockopedia has had to 'moderate ' them.
Following the US bond market doesn't automatically make you an investment guru with more important opinions than the rest of us, so a bit of humility wouldn't go amiss either.
Politeness and courtesy are two of the things that separate Stockopedia from a lot of other low quality bulletin boards. Let's try and keep it that way and then we can all benefit from what contributors have to say.
My posts have no aggressiveness in them. It’s just personal opinions based on facts and experience. You say you are invested 100% now so I think it’s better to explain to us the reasons you are fully invested. Where is the growth coming from? Which companies do you think and why they will keep on growing? Are you not worried with what is all these trouble in so many high streets at the moment? Please give some numbers with your reasoning.
I have in many occasions given here companies that have outperformed the market by far.
Finseta (LON:FIN)
McBride (LON:MCB)
IG Design (LON:IGR)
Gulf Keystone Petroleum (LON:GKP)
Billington Holdings (LON:BILN)
And many many others.
So instead of trying to teach others manners I believe it’s more beneficial to the board to explain your reasoning behind the fully investment case.
I am very much interested to read them.
Personally I hold 4 UK listed small caps in the UK and I have explained in detail why I have invested in them.
All the best
My posts have no aggressiveness in them. It’s just personal opinions based on facts and experience. You say you are invested 100% now so I think it’s better to explain to us the reasons you are fully invested. Where is the growth coming from? Which companies do you think and why they will keep on growing? Are you not worried with what is all these trouble in so many high streets at the moment? Please give some numbers with your reasoning.
Can you not see that your first sentence is completely at odds with those that follow? Why should anyone need to explain why they are fully invested here? As I explained in my first post, what even does “fully invested” mean? Everyone will have their own definition and without knowing someone’s entire financial picture what is the point? For instance, I’d be fully invested if I was still working but I’m not, so my risk tolerance has been reduced and I’m happy to hold more cash. The one thing I know for sure is that no-one here knows the future, including you. The worst thing for an investor is the illusion of knowledge about the future. We have to accept that the future is unknowable and invest on that basis.
No one knows the future correct. I definitely don’t know the future but I try to predict it using methods that I believe give me more chances to be correct than being wrong. Following the bond market is not an illusion. Illusion is not to respect the bond market.
But to make money in this game we all basically try to predict the future. My predictions is that the US will be in a recession in 2025 and that will affect global markets. This is the reason I am 75% cash now and doing my homework for the upcoming investment opportunities. Will I be right? I don’t know
I believe that whether you work or not has nothing to do with the investment approach you take.
I don’t work as well (I don’t work for anyone perhaps is the right phrase) ; I have different sources of income BUT I am not fully invested at the moment.
We all have different investment approaches and that’s why our portfolio are different. No need to get annoyed if someone is 75% cash or fully invested. I will certainly be happier if I am wrong and the market moves higher. I don’t like to see people losing their hard earned money. I will adjust my investments appropriately.
I don't find yiannos's posts aggressive. 'wind your neck in' is though
I believe that whether you work or not has nothing to do with the investment approach you take. I don’t work as well (I don’t work for anyone perhaps is the right phrase) ; I have different sources of income BUT I am not fully invested at the moment.
Sorry, I should’ve been clearer. I’m retired and if you live from your investments and have no other sources of income your investment approach and attitude to risk necessarily has to change. It’s idiotic to accept the same risk as when you are younger and have the comfort of a regular monthly income from a stable and secure professional job.
We all have different investment approaches and that’s why our portfolio are different. No need to get annoyed if someone is 75% cash or fully invested. I will certainly be happier if I am wrong and the market moves higher. I don’t like to see people losing their hard earned money. I will adjust my investments appropriately.
I’m not angry, my point is: 75% of what? Investment accounts only or total net worth? If investment accounts only, and I say I’m fully invested, is it OK to be 100% government bonds and gold? Or is the percentage you quote related to an equity only portfolio? I hope you can see the point I am trying to make. Everyone will have a different idea of what constitutes their portfolio and it will be a different percentage of their net worth which will predicate the approach they take.
It’s idiotic to accept the same risk as when you are younger and have the comfort of a regular monthly income from a stable and secure professional job.
Then I’m an idiot.
What a surprise? Seems I'm an idiot as well.
cheers
With respect you can't be - I am Spartacus!
Hi Yiannos1. Like you, I follow the signals from the bond and futures market. I do however think you would do well to temper your confidence in the predictive power of those markets. At the start of this year, five cuts were expected. By June, possibly only 1. Now we are in the middle of that range, and I tend to agree that 3 cuts are coming before new year. But the market has got it wrong all year long. Can we be so sure it is correct today?
Hi BnB
You know very well obviously from your experience that these markets predict ‘Today’ for ‘Tomorrow’.
On Friday these were the predictions that the rates by year end will be 4.25% meaning at least 1% rate cut. Remember that it is August now and we are getting closer to year end and this is exactly what JP and the other members are looking at to decide their rate moves.
All the best
And now the usual evening abuse begins.
How on earth the management of stockopedia can accept this I have no clue.
Chill. You are right. US debt is unsustainable its just 'when'. There is limited political will to deal with any 'hard' subjects - from any governments on both sides of the pond.
Meanwhile the Green King earns income from offshore green windfarms (made in China and limited recyclability and huge maintenance cost helicopters, subs etc) and Scotland chops down trees to er 'go green'. Anyway I like a bacon sandwich.
But when America coughs we go into 'covid' and so will most of the world.
But lets be positive 'Avon Protection' is now 'Avon Technologies' - just supply top drawer helmets as demand - simple. Anyway I still see 'lipstick' less tyres.
Even gold got whacked today so yes - lets shut down the screens and more DYOR in 'interesting times'.
See Raspberry PI Holdings (LON:RPI) is doing a ST.
On a day like today it is interesting to see which stocks buck the trend of collapse. In my portfolio I was surprised to see that Brave Bison (LON:BBSN) was up for a second day on a full volume of trading. I like the stock but I cannot see any obvious reason for a 2.1% rise. This is not an amount that would raise an eyebrow normally, but it is a standout amongst the wreckage .
This is the same portfolio that on Tuesday took me to an all time high. Yesterday it was down 2.4%, and today it's down an additional 2.6%.
No meaningful company news but collectively worth 5% less according to Mr Market. I wanted to post this as I know many others will have had a bad few days. Remember this is just macro noise. Trust your investments and don't make the mistake of selling good shares on the cheap into poor liquidity on no company specific news.
Let's all hope the rest of August goes a little better!
Well what a pleasant 36 hours to end the week………..
Often seems to happen in August - zero liquidity so any macro negatives send shares into an absolute tailspin.
I guess a number of bargains cropping up again.
Indeed, lots of buy trigger prices sending email notifications today for me.
But I am also one that has contributed the the negative liquidity, "enjoying the Friday sun" and will be off traveling for a while, so even though I think I should be hunkering down at my desk and figuring out if I should buy, I will be out of the markets for a few days at least!
Very true David up to I think it was Thurs lunchtime I was sitting there feeling very smug as my portfolio had been steaming up in recent weeks, came back from an hours walk and the market had well and truly given me a dig in the chops.
Thank you planetx for your comment this morning on National World (LON:NWOR) which I hold.
I so agree with your views. I wrote to Investor Relations at National World (LON:NWOR) earlier this year about their use of EBITDA but did not receive a reply.
I first bought in Sept 2021 at 40p and added in Feb 2022 at 28p and added again in May 2022 at 21p. Currently down 40%. A small position at 2.4% of my portfolio so just feel I need to be patient. Richard Leonard was keen in December 2021 as he felt the Company was a consolidator in a declining industry.
Thanks portugull.
I was dying to know what prices you had bought and sold at. (said nobody)
Come on now paul, I feel someone needs to pipe up and let you know that you are out of order here
Portugal was thanking planetx and talking his own book, nothing wrong with that
He's not ramping or offending anyone so you could have easily scrolled on
Carry on like this and your going to drive members new and old away from this community
Sorry to say this as although I don't personally know you I actually like you and listen to your podcast etc and follow and respect your views on here I hope Ed reads this, as comments like yours which I'm highlighting needs to be stopped
I disagree, Callum. If everyone on this forum was to talk about their buying and selling prices it would soon become clogged up with uninteresting waffle rather than the useful insights that our knowledgeable readers currently produce. I am happy that Paul reminds subscribers of this now and again.
Portugull has been a paying subscriber here since 2013, and in no uncertain terms does he deserve snide comments arising from his post
He has declared his buy prices as part of a wider post in relation to a company being discussed by the community
There is far more irrelevant posts on a daily basis on this thread
As paying subscribers we should feel comfortable to post on here without ridicule and I'm sure paul and stocko management would agree
Our discussion is also cluttering the board so I am happy to agree to disagree and move on
Hope you have a lovely weekend and let's cross our fingers the market is in a better mood next week after the last few weeks
Last line should read last few days, bloody phones!
Callum I couldn’t agree more!
Actually I like Portugull comments and always read them. I think it’s the average down that bothered some people!
Everyone should be allowed to post here without any interruptions from others. If you don’t like anything then scroll on-move on.
Personally I like to read investors experiences.
All the best
Really??? Have you always treated your loyal paying customers this way?
Paul, the tone of your message to Portugull was in my opinion inappropriate. If you wish people not to contribute details of individual trades can you not do so in a more respectful tone befitting the high regard you're held in, and professionally demonstrating that you are representing Stockopedia? I know you personally are sometimes, quite understandably, upset or offended by comments in the SCVR but all the more reason you rise above the fray.
Hi Portugull, you certainly know how to write a post that produces a reaction! I've had my head down after Friday's market and only now surfacing and reading the SCVR on Sunday afternoon.
While I'm not personally keen to read about individual commentators trades I respect your right to publish them and they were in context as highlighted by Callum, and on another day (had the community been feeling a little less fraught), they might have led to a useful discussion about averaging down as noted by Yiannos. I do think Paul was within his rights to request trades are not highlighted, but ultimately that's up to you and I see a lot less useful commentary here. Any comment relevant to small cap investing should be welcome if respectful and well meaning, and you did not deserve Paul's sarcastic and unhelpful reply. It's enough to make one wish Stockopedia had not withdrawn the thumbs down voting option. I'm sure it makes less confident investors wary of commenting. You certainly did not need to post your later apology.
I'd be much more interested in knowing what prompted you to buy more of National World (LON:NWOR) as the price fell, and what you've learned with hindsight? I'm sure there are advocates of averaging down, and others for whom it borders on recklessness. Yiannos highlighted your buying history with this share so I imagine could articulate his approach way better than I can. I know another respected and frequent commentator, Wolf on Small Street highlighted as recently as this week that he never averages down. It rarely works in my view, distorts one's portfolio and in layman's speak is throwing good money after bad.
I hope this reply is more positive and supportive. Best wishes.
Wise words there TEIN
Averaging down rarely works and I never use it. This has been explained to me in detail from my early days in the business that the success rate is very low indeed. The risk/reward is against the investor in these tactics. It does work sometimes but overall one will lose when averaging down.
I had three profit warnings in my portfolio the last 2/3 years. Revolution Beauty (LON:REVB) Mobico (LON:MCG) and Good Energy (LON:GOOD). I have exited my positions immediately after their PW announcement and moved on to better things. One should have in mind the opportunity cost in averaging down but more importantly is the commitment of more capital that makes losing positions your top committed holdings in your portfolio!
From my personal experience and having talked and had meetings with so many investors I realised early on that the most difficult thing in this game is the management/discipline in one’s portfolio. Believe me the easiest is the stock picking!
All the best
Yes, Yiannos, and thank you. I have learned the hard way but find it strange with hindsight I did not recognise sooner that some of the causes of a decision to average down are also the very reason I should have sold up! For example, the price falls below ones buy price due to:
1) Profit warning,
2) A change in the industry or narrative that changes or destroys the investment case,
3) The breach of a particular technical measure(s).
I am sure there are other red flags. All are cases of emotion, optimism or some psychological factor trumping logic and rules.
Kind regards,
Capita (LON:CPI) Interesting comments Paul. I personally think their brand is tarnished following last years data breach. Revenue continues to fall despite inflation linked contracts. This implies to me that they are losing contracts and not winning many new ones. Im sure my pension scheme will ditch them once the contract ends, given all the angst from the personal data breach where the story continually changed for the worse! I think they are a 1990 to 2000s style outsourcing company struggling to compete in a more digital cost effective world (ie legacy systems, legacy cost base).
A more radical restructuring (splitting the business into two via demerger or trade sale) along with a name change may be required. Its been a recovery stock for too long. I would rate it as Amber personally, as if you follow the cash it doesnt generate much from its operating cash flows and predicts more of the same in the outlook. No dividend anytime soon. Its only not gone bust by selling things.
For the record, I purchased some stock last time it was recovering but sold after the data breach for a tidy profit. I'm not tempted back in again!
Well Hardwood are getting involved in Capita (LON:CPI), so that restructuring could well happen. Did you see the Richard Staveley interview fairly recentlyabout them? I don't hold.
Hargreaves Services (LON:HSP) and TT electronics (LON:TTG)
Investing is simple but not easy, not original to me, but nevertheless true.
I have held both of the above shares on several occasions. Hargreaves Services (LON:HSP) has been successful for me, but as usual I sold too early have made a reasonable return, TT electronics (LON:TTG) has been less so. The latter's chart has been woeful. I am not a chartist but the direction of travel of the shares doesn't inspire confidence. Also as far as I can tell that the new CEO, Peter France has not acquired any shares since his tenure began over 6 months ago, please correct me if I am wrong. Conversely Graham Banham, CEO of Hargreaves holds just over 8% of the company.
I am reasonably familiar with Hargreaves Services (LON:HSP) and its component parts, Services, Land and the German recycling operation. Services and Land should be provided with some tailwinds from the Labour government proposals to encourage house building, infrastructure and energy generation, although the Lower Thames crossing may be put on the back burner by the Government. I have also done a little research into the Carbon Border Adjustment Mechanism (CBAM) that was referred to by Nicholas Mills in the recent Vox Markets interview. Below is an extract of an email from Michael Taylor in which CBAM is explained.
TT electronics (LON:TTG) has been a disappointing investment on a couple of occasions, so I have exited, possibly at the bottom having bought at around the same price and reinvested the proceeds in Hargreaves Services (LON:HSP).
Time will tell if I am wise or foolish, both should announce results next week.
"Hargreaves Services had been on my watchlist because of the chart but I’d never bothered to look into it properly.
Nobody has, according to Christopher.
Because nobody seems to have realised that in January 2026, the Carbon Border Adjustment Mechanism (CBAM) comes into effect, which means that any material that is carbon intensive and imported into Europe will be subject to carbon tax credits.
Hargreaves Services produces pig iron, which has rocketed in price since the Russo-Ukrainian war. That price has settled a little, but Hargreaves Services produces 250,000 of pig iron per year.
We know that there will be half a credit to two credits attached per ton of imported goods, and we know the current carbon credit price is around €66, so €33 multiplied by 250,000 tons gives €8.25 million in additional profit.
Given that SharePad has profit after tax of £12.8, that’s a nice uplift.
There’s also a potential Russian embargo coming. Russia currently exports 1.6 million tons of pig iron but was dumping pig iron into Turkey, that was then being sold into European countries. It’s now being looked at by the European Commission.
Furthermore, Harwood believes that the existing asset backed price of the shares is 800p against the current market price of 560p.
That’s without any CBAM and without any incremental growth."
TT electronics (LON:TTG)
Thanks jonno interesting comments - coincidentally i have had an email this morning from stocky flagging up that the 142p price alert level has been triggered. for anyone who doesnt use price alerts they are a brilliant tool for keeping up to date on stocks you slightly follow but dont pay too much attention too - i thought i had missed the boat on both TT electronics (LON:TTG) and Journeo (LON:JNEO) - i put in some pretty lowball alert levels for both and they have both been triggered - without the alerts i might not really have noticed that they were looking cheap.
Anyway i am still lurking with TTG at present but i am attracted by the cheap pe (6.9 !!!!**) and the fact that 2025 earnings at present are expected to show 10% plus progres over 2024. the 2024 numbers look decent compared to the past so it would seem odd to me if they were over egging the 2025 boat if there is no need to - i would much rather start with conservative growth estimates ref profits 1 year ahead rather than glass half full and to having to downgrade later. I dont know the company well enough though to see how reliable ref churing out profits and what variability they may have in that regard - the past numbers look way sketchyn on stocky so my worry would be could earnings suffer large downgrade with little notice or whether they only have short spells of making hay with trouble around the corner?
perhaps time for me to do some more research - thanks jonno for updating ref this company useful to have thoughts of others.
nowadays i prefer to get trading update before buying in but sometimes the drop in price with no change in fundamentals can be too much temptation - i bought into Journeo recently and was almost immediately in panic mode that something may be up behind the scenes thankfully that was not the case there - could TT electronics (LON:TTG) be the same i know not.
** although p/e on stocky seems super cheap there is a material amount of debt here - so any investment here does come with heightened risk imho - eg if earnings where to drop materially with debt they have they could be in a reeet pickle !
I try to stay away from over indebted companies normally but if propsects have changed and they are paying debt down we all know what can happen there (card factor and mcbrides) - ref debt they did seem confident in that regard but really debt for them over £70 mill is probably too much to be carry imho long term (say 2 * profit after tax) - at ye they had £106 mill excluding leases
their recent comments ref debt
We ended the year with net debt of £126.2 million[1] (2022: £138.4 million), including lease liabilities of £20.8 million (2022: £23.1 million). Year-end leverage was 1.7 times (2022: 2.0 times), within the Board's target leverage range of 1-2 times. We are confident this downward trajectory will continue as EBITDA increases and as we deliver further strong free cash flow in 2024.
Tough call on TT electronics (LON:TTG) . I may end up buying back in? It looks very cheap, but has been a serial disappointer for me. As for Journeo (LON:JNEO) I also hold and added recently after the trading update.
Hargreaves
Im pretty certain the wind farm Assets are very understated .
Lots in planning, takes up to 5 years then windfarm incone os eye wateringly high .
They cant account for any “potential” pr upside with developpers who do the work and pay the lamdowner circa 7-9% of income for 30 years .
I know someone with 200 hectares of forrestey in scotland , circa 1.5 million valuation as forestry .
Decelopper wants to put on 13 turbines and thsf will pay a yearly 9% amount circa 800k for say 30 years .
Huge upside on these numbers if you rake a 5 year view .
does Hargreaves qualify for inheritance tax relief
There's a question mark over its qualification for BPR/IHT due to some of the assets which are joint own and could be seen as investment assets. You could seek clarity with the company but for me it goes into the too uncertain category and not worth the risk.
Im pretty certain it qualifies checked it a few years ago and it did then
When I checked it was doubtful. It may be academic anyway !
Beginner's question - how do I find which stocks quality for IHT tax relief?
Beginner's question - how do I find which stocks quality for IHT tax relief?
You can't. There is no list. Start with the gov.uk website where the criteria are listed and then apply them systematically to a portfolio. Provided most of the shares you select subsequently qualify, the portfolio will have achieved its objective.
Beginner's question - how do I find which stocks quality for IHT tax relief?
As a starter, you could check for AIM shares where Octopus AM have a substantial holding. They run a large AIM IHT portfolio for clients. I quickly checked through the AIM 100 last night and Octopus have > 10% holdings in quite a few companies discussed here, including Brickability (LON:BRCK) Sanderson Design (LON:SDG) Renew Holdings (LON:RNWH) and H & T (LON:HAT. There is no list as such, and even companies that run IHT portfolios have a disclaimer that they cannot guarantee the IHT status of all holdings.
Thin market offering some nice top up opporrunities ?
Seems a very thin market with presumably everyone away in the sun
On smallcaps a fee sales knocking 5-10% off intraday swings and a few buys send it the other way.
Im not buying anything new just increasing a few on these swings .
Downing seem to be rhe seller on Centaur media and they are now below 3% thats keeping cebtaur pinned back, still buying the dips there .
Centaur Media (LON:CAU) £24k CEO buy reassuring too.
Just a general question if anyone knows.
A closed period, prior to a company announcing it's results.
What is the typical length for these periods?
From Investopedia :
That's the basic definition and is useful. However, close periods are affected by other variables that will not be in the public domain - such as the period of time it takes for a company to complete and announce a significant contract or finalise an acquisition. Such things can lead to close periods extending out to months outside of in conjunction with those applying to the release of results.
Harish
It's usually 2 months before annual results.
Tender offer on the table for VCAP shareholders at 20% premium to close of play share price yesterday. Hopefully that's a good result for holders here.
I would never buy shares in Wizz Air Holdings (LON:WIZZ) as I would never fly with them. They are so terrible in everything they do. As for Jet2 (LON:JET2), I'm not sure they should be classified as a budget airline? More like mid-range? I usually find them way more expensive than the other 3, but at prices that I'm willing to pay as the experience is a lot better.
Wizz Air Holdings (LON:WIZZ) has also previously run into problems with the regulator. It's extremely rare for the CAA to take action against any airline under its consumer powers: https://www.caa.co.uk/newsroom...
Which? constantly warns Wizz Air Holdings (LON:WIZZ) is terrible as well: https://www.which.co.uk/news/a... whereas Jet2 (LON:JET2) regularly wins their recommended provider award.
I don't think anyone (reader or Paul/Graham) flagged the National World (LON:NWOR) results yesterday. I bought this fairly recently and think it looks pretty decent:
* Revenues up 17% albeit mostly driven by acquisitions
* Full year EPS expected of 3p (vs 17.5p share price this morning) - yesterday said it is trading in line with full year
* Net cash of £13m (equivalent to 5p per share)
* No defined pension obligations
* Dividend c. 4% (although I appreciate there are better divis out there right now)
* Growing through acquisitions and organic growth in some divisions e.g. events.
Similar business Reach (LON:RCH) has more debt with pension, although has a better dividend and is slightly cheaper on a pure p/e basis (although not on a debt/cash adjusted basis).
Never going to get a high p/e at National World (LON:NWOR) because of the structural decline of some of its markets, but if it can continue to grow revenues and profits then there is hopefully upside through both growth and maybe a slightly higher p/e. Maybe a max p/e of 7-8 isn't unjustified?
Not sure why you think National World (LON:NWOR) only deserves a p/e of 7 or 8 especially with it's 5 pence per share worth of cash. I would have thought there is plenty more consolidation left in the local newspaper/media sector and David Montgomery knows the sector better than anyone.
I note Harwood recently bought Downing's 4% stake.
National World
There is one huge problem .
David Montgomery and his cronies run this purely as their “vehicle” and its not about shareholder value or returns .
At best you are along for the ride with a greedy pocket filling self incentivised ego driven highly paid rewarded and incentivised person who has no qualms rewarding his own brilliance .
Cheap for a reason.
I used to Hold a big chunk but got annoyed with the management just treating it as their own personal gravy trainset .
no odea why but i bought a few last month.
Horrible management ethos when the show is all aboit them .
National World (LON:NWOR) I am sure Montgomery is well rewarded but he has set up a good business from the failure of that company that went bust. I am not aware of excessive rewards for other directors, and am pretty sure that the substantial shareholder would not allow excessive rewards. (have forgotten names and too lazy to look up )
He is a veteran of local news and seized an opportunity when it appeared. He has made mistakes in the past but he and his ex FD (forgot his name) ex Reach know the business inside out. Do not agree that the business is ex growth, the sector maybe, but I doubt even that. There may be plenty of money to be made consolidating. Democracies need local news, more than they need monster American tech companies draining local economies.
I suggest that the recent price weakness has been caused by several institutions having to sell in a thin market eg Downing.
National World (LON:NWOR)
There is no growth here-it’s a declining business-LFL revenues fell 10%.
All the best
Yes I agree with yainnos01 & others.
Sorry we're not going to waste our precious time on crap like that.
P. xxx.
Paul, I am surprised by your comment. You were often bullish on Johnston Press , and this is JP without the debt and with cash, on a low p/e
Regards,
Graham
It is a poor-quality business in a declining market run by a Board out to cream off what they can.
I was going to say pretty much the same thing. My BIL was Marketing Director at The Scotsman before leaving to set up his own business which he sold last month. His advice? Like Planet says .... look at the Board. I sold out a while back (for a loss) once I had been fully educated,
Education always has a cost.
National World (LON:NWOR)
That’s where companies with no growth trade ; even lower around 5.
All the best
I know no one can predict the future... and I hope you don't mind (if it's not against any stocko rules) but I'd quite respect your views @yiannos1 on how the UK market will do going forward the next twelve months ?
Well about 100 years ago, when asked the same question, (about the US market) J P Morgan said "It will fluctuate"
That's probably still the best guess for today.
yes true, good response !
also, can anyone tell me how a stocks quality rank can fluctuate when no new figures have been released by the company ?
Are they not being compared to others in the same sector, so if others change that could affect the quality rank?
Stocko says: "The Quality Rank is ranking system that aims to find the best quality listed companies. It is based on a blend of measures that include an assessment of company franchise (profitability, cashflow, margins), company risk (bankruptcy, volatility) and fundamental trend (F-Score). These inputs are computed for every company in the market on a daily basis, ranked, blended and then re-ranked as a percentile from 0 (worst) to 100 (best)."
yes that must be the reason, thanks ! much appreciated
LOL .... possibly a lot.
My forestry and agricultural land holdings probably fluctuate a lot, but thankfully they are illiquid, and I cannot check on a screen
.... which saves me from selling good assets.
...and from my own fear of volatility.
How true
I wouldn't be without stocko and these boards, but they do encourage itchy fingers
The 30 day federal funds futures show TODAY that the FED will cut interest rates three times before the end of the year taking the Fed fund rate to 4.25% from 5.25%. For 2025 the same futures show TODAY that the rates will be at 3.25%. The US debt is dangerously accelerating and will damage the global economy. Interest payments on this debt is higher than the defence spending in the US.
These reductions are always bearish for stocks and the inverted curve has already started to normalise. Do not get carried away that interest rate cuts are bullish cause they are not!
I do not think that the UK market as a whole (FTSE100) will offer any meaningful returns BUT opportunities are always out there if you can spot them. It’s all about stock picking.
I am 75% cash now and will be researching for the rest of the year for any opportunities. I only hold Made Tech (LON:MTEC) Kier (LON:KIE) SysGroup (LON:SYS) and Gulf Keystone Petroleum (LON:GKP). If the correction continues all stocks will at some point be affected. I will not sell though these positions.
In general I can see 2/3 very difficult years for the stock markets. The UK small cap sector as a whole will shrink even more. The decision also for the North Sea oil by the current government is suicidal BUT I believe they will reverse it in the near future.
Hope that helps.
Personal opinions DYOR.
All the best
thank you, it does help, I remember you cautioning re: US debt many months ago...
totally agree re: stock picking, Paul and Graeme and many more illustrated this last year
Trump getting in a strong headwind also... eeech
obviously I will DMOR
all the best
Totally agree ... no value here. Let's move on.
Graham has done 40% this year, me 36%.
Yup, no value!
Well done ...seriously.
It might have a value as a swing trade ... as a long-term hold, it is not for me. I simply don't trust the Board. Their incentives are not aligned with mine.
Montgomery will paddle his own canoe in his own river, and he has form.
Other than your views of the Board's incentives and approach, whether or not you decide to maintain a longer-term position depends entirely on your view of the ability of digital with its super low costs to compensate for declining print volumes and the ever-increasing unit cost of newsprint.
I see little value here, but different views make a market. When I sold a couple of years ago, someone else bought. They had a different view and that is OK.
Late news yesterday that many may have missed - Bloomsbury Publishing (LON:BMY) is now in the FTSE 250. https://www.bloomsbury-ir.co.u...
That explains a large transaction (over a million shares) two days ago that increased the buy price by 20p
Not a small, or even a mid-cap, but I like the TU from TIC (testing, inspection, certification) giant Intertek (LON:ITRK), a British company that is part of a global “triopoly” with SGS and Bureau Veritas. The RNS reads exceptionally confidently after some years of moribund market conditions. Turbulence in indices might put paid to a jump in the SP today, but perhaps that’s an opportunity to pick up some of this very long term performer with superb returns on capital, very high margins, strong, growing and well-covered dividend, and a reasonable valuation relative to history. Warning: quality doesn’t come cheap, but it’s better value than most other industrials with comparable operating numbers. If current market volatility correctly signals a recession, then this would be a bad time to buy, otherwise I see upside.
You are right - I have just done a comparison with Halma (LON:HLMA) which is even more expensive and does not even pay 1% divi despite their record of increasing divi for the last umpteen years!
I do hold some because the track record is good, but every time I read one of their press releases I want to scream.
"Our highly engaged, customer-centric organisation is laser-focused to take Intertek to
greater heights..."
I normally get rid of companies that serve up word salads. I've been suspending my usual prejudice on this one because the CEO is French and they operate in an industry where you have to make "Don't be bloody stupid" sound sophisticated....
Morning All,
At 1230 yesterday, i was feeling hopeful of a nice recovery in UK markets. One hour later and all had changed. Markets eh?!
And look what happened in Japan - Nikkei down 5.88% this morning
Remember the old saying... it is when the tide goes out, where we find out who isn't wearing shorts.
Making money in a rising market is easier than preserving your capital in a falling market. If this indeed is a start of a correction...
where we find out who isn't wearing shorts
Burberry (LON:BRBY) should look at this as an opportunity !
James Halstead (LON:JHD) - for those that missed the discussion a day or two ago, JHD has an elevated valuation because of its appeal as a safe haven from IHT, being a qualifying AIM stock. It used to have an even greater valuation as a very reliable yield play at a time when the risk-free rate was zero. That valuation has come right down as a result of higher government bond yields - why take more risk to achieve the same yield? Although the valuation could now be supported by falling interest rates - unless they are tumbling because of recession, when everything will fall. Finally, with a twelfth of its market cap in cash, the effective PER is closer to 17x. But it’s still not growing!
There is also the potential removal of the IHT benefit come October. That would likely impact the share price, but difficult to tell as we don’t know what will be in the budget yet.
I just hope investors have the common sense to only invest in Aim companies they believe in - not solely for IHT benefit which I suspect will indeed be withdrawn - except perhaps for directors and employees - but then they have EBTs
IHT
Petsonally I think there is zero chance of removal of IHT cover or business taper relief .
Its just not a risk a new government are going to take .
If they do guess it will have to more forestry .
Just isnt going to happen .
And if they did ill have to get married pronto !
I think there is zero chance of removal ofr business taper relief .
if you are talking about the low rate of cgt on business disposals i would be betting that there will be material increases here. I just cannot see 10% remaining when they are really struggling to get numbers that add up without breaking promises or making themselvs look like fools when thye do raise taxes (eg starmer was moaning about tories possibly removing winter fuel allowance last year i think)
Hey ho - they may be in for a real windfall if interets rates keep dropping - i think interets bil alone is 4th biggest spend currently at over £100 bill - oh what we could do if we hadnt stolen from future generations for the last 50 years.
I think that Planetx was referring to IHT planning by using BPR on some Aim stocks...
IHT
I went to the AGM of a qualifying company this week, and they and their broker were convinced that IHT cover would be removed by Labour. Has seriously worried me, and getting married wont even help
James Halstead (LON:JHD) - Back in 2019 Chris Brown wrote an informative piece about the potential impact of the withdrawal of BPR. Here is the link:
https://www.stockopedia.com/content/inheritance-tax-the-exposure-of-aim-to-business-property-relief-522736?order=createdAt&sort=desc&mode=threaded
At the time he estimated that some £3.2B was invested in AIM IHT portfolios -perhaps not much greater today given the uninspiring record of AIM over the past few years. Interestingly the exposure of James Halstead (LON:JHD) to BPR was relatively low at around 8% of its then market cap.
I run a self-invested AIM portfolio including James Halstead (LON:JHD) and I’m considerably less sanguine about the continued availability of BPR. Given Labour’s commitment not to raise taxes on ‘ordinary working people’, pensions, CGT, and inheritance taxes are prime candidates for raising additional revenue. I don’t agree with planetx that there is zero chance of the removal of BPR. On the contrary, I think it possible there will be measures included in the October (?) budget to raise revenue such as:
I think the new government is likely to take this step early in their administration because it is the time when they have maximum political capital, and they need the flow of revenue to support their plans. And it fits the mantra of those with the broadest shoulders carrying the biggest burden. Leaving such changes to late in their administration would give a hostage to fortune. Of course, I could be wrong, and I hope I am.
Chris Brown argued that the overall effect of the withdrawal of BPR may not be as severe as it might seem, and could offer an opportunity to buy into AIM companies at attractive valuations. But bringing CGT into line with income tax rates would alter the balance of risk/reward in all shares especially if accompanied by an upper limit on tax relief available through ISAs for example.
October is not far away, and we will not get advance notice of any changes to come. So, what to do now? My thinking is along the following lines:
Then think again when we know the worst. Any comments would be welcome.
Thank you for your comments. I had not thought there was any chance of removal of the IHT reliefs until I was at an AGM of a qualifying company on Tuesday, where they thought it likely.
I also run a portfolio of qualifying companies for my mother. So far I can not think of anything to reduce the risk of a change in the rules. There are large gains in all the shares not held in an ISA, and I would not be able sell any easily so a stop loss is not practicable.
At the moment I think holding onto our hats and hoping for the best is the best option, especially as there are so many possible variants of what they might do. I had always assumed that the government would have to give several years notification of a change in BPR relief as it would otherwise be a retrospective tax in that the IHT tax saving incentive to buy qualifying shares required them to be held for two years so for every qualifying holding the decision to buy was made at least two years prior.
I have read Chris Brown's very good article and the only good thing is we don't hold any of the shares mentioned.