Small Cap Value Report (Fri 20 Aug 2021) - VTU

Good morning, it's just Paul here today, with the SCVR for Friday.
Today's report is now finished.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to cover trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Agenda -
Paul's Section:
Vertu Motors (LON:VTU) (I hold) - another big upgrade to H1 profits, and the full year. Exceptional conditions won't last forever, but even if we normalise earnings, this share looks very good value. Fully underpinned by tangible net assets too. Divis & share buybacks are resuming. This is strikingly cheap, I reckon.
Also I summarise the recent webinar with VTU management, and a quick review of recent ITV Undercover Big Boss episode featuring Vertu's CEO.
Nothing else of interest today from small caps.
Paul’s Section
Vertu Motors (LON:VTU)
(I hold)
47.2p (pre market open) - mkt cap £174m
It was only a few days ago here on 29 July, when I covered the last in a series of positive trading updates from this car dealership (its main brand is Bristol Street Motors, as well as Vertu).
Share Buybacks - announced today that these will resume.
Vertu has already bought back about 7.5% of its shares in the last 3 years. I’m generally not a big fan of share buybacks, unless the share is trading at an irrationally low valuation, which is certainly the case here. VTU shares are below NTAV, and on top of that the company is enjoying a current trading bonanza. So buybacks are an excellent idea in my view, if there is surplus cash that is not required for other investments. It enhances EPS for existing shareholders, removes loose stock from the market, and should therefore drive shareholder value in the medium to long term.
Today’s buyback announcements is -
- From now to 28 Feb 2022
- Maximum of £3.0m - so not large, at under 2% of the market cap
- Zeus Capital will carry out the purchases on VTU’s behalf, which is normal
My opinion - this share looks irrationally cheap to me, so share buybacks make complete sense. The more, the merrier!
...the Group is providing an update on current trading and a further upgrade to the full year outlook.
Exceptionally favourable conditions for used cars sales & margins are continuing
Adj profit before tax (PBT) for H1 upgraded to at least £50m - that’s a huge upgrade coming in the last month of the H1 period (6m to 31 Aug 2021). We were last guided, on 29 July at >£40m adj PBT for H1.
New vehicles - order intake for Sept 2021 is above last year
Supply shortages likely to result in delivery delays (a widely known factor, so nothing new)
Shortages of new vehicles may also restrict supply of used vehicles
Labour issues reiterated - covid absences, high vacancies, upward pay pressure, labour shortages
Dividends - to be reinstated when interim results finalised
“Very confident” in the prospects for the group
Revised full year guidance - upped from £40-45m, to £50-55m for the full year to FY 02/2022. This implies no change to H2 performance, at £0-5m for Sep 21- Feb 22. All the increase has come from obviously exceptionally strong trading in Aug 2021.
Hence I wouldn’t be surprised if we get more upgrades later this year, as the bar has been set low for H2 - although note that the business does have a natural seasonality with H1 profits being much higher than H2.
My opinion - the whole sector look cheap, but VTU is the pick of the bunch for me, because it has such an outstandingly strong balance sheet - made up of freehold property, and working capital. Other car dealers I’ve looked at have much less balance sheet strength, as measured by price to NTAV ratio.
Even though current year trading is a one-off, it will leave a permanent boost to the balance sheets & liquidity of all car dealers. Hence they are worth more now than they were say 6 months ago. Expect consolidation in the sector.
VTU strikes me as the most obviously under-priced share in the small caps space right now. It could stay cheap though, often value shares are just unfashionable with investors, and they can stay cheap for a long time. That doesn’t matter to me, as long as dividends are flowing (which are resuming shortly), then sitting tight is very comfortable.
I think it’s a sitting duck for a takeover bid from private equity too, given all the freehold property, and very low PER.
There was a really excellent webinar with VTU management recently, which I took notes on, so as there’s nothing much else of interest today, will type up my notes below. That will take me about an hour, so should be up here by about 09:30.
.
Vertu webinar - this is a really interesting & quite entertaining (the CEO of 15 years, Robert Forrester, is quite a character!). My notes are below, it's a bit unstructured, because the commentary jumped about a bit, especially during Q&A -
.
My notes on this webinar - as always, my notes are not complete, and may contain unintentional errors or omissions. I jot down the most important points (to me) only -
Lockdowns have been frustrating, because CEO likes to spend his time out & about visiting branches - “Got to see the coal face, it’s the only way you find out what’s going on. Sitting down for 90 minutes with staff in branches, is best use of my time”
Click & Drive sales technology is best in the business. We use data extensively.
36 new outlets added since Jan 2020 - e.g. BMW/Mini, and MG
Current number of sites: Bristol Street Motors (82), Vertu (59), Macklin Motors (14)
Also acquired some ancillary businesses, e.g. Ace Parts - online parts company
IT - VTU has 45 full time software developers - cost is expensed, not capitalised, because it’s an ongoing payroll cost of running the business
Bricks & Clicks - online only doesn’t work, as only 0.8% conversion
Car dealers - it’s a low margin sector, so driving down costs & improving efficiency are key
Financial review by CFO - aftersales is 43% of gross profit (splits down as 74% servicing, 21% parts, and 5% accident repair). Used cars: 31% of gross profit. New cars: only 18% of gross profit. Fleet & commercial: 8%
Aftersales margin has been improving in recent years.
Net Tangible Asset Value (NTAV) is 50.2p per share.
Surplus properties have sold for above book value.
Net debt only £4.6m
20 year mortgages recently negotiated.
“We have firepower to grow, with strong balance sheet”
Share buybacks - potential to do more (announced subsequently, today). Have bought back 7.5% of total equity in last 3 years.
Internet only car dealers (e.g. Cazoo, Cinch) - very small. Pure eCommerce is not viable. Have to spend a fortune on marketing, for very low conversion rate of 0.5-0.8%
Change in dealer/,manufacturer relationships - in the pipeline, still being negotiated. Shouldn’t make much difference to us. This is the industry trend, it’s designed to reduce discounting & allow manufacturers to better control the price of new cars. Will kick in in 2023.
Electric cars - latest data shows the servicing bills are actually higher. New tech tends to go wrong (at least in first 5 years).
Online sales - VTU sold 434 cars online only, out of 8,500 in total (not stated over what period. So online only is small beer. Not many people are comfortable just buying online. 75% want to test drive. Most customers want to flex between physical & online.
“We can do everything the online only competition can do. The only advantage they have, is more marketing dollars”
TV appearance last week - Undercover Big Boss - was to drive brand awareness & share the values of the group. Has worked well, with web traffic, etc responding positively.
Manufacturers selling direct to the public - e.g. Tesla. Is this a threat? Don’t think so. Polestar, and a Hyundai startup are also trying this, but don’t see major manufacturers switching.
Aftersales are very busy at the moment.
Massive shortage of MoT capacity, so likely to remain busy.
Record trading conditions - “in 20 years I’ve never seen anything like it”.
Used cars are currently making exceptional profits - strong demand, and tight supply.
New cars - supply is still constrained. “All the cars booked for delivery in Sept are not likely to arrive in Sept in my view”.
Very strange environment - “if you’re not making money now, you never will!”
Unique situation, and new car constraints could last another 9 months.
“Very favourable conditions, so we must not get delusional”.
Cost pressures emerging - especially over wages. We have to pay more to retain & attract good people.
Supply chains - should improve in Q1, but varies by manufacturer.
“But remember, every time we see shortages of vehicles, our margins go up!”
Are Parkers Guide prices reliable? Yes, they’re accurate, and up-to-date.
Demand for cars should remain robust, due to full employment & nervousness about using public transport - where possible people prefer to use a car.
There will be another shortage of used cars in 3 years’ time, when shortage of current new cars feeds through to secondhand market. So it will take a long time for things to completely normalise.
Stellantis (Fiat, Chrysler) - risk re contract? Not a risk to the number of outlets. Too early to say re other effects. Having discussions with manufacturers over future relationships.
Electric vehicles - I don’t draw much distinction, it’s just another car for us to sell. Will take decades for the full impacts to feed through (of phasing out of petrol/diesel), much longer than most investors timescales.
Is Ford a declining part of your business? No, it’s our most profitable division!
Robots (i.e. special software to automate processes) - we have active robots, doing things like managing bookings, taxing cars electronically, contact centre, anything that involves re-keying is targeted for automation. Planning a 4th robot soon, to automate car buying. 5 or 6 robotic engineers will be busy for a while.
Shortage of car technicians - so wages are going up.
Selling a 3 year maintenance plan is great business, as customer pays monthly & greatly improves customer stickiness.
Asked about claimed competitive advantages (disruption) of online only competition - absolute nonsense! For a while we were buying cars from Cazoo, because they underpriced them! But that’s stopped now. But new competitors will get better. The used car market is near enough a perfect market. So the idea someone can enter that market and disrupt it by buying cheaper, is nonsense! They have no buying advantages at all.
Question about what makes a good CEO? Someone who builds a good team, with a good culture, understands data and the modern world. And definitely needs good mentors - I had great mentors.
TV Show
I watched this on catchup. It’s entertaining, and shows the CEO in an ill-fitting wig, pretending to be a history teacher, shadowing various staff in the branches.
Lee, the laddish van salesman - is praised for his high energy, successful online videos, which have worked well. But given a telling-off for his immaturity, swearing, and laddish sexual innuendo in videos. Made to sweat, but then rewarded with a promotion to overseeing group-wide training & promotion of online videos, and cleaning up the content.
Salesman - very good at his job, but revealed he was having family troubles (unspecified) and found challenging sales targets too much pressure, so was threatening to leave. Was given a pep talk, and an all inclusive holiday as a reward, and decided to stay.
Valeter - works flat-out, but only employed on an agency contract with no job security. Rewarded with a proper contract, and £15k towards a house deposit.
Did the company come across well? Yes an no. It was good that the boss went out there to find out what was going on. But the impression I was left with, is a company that hasn’t been properly looking after its best staff, so putting that right is hardly earth-shattering.
.
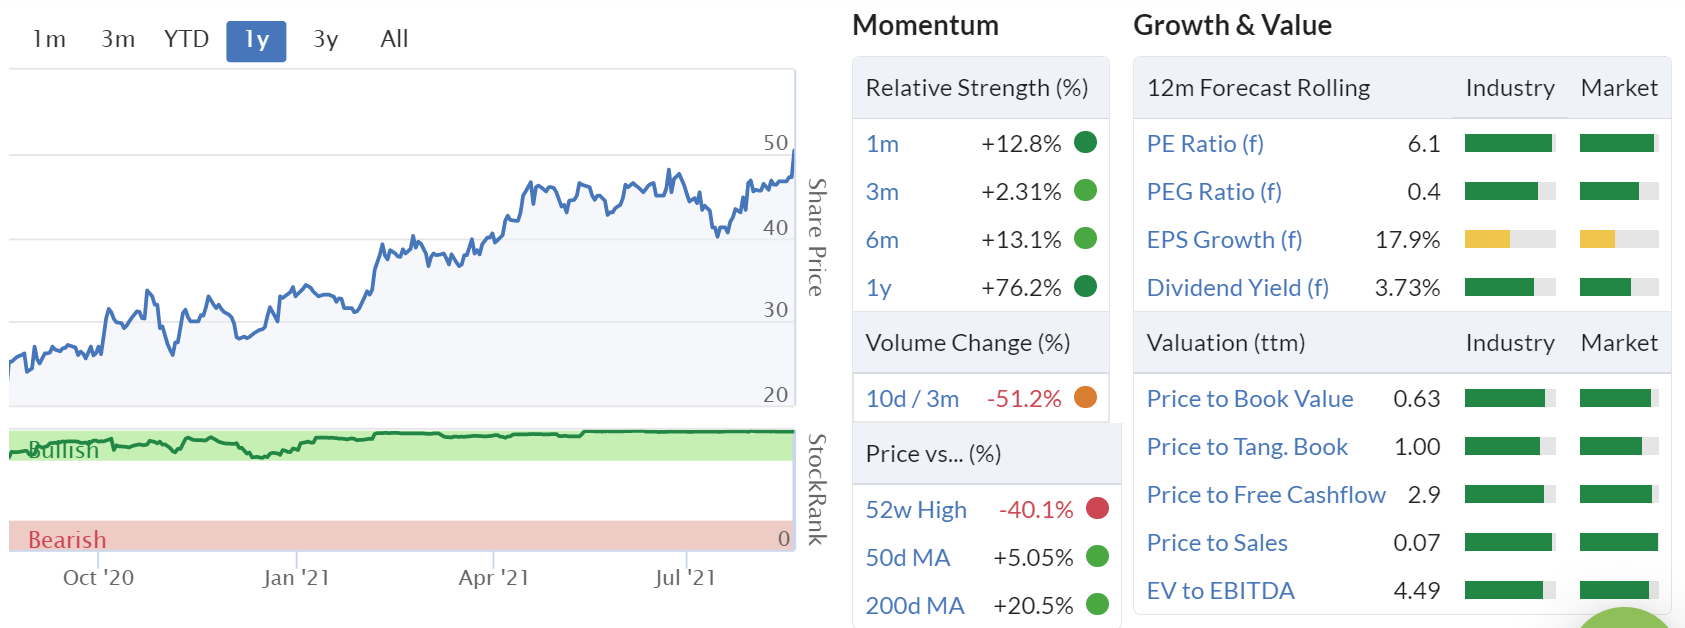
Look at all this green!
.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

38 comments
This is a great SVCR article on VTU I bought some in July after researching the company and then doubled my holding before the latest trading update so this is a winner for me.
As a director of a business that has both benefited from government support and had substantial profits over the last 18 months I couldn’t disagree with you more, Si. The support that was given allowed us to avoid making redundancies (that we obviously didn’t want to make) but it wasn’t a “free decision”. There were costs to continuing to employ those people that we along with the government (in varying percentages over time) shared together. We are grateful to government for supporting the business and jobs of our employees but for most companies, repaying furlough monies now is a bizarre idea. If the government had made the payments a loan repayable when we came through the pandemic, no reasonable company could have partaken, given the risks at the time.
I hope you can see this is a very one-eyed view. What about the taxpayer? What about all those businesses that didn't need to take furlough money but at their own expense had to layout capex to ensure they could continue trading without taking a penny? And what's more, other dealers have already paid the furlough money back i.e. Marshall Motor Holdings (LON:MMH) If someone offers you money and you take it, IMHO you should pay it back when you are able. It seems perfectly obvious Vertu Motors (LON:VTU) could pay it back at the end of FY22 but will not.
If you don't find it wrong that a company can take £27.8m from the taxpayer in furlough money and two years later propose paying £7m to its shareholders in dividends, then I'm not sure what that tells us? I guess my moral compass is the one that is wrong then? It is just not right as far as I'm concerned and reflects badly on the management. Apart from anything else, when you look at how much furlough money they had to take it only further illustrates how high the overheads are and why margins are so low. It's roughly 12 months operating profit!
Also, I found the CEO's response to the Q&A remarkable given my own recent first hand experience of buying a car and talking to several dealers. I would say, most of it falls into the "he would say that" category and he was clearly talking his own book. I'm not sure a private equity company has ever bought a bricks and mortar car dealership but they are positively piling money into on-line used car market places. Even if it does not mean the end of the old fashioned car dealership, it will at the very least provide significant additional competition. It's an industry ripe for disruption.
All the best, Si
I sold out of Vertu Motors (LON:VTU) at the end of June having bought in July last year when it was a proper value proposition i.e. PTTB < 0.5. A 100% gain in under 12 months was good enough for me. I remember someone once said you should always leave something for the next person...
I'm not about to get on a moral high horse, but one of the reasons I decided to sell was the following statement from the FY results:
Government Support
Given the forced closure of the business due to Government lockdown regulations, the Group received Government assistance during the Year in two key areas. For the full financial year, furlough grant receipts of £27.8m and business rates relief savings of £8.7m arose. This assistance offset substantial losses particularly in the first lockdown. In April and May 2020, for example, the Group reported a pre-tax loss of £20.1m after Government assistance.
The Group does not intend to repay this Government support which arose due to the forced closure of its operations.
Personally, given that they are now seeing massive profits as a direct result of the subsequent re-opening following the pandemic, gained indirectly through massive amounts of government support for the economy, I find this stance morally disgusting. If you invest in Vertu Motors (LON:VTU) make sure you have a peg on your nose.
All the best, Si
As a director of a business that has both benefited from government support and had substantial profits over the last 18 months I couldn’t disagree with you more, Si. The support that was given allowed us to avoid making redundancies (that we obviously didn’t want to make) but it wasn’t a “free decision”. There were costs to continuing to employ those people that we along with the government (in varying percentages over time) shared together.
We are grateful to government for supporting the business and jobs of our employees but for most companies, repaying furlough monies now is a bizarre idea. If the government had made the payments a loan repayable when we came through the pandemic, no reasonable company could have partaken, given the risks at the time.
Now we benefit from having an experienced workforce in place which has allowed us to capitalise on the opportunities in front of us. The government has done its job and helped business generally survive a brutal systemic shock (no small thing) but anyone who believes that there both isn’t worse ahead and going to be less support from the government when it happens just really is not paying attention.
As an investor and a shareholder of many businesses, I am clear that management’s key duty to me is to secure the future of the business and maximise profit. That doesn’t include paying extra taxes that David Cameron determines are morally justified (but doesn’t have the balls to try and introduce to parliament). It doesn’t include repaying money that isn’t due that otherwise could be used to drive further growth or protect the business during the downturn which has to come over the next 18 months. If government wants the cash, you know they have the power to take it, right?
In my opinion, the only companies that should repay money to government are those for which it’s a tiny overall percentage to benefit from positive PR or UK supermarkets who received such a sweet deal from the exchequer and have such a central role in the UK economy that they are quasi-parts of the government anyway.
Note: Like you I was a holder of Vertu Motors (LON:VTU) until yesterday. I didn’t sell out because I think the prospects for the company are poor or because they didn’t pay government back monies. It’s because I’m taking profits where I can and reducing general exposure. I think Vertu Motors (LON:VTU) is likely to do very well over the next year but I don’t trust the market right now.
Hi Phuntt, v interesting, thanks for explaining so fully.
Are you sure you mean David Cameron?
lol, no not really. David Cameron’s political philosophy is that everyone should pay less tax if possible. Don’t really know where that came from (blame a high horse and a Saturday night bottle of wine).
As an investor and a shareholder of many businesses, I am clear that management’s key duty to me is to secure the future of the business and maximise profit
No it's not. At least not legally.
Corporate managements do not work for shareholders. They work for the corporation which technically is a "natural person" - i.e. it exists independently of shareholders and employees. This isn't legal sleight of hand - although shareholders have certain rights in respect of the corporation, the employees of the corporation do not work for shareholders and the corporation's money is not the shareholders'. And there is no obligation on managements or employees to maximise shareholder value, whatever that means.
And because of this the entire edifice of the mantra of shareholder value maximisation - and its corollory, that the corporation need not take a moral position on issues of societal importance is also wrong.
The idea that corporations exist only to maximise shareholder profits dates, in its modern incarnation, to Milton Friedman's NYT article in 1970: "The Social Duty Responsibility of a Corporation is to Increase its Profits". It's pretty much been discredited by anyone working in business management but it does retain a certain allure for shareholders, for reasons that are presumably obvious.
timarr
I don’t believe that companies or their management are immune from moral obligation to their stakeholders or society. On the contrary, I believe that if they don’t act to support the community they operate in, sooner or later it will probably spell the end of that corporation.
However, tax is not and shouldn’t be treated as a moral act. Government has the power to take whatever money it deems fit from business and the idea that companies should pay monies they don’t actually owe on top of that seems bizarre to me (something I would expect in China rather than the UK). And while shareholders are only one of the stakeholders in a business, if management overpays money, it is shareholders money they are choosing to send (or at least they are reducing the available pool of capital in the business to which the shareholder has a legal claim). Their may be a logical business reason to do so in some cases but in most it just doesn’t make sense.
Government and tax are not a charitable exercise and shouldn’t be treated as such. That confusion leads down a dark path. Corporations do not exist to only maximise shareholder value but any business that chooses to ignore that it is important isn’t likely to succeed.
... if management overpays money, it is shareholders money they are choosing to s[p]end
No it's not. This isn't an abstract point, the money owned by a corporation isn't shareholders' money despite the fact that most shareholders seem to think it is. A company's money is the company's money in the same way that my money is mine. The fact that various parties have a claim on my money doesn't make it any less my money.
The whole area is complex but if corporations uniformly act to maximise their earnings then they must also act to minimise their employees' earnings. If every company does this then who has the salary to afford anything?
A similar argument can be made around taxation - although I accept that companies ultimately are subject to laws made by government. But if corporations can exploit the differences between nations to deliberately avoid legitimate taxes or even pay to subvert democracy as Uber have done in California then you have to ask where the line should be drawn.
timarr
You are right Timarr - a corporation is a separate legal entity. Sorry if my loose language is leading you to believe that I don’t accept that.
I’m not sure where we are going after that. I think I agree that corporations shouldn’t be allowed to act uniformly to minimise workers wages and we talked here a few months ago when I vigorously advocated for higher taxes on international technology companies exploiting tax loopholes.
So we agree then?
You are right Timarr - a corporation is a separate legal entity. Sorry if my loose language is leading you to believe that I don’t accept that.
All true, I'm allowing a particular grievance to run away with me. As you are kindly, but not directly, pointing out. Apologies.
It would be lovely if companies voluntarily accepted their responsibility to pay higher taxes, but we know that won't happen. Still, I do think Vertu Motors (LON:VTU) should recognise that some of their current profits are due to being able to keep employees on the payroll through government support that they would otherwise have let go.
But yes, we agree :-)
timarr
I think our difference in view comes from a difference of opinion in what furlough was.
That's not true. I fully understand what the furlough scheme is. The difference of opinion is entirely on moral grounds.
Say I was in desperate need of money and you gave me enough to see me through until I was able to get back on my feet, but told me there was no compunction to pay it back. How would you feel if when those better times duly appeared only a year later, and I was making super-normal profits, I decide to blow those profits on lavish presents for all my friends and family without so much as a small acknowledgment by way of a gift to you. Because that's what Vertu Motors (LON:VTU) have done to the taxpayer. You can paint it any way you like, but it stinks.
We're never going to agree on this because you are talking your own book. I'm surprised the media aren't all over this. I have time on my hands these days having retired at the end of last month, so perhaps I'll contact the press and stir the pot myself.
Si
Maybe, Si - I’m not unbiased here.
But you gave an example, let me give some alternatives. Say in March last year, Vertu Motors (LON:VTU) believed it was likely that due to massive government spending and supply shortages used car prices were going to skyrocket. Say they could make most of their staff redundant for £2m, rehire and retrain for another £2m in a year’s time and government offered to loan them £28m to pay staff in the meantime repayable if it came good. As the management of Vertu Motors (LON:VTU) would you take that deal? It would certainly be the moral thing to do. But I’m sure that a percentage of businesses in the same situation wouldn’t and that means the very thing the government was trying to achieve I.e. keep people in employment would have failed.
I made an investment in a VCT last January that I’m certain has benefited massively from government COVID spending in the last year giving me a generous profit. Should I repay the tax rebate on earnings I received at the time?
I invested in a startup that also benefited massively because of government grants. It then went on to be a massive winner because of COVID restrictions on competitors. Should it repay the grants?
I invested in an airline last November that has suffered badly because of government restrictions I don’t think should have been imposed. Should I sue the government? Should the airline sue the government?
The point I’m making is morality and tax is a not a mix. The government not only sets the economic rules and incentives to achieve what it wants and it also has the power to arbitrarily change them at any point. All companies and investors can do is try and position themselves best to win on the gameboard the government puts in place. The idea that the winners should also then give the money back to the government because of some moral obligation is simply bizarre to me. You may feel differently.
I think it is an interesting debate re morals etc. I agree with both points of view. My situation is that I set up a new business on 1st March 2021 (really bad timing i.e. started trading) and took my first member of staff on on the same day. I was waiting for this new staff member to arrive to begin trading. I initially couldnt furlough the staff member due to the relevant dates etc then they changed those dates so that he could technically be furloughed apart from the fact he was paid monthly on the 25th of each month. Therefore he could not be furloughed basically beacause he was paid monthly and after the furlough scheme's cut off date earlier in March. Business instinct said - make them redundant; but my morals dictated that I couldn't do that so I paid them from my own money and then further down the line I took out a BBL that I have now started to repay (and fully intend on paying the full amount).
Then some companies as we know got millions from the furlough scheme to do the same as what I was doing - pay the staff. I will repay what I took in form of BBL and be at a loss for the monies I paid from my own pocket.
I am also a director of my other company taking a small salary and the rest made up in dividends. So here I got about £800 furlough payment.
So all in all I feel that I was a "Loser" of the pandemic - financially anyway - but for me its just a small time period in the book of life.
I am happy with what I did because its in line with MY morals. And after the long run up to the wicket; this is the crux of the debate. Morals are not universal and therefore can be the fuel of an endless debate.
Morally, I actually do not think any company should pay back that which it does not need to (under compulsion of the law etc). If it were my company then I would pay it back but thats just me. I do not want financial help and take great pride in working for everything I have. Disclosure, I am a lawyer and always loved the writings of the Hart and Lord Devlin debate. Should the Law enforce Morals?
My morals are not your morals; or his morals; or her morals. For me, I like to sleep at night so sticking to MY morals and staying on the right side of the law does that for me. And sure enough one day I will die (hopefully in a long time), so thats why it doesn't really bother me about repaying govn monies; I try to ask, if I didnt have my health would it bother me? And I accept that I will in effect be paying some of Vertu's support monies back by way of higher taxation.
Finally, I do believe that we should have different rates of Corporation Tax in the future. A lower rate for those that had support (and did repay) or didnt have support; and a higher rate for those that had support (didnt repay) AND had unusally high profits! For me that would be fair and the karma in action.
I think our difference in view comes from a difference of opinion in what furlough was. Some western countries chose to run a furlough type scheme and some not to but had increased unemployment payments or pandemic related payments instead.
The UK chose to put furlough in place and I think it was the right decision because it avoided the chaos from having so many people hit universal credit at once and allowed businesses to rebound quicker whenever the pandemic ended.
In effect, Vertu Motors (LON:VTU) received £27.8m from the tax payer, topped it up and paid it to those staff during the period. The employee received their pay, the government and society avoided riots and the companies had staff in place for an undefined future reopening. It was a good deal for Vertu Motors (LON:VTU) but it wasn’t free money handed to support the business. It was £27.8m sent directly to support the staff, not the business. The government also supported business but did so in the form of loans that were repayable, assuming the business survived to do so.
The people on furlough were legally forbidden to do any work for the business. This was required to avoid obvious abuses of the system but it’s key. The money paid to staff did not benefit the business in any way at the time.
Vertu Motors (LON:VTU) now is doing well due mainly to massive growth in the prices for used cars. Granted, they are better able to take advantage of this opportunity due to having trained and loyal staff they could recall as required to work in the business but they would have benefited either way from the increased prices.
The fact that competitors chose to pay that money back or that other unrelated businesses had to make capital expenditures to continue trading is neither here nor there.
There were always going to be winners and losers from the pandemic. As a winner I don’t believe Vertu Motors (LON:VTU) is morally required to repay the money government gave them to pass on to their staff. In fact, I don’t believe it is a moral issue at all. As I say, the government is free to introduce further taxes on businesses deemed to have been successful if it wishes to.
As it's a Friday evening and investors will be putting their feet up for the weekend, I thought I'd post this new YouTube talk by Michael Levin, who is a Distinguished Professor in the Biology Department at Tufts University, Massachusetts. It's unrelated to any small cap company at present and may seem totally out of place here, but I know that many Stockopedia subscribers have a scientific background and use their knowledge of relatively unknown research fields to help shape their long-term investment outlook in sectors such as biotech.
I've followed Levin's work for several years now, and although we're still in the early stages of unlocking the fascinating properties of bioelectric networks (with meaningful therapeutics probably at least a decade away), the progress his team is making is both rapid and remarkable.
If you haven't seen one Levin's talks before, prepare to have your jaw dropped in places. The implications of this research are profound, and it certainly goes well beyond the biology you were taught at school.
[Levin's talk ends at 39:27 and the questions section begins at 45:16.]
Notice given that Science (LON:SAG) have upped their holding in TP Group to 17.9%. Tanks now off the lawn onto the veranda ….
https://www.investegate.co.uk/...
Gus.
Notice given that Science (LON:SAG) have upped their holding in TP Group to 17.9%. Tanks now off the lawn onto the veranda ….
That looks like Ruffer's stake. Bought at 6.5p though, so that's now the base for a bid. I doubt existing Tp (LON:TPG) shareholders will be too disappointed.
They've also bought a few in the market.
timarr
Interesting article on the next financial crisis on Alphaville
Alphaville Further reading 20/09/21
The source is here
Original paper
Their answer (in respect of the US) is 36% chance in the next 3 years.
Not sure if that is more or less optimistic than me.
The "ahead of expectations" announcement from Vertu Motors (LON:VTU) this morning serves to further emphasise the disgraceful behaviour of the Board of Cambria Automobiles (LON:CAMB).
On 22 March, the company announced that it had consented to a "Management Team" exploring a possible acquisition at a price of 80p per share. The Management Taam comprised Mark Lavery (CEO and a 40% shareholder), James Mullins (FD), and Tim Duckers (MD).
On 17 May, it was announced that the Management Team had now become a "Management Offeror", just Mark Lavery, but that James Mullins and Tim Duckers would continue in their current roles regardless of the outcome.
On 9 June, the company announced that an "Independent Committee", comprising all directors excluding Mark Lavery, had recommended the 80p offer. Laughably, Mullins and Duckers are members of this "Independent Committee", in spite of originally being part of the Management Team putting together the takeover.
On 30 July, the bid price was increased to 82.5p.
This has gone on against a background of car dealership peers announcing record results post-lockdown. However, the Cambria Automobiles (LON:CAMB) Board seems to be deliberately trying to keep its shareholders in the dark regarding the performance of and prospects for the business. Forecasts are still suspended due to "uncertainly", a situation that seems to be unique to this company. Indeed, with only 11 days left in the current financial year, shareholders still have no indication (beyond the interims) of what the final results will look like. The same cannot be said for the "Management Offeror".
The Cambria Automobiles (LON:CAMB) hall of shame:
Philip Swatman - Chairman
Michael Burt - iNED
William Charnley - iNED
Paul Gerard - iNED
James Mullins - FD
Tim Ducker - MD
Mark Lavery - CEO
If you missed the Kenmare Resources (LON:KMR) webinar yesterday you can catch up via the recording below. The company reported record H1 results and the second half has the potential to exceed H1 as the company benefits from higher commodity prices and higher production. This all bodes well for further improvements to free cash flow and the dividend where mgmt have committed to returning at least 25% to shareholders.
Vertu Motors (LON:VTU) In a previous life I owned one or two small dealerships so I have some experience - but years out of date now. Firstly thanks Paul for the notes on the Investor Presentation. I was looking forward to watching it but after 2 attempts I found the sound quality made it unwatchable for me. Not PI World's fault as I understand from Tamzin that the sound went at the start and there was no time available for Vertu to repeat. My Impression of the TV show was that the CEO , whilst he may be an excellent data person his knowledge of the real sales process was very limited, however, I certainly would have retained all those staff as he did.
The figures for the Company certainly stack up to me - and that's what matters to us in the end.
Paul if you're a bit quieter today a look at Marks And Spencer (LON:MKS) positive trading update would be fantastic (I hold). It's obviously not a small cap but I think it does have read-across to the small cap retail sector and it is an interesting purchase idea in its own right. I've been positive on Marks And Spencer (LON:MKS) because:
The main downside, other than COVID restrictions, could be from its strategy of bringing in more third party brands. The intention here is that it drives shoppers to Marks And Spencer (LON:MKS) who then benefit from higher sales of its own brand products, but it could also mean existing customers buy more third-party product and lower own-brand product which may affect overall margins and profits.
By my calculations Marks And Spencer (LON:MKS) EPS estimate is potentially for late teens for FY22, so even after today's share price uplift this looks good value and longer term this could go back to 300p+ if store food growth and online growth for all products continues.
I know Marks And Spencer (LON:MKS) always sparks commentary about the brand being tired etc, but from an investor perspective I don't think this should be trading on a single digit P/E.
Beware periods being compared, whilst sales at Marks And Spencer (LON:MKS) clothing and home unit during the 19-week period jumped up 92.2 per cent on last year these were still down 2.6 per cent on the same period in 2019 before the pandemic. Marks And Spencer (LON:MKS) said the figures arose due to “more focused ranges, fewer promotions and a substantially smaller summer sale”.
I am not anti Marks And Spencer (LON:MKS) at all. But I just want to see the broader picture going forward.
We knew the past 6 months has been strong for retailers but what about the future? What about when there is less free COVID money around that Boris pumped out via furlough etc.
My question is this sustainable???? Buying this share now....it could drop in tougher conditions.
ONS data released on Friday showed that UK retail sales fell 2.5 per cent from June to July.
Saw this from the Marks And Spencer (LON:MKS) trading update:
"The pivot to online has continued with store sales down -19.8% on 2019/20 as many locations remain in slow recovery from the pandemic" (based on 19 weeks to 14 Aug)
No good for any retailers with a store network still heavily retail and not online? Quiz (LON:QUIZ) and Shoe Zone (LON:SHOE) come to mind.
Hi dahoko,
I'm not sure your read-across comment is accurate -
No good for any retailers with a store network still heavily retail and not online? Quiz (LON:QUIZ) and Shoe Zone (LON:SHOE) come to mind.
Quiz (LON:QUIZ) (I hold) ditched all its leases in a pre-pack administration, and signed new leases on turnover rents for the viable sites only. Hence it's ideally set up, with rents that flex up and down according to revenues. In my experience (I used to manage the finances for over 50 sites on turnover rents), this brings the breakeven point drastically lower.
Also QUIZ has a well developed online offering, which has been doing quite well for years. It was hit particularly hard by its specialism in special occasionwear, but as special occasions are returning, then so should its business.
Shoe Zone (LON:SHOE) - probably a fairer read-across candidate. Although it does have a flexible store estate, with short leases. Online sales are too low to make me want to touch this share. Also, no prospect of divis for several years, and overly dominant founder shareholders.
Another factor to think about, is the high cost of bringing in physical goods from the Far East. The current price spike from c.$1,500 per container to about $20,000 per container is proving a nightmare for many companies, especially smaller ones, who can get pushed out by demand for the biggest companies.
In the case of SHOE, it brings in cheap but bulky items (shoes, in boxes) from China. So that must be a major cost problem for them right now.
Whereas Hotter Shoes (part of Electra Private Equity (LON:ELTA) - I hold) imports the components flat packed, and then assembles them in the UK - meaning that, per container, Hotter will be able to bring in a very much higher end product value, than would SHOE.
I feel the current problems with freight, plus the shortage of UK lorry drivers, could be laying the ground for a season of profit warnings from the many companies which have foolishly become far too reliant on China supply chains. Even those that source closer to home, may have problems getting the product to the end customer.
So time for us to do that Christmas shopping early this year, rather than leaving it to a midnight petrol station dash on Christmas Eve, as I usually do LoL!
Best wishes, Paul.
Yes there are real problems with deliveries, some pubs are having to close because they have run out of beer, things will get worse if a haulage strike goes ahead.
Indeed, good point on Quiz (LON:QUIZ) that I'd forgotten, that they'd moved to revenue based rents. Hopefully with no minimum floors that are too high.
Shoe Zone (LON:SHOE) does look like up against headwinds this year. Rents, shipping costs, and also business rates. They did a big rant on them last autumn, so presume they are a big thorn for them.
Hi Paul,
Are you considering topping up your Cambridge Cognition Holdings (LON:COG) position? Is sub 150p a "cheap" price?
Hi Josh
How are you assessing Cambridge Cognition Holdings (LON:COG) what is your thoughts on the current price and future prospects, how do your numbers work out?
Cheers
Tommy
Hi josh,
I'm not interested in doing ongoing commentary about my portfolio, shares & price movements. Decisions to top up, top slice, etc, are personal to everyone. I just review the trading updates & results statements here. COG remains one of my core long term holdings.
Paul.
We hold. Very experienced management team and agree with Paul, Vertu is the pick of the bunch on balance sheet strength. Add on off days.
Hi Paul thoughts on Marks And Spencer (LON:MKS) trading upgrade, read across for J Sainsbury (LON:SBRY) and Tesco (LON:TSCO)
I'm on a tight schedule today, so won't have time to comment on any large caps, sorry. There's plenty of commentary available elsewhere about companies like MKS, SBRY (I hold) and TSCO (I hold) from the many brokers that cover them.
My morning smallcap tweet: Boiling up the bones of briefings
Tiziana Life Sciences (LON:TILS) Vertu Motors (LON:VTU) Colefax (LON:CFX)
Tiziana Life Sciences (TILS) to delist and be directly listed only on Nasdaq. [SP=58 Cap=155m]
Vertu Motors (VTU) revs up FY(Feb22) pretax guidance to £50-55m (previously £40-45m) as strong used vehicle gross margin retention continues. The 3rd upgrade in 3 months. £3m buy-back. Will resume divs. [SP=46.76 Cap=173m]. I hold.
Colefax (CFX) will tender for 14% of shares at the lower of: 615p or 105% of average closing mid-market price over the five days before the Take-up Announcement Date. [SP=565.5 Cap=51m]
Shame about Tiziana Life Sciences (LON:TILS) as I hold in my SIPP and cannot hold Nasdaq shares as far as I am aware (certainly cannot buy/sell them online).....now got to decide when to sell.
Shame about Tiziana Life Sciences (LON:TILS) as I hold in my SIPP and cannot hold Nasdaq shares as far as I am aware (certainly cannot buy/sell them online).....now got to decide when to sell.
and/or move to a better SIPP provider? No good reason NASDAQ shares should not be tradable.
Vertu Motors (LON:VTU) has increased guidance again. Now expects £50 million in profit for the first half up from £40 million 3 weeks ago.
Still seems overly cautious for the second half so could see further upgrades imo.
Also starting a share buyback programme.
I hold.