Small Cap Value Report (Fri 20 Dec 2019) - FLK, UCG, TRD, BKS, GDWN

Good morning,
There's quite a few things to catch up on today. I will probably write through the afternoon.
There are updates from Fletcher King (LON:FLK), United Carpets (LON:UCG) and Triad (LON:TRD) - these are all sub-£10 million market cap, but I plan to cover them briefly.
Also:
- Beeks Financial Cloud (LON:BKS) (added this in response to reader comments)
- Catalyst Media (LON:CMX)
- Focusrite (LON:TUNE)
- Warpaint London (W7L)
And from yesterday:
- Goodwin (LON:GDWN)
Please bear with me while I work through this!
Cheers
Graham
Fletcher King (LON:FLK)
- Share price: 42p (-3.5%)
- No. of shares: 9.2 million
- Market cap: £4 million
This tiny property company has occasionally looked like an attractive "value" investment, available to purchase at a discount to tangible book value.
It provides a range of property services, including the management of small property funds, and invests in its own funds.
These H1 results show a fall in revenues to just £1.3 million, giving rise to a small pre-tax profit of £108k.
At least this is better than the pre-tax loss that was suffered in H1 last year.
Performance reflects "the subdued property market associated with uncertainties over Brexit and the UK political situation".
Sales and lettings were "severely impacted", and decisions were put on hold due to political uncertainty.
Commercial property investing reached a 5-year low, and this situation helped to bring about the suspension of M&G's property fund.
As others have already said, I think the clarity that the economy might enjoy in the next few months could trigger quite a lot of pent-up activity - we shall see!
On the bright side, for FLK:
Steady and predictable revenue from asset management clients provides ongoing support for the business along with a regular supply of valuation instructions from lending banks.
Outlook statement concludes by saying that no clear guidance can be given:
Although the political climate is now clearer, it remains hard to predict the final outcome for the rest of the year and our previously stated views on the difficulty in maintaining profitability remain.
My view
This is valued at approximately its book value (£4 million, mostly consisting of cash and financial assets). That strikes me as fair value, although the StockRanks are more impressed, giving it a StockRank of 86.
Some interesting facts: this company's share count has barely changed in 30 years, and the Chairman (who surname is in the company name) owns 15%. These are the sort of things to look out for in a "safe" or "value", conservatively-run microcap.
Edit: I've just tried Stockopedia's new "Major shareholders" facility. Huge congrats to the team for getting this feature set up!
This is what it looks like for FLK:
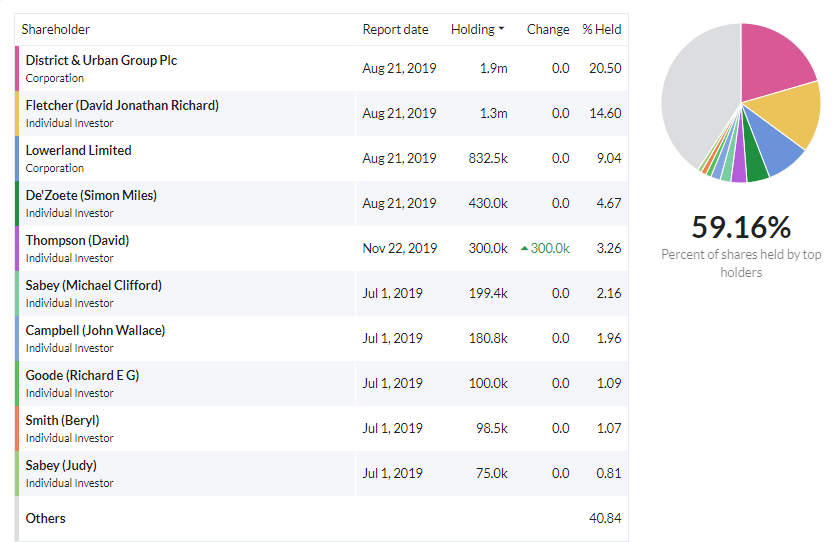
What an attractive way of presenting this data. It was worth the wait!
To get this data for any share, go to "Accounts - Major Shareholders" from the StockReport, on the new site.
United Carpets (LON:UCG)
- Share price: 5.5p (+5%)
- No. of shares: 81 million
- Market cap: £5 million
United Carpets Group plc (LSE: UCG), the third largest chain of specialist retail carpet and floor covering stores in the UK, today announces its interim results for the 6 month period ended 30 September 2019.
I owned shares in this before, and lost money on them. The experience helped me to give up on investing in "cheap" retailers. It also created in me an allergy when it comes to floor covering shares in general.
If you check out the history of this share, you'll see that it sort of went bust in 2013, but the franchise model saved it and UCG shareholders avoided ruin. The franchise model continues to be something that is of interest to me.
These H1 results are "ok" - there is a small profit before taking IFRS 16 into account.
IFRS 16 front-loads lease expenses to the start of their term. This effect unwinds as leases expire.
So when UCG takes IFRS 16 into account, the result for the period is breakeven, rather than a small profit.
CEO Paul Eyre (click here for 1990s vintage advertising!) has the following remarks, after revenue increased by a remarkable 36%:
the Group generated a significant increase in revenues, primarily driven by a small increase in the average number of stores trading compared to the prior period and the Group's fledgling instalment payment model, a new business channel for the Group with the potential to become an important future profit centre.
Instalment Sales
The new instalment payment channel is being treated separately to the existing operations. It targets "a different customer base" and offers "a separate, limited range of products". Customers pay weekly on an interest free basis.
I've noticed a few funny things about this:
- £770k of these new instalment sales had to be written off during the six-month period, due to customers defaulting - that's 15% of UCG's market cap!
- The impairments are also very large when you consider that total instalment sales during the six-month period were only £2.2 million. A very large percentage of customers must be defaulting!
Outlook
While like-for-like growth in the core retail/franchising business was 1.8% in H1, things have deteriorated since period-end:
For the business to flourish requires a positive market environment which has not been the case for some time alongside the ongoing political uncertainties which has unsettled consumer confidence and also the housing market. In the face of further Brexit uncertainty and a snap General Election, the important trading period since 30 September has proven to be more difficult with like for like sales for the 11 weeks since the period end 3.5% down.
While the Board remain confident in the United Carpets model, the outcome for the full year could be significantly influenced by the ultimate conclusion to Brexit and also in the event of any prolonged period of significant adverse weather conditions. The Board therefore remains cautious over the outcome for the full year.
My view
I still find this one interesting, and the results aren't too bad. The 36% revenue growth is very interesting, although the impairment of instalment sales and the set-up costs for that division held back profitability.
I would probably "punt" on this company and its ability to make a success out of instalment sales, if my portfolio had a section of it that was devoted to punting.
But the impairment numbers are scary, and I think the company is being brutally honest when it says that it needs a positive environment to do well.
In a recession, with depressed consumer sentiment, I expect that its franchisees will run into trouble again, just as they did in 2013.
Ultimately, this one is operating in a sector (cheap floor coverings and beds) that is too cyclical and too competitive to enable me to sleep well at night. For these reasons, I'm out!
Note that it has a StockRank of 98, so it is primed to do extremely well from a statistical point of view.
Triad (LON:TRD)
- Share price: 35.3p (-14%)
- No. of shares: 16 million
- Market cap: £6 million
This is a staffing/consultancy business that has slipped into the red in the latest H1 period.
I've written about it before, saying that it held little appeal. Probably not worth bothering with - let's move on.
Beeks Financial Cloud (LON:BKS)
- Share price: 107p (+19%)
- No. of shares: 51 million
- Market cap: £54 million
Thanks to readers for alerting me to this one - I missed it on my initial skim of the RNS. And well done to anyone who bought into it recently. I don't normally comment on contract wins, but let's take a look:
- The first contract is a "SaaS-based contract" that "will commence in January 2020 and is committed to grow to a run rate of $1 million annually, with the potential for further expansion thereafter.
A few quibbles - does this mean it's not starting at $1 million, but will grow to $1 million in a few years? What level does it start at, and when will it reached $1 million, I wonder?
The description is promising. The customer is a "global financial markets technology provider", for whom Beeks will be "the preferred cloud vendor".
- The second contract is worth £1.1 million over 3 years. It's in a new sector, "Open Banking and Payments".
The customer for this one is a "cloud-based payments solution provider", for whom Beeks will "design and supply a private network and fully managed infrastructure environment". It's hard for me to visualise this, but it certainly sounds impressive!
My view
I can't see any upgrade to forecasts, yet, from the likes of Progressive Equity Research or the company's broker, Cenkos. The share price reaction today does suggest that upgrades are expected.
Existing forecasts are for net income of £2.2 million in FY June 2020, followed by £2.9 million in FY June 2021.
As noted previously, I don't understand what the barriers to entry are in this field (cloud computing, with servers near financial exchanges). But Beeks deserves credit for achieving a very nice growth trajectory in recent years, so its above-average earnings multiple might be justified.
Stocko is perplexed, only giving it a ValueRank of 6.
Goodwin (LON:GDWN)
- Share price: 3139.5p (+7.5%, recovering some of yesterday's fall)
- No. of shares: 7.2 million
- Market cap: £226 million
Let's go straight now to Goodwin, since it's a company that many of you hold. It reported half-year results yesterday. I've never written about it before.
The results were met with dismay, and the shares finished minus 17.5%.
Revenue was up 3.8% but profits fell 5.1%, and I don't think that IFRS 16 can take any of the blame. Footnote 5 isn't very clear to me, but I think it implies that there was only a marginal impact from the implementation of the new accounting standard.
Goodwin is a mechanical engineering business with 1,000 employees and a large collection of operating subsidiaries engaged in casting, machining, making valves, pumps, cement, etc.
If we consult the new major shareholders section on the StockReport, we can see lots of involvement by the Goodwin family. That's good - they are likely to have a great sense of stewardship.
If I scroll through the archives, I see something remarkable: the company hasn't increased its share count or reported an annual loss for 30 years.
Companies with track records like this tend to be extremely attractive investments. Indeed, patient long-term shareholders in Goodwin have done very well.
More recently, things have been a little more difficult. Reduced profitability "is a feature of the disruption caused by the commotions in our parliamentary system over the past six months where the uncertainty has temporarily stalled projects."
I'm not sure if I can follow that explanation, seeing as revenues were higher - if revenues were higher, then why can't profits go higher, too?
Key points for the 2020/2021 outlook:
- profits to be flat in H2 (i.e. from now until April 2020), but cash flow to improve
- the company expects the demand for energy to increase, thanks to growth in developing economies, and this should boost the mechanical engineering division
- Radar systems subsidiary gets its first foreign order for surveilliance systems
- demand for jewellery has declined, which hurts demand for the casting powder which Goodwin suppliers. This market is "beginning to improve"
My view
Firstly, I need to concede that I don't know too much about this company. There are lots of subsidiaries to keep track of - too many, for my liking.
But I can't deny that it appears to earn its cost of capital with ROC of 12.5%, according to Stocko.
And I like to see family businesses which are profitable for extremely long periods of time, with the family maintaining its involvement.
Net debt of £27 million appears to be manageable. Banking headroom is said to be "significant".
I'm happy to give this a cautious thumbs up, based on an initial look.
That's all I can handle for today - have a good weekend everyone.
Cheers
Graham
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

35 comments
A big thank you to Graham, Paul and contributors to SCVR. I started out as a knee-jerk investor and understandbly lost out, but things have changed for the better since I subscribed to Stocko and started following the reports and other articles here. I am now more patient and do my research before I put my cash down. Not saying that I am successful everytime but the failure rate has gone down considerably.
Stockopedia is a wonderful piece of software, so thank you Ed and team!!
Merry Christmas and a very happy 2020.
My fiver's in the post! LOL only joking ;-)
This was certainly an exciting morning for me so close to Christmas with major news from Beeks Financial Cloud (LON:BKS), Triad (LON:TRD) and United Carpets (LON:UCG) .
In my view (and according to my model) the Beeks news really transforms their outlook. I covered the news in my blog at lunchtime, but am now writing another piece trying to explain their business model, specifically to address very reasonable questions that often come up like that asked by cmpeckham above. To this end, if you have any questions feel free to message me on twitter (I am open to message requests) or elsewhere. I'll be posting the article first on Stockopedia on this occasion.
Triad is a company that I know a lot about but am less inclined to discuss publicly - feel free to message me with any questions though (during working hours).
On the subject of United Carpets (LON:UCG), I think this whole sector has been hit by the tax increases on private landlords. These people are now pulling out, so they are no longer putting in new cheap carpeting, from the likes of United Carpets (LON:UCG), every time there is a tenant change. I don't see this as changing any time soon. Selling cheap carpeting on installment plans sounds like desperation. I suspect those firms with more business in larger fit-outs, or in more up-market floorings, will do a lot better over the next few years.
It's a shame Graham moved on so quickly from Triad (LON:TRD), since I was really looking forward to his comments on this random paragraph that appeared in the commentary:
"In addition to these relationships, we will be announcing partnerships in the Robotic Process Automation arena and the Blockchain sector."
Those words certainly moved me - all the way to my online broker to hit the sell button before even reading further.
My summary - they're expanding headcount whilst business is reducing and making optimistic noises, whilst sitting on a large enough cash pile to maintain the interim divi despite the loss in the half. Could either go very wrong, or if they get it right could be very cheap.
Morning guys. A company I follow but haven't invested in is Renewi. They have announced that the Dutch authorities have lifted a ban on thermally treated soil today after a period of testing. Mkt Cap circa £200m so should fall in your remit (although Enterprise value sigificantly higher as can be exected with these capital intensive businesses) and their share price has responded from the doldrums. Lumpy contractual stuff but in an increasingly popular sector recycling waste. Stocko has it as a 63 largely driven by value 90. Bal Sheet not good. On cash accruals screen.
the issue with the Dutch is totally political. There is nothing wrong with the soil, all tested but the politicians needed a way out! I met the CEO some months ago. Will go for a Euronext quote in 2020 I guess.
Fletcher King (LON:FLK) also buy, refurbish, tenant and then sell on office blocks. They currently have one on the blocks. It seems rather profitable, and generally results in a handsome special dividend.
Maybe the wrong place to post this, if so apologies, but Andrew Bailey confirmed today as new governor of Bank of England. Awful decision as far as I'm concerned, he's done absolutely nothing to help/protect individual investors in his current or previous jobs. The lastest, in a very long list, is current failure to do anything to stop advertising for very riskY and unsafe "mini bonds" to all an sundry.
Hi - Any chance you can comment on Accsys Technologies (LON:AXS) - accsys - They have just successfully over-placed new shares at 105p to raise approx £45m - when the price has been well below this for some time - and still is...? What am I missing..?
Probably not missing much. There have been some recent threads and some good points made by people knowledgeable of the industry.
I’ve followed this for a while. It seems a good product but possibly limited by production capacity and manufacturing requirements.
New plants will take time to prove that this is a volume product – hence slow progress.
The Accsys Technologies (LON:AXS) offer for new shares was at EUR 1.05, which is about 89p.
With a huge spread, little liquidity and uncertain profitability, what are the attractions of Fletcher King (LON:FLK) ?
re: Fletcher King (LON:FLK)
The attractions are mostly just the assets, plus a track record of making small profits and paying small dividends. So it trades at book value!
I can get assets at book value and a small dividend from a bank account - and that offers a zero spread and complete liquidity!
Too true, FREng. The yield at FLK is 4% which is certainly not enough to entice me (edit: as pointed out above, you do occasionally get a nice special...)
Two big announcements today for me
1) Beeks Financial Cloud (LON:BKS) these additional contracts make for very good reading. Firstly, the more Tier 1's you sign up the more likely others also sign up. ie you quickly become accepted and the procurement process becomes vastly quicker. Comfort in numbers. I know this from personal experience with them. Secondly they have just added a new market segment in Open Banking and Payment solutions. This was unexpected. I remember Graham questioning how they would grow (or when they might reach saturation point) and whilst I was comfortable there was plenty of room in the existing model I am now very pleased to see the additional high revenue potential markets they can expand their infrastructure into. This years results were already under-pinned by recurring revenue to the tune of 85% at the start of year so I think these two contracts now probably significantly de-risk next years numbers of around 5p EPS. Given the growth, market segment expansion and tier 1 momentum building 20* earnings looks pretty good value to me.
2) Immotion (LON:IMMO) is starting to look like a really interesting stock. I'm surprised by the price reaction. Breakeven in Q1 of 2020 and looks like they go into that quarter with ARR of circa £8m+ and a small profit for the year of 0.3p EPS according to brokers. For a market cap of £17m this looks like it could have a very nice future in an expanding market, so I am thinking of now buying. I prefer businesses to be moving into profitability, which this clearly is. If you believe broker forecasts then eps of 1.4p in 2021. I am minded to think this may be optimistic as it assumes high revenue growth but that puts it on a fwd PE of 4 !! Management has a successful track record too so I rate them. The only thing that slightly nags at me is whether VR is "moatable". It feels to me as though first mover advantage (especially in the aquarium space) is key to longevity as once aquariums have them installed and are making money from them would take a lot to uninstall and replace, but maybe I'm wrong. Clearly content is also king and they appear adept at that so maybe that's another small moat? Be interested to hear anyone else views before I make the leap...
Beeks : odd how the CEO sold 2.6m shares at 84p recently. I met the guy at the Mello before last and was impressed with the hedge fund service he provides. The bigger he gets the more attractive a target Beeks becomes. Perhaps Gordon bought a new town to launch on Loch Lomond.
CEO sale at Beeks Financial Cloud (LON:BKS) was small, relative to his holding.
Hi Graham,
Mattioli Woods (LON:MTW)
Mattioli Woods has announced an acquisition today. They have bought The Turris Partnership for £1.6m. Assets "under advice" - £65m revenue £450k, profit before tax £150k. Apparently earnings enhancing in the first full year.
Do you have any guidance for us on how to value an acquisition in this sector?
morning, question on £W7L. ... earlier this year they bought one of their foreign distributors. Tim Steer mentions this as a "red flag" for short selling in his book. But doesn't explain why this often boosts profits (artificially). Can anyone explain? Is it to do with valuation of inventory? Thanks!
Bruce
There was a statement to this effect in the subsriber comments under a recent SCVR - probably within the past week. Something to do with bringing the receivables from the distributor into inter-group debts, I half recall (but can't currently see how that helps boost profits).
Re: why is buying a distributor a red flag?
As Freng says, this was mentioned recently and someone probably gave a different/better explanation than I am capable of, but:
There is a practice known as "Channel stuffing" see:
https://en.wikipedia.org/wiki/Channel_stuffing
which inflates profits on a temporary basis. Unless they keep stuffing, this artificial boost to profits will unwind. But if they buy the distributor holding the excess, then the future downward adjustment to sales will be hidden within the newly combined company. If the sales were going to turn in to a bad debt and so be written off against profits, then that will not now happen, but of course the underlying problems haven't really gone away, they've only been compounded. There may be other reasons that others could add ...
I brought this up the other day and cmpeckham has done a good job of explaining an aspect of why this can be a red flag. In my view the key issue is that when a distributor is external then the outstanding receivables amount is shown in the accounts - and you can see whether the debtor level is rising, whether it's being written off and so on. Actions taken in this area can boost sales in the short term but will eventually have to unwind.
However if you buy the distributor before recognising that the distributor has too much of your stock then you can avoid (to some degree) unwinding this excess stock in public. And even then if you do have to write off some of your stock then this will take place in the future a fair while after profits have been inflated.
Note that this is just my take on things - I'm not an accountant!
Thanks - if you've got a link to the comment I will have a look. I imagine you could make a fair value adjustment (write down) the inventory of the distributor on acquisition. The tangible assets would be lowered, and the goodwill would be higher. But it would mean that you wouldn't have to write off your own receivables, they would just be captured in the goodwill that you (over)paid for the acquisition?
Anyway - buying a distributor does seem to be a "red flag". Thanks for your comments. And do post a link to the original discussion if you can find it.
Thanks Bruce. Looking back we were talking about Tristel (LON:TSTL) here: https://www.stockopedia.com/co...
Blue Whale Capital's, Stephen Yiu, answers investors' questions.
https://www.piworld.co.uk/2019/12/20/blue-whale-qa-december-2019/
Covering such issues as opportunity cost of holding cash, the influence of fluctuating exchange rates, the turnover of stocks in the top 10, and much more.
Graham , I would just like to say thanks to both you and Paul for the time and effort you put into these reports. I'm not from an accounting background so your analysis really helps me to understand how to look at the narrative and figures in updates. I also enjoyed your northamber write up. The contributions from far more knowledgeable members than I also really add value. I wish you all a Merry Christmas.
I'd like to echo this sentiment completely. It's been a rocky 2019 for the markets, and Paul, Graham, and the rest of the Stocko Team (particular thanks to Ed) have helped us get through it, undoubtedly in better condition than we would have done without them.
Everyone have a great Christmas and new year, and let's ask the universe for better conditions in 2020.
Chris x
Much appreciated, Phil.
A couple of good contract win announcement this morning for £BKS.
The company themselves describe them as significant with one of them expected to be their first contract over $1m a year.
Whilst clearly this is very good news for those of us waiting for these type of announcements (I am long on BKS) this is to some extent factored already into its SP. The key thing for the company though is continues to enhance their capabilities to other potential clients and can develop a nice snowball effect over time.
I continue to remain optimistic that this is a very good long term play although I do expect at some point if they do develop a nice niche someones going to come along with an offer they can't refuse.
Re: Beeks Financial Cloud (LON:BKS) please help me understand one thing: what is it that they actually own that confers them with a competitive advantage? Do they actually own physical space in the critical place, or is this space just leased? How do they own it if it is in the same location as the critical servers? If leased, what is their long term moat?
It's probably an ignorant question but someone's help will be appreciated.
cmpeckham --- I also would like to know if there is a source of long-term competitive advantage at Beeks. It's not an ignorant question, it's a great question! G
Hi, there's an excellent video on PI World where Beeks Financial Cloud (LON:BKS) explained what they do at one of the Mello meetings - https://www.piworld.co.uk/2018... - which I think you may find answers at least some of your questions.
My morning smallcap tweet: Warpaint battles headwinds.
Beeks Financial Cloud (LON:BKS) Falanx (LON:FLX) £W7L Iofina (LON:IOF) Nanoco (LON:NANO) United Carpets (LON:UCG) Immotion (LON:IMMO) Benchmark Holdings (LON:BMK), Hermes Pacific Investments (LON:HPAC)
Beeks Financial Cloud (BKS) Wins additional Tier 1 customer and enters Open Banking and Payments sector - contacts worth $1m and £1,1m.
Falanx Group Limited (FLX) gets shot of lossmaking Furnace business for £1.1m, to be funded by an unsecured 5 year loan note (at 5%) plus 20% of the shares in newco. Pretty easy terms.
Warpaint (W7L) guides FY rev in line but adj pretax £5.1-5.5m. Previously expected £6-7m. Blames FX, margin mix. Joint CEOs changes to CEO + MD.
Iofina (IOF) FY trading sounds in line. "Directors are diligently exploring various options regarding debt restructuring and are confident of a solution in H1 2020." Diligently? Don't they do everything diligently?
Nanoco Group (NANO) sale talks continue, continues to review possible sources of additional funding. I'm short.
United Carpets Group (UCG) H1 in line but recent LFL -3.5%. Blames weather, political uncertainty.
Immotion (IMMO) guides FY rev £3.6-£3.8m, towards lower end of expectations but underlying EBITDA loss in line.
Benchmark (BMK) FY presumably in line with FY trading stmt. Outlook: guides FY adj EBITDA flat. "Weakness in the shrimp and sea bass/sea bream markets continues and while some recovery is expected, it is unlikely to recover to 2018 levels in 2020."
Hermes Pacific Investments (LON:HPAC) in line.