Small Cap Value Report (Wed 18 Dec 2019) - FRAS, SDI, TSTL, STAF, 600, GRC, MIDW, BIDS, PRES, SYM

Good morning, it's Paul here!
I'm up early today, so thought I'd start with some brief comments on a couple of interesting company updates from yesterday, that Graham missed due to focusing on a macro ramble instead.
Estimated time of completion: 3pm
Update at 14:46 - today's report is now finished.
Sports Direct
Name change - it's now to be called Frasers. We saw a staggering rise in share price this week, to about 470p. That means if has more than doubled since the low of about 220p just 5 months ago. Whoever said that elephants don't gallop, was wrong!
The narrative with its interim results was interesting. A bit like Tim Martin of 'spoons, Mad Mike Ashley obviously revels in his outspoken, unorthodox way of doing things. Both are brilliant & talented entrepreneurs, so personally I think they've earned their stripes, and should continue saying whatever they like, in whatever style they like.
The one thing that does irk me, is that Ashley gave the impression from previous trading updates, that buying House of Fraser had been a terrible mistake, indeed he even referred to its problems as "terminal". Therefore, investors assumed that this was bad news for the company & its shares. Along with a catalogue of other bad buys - such as Debenhams (where he lost out to hedge funds, and has choice words to say about that too!), Goals Soccer Centres, and other sometimes rather stupid mistakes.
The latest update this week, seems to be now talking up House of Frasers somewhat, with green shoots and being integrated into the larger business, in IT, supply chain, etc. Changing the group name to "Frasers" does rather suggest that House of Fraser is now an important part of the group's future.
Narrative matters, but it's the numbers which matter more. There's an updated broker note on Research Tree, which I'm looking at, showing huge increases in forecasts - e.g. 43% increase in current year EPS, and EPS for next year going up from 19.3p to 30.3p, up 57%.
These are extraordinary forecast increases, for a mainstream retailer of this size. Therefore the dramatic re-rating in share price looks fully justified to me.
SDI (LON:SDI)
Share price: 75p (up 3% yesterday, at market close)
No. shares: 97.2m
Market cap: £72.9m
SDI Group plc, the AIM quoted group focused on the design and manufacture of scientific and technology products for use in digital imaging and sensing and control applications... for the six months to end October 2019.
For clarity, I like to see the company description separate from the trading performance, so I split out the first paragraph summary, which said;
... is pleased to announce another strong set of results and solid operational progress...
Highlights section looks good (my comments are below). We should always keep in mind that many companies let their PRs run riot here, and cherry-pick the best bits only! So we still have to check the full numbers below. I've lost track of the number of occasions where I've impulse bought shares at 8am, only to find that I missed something important further down in the announcement which negated the buy decision. It's strangely difficult to sell though, even if you do realise you've made a mistake - that's one of the nasty emotional factors that undermine our investment performance.
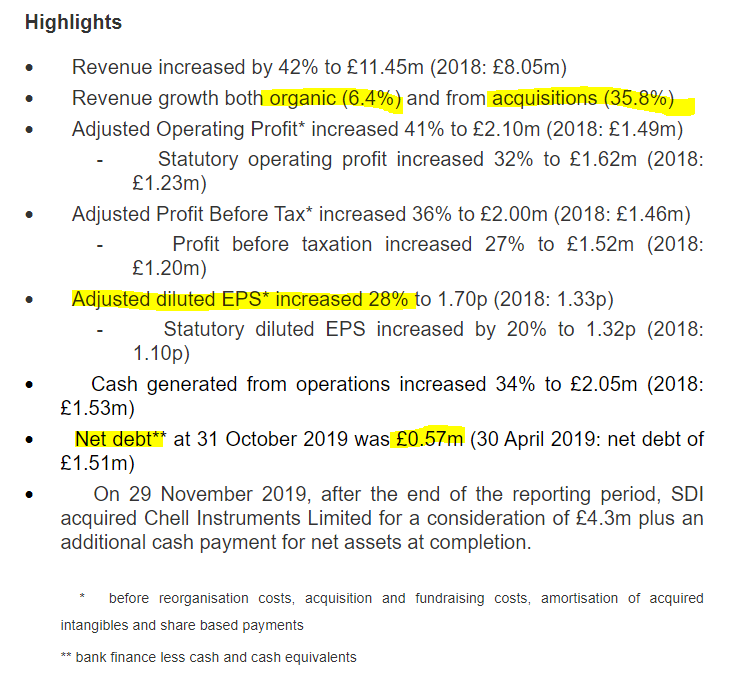
Most of the growth has come from acquisitions, but 6.4% organic (revenue) growth isn't too shabby either. I would like it if the profit growth were also split out re organic & acquired, as they're not necessarily the same thing.
EPS growth of 28% is lower that 36% profit growth. That's either because more shares have been issued, or the tax charge has risen disproportionately high. Checking the StockReport, it does seem as if SDI is quite fond of issuing new shares. The average share count has risen from 24.5m in 2014, to 97.2m now. Although since the share price has risen 10-fold since the low in Apr 2015, then it seems as if SDI management has used the new equity very wisely, in what must have been some excellent acquisitions.
Net debt - is minimal, which is reassuring. So many acquisitive groups load up with too much debt, and come a cropper. No such worries here, even allowing for the post period end acquisition noted above.
Outlook - is only in line, so that probably means limited scope for further share price appreciation, perhaps? Once the PER is knocking on the door of 20, then I feel companies really should be beating, rather than just meeting expectations.
The Group has made a good start to the financial year. Despite the potential for economic variability, influenced by political conditions (including Brexit) and currency fluctuations, the Board is confident that our diversified portfolio of businesses is on course to deliver a full year financial performance in line with market expectations.
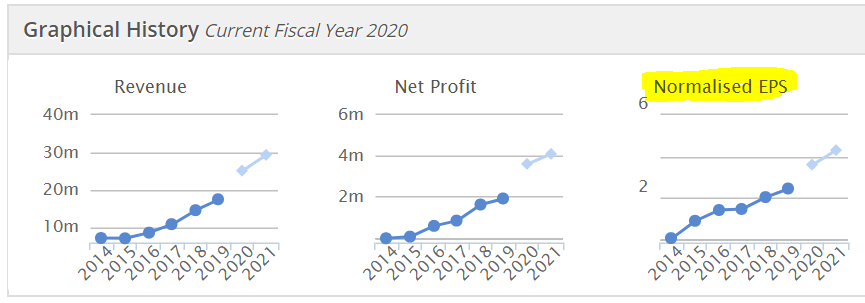
Valuation - forecast EPS is 3.6p for FY 04/2020, for a PER of 20.8 - getting a bit warm. Although, given the excellent track record on EPS growth (see graph below), then I can see why investors have rewarded the company with a higher rating.
That in turn allows the company to issue more paper at a decent price for future acquisitions. After all, if you can acquire a company on a PER of 12, and pay for it using paper you've just issued on a PER of 20, then that's good business, and drives up the share price further - providing none of the acquisitions go wrong.
Balance sheet - looks OK overall. However, one criticism is that the company has adopted IFRS 16, and lumped lease liabilities in with bank debt, calling it "Borrowings". That results in net debt looking as if it's £3.08m.
Of course, in the real world, lease liabilities are not debt at all. They don't carry interest, don't have covenants, and cannot be withdrawn (unless the tenant defaults on rent payments). Lease liabilities are actually future rental costs of buildings, as we all know. That is completely different in nature to bank debt, hence if we must have IFRS 16 figures, then they should at least be clearly marked on the face of the balance sheet, in my view. Many companies are displaying them separately, which is good.
Here, we have to rummage around in the notes to get the real world picture, in note 6.
Cash is £2,727k, and bank debt is £3,300k (drawn from a £5m facility with HSBC expiring in April 2023. This has been increased to £9.8m post period end). Therefore net debt is £573k, which ties in with the net debt figure shown in the highlights section of the RNS.
My opinion - I like the look for the figures, and the excellent track record of this group.
The latest acquisition looks sensibly priced, and is profitable.
Overall, it looks good, and warrants a thumbs up from me. Obviously, that's just my personal opinion, it's not any kind of recommendation. Subscribers should always do your own research, as I don't have time to go into the detail that a purchase would require.
Tristel (LON:TSTL)
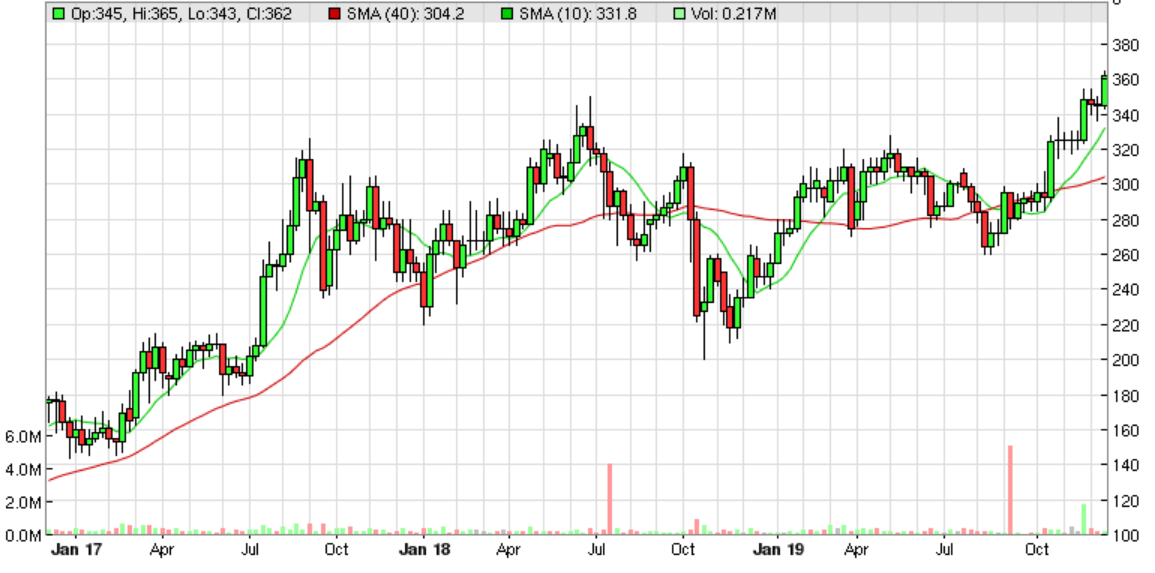
Share price: 362p (up 4% yesterday, at market close)
No. shares: 44.7m
Market cap: £161.8m
Tristel plc (AIM: TSTL), the manufacturer of infection prevention products...
At the AGM, this update was given;
"We expect unaudited pre-tax profit (before share-based payments) for the first half to be no less than £2.8 million, compared to £2.4 million for the same period last year. The expected pre-tax profit includes a positive contribution from our operations in Belgium, the Netherlands, France and Italy which were all acquired during the past year.
The Company is performing in line with management's expectations and our United States regulatory approvals project is progressing well."
A fairly modest rise in profit, at least some of which has come from acquiring its overseas distributors, doesn't strike me as particularly good. Not for a stock which is now rated very highly, on a forward PER of about 30. I would have wanted to see more than that, if I held this stock, at such a high rating.
Don't get me wrong, it's a very nice little business, with a strong track record of growth. I'm just questioning why it's valued so highly, when the products seem very niche (only small sales in each country)?
USA market - this is probably the answer, as it would clearly be a huge addressable market, once regulatory approvals are granted.
My opinion - nice company, but looks very expensive. There's no scope for any disappointment at this level. The US market is obviously very interesting. In such a litigious environment, I can see why a specialist disinfecting product might have more appeal, and achieve higher sales than the small amounts achieved in other geographies. Maybe, who knows? I wonder what the company's sales strategy in the USA is going to be? Presumably it will have to be via a distributor, due to the marketing costs otherwise being too high to sell direct.
Staffline (LON:STAF)
Share price: 106p (at close last night - likely to fall considerably today)
No. shares: 68.9m
Market cap: £73.0m
(for the avoidance of doubt, I do not currently hold this share)
Staffline, the recruitment and training group, provides the following update on Group trading and outlook.
Directorate change - whenever I see trading update, and a directorate change RNS come out at the same time, then it's nearly always a profit warning & either the CEO or CFO being fired.
In this case, Mike Watts, the CFO, has been fired. He is thanked - to borrow MrContrarian's phrase! Looking at the other RNS out today, the profit warning, I can see why the CFO had to go - more accounting irregularities are disclosed, as well as a profit warning.
He joined as a divisional CFO in 2017, and went up to Group CFO in Jan 2018.
Trading update (profit warning) - poor trading in Q4 means reduced profits for FY 12/2019. Helpfully, the damage is quantified, so we can work out revised valuations;
Given the challenges to trading in Q4, the Board now expects the Group to deliver full year adjusted operating profit (being profits before interest, tax and non-underlying charges) for the period ending 31st December 2019 of approximately £10 to 12 million.
The most recent forecast I can find, from Sept 2019, is in a broker note on Research Tree. This shows forecast adj EBIT (which is another name for adj operating profit) of £18.0m. Therefore this is a £6-8m miss, or 33-54% miss. Coming late in the year, that means that Q4 would proportionately have been worse than this. On the other hand the percentages look large because the company is now not that much above breakeven.
Another lurch down in share price today looks inevitable.
Is it going bust? That's the key question whenever companies repeatedly warn on profits. STAF has a weak balance sheet, but it did an emergency fundraising earlier this year, at 100p, which improved things somewhat, but not enough in my view.
Today's announcement reassures to some extent;
The Board expects year end net debt to be approximately £50 to £55 million, in line with current market expectations.
Staffline maintains a constructive relationship with its lenders and consequently the Board does not anticipate any covenant issues over the year end.
Furthermore, the Company is considering certain strategic options which may significantly reduce net debt during H1 2020.
I reckon that last paragraph probably refers to doing some kind of deal with its large Singapore-based shareholder, which operates a highly profitable & cash-rich staffing business. Perhaps a placing, convertible loan, or some other fundraising, to shore up Staffline's finances? The trouble is, that may be disadvantageous to other STAF shareholders, particularly small investors. After all, why would the Singapore investor want to be kind to other shareholders?
EDIT: Liberum points out that Staffline could sell its Irish business, to reduce gearing, in a fresh note that's just come out. End of EDIT.
Notwithstanding the current short-term trading challenges, Staffline remains a cash generative business, is one of the most financially robust operators within its immediate peer group and continues to benefit from considerable liquidity headroom.
Accounting irregularities - remember that Staffline shares were suspended in early 2019 due to discovering accounting irregularities re minimum wage regulations.
Today it announces that more problems have emerged - of £4m, this time relating to costs not being correctly booked. So possibly an error, but possibly fiddling the figures, as that's a lot of costs to overlook.
It creates the impression that STAF's internal controls are still not up to scratch. It's quite a sprawling business, with lots of moving parts. But even so, it's the finance department's job to keep properly on top of everything. And the CFO's desk is where the buck stops.
My opinion - I think it looks too risky now, for me to want to revisit it.
The downside is that existing shareholders could be diluted heavily in the next fundraising. Look what happened last time! there's no doubt in my mind that the business is likely to survive, but the question is more about who will own it?
Given that the UK economy is operating at very high levels of employment, and low unemployment, then staffing agencies appear to be under pressure - from employers wanting to take on good people as full-time directly employed, rather than temps through an agency. STAF doesn't seem to mention this factor in its update today, although it did mention this issue earlier in 2019. Today it talks about macro factors for the disappointing Q4. I don't buy their explanations. In particular, this section below, indicating a 16% drop in demand in Nov 2019, is far too large to be attributable to the macro picture, in my view;
During November, customer demand was down approximately 16% from the prior year which the Board believes reflects high levels of consumer uncertainty across the UK.
Whilst trading in December has improved, trading performance for the month is also anticipated to be below the Board's expectations.
For the sake of balance, I should report some positive noises made about the PeoplePlus division, despite a poor end to 2019;
...Despite significant growth within the year, Q4 performance is expected to be below the Board's expectations, principally due to the impact of the general election purdah on short term procurement opportunities.
However, following a first half of transition and multiple new contract implementations, the second half has evidenced the potential of the business with operating profit in each of October and November reaching £1 million.
PeoplePlus has built a significant platform for future growth and with the majority of 2020 revenues already contracted, the Company maintains a positive outlook for PeoplePlus in 2020 under its new operating model.
Maybe they should sell or shut down the rest of the business, and concentrate on PeoplePlus, if it's going to make £1m per month profit?
600 (LON:SIXH)
Share price: 14.0p (down 26% today, at 11:36)
No. shares: 115.4m
Market cap: £16.2m
Trading update (profit warning)
The 600 Group PLC ("the Group"), the diversified industrial engineering company (AIM: SIXH), today announces a trading update.
Its year end date is c.30 March 2020.
There's something funny about this company - it might be a massive pension scheme, and/or debt. I'll check that after looking at its profit warning today.
What has gone wrong? - once again problems in the automotive sector are causing problems in its supply chain. I think investors need to be particularly careful right now about owning shares in companies which supply the automotive sector;
As noted in our interim results, the Group has been experiencing certain macro-economic and political uncertainties across our end markets which it anticipated might create some short-term disruption to trading.
Consequently, order intake for the fourth quarter [Paul Scott: Jan-Mar 2020] is now expected to be significantly below originally predicted levels, with orders for Germany and the Far East, in particular, suffering delays heavily influenced by the global automotive slowdown.
Some positive comments -
There has been good progress in the UK business, where orders remain over 100% up on the prior year as well as continued good performance at the newly acquired CMS business, driven by its focus on healthcare and pharmaceuticals.
Gross margins across the Group are also holding up well.
Overall it's not good -
However, these positive factors will not be sufficient to make up the shortfall from the likely revenue reduction and as a result, the outturn for the full year is expected to be significantly below the Board's previous expectations.
Revised forecasts - the house broker has slashed its profit forecast by 43% for FY 03/2020, which seems a huge drop, considering it's only lowering revenue forecast by 7%. It must be very high margin business that has fallen away.
The revised EPS forecast is US cents 2.1 (about 1.6p in UK money), down from 3.69 cents in a previous forecast published very recently, on 2 Dec 2019. One of our subscribers comments below that they cannot understand how forecasts can be reduced so much, in such a short space of time. A very fair observation.
I make that a FY 03/2020 PER of 8.8 - which doesn't strike me as cheap, considering this company has substantial net debt.
I'm also worried about the apparent lack of earnings visibility, given that expectations can change so much when the company is already 3/4 of the way through its financial year.
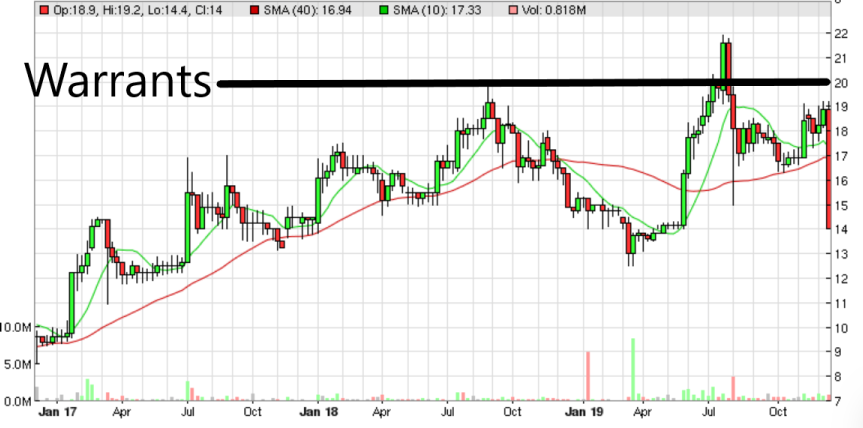
Capital structure - A helpful note from WH Ireland reminds me of the unusual capital structure - namely £8m of loan notes, and 44m warrants exerciseable at 20p. The warrants don't matter so much, now the share price is well below that, at 14p. But the warrants could cap the upside going much above 20p share price, because warrant holders would then be incentivised to exercise their warrants (i.e. turning them into newly issued equity), and then flip them for an instant profit. 44m potential new shares is very considerable dilution, compared with 115.4m existing shares in issue. Potential investors here should therefore carefully investigate the terms of both the loan notes, and the warrants. In particular, what is the expiry date of the warrants (if they lapse soon, then they disappear as a problem), who owns the warrants, why were they issued, etc? The Annual Report is your first port of call to look into that.
My opinion - when I last looked at 600 Group, I came away feeling that it has some good quality businesses. However, this update today has really put me off. The warrants effectively limit the share price upside to about 20p. Why would I want to buy shares in something where my upside is capped like that?
Therefore, it's not for me, but good luck to holders.
GRC International (LON:GRC)
Share price: 17p (down 28%, at 12:15)
No. shares: 64.5m
Market cap: £11.0m
GRC International Group plc ("GRC International" or the "Group"), a leading supplier of IT governance, risk management and compliance products and services, is pleased to announce its unaudited interim results for the six months ended 30 September 2019.
This floated on AIM in Mar 2018. Yet another high quality offering on AIM I see, from its chart. Dear oh dear;
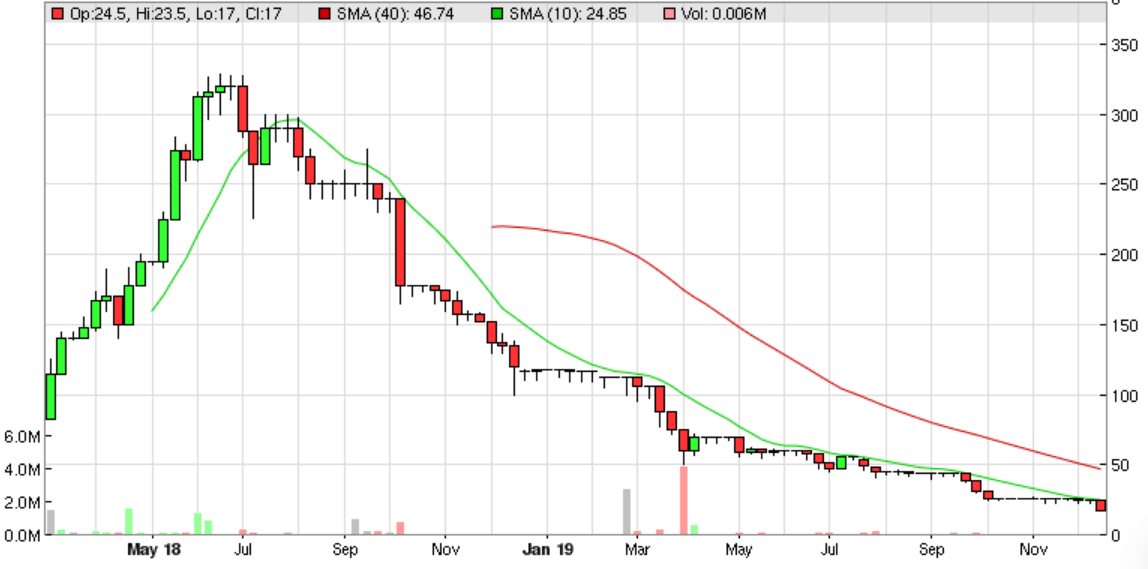
Kudos to our Graham, who spotted that this was a crock, a year ago in this article, specifying exactly why he thought it wouldn't be any good. The share price was 117p when Graham wrote that a year ago. It's since lost the 1 on the front of the share price, and is now 17p!
Balance sheet - it's insolvent.
My opinion - there's a long going concern note, which makes clear that this company is in serious financial trouble. Its creditors will need to take a big haircut before anyone in their right mind would be prepared to put in fresh equity. And why would anyone want to invest in a heavily loss-making business anyway?
... In light of the above, the Directors have identified a material uncertainty that may cast significant doubt over the Group's ability to continue as a going concern for the foreseeable future.
The equity is clearly worth nothing. Therefore if I held shares in this, I would ditch them for anything I could get.
As mentioned in Monday's report, my message for 2020 to UK brokers is this;
"Stop floating over-priced crap!"
Midwich (LON:MIDW)
Share price: 565p (down 7% today, at 13:15)
No. shares: 80.0m
Market cap: £452m
Trading update (profit warning)
Midwich, a specialist audio visual distributor to the trade market, is today providing a trading update for the year ending 31 December 2019.
There seem to be a lot of companies putting out updates, complaining of a soft Q4. I'm starting to wonder if that might create some buying opportunities, since the general election created much greater macro uncertainty than Brexit alone. With a decisive result, I think there's a good chance that at least some business confidence might return in Q1 2020. We'll see. Anyway, that's the specific reason why I think mild profit warnings around now from fundamentally sound companies, might be opportunities in some cases.
Midwich complains of a tough Q4;
Following strong trading through the first three quarters of the year, the Group has seen a slowdown in demand in recent weeks in both the UK and across key territories in Continental Europe.
In particular, we have seen fewer larger projects, which in turn has held back progress in gross margins. Hence, while we anticipate delivering total revenues for the year in line with expectations, the product mix effect on gross margins means adjusted profit before tax in 2019 is now expected to be in the range of £30 million to £31 million.
I don't quite understand how that hangs together - slowdown in demand, but revenue still in line. But lower margins. Maybe they had to discount prices to get sales closed by the year end?
Broker updates - nothing that I can get hold of.
Last year's results showed adjusted PBT of £29.1m. Therefore the revised figure for this year of £30-31m is a slight increase against last year - so hardly a disaster.
Interim results for this year showed an increase of adj PBT from £12.9m LY to £13.7m this year.
Taking one from the other, gives H2 adj PBT as follows:
This year adj PBT: H1: £13.7m H2: £16.8m FY: £30.5m
Last year adj PBT: H1: £12.9m H2: £16.2m FY: £29.1m
That looks OK doesn't it? Hence I think why the share price is only down 7%, because it looks a mild profit warning only.
Polite message for Berenberg & Investec - in future it would be very helpful, and save investors (and humble shares bloggers) a lot of time, if you could include a little asterisk in the RNS, and a footnote explaining what the existing market expectations were. Lots of other companies do this, and it's helpful. Then we can instantly see what the extent of the profit miss is, rather than having to spend ages ploughing through the last year's and most recent interims, to quantify it. Thank you kindly.
My opinion - this mild profit warning doesn't look serious enough to frighten off investors who are already in the stock. Although I can't see any compelling reason for me to want to buy the stock either.
Time is running short now, as I've already spent about 6 hours on this report, so let's move to quick comments format;
Bidstack (LON:BIDS) - a small speculative concept share, that is trying to embed adverts into computer games.
Profit warning today - 2019 revenues are not expected to be significant. Revs were £30k in H1.
Discussions continuing;
Bidstack has also been working closely with some of the world's largest names in computer game development and publishing. Access to a number of well-known games is expected in Q1 and Q2 2020.
When's it going to run out of cash? Nothing is said about that today. It had £6m cash at 30 June 2019. The operating loss was £1.8m in H1, so assuming a similar level of cash burn in H2, then it should have c.£4.2m in cash now - enough to keep running into early 2021. So no immediate concerns re cash.
The market cap is down to about £18m after today's 37% fall - which still looks expensive for something that has to date not generated any significant revenues. However, if the concept is proven, and sales soar, then it could get exciting again.
Therefore very much a share for gamblers!
Pressure Technologies (LON:PRES) - results out yesterday look good.
However, it's uninvestable for me, given that the company was found guilty re a fatal accident;
In November we announced that a trial had commenced in respect of the prosecution by the Health & Safety Executive (HSE) following the fatal accident at CSC in June 2015. At the conclusion of the trial, in late November, the jury delivered a guilty verdict pursuant to Section 2 of the Health and Safety at Work Act 1974 and we await the sentencing hearing which is now expected to take place in the New Year.
The outcome of the sentencing hearing is uncertain and whilst the range of possible outcomes is significant, the Directors are satisfied that the Group can continue to prepare its financial statements on a going concern basis. Further details are in Note 11 of this preliminary announcement.
I'm conscious of the fact that it seems crass to be talking about investments when someone has tragically died. According to google, the fines for corporate manslaughter (assuming that's what this is?) are based on an organisation's revenues, and could be up to a maximum of £7.5m for a group of PRES's size.
Note 11 gives more information. This sentence concerns me, although I'm not entirely sure what it means - can any readers shed any light on this?
Given the nature of the contingent liability the Directors' have determined that the exemption given in IAS 37 from providing all disclosures where disclosure can be expected to prejudice seriously the position of the entity in relation to the sentencing hearing is appropriate.
My opinion - Given that PRES has quite a weak balance sheet, and a potentially large compensation/fine liability looming, then I think it makes sense to steer clear of the shares for now.
Our condolences go to the family & friends of the poor man who died, John Townsend, a long-serving employee of PRES.
Symphony Environmental Technologies (LON:SYM) - profit warning for 2019, issued yesterday;
... revenues for the full year 2019 will be below market expectations resulting in an operating loss of approximately £0.5 million.
This company seems to bump along with revenues between £6-8m every year, never really gaining much traction.
I'm embarrassed to admit that I got caught up in the speculative bubble in May 2018. A mate rang me up to say it was super-exciting, so like a fool I bought some despite not liking the fundamentals. I assumed he'd done painstaking research on it. Anyway, it later transpired that it was a total punt & he knew almost nothing about the company! So that cost me £10k, but was entirely my own fault for ignoring the fundamentals. He can buy the drinks next time we meet up for a chat! (and I'll ignore whatever hot stocks he pumps!)
That's it for today, my brain has ground to a halt!
Graham's looking after you tomorrow.
Best wishes, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

57 comments
I hold Ra International (LON:RAI) and despite initial enthusiasm for this morning's update, on reflection I'm actually a little put off and am tempted to sell my entire holding.
My thought process:
Sept 2019 (H1 interims published):
H1 Rev = $23m
Backlog = $166m as of June 30th 2019
Today (trading update)
Full year revenue expectations slightly exceeded, let's assume $61m vs expectations inJuly 2019 stock report of $60.2m, and a backlog of $148m.
So $23m H1 revenue + $38m (balancing) H2 revenue = $61m revenue for the year.
This seems low, especially given that $9.1m of this $20m was announced today (very close to YE) and is vs $65.8m of orders won in H12019
The H2 order position looks even worse if using today's 2019 revenue expectations of $59.3m
Conclusion
I bought into this company in the full knowledge that orders would be lumpy but a swing in orders from $65.8m in H1 to $20m in H2 is perhaps a bit too lumpy for me.
Booked revenue for 2020 is already $55m vs expectations of $65.2m, so that takes away some risk, but if Ra International (LON:RAI) are really not winning many orders at the moment what are the chances they'll book many orders during 2020?
I'm not sure what to do next though I'm leaning towards selling out. Thoughts from others appreciated. Am I missing something?
Cheers
A
Apologies for the off-topic.
abtan
- I sent you a PM a couple of days ago, but it just occurred to me that you're using the new site where private messages have not yet been implemented. Nothing earth-shattering, but it might be of vague interest - you'll need to switch back to the old site to see it.
I hold Ra International (LON:RAI) and despite initial enthusiasm for this morning's update, on reflection I'm actually a little put off and am tempted to sell my entire holding.
My thought process:
Sept 2019 (H1 interims published):
H1 Rev = $23m
Backlog = $166m as of June 30th 2019
Today (trading update)
Full year revenue expectations slightly exceeded, let's assume $61m vs expectations inJuly 2019 stock report of $60.2m, and a backlog of $148m.
So $23m H1 revenue + $38m (balancing) H2 revenue = $61m revenue for the year.
Taking away 38m H2 revenue means the H1 backlog of $166m reducing to $128m, and the backlog today of $148m implies that only $20m in new orders was therefore received in 2019H2.
This seems low, especially given that $9.1m of this $20m was announced today (very close to YE!) and is vs $65.8m of orders won in H12019
The H2 order position looks even worse if using today's 2019 revenue expectations of $59.3m
Conclusion
I bought into this company in the full knowledge that orders would be lumpy but a swing in orders from $65.8m in H1 to $20m in H2 is perhaps a bit too lumpy for me.
Booked revenue for 2020 is already $55m, vs expectations of $65.2m, so that takes away some risk, but if Ra International (LON:RAI) are really not winning many orders at the moment what are the chances they'll book many orders during 2020?
I'm not sure what to do next though I'm leaning towards selling out. Thoughts from others appreciated. Am I missing something?
Cheers
A
Re. RA International (LON:RAI) (I hold)
Here are what I think they have stated the contracted backlog to be on every occasion I can find that they have stated it:
31/12/2017 $112m (prev figure stated in H1'18 interims narrative)
30/08/2018 $114m (Snapshot at H1 '18 interims release date, from narrative)
31/12/2018 $119m (FY 18 figure)
10/04/2019 $130m (Snaphot at FY 18 release date, from narrative)
24/06/2019 >$150m (Trading update)
30/06/2019 $166m (H1 '19 figure)
18/12/2019 $148m (Trading update)
This appears to be the first time the stated figure has actually gone backwards. However, the longer trend still looks upward to me. Personally, I can live with lumpy, as long as the longer trend continues upward, particularly given the recent CFO purchases.
”The share price was 117p when Graham wrote that a year ago. It's since lost the 1 on the front of the share price, and is now 17p!”. Made me chuckle.
I think I saw somewhere that Stockopedia covers 48,000 different stocks (if you subscribe to all regions, I don’t), but if that is the case with 47,999 other possible investing candidates would anybody invest in a company like Bidstack (LON:BIDS)? I just don’t understand how the risk reward scenario could ever be favourable?
Thanks for this Paul. The expiration date of warrants for 600 (LON:SIXH) is the 14th Feb 2022, so still a couple of years left of potential capped upside.
Thanks Paul for the write ups. I find them very informative.
Can you have a look at STM please? It's profit making but currently has a negative EV.
Non-standard Finance (LON:NSF) - Alchemy Special Opportunities who bought out Woodfords share of NSF and have today increased their stake from 19.2% to 29.95% ie max possible before a mandatory takeover bid.
Share price remains 1/3 of what it was before the failed bid for PFG was launched in Feb 19. All All 3 Underlying businesses (EDL - no 1 in branch based lending, GLD - no 2 in Guarantor lending and no 3. Loans@Home are doing reasonably well IMHO ie growing reasonably fast and with low levels of impairment (for sectors) so risk-adjusted margin is >30%.
However, rate of growth has slowed as they price up ahead of any recession, have made changes in response to FCA rulings and most critically as they are start to run out of money to lend !! Alchemy is no doubt part of the answer to that. Balance sheet needs strengthening urgently to in turn enable a restructuring and expansion of loans. A Rights issue or Placing must be on the cards (esp as new broker appointed a few weeks ago!).
Question to community - do Alchemy ever own businesses outright ie is a takeover likely?
Despite the appalling share price run to date and recent profit warning (and risk of total loss if economy suddenly goes south), I would like to hold on to my stake. Current price of 20p as it is only only 0.3 xBook value (from Stockopedia today) and I think that operationally the businesses are much bigger and better than when they were acquired.
Press speculation has been that Alchemy is forcing a restructure by selling off Loans at Home. This could be an attractive purchase to Morses Club (LON:MCL) if regulators allow, giving them roughly 30% mkt share (ie +8% ppts) in Home Credit vs Provident Financial (LON:PFG) at 50% and a further source to integrate with their recent digital purchases. It could just about be a standalone operation or add on to another sub-prime specialist like Amigo Holdings (LON:AMGO) or S&u (LON:SUS)
Detaching Loans@Home would leave the EveryDay Loans national branch network and the Guarantor Lending Division, 2 businesses that would be a perfect and satisfying purchase for Provident Financial (LON:PFG) to integrate - a complete reversal of the failed takeover. With a stronger balance sheet and a 3-5 year outlook, both are great business opportunities.
I hold (too much) NSF but am consdering doubling down and buying more !!
Agree with all you have said, NSF at current levels with receivables and returns are very good value. In terms of funding they have lines out a few years as I remember the chair commenting recently on but they seem to be in a holding, wait and monitor the book before embarking on further expansion. EDL seems solid but with Amigo not in a great shape so has implications/market concerns for Trust2/Georgebanko. Also the people in every part of this business are sub prime lending ingrained right up to the Chair ex Chair of Provident. Alchemy will take the lot if they can and if lenders remain confident, no reason for them to share the pie IMO.
Great report today, Paul. I think SDI (LON:SDI) could have further to run against a possibly increasingly supportive backdrop. I do worry about the heavy dilution here over the years but think that may be ignored in the general excitement. I could see this appealing to PE at some point
Exceptional report today Paul. Both in volume and quality of coverage. Many thanks!
Strongly agree with you bryans1311 about the exceptional report today, and that applies on so many days. So it took Paul at least 6 hours. Wow!
One big plus is that the depth and quality of information on the shares Paul and Graham cover is so useful when researching Stockopedia for further potential buys, so that cumulative benefit beyond the days of the reports themselves is becoming such a useful benefit too. It’s worth the subscription just for the quality of these reports and a lot of the replies, with masses more here on top, in for free. A bit like a share with cash more than covering the share price, with a good business thrown in for free.
It’s a shame that when accessing the reports on an IPad the thumbs up doesn’t work. IF there is a way to give a thumbs up on an IPad can someone please explain how?
Also agree, particularly your second paragraph. I have a checklist for filtering and analysing companies. Reviewing historical SVCR’s is at the top of the “qualititative” section of my checklist. It’s the idiosyncratic analysis I find adds so much value to the numbers found elsewhere.
I was able to give you a thumbs up on my iPad by clicking on the “in reply to post...” part, and doing so in the pop up window. Otherwise it’s not possible using an iPad on the old site. Altogether impossible to thumbs up the SCVR at the top.
Exceptional report today Paul. Both in volume and quality of coverage. Many thanks!
Thanks for your positive feedback, much appreciated :-)
Best wishes, Paul.
Grc International (LON:GRC) Having made a lot of money over the years in RWS and LTG (and still hold large amounts by my standards, now at nil cost), I broke my normal rules to buy (thankfully very modest) 3000 shares at 160p in GRC because of the Andrew Brode connection. Guess you cannot win them all - not sure if he will allow it go bust, but have mentally written it off. Lesson - stick to your proven strategies! In my case, these focus on cash generation, low debt, significant director shareholdings and profitable growth - in that order.
RA International (LON:RAI)
I picked up some shares recently as a punt - the shareprice was very bombed out and i think i got lucky with my timing as they announced chunky director buys the very next day. In some respects i see this as a binary bet - easily 60p+ share price target if things go right - only myself to blame if it all blow up and goes wrong.
Broadly in line with very decent order book is fine by me
Balance sheet rock solid.
Us government contracts signed probably a plus - rather them than the south sudan government meethinks :)
So it really boils down to the attitude for risk.
chunky contracts risk
overseas earnings risk
risky countries they work in risk (the fact they are working in south sudan says it all risk wise.)
main shareholders own 80% risk (that fact alone is probably enough to put most bods off investing!)
Note this is an england/wales incorporated company - the logic of them being listed and being resident in the uk for transparency and to aid the granting of contracts (specifically uk government - the listing document shows a very impressive list of customers) seems to make sense. Also it looks like most of the funds raised on admission have been retained within the business - so its not as if the company has been loaded with debt for the founder sellers to make their quick buck as so often is the case.
Paul ref whether the update is positive - based on how bombed out the shareprice has been broadly positive is fine by me , main thing is the order book is still healthy and there are no major nasties - currently 148$ mill order book compared to a similar amount in june (over $150 mill at that time).
I liked the idea of RAI - working for Western organisations in very difficult parts of the world. 3 things put me off; I've not invested :
Ra International (LON:RAI)
The answer to your third item is in the Interim report
... a new contract whereby we will be undertaking construction works at the US embassy in Denmark. We primarily bid on this contract to provide us with the track record and experience required to undertake similar contracts in Africa; and less than 2 months following this contract win we were awarded a similar contract in South Sudan where we have now materially increased our footprint. We are optimistic that we will win additional work in South Sudan allowing us to maintain a significant footprint in the country for years to come.
RA International (LON:RAI)
garbetklb
They won a significant contract in Denmark with the US Embassy. How on earth are an African focused company competitive in Denmark? And why would they want to be diverted from their prime focus? Something doesn't add up
That's an excellent question to ask the company - i am guessing they aren't adverse to doing business anywhere and they have been keen to say they are looking to expand geographically and they have married up with us entities to have some sort of shared framework for completing contracts for the us government - i'm not sure if they do the bidding and subcontract or do the subcontract work for the bidder.
Note they said the following in the 2018 finals which referenced a global agreement.
Note IAP mention they work with the US government on their main webpage - so i am guessing the Denmark contract is just a consequence of signing this worldwide agreement or some other similar type opportunity - if they have the relevant technical ability to deliver to the US government in Africa sorting somethingsimilar in a European country should be simples for them. To me the more territories they deliver too the more diverse their income stream and the less likely they are to run into big problems if there major strife if one or two of their marketplaces. Obviously there is the operational danger they will move away from their core competence and take on something they shouldn't
I agree that there are certain things that are worrying with RA International (LON:RAI) - Dwit199 has given you the company’s answer to the Danish contract - and it is fair to say that the company’s answer was similar even before the South Sudan contract - ie we went for the Danish contract because it would help us with winning embassy contracts in Africa.
I was at the last AGM (and am still a very small shareholder) and while being very personable - I am not convinced she is really ready to run the company as a public company and be fully transparent to shareholders.
The other issue with the company is that at the IPO, the rationale for raising the money (all primary shares - existing owners sold nothing) was to allow the RA International (LON:RAI) to bid for much larger projects (credibility and working capital). But since IPO, they have still not won one such contract.
Hi Paul,
Good stuff but I do have to take issue with the following comment:
'Once the PER is knocking on the door of 20, then I feel companies really should be beating, rather than just meeting expectations.'
If a company has for example a PE of 30, PEG of 1, hitting EPS growth of 30% is a perfectly acceptable outcome. Beating the forecast is not required if the growth rate is maintained.
One of the final presentations from Mello November 19, just published:
Polar Capital Global Healthcare Trust (LON:PCGH) by Gareth Powell, Co-Head healthcare team.
An overview of the healthcare sector including the innovations & the US political landscape.
https://www.piworld.co.uk/2019/12/18/polar-capital-global-healthcare-trust-pcgh-mello-london-november-2019/
Regarding Staffline (LON:STAF) (I have never held) today has hardened my decision to act immediately on a PW. This followed the Stocko study/seminar on PWs a couple of years ago.
In this case there was a major PW on May 17th. It closed at 782p on the 16th and 309p on the 17th. All credit to Paul for writing on that day "I don't hold, but if I did, I would sell on the opening bell".
Even if you had sold at the closing 309p you would have been thankful that you had done so now.
However, it is very painful, particularly if you were already at a loss. For the record, I know that pain having sold Tricorn (LON:TCN) and Synectics (LON:SNX) on PWs in the last few months.
Marshall Motor Holdings (LON:MMH) announce today that they are buying some more Volkswagen and Skoda passenger and commercial dealerships for not that much money (net of stock) although they will be loss making for the next year or so.
Otherwise they say "we performed well in the challenging market and the board’s outlook for the full year remains unchanged despite trading conditions weakening further in Q4 2019.
Re 600 (LON:SIXH)
I looked at this earlier in year when sold pension asset for cash. This looked positive and potential deleveraging story but then they bought US laser business...
that seemed bit desperate/misjudged given high existing debt and working capital requirements plus possible increased investment phase ahead as capital looks bit tired as UK operations nearly fully depreciated and they're in the machine tool and instrument business.
Overall, looks very vulnerable to any cycle turndown...a restructuring story to come. My hunch is that the shiny new US business will become the focus and something done with the less shiny legacy business and assets/liabilities. This could be equity raise to refinance activity (potentially through dilutive new terms on existing convertible due early 2020) or finding a buyer for the non-US laser stuff for a fairly minimal amount.
Re SDI (I hold) I think it's significant that whilst previous acquisitions have been dilutive, the latest, after the period covered by these results, is not. The stock has often been compared to an early stage JDG, and the Chell acquisition follows the non-dilutive JDG approach. I think it's also worth mentioning that Management performance in identifying and executing acquisitions has been pretty much faultless whilst, even more important, their record on integrating them into the group whilst helping them enhance performance has been excellent.
I do often think that 'Quality of Management' is something undervalued by investors. I know the quantitative end results of good management - EPS, ROCEetc.etc - are things we all use, but the points of difference between successful and super successful managements are often qualitative, and show up in things like acquisition strategy and execution.
Hi Paul, on management departures both CFO and Chief Executive left Hostelworld (LON:HSW) and the share price subsequently fell around 75%. I'm doing some work on this signal, because I think you're right.
Often a "signal" isn't something in the numbers, or the management commentary ...it is not what management say, it's what management do (ie leave the company or insider selling). I'm planning to see if I can build something with combining stockopedia's new "major shareholder" tool with my own data sets.
On the Tristel (LON:TSTL) front I agree that it seems rather highly rated given how slow US progress has been. Also this sentence gives me pause for thought:
"A fairly modest rise in profit, at least some of which has come from acquiring its overseas distributors, doesn't strike me as particularly good."
I seem to recall that one way to cook the books is for a company to buy its distributor. Doing this means that overdue receivables can be vanished because they are now internal to the group - hence potentially over-stated historic profits never need to be re-stated?
Now I'm not suggesting any malfeasance at Tristel (LON:TSTL) but holders might wish to consider this angle?
Damian
I can be accused of confirmation bias, because I am heavily invested in investing Tristel (LON:TSTL) and so watch them like a hawk and attend updates regularly.
I am very happy that they are buying out distributors as part of their global roll-out programme. It makes very good sense and hugely boosts margins. In some cases, they have supplemented the group - most obviously Bart Leemans, who is an impressive individual, now on the board.
The US initiative is clearly very important, but I think that the market generally misses the point that there are huge opportunities to grow the business pretty easily, however long the US approval programme takes. Start with France and Germany and then look at South America and the Far East. I don't share the view that the share is fully priced, but I do agree that any news that is less than wonderful may result in a price dip. That is when I will add more.
Hansteen Holdings (LON:HSTN) has received an agreed takeover bid , announced at 0921 this morning. There is a 10% premium to the current price. This is not a small cap, but there are perhaps some interesting indications about the UK commercial property market here. The fact there is a takeover suggests someone has some confidence here, but at the same time the limited premium suggests the Hansteen Holdings (LON:HSTN) management do not necessarily share it. Any comments please?
Londonmetric Property (LON:LMP) which owns similar properties i.e. urban logistics, is trading at a 29% premium to the latest NAV. Hansteen Holdings (LON:HSTN) bid is only a 12% premium to latest NAV. Perhaps a counter bid might arise - I'm holding on to my Hansteen Holdings (LON:HSTN) for now.
It looks a modest premium agreed but I wonder if there is a chance of a counterbid? The directors recommend and hold 5%. Institutional holdings are very diversified with none over 10% and none in the same business. Current holders have received magnificent returns over the past five years. The company has to be actively managed given it leases out a diverse portfolio so a purchaser is certainly not getting something for nothing. Blackstone has, I think, a good record and this is a very small investment for them though they seem to be getting more active in the UK. My guess is that it will go through at this level but I will probably hold till payment in the 90% certain knowledge that there isn't much downside.
Thank you melody and Wombat; very helpful. The management at Hansteen Holdings (LON:HSTN) had a similar vehicle in the 90s (Ashten?), which did rather well, but they then sold up in c. 2006, prior to the meltdown. That may have been a fluke, but it might suggest these chaps know the market, and are voting with their feet.
Hansteen Holdings (LON:HSTN)
Mucklow was acquired by Londonmetric Property (LON:LMP) at 11.4% premium to NAV. So a similar sized premium for a similar-sized portfolio although this was at a 19.7% premium to the prevailing share price and arguably at a more uncertain time in May. This bid is for cash but I actually preferred the Londonmetric Property (LON:LMP) bid as it gave the option of shares in Londonmetric Property (LON:LMP) which have continued to perform. With cash, CGT is payable and the cash will have to be re-invested
Morning all,
Allegedly transformational deal for Arrow Global (LON:ARW) this morning: €838.0 million fund raising for inaugural pan-European NPL fund, where Arrow Global (LON:ARW) is contributing - £500m or 24.9% of fund commitments.
NPL is non performing loan. A key rationale is that it furthers a key objective to become more capital light
The market seems to like it. The short interest has been coming down for some time, perhaps this could shake the rest out.
I like it and have stuck with it, although for many I think it's still a Marmite stock!
Very positive update from Ra International (LON:RAI) this morning, if you have any thoughts on that Paul?
Hi Jack,
Is it a very positive update from RA International (LON:RAI) this morning?
The upshot is a slight earnings miss ("broadly in line");
This company looks cheap on conventional metrics, but seems such a peculiar company that I don't think I can add anything meaningful in terms of analysis.
Regards, Paul.
Hi Paul
Thanks for the reply! Sorry, you're right that read out of context with the share price it does not seem that positive, but relative to what appears to be priced in, it is indeed really quite positive!
Jack
Particularly if you take into account the cash on their balance sheet
The CFO of Walker Greenbank (LON:WGB) (Mike Gant) has resigned and been replaced by an interim CFO. Mike Gant was awarded 377,532 LTIP shares last month (these don't vest for 3 years) so he's walking away from at least £250K.
Maybe he has been offered a very well paid position elsewhere, but it's enough to make me decide to sell my small shareholding.
Hi FREng,
I agree with you. After the debacle of 2 CFOs leaving in rapid succession at Revolution Bars (LON:RBG) a few years ago, then a string of profit warnings, which turned out to be due to poor forecasting models, and general lack of financial controls, I am now very wary indeed of abrupt departure of CFOs. At the very least it seems to be that there's been some kind of disagreement. Or worse, it could be a precursor to trouble ahead.
It would be interesting to get an intern to do a project on that actually - i.e. look at sudden departure of CFO, and plot on a chart what the share price subsequently did & compare that with the rest of its sector, or market as a whole?
Regards, Paul.
Hi Paul,
Sadly it doesn't always follow. I had a holding in Cml Microsystems (LON:CML) which plunged after a profit warning in January 2019. As a small speculative holding in my portfolio I held on in the hope of a recovery (usually a mistake given the Stocko research on profit warning) but sold in early November at c. 306p as no improvement evident in results/trading updates. At the end of November the Group Finance Director resigned and since then the share, on no other news, has increased to c. 353p - a 15% gain. Not sure if this a one off but as you say potentially an interesting project for an intern
Re Sports Direct and retail generally, love him or loathe him here is an interesting and quite reserved interview with Mike Ashley on Sky from a couple of weeks ago. An interesting 11 minutes for those interested or invested in retail in all its forms:-
https://news.sky.com/video/in-full-mike-ashley-on-the-future-of-the-high-streets-11571037
The clip is actually from a year ago
Ooops! Sorry. I wonder why it only popped up on my Yahoo finance feed yesterday, I noticed the day/month but didn't think to register the year. I guess a lot of water has flowed under the bridge since then.
Staffline (LON:STAF)
No need for a long post today - one word sums up this company for the last two years "Jackanory" - the cocksure incompetent (or perhaps lying/disingenuous or other similar phrases) board have told us a nice one that's for sure.
They even mentioned that they were being prudent when they updated the market back last march saying the issues were put to bed ref 2018 without much ado about anything from their warped mindset - despite having to make material provisions despite saying 6 weeks earlier they were confident in their numbers !
I guess is some strange respects by not releasing the full facts back then existing shareholders have probably suffered less dilution than they would have had to (i am in that bracket) - however one should demand honesty and there will have been plenty of bods who bought or topped up based on the Jackanory statements from this board when they really should have ensured they got it right based on their previous failings.
Perhaps there is a a case for reporting this board to the authorities for material miss-statements perhaps?
Hi Paul, have you covered INSE (Inspired Energy) before, I was looking back at your reports but can't find them. Thanks
Hi Barry,
I don't normally cover anything with "Energy" in the name. Although I do seem to have reported on INSE in 2014 and 2015, but not since.
A very bad experience with Utilitywise (which went bust, after being a previously successful share, after its accounts were found to be riddled with problems) has put me off this sector completely.
I believe that INSE's accounts are much more conservative, but even so, nothing would ever persuade me to buy, or even want to look at, any company providing energy consultancy services.
Regards, Paul.
600 (LON:SIXH) Has dropped significantly this morning on news of significant weakness. Would be great to get your thoughts Paul.
600 Group - yes, it's on my list!
Is this a record? Just 16 DAYS after 600 (LON:SIXH) reported a "positive outlook" at their half year results a downturn in orders now means full year results will be "significantly below expectations". Great visibility in that business then! Hard luck to any holders.
Nice to see the CFO of Staffline (LON:STAF) being thanked. As in "take him round the back of the office and give him a damn good thanking".
Yes, if I were a shareholder, I wouldn't be thanking him...
Morning Paul,
Thanks for the swift and early write up. in relation to your comment...
"Subscribers should always do your own research, as I don't have time to go into the detail that a purchase would require."
It reminds me, I was watching your fine presentation from Mello last year (2018) and you mentioned that you were making your checklist points available, but I can't seem to find it. I'd be grateful if you could direct me to the document if you have time.
Thanks in advance,
Tony
Hi Paul
£staf today forecast full year adjusted operating profit of £10 - £12 million to year end Dec 31. Only three months ago they forecast £20 million.
And today they report ~£4 million profit overstatement from 2018 and CFO being replaced with immediate effect.
Seems to be continually going wrong for £staf I was hoping you may have time to comment on them.
Hi jonbirdy,
Yes I'm on the case re Staffline (LON:STAF) - half a section is up already, and working now to finish it.
Sorry for holders of the stock, looks like it's going to be another difficult day.
Regards, Paul.
My morning smallcap tweet: Staffline s**** down shareholders' Xmas chimneys
Staffline (LON:STAF) Bidstack (LON:BIDS) Walker Greenbank (LON:WGB) RA International (LON:RAI) Midwich (LON:MIDW) £RM2 Touchstar (LON:TST) Trakm8 Holdings (LON:TRAK)
Staffline (STAF) warns both reccuitment and PeoplePlus rev below expectations. Giodes FY adj op profit £10-12m. 2018 profit was overstated by £4m. CFO sacked. YE debt in line. "We remain optimistic about future potential of the group with the challenges of 2019 behind us." Hmm. I hold.
Bidstack Group (BIDS) guides FY rev below expectations. "The conversations we are having are extremely detailed and have therefore taken longer than we would ideally have anticipated" is the waffly excuse.
Walker Greenbank (WGB) CFO scarpers. He is thanked.
RA International (RAI) guides FY rev slightly ahead of expectations, profit broadly in line. Wins $9.1m contract extension tofall in 2020.
Midwich Group (MIDW) guides FY rev in line but adj pretax only £30-31m.
RM2 International (RM2) proposes delisting. Looks a done deal. Shares still suspended, accounts delayed as it seeks funding.
Touchstar (TST) guides FY rev only £7m, profit below expectations. Blames order delays due to political uncertainty and stock shortage to deliver orders placed late in Q4.
Trakm8 (TRAK) gets £1.4m loan. Not interest rate stated. Has received tax credit cash of £1.01m.
In line: Marshall Motor Holdings (LON:MMH)
$tstl New to Stocko since January, but understand the analysis on TSTL. It's my largest holding and I've got my stake money back long ago. Its a stock I've held for several years so I've got to appreciate the business. It's super niche and small with a patented moat. This together puts off competitors. IMO when the US approval comes - which it will - we will see a delayed hike in sales - but more importantly some bigger players will tray and buy it.