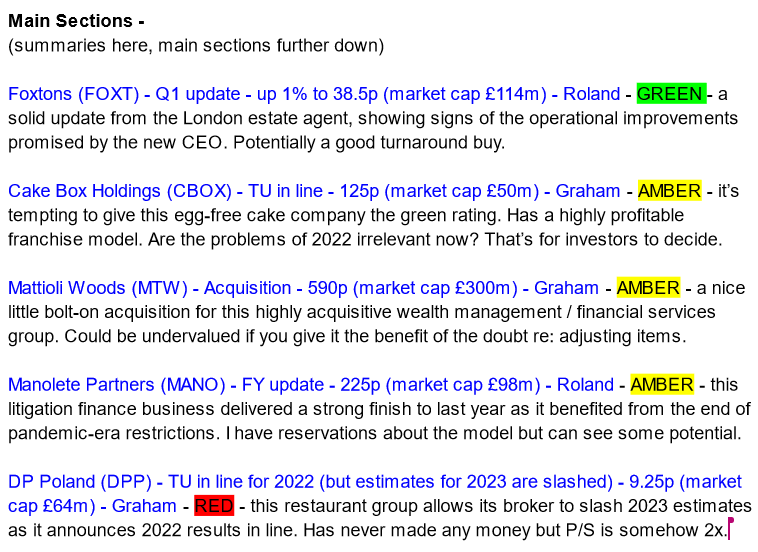
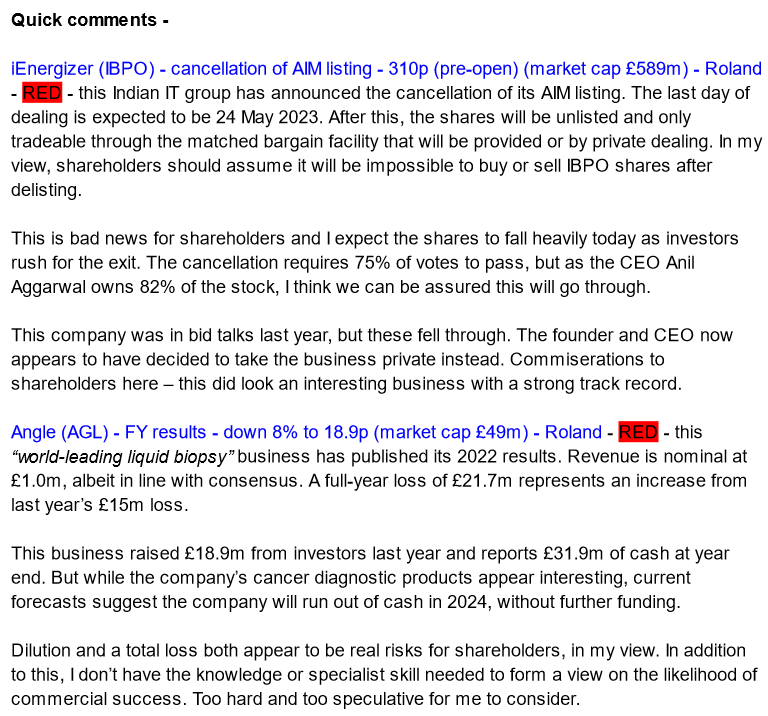
Small Cap Value Report (Fri 21 April 2023) - IBPO, CBOX, FOXT, MTW, MANO, AGL, DPP, TAM

Good morning, it's Roland and Graham here with today's report.
The RNS feed is usually quieter on Friday, so we're hoping to look at some backlog items from earlier in the week in addition to today's news.
Today's report is now finished (10.10). Have a great weekend!
Correction at 14.00: Revenue at Angle was £1.0m in 2022, not £1.1bn as I originally mis-typed. I've amended this below.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Graham's section
Cake Box Holdings (LON:CBOX)
Share price: 125p
Market cap: £50m
For my first share from the backlog today, I want to look at the full-year trading update issued by Cake Box on Wednesday.
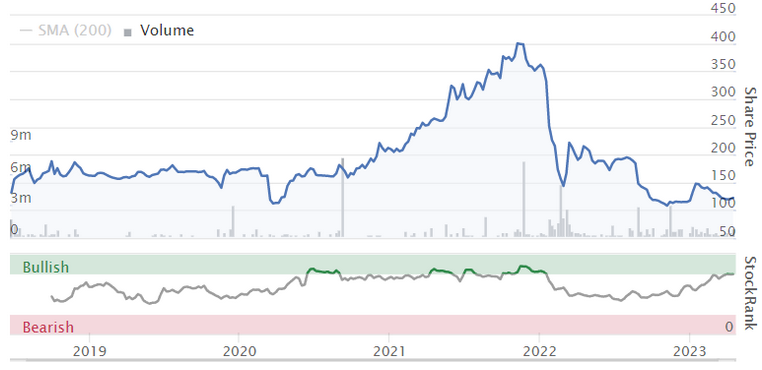
You may recall that this company had some accounting issues in early 2022, that caused the share price to collapse:
Let’s see where trading is currently. This update relates to FY March 2023:
Full-year revenues +5%, adjusted PBT in line with expectations.
Positive like-for-like sales growth.
Group margins improved due to reduced freight rates.
Remember that this is a franchise business; it does not operate any of its own stores. At the franchisee level, inflation is also a challenge:
Franchisees continued to face inflationary pressures but introduced measures to mitigate the impact of increased costs and, with the help of effective marketing initiatives, sales and margin levels were maintained.
Store estate: 10 new stores opened in H2, 20 in the year. Total stores at year-end: 205.
Net cash improves to £6.3m. One of the benefits of the franchise model is that franchisees are on the hook for any leases they sign. CBOX has less than £3m of lease liabilities on its own balance sheet.
Graham's view: as readers will know, I have lots of positive things to say about the franchise business model.
However, we have to treat each case individually, on its own merits.
There was an auditor resignation at CBOX in early 2022 (see coverage here by Paul) which flagged up a range of issues at the company, and the CFO/co-founder left shortly afterwards (see coverage in CityAM).
Interestingly the CBOX share price was much higher, while all of that was happening, than it is today!
Earlier this month, CBOX announced the appointment of another new CFO, Michael Botha. Since 2016, he has been the CFO of one of the largest franchisees of Domino's Pizza (LON:DOM) in the UK. So that is good, relevant experience for CBOX.
One of the stand-out features of the accounting story was prior share sales by insiders. Stockopedia’s very helpful “Directors Dealing” page shows us the story:
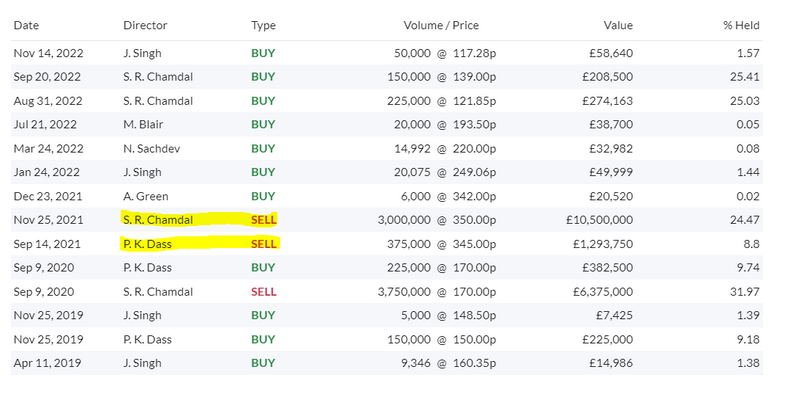
As you can hopefully see from the above image, the CFO/co-founder at the time sold £1.3m in Sep 2021 at 345p.
Additionally, the CEO/co-founder sold £10.5m at 350p in Nov 2021, after already selling £6.4m in Sep 2020 at 170p.
More recently, the CEO has been buying again. His recent amounts bought were c. £275k (Aug 2022) and c. £210k (Sep 2022). I’ll leave it up to you to decide if these amounts are material for him. They may be. But they are also clearly a tiny fraction of the proceeds of his prior sales. He currently owns 25% of the company.
Given everything that happened, my instincts are to not touch this stock. However, it does look like it is probably undervalued relative to its quality and profitability. Stockopedia calculates its return on capital as 30%, and the value metrics look good, too:
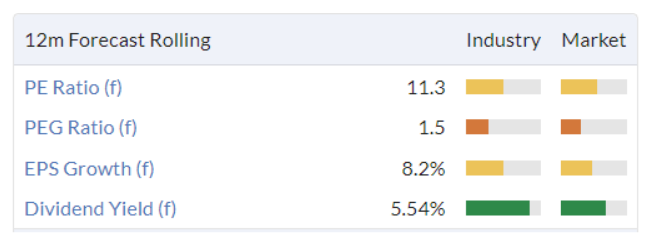
For me to give this stock the “green” rating I would need to have faith and trust in the management team, and personally I’m just not there yet. But I can see why other people might think this now represents a good GARP opportunity. It even passes a Philip Fisher growth screen:
Mattioli Woods (LON:MTW)
- Share price: 590p
- Market cap: £300m
This backlog story is a £15m acquisition of Doherty Pension & Investment Consultancy Limited, described as “one of the largest financial planning and wealth management businesses in Northern Ireland”.
The £15m bill is made up of various parts: upfront cash, upfront shares, deferred consideration and contingent consideration.
The acquired company has 28 staff, and assets under advice and administration of £635m+.
For context, MTW recently reported having a total headcount of 877, and assets under management, administration and advice of £14.6 billion. So this looks like a nice little bolt-on acquisition.
Deal terms appear sensible: Doherty generated revenues of nearly £3m and “profit on ordinary activities before taxation” of £1.45m in 2021 (hopefully 2022 was just as good?).
According to MTW, the deal will “strengthen our position as the only SSAS and SIPP operator based in Northern Ireland”.
Equity Development have nudged up their FY May 2024 forecasts, which now suggest adjusted profit after tax of £26.8m, or actual profit after tax of £16.3m.
Graham's view: MTW is a successful consolidator of wealth management businesses that provides a very wide range of financial services to various types of clients.
The adjustments made by Equity Development to its profit forecasts include many of the things that we’ve become accustomed to over the years, for acquisitive companies. MTW is highly acquisitive - and seems to be quite good at buying and integrating business!
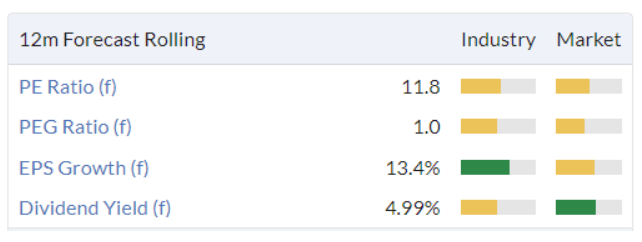
If you are willing to use its adjusted profit figures, you can make a case that this one is undervalued. Using adjusted numbers, this is how Stocko views the P/E multiple and other value metrics:
DP Poland (LON:DPP)
Share price: 9.25p
Market cap: £64m
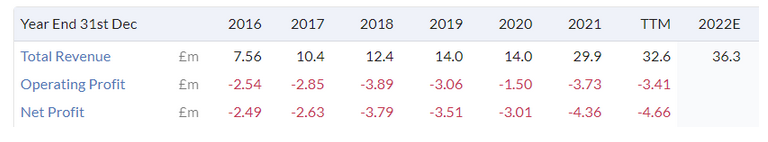
This company has never made any money:
Let’s check yesterday’s Q1 update, to see if there are any signs of improvement at all:
19% like-for-like sales growth after its first TV advertising campaign in five years.
“First signs of cost pressures reversing on food”.
EBITDA for FY 2022 to be in line with market expectations.
Food price inflation was 24% in Poland in February 2023, which is a critical fact we need to bear in mind when looking at the reported sales growth above.
The company also mentions that demand for dine-in meals was affected by Covid restrictions in Q1 last year, so that’s another reason to expect sales growth in the current year.
Therefore, I’m afraid I don’t think we can get too excited about 19% LfL sales growth. The company does at least say that order counts increased.
Note that this company operates the majority of its sites, rather than using a franchise model.
Graham’s view
I previously gave this company an Amber rating. However, I’ve already given two much more credible companies an Amber rating today, so I’m afraid that DPP is going to have to get the Red.
Having checked the latest broker note, I see that the FY 2023 EBITDA forecast has been slashed from £2.5m to £0.5m. Even £2.5m would have been a poor EBITDA number, in my view. But now it turns out that expenses are higher than previously forecast.
Adjusted EBITDA for 2022 is negative (on a pre-IFRS 16 basis).
The restaurant sector is a risky one, in my experience. Foreign restaurants with extremely poor track records and with more losses coming down the tracks are worth vigorously avoiding, in my view. I see no reason for this to trade at a price/sales multiple of 2x.
Roland's section
Foxtons (LON:FOXT)
Share price: 38.5p (+1% yesterday)
Market cap: £116m
Strong growth in Lettings drives revenues as operational turnaround progresses
We’ve had a run of strong results from estate agency groups recently. Foxtons is still in turnaround mode, but the firm’s Q1 numbers appear to have been in line with expectations.
For background on recent performance, Graham covered Foxtons’ recent 2022 results here.
Let’s take a look at this week’s update, which covers the three months to 31 March 2023.
The headline numbers are largely as I’d expect, showing a decline in sales revenue and an increase in income from lettings. Overall, group revenue rose by 10% during the quarter.
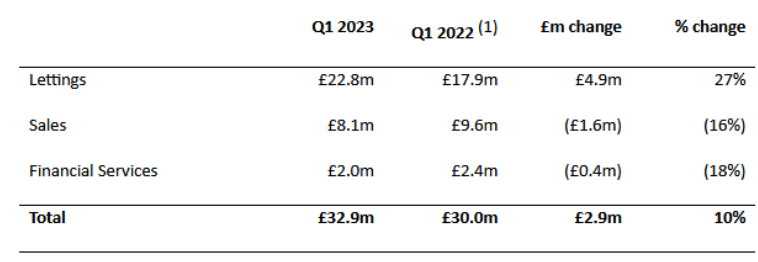
Lettings: revenue was boosted by acquisitions in May 2022 and March 2023. On an organic basis (excluding acquired revenue), Foxtons says that lettings revenue rose by 20% during the first quarter.
Lettings now contributes 69% of group revenue, up from 60% last year.
The company reports an increase in average revenue per letting transaction. This is said to be due to an increase in non-cancellable tenancy terms, higher rental values and cross-selling of property management services. That all seems positive to me.
Sales: there was a reduction in sales exchange volumes during the quarter, as a knock-on effect of September’s mini-budget.
However, Foxtons says that its share of new instructions rose during the quarter. Surprisingly (to me!), the company says it completed the highest number of quarterly viewings in five years.
Buyer demand is said to be strong, supporting an increase in the under-offer pipeline.
This commentary suggests to me that Foxtons is improving its operational execution, as promised by newish chief executive Guy Gittins.
Financial services: lower sales market activity was partially offset by an “investment in adviser capacity”, supporting a marginal increase in remortgage volumes. Again, this seems a solid result in the circumstances.
Roland’s view
Foxtons’ shares have yet to return to meaningful growth, after a long-running decline.
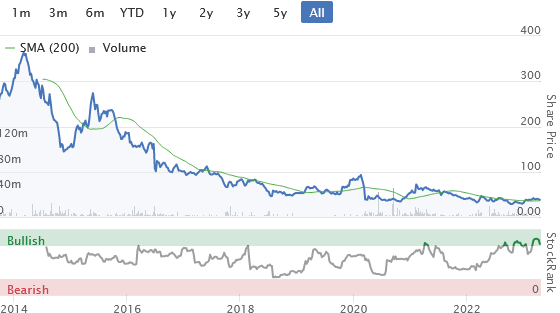
However, the business looks reasonably valued to me and appears to be performing well. I’m encouraged by signs of operational improvements that should drive profit growth further down the line.
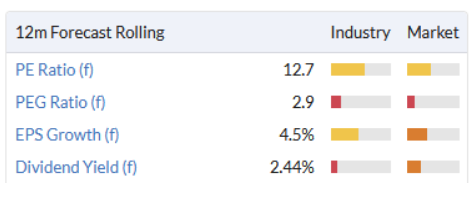
I think that some of the other listed estate agencies are better quality businesses. But if the turnaround succeeds, then I’d expect Foxtons to do well when London property sales start to improve. I’d view the shares positively at current levels.
Manolete Partners (LON:MANO)
Share price: 230p (unch. yesterday)
Market cap: £98.5m
Having navigated through a very testing last two years due to the unique challenges of Covid-19, we are pleased to see the business drive back into profitability in the second half of FY23
Manolete Partners is one of a number of litigation financing companies that has listed on the London market over the last decade. Manolete listed in 2018 and its main focus is insolvency cases.
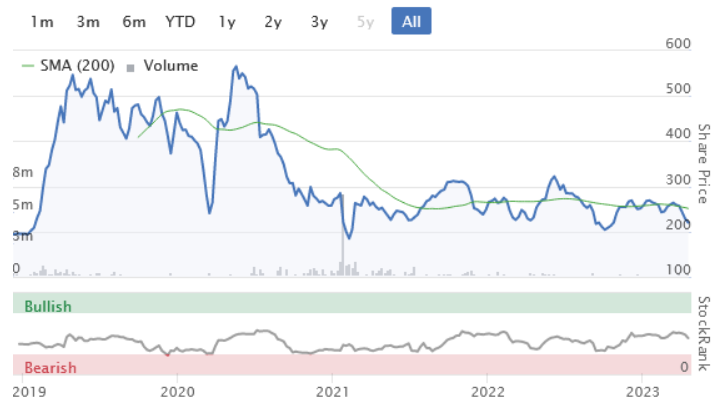
Thursday’s trading update provided an update on trading for the year ended 31 March 2023. The company says it achieved a number of new record operating metrics last year, as the pandemic-era restrictions on insolvency proceedings were lifted.
Let’s take a closer look.
Record new case investments: the final number of new case investments in FY23 was 263. This is 65% higher than the 159 new case investments in FY22 and represents an all-time record.
The growth rate accelerated during the second half of last year, as insolvency market conditions returned to normal after “a two-year suppression of the market by the UK Government”.
This suggests there could be an opportunity for Manolete to deliver on its original potential now the pandemic has receded.
Record new case enquiries: new case enquiries rose by 48% to a record high of 798 last year, as market conditions returned to normal in H2.
Record case completions: Manolete completed 192 cases last year, a new record (FY22: 139 completed cases).
Last year’s completions represented an aggregate of £33.7m in legally-binding settlements (FY22: £15.3m).
This record level of completed cases will drive cash income for the foreseeable future, as the Company collects in the cash owed by defendants on these matters.
Record gross cash recoveries: the company achieved gross cash recoveries from previous cases of £26.7m, 72% higher than the £15.5m achieved in FY22.
The £26.7m is spread across 237 completed cases, giving an average of £113k per case (FY22: £85k).
Management say that after all costs, the company generated £1.9m of net free cash flow in FY23, equivalent to a 2% free cash flow yield. This compares to a net cash outflow of £4.4m in FY22.
Cash generation is a crucial metric for these businesses, so this appears to be a (modestly) positive result. But I still have some concerns, as I’ll explain in a moment.
Profit estimate: the company provides a preliminary estimate of pre-tax profits performance for FY23:
H1 FY23: £(5.5)m
H2 FY23: £1.6m
FY23: £(3.9)m
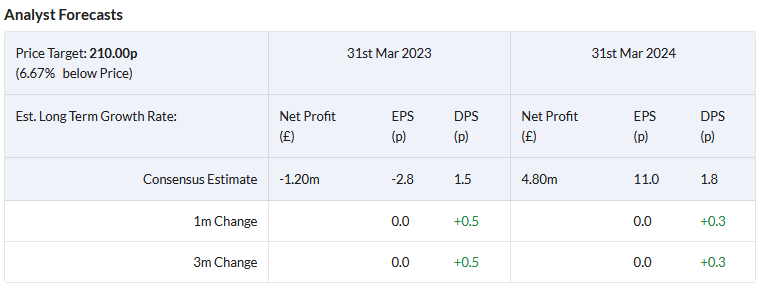
I’ve not been able to find an updated broker note for Manolete on Research Tree, but my feeling is that this is a slightly worse result than the current consensus estimate shown on Stockopedia for after-tax profit. It’s hard to be sure, given the adjustments and tax factors involved.
However, last year is in the past. What matters for shareholders now is whether the improvement seen during the second half of last year can be sustained, now that market conditions are normalising.
Outlook: it’s an ill wind that blows nobody any good. The current weak economic outlook for the UK may well be positive for Manolete Partners. Chief executive Steven Cooklin appears to think so:
With the UK economy facing challenging macro headwinds, particularly high inflation and high interest rates, we expect our market to remain strongly buoyant for the foreseeable future.
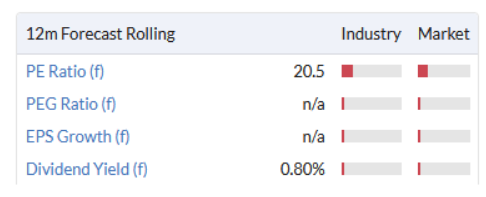
For what they’re worth, consensus forecasts for FY24 show Manolete generating a full-year profit of £4.8m, pricing the stock on 20 times forecast earnings:
Roland’s view: For me, there are two questions to answer here.
First of all, can growth be sustained from the level seen in H2, or does this simply represent a release of pent-up demand?
On balance, I think it’s likely that the company can continue to expand, albeit at a lower rate.
However, the bigger concern for me is whether shareholders will ever share in the proceeds of Manolete’s activities. Like many of its listed peers, Manolete tends to reinvest most of the cash it generates into new cases.
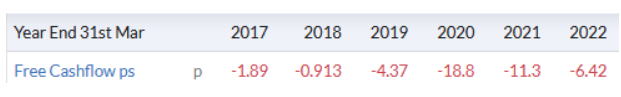
If the company can report genuine free cash flow for FY23, it would be the first time ever in its history as a listed business, according to Stockopedia:
There’s also the question of debt. Manolete reported net debt of £9.4m in its half-year results. We’ll have to wait for the full-year numbers to see how this figure changed during H2, but I’d suggest that borrowing money to make speculative investments (in legal cases) obviously carries a degree of risk.
I don’t find the litigation financing sector attractive as a potential investment.
However, I can see that Manolete’s business benefits from higher volumes and shorter durations than some others. This could potentially make it more predictable and consistently cash generative, I suppose. The shares seem fairly priced to me at the moment, until we learn more about FY24 trading.
On balance, my view is neutral.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

95 comments
My SCVR Summary spreadsheet is also now up-to-date -
https://docs.google.com/spread...
(not for sharing outside of Stockopedia please, as subscribers here are indirectly paying for me to do the work!)
My weekend podcasts are up here (and on the main podcast platforms).
This week's mystery share is Volex (LON:VLX)
Regards, Paul.
Volex (LON:VLX) - breaks 300p then worth a look. I held then got bored and burnt. So 200 a base but why such draw down from 400p. Debt rising so as the Dragons say - 'I'm out'.
Hi HH,
Actually the debt at Volex (LON:VLX) surprised positively. Singers last note forecast $102m net bank debt, but actual is much lower at $76m - which dropped a substantial $22m just in H2. This is only 1.0x EBITDA leverage, which is quite low. Obviously we would need to see the full accounts to see how other items in working capital have moved, but I don't see debt as being a problem at all.
Ahead of mkt exps for FY 3/2022 hence the strong bounce last week. Valuation is only about 10x PER by my figures, even after the big rise.
Outlook comments sound positive, with strong momentum into the new financial year. Active acquisition pipeline, and bear in mind acquisitions to date seem to have all gone well, so they know what they're doing.
It's demonstrated pricing power, and ability to pass on cost increases. Could now benefit from lower input prices maybe?
There's lots to like with Volex. I think in a recovering stock market, we could see a double benefit here - rising earnings, and a PER that I imagine could rise from 10x to 15x, to better reflect the impressive performance, favourable sector tailwinds (e.g. from data centres and EVs), reshoring of component sourcing nearer to home for European manufacturers.
There's lots to like with Volex, so I find it surprising to hear a negative view on a cheap share that is trading well! Still, always good to hear contrary opinions.
Regards, Paul.
iEnergizer (LON:IBPO) and Kape Technologies (LON:KAPE) - both the big holders taking the small shareholders money - this kills the idea of AIM in my view. London junior market is becoming a backwater full of sharks.
Hi Wolfspirit. There is a way to prevent this scenario. For any share that you are looking at buying then check Accounts Major Shareholders on here from the stockreport. If the biggest shareholder has over 33% then don't buy it because they have too much control over the fate of the company.
A share I've been pondering for a while is Goodwin (LON:GDWN) - makes you wonder.
As a Goodwin (LON:GDWN) holder I’d argue that as one of the 10 oldest fully listed companies on the LSE founded in 1883 & v much rooted in Stoke onTrent..albeit with operations all over the world with multiple generations (4 of the latest generation are running it currently)of the family involved & just over 50% of shares widely held by Goodwin family members is somewhat different to an Indian outsourcing company listed on AIM & domiciled in Guernsey with one 82% overseas domiciled shareholder..but obviously I’m biased
Kape Technologies (LON:KAPE)
To be fair to Mr Sagi he did at least offer a small premium to the prevailing price - he didn't just leave the minority high and dry. I felt aggrieved at the price personally, but looking at what happened at iEnergizer (LON:IBPO) today I feel somewhat lucky in retropect.
I assume the same protections afforded to minority interests under UK law don't apply in Guernsey?
Channel Island jurisdiction another 'red flag' to add to the small cap investors check list.
Having been busy most of the day, I didn't really have a chance to look at the iEnergizer (LON:IBPO) saga. Am I correct that about £500m has been effectively 'written off' ? - well unobtainable in any case. I tried to look into what they do - I find their website deliberately obtuse (omnis**t). I get the feeling that their business is Indian customer service centres - where the likes of BT etc get their customer service outsourced to (I found much more information under iEnergizer Noida)
edit : of course Mr Aggarwal holds 93.5% so it is £37.5m of everyone elses money that is being dissappeared..
IBPO
I've noticed that two new Board members were appointed on April 6th with two stepping down with immediate effect to pursue other interests.
I think that's an important point that they left. I suspect they could be called as witnesses should shareholders (e.g. one of the funds) decide to take the existing directors to court.
just tried venting my feelings at the IBPO board funny they don't seem to be taking e mails at the mo
Please state the stock referred to each time you post, thank you.
iEnergizer (LON:IBPO)
Fortunately for me it was a small position, but I have sold my IBPO shares today at a 75% loss. I'm sure others weren't so lucky. So this may seem a naive post, or one born out of rawness of the situation. But there is a big questions in my mind:
Shouldn't the board be compelled to offer a nil-premium tender for stock-holders (especially small holders), at pre- announcement close price, in this kind of situation?
Otherwise whats to stop Aggarwal / insiders depressing the price, to buy up the remaining listed stock cheaply? If that is whats happening, is that not market abuse? Really think AIM's credibility is on the line here, what is the point of them if they cant protect investors from this kind of thing happening.
I may be off the mark here. Would welcome views from others
Re iEnergizer, this morning is a right kick in the nuts, I was already down, I'd been hovering on the sell button for sometime but was hanging on and giving it time to breathe in the hope there would be some bounce. It had a stocko quality rank of 98, a PE of 8 and a yield 7.8, to idiots like me it looked like a good stock!
You do wonder given the heavy, at the time, unexplained down pressure, if a lot of people knew it was on the cards, feels like sucker small investors being fleeced yet again.
Can anyone remind me of that website that publishes which companies are being shorted, it'll be interesting to see whos shorting it and from when
shorttracker.co.uk
I’m fairly new to investing so this is new on me, how can the board just decide to take the company private while investors are left with a heavy loss. They should at least have to make an offer to existing shareholders near the market value.
No board can "just decide" to take a company private - they have to call a general meeting and 75% of shares have to be voted in favour. iEnergizer (LON:IBPO) have called such a meeting for May 16th. The problem here is that EICR (Cyprus) Limited (the vehicle of CEO Anil Aggarwal) holds 82.74% so the resolution will be carried!
We will be featuring this awful abuse of shareholders in the MelloMonday show at the start of next week https://melloevents.com/mm2404... We will have fund managers on the show that have their views on it and hopefully a representative from the LSE as this should not be allowed to happen considering this is a company that was far larger than the average company needing to delist and was growing and paying significant dividends.
Angle (LON:AGL)
Thanks for your commentary Roland. I agree with you - massively cash burning and barely any revenue which is sadly the case with so many drug development companies. I avoid this sector because of this. I also noticed in your commentary you say Revenue is £1 billion but it is actually £1 million which is an alarmingly small figure when the FY loss was £21m.
Angle (LON:AGL)
I hold.
I listened to Andrew Newland’s results presentation this morning and was impressed with the progress that has been since FDA accreditation of Parsortix (which is not a drug). The presentation slides are on the web site but no recording as yet. Commercialisation has been slower than wished for – partly due to the current economic backdrop affecting potential customers – but is picking up strongly.
The company has enough cash to last into H2 2024. Revenue is increasing strongly with Q1 2023 being more than H1 2022. Of the current 4 companies using the lab services, 3 have signed new contracts and the 4th is in negotiations. Each contract can have a value of over £1m. Numerous other deals are being discussed with medical and pharma companies with Abbot and Astra Zeneca active.
I would urge other Stocko members to DYOR – you may be surprised.
Angle (LON:AGL)
FYI, there will be a presentation via Investor Meet Company on Friday 28 April.
Angle (LON:AGL) - v high risk that may not work out...but I too hold within basket of life science / biotech stocks that I'm growing where each is small holding as could be zero but I believe the return potential as a basket is high (skewed to relatively well funded and later stage proven tech). Angle have passed through a lot of the science risk and have used capital to date to build valuable facilities and fund studies that promote their capability. There is clear commercialisation risk but not of the FDA hurdle sort and more re making commercials with drug cos. BUT there probably not a competing tech that comes close to what they offer and their approach way outcompetes biopsies on total human care to commercial spectrum. There's a chance that as we move to more and more tailored/precision medicine that Angle is the only worthwhile diagnostic partner for precision cancer treatments. The upside potential is v large. Its an uncomfortable return spectrum tho from zero to multi-bag....and it will require patience as wont unfold overnight
But cash burn is a scary £2m a month which doesn't sit well in current market environment. However, my gamble is that the next raise (there will be one) occurs at price above current levels (I bought around recent lows). I also guess (and I'm not domain expert by a long shot) that trade value of the assets is likely decent given the capability of their platform and industry need for it (plus FDA approved) plus the supporting lab infrastructure they have developed.
their tech is revolutionary and they may run out of money ...but at this price defo worth a punt- a lot of retail money will be pinging this one about
Hi Michael,
Thanks for pointing out this error. I've corrected it above now.
Regards,
Roland
Thanks for the great work that is put into the SCVR by a variety of contributors.
Slightly off topic but I was wondering what an automated chatgpt / NLP style execution algorithm might have made of revenue being temporarily stated as £1bn not £1m. Probably algos like that have a lot of safeguards and validate news from multiple sources. It does make you wonder though whether we could be in store for more flash crashes and price spikes based on human errors that humans would pick up as errors and wouldn't trade on but algos might trade on. This is obviously an extreme case, and a small company that institutional algos might not cover, but still interesting to consider (at least for me). Not intended as a criticism of Roland, I enjoy and learn from the content you and the others produce. More of a reflection of where markets are headed with tech. Interested in what others think about this as well.
Roland, you chaps who write for SVCR write reports on so many companies, there is bound to be the odd error. I notice so many typos of my own that it's embarrassing! And on some forums such as Twiiter you can't edit them.
Diaceutics (LON:DXRX) full year 2022 results presentation given to analysts with results on Monday video & podcast. Excellent growth:
Summarised by a 'Strong trading performance in 2022 and continued momentum is driving the accelerated strategy investment announced in early 2023'.
DXRX IPO'd in March 2019 and appear to be delivering exactly what they stated at IPO. They provide pharma companies with an end-to-end solution for the launch of precision medicine, for more detail look at their Capital Markets Day 2021 here.
Diaceutics (LON:DXRX)
Thanks Tamzin. I agree they are doing exactly what they said and are growing well. Worth watching and having a look at their progress. Breakeven with a cash pile of £20m while investing for growth. Gross margin 86%. Platform biz moving to subscription. Order book up to £16.9m, £10.9m for 2023. All the largest US and Euro pharma are client. DYOR.
I hold
Wimbledonsprinter many thanks for your interesting post on iEnergizer (LON:IBPO)
Re Angle (LON:AGL) I think, with respect, that Roland is being too pessmistic. Andrew Newland, CEO, who is not prone to overstatement, said this morning that the company had sufficient funds till at least the end of 2024. It is accruing v high gross margin contracts at a very encouraging rate.
Ref iEnergizer (LON:IBPO) - does anyone know, if I held onto them past 24th May, on the understanding that I would never be able to trade them, would I still be entitled to and receive my dividend? Or now that it is delisted we are in total bandit country and I could be diddled out of that too?
Edit - Ignore - BIACS has answered this below.
It is important to have a view of the ethics of the management of any company that delists. I have held delisted companies in the past and in a couple of cases have done well when the business was sold on and the the proceeds distributed at a price that was a multiple of the price available on delisting. In both cases the dividends continued to flow at a level that indicated the shares were worth more than could be obtained by matched bargains. So you need patience and trust in the integrity of the management to make holding delisted shares worthwhile.
Anglo-Eastern Plantations (LON:AEP) FY 22 results. Palm Oil producer. Dividend 25 cents (2.5%), £320m mkt cap, £107m profit before ta4, Cash £178m, no debt.
A small share buyback is planned.
Plus a 51% shareholder which is worthy of consideration after this morning.
Crude Palm Oil has not mirrored food inflation so suspect Indonesian government influences in some way to keep price low and supply available for their own populations (guessing, need to study the industry). All good for the S in ESG but maybe not investors.
Hold M P Evans (LON:MPE) which hasn't done much. R E A Holdings (LON:RE.) but highly speculative microcap.
If I remember correctly, there are regulations concerning the use of palm oil (EU certainly, perhaps also still in the UK), because of the deforestation risks, and so I think there is a register for palm oil that is supplied in a 'green' fashion (so maybe knocks the E out of your ESG !). I dont know for AEP, for any investors it may be worth checking this point, but may also explain why palm oil has not kept up with food inflation.
Simple google says palm oil in 50% of the products on supermarket shelves inc fast food outlets confectionary hygiene products and Coca Cola to name a few. But suspect old data and most seem to have removed/reduced or gone 'sustainable palm oil' (?).
It is very efficient producing high quantities of oil over small areas of land all year round so popular for smallholdings and has culinary and maybe health benefits.
So Western consumer brands have stopped buying, although probably still popular in the East. So with a 51% shareholder pretty much knocks E, S and G.
But high quality good value and on 8 Long screens so worth further research.
Trading Economics palm oil forecast seems to support my suspicions - the EU laws are getting stricter, and this seems to be affecting prices. Not for me, but at least you know what to look out for !
Palm oil plantation
Interesting palm oil
I have a supplier in northern Indonesia who is supplying me hardwoods , all sourced from fallen / tsunami trees for some projects we have .
I said to him “ important is that all our timber must have complete supply chain provenance as all UK customer always comment “oh yeah - another rain forest destroyed”
He said , “funny my grandfather is a woodsman he tells me stories of long lost hardwoods we no longer have because 30 years ago all UK and USA company come and build palm oil plantation and destroy our livelihoods “
I’m going over there in a few weeks, will be an interesting trip as we have the bones of a plan to plant what they call “grandfather tree” this is where a grandfather plants trees for his grandchildren normally red cedar .
Anyway bit of a side story but anyone investing in palm oil plantations has to take a long look in the mirror .
Hi planetx,
Have you looked at Accsys Technologies (LON:AXS) as a hardwood substitute?
Acetylated wood is a modified, sustainably grown softwood from New Zealand (not sure about that). The acetylation process increases the amount of acetyl molecules and reduces the amount of hydroxyls in the wood, which improves durability, dimensional stability, insect resistance and the service life of coatings. Acetylated wood is particularly suited to exterior applications where high performance is required. Ok - oak does it for free.
Commercial name Accoya manufactured by Accsys Technologies (LON:AXS)
This is a viable alternative to hardwoods in our damp climate. Oak was once the go to but not the 'green' product (not matured) which I believe latent defect insurers are excluding from their cover due to failures.
Cheaper pressure treated softwood is ok for the factory house builders but needs good design, detailing and ventilation. Only reason to go hardwood is customer demand high end houses - staircases floors etc which is ok in the dry.
For doors and windows a bit more exposed or needs maintenance - remember the old days when redecorated the house every 5 years - lol.
Its a good product but needs to supply a large hungry industry - great having a good product and have sold it to the market but need to deliver - Avon Protection (LON:AVON) first thoughts on that.
Western Red Cedar is an excellent wood - lightweight for cladding etc and very robust so if produced in the East then something new. No strength for structural products though.
Talk about bad choices in life, I had to raise some capital last month and decided to sell either Sureserve (LON:SUR) or iEnergizer (LON:IBPO) . I actually burst out laughing when I spotted the news this morning, but I have been told laughing at your own misfortune is a sign of strength. Lesson learnt, and I like owners with skin in the game, but no more than 40-50% from now on. A bottle of red later to take the pain away. Sorry for anyone else who got caught out.
I bought iEnergizer (LON:IBPO) on 2 March and sold this morning at 95.2p for a loss of 74%.Ouch!
This is the second time I have held a Share which has been or will be delisted. I will never buy a Share again were one Shareholder owns more than 50% of the Shares.
Portugull
That might be a good rule. The takeover Panel rules make it tough for a large shareholder to get from 30% to 50% but a lot easier thereafter. This is largely for a good reason; that once you control 50% of a company (under UK company law) there are limited blocks on your control. So as you move from 30-50%, the real-life protection of minorities get weaker and weaker.
But I would point out:
1). To delist (from AIM) requires approval from 75% of those voting at an General Meeting. So 50% ownership does not give the automatic power to delist.
2). If you look at the case of Sourcebio - this was delisted last year (only 2 years after being listed) and there was no one controlling shareholder. Instead ?3 large shareholders combined had enough votes to guarantee the success of the delisting. In Sourcebio’s case, the delisting was accompanied by a nil-premium partial tender to minorities.
Surely another example of the regs needing to be tightened. Where the majority shareholder decides to delist - it's effectively a buyout and he should at least be prepared to buyout remaining shareholders at the price prior to the announcement. What's the betting he is laughing whilst buying them in today at the knockdown price
Ive just delved a bit further into the shareholdings and just cannot believe the list of Institutional holders who were prepared to invest in this company with 83% of the shares held by the CEO - In fact this left the company with just 3% to trade in the 'open' market.
I thought there was an obligation from LSE to have a certain level of percentage available for trading - otherwise what is the point of a listing in the first place - see link below.
https://www.stockopedia.com/sh...
Anil Aggarwal is a pretty rich man. I've seen his name on lots company shareholder lists
Anil Agarwal: Take a look at the business journey of Bihar’s richest person; Know about his net worth, family, and more (msn.com)
iEnergizer (LON:IBPO) (not a holder) this is another example of the risks of too much skin in the game. I own Fulham Shore (LON:FUL) which is another example.
Disappointed with Fulham Shore. I knew they would sell the lot at some point, but not now and not at this price.
Does anyone know why Stifel rated On the beach (OTB) to sell with a price target of 120 only ?
They think that competition from easyJet Holidays and Love Holidays will drive down profitability as it drives down prices for customers
I hold and it appears falling back to the sp when there was no good news after pandemic, surely it cannot happen? No debt business is running well I presume
Hi Eesha,
Interesting that Blackrock announced a 5% holding in OTB last night, 2 days after Stifel downgraded. Pure coincidence I'm sure ;-)
Regardless of any potential conspiracy, looks a great opportunity to me. On a forward pe of 8 and that doesn't include the huge cash pile (£64.5m own cash + £69.5m customers), 68% growth last update in Jan...
This is the answer google Bard gave when I asked if 5% stake of the OTB is true?
" No, it is not true. Blackrock did not announce a 5% stake in On The Beach yesterday. In fact, Blackrock does not have any stake in On The Beach at all.
The rumor that Blackrock had acquired a 5% stake in On The Beach was started by a fake news article that was published on a website called "The Economic Sentinel". The article was quickly debunked by On The Beach, who issued a statement saying that the rumor was "completely false".
Blackrock is one of the world's largest investment firms, with over $10 trillion in assets under management. The firm invests in a wide range of assets, including stocks, bonds, and real estate. However, Blackrock does not have any investments in On The Beach."
Interesting..
How about going 'old school' and checking RNS's:
RNS Number : 9694W On the Beach Group PLC 20 April 2023
The RNS yesterday says they have over 5% of shares in On Beach group (LON:OTB) ?
Interesting in the sense that it highlights how useless Bard is in its current form. You cannot rely on Bard for a factual answer to anything. It is worse than ChatGPT for making stuff up. It told me the quote about a 5% stake by Blackrock was fake and that the claim was from a book published in 2009 about the 2008 recession. Complete rubbish.
Sureserve bid .
Bid looks ok both sides the buyers are getting a bargain but the stock market was undervaluing it .
Good business , huge order book , great sector , slim margins , cash in bank but going to do incredibly well in private hands .
Wonder how many similar cash rich asset backed business with big order books in good sectors are going to get taken out simply because market has undervalued them .
This was my second biggest holding around 13% weighting so all in all a good start to the day .
Interesting read across from Crestchic similar fundamentals , private buyers are clever and know when Mr Market ie materially undervaluing a business .
Eurocell (LON:ECEL)
I posted the message below rather late yesterday so have copied and pasted it for anyone who is interested in Eurocell (LON:ECEL) that may have missed it.
This share was one of Paul's mystery shares in March, following release of FY'22 results on 16th March.
The SP today is down 8p but that simply reflects going XD today in respect of the final dividend of 7.2p.
In March the forecast EPS for FY'23 was 18p. It is currently shown on Stocko at a slightly reduced figure of 17.3p.
However, on the company website, consensus forecasts were updated in March as follows:
FY'23 EPS - Peel Hunt 15.5p, Berenberg 15.4p.
FY'24 EP - Peel Hunt 17.2p, Berenberg 17.4p.
The reduced FY'23 forecasts have not been updated on either Stocko or Sharepad. Seems rather strange (and unusual) that the revised figures have not filtered through to either.
Without these revised figures feeding through there is a heightened risk of a profit warning.
Paul's valuation was based around FY'23 EPS of 18p then reverting to a longer term reversion to at least a steady historic level of 20p. That might take a while longer than Paul expected in March.
I was doing some research with a view to opening a position but it looks like a downward revision of expectations is required. Not quite the slam dunk bargain it appeared so may pay to hold off for now.
This is the first time I have seen a company provide consensus forecasts on their website so credit to Eurocell for providing this information.
Snazzy
Hi Snazzytime,
I think from memory we have more recently flagged that Eurocell (LON:ECEL) indicated it's expecting a more downbeat 2023.
A recent webinar from the mgt was rather uninspiring I thought.
So not madly exciting in the short-term, but I still think it's a very nice business taking a longer-term view.
Regards, Paul. (no position).
iEnergizer (LON:IBPO) Proposed delisting is a blow for both shareholders and AIM
I guess it shows the danger of holding shares in a company with a large majority shareholder (EICR with 82.74%) but it still rankles. They’re claiming the costs of maintaining their listing contributed to their decision, alongside limited liquidity due to the majority shareholder.
My sympathies for any shareholders as I fear today could be painful.
Many thanks AG for highlighting.
#IBPO is a £600m mrkcap stock too. Really unusual decision for such a large business.
Anil Agarwal has some form in the treatment of minority shareholders (within the rules). Look at what happened a few years ago at Vedanta (being a billion pound market cap company listed on the main market in London and in India).
I did not notice any statement about dividend policy in the RNS on delisting iEnergizer (LON:IBPO) . But did see that the relationship agreement between Agarwal and Ienergizer would terminate - allowing transactions on a non-arms length basis.
(Not a holder).
iEnergizer (LON:IBPO)
I am under the impression that Anil Agarwal of Vedanta and Anil Aggarwal of iEnergizer are different people. ..but yes, there is a history of governance issues.
Laurie Thanks for pointing this out. My mistake. Sorry.
Vedanta passed to Vale over the heads of its shareholders by an Indian Mogul. I held.
What I fail to understand here, why was the proposed bid last year of 520p not accepted? And why would the majority holder be willing to see his investment halve?
Hi JohnDoe2378,
The iEnergizer (LON:IBPO) sale process was terminated in September last year.
For the majority shareholder (the CEO) the delisting isn't a big problem -- they will still control the business and be able to draw dividends/sell to a trade buyer/etc as they wish.
External shareholders may still be able to receive dividends, but they will have no liquidity and no visibility of what's happening in the business.
Regards,
Roland
I'd appreciate peoples thoughts on whether it is still worth selling iEnergizer (LON:IBPO) , at <1/3 of yesterdays price. Obviously my (thankfully modest) holding is now worth little if I sell now. If the company were to keep paying dividends in future (or be taken over) then presumably I could gain by holding. Are the logistics of holding a small unlisted investment even feasible? Like others shares with a single majority shareholder will be off the list from now on - a costly lesson!
Obviously no-one on here can give you any advice as to what you should do.
technically there should be no issue continuing to hold as an unlisted share if you so choose. Indeed as you point out, as a private vehicle the business may continue to flourish and be worth more in the future.
However, a few potential downsides to note as well. Unless they put in a matched bargain facility there will be little to no liquidity. You may be able to ask the company to find someone to buy your shares but there is no guarantee of that nor any price discovery.
Also, you may get very little information on the progress of the company. You should be able to find accounts but they will be historical, there is no guarantee the owner will communicate with smaller shareholders.
Watch out for tactics that force small shareholders out. It can be dressed up by the company as tidying up the register and involves heavily consolidating the shares with fractions being paid out in cash. There should be rules governing the cash value amount but not entirely sure what they are these days. It doesn't damage the large shareholder of course as their %age holding remains intact but it does wipe out the holding of relatively small holders. eg doing a 10,000 for 1 consolidation means anyone holding less than 10,000 shares would just get some level of cash compensation and would relinquish their fractional holding but anyone with 10,000 shares would have 1 share in the company and no cash, but importantly the same percentage in the new share structure. The idea is that everyone is compensated equally but that depends on the value placed on the cash equivalent of course. I can't remember off the top of my head whether that would require 90% or 75% of shareholder approval so may be worth checking.
Commiserations to holders here - days like this are very trying.
It does make things feel a little more casino-like than any of us would like. My wife always insists share investing is gambling no matter how hard I try to convince her of the differences via risk control and mitigation methods and benefits of knowing the investments and the market etc. You could argue today's scenario is avoidable if you never touch a share with a big owner majority holding of course - thus making my point on risk limitation - but you can never protect against everything. I myself have had a couple of left field disasters recently of entirely different kinds (thankfully I avoided iEnergizer as a third one would have been very hard to bear) and it does make one worry that the only way to avoid this fully is to succumb to collective investments and give up on individual share portfolios... but how boring would that make life?!
Back to iEnergizer (LON:IBPO) (and back to gambling!)- the dividend yield on this is now 30% in theory if they maintain the forecast dividend (a big if once privatised). If this were to fall heavily again from here before the delisting date to a point where the price was suggesting a dividend yield of say 50%, could there be a punt play on this for dividends? Obviously you would be entirely at the whim of the controlling owner (and if he decided not to pay dividends or restructure the business to pay him more via a salary or a management contract of some kind instead of dividends you would be stuffed) and you would likely be trapped in the shares with no exit route, but if you believe the owner will want to keep extracting money via dividends, and if it got to the point where it would only take two annual payouts to recover your entire investment and a third to make 50% profit and anything beyond that is just a very juicy cherry on top, then if you got lucky (e.g. the dividend trundled on for 10 years or more or the owner sold the business privately at a premium along the way and your shares got bought out) you could potentially bag a huge return on being 'stuck' with these shares if you bought in low enough. Punt money only of course and it's probably more likely you would never see a penny. Actually, thinking about it, even worse the majority owner could probably recategorise the shares into classes and cut you out of the dividends even if he wanted to keep paying them to himself only? (anyone know if this is possible without the minority shareholder being involved? I would imagine even if not currently they could just change the company constitution and make it possible if they saw fit?).
So yes, the above is probably madness, as you would have no control and potentially face a 100% wipe out and you may not get dividends even if there were any. But having said that, even while the business was listed you were essentially at the whim of the owner too and your only 'leverage' or control was to sell out of the shares (which as today has shown doesn't offer all that much downside protection) so as a pure thought experiment it's interesting to ponder the difference in risk between holding these shares yesterday at 300p on a 7.5% yield and buying them at say 50 or 60p and seeing them delisted. It also makes one consider the value (and more importantly the limitations...) of a liquid market and the 'protections' offered by the listing rules.
I am not really going anywhere with any of this and its very much a stream of consciousness. I almost deleted this without posting it since it's a bit of a ramble and doesn't really go anywhere or make any particular point, but I actually think there are some interesting threads above on:
(i) the nature of risk and risk management in the 'casino' we call the markets that it is worth taking a step back from our day to day portfolio chat to consider; and
(ii) what it means to be a small insignificant shareholder in a business, listed or unlisted.
BIACS
I feel sorry for everyone who is invested here, as fellow investors have pointed out yet another case of the AIM Casino and private investors being shafted yet again, MTR (Metal Tiger) delisted from AIM last month and share price as with IEN suffered severe share price drop. As covered IEN had excellent fundamentals on Stockopedia but this certainly hasn't prevented for some a massive loss, it ceratinly is a painful way for Investors to learn of risks involved even with shares that appear half decent.
Thanks BIACS and davidjhill for the helpful replies. What has surprised me about this one (due to my naivety) is the mechanism for the loss. I think we all know we are taking on risk with any individual company share, and have to diversify and take the downs with the ups, especially if we stray into small and mid caps. However I would normally expect a near complete loss of capital to be because the business model does not work out and the company goes bust or needs a huge placing, or (thankfully rarely) there are rules/laws broken (e.g. as unfortunately seen recently with WANdisco (LON:WAND) ). Its quite surprising that a single shareholder can legally, and fully within the rules of AIM, take most of the capital from all other shareholders in a £600m profitable company. Very much agree with the posters below - AIM (and ? main LSE - on quick look I cant see that this is just an AIM specific risk) could really do with addressing this, and its a painful way to learn more about risk!
Usually when a company lists there is a minimum free float of shares that is designed both for liquidity and to stop a single shareholder being over the 75% threshold that allows them more or less free reign. In this case I'm not sure how it was listed with a single 90% holder as I haven't looked at it as a company before.
Certainly whenever assessing a share look at the shareholder register. Anything over 50% would be a red flag to me as the company is really being run for a single shareholder at that point.
It stinks which ever way you look at it. AIM need to sort this out, what is the point of investing if the majority holder can just delist and you lose 75% of your money. No incentive to buy shares if this is possible.
What really gets my goat it that our Chancellor assumes that our profits are a given and taxes without allowing for the risks we take in this casino.
My morning smallcap tweet: Dancing to the City's tune or sitting out?
Sureserve (LON:SUR) Thruvision (LON:THRU) iEnergizer (LON:IBPO) Kelso group (LON:KLSO)
◄Sureserve (SUR)► 125p rec offer, a 39% premium [SP=NA Cap=NA]
◄Thruvision (THRU)► guides FY-Mar rev up 48%, adj EBITDA loss c.£0.2m (£1.7m). In line? [SP=24 Cap=35m]
◄iEnergizer (IBPO)► proposes de-listing. Blames costs, 17% free float and listing unlikely to provide significantly wider access to capital; [SP=310 Cap=587m]
◄Kelso (KLSO)► will provide an update on its Proposed Placing next week. Buys CFDs in THG. [SP=3.11 Cap=6m]
Good morning. Noticed an RNS late yesterday from battery metals and recycler Technology Minerals (LON:TM1) (I hold) that a certain Jonathon Mark Swann has taken 7% if the company. I assume this is the ‘hi net worth’ individual who invested a chunk of change in this company. Is he known? I see an underwriter of that name.
Morning, does anyone know how cancellations work? Re iEnergizer (LON:IBPO) announcement today
iEnergizer (LON:IBPO) Sell at the opening bell.
Interesting thread here in the comments section about the CEO and the dangers of a large shareholder whose interest is not aligned with shareholders: https://www.stockopedia.com/co...iEnergizer
Not wanting to start yesterdays long back and forth again but what you have posted here is a perfect example of what would not have been found in the discussion tab when researching iEnergizer (LON:IBPO)
I would find it useful if we could find any comment made on a particular stock by any of us.
It shouldn't be a big deal to implement that additional feature Albm7 as generally people who have anything useful to contribute on a stock will include its stock code in the post.
Yes I agree as long as we all use the correct ticker format (which most of us do) it should be possible - I realise that with limited resources Stockopedia cannot do everything but I think it would be a useful enhancement. I will send a message in at least to raise the idea formally.
On this 'quiet' Friday we will all be checking back on the free float figure in our investments. Thanks very much for the link laurie.
Great spot laurie - how on earth did you manage to find that?
I found out something yesterday which explains how Laurie found this post and which isn't generally known I suspect. To recover a post that you remember posting yourself or if you remember another person posting, click on the person's user name or your own user name and you get the user profile. go down the screen and you'll see "Activity". Click and you'll see posts going back in date order.
I found out something yesterday which explains how Laurie found this post...click on the person's user name...and you get the user profile. go down the screen and you'll see "Activity". Click...
That is true, Samsgrandad.
Additionally, I use this method to read the posts of people who appear to have an in-depth knowledge of a particular company, sector or situation. I have also read pages of posts by people who have written something particularly insightful in an attempt to find any other helpful comments that I may have missed.
There are many people here who have substantial useful knowledge and long memories. I am grateful to those who share their thoughts.
It usually works when the share price is at a low, never on a high, and its other name is daylight robbery. I don't hold iEnergizer (LON:IBPO) but as a PI have been caught out unguarded several times.
iEnergizer (LON:IBPO)
Market value of the minority last night £102m
Market value of the minority a few minutes ago £21m
Market value of the majority I would argue has been enhanced.
"Following careful consideration, the Directors believe that it is in the best interests of the Company and Shareholders, taken as a whole, to seek the proposed Cancellation at the earliest opportunity."
I really don't think so !
(Don't hold)
Sureserve (LON:SUR) Just received a bid from Bidco of 125p I hold
Sky business flagged this last night. Slater and Hardwood have backed the offer. So looks done and dusted.