Small Cap Value Report (Fri 21 Jan 2022) - PHTM, ECEL, OTMP, WRKS

Good morning, it's Paul & Jack here with the last SCVR for this week. We've been so busy with numerous company updates, that the whole week has gone by in a blur, I can't believe it's Friday already. If it's quiet for news today, then we have plenty left over from earlier this week to circle back to.
Weekly audio (and written) summary
Jack & I have recorded another weekly summary on audio, click on link above.
Please bear with us, as we tweak the format, and trial various ideas. Over time we'll improve audio quality, and where we publish it. At the moment I'm just publishing the audio on my personal shares website, for convenience. There's now a donate button for ZANE on there, if you're feeling generous.
Agenda -
Paul's Section:
Photo-me International (LON:PHTM) - a controversial takeover bid at 75p cash, from the CEO (largest shareholder). Where's the bid premium? This looks a poor deal for small shareholders, who have endured the losses & uncertainty from the pandemic, only to see the post pandemic upside now being taken away from them by the CEO.
Onthemarket (LON:OTMP) (I hold) - when is a profit beat not a profit beat? When they decide to start capitalising development spending! Overall, this update reassures rather than scintillates.
Works Co Uk (LON:WRKS) - a very good update. This looks good, with strong trading, and divis likely to resume. Digging a bit deeper though, the cash pile is needed to pay heavy trade creditors, so not surplus cash. In the absence of broker forecasts, I crunch my own numbers, concluding it's pretty good value, but not as cheap as it looked at first glance on that eye-catching £15m EBITDA guidance.
Jack's Section:
Eurocell (LON:ECEL) - strong sales momentum and FY profit before tax to be slightly ahead of the consensus figure of £26.5m. Ongoing cost inflation is being mitigated by price increases and surcharges. There are also a couple of growth projects that should help the group in the medium term. It’s not the kind of stock that has ever traded at a premium valuation though, so I wonder about the upside from here.
Preamble from Paul
People seem to like my general market/macro ramblings, so I'm getting up very early to do more of them.
Some snippets of recent news that caught my eye -
US markets continue to be under pressure. In particular, the £COMP is now down over 10% from its recent peak, in a rapid move down. Even the biggest tech shares are now falling (although still near highs mostly for the mega techs), partially masking much bigger falls in many highly rated, rapid growth shares.
Netflix - plunged 21% to $405 in after-hours trading last night, as earnings beat, but subscriber growth outlook slowed. It peaked at c.$690 in Nov 2021, and has since fallen 42%. It still looks too expensive to interest me.
Peloton - a glamour stock of lockdown in 2020, peaking at $160 in early 2021, is now just $24 - a drop of 85%.
There are loads of other examples of US shares where people ignored valuation, assumed rapid growth would carry on forever, and have been brutally reminded by Mr Market that valuation does matter, and rapid growth eventually reaches a ceiling, as competition is attracted by the opportunity.
Personality cults - are a typical feature of speculative bubbles. Fallen angel Cathie Wood has totally lost the plot now, claiming that her wildly over-priced momentum stocks are cheap, and that there’s a stock market bubble - in value shares! Why do people find it so hard to admit they got it wrong? How long before Elon Musk loses his cult-like shiny gloss? I think the clock is ticking there, before Tesla shares return to earth (with a re-usable rocket?!) in valuation terms. Tesla the company is doing well of course, but the shares' valuation is at least 10x what seems reasonable to me (disclosure: I'm short of Tesla shares, but like the cars!).
Inflation - inflation is all around us now, for how long, nobody knows. Probably quite a while, as companies reporting in my space are often only talking about price rises now, yet to be implemented in many cases.
BT has announced a whopping 9% rise in its prices for internet & landlines. Although it says that’s only £3.50 per month per household, on average. I don’t begrudge paying more for internet, as it’s vital. But paying for a landline that I don’t want is really irritating, literally gathering dust, and serving one function only - to allow one elderly relative to ring me occasionally, as she flatly refuses to call my mobile, even in an emergency.
Lots of other costs are going up too, as we know. Although inflation is an annual measure, and if supply chain pressures ease, then the pressure to continue raising prices would also ease, and the annual rate could fall back again in 2023 possibly? Who knows. That’s what happened in 2008 and 2011, when (from memory) spikes in the cost of oil, and forex movements drove up inflation, which then washed through the system and returned to normal, as you can see below -
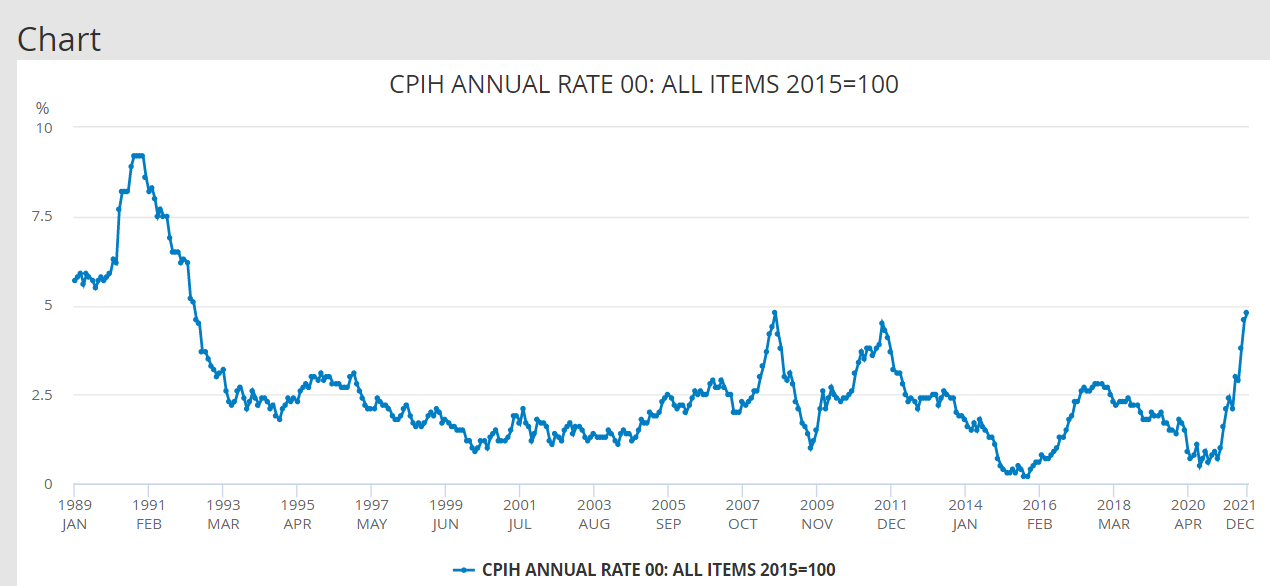
Remarkably, as you can see from the graph above, we’ve not had persistent, problematic inflation since the late 80s, early 90s, when the Lawson boom turned to bust. So why would it return now?
We have had massive asset price inflation though, which isn’t measured in the official consumer price index figures.
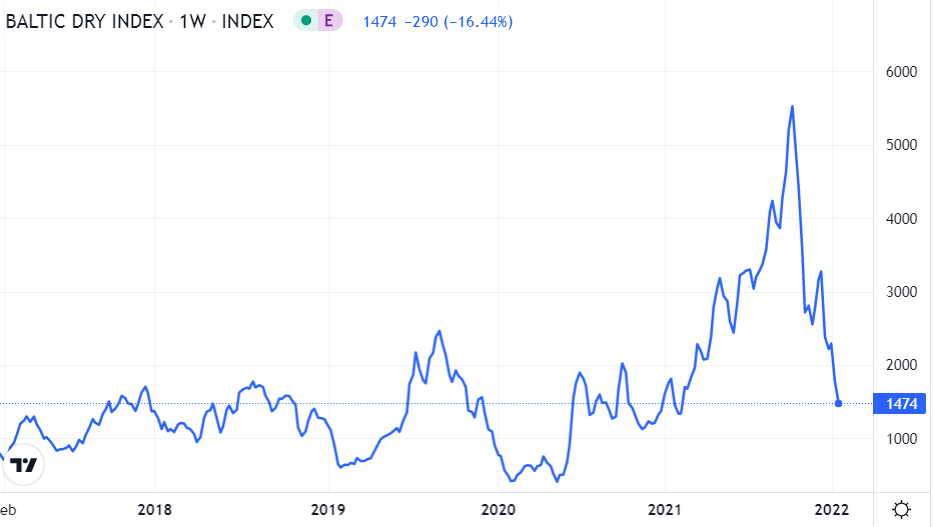
Supply chain - possibly some positive early signs of improvement? The Times says freight rates are now falling, and the supply chain crisis could be over. Do any readers have expertise in this sector, if so please do post a comment about what’s going on.
Doing some googling, I see that the Baltic Dry Index has indeed plummeted (source: here) -
.
I don’t know how that feeds through to costs of container shipping though, which is probably more relevant for most of the shares I cover, importing containers from the Far East, rather than the raw materials covered by the Dry Index.
The only chart I could find on the cost of container freight shows very high rates still -
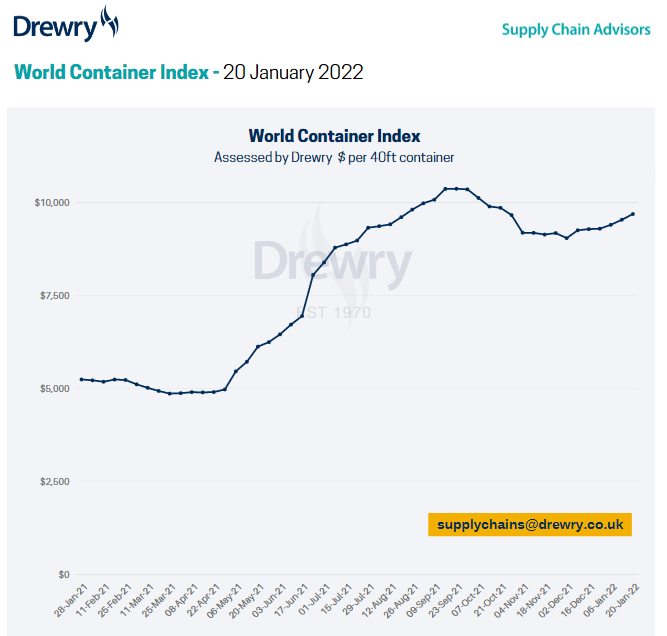
With thanks to both websites, for their charts - I hope it’s OK for me to copy them here.
The other question is whether UK companies book their freight costs in advance, or just pay spot rates? Companies should be disclosing this. It seems to me that a key risk has emerged in this area, forward contracting the cost of freight looks very important. The same with utilities, and digital marketing costs - these highly volatile costs can make or break companies that haven’t hedged their costs or secured long-term pricing (if possible).
The danger now might be that CFOs lock in long-term deals at elevated prices, so it’s very tricky knowing when to fix costs (if you can at all).
Anyway, I’m only bouncing ideas around here & trying to figure out what’s going on, none of the above is my area of expertise, so I encourage readers to DYOR and post comments if you have expertise in these areas.
Demand distortion? I had an interesting chat with a friend yesterday, and he reckons that the shift from people buying holidays/entertainment to buying physical stuff during the pandemic (which is mainly what has caused the supply chain problems, according to Fed Chairman Powell, since import volumes are up 20%) - could have pulled forward demand for consumer durable goods. So he reckons we should be careful not to assume that bumper profits generated by some companies in that sector in the last year or two will carry on.
That’s certainly helped cause the big de-rating of eCommerce shares. Although I reckon there could be an opportunity now, with possibly structural, normal rates of eCommerce growth returning in 2022, showing that these are still growth companies. It’s just that growth was pulled forward into 2020, then plateaued in 2021, it hasn't stopped altogether. Growth could resume in 2022, who knows?
There’s a lot of uncertainty out there at the moment, so shares are particularly hard to value.
I think it’s essential to keep away from anything on a really punchy PER, and with high growth assumptions at the moment - given that these are very much the shares that are being sold off so brutally in the USA. We seem to follow the USA, in everything. The slightest disappointment in growth rates, and shares collapse, as we saw with Netflix last night.
Or, a contrarian might see these as buying opportunities, for growth companies that are now more reasonably priced? I’ve been looking at US companies, and the trouble seems to me, that even after huge falls, a lot of growth companies still look too expensive on conventional metrics, like price earnings, or price to cashflow.
I’ve never accepted price to sales as a sensible valuation metric, because it ignores margins. Hopefully we might see that valuation method come under more scrutiny.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul’s Section:
Photo-me International (LON:PHTM)
75.6p (y’days close) - mkt cap £276m
I think there are likely to be a lot of miffed private shareholders here today, and bulletin boards overflowing with indignant messages.
The CEO, Serge Crasnianski wants the upside for himself, so has bid 75p cash (no premium) to buy the whole company.
He already held 28.8% of the company, and is buying another 7.7% (at 70p), which has triggered a mandatory bid under the Takeover Panel rules (going over 30% requires a bid, unless an exemption has been agreed).
The announcement says borrowings have been lined up through Credit Agricole Bank to finance the cash bid.
My opinion - this looks a bum deal for smaller shareholders, because there’s no bid premium. We don’t buy shares to have the upside whipped away from us, especially for people who held during the difficult pandemic times, and now face losing the upside on post-pandemic recovery. That’s not nice, but I suppose people can always vote against the deal, and refuse to sell their shares. But where would that leave things? Someone controlling the company who doesn’t want external shareholders involved.
The share price had been rising recently, and it was tipped as a main buy recommendation a few days ago in SCSW magazine, which might have pushed up the price, or it could have been insider dealing from persons unknown who knew a 75p bid was coming possibly?
There’s been no dilution during the pandemic, with 378m shares in issue for quite a few years now.
The forward PER is only 9, and the company’s prospects have been improving. Although there has always been inadequate information about which divisions generate the profit, and the longevity of photo booths (almost certainly the main profit generator) is in doubt.
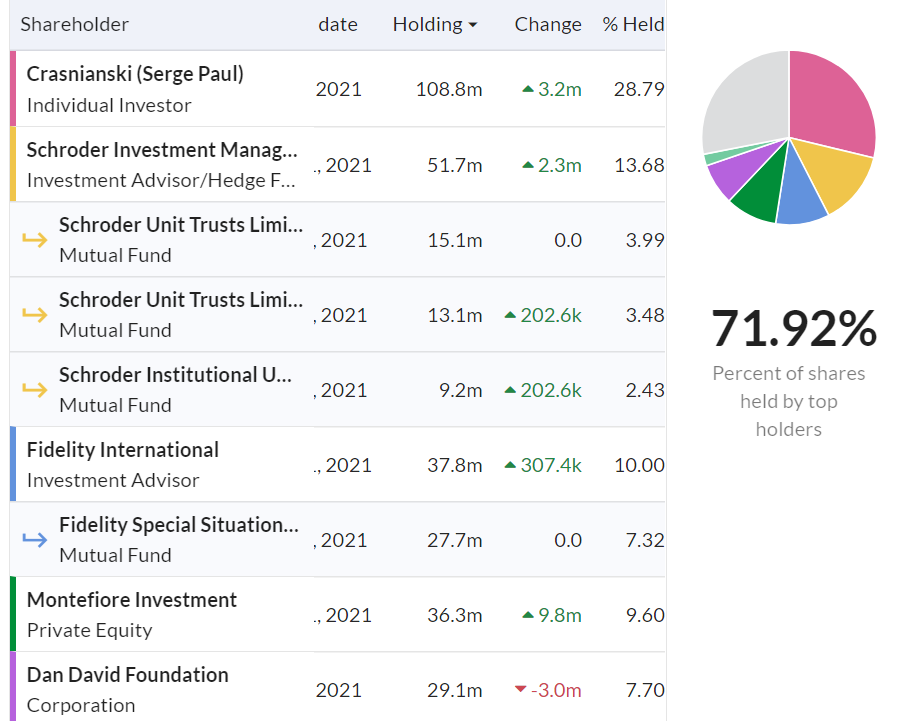
Looking at the shareholder register, the bidder already holds the biggest (pink) wedge, and looks like they’ve just bought the green wedge, as that’s 7.7%. Therefore, the decision is going to be made by the 3 remaining large holders - Schroders, Fidelity, and Montefiore. If they agree it, then this looks a done deal. Hopefully they might negotiate hard for a higher price for everyone - over to you, Andy Brough (Schroders), kick some ass!
In less liquid shares like this, institutions often welcome a liquidity event, of a takeover bid, as it enables them to exit and move on. That might be different to how PIs view the situation, as we can sell any time in the market.
.
Onthemarket (LON:OTMP) (I hold)
121p (up 1.7% at 09:01) - mkt cap £90m
OnTheMarket plc, the majority agent-owned company which operates the OnTheMarket.com property portal, is pleased to announce the following update on trading.
Company headline -
Adjusted operating profit1 ahead of expectations
The current financial year ends on 31 Jan 2022, imminently.
Trading sounds quite good -
The Group's operational performance has continued to be strong through H2 21/22 and revenues for the full year ended 31 January 2022 ("FY 21/22") are now expected to be slightly ahead of market consensus.
The Company's focus on disciplined operational and cost management has continued.
Profit guidance - is positive, but has a sting in the tail - development spending is being capitalised, which boosts short-term profits. We need to know a figure on that, to ascertain how much of the improved profit is due to this accounting policy change. That’s not provided, so we’re in the dark, and that’s why the share price hasn’t changed much, I reckon -
When combined with a higher level of development investment in the new website and brand launch that will be capitalised rather than expensed as incurred in the income statement, the Group now expects adjusted operating profit1 to be positive in H2 21/22 and to be at least £2.5m for the full year FY 21/22.
Outlook - unchanged from last update.
My opinion - I like the strategy of the newish CEO, who seems to have injected some impetus into the business, with fresh ideas for developing the services provided to estate agents & website visitors.
Subjectively, I thought the latest TV ad was quite good (can’t find it on youtube). Previous ads had a group of people singing a catchy tune. I’ve told you this before, but I’ll never forget the facial expression of the former CEO when I sang his own jingle to him, in an investor meeting at Shore Capital’s office! (It had just been on the radio. I’ve not been invited back, strangely, probably due to the pandemic). In my head, the jingle merges with the Village People - “On the market” to the tune of “In the navy”. But that’s just me.
OTMP is generating decent subscription revenues now, and covering its own costs. So as long as the CEO doesn’t blow the cash pile on marketing & do another placing, then I’m happy with the speculative upside here.
As a wild card, shrewdie Christopher Mills, spoke very highly about OTMP in a recent interview with Paul Hill on Vox Markets. He said that his fund, Harwood, is sitting on the market (!!) bid, mopping up OTMP shares, but just can’t get enough. It surprised me that he would reveal this, as it greatly improves risk:reward for me - knowing that there is a large buyer in the market, mopping up any sellers, puts a floor under the price presumably?
Overall then, I find today’s update reassuring, rather than earth-shattering.
I do love Paul Hill, he's so irrepressibly enthusiastic about the markets! I've told him he interrupts too much, but he just said he can't help it, as he gets so excited, lol! Christopher Mills has a fantastic track record, so well worth listening to.
OTMP is mentioned from 15:10
.
Works Co Uk (LON:WRKS)
63p (up 12% at 10:00) - mkt cap £40m
The Works, the multi-channel value retailer of arts and crafts, stationery, toys, and books announces its interim results for the 26 weeks ended 31 October 2021 (the "Period" or "H1 FY22") and an update on current trading.
H1 revenues +17.9% over pre-pandemic levels - looks good, but the period covered (May-Oct 2021) had (I think) unrestricted trading, and may have benefited from pent-up demand from the lockdown in early 2021?
Like-for-like (LFL) figures are always more useful, as this strips out the effect of new store openings, and store closures, to give underlying performance - and this does look good -
Strong two-year LFL (1) sales growth of 14.5%, ahead of the Board's expectations. Store two-year LFL sales increased by 7.3% and online sales by 80.7%.
Still loss-making in H1 though, but at least a positive EBITDA means it should be generating some operating cashflow -

Cash is up a lot - which surprises me, so I’ll look into where that cash has come from -
Further strengthened balance sheet as net cash balance increased to £17.8m (H1 FY21 £9.3m).
Current trading - they say it’s strong, but has slowed from the +17.9% in H1 (vs 2 years ago) -
Sales in the 11 weeks since the end of the Period have remained strong, with a two-year LFL growth of 9.0%. |
EBITDA guidance - this looks very strong, and suggests there must be a heavy H2 seasonal bias, as H1 was only £2.5m, so H2 would be £12.5m - that’s a lot for a company with a £40m market cap! -
Overall good trading performance is expected to more than offset significantly increased container freight costs; Pre IFRS 16 Adjusted EBITDA for FY22 is forecast to be approximately £15.0m, assuming no further COVID related impact on trading, ahead of the Board's previous expectations. |
Dividends - we're told divis are back on the agenda, if actual results for FY 4/2022 are in line with guidance.
EBITDA/PBT - I’m obviously quite taken with that £15m EBITDA forecast, so am looking back to previous results to determine how much of EBITDA turns into actual profits.
The company reports pre-IFRS 16 EBITDA, which is good, because that properly accounts for rents on leases. Whereas post-IFRS 16 EBITDA is absolutely meaningless, because a lot of the rents by-pass this figure and end up lower down, in finance charges.
Here’s the previous pattern:
FY 4/2021: Adj EBITDA £4.3m becomes adj PBT of £(3.6)m loss, worse by £7.9m
FY 4/2020: Adj EBITDA £10.8m becomes adj PBT of £2.4m profit, worse by £8.4m
FY 4/2019: Adj EBITDA £13.9m becomes adj PBT of £6.9m profit, worse by £7.0m
If we take the average of the 3 previous years, adj PBT is £7.8m worse than adj EBITDA. Therefore the £15.0m EBITDA guidance for this year (FY 4/2022) becomes £7.2m adj PBT for this year. Take off say 25% tax (in future years, so I want to use that rate now), is £5.4m earnings, divided by 62.5m shares in issue = 8.6p per share. At 63p per share that’s a PER of 7.3 - which looks good value.
That’s the current year though, what happens when business rates, a substantial fixed cost, kick back in again in future years?
Unfortunately, I can’t find any broker research, but I imagine with big cost headwinds on the way (rising wages and business rates resuming, in particular), it might be difficult for WRKS to grow profits any further, any time soon? But that depends on future sales growth, and future gross margins, which are unknown, as they are for almost every company.
Business rates relief - I'm raising a question mark over this. It's not clear how much benefit WRKS received from business rates relief in H1 TY. However, note 1 (b) (iii) mentions re-stating last year's numbers to move the business rates relief from operating income, into cost of sales. Fine, it doesn't change the overall profit result last year. But it'a a massive number: £7.2m in H1 LY. My question being, how much of this year's profit is coming from business rates relief? It could be highly material, if it's anything like last year's number, and of course it's being phased out. So a very large headwind for next year, by the looks of it.
Business Rates Relief
In the FY21 interim accounts, business rates relief was disclosed within other operating income, with cost of sales including the gross rates payable figure. This treatment did not accord with required practice and therefore these items have been restated in the comparative figures. The business rates relief is now reflected via a £7,215k reduction in cost of sales (from £85,219k to £78,004k) with a corresponding reduction in other operating income (from £12,276k to £5,151k). There is no impact on the overall H1 FY21 result.
Balance sheet - NAV is £10.2m, less intangible assets of £2.3m, gives NTAV of £7.9m - at least it’s positive.
IFRS 16 lease entries are £102.8m RoU asset, less £27.9m + £94.5m liabilities, a net position of £(19.6)m deficit.
Eliminate these entries, and NTAV would rise to £27.5m, which is actually quite healthy. Although most of that is made up of arguably worthless (resale value) shop fittings.
I don’t see any risk of insolvency, whilst trading remains positive.
Cash generation looks amazing, but it’s heavily boosted by favourable working capital movements (around £20m benefit in H1!). It looks like H1 benefits from a seasonal improvement in working capital, which then reverses somewhat in H2, judging from last year's numbers.
Trade payables are enormous at £64.3m, so the cash is going to be needed to pay these down. Last year trade payables dropped by £28.2m in H2, for example.
So don’t get carried away with the “half the market cap is cash” argument. I would treat the £17.8m cash pile as being a favourable, seasonal blip, rather than genuinely surplus cash. I’d like to know the average daily cash balance, which I suspect would be considerably lower.
My opinion - the outlook for this company has clearly improved tremendously, compared with in the early stages of the pandemic, when it looked precarious.
I can see the appeal of the shares, but on closer inspection, it’s not as cheap as it initially looked.
Overall not bad though, and the product ranges are interesting, with not much competition on the High Street. I can imagine this share might have further to run. It looks like one of those companies that has been improved during the pandemic, and managed to get through it without diluting shareholders. However, remember that this was a troubled company before the pandemic hit, having flopped after listing, and has a real question mark over what it was for, why it existed, and would it go bust if negative trends continued. Then the pandemic hit. Has it really been transformed into an amazing company over the last couple of years? It's a lot better, for sure, but I'd like to know .
I'm also worried that profits may be receiving an unsustainable, and large benefit from business rates relief. It was £7.2m in H1 LY (last year) for example. It might be less this year, but could still be boosting profits artificially & unsustainably. That's the big question that investors need to find the answer to.
.

.
Jack’s section
Eurocell (LON:ECEL)
Share price: 266p (+3.5%)
Shares in issue: 111,972,477
Market cap: £297.8m
Trading update for the year to 31 December 2021
This is a vertically integrated UK manufacturer, supplier, and recycler of PVC products.
Eurocell’s strong sales momentum has continued in the last two months of the year, supported by good underlying demand in its markets. Having navigated ongoing cost inflation and supply chain pressure so far, the group expects profit before tax will now be slightly ahead of expectations.
The analyst consensus profit before tax forecast for 2021 is £26.5m.
Group sales for the six months to 31 December were up 23% on 2019 comps and up 7% year-on-year (with 2020 having a very strong second half). Full year revenue was £343m, up 23% on 2019 and 33% on 2020.
Here’s the divisional breakdown:

Demand in the repair, maintenance, and improvement (RMI) market has moderated from unprecedented levels seen in H2 2020 and H1 2021 but the sector ‘remains strong’ going into 2022. Profiles (+22% on 2019) has benefitted from good contributions from trade fabricators and another strong performance from Vista Doors. New build sales have improved in H2 ‘as housebuilders focus on achieving year end completion targets’.
Building Plastics was positive across Eurocell’s own-manufactured products and traded goods, supported by a strong order book, with 12 new branches opened in the year (taking the total estate to 219 sites). Four of these openings are a new, larger format.
Eurocell expects raw material constraints to ease over the coming months and has so far mitigated cost inflation with selling price increases and surcharges. Price inflation became a larger part of sales growth as the year progressed.
The group’s recycling plants have also ensured its supply of resin. This seems like a slight differentiator.
These plants supplied 27% of our raw material consumption for the year (2020: 25%), driving significant cost and carbon savings compared to the use of virgin material.
That’s a respectable figure. I wonder if there is room to grow this?
Net debt ex-leases was c£11m as at 31 December 2021, down slightly on £10m a year earlier, and reflecting the ‘substantial’ impact of inflation on working capital.
New Warehouse and Manufacturing Capacity Expansion - fit-out of a new state-of-the-art warehouse is complete. This will increase capacity and operational efficiencies. Management is ‘optimistic that operating performance will exceed our original expectations’.
The 2021 manufacturing capacity expansion, including 5 new extrusion lines, together with the associated mixing plant upgrade and tooling, is also now complete. Another 5 lines will be added in 2022. The combined investment will increase extrusion capacity by more than 15%.
Diary date - full year results to be released on 18 March 2022.
Conclusion
This looks good - not just in terms of the market backdrop, which appears set to remain favourable, but in Eurocell’s significant growth investments which should allow it to capture more market share.
It looks like the group was consistently growing revenue pre-Covid.

Financial health scores are positive, as are the profitability metrics. Although operating margins and returns on capital have been on a declining trend. I wonder what’s driving this - competitive pressures, rising costs?

Still, the track record so far is enough to generate a strong Quality Rank of 97.
It doesn’t look like Eurocell has ever traded on particularly high multiples, so today’s forecast PER could be fair value. Possibly on the cheap side given the outlook and growth initiatives but then again there is the declining margin trend and cost inflation to consider.
PBT will be slightly ahead of £26.5m, so let’s call it £28m. After subtracting a notional 20% tax charge, that would make for 20p of earnings per share and an FY21 PE ratio of 12.8x. I suspect the valuation is about right given its industry, although the company does appear to be executing well.
A good operator perhaps, but one I’d be more interested in at a bit of a discount.

Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

123 comments
CEO of Photo-me International (LON:PHTM) had to make mandatory offer as his holding went over 30%. So why is Sagi at Kape Technologies (LON:KAPE) allowed to hold 54%?
Another week of great updates. Tell me, how are you shorting Tesla as I’ve watched its rise and rise beyond excessive, through exceptional to unbelievable.
I don't like the idea of a short in Tesla..what with them being electric!
To me shorting Tesla is like a Test Your Strength! fairground attraction. Its more about proving something to yourself e.g. I am fit and strong; the world is rational etc . But the point is, its the fairground owner who always take the money, whatever happens.
Yours faithfully
Trident (A 7 stone weakling!)
Re: Inflation. I watched an interview with Mark Bristow (CEO of Barrick Gold) this AM. He mentioned that they were minimising wage inflation in North America by managing the age of their employees i.e. employing younger people is cheaper! I thought that was an interesting comment. I didn't know, but it seems age discrimination in the US only applies to people over 40.
Re: Jeremey Grantham. For those that don't know, he is a well-known value investor who has been wrong for 12 years. About a year ago he claimed the S&P500 was in a bubble and was going to crash. It didn't. Now we've seen a few weeks of price weakness he has put his head above the parapet again with a new buzzword "super-bubble". You never know... this time he could be right! But when you've been wrong for 12 years I have no idea why anyone would bother taking you seriously anymore. If others find him interesting, then fine, but we're much better off ignoring these talking heads that pop up on Bloomberg and CNBC. We need to stick to things where we can add value, which means finding good small and mid cap companies to invest in for the longer term.
All the best, Si
Subject of Jeremy Grantham always being wrong reminds me of BBC news dragging out Bob Beckman to comment on the crash Black Monday 1987, because he had predicted it! Well yes he had but a few years before and the crash in 1987 took the market down to a value that was twice as high as when he wrote his book The Downwave!
I remember going with my Dad to a talk by Bob Beckman about the Downwave in the early 1983 perhaps? I can only have been about 12. I learned never to believe anyone who thinks they know how the world will be.
I remember as well, when I was young, seeing this guy Bob Beckman on a television programme claiming a lot of things would go bust including a lot of banks. I remember thinking that he was either very clever, telling it as it is, or a conman or a bit of both. It was a moment that stayed in my mind. Banks going bust seemed unthinkable at the time, the odd one yes. He must have been clever, if true, to have made a million by the age of 26, which is what he claimed. Although losing it by the age of 27. His next million taking 13 years with a more careful approach.
Although not looking for it, years later by chance, I found his book 'The Downwave' (published 1985) in a charity shop. It is based on the 'Kondratieff Wave'. Later I found his book 'Into The Upwave' (published 1988). In 2012 a journalist wrote, 'Into The Upwave was published in 1988, but some of it is so relevant now that they might as well save money on economists and read the first few chapters out loud on the Ten O'clock News every night.'
Haha agree Si - a broken clock is of course correct twice a day. The problem with perma-bears is that because stock market corrections/crashes are fast and furious (thus great fodder for the Media who love bad news) when they are finally right everyone thinks they are a hero. For the rest of the time they are just wrong, and presumably losing money, which we don't hear about. As with most commentators they talk their own book and most so called experts have poor track records of predictions......but hey, you've gotta wheel someone out to talk sagely in the media!!
I have no idea where we go from here but I don't think the tech / data / space narrative medium term story has remotely gone away. It was definitely frothy, so a 10-20% correction always seemed likely at some point on the tech indices and we are around the middle of that now.
I have no idea where we go from here but I don't think the tech / data / space narrative medium term story has remotely gone away. It was definitely frothy, so a 10-20% correction always seemed likely at some point on the tech indices and we are around the middle of that now.
Well, you’ll never get on Bloomberg TV admitting you don’t know with great certainty what happens next :-)
I agree that a pullback was necessary in Technology et al. and not unexpected at some point. As such, it seems a healthy thing to happen. Next week will be important in the US with Microsoft and Apple reporting. Meta, Amazon and PayPal the week after.
All the best, Si
I have a Tesla Model S, bought just over 5 years ago. Now with over 100 000m on the clock. Cheapest car I have ever had! With 100% capital allowances (bought through my company), huge BIK savings, no congestion charge, next to no service costs (still on same brake pads and disks) and free electricity courtesy of Tesla superchargers, I am saving bucket loads of money against the Audi I would have been driving. Has let me down once in 100k miles and that was covered by warrantee. And it's great to drive. I'm going for 200 000m.
When V2G (vehicle to grid) becomes mainstream I can start earning money from it as well.
I have a Tesla Model S, bought just over 5 years ago. Now with over 100 000m on the clock. Cheapest car I have ever had!
Yes but it's cheap to run because it's electric, not because it's a Tesla. I can't see how Tesla can maintain a major competitive moat once the big boys really get going on electric, as they are.
It’s cheap to run because there is no tax on the electric, if you took the tax off petrol it would different. This is an issue Govt. need to tackle one day. The problem is depreciation on EVs, for me it would be far more expensive to run an EV never mind a Tesla. How long will the batteries last? Cost to replace could right some of them off.
. How long will the batteries last? Cost to replace could right some of them off.
With regard to Tesla the tests they have run on battery performance have been remarkably acceptable all things considered. I think some other companies have much larger issues with degradation compared to Tesla.
https://electrek.co/2020/06/06...
Real-world data showed that Tesla battery degradation was less than 10% after over 160,000 miles (257,500 km):
More recent stats available that are beter but these come from Tesla
According to the company's data, the average vehicle battery in Tesla should still have about 90% of its original capacity after 200,000 miles (322,000 km) of usage.
https://insideevs.com/news/525...
Certainly those numbers seem reasonably decent to me if you are lucky enough to be in the average bracket.
. The problem is depreciation on EVs,
https://www.buyacar.co.uk/cars...
I think each survey will show different results so my chosen search may not statistically prove anything but looking at lists of slowest depreciating vehicles electric cars seem reasonably well represented. On the above selected recent link Tesla model s came in as the best ie depreciated slower than everything else.
"The rise of Tesla has been meteoric to say the least, and the all-electric manufacturer’s Model S holds on to its value at a similarly impressive rate."
I was talking more generally than Tesla batteries. I don’t think use is the issue , it is more to do with time, judging by my lithium batteries, they are ok for 5 years but then go down hill quite rapidly after that, so it’s a concern if buying a used EV which is around 5 years old. I won’t be buying one for another 5 years because the range of older ones is just too low. If I can buy a 5 year old Golf type for £10k, I may do that, with range of 200 plus miles. If the batteries only last around 8 years then that could be a real issue, unless battery costs come down considerably.
Depreciation depends on the starting value, my car depreciates around £1k per year, but a £70k one, is likely to depreciate much more in £s, even more if the batteries only last 10 years.
Quite a long torygaff article the other day on battery life (paywall removed) https://12ft.io/proxy?ref=&...
Typical estimate seems to be forecast 2.3% pa loss of capacity, leaving say 80% after 10 years or 70% after 15. But obviously limited real world data so far and in practice may look more S-shaped. Also affected by host of environmental/useage factors. Note that they all now incorporate lots of clever tweaks, eg inhibit too frequent fast charging as that shortens life. As others have said, look at lease rates to get a feel for likely residuals.
I do feel the industry missed a trick in not going down the path of swappable battery packs. As far as I know, only Nio has championed this. Crazy world where EU wets its pants over the trivial issue of iphone charging cables yet ignores major initiatives like this which, if properly thought through, could have substantially reduced the need for expensive fast charging stations cropping up everywhere.
Thanks that's somewhat reassuring. Doubt I will be around in 15 years time anyway. By then it's predicted, by some, that we won't own cars and the will be driverless. I think it will take longer than 15 years, many things do. Some were predicting, most people would be buying EVs in the USA, by 2021, that never happened.
Yes I thinking changing batteries is an issue and the cost of them. Shortage of lithium could be an issue and there are enviromental concerns about lithium, switching away from lithium maybe a good thing. Other issues is where is all the electric going to come from if people do switch from petrol/diesel to EV and also switch heating from gas to electric. At the moment we are using around 40% gas to make electric, we are even still using coal when it's not windy. Recyclable only produce around 25% of our electric production, we are also importing around 10% from various countries. Problem is if its cloudy and not windy then recyclables produce next to nothing, some days it's down to around 7%. Solar in winter is very low in the UK, often around 1% on average. The only answer seems to be nuclear but that takes many years to build, around 10 and is unpopular with some people. Here is the live UK electric production: https://grid.iamkate.com/
"If the batteries only last around 8 years then that could be a real issue, unless battery costs come down considerably."
I think you are right to be skeptical about picking up any second hand ev - i would guess there will me massive variability for some time to come (and then some if some makes fall off a cliff unexpectedtly after that ) . I remember watching an telly program a while back and they were specialists at adding range to ev's - so perhaps over time more garage type businesses may morph into doing a tart up of vehicles by removing or adding to the battery packs , thats unlikley to ever come particulalry cheap. so i guess value wil be what someone is willing to pay i guess a car that only does 50 miles might still have some use to some if they know they are paying bottom dollar rather than top dollar. Could easily see it being a trend if battery tech moves on well that keeping the shell of your old car and simply replacing batteries and other bits and you might be good to go for another 10 years.
My neighbour just bought a diesel Kia. He enquired about the hybrid and was warned that a replacement battery pack would cost £15k. And as the initial price was £10k higher and it was his own money he chose the diesel.
I thought the free Tesla charging had stopped now?
Yes if you live in London and do high mileage I can see the benefit.
The other factor that will keep shipping rates high is US and Chinese port congestion. There are huge numbers of ships tied up, not moving. That means less supply for U.K./EU moves AND the sky high China to US rates (20%+ than Europe) incentivise carriers to put any spare capacity onto those routes.
As noted above this isn’t going away until mid 2023 save for a huge recession.
Following the many comments regarding the fall in the value of growth share (particularly in the US) its important to remember that while many stocks are down big on the surface, it is not the same as saying they are cheap or a bargain. If it turns out that future earnings growth was pulled forward, and future growth rates have been sacrificed, then these stocks may have much further to fall, especially as rates rise.
Not my words. An interesting article from another web site
https://www.investing.com/anal...
Another way of saying "value does matter" DYOR
hi Paul and Jack.
Thanks for getting up even earlier for the ramble. Much appreciated. Regarding Tesla, I have spoken to several customers of Tesla recently and one also talk of them being a cult. He said they were more interested in welcoming them to the club (cult) than in selling them the car. His view of the car he owned was terrible. Overpriced and poor quality with the cheapest cars starting from £65k, we’re very lacking in mod cons.
Another customer loved them though, despite having broken down 3x and needing a new battery at a cost of £15k.
I think a short is a good idea with them. What I find crazy is the amount of money our government is throwing at Tesla in the uk. It is this money that makes Tesla profitable in the uk. So how much longer will the government keep giving them grants?
I forgot to mention the first person I spoke to about Tesla was talking of getting rid and going back to petrol.
Tesla doesn't get grants in the UK because their cars are more than £35k.
https://www.gov.uk/plug-in-car-van-grants
that was just something I’d read somewhere. Maybe it was another country. Will have to see if I can find it again.
ahh found it. You are quite right that Tesla does not receive grants from the UK as they have stopped now. Back in 2020 they apparently received £613m from grants in the UK.
https://www.investorschronicle...
This is the article;
An Investors’ Chronicle analysis has found that state grants for Tesla motors soared as their popularity rose last year, before the government decided to exclude expensive vehicles like those sold by Elon Musk’s company from the scheme in March. Now industry watchers are questioning whether these incentives were necessary in the first place, arguing that Tesla will continue to lead the UK electric car market even without the grants.
According to the IC’s review of public disclosures, the transport department spent at least £61.3m lowering the price of new Tesla cars for UK drivers in 2020 — equivalent to almost £1.2m per week. That’s 66 per cent more than it spent in 2019, reflecting a surge in sales of Tesla vehicles in the UK after the company launched a right-hand drive version of its popular Model 3.
Tesla is not the only carmaker to benefit from the state funding — since 2011 the government has invested at least £1.1bn in the scheme, which currently aims to incentivise sales of zero-emission vehicles by paying up to £2,500 of the purchase price for plug-in vehicles. But, as Brits rushed to snap up Tesla’s trendy motors, the taxpayer has recently spent far more subsidising its cars than those made by other companies.
Of the 19 carmakers identified by the IC as beneficiaries of the scheme in 2020, none received as much as Tesla through the programme. That year, the transport department paid more than twice as much to Musk’s company as it did to BMW (DE:BMW), Renault (FR:RNO) or Hyundai (KR:005380) — manufacturers that have all produced more affordable electric vehicles than Tesla. Now analysts and campaigners say the initial decision to include higher-priced cars in the scheme was an oversight by the government.
Reading the article I see you have missed a decimal point in your Tesla UK subsidy. It was £61.3m, not £613m
Yep my mistake again. Think it’s time for me to get those reading glasses.
gmtrader
ahh found it. You are quite right that Tesla does not receive grants from the UK as they have stopped now. Back in 2020 they apparently received £613m from grants in the UK.
Hmmm sketchy
That article link doesnt work i did find an article that mentions £61.3 million exactly a tenth of your quoted total (decimal in thw rong place?) and it looks like its the customers grant not tesla's
https://www.investorschronicle...
Seems clear they are simply talking about the subsidy that is given to the buyer of electric vehicles - so its the purchaser benefiting here from the discount not Telsa.
It's clear on the direct gove website that this is the case.
https://www.gov.uk/plug-in-car...
You can get a discount on the price of brand new low-emission vehicles through a grant the government gives to vehicle dealerships and manufacturer
It might be they did get £613 million in grants but would be useful if you could provide evidnce please if that is the case.
Peloton was always overpriced because the market size for at home equipment is very limited but they ultimately fell from grace because their pricing structure was all wrong other than during 2020 lockdown when they could get away with charging £35 pm.
The issue came when iFit and Nordictrack came out with the same equipment, better training content in locations like French Polynesia, Lake District and the Alps etc for £7 pm (1/5th the cost).
This is where the equilibrium for home training pricing is in normal times given the discretionary nature and ease of copying.
Netflix, however, I think commands a high price and the total returns back that up. At 5600+% total return since IPO in 2002 from buyback etc, it is a world leader in content in the Western World and is only just getting started in India, APAC and LATAM at the end of last year and they will focus on native content. (Only ~34m customers in each)
It also went into gaming on their app in Nov and it is their next big move to provide the best content for both and the CEO stated last night they will pursue acquisitions to achieve this.
On a PE basis 40x is high but when you dig into the $2bn in capital costs last year you see why it is only 12x EV/EBITDA which is on par with much worse companies.
The best thing about strong proprietary content is that it lasts forever for new customers and they get more value for money.
They increased UCAN prices 10% in Q4 2021 and still added 1.2m customers (albeit out of 75m currently).
I haven't owned Netflix and been put off by the price but will buy into this weakness as I don't see any real challengers for content - Apple TV and Disney are largely a flop with Disney being better due to Star Wars branding alone (Marvel has been rather poor).
Onthemarket I used to own. Bought at 60p and more at 33p on the dooms days after covid. However, I sold at 95p about a year ago or so as I lost sight of the strategy but it does seem the new revamp is much improved and might get them to take some of the enormous market share held by Rightmove. If they do that, the ROE could be very good but it requires a lot of funds to break that cycle.
I mystery shopped TGI Fridays (bournemouth) branch again yesterday for lunch. Well, I say "mystery" shopped, but I've clearly blown my cover by complaining about the diet coke again (which was completely flat. Again!). So they've rumbled me as the person who complained to H.O.!
On arrival, I asked if the fizzy drinks have been fixed, as they've been flat for the last few weeks. Yes, the waiter assured me. Definitely? I pressed with a smile. Yes, definitely, replied the charming waiter, also smiling with his eyes (he was wearing a mask, so I couldn't see his mouth).
Then a flat diet coke arrived. Grrrr. So of course I complained.
The absolutely lovely waiter tried to fob me off, saying oh that's just how diet coke is, compared with normal coke. I wasn't having any of it, firmly but fairly rejecting the flat diet coke ("Come on, you wouldn't drink that, would you?"), asking for a bottle instead, and commenting that I would need to complain to head office again, who had already promised me it would be fixed (in my interview with the CEO earlier this week).
Then my sorry reflex kicked in, as the waiter looked like a puppy that had just been kicked. Oh my God, he thinks I'm a terrible person now, "Sorry. Yes, sorry, I hate to complain" I heard myself saying, whilst thinking that he should be saying sorry to me, not the other way around!
Anyway, I got a fresh, fizzy diet coke in a bottle (pictured below), and some tasty & well presented food (avocado hummus, and Louisiana chicken burger - very tasty, but look how thin the chicken burger is (half-eaten picture below).
Anyway, the bill arrives, and I'm generally happy. With a 10% tip, it's £25 - which is expensive, there's no disputing that. But I could have had a free rendition of happy birthday from the staff, if I'd told them it was my birthday, but it wasn't, so I didn't.
As I'm about to pay, the Manager, Josh (also lovely) appeared, knelt down so I didn't have to look up, and reassured me that they had received a message from Head Office about the fizzy drinks not being right, and an engineer has been booked, and should fix the drinks machine very soon. I left the restaurant very pleased, that the company Hostmore (LON:MORE) (I hold) is indeed responsive to feedback.
To be fair, I've also had excellent service at Fulham Shore (LON:FUL) nearby (Franco Manca & The Real Greek).
hi Paul
As an aside, I was in Wimbledon on Tuesday with some friends. After a few drinks we had a wander looking for somewhere to eat. One of the options was Franco Manca but we were put off as there were only 3 people eating in. This was around 8 o'clock. We found an Italian restaurant which was very good. On returning and walking past Franco Manca I noticed it was still vitually empty - this was at 10 o'clock. I've just checked the Trustpilot reviews for that outlet - average score 3.5 with 20% of 205 reviews either poor or terrible. Not good.
The nearby one in Southfields is reliably full and good. Branch specific problem?
That looks truly awful food to me and why not have healthy sparkling water rather than Diet Coke ? You really need to see a nutritionist Paul. We don’t want you popping off before your time :)
Hi Paul and all
I noted various comments about Tesla $TSLA. Most being bearish and even shorting.
If you have not dug quite deeply into Tesla it might be useful to take a look into the multiple segments of Tesla's growth strategy.
They are becoming an energy company through their Powerwall technologies and its abilities to feed excess power back to the grid for compensation from an energy supplier.
They are becoming a necessary energy storage utility to support wind and solar energy generation. Such installations will evolve to support energy balancing across the whole grid system (in US).
Their Solar panels business is correcting itself. Which is a close companion to both its Powerwalls and Telsa cars, offering a complete home (and small community alterative energy source).
Tesla are way ahead of others with regard to autonomous vehicles, the associated AI and now specialised high performance chips (Dogo).
Tesla are significantly more efficient in their manufacturing capabilities than others with highly automated factories and high degree of robotics expertise.
Their battery technologies are some of the most efficient around (some new technologies are catching them up).
Also, Tesla have a large portfolio of EV charging stations which they are opening up to other types of EVs so they are in the EV energy supply space (think petrol stations).
Adding to these strategies Tesla are rolling out factories across continents. China, Berlin, California and now Texas. There have been speculations about a Russian factory.
Clearly much can be identified as jam tomorrow. But, I am firmly of the opinion Tesla ought not to be assessed as a car manufacturer. Possibly an energy company, or an AI software company in addition to being a transportation company (cars, vans, lorries etc), and in the near future a robotics company.
I expect many on here will disagree with me, but thought a slightly wider perspective might prompt some other bull comments.
FWIW I proactively ignored Tesla for quite a while thinking it was hype. Then I began to dig deeper and have become an investor (for the long term) but expect to have to ride quite a few ups/downs.
Regards
Howard
I agree. Once you dig deeper, this is an amazing company with massive growth, long runway, widening moat and optionality. Not many people appreciate the ROIC and operational leverage.
Sure, it will need to execute, but they've got through the hardest part and I don't think it's as overvalued as many people perceive.
Rivian, on the other hand...
Howard,
I'm sure all of that is true.
But how much is Tesla worth? That's the area of dispute - valuation.
Regards, Paul.
Tsla
I see your logic here Paul much less risky bet at £1 trillion than $50 bill as i think we would all agree you cant keep growing that exponentially that quickly that EASILY (not sayinmg its impossble to get to $5 trill though)
What many who have shorted Telsa though fail to concede is that they got it wrong when they though the company was overvalued at $50 billion - reality is the valuation was right (probably conservative) and it was their lack of understanding how good tesla tech and design is that led then to understate how good the company were back then. The solid foundations of how good they are now were easily visible back then. Whats that saying once a fool .....
If we look at expected FCF come end of 2022 - you would have to be pretty pesimistic(silly) to presume tesla aint worth at least at least $200bill at the minimum - unless you are part of the group who believes everything they say and do is either a lie or a fraud. Tesla are even barely on track to do all they had plans to do with these great numbers (no cybertuck yet)
ref fcf - from the net
Therefore, using this measure, Tesla could reach $11.3 billion in FCF on a run-rate basis by the end of 2022. This is the result of multiplying a forecast 15% FCF margin by the revenue estimate of $75 billion.
Personally stick a finger in the air and $500 bill doesnt seem silly with potential to get to $1 trillion and beyond if they carry on and or gain momentum. I can see ahy soemone would short but i can also see they may end upa loser here.
Musk being musk i bet he would love it if he could take apple on head to head with mobiles and destroy them and do similar with a tesla operating system - unlike Keegan i reckon he could do it. Watch that space - the mere announcement of the tesla mobile phone could easily add $500 bill to the market cap and probably will do if its the all in chips variety of this is betetr than iphone in every area.
Lets be frank would anyone bet on apple beating telsa on head to head battle on tech and design - IMHO anyone who would choose apple as winners there is likely to be on the wrong side - although to be fair to apple they have probably seen this coming and are probably preaping for the battle teh best they can by using their own chips and design now etc - hmm somewhat copying what tesla do.
I could be wrong that this will end in tears for Tesla - certainly think his ego is such that he has it in him to do something silly - but with the valuation they have they have a great position form which to do well.
Tesla batteries are too expensive, even Tesla thinks so. "Oct 21 (Reuters) - Tesla Inc (TSLA.O) wants to shift to a less expensive battery for its electric vehicles but first needs to figure out how to overcome political tensions to get a Chinese partner to build the iron-based batteries near its U.S. factories."
Have you seen how much those batteries cost for the home?
The issue with Tesla is they did not produce a hatchback for the European market and their cars are far too expensive to be mainstream.
I agree an innovation company but the valuation looks over the top, even Cathie Wood is getting out.
Spot on and the Iron Phosphate batteries come from CATL (chinese) and it is their proprietary tech which they license to Tesla but also BYD and Enphase (for home battery use which is another thing people say Tesla might get into but seems unlikely with Enphase far ahead of them on the technology for this such as inverters and off-grid use etc.).
BYD and Chinese automakers have 13 of the top 15 best sold EVs in China.
The idea of 8 years 50% YonY growth (to achieve 10x PE in 8 years at $1trn valuation) was dependent on Tesla taking a big share of the Chinese Market - they are largely failing at that.
I would also point out they haven't made a new car for several years while VW etc brought out 5 EVs last year alone........
Many reasons to be bearish Tesla from a business perspective.
Hi Jack, my first posting, so hope its of interest to people.
I own 4 businesses in the UK, we import circa 300 - 20 and 40ft containers a year, we are too small to book freight rates ahead, shipping lines simply won't let us (and we work with one of the UK's largest freight forwarders), we were paying US$1,000 - $1400 for 20 and 40ft loads, we are currently paying $16,000 for 40ft's and $10 - $12,000 for 20ft's, and sure it's eased a little lately, we were paying $18,000 for 40fts.
We are being told not to expect things to get back to normal until 2023 (When new ships will be launched)
It costs circa $250,000 per day to hire a container ship, and to sail from China to UK takes 20 - 25 days. A lot of the super sized company's are simply hiring ships to carry their cargo, this is leaving the rest of us short on capacity. And sure the likes of Tesco can block book containers, but they will still be paying 6x more+ than they were in 2019.
Freight costs for my businesses have risen from 3% of our material cost to 8%, thats 5% price increases for my clients.
Wages - My team will get a 4% pay rise this year, and 5 of my team will get more than 10% because they are key employers, they know it and have had their hands out. My wage bill was 4% of my product cost, its now nearly 6% and rising - Wages are not taken back.
Now throw in heating, UK logistics, packaging cost increases etc, we are at least 10% up across the board.
My businesses are food ingredients, we've passed on perhaps half of these cost increases, and later this year we pass on the other half (It takes 6 months to get increases through, and we are not certain of what else is coming) and we supply producers, producers take a further 6 months to pass price increases through to the consumer.
(Lest we forget, we are in business to make money, so any tax rises/NI increases/Pension costs etc - it ALL gets passed onto the consumer at some point)
I hope you see where I am going, it will be end 2022 (In the UK), when the consumer see's the full impact of mine and the producer price increases, and another year before/if/perhaps those prices come down, remembering wage inflation is permanent.
Lastly, and for the sake of doubt, I do a round table with 5 similar sized SME's in my region of the UK, we help each other and have done this past 2 years, one makes fabrics, another certain parts of sports shoes, another furniture, and another is in logistics. ALL our businesses are booming, and ALL without exception are singing from the same hymn sheet, its 2023 onwards before we see any kind of relief, so we are passing costs on.
Just my opinion of course, but when the public and institutions realise inflation will remain 4 - 6%+ for the next couple of years, and interest rates unlikely to get past say 2% (Without crippling both government, and public purse), I see a significant rethink of valuation calculations, everywhere. Buy low, sell high, but most of all, have fun. Cheers, Nick
Nick, excellent first post and very interesting. Thanks.
Re Nick Barnes posting.
Very interesting, Nick. A most informative and intelligent post.
Excellent.
Many thanks Nick, getting this sort of insight from business owners is very valuable and much appreciated.
Hi Nick,
A great insight into whats happening to prices & inflation in the real world.
I Appreciate your explanation why prices are going to increase through 2022. However, prices don't have to come down for inflation to come down. Providing you don't have to put your prices up again next year then the inflation rate comes down year on year.
Thanks again and I hope your business does well.
As one with memories of 1970s inflation I'm always troubled by the potential wage-price spiral. We accept that raw input costs (energy, commodities etc) can wax and wane on a whim but wages are strictly one-way in Western economies (is that a record for initial w's?). So inflation rates tend to be stickier when declining than perhaps logically they should.
Many articles now on people wanting to quit for easier conditions and top law grads now trousering £150k pa https://www.bbc.co.uk/news/bus... and https://www.cityam.com/half-of...
yes indeed, and the problem is when people start accepting big rises in the costs of things and demanding higher wages, and then spiral gets going and is really tough to stop, then we have to try incomes policies etc. The truth of it is, we had huge inflation which was only controlled by Mrs Thatcher, by a massive recession and very high unemployment, people don't strike for higher wages when they fear for their jobs. Then after that we signed up for the free movement of labour within the eu. Now that obviously meant you didn't have to pay more you just paide people from poorer countries in Europe. Now all that's gone, along with a surge in demand for physical items rather than holidays. Now that will reverse, possibly as soon as this summer, and that might swing too far the other way, as people who haven't been abroad for a couple of years, rush there. (exporting inflation to those places and causing more here as holiday prices go up through supply and demand)
If we learnt anything from the 70s and 80s it's that once inflation gets intrenched it's really hard to shift. And it eats away at peoples savings, while they can earn nothing in interest in the bank to offset it (that was the root of the destrest mortgage crisis), here the governments have screwed things up by having such low interest rates, and compounded it by being late to move them up, and on top of that having the help to by scheme extended (help to ramp up prices more like) followed by a stamp duty holiday.
So now we have lots of people with huge mortgages who can only afford them because rates are low, we have huge national debt, we have a government who through help to buy owns 10% or 5% of a lot of properties, so they're exposed to house prices too. So the thing to do (like the irishman said when asked for directions " I wouldn't start from here" ) is to start raising rates earlier, unfortunately now, so man people are trapped by the expectations of low rates, rates haven't risen since before the financial crisis, (apart from the recent tiny one). pushing up rates to take the heat out of inflation would be very painful indeed, it would hurt not just consumers but the government too. plus letting it rip, well think of the advantages, that debt we've built up, gets inflated away. I really hope I'm wrong, I really hope that inflation drops back in the summer, when demand changes and that some prices will fall again, why wouldn't raw materials fall ? surely energy costs will fall back ? solar and wind must be very profitable at these elevated levels, why wouldn't more be built to satisfy demand and stop using gas to generate electricity ? why would wood prices stay high if demand falls ? etc etc,
not many remember what it was like, really hope we don't end up there again,
Cheers K
Jack did a great pitch on Centralnic (LON:CNIC) in the Stockopedia/PIWORLD StockSlam this week. Here's the recording including of the whole event which covers 'slams' on Henderson Smaller Companies Investment Trust (LON:HSL) Frasers (LON:FRAS) Getbusy (LON:GETB) Shield Therapeutics (LON:STX) Jade Road Investments (LON:JADE) Premier Foods (LON:PFD) Bango (LON:BGO) Time Finance (LON:TIME) Beazley (LON:BEZ) Centralnic (LON:CNIC) All the pitches are great, and shows the very broad mix of investing styles of the PI community. The Slam only happens because of the Slammers and the great community, so if you'd like to take part in the next one, 6th April 6pm, please get in touch! Video & podcast.
In the next few days, we should have the recording of the Accrol Group (LON:ACRL) H1 webinar.
I think at one stage this week, you might have commented on Alliance Pharma. (I hold) Seems to be doing well, and perhaps in an area less likely to be severely buffeted by these storms.
Jeremy Grantham's latest views are here. Very bearish as he has been for some time.
LET THE WILD RUMPUS BEGIN* (Approaching the End of) The First U.S. Bubble Extravaganza: Housing, Equities, Bonds, and Commodities
Jeremy Grantham's latest views are here. Very bearish as he has been for some time.
Yep. Just like the clock on Grantchester Church it's forever ten to three. At least the clock is right twice a day, unlike poor old Jeremy.
All the best, Si
To be fair to Grantham he does have a better record than most at picking market tops.
To be fair to Grantham he does have a better record than most at picking market tops.
That's not saying very much though, is it? It is only MHO, but only an idiot would think they can forecast future moves of something as random as the stock market.
All the best, Si
Paul - the formula used by BT for annual price increases is December CPI +3.9%. CPI was 5.4%. The same formula is used by Vodaphone but TalkTalk add 3.7%. https://www.moneysavingexpert....
Think yourself lucky you are not with Virgin. They use RPI + 3.9%. RPI was 7.5% in December but I think they use the January figure.
As for the telephone part of the package that is really in for free with the broadband - in fact my Plusnet (part of BT) bill shows the landline charge as nil.
Zen internet promise not to raise your charges while a customer, so you don't get annual inflation related charges
Many thanks Paul for your update on Onthemarket (LON:OTMP) AND for including the access to that Christopher Mills/Paul Hill interview. WOW! It’s well worth listening to and discovering why he is SO enthusiastic. I already hold as a potentially very exciting long term lockaway (though short term share price performance is good too and up 30% since their results in October). Having listened to that interview I’m more convinced now.
e.g I realised that Rightmove was on a much higher rating but not how much higher! Rightmove at 15 times sales compared with OTMP at just 2 times.
Paul, be careful shorting £TSLA shares. It hasn't worked out well for others!
Alan,
Paul, be careful shorting £TSLA shares. It hasn't worked out well for others!
I'm very much aware of that! But I think the timing is looking a lot better now for some carefully selected large/mega cap shorts.
A friend lost a £7-figure sum shorting Tesla. He just got steam-rollered by its totally illogical rise way above any rational valuation. Amazing company, and a visionary leader, but it's more a cult than an investment now. That makes it very vulnerable to a correction, sooner or later.
However, now the valuation is about £1 trillion, there's not much further up it could realistically go.
I've sized my short so that I could cope with it doubling in price from here. That's the trick isn't it - position sizing.
Regards, Paul.
It is not just position sizing if it is a SB short. If market falls, VIX goes up and SB firms increase margin and deposit requirements that can make it difficult to finance. I remember 2008 when I had margin requirements go up 16 fold.
However, now the valuation is about £1 trillion, there's not much further up it could realistically go.
I know what you mean. It's a psychological barrier. I thought the same when $AAPL got to $1tn. Now it's 3 times that...
Hi Paul, a quick note to say I am also a big fan of your general market comments. Regarding growth stocks another "asset" that is tumbling is Bitcoin et al. In addition the property developer debt situation in China is starting to look pretty serious. It would be good to hear your views on how important or not these factors might be.
Yes, it will be interesting to see how Bitcoin moves over the next few months. Aficionados will quite possibly see the future as bright as they may see it as a hedge against inflation (the total number of bitcoin being fixed). But on the other hand, those that are in it for high risk speculation may see it as exactly what they do not want to hold in a risk off environment and sell out. If it comes back down to earth, let’s hope that it is not a crash landing.
Bitcoin moves almost in sync with the speculative end of the market. How it hedges inflation or remains a 'true store of value' is completely beyond me. If the market goes so will Bitcoin et al.
On the subject of macro market analysis I am perplexed as to why a ‘correction’ in Nasdaq (see John Auther’s note this morning) should see a significant fall in our indices. The financial media regularly bemoans the lack of large technology companies in our main indices arguing that the prevalence of ‘value’ type shares (Energy, Banks, Miners, etc) is a drag on performance. As we see this morning when there is a blip on Nasdaq our markets always take a hit - it doesn’t seem logical to me but then as someone once said or something similar (Keynes?) ‘markets can stay irrational longer than you can stay solvent’!
It's a good day to read John Auther's e-mail. He graphs the trading during the day and shows the fall was all an indiscriminate sell-off in the last hour. We are back to a "risk-off" sentiment and the key word for me is "indiscriminate".
+1
I fully expect to see lots of indiscriminate movements across many shares, when so much of the market is "owned" by passive funds like ETFs.
Brilliant for individual stockpickers. DYOR and have a list of what you think are good quality shares, and their bargain prices. And just wait. For the indiscriminate selling to force those prices to levels where it is a no-brainer to buy.
Of course... depends if you have the skill to pick quality companies. Nd calculate the no-brainer pricing...
Interesting, I am short on Tesla and have been for a couple of months as often referenced on DT investing comment. On my estimation, to justify its valuation, Tesla will have to win around 50% of the global car market and at sector defying margins - not going to happen. The e-car space is becoming crowded and the best cars coming through now are not from Tesla.
I just don’t see how a Tesla short position can fail from here. I do see Tesla as the best shorting opportunity in the current market. About 10 times a fair price is how Tesla is currently valued. But as ever with all things investing, patience is required.
I’ve avoided investing in Tesla for the reasons you described. This has meant missing out on the most spectacular gains, but it has never made sense to me as a long term proposition, unlike big tech.
I can see, and agree with, your logic about Tesla. But this is perhaps a case where Maynard Keynes's words are particularly worth bearing in mind - “Markets can stay irrational longer than you can stay solvent."
The is a growing perception now that Tesla is grossly over priced. Other, smaller high priced tech that is priced no more crazily than Tesla is already crashing out. I have a keen interest in cars lasting for over 40 years. Primarily Tesla have to displace Toyota. You just have to look at what Toyota have achieved with their GR series of cars. I recently bought a GR Supra 2.0. An efficient car with astounding power delivery and balance, the car is a design marvel, a completely addictive drive.
Not an e-car I know, but the GR range demonstates just how innovate Toyota have become, Toyota will produce e-cars that are superior to Tesla going forward. Plenty of other creative brands out there, all of which Tesla will have to commercially annihilate if it is to justiy its valuation. I can stay solvent for a long, long time. Tesla is now the big short of this market.
Over 95% of my positions are long, but if a little more liquidity becomes available to me and Tesla's price stays high, I would like to increase my Tesla short further.
Toyota will produce e-cars that are superior to Tesla going forward
This has been my view all along. That the highest quality auto manufacturers like VW and BMW would bring their centuries-old experience of coachbuilding and chassis design to bear on the creation of electric cars that offer a better overall experience. Certainly Tesla's interiors, handling and build quality have disappointed this consumer so far. I also question how broad a marque can get and still appeal to all its potential customers - yet that is necessary for Tesla to achieve the scale its valuation envisages. The cachet of the Mercedes brand has been much diluted of late, for example.
But it's important not to ignore the alternative viewpoint eloquently argued by Howard and long espoused by Baillie Gifford.
Agree, the majors are not standing still. The Mercedes Vision EQS looks better than anything Tesla have to offer. OK still not in production & expected to be £100k + so perhaps not a vaild comparison.
Tesla certainly have had first mover advantage for a while but the others are catching up fast.
I've always been of the opinion that it's madness to short a company like Tesla - you might ultimately be right but the popularity and support of story stocks and those that do actually have huge growth potential means that you're likely to be shafted long before you're proved right. There must be easier shorts out there. But totally ignoring my own advice, I did actually open a very small short position against Tesla last night - if it's ever going to tank, then it feels like this is the time. I do think it's an amazing company though - just wish I'd worked that out earlier and bought them a few years ago!
"I just don’t see how a Tesla short position can fail from here."
Channeling Dickens:
Short 1 share of Tesla at 1000. It rises to a peak then falls to 100
Spreadbet account balance 1000, Share price rises to 1996, result happiness.
Spreadbet account balance 1000, Share price rises to 2006, result misery.
"I do see Tesla as the best shorting opportunity in the current market."
Channeling me:
In 2007 I said housing was overpriced and there will be a big fall. One day I will be right. Currently patiently waiting.
There was one in 2008!!
Hi Paul, another chart on freight rates below - this tracks cost of shipping 40ft containers on the Baltic Index (as opposed to Dry Bulk, which the Baltic Dry tracks). I think this is probably more relevant to consumers goods (although also not an expert) but is unfortunately not showing the same declining trend as Baltic Dry and is a similar shape to the global container chart you have above.
Source is here: https://fbx.freightos.com/
Hi Paul - you said of the BDI - "I don’t know how that feeds through to costs of container shipping though". Short answer is - it doesn't! They cover entirely different and distinct parts of the market and a precipitous slump in the BDI does not mean the same is coming for container freight rates since the cargo and industry sectors involved are different. Most in the industry seem to think high container rates are with us for at least another 6 to 12 months - possibly beyond. There can be times when the two move together for various reasons, but this isn't often the case - for example the price of shipping coal or grain is not very closely correlated to the cost of shipping TVs and clothing.
Cheers!
BIACS
I’m fortunate to receive updates from my bank’s economist daily. As I’m a growth investor it hasn’t made me conspicuously successful recently - although my wife and mother are getting terrific results by doing as I say, not as I do.
His comments are a useful counterpoint to the typically backward-looking sensationalism of the mainstream media. Importantly, he sees inflation as having peaked already in much of the data he surveys. Martin Sandbu in the FT agrees https://on.ft.com/3rzaj0N (subscription required)
Economists have form for misreading the runes and the bank’s economist admitted to me privately back in October that he was then unsure of the trajectory for inflation. He seems more confident now that the data has started to roll over.
I’m not going to make any projections but I would pick up on your point, Paul, that inflation is a measure, not of prices, but of change in prices. Investors are worried that prices might stay high. But if prices have risen 7% in Autumn 2021 and then rise a further 3% by Autumn 2022, then inflation is 3%, not 10%.
As Sandbu explains with far more clarity and depth than I’m capable of, tackling inflation is all about freeing up supply chains and shifting demand from goods to services. And those, in turn, depend on the trajectory of the pandemic and the ability to re-open. I share the worry expressed elsewhere that China’s zero tolerance approach to Covid might have bottled up a big potential spanner in the works.
While this plays out, cyclical and value stocks look much safer, but markets decided on that view back in November and growth has taken a big hit already. US banks, which should be the biggest beneficiaries of rising rates, have been smashed after earnings reports that have disappointed. My feeling is that no segment of the market is particularly secure today, including energy, which has had a good run. Any further spike in the price of oil could kill demand. After all, the best cure for high prices - is high prices!
I might elaborate on this in a future post, but the choice, if you share my view that we will endure a choppy spring, is either to sit out the market like a trader or to remind oneself that one is not a piggy-backer but a business owner. Ask yourself, is the underlying business performing to your satisfaction? If so, then sit back, enjoy the progress of your companies, take whatever dividend you earn, and wait until such time as a company’s performance disappoints, or the market makes you an offer you can’t refuse.
Hi BnB,
Fantastic stuff, I agree with all of that!
Regards, Paul.
Thank you for this - really interesting read!
The two big unknowns, when we look at company performances in the last year, are the following for me.
Hence, I think the next six months will see many companies warn on growth, or even go to ex-growth, based on the two things above, whether they're B2C or B2B.
On China, it is clear that if there is an increase in outbreak, the policy response will be zero-COVID lockdown policy. Right now its negligible - tens of millions of people only, a few spots nationwide. But if there ever was an outbreak in large cities or regions, where we see hundreds of millions in lockdown, this will have a huge impact on production, and global goods supply. Not to mention the hit to China GDP growth, and the country is also increasingly a big consumer of goods/services from abroad. Less so for the UK, but more impact on the likes of Germany, USA, Japan.
My betting is that it would be foolish to assume no more outbreaks in China. It just keeps leaking in. A small hit to GDP. Minor, localised hit to supply chains. Best case - we get small ones, sporadic, all controlled well. Worse case - it spirals out of control, and for 1-3 we get zero-COVID lockdown measures, until the government gives up and accepts its endemic, in the worse case scenario.
Companies can't keep "stocking up" forever
Yes, inventories have been building up and that might ultimately lead to a big drop in demand for products like semiconductors. But it's also disinflationary. Rising inventory in US autos for example, where inflation has been rampant, offer a promise of moderating prices.
I'm with you on China as the biggest wild card, as I stated in the original post.
Where is inflation going? What further influence will the pandemic wield? How far will the Fed push rates? How extensive will the Fed's balance sheet reduction be? I think this level of uncertainty is giving investors plenty of reason to take money off the table right now.
I seem to recall you writing that you're quite tolerant of volatility. Compared to professional money managers we are blessed by not having a benchmark or competitors to be compared to. Who else cares if you beat the index or outperformed Terry Smith? We should hope that, by owning strong companies which perform well across the cycle of macro conditions and valuation regimes, we'll be intellectually stimulated throughout and financially secure when it matters - well beyond today's volatility.
I think this level of uncertainty is giving investors plenty of reason to take money off the table right now.
yes, the problem is what do you do with it, it's depreciating quiet rapidly as cash, how to get a return, on something that isn't likely to fall in value, that's the challenge !
I find it quite difficult to press the sell button to liquidate at, say, an average of 10% down on portfolio with no prospect of putting it anywhere which will make money. I recently invested in Liontrust (tipped by several as their share of the year) which has promptly dropped 15%! If I wait 2 years it might come back, otherwise I just crystallise that’s loss now.
Paul, Jack if today is a quiet day would you be able to comment on yesterday's TU from Luceco (LON:LUCE)
They seem to have navigated supply chain issues well & have been successful in passing cost inflation onto customers so they must have pricing power. Probably a long term term hold for me.
Dennis.
Re Photo-me International (LON:PHTM) , as I understand things, it is mandatory for Crasnianski to make an offer for the whole company as he now holds over 30%. Perhaps all he is doing is meeting this obligation.
Its up to other shareholders to decide what they do about this. There's no suggestion that its mandatory to accept the offer. Presumably 75p is the lowest offer Crasnianski can make and who can criticise him for setting it at that level?
Photo-me International (LON:PHTM) nonetheless very cheeky having snuck his daughter onto the board last year.
The offer doc tries to suggest they are doing shareholders a favour because liquidity is low with minimal daily trading. Of course this is because shareholders (I hold) have been patiently waiting a return to normal trading in photo booths whilst enduring significant write-offs off company assets whilst cash flow has gone into building the laundry and fruit juicing businesses. So in some respects one could argue that Crasnianski has been keeping the valuation depressed whilst simultaneously preparing the business for a very successful future at the expense of current shareholders!
Also says “If the Offer becomes unconditional, Bidco does not intend to procure that Photo-Me makes an application to cancel trading in Photo-Me Shares on the London Stock Exchange or the listing of Photo-Me Shares on the Official List.”” Does that mean there will continue to be an ongoing market in the shares?
Hi Paul
Many thanks for the interesting preamble.
On the subject of inflation I think that we are perhaps further away from the end of supply chain disruptions than we realise as China is still pursuing a zero Covid policy of locking down huge cities even if they have just one or two cases. Additionally, if the Ukraine situation goes badly the price of gas in Europe could go higher. And of course, economies are so interconnected these days, one small component made in some far flung country can bring a whole production line to a halt somewhere else.
So, I very much doubt that we can have a good idea of what inflation is going to do. Economists and central bankers forecasts for GDP are often wrong to a significant degree and so I have no faith in their inflation predictions either.
The problem for China is that the approach of lockdown is not an easy way through, and they are in effect prolonging the pandemic. They operate a sort of Covid traffic light system on mobile phones (which practically all Chinese have,) which determines relative levels of movement freedom, and for Shanghai, this has changed from green recently due to a few cases there. Its always foreigners, or foreign goods that have imported it, according to the news there, so hard to tell what the actual situation is. Therefore travel is likely to be more limited as we approach the Chinese New Year, although some have left early to avoid restrictions. Its beginning to take its toll on the economy, with jobs less easy to get. I can't see how they will avoid Omicron becoming endemic, but whilst I can understand their worry that the Health system could be easily overwhelmed ( if you want to see an over worked, tired and under paid Doctor, go to a Chinese State hospital) as the Health system runs pretty hot most of the time. This is a political Gordian Knot for the CCP, but loss of political face would be hard for them to take. Its also a fine line on whether they will damage the economy if they choose to be intransigent, as few are spared when full lock downs occur. The only blessing is that Chinese winters are relatively short, but of course more mixing is a boon to Omicron. What this means to the West and supply chains is hard to call, but doesn't bode particularly well in the short term.
I think that the zero Covid approach in China will have to change eventually as Omicron is so infectious but I can't see it happening before the Winter Olympics are over. They are scheduled to run from Feb 4th to 20th and anything going wrong there would indeed involve loss of face.
Guys,
Any chance you can have a look at Works Co Uk (LON:WRKS) ?
Highlights...
Revenue increased by 30.6% compared with H1 FY21, 17.9% compared to pre-pandemic performance (H1 FY20)
Strong two-year online sales up 80.7%
Net cash £17.8m - H1 FY21 £9.3m - 50% of Mkt Cap
Pre IFRS 16 Adjusted EBITDA for FY22 is forecast to be approximately £15.0m
The Board proposes to bring forward its review regarding dividends, with a view to recommending a final dividend for FY22 provided the preliminary results to be published in late July 2022 are in line with the forecast noted above
Thanks in advance
Morning matylda!
Sure, I'll look at Works Co Uk (LON:WRKS) next. CockneyRebel has been on to me, saying it's interesting, and he's very good at spotting turnarounds & bargains in retail.
Regards, Paul.
Thanks in advance Paul - Much appreciated
Just to say thanks for the deeper dive on Works Co Uk (LON:WRKS) Paul - It's much appreciated - Have a great weekend and go easy on the deep fried stuff :)
Paul, if you subscribe to Skype they provide you with a landline number that your elderly relative can ring (they wont know its ringing on your computer). Have just done this for my Dad but he is a great one for turning the computer off to save electricity which kind of defeats the purpose.....
Thanks colin, made me chuckle!
Trouble is, I don't think BT give you the option - you get a landline, if you want internet. I've never been keen on buying internet from a third party that just re-brands the BT service, because it's much harder to get repairs fixed - both companies blame each other. Hence buying internet from BT, they can't pass the buck.
P.
You can get internet without phone line from Virgin Media as I do. £25pm for 100Mb.
You won’t get those speeds in some areas. You can get broadband with phone for less than that.
You can get 5g router now
5G, we have hardly got 4G here. How much will that cost you?
Some people are switching to mobile broadband but the signal here is rubbish and it's no cheaper. You can get phoneline and broadband 36mbps for around £20pm, Vodaphone were the cheapest when I last checked, but some reviews are not good, so I would check them out before moving, I stayed with BT in the end. At least if there a problem they should fix it quicker.
Elon Musk can sort you out - for a price. £495 upfront plus £89 per month gets you a satellite internet.
https://www.starlink.com/
Far too expensive. That’s over £1,000 a year plus £495 set up.
You could checkout Starlink as an alternative internet connection
Hi Paul. Just doing the same research for my mother. You can order a BT broadband connection without phone line. From memory It saves about £3 pm.
like your father she won’t be without a landline but mainly because her friends won’t ring a mobile!
Paul, I'used BT, Plusnet(owned by BT) & John Lewis (suppled by plusnet). We live in the sticks so many problems with internet/phone lines, always have to be fixed by Openreach, who invariably offer second rate service. So apart from things like billing I don't think it matters who provides your service as you will ulimately end up at the mercy of Openreach.
Be aware that if you are offered a phone number without having a physical line you are likely using VOIP which is fine until the power goes down, again a common problem in the sticks. Maybe not so in sunny Bournemouth.
”Why do people find it so hard to admit they got it wrong?”
The best solution is to be a value investor so you never have to admit you are wrong, you just haven’t been proved right yet.
”Why do people find it so hard to admit they got it wrong?”
The best solution is to be a value investor so you never have to admit you are wrong, you just haven’t been proved right yet.
That's brilliant, I have extensive requirements for this reasoning!
P.
Hi Paul,
Re your quote why should inflation return now ? do you not think the trillions globally handed out to the public has played a huge part in this almost the precursor to a universal basic income coming in at some point.
In 08/09 when QE was last used in huge quantities the banks held on to all the money negating inflation getting into the system.
It will be interesting to see how central banks react to the next crisis as pouring more QE into the system now could even hasten the falls in markets further as it should currently add to the inflation problem.
I do wonder if at some point we will have a global debt reset in the developed world and all the trillions will be wiped off and the governments of the world can then start running them up again from a zero base.
The other thing I find odd though is US, UK and Europe all suffering with inflation but Japan still can't get inflation even though they want it why is that in the current hugely inflationary times ?
Regards
Andy
Good morning Paul,
I'd be interested in your thoughts on the mandatory offer for PHTM this morning?
Offer price of 75p, which is actually slightly less than yesterday's closing price?
Paul, luckily I have just recently renewed my BT internet contract in spite of all the pavement cable-laying that has gone on around me but may I point out that without paying the landline charge I would have no BT internet.
You can get internet only, no phone but the price is usually the same. BT contracts the price is not fixed, so you can expect a rise during it, if it’s over 12 months. Prices for broadband have been coming down, my BT contract fell £6 at renewal and that was not the cheapest deal around.
It looks like the long awaited bid for Photo-me International (LON:PHTM): has arrived and also as expected its the main man looking to take it private on the best terms possible for himself.
RE £PHTM I read it differently. I thought it was him making an offer because he had to and making it such that it was unappealing to shareholders as he doesn't actually want to take over the company. I may be wrong, I don't follow the company closely. I guess it depends on your opinion of the CEO and Executives in general. If you are of a cynical disposition, and I would normally include myself in that camp, you may think he is trying to pull the rug from under shareholders. If you are of a less cynical disposition, you may give him the benefit of the doubt.
Is he allowed to come out and say he doesn't actually want to take over the company, if that is the case? Genuine question, I don't know the 'ins and outs' of the rules on take over bids.
Edited to include Ticker. (Which doesn't seem to want to work)
Paul - Great notes, thanks for sharing - Have a look at Skype - I pay about £30 a year for a landline number - Good weekend to you and Jack.
I use sky broadband and telephone package and I now don’t pay the landline charge.
How much do you pay though?
.
Morning Paul
Loving your pre-market rambles, awesome reading while having a coffee, please keep them up
Morning Paul
Do enjoy reading your morning preamble. I agree with your sentiments. I think Mr Market has more in store for us.
Morning Paul
Do enjoy reading your morning preamble. I agree with your sentiments. I think Mr Market has more in store for us.