Small Cap Value Report (Fri 21 June 2024) - FRAN, NCC, XPS, KETL. Brief: BVIC, TIDE

Good morning from Paul! Here's something I prepared earlier... (isn't that from Blue Peter?! For a 1970's reference).
Hardly any news today.
By the way, it's fine to disagree with my opinions, we welcome courteous debates. Do remember that these articles are just one person's quick review, and are intended as conversation starters.
Explanatory notes -
A quick reminder that we don’t recommend any shares. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech, investment cos). Although if something is newsworthy and interesting, we'll try to comment on it. Please bear in mind the "list of companies reporting" is precisely that - it's not a to do list. We typically cover c.5 companies per day, with a particular emphasis on under/over expectations updates, and we follow the "most viewed" list of readers, so if you're collectively interested in a company, we'll try to cover it. Obviously with the resources available, we can't cover everything! Add you own comments if you see something interesting, and feel free to discuss anything shares-related in the comments.
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to, if they are using unthreaded viewing of comments.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. And/or it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom), Video update of results so far, June 2024.
Frozen SCVR summary spreadsheet for calendar 2023.
New SCVR summary spreadsheet from July 2023 onwards.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Phil Hanson's data analysis measuring performance of our colour-coding system in the SCVRs, from July 2023- Mar 2024 (with live prices). My video explaining/reviewing it.
My other video (June 2024) - How to screen for broker upgrades on Stockopedia.
Companies Reporting
Summaries
Franchise Brands (LON:FRAN) - down 11% to 152p (£295m) - FY 12/2023 Results - Paul - AMBER
Fires its CFO. Results are quite late. Major acquisition has resulted in debt being a bit too high for my liking. FY 12/2023 profit up strongly, but EPS flat. Cashflow looks inadequate to reduce debt fast. Overall, I don't have a strong view either way. Shares look fully priced for now.
NCC (LON:NCC) - up 8% to 156p (£490m) - Trading Update - Paul - AMBER
It's a slight beat against expectations, but these have been greatly lowered from the original forecast. Balance sheet weak. Poor long-term track record, so I'm underwhelmed by this cybersecurity company. Shares have partially recovered from a profit warning in 2023, so seem to be in an up-trend now.
XPS Pensions (LON:XPS) - up 5% to 283p (£588m) - FY 3/2024 Results - Paul - GREEN
I'm really impressed with this quality business that provides various services to the pensions sector. Impressive results for FY 3/2024, following a strong prior year too. Not cheap, but I think the valuation is justified. Positive outlook suggests more growth is in the pipeline. Debt almost cleared from a disposal. Looks good!
Strix (LON:KETL) - up 1% to 85p (£195m) - AGM Statement - Paul - RED
Trading in line with expectations. Some progress on debt reduction, including a recent 80p placing (nil discount), 5% dilution. However, debt will need refinancing in 2025, and is still way too high. Cashflow poor. I'm wary of this share until it's properly refinanced. Maybe RED is harsh, but there's dilution/insolvency risk here if the lenders don't play ball, so why get involved?
Paul’s Section:
Franchise Brands (LON:FRAN)
Down 11% to 152p (£295m) - FY 12/2023 Results - Paul - AMBER
Franchise Brands plc (AIM: FRAN), an international multi-brand franchise business, is pleased to announce its audited results for the year ended 31 December 2023.
CFO Mark Fryer seems to have been fired, with immediate effect. A former CFO, and then COO, Andrew Mallows, becomes interim CFO.
FRAN shares have done OK since floating in Aug 2016, being about double that level now, although all the 2024 gains have now been given up -
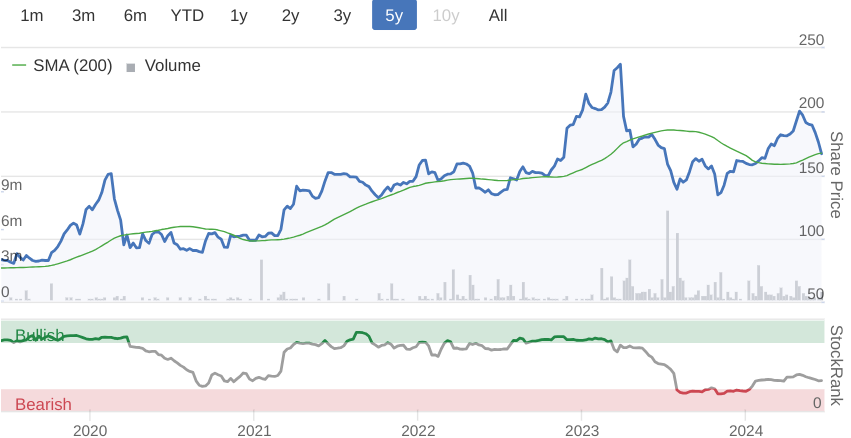
FRAN has grown rapidly through acquisitions, and the share count has almost tripled from c.70m to about 194m now.
A fairly recent acquisition was large, and in my view involved taking on too much debt, with leverage multiple looking a bit high for comfort -
Adjusted net debt**** of £74.7m at 31 December 2023 (31 December 2022: net cash of £9.8m), 2.48x Adjusted EBITDA.
Profitability rose decently in FY 12/2023 -
Adjusted profit before tax increased 55% to £19.7m (2022: £12.7m*).
Although no increase in adj EPS -
Adjusted EPS*** increased by 1% to 8.42p (2022: 8.34p*).
That gives a PER of 18.1x
Dividends total 2.2p for the year, a yield of only 1.4%
Major acquisition - management are certainly ambitious here -
“Another year of momentous change for the business with the acquisition of Pirtek Europe Ltd for £210.8m*****, funded by £100m of bank debt and £114.3m of equity, which has again doubled the size of the Group.”
It seems to have worked OK -
“During just over eight months of ownership in 2023, Pirtek traded at record levels, contributing as expected to the Group's results.”
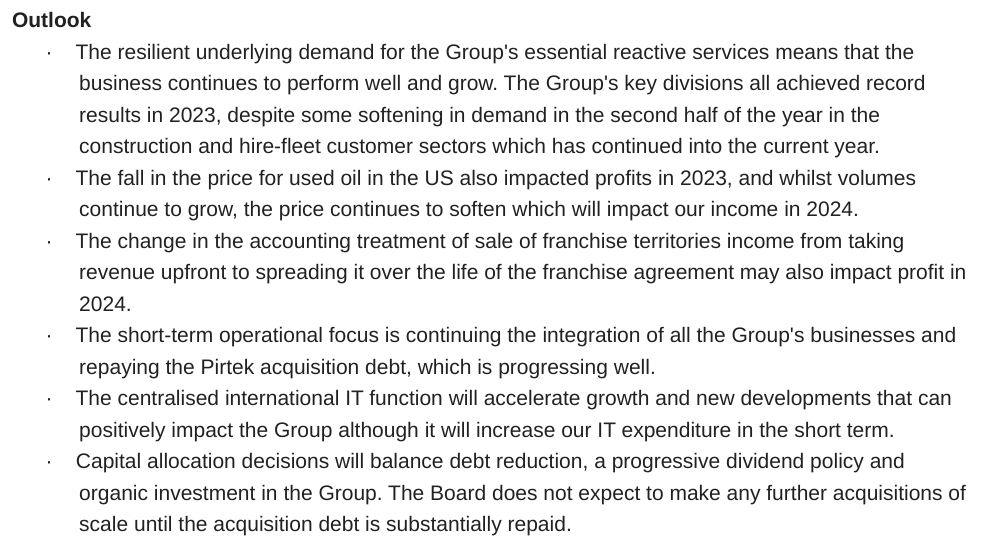
Some areas of concern in the outlook -
Balance sheet - NAV is £214m, but that includes £305m of goodwill, less £34m deferred tax, so I make that NTAV (my method of calculating it) of negative £(57)m. Not great, but since this is a franchising business, the working capital is mainly on the shoulders of the franchisees. So I wouldn’t expect there to be much capital in the franchise owner group.
As mentioned above, debt looks too high, so I think FRAN needs to demonstrate it can pay down debt from cashflows in future.
Cashflow statement - it’s only really generated about £10m of positive cashflow from operations, after finance costs and leases. That’s not enough to make a major dent in the debt pile. So I think the jury is out here about ability to reduce debt in a reasonable timescale.
The big numbers are all acquisition-related, being large debt and equity raises.
Paul’s opinion - I don’t have a strong view either way, and am happy to sit on the sidelines to see how things pan out. AMBER feels about right for now, as we watch to see how the acquisitions bed in, and debt changes. As VCP mentioned in its recent results, it’s a lot more expensive to fund acquisitions with debt now. This makes it much harder for acquisitive companies to demonstrate that acquisitions add value.
Back in the zero interest rate era, I remember every acquisition announcement from every company said it was earnings accretive, as the alternative was cash in the bank earning nothing. That’s changed now, so I think investors should be asking much tougher questions about whether acquisitions really make commercial sense, or have squandered shareholder value from management chasing share option incentives? (that's why I generally prefer owner-managers, with interests aligned).
NCC (LON:NCC)
Up 8% to 156p (£490m) - Trading Update - Paul - AMBER
NCC Group plc (LSE: NCC, "NCC Group" or "the Group"), a leading independent global cyber security and resilience provider, presents the following unaudited post-close Trading Update for the 12 months ended 31 May 2024 in advance of publishing its unaudited 12-month results on 1 August 2024.
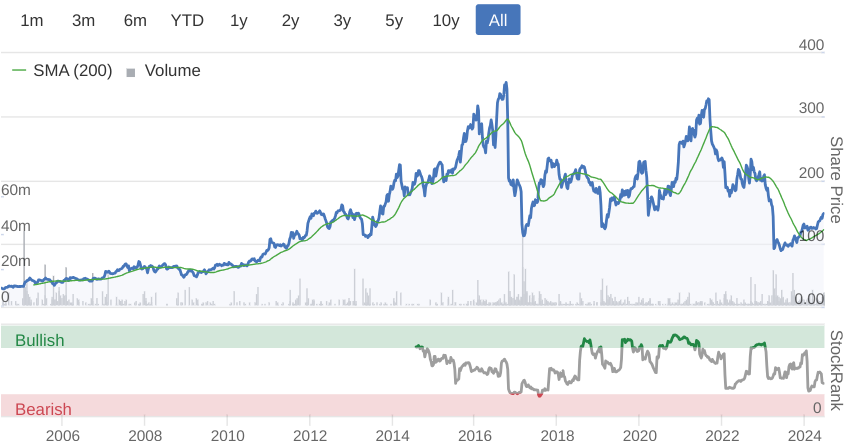
We’re overdue a fresh look at this acquisitive cybersecurity group. I last reviewed it on a profit warning here on 31/3/2023. It took a while, but since then shares have gradually formed a base, then risen c.50% from the lows more recently. Although the long-term track record is not good, with the share price currently about where it was 12 years ago. Have acquisitions added value? Doesn’t look like it to me.
On to the latest update, which sounds a bit mixed -
Revenues - at £324m there’s no growth, down 1% at constant currency (down 3% reported) for FY 5/2024.
Profits look good, although I prefer higher profits from growth, rather than cost-cutting -
“Adjusted Operating Profit1 expected to be ahead of consensus2 at c.£31m driven by delivering targeted efficiencies in both gross margin and operating costs. Group gross profit margin has improved by +c.2% YOY, supported by an improvement in H2 2024 in Cyber Security gross profit margins of c.800bps to c.38% as a result of strong utilisation and operational efficiencies.”
2 Consensus as at 12 June 2024 and as outlined on https://www.nccgroupplc.com/investor-relations/results-media/. Adjusted Operating Profit consensus amounted to £29.7m and Net debt (excluding leases) amounted to £50.4m.
That’s about a 4% profit beat - helpful, but no great shakes.
Net debt looks OK - this looks comfortable -
Net debt (excluding leases) to be better than consensus2 at c.£39m, c.£11m improvement from FY 2023, after consistent strong cash conversion and disposal gross proceeds of c.€9m from the DetACT non-core disposal as described in December 2023.
Leverage (excluding IFRS 16) as at 31 May 2024 to be c.1.0x Adjusted EBITDA (excluding IFRS 16) (H1 2024: 1.9x).
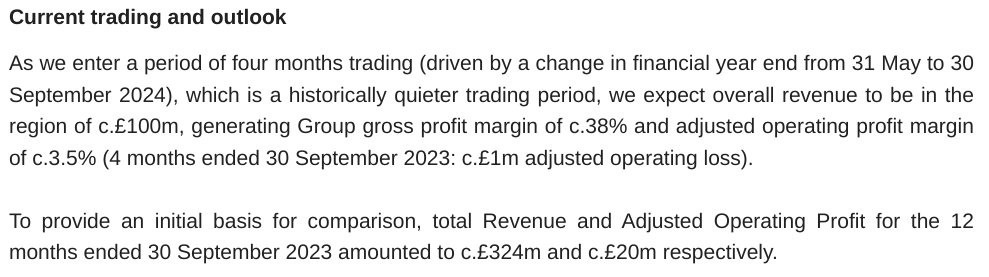
Outlook - a change of year end muddies the water, and makes it harder for investors to ascertain how a business is performing -
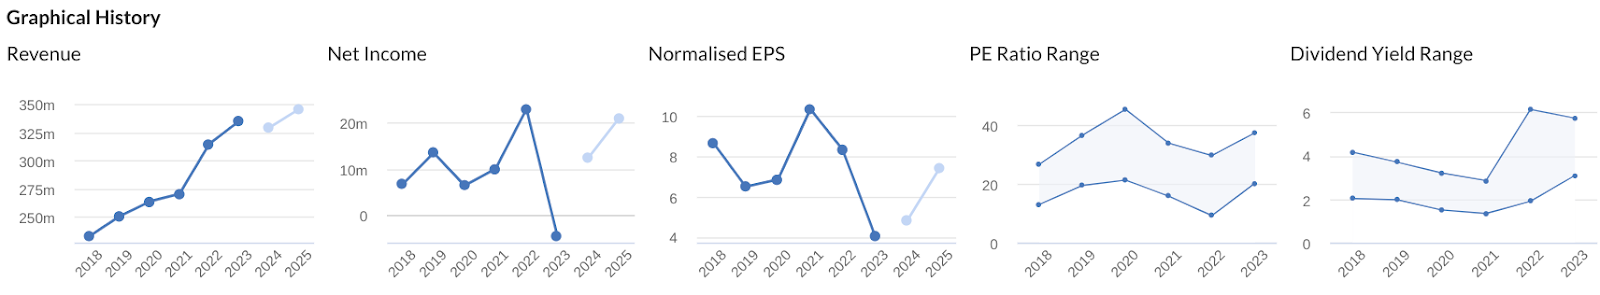
Paul’s opinion - I’m a bit underwhelmed by this. Cybersecurity is obviously a fashionable area to invest, for obvious reasons. However, NCC’s track record is distinctly blotchy, as you can see both from the lacklustre share price, and erratic fundamentals -
The last reported balance sheet was weak, with heavily negative NTAV.
It seems to have spent a lot on acquisitions over the years, with not much to show for it. So I worry that management are maybe just not very good, in particular at acquisitions?
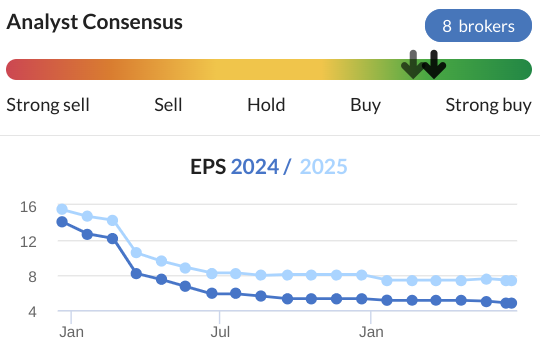
It’s a slight beat against expectations, but look at the trend for expectations! -
Overall, I’m struggling to avoid the impression that NCC looks a bit of an also-ran, in a sexy sector, hence possibly priced at an undeserved premium?
I wonder what competitive advantages, or proprietary technology it has? I don’t feel motivated by these numbers to do any deeper research.
So for me, it’s at best AMBER. Tell me if I'm wrong! We necessarily have to flit from one thing to another with these reviews.
XPS Pensions (LON:XPS)
Up 5% to 283p (£588m) - FY 3/2024 Results - Paul - GREEN
XPS Pensions Group plc ("XPS" or the "Group"), the leading Pensions Consulting and Administration business, is pleased to announce its audited full year results for the year ended 31 March 2024 ("FY 2024").
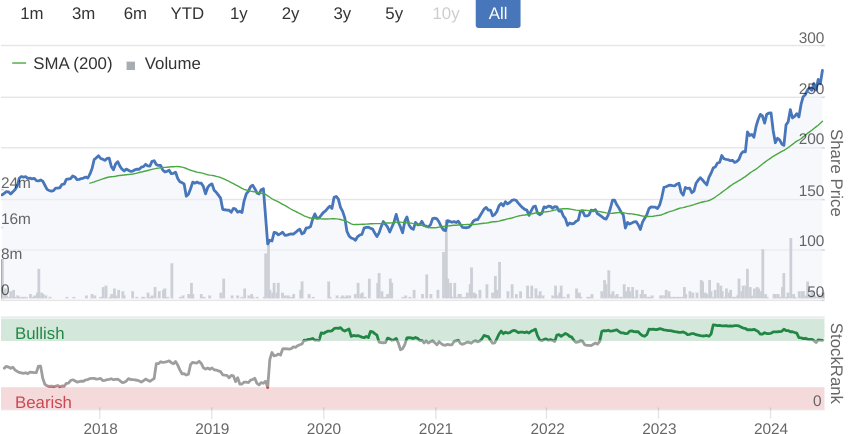
Graham normally covers XPS. Checking back, he liked its H1 results on 23/11/2023, concluding GREEN at 227p/share. Previously he was also GREEN in June 2023, at 170p/share. Interestingly, he thought it looked good, but pricey (for a consultancy business) on both occasions, but forecast upgrades mean that it’s not only grown into the valuation, but actually now looks reasonably priced (in my view) despite a lovely rising share price -
Results for FY 3/2024 look excellent to me. A few key numbers -
Revenue up 21% to £197m, said to be due to strong demand and inflationary price increases (demonstrating pricing power).
High margins, with adj PBT up 37% to £44.5m
Disposal for £35m of NPT, has eliminated most of the group's net debt.
Adj EPS up 24% to 15.1p, a PER of 18.7x
Dividends total 10p for the year, yielding 3.5%
Recently announced - XPS will join FTSE 250.
Outlook - excerpts of key points -
We have seen continued strong demand of our services since the beginning of the year and maintain an active new business pipeline. We have continued to grow market share, but with this still under 10% there is considerable scope for us to grow further…
The strong momentum from FY 2024 has continued into the new financial year and we remain confident in delivering against our expectations for the current year.
This looks a business on a roll - see the lovely trend on the broker consensus forecasts -
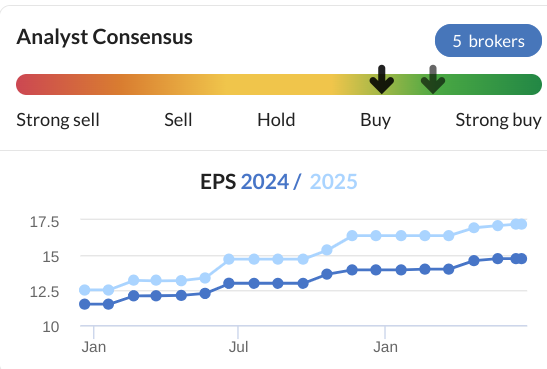
Balance sheet - NAV is £186m, but that includes intangible assets of £208m, which checking back to the 2023 annual report this is nearly all goodwill and similar relating to multiple acquisitions. There’s also £16m in deferred tax, which we usually find at companies with a lot of goodwill on the balance sheet, so I’ll write that off too. Which arrives at NTAV of £(6)m. So there’s no asset backing. Is that a problem? In a word, no! That’s because this is a people/knowledge based business, so is capital-light - ie no need for any significant physical fixed assets, and no inventories. So even though there’s no asset backing, the balance sheet looks fine to me. Negligible net debt, after the NPT disposal, means I think it has the firepower to fund more acquisitions from debt, if it wants to. I don’t have any worries about the finances, and would say dilution and insolvency risk are almost nil.
Cashflow statement - looks healthy in both FY 3/2024 and the previous year. I won’t go into all the detail, but the stand out numbers are disposal proceeds from NPT eliminating most of the bank borrowings. This looks a good, genuinely cash generative business, no funnies here!
Paul’s opinion - I’m really impressed with these numbers. Yes XPS looks a bit pricey for a consultancy business, as Graham always says when he reviews it, but I think the valuation looks fully justified. Also this is a high margin business, so it clearly has some kind of moat, and pricing power. So why wouldn’t it be on a decent PER? Hence I’m happy to run with GREEN.
FY 3/2024 results showed smashing profit growth, and that’s on top of strong prior year results. Personally I wouldn’t be buying after such a strong run, but am happy to have this one my watchlist as something to possibly buy on the dips. Trouble is, it’s this kind of instinct that caused me to never buy Warpaint London (LON:W7L) so sometimes it’s best to just pay up for a good growth company and add more on the dips, rather than stubbornly waiting for a big pullback that never comes!
Strix (LON:KETL)
Up 1% to 85p (£195m) - AGM Statement - Paul - RED
Strix Group Plc (AIM:KETL), the AIM quoted global leader in the design, manufacture and supply of kettle safety controls and other complementary water temperature management components…
Tentative signs of recovery in its markets.
FY 12/2024 profitability is in line with current market expectations (no explanation of what those are)
Cash generation slightly ahead of expectations (no numbers).
“anticipated net debt leverage position of less than 2.0x” (When? Year-end Dec 2024 presumably?)
Recent placing has helped discussions with lenders (£8.7m [before fees] fresh equity raised at 80p, nil discount, 5% dilution)
Bank facilities refinancing hoping to be done in 2025 (I see this as a considerable risk).
Restructuring re cost-cutting and efficiency underway.
Paul’s opinion - I’ve never been comfortable with the figures at Strix. I’ve just taken another look at its H1 results, and this reinforces my scepticism. In particular, cashflows are poor, once heavy finance charges (from excessive debt) are taken into account, and £4.1m capitalised R&D in H1 alone, earnout payments, etc. This resulted in a very weak balance sheet with NTAV negative at £(34)m by June 2024, and £93m net debt (excl. leases). The remedial action taken to date only makes a small dent in those numbers.
I’m wary of this company, which is clearly financially distressed, so I think it’s safer to sit on the sidelines and wait for it to refinance the bank borrowings in 2025. The £195m valuation, and strong share price recently, do not make any sense to me. The whole thing doesn’t “smell” right to me, so I won’t be getting involved at pretty much any price. Opinions differ though, so good luck to bulls, I hope it works out for you.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

78 comments
Further to my Crimson Tide (LON:TIDE) note the market is clearly not in a believing mood about the Ideagen bid at 312p since it is still possible to buy at 260p which I find a bit surprising.
On June 4 th when Crimson Tide (LON:TIDE) was at 175p I suggested that the Checkit (LON:CKT) offer was way to low and that I would not expect Barrie Whipp to agree it, my own valuation reckoning that it was worth at least double the then price. Lo and behold, a couple of hours ago Ideagen (LON:IDEA^G22) offers 312p! I am going to start making sure that this column knows what I think my other stocks are worth - clearly eyes are on us!
Seriously though it does highlight the stunning value on offer in some small/microcap stocks, and, on this occasion, I am delighted that a UK company has figured it out.
hi yiannos1
Gulf Keystone Petroleum (LON:GKP) Do you have access to this?
Herman Wang@HermsTheWord·5hMassive convoys of trucks, hundreds of illegal topping plants, fuel smuggling via packhorse: @LK_Holt with a deep dive into Iraqi Kurdistan's oil sector, which is pumping up to 300kbd in a thriving local market with its main export pipeline closed #OOTT
https://plattsconnect.spglobal.com/#platts/newsArticle?articleID=9f2b42b9-b4bf-4081-ba9d-b1ccec57e289
I don't but would be interested in your views if you do. Ta
I tend to invest based on the numbers I have in front of me and not on different conspiracy theories based (most times) on the writers personal financial interests.
Gulf Keystone Petroleum (LON:GKP) is not a Kurdish nor an Iraqi company if that helps.
Same comments one can make on the different cigarette companies operating here in the UK as cigarette smugglers have been thriving for years. Still British American Tobacco (LON:BATS) is a great company.
All the best
Breaking news on PayPoint (LON:PAY):
Thanks Mark. There's an after close statement from PayPoint (LON:PAY) to confirm if not enlighten. It must be materially important to PayPoint, specifically for Collect+, to keep Yodel's wheels rolling.
Latest FY Mar24 results from PayPoint (LON:PAY) show that their eCommerce division (which is where revenues from Yodel / Collect+ sit) increased +61.6% YoY. The fastest growing division they have by far.
So clearly, very important for Paypoint to continue their growth trajectory.
From a strategic perspective, the Yodel/Collect+ is also important for Paypoint; it allows them to sell to corner shop owners that Paypoint will bring in incremental foot traffic to their stores. Thus, driving high margin Paypoint One/Mini sales and sticky customers.
For me, I need more details... £10m isn't alot of money, Paypoint can afford it. But what do they get? Strategic play to almost guarantee Yodel is exclusive to Paypoint? Better commercial terms?
And what does this mean for the share buyback plans (£20m for next 12 months in FY25)?
(I hold in the Boon Fund)
Pennant International (LON:PEN)'s results say “the Group posted a consolidated adjusted EBITA profit of £1.7 million (2022: EBITA £0.5 million) which is in line with market expectations.”
Presumably the “adjusted EBITA” figure adjusts out the £300k exceptional acquisition costs. Seems reasonable.
Stocko shows forecasts for 2023 net profit of £1.2m / EPS of 3.5p.
To get from an adjusted EBITA of £1.7m to a net profit figure, we need to deduct interest, tax and amortisation.
Interest was £463k.
Tax was an accounting charge but it arose from the treatment of deferred tax and on a cash basis there was an inflow from tax of £120k, so let’s treat tax as an inflow of £120k.
The amortisation charge was £1.33m (£1.24m of which was software development).
This gives an adjusted net profit figure of £27k, which is not in line with the Stocko figure of £1.2m.
If you ignore the amortisation charge you get a net profit performance that matches Stocko’s number. But to avoid tooth fairy territory you need either to include the amortisation charge or instead use the cash cost of software development (£1.425m, £1.452m or £1.453m depending on which of the three figures you use from the cash flow statement and notes 2 and 5).
WH Ireland's note says results are in line with a PBT forecast of £1.3m "adjusted for amortization" and acquisition costs and they add an asterisk to their forecast table saying that the PBT and EPS numbers are adjusted for amortisation (and exceptionals).
XPS Pensions (LON:XPS) (i have held for 2+ years)
Happy holder, good results, and intend to hold until the facts change.
Anecdotally have heard they are having growing pains - you get that a team on the bid and then the c team for the implementation. This is just an anecdote, but over the last couple of years almost all previous anecdotes have been glowing
IG Design (LON:IGR) results 25 June.Share price is on a roll again up to 230-235p a share.Stick or twist?
"With a 345p price target, implying 70% upside, Liberum Capital points out IG Design's cash pile is already ahead of expectations, so surplus returns to shareholders could be the surprise over the next 12 months" IG Design (LON:IGR)
IG Design (LON:IGR) I hold
It's a dilemma, isn't it? If you zoom out from the stockopedia price chart from 1 year to 3 years to 5, what looks like a recent lift off in price looks no more than a blip. Psychologically it is so difficult to keep buying a rising share price - see Ed's recent article!
IG Design are in that happy place of having a huge turnover so that any improvement in margin has a significant impact on bottom line. The new board have been exiting unprofitable contracts and cutting costs where they can. (I think in the past supply chain issues hurt the company and management seemed to be chasing additional revenues at any cost.)
For me this looks like it is set up to beat current forecasts and so I feel there is more to come. I am therefore GREEN on this share.
Off topic (as it’s Friday): last day in Malta, had a fleeting thought of following in Paul’s footsteps by heading of to Gozo and writing some reports for Stocko, but quickly realised that I don’t have the training, knowledge or acumen required. I’ll share one photo of Mdina Old City.
I keep getting the impression that stock picking at the end is a losing game at least for UK stocks.
I have a long list in my watchlist - hundreds of UK stocks - if you check the long term trend over many years for many of them the stock prices end up going down. Sure, you get lots of ups and downs but its very tricky to pick bottoms and even if you get it right a few times you'll get nailed on the ones you get wrong. I'm a bottom feeder but I daresay that for long term investors who hold on for many years it is even worse unless you are really lucky.
And its not just AIM stocks - even the blue chips are being pummelled hard after even a mild profit warning. The fact is we don't have sufficient information to judge a stock - we are not insiders - directors are only mainly interested in their own self-interest - how much they can extract out of the business in stock awards and salaries - they don't care about shareholders mostly. And you can't really trust what they say to shareholders. The last three years for me have been an uphill constant battle.
How much is the statistic? More than 80% of spread betters lose money - to put it mildly. I think the statistic isn't any better for share traders/investors.
"I'm a bottom feeder"
When I started investing 3 years ago, I also followed this as a strategy - "If I can buy the low, there is a long way up, I only need one or two big wins to make lots of profit". The reality is, for me at least, this strategy rarely worked and very few of the companies completed the envisioned turn around, or ever significantly rerated as I felt the numbers suggested they should.
More recently I have focused on buying companies where the share price is on the up and the turn around has already started. I would recommend the following discussion by WOSS if you haven't read it as food for thought- https://www.stockopedia.com/co...
The one bag in a year mindset championed by Cockney Rebel on his substack and his focus of bowls I have also found helpful.
With such a huge watch list you will inevitably just track the market averages for the most part and any big wins will be diluted. Some very knowledgeable investors like BnB have great success with large portfolios. However, for me personally as I am working full time, 15-20 stocks that I can know in a fair bit of depth and study any RNS before work, has been more successful for me.
Finally, I just really love investing, I find it so fun and really engaging. This might be the case for you also, however, I think that if that enjoyment isn't there and the focus is simply on making money then it might not be for you.
If you've a watchlist of hundreds of shares doing badly Ben I'd suggest you bin them all and start again. Just because something is "cheap" doesn't make it any good, could get much cheaper if no one wants it. Who would buy a donkey to win Ascot. How many in your watchlist are trading well with growing earnings?
Really shouldn't be getting nailed on losers, just use a boring stop loss. Its no use wishing for the market you want, just bend with the market you have or buy a tracker.
Edit: just to prove what has basically been a pretty easy market the last 6 months, from the 1st November 2023 (which is usually the start of the strong period) theres been 45 companies at least double in price. Last year there were 19.
These are just the companies which are profitable. I've only owned 3 of these so missed loads but that's enough for a decent gain.
off this list i successfully profited off Serabi Gold, Intercede, Rolls Royce and Base Resources
Spread betting tends to be a zero sum game i think as it's leveraged.So you can effectively lose the whole bet if you can't/don't post further margin money.At least if you own a half decent company you can own it for as long as it's listed and a lot do come back eventually from profit warnings and some of the best ones : i took a real punt on Indivior (LON:INDV) , which was a special situation and it was a punt but it paid for a few underperformers.Yu (LON:YU.) bagged majorly if you waited a few years.Everyone will get a couple of ones that go bankrupt that they might miss and or/ frauds but most won't.
Sure in high interest rate environments, perhaps apart from the experts, it might have been best just to sell all smallcaps in hindsight and invest in large caps/megacaps.But it's easier said in hindsight and if rates do go down eventually and similar hikes start happening 10 years down the line, you'll know what to do.
It's sure a frustrating at times, though if you have a well thought out, longer term strategy you try not to deviate from too much, the odds are in your favour of positively compoundng your money.Also everyone has a different strategy.Do what works for you, but patience is definitely need, amongst a bit of shorter term fun!I'm no good at picking the correct time to invest.... so i get a lot wrong, but some will multibag from lows and make up for the bad ones.I picked up YouGov (LON:YOU) as a previous quality business yesterday and will wait.. perhaps wait and hope.But i believe the business hasn't gone from quality to rubbish overnight like the share price.I do try to focus more on previously quality businesses now though that are going through problems.
Share trading/investing is not supposed to be easy. Despite that, and I am not a genius (I got a 2:2), since 2009 I have made an average 26pc gain (inc divs), virtually all London listed. I have had no other source of income. I had some spectacular years, but admit to losing over half my money in 2022/2023. So it is possible to make money in UK stocks. The only regret is I didn't get the sack and paid off earlier, as my lifestyle is 100pc better now, no trudging to the office each day and getting on flights to London City twice a week for 12 hours of boring unproductive meetings.
Great stuff Orval care to share what's worked for you and what hasn't worked ?
Regards
Andy
If you don't enjoy the game then best to go with a market tracker. The World Tracker ETF gives the best diversification.
having the hundreds of stocks in my watchlist doesn't mean that they are in my portfolio. I just watch them everyday and I've been doing this for years. The vast majority go down! One of the analysts here was a huge fan of Boohoo when it was much much higher - see where's it has ended now. He also loved Revolution Bars - see where it's ended. I'd rather not mention names ;P
What exactly is the point of your entitled whinging Ben, just to have a go at Paul?
Does it help you cope with losses if you blame someone else. Do something productive with your time.
My point is that many end up losing money and that its a negative sum game!! Its the directors and insiders who profit if any. No one tells you that here.
I thought reading our analysts opinions here is productive but is it really?
The analysts opinion here are just a starting point for you to do some work.
I am totally lazy, unless the analyst says GREEN I tend to look no further, now if they say BLACK/GREEN then I am really interested, but again its only a starting point.
I tend to see if they are on any of my screens, again I am lazy, if they are I'm virtually on the point of buying.
I have 3 screens and the criteria is tight, lucky if I have 10 shares between them.
Suggest you buy less often but buy higher quality instead using the STOCKO screens. I average around 13% a year for an hour a day research tops, which will do me.
Love the old feet up approach Bob as you say if you don't over complicate and can stick to stops you should do ok over time.
I think if you have a negative attitude you will prend up losing money. Sounds to me that you are better getting out and finding some other pastime you enjoy.
Being optimistic doesn't make you money. In fact being optimistic usually loses you money as you become more gullible and there are countless directors out there that cannot be trusted!! Just do a research for the thousands of companies on the LSE. I'd bet that 70% of them are down in the last 2 years.
In fact being optimistic usually loses you money!! Just do a research for the thousands of companies on the LSE. I'd bet that 70% of them are down in the last 2 years.
ftse all share index total return over last 2 years shows up as being 9% up !!!
https://www.londonstockexchang...
Just do a research for the thousands of companies on the LSE. I'd bet that 70% of them are down in the last 2 years.
Your 70% of shares being down on a total return basis over 2 years is more or less correct for AIM. A large equally weighted representative sample would on average have lost about 12%. It is not correct for the All Share Index where about 65% would have made money and our large equally weighted sample would have a positive return of around 15%. Over the same period, my own unitised share portfolio which I manage on a predominantly quantitative basis using a system derived from Stockranks, has shown an increase of about 25%.
Well I do believe Paul and Graham's annual lists, link as per spreadsheet at top of page are doing very well for last couple of years. Probably better than the Investors Chronicle "bargain portfolio".
Of course this is just the small cap sector and its largely AIM stocks, and many investors would not touch AIM.
There are of course the Stocko QVM ratings which cater for larger stocks and can produce a portfolio of winners if you want to go that route.
But...this is what I think. Different styles work in different markets. The Mr Market philosophy from the classic Ben Graham - Intelligent Investor is effectively a value orientated approach. On Stocko, there is a Ben Graham Net Net screen which has done +223.2% since inception (2012), thats better than most UK fund managers - but over 5 years it has produced just 5%. The original Mr Market theory pretty much says buy cheap and wait for the market to respond but could it be out of favour ?
If Intelligent Investor is the first investment book you read then this can dominate your thinking for a number of years (yep guilty) - but his most famous student changed course from value to (influenced by the great C Munger) "Over the long term, it's hard for a stock to earn a much better return than the business which underlies it earns. If the business earns 6% on capital over 40 years and you hold it for that 40 years, you're not going to make much different than a 6% return—even if you originally buy it at a huge discount.”
Need to make sure any downtrends have stopped before buying maybe.
That said I often find as companies trading in line with spare cash are often decent punts (excluding mining/biotech type things which are often taking binary bets with such cash). But somehow I didnt buy CMC markets earlier this year/last Nov !
Everyone gets stuff wrong , Paul, Graham, Roland throw up loads of ideas its up to us to judge if they are any good or not and equally to have a game plan in place if we buy in and then find out we are wrong.
Thats not having a dig Ben I have a pretty good hit rate on winners 7/10 but I am sh-t on the gameplan if i am wrong, mainly do stubboness (I'm going to be proved right the market is wrong I know best) and lets just say thats not always ended well.
I did say on another thread I put in 15-20 hours per week research which I enjoy but longer run I probably do as well as Fundsmith/Rathbones Global Opps so have come to the conclusion I'm not disciplined enough to get on the top table.
So I am putting together a group of investment trusts with a global spread, gold bullion etf, dollar tracker etf and a sprinkling on bond trusts.
I am pretty confident i will average out north of 8% per annum for couple of hours work per week with either quarterly or half yearly rebalancing.
Trusts also won't halve over night and are generally safer to average down into, flip side is unless stellar year like 2021 I won't make 20% plus pa but if I can grind out 8% pa for couple of hours per week I will take that.
I've been trading since 1996 and also reckon maybe only 10% really make north of 15-20% per annum yes Paul's had his howlers but he's also had plenty of years when he's made stellar returns.
I think its easier to pick a top performing fund than a top performing share. So kind of similar to what I am doing. But allowing for a sprinkle of inspired own picks alongside.
Have to be mindful however that recent market performance of even the worldwide index is boosted by the FANGS. Question is do you accept the imbalance or do you reduce it and vary from the index.
Hi Dave my intention is to go for equal weighting europe, Pershing Square for US exposure, Nasdaq etf, Japan, FTSE 100, BlackRock World Mining Trust (LON:BRWM) for industrial metals exposure, gold bullion etf, dollar index etf, 4 bond funds and emerging markets trust.
I'm heading towards the old 60/40 equity / bonds, gold, dollar split, from memory 60/40 has achieved around 8.5% in the very long term so I'm hoping having gold in the 40% will help shore things up a bit and add a bit more diversifcation.
Hi Ben,
Benjamin Graham, the founding father of modern investing, once said:
“The investor’s chief problem, and even his worst enemy, is likely to be himself”
Maybe it's time to take a hard look in the mirror - perhaps active investing doesn't suit your skill set? Better to accept that, cut your losses and go and do something you enjoy rather than having digs /blaming others, UK markets, self interested directors etc etc
Bensummers - fascinating.
OK it's a Friday afternoon and I'll bite, as I rarely tire of these investment discussions. So lets go.
Yes. I think you are correct in some ways - ie
having the hundreds of stocks in my watchlist doesn't mean that they are in my portfolio.
Well yes indeed. I think I could dump most the cheapest end of AIM and the FTSE Smallcap into a watchlist and I'd be none the wiser. Especially if I watch them everyday? I'd probably never leave my desk? And get very stressed?
The vast majority go down!
Plenty of studies out there show this is true. I think that recent webinars or articles by Ed Croft and Mark Simpson have mentioned this as well.
I seem to remember it being quoted that 4% of the companies on the market produce most of the gains?
My aim is not to be looking at the vast majority.
There is a tendency to assume that since the vast majority go down - anyone who outpeforms with their investments is lucky? I disagree. As Gary Player once said in answer to the question why do you have so much luck?
I find that the harder I practice the luckier I get!
In the book Common Stocks and Uncommon Profits Phil Fisher describes 2 types of investor.
One type is those who are lucky and able.
The second type is those that are lucky they are able.
I count myself in the second group. As did Phil Fisher, and I think he counted all successful investors in the second group.
I used to hope for luck. I don't anymore. But if luck does happen by I'm not above grabbing with both arms and running with it. In the meantime I'll be practicing and then more practicing. As I much prefer getting even to getting mad.
I'd rather not get into examples, let alone names (but I'll always be grateful to a certain poster who reviewed Boohoo (LON:BOO) when it was at 26p - doesn't mean I would touch it with a bargepole now and any mistakes along the way are entirely my fault and have been used extensively for my continous improvement programme).
I run a concentrated folio of 13 UK small caps, mainly AIM, and I do ok - just as well because as well as being my sole investment (other than my house and yard full of ancient landrovers ) I live from the proceeds!
My watchlist is much smaller than my portfolio, maybe a couple of companies most of the time, since as much effort as I can possibly expend goes in researching my holdings, their progress and continously challenging my investment rationale. Though I stay aware of as much information in my sectors and markets as possible and am always open to a better opportunity. They tend to come along when I least anticpate them. Maybe one or two a year tops.
Paul Hill always quotes successful investors as having a hit rate of 60%. And assuming that I qualify as a successful investor - then I agree - my hit rate is currently 62%. (for clarity I've held my largest holding for over 10years and my second holding for almost 20years - and have one new holding in the last year - so current hit rate is pretty much it). It's all in the position sizing and what you do with success when it arrives . For me there is no magic nirvana of complete success. Just a lot of hard work that I actually enjoy very much - for me it beats working for someone else for a living.
There will always be periods when returns are poor. I use those periods - FY20-FY22 were my worst ever - I believe that the experience has made me much stronger and I enjoy the work much more now.
I also hugely appreciate the many talented investors in this community who share so fully. I might not agree with them all - and they certainly don't all agree with me, but I gain from every contribution, however else it might seem at the time.
I think Charlie Munger said something along the lines of 'most folks can learn to be successful investors. But if you don't want to do the hard work and learn then you'd better off buying a tracker.' I've probably mixed it up but you get the gist?
I think you could do worse than head over to the Stocko academy and work out where what you are currently doing does not work according to the resources there? I had to do it and it always helps me - though I never do what Ed suggests I can still use the learning in my own approach. Good luck with whatever approach you decide to use
cheers
Mark
I think the statistic isn't any better for share traders/investors.
there will always be poor stock pickers and people who blame others for their shortcomings - no one is forcing anyone to invest in shares or do spreadbetting or similar.
What is 100% clear though is that if one invests in decent spread of highly ranked shares by stocky or one invests long term in sensible low cost trackers most people should most certainly not be losing money over the long term "most of the time". Heck the ftse 100 has performed pants the last 10 years but has still returned 84% - so its still positive expectation stuff for most people unless they are making poor decisions or have been very unlucky with timing. Note the prior 10 year period for the ftse 100 returns were much better - so the long game really can matter here as no one knows when the expected positive return will turn up.
From 31 December 2012 to 31 December 2022, the price return of the FTSE 100 was just over 23%. Yet, if dividends were reinvested when applicable, the return was over 84%.
Obviously ref the future we dont know - but if you are buying company with positive cashflow and paying say 10-20 times earnings and profits are matching inflation its pretty easy to see why one should be getting money returned as part owner - there are plenty of companies out there making profits that are reasonably consistent over time.
I beg to differ - if you follow a disciplined approach and focus on good quality, undervalued shares you should do well. I use the FTSE 250 as my benchmark (the closest thing to my investment universe) and outperformed it comfortably for each of the last 5 years - roughly doubling my money over 5y verus a flattish return for the FTSE 250. Stockopedia of course has also been a big factor in this - the small cap report, the community and the stock reports all extremely useful tools to complement my own research.
Hi Ben,
The simplest thing you can do is concentrate on a portfolio of 12-20 stocks and ALWAYS make sure you have about 20% of your portfolio in CASH. You can invest 30% in shares listed in the UK and 70% on shares listed in the US. Do not invest in shares that their revenues are declining and have debt. Use a forward 2-3 year approach (2026 and 2027 estimates) to decide if you will invest on any single share. Do not invest more than 5-8% on any share.
The best thing to do is ask here before you invest on any share and there are people here that they willing to help you and give to you their own expertise opinion and then you can do your own research as well and decide what to do. Have an open mind and accept that others make very good money in this game and if you do not understand how you can either follow these people or simply do not get involved at all and do something else with your hard earned money.
All the best
hi yiannos1
I hope you don't mind me saying that it has been very refreshing to witness, in recent months, the transformation in your contributions on SCVR.
I don't think I'm being controversial in saying that you were previously building up a reputation for being confrontational and had little patience for those less investment savvy than you. Also your posts were regularly being deleted by the moderator.
Nowadays you are posting very helpful commentary for the community, some excellent investment suggestions and when you challenge others opinions you do it in a constructive and friendly manner. No signs of confrontation any more.
Don't know how you've managed this change but good on you for doing it. Long may this continue.
Snazzy
Don't know how you've managed this change but good on you for doing it. Long may this continue.
Ive been posting him a few horse tranquillisers:)
Agree tho, always worth listening to Yiannos.
i'll second this , Thanks Yiannos i always enjoy your contributions to the share knowledge and agree you have trimmed your style for the better. Glad you didn't let your subscription expire, long may your useful comments continue :)
Hey Ben, I just buy stocks that go up and have rising broker forecasts. I don’t care what they do as long as it’s not mining, oil or pharma. I don’t look at debt, PE ratios, free cashflow etc. if the stock is going up then the market is happy with those metrics. This game isn’t that hard if you don’t try and be too clever. Oh and always use a stop and add to winners.
Disco this is pretty much the Robbie Burns approach I've been on a couple of Robbie's advanced days and he screens a stock in about ten minutes this process filters out 99% of the rubbish such as big debt, big spread, micro caps, loss makers.
He then takes a position and sticks to his stop loss and this is what separates him from the 90% of traders who lose over time if something goes down past his stop its gone no messing about.
When you go on his learning days you sit there and think this is too simple he can't have made millions doing this but he has basically by sticking to stops, not over complicating and filtering out rubbish.
It could be worth booking on one of his courses Ben he's a brilliant speaker and 99% of the people who turn up would be there all week if he didn't kick us out at 10pm.
bensummers
With respect, you seem to be in a very confused and bitter place. I could only suggest you either give up and move on, invest in collective assets like Investment Trusts or ETFs or start again from scratch.
I would never attempt bottom feeding as a methodology. Stocks are at a bottom for a reason and probably have a better chance of staying there or going lower (or bust). I wouldn’t presume to have the skills to pick the probable winners. Read the stuff in the Stocko learning sections to find the proven best approaches to decent results.
You do not have what I would call a watchlist of hundreds of UK stocks. My current watchlist contains 20 stocks picked from my Stocko screens, SCVR references and a subscription publication. I have already done some prelim research on these and if funds become available will do further (current) work on them before investing.
If you do stay with investing in individual stocks and are unsure about building your own Stocko screens you could as an example start with a copy of the Stocko team’s Screen of Screens and add a few sieves of your own. Stocks on this screen have passed at least one GURU screen. I have 12 stocks on mine which have passed at least 4 GURU screens.
Cynically inclined myself, I wouldn’t say all Directors are only interested in themselves ………… hmm
Hope this homily is of some use – good luck whatever you decide.
Ben, I thought long and hard about whether to write anything as I didn't want it to come across as gloating. It's late on Friday and you may not even read this.
I left my job in my late twenties and started seriously investing from 1999. For the first 5 years I didn't know much and would make + or - 50% as I followed the latest craze.
2003 recession taught me about the importance of cashflow and cyclicality. 2008/Covid taught me about black swan events, the importance of looking ahead and never being a forced seller.
I have only ever invested in UK AIM/small/midcap companies and no oil/mining/banks. It means I can follow 300 companies and generally feel that I'm ahead of the curve on most of them. I don't follow them all every day - often you can see when a company is entering a rocky patch and it's not worth wasting time on it until it's stabilised.
The net result is a 23.6% compound return over the last 25 years (that's given me £201,000 for every £1,000 I started with). Consequently, my portfolio is the size of a small fund (which has its own investing drawbacks).
Am I a great investor? No way.
Do I make mistakes? Yes. Every week.
Do I suffer from FOMO and impatience? Oh yes but you get better at handling it over time.
My point is it's very possible to make good returns from UK smaller companies but (for me) it takes 5-6 hours a day as there's always something new to learn. Learn about the companies you follow. Learn which managements know what they're doing. Learn about the importance of free cashflow and be able to forecast it. Learn from that sick feeling in your stomach when you make a big loss. Learn when you get something right. Learn about risk management and portfolio sizing. After 25 years, I still learn something new every day, often about myself.
Good luck.
Thanks for posting and and an enviable track record.
would b good to understand some of the most important lessons you have learnt ?
That's a hard one. Most of it has been said on stockopedia in one form or another and far more eloquently than I could. Most of it is also pretty obvious although our human nature is always getting in the way.
1. Everyone is different. Play to your strengths, avoid your weaknesses. e.g. I'm good at seeing which companies are going to be ahead of where the market thinks in 3 years time. I'm bad at short-term trading.
2. The market swings between overoptimism and end of the worldism. Why should a good quality company with decent financial resilience be valued at 12x FCF one day and 4x FCF 6 months later? I'm happy to average up or average down if the fundamental story hasn't changed. I find it more satisfying (and remunerative) making 25% on a large holding than 100% on a small (but stressful) holding .
3. Numbers (particularly net cash and cashflow) don't lie 99.9% of the time except when there's fraud. I used to meet a lot of management face to face but was bad at telling a good salesperson from a good CEO. Thanks to COVID there are a lot of webinars where you can get a flavour of management and ask questions while still keeping your distance and impartiality.
4. S**t happens. If you missed or (worse) ignored the signs, learn from that. If there were no signs, then feel bad for a couple of days and get over it. Adjust your risk management accordingly.
5. Money is important but quality of life is far more important. Take your largest holding, assume it's a zero and ask yourself whether you can still sleep at night?
6. Keep evolving. Stubborn can be good at times but it can also be stupid. Work out which one you're being. Patience and the ability to view yourself objectively are probably the two most important attributes for an investor in my view.
7. Love what you do because there are going to be times when the markets crash or (worse) grind lower for 2 years and you need to be able to get up every morning, read those RNS's and bring your best game.
Hope that helps.
The Brothers.
Fantastic story Brothers congratulations, a few questions if i may,
Did you come from a financial services background or were you self taught
What was the best book you have read on investing/trading
How many stocks do you hold in your portfolio on average
Do you top slice on the way up if so what triggers the point to add
Do you look at support and resistance charts
Do you use stops and if so how do you apply them
What has been your biggest learn that improved your trading performance.
No issues if its a ball ache replying, I like the fact you see the bigger picture with quality of life over stuff.
I'm in mid fifties now work for myself I make enough to get by and eat out 2-3 times per week, but against my old jobs financially I've never earned less, the trade off is I only work mon-wed and can have eight weeks off per year.
I am aware now I might only have 20-25 years left on this planet and its important to me not to get to stressed and be able to spend time with friends and family, plus on a Thursday morning sitting in the garden with a daily paper listening to the birds sing is great.
Regards
Andy
Fantastic story Brothers congratulations, a few questions if i may,
Did you come from a financial services background or were you self taught
Yes. I did corporate finance at an investment bank although most non-traders I knew there weren't very good at investing for themselves (not to mention the hassle with all the compliance). The one thing it taught me was finding my way around a set of accounts.
What was the best book you have read on investing/trading
Believe it or not, I've never read one. Obviously I've read excerpts and articles online and stockopedia is very good . I guess I preferred learning from experience - probably very stupid with hindsight.
How many stocks do you hold in your portfolio on average
60% of my portfolio is in 25 stocks. Then I have a long tail of smaller holdings. When you follow companies for 10/20 years you often get invested in their journey and I like to have small holdings in a lot of companies to monitor them. I'll then adjust up or down as they progress (or not). The other issue is that once your portfolio grows, liquidity in smaller companies becomes an issue.
Do you top slice on the way up if so what triggers the point to add
Not usually. Sometimes I will to limit my exposure (currently 10% max per stock although that's flexible if a stock rises a lot) or if there's some uncertainty creeping into my investment thesis.
There are no hard and fast trigger points to add. I'll often add if the market looks like it's beginning to cotton on to the undervaluation, but I'll also add if the market gets bored and a stock drifts lower. Patience is one of a private investor's biggest advantages.
Do you look at support and resistance charts
I glance at them but generally find them to be backward looking. With low liquidity stocks they're not always that helpful. Having said that, there are often times when a chart seems to precede positive or negative newsflow and I have huge respect for people who can get a decent hit rate using them knowing that mine's about 50/50.
Do you use stops and if so how do you apply them
No. I will set stockopedia to notify me if a share price drops below a limit and then I'll re-examine my thinking on the stock. The resulting action could involve selling out/reducing but often it involves averaging down. When you own 1-2% of a small company, it's very hard to trade in and out.
What has been your biggest learn that improved your trading performance.
Tricky one. Most of it's on stockopedia in one place or another.
Resilience - company cashflow, balance sheet strength. Can I sleep at night if my largest holding is a zero? No personal issues that might cloud your investment judgement e.g. debt etc.
Performance - leader/disruptor in a growing market. Long runway. Big moat. Network effect. Trustworthy and competent management. I need to see it (or the beginnings of it) in the numbers rather than listen to the spiel. Likewise with cyclicals - stabilisation at the bottom of the cycle. Turnarounds - show me the cashflow. I tend to invest too early and have to wait a while for my "brilliance" (haha) to be recognised. Hence the importance of patience.
Improvement - try to be better at investing tomorrow than you are today. It sounds a bit trite but make bigger investments when you're right. Learn to identify and rectify your mistakes earlier because you're always going to make some. Watch out for hubris and depression. Use communities such as this one. Listen to other investors - you may not agree with them but at least give them the courtesy of your (hopefully) objective consideration.
No issues if its a ball ache replying, I like the fact you see the bigger picture with quality of life over stuff.
No problem. Investing can suck you in. If you can keep your perspective, you'll probably do better in the long run and certainly be happier.
Many thanks for sharing your story brothers, sounds like you have made it into the top table of 10% of investors, with a lot of hard work along the way, as you say helps if you love what you do.
Your a way better investor than me but one thing I would humbly add given it seems your on top of the mountain and you also value the things wealth can bring for others than yourself.
Maybe consider putting five years of living costs to cash or near cash that way if we have a bad run mentally there shouldn't be as much pressure on yourself as you would know the next five years living costs are covered come what may
I remember when Paul S lost his fortune he said it took roughly 2-3 years to get his belief/confidence back in himself, Paul's undoing was excessive gearing and being over invested in a few micro caps that he couldn't exit during the financial crisis.
I'm not for any minute saying your doing the same as your track record speaks volumes just saying having been uber successful it might be worth considering in case we had a prolonged 1-3 year bear market.
Regards
Andy
Magic results. 23% compound is impressive. Interestingly much of what you say is stuff I have slowly been learning too. I used to think I should have a piece of Japan, USA, Europe, Uk but all I really had was a global tracker.
The better I have become at this, the narrower my focus. Fewer shares, UK only, do some research, learn who to trust.
I note that the Stockreport for XPS Pensions (LON:XPS) has already been updated to include the final results which were only published yesterday! That is remarkably quick and very welcome! I find it very frustrating if I have to wait ages for Stockreports to be brought up to date. Is the situation with XPS unusual? Or has there been some process change which will do this as a matter of course?
YouGov (LON:YOU) finished the day at 440p yesterday. Yikes. It is now a ~£500m company. What an almighty fall.
If the slow sales were one off and they will be back on track soon, with the acquisition fully embedded, it may represent an absolute bargain. Stockopedia has the forward PE ratio at just 9 now (based on previous estimates before yesterday's bombshell). Of course, this is out of date now, but still puts the fall into context. A couple of days ago the 2025 forward PE was around 17 I believe.
YouGov (LON:YOU)
My biggest concern is the loan repayment schedule that the company produced here -26th of March, at around 34 minutes-. I don’t know how flexible this is and there are no numbers for the current year.
To save interested parties the trouble of gifting email addresses to YouGov to view the video (above), the repayment figures are 36 million Euros for FY25, 48 mil for FY26 and for FY27, and 108 mil for FY28. Compared to the £41-44 mil operating profit now expected for FY24, things look a bit uncomfortable.
No position.
re YouGov (LON:YOU) the H1 statement is worth a reread. Paul has given it amber /red ... understandably based on yesterday's statement. There are now three divisions, Data Products Revenue -2% Margin down from 42% to 39%. research Revenue -2% but margins up from 18% to 19% .... the operating profits of these two divisions are similar ... £16m ... but contributed -£1.5M. Central costs also rose £1.6m. This is a core business contribution of -£3.1m on a base of £22.6m ...which is a fall of 14%. Adding in the acquired CPS pushes the business back to growth. Bizarrely because CPS bills end of January they collect a high contribution compared to what you might expect from a deal that closed in January. £14.1m Revenue £8.4m Adjusted Operating Profit! I have to say it's still mind boggling to get back £42m current guidance from a £28m H1.
The point is that a careful read of H1 already reveals an amber/red flag.
The trading statement confirmed this. Also during the first half, Chief Commercial Officer was replaced ( previously Chief revenue Officer) Chief business Officer stepped down, so COO was managing the integration.
The stock got crushed yesterday. Historically a Stella compounder. They have already highlighted in their statement that in 2025 they will focus on optimising the cost base. Operating costs of about £180m leave scope to reduce 5%? to add back £10m to 2025. This probably gets you the majority of your bridge between 24 and 25. If the 25/26 nos can remain intact then the shares after the fall will no doubt look cheap. But something has gone very wrong though. Growth in 2022 was strong as were margins... there is an Edisson note on the company website with a £60m 2024 PBT forecast which I doubt had CPS in it!
On a positive for a business with such a strong track record you have to think private equity will have a look. The shares will pop on this... but who knows what they might find. I won't be doing anything ( despite being really tempted) until we get to see the final results and what the plan is for 2025.... still woefully short of information here.
RD you've probably seen it but 3 brokers downgraded today biggest was HSBC who cut target price from 11.65 to 3.70. Ouch
Thought there may be a bounce back trade yesterday but it never materialised and todays poor attempt has fizzled out.
Adnams (OFEX:ADB) yesterday pm announced (bizarrely 5 days ahead of the AGM) that trading was in line with expectations, and that the strategic review of fund raising options was progressing well, whatever that means. And that the Chairman will retire by next year's AGM, meaning no more famnily involvement. I expect Malcolm Heald will grab the throne.
Be interested in anyone's views as to why they have been underperforming other larger rivals such as Youngs, Fuller ST, etc.
'Be interested in anyone's views as to why they have been underperforming other larger rivals such as Youngs, Fuller ST, etc.'
For what its worth - my view......
Young & Co's Brewery (LON:YNGA) sold the Ram brewery site for redevelopment - now known as the Ram Quarter - and its beer brands ended up with Marstons, which in turn has sold them to Heineken. Fuller Smith & Turner (LON:FSTA) sold its iconic Griffin brewery in Chiswick to Sapporo. Leaving both companies able to invest in their estate of london based pubs and inns, through which they can earn a return on investment far greater than investing in the brewery. Sadly.
For those breweries that are still independent - making the right choice on allocation of scarce capital between pub estate, breweries and other ventures (they all seem to want distilleries these days ) must be very hard and unforgiving if not executed perfectly?
Very few of the olderregional brewers now remain, with Adnams, Shepherd Neame the unquoted Hall and Woodhouse (badger), and family owned Wadworths etc being fine exceptions that I can think of off the top of my head. The silver lining is that there are hundreds of newer more innovative breweries which do have the potential to grow.
cheers
Mark
There is also Daniel Thwaites (OFEX:THW) Which had figures 2 days ago. Currently trading at 85p. EPS of 12p and NAV an almost unbelievable 412p ! Small raise of dividend.
Like others seem to have sorted out staff shortages, inflation less of a problem, looking forward optimistically to a good year, especially with a new Lake District hotel which is their biggest investment now open and doing very well apparently.
And Hook Norton.
Where are Hook Norton quoted Sharewallah ?
And Hook Norton.
Yes indeed. Thanks for the reminder, I had a bottle of Old Hooky just the other week,
cheers
Mark
Pennant International (LON:PEN) have spent just shy of 6 months drawing up their 2023 results.
Note 5 shows additions to intangibles in 2023 as £28k software + £1,139k development costs = £1,453k total. The two numbers don't sum to the total.
The notes to note 2 state that capitalised R&D in 2023 was £1,452k ("in 2023 research and development costs of £1,452k were capitalised (2022: £1,139k)"), so presumably £1,452k should have been included in Note 5 in place of the stated figure for development costs of £1,139k (which was the 2022 figure). But if that correction is made, then the total in Note 5 for additions to intangibles in 2023 should be £28k + £1,452k = £1,480k (not the £1,453k stated).
The notes to note 5 state "During 2023 the Group capitalised £1,425k (2022: £1,139k) of costs in relation to the ongoing development of the GenS software solution". So now we have £1,425k being capitalised (rather than £1,452k mentioned in the notes to note 2).
If we go back to the table in note 5 and use £1,425k as the figure for development costs in 2023 and add the £28k software, we get the stated total of £1,453k. Using £1,425k in place of £1,139k in table 5 also makes the costs total for 2023 correct (as it stands 9,911k - 21k + 1,139k does not come to the claimed £11,315k).
Shouldn't the numbers be checked by the exec team and the advisors before they're released? What else is wrong?
Pennant International (LON:PEN) As a Chartered Accountant i hear what you are saying. I would add that the accounts are quite difficult to find on the their website, the font used for the headings is faint and hard to read and i noticed one of the lines of numbers were not fully aligned.
Most people would say this is trivial but it does show a lack of care or attention to shareholder interests. For me a red flag.
On the subject of NCC (LON:NCC) I attended yesterday’s Capital Markets Day for their Managed Services division. Several interesting presentations & I feel I better understand the business. It’s a very competitive space but they’ve now put their suite of services under a unified cyber platform which they believe will improve gross margins (currently c38%), let’s see
I have a shareholding as I can see them selling their Escode escrow division in the near future for a decent price; they’ll then be a much more attractive company for a competitor to acquire- a rather simplistic view I know but the rising 1 year chart suggests I may not be alone in this view
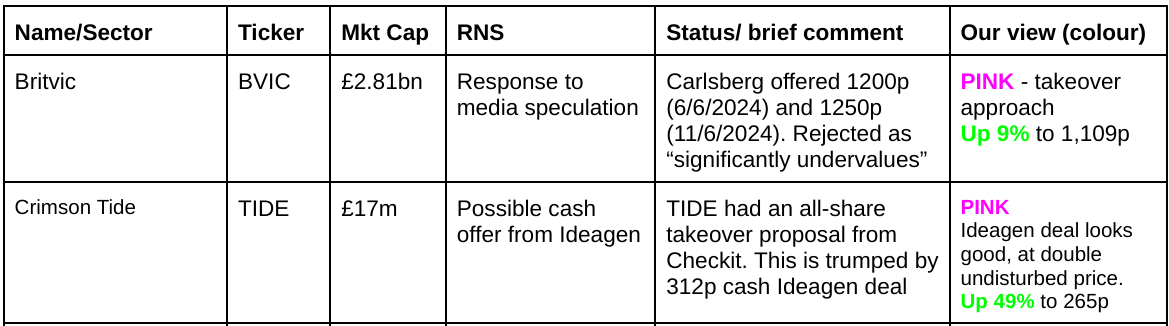
Britvic (LON:BVIC) another take over proposal gets rebuffed. This time Carlsberg offers 1250 pence for Britvic. The initial offer was at 1200p made on the 7th June before being upped on the 11th June. Another example of only coming to light through media speculation.
I know it’s a controversial subject but I think with UK valuations so low, boards are absolutely within their rights to bat off a “low ball” bid without saying anything, because let’s be honest in most cases when the bid does come to light ( normally a second or third higher bid ) then the co is a dead duck, so why not wait and squeeze the best price possible. The impetus is then on the board to pull their finger out and justify the rejection. What we are seeing now is the predator coming directly to the market and/or discretely leaking it through the press.
Hi planetx
I weighed HSS vs SpeedyHire when I was looking to rent a small number of cyclicals back last winter. Neither is a great business, but happy to have plumped for the latter - mostly based on the mentions of AI (only kidding).
Pennant “do I not like that “
Nice update .
New chairman statement dynamic .
Margins up to 50%
Rockwood increasing .
9 million assets
A post year end property disposal of 500k
Super hot sector .
Under the radar this , I spoke to the CEO a week ago and he’s very open, was due to go down last week but I bailed until after results .
The failed corporate activity charge of 300k is interesting and I got the impression this is very much just on hold so I’m suspecting there’s a reverse takeover of something much bigger going to happen in the next 24 months .
No idea what that means apart from a massive fund raise so that’s a bull and bear question .
Share price has been incredibly weak not sure how it will respond to this , probably up slightly is my guess .
If it drops I’ll add more
Hi Planetx
I have owned shares in Pennant International (LON:PEN) for quite some time now. I have spoken numerous times to management who are super keen, open and have moved the business from massive losses from an onerous and costly large contract which concluded last year and low margins to a much higher margin software biz with a sensible balance sheet.
Recently, since Rockwood bought in, the board has been substantially beefed up by the addition of Ian Dighe ex Miton amongst others. The potential opportunity is significant. Pennant operate in the defence training sector which does not do well at the start of the defence spending cycle but can benefit significantly at a later stage. Some contracts have been delayed due to spending on the Ukraine war taking precedence but Pennant are embedded in many of their clients so the delays should turn into contracts over time.
I continue to be patient.
HS hire v Speedy Hire
HS lost the amey contract which was 20% of their turnover
Picked up by Speedy hire .
This is interesting as it reflects something Lawrence Hulse of Dowgate spoke about .
Speedy had invested heavily in hydrogen powereed generators and other green initiatives that have given them some short term pain in building up the fleets .
He commented on the ESG requirement if the big contractors especially the ones with blue chip clients so this is exactly that kicking in .
Have to say Speedy may have played a blinder here and are poised to reap the benefits of investing heavily to produce the countries greenest hire fleet .
Still no need for so many initiatives and management speak and mentions of AI in their RNS .
But looks like their CEO took some bold long term steps and has positioned them now to do well and after a fair degree of criticism because of the investment required .
Gulf Keystone Petroleum (LON:GKP)
An interim dividend just announced and continuation of buybacks!
Cash balance increased by $7m in a month after taking out the $6m already used for buybacks.
Even without the resumption of the pipeline this is still an undervalued stock.
Have a nice weekend all.
All the best
Homework finished on Gulf Keystone Petroleum (LON:GKP)
They will be generating FCF of about $90m at the moment on local sales and only by selling at $28-all $90m FCF will be returned to shareholders.
It is clear now that anything above $80m held in cash will be returns to shareholders by dividends and/or buybacks (hopefully more on buybacks).
All the best
Well done Yiannos, you picked it.
Thanks yiannos for the further posts on Gulf Keystone Petroleum (LON:GKP) today. I’ve held since December 2020 except for a few months after selling at £1.60 on the pipeline closure news in March 2023. I bought back in again around £1 last August and September and added more in May at £1.20. It was a share that featured regularly on the BARGAIN threads on Mike Walters bulletin board from 2020.
Gulf Keystone Petroleum (LON:GKP) seem to be coping remarkably well considering the pipeline is still closed, so when the pipeline eventually reopens could the share price exceed the previous £3 high and then some?
And the news of a 5.3p dividend today is a pleasant surprise. Though unlike yiannos I prefer dividends to buybacks, the buybacks mean fewer shares on which to pay the dividend.
And Gulf Keystone Petroleum (LON:GKP) paid huge dividends ahead of the pipeline closure and they were so big with 23p in 2021 and 87p (5 dividends in 2022) that those 2 years alone covered my entire stake in Gulf Keystone Petroleum (LON:GKP) bought at about £1 in December 2020. If they can return eventually to dividends at even half the 2022 level investors will be getting a near 30% dividend yield at the current 150p share price.
It’s a share well worth checking out.
A special Hat Tip to yiannos1 for his suggestion to readers to take a look at Gulf Keystone Petroleum several weeks ago, I did and liked what I saw, agreed still early days but looks very promising.
All The Best, Have a Good Weekend, I Will, Thanks Again