Small Cap Value Report (Fri 21 May 2021) - ELTA, HEAD, GATC, CARD, STAF

Good morning, it's Paul and Roland here, with the last SCVR of this week.
Timing - I've got to finish by 12:30 today, due to more zooms, and travel arrangements. Today's report is now finished.
Yesterday was a bit of a nightmare, with so much to do (including 4 zooms), and very tricky accounts to decipher from N Brown (LON:BWNG) (I hold). This is just to flag up that I finally published my section on BWNG at about 7pm last night, so many subscribers may not have seen it. Here is the link to yesterday's report, with the BWNG section, to start you off today.
Agenda -
Paul's section:
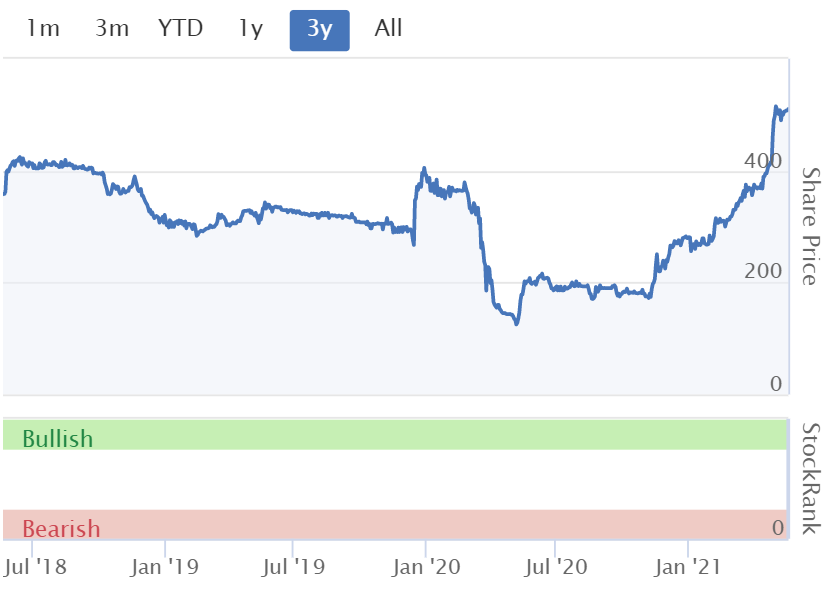
Electra Private Equity (LON:ELTA) (I hold) - really good news today. The planned disposal of its 2 main investments (restaurant chain TGI, and Hotter Shoes) will now be through demergers, and separate listings. I think this could maximise value for ELTA shareholders. NAV has shot up 46% in 6 months, to around the current share price, but still looks well below possible sum-of-the-parts disposal values. So plenty more to come, in my opinion, even after a strong share price rise of late.
Headlam (LON:HEAD) (I hold) - a reassuring, in line with expectations AGM trading update. Revenues now almost back to 2019 pre-covid levels. Shares have risen a lot, but still look very good value to me. Bulletproof balance sheet includes c.£100m freehold property. Generous divis should resume. There's lots to like here, for value investors.
Gattaca (LON:GATC) - "Improved outlook" - a positive update, although forecasts have been slashed to near-zero, so not madly exciting to be beating such a low forecast. Good signs of recovery. Share price has already tripled, and I don't see obvious immediate upside on the current valuation. Balance sheet looks OK, so probably little to no dilution risk.
Roland's section:
Roland:
Card Factory (LON:CARD) - this indebted retailer has now released details of the refinancing package it agreed in April. Shareholders seem likely to face dilution as the company needs to secure additional cash to fund accelerated debt repayments.
Staffline (LON:STAF) - this recruiter has just launched its second refinancing in 12 months. Existing shareholders face big dilution, but this could provide a more solid foundation for a recovery. However, the stock still looks quite fully priced.
Sanderson Design (LON:SDG)
(Paul: I hold)
One of the company webinars I attended yesterday was with management of Sanderson Design (LON:SDG) - the relatively new CEO Lisa Montague comes across tremendously well - with a crystal clear strategy, being implemented well. Her focus on efficiency has already delivered transformed results in H2, as I reported here on Tuesday.
In particular, efficiency gains have enabled a headcount reduction of 10% saving about £3m p.a. - obviously difficult for the people concerned, but in the interests of the business and the rest of the staff. A big reduction in the number of stock lines (SKUs) has freed up cash by reducing inventories, and improved manufacturing efficiency. SDG now produces fewer, but better new collections.
It struck me also (as with many other companies) that the pandemic has accelerated adoption of technology, and helped companies focus on better, more efficient ways of doing things For example, SDG said that they've now moved entirely to digital launches of new product ranges, whereas in the past a team of people would hit the road and physically show the new ranges to customers. That isn't necessary any more, and the whole sector has happily adopted doing things online instead, including customer ordering ("not quite as slick as Amazon yet, but we're getting there").
Peak Earnings
I've largely abandoned broker forecasts for valuing companies, because they're often way too pessimistic, and don't really make sense. This is causing a lot of good shares to have apparently very high forward PERs, when they really don't. This is providing us with opportunities, to spot companies where the forecasts are too low, and buy in ahead of forecasts being raised. Two shares I hold Vertu Motors (LON:VTU) and Joules (LON:JOUL) both saw large broker forecast increases last week, and I think many more are in the pipeline. I don't think analysts are doing anyone any favours by being super-cautious, due to macro uncertainties, when the positive evidence is all around us of a V-shaped economic recovery underway, company profits rebounding, plentiful household savings, labour shortages, etc.
Instead of using broker forecasts, I've been tending to look back pre-covid, and see what peak (usually 2019) earnings were, and assuming that companies could return to that level over the next year or so. Providing covid is beaten, or at least brought under control, that is. It's vital to check if there has been any new share issuance from placings during the pandemic, as that needs to be taken into account when working out EPS (more shares means lower EPS for a static level of profit).
More recently, it's dawning on me that peak earnings pre-covid is not necessarily a big enough target. So many companies have stripped out costs, become more efficient, and increased margins during the last year. For that reason, I think the better companies could exceed previous peak earnings, giving further upside on some share prices. Although I need to see evidence of this, not just a wish.
For this reason, I'm not worried about share prices being too high generally. In some cases momentum seems to have gone too far, and there are lots of shares which are too pricey for me. However, in many recent SCVRs my conclusion is the same - that the share price has risen a lot, but that looks justified by fundamentals. As long as we're only holding shares which are valued sensibly, then we should be reasonably OK, even if the market as a whole does correct from its highs. In fact, these dips can be nice topping up opportunities, as flaky holders (traders, etc) bank their profits, or panic sell at the slightest downturn.
.
Paul’s section
Electra Private Equity (LON:ELTA)
(I hold)
510p (pre market open) - £195m mkt cap
This is a very interesting special situation, which a friend flagged up to me recently, as I never would have found it otherwise. So he’ll be getting a lavish lunch at my expense as a thank you, in due course!
I did a write-up about ELTA here about 3 weeks ago, explaining why I see hidden value in this share.
The short version is this: Electra is an investment company which is being closed down, through disposals of its holdings. There are 2 main holdings left - TGI Fridays (casual dining chain), and Hotter Shoes (mainly internet specialist shoe maker/retailer). Both are very attractive, profitable, growing businesses.
The sum of the parts could considerably exceed the current share price. The timescale for completing the winding up & distribution of cash to shareholders, is end 2021, so we don’t have to wait forever to get paid. I think the eventual payout could be as high as 1000p+ (double the current share price), but that depends on management achieving good sale prices for TGI and Hotter, which obviously isn’t guaranteed.
EDIT: My understanding is that the method of distribution is likely to be "in specie" - i.e. ELTA shareholders will get shares in TGI, and then ELTA shares will morph into Hotter Shoes shares. I'm really pleased with that, as I see this as a cheap entry point into 2 excellent future standalone shares. End of edit.
The big news today is this, which I’m delighted at, because I think this is more likely to maximise the value of the disposals above trade sale prices -
Decision to list Electra's Two Largest Remaining Portfolio Assets, TGI Fridays ("Fridays") and Hotter Shoes ("Hotter"), on the FTSE Main Market and AIM, Respectively
Both companies are ideal for separate listings, and should be attractive to private investors, since they are good quality consumer focused companies. Re-opening for TGIs restaurants also makes this ideal timing, with pent-up demand being unleashed, and there are very few listed restaurants, in the UK, so I imagine there could be good market appetite for these listings.
The new management teams at our two remaining larger portfolio assets, Fridays and Hotter, have performed admirably through the pandemic, not just sustaining their businesses in the most difficult circumstances, but also transforming them. In light of this, and their potential for further significant longer term value creation, the Board has decided that the optimal outcome for shareholders is likely to lie in a capital market solution for both businesses. It is our intention to demerge Fridays onto the FTSE Main Market late in the third quarter of this year and, subsequently, in the fourth quarter, to bring Hotter on to AIM through reclassification of the Electra entity. Plans are well advanced for both listings."
NAV - has greatly increased, and still looks extremely conservative to me -
Net asset value ("NAV") as at 31 March 2021 of £196.9 million or 514.3p per share (September 2020: £135.3 million or 353.4p per share)
Here is the table for how NAV is arrived at -

.
As you can see above, there’s been a tremendous increase in NAV per share, up 46% in just the last 6 months, to 514.3p per share. This is why the share price has been rising, as the market anticipated that NAV would rise.
Remember too that NAV is calculated on cautious assumptions for how to value TGI and Hotter, the 2 main investments. The values at IPO should be considerably higher, in my opinion.
My opinion - as explained in my separate post about ELTA, I see considerable upside here on a sum-of-the-parts basis. Floating Hotter & TGI separately should maximise the value of the disposals.
Net debt at the individual companies is higher than I expected: TGI now has £62m net debt (I had worked on c.£40m), and Hotter has net debt of £12m. That would need to be taken into account in pricing the disposal values.
Reading through the commentary today, TGI has had a thorough sort-out during lockdowns, and is now revitalised under new management. It also has a strong pipeline of new sites, on attractive terms and often already fitted out (so lower capex than historically), plus a new format of USA themed cocktail bars called 63rd + 1st - which sounds like a reference to an address on the New York grid pattern road map.
Hotter is achieving +30% online sales growth, and is also decently profitable.
I think both would be very attractive new floats, which institutions may well snap up. If the valuations are decent, then ELTA shareholders could see a lucrative payday in the next 6-9 months. Hence I’m very happy to sit tight and await developments.
.
.
Headlam (LON:HEAD)
466p (flat, at 09:52) - mkt cap £396m
Headlam (LSE: HEAD), Europe's leading floorcoverings distributor, provides the following trading update in respect of the first four months of the year...
It calls itself Europe’s leading floorcoverings distributor, but the UK is its biggest market by far. Also as previously announced, its small Swiss business has been disposed of, which has now completed. That’s fine by me, I think small overseas subsidiaries are probably a distraction for management, and don’t move the dial in terms of profit or growth potential.
Today’s update is encouraging, with the summary being -
Pleasing performance with trading improving throughout the Period
Main points -
- Trading in line with expectations
- Soft start to the year (Jan-Feb 2021), since improving - Mar, Apr, May 2021 all good
- Revenues for Jan-Apr 2021 up 30.6% vs 2020 (impacted by lockdown 1), and slightly below the more meaningful 2019 comparative
- Demand - residential strong, commercial soft
- Capital Markets Day 1 July 2021 - not sure why, as the balance sheet is strong, so it doesn’t need to raise fresh equity
- Sales team being reorganised, to make them more efficient
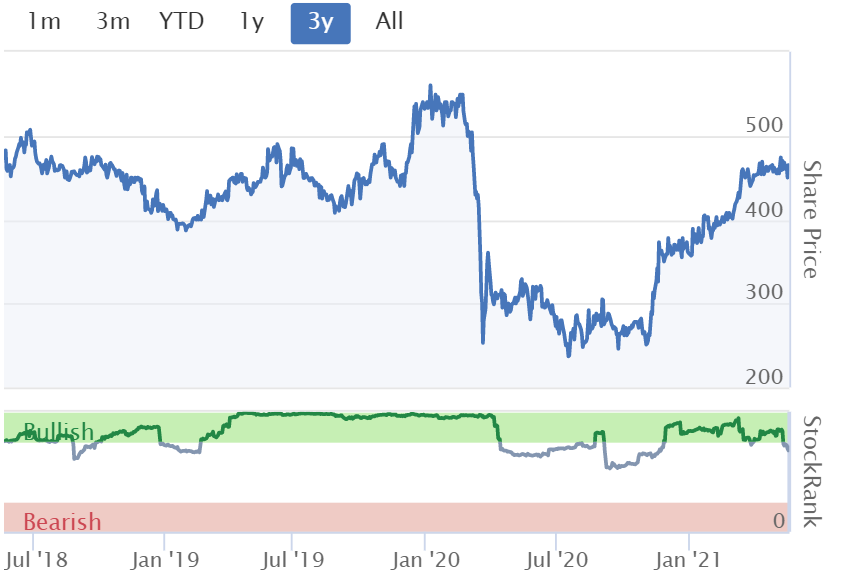
Valuation - the share price has risen almost continuously since the vaccine news broke in Nov 2020. Is it too expensive now?
Broker consensus is 26.0p EPS in FY 12/2020, and 30.4p in FY 12/2021. Those forecasts look too low to me. Since revenues are almost back to 2019 levels already, then we should be valuing the company on pre-covid earnings, which were c.40p EPS. Particularly as the company has been on a cost-cutting & efficiency drive, so there’s a good chance earnings could exceed previous peak, which ties in with what I was saying above in the preamble.
Hence I think it’s logical to ignore broker forecasts, and value HEAD shares on a multiple of 40p EPS pre-covid. That works out at a modest PER of 11.6 times. So not expensive at all, actually rather cheap.
Bear in mind also that HEAD has a smashing balance sheet, including c.£100m of freehold property. This increases the chance of a bid from private equity, or someone like Victoria (LON:VCP) - since they could sale & leaseback the property to help pay for the acquisition.
Dividends should also return, and a twice covered divi should yield about 4-5%, if my estimate of a return to 40p EPS is on the cards.
My opinion - I’m very happy to continue holding, as this share remains good value in my opinion. The price last summer/autumn was absurdly cheap, and it’s just recovered to a level which is more reasonable, but arguably still cheap, once a full recovery is factored in. In my head I'm valuing it at 600p+
With a bulletproof balance sheet, and strong cashflows (allowing a good divi yield to resume fairly soon), I see lots to like here, for value investors.
.
.
Gattaca (LON:GATC)
151p (up <1% at 11:51) - mkt cap £48m
Trading Update - Improved Outlook
An interesting innovation - putting a two word summary in the RNS title. I wonder if it will catch on? It certainly drew my attention to the announcement.
Gattaca plc, the specialist Engineering and Technology recruitment solutions business, today issues a trading update for FY ending 31 July 2021.
... faster rate of recovery in NFI than originally expected
(NFI is Net Fee Income, which is revenues due to the company, stripping out the pass-through wages of the contractors they provide)
Q3 saw +13% sequential growth on Q2
changes arising from the introduction of new tax legislation (IR35) had less of an impact on the Company than we anticipated.
We now expect NFI in H2 to be in the order of 10% up on H1 2021.
making targeted investment in sales and delivery headcount, whilst closely managing our cost base.
New IT system launched successfully in April.
Outlook - this looks good -
Whilst there remains uncertainty around Covid-19, our current expectation is that this rate of recovery will continue, and we therefore expect our underlying continuing profit before tax for the year to 31 July 2021 will be significantly ahead of market expectations.
Dividends - a “modest” divi will be introduced for FY 07/2021
Why hasn’t the share price gone up today, in response to this? Possibly because they took an axe to forecasts a while back, and set the bar at zero! So it wasn’t hard to step over it, arguably -

.
Dilution - we’re getting a lesson in the danger of investing in companies that have stretched finances today, with Staffline (LON:STAF) and Card Factory (LON:CARD) both tumbling on announcements of fundraisings. I’m sure there will be more to come. Banks have filled the gap in the short term, but once things settle down, then banks are looking to reduce their risk from demanding companies refinance at shareholders expense.
I’ve heard from city friends that the institutions are getting tougher on fundraisings now - things that would have gone through on the nod a few months ago, are now being challenged, and the price for institutional support is now a deeper discount. So this is becoming a much bigger issue, and we all need to be careful about holding shares which are under-capitalised, as the fundraising may not happen in a way which is helpful to private investors.
Does GATC need more equity raised? I’ve checked the last balance sheet in the interim results, and in my opinion it looks fine, with positive NTAV, and plenty of net cash. Hence I’ll stick my neck out here, and say that shareholders probably don’t have to worry about dilution risk.
Valuation - this is the tricky bit. Pre-covid performance was quite erratic, so there’s no obvious stable level of profitability to refer back to.
Consensus for FY 07/2022 is 13.4p, which looks reasonable to me, for a PER of about 11 - given the uncertainty, that looks about right to me. Smaller players in this sector tend to be permanently on low PERs.
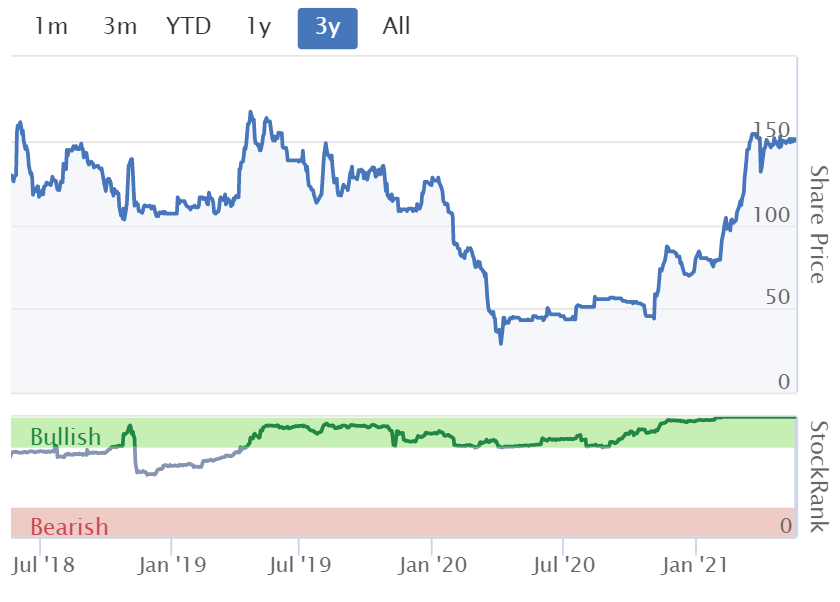
My opinion - the share price has tripled in the last year, and looks about right to me now, but of course I don’t know what level of earnings are likely to be achieved.
The US legal action that GATC is defending worries me, as it’s already consumed a lot in legal costs.
On balance, I’ll say I’m neutral on Gattaca. There could be upside from a strong economic recovery, but a lot of that seems to be already priced in. The chart below is saying the same thing - fully recovering from the pandemic.
Note the very high StockRank of 99.
.
.
Roland’s section
Card Factory (LON:CARD)
86p (pre-market open) - £294m market cap
Discount card and giftware retailer Card Factory has released details of a £225m refinancing plan to relieve the pressure on its balance sheet.
Card Factory, the UK's leading specialist retailer of greeting cards, dressings and gifts, today announces both an update on trading post the re-opening of non-essential retail and the completion of a £225m refinancing with its current banking syndicate.
The pandemic hit the group hard, due to its dependence on store sales. But in reality, the business was having problems before Covid-19, due to a combination of stagnating sales and excessive debt.
Card Factory has been a popular recovery and the shares have doubled since the end of February. Many shareholders seem to have been happy to ignore the risk of dilution in any refinancing. Unfortunately, today’s news suggests to me that this remains a big risk.
Paul last commented on Card Factory in April, when the company announced that details of a refinancing package had been agreed, but not documented.
We now have that information, coupled with a solid post-reopening trading update.
Trading update
I’ll brief over Card Factory’s (brief) trading update first, to give some context. Stores across the UK have reopened in stages from 12 April based on national guidelines. Initial store sales were ahead of both expectations and the performance seen after last year’s lockdowns.
However, the company says that “initial strong demand has been satisfied”. Like-for-like sales for the first five weeks of reopening are said to be “marginally down compared to the same period in 2019” (my bold). I guess that’s to be expected, as in my experience, not all shoppers are ready to return to the high street yet.
One area of concern for me before the pandemic was that Card Factory was lagging behind other retailers online. The company has taken big steps forward in this regard over the last year. Sales online are said to have fallen since stores reopened, but still remain ahead of pre-pandemic levels.
Unfortunately today’s trading update does not include any numbers and does not mention total sales. As a result, I’m finding it hard to get an accurate feel of performance since reopening. On balance, my feeling is that trading is broadly in line with expectations so far, but with some risk of disappointment.
Refinancing
Card Factory has agreed a £225m package of facilities with its existing banks. This increases the company’s liquidity from £200m previously, although the term of the facilities is not extended - they will need renewing in September 2023.
Net debt stood at £110m on 16 May, so has fallen somewhat from last year’s half-year figure of £143.9m.
There are three elements to the new facilities:
- £100m revolving credit facility (RCF): This is the company’s main credit facility and is essentially an overdraft. The terms are said to be “substantially” unchanged, except for revised covenants.
- £75m term loan facility
- £50m in coronavirus loans under the government-backed CLBILS scheme.
Card Factory says these facilities should provide enough liquidity to strengthen the group’s online operations and provide the capacity to fulfil sales demand.
My reading of this is that additional borrowing will be needed to fund working capital as the business restocks and builds inventory for the remainder of the year. I expect net debt to rise, in the short term, at least.
£70m equity placing
This refinancing does not include a compulsory equity placing. But the company has agreed to use its best efforts to raise £70m in new equity. This cash will be used to fund a schedule of early repayments that runs from 30 November 2021 to 30 July 2022.
If Card Factory fails to make these prepayments, it will have to pay up to £5m in additional fees to its lenders.
Interestingly, the company’s lenders are also willing to accept prepayments funded from “other subordinated sources”.
My impression is that Card Factory’s lenders have decided that their best chance of getting their money back lies in continuing to support the business. But they aren’t happy with the current level of exposure, hence the prepayment schedule.
Covenants
Card Factory says that covenants on the new facilities will be based around total net debt and last 12 months’ EBITDA. No details are provided, but they will be tested monthly until March 2022.
After this, covenant tests will return to quarterly tests of net debt/EBITDA leverage and EBITDA to interest cover. The thresholds on these tests are phased “to return to 2.5x leverage and 2x interest cover by January 2023”.
Card Factory has historically enjoyed decent margins and strong free cash flow. But for a low-growth high street retailer, leverage of 2.5x EBITDA is still more than I’d want to see.
My view
Card Factory’s trading appears to be returning to normal. In my view, the refinancing package should mean that the group avoids the risk of administration, for now, at least.
However, shareholders are not out of the woods yet, as a £70m placing would generate significant dilution.
Card Factory’s share price has rocketed since the government reopening plans were announced in late February, but I suspect that a placing would have to be priced well below current levels to find buyers.

Stockopedia shows a consensus forecast for earnings of 2.6p per share in 2022 (y/e 31 Jan). Digging around for broker forecasts, I’ve found estimates for earnings of around 11p per share in 2022/23.
These forecasts put Card Factory on a P/E of 30 for FY22 and 7 for FY23. This suggests to me that a full recovery has already been priced into the stock. Hence any new shares issued could be at a significant discount.
On balance, I think that today’s news is positive for Card Factory’s business. But until funding for the prepayment schedule is secured, the shares remain uninvestable, in my view.
.
Staffline (LON:STAF)
59p (-16% at 09:25) - Market cap £39m
Proposed Placing, Open Offer & Debt Refinancing
Recruitment group Staffline (LON:STAF) is a big faller today, as the company has announced a £48.4m equity placing and open offer at 50p per share. This fundraising is linked to a refinancing deal that’s intended to stabilise the group’s balance sheet and provide headroom for a return to sustainable growth.
The company has also provided an update on recent trading. This doesn’t really add much to the first-quarter update which Paul covered in detail on 26 April, so I won’t reiterate it here. In summary, all three of the group’s divisions were profitable during Q1 and trading conditions are improving as the pandemic eases. The company is confident in the overall outlook.
Fundraising and refinancing
Staffline’s equity fundraising and refinancing deal are linked. The company must raise the equity cash in order to secure the new financing facilities. This is what I expected to see with Card Factory too - it’s a more typical scenario for a struggling firm.
Reasons for fundraising: In April’s update, Staffline revealed that its net debt of £54.9m included a £46.5m VAT deferral. These VAT payments are now starting to come due and will be paid with the proceeds of the equity fundraising.
Refinancing: The new arrangements will replace a number of the company’s existing facilities with new receivables financing facilities totalling £90m. The new facilities will be secured “on all the assets and undertakings of the company and certain other members of the Group”. However, some existing customer-specific invoice factoring arrangements will be maintained.
The new facilities have a 4.5 year term, which should provide some stability and headroom.
The extent of the group’s current leverage is clear from the lending terms - interest costs will start at 2.75% over SONIA (the successor to LIBOR) when the group’s leverage is greater than 5x net debt to EBITDA. The interest rate will fall to 2% when net debt is less than or equal to 3x EBITDA. These are high levels of leverage.
Equity fundraising: Staffline plans to raise up to £48.5m by issuing new shares at 50p.
This is a big equity raise that will more than double the current share count. It will need shareholder approval, but today’s update suggests that if this isn’t forthcoming, Staffline could run out of cash and fall into administration.
There will be three elements to this fundraising, targeting a range of investors:
- Placing of 87m shares (£44m) - to institutions and certain Directors/employees
- Direct subscription of 750k new shares (£375k) - to Directors/employees
- Open offer of 8.8m shares (£4.4m) - existing shareholders will be able to apply for 10 new shares for every 78 shares they own
The board are putting some cash in, although not vast amounts:

If this raise goes ahead in full, it will increase Staffline’s share count from 68.9m to 165.8m. That’s an increase of about 140%.
To recalculate earnings forecasts to reflect this dilution, we need to divide by 2.4.
Stockopedia is currently showing 2021 forecast earnings of 2.33p per share, giving a P/E of 30:

Recalculating this to reflect the dilution from the planned equity raise gives 2021 earnings of 0.97p per share and a forecast P/E of 50 (at the placing price of 50p).
Staffline looked fully priced to me before today’s news. The stock now looks decidedly more expensive.
As with Card Factory, these numbers suggest to me that Staffline shares were already priced for recovery, without any allowance for the risk of dilution.
My view
As with Card Factory, Staffline has provided a painful lesson about the risk of buying shares in highly-leveraged turnaround situations. With the stock trading at 59p as I write, it’s remarkable to think that Staffline once looked reasonably priced at 1,000p.
In my view, this refinancing package may finally be enough to provide solid foundations for Staffline’s recovery. But with an implied valuation of 50 times 2021 forecast earnings, I think the stock still looks expensive given the company’s mixed record in recent years.
Even if earnings double in 2022, the shares would still trade on a post-placing P/E of 25, without any capital appreciation.
Staffline still looks speculative and risky to me. I think there are far better listed choices elsewhere in the recruitment sector.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

89 comments
Paul, sorry to trouble you but has something fundamental changed with Gattaca? It has gone up 40+% in the last 10 days or so and, as a relatively new member, I can't find anything to back up such an increase in such a short period. Is there anywhere within Stockopedia that notes such increases. Thanks
I have had an Idealing account for many years and have found their customer services very good.The main problem i have with them is that they do not do W-BEN forms this means if you buy a share like Somero you will pay more in USA tax on the dividend than if you buy Somero with a broker who offers a W-Ben form like AJ Bell .
Have not read in full but re:
“Yesterday was a bit of a nightmare, with so much to do (including 4 zooms), and very tricky accounts to decipher from N Brown(LON:BWNG) (I hold). This is just to flag up that I finally published my section on BWNG at about 7pm last night, so many subscribers may not have seen it. Here is the link to yesterday's report, with the BWNG section, to start you off today.”
I just amazed at your output and your ability to turn out these reports and that you are able to focus for so long each day. It is extraordinary. I hope you are looking after yourself.
Thank you.
Regards
Michael.
I have accounts ISA accounts with HL, IWeb and iDealing and SSAS accounts with HL and iDealing and used to have a SSAS account with AJ Bell before they decided they didn't want to service those any longer.
By far the simplest is iDealing. Reasonable charges. Wide range of available shares, ETFs, ITs and bonds. If I've ever come up with something I wanted to buy that wasn't on their system I've contacted them and they've added. If I wanted to make purchases above the NMS I've called them and they've dealt at the standard online charge. Dividends are invariably credited a day or so before HL manage to do so for the same shares. Never had a problem getting through to a human on the phone but very rarely needed to. .
The site is pretty basic - no research/news facility but that works for me. I just want to buy and sell shares etc simply.
If it wasn't for the FSCS £85,000 compensation limit I'd probably ditch the others.
No doubt others will have other experiences to impart.
I will have a look at iDealing account.
Re FSCS compensation limit, I think you will find it is different on share dealing platforms.
I had a look at at iDealing, fees not cheap and many additional fees such as for transfers etc.
Re FSCS compensation limit, I think you will find it is not £85,000 on share dealing platforms.
I believe it is:
https://www.fscs.org.uk/media/...
Mostly that would only apply to any cash in the accounts. Typically investments should be ring-fenced, although if the firm goes bust then the administrators may sell client assets to fund the administration, when the FSCS limit would apply (I believe, it's complex, best not to need it if possible, don't use small providers).
timarr
Yes and administrators can charge their fees to the clients as in Beaufort, where in the end, they were capped at £10,000 per client.
I could well be wrong (must be age finally catching up with me) but didn't that mean that the FSCS ended up covering the £10,000 per client?
If so, clients didn't end up losing money but had to go through the torment of initially thinking their loss would be substantial and still having to wait a long time for things to get sorted out and control of their holdings.
I have just looked into that, it. Seems the FSCS did cover the PWC fees, so yes they did not lose money. My understanding is the FSCS covers cash and fees if your platform goes bankrupt. Shares and other investments should be ring fenced, so you should get them back although this could take many months. So you are not limited to investing only £85,000 in shares etc. due to the FSCS compensation limit?
"Shares and other investments should be ring fenced"
Until they're not.
Mildly relevant article and comments on the broker risk point https://www.finumus.com/blog/w... Author seems quite risk averse in suggesting < 10% of one's trading accounts on any one platform but, yes, the Beaumont thing was a shock to the complacent.
I'd also understood there's a (remote) potential issue with broker cash. Eg if my shareholdings are correctly identified by the nominee/custodian yet I have £200k cash with said broker, fine because broker would normally spread his overall client cash over say 5-10 reputable institutions. So the £85k cap shouldn't intervene..........except that I have outside the broker £85k in Northern Rock and Northern Rock is the one that suddenly fails, then I potentially am at risk for the proportion of my £200k held with Northern Rock as I've already reached my compensation limit. And you won't of course know how your cash holdings with the broker are allocated. This is a fairly extreme risk I agree.
The more material risk as others have identified would appear to be the broker going titsup. Especially if they'd been struggling for a while - perhaps records aren't up to date. I'd like to think it's well nigh impossible for a broker to transact for a client without the nominee being updated but who knows how badly things can go? Then there's the potential risk of fraud if there's a bad actor(s) at the broker - false contract notes are issued and your funds haven't been invested where you thought? This would require collusion by multiple parties so hopefully a negligible risk except for the smallest, dodgiest brokers. Remember that dodgy brokers may also have client assets in unquoted securities, high interest loans etc, where there's greater scope for misallocation (part of the Beaumont problem I thought?).
I'm unsure where the spread betters fall in the risk spectrum but inherently feel there's a higher risk. Likewise with the recent 'commission free' set-ups like Trading212 which might be pushing their client trades onto bigger brokers (is this is what the industry calls 'flow'?).
Probably not enough to keep me awake at night, but I certainly won't be consolidating all my pensions into just one platform.
Would be worth hearing from the seriously rich with 8-figure sums how they mitigate these risks. I expect they're delegating to specialist asset manager institutions in most cases who will themselves have bullet-proof procedures.
Hi Wilbraham
It's an interesting article.
Break accounts can go both ways, of course, brokers sometimes find themselves with an excess of stock rather than a shortage. The amusing idea, though, is that people might end up being left behind in a rush for the exit. Given the pace of most brokerage account transfers the chance of avoiding a broker meltdown by moving must be considered pretty small :-/
Back in 2008/9 the possibility of brokers going bust wasn't just theoretical, a lot of us were seriously worried that it might actually happen. After that shock I moved my holdings into larger companies - TDW, HL, AJB and Saxo. TDW subsequently got taken over by ii and I'll be happier when they're finally listed.
To my mind there are four benefits of being on the larger, quoted brokers. Firstly, they make lots of money, so if there is an issue there should be plenty of funds to solve the problem. Secondly, there's excellent visibility of the accounts, so that if anything is going wrong there should be plenty of early warning signs. Thirdly, the sheer size of them means that if there is a major problem then the political pressure to fix it will be enormous. And finally, it's one less thing to worry over.
The downsides of the larger platforms have been well testified to on these boards. Their systems aren't built to handle high levels of volatility and trading and so are apt to fall over at inconvenient times. The underlying point, of course, is that frequent traders are not at all their main customers, so if they annoy a few very active customers into leaving that won't worry them at all.
On the issue of spreadbetters - I'd say the same issues apply. For instance IG's spreadbetting business dwarfs its brokerage account side, plus it's an enormous company. It's hard to imagine nominee customers ever having an issue there. The risk might be that they sell the brokerage business off to some smaller, fly by night, company.
In short - I think investors should worry about the financial stability of their nominee account providers. It's a tail risk - a very small chance of a very bad thing happening - but if it does happen, it's catastrophic for the individual. Trading off the security of your investments for a small improvement in fees or occasional system performance is, in the words of Nassim Taleb, picking up pennies in the path of the steamroller. Great while it lasts, but don't slip, and hope like hell the operator doesn't fall asleep at the wheel.
timarr
I have used iDealing for some 20 years and I really like their platform. It's bare-bones and simple and exactly what is needed by a trader. Also they don't appear to mess about with the platform as so many other brokers seem to do. They were my first broker and I have tried several others since. Charges for day-to-day operations are very reasonable and I have no experience of their other charges. My one concern is that they are a small boutique type of broker without the backing of a major finance house but so far - so good over a reasonable time period.
Agreed. I use iDealing, along with 2 others, and while the iDealing site is basic it does what I want, it's cost effective, and when I've had reason to contact them about issues or trades that proved hard to shift they've been excellent.
£ELTA
Reading through the half-year report I noted that the executives are entitled to £3.7m net proceeds from share awards. The gross cost of the awards amounts to a reduction in the NAV of 18.8p which isn't reflected in the 514p they announced today (Post Balance Sheet Events note).
While it's a reduction in NAV initially, I take it as a very positive sign that the full proceeds are being reinvested into the trust via subscription and hopefully a clear sign of much greater things to come.
I thought Boohoo(LON:BOO) followers may be interested in this article thread as I have not seen it mentioned thus far. https://www.thisismoney.co.uk/... "Boohoo has confirmed it will link multimillion-pound bonuses for its directors with improvements in its supply chain following allegations of poor working conditions and questions over its corporate governance practices."
Boo has been widely criticized for not linking directors bonuses to ESG targets in the past and they have been prompted on the issue several times. IMO this is a good move and a necessary one for for BOO if it is to get its share price back on track to previous highs. ( I hold)
Hi Paul
Re SDG, I see that Stocko has pencilled in something just over 3p for this year, giving a modest yield, but wondered if there was any mention of dividend expectations for this year or next by the Board?
Thanks
S
Hi Paul, not sure about Victoria (LON:VCP) acquiring Headlam (LON:HEAD) - think the CMA may get a bit twitchy
Headlam (LON:HEAD)
For all of the reasons Paul mentioned and with its distribution skills and large warehouses all over the country i can see Headlam (LON:HEAD) as a potential takeover target for a number of different businesses, not just Victoria (LON:VCP). For the same reasons Smiths News (LON:SNWS) looks a possible takeover target to me too.
Sorry to be off topic. A comment came up the other day, and frequently does about the efficiency of online brokers. As an up date to the post about Lloyds the other day I received this letter today about my transfer out of IWEB:
"Our aim is to provide a smooth transfer which can take 6-8 weeks to complete. (its already taken 8 weeks to get this letter telling me its going to take 8 weeks!). If you sell any of your holdings or buy any new ones during this time please let us know as it may delay the transfer. I don think they need any help in that department! Jeezzzzz
That is ridiculous!!
I had made a complaint to HL about a couple of issues and had heard nothing so i jogged their memory yesterday. This morning i had an email telling me the FOS gives them 8 weeks to deal with the case. I told them that although the FOS might give them 8 weeks I wouldnt.
I have no experience of IWEB or LLoyds but HL's platform is old, slow and not fit for purpose in my opinion. I will be moving but not sure where to.
Any tips?
Richard
Unfortunately, 8 weeks is the regualtory timeframe a business is given to resolve a customer's complaint. Ideally, it should be resolved as soon as possible, or within 4 weeks. if you have not had a final response after 8 weeks, you have the right to refer your complaint to the FOS and the case becomes 'chargeable' (HL will have to pay FOS to investigate).
From my experience, most businesses hate FOS referrals because the charges do stack up, and all these complaint numbers need to be reported to the FCA who actively montors the levels of customer complaints and if they're being handled within the prescribed timescales. I suspect HL will escalte your complaint the close the 8 week deadline looms.
I agree about HL, very poor service recently, took over 2 months just to transfer some cash to another ISA platform. I have a good mind to transfer my account elsewhere. HL fees are too high and the service is not as good anymore.
Platforms have a lot of room for improvement in the UK.
I’m possibly a lone voice in the wilderness here, but for the record I’m very happy with the online dealing platform service I get from Charles Stanley Direct. Decent, easily navigable website; good trade execution usually well within quoted market spreads; efficient admin (they’ve handled several PrimaryBid share transfers and a recent share certificate dematerialisation with no bother); and corporate events such as rights issues are communicated promptly and instructions implemented accurately. I recently transferred a joint account over from another platform (albeit in cash not in specie) which took about two weeks. Reporting of income and capital gains is readily available on demand in a report I submit as part of my annual tax return.
They’re not the cheapest (£11.50 per trade) but as I tend to buy and hold rather than trade positions this is less of a concern. Platform fee is similarly at a bit of a premium to some of the alternatives but little more than a rounding error in the scheme of things. Overall, I can’t fault the service I receive when I hear some of the problems others are having with their platforms (possibly why I bought the parent company £CAY shares too).
Gus.
Hi Gus,
Thank for your comment.
I looked at CDC and because it looked too good to be true i rang them.
If you trade once in a calendar month in either your ISA or SIPP ALL your platform fees are waived for that month !!!
There may be an issue with SIPP withdrawal but they are going to advise me on this. If the news is good i will probably transfer to them.
I notice that they have an APP , have you used it ? If so is it any good ?
Richard
Hi Dicktrade.
I have used the Charles Stanley App. If anything it is slicker and easier to use than the website although I tend to stick with the website on a desktop PC rather than the phone/iPad App simply because I need to use a larger screen to be able to read the data! I think the App would be a good facility if you’re out and about during the trading day.
Gus.
I am a very satisfied customer of Flatexdegiro. Low fees ,excellent service and user friendly site. Not suitable for SIPP and ISA though
Well done Gus. Its great to hear of 1 satisfied customer. I don't really mind what the trading cost is.It really doesn't make a difference whether I pay 3, 5 10 or even 20. Somehow I feel it would be beneficial to some of these companies to concentrate on investment and service rather than trying to be the cheapest. I do expect a reasonably competent level of service which seems way beyond IWEB or Lloyds, otherwise we might as well trade on eToro for 'free.' I particular chose iWeb because I knew Lloyds were the parent bank and I foolishly thought it might be safer to be part of one organisation. Plus there is no charge for ISA after initial one off fee. Some seem to have a monthly management fee which is a bit rich. I'm going to Jarvis which is where I was 12 years ago till I took an enforced break. Unfortunately for some bizarre reason IWEB doesn't actually work trading trusts anymore. I can buy but not sell. I have tried different computers so its nothing to do with browsers which is the usual lame excuse, anything but admit blame and they obviously don't want to talk about it. That makes me think that is possibly not the only glitch in their system.
Thanks, I did look at Charles Stanley but their are a bit too high for me especially on US trades, with IG I only pay 0.5% forex and no other fees.
All my shares are in ISAs so no need for any tax returns.
I have to say that Interactive Investor (ii) do everything they say on the tin - no access or fund delay issues plus, they offer all the products and services that have been mentioned in this thread.
Dicktrade, I was (forcibly) moved from The Share Centre earlier this year, reluctantly taking up ii's offer to give my business a home. I've been pleasantly surprised and found things I could do online that before took postal letters. I guess it depends on what you want to do but from what I read of ii's competitors they are straggling.
Silver
About 10 months ago it took 8 weeks and a day for me to transfer ISA cash from HL to iweb. The longer they hold it the more money they make
Yes the more they make but upsetting your clients is not good practice as they will more likely go elsewhere. I have a SIPP I'm looking to move but it won't be to HL now. I'm also inclined to move more cash or even transfer it all to another platform.
Hi
I have had a similar experience transferring some funds from Psigma to HL. The Financial Ombudsman recommends that cash transfers should take no more than 30 working days. I have submitted a complaint to HL and set out a consequential loss claim that amounts to over £13k based on a simple calculation of the loss I have suffered from not being able to invest my cash in increasing existing holdings. I have spoken to the office of the Ombudsman and they have confirmed that they can consider consequential loss claims.
If a sufficient number of people claim compensation and refer brokers to the Ombudsman they will soon work out that it is in their interests to staff their transfer departments properly. It is unacceptable that a cash transfer between ISAs takes even a week let alone 30 working days but for periods longer than that I can't see the broker has any defence.
I will post when I hear back from the Ombudsman and am available to help anybody who wishes to draft a watertight case for consequential loss. I am not a lawyer but I have sufficient legal experience to write a letter that a broker will know they have to take seriously!
Hi Roland,
Excellent piece of Card Factory (LON:CARD), and a reasonable conclusion.
I've updated my model with the potential new equity raise and am happy to continue to hold the stock. Link added below
https://www.stockopedia.com/co...
DYOR
BSV
Admittedly only one person's experience, but I found trying to open an account and send a couple of cards online last week using Card Factory a frustrating experience. After failing for 20 minutes, I then opened an account with Moonpig and sent the cards without problem within 5 minutes. Guess which company I will use in future?
Here are my SCVR heat maps for today (prices as at ~9:10am).
I share these heatmaps with the intention of giving a visual indication of what is going on in the SCVR world: who’s reporting (and it's impact on the share price); and what’s moving more than 'normal'. There are no associated recommendations, implied or otherwise, just information. How, or indeed if, you choose to use that information is up to you. Please feel free to ignore them if you don't find them useful.
Please read my heat map thread for a great deal of explanation of how the heat maps are formed and how I use them to guide me with my research, and for a full key to the contents.
I very much welcome feedback so if you do have any feedback, not already covered in the heat map thread, it would be very helpful if you could post your comment in the heat map thread rather than the SCVR thread. The more specific and constructive the feed back is, the more that likely it is that I will be able to act upon it. Thank you all for the feedback so far.
Small / Micro Caps reporting today:
Big movers today in the SCVR world (moving more than a 20d EMA of the ATR against either yesterdays close, or today's open):
Warm regards, stay safe, and best of luck!
greensiax
Northern Bear (LON:NTBR)
The company has surpassed themselves with the self congralutory twaddle this morning and ability to make us go away and do the maths rather than simply stating what they did.
Luckily for me i know the companies PR is on a par with a well known chubby football club owner just up the road from them so i don't really expect anything above a cryptic half year update written in reverse morse code , a crptic year end update and finallya fairly decent set of year end figures compared to the perennially low market cap - albeit we are back at the heady heights of £10.1 million market cap now according to stocky today as the shares are now trading 10-15% above the recent lows.
Can this company make £3 million profit whilst guiding that they expect growth the following year and command a pe of 10 - resulting in a trebling in share price ? - hell yes. will the company deliver £3 million profit while guiding they expect growth the following year and command a pe of 10 - probably not as they have presumably never listened to any D:ream songs.
Ok when they say the following what do they mean ?
we expect to report profitability from underlying trading in H2 FY21 to be in line with H2 FY20 for the Group as a whole.
Ok they did £2.0 mill operating profit less finance costs ye 31/3/2020 (i am happy with operating profit less finance costs as a reaonable metric for this company) - they did £1.27 mill operating profit less finance costs h1 - so they delivered £0.73 operating profit less finance costs H2 according to my made up calcs. I would have hoped for better as we are having a secret boom in construction work up here in the north east (you can't buy a house in my neck of the woods unles you pay 50k over the asking price at present as we are experiencing mass influx of inward migration from the south - with all these bods having huge wads of cash available to buy a house). To be fair to the company they do lots of stuff where covid has impcated their ability to be a "fighting fit lean mean profit machine".
Note they did 400k operating profit less finance costs H1 - so lets say £1.1 mill profit pre tax ye 31/3/2021. With the backdrop of covid this is a very good result in what must have been their toughest year since the bad old days of 2008.
Now they have guided us ref the future which is good
Assuming no further significant disruption or margin impact from COVID-19 or supply chain pressures, our current expectation is for a resumption of more 'normal' trading and profitability levels, closer to those seen in financial years prior to FY21.
Looking at stocky number we have probably average of £2.93 equivanlent pre tax 2018 and 2019 and £2.4 mill post tax 2018 and 2019. So hopefully they are now guding to net profit of something appoaching £2.4 mill going forward - if we use 60p shareprice thats £11.1 mill market cap and p/e of 4.6 thats cheaper than Norcross in its dark days !
A slight word of caution here the balance sheet of NTBR isnt the best - its adequate and presuming no acquisitions should really strengthen over the next 2 years if they can churn out £5.00 mill of profits.
The haters here will bang on about directors salaries being excessive - but the salaries are what they are and with the sub companies format as it is they need good leaders in each unit - so its not really a gripe of mine.
I continue to hold hoping out of the magical day when we are expecting £3 mill net with increasing profits and the shareprice is £1.61 and NTBR makes into my top ten list of holdings - hmmmm i am into my second half century now so perhaps time is not on my side in that regard.
Electra Private Equity (LON:ELTA) good NAV uplift but Fridays seems to be valued on just 4.5x ebitda (based on £32.7m expected ebitda if trading returns to 2019 levels). I think 8x ebitda is fairer, while would also expect earnings to surpass 2019 levels given that 21% of competition has gone (according to the report) and release of pent-up demand. With holidays off the agenda this year, this could also benefit restaurant spend. Hotter Shoes also looks a very decent little business, so overall very pleasing update and see further upside here.
Agree with comments re Electra Private Equity (LON:ELTA) but you do have to factor in the debt - so pro forma valuation based on 8x EBITDA is £261m less £62m debt is £199m. The mix of lease and owned real estate will effect the multiple ... 8 or 9 seems fair. £199m compares favourably with todays uplift to £146m. Im guessing that the pro-forma numbers gets a nice uplift prior to IPO ... lets say ( guess) £ 36m. So on your 8x .... you could be looking at £230m net equity for the IPO which is a huge uplift on todays £146m. All good so far.
One small issue to note however is whether Electra Private Equity (LON:ELTA) shareholders are really in TGI for the long term? The failure of the board to achieve a trade sale must be taken on board and no doubt some are disappointed to not be getting an exit. No doubt there will be more info and some volatility in the run up....
All is not lost re trade sale however, and in the first vehicle £SIGA ... F&C was the target company and although the initial sale process failed the company was bought out by the Chinese in the end. The IPO process could well flush out a buyer yet to be approached.
An article in the Evening Standard today is headlined TGI Fridays set for £275 million stock market listing. I guess that's an opening ask. They estimate Hotter at £45m.
Angle (LON:AGL) presented last night on the Proactive One2One Investor forum. Very interesting Q&A session which covered FDA additional questions, potential NASDAQ listing and probable reaction to any takeover bid.
https://www.youtube.com/watch?v=H51LE6jEJ5c
Presentation at 1:07:00 Q&A at 1:24:47
Wrong link. Is here at
;ab_channel=ProactiveProactiveEkf Diagnostics Holdings (LON:EKF) shareholders have an opportunity to subscribe for shares in the flotation of Trellus Health. The issue price was conformed as 40p yesterday after the market closed.
Has anyone here done (or seen) an analysis that would help me understand whether this is good value?
just fixing the ticker Ekf Diagnostics Holdings (LON:EKF) . I don't have any specific investing insights to offer unfortunately, but also hold some Trellus entitlements via the spin-out from Ekf Diagnostics Holdings (LON:EKF) . From what I understand, taking part in the offer is not entirely straight forward for private investors - it very much depends on which platform you hold these on. I think HL customers are currently losing out, whereas AJBell is making it possible for their customers.
ii are also making the Trellus offer available for their customers but the closing date is today.
I don't usually refer to the other place, as they say in Parliament, but the EKF Diagnostics Holdings (LON:EKF) thread at ADVFN has dozens of posts regarding attempts to get brokers to allow bids for Trellus IPO shares.
(For those not following EKF issued an in specie dividend of Trellus A shares in December and as part of the IPO there is a section of the placing restricted to the holders of those shares).
Results so far are ii coming out best for communication with holders, AJBell slated at first but eventually giving way and setting up a mechanism, Barclays saying no but then issuing confirmation of holding emails so that their clients could apply directly as if they held in own name, and Equinity and HL coming out worse for not having anything to do with it.
What a shambles - rights of nominee holders need strengthening.
Just a heads-up to any HL customers that were hoping to take part - I have just received a secure message from them that they now are in fact making the Trellus offering available. There is a very tight deadline: 7 AM Monday, 24 May 2021.
RE: Trellus
Has anyone here done (or seen) an analysis that would help me understand whether this is good value?
I haven't seen any. As I understand it Trellus are still building out their platform so this is a very early stage proposition, based on the underlying research from Mount Sinai.
I've elected to invest a small amount via ii on the basis of a) I like the proposition, b) the founders talk a good game and c) the pedigree is excellent.
There's a decent discussion here, if you can get past the interviewer's style:
https://www.voxmarkets.co.uk/a...
ii have been excellent in the process so far. They're also exploring an IPO, hopefully they'll preferentially prefer customers as Aj Bell (LON:AJB) did. If the float turns out half as well as that one did I'd be very happy.
timarr
I contacted HL by phone and had very helpful chat with the helpdesk.
I was told that Trellus shares could only be taken up by professional investors.
He did intimate that it seemed unusual that other brokers were allowing people to subscribe. I thanked him for his time and resigned my fate to non purchase of the shares.
5 minutes later an email from HL stating that the offer is NOW OPEN to all investors. Click on ‘Corporate Action’ button next to your Trellus application.
If you don’t ask you don’t get! Nice service from HL.
Stockopedia/piworld Virtual StockSlam, which was hosted live on Wednesday has now been published video & podcast. Slammed and Slammers listed here:
Softcat (LON:SCT) by Damian Cannon
Paypoint (LON:PAY) by Jamie Streeter
Cvs (LON:CVSG) by D’Arcy Andrews
Ergomed (LON:ERGO) by Lilian Nandi
Innovaderma (LON:IDP) by Francis Evans
Just (LON:JUST) by Dee O’Hare
Tremor International (LON:TRMR) by Ed Croft
Orchard Funding (LON:ORCH) by William Woodard
Celtic (LON:CCP) by David O’Hara
Surgutneftegaz Pao (LON:SGGD) by Rob Mahan
Fast, fun and informative. Next Slam is 25th June, get it touch if you'd like to Slam, we'd love to hear from you.
Hi Tamzin,
I was under the impression that the next StockSlam was on Wednesday 23rd June and not Friday 25th June.
£SHOE- As a relative newcomer would be grateful to know of likely implications of owners increasing their holdings from 50% to 54% yesterday please.
They'll find it easier to take Shoe Zone (LON:SHOE) private on the cheap. Only need another ~20% of shareholders to be on board. If they get Premier Asset Management on board, they hold 66%.
If the founders then raise their stakes to 30% each before announcing takeover, then with Premier they will have 71%, close to the 75% threshold.
Big director buys at Shoe Zone (LON:SHOE) today.
Now it makes sense why the interim results a few days ago had a lack of numbers to back up the woolly statements and was just generally frustrating to work out forward prospects...
Thank you Paul for the extensive work on N Brown (LON:BWNG) yesterday. I hold. I read the results, read your work and then read the results again and finally it all began to make better sense. It really does look like the ultimate old world lumbering beast that by chance finds itself relatively well positioned in the new world. (Which was broadly why I bought it). But its product presentation was poor, its IT systems inadequate, its marketing involved throwing wads of money at the problem, to sell to customers who then don't pay....(It seems they have only just discovered the power of social media and proper credit scoring.) And yet despite all that they somehow manage to turn a small profit.
It does appear that they have identified the key issues, and the noises that they make suggest intention at least to try to address them. Execution will be the key to unlocking value. As Paul points out, given the success of others in the space, if they managed to fix most of these problems, them there is a real opportunity. So I will be in there for a while to see what happens. But I do wonder whether it will remain a public company, given that so many of the shares are owned by members of the Alliance family.
Hi JAmes,
That's a nice summary of N Brown (LON:BWNG) I agree with your thoughts.
Chance of a bid from the Alliance family. Meanwhile the current market cap is underpinned by NTAV, so it's pretty copper-bottomed. Hence limited downside risk in my view. Speculative upside potential if they fix all the problems as you say. If they manage to crack digital marketing, and get their IT spend down to a sensible level (migrating to cloud software maybe?), improve product & margins, and lower the customer default level, then this could become a decent company. Quite a long list of fundamental things need fixing though, but as you say, management do seem to have at least identified what they need to do.
Overall then, risk:reward seems quite good to me, but I'm taking a 2+ year view.
Regards, Paul.
Retail sales soar in April
Interesting announcement from Electra Private Equity (LON:ELTA) - two remaining portfolio companies floating on FTSE and AIM in Q3/Q4.
I'm writing up a section on Electra Private Equity (LON:ELTA) (I hold) as we speak Should be up before 10am.
Many thanks indeed, Paul. Will be interesting to see the level of institutional demand.
As you highlight, the net debt numbers seem to have crept up. (Perhaps understandable given the circumstances).
Electra Private Equity (LON:ELTA) are retaining Hotter Shoes under their listing and renaming themselves. I'm not sure that will realise much of a premium in the way a sale might. I think the focus is on the much higher value of TGI's.
I would anticipate shareholders selling out once they get the TGI proceeds rather than wanting to hold a small footwear company.
Staffline (LON:STAF) please
Morning all,
Encouraging update from £GATT this morning...
Will you cover Paul/Roland?
Regards
Morning John,
I think you mean Gattaca (LON:GATC)
Yes, I'm hoping to cover that one later.
Regards, Paul.
Many many thanks Paul, and to your friend, for the heads up on ELTA a few weeks ago. I’m a big fan of Investment Trusts and had regretted not buying ELTA earlier as they have been winding down for a while and have sold businesses and returned the proceeds to shareholders at very good prices, So as soon as seeing your update I did what I very rarely do and bought blind as the case for buying ELTA looked SO convincing.
As soon as I bought I was shocked to find that ELTA seemed to be trading at a 20% premium to NAV. I very rarely buy a Trust at a premium since one of THE biggest plus points for an Investment Trust is that some very successful Trusts (e.g like Canadian General and North Atlantic Smaller Companies currently around 30% discounts to NAV) can be bought at big discounts. Such Trusts are bargains whereas paying more than a Trust is worth isn’t!
But as soon as I checked ELTA’s NAV figure of just 350p against that then £4 share price I saw that the 350p figure was from the previous September, and breathed a sigh of relief! ENET better when I then checked the share price again it had risen significantly! That’s the power behind such a quality and well argued Paul Scott update! And your update Paul had made it so clear that that figure was way probably far too low and now way out of date. ELTA was indeed a bargain. Sure enough today they have upped that NAV figure to over £5. That looks too modest. But at least the 40% premium the share was trading at yesterday is now around par instead.
Key thing now is to get Hotter Shoes on AIM and TGI on main market asap and while Markets and trading are buoyant. ELTA was a fantastic buy when Paul updated and imo too it’s nowhere near too late to buy. The reasoning for that opinion along with potential further big share price upside is in Paul’s update today.
Hi Paul,
Yes, that one!!
Don't forget there's a Department of Justice investigation to Gattaca (LON:GATC) in their role of circumventing Iran sanctions and supplying telco contractors.
Gattaca to spend £3m+ in 2019 on legal fees and £1m+ in 2020 (from my foggy memory). I remember being struck by the amounts, for a £40m market cap company. If one is willing to "fight" by spending such huge sums on lawyers, that means that the fine or current settlement offer demanded from the DoJ must be much higher amounts... thinking maybe 8 figures?
Hence why Gattaca (LON:GATC) is on my bargepole list pending the outcome of the DoJ investigation.
I also note that no directors have bought in 2019, 2020, 2021 after the DoJ investigation has been announced. Not much insider confidence on their shares being worth something in the worst case scenario...?
Rec Card Factory (LON:CARD) - Trading & Financing Update today that brings some clarity to its position and is interesting. Last 5 weeks trading (ie since re-opening) has "exceeded expectations and is marginally down vs 2019 (so lets say -5%, wish they would!). Within that volume down and value per transaction up - so some stay away but those who come out feel flush?
On financing we at last have some clarity. New £225Mn deal secured but with several strings. Firstly, its 3 parts: £100Mn revolving, £75Mn term loan and £50MN CIBILS from the govt. Secondly, lenders remain skittish - there could be a £5Mn penalty if debt reduction (leverage?) not reduced and the interest rate was not disclosed so I guess it was high. Finally, as expected an equity raise is required (they say "best efforts to raise" but you can see the outline of the gun). Target is £70mn fresh equity. Price/timing not disclosed. Net debt May '21 is +/- £150Mn vs £133Mn 12 month previous - so you could say that's a £20Mn hit from COVID.
The extra equity will also be used in "enhancing our card-led proposition through all sales channels and accelerating the increase in our capability and capacity to fulfil sales demand via our online channel, and so capitalise upon the move to online adopted by more customers over the last year." Interesting that they see at least some of the move online as permanent. The scale of this move will determine if COVID has been been good or bad for them long term. Personally, I think they have a big omni-channel opportunity if they advertise the online service (since this will also drive customers to their branded stores whilst a lot of competitors have had to close). Medium term rent reductions and a less good jobs market will offset any re-emergence of small, even temporary competitors in empty shop for whom high margin, low CAPEX cards must seem a good use.)
Before COVID, the market value of physical cards was reported to be 87% of the total, with CARD the dominating market leader. Even if a few % move online, I see the market mostly going back to where it was before ie mostly bought just before an event or on impulse. So I think CARD will do very well again - a 60% share of the overall card market in a smaller, better stores portfolio would still be hugely profitable I think.
Personally, as a shareholder, I thought the market had got it about right on pricing at current levels and I think with a clear equity target now, they will raise the money without much discount and then recover. So I hold and will participate in any equity raise if offered.
I think the risk with Card Factory (LON:CARD) is that a placing is done at a discount, shafting private investors. Also, when you tot up all that debt, and a inexplicably high market cap, the enterprise value seems way too high, given that they've missed the boat on internet, with Moonpig (LON:MOON) and others having eaten their lunch.
Another problem is that I simply don't see High Street footfall returning to pre-pandemic levels. People have learned they can buy everything they need online, which is so much easier.
CARD is still a good business, and I'm sure will be profitable & cash generative in future. However, there's dilution coming from a raise, and maybe another one some time later. Cashflows will be needed to pay down debt that was already too high pre-pandemic.
Put it all together, and the price at the moment looks ridiculous - far too high.
I think this is a general problem - there are too many retailers that were struggling pre-pandemic, which have soared in price recently, on the assumption that all their problems have somehow disappeared with re-opening. I'm thinking;
Card Factory (LON:CARD)
Works Co Uk (LON:WRKS)
Shoe Zone (LON:SHOE)
Superdry (LON:SDRY)
Ted Baker (LON:TED)
All of these companies still have big problems that need to be resolved somehow, and could take a long time, if they can turn themselves around at all.
Mind you, the announcement today of big Director buys at SHOE does indicate that one might be worth a closer look. I was neutral on it when reviewing recent results.
Regards, Paul.
Hi Paul.
I agree with your comments about the likelihood of several U.K. retailers being overbought in the recent vaccine euphoria when many still have significant underlying problems. At risk of being guilty of “anchoring”, I think Shoe Zone (LON:SHOE) might not be quite such a basket case. Pre Covid, the shares were trading above 200p each (vis c. 80p now) and paying dividends in excess of 10p a share that were more than 1.5x covered by earnings. Post Covid, which certainly whacked their high street trading performance badly, they seem to have sorted out much of their leasehold estate to more manageable rentals and have built quite a healthy online business without cannibalising margins or bleeding through high return rates. Agreed this has been done with a significant increase in the debt figure but equally the share count has been static so no dilution.
Arguably it’s a better placed business now than it was in 2019 on a significantly depleted high street with a target customer demographic (“value” customers looking for low cost footwear) that has probably grown as a result of Covid’s impact on “casual” gig employment. The presence of significant management skin in the game (increased yesterday by 4% of the company shares yesterday to over 50%) suggests both confidence in the turnaround and a feeling by “those in the know” that the shares are still undervalued. With the added debt on the balance sheet, I don’t think we’ll see 200p a share anytime soon, but if previous earnings can be restored and debt reduced from the proceeds there’s good potential for a nicely geared uplift from current levels (unless we get MBO’d first). I hold.
Gus.
Thx (to all) for feedback. If £CARD placing is at a discount, I will participate - so my key risk (as I see it ie I have already in principle accepted the balance of commercial risks) is that as a small existing shareholder I get excluded from the raise - which since they have as long as they to do it and a lot of private investors, should not occur. I will be writing to their investor relations on this point! I am also nervous about the “other subordinated sources” of lending they will consider - I think they would easily get this but at a higher cost than normal lending or with conversion to equity options I dont want to give.
I think physical retail is going evolve very fast in next 2-3 years and consolidate on a mix of fewer core commercial centres (key High St + retail parks) plus a lot fewer more convenience stores. Given the short lease lengths on most Card Factory properties if they are nimble they can get to better locations on v good terms fast , drop a few poor sites and so have cost optimised store footprint with fewer competitors.
Online, they are a poor 3rd at the moment and there is an online advantage to being the market leader but unlike the other retail chains cited, Card Factory (LON:CARD) have a hugely dominated market share position in the main market (which is phsyical cards still), a cost advantaged supply chain in terms of production and likely lower cost pressures on the 2 most important parts of the physical model rent and labour costs for the next few years
They need to be both aggressive and patient and spend more of this (my assumption) cashflow than before on buying advertising space online, driving trial and offering deals that MoonPig as an online only operator cant - buy your card online and pick up an inflated balloon instore for example. This will build them online AND in physical stores.
If they do things right, on my assumptions, I can see the price doubling over 3 years even allowing for a 3:1 or 4:1 dilution to raise the £70Mn the lenders require.
Anyway, different views is what makes a market - interesting today to read the various top 10/Top 3 shares held and to to see both commonalities and differences vs my own. I look forward to annual report for Card Factory (LON:CARD) ............in 2024.
Hi Paul,
I'm in the industry and know quite a few independent card retailers. Trade since re opening was very good in the first week but has rapidly tailed off. Lfl sales with 2019 for the last two weeks are on average 30-40% down. I can't see it being much different at CARD? The reason they're only "marginally" down is because they had such a strong opening week. Clearly this is untenable for retailers and landlords if it continues.
Obviously this is anecdotal and punters may return in time but I can't help but think a lot of footfall has been permanently lost from the high street. I wouldn't touch any retailer without a significant online offering.
Hi Zipmanpeter,
Total agree with you. As Buffett would say 'be greedy when the herd is fearful.'
Good luck with your investment.
BSV
Intercede: LON:IGP
Biden executive Order of 12th May contains:
"the requirement that within 180 days of the date of the order, agencies shall adopt multi-factor authentication and encryption of data at rest and in transit, to the maximum extent consistent with Federal laws."
Biden Administration Executive Order on Cybersecurity - Making it Real - Intercede
Multi-factor authentication is Intercede's business and most of their clients are in the USA.
I hold
A nice TU from Headlam (LON:HEAD) in advance of its AGM. Recovering nicely after lockdown and its SP shows a continued steady climb - no great peaks & troughs. I hold and will continue to do so as it continues to grow and keeps bringing in the revenues and paying the nice Dividends. Hopefully a catch-up in lost commercial sales (as businesses recover and get back on track) will help support the ongoing growth.
Thought I would put a marker down for the Tracsis (LON:TRCS) comment this morning in response to the government’s Plan for Rail report released yesterday.
https://www.investegate.co.uk/....
The company itself seems quite happy with the potential opportunities coming out of any reorganisation and the share price ticked up yesterday suggesting the wider market is too after some recent softness, possibly in anticipation of a more onerous outcome. Don’t hold - was waiting/hoping for a chance to buy in at a lower level (that may not now come along).
Gus.
p.s. “Austin Powers: International Man of Mystery” in response to Mr Contrarian Northern Bear (LON:NTBR) comment.
Hi gus 1065
RE: Tracsis (LON:TRCS)
The recent softness looks like it was normal market jitter on noise, rather than anything predictive (as is the case nine times out of ten). The proposed changes will almost certainly lead to reductions in procurement spending in the longer term but a large part of what Tracsis offer is efficiency savings, so that plays into their strengths.
It's also worth noting that a significant part of their business pre-CV-19 was around event management - managing traffic flow around festivals, for instance. As and when events restart, hopefully later in the summer, those revenues should recover quite sharply too.
timarr
My morning smallcap tweet:
Staffline (LON:STAF) Sensyne Health (LON:SENS) Novacyt SA (LON:NCYT) £OCTP Tracsis (LON:TRCS) Gattaca (LON:GATC) Electra Private Equity (LON:ELTA) Shield Therapeutics (LON:STX) Northern Bear (LON:NTBR) Card Factory (LON:CARD) Urban Exposure (LON:UEX), Quartix Holdings (LON:QTX), Circassia (LON:CIR), Headlam (LON:HEAD)
Staffline (STAF) a no-surprise £44m placing and £4.4m OO at 50p, a 30% discount, to cut debt. Also negotiating contracts with prime Restart suppliers in relation to Gov't Restart programme. [SP=70.2 Cap=48m]
Sensyne Health (SENS) agreement covering 2.5m patients in US brings combined total of anonymised and de-identified patient data for medical research to 10.9m. [SP=153.5 Cap=253m]
Novacyt (NCYT) re dispute with Gov't concerning second covid test supply contract - dispute may now have a material impact on these revenues in Q1. "The Company has taken legal advice in relation to the dispute and believes it has strong grounds to assert its contractual rights." [SP=419.6 Cap=319m]
Oxford Cannabinoid Technologies (OCTP) YACL - Yet Another Cannabinoid Listing. [SP=NA Cap=NA]
Tracsis (TRCS) welcmomes yesterdays' Williams-Shapps Plan for Rail in the UK. "Tracsis is well positioned to benefit from the commitment to greater innovation and investment in a digital railway. This is currently reflected in our pipeline of new opportunities." [SP=819 Cap=240m]
Gattaca (GATC) guides FY(July) pretax ignificantly ahead of market expectations. Cites faster rate of recovery in NFI (huh?) than originally expected with Q3 up 13%. Also application of IR35 (self-employed) tax tightening had less impact than expected. Guides H2 NFI up 10% on H1. [SP=150.2 Cap=48m]
Electra Private Equity (ELTA) the fund in wind-diwn will list its main assets. TGI Fridays will list on LSE in Q3 then reclassification of Electra entity as Hotter Shoes. Will probably realise more. than PE sales. NAV at end March 514.3p/sh. [SP=518.65 Cap=199m]. I hold.
Shield Therapeutics (STX) on track for the US launch of its lead product Feraccru/Accrufer by the end of June after progress accelerates with placing funds. [SP=57 Cap=123m]
Northern Bear (NTBR) the perenially cheap building services. co guides profitability from underlying trading in H2 flat. In line? Throw me a frickin' bone here*. Order book remains strong. [SP=55.05 Cap=10m]. I hold.
Card Factory (CARD) reopened store sales "exceeded both our expectations and the sales performance realised after reopening following the first and second lockdowns". LFL marginally down cf 2019. Completes debt refinancing. [SP=86 Cap=294m]
Urban Exposure (UEX) as mooted, GM to vote on delisting and proposed liquidation. [SP=66.08 Cap=48m]
In line: Quartix Holdings (LON:QTX) Circassia (LON:CIR) Headlam (LON:HEAD)
* name that film
Film:Austin Powers! What’s the prize? 10000 Pcf (LON:PCF) shares?
Mr C
Gattaca - NFI: Net Fee Income?
Recruitment sector bubbling nicely? If it can stay solvent - Staffline fundraise for example
On Northern Bear (LON:NTBR) - looks like they've created themselves a bit of wiggle room for disappointing margins (and potentially delays to top line revenues too) this year:
"Assuming no further significant disruption or margin impact from COVID-19 or supply chain pressures, our current expectation is for a resumption of more 'normal' trading and profitability levels, closer to those seen in financial years prior to FY21."
It has been well reported that there are big supply issues at the moment with building supplies in general, and roofing supplies in particular, along with price increases. As a small customer, Northern Bear is not going to have it easy vs the big construction companies...
Hi Paul, regarding Sanderson Design (LON:SDG) did they comment on the Government’s furlong loan of net £2.7m which seemed to contribute a good part of the positive results. I admit I top sliced some of my position as a result. Having said that I was impressed with the operating margin and the progress they had made on the transformation. Perhaps that will be irrelevant as we get back to the new normal. I still hold.
Hi Andy,
Sanderson Design (LON:SDG) - Yes that's right the £2.7m furlough grant (not a loan!) basically offset some of the H1 losses from reduced demand. With demand now normalised, and 60% gross margins, and reduced overheads, then I think the H2 rate of profitability implies something like maybe £12-14m annualised run rate of profits without any assistance from taxpayer support? My estimate. In which case the stock still looks good value, despite having 4-bagged in the last year.
Factories are currently running at full capacity. CEO gave more colour on this, saying it's based on working a single 10 (or 8?) hour shift each day. Therefore the next step is to introduce a night shift, hence she's got capacity to double production.
Interesting comments on how SDG has benefited from having UK production, whereas competitors import, and then re-export and are having all sorts of logistics problems.
I think Brexit might lead to a lot more on-shoring of production into the UK, and for subsequent export to RoW, rather than relying on European supply chains which can now be problematic.
Regards, Paul.
Sanderson Design (LON:SDG) £15m cash on the BS, and a SP going through the roof as the business thrives, makes keeping the furlough cash not a great PR look, although obviously fully justified when they took it. Most companies have worked this out by now. A bit surprised that Sanderson Design (LON:SDG) have decide the reputational hit is worth £2.7m
Yes I appreciate this is virtue signalling but thriving companies that had every right to furlough money, such as Games Workshop (LON:GAW) , returned it many many months ago.
"Sanderson Design (LON:SDG) £15m cash on the BS, and a SP going through the roof as the business thrives, makes keeping the furlough cash not a great PR look, although obviously fully justified when they took it. Most companies have worked this out by now. A bit surprised that Sanderson Design (LON:SDG) have decide the reputational hit is worth £2.7m
I guess its each to their own , if we look back at furlough it was originally designed to stop staff ending up on the dole queue. If sanderson take the viewpoint these staff would have been laid off had the furlough not existed then all furlough has done really is kept them in the same position as they would have been had staff been laid off. If they repay teh £2.7 mill then they are out of pocket to the tune of £2.8 mill after doing the government a favour. So whilst i like it when companies are paying back these funds i don't judge harshly those that have kept funds and not really profited on the deal as the income has a matching labour cost that wouldnt have been there otherwise.
Obviosly furlough has now morphen into something comepletely different where waht may have been idle time or non efficient time can potentially simply be put down as furlough therefore directly increasing profits - how many comapnies pimp this up too much i know not
Thanks for taking the time to reply Paul.
Hi Paul, I guess you’re going to give some insight into your thoughts on Electra, looks like they had the same idea as you an intend on listing on the markets (I hold)
Update from Electra Private Equity (LON:ELTA) , a situation Paul referred to in a separate post a few weeks back.
https://www.investegate.co.uk/...
Looks like they intend to IPO TGI Friday’s in Q3 and then list the final holding in Hotter using the existing Electra vehicle in Q4. Looks a good way to maximise sale value if markets are still benign and possibly give holders a chance to continue the ride in these two entities. NAV per share updated to March 31st of 514p (shares closed yesterday at 510p). I’ll copy this link onto the original Electra Private Equity (LON:ELTA) thread.
Gus.