Small Cap Value Report (Fri 22 April 2022) - ESYS, REC, IBST, BRCK, SOLI, PROC

Good morning from Paul & Roland.
Agenda -
Paul's Section:
Essensys (LON:ESYS) - interim results yesterday triggered a 36% rise in share price. Interim figures look poor to me, with revenue growth almost stalled. However, the balance sheet is strong (for now anyway, it intends burning through the whole cash pile in the next 2 years). Outlook comments indicate growth is accelerating now people are returning to offices. However, forecasts show it needs to more than double revenues, and still won't reach breakeven. Hence this looks a high risk business model, and shares are just a punt at this stage.
Solid State (LON:SOLI) - an impressive year end update, with the latest in a series of profit upgrades. Record order book gives comfort for the new year just started. Cost headwinds seem to be absorbed within increased revenues. 2 acquisitions have performed well. Valuation looks about right to me.
Procook (LON:PROC) - my first look at this recent IPO, which retails kitchenware online and in c.50 UK stores. I like what I see! Valuation probably still too high though.
Roland's Section:
Record (LON:REC) - this specialist currency management business saw a slowdown in AUME growth last year, but appears to be benefiting from rising interest rates. I can see some attractions, but I wonder if the business model may face tougher competition than in the past.
Ibstock (LON:IBST) - this FTSE 250 brickmaker upgraded its 2022 guidance yesterday following a strong Q1. The company seems to be on a sound footing and the stock looks reasonably valued, but I’m wary about cyclical risks and might prefer to focus on the top performers in this sector.
Brickability (LON:BRCK) - This fast-growing building materials group now expects to report FY22 EBITDA 19% ahead of previous guidance. I’m encouraged by the presence of owner management and this group’s strong progress since its 2019 IPO. Although I can see some cyclical risks, I have a favourable impression of the business.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul’s Section:
Essensys (LON:ESYS)
Shares up 36% yesterday to 115p
Market cap £74m
For the 6 months ended 31 Jan 2022.
We had a deluge of company news yesterday, and this one slipped through the net. We try to report on big movers, so as there’s nothing of interest today, I’ll look back at a few big movers we missed yesterday, starting with this SaaS company focused on “delivering digitally enabled buildings and spaces”. It’s not at all clear to me from Essensys website what the company does, and how it’s better than other IT services.
Essensys floated on AIM in May 2019. I don’t seem to have looked at it before (although it looks vaguely familiar to me as a jam tomorrow, heavily loss-making company that is one of the worst places to invest at the moment, as these things have heavily de-rated), but Jack reviewed its FY 7/2021 trading update here in Aug 2021, and concluded the valuation “seems steep” at 315p. Good work Jack, as the share price has since collapsed, bottoming out recently at c.75p.
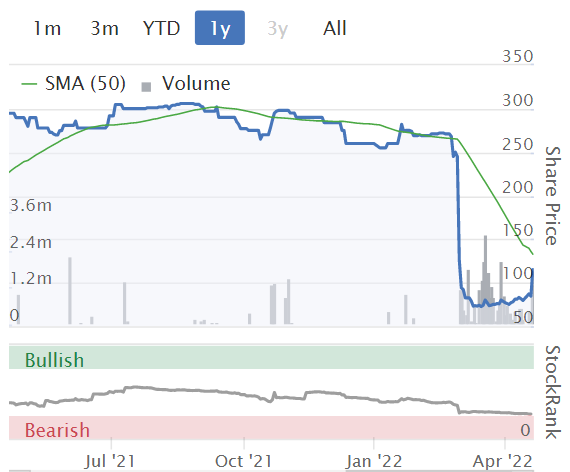
As you can see from the chart below, something awful happened on 1 March 2022 - a profit warning, saying that growth had slowed, a client was lost unexpectedly, and providing lowered FY 7/2022 guidance of £23.5m revenues, and a £(7)m EBITDA loss. No wonder the share price tanked! Although it also talked of a strong pipeline.
.
.
Interim Results
Published yesterday.
Revenue growth has stalled to low single digits, at only £10.9m for H1. It’s nearly all recurring revenue though.
H1 loss before tax of £(4.7)m - pretty awful.
By my calculations, revenues would need to rise by c.70%, just to reach breakeven! Broker research shows it's worse than that - even a doubling of current revenues to £42.3m in FY 7/2024 would still result in adj PBT of a £(6.1)m loss, and all the cash pile having been burned up.
Capitalised R&D of £1.5m in H1, so remember to deduct this cost from adj EBITDA of £(2.9)m, which ignores it.
It’s pleasing to see the software development moving to the UK -
As previously reported, the Group continues to invest heavily in product development. Increasingly these costs are borne in the UK following a decision to increase the UK based development team and reduce the size of the Group's outsourced offshore development centre.
Balance sheet - is strong (for now), as the company did a big £33m equity fundraise in July 2021, and is sitting on a £30.5m cash pile - although it’s burning through that cash due to ongoing losses, and increased overheads. So it's only expected to last for 2 years - a scary rate of cash burn that looks reckless to me.
Receivables look high, at £6.1m, compared with £10.9m revenues in H1, suggesting the customers are not in a rush to pay - which might indicate maybe some disputed invoices? It’s a question to ask management, if any readers speak to them.
So far, so bad. These H1 numbers definitely don’t justify any increase in share price, so it must be the outlook comments that excited people yesterday, to chase up the share price by 36%. Or just day traders playing around, which we're seeing a lot of at the moment - spikes up in price that often don't stick.
Outlook - says that growth is accelerating again.
Pipeline up 23% since Jan 2022.
Caution expressed over inflationary cost pressures.
Structural growth drivers returning, as workers come back into offices after covid.
Concluding -
The Group continues to expect to meet FY22 consensus market expectations and remains confident in the longer-term structural growth opportunity
Webinar today - There’s a webinar today at 11am on InvestorMeetCompany. I tend to watch the recordings over the weekend.
My opinion - the current £74m market cap seems a lot more realistic than when we last looked, at around £200m. Particularly as the company has 41% of its market cap sitting on the balance sheet in cash - hence fully funded to expand, although depleting its cash rapidly along the way, with continued heavy losses expected as overheads are cranked up (expanded sales teams, etc).
If you’re tempted to buy this share, do first have a look at Singers research notes, available on Research Tree. This shows continuing heavy losses, despite forecast revenues almost doubling by FY 7/2024, and the cash pile completely gone by the end of that year.
That looks a scary investment proposition to me! It looks as if Essensys has much too heavy overheads, which swallow up the strong revenue growth anticipated. It doesn’t even reach profitability with revenues almost doubling to £42.3m in FY 7/2024 - which requires a faster growth rate than has been achieved before.
Too risky for me. I think readers would need to properly research the software, compare it to the competition, talk to users of the software, etc, to be sure that the upside is strong enough to justify paying £74m for a heavily loss-making company, which intends burning through its cash pile over the next 2 years in an attempt to more than double in size, and still be loss-making at the end of it! That doesn’t strike me as a very good business model.
.
Solid State (LON:SOLI)
1110p (down c.3% at 09:43 today), up 13% yesterday
Market cap £84m
Solid State plc (AIM: SOLI), the specialist value added component supplier and design-in manufacturer of computing, power, and communications products, announces a trading update for the 12 months ended 31 March 2022 (the "Period" or "FY22").
This share caught my eye yesterday, with a decent move up +13% on a positive trading update. It’s slipping back a bit today, but on negligible volume reported so far (remember bigger trades are allowed delayed reporting, which is why prices often move in a way which seems strange to people following the reported trades - you’re only seeing a partial picture of small retail trades in real time. The bigger trades might be being worked in the background).
SOLI shares have held up very well in the last 6 months, a period when many small caps have relentlessly dropped due to macro concerns. Is SOLI a shining star, or an accident waiting to happen?

.
Trading update - this looks excellent! -
Following an exceptionally strong finish to the Period, the Company expects to announce record results with revenues for FY22 of approximately £85m (2021: £66.3m) up 28% over the prior year, and adjusted profit before tax for the Period of approximately £7.2m (2021: £5.4m) up 33%; both ahead of recently upgraded consensus expectations1.
The like for like open orderbook at 31 March 2022 is up 106% over the prior year at a record £85.5m (31 March 2021: £41.5m).
Here’s the very clear footnote below - why can’t all companies provide these, it makes life so much easier for investors, and the clarity makes us more likely to want to buy the shares.
1 Analysts from brokers WH Ireland Limited, finnCap Limited, and Edison Investment Research Limited, provide equity research on Solid State, and the Company considers the average of their research forecasts to represent market expectations, being, for Solid State's 2021/22 financial year, revenue of £80m, and adjusted profit before tax* of £6.5m.
Note that 28%revenue growth is 8% organic, the rest from acquisitions.
That’s a 6.3% beat vs expectations on revenues, and a 10.8% beat on adj PBT. Hence yesterday’s +13% share price rise looks logical.
To beat estimates at the end of the financial year is impressive indeed, especially when the context is a series of upgrades to estimates earlier in the year -

.
Broker updates - Edison (which is effectively from SOLI, as it’s commissioned research) estimates EPS of 71.2p for FY 3/2022, and similar for next year - which assumes that £5.0m higher revenues are mainly absorbed by cost increases.
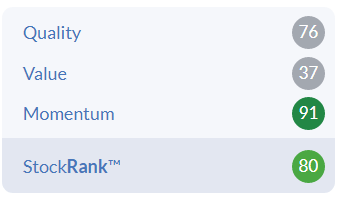
That gives a current PER of 15.6 - which doesn’t strike me as cheap in a very cautious small caps market. Priced about right, perhaps? (assuming that performance can be maintained).
Cyanconnode Holdings (LON:CYAN) is mentioned as a major customer, which makes me nervous because it has a history of being loss-making, and repeatedly raising cash. Checking its last accounts, CYAN is small, still loss-making, with a weak balance sheet (unusually high debtors looks a problem), and recently did a £2m placing. So a blue chip customer, it is definitely not! Hence I hope SOLI’s CFO is insisting on pro forma invoicing only (i.e. payment up-front), or trade credit insurance, as that could be a higher risk receivable otherwise.
All sales are a gift, until they’re paid for, remember!
Acquisitions - SOLI seems to be good at making acquisitions, with “notable contributions” from Willow Technologies and Active Silicon, and both “performed ahead of management’s expectations since their acquisition in March 2021”.
Supply chain & inflation - this partially reassures, but I’ve heard from IT companies that lead times on electronic components are currently getting worse, so problems in supply chains is still a considerable risk I’d say -
As previously reported, Solid State has navigated the long-term supply chain challenges associated with semiconductor shortages through careful inventory management and pro-active engagement with customers to manage order scheduling.
Given the success of this experience, the Group is taking a similar approach to the management of input cost pressures and inflationary effects of recent global events, continuing to manage the ongoing supply challenges and help mitigate potential margin erosion risks. This is enabling the Group to share the risk with its customers and pass on some of the cost increases.
Only some, not all of the cost increases passed on.
Inventories have been increased, which is a sensible approach.
Outlook - there are various comments scattered through the commentary, but this is the concluding paragraph -
Solid State continues to deliver on its organic growth strategy through the targeting of structural growth markets and remains focused on complementary acquisition opportunities. The record open order book and trading momentum underpin the near-term prospects and give the Directors optimism for the future.
My opinion - this is an impressive update. The share price looks about right to me. A PER of 15.6 would have seemed cheap a year ago, but with all the current macro worries, it’s difficult to justify why I would want to pay any more than that right now.
A strong order book, good acquisitions, and seemingly having the supply chain under control, would probably give me enough confidence to continue holding, if I were an existing shareholder.
.
Procook (LON:PROC)
121p
Market cap £132m
This company floated on the UK main market in Nov 2021, at 145p, for a £158m market cap.
It’s only down 17% since then, quite good for a recent IPO!
Existing family shareholders cashed out £39.7m at the IPO.
Here is the Prospectus, which I’m having a quick initial look through now (it only takes a few minutes so skim read the key sections, and ignore everything else at first)
Here’s a 5 minute video introduction from ProCook, which sells kitchen products, pots & pans, knives, and other kitchen products, online and from about 50 UK stores.
Shareholder structure is striking - it’s controlled by the O’Neill family, with a tiny free float. They owned 100% pre-IPO.

Pre-pandemic, it was growing fast, but only operating just above breakeven.
Profit before tax ballooned to £8.4m in FY 3/2021, clearly a major beneficiary from the pandemic, which immediately raises the big question whether this was an opportunistic float based on unsustainably high profits from the pandemic?
Net assets look modest.
Interim results for H1 of FY 3/2022 showed a decent rise in revenues to £32.1m (up 34%), but a drop in profits - underlying PBT of £3.6m (down 11% from previous year).
There’s also a striking drop in u/l operating profit margin from 19.0% to 10.4%.
That sets the scene, on to the most recent news, yesterday -
FY 3/2022 revenues of £69.2m, up 30% on LY, and up 78% on 2 years ago
Strikingly high gross margin, of 67.2% (down from 68.6% LY, due to higher marine freight costs)
Profit guidance -
We anticipate full year adjusted PBT will be broadly in line with market expectations5.
5 Latest analyst expectations reflect adjusted PBT of £10.0m for FY22
Outlook -
Trading conditions have become more challenging over the last quarter with a number of well-documented pressures impacting consumer shopping habits and operational costs. Despite a tougher consumer and macro environment, we continue to attract new customers to the brand, are outperforming the market, and remain confident in our value-for-money, specialist offer.
Returns rate? Not provided in the update, but would be interesting to find out the online customers returns - likely to be low, I would imagine.
My opinion - this is only my first look at ProCook, but have to say, I like what I see. This looks a decent business.
Bull points -
- Specialist niche, with very high gross margins
- Huge skin in the game, from founding family, which still owns most of the business
- Reasonably good Q3 & Q4 trading updates, showing that bumper pandemic profits were not a flash in the pan [!!], and are being maintained
Bear points -
- Main one is valuation. The whole sector has been smashed to pieces in the last 6 months, so PROC is now looking too expensive.
- Balance sheet is adequate, but not strong, with £10.7m NAV
Roland's Section:
Record (LON:REC)
Share price: 66p (pre-open)
Shares in issue: 199m
Market cap: £133m
“Net inflows of $2.4 billion during the financial year”
Specialist currency and derivatives management firm Record (LON:REC) has released a fourth-quarter update today. Record’s core products are dynamic and passive hedging strategies used by institutional clients to manage their currency exposure. The company is also diversifying into asset management with a number of debt and FX strategies.
Record put on a growth spurt after CEO Leslie Hill took charge in February 2020 and reported net inflows of $9.7bn for the year ending 31 March 2021. But today’s update suggests to me that this early momentum may be slowing.
Despite this, Record scores highly for quality and offers a tempting 6%+ dividend yield. I think it’s worth a closer look.

Financial highlights: Record reports its activities in fund manager language, disclosing net inflows, assets under management equivalent (AUME) and performance fees. This emphasises the ongoing nature of the company’s services, as opposed to the transaction-based services provided by some rivals.
For example, an institutional client might sign up to maintain a specified level of hedging to protect its overseas assets from currency volatility.
Today’s update covers the fourth quarter and full year ending 31 March 2022. Record appears to have achieved modest growth in FY22, despite a poor fourth quarter:
- AUME +3.7% to $83.1bn in FY22
- Net inflows of $2.4bn in FY22
- Q4 AUME -2.7% (-$2.3bn) due to market disruption caused by the war in Ukraine.
- Performance fees of £0.5m earned in Q4 and FY22
- Further $1bn inflow into dynamic hedging after the period end. A further $1bn is expected during H1, as a major client expands its mandate
Profitability: Record has always been highly profitable. But like many asset managers, it has suffered from pressure on fee margins in recent years. In today’s update, the company says that fee rates were “broadly unchanged” during the fourth quarter. Similar wording was used in the Q3 and H1 reports.
I’d guess this means that there’s been some slight pressure on fee rates, due to the use of the word “broadly”.
Management warns that the ongoing fee rate for Dynamic Hedging is now expected to fall, due to the recent increase in mandate size from an existing client.
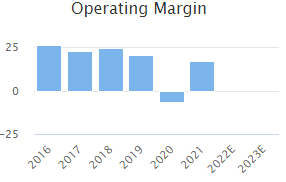
It’s not easy to be sure of the exact fee rates charged by Record. This information isn’t disclosed. But I think the operating margin trend gives us an idea of the underlying fee margin trend:

Performance fees: These charts from the FY21 results presentation show that management fees have increased relative to revenue since 2019. This seems to imply that Record may not be generating as much income from performance fees as in the past.
However, CEO Ms Hill said today that the £0.5m performance fee earned during Q4 (when AUME fell!) was linked to opportunities arising from recent interest rate rises. If rates continue to rise, I wonder whether we might see further performance fees in 2022. That could have a significant impact on profits.

Source: Record FY21 presentation
Outlook: No new guidance was issued today. The company will announce its full-year results for the year ending 31 March on 21 June.
My view: Record was founded by Neil Record in 1983 and claims to have offered the world’s “first standalone currency hedge in 1985”. It’s always appeared to me to be a clever if slightly niche business. But Record has struggled to deliver consistent growth in recent years and I’m starting to wonder if the market environment has changed.
A number of outsourced currency management businesses have been launched in London and elsewhere over the last 15 years. Alpha Fx (LON:AFX) and Argentex (LON:AGFX) come to mind, but there are others. I wonder if the technology and data that are widely available today (but weren’t in the 80s/90s) may mean that Record’s hedging strategies no longer have the edge they once did.
I should stress this is speculation on my part. Record remains highly profitable and cash generative and today’s update seems reassuring enough to me.
It’s also worth noting that broker forecasts remain bullish and suggest a return to growth over the next two years:

The balance sheet looks bulletproof to me, with substantial net cash. Record is also highly profitable. Margins are high and return on equity has averaged 21% since 2016.
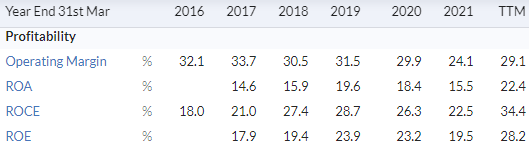
Record’s share price has pulled back from last year’s high.
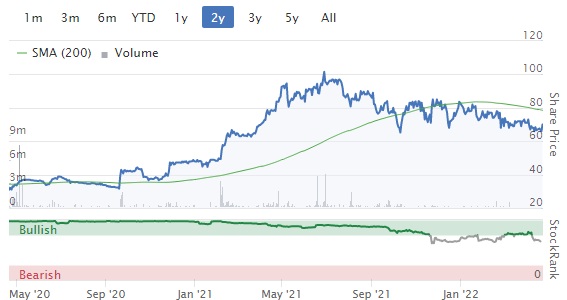
The stock now looks quite reasonably priced to me, on a rolling forecast P/E of 14, with a prospective yield of 6.7%.

I think Record could be attractively valued at current levels. It might be worth further research. I’ll certainly be watching with interest, to see how the business performs over the coming year.
Ibstock (LON:IBST)
Share price: 179p (-1% at 09.00)
Shares in issue: 409.6m
Market cap: £681m
AGM trading update (from Thurs 21/4)
I’m circling back to look at updates from yesterday from two brickmakers. I’ll start with FTSE 250 firm Ibstock (LON:IBST) which is now at the upper end of our market cap range.
Ibstock closed up 8% yesterday after issuing a strong update and upgrading its guidance for 2022.
- Q1 performance ahead of expectations thanks to stronger brick volumes and “resilient margin performance”
- FY22 guidance now “modestly ahead of previous expectations”
- £30m share buyback programme announced as part of value creation strategy
- Cost inflation a concern, but energy requirements for FY22 are now largely locked in, with one-third purchased for 2023.
- The group is committed to take action to protect margins
Demand in both the new build and RMI (repair, maintenance and improvement) markets is said to remain robust. Ibstock says it’s taking an active approach to managing cost inflation.
My view: Brickmakers including Ibstock have enjoyed good trading conditions in recent years, thanks to strong demand from housebuilders and economics which favour UK production.
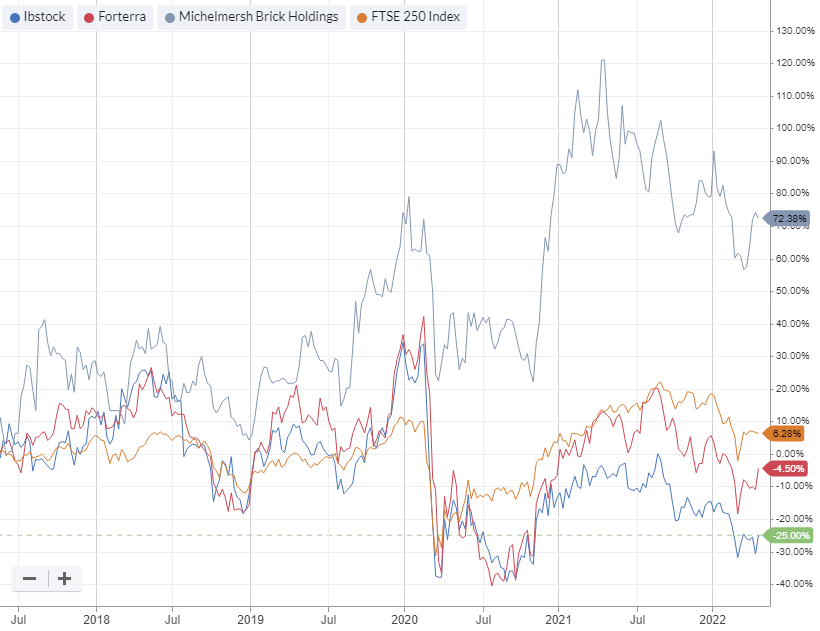
But Ibstock’s performance since its 2015 IPO has been underwhelming, in my view. The firm doesn’t seem to have been able to protect its margins or deliver consistent growth:

Ibstock shares are trading below their 2015 IPO levels and have lagged key rivals substantially over the last five years:
In fairness, Ibstock does seem to be on a sounder footing now. Debt levels have been reduced and the dividend looks more sustainable to me. At first glance, the valuation appears quite reasonable:

However, I’m wary of cyclical risks at this point, given the sharp increase in energy costs and the likelihood of rising interest rates.
Ibstock looks reasonably valued and the outlook for trading seems strong. But I’d want to do more research before deciding whether to choose this company over its better-performing rivals.
Brickability (LON:BRCK)
Share price: 100p (-0.5% at 09.30)
Shares in issue: 298.5m
Market cap: £293m
Pre-Close trading update (from Thurs 21/4)
Results for the year ending 31 March 2022 ahead of expectations
AIM stock Brickability (LON:BRCK) supplies building materials rather than producing them. The group’s roots are in bricks and building materials, but Brickability has expanded through regular acquisitions, and now offers a wider range of products and services.
Trading update: Results for the year ended 31 March 2022 are expected to be ahead of previous guidance.
- Revenue of £520m (+11% vs previous consensus of £470m)
- Adjusted EBITDA of at least £38m (+19% vs previous guidance of £32m)
The company says it remains confident that underlying demand for UK housing will be robust, as will construction activity generally.
Management are confident of further organic growth and say the “acquisition pipeline remains strong”.
My view: Brickability floated on AIM in 2019 and has been highly acquisitive since then. Since August 2021 alone, the group has announced three acquisitions and one joint venture.
Buy-and-build businesses can sometimes implode, but when done successfully they can create significant value for shareholders. Brickability’s management are highly experienced and at least some of them remain invested in the business.
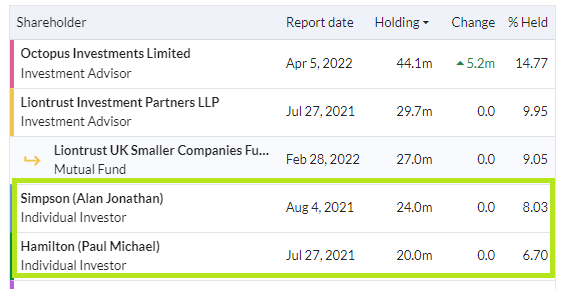
The company’s track record as a listed company is still short and we have not yet seen how Brickability will perform during a construction or housing downturn. However, progress so far seems encouraging to me and acquisitions have been achieved without diluting shareholders.
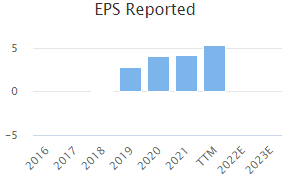
Broker forecasts have already been upgraded on several occasions over the last 12 months.
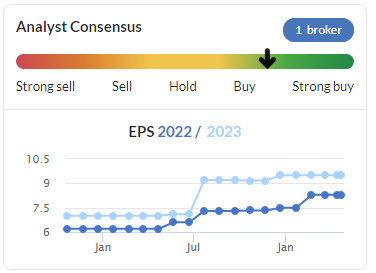
After yesterday’s update, house broker Cenkos has increased its FY23 earnings forecast by 4% to 9.9p per share (updated note available on Research Tree). This values the stock at 10 times forecast earnings, with a prospective yield of around 2.4%.
As with Ibstock, I’m a little wary about investing in this sector at the moment. But I would be more inclined to consider Brickability than Ibstock, given the group’s entrepreneurial management and strong recent track record.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

36 comments
Some big volume in Hostmore (LON:MORE) this afternoon. 2 x 5m trades at 60p, possibly overhang cleared or maybe more to go? 5m shares would be over 4% of the company.
M&G were recent sellers, they had 6m left at 6th January.
Not the greatest fan of the company but its only on 6x P/E so maybe worth a trade.
Awful lot of "trigger" selling going on driving prices down. Been watching a few shares today and noticed that small sells are triggering others to sell quickly after leading to price falls and further sells.
Pretty miserable environment but certainly seems like retail investors remain very fragile and trigger happy.
It looks like reasonable behaviour to me.
Personally, I can't see any benefits in holding a falling stock, especially if the sector as a whole or the broader market is weak.
It took me several years to accept- and realise that it's vital to keep your losses small, in relation to your winners. As they say, you can always get back in.
Not saying it is reasonable or unreasonable - just that sentiment is clearly very fragile as we are in a trigger selling phase for retail investors.
Hi BoB,
"Personally, I can't see any benefits in holding a falling stock, especially if the sector as a whole or the broader market is weak."
What about the many takeover bids that are happening?
Also, it can be difficult/impossible to buy back a decent-sized stake in a small cap that you've sold, as once it issues good news, you can't get the stock in decent size. I found that a big issue in March 2020 for example - hardly any of my buy orders at the market low got filled.
Market sentiment can turn on a dime, and studies show that if you're out of the market on a few key days, then you miss much of a big bull run.
I do understand your point, so am not disagreeing with you, just wanted to counter-balance it with some positive reasons, particularly as you said "I can't see any benefits....", when actually, there are some!
I could understand it if you said that you think the benefits are outweighed by the risks right now.
Also, many people don't want the time or stress of trying to time the market, and are happy to hold through volatility. At the moment it sounds like many readers are turning into traders, not investors. Fine if you can make money doing that, whatever floats our boats! All good to discuss.
Regards, Paul.
I agree David
The good news is that a few companies on my watch list are approaching strong support levels on rising channels. Somero Enterprises Inc (LON:SOM) (I hold) Saga (LON:SAGA) Begbies Traynor (LON:BEG) Photo-me International (LON:PHTM) (I hold) I’ll be buying as there is bound to be a short term bounce and hopefully one or two of them will stick.
Also there are one or two small/micro caps that have risen off lows without the usual immediate selling Unbound (LON:UBG) for example. Maybe the sellers are running out of steam? Let’s hope so.
Just to counter-balance your (entirely reasonable) opinions, I've found that my best (as in most profitable) purchases have been when everyone is scared witless. As recently as March 2020, and Oct 2021, we had stunning buying opportunities when everyone was panic selling. Many shares produced blisteringly good returns in just a few months from that point.
I'm not claiming any expertise in market timing (clearly, given my terrible performance in the last 6 months!), but it does feel to me as if we might, repeat might, be getting near the point where it makes sense to snap up some bargains.
Look what happened in early March 2022. Crazy, irrational selling, and people who were brave enough to buy, are generally up c.30% on those purchases already.
Whenever I get a real panic impulse to sell, it's nearly always at or near a market low.
Everyone's got to do whatever we're comfortable doing. There's no right or wrong on market timing. We're just focusing on company fundamentals here at the SCVR, on the basis that even if people aren't ready to buy, then building up a watch list of potential bargains is a really good way of making outsized gains when you're ready to push the buy button.
One thing that strikes me, is how in recent weeks, we're often reporting positive updates from companies whose share prices have been relentlessly falling. So the idea that the market is all-seeing and all-knowing just isn't right. Sentiment drives prices in the short term.
I'll spare you all the predictable Buffett quotes, which confirm all the above, as a friend recently told me that was an appalling thing to do, and undermines your argument! A bit harsh, but I took his comments on board.
Regards, Paul.
P.S. I'm impressed by the marketing strategy of Naked Wines (LON:WINE) - a box of 6 bottles of Chardonnay has just turned up, which apparently I pre-ordered months ago. Perfect timing on a Friday afternoon!
"... we're often reporting positive updates from companies whose share prices have been relentlessly falling. So the idea that the market is all-seeing and all-knowing just isn't right."
Indeed the market isn't all-knowing, but presumably you'd agree that there are lots of valid reasons for a share to fall, and go on falling, despite a positive update. Any update is 99% about the past, whereas the market is trying to give a probability weighted view of the future.
Even if the update and the market's outlook weren't different things, there are lots of reasons for a share to fall regardless of business performance. The mere fact that the market falls is good reason. The mere fact that we're in a risk-off environment is good reason for small caps to fall further.
Any update is 99% about the past, whereas the market is trying to give a probability weighted view of the future.
I don't see it like that. As we cover here every day, it's the outlook comments, and the nuances even, that matter the most, not historic performance.
If markets are being rational, then why are share prices of strong companies, which are trading well, and have a good outlook, plummeting, then shooting up when they tell us that trading & outlook are good?
Anyway, look, it's Friday evening, let's relax and enjoy the weekend!
Best wishes, Paul.
I’m following the Benjamin Graham / Buffet / Monger strategy of watching “Mr Market” who is irrational and led by fear and greed.
There are some great companies, posting great results in good sectors with nothing fundamentally changing other than Mr Market taking a dislike to them .
If yiu are buying part of a company not trading a share for short term gain then focus on fundamentals of great companies and trust the research you do and ultimately great companies will have great share prices .
Avoid the hyped dross and look for the quality .
I’m actually having a record couple of weeks having taken strong positions on a couple on my watch list that we’re getting hammered for no reason other than sentiment .
What's irrational about that? The company announces better than expected performance so the shares go up. So far, so rational. You seem to be focusing on the part where the price has gone down, but that need have nothing to do with company specific issues.
For example, the odds of a 2023 recession have gone up significantly e.g. see here:
A US recession in 2023 is expected by a lot of investors | World Economic Forum (weforum.org)
What company update ever comments that far ahead? They might comment on expectations for the current FY but that's it, other than bland hopes for the future.
So it would be entirely rational for small caps to be trading well but being marked down for a long list of reasons (even if there is no recession on the horizon).
The FX world knows nothing about morals with the Rouble almost back to where it was against the Dollar pre war and Sterling continuing it's downward trend against the Dollar.
The GBPUSD is easy to explain. Higher interest rate expectations for the USA, and a "flight to safety" (USD still seen as more safe than GBP).
Unfortunately, I believe inflation will be higher and more persistent in the UK than the USA. So at some point in the future BoE will have to raise rates higher than the Feds. All IMO so I'm taking the current sterling weakness as temporary (horizon half a year to two years temporary).
Essensys (LON:ESYS) (no position)
Hi Paul
You asked:
"Receivables look high, at £6.1m, compared with £10.9m revenues in H1, suggesting the customers are not in a rush to pay - which might indicate maybe some disputed invoices? It’s a question to ask management, if any readers speak to them."
Here is my question and the CFO's email response when I queried this in November 2021:
"Q - Outstanding payments from customers seem quite high. Should we expect this to remain elevated going forward?
A - This very much depends on activity levels with site establishment charges and where we are in the revenue growth cycle. I would not expect it to increase proportionately."
Not a very convincing response IMHO.
A
Hi abtan,
How interesting, thanks for posting that re receivables at Essensys (LON:ESYS)
I agree, the response from the company seems unclear at best!
Annual Reports give more granularity on things like receivables, so for anyone considering buying the shares (I'm not) then it would be worth having a look through the last annual report, to see if there's any more information on receivables, e.g. age profile of unpaid invoices, etc. There might be other things in receivables, e.g. accrued but not yet invoiced charges to customers.
It's not a red flag, just something to investigate, as SaaS companies usually collect in cash up-front, rather than have extended receivables, so it doesn't look normal to me.
Regards, Paul.
Essensys (LON:ESYS) re debtors
At year end 31 July 2021, the total trade receivables was £5.3m (see Note 19 page 82 of the statements). This balance included £1m of prepayments and other debtors of £0.7m. Trade debtors of c£3.5m include £2.7m which are less than 90 days old and £0.8m (net of provisions) greater than 90 days old. These balances are approximately consistent with 2020. Turnover is c£22m so "old" debts (at the time) represented about 3.5% of annual turnover. Not great, but not a major threat to the business either (IMO). I've also contacted the business and asked for further details.
For me the bigger issue is whether they will deliver the new contracts/sales to justify the significant investment in headcount over the next two years. They seem confident, and the CEO is the founder and largest shareholder (with 31% of the equity), but as ever we'll only know definitively in retrospect. In the meantime they are unlikely to go bust as the cash has already been raised.
Essensys (LON:ESYS)
Hi AcornInvestor
I'm not sure it's fair to exclude an overdue payment simply because it's been provided for in the accounts.
Payments are meant to be made within 30 days, so there were £2m of invoices overdue at the Year End.
Revenue in 2021 was only £22m = c10% of annual revenue that isn't paid on time.
That seems too high for what is meant to be a 90% recurring revenue model.
A
Hi Abtan,
Essensys (LON:ESYS)
Whilst technically correct, that's quite a hurdle you are expecting of your investments! Personally I've never come across an international (or even UK-only) business whose invoices are all paid within 30 days, but happy to invest in such if they are out there.
I'm certainly not trying to push this as an investment proposition; it isn't perfect (just like all of the companies out there) but it has some attractions, to me at least!
I'll let you know if/when I get a response re the 90 day+ debtors from the CFO (via their IR team).
Good luck with your investments.
Dear AcornInvestor & abtan,
A quick thankyou for some quality digging there, on Essensys (LON:ESYS) receivables! As I have to flit from one thing to another every day, I can only flag up potential problems, not investigate all of them.
There's obviously been some problem with customer(s) disputing invoices, hence the bad debt provision. But that's taken into account with reported receivables, which are still high.
Overall then, I'm not completely reassured.
The best thing, with this type of SaaS business, is to find a way to talk to users of it. I've only managed to do that a few times with other companies, and have been horrified at how rubbish people using it, often find the software to be. NB this is a general point, absolutely not directed at any particular company, and definitely not Essensys.
I was involved in 2 big IT implementation projects in the 1990s/early noughties, and in both cases they were a disaster, and what the salespeople promised was nothing like what they delivered. Friends tell me that is very frequent, hence pay the most money you can afford for a corporate lawyer to set up the contract, rather than signing whatever the vendor puts in front of you.
Another, much smaller SaaS provider of buildings management software claims to be market leading. A friend who is a corporate concierge in London, told me their software was awful, and that nobody knew how to use it, and it kept going wrong. So be careful in this space I think!
Getting our information just from companies, and RNSs, is quite dangerous.
P.
Essensys (LON:ESYS)
To be honest you both have perfectly valid points here - i will definatly say ongoing materially high receivables well past due date is a deffo red flag to me IMHO. Treble so when the amounts would materially affect recent stated results. Eg if they needed to w/off £1.5 mill of sales over say 2 year period that would be £0.75 mill of the bottom line each year - more than the sum of the profits here between 2018-2020. Seems crazy for loss making company providing "mission critical" stuff where presumably you should be able to give most customers no option but to pay - to be in this position. The reality is we simply don't know the detail here though, may be summit over nothing if they have given good customers (who may have cancelled and provided nil cashflow) help ref cashflow over the covid period. Would be nice to prod the CFO about the potential increasing proportion here too (debtors days to sales) when he stated that the proportion would not increase - his prior reponse to Abtans valid question was pretty sketchy imho.
Ref high hurdles being expected ref investing - i suspect thats a very sensible route to ensure you cut out the companies that are trying to post an over optimistic picture of where they are going or the picture they are trying to piant doesnt quite match with relaity - just look at teh adjustments on the THG numbers posted to see the picture of underlying prfitability and reality of bottom line profits are completely different.
Essensys (LON:ESYS)
Great stuff abtan
Unless there are non trade receivables in the £6.1 mill o/s this figure appears to have increased £1 mill or 20% on reasonably static turnover compared to last year. So it appears to have grown proportionely by 20% at exactly thne time the company said it would not grow proportionely. Note there could very well be non trade stuff in receivables so there could easily be innocent explanation - would be interesting to see reponse company if you prodded them again. Also intersting that sales are flat when they say they said they are in revenue growth cycle - its growth just now now scotty.
Hi Paul and Roland, if you're looking at yesterday's results too then Integrated Diagnostics Holdings (LON:IDHC) had preliminary results, reporting 'outstanding performance', 'record-high margins' and profitability at an 'all-time high', with an increased dividend. Jack covered it in November.
Integrated Diagnostics Holdings (LON:IDHC) (I hold) announced a whopping dividend too for FY 2021, around 9p per share at current exchange rate, SP $1.16
Hi Indie,
I had a quick look at Integrated Diagnostics Holdings (LON:IDHC) on your prompting, but it's not the sort of thing we cover here - a healthcare company operating in M.East & Africa, but listed in the UK, is not something I would touch. Reason being that, as Mark Slater once put it, overseas companies listing in the UK "usually have something wrong with them". I've seen dozens of them blow up & result in major losses for investors here.
That said, IDHC has been listed in the UK for over 7 years, which is a plus (the dodgy ones have usually blown up by then). Also, it has a history of paying divis - again, a good sign, because frauds don't usually pay divis, or if they do, only small ones, and not for very long.
Also, I see that IDHC has not issued shares, remaining at 600m for years now, another good point.
Everything else on the StockReport looks really good - a lovely trend in revenue & profits, large upgrades in forecasts, high profit margins. Fwd PER of only 12.
So, for investors who do invest in overseas companies (via a Jersey holding co) listed in the UK, then this one might be worth a closer look. Good luck with it!
Regards, Paul.
Thanks Paul, much appreciated.
Hi Paul, I’m surprised by your comment about Mark Slater, as for a number of years his largest holding was Hutchmed (china) (LON:HCM), over 10% of his fund at one time, which is based in Hong Kong.
Hi Rustbucket,
Yes that's right, I remember Mark Slater talking at conferences a while back about £HCM and why he backed that, whilst telling us (rightly) that almost all other China stocks on the UK market at the time were frauds! (which they were - e.g. Naibu & Camkids, and others, which I warned people away from with great vigour).
Slater basically said that his team had done detailed due diligence on HCM, and come to the conclusion that it was so well run and ethical, that it was lower risk than most UK & US large caps.
That was his view, not mine. I wouldn't touch anything based in China.
The situation with Russia is a key reminder why it's too risky to touch these things in countries which are run by despots, and are flexing their military & economic muscles. The game's up with globalisation in my view, and Taiwan such a big risk, that nothing would persuade me to buy any Chinese stock, or Russian, or anything other than UK, USA, or Europe. Why take the risk? Well, there is one reason - if you're a special situations investor, who has the expertise, which I don't.
Regards, Paul.
UK Retail Sales - ONS said sales volumes fell 1.4 per cent in March.
Online sales bore the brunt, dropping 7.9 per cent in the month, following on from a 6.9 per cent fall in February.
The ONS suggested that the fall in online sales could be due to the end of lockdown restrictions and shoppers feeling confident returning to stores, when compared with December and January as the Omicron variant of coronavirus ran rampant.
Its a strange one as I think the general feeling was the rise in online was accelerated during COVID but not sure too many felt it was not going to be maintained post COVID. We're in a very different place now with Putins war and you have to wonder whether the model of delivering orders often in several deliveries makes sense in the world of high fuel costs.
I am long overdue really taking a deep look at my investments and seeing whether they make sense in the new world order (without really knowing what that will be.)
I think someone said on this board a few days ago that a recession is looking more likely by the month with a squeeze on consumers and high inflations and interest rates (which will come.) Going to be an interesting year or two I suspect
Brookeda....Gosh never even thought about the fuel cost on deliveries, interesting thought!
I just don't see my children going out to the 'high street' anymore. it was ingrained in us as kids. A trip to town on a Saturday. When the first self service till came out I vowed never to use it and here I am, my first choice if am honest.
I wonder if the delivery of parcels will further drive the age of electric with fuel prices so high, I did see an electric delivery van a few weeks ago which was quite a surprise.
I totally agree with you on the portfolio, but as you say, where are we going? Putin could quickly take the southern corridor in Ukraine and could be all over in a few weeks, and then what? I see shares getting a bump and sanctions being removed with our normal short term memory for things...although I do suspect a long drawn out war with the West attempting to give Putin a bloody nose via proxy.
Thanks for the grey matter nudge, is it always this uncertain?
Roland,
Thank you for your write up about £REC. Edison estimates the margins by product as follows: passive, 2.6bp; dynamic, 13.6bp; currency for return, 12.5bp; multiproduct, 18.2bp. So relatively smaller growth in sums under management in the more profitable lines are worth much more to REC than growth in passive.
The costs of adding additional funds to a strategy are very low and so an incremental $2bn for dynamic in H1 FY23 is attractive even at a slightly lower average margin.
“Currency for return” is a reference to the carry trade. REC did very well out of this trade in the run up to the 2008 crash but it collapsed as interest rates globally converged to roughly zero. The re-emergence of interest rate divergences (look at Japan’s interest rate and the collapsing Yen) may support significant growth of this trade.
I don’t see, say, AGFX as providing an alternative to REC: AGFX is voice brokered exchange to support say a trader doing business in Germany. REC provides hedging strategies to managers of financial assets.
Hi Alistair,
Thanks for your comment, I'll take a look at the Edison note.
I agree that Argentex (LON:AGFX) isn't a direct comparison. My thought was that perhaps there are now other, more flexible and efficient ways for institutions and corporates to manage their currency exposures.
This is only speculation , and I agree that Record (LON:REC) probably still has a niche of its own with larger institutions looking for ongoing FX protection. But technology and data have disrupted many areas over the last 20 years. My impression is that this may also be happening in the staid and (historically) conservative world of FX.
Regards,
Roland
94 thumbs up! (which could re-use the lube you mention!)
You've demonstrated how to please the readers - slip in a little double entrende ;-D
As always MrC, thanks for your brilliant early morning summaries, have a great weekend :-)
MrC's bone dry humour ... dispensed in judiciously minute amounts ... is a much anticipated SCVR highlight every trading day.
I agree, although half the time I don't get them. Not a problem today.