Small Cap Value Report (Fri 22 Dec 2017) - Bitcoin Pt 2, CLLN, MOS, AHCG, RGD

Good morning everyone,
The RNS stream today is not exactly fireworks, but you've made a few suggestions in the comments so I will have a look at:
- Carillion (LON:CLLN)
- Mobile Streams (LON:MOS)
- Action Hotels (LON:AHCG)
I'm also making a short comment on Bitcoin, adding to Paul's comments yesterday, so I hope you don't have Bitcoin fatigue!
Regards,
Graham
Bitcoin (obligatory comment)
Firstly, bear in mind that I am a nocoiner (someone who doesn't own any crypto-coins). So perhaps I'm bitter about never buying any, despite being aware of them for longer than most people? I don't think I am bitter. But maybe it's unconscious?
Anyway, I did consider the investment merits of bitcoin, and rejected it.
The practical argument
In simple terms, my reason was as follows: while the supply of bitcoin may be limited, the supply of crypto-currency in general is unlimited. There are over 1,000 crypto-currencies, and more are being created all the time.
So buying bitcoin as an investment is not a bet on crypto-currency in general succeeding. It's a bet on that specific crypto-currency succeeding.
Based on my limited reading on the subject, litecoin appears to be a far superior currency than bitcoin. And as things currently stand, the size of the bitcoin network has resulted in transaction fees running into the tens of dollars. This makes bitcoin impractical for micro-payments and effectively renders it useless as an everyday medium of exchange.
There are plenty of other currencies to choose from, so why should bitcoin be the best? It's quite reasonable to think that some other crypto-currency will eventually overtake it in popularity, despite bitcoin's first-mover advantage.
Maybe I should have bought a crypto ETF, to hedge my doubts about bitcoin and my lack of ability to predict a crypto-winner? Perhaps. That's a much stronger argument versus buying one coin in particular.
The economic argument
But there's something else holding me back.
I've made no secret about the fact that I'm a goldbug, and have always had an interest in the gold standard.
There's a thing in economics called the Regression Theorem (by Mises). My understanding of this, which I developed before bitcoin was invented, explained that money gradually emerged as the most marketable commodity in a barter economy.
If you think of a pre-money economy, you have people bartering cattle, wheat, metals, etc. At some point, a commodity which is widely demanded becomes attractive merely for its use in exchange. So you get people accepting it as a means of payment, even though they don't plan to use it themselves. But they know they can use it to buy things, since other people want to use it.
Eventually, one commodity becomes the common means of payment for the entire economy - the money.
The problem with crypto-currency is that it has no use, except as a currency. Unlike gold and silver, we can't do anything with in the real world, except use it as a currency.
So crypto lacks that foundation, that underlying reason for someone to want to hold it. The Regression Theorem doesn't apply.
We can understand why people use paper monies: because we are legally compelled to. We have to use these paper successors to gold. And that's always a strong economic argument to do something - to avoid going to prison. But crypto lacks both the underlying use value and the legal compulsion.
Conclusion
I might add, in conclusion, that my practical and economic arguments are related to each other. It's no coincidence that an asset with an infinity supply is also an asset which has no economic value. Those two qualities tend to be related to each other! For example, it's not easy to sell air in normal conditions and at normal altitudes. It has an infinite supply in normal conditions, so even though it's useful, it has no economic value.
I should add that some people have gone to great lengths to revise and update the Regression Theorem, and to explain how crypto does not violate it and therefore makes good economic sense to be used as money. Perhaps I am not smart enough or have not spent enough time trying to understand these arguments. I will happily revise my opinion if it turns out that I'm wrong, but these arguments are unconvincing to me. I think that anyone who railed against "fiat currency" prior to 2009, should still be sceptical about it today.
Perhaps if I was really smart, I would have done the same as Charlie Munger (at 38:40). Charlie says regarding crypto-currencies:
"I think it's perfectly asinine to even pause to think about them."
Carillion (LON:CLLN)
- Share price: 17.6p (+2%)
- No. of shares: 430 million
- Market cap: £76 million
Update on financial covenant deferral
A quick update on this large support services business which has fallen on hard times.
It has achieved deferral of its covenant tests from 31 December until 30 April 2018.
This is standard procedure for a company in breach of its tests.
Discussions with stakeholders (i.e. lenders) are "progressing well", as it seeks a solution to reduce debt and fix the balance sheet.
Checking my notes and previous comments on Carillion, net debt for 2017 is c. £900 million on average.
So the enterprise value here is significant. If it does fix the balance sheet and avoid shrinking too much, it will probably once again be too large for coverage in the SCVR. Although I suppose it's possible that sceptical investors might give new-Carillion a much weaker valuation rating, in which case we might be covering it for a while!
Carillion is still the UK's most shorted stock, whether measured by the number of shares sold short in disclosable positions, or the number of funds who have disclosed their shorts on it.
I'm a bit surprised that this is still the case. Surely a market cap of £76 million is getting into the sort of small-cap territory where the risk of a short squeeze begins to outweigh the benefits of maintaining the short?
These funds apparently beg to differ and are holding on for a maximum additional gain of just £12 million, if the shares head to zero from here.
At least they will be enjoying a little bit of Christmas cheer, unlike the long-suffering shareholders. In my opinion, these shares are close to worthless prior to recapitalisation.
Mobile Streams (LON:MOS)
- Share price: 2.75p (unchanged)
- No. of shares: 91.6 million
- Market cap: £2.5 million
I agreed to cover this before checking the market cap. Silly mistake! I bet that a handful of you own houses worth more than this.
Anyway, let's see what it's all about. Paul (who owns shares in £MOS) can also be found commenting on it in the thread below.
Mobile Streams licenses and distributes a wide range of mobile content including games and apps that are retailed around the world, primarily in emerging markets. The Company's main operations are in Latin America and in particular Argentina, with recent expansion into India.
Sales for the year to June 2017 collapsed by more than 50% as a consequence of weakness in the company's main operation in Argentina. The explanation is partially as follows:
During the period, both the Group's Mobile Internet revenues and its Mobile Operator revenues decreased. As consumers steadily update their phones from legacy feature and flip phone models to smartphones, they have generally used the operator content portals less.
I hope I'll be corrected if I'm wrong, but the company is buying up games and then seeking to distribute them via carrier portals. The problem with this is that people don't use carrier portals when they have an iPhone or a good Android phone. They use the Apple Store or Google Play.
The company owns mobilegaming.com, which looks terrible on a desktop but does look a little bit better on a phone.
The first game on sale there is Flying Birds 2, which is an obvious rip-off of Angry Birds. The second game is Farm Ninja, which is an obvious rip-off of Fruit Ninja. It's also got Solitaire, math games, etc.
So it looks to me as if the company is buying rip-offs of famous games, and other very cheap titles, and selling them to consumers who can't afford or can't access anything else.
And since the Argentinian consumer has moved up the food chain, Mobile Streams is moving on to try this model in Indian.
The roll-out in India is progressing well:
Mobile Streams now has direct carrier billing with five of the leading six Indian telecom operators so that it can bill its mobilegaming.com games service conveniently and easily. Four of these connections are live and one is currently in the integration phase.
So perhaps there will be an opportunity for them to make money in India, for a while?
The company made a £1.5 million pre-tax loss in the most recent financial year, on £5.7 million of revenue. It had cash of £2.2 million.
In the prior year, when revenues were more than twice that level, it still made a loss.
It has reduced headcount very significantly, so perhaps the costs will be under control now. And revenues in Argentina are said to have stabilised.
On balance, It looks to me as if the company will do extremely well to avoid raising any more funds. Not investment-grade by any means. This is punting territory!
Action Hotels (LON:AHCG)
- Share price: 28p (unchanged)
- No. of shares: 148 million
- Market cap: £41 million
Related party transaction and trading update
Red-flag alert. This is an AIM-listed stock which is incorporated in Jersey, has most of its operations in the Middle East, and 66% of shares are held by the Chairman who is also a major lender to the company.
So let's tread with caution.
This is a hotel group which owns and operates 3- and 4-star branded hotels, mostly under the ibis brand name (ibis is owned by Accor, listed in Paris with ticker ACP).
As with every property company, I immediately check the NAV. At the interim results (for June 2017), NAV was $192 million 106p per share. So this is trading at a very considerable discount.
The shares have been sliding more or less continuously since the Dec 2013 IPO:
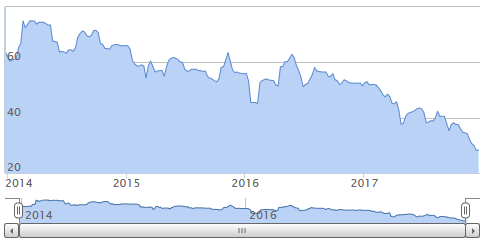
The NAV calculation for June 2017 was based on hotels and land valued at c. $475 million, offset by $253 million of borrowings (of course there are plenty of other items on the balance sheet).
If you trust the numbers and the management, this looks highly attractive at first glance.
Related party deals
The main question here is probably whether minority shareholders are going to ultimately get a good deal from the major shareholder, from whom the company is borrowing money and leasing hotels.
Actions both borrows from and lends to related parties (controlled by the major shareholder). It buys services from related parties. And according to last year's annual report, it sold an investment property to its major shareholder. It also "wrote off related party balances" worth some $600k. In other words, it is constantly interacting with its major shareholder.
Also, there is a very complicated corporate structure which means that Action does not own the voting shares in its own operating subsidiary! Instead, the related party owns all of the voting rights, but it gives Action the power of attorney to vote on its behalf.
I can't see what the overall interest rate is, but Action is paying interest at rates of between 4-8% on various international loans, and 9.9% in loans to its related parties. This is a higher rate than the rate which it receives on loans to related parties.
The result is that finance costs have mostly cancelled out Action's adjusted EBITDA, and it has been making a loss since 2016. It has also failed to comply with terms of various loan agreements (i.e. covenants), but lenders have been forgiving.
Today's news
Sorry for the preamble, but the above seems like essential background info!
Today, we learn that the related party is giving Action a waiver on some rent which Action owes, as a "one-off occurrence". This will help to mitigate this year's expected poor performance against original expectations, and I interpret it as a gesture of goodwill from the related party to Action's minority shareholders.
We also learn the company is delaying another hotel opening, in order to concentrate available resources on a project in Australia opening in April 2018.
My opinion
I'm actually quite intrigued about this share. Maybe it has reached such a bombed-out discount to NAV that it actually represents good value, despite all the issues it faces?
The hotel valuations are continuously updated, so if they are at all reliable then the NAV should indeed be a decent measure of the book value. The complicating factors are:
- Very complicated relationship with the related party, with many opportunities for minority shareholders to potentially be mistreated. So there is a lot of trust needed in the majority shareholder.
- The economy in the Gulf is still suffering from lower oil prices than were anticipated several years ago. Luxury spending has been badly hurt. Action says it is positioned in the mid-market sector, so it is not hurting quite so badly as the five-star hotels.
- If the valuations are wrong, then this has a disproportionate effect on the NAV, given the leverage involved.
- Failure to comply with loan covenants suggests there is some potential for distress, though lenders have been very relaxed about it.
- High interest rates on loans make it difficult for Action to generate really strong returns for equity investors.
I'll keep an eye on this one from now on, in case it turns out to be a diamond in the rough!
Real Good Food (LON:RGD)
- Share price: 21.75p (+2%) - market closed before results announcement.
- No. of shares: 78 million
- Market cap: £17 million
Interim results/further funding
This is a very sneaky move by this food manufacturer and distributor - putting an RNS out after the market closed. Thanks to shanklin in the comments for bringing this to my attention.
As part of a re-forecasting exercise the Board has identified that further substantial additional funding will be required over the coming twelve months for working capital and investment purposes in order to implement the Group's business plan as it continues to grow. The Board is currently exploring its options as to how this additional funding will be financed, which include, inter alia, the issuance of new equity.
Th company is suffering a cash crunch and in order to survive Q1 2018 and release its interim statements with a going concern basis, it is raising £3 million from its major shareholders, at a 10% interest rate.
Note 2:
An additional £3m funding... will ensure that the Group remains a going concern until the end of the first quarter based upon current forecasts and the Board believes this will provide sufficient time to source the additional funding. In the event that the Board is unable to source this additional finance, and in the unlikely event that the major shareholders, whose support has thus far been strong and continuing, decide not to provide further support, then the Directors cannot be certain that the Group will be able to continue as a going concern.
We definitely need to put a black mark against companies which release statements at the last available opportunity or when they hope everybody will be on holiday. Why not just admit things are going badly?
That's it from me for the long weekend. Have a great Christmas and I will see you at some stage next week.
Best wishes
Graham
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

31 comments
Paul, I completely disagree with you on crypto currencies, saying that supply is unlimited is like saying that the supply of .com's was unlimited before the dot com crash, yet didn't Amazon look like one of the winners then ? didn't google ? So when the market crashed, sure they fell in value, but how have they done over the long term ?
You may not be able to predict the winners now, and I'm not saying that bitcoin doesn't have some challanges, but I think I would predict that bitcoin would be one of the winners.
you also mention that bitcoin as no use or value as anything but money, and that's a bad thing?
How do you feel about , say, money ? what other uses do those paper notes have ?
as for the benefits of gold, I kind of agree with you, but what about if a huge amount of gold were found ?
would that not be challanging to it's price ? or if scientists find ways to extract it better, or create it ?
won't that put a lid on it's price or desirability (a bit like man made diamonds are getting better all the time),
where as there will only ever be that fixed number of bitcoins. I'm not ready to invest heavily, but as a punt, why wouldn't you spend a couple ok thousand to have some exposure ?
K
Hi kenobi
Hindsight tells us that Amazon and Google were winners, but if they were such obvious no-brainer champions then we would all have been invested. We weren't, for the very good reason that it was difficult to pick winners and losers - remember Yahoo? Hindsight is a lousy way of making investment decisions.
And, of course, the point being made about gold is exactly the issue - if gold was suddenly in infinite supply then its value would collapse. To make the analogy of gold and cryptocurrency you've got to establish the scarcity equivalence - and it doesn't exist.
True, standard Bitcoin is limited in its total volume (let's not even go into the politics around Bitcoin Cash) but even if we can somehow make the argument that that makes it valuable in its own right, which is difficult given the proliferation of cryptocurrencies, that very limitation puts a cap on its usability as money. Consider, if the total amount of sterling in circulation was capped at a million pounds in denominations of one pound notes, how much actual commerce could get done?
And as for the punt argument, consider this dotcom equivalent statement - as a punt why wouldn't you spent a couple of thousand in {insert name of favourite 1999 dotcom stock here} to have some exposure?
I disagree that crypto-currencies have no real value, but they will be regulated and the winners are likely to have the characteristics that regulators like. However, each to their own, I've no doubt some people will - and already have - make a lot of money out this mania. As ever, the challenge will be keeping it.
timarr
As for fiat currencies, why would you attribute anymore value to the digital keystroke that Carney, Draghi and Yellen authorise to create more QE than to the hugely expensive mining effort that goes into producing the digital keystrokes that create a bitcoin
Fiat currencies are backed by governments - which represent huge national assets. All the currency created as part of QE has failed to have the effects predicted - massive inflation, high interest rates etc - by the doom mongers. Of course all those things can happen, and have, but they don't where the central bank is backed by a reasonably stable economy and government. There is a massive difference between a currency that is controlled by a central bank, and that may involve printing money at times for reasons of monetary policy, and a currency that is based on an arbitrary set of rules, whose main reason for existence, outside of speculation, is by those who want to be able to launder proceeds of illegal activity, or avoid tax obligations to the states that create the conditions in which they can operate.
As such they must be prime targets before too long for regulation. There may be difficulties with that, but in the absence of any underlying asset it's a bubble waiting to burst once anyone starts taking them seriously.
Peter
Dear Paul and Graham,
I would like to add my thanks to all your other followers and wish you a Merry Christmas and a prosperous New Year.
I must however take issue with you on bitcoin and some of the other cryptos. A couple of years ago I thought that no matter how much I read about it in The Times or online I am not really getting any wiser. Consequently I decided to buy some, more to try and understand it than any other reason.
I am now a complete convert, not simply because of the profits but also because I have come to understand the sector a bit more.
How I see it is that BTC may well become the reserve currency, it may also be replaced ultimately with something with more utility, but in the interim it has been and will likely continue to be an appreciating store of value. To your point that it is not useful, it is as useful as gold, it is just not as decorative. Gold (of which I am a holder) is very similar, it is expensive to mine although the early stuff was cheap as one could just pick up nuggets where they lay but gradually as it got more scarce the value increased and the cost of extracting it became increasingly expensive. Bitcoin follows this pattern exactly and like gold has a finite supply, in fact probably a more easily identified amount beyond which there is no more. It is thus deflationary.
As for fiat currencies, why would you attribute anymore value to the digital keystroke that Carney, Draghi and Yellen authorise to create more QE than to the hugely expensive mining effort that goes into producing the digital keystrokes that create a bitcoin. The bankers will carrying on creating more devalued currency until inflation one day ensure that they all disappear up their own fundaments.
I am not sufficiently technical enough to understand if blockchain technology will be the new internet and it may be at a similar stage to that of the internet just before the .com bust but if that is so there may also be Amazon type businesses that have already been created lurking there. Factom perhaps may well be one of them.
To close your minds to it completely without at least getting involved for the purposes of experimentation seems unlike you and to my mind unwise.
Hugh
Paul, Graham, I'd just like to add my sincere thanks for all your highly valued and informative reports in 2018! As well as leading me to research some interesting shares, just as importantly, your comments have stopped me from wasting time researching not so good ones which on the surface looked interesting.
I'd also like to thank all those regular contributors in the comments section each day which is often very insightful and can add more 'flesh to the bone' to a stock's story or management..
I hope you both have a wonderful festive season and here's to a successful 2018 for all!
Regards
Dom
P+G, Thanks for all your efforts this past year !
Hi Graham,
Many thanks for today's excellent report! Thanks also for the Charlie Munger video, it's fascinating & very entertaining, what a remarkable man.
It seems to have been a good day to bury bad news for several minnow stocks;
London Capital Group (LON:LCG) - down 47% today. Just 42 mins before the market shut, it announced plans to de-list from AIM. Although it's moving to a smaller exchange (which I've never heard of before) called NEX Exchange Growth Market. Looking at the companies listed on NEX, it looks like a reincarnation of the old Plus/OFEX market. So shareholders might still be able to deal. The largest shareholder in LCG owns 78.1% of the company, so can force through the shareholder vote (requiring 75% support).
Concepta (LON:CPT) - down 7% today - 60 minutes before the market closed, it issues a profit warning. Delivery of a big contract has slipped from 2017 into 2018. This is another jam tomorrow share from the Adam Reynolds stable of highly speculative stuff. The company says it has enough cash, following a recent £2m placing.
Integumen (LON:SKIN) - down 35% today - 83 minutes before the market shut, this company announced a small placing, and what looks like a profit warning - "some of the existing product lines are taking longer to generate the level of revenues expected by the Board whilst others, in the Board's view, have the potential to outperform. The Board is also reviewing its overall cost base ")
In passing, I note that troubled Accrol Group (LON:ACRL) is still languishing well below the mooted 50p placing, with the shares at 35.75p. I'm doubtful whether the placing is still going ahead at 50p, or whether placees might demand a discount? The company should have left the shares suspended until the placing was completed, in my view.
So the above announcements on the last trading day before Xmas have probably resulted in a few people's festive season being ruined. Such are the perils of micro cap investing!
Regards, Paul.
Nex is the old ISDX. I found out about it because there are a large number of LSE traded companies that are also traded on Nex and if you make a trade you don't know where it has been traded until it appears on your contract note (or if you wonder why it hasn't appeared on lists of trades). More here:
https://www.sharesmagazine.co.uk/video/max-raynor-sales-nex-exchange
Ironically London Capital Group (LON:LCG) is already dual-listed:
http://www.nexexchange.com/member?securityid=18409
Thanks for all the great reports this year Graham. Have a good Christmas.
Regards
Andrew
Graham - Better explained here http://www.bbc.co.uk/programmes/b054423q than I ever could, but barter has never been anything other than an insignificant part of the economy, and isn't the source of money. Even today the conventional non-money transaction between friends is "I owe you one", not, "here have my shoes and coat." Barter simply doesn't cope with the asynchronicity of supply. So debt and money are the same thing.
Anyway, thanks to you and Paul for your commentaries through the year, very useful reading. Have a good christmas and new year.
Thanks Paul & Graham for all the valuable reports this year.
Happy Christmas to all :-)
On bitcoin:
1. It has no intrinsic worth
2. It is possible to make a lot of money investing / gambling on it
So:
1. Could I recognise the bubble forming early enough to buy cheap?
2. Could I recognise the top to get out before the bubble bursts
If Yes to 1. And 2. Then buy
For me the answer is no. I would have no idea how to time this. So Charly Munger is right. Don't even think about it.
With the completion of the demerger yesterday, Oxford Pharmascience (LON:OXP) has become Alba, with the (re-used) ticker ABA. It's now a cash shell (which I hold). I hope it announces that it's moving into blockchain next week!
Stockopedia hasn't updated for the new name yet. It's going to be a pain transferring the portfolio data across if it isn't automatic.
Consistent with tradition, one company, this year Real Good Food (LON:RGD), has issued a real stinker of an RNS after the market closed on the last business day before Christmas, to wit...
https://www.investegate.co.uk/real-good-food-plc--rgd-/rns/interim-results-further-funding/201712221304532630A/
I see from the trading statement issued on 23-Oct-17, they had previously guided that results would be issued in early December...
https://www.investegate.co.uk/real-good-food-plc/rns/trading-statement/201710230700042722U/
So everything is going to plan at the company.
Bah Humbug. Cheers, Martin
Real Good Food (LON:RGD)
Well-spotted, Martin! Thanks.
Naughty!
graham, here's a bit of light christmas humor & only because I caught your quote 'For example, it's not easy to sell air in normal conditions and at normal altitudes. It has an infinite supply in normal conditions, so even though it's useful, it has no economic value.'
http://www.independent.co.uk/news/uk/home-news/man-sells-british-fresh-air-to-wealthy-chinese-elite-for-80-a-jar-a6857461.html
Haha, thanks for that tic_tac_toe! G
Many thanks to Paul and Graham for the brilliant Smaal Cap Value Reports. High quality analysis and it must take ages to do. You’ve helped your readers find some very big winners including BOO HOO at just 35p and equally useful enable us to avoid losers too. E.g might well have bought a few KOOVS but for reading Paul’s comments.
These reports should be a must read for Fund Managers too. E.g Would Neil Woodford have bought so heavily in to some of his big losers if reading your updates? Or if using Stockopedia?
Stockopedia is far and away the best investment tool I’ve ever found.
Also comments here are such good quality too ncluding Mr Contrarian’s daily updates.
Mobile Streams (LON:MOS) - it's a total punt, in my view. I hold personally, and in BMUS. Not my normal kind of thing at all, so it carries massive risk warnings!!
The upside case is that the company has previously built a profitable mobile games software business, in Argentina. That is still going, but it has withered considerably, due to forex problems to start with, then just general decline.
They're trying to replicate that previous success in India. Will it work? Who knows. Probably not, I would say. However, at the merest inkling that it might be working, this share could be a serious multibagger, as the market cap is so low.
Check out the chart - it's done huge spikes up before, which are very lucrative, if you can time your selling right;
Westminster (LON:WSG) up 63%. I was definitely researching the wrong stock! What about that one our Graham?
Morning all!
There's a profit warning today from Action Hotels (LON:AHCG) (I bailed out some time ago). They don't mention the dividend (which on paper must now be very good) so I would guess that's at risk. Huge debt, and they're now slowing the growth. There might be a time to get back in, but I suspect this isn't it.
There's also an acquisition RNS by Empiric Student Property (LON:ESP). I've never held this one, and hadn't noticed how much the price has fallen over the last few months - it now looks quite interesting. Again there is a massive amount of debt - although at least in this case it's 50% of the MCAP as opposed to AHCG's 625%! I'd appreciate your take on this one.
I did once hold some Mobile Streams (LON:MOS) but gave it up as a lost cause after too many dramatic falls. The promised jam never seemed to get any closer, so I'd be wary of getting involved again.
Thanks Paul & Graham for all the analysis - it's been an interesting year!
I was an early buyer of Empiric Student Property (LON:ESP) but have recently sold out. What I came to realise is that their assets are largely sub-optimal. 60 70 even 100-200 bed units just do not compare with the 400 plus units that the big players hold. This affects not only the net rental stream but also the capital values. By way of comparison (not strictly the same model I know) check out the units that £WJG build. Their understanding of market dynamics far superior to #ESP
I’ve held Mobile Streams (LON:MOS) in small size for a couple of years. Not quite sure why, more in hope than expectation.
It’s a bit of a Don Quixote stock to be honest. Constantly tilting at windmills but rarely finding the target. Their business is a derivative of the telecoms industry (they sell phone apps) and they tend to focus on lesser developed economies. They had some success in Argentina a few years ago that saw the shares spike massively but then struggled to sustain the business and remit the cash out of the country. The next big thing for them is India which is itself going through a highly disrupted period of development making progress slow. Bulls see it as a huge market of boundless promise. Bears as a market where average subscription receipts are likely to be in pennies (well rupiah). Nothing in today’s RNS makes me any the wiser about future prospects.
They still have some cash (topped up by a fundraising via Primary Bid last year) to keep them going for a while but need to get some substantive success in India to keep the show on the road. Shares are quite closely held (Directors have a big holding) and quite illiquid so daily price movements can be dramatic. Shares are also pumped and dumped regularly on some of the bulletin boards (ADVFN is usually good for a chuckle) which further exacerbates the volatility. They could be one “killer app” away from multi bagging but don’t hold your breath. Makes Bitcoin look a bit staid IMO ....
Gus.
Re Mobile Streams (LON:MOS). Gus has said it all really. I held these for a while some time ago during which the CEO sold 6m shares @ 55p - earning more than the market cap is now. I sold later - at a loss. So, I think he's a smart cookie who might repeat his earlier success in Argentina, although I have my doubts. I won't be reinvesting.
I find it very difficult to analyse Mobile Streams (LON:MOS) so would appreciate your understanding on it.
Thanks.
Good morning Graham,
Mobile Streams (LON:MOS) made an AGM statement today. If you can, it'd be great to get your view on it.
cheers
Francis
Thanks for the suggestions, Francis and others. I have covered Mobile Streams (LON:MOS).
Good Morning Graham & chums! I am just starting to research Mobile Streams (LON:MOS) and whilst there is nothing material in their AGM TU it sounds good but wondered if you & others had an opinion? Paul has bought in lightly for BMUS. Cheers!
"AGM Statement
At its Annual General Meeting which is taking place today at 9am at the offices of Grant Thornton UK LLP at Grant Thornton House, 30 Finsbury Square, London, EC2P 2YU, Mobile Streams will provide the following update to its shareholders:
"In India, Mobile Streams is gradually establishing itself in the market by working with the majority of telecom operators and forming relationships and partnerships with a number of the industry's leading players.
Mobile Streams now has direct carrier billing with five of the leading six Indian telecom operators so that it can bill its mobilegaming.com games service conveniently and easily. Four of these connections are live and one is currently in the integration phase.
At an industry level, whilst Reliance Jio's launch in September 2016 was widely expected to shake up the market, the scale of disruption has taken many by surprise. Operator revenues have fallen quarter on quarter across the board and consolidation has taken place (Tata and Telenor are exiting India and Vodafone is merging with Idea). Reliance Jio has now acquired approximately 150m subscribers in 12 months, initially through the free voice, cheap data packages, retained though the ongoing cheap high-speed data connections.
For 2018 and beyond, the Company's primary focus is ensuring that our net revenues exceed our marketing expenses for each of our key relationships and so we are reviewing the way in which we pay for advertising so as to ensure that it is as linked to successful customer acquisitions as possible.
We are also working closely with key players in the industry who have vast experience and a history of success in the Indian market.
In Argentina, revenues have been steady for the past few months. Our current portfolio of products include a HTML5 games portal and glamour and fashion sites among the premium ones, while we keep the legacy applications and content downloading products too, while moving all the base to premium subscriptions to increase our overall revenue shares."
My morning smallcap tweet:
LXB Retail Properties (LON:LXB), Westminster (LON:WSG), LSL Property Services (LON:LSL)
LXB Retail Properties (LXB) sells retail units at Stafford for £35.9m gross (£10.2m net of borrowings) plus leisure property at Stafford for £4.3m net plus contingent £4.8m. Also lettings at Rushden Lakes Sutton. Don't give gain/loss on NAV. I hold.
Westminster Group (WSG) update on its previously announced major long-term project opportunity within the Middle East. "All but a few more minor commercial and contractual issues have now been agreed. Due to the complexity and increasing potential scope of this project, it has now been agreed to undertake the project in phases, with the initial phase expected to be worth approximately €24m PA."
LSL Property Services (LSL) wins multi-year extension to its contract to supply UK residential survey and valuation services to Santander. No value given.
Just to say thank you MrContrarian for your daily blog here. I am sure I speak for many others who also find it useful.