Small Cap Value Report (Fri 23 April 2021) - FUL, PHTM, BOOM, REC

Good morning, it's Paul and Jack here with the final SCVR for this week.
Timing - today's report is now finished.
Agenda -
Paul's section:
Fulham Shore (LON:FUL) - strong trading in first week of re-opening. Upbeat about the future. I like it, but it's looking fully or over-priced.
Photo-me International (LON:PHTM) - a big rise in profit guidance, thanks to a surge in activity in Japan, driven by Govt action. Looks worthy of a closer look, but I still find it impossible to value, due to uncertain long-term outlook for photobooths, and lack of divisional breakdown of other activities.
Audioboom (LON:BOOM) - good revenue growth, but it's only just reached breakeven. >£100m market cap is factoring in a lot more growth. Definitely not my type of investment, but I bounce around ideas as to why it might appeal to speculators in a bull market.
.
Jack's section:
Record (LON:REC) - ongoing fee pressure in core Passive Hedging product but growth in (smaller) higher margin products and good inflow momentum from this outsourced currency manager.
.
Paul's Section
Fulham Shore (LON:FUL)
16.0p (pre market open) - mkt cap £99m
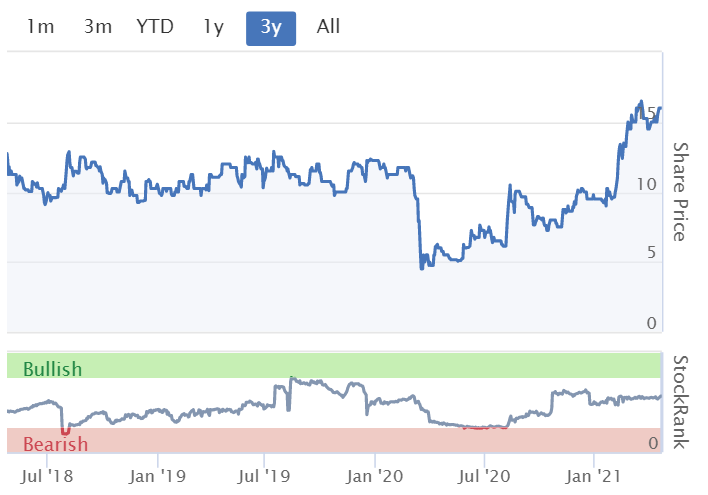
As with so many shares at the moment, I’m very surprised the valuation of FUL has run so high, before it’s even properly re-opened. Yes, it’s likely that the company and other hospitality companies are on the cusp of a bonanza, as newly freed customers want to enjoy eating & drinking socially again. But does that really justify the price now being c.50% higher than before covid? Maybe people think it does, I’m just asking the question, and can’t see it being reasonable myself.
.
I have to laugh, as less than a year ago, I remember quibbling over buying at c.6.5p, thinking it was too expensive! If only I’d had a crystal ball back then.
Re-opening step 2 - for hospitality this meant outside spaces only, happened on 12 April, only 11 days ago. Therefore, FUL giving us an update today, suggests they’ve traded really well - companies are usually eager to get good news out fast, whereas bad news takes longer.
So I’m pretty sure this update is going to be good, without even having read it yet!
The Board of Fulham Shore (the "Board") announces the following update on trading, as well as an update on new restaurant opportunities.
Current operations -
As of today, Fulham Shore has re-opened 70 out of its 72 Franco Manca and The Real Greek restaurants for various combinations of al-fresco dining, delivery and collection services. The restaurants' terraces are operating as much al-fresco dining as possible. Currently, 37 out of the 52 operational Franco Manca pizzeria and 16 out of the 18 operational The Real Greek restaurants have outside tables.
A reminder that FUL has done well from delivery & collection over the pandemic, which could be a reason why the shares have up-rated? Possibly investors might be thinking that the pandemic has made the business better, by developing its takeaway and delivery channels?
First week’s trading - has been excellent, being ahead of the comparator week in 2019 (since 2020 not comparable due to lockdown 1). That’s remarkably good, since no indoor seating was available. It must vary a lot from site to site, e.g. the Real Greek in Bournemouth has a large outside terrace, whereas the Franco Manca in Islington only has about 3 small tables outside on the pavement.
Pent-up demand is very much in evidence, and in my view, likely to increase as the weather becomes warmer -
These trading results were achieved without any inside seating and our colleagues in the restaurants deserve great credit as demand has far exceeded the number of seats available at peak times.
New sites - this could be another reason why FUL shares are expensive - that it is actively seeking out new sites to expand, boosting future profits (if they chose the sites well, and don't over-pay). As we know, and the company has previously indicated, very attractive deals are currently on offer from landlords, desperate to fill empty units. There’s another benefit at the moment too -
Many of the restaurant locations we are seeing are available as a result of insolvency events and, as a result, are typically pre-existing fitted units. Sites of this nature have a lower opening cost to the Group compared to shell units. We therefore expect a reduction in the Group's average capital expenditure per new site in the short term, and that this should improve our return on capital.... The Group continues to be presented with a number of excellent potential retail locations, almost on a daily basis.
They're spoiled for choice, which is a wonderful position to be in. In my experience, retail/hospitality that can expand in times of widespread business failure, often sow the seeds for a highly successful business in the future. Because they can pick up good sites, for a song, in a recession. Landlords often also give long rent-free periods, and capital contributions (reverse premiums), which can make expansion self-funding, i.e. requiring little to no capex once the landlord contributions are netted off.
Outlook -
The Board believes that the next few months may be the most exciting in the Group's short history and looks forward to opening our restaurants fully once permitted and capitalising on the property opportunities that are being presented to us.
I think they are right to be excited. Businesses that have survived the lockdowns intact, and have funding available for expansion, are set for a very buoyant period of trading, in my view.
The game-changer (we hope) is the successful vaccinations programme. The latest UK data on that looked highly encouraging, with less than 3 dozen confirmed cases of vaccinated people being hospitalised from covid, out of 74k between Sep 2020 to Mar 2021. Providing no disastrous mutations occur, then it seems possible we might have seen the last lockdown, but let’s not count our chickens. That’s what the stock market is clearly thinking, otherwise valuations wouldn’t be this high. Plus, the Government is saying that amended vaccines (to take into account mutations) are already being worked on. So it seems likely we’ll get booster jabs in the autumn/winter, and probably as a matter of routine every year in future.
My opinion - it’s all good, and as I’ve mentioned many times here over quite a few years, I really do rate FUL as a decent business, with good restaurant formats that are nicely differentiated (as opposed to the “me too” pizza/pasta offerings from e.g. the Kayes, and others who still seem stuck in the 1990s).
For valuation purposes, I’m increasingly using peak earnings pre-covid as my starting point, then checking for (and adjusting if required) for any dilution during the last year from placings. A higher number of shares, means lower EPS (earnings per share).
FUL did a smallish fundraising, and its share count seems to have gone up from 583m to 619m currently, up about 6%. So 16p per share today, is the same valuation as 17p before the fundraising, not a huge difference. And of course armed with more cash, the business is arguably worth more after a placing.
I think peak earnings valuation method is more reliable than looking at broker forecasts, which still seem to be all over the place. Many brokers seem to be far too pessimistic in recoveries, as they are at the moment, which provides us with some nice opportunities, especially in smaller caps where research is thin on the ground and can be difficult to obtain.
Another way to value shares is on an EBITDA multiple. I was reading a report, suggesting that private equity deals in the hospitality space are typically being done on about 11 times EBITDA. FUL produced £7.8m in EBITDA in its last pre-covid results FY 03/2019, giving £86m enterprise value. The market cap is £99m currently, so allowing for a bit of debt on top of that, EV would be well over £100m currently. However, the valuation just about stacks up if you factor in a year or two’s growth in profits.
Personally, I’m pretty disciplined about my buying prices. Hence I just won’t overpay for anything, which does mean missing some opportunities in a bull market. However, it also means (usually!) avoiding gut-wrenching losses, when valuations reset to more rational levels in a market correction. Value investors don't tend to panic sell in a correction, whereas momentum traders do, because they use stop losses - that makes the corrections worse for the more speculative shares. The 1987 market crash happened because of automated sell orders, for example.
There is scarcity value for hospitality sector shares, which could also explain why prices are high currently.
Who knows where the FUL share price could go? It seems a market driven by optimism, momentum, and speculation. Sooner or later though, that kind of market runs out of steam, then valuations reset to be more driven by fundamentals.
For what it’s worth, I think FUL shares look (at 16p) valued at the top end of what can be justified by fundamentals. If you look at the long-term chart, it has traded sideways for long periods of time, after becoming over-valued in the past, and that's the trouble when you buy after a long rally - you could be buying at or near the top, and then sit on losses for a long time afterwards.
Overall, I really like the fundamentals of this business, but the shares look fully or over-priced to me, hence are not of interest.
.
Photo-me International (LON:PHTM)
69.6p (up 6%, at 09:31) - mkt cap £263m
There’s been a positive market reaction to this update (up 6%), so I’ve moved it up our running order.
Here are my notes previously from March 2021, when I reviewed its FY 10/2020 results & outlook, concluding that it was impossible to value this share because we’re not given a breakdown of performance by division. Also, profit guidance from PHTM of £9m profit before tax (PBT) for FY 10/2021 seemed lacklustre for the valuation.
Photo-Me International plc (PHTM.L), the instant-service equipment group, announces an update on the Group's trading position.
This is for FY 10/2021, and it sounds positive -
In the first five months (ended 31 March 2021) of the 2021 financial year the Group performed better than expected, driven by stronger than anticipated trading momentum in Japan due to an increase in applications for the My Number card, the Japanese government's social security and taxation photo identification card scheme….
Consequently, the Board has revised its expectations for the financial year ending 31 October 2021 and is pleased to announce that it now expects to report revenue of between £190 million to £200 million (previously £175 million) and profit before tax of between £15 million to £19 million before exceptional items (previously £9 million before exceptional items).
Outside of Japan, trading in the period was in line with the Board's expectations. The Group's multi-country restructuring plans to improve profitability are on track to complete at the end of April 2021 and vaccination programmes continue to provide encouragement…
It goes on to say that covid uncertainty continues, and is important because France is “a major contributor to the Group’s results”, plus threats of renewed lockdowns in Japan and Germany. My feeling on that, is that the EU seems to be starting to get its act together, belatedly, with vaccination programmes, according to figures in a recent press article I saw a few days ago. Hence hopefully these issues could be temporary.
My opinion - this is a big upgrade in profit guidance, from £9m previously, to £15-19m today. I think that is good support for a share price that has bounced strongly this year.
My problem remains, that I don’t know how to value this company. In a way, today’s upbeat reinforces that problem - Govt action in Japan has spurred increased activity of PHTM’s photo booths, but how long will that last? Is it temporary, or permanent?
Will the newer activities (laundry machines, bank self-service kiosks, fruit juicing machines) be able to make up for likely long-term decline in photo booths? Might photo booths last longer than we think? So many uncertainties.
Overall then, this is a very nice update today for holders of the shares, with a big increase in guidance.
The long-term chart below is interesting. It had a much higher peak during the tech boom in 1998-2000, when it spiked up to 375p, which is just off the page on the left. I can also remember this share being as low as 10-12p several times. So it has a long history of crashing in price, when people write if off as old economy fag butt type of share. Then it surprises with its resilience & cash generation, and there’s a burst of excitement, it multi-bags, then drifts back down again. Hence I think this is a very nice share for traders, if you are good at market timing!
This time around, could this share have legs up to 100p? I think that looks possible. Especially if it reinstates divis at some point, and if the re-opening news from France is good later this year. The burst of activity in Japan is worth investigating - if that is likely to continue, then it could be happy days for PHTM shareholders.
Overall, it's quite interesting, and more interesting after today’s update, but I still have no idea how to value this share, so declare myself neutral.
.

.
Audioboom (LON:BOOM)
695p (up 5%, at 10:58) - mkt cap £109m
For background, I reviewed AudioBoom’s FY 12/2020 results here. Reading through those notes to refresh my memory, the 2020 figures showed a reduction in losses, and a not very good balance sheet. But the outlook statement did look interesting, with >80% of FY 12/2021’s revenues already booked in with advertisers. Speculative, but not a complete basket case, was my conclusion just over a month ago.
Today’s update - remember this says revenues, not profits (or losses in this case) -
Revenue expected to be significantly ahead of current market forecasts
Audioboom (AIM: BOOM), the leading global podcast company, is pleased to announce that it has continued its strong sales momentum, with signed advertising bookings for the year now representing more than 95% of the recently upwardly revised market forecast for revenue in 2021.
In light of this continued strong trading and the prospects for the months ahead, the Board now expects that Audioboom will generate revenues significantly in excess of the current market expectations for the year and an increased adjusted EBITDA.
That does sound encouraging.
More detail is given, saying that revenues are being driven by content creation. That’s fine, but content costs money to create.
Revised forecasts - many thanks to Allenby for providing us with an update note today. This shows a 10.5% increase in forecast revenues to $41.4m.
Adj EBITDA rises from $51k, to $118k - so it’s more than doubled from diddly squat, to diddly squat. Adj PBT is forecast at $18k - about the same as one person doing a minimum wage job.
It’s valued at over £100m.
OK, it’s not fair to value a company on a breakeven year, the question is whether it can scale up and become profitable in future? Then the company might become valuable. Adj profit of $1.0m is forecast for 2022.
My opinion - Audioboom is now generating meaningful revenue growth, which is clearly good news. But its gross margin is low, so there’s not much operational gearing, which is the bit that makes growth companies exciting.
There are so many podcast platforms, that I don’t think users particularly care which platform a podcast is on, and ads are annoying.
If this is the (long-awaited) start of exponential growth, then this share could get exciting though.
In buoyant stock markets like this, there are lots of new entrants, who open trading accounts, and generally go for growth companies, often story stocks. Because these companies are often loss-making then you don’t have to worry about crunching any numbers, or valuation, and you just buy anything with a good story and a rising chart. There’s nothing wrong with that, in the euphoric bull phase of a market, and people can make a lot of money quickly. The trouble is, when the music stops, it’s a long way down for shares where the fundamentals don't support the share price, once sentiment turns negative.
Hence for me, personally, I tend to avoid this type of share. Having said that, we’re in a lovely euphoric bull market, so there’s money to be made, if you can get out before things collapse, which could be a long time, who knows? A few of these small, speculative companies could do well, longer term, but most don't.
BOOM is now at breakeven, so hopefully it shouldn’t need to raise more equity, or not much % dilution if it does. Therefore it’s a much more sensible-looking share than say a couple of years ago, when it looked doomed to failure.
Overall, it doesn’t appeal to me, but if you buy into the growth story, and think it can become decently profitable in future, then who knows, it could do well? >£100m market cap is already factoring in quite a bit of success though.
This is the type of share where some investors buy a basket of similar shares, knowing that most won’t work too well, but one might become a monster success. A perfectly valid strategy, especially if you can de-risk things by top-slicing on the way up & running the balance at nil cost. Although American stock markets are a much better hunting ground for investors with that approach.
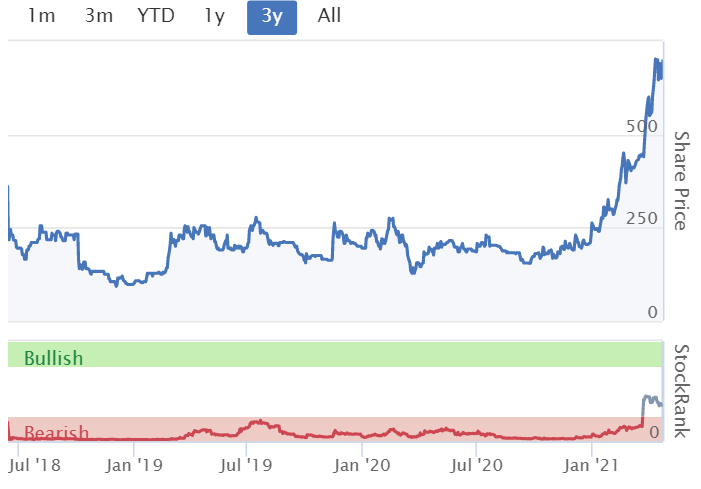
Note the 3-year chart below - the market has clearly decided this share is going places, so well done to holders. Nobody ever went bust by top-slicing a bit, after that kind of move.
.
.
Jack’s section
Record (LON:REC)
Share price: 78.5p (pre-open)
Shares in issue: 199,054,325
Market cap: £156m
Record (LON:REC) is a leading currency and derivatives management firm, with assets under management (AUM) for pension funds, foundations, and other institutional clients worldwide. The group’s services include Bespoke Currency Hedging, Currency for Return, and additional currency solutions and consulting services.
It is notable for its Quality metrics.

The business was established in 1983 by Neil Record who previously worked at the Bank of England. He is currently the chairman and biggest shareholder, with nearly 30% of the business - but he did sell 4m of shares last September, so it’s possible he might be looking to reduce his stake over time.
It has grown over the years by hedging for corporate and institutional clients, with mandates including the world’s first stand-alone currency hedge in 1985. So there is a precedent for innovation there.
Since 2009, it has been diversifying its range of products and services in response to fee pressures in its Passive Hedging segment.
Actual asset management is experiencing margin compression, so I’m curious to see whether an outsourced currency manager occupies a more resilient market position, or if it will end up suffering similar headwinds. It looks like the latter.
The Group has four principal reporting lines:
- Dynamic Hedging, where Record seeks to eliminate the impact of negative currency movements on elements of clients' investment portfolios but participate in the positive movements;
- Passive Hedging, where Record seeks to eliminate fully or partially the economic impact of currency movements;
- Currency for Return, in which Record enters into currency contracts for clients with the objective of generating positive returns; and
- Multi-Product, where the client mandate includes combined hedging and return-seeking objectives.
Fee pressures aside, this does have some of the hallmarks of a quality compounder, due to the high margins, large market, and presence of a founder-owner. It’s also a high Ranking Financials stock that could play a useful role in a diversified portfolio.

The shares have been very strong recently and, as with many stocks at the moment, there has been a strong rerating here. Record was just above 30p back in September 2020 and now it is approaching 80p.
The forecast PEG is just 0.5 though, which is a promising initial sign.
The group reports two distinct periods: the three month Q4 and the twelve month FY21 that this caps off.
AUM grew by 7.4% in the quarter and by 37% for the year to $80.1bn (£58.1bn), including net inflows of US$9.7bn.
In terms of quarterly progression in AUM across the group’s products:
- Dynamic Hedging was up 16.3% to $9.3bn,
- Passive Hedging was up 6.2% to $61.5bn,
- Currency for Return was up 8.3% to $3.9bn,
- Multi-Product was up 6.2% to $5.2bn, and
- Cash & Futures was stable at $0.2bn.
We can see that Passive Hedging strategies are responsible for 76.8% of the total $80.1bn AUM (compared to 77.6% in the preceding quarter). This is where the fee pressure is.
Dynamic Hedging and Multi-Product are higher margin, so a step up in growth here is something to watch out for. And it does look like, over the twelve month period, inflows were encouraging in this regard.
Diversified AUM net inflows in the year of US$2.1bn into Passive Hedging, and across our higher-margin Dynamic Hedging (US$6.6bn) and Multi-Product (US$1.0bn) strategies.
Most of the segments (barring Cash & Futures, again stable at 0.2%) also had quarter-on-quarter inflow growth. Record enjoyed inflows of $4.9bn over this three month period ($3.7bn of which came from Passive Hedging), so it looks like there is healthy demand for its services.
The group closed its Dynamic Macro Currency and Global Macro strategies to focus resources in higher growth opportunities.
Client numbers grew by +17 (24%) to 89 in the twelve months and by +10 in the last quarter alone.
The group has also set up a new EM Sustainable Finance fund, which is expected to launch in the current quarter and will have an initial size between $200m and $500m.
This product has been developed in collaboration with one of the largest wealth managers in Switzerland, and offers higher margins, product diversification benefits. Record intends to actively increase its presence in the fast-growing ESG and sustainable investment market.
Leslie Hill, Chief Executive of Record plc, commented:
Whilst the growth to date has broadly been across our core suite of currency products and services, inflows into our higher-margin products including Dynamic Hedging and Multi-Product have changed the revenue mix, reducing the dominance of our lower-margin Passive Hedging products over which we expect to see continued fee pressure in the future.
Conclusion
There is some succession planning going on but it all looks like it’s being carefully managed ahead of the event.
Can you maintain an edge in forex? That’s a question. At the more passive end of the spectrum business looks tough but this is a huge global market and my initial hunch is that there is scope to continue adding value for more active clients and with innovative products.
This requires an ongoing and significant shift in AUM into higher margin products with a brighter future. If it can continue this shift then there could be an opportunity here, but it will need to attract a lot more AUM in order to really move the dial.
But the group is well positioned with a robust balance sheet, long-standing and strong client relationships, and an experienced team. So if it can seize the opportunity then I imagine this could be an extremely scalable opportunity.
So it’s worth checking out in a little more detail, even after the strong share price run, although at these prices you are now relying much more on future growth than existing value.

Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

42 comments
Open letter from 22 eminent scientists telling the government that we are reaching the point where covid related restrictions should now be ended or if not now in the very near future.
https://www.dailymail.co.uk/news/article-9507449/Scientists-say-vaccines-cut-deaths-98-call-end-restrictions.html
If the unbelievable stat that only 32 of the people who have been hospitalised with covid have been vaccinated (3 week point after first dose) is true then it looks clear cut that the level of danger now posed by covid is orders of magnitude less than it was a few months ago ago. As the vaccine rollout continues this risk should further diminish. Certainly one of the main reasons for lockdown/restrictions that hospitals were overloaded is thankfully at present not the problem it was.
No certainty that this good position will last but it does seem over the top to continue excessive measures beyond the end of may if there is no scientific justification for doing so. I guess the fact the roadmap back to normality - one step at a time doesnt have long to play out means there is little incentive to speed things up.
Hopefully in the meantime as we quietly continue vaccinating people covid issues will continur to trend downward.
After that lets hope that they concentrate on planning for whatever may need to be done to keep the newfly found protection at a level is sufficient to avoid similar problems next winter.
Open letter from 22 eminent scientists telling the government that we are reaching the point where covid related restrictions should now be ended or if not now in the very near future.
There's a notable overlap between these eminent scientists and the people behind the farcical Great Barrington Declaration, who were demanding full reopening last summer and last November. Oddly the Mail article fails to mention their history of failed predictions.
Take India - apparently safe a few weeks ago. Now health services have collapsed and their hospitals are full of under 50's. Funeral pyres in car parks, people dying for want of oyygen ... Watching that, and after all we've been through, why would we risk anything for a few extra weeks of relative freedom?
Quite how we safely open up to overseas travel is another question, the safer it is at home the more problematic that becomes.
timarr
There's a notable overlap between these eminent scientists and the people behind the farcical Great Barrington Declaration, who were demanding full reopening last summer and last November. Oddly the Mail article fails to mention their history of failed predictions.
You may be right that this group of scientists has a biased viewpoint with how we should proceed, as long as the science is presented factually it does at least open the debate. It should obviously be expected that scientists pro lockdown ending previously would remain in the same camp.
If we take the viewpoint that only 32 people who have been vaccinated have ended up in hospital , or even if the number is anything like this total. I think then scientifically speaking this is a complete game changer with regard to where we are at. Mentions about things going wrong last winter appear to be changing the subject completely and harking back to a time we are not at now ! - i see you make no refernce to this positive stat and all your comments are directed at items that could go wrong from here!
Take India - apparently safe a few weeks ago. Now health services have collapsed and their hospitals are full of under 50's. Funeral pyres in car parks, people dying for want of oyygen ... Watching that, and after all we've been through, why would we risk anything for a few extra weeks of relative freedom?
I am in no particular hurry to reopen quicker and save a couple of weeks - all i was doing is pointing out the good success we seem to have had and that the future seems positive.I think your viewpoint that India was safe a few weeks ago is completely different from my viewpoint that any country without close to 50%+increasing vaccination rates is simply not safe - thankfully the uk is not in the same position as india. So you say india was safe - i say india was reasonably likely to suffer a similar fate as we suferred when the new uk variant took hold here.
At some stage we will have to make a decision to either worry about what might happen but is not happening or not worry over worry about these possibilibilites - there are many things that could go badly wrong in the next 6 months but hoepfully none of them will go wrong . If we take the viewpoint that there is no evidence the india variant is more dangerous than other strains to vaccinated people is this reason enough to continue to keep the country under excessive lockdown in the near future ? there will likely be another similar new variant next month AND the month after that and the month after that.
There is a middle ground here that we can open up the uk and try and keep these new variants out - caution is great but i suspect its impossible to keep the genie out the bottle anyway in that regard . So perhaps quickly closing direct travel when new variants emerge (as we did not do!!) and then seeing how the mop flops at least gives us more time before any new variants show up in large numbers. The good news is based on the 32 number and similar data from israel the vaccine seems to be doing a better job than we would ever have hoped for and i have seen no evidence that the new variants are likely to change this position soon - i would say ref india variant we have not had enough time for any meaningful data to come through so the lack of bad news in that regard isnt exactly great news.
It should obviously be expected that scientists pro lockdown ending previously would remain in the same camp.
That suggests to me that these people can't be trusted. Their previous judgements have been flawed and the fact that they repeatedly re-present the same viewpoint without acknowledging their past errors - which would have led to many more deaths had they been acted on (and, indeed, may have been a factor in Johnson not taking action sooner last autumn) - suggests that their viewpoint is primarily ideological rather than scientific.
In terms of the positive data - yes, I agree it's very positive indeed. I'm very optimistic. However, we have two examples of countries that are ahead of us in vaccine deployment that we can use as a partial template.
Israel has taken a careful, data led, approach to re-opening that has included measures to encourage younger people to get vaccinated and now includes vaccine passports if anyone wants to re-enter normal life. The results have been stunningly successful and show that it is possible to move back to something close to normal society on the back of a vaccination program, albeit with border restrictions.
Chile has been rather more cavalier, reopening before their vaccination program had been fully rolled out. Despite that fact that the majority of the supposed at-risk population has been vaccinated at least once they now have a full-blown crisis, with healthcare stretched to its limits and another lockdown required.
Because this is a new disease and we're learning all the time there's always going to be some uncertainty about how to proceed. However, the successful Israeli template is the one we're most closely following while the eminent scientists quoted earlier want something closer to the failed Chilean approach.
Under the circumstances I think both our politicians and their advisors - the real scientists making life and death decisions - can be forgiven for being cautious.
timarr
That suggests to me that these people can't be trusted. Their previous judgements have been flawed and the fact that they repeatedly re-present the same viewpoint without acknowledging their past errors - which would have led to many more deaths had they been acted on (and, indeed, may have been a factor in Johnson not taking action sooner last autumn) - suggests that their viewpoint is primarily ideological rather than scientific.
Amen to that, Tim. You just saved me writing the same paragraph :) These people are like a stopped clock, eventually they may be right but up to now they have been proven totally wrong by real-world events. Like many experts, they can't handle being proven so plainly wrong and their opinions completely discredited.
All the best, Si
Yes the vaccine program seems to have been highly effective in the UK but in other countries which also have been vaccinated to a similar extent are still having problems, look what happened in Chile. USA is still having high numbers of deaths, despite their effective vaccines. Lockdown is ending in the UK soon anyway, pubs and restaurants will probably fully be reopen in May. I think one step at a time is the sensible approach, as then we can see if there is a spike up in cases, what is cause. So far so good but no point in rushing things. No one wants another lockdown.
Would love it if you could look at Sheffield Insulations (LON:SIG). I appreciate it is a mid cap and may not qualify for your attentions.
Happy St George's Day. Find a beer garden and have a pint of English Ale.
$SAM :NYSE Boston Beer Company - appreciate that Stockopedia does not report very much on US quoted shares but this one is worth a look at. First Quarter results out on Thursday night after close were incredible under every metric. Stockopedia is not updated yet but look at report on Yahoo Finance. Interesting to see how breweries in Europe might grow post pandemic. Own this for a while and does not disappoint - share price up over 200% for year.There are lots of hidden gems in the US market which even the screeners on Stockopedia might throw up. This one came to me from rooting around the internet
$SAM:NYSE Agreed. The figures are really impressive – growth in revenue, eps, no debt, cash etc. I got into this last year through the screeners on Stockopedia. “There are lots of hidden gems in the US market..” Not only the US but the rest of Europe.
Thanks Ragusa
I completely agree on your comment on gems listed abroad, so I will certainly check out Boston Beer Company.
On a similar note on foreign-listed firms, I wonder whether anyone would be kind enough to educate me on the various listings of Apple. Please see the below screenshot from Degiro.
My preference is actually to buy in EUR. Is there any risk buying Apple shares listed on XET (Germany) as opposed to the Nasdaq listed shares?
And why is there a listing in Frankfurt too (also Germany)?
Any insight would be much appreciated,
Thanks
A
My broker advised me that if one buys a US equity on a European Exchange that it might not be as liquid and sometimes one cannot get a price quote. The broker recommended generally to buy on US Exchanges.
A few people on here invest in the US markets but this thread is for U.K. small caps.
It’s probably best if you start a new thread about US shares, as it’s probably going to be lost on here.
Sorry did not understand this and not sure how to set up separate thread. Maybe Stockopedia would designate one.
Just go to Discussion Home then create New Post, top right of the screen.
piworld have just published Mercia Asset Management (LON:MERC) event from Tuesday. This showcases Mercia’s team, portfolio companies and an overview of the Group’s recent performance. Led by Mercia’s CEO Dr Mark Payton, this provides insight on the progress that Mercia is making on its three-year strategy. Mark was joined by Martin Glanfield, CFO, Julian Viggars, CIO and Jill Williams, Investment Director. The event includes short presentations from the CEOs of several Mercia investee companies within both its direct investment portfolio and third-party manage funds’ portfolios. At the end there is a short Q&A. Video & podcast.
Next week 1spatial (LON:SPA) are reporting FY results. Management will present as part of their roadshow on Thursday 29.4.21 at 1pm. Register here.
Property Franchise (LON:TPFG) are also reporting FY results. Management will present as part of their roadshow on Wednesday 28.4.21 at 1pm. Register here.
I'm personally unconvinced by PhotoMe's regular assertions that the My Number photo cards in Japan are going to result in a sustained boost to their earnings. Photo Me are just one of a number of photo booth operators in Japan and while the government is trying to incentivise their adoption, the My Number cards are absolutely NOT compulsory. I know because I am a Japanese taxpayer, resident in Tokyo.
Of course, Photo Me may have a long-term future by diversifying into new areas such as laundry, but photo booths are surely going the way of the dinosaurs and when there are so many alternative companies with more obviously sustainable future growth to invest in, a P/E of 13 for Photo Me seems pretty generous.
B2V
The largest shareholder had been buying significant amount of shares over the last 9 months .
Paul - Gear4music Holdings (LON:G4M) I share your view that any 2022 analyst projections appear misleadingly low. I did some analysis a while back when I originally bought the share at circa 350p. I looked at the overall annual market growth pre Covid and applied that to previous year revenues and took the excess as the true uplift related to the Covid lock downs. FY 22 I then assumed similar overall market growth rates from the higher base but stripped out the excess covid related gains.
It appeared to me that even if Gear4music Holdings (LON:G4M) did not outperform overall market growth in this coming year then revenues should still actually be slightly up YoY and given the operational gearing effect EPS closer to 60p.
I may not be completely accurate in my calcs but it did make me wake up to the idea that the 2022 forecasts seemed remarkably off and I can see EPS perhaps being as high as 75-90p by the time we end FY23 but we will see.
Nonetheless 900p share price does feel somewhat miserly given the fragmented nature of the market, the international expansion opportunity, the rising gross margin, the operational gearing and the low %age market share. It's also a long term hold for me despite having risen almost 3*.
Bigblu Broadband (LON:BBB) seems to be well misunderstood and never approaches a reasonable valuation in my view. somewhat irritating. I hold
They already had approx 15p of net cash I think + 84p from the deal announced today means 99p is made up of cash and the rest of the business is thrown in for 20p or valued at about £11m ! that seems phenomenally low for 2 reasons
1) At the price paid for the Quickline business then their 8% residual stake is worth £7m+
2) The ongoing broadband residential business had an EBITDA of £6.2m last year, which you are now basically buying for £4m!
If you put that on between 7 & 10 * EBITDA that would £43m to £62m for the ongoing business or between 75p and 112p, so feels like the true value of the overall business should be somewhere in the region of 160-220p.
Most odd - I think fundamentally its a misunderstood business though. Everyone seems to think the satellite business will be killed by Musks StarLink network without actually realising that Bigblu Broadband (LON:BBB) are a bundler/re-seller of wholesale satellite to retail and are just as likely to buy capacity from StarLink and sell it in their target countries (just as they do with Eutelsat and Avanti). Anyway hopefully value will out shortly.
I'm a former shareholder of Fulham Shore (LON:FUL)
In what was a personal record I held the shares through thick and thin for a sum total of about 5 hours. (Making 0.7% after costs)
I bought on the back of an impressive update on growth back in 2019. It was only after fully unpacking the detail behind the update that I realised their like for like performance was almost certainly down.
It is in this context that I consider today's statement
So just to be clear ; in the first week that the restaurants were open revenues were higher than when they were closed. Okay.The comparison against 2019 is of course more impressive, particularly given they can only thus far utilise outside tables, it does though need to be taken in the context that they have nearly 20% more (open) restaurants now than they did in 2019.
To be fair that is still impressive. I do actually like the business and I can see the case to argue that it is worth more now than it was pre-Covid.
I just can't though bring myself to own shares in a company where I don't think I can trust anything the management says at face value.
Comparisons to 2019: alarm bells went off in my head that it wasn't a like for like comparison. And you're right, they have more branches open now.
Also, the comparison week in 2019, looks like it was Easter week? Or maybe not (hard to tell, they weren't specific in their statement!). So that could have influenced.
In addition, we all know last week was exceptional - many other chains reported as such. So it would have been more surprising if they haven't traded robustly last week.
It would have been easy for Fulham Shore (LON:FUL) management to offer a LfL comparison with 2019, looking at revenues for stores that were open back then and now. But they chose not to. Usually, it is what is left unsaid that tells the story.
Fulham Shore (LON:FUL)
It would have been easy for Fulham Shore (LON:FUL) management to offer a LfL comparison with 2019, looking at revenues for stores that were open back then and now. But they chose not to. Usually, it is what is left unsaid that tells the story.
IMHO these comments are a bit harsh they have only been open 1 week - to me its plainly obvious that the first week will be an outlier in all respects and its not really fair comparing lfl's when presumably over 50% of the seating capacity is not available that would probably be as unfair a lfl as you could get - the numbers speak for themselves plainly enough to me - that this week was a good week - it doesn't really say any more or any less. The number of stores open now and then is well known fact , so anyone who is lazy enough not to do the maths - well that is their problem.
Are they pimping things up here by showing glass rammed full ? possibly ? is that bad for shareholders probably not if shareprice is bouyant with the good vibes ?- to me the company looks perfect candidate to be bought out by a bigger player - or someone with the cash to roll out epansion quicker or someone who simply wnast to gobble up their brand formats that seem to work. I would say at current prices though the stock doesn't interest me.
Re £SAGA - good news that the Government is going to assess the Covid travel status of islands separately from their national country; so eg Madeira and the Azores will likely be Green status irrespective of Portugal's status. Greece is apparently focused on getting people vaccinated in travel hotspot islands. All helpful for getting island hopping cruises on the move again.
I hold
Universe (LON:UNG) - an interesting RNS re 2 board appointments today.
In particular i note Graham Bird joining as an NED. He is ex Gresham House (LON:GHE) and now CEO at Escape Hunt (LON:ESC) which is expanding rapidly into the on-line entertainment/gaming world. i'm assuming that he is 'busy' at Escape Hunt (LON:ESC), so read the NED appointment as either he is collecting some handy salary for an NED role or, more positively, he is willing to put his reputation behind the new CEO at Universe (LON:UNG) and Universe (LON:UNG) having an exciting potential.
disc a nervous holder as i can't yet see chart confirmation of the potential (i.e. knowledgeable buyers backing any potential upside)
Or.... he's doing going to be doing a poor job of being CEO at Escape Hunt (LON:ESC)
Take your pick!
Photo-Me International (LON:PHTM) update today looks encouraging.
Revenues and profits ahead of previous guidance. Perhaps a tempting recovery share, assuming vaccination programmes in the Countries where they operate along with no new mutations resistant to them enable a wider return to normal ahead. I can’t get too excited about laundry machines and never saw one being used in France pre pandemic. Looking forward to reading Paul’s thoughts on PHTM. Stockopedia rating is 93.
An irritation is that on the PHTM stock page the dividend yield is still shown as 13%. The reality is that the dividend was cancelled around a year ago, and there is no immediate intention to resume dividends. There are too many similar examples of incorrect dividend yield figures, some too high, others too low, and some pure fiction. . e.g NAHL hasn’t paid a dividend for a good while, yet the dividend yield is shown as 22%. Figures are no good if they can’t be relied on.
Fascinating share price action today on Photo-me International (LON:PHTM)
Initially jumped higher, almost 10% I think I saw in the morning, before drifting steadily back down throughout the day, and ending just negative.
One thing to watch is the chairman - he likes to buy after announcements, and has been steadily accumulating. His buys over the past year is quite impressive.
@ dahokolomoki - Why did the SP have such a reaction? Rather strange given the positive news...or was the news already anticipated by the market?
Here's your weekend viewing. The first of a piworld series with Edmund Shing, Introducing your kids (or anyone!) to investing. The fascinating Rule of 72, which illustrates how quickly you double your money. Divide 72 by the percentage growth you achieve over the year, which gives the number or years you'll take to double your capital. If 10% pa, 7.2 years, if 20% just 3.6 years. How can you not afford to invest? Here Edmund covers some of the basics, with more detail to follow in later episodes. As always Edmund is thoroughly entertaining and wise. Video & podcast.
Excellent chat. Must try and introduce my boys to this. I gave them a copy of Moos Law and Naked Trader to digest recently. The youngest is dabbling a bit and funnily enough invested in Gamestop before the Robin Hood lot arrived so did quite well, sold half, runs the rest for free clever lad. Also like to thank Ed for bringing ETF FOGB to my attention which I opted for over ANIC in the end. Clearly the new food production revolution is going to be massively important in coming years both as an investment but more importantly to animal kind. I can't bring myself to pay 4.5 X NAV for Anic. Might be short sighted and still monitor with interest. Yes discipline over mathematics very good advice.
Novacyt issued an optimistic RNS today entitled "R&D and UK operational update":
https://www.stockopedia.com/share-prices/novacyt-sa-LON:NCYT/news/novacyt-sa-rampd-and-uk-operational-update-urn:newsml:reuters.com:20210423:nRSW3778Wa/
Novacyt SA (LON:NCYT) The market likes it, shares are up 18% at the moment.
Although I would like more clarity on the NHS contracts, following a profit warning only 2 weeks ago. Some figures would be useful.
Hi Paul, on Wednesday you spoke about highly geared positions. Is this when you keep buying shares in a company as the price goes up?
TIA
Tony
Morning Tony,
Hi Paul, on Wednesday you spoke about highly geared positions. Is this when you keep buying shares in a company as the price goes up?
Sorry, no when I referred to gearing, I meant using CFDs or Spread Bets, which personally I use for part of my portfolio. The gearing occurs because the gross market value of my positions is larger than the cash I've provided to the CFD/SB provider. Hence rises or falls in share prices are exaggerated by the gearing (borrowings effectively).
It's much safer not to use gearing at all.
Regards, Paul.
Thanks for your reply.
Hi Paul, on Wednesday you spoke about highly geared positions. Is this when you keep buying shares in a company as the price goes up?
"Gearing" is share speak for buying using debt - it's a measure of financial leverage.
It's the same effect as with a mortgage. If you buy a house for £200,000 with a £100,000 mortgage you are 100% geared.
Gearing with shares is usually done with CFDs or Spreadbets, as Paul indicates. It's extremely risky for anyone who doesn't know what they're doing because unlike mortgages the companies running these can call in your debts at the worst possible moments, so you are forced to sell at a loss.
Gearing can dramatically multiply your returns but can also completely wipe you out.
timarr
Thank you Timarr .... thats a great help!
”Gearing can dramatically multiply your returns but can also completely wipe you out.”
And more frequently does the latter than the former.
Full disclosure never used leverage and never will, mainly because, in Tim’s words, I don’t what I am doing.
And may I add from personal experience, you never know what the market is going to do - remember the "flash crash"? - I had a big spreadbet on Bank of America, and went from a £10k paper profit to a £12k loss in 1 minute. I was physically sick. Lesson painfully learned.
My morning smallcap tweet: Photo-Me guidance a picture
AEW UK REIT (LON:AEWU) Supply@Me Capital (LON:SYME) £MRIT Bigblu Broadband (LON:BBB) Fulham Shore (LON:FUL) Sealand Capital Galaxy (LON:SCGL) Photo-Me International (LON:PHTM) Watchstone (LON:WTG) E-Therapeutics (LON:ETX) LSL Property Services (LON:LSL) Record (LON:REC) Audioboom (LON:BOOM), XPS Pensions (LON:XPS)
AEW UK REIT (AEWU) wins cases for unpaid rent totalling £602k. [SP=92 Cap=146m]
Supply @ME Capital (SYME) delays FY(Dec) accounts to May. [SP=0.42 Cap=124m]
Merit (MRIT) name change from Dods effective today. [SP=NA Cap=NA]. I'm short.
Bigblu Broadband (BBB) to sell holding in Quickline for up to £48.6m (84p/sh). £10.1m iscontingent and £5.6m loan notes. Price is up to 5.8x investment. Co will review the steps needed to return any surplus cash to shareholders within this FY and also consider investment opportunities. [SP=110 Cap=63m]
Fulham Shore (FUL) sales (without any inside seating) in the week ended Sunday ahead of same week two years ago. Planning expansion. [SP=16.18 Cap=100m]
Sealand Capital Galaxy (SCGL) wins contract worth HKD 2m (£186k). [SP=1.6 Cap=8m]
Photo-Me (PHTM) ups FY(Oct) guidance to rev of £190-200m (from £175m) and pretax (before exceptionals) £15-19m from £9m. [SP=65.6 Cap=248m]
Watchstone (WTG) plans move to Aquis exchange when suspended from AIM due to cash-shell rules. Co "intends to make further cash returns to shareholders as appropriate as its litigation assets are resolved and will continue to consider other commercial opportunities." [SP=52.34 Cap=24m]
e-Therapeutics (ETX) to receive two key milestone payments from Galapagos after meeting operational and success-based milestones. No £££. [SP=18.91 Cap=80m]
LSL Property Services (LSL) JV with Pollen Street Capital to create a new mortgage broker. LSL has committed up to £33.5m and PSC up to £62.4m to support acquisitions. [SP=336 Cap=353m]
Record (REC) Assets under management equivalents up 37% [SP=77.71 Cap=155m]
Audioboom (BOOM) guides FY rev significantly ahead of current market forecasts. No figs. [SP=660 Cap=104m]
In line: XPS Pensions (LON:XPS)
Interesting announcement from remote broadband provider Bigblu Broadband (LON:BBB) with the disposal of their holding in Quickline.
https://www.investegate.co.uk/...
Worth up to 84p per share (vs. CSP of about 108p) with a residual interest carry being retained so material in the context of the overall valuation of the company. Seem to be operating a “buy, build and sell” strategy (this is their second significant divestment). I hold.
Gus