Small Cap Value Report (Fri 25 Oct 2019) - BEG, CCR, VNET, GOCO

Good morning!
Company news is dead today so let's circle back and look at a few miscellanous things from earlier in the week.
In the end, I covered:
- Begbies Traynor (LON:BEG) (today's news)
- C&C (LON:CCR)
- Vianet (LON:VNET)
- Goco (LON:GOCO)
Begbies Traynor (LON:BEG)
- Share price: 87.8p (+3%)
- No. of shares: 126 million
- Market cap: £111 million
Another acquisition by inslolvency practitioner Begbies, hot on the heels of the one on Monday which I commented on.
Monday's target was a business agent, Ernest Wilson.
Today's target is ALJ, a London-based "insolvency and business recovery practice." Would it be fair to think of it as a "mini-Begbies"?
Here is its website. There are 23 individuals on the "Our people" page.
Terms
The price is £2.35 million up front (mostly cash), and then another £4 million in defcon over five years. Max defcon will only be paid "in the event of significant growth.
Comparison to earnings: ALJ earnied PBT of £0.9 million in the most recent financial year.
CEO comment
"This acquisition is in line with our strategy to increase the scale and market share of our market-leading insolvency practice."
Outlook
Since July, Begbies has raised £8.3 million in a placing and acquired three companies. Begbies thinks that the aggregate impact of these actions will be earnings enhancing, both in the current financial year (FY April 2020) and in future years.
My view
Begbies is picking up companies on the cheap - good news for shareholders.
I don't think this acquisition will change anybody's view. It's a continuation of the existing strategy.
So if you are comfortable investing in this sector and/or you think that the economy is going provide a lot of work for insolvency practitioners in the next few years, then this share could be of interest.
I continue to view this share as an interesting hedge against recession.
It gets rated as a High Flyer by the algorithms.
C&C (LON:CCR)
- Share price: 377p (-0.4%)
- No. of shares: 311 million
- Market cap: £1,173 million
Half-year Report (yesterday)
Please note that I have a long position in C&C.
A quick warning that the algorithms can't handle this share right now. It recently cancelled its listing in Dublin, and changed the denomination of its shares from euros to pounds. This has made statistical analysis go haywire.
It's obviously too big to be covered in this report. But I own shares in it and it's a quiet afternoon, so let's take a look! It's smaller than Tesla, after all.
Background
C&C (formerly Cantrell & Cochrane) owns a wide range of drinks brands. The flagship brands are Bulmers cider (in Ireland, known as Magners in the UK), and Tennent's Scottish beer. It also has a wide range of craft brands, local brands, wines and soft drinks
And it has very significant capabilities in drinks wholesaling and distribution.
Those of you who've been here for a while will remember that I was outspoken on the topic of the late Conviviality (CVR) and its disastrous acquisition spree.
One of the triggers for me to keep a closer eye on C&C was noticing that it picked up Matthew Clark and Bibendum for almost nothing from the carcass of Conviviality.
While those aren't high-quality businesses, they do have some value for investors and buying them out of administration looks like a tactical, opportunistic decision by C&C.
Results
While the CCR share price is a little soft today, it reacted well to these results yesterday.
Some of the things I liked from the RNS:
- Matthew Clark: The key performance indicator OTIF (on-time in-full, measuring whether customers get what they want, when they want it) at has improved from 64% at acquisition to 96% now. What an amazing improvement! Another KPI, "Availability", has improved from 42% to 98%!
- Group H1 operating profit +9% to €64 million (excluding IFRS 16).
- Group like-for-like adjusted diluted EPS up 5.8%.
- Free cash flow of €80.6 million, using the company's own calculation method. The cash flow statement shows €91 million in after-tax operating cash flow, offset by small investing outflows.
- Net debt reduces to €255 million (excluding the impact of IFRS 16), compared to €279 million a year ago.
The core drinks brands are mature and their net revenue growth, as you would expect: +2.7% in Great Britain (despite declining volumes) and minus 3.1% in Ireland (mostly driven by price and mix effects).
Weather and the World Cup were a big help in 2018, making for tough comparators this year. Hopefully Euro 2020 will help to boost next year!
Dividends - there is a small increase in the interim dividend, to 5.5 cents per share.
Buybacks - the company, through its broker, buys back its own shares, to offset the dilution of scrip dividends. €11 million was invested in this way, and the shares bought back were cancelled. I'm not a big fan of scrip dividend schemes, but this is a reasonable way to manage them.
FTSE - thanks to the cancellation of its Dublin listing and the change in the share price denomination, CCR will be eligible for inclusion in the FTSE-250. This will help to drive awareness among investors, and could bring passive investors in, too.
My view
It's a very detailed RNS but I think the big-picture view is absolutely fine.
The core brands are holding up well, despite the long alcoholic drinks market declining in both the UK and Ireland. Market share performance is mixed but mostly stable.
Meanwhile, the acquired distribution companies are seeing their performance improve and are making a meaningful contribution to operating profit.
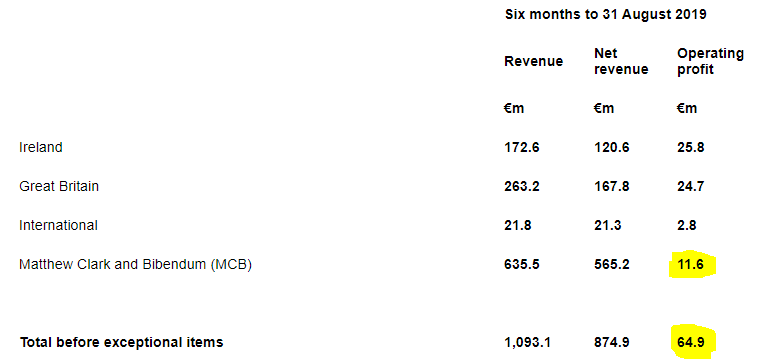
You can see the contribution of Matthew Clark and Bibendum in the table below. CCR wants their operating margin to improve from 2% to 3%, which would be another very nice boost to Group profits (the numbers below are after the introduction of IFRS 16):
Net debt has been a little on the high side, and that's one of the reasons I kept this to a very small percentage of my portfolio.
Thankfully, there are signs of progress on that front. I wouldn't mind seeing a continued reduction in leverage from here. Net debt of €255 million compares with forecast EBIT in the current financial year of €117 million - not too scary.
The market cap is equivalent to about €1,350 million, while annual net income is planned to increase to about €100 million over the next two years.
So while I'm not expecting this share to be a multi-bagger, I do think it offers plenty of value and without too much risk.
The cider brands and Tennent's are two strong franchises, in my view. Craft beers (e.g. 5 Lamps) and wines offer some diversification, and the distribution businesses might be further improved under the responsible stewardship of C&C.
So I think there's a lot to like, and I'm happy for this to be a small component of my portfolio. I might bump it up to a bigger size on additional study or if prospects further improve.
Vianet (LON:VNET)
- Share price: 137p (+3%)
- No. of shares: 28.5 million
- Market cap: £39 million
Trading Update (Tuesday)
This is a "provider of actionable data and business insight through devices connected to its Internet of Things ("IOT") platform".
This PLC has been around for a while - since 2006.
At its heart is the Brulines business, which records the volume of liquid that passes through beer lines.
Trading in H1 is in line with expectations.
CEO comment
The team has continued to make very good commercial progress, particularly with contract wins for our telemetry and payment solutions in the coffee vending and unattended retail vending market, with solid support from our Smart Zones business which is developing new revenue lines. Double digit growth in the period builds on our successful recent track record and further demonstrates that the strategy of leveraging the power of our cutting edge technology to bring game changing business insight to our customers has exciting prospects."
My view
I've just spent some time on the company's website and checking its most recent annual report. I'm very excited by what I've read.
See its investor relations website.
I wanted to remind myself which of its divisions did the beer monitoring, which I understood to be the activity responsible for most of its historical (and present?) profitability.
I was presented with two divisions: Smart Machines and Smart Zones.
Smart Machines:
Hmm. Where's the beer monitoring?
Maybe it's in Smart Zones:
Cloud-based, big data in the Internet of Things. Sounds like the perfect investment, doesn't it?
There is a reference to flow monitoring in the description of Smart Machines, so I guess this must be it.
Ah yes, iDraught:
Another investor keyword: "ecosytem".
So Vianet provides cloud-based, Big Data ecosystems in the Internet of Things.
That's almost everything that I'm looking for in an investment, but I also look for "software as a service".
Alas, I could find no reference to "Saas" on Vianet's website.
It took a little bit of digging but, thankfully, I was able to find a reference to SaaS on vianetplc.com.
Its "Statement of Compliance with the Corporate Governance Code", published last year, dutifully informs us that the company's Directors have the necessary "skills and experience, including in the areas of IOT, b2b, software as a service..."
Boom!
Vianet makes cloud-based, Big Data, software-as-a-service ecosystems in the Internet of Things.
If only it could apply itself to a hot sector like crypto or cannabis, then who could resist investing in it?
My actual view
Vianet looks fairly valued at 14x forward earnings: it has a stable beer monitoring business which is performing ok (even though pubs in general are doing poorly) and other activities which are growing more quickly from a low base.
"Smart Machines" (the growing part of the business) made PBT of nearly £1 million last year. Excluding the acquisition it made, profits in this division were £560k and revenue growth was 42%. Has potential.
Goco (LON:GOCO)
- Share price: 99.4p (+1%)
- No. of shares: 418.5 million
- Market cap: £416 million
Refinancing of Group Debt Facilities
(Please note that I have a long position in GOCO.)
Goco has a credit facility: a 4-year RCF for £105 million, and 4-year term loan for £15 million.
The leverage covenant moves from 2.5x adjusted EBITDA to 3.0x adjusted EBITDA, signalling the banks are comfortable with the stability of the business.
CFO comment:
"The agreement secures an increased and more flexible facility, providing the Group with capacity to deliver against its strategy of accelerating the customer numbers in its AutoSave business whilst maintaining a disciplined cost of customer acquisition.
"I am pleased that we have been able to agree attractive terms with the banks and that they are supportive of our strategy, which we believe will lead to a significantly higher EBITDA margin profile for GoCo Group and be transformative to Group earnings by 2022."
My view
This has been another pleasant holding and I'm glad the banks are supportive. The next task will be to use this facility responsibly and carefully.
Net debt was last reported at £70 million. EBIT is forecast to be £27 million this year, rising to £33 million next year.
Much like with Britvic, I wouldn't mind seeing Goco paying off its debts, but I'm also not overly worried by the existing debt load, relative to the company's profitability.
More customers are signing up for the automatic switching products (I like to call it price comparison-as-a-service), and this could help to boost revenue visibility. And Goco's track record is already pretty good, when it comes to the consistency of profitability. I think it makes good sense that banks would want to lend to it!
Happy to continue holding this one, and there is a chance I could increase position size.
StockRanks are neutral on it - it's held back by the fact that it has negative NAV. This means that P/BV, P/TBV and ROE can't be calculated.
It has negative NAV, and tangible net asset value (NTAV) is deeply negative at minus £75 million.
This doesn't bother me very much, because it's a collection of price comparison websites and services - what tangible assets does it really need? All I care about is that it's profitable and can manage its debt load.
Out of time for today, but thanks for dropping by as always. Have a great weekend - you'll be back in Paul's capable hands next week.
Cheers
Graham
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

26 comments
Hi Graham,
I've met management of Vianet (LON:VNET) a few times over the years.
The Chairman, James Dickson, was originally very prickly, almost hostile towards private investors (when I rang up & asked to meet with him). In the end, he relented, and I met him with David Stredder, at the Institute of Directors. I laid on some nice sandwiches & coffee in one of their ornate meeting rooms, and he began to relax with us.
After that, David Stredder persuaded him to present at Mello Beckenham one evening. I recall trying to ply him with lager beforehand, so that he'd speak more freely, but he refused. Then relented, and said "go on, but I'll just have a half!"
He went on to give a refreshingly frank description of the business, and answered questions very openly. I probably shouldn't repeat this, but I will. When asked why some of their acquisitions hadn't really performed very well, he replied, "Because we bought a lot of dogs!"
This was a long time ago, I should add, and Vianet has since disposed of the petrol stations business, which was a complete waste of time.
So the Chairman's a good egg. Although this very positive commentary in previous years, about the brilliant prospects for the business (e.g. USA growth, iDraught, etc) has basically come to nothing.
More recently, I thought the CEO Stewart Darling, seemed a safe pair of hands.
The CFO, Mark Foster is a complete jerk. In a meeting a couple of years ago, he sat semi-sideways on his chair, looking away from me, looking out of the window, and answering questions with a disdainful, exasperated tone. I thought to myself, who the hell does this arrogant twerp think he is?
I had a list of questions supplied by readers here. One question asked whether the "internet of things" was all just window-dressing, to glamorise a rather stale, declining business (Brulines)? The cocky CFO sniffed, and replied, "If that's what your blog readers think, then tell them not to bother buying our shares!" - or something along those lines. What an idiot!
Other than that, Vianet shares have done OK over the last few years. Plus if you add on the static 5.7p p.a. divi, the overall shareholder return has been reasonably good.
Regards, Paul.
Vianet (LON:VNET)
Now there is a proper Friday bonus - an excellent and witty write up by Graham and an awesome "did he really say that" insight from Paul.
Proper quality!
I can only add that reading Graham's piece I had my first proper chuckle when I got down to "I'm very excited by what I've read." As I am sure I have noted in response to previous company announcements, the management seem to live in a constant state of excitement (for the future). They were a little muted this week, only managing to note that Smart Zones "has exciting prospects".
Should the lack of further ebullience be a sell signal?
FWIW - I no longer hold, but may well buy back in the future and in defence of the BS - of all of the companies that prattle on about IoT, they are actually doing it.
Vianet (LON:VNET) would have to have an incredible business for me to disregard the BS & invest. I believe they still do beer monitoring and vending machines.
I use one of their "Vendman" machines in Milton Keynes library about once a week which does quite a nice proper coffee from real beans.
However, it takes my money and fails to serve the coffee about 25% of the time, so I have to get the staff to it. If this were a truly "smart machine", it would work >99% of the time and actually refund my money if a coffee wasn't served up.
Also, apparently the manufacturers don't know how to fix it. Now you think a "smart machine" would have a good diagnostic log for them to diagnose the problem.
Since I get the problem about 25% of the time, they should also be able to reproduce it and fix the issue.
Last time I looked a their reporting, earlier in the year, apparently they were doing well selling vending machines for contactless payment.
Thanks for looking at Vianet (LON:VNET) Graham - made me smile also. Of course, they might not live up to the hype OR they could be in the middle of a genuine transformation. With a 4% divi, underpinned by the legacy business, I quite like the risk/reward. It will be interesting to see how this one pans out.
Thanks for covering Vianet (LON:VNET) Graham. I enjoyed your Sarcasm as a Service!
Your Vianet (LON:VNET) review made me smile, Graham!
I was reading along thinking "well this doesn't sound like the Graham I know, but let's go with it" until I got to this and realised you were teasing us.
I held Vianet a few years ago when it looked as though they might be breaking into the US market and sold at break-even when that did not happen. It's a well-run business but struggling to break free from its legacy in the pub trade, in my view.
I agree Edward Vianet (LON:VNET) is interesting and is a relatively new addition to my own portfolio. There is lots to like such as recurring revenues, mix of mature business and growth potential (the latest research note on Research Tree is worth a read in relation to the opportunity), quite defensive, reasonably priced and paying a decent divi. It will be interesting to see what Graham makes of it.
Cheers
Simon
I'm interested to see what you think of Vianet. I think it's an interesting combination of a mature business (flow monitoring in pubs) with one that has real growth potential (vending machines, which are being converted to contactless payment systems). Very high % of recurring revenue from both businesses.
Also would like to see the Vianet (LON:VNET) write up. Moving to a subscriber based model for me is the gamechanger - recurring yearly revenues is always a good model, assuming that you dont get undercut.
Videos
1. ECSC (LON:ECSC)
Presentation at ShareSoc October 19.
A good overview of the business by Ian Mann, CEO & Founder. And a useful insight into the general cyber security market.
2. Instem (LON:INS)
Here's the Instem investor presentation by Phil Reason, CEO, given at the piworld-Progressive Equity Research event in September. Phil was over for the H1 19 results, (normally he's in the US).
A very comprehensive overview of the different parts of the business, and a positive outlook.
Interesting news today from the murky world of sub-prime lending. Market leader QuickQuid has announced it will be leaving the UK market, joining a lengthening exist list of deep sub-prime short term lenders to exit eg Money Shop and several smaller players.
Demand has not gone so this makes the market better for the remaining players with more regulatory friendly business models and better lending practice histories/impairment rates. Companies like MCL/NSF/HAT.
Non-standard Finance (LON:NSF) remain over 1/3 down (<40 vs >60p) vs their level in Feb 19 ie prior to their attempted takeover of PFG . They last week parted company with the CEO of the largest and most valuable part of the business (EDL) who was also a co-founder of the group. There has also been no news about the re-financing they want/need. However, IMHO their 3 underlying businesses continue to do well and they now offer a >10% yield and . New financing a potential catalayst for re-appraisal - up if got or down if accompanied by an equity raise which is lkely by my estimation. High risk but potentially high reward medium term.
Morses Club (LON:MCL) are down by a similar amount after reporting larger than expected losses in the short run from adding digital lending and banking services through acquisition to their profitable and steady doorstep lending base.
I hold both and see their issues as relatively limited and short term. I see all financial stocks as currently unloved, especially non-standard ones but I expect them both to hold up well in the medium term especially if the economy stagnates or turns down. As you can guess, I hold both.
Graham,
Your thoughts on Goco (LON:GOCO) would be interesting. Clearly the market scented an opportunity last month when they announced rapidly exceeding their previously announced targets for signing up "flippers" - people who will outsource the boring/administratively intense job of shifting utility provider to someone they trust to "AutoSave" better pricing , potentially worth £000's on energy alone to the 4 in 5 who do not switch providers every year.
"GoCo Group plc ('the Group' or 'GoCo') today announces that its AutoSave business has in excess of 220,000 live customers, an increase of c.28% since the 8th July and surpasses the previous guidance to grow customers by at least 25% by 31st December 2019." Sept 26th 2019
I myself have now gone from the MoneySavingExpert Energy Club who simply advises of better deals to this new service as an experiment. Obviously "Autosave" could long term expand to many other utilities like Broadband & Insurance.
Personally, as an ex P&G marketeer, I like the boldness of creating and investing in new dedicated brands (WeFlip,/LookAfterMyBills) to address specific, research-identified consumer segments of the market. ( See Flummoxed Fretters ("it's too hard to change") & Busy Bystander ("I've no No Time to manage change") in their excellent capital markets presentation of 21st March on the GoCo website). This compares to the cheaper, lower risk but ultimately more restrictive route of brand extending (eg Auto-Sergei from Compare-the market).
I also like their focus on margin and developing a distinctive USP in their comparison site business to generate more cash to put back in marketing for the potentially "transformative" new Autosave businesses.
I therefore think GOCO have an excellent "investor story" for 2020 brewing here as the the product concept is surely going to be a long term winner and GoCo have a chance to be the "first" to have big visible brands addressing the opportunity. However, I think if they succeed too much then then utilities will simply start giving better service/discounts to existing customers - ultimately fair & rationale - and competitors will come in as on comparison websites. This will crush the money available to 3rd parties for introducing switchers.
Unusually, I am therefore in on a trading basis here, hoping for a short term bounce and to exit at the right time. Recipe for for disaster then! Do you see a long term opportunity?
Does anyone have a view on Concepta (LON:CPT)? Potentially huge market for fertility tracking product but they don't seem to be converting to significant sales yet.
Looks like a complete and utter Sucker stock. Last time I saw anything with that many Red Flags it was a British Red Tractor Flag on a nice steak I was buying. Don't waste your time on rubbish is my view.
Concepta (LON:CPT) I'm quite interested in this one. It's a good story, it has improving figures and looks as if it is about to become profitable. But it also has a history of mis-steps and is a one trick pony (at the moment) in terms of the product. So it all comes down to whether you have confidence in the management. I'm waiting!
Good morning Graham
It would be good to hear your thoughts on Synthomer Synthomer (LON:SYNT)
I would be surprised if Graham comments on Synthomer (LON:SYNT) owing to its size.
The current markets, and outlook for 2020, both look very challenging for the company, and the interims were very mixed with Q2 making up some lost ground for a Q1. I would be surprised if there is much to move the price upwards in the short term, even though a current PER of less than 10 is undemanding in itself. The price has almost halved in 13 months, which isn't great.
Good point Andrea, I forgot it was called 'Small Cap Value...'
They reported an update today... challenging trading especially in Europe... and hinted at further downturn if things weren't turned around by the end of the year...
Down 10% today and I have sold out at a modest loss. Worth another look though when it bottoms out because this is a company which is going through a transformation. They made a transformational acquisition earlier this year and have brought in a new management team of former Ineos Directors to head up the transformation.
Graham's probably too modest to mention that there is commentary on today's trading update from Synthomer (LON:SYNT) on his website: -
https://cube.investments/cube-midcap-report-fri-25-oct-macro-worries-spill-profits-at-synthomer-synt-wpp-barc/
Morning Graham. As it's a quiet day I wondered if you might be able to circle back around and take a look at Vianet (LON:VNET) which issued a fairly positive trading update on Tuesday. I know you're sceptical when IoT gets bandied around but in this case it seems fairly justified with them having a quarter of a million remote devices reporting data to them daily. They have 85% recurring revenue and the valuation seems fairly sensible to me. The proposition that vending machines will become more lucrative as they migrate to contactless payments and real time reporting seems plausible and I've followed (and held) this for a couple of years now and they seem to be ticking along nicely and somewhat under the radar. This week's update was an inline, optimistic update "..first half .. has been strong, with revenue and operating profit growth in line with market expectations." I'd be interested if anybody has any experience in the sector or any insights? Stocko loves it with a 95 Super Stock rating. Many thanks.
Good idea John, I'll take a look! G
Re Vianet (LON:VNET) - I held for several years but eventually sold out. The business has been cleaned up, simplified and focused on IoT but ultimately the majority of profit still comes from the historic but declining UK Brulines pub drink monitoring business that has never really kicked on elsewhere (the States was once going to be big). Equally, the vending segment has promised great things for many years.
But in the end, when you look back, the total company revenue and profit are lower than they were 5 years ago. Put another way 250,000+ connected machines do not seem to generate much revenue once the the income/profit from 1260 pubs with IDraught beerline monitoring is stripped out.
I think the same will be largely true in another 5 years.
I have held since 2004 and have bought 15 times between 60p and 104p - it's perfomance has been very dull it seems to trade in a range of 110 to current levels which are top end and not do much more - however generous dividends of around 4.5% which have always been paid, fuel business was sold and clearly a change of direction taken into vending and away from pubs and fuel which is sensible in my view. Main issues I have is the CEO has always refused to take my phone calls which I object to as have a significant holding although he often buys the shares and is a big holder. I don't think it will ever shoot the lights out but equally it is highly unlikely to go belly up so a good plodder but maybe a re-rating could be on the cards if the business starts to motor forwards.
Quiet day.
Begbies Traynor (LON:BEG)
Another acquisition which looks like an excellent fit and good value. They seem to have more-or-less spent the proceeds of the recent fundraising. I do find it strange that insolvency practitioners want to sell out at this stage of the cycle - perhaps it's just a scale issue in competing with the big accountancy firms.
Phil
Edward, I think it is probably the structure of the sales in this sector. They tend to have a high proportion of future earnings tied to final payment.
My morning smallcap tweet:
Concepta (LON:CPT), Vivo Energy (LON:VVO), Essentra (LON:ESNT)
Concepta (CPT) CFO resigns, replaced. She is thanked.
In line: Vivo Energy (LON:VVO), £ESNT