Small Cap Value Report (Mon 21 Oct 2019) - BON, BVXP, MIND, BEG, TRI, ANG, WTG

Good morning!
Today I'm looking at:
- Bonmarche Holdings (LON:BON) (in administration)
- Bioventix (LON:BVXP)
- Mind Gym (LON:MIND)
- Begbies Traynor (LON:BEG)
- Trifast (LON:TRI)
- Angling Direct (LON:ANG)
- Watchstone (LON:WTG)
Bonmarche (BON)
There is going to be a lot of politics today, to distract us from the markets.
One story where I'd like to add a footnote is Bonmarche, which is now in administration.
Paul and I covered this stock many times over the years - see the archives.
In September 2018, I noted that it was "cheap on conventional metrics" and "could be worth a look, as a contrarian play", while also noting that the company had no plans to reduce its large porfolio of more than 300 stores. This stance I described as "complacent".
Things went from bad to worse since then, and I grew increasingly wary of the company's outlook.
The Chief Executive has now admitted in a statement:
"We have spent a number of months examining our business model and looking for alternatives. But we have been sadly forced to conclude that under the present terms of business, our model simply does not work," she added.
For my point of view, Bonmarche has (or had) three major problems:
- online sales much too small relative to store sales (c. 12% of total).
- no planning took place to reduce the store estate, if necessary.
- the brand identity doesn't jump out.
For now, the stores continue to trade as normal and the website is still live. No redundancies have been made, according to the BBC. The business is being marketed for sale.
Philip Day's investment vehicle, which owns 95% of BON shares, says it is "disappointed with the result of our investment in Bonmarche."
My view - if Philip Day can get it wrong, and if a company which looked cheap on conventional metrics can go under very quickly, this provides further confirmation to me that we need to be extremely cautious when it comes to the retail sector.
The trend of legacy retailers collapsing shows no sign of abating. I wonder if Marks and Spencer (LON:MKS) might be the next Big Short?
Bioventix (LON:BVXP)
- Share price: £33.90 (-5%)
- No. of shares: 5.1 million
- Market cap: £173 million
Results for the year ended 30 June 2019
This popular and succesful company reports its annual numbers.
It sells "a total of around 10 grams of purified physical antibody per year".
In addition to these sales, it earns royalties from the sale of diagnostic products which use BVXP antibodies. These royalties generate about 70% of BVXP's revenues.
Results
- revenues +16% to £9.3 million
- its key product (used for Vitamin D deficiency testing) saw sales increase 27% to £4.3 million
- PBT +14% to £7 million
Comment on market conditions:
Once again, sales have surpassed our expectations. Despite this pleasing news, we are increasingly sure that price pressure (i.e. $/test prices achieved in the downstream market) is balancing the increase in market volume leading to a flattening total market in US Dollar terms.
This is clearly evidenced by a number of our vitamin D customer revenue streams which, after a period of significant growth now appear to have reached a plateau.
Currencies - most income is in dollars and euros, and BVXP has no plans to hedge. Therefore, with the pound sterling recovering (and in my view, likely to continue strengthening), this could act as a headwind to the reported numbers in future periods.
No capitalised research - BVXP doesn't capitalise its research expenditure, and highlights this in the commentary today. So on that basis you could view the accounts as "conservative" - i.e. underestimating the value that the company is creating.
Cash/Dividends - the company says that it only needs £5 million, less than its current £6.5 million cash balance. It therefore announces a special dividend, to distribute some of the surplus cash. Good shareholder orientation.
Future developments - the company is working on troponin tests (I'm not a doctor, no point in asking me to explain this!). It says:
There are no antibodies in the future pipeline that are comparable to troponin in clear potential value and the ability to influence revenues in the next few years.
The success or failure of this project is therefore of major importance!
More competition?
The CEO describes some additional competition which has arrived and may be coming:
We are aware that rabbit monoclonal technology – a competitive antibody technology – does exist at some of our customers labs and this is likely to have resulted in some lost opportunities for our SMA technology. In addition, the steady development of “synthetic” antibody technology (known in the industry as “library” or “display” technology”) has continued. This technology is perhaps not so directly competitive but is useful for targets which are fragile and liable to dissociation upon immunisation into sheep.
My view
Those who've been invested in this company for many years have been very handsomely rewarded, and it remains profitable and cash-generative.
As its success has become more widely known, the valuation has really taken off. And this valuation is currently very rich:
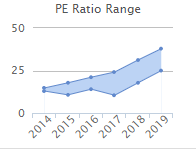
The CEO's commentary today, while still positive on many fronts, explicitly highlights negative pricing pressure and new competitive threats to BVXP's business.
So I suppose investors in this might want to ask whether the high valuation multiple continues to be justified, despite the mixed tone of these comments.
I don't have a strong view on this one, and am reluctant to speak bearishly on a company which is so successful, but there are clear risks:
- the troponin project might not work out as hoped.
- negative pricing pressure and competition might persist, dampening revenue growth.
- GBP might continue to strengthen, reducing the value of BVXP's foreign income.
I've never invested in this business, and will continue to stay away on the grounds that I lack industry insights. The medical field is outside my circle of competence.
Historically, the correct thing to do has been to back Bioventix, and that might still be true today. But I am going to stay neutral on it at current levels.
Mind Gym (LON:MIND)
- Share price: 133p (+9%)
- No. of shares: 99 million
- Market cap: £132 million
This is a training business. I covered its admission to AIM last year.
H1 has gone well:
Reported revenue is expected to be c.24% ahead of the comparative period last year having grown to around £23.9 million. On a constant currency basis revenue is expected to be c.20% ahead of the comparative period last year, with both the US and EMEA regions performing well and as a result, on a full year basis, we expect revenue to be slightly ahead of expectations.
It is focusing on repeat revenue from existing clients, and a greater share of revenue from its top 25 customers.
Note that when a company's customer base is becoming more diversified, this is generally touted as a good thing.
In this case, the reverse situation is being described positively, i.e. "Our strategy to focus on deepening key client relationships is paying off". But at least revenue is going in the right direction!
Outlook is in line with expectations when it comes to profitability:
The Board expects H1 adjusted PBT to be broadly consistent with the same period last year and remains confident of meeting market expectations for the full year.
My view - browsing this company's website, I must admit that I like its approach to training.
For example, under "management development":
No one loves middle managers. From "The Office" to "Horrible Bosses", in popular culture, managers are portrayed as buffoons or beasts".
You can browse all of the topics under this heading. Modules include "Buddy to Boss" (when you get promoted ahead of your friend), "Create your own luck", "Fleeting meetings", etc.
Mind Gym claims that team performance soars whens managers take its courses (of course it would!).
Does it have a competitive moat? Maybe it does, in the form of its reputation and the business model of having self-employed trainers?
I require a little bit of convincing when it comes to that question but overall this seems like a decent addition to AIM.
Begbies Traynor (LON:BEG)
- Share price: 85.85p (+1%)
- No. of shares: 126 million
- Market cap: £108 million
The insolvency practitioner Begbies has bought the business agent Ernest Wilson.
The price is £4 million (of which £3 million is in cash), plus contingent consideration of an extra £1.6 million, "with full payment only payable in the event that significant growth targets have been achieved".
In FY July 2019, Ernest Wilson made PBT of £0.7 million. So the valuation multiple is modest.
It's not hard to imagine that there could be strong synergies between an insolvency practitioner and a company which organises the sale of small businesses. So I'm happy to give this deal a big thumbs up.
From Ernest Wilson's homepage, you can see the categories of business that it typically deals in: bakers, butchers, cafes, hotels, pubs and bars, restaurants.
With financial distress having picked up, and particularly on the High Street, it would not surprise me if there were busy times ahead both for Begbies and for EW.
Trifast (LON:TRI)
- Share price: 165p (-14.5%)
- No. of shares: 122 million
- Market cap: £202 million
This is "a leading interational specialist in the engineering, manufacturing and distribution of high quality fastenings to major global assembly industries".
I've previously found it difficult to get excited about this company. Here's the dramatic corporate video from 2017.
Kudos to Paul, who highlighted back in April that Trifast's automotive exposure was a worry.
The company today says:
The challenging market environment highlighted in our Annual General Meeting update on 24 July 2019 has continued into Q2 of FY2020, with end markets across a number of sectors remaining weak, particularly in the automotive sector. This has led to some reduced volumes to existing builds across the UK, Europe and Asia. As well as lead times on production schedules moving out on a number of new business wins.
Trifast notes that its cost base is "semi-fixed", i.e. there is reverse operational gearing now at play.
Thankfully, it quantifies the new expectations in the RNS (all companies should do this). It now expects underlying PBT in the current financial year of "approximately £22 million".
I can see an existing forecast of £24.2 million, so we have an approximately 10% miss on that measure.
The price dropping back by more than 10% suggests that investors think this is more than a temporary blip.
But the company remains confident for the long-term future:
Notwithstanding the current high levels of uncertainty, we are pleased to report that our pipeline of new wins remains reassuringly solid and activity levels around the Group continue to be encouraging across all sectors. Both our USA region and our latest UK acquisition, PTS, have continued to perform exceptionally well in the first half of the year, comfortably delivering double digit revenue growth.
M&A - it is looking for acquisitions, with the help of an £80 million banking facility, and notes that opportunities are starting to increase thanks to the economic uncertainty.
My view - I have a good impression of management here. As discussed in my previous note, they focus on efficiency through the ROCE metric and believe that they achieved underlying ROCE of 18.8% last year (Stocko puts it at 12.9%, using statutory numbers, which is still an acceptable level for this type of business).
On the other hand, I doubt that these shares would offer much protection against a global economic recession. The company was unprofitable in 2002 and in 2009-2010. Given that it has a "semi-fixed" cost base, I assume that it will be unprofitable again when the next major economic cloud arrives.
It's hard or impossible to time these things, however. So I could understood someone who preferred to own these shares now, rather than stay on the sidelines in fear of tough economic times which may or may not occur in the short-term.
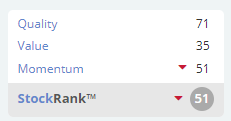
Stocko gives it an average rating. I'm neutral.
Angling Direct (LON:ANG)
- Share price: 61.8p (+0.5%)
- No. of shares: 65 million
- Market cap: £40 million
A short announcement, that Angling Direct opened its new store in Rotherham on Saturday, bringing the total number of stores to 32.
Located in a hugely popular fishing area, with a large angling community and a series of lakes and river venues, such as the river Don, the store is the only fishing tackle "destination store" of its kind in the area.
I maintain my view that this company, while far superior to Fishing Republic (FISH), still has a lot to do, to justify a £40 million market cap.
Watchstone (LON:WTG)
- Share price: 154.64p (+44.5%)
- No. of shares: 46 million
- Market cap: £71 million
Settlement with Slater & Gordon (UK) 1 Limited
Brilliant news for Watchstone, formerly known as Quindell (QPP):
Under the Settlement, which is made without admission of liability by either party, all of S&G's claims or potential claims for alleged breaches of warranty, deceit and fraudulent misrepresentation against Watchstone its present and former directors officers and agents relating to the historic sale of the Group's professional services division ("S&G Claims") in May 2015 have been unconditionally withdrawn.
The price of the settlement? £11 million.
Watchstone had put £50 million in escrow, in relation to the matter. £39 million will now be released back to it.
I note also that Watchstone reached a confidential settlement with former CEO Rob Terry last week.
A mountain of cash
Watchstone sold its Canadian healthcare business for £22 million last month (see the SCVR).
At June 2019, it had cash of £41 million, excluding the £50 million in escrow.
And it now has an extra £39 million to play with. So it could have a very large cash pile at this stage, bigger than the current market cap.
It also still owns Ingenie.
For the first time ever, I'm tempted to pick up a few of shares of this, on speculation of a generous capital return. It will be interesting to see how management choose to reward shareholders for these recent wins.
All done for today, thanks for your feedback everyone!
Cheers
Graham
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

33 comments
I like Bioventix because of the superb returns on capital. I don't pretend to understand the company business very well, and Graham's points of possible concern are direct from the horse's mouth, but managemnt are quite open on all fronts, and correctly (imv) charge ALL R&D to the P&L account a la any self-respecting Japanese drug company. This is a company run entirely without hype, self-conceit and misplaced over-ambition.
There is an interesting paradox there imho.
By not capitalising their R&D, they are arguably understating their Capital, also obviously understating their Return, so that is not intended as a criticism.
But this reminds me that I feel ROCE can sometimes be a deceptive measure.
The Bioventix (LON:BVXP) results show that they have capital of £10.9m and a ROCE of 64%.
That would be truly sensational IF I believed that they could deploy an additional £10.9m and double their profits - I don't believe that is the case. (In fact in the year just gone R increased by 1% whilst CE decreased by 2%)
Theirs is not a business driven by capital, but rather by intellectual property. (Whose value does not appear on the balance sheet.)
As per Stocko the market cap is £183m and as per today's results the NAV is £11m.
You can argue that "the market" values their IP at £172m. If they had had to buy that IP in from a third party it would sit on the balance sheet as an intangible. If that were the case ROCE would be a meagre 4%.
With a PE ratio of somewhere in the low 30s one has to assume the notional value of that IP includes the pipeline of developments as well as those already launched and bearing fruit.
It is certainly the case that R&D at Bioventix (LON:BVXP) thus far has made a fantastic return on capital (creating a huge implicit IP asset).
However the question now has to be can they continue this in to the future? A 10% forecast increase in earnings for next year (which may be reduced on the back of the caution in today's statement) is quite modest for such a high PE multiple. But can they deploy more capital to accelerate future growth in earnings?
By no means am I trying to knock Bioventix (LON:BVXP) as an investment - it has been a fantastic one thus far ; but I do think the high ROCE could be a deceptive comfort blanket, unless they can make the same scale of breakthroughs in the next five years as they have in the previous five. I do not know where they are on their potential growth curve.
I actually think the headline ROCE of 72.6% (BVXP stockreport at the moment, might change as the results filter in to it) is a pretty good approximation of their incremental ROCE over the last few years.
As you point out, they don't capitalise R&D, so the headline capex is no good for an incremental ROCE calculation, instead if I sum up EPS over the last 6 years 2013-2018 I get cumulative 434.9p eps. Then if I sum up cumulative dividends I get 320.7p dividends (including the 40p and 55p specials in 2017 & 2018 respectively.) Hence I figure that ~114p/share of profit has been re-invested in the business over that time frame. The net result of that is that eps has increased from 40.5p in 2013 to 112p in 2019, so approx 71p increase for 114p invested, or about 62% return on the incremental capital. Very rough and ready I admit.
Now, I agree absolutely that high incremental ROCE is then made irrelevent if they cannot continue to grow. However, I am sure that Troponin will meaningfully ramp up over the next few years, and in the background they continue to work on projects for further in the future. So whilst there are no guarantees, I see no reason why earnings should not continue to grow with minimal capital expenditure, and the beauty of the sky-high ROCE is that we can continue to enjoy a majority of earnings dropping through as divis and specials even whilst they develop the antibodies for the future.
I'm sure that if anyone is at a lose end this evening the Panorama programme would be worth watching. Why investing with fund managers can be risky..starring you know who!
Marks and Spencer (LON:MKS) I had a surprising answer to a question that I asked a group of people in their 20s. The question I asked was 'Where do you buy your clothes?' The people asked were mostly at university, academically successful, dressed neatly, with some high-powered parents. They all said 'mostly Marks and Spencer', but they said it quietly as if they suspected that it would be better to have a different answer.
Superdry (LON:SDRY) Have you looked at the re-vamped website? There are changes happening. The previous offering was full of scruffy kid stuff. What is shown now looks good/fashionable/desirable. disclosure: I own some shares in SDRY. I am not in the intended demographic.
Surely with technical advances in recent years, the general public could replace government and MPs? Why not have an online secure and verified voting system, where we can vote on everything from Brexit amendments to tampon taxes? At least we won't have to put up with another sh** shower like the current lot, and have to pay their expenses for the pleasure.
I suppose for the same reason that we entrust our investments to a Board of Directors.
Who would propose the Brexit ammendments or individual taxes (or everything else for that matter) for us to vote on?
A fixed term parliament seemed like a good idea at the time (to me at least). Now, not so much. If it wasn't for that then we would all have had a chance by now to make our feelings known and hopefully have got rid of a lot of that shower you mention.
PS - I wish Stocko could add a spellchecker to the site as part of their upgrade - I'm a useless typer and re-reading and correcting takes an age.
- providing the spell checker is in British English .........
My posts are spell-checked by the browser (Firefox). Maybe see if there is a feature you can turn on somewhere in yours.
Technology has advanced but the way that technology serves democracy has gone backward. It's true in this country but if you want to see the issue with a little perspective look across at the US, fake news n' all.
It's one of many reasons why representative democracy is the worst possible form of government, apart from all the others.
Further to bryans1311 comment about the general public replacing government, I would suggest that a more practical approach would be to start a non-political party which would base its decisions and policies on expert analysis, including scientific analysis. It would have no political views in much the same way that many voluntary organisations and some companies have have no political views. Perhaps it should be called the rational party. I would vote for it!
So this is funny:
@ a BBQ last summer (2018) when Brexit was going to work out great or not at all (times change but not Brexit), I proposed a party called the rational decision making party.
At the time i was asked what the party would do about Grenfell (I said nothing - 70 people dying is sad but not relevant to a government responsible for more than 70m people), the council should handle Grenfell and if there are any decisions around building regulations, the party would consider the information and respond accordingly.
Admittedly it was my wife's friend's BBQ (are double apostrophe frowned upon like double negatives?), But suffice it to say it would not have won many votes.
As per my right honourable friend (above), the minister for Peckham, technology is about as good for democracy as democracy.
Winston Churchill put it best when he said, the problem with democracy is the average voter (a gif that was shared (many times) among remain brethren).
Then we have the rational decision making party without elections, which is a dictatorship, notwithstanding a successful and not politically compromised dictatorship - not dissimilar to Singapore.
#fullcircle
Yes, the 'public' likes to blame politicians for everything, and let's face it the current crop haven't done themselves any favours.
But whose votes made for a minority Govt. Who also punished the liberals when they sought a middle ground with the Tories.
Time for a check in the mirror methinks.
Peter - who are these experts going to be? Many economic forecasts finish up being nonsense. Look at the forecasts of loss of jobs in the City following the Brexit vote. I suggest your guess and that of many people on here would be just as good as any "experts".
Video: Everyman Media (LON:EMAN) H1 19 presentation given to investors, at end of September. This was delivered at the Everyman Kings Cross. Both CEO Crispin Lilly and new CFO Elizabeth Lake (who joined from Science in Sport), are presenting. Gives a good overview of the company, and of management. c.50 mins.
oh I see-it does work!
also Trifast (LON:TRI) for me please. Seems a very harsh reaction
I can't get the ticker to work
All parties are looking for Tribal political advantages using Brexit as a mechanism. This is complicating getting a decision out of Parliament, and points to the downside of minority Govts on big issues.
An election is the answer, but this again is a football in the process. I wonder if the Queen has the right to dissolve Parliament, with the permission of the current Govt, to issue notice of an election? Its unlikely anyone will form an alternative Govt. Starting to make Italian politics look normale!
Morning, Graham.
Could you cast an eye over today's update from Trifast (LON:TRI) please? I don't currently hold, and the update doesn't seem to me to justify the market reaction.
.... and many thanks to the Stockopedia team for getting the £ticker mechanism working on the new site.
Morning FREng, sure - I'll see if I can add anything on that story! Cheers. G
Morning! Is it time to go long FTSE yet?
I did this morning on a small punt 30 pips up at the mo, beer money really.
Overall though Brexit could go either way, so its still a punt (not a studied trade where I am certain of the outcome) in my opinion. Personally, anything GBP or UK Indices needs to have a guaranteed SL on opening at the moment, the market are so volatile and technical analysis is predicting accurately and fundamentals are unknown due to the politics.
at the minute im guessing over the next few weeks our chances are;
but every few minutes i change my mind
referendum is hard to guess, it seems too much to ask the public to vote on the contents of a deal when the documuments for that deal is likely to be long and difficult to read. the question is too complicated for a yes no vote
those of us old enough to remember ‘Stingray’ on TV will recall the phrase ‘ anything could happen in the next half hour’ This is exactly what I think about Brexit and I am sitting on the side lines. My gut reaction is that there will be another referendum because Parliament will demand it as a condition to vote for any deal. Having said this whatever happens we must not have a Corbyn government or the ‘ last one put please switch off the lights’ moment will be with us.
In response to your comment and the following one from Martin Verlaine from what I can gather there is little chance of Parliament voting for another referendum. As far as the question being too complicated for a yes or no vote I hope you don't mean it is too complicated for the public to decide because if it is then it is also too complicated for MP's to decide! They all have there own prejudices just as I and most other people do.
the comment meant, very few people will read what the deal actually says or the source material, and to be honest it would be unreasonable to expect them too, that leaves everyone vulnerable to whoever is putting a spin on it.
over the last 3 years my trust in the politicians and the media has reached a real low and i've realised that politicians want chaos, it gives them a profile and an angle, they try to make us think theyll come along and save us, and somehow we all forget they started the chaos.
that says my post is getting negative likes so it looks like i'm on my own here
the narrative is how to do brexit, thats on both sides, theres nothing about whats the benefit of it is, the fight is who owns brexit not what it will do for us. "lets get brexit done as its hurting business" like it was you who started it and its not your fault we've had 3 years of it!
all i see is they the politicians benefit from chaos.
that says my post is getting negative likes so it looks like i'm on my own here
I think the point is that it's not investment related, other than in the most general sense that everything is investment related. Discussing how your beliefs are affecting how you're investing would be relevant.
I remain of the opinion that there's no way of predicting the outcome of events around Brexit and therefore the safe approach is a balanced portfolio. I'm holding a mixture of cash (30%, unusually high), gold (5%, ditto), a range of private equity vehicles (5%), short-dated corporate bonds (10%, arguably a cash proxy), overseas equities mainly through ETFs (20%), some very undervalued smaller UK equities (5% mainly, but not exclusively REITs) and a mixture of "quality" mid and small cap UK stocks mostly with significant overseas earnings.
Once a decision has been made I'd expect to commit most of the cash and cash equivalents into the market quite quickly. However, what I commit into will be determined by the actual decision. As an investor probably the best outcome would be an unexpected no-deal exit followed by wholesale market panic - but that's probably the worst result for the country.
Uncertainty rules, I don't think there's a predictable outcome here, 1214 days on the referendum result.
timarr
point taken. my original post was meant to be the possible next stage of brexit and the chances of whats going to happen next. i was struggling to assess the chance of another vote and i got distracted and sucked in.
although in my defence i tried to keep away from either side and only express my hatred for politicians of both sides, i hate them both equally, a career politician is socially as damaging as a career criminal (bugger, there i go again i cant help myself, even while apologising i'm doing it. I will now shut up and stop posting)
Just to be clear, the deal as proposed only increases the uncertainty, since what would happen next would be months of negotiations with potential trading partners - lack of agreement on a trade deal with the EU could easily result in a No Deal Brexit if the Government keeps to its December 2020 deadline. (Hence the Letwin amendment on Saturday.)
The investment outcome depends on second guessing how others will react (eg a knee-jerk euphoria for UK stocks if the deal is agreed by Parliament, followed by reality kicking in when it's realised that No Deal remains a real possibility?).
Crumbs, you're optimistic. We'll never see the process agreed in our lifetime. It will drag on and on, like the Jarndice Will in Bleak House, until everyone has forgotten what the initial aim was.
I assume that if a deal is done, the pound will rise sharply and the FT100 will fall because of the reduced value of overseas earnings though the 250 and small cap would rise because of their more domestic focus. Is that the general view?
The second part of that is correct but the politics have become far more complicated now.
If Johnson does not get straight vote on his deal today, the Letwin amendment will be voted on a Labour will table both a second referendum and a custom union.
Both of which the govt cannot accept but at least one will likely win, and the govt will be forced to try to push through an election - possibly by calling a straight vote on it. That will mean extension.
My morning smallcap tweet: Long-running farce "Quindell Hell" on City stage ends suddenly.
Image Scan Holdings (LON:IGE), Oxford Metrics (LON:OMG), Trifast (LON:TRI), Watchstone (LON:WTG), Osirium Technologies (LON:OSI)
Image Scan Holdings (IGE) FY trading very poor as flagged with rev down 32%. But order book £1.7m (£465k) mostly for delivery in H1.
Oxford Metrics (OMG) guides FY rev in line but adj pretax only broadly in-line with mkt expectations.
Trifast (TRI) H1 trading: the tough market has continued into Q2, especially automotive.
Watchstone Group (WTG) Slater & Gordon settles claim for only £11m of the £50m held in escrow. That's a great result considering what a pup S&G were sold.
Osirium Technologies (OSI) placing at 35p (1 3% premium). Also convertibles issue. Total raise £4m.