Small Cap Value Report (Mon 25 June 2018) - PRV, AVG, CWD, MRL, Mind Gym

Morning, folks. Today I'm planning to cover:
- Porvair (LON:PRV)
- Avingtrans (LON:AVG)
- Countrywide (LON:CWD)
- Marlowe (LON:MRL)
- Mind Gym - Proposed Admission to trading on AIM.
Porvair (LON:PRV)
- Share price: 493.5p (+3%)
- No. of shares: 45.6 million
- Market cap: £225 million
I like how promptly this has been reported. Other companies have only released their annual results for the period ending December in the last few days, while Porvair is already releasing interims to May.
Porvair plc ("Porvair" or "the Group"), the specialist filtration and environmental technology group, today announces its half yearly results for the six months ended 31 May 2018.
I'd give the company a premium rating simply for keeping on top of its accounts so well, and keeping shareholders properly informed!
Financial highlights are good;
- Revenue up 7% to £59.7 million (2017: £55.5 million), 12% on a constant currency basis*.
- Profit before tax up 8% to £5.2 million (2017: £4.9 million).
See how the currency movements were a headwind to revenue. 12% is the measure I would use when thinking about underlying growth rates. Most of the company's revenue originates from the Americas.
ROCE
Encouraging to see the company specifically mention its ROCE performance:
The Group's return on capital employed was 14% (2017: 14%). Excluding the impact of goodwill, acquired intangible assets and the pension liability the return on operating capital employed was 42% (2017: 43%).
It has grown by acquisition and therefore the goodwill and other intangibles are a very significant portion of the balance sheet: £65 million (for context, balance sheet book value is £80 million).
This is why you have such a large discrepancy in the ROCE calculation, depending on whether or not goodwill etc. is included.
14% is the actual number enjoyed by Porvair shareholders (Stocko roughly agrees, estimating Return on Capital at 12.6%).
42% is the company's view of its return on tangible capital employed, also ignoring the effect of its pension deficit. What that says to me is that the underlying businesses must be very interesting in terms of their ability to generate a return for shareholders. Porvair management have had to pay up to acquire them and therefore the return for Porvair shareholders is not as high as 42%. But they are likely to be high-quality businesses.
Outlook Statement
Porvair traded well in the first half of 2018, with a healthy order book for the second half and robust levels of activity. The business is achieving further organic growth through incremental new product introductions and we continue to expand manufacturing capacity to meet demand.
My opinion
Despite considerable acquisitions having been made over time, the company's balance sheet is in reasonable shape with tangible net assets of £16 million and a small net cash position. That's a nice achievement actually - some businesses like this have a tangible asset deficit and a heavy net debt position.
It has an unbroken dividend stream stretching back at least to the mid-1990s. Dividends were cut in 2003 but have been rising again since then.
Everyone can see that the shares are on the expensive end of the spectrum. For a ROCE of 13%-14% and a consistent track record, I can see why they are priced at almost 3x book value.
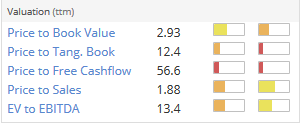
I'll continue to leave this on my watchlist. A nice stock to keep an eye on for share price weakness and a buying opportunity.
Avingtrans (LON:AVG)
- Share price: 216p (+3%)
- No. of shares: 31 million
- Market cap: £67 million
Avingtrans (AIM: AVG), which designs, manufactures and supplies critical components, modules and associated services to the energy and medical sectors provides an update in respect of its financial year ended 31 May 2018.
This is a group of niche engineering businesses, seeking to become a leader in the energy industry (nuclear power, oil & gas, etc).
Results for the year ending May 2018 will be in line with expectations.
What really matters, though, is expectations for FY 2019, the first full year of ownership of Hayward Tyler.
We are getting a boost to these expectations:
Following the successful integrations of Hayward Tyler Group and Ormandy, the Company is pleased to report an improved margin mix and, as such, expects its profit in FY2019 to exceed previous expectations.
A few months ago, with the share price at 226p, Paul predicted this:
... the market is currently clearly assuming that broker forecasts are way too conservative, and that the company will thrash them... Possibly the bar is being set low, to allow the company to out-perform, and put out positive trading updates in future?
Well done Paul!
Brokers have increased their 2019 EPS forecast from 9p to 10.3p. This lowers the forward P/E multiple, at the current share price, from 24x to a more reasonable 21x.
My view - another solid performer. Frustratingly, I again can't see any particular reason to buy the shares at the current level. Brokers point to the company benefiting from a recovery in the oil and gas sector - not something I am keen to bet on myself, but I can see the merits of that argument.
Countrywide (LON:CWD)
- Share price: 59.5p (-24%)
- No. of shares: 238 million
- Market cap: £142 million
Capital Structure, Recovery Plan and Trading Update
This has produced CWD's biggest-ever 1-day share price fall.
Countrywide plc ("Countrywide", the "Company" or the "Group") (LSE: CWD), the UK's largest integrated property services group, today provides an update in relation to: putting in place a long term capital structure; progress on its back to basics recovery plan; and current trading.
The thing is that an equity fundraising was already on the cards. As Paul said in March, investors had plenty of warning that the balance sheet needed to be fixed.
Today, the company says that it wants to reduce debt levels by 50%, using fresh equity financing.
I note the approval of US group Oaktree, Countrywide's largest shareholder. Oaktree's recent involvement in Ranger Direct Lending Fund (LON:RDL) is what initially sparked my interest in that fund (and I currently own shares in RDL).
Doing a little bit of background reading, I am unsurprised to learn that Oaktree built its Countrywide stake via investment in its bonds, not its equity, during the financial crisis of 2009-2010.
Oaktree is a deep value investor and tends to look for situations where the downside is limited and the upside has some potential. It has particular expertise in distressed debt, and it was an Oaktree distressed debt fund which accumulated the position in Countrywide bonds. When these bonds were restructured, Oaktree was left with a large equity stake.
I will be curious to see how much fresh equity, if any, Oaktree decides to put into Countrywide as part of this deal.
Personally, I concur with Paul's assessment from March that the shares are uninvestable, given the ongoing uncertainty over the balance sheet and the scale of dilution required.
Net debt was last recorded at £192 million, so it will need to raise c. £100 million. Once again, it has suffered financial distress as housing market conditions have deteriorated.
This is its description of latest conditions:
The market in the first half has continued to be subdued and we have experienced longer transaction cycles. As previously announced, the Group entered 2018 with our Sales pipeline significantly below that of 2017.
It's not for me due to its cyclicality and lack of barriers to entry. I would only consider it as a potential deep value investment if the balance sheet was strong enough and perhaps, like Oaktree, if I could buy its bonds at an attractive discount to par.
Marlowe (LON:MRL)
- Share price: 417p (+3%)
- No. of shares: 34.5 million
- Market cap: £144 million
Marlowe plc, the UK support services group focused on acquiring and developing companies that provide critical asset maintenance services, announces its audited results for the year ended 31 March 2018.
It looks like I possibly got this one wrong last December, suggesting it was too expensive at 347p.
It's executing a buy-and-build strategy in fire protection, water treatment and air ventilation.
Reflecting my caution toward buy-and-build plays, I was put off by its price to book value ratio at the time.
The market remains happy to price this at significant multiples to book:
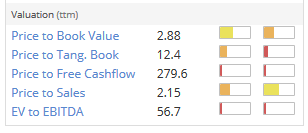
The market is saying that the underlying businesses are better-quality than I've given them credit for up to this point, and/or that the synergies from combining them will create more value than I would have expected.
Key numbers:
- Revenues up by more than 70% to £80.6 million. Run-rate revenues "approaching £100m".
- Operating profit (adjusted): £6.2 million (up from £3.5 million).
- Actual operating profit: £0 million
The adjustments to operating profit are very heavy, and include £0.7 million of bad debts attributable to Carillion (CLLN).
Total adjustments are £6.2 million. Last year, there were £2.6 million of adjustments. It would be prudent to expect several million of these every year, I reckon. A buy-and-build strategy is complicated and expensive. The goal is that after several years, we will be left with a far bigger business enjoying synergies (e.g. cross-selling opportunities) between its various parts.
Thankfully, its balance sheet is in ok shape, and it has plenty of slack in its debt facilities:
The Group has sufficient headroom on its facilities to continue to fund acquisitions with debt should it so choose.
Outlook statement is confident. Trading is in line with expectations.
My view
Management have executed very well so far, so I can understand some element of the premium in the share price.
I remain to be convinced about the investment merits of these businesses, and why they should trade at a premium rating. Building support services haven't been good to shareholders during my investing career.
In fire protection, the company reminds investors of the "increasing barriers to entry that we perceived, the regulation that drives its growth, high customer retention rates and its attractive earnings visibility
More generally, it says:
Marlowe's defensive market qualities, strong channel to market, organic growth momentum and potential to acquire new businesses strongly position us to continue to create shareholder value.
I understand its high retention rates, earnings visibility and defensive qualities. These are all good things.
My concern is that there are probably good reasons why its markets (fire/air/water services) are highly fragmented: namely, that that it's difficult for these companies to differentiate themselves from the competition.
So I still don't understand why this stock is rated so high.
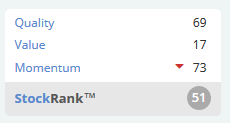
Stocko also doesn't see much value:
Mind Gym - Placing and Proposed Admission to Aim.
Continuing our review of recent and forthcoming IPOs:
Mind Gym is a behavioural science business that uses scalable proprietary products to deliver human capital and business improvement solutions to large corporations.
When I first read this, I feared that it might still be at an early stage of its development, and was prematurely hitting AIM.
It turns out that it was founded 18 years ago and has had dealings with most of the FTSE-100 and S&P-100 companies. Lots of blue-chip clients, then?
The coaches who deliver its live training sessions are self-employed.
On this basis, it includes its live sessions within the category of revenues that "require minimal attention from Mind Gym employees to fulfil", and are therefore highly scalable. It thinks 77% of its revenues are scalable.
The numbers are as follows
In the financial year ended 31 March 2018, Mind Gym generated revenues of £37.0m, adjusted EBITDA of £7.9m and profit after tax of £4.4m.
My view
Seems worth looking into. It may have some valuable IP. I'd consider this a B2B media company, in a similar category to the likes of Euromoney Institutional Investor (LON:ERM) and Informa (LON:INF) (it's much smaller than them for now, of course). I'm generally favourable towards this sector.
Note that the deal will raise no new money for the company. Insiders will sell about one-third of the shares at a valuation of £145 million, or 33x trailing earnings. It may need a profit warning or two to bring it back to a level where a value investor could get interested!
Cheers, that's all for today!
Best wishes
Graham
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

21 comments
Unfortunately about half of the revenue is from the UK; if we end up falling out of the EEA then Prv (and many others) will be hit very hard
An alternative to PRV is Donaldson DCI, which has little uk exposure
However both are highly priced
https://seekingalpha.com/article/4138971-donaldson-company-dust-settles
Buy either on weakness?
I haven’t looked at their IPO but I have worked alongside MindGym in the past and seen them at trade conferences a few times. Basically, they are a training company. Their initial product was 90 minute “brain friendly” workshops (their edge was to condense a 2/3 day course into 90 minutes). They subsequently developed online/remote offerings (eLearning/webinars).
I haven’t looked at them for the past couple of years, so the above might be a little dated.
Regarding blue chip clients - be careful. Even as an independent practitioner I had several FT100/S&P500 clients. And later, as training director for a Nasdaq mid-cap I bought from them a couple of times to fill a tactical need. But that sort of business isn’t sticky and needs constant sales/marketing effort. This said, the first time I encountered them was when they and I were 2/3 co-vendors fulfilling a 2 year rolling programme for a FT100 company (this is good quality business). Another area that could be interesting is their online offering - this will provide a form of SaaS type income perhaps (but I would be careful about the renewal percentage in this sector - some of this biz will stick long-term and some will be quite flaky).
I’m not really interested in this type of business as an investment, so haven’t researched further. I agree with Graham that there will probably be some profit warnings along the way at which point MindGym might become interesting as an investment. They do have a decent brand reputation. I hope my industry view gives some indication why I am cautious about the quality of earnings in this sector (same bucket as recruiters, consultants in my book). They also tend to be pretty cyclical of course.
Cheers
Simon
Erm... If anybody more hip, cool and groovy than me who understands this sort of guff stuff could translate it into understandable English for old farts like me, I'd be very grateful. :-)
Gostevie
Erm... If anybody more hip, cool and groovy than me who understands this sort of guff stuff could translate it into understandable English for old farts like me, I'd be very grateful. :-)
"We have some software that builds on psychological research to profile peoples' behaviour, and we then use the results to tell companies how to do things better. And they pay us for it, although not nearly enough to justify our valuation, but we don't care because we're all rich now".
Sass that hoopy frood.
timarr
There is no way mind gym are worth £145m Well done to the founders for a fantastic result though
If most of Mind Gym's trainers etc are self-employed, I wondered if there will be future possible headwinds that have buffeted Deliveroo, Uber, and Pimlico Plumbers in respect of self-employed staff being treated as staff, or subject to certain employment protections?
The Govt effectively caused most public bodies using service companies 'staff' to reverse their policies (see BBC etc), and are currently in 'consultation' mode with the private sector. Whilst that's hanging over their heads, and if Mind Gym are using a significant number of self-employed staff this may be a continuing risk, which I am sure is marked up in the risks section of the Public flotation documents.
Wouldn’t mind gym be more like Learning Technologies (LON:LTG) or at least the net dimensions business before Learning Technologies (LON:LTG) bought them. They seem like a learning and development company than a b2b media company?
I’ve been aware of mind gym for a while but will look more deeply into them now they plan to list.
Re Marlowe (LON:MRL)
Thanks Graham for your analysis.
The team behind Marlowe (Lord Ashcroft - major shareholder; Charlie Skinner - is a NED but also CEO of Restore (LON:RST); Alex Dacre - CEO but used to be at Restore and Impellam (LON:IPEL) ) have a great track record of buy and build.
Restore (LON:RST) is a good reference point for how fragmented businesses - in their case box storage, shredding and removals - can be acquired and create shareholder value. If you look at Restore's PE you'll see it's also highly rated and it wouldn't surprise me if Marlowe (LON:MRL) ended up on a similar or even better rating as it's strategy is similar but it's also in a more regulated space.
I'm a happy holder
Cheers
Francis
re: Marlowe (LON:MRL)
Hi Francis- great insights, thank you. Will bear that in mind in future reporting on this stock!
Best wishes
Graham
There's another reason Marlowe (LON:MRL) could end up more highly rated than Restore (LON:RST). Marlowe's cross-selling activities across Fire, Water and Air are essentially to the same customer. So for instance, a hotel group would have one department looking after all these critical services and its therefore easier to cross sell and make the customer's life easier (fewer suppliers to deal with). It's also easier for the customer to buy a plc supplier than a small local supplier.
Restore plc's customers on the other hand are in different departments so its harder for instance to get the Librarian (who buys box storage) to also buy removals (that's the job of the Porterage department).
cheers
Francis
Thanks Graham.
There's another reason Marlowe (LON:MRL) could end up with a similar or better rating to Restore plc.
The customer Marlowe serves buys all the Fire, Water and Air services. A typical customer, say a nationwide hotel group, has one department responsible for ensuring their fire, water, air ducts etc are properly looked after. So its easy for Marlowe to introduce one of the other services to that same customer. The benefit to them is fewer suppliers and also it's less risky to switch to a plc supplier than a small local one (easy purchase decision to defend).
Restore on the other hand has had some success with cross selling but the reality is the purchase decision for their various services is taken by different departments. So for instance the Librarian who buys box storage is in a different department to the Porterage person who buys relocations.
So for me Marlowe could be a better long-term business.
cheers
Francis
If you look at Bioquell (LON:BQE) trades you will see two before noon and dozens after - this is typical of the ST effect. I believe his emails go out at noon to those who subscribe. Having suspected this the next step is to go here:
https://www.investorschronicle.co.uk/search/?q=bqe
Voila!
Bioquell (LON:BQE) has shot up 15% over lunch, anyone aware of any reason why? I cant see any news.
Re Bioquell, I think Simon Thompson of Investors’ Chronicle put out a positive note on it. Might have played a part.
Regards
Andrew
Ah that would explain it. Many thanks.
Somero Enterprises Inc (LON:SOM) is c 5% of revenue in China...and c 72% in the USA so any trump trade barriers to cheap Chinese kit landing in the US is a net benefit to SOM?
Graham, a bit broader than normal but just interested to know if you have a view. We have touched on Somero and Water Intelligence both US businesses, somero is looking to business in China. I am of the view that given Trump's stance these are both very highly valued businesses which are fast looking shorts.
Hi Camtab, off the top of my head I can't remember WI's position. As far as Somero goes, it has very little traction in China yet so US-China protectionism shouldn't affect its existing revenue streams very much.
Thanks Graham. I think my thoughts are related to the fact that expectations are high and disappointment can disproportionately affect these growth shares. So it is kind of how much risk for possible return. I do believe you mention China in the same breath as any company and it gets a filip. Whilst that company only does 5% now some investors will be buying for a higher percentage in the future so a multiple of 16x possibly holds some of that expectation which on current political momentum is going to be lower than perhaps we thought pre Trump. Just looking for ideas really and I appreciate your response, as well as rhomboid, phoenixnight and LeoLeo. All the best
Hi Camtab
As a holder in WI, could you explain the rationale between Trump & shorting WI please? I've scratched my head and given it some thought but am struggling.
Thanks
Paul
Paul,
Accepting that this is a US business with a strong US market and therefore limited exposure to international trade, it is nonetheless in their own words "a leading multi national provider", with ambitions to create business in a number of international markets not the least of which is the UK, "UK-based municipal business strong first full year after acquisition". At least this is my understanding. At some level a business on a pe according to Stocko of 35.3 all be it with growth of over 30% expected is valued with all growth expectations in mind. Any overseas ambitions are likely to be limited on the current political trajectory, I therefore think this is a pretty full valuation with an operating margin below 10%. Incidentally I am not a holder of WI as I sold out on the rise in April. No attempt to influence anyone else just very interested in peoples' thoughts.
Camtab, it is interesting you say that because I've also been thinking about my US exposure in light of recent events. The issues in my mind are:
* Growth risk. Current policies are pro-cyclical expansionary and so in the short term are bullish, but are likely to deepen the next recession.
* Currency risk. By which I mean the risk to the translation of US earnings into pounds. The dollar has recently been driven by interest rate differentials and a weak pound / euro. There is some risk that the government will in future intervene to limit Fed interest rate rises for political reasons resulting in an inflationary and devaluationary spiral.
* Investor protection / climate. Foreign companies, or those with predominately foreign investors, or those mainly quoted from a foreign exchange always at higher risk of confiscatory policies. The climate has long been deteriorating in the US - witness how BP and arguably VW were treated, withholding tax policies etc. While it is nowhere near as bad as most developing countries, let alone China, they are undeniably moving in that direction. The current hierarchy of countries is of course highly debatable and controversial.
* Moral position. There are sectors and countries that I avoid investing in to various degrees. For those that consider this sort of thing (a minority, I think), it might get to the stage where this precludes you from investing in US companies. Again, the current hierarchy of countries would be highly controversial (= I won't discuss it here).
Somero Enterprises Inc (LON:SOM) - I would describe them as moderately rather than "highly" valued, and I don't think the price reflects any expectation of Chinese growth. In the short term, current policies should be very good for their US business. Foreign earnings would mitigate the impact of a potentially falling dollar. They are mostly owned by UK and Canadian institutions and so are at risk from adverse US government action but not so much from management action. (I have a moderate holding).
Water Intelligence (LON:WATR) - These could reasonably be described as "highly valued" in UK terms, but not for a US growth company. Current policies may adversely affect their business to the extent that leak detection is driven by regulation. Earnings are all in the US and so would be badly affected by a potentially falling dollar. Ownership is by a US institution, US management, some UK institutions and an unknown mixture of US and UK private investors. I would say the risk here is more of adverse management action, but frankly the most likely thing to happen is for the listing to be moved to the US which should result in a significant re-rating in the shares inline with higher US share valuations. (I sold out on valuation and management language concerns).
The bigger issue for me is probably exposure through the FTSE 100 trackers I own and the risk of a US market crash impacting general UK valuations. These I have hedged with S&P PUTS.
Porvair (LON:PRV) reported another sound set of results for H1. I hold but and I am trying not to fall in love with a company that continually comments modestly and clearly,while showing steady improvement in its numbers. The outlook is hedged around with warnings about the short term lead of orders and potential unpredictability, but over the years the management has shown a n ability to justify the rather high p/e
Good morning Graham
A positive update from niche engineer Avingtrans (LON:AVG). Integration of the recent acquisitions has gone well and it states that trading has remained strong with profit expectations for the year ending May 2019 anticipated to be ahead of expectations. It also announced a new £5m government contract with the opportunity to tender for further business.
I hold and would welcome your thoughts if you have time.
All the best
Jonno
Hi Jonno, thanks for the tip - will take a look! G
My morning smallcap tweet:
ST Ives (LON:SIV), Toople (LON:TOOP), Zinc Media (LON:ZIN), Countrywide (LON:CWD)
St. Ives (SIV) Sells St Ives Management Services Limited for £9.5m. It had rev of £49.5m and pretax of £5.1m. What? Sold at a PE of 1.9?
Toople (TOOP) wins contract that gives 'significant additional monthly revenue'.
Zinc Media Group (ZIN) Wins 2 commissions worth over £2m total. New series of Emergency Helicopter Medics and a 3 hour special "Soaps' Most Controversial Storylines". It usefully includes a long promo para on the latter. Sounds well worth 3 hours if you have been stranded on a desert island and have found a TV.
Countrywide (CWD) warns, plans placing and says its recovery plan is going great. I'm short.