Small Cap Value Report (Thu 8 Mar 2018) - CWD, CVR, FUL

Hi,
It's Paul here. Today I shall be covering results from;
Countrywide (LON:CWD) - results - bank covenant worries - needs a fundraising.
Conviviality (LON:CVR) - massive 59% drop in share price - overdone? Maybe, but Graham foresaw it! So a hat-tip to my co-writer here.
Fulham Shore (LON:FUL) - mild profit warning - horrible sector.
(the above list changed during the day, as profit warnings are more interesting than in line with expectations results)
Just to flag that Tuesday's report, and Wednesday's report, are now finished, with extra sections added. Sorry they were rather slow in emerging.
Countrywide (LON:CWD)
Share price: 83.75p (down 5.8% today, at 14:18)
No. shares: 237.9m
Market cap: £199.2m
This is a large chain of UK estate agents.
The narrative is particularly interesting, as it squarely lays the blame for the group's poor performance at the door feet of the recently departed CEO. The Chairman has taken over for now, rising to Executive Chairman, with a "back to basics" strategy change. Here's a flavour of the commentary today;
Industry expertise in all areas of our business is key. Within Sales and Lettings, the previous strategy resulted in us losing a lot of that expertise.
In the Group, we are fortunate in that we have an industry veteran, Paul Creffield, who has been promoted to the role of Group operations director. His deep understanding of the market and operations means that we have quickly been able to identify what we need to do to begin addressing our under-performance.
I am greatly encouraged by the number of high calibre industry business leaders that we already have within our Sales and Lettings business and a number of similarly experienced and high calibre industry people who previously left us and want to rejoin now that Paul is in this role.
Let's look at some key numbers for calendar 2017;
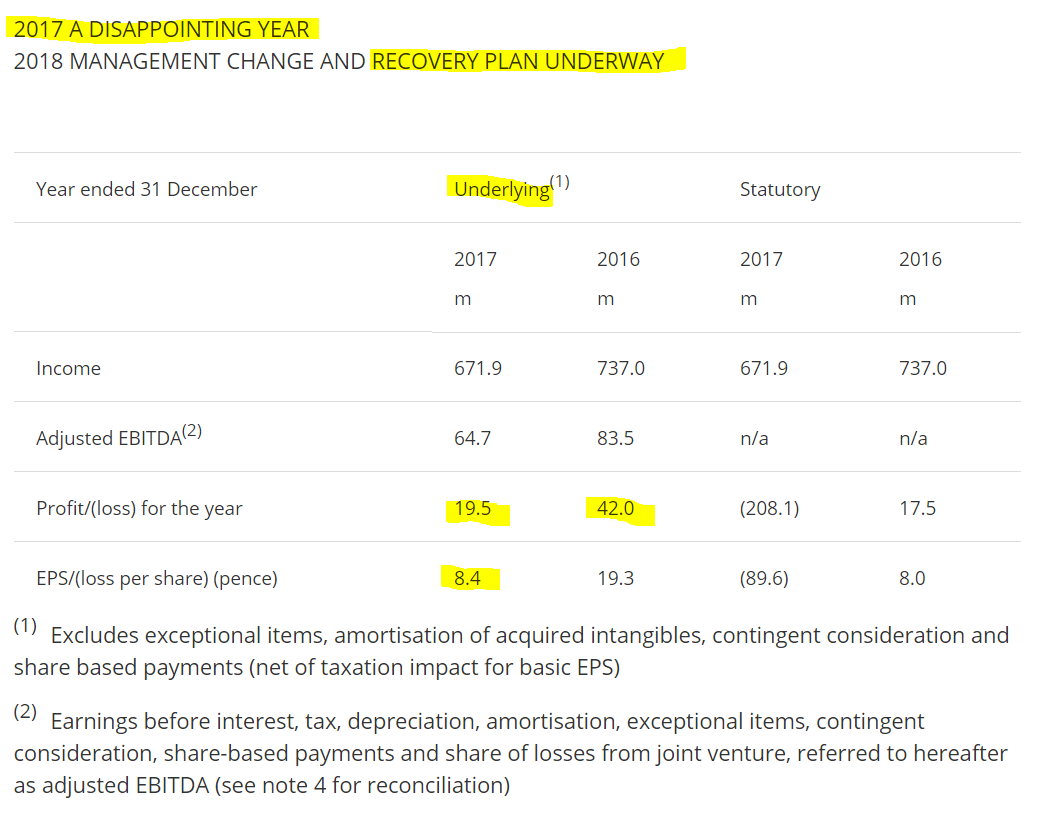
I've left in the footnotes, so you can see that the "underlying" figures strip out quite a lot of items. However, these are all fairly usual items. It's important to remember what companies are trying to do by presenting adjusted/underlying numbers;
1) Focus us on an inflated profit number, in order to achieve a higher share price!
2) To show the underlying trading performance of the business, stripping out items of a one-off, or non-cash nature.
So whilst a degree of cynicism is useful, and it's always worth reasonableness-checking adjustments at every company, the underlying/adjusted figures do usually serve a useful purpose. The one adjustment I find unacceptable, is share based payments, since this is just part of the remuneration package for Directors & senior staff, so it should be expensed through the P&L normally in my view, and not adjusted out.
The other adjustments here look fine to me, to arrive at an underlying trading profitability figure.
Anyway, as you can see from my highlighting above, the profit after tax has more than halved to only £19.5m.
The full detail is given further down the announcement, and I note that finance costs look very high, at £12.6m - since the group is heavily indebted. However, on the plus side, there is a heavy depreciation charge of £27.7m. So cashflow should be better than profits.
Note also that the statutory profit is a giant loss, of -£208.1m, which looks like a big impairment write-off on the balance sheet. My main concern with this share has always been its weak balance sheet & heavy debt, so let's focus on that next.
Balance sheet - here are the usual figures;
NAV: £309.1m (down from £479.5m a year ago, due to a big goodwill write-off)
NTAV: is heavily negative, at -£191.0m. This is because the balance sheet is laden with intangibles, which when written off, leave a yawning gap.
Something that dawned on me the other day, is that when a company has a lot of intangible assets, there is often a related deferred tax creditor. So when writing off the intangibles, we should also add back the deferred tax that relates to them.
In this instance, note 24 to today's accounts shows that there is a net deferred tax liability within creditors of £23.8m, but it doesn't explain what this deferred tax relates to. It's an obscure point really, so I won't waste any time investigating further, but just to flag up that if we also write off this deferred tax liabilty, then adjusted NTAV is -£167.2m, i.e. still awful, so it doesn't make that much difference.
What does negative NTAV actually mean in practice? It depends on lots of things, but in simple terms it usually means that the business is under-capitalised, hence is relying on creditors (banks & trade credit) to support its business operations. Providing the business is profitable & cash generative, that's not necessarily a problem. However, if profits/cashflow drop, or disappear, then creditors can get the jitters, worry that they won't be paid, and in extremis, pull the plug on the company, forcing it into Administration. Or, they might put sufficient pressure on the company to force it into doing a rescue equity fundraising, which can be very dilutive to existing holders. Overall, it makes a share much more risky, if it is relying on the support of creditors to continue trading. That's why I much prefer a strong balance sheet, with little to no debt. Then the above risks just disappear, which improves risk:reward for investors, making it more likely that we'll have a successful investment over time. Or at least fewer investing disasters.
Looking at working capital, current assets are £125.6m, current liabilities are £114.3m. Divide one by the other, and we get a current ratio of 1.1 - that's a bit on the weak side - I normally like to see a minimum of 1.3, or preferably 1.5+ to feel comfortable.
Long-term creditors is where the problems lie. The total of £273.9m includes £213.5m in bank debt. Overall net debt is £192.0m, which is usefully down from £247.9m a year earlier, but still far too high. Note that the company did a placing at 175p in Mar 2017, which raised £37.8m before expenses, so that seems the primary driver of reduced debt.
It seems to me that the company needs to do another, larger placing now, to shore up its balance sheet & avoid the risk of the banks pulling the plug.
Net debt to EBITDA ratio is 2.97, unchanged from last year. That's getting into danger territory. For businesses like this, which has little to no asset base (there's negligible freehold property for example), then I'd be surprised if the banks would grant a Net Debt: EBITDA covenant of more than 3. Around 2.5 times seems more normal. But I'm forced to guess on that point, because despite searching the 2016 Annual Report, where the word "covenant" appears 16 times, it does not state what the actual covenant figure is, for Net Debt: EBITDA. It seems to me likely that the group is probably hovering very close to this covenant, with very little headroom, but I don't know that for certain. The narrative today reinforces that I'm probably right, especially this extremely worrying going concern note below.
Going concern note - these should always be read carefully, especially at highly indebted companies. There is a very nasty going concern note in today's statement, which for me makes this share uninvestable. It sounds as if there's a considerable risk that the group might breach its net debt : EBITDA covenant in 2018. That could trigger insolvency, or at least an emergency, discounted equity fundraise. Why take the risk of running into that scenario?
Here is an excerpt of the most important part of the going concern note today;
... Failure to achieve one or more of the above would result in lower adjusted EBITDA with a consequent negative impact on headroom of the leverage and interest cover covenant ratios and higher projected net debt.
If the Group's forecast is not achieved, there is a risk that the Group will not meet the Net debt to EBITDA leverage covenant and should such a situation materialise, the banks reserve the right to withdraw the existing facilities.
Without the support of the lender group, the Group and parent Company would be unable to meet their liabilities as they fall due. [Paul: i.e. insolvent]
Given the timing and execution risks associated with achieving the forecast and therefore remaining within the leverage ratio as stipulated by the banking covenants, the directors have concluded that it is necessary to draw attention to this as a material uncertainty which may cast significant doubt about the Group's and the Parent Company's ability to continue as a going concern in the basis of preparation to the financial statements.
That is a stark warning. Ignore this at your peril!
Dividends - as you would expect for a business in financial trouble, there won't be any divi for 2017. That makes sense. Debt reduction is more important.
My opinion - as you've probably gathered by now, I would not consider investing here, as the group is clearly in a precarious situation with its bank borrowings, and probably close to a covenant breach. In that type of situation, I would get the hell out, as quickly as I could, if I owned any shares in this.
The market cap of £199m looks way too high, given the excessive debt, and risk of a discounted fundraising. Small shareholders don't need to take that risk - they can just sell, and watch from the sidelines. Whereas large shareholders are high & dry.
It might well be that the big shareholders support another fundraising. I think it needs to raise about 100m in fresh equity, to reduce risk to an acceptable level. The trouble is, we don't know at what price such a fundraising might occur at. So small shareholders are very vulnerable to potential dilution here. That said, the fund managers who already hold a big slice of the equity, might want to protect the value of their existing holding, so could be co-operative on the price of another fundraising. The key thing is that we just don't know - it's a major uncertainty, so that makes valuing the shares almost impossible right now.
I would definitely look at this share again, as a potential turnaround, once it's fixed its balance sheet. It sounds as if a lot of the under-performance is self-inflicted, by poor previous management (if the Chairman is to be believed - he might just be scape-goating?).
We also have to consider that the housing market seems to be slowing, is wildly over-priced on traditional income to value metrics, and that interest rates seem likely to creep upwards (albeit still historically low) in the coming years. The latest consumer confidence data has been quite soft.
What about internet disruption? There are lots of new online estate agents, the market leader being controversial Purplebricks (LON:PURP) , chipping away at the business of traditional estate agents. Although I've come round to the more bearish view that online estate agents, where customers pay up-front, regardless of whether the property sells or not, could be leaving behind a long tail of dissatisfied customers.
In reality, I think there's room for both - online selling makes sense for experienced property vendors, but people who need their hand holding, or are trying to sell an unusual property, are probably best off using a conventional estate agent.
Tenant fees are set to be abolished in 2019, adding further misery here, although the group is looking to mitigate this - presumably by hiking fees to landlords?
Overall then, this looks a real mess, and is uninvestable for me, until the balance sheet is fixed. It might then be worth looking again, at the turnaround potential.
Conviviality (LON:CVR)
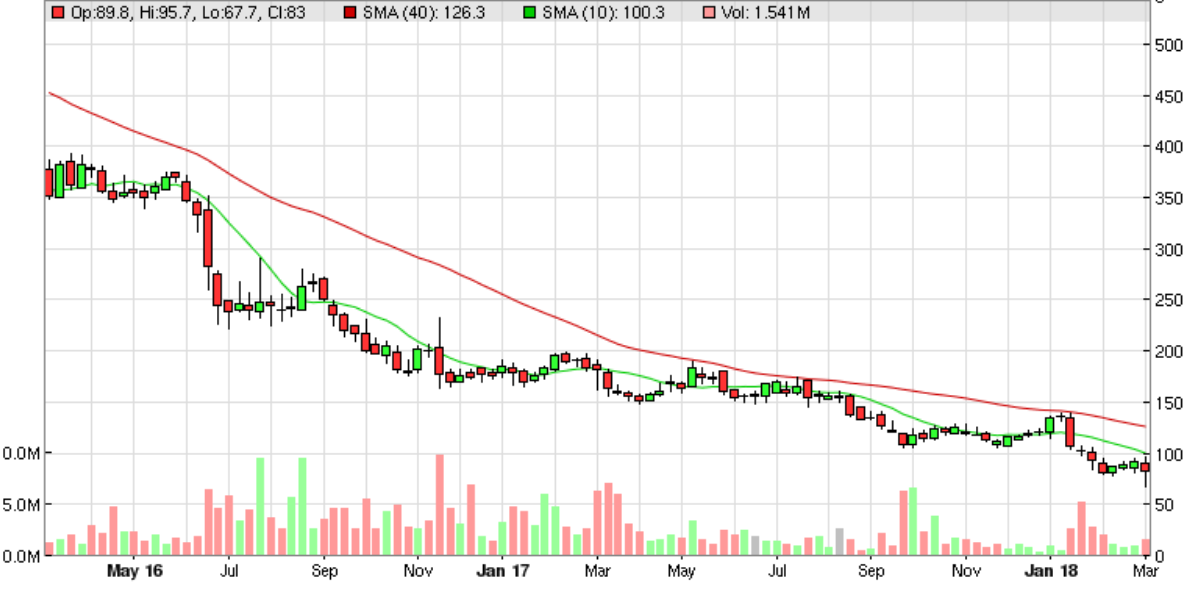
Share price: 123p (down 59% today, at market close)
No. shares: 183.28m
Market cap: £225.4m
Trading update (profit warning)
(issued at 3:07pm today, during market hours)
Conviviality Plc (AIM: CVR), the UK's leading independent wholesaler and distributor of alcohol and impulse, serving customers through its franchised retail outlets and through hospitality and food service, is providing the following update on trading for the 52 week period ending 29 April 2018.
This update has triggered a calamitous fall in the share price today of 59%. It's doubly annoying for shareholders when a profit warning is issued during market hours. Apparently there is a compulsion on companies to issue bad news to the market as soon as they become aware of it. Surely the process could have been managed better by the company - e.g. by calling a board meeting to discuss current trading after the stock market is closed, then issuing the RNS at 7am the following morning? Most companies seem to be able to manage that, so an intra-day profit warning just reinforces the impression that management may not be in control.
A share price fall of 59% in 1.5 hours, usually means there's something seriously wrong. Or maybe it's an over-reaction?
What's gone wrong?
Following a review of current year projections, the Company now expects that adjusted EBITDA for the current year will be approximately 20% below current market expectations.
The previous guidance for net debt of approximately 150 million for the period ending 29 April 2018 remains unchanged.
It very worrying that the company has discovered a shortfall of 20% in adjusted EBITDA at this late stage in the year ending 29 April 2018. That suggests to me that either something serious has gone wrong recently, or that the company has not been correctly reporting its profits earlier this year. Or both.
A 20% fall in EBITDA would normally feed through into a greater % fall in profit before tax. So the underlying problem could be bigger.
Two specific reasons are given;
1. An accounting error, in forecasts, of £5.2m at the EBITDA level.
2. Margins have softened in Jan & Feb 2018. This is assumed to continue in March & April.
What are they doing to fix things?
A number of enhanced controls and disciplines have been introduced to address this and management believes that appropriate corrective actions are in place.
The Company has not seen any material weakness in overall demand and the previously announced cost saving actions remain fully on track.
That doesn't seem particularly bad to me. Not enough to cause the share price to crash 59%.
Broker updates - we'll have to wait until the morning, as this happened too late in the day to be covered today. Thankfully, the house broker contributes to Research Tree, so I've looked up their last forecasts, which were issued in late Jan 2018. They mention a new FD in that note, so perhaps the profit warning relates to newly discovered errors by the former FD? Or the new FD might have ballsed up the forecasting? I'm guessing there.
The old house broker forecast was for £70.0m adj. EBITDA for y/e 04/2018. This would have produced adj. PBT of £53.3m.
Today's update says 20% below expectations, so I make that £56m revised EBITDA (20% down) and £39.3m revised adj. PBT (down 26% on previous forecast).
If we assume that EPS would also be down 26%, then that gives about 17.5p revised adj. EPS for 04/2018. At 123p per share, that's a revised PER of 7.0.
Whilst that seems low, remember that CVR reckons it will have £150m net debt, which is 67% of the market cap, so very significant.
A reader comment below flags up that this might mean banking covenants in danger of being breached. Net debt: EBITDA would be 150:56, which is 2.68 - getting a bit high - and above the limit of 2.5 times (see below). Whereas on the old forecast the ratio would have been 150:70, or 2.14.
The last results statement indicates that the covenant is 2.5 times. So it looks as if the company could be heading for a bank covenant breach, perhaps?
At 30 April 2017 the Group’s net debt totalled £95.7m (1 May 2016: £86.1m) and comprised £95.8m of term loans and £10.7m drawn down under the Group’s working capital facilities, less cash of £10.4m and unamortised banking arrangement fees.
The bank facilities include a leverage and an interest cover covenant. The leverage covenant requires debt (excluding any amounts drawn down on under the Group’s invoice discounting facility) to be less than 2.5 times the last 12 months adjusted EBITDA.
The interest cover covenant requires adjusted EBITDA to be at least four times net finance charges. At the measurement date of 30 April 2017 leverage was 1.6 and interest cover was 11.5.
(excerpt from final results, published 17 Jul 2017)
Therefore, I would say that there is now an elevated risk that the company might need to shore up its balance sheet with another placing.
EDIT (10 Mar 2018) - the house broker has issued an update note, which makes some reference to the bank covenants. Its view (implied, but not specifically stated) is that CVR might remain within its bank covenants, because the £130m invoice discounting facility (of which £61.1m was drawn at the last interim results stage, is outside the scope of the bank covenant).
This is very important information. Why on earth didn't the company flag up its expectations re compliance (or not) with banking covenants in yesterday's statement? I think the company should issue another RNS, clearly explaining the situation with regard to bank covenants, to the market.
Based on the new information from WH Ireland today, it strikes me that I probably don't need to be as worried about banking covenants as I initially was. Hence this update, since new information has emerged. (End of EDIT)
My opinion - I've never been particularly keen on this low margin, indebted business, and have never owned any shares in it, as far as I can recall - although there were a couple of times when it looked tempting, on a low PER & very high dividend yield. I stopped reporting on it in 2016 once its market cap went above my then cut-off of about £300m.
Graham has reported on it more recently several times, being consistently bearish. Indeed, his report recently on 29 Jan 2018, was prophetic, so take a bow Graham, for sticking to your guns, and spotting the potential problems here over a month before this profit warning;
I am a long-time bear of this alcohol wholesaler and retailer, and have generally been on the wrong side of the share price.
Having said that, the last time I covered it, the share price was 386p. Perhaps the tide is turning
Trading is said to be in line with expectations for the full year. But although it isn't explicitly said, there is an implication that H1 did not quite go according to plan, and the shortfall will be made up in H2.
As Graham mentioned in his report of 15 Dec 2017, the problem with Conviviality is that it's "low margin, acquisitive, debt-ridden" - put those 3 things together, and it's arguably an accident waiting to happen. Note that Graham spotted the warning signs, which the computers didn't particularly - the StockRank was a fairly respectable 68 - so sometimes I think man can be one step ahead of the machines!
I do wonder if CVR bit off more than they could chew, in terms of acquisitions? Management have grown the group by about 5-fold, in terms of revenues, through acquisitions. It strikes me that the finance department just couldn't cope, and messed up the forecasting.
The balance sheet was already stretched, and now it looks likely that banking covenants might be breached. That would probably need a refinancing to be done, raising fresh equity.
Is it an opportunity now, after the 59% share price fall? For me, it's a no. My golden rule on profit warnings these days, is to forgive one-off, easily fixable issues, but to run for the hills when something serious has gone wrong (e.g. possible/likely breach of banking covenants).
As mentioned earlier this week, I've recently re-read the outstanding Stockopedia guide to profit warnings, which is available here in eBook, or here in a video. The clear conclusion from that study, was that statistically it has been better to sell immediately. On average companies which have profit warnings tend to under-perform the market for some time afterwards. That's an average mind you, so there are exceptions which do recover quickly.
I suppose it's possible that today's 59% drop might have been due to stop losses & panic sellers. I wonder if in the morning, Institutions might decide to come in and support the share price? There might be scope for some nifty trades, who knows, but personally I'll pass on that - it's too easy to get sucked into averaging down on losing trades, and before you know it, you're left with a thumping great loss, trying to catch the falling knife.
I expect Graham might mention CVR in tomorrow's SCVR, which should be interesting.
As an aside, I think we should all be questioning valuations a bit more. Given that the market as a whole seems expensive, and that share prices are slammed hard when anything goes wrong, then is risk:reward favourable at the moment overall? Possibly not.
Look at this for a horrendous chart. That fall has been so severe, I wouldn't be surprised if there's a partial bounce at some point in the next day or two?
Fulham Shore (LON:FUL)
Share price: 9.0p (down 16.3% today, at market close)
No. shares: 571.4m
Market cap: £51.4m
(at the time of writing, I hold a very small residual long position in this share)
Trading update (profit warning)
This is another one that has put out a profit warning during market hours - at 3:36pm today. This is one of the reasons that I don't personally use limit orders (automated buy orders, which are triggered if a price drops sharply). Companies need to stop doing this. Meetings to review financial performance must be held at the end of the day, so that if a profit warning is to be issued, it can be planned overnight & released at 7am. For goodness sake, get with the program guys!
Fulham Shore owns 2 casual dining chains - Franco Manca, which makes very good wood-fired pizzas, with authentic Italian ingredients. The Real Greek, which is a smaller chain doing nicely presented, but fairly basic Greek-style food & drink.
I like this group - it has experienced management, who know what they're doing. Also, based on my (admittedly small sample) of talking to staff, it treats them well - this is vital because it's not only the right thing to do, but if staff are treated well, they stay put - saving on recruitment & training costs.
There is a big shortage of good chefs at the moment, I am being told by my sector experts. Also, I recently entered the sector myself, having funded a private restaurant startup. It is tough out there! Casual dining is probably the worst sector I can think of at the moment - due to rising costs, and lots of excess capacity. Weeding out the weaker players is likely to take years.
So this share could be a long-term winner, in my view, but at the moment it's difficult to find anyone winning in casual dining, apart from the consumer.
How bad is it? Not good, but not a disaster either;
The Fulham Shore's current financial year ends on 25 March 2018 and the results for that year will be announced in mid-July 2018.
We expect to report an increase in turnover and Headline EBITDA* for the year ending 25 March 2018 over the last financial year ended 26 March 2017.
Whilst turnover for the year ending 25 March 2018 will be broadly in line with market expectations, our Headline EBITDA will, however, be below market expectations.
This is primarily due to trade in our suburban London restaurants which, whilst they are still busy, are serving fewer customers than last year with higher operating costs.
That last sentence explains what is wrong with the whole sector - fewer customers (due to over-capacity) meaning that customers are spoiled for choice. Whilst costs are rising significantly. I think even the best operators can probably only mitigate the effect of these problems, so expect profits to fall everywhere - the only issue is by how much, and can they survive?
As usual, we now have to try to work out the financial impact. I feel less inclined to buy the shares, given that the company can't just give a more straightforward - profit will be down X% to £Y. I get so fed up with the rubbish disclosures of so many company updates, wasting mine & other peoples' time, by partially disclosing the facts, and then creating a trail for us to follow back, so we can work out the actual figures.
It's difficult to avoid the impression that companies and advisers might be deliberately confusing private investors, so that people paying for research can move first, with better information?
In fairness to the company, it did warm us up to the idea of an H2 warning, with this comment published on 15 Dec 2017 with its interim results;
Although we believe our half year figures to 24 September 2017 were satisfactory, our full year Headline EBITDA* to 25 March 2018 will depend on how our suburban estate performs in the second half of the year and also on the timing and performance of new openings.
I visited a number of its new openings, and they were absolutely deserted.
Indeed, without wishing to sounds like a smart-ass, my comments here on 9 Jan 2018 specifically foresaw another profit warning with this share;
The only restaurant chain I'm interested in buying more of (to add to a tiny scrap I currently hold) is Fulham Shore (LON:FUL) . However, having seen how empty several of its new sites are (taking space from Debenhams), I think FUL could have another profit warning in it. Also I'm a little nervous about its bank debt. So I don't think there is any rush at all to go back into this very difficult sector. There are likely to be many casualties, particularly of independent operators, in my view.
My opinion - I've consulted my sector expert today. He and I both agree (and have done for some time) that FUL is the only decent casual dining sector share to even consider buying right now. The rest are dross (see EDIT below for clarification on this).
However, he reckons that this sector is in for a maybe 3-year period of terrible pain, as costs continue to rise (especially staff, and rates), whilst over-capacity means that there's not enough business to go around. It's not consumer confidence that's the problem, it's just that there are way, way too many restaurants. Some will have to close, in order to enable the survivors to rebuild their LFL sales, and margins.
For that reason, much though I would like to buy back into FUL in decent size, it feels far too early. I'd rather just wait, there's no rush here, in my opinion.
EDIT: A reader kindly pointed out that, whilst not a restaurant chain as such, Patisserie Holdings (LON:CAKE) is anything but dross. I agree with him completely, so just want to clarify that I did not mean to include CAKE in my original comment. I was more referring to Restaurant(LON:RTN) (I have a small short position on this) where tired brands are seeing falling profits, and Tasty (LON:TAST) , Comptoir (LON:COM) , and Richoux (LON:RIC) - all three of those are really struggling.
A new broker note on FUL from Allenby has been published today, which is available on Research Tree. It reinforces my view that FUL shares are not actually good value yet, despite recent falls. With the roll-out of new stores almost grinding to a halt, and with cost pressures continuing, Allenby is forecasting profits to flat-line from here onwards. Also, debt is a bit higher than I would like. So this broker update has confirmed my initial view that there's not much appeal right now to buying FUL shares. It's difficult to see much upside in the next, say, 2-3 years. End of EDIT
That's it for today. Sorry I didn't get round to CMS or IDP or TTG, but the profit warnings were more interesting.
EDIT: Graham covered IDP and TTG in the next day's report here. End of EDIT
As you might have gathered, I'm struggling with the workload, pressure & declining motivation, after 5 years writing these reports, so I'll be easing towards a sabbatical in May 2018 onwards. Partly because I want to write a couple of books on investing, and do some travelling. More on that later, but it feels like we're nearing the right time for me to pass on the baton re the daily small caps reports. But that's up to Ed & Dave of course.
Regards, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

85 comments
Seeing Paul's comments about semi-retirement made me realise one of the reasons I have appreciated the SCVR - his combination of insightfulness and no holds barred dissection of management guff reminds me of the "Weekly Shop" from Seymour Pierce's Richard "Ratty" Ratner which was great fun till his premature death 10 years ago. So Paul - how about a Weekly Shop every Monday? If you were prepared to add in regular reviews of the best chocolate éclairs on the market that would make me really nostalgic.......
Conviviality (LON:CVR)
IC now say "our faith in management is shattered ... our confidence in a near-term re-rating is low. Sell at 103p."
It seems hell hath no fury like a journo embarrassed
Paul has called the top!
Correctly imo.
We have spent the last 10 years in a QE debt financed bubble
We have crossed the rubicon
Fat lady singeth soonish.
It'll all be blamed on brexit or Trump or whatever.
Paul,
I am very pleased to hear that you wont be leaving us completely. Unlike reading the Investor mags your writing has taught us how to think like a business analyst, weighing up the available information before coming to a view. Long may it last in whatever new format that evolves. Ian
Thought for Ed and Stockopedia team, if Paul does withdraw from SCVR, would it be possible to persuade him to lead a specialist WEEKLY column on RETAIL (could include everything from all online to F&B)
Having avidly read for SCVR report for over 2 years now including all feedback, I would suggest this would be popular with the average private investor using Stockopedia and cost/time effective for all parties ie columnist, Stocko and readership. Whilst ethos is DYOR, ordinary PIs need entertainment as well to keep forking over for Stockopedia !)
Oh dear, Mr Scott! (That's for me). Oh good, Mr Scott (that's for you, the signs have been showing). I'm old enough to respect that health is the real wealth, although it is tough to prove that 'no money' can buy happiness. However, I guess - and hope - that you are not actually poor, and that you have earned some benefit yourself as well as dispensing a lot of benefit to we others......so enough to have a few business class trips in your planned travels. I will seriously miss your thorough analysis from which I have learned such a lot. I believe you are irreplaceable, not because you are perfect but because we have all become used to the qualities and style of your offerings and that would be too hard an act to follow. I hope that Ed and Co do continue with this very thorough SCVR with the appropriate staffing - 2 people of high quality, including hopefully Graham, so that it really doesn't become a burn-out experience for your successor. Come to think of it, don't know how you have continued with it for so long. If you can continue in some way, as has been suggested in other contributions, then we will all be the richer. If not, then I hope at least to have the opportunity to buy you a drink at Mello Derby before you become totally paralytic after consuming drinks bought from all those further up the queue wanting to do the same. Very best wishes for your 'retirement'.
Fortunately I operate an automatic trailing stop loss system.
Convivality looked to me a buy and hold `growth & income` stock. but your instincts only need to get it badly wrong once and it is a long way back
Unless you are Warren Buffett be very cautious about picking `buy and hold` stocks
I think that's sensible. I don't use an auto trailing stop loss as my broker only allows to put it in pence instead of a percentage, so it naturally tightens as a stock price increases (good as useless imo). Instead I use a manual trailing "back stop". I review them at least once a week.
Just to add my vote of thanks to Paul for his articles - they have been incredibly helpful.
And I agree with previous suggestions that it might still be of interest to Paul to write once a week or on an ad hoc basis when something of interest comes up - we will certainly be happy to hear what Paul has to say even if it's only on an irregular basis.
Conviviality (LON:CVR)
The Investors Chronicle's tip of the week has now been updated by a sell note.
From buy at 305p to sell at 103p in less than 24hrs.
I really love it when a plan doesn't come together!
Phil
Conviviality (LON:CVR)
This update has triggered a calamitous fall in the share price today of 59%. It's doubly annoying for shareholders when a profit warning is issued during market hours. Apparently there is a compulsion on companies to issue bad news to the market as soon as they become aware of it. Surely the process could have been managed better by the company - e.g. by calling a board meeting to discuss current trading after the stock market is closed, then issuing the RNS at 7am the following morning? Most companies seem to be able to manage that, so an intra-day profit warning just reinforces the impression that management may not be in control.
Let's imagine that the FD found out during the day and informed the Board who deferred actually meeting until 5pm and announced at 7am this morning. IC recommendation came out. Investors bought (some placing opening limit orders the night before). Company can then be sued for not releasing the info. It's not nice for us when it happens during hours, but they have no choice sometimes.
Hi Paul
2 points
1. A huge thank you for your efforts on this site and the insight that you provide. I have followed the usual suspects over the years (Simon Thompson,TW et al) and have lost more than I have made from their "tips". Your forensic analysis continues to be the only "public" review of company performance that I follow. Good luck with whatever you decide to do.
2. With regard to Fulham Shore (LON:FUL) I have some doubts as to their strategy of taking space in Debenhams (LON:DEB). I used to run a bunch of retail companies in the middle east and spent some time in negotiation with a household name American Supermarket chain who were interested in bringing some of my brands into their superstores. It was obvious that the RPF was low and it was an opportunity for them to extract some rental income from an unsuspecting(?) tenant. We did not pursue the project. One of the key problems with opening a store/restaurant in a much larger unit is the loss of brand identity (unless the footage is prominent 'front of house'). If for example, £.JLP sold/franchised their coffee shops to "Latte R us" would you arrange to meet a friend in "Latte R us" or continue to "meet for a coffee in John Lewis". I suspect the latter. If the footage isn't working for the host retailer then why should it be any different for the tenant? The fact that the host retailer is Debenhams (LON:DEB) which is a failing brand in itself is also something of a concern.
Hi cojode,
I think you might have got the wrong end of the stick, re Fulham Shore (LON:FUL) taking space in Debenhams (LON:DEB) stores. The space being taken by FUL is at street level, with a street frontage, and its own separate doorway. So you wouldn't actually notice initially that the Franco Manca pizza restaurant is within a Debenhams store, because it looks totally separate, with its own shop front & own entrance. I'm basing this on the Bournemouth & Reading sites within old Debenhams space which I have visited recently. There is also an internal door, or archway, so that customers can move from Franco Manca into Debenhams, and vice versa, but most trade is people walking directly into Franco Manca, from the street, and not even being aware that they're technically now in Debenhams.
It seems to me a sensible move, whereby DEB gets a rental income from some of its prime ground floor space, and FUL gets a decent new site, in a high footfall area, probably on attractive rental terms (I would imagine DEB probably give them a decent rent-free period, at least).
I've recently opened a new long position in Debenhams (LON:DEB) because I think it's quite interesting the way they are filling some of their surplus space with outside companies, providing restaurants, and other things - e.g. I saw an article saying that DEB will convert & sublet some of its upper floor space into workspaces for small companies. That seems a great idea to me.
Regards,. Paul.
Hi Paul
I wonder if there is a way to pass the baton on, yet still retain much of the value that you deliver to your readership here.
My suspicion, as a man with a low boredom threshold myself, is that ploughing through detailed reports on companies that you wouldn't want to invest in must be tedious. If so, how about you do one review of the week just gone highlighting anything you thought looked potentially interesting, and why?
It must be less tiring to write about companies you like the look of, I would think. And weekly takes away the pressure of the daily deadline, in that you will still be scanning results, reading discussion here etc. but you can write about shares that got your pulse to quicken only when the mood takes you. And if nothing leaps out you can say so, and wait for the following week.
Just a suggestion, and I hope not presumptuous. I am sure most of us would like to keep you contributing if at all possible, but you have done your years before the mast.
All the best
Jon
Hi JonTheTourist,
My suspicion, as a man with a low boredom threshold myself, is that ploughing through detailed reports on companies that you wouldn't want to invest in must be tedious. If so, how about you do one review of the week just gone highlighting anything you thought looked potentially interesting, and why?
That's a really good idea - I very much like the idea of me writing one article per week, focusing on the companies which I like the look of the most. Let me speak to Ed about that. The idea is that I'll still be around here on Stockopedia, writing articles in some new format, just probably not the daily SCVRs. Although I'll probably still be around to cover for Graham's holidays, or during the busiest reporting season.
Thanks for the kind comments from everyone too, much appreciated. We get such positive feedback all the time from SCVR readers, it's very rewarding to know that people find mine & Graham's work helpful.
Best wishes, Paul.
Hi Paul
Glad you like the idea.
To use an analogy from another industry, it's like being promoted from reporter, sent to follow stories wherever they occur, to columnist, expected to contribute an insightful opinion piece on whatever catches your attention. The job still comes with pressure, but of a very different kind.
And for us, your readership, we get to keep the best of what you bring to the party - brilliant analysis driven by a sense of comradeship with fellow investors, and untainted by self-interest. If that comes at any personal cost to you, I don't think we can really enjoy it. So we are all invested in finding a better way of utilising your talents.
All the best and see you at Derby.
Jon
Paul, thank you for all the reports over the years. Very insightful and helps and deepens our understanding. 5 years is a long time and a big commitment to consistently write these detailed reports on a very large population of companies. I hope we don’t lose you altogether and you will make some appearances.
All the best Paul. I don't go out of my way to ready anything by other commentators. My advice would be to take the break, then do what you want. Something else, this, or this sometimes.
And I decided not to buy £RTN! At least for now. I know there will be a time that I should (unless I change my mind about the management), but not yet, and I hope I don't forget.
Hi Paul.
Just wanted to thank you for today’s insights and wish you all the best for your sabbatical. I reached a similar sounding state of career fatigue about a decade ago and made the decision to swap a 100+ hour week in the City to that of a semi-retired house husband. Never regretted it for one minute. Horrible cliche, but I finally realised that life’s not a rehearsal, you only get one go at it ....
Best of luck.
Gus.
Been there myself Gus these days I put in about 30 hours per week and bit of trading would rather have less cash and less stress, key is not to have to much debt as that puts the hammer on freedom.
Out of interest do you trade full time you seem one of the more clued up posters on here ?
Regards
Andy
Well Paul,
Thanks as always for your detailed analysis which I look upon (as I do with Graham) as a huge and most welcome addition to my investment day. I also value and welcome the majority of contributions from fellow members, many who seemingly have more experience and knowledge than I do. It's great the way the majority here take time to document and share as well as maintaining respect (most of the time).
Should you decide to and be of the mind to continue through March and April, I for one welcome it. Should you not, or should your contributions be more sporadic, it is clearly understandable.
Hope you enjoy the well earned rest. Time and health are so important, wealth can always be gotten back.
Thanks once again and all the very best in what you do (look forward to hopefully meeting you at Mello).
Re: workload and motivation. You will be missed! I am a big fan of your SCVR and the contrast in style between your breathless enthusiasm and Grahams careful manner is part of what makes the column so good.
But if you are struggling with sleep patterns and workload something has to give. Come back stronger, or maybe just do a weekly contribution?
Conviviality (LON:CVR) even if they don't breach banking covenants, the dividend is definitely a thing of the past now for a few years while they conserve cash flow.
So a 8x PE ratio for an unsexy drinks distributor and retailer with low margins and high debt and no dividends seems like the highest rating it will get for the next year or two.
Anybody been clocking £K3C by the way? That sp 's been going like the clappers. Totally the one that got away, I think I raised it once for the SCVR back in Sept or whenever it was but without a comment on it I didn't feel confident or have the info to go in. Now just about 3x. Surely that party can't last forever!
Now I'm feeling shamed as someone who just posted a request for TTG without any contribution of my own, quite right too! :) I don't have much in the locker but to add a comment or two at least for what its worth
I think TT electronics (LON:TTG) is showing some management smarts. If I recall correctly they were in a bit of trouble in 2015, started to recover and nursed a failing transportation division back to profitability which they sold 6 months or so ago for $120m or whatever it was, turning a 60k debt into 60k on the books (apologies typing on my phone and not so easy to check the exacts here but to that effect I believe). That was a lower margin business so I expect once stocko's numbers reflect these latest results for it to look a lot better. It just suggested to me the management knows what they're doing. I've been holding since last summer so the SP hasn't done a great deal in that time but happy to carry on holding and pleased to see a generally positive market response today.
Organic revenue growth in today's numbers didn't strike me as exciting as perhaps some of the other highlights but their recent bid for Stadium, if that goes through, adds a bit of spice to the mix perhaps. I can't quite remember what other notes I took at the time (lots of broker recommendations I recall, still are though some recent downgrade on that front), in any case its been a steady as she goes type of share for me, I'm hoping continued solid success will see this go up a bit in he weeks ahead, especially if their acquisition gets approval.
Thanks
Just checked and you could buy TT electronics (LON:TTG) for under 20p in March 2009. So yes, I would agree management know what they are doing. Wish I'd bought more . . .
Jon
What the deuce? Countrywide (LON:CWD) has recovered to only 1.4 down by the close. It opened down 18.
Good point from Paul about the EV/EBITDA covenant. The Exec Chmn feels very free in slamming operational issues due to the sacked CEO but the covenant test remain behind the veil. It's a material risk to the SP. I wonder if the analysts had the wit as ask in the conf. call (assuming there was one).
Not good enough.
A poster on ADVFN says that Conviviality (LON:CVR) is tipped in this evening's Investors Chronicle @305p.
Conviviality (LON:CVR)
It is tipped at 305p. Some comments have already been made on the IC website - but as of 2 mins ago it's still there.
Phil
EDIT: Considering my subscription !!!
FREng, re: Conviviality (LON:CVR) tip in IC.
I thought honestly thought you were joking and gave you a thumbs up for giving me a laugh. Still funny I suppose... provided you don't own CVR or subscribe to IC.
Will be pretty embarrassing for the young journo. Lends evidence to the view that the company just didn't see this coming, on top of the directors' buys.
Though my view is that this sort of company ought to be on a low rating in any sane stock market - I take the same lesson as Paul from that.
Looking at other listed companies exposed to the high street food environment, Patisserie Holdings (LON:CAKE) stands out as perhaps being vulnerable.
It does have a niche position (i.e. desserts). But the forward PE assumes a healthy rate of new openings, so if management decide to be cautious and slow down for a while, it will cause the PE to deflate (even if the underlying EPS is still good).
Just my two cents!
on £CONV note that a month ago the CEO, CFO, chairman and 2 non execs bought £600k of shares. Looks like no on the board aware of the decline in trading
So the management were in the dark about the financial performance of the business?
Returns on Equity, Assets and Capital Employed all on the slide over a number of years (see StockReport) - margin so thin a puff of wind from the wrong direction could blow it away.
From the company's website:
"The Board is responsible for establishing and maintaining the Group’s system of internal control and for reviewing its effectiveness. The system is designed to manage rather than eliminate the risk of failure to achieve the Group’s strategic objectives and can only provide reasonable and not absolute assurance against material misstatement or loss.
The Board has reviewed the effectiveness of the Group’s system of internal controls and has considered the need for an internal audit function. At this stage the Board has decided that an internal audit function is not required as the Group’s internal controls system in place is appropriate."
Enough said.Bonitabeach
No position.
P.S. I do feel aggrieved for investors who are let down like this by incompetent management that appears to have overstretched itself. This is always a risk following a large acquisition, paricularly by a smaller business. Management are quick to grab the credit (and bonuses) when things go well - they deserve the responsibility when things go wrong.
I'll mention something brief on Conviviality (LON:CVR) in today's report (which will be finished later this evening, I'm in the wrong time zone in my head!!), but I've just messaged Graham to congratulate him for his correct, bearish view on this company. I expect he might want to comment on it tomorrow, so I'll keep my comments today in the main article (yet to be done) fairly brief.
Regards, Paul.
I'd like to add my thanks to Paul's step by step guides on how to dissect company updates. The quantity and detail is amazing and no wonder you need a break. I rather hope you come back, however, once refreshed but that is me being selfish. Anyway, muchos gracias
Like the other Paul wish you the best with whatever you decide I reckon your trading life would make a great read if you do pen a book remember you and your blash strategy from the Mike Walters days.
In the perfect would Rob Burns would make a great third addition to join you and Graham to reduce your work load unfortunately I feel he to will soon be riding off into the sunset, like yourself another guy who has helped the little guy learn a lot.
Hopefully you will remain around to pop in now and again in some form best regards.
Andy
Conviviality (LON:CVR) - looking like they could be in breach of banking covenant. I make net debt to ebitda about 5 now when 3 is as normal covenant. Debt up,ebitda 20% down. Wonder why they haven't mentioned this yet?
Re: Conviviality (LON:CVR) covenants. As per the half year results the leverage covenant is actually 2.5x, but this is based on adjusted EBITDA (which has share based payments are added back in) and excludes invoice discounting debt.
End H1 term loans: £94.5m
H1 adjusted EBITDA was £23.3m
H2 adjusted EBITDA forecast maybe £25m down from £40m
I think the business is normally H2 weighted but the 20% miss appears to be on FY figures. I think there is an implication that H1 figures were "wrong", but this does not affect the FY forecasts.
So ratio around 2x worsening from 1.5x? It doesn't look in serious trouble, but clearly a credibility issue.
Reference: https://investegate.co.uk/conviviality-plc--cvr-/rns/half-year-results/201801290700041242D/
Re Conviviality (LON:CVR) - thanks for correcting me on that. I didn't check the accounts (mea culpa) so assumed the savage sell-off was partly worry about the level of debt. But it seems that it may just be because the valuation was excessive
mammoko, re Conviviality (LON:CVR) , actually I think you are right - a 60% price fall can only really be explained by concerns over gearing. However I think these are unjustified as (based on the real forecasts quoted by Paul rather than my made-up figures), the tested ratio is now 1.7-1.8x.
At 100p they look cheap (updated PE of maybe 5.5) and I have bought. Convenience retail is a structural growth area with the death of out-of-town shopping (bizarrely often characterised as the death of the high street) and the return of town / city centre living (aided by by planning changes, population pressure and closure of legacy shopping). For the same reasons I think the current casual dining rout is cyclical oversupply rather than structural and will turn around in 2-3 years.
Hi mammyoko,
Thanks for mentioning the bank covenants for Conviviality (LON:CVR) - it prompted me to do some work on it, which is now in the main article. I think your figures look wrong, but it does look like CVR could be about to breach its Net debt: EBITDA covenant - see figures in main article.
Cheers, Paul.
Bravo to Graham who has been a constant bear on £CVR
Interesting RNS from Fulham Shore (LON:FUL) this afternoon leading to a sharp fall in the SP
The Fulham Shore plc
("Fulham Shore" or the "Company")
Trading Statement
The Fulham Shore's current financial year ends on 25 March 2018 and the results for that year will be announced in mid-July 2018.
We expect to report an increase in turnover and Headline EBITDA* for the year ending 25 March 2018 over the last financial year ended 26 March 2017. Whilst turnover for the year ending 25 March 2018 will be broadly in line with market expectations, our Headline EBITDA will, however, be below market expectations. This is primarily due to trade in our suburban London restaurants which, whilst they are still busy, are serving fewer customers than last year with higher operating costs.
We have opened 13 new restaurants in the financial year to 25 March 2018, taking the number of restaurants operating at the year end to 41 Franco Manca pizzerias in the UK, 1 Franco Manca pizzeria franchised in Italy and 16 The Real Greek restaurants. We are currently building a new Franco Manca pizzeria in Bath and we have exchanged contracts on a site for later in the year on South St Andrew Street, Edinburgh.
We are operating in an uncertain economic outlook for both the UK and the restaurant sector in particular. As a consequence, we will bring forward our plans only to fund new restaurant openings from our internally generated free cash flow by reducing the number of new restaurant openings for the coming year. We will also choose those locations that we believe will give us above average returns and sensible property deals.
We continue to offer freshly prepared food at great prices which, we feel, has led to our continuing profitability. All of our cash generated is reinvested back into the business. With this policy we keep our prices low and create jobs in new restaurants. Many of our employees are shareholders, creating a 'super family' of investors. In addition, our restaurant sites have been chosen with care and we have avoided property leases with excess space or particularly high rents.
This affordable menu position is where we believe we should be placed within the restaurant sector. We believe that this, along with a prudent opening plan, puts us in a good position when the UK economic environment improves.
I don't hold but it does again illustrate that the casual dining sector is over supplied.
cheers
Francis
That's a savage reaction to the Conviviality (LON:CVR) update. Down 52% and still falling.
Something that is puzzling me re. Communisis (LON:CMS) announcement today is the reduced net debt from £30.4 end 2016 to £24.3 end 2017. Looking at the Stockopedia report end 2016 net debt is listed as £21.3m and a look at the BS seemed to align with this.
On further reading of today's announcement I spotted an additional £9.3m repayment of Promissory loan notes - and there is a cashflow table showing this. However I cannot see where this item is sitting on the end 2016 balance sheet? How could I have know that the 2016 net debt was £30.4m?
marshr2 - yes, I also struggled with that problem on the Communisis (LON:CMS) balance sheet.
I decided that the loan notes were not interest bearing and therefore did not appear with bank borrowings on the line Interest-bearing loans and borrowings. Going back to last year's accounts it looks as if they are under 'other payables' as last year they passed from non-current (first line) to current (second line):
1,511 (11,474)
90,968 (71,756)
That raises the question as to why Trade and other payables have gone up this year!
"How could I have know that the 2016 net debt was £30.4m?" Answer - back to last year's announcement:
Net bank debt
(19.5)
(28.0)
Finance lease creditor
(1.6)
(2.1)
Promissory loan notes
(9.3)
(9.3)
Net debt
(30.4)
(39.4)
Not sure what it is with this week and updates being released during market opening hours... Conviviality (LON:CVR) have just released a pretty horrible sounding RNS as well. No position - or request for comment - just an observation that this habit seems to be sneaking into the market unfortunately.
EDIT: Sheesh, add Fulham Shore (LON:FUL) to that list as well, which is a shame as I really like their pizza...
£CMS
K P - as you have only just subscribed and started to post you must be forgiven. To name a stock the £ must go in front of the code and a space after - without even a space it will not work (and the system does not work with numbers anyway). To avoid a second try you could have altered the first using the edit button which appears for a limited time (an hour I think) after posting.
Paul has already said he will comment on Communisis (LON:CMS) but please note you are encouraged to say why you want a share discussed or put your view on it.
CMS£
Good afternoon,
Some interesting reader comments today, thank you. Also, I appreciate that many readers have taken on board my pleas for a bit more information in your comments, not just a one-liner asking me to do the work! That's much appreciated, and makes the comments a lot more interesting for everyone.
Here's the list of companies I've decided to write about today;
Countrywide (LON:CWD) - looks a mess, dividend scrapped on poor results
Communisis (LON:CMS) - reader request
Innovaderma (LON:IDP) - down 25% today. Reader request.
Others - Alfa Financial Software Holdings (LON:ALFA) - too big for me, although I see Graham has written about it before - he strays out of the small caps space more than I do.
Action Hotels (LON:AHCG) - re-readingmy notes from 19 Sep 2017 was enough to remind me how awful this company's balance sheet is, so I won't be covering it again today.
That's probably enough to be going on with. If there's any time left over, I might have a look at TT electronics (LON:TTG) results.
Regards, Paul.
10 minute presentation by CEO of Communisis (LON:CMS) now available:
https://www.youtube.com/watch?v=QB-ldiRcZTM
Countrywide (LON:CWD) a bit of a mess, will take some fixing
Hi Paul, will you be taking a glance at John Lewis again this year? I think I recall you investing a lot of time on reviewing the performance for the results from the previous year last time you did!
The press release for their latest annual results is here: http://www.johnlewispartnership.co.uk/media/press/y2018/press-release-8-march-2018-john-lewis-partnership-plc-unaudited-results-for-52-weeks-ended-27-january-2018.html
On a more positive note, Communisis (LON:CMS) "the integrated marketing services provider, announced full year results this morning with revenue growing by 4% to £375.9m (2016 £361.9m). Adjusted operating profits rose by 9% to £21.2m (2016 £19.5m). Communisis has also taken prudent measures to reduce its debt by 20% and pay down the pension deficit." to quote the excellent TechMarketView's free daily email.
High Stockrank. Modest rise today. Looks worth investigating. I don't hold.
ATTRAQT (LON:ATQT) (another sucker stock) has announced increased revenue and profits but whilst acknowleging that this reflected the aquisition of their main competitor, Fredhopper, last year, failed to say that the combined revenues were higher before the acquisition. The shares are up 8% today. Maybe they will find a new CEO and achieve a real recovery but I'm not optimistic. I don't hold and I'm not tempted to.
Hi FREng,
ATTRAQT (LON:ATQT) (another sucker stock) has announced increased revenue and profits but whilst acknowleging that this reflected the aquisition of their main competitor, Fredhopper, last year, failed to say that the combined revenues were higher before the acquisition...
That's an interesting insight on ATTRAQT (LON:ATQT) , thanks.
ATQT has nice software (a plugin for websites, that helps improve conversion rates through better search results). However, my worry is that it's a stop gap product. When customers re-platform their websites onto the latest cloud-based software, then they don't need ATQT any more. Hence I think it's possibly a company that is likely to wither away unless it diversifies into other products & services.
So it's not of any interest to me.
Regards, Paul.
Innovaderma (LON:IDP) seconded Paul would be good to have an idea of what warning signs you look for with this kind of stock.
Innovaderma (LON:IDP) seconded Paul would be good to have an idea of what warning signs you look for with this kind of stock.
Top of the StockReport says it all - Highly Speculative, Micro Cap, Sucker Stock. Why bother with companies like this? I don't.
All the best, Si
Another interesting point about Innovaderma (LON:IDP) and other stocks in a similar market, (Warpaint, Science in Sport, Creightons, Swallowfeild etc) is the curious difference in Stockranking by peer group.
Innovaderma has a Stockrank of 12 when ranked against European peers, but if you change the ranking to a comparison with global peers, the ranking moves to 19.
While still not good it seems to suggest that the rest of the world has some truly skanky peers.
Innovaderma (LON:IDP) - That is so so naughty - 3 weeks after stating "The Company has made considerable progress, both in terms of revenue growth and new product development across multiple categories which it believes will create additional revenue channels and substantial profitability in the second half of this financial year, and therefore the Board remains confident in meeting market expectations for this financial year."
Prime example of why I trust the price and volume action rather than what companies say.
£Innovaderma - This guy Haris Chaudhry seems to say the same things all the time ie market share increasing , share price tells a different story share price now down 65% since high 9 months ago , fortunately my holding was embarrassingly tiny so not too much damage done maybe Stocko right 'sucker stock' and what with the 10am announcement ? All a bit messy in my view interested in other opinions on the stock .
Innovaderma (LON:IDP) have released a trading update stating full results will be similar to FY17 and orders being placed by Superdrug have been less than expected.
https://www.investegate.co.uk/innovaderma-plc--idp-/rns/trading-statement/201803081013481171H/
Another for Communisis (LON:CMS) please - what is your take on the balance sheet now that both net debt and the pension deficit are down?
Net debt reduced by £6.1m to £24.3m (2016 £30.4m)
The pension scheme accounting deficit at the year end decreased to £38.2m (2016 £55.5m).
This is the 19th top-ranked share (98) but I am put off by the management-speak verbiage.
I had more of a read whilst travelling today and I have to say that whilst I often do have something of an aversion to management-speak/ BS; in this case I didn't find anything that I took exception to - all fairly rational I thought.
However, for the strategy review to target growth in EPS of 5% PA is hardly inspiring. To be fair it probably does reflect that a lot of the markets are quite mature, but even so on that basis this aint no multi-bagger!
Based on what they are doing, I'd suggest they are under-promising in the hope of over-delivering, which is always good, but I'd really rather see a little more ambition.
I bought my small position on a "strategic ignorance" basis, so I'm reluctant to start tinkering now, but whilst this looks like a decent company doing the right things and at a relatively cheap rating (earnings wise anyway) I don't think I'd be compelled to buy on what I've seen. Seems that maybe "the market" agrees - having been up 11% in early trading it closed only 3% up (as was briefly negative in the afternoon)
Any thoughts on 4imprint please Paul? Results out yesterday resulting in sp down.
Thanks all for the link advice, I'll use my eyes also next time
Alfa Financial Software Holdings (LON:ALFA)
please
20% fall on what sounds like a reasonable earnings announcement.
Perhaps it got ahead of itself.
FYI andrewb, might be useful...
https://www.sharesmagazine.co.uk/news/shares/the-market-may-have-over-reacted-to-a-minor-setback-in-alfa-financials-results
Thanks
Can I second Communisis (LON:CMS) please - I sold out at 62p, but it's quite spikey so I might buy any dips for the boring and reliable dividend part of my portfolio. They recently had their TV licencing advertising deal extended.
A decent looking set of results from Communisis (LON:CMS) . EPS up 5%, strong cashflow & useful reduction in net debt.
Last covered here in August, when Paul was not too impressed with the balance sheet (should be somewhat better now). I don't know too much about them, but have a small position in a "strategic ignorance" portfolio experiment.
I'd be keen to hear your thoughts on TT electronics (LON:TTG) Paul if poss! Thanks
I would be interested in your views on TT electronics (LON:TTG) Paul. The turnaround of the company is gaining traction with the sale of the transportation division, margin improvement, increased ROIC, sales and order book. Following the sale of the Transportation division the company has net cash of £47m, pending the purchase of Stadium (LON:SDM). Underlying EPS up 40% at 10.9p (2016 7.8p). Market cap about £415m.
Cheers
Jonno
Hi Paul
How about Spirent Comm PLC (SPT)
FY PBT 43M / aPBT 59M / REV Flat / Cash 128M / Free Cash 56M / FY18 H2 Weighting / MCAP 665M
Not sure on the H2 weighting but looks to have streamlined and focused in growth areas.
Perhaps the MCAP to high to qualify ?
Origin Enterprises (OGN), I don't have a holding but I coughed at the nett debt to pbt (a small loss) for the half yearly today and the claim for a strong balance sheet, until I looked at the full (last) year which indeed gives a much better nett debt ratio, can anybody explain how and why their profitability suddenly increases dramatically in the 2nd half please
Confused.
I'm sure I'm In a minority but I'd appreciate a look at Share plc (LON:SHRE). (as an aside how do I add the link to the share here ?)
With rising interest rates and increasing market share the results look ok to me:
Revenue and revenue market share reached record highs - helped by the emerging benefits of a major new partnership agreement and strong trading volumes
Revenue up by 28% to £18.7m (2016: £14.6m):
commission income rose by 51% to £10.6m (2016: £7.0m)
fee income grew by 7% to £7.2m (2016: £6.8m)
interest income increased by 14% to £0.9m (2016: £0.8m)
Revenue market share excluding interest (*) reached 12.81% (2016: 9.85%)
Assets under administration increased by 27% to £4.7bn (2016: £3.7bn)
Operating losses reduced by 41% to £0.8m (2016: £1.3m)
Profit before tax was £0.4m (2016: £1.0m) including respective one-off items
Underlying (**) earnings increased to £383,000 (2016: £4,000)
@threeputt
You put a £ in front of the ticker without any spaces. It only works on symbols that are all letters, numbers throw it out.
So Share (LON:SHRE)
Edit: That’s interesting, no idea why that didn’t work! I’m typing this on iPad but that hasn’t been a problem before.
Share (LON:SHRE)
Further edit, I’m seeing it displayed differently now so something changed between my edits.
The way to create the link is to put a £ sign immediately before the ticker symbol but don't put any punctuation immediately after the ticker symbol. Hope that's clear
cheers
Francis
Or if you forget the hint is at the bottom of the Discuss trail
Not sure that Share (LON:SHRE) is Paul's kind of thing, but Graham has expressed an interest in getting in once revenue started rising significantly. I hold, but rarely look at it, it's that kind of share. It also stops me resenting any dealing and account charges . . .
Jon
My morning smallcap tweet:
Countrywide (LON:CWD), Tern (LON:TERN), FIH (LON:FIH), Action Hotels (LON:AHCG)
Countrywide (CWD) FY. Having sacked the CEO CWD discovers a sudden honesty: "2017 A DISAPPOINTING YEAR...Industry expertise in all areas of our business is key. Within Sales and Lettings, the previous strategy resulted in us losing a lot of that expertise". U/L EPS 8.4 (19.3). Div passed. Outlook: Pipeline significantly below that of 2017, taking steps to build back the pipeline "but this will take time". Guides H1 EBITDA down £10m, unlikely that the shortfall in the first half will be recovered. I'm short.
Tern (TERN) There is life after death spiral! TERN terminates Convertible Unsecured Loan Note facility, raises £650k at 2.55p, a 15% disc. The SP was 5p when it announced the death spiral in Nov.
FIH Group (FIH) Guides FY pretax higher than previously anticipated, and materially ahead of 2017. Outlook for the following year remains generally positive.
Action Hotels (AHCG) Guides FY Revenue and adjusted EBITDA broadly in line with market expectations but pretax loss materially higher than expected at approx. -$12.2m "mainly due to not being able to capitalise some of the interest costs in the year ended 31 December 2017 as there were delays in two hotel openings, early repayment fees and a higher than forecast depreciation charge as valuations have increased." Will significantly reduce divs going fwd. Outlook: recent 2 months encouraging. LFL rev up 6%.