Small Cap Value Report (Fri 9 Mar 2018) - TUNE, RM2, TTG, VLE, IDP

Good morning! Taking into account reader suggestions so far, my list is as follows:
- Focusrite (LON:TUNE)
- £RM2 (LON: RM2)
- TT electronics (LON:TTG)
- Volvere (LON:VLE)
- Innovaderma (LON:IDP)
Only the first two were announced today, but there was quite a lot of news during the week, so plenty to discuss.
Also worth mentioning that I think Paul did a fine job discussing the late profit warning from Conviviality (LON:CVR) in yesterday's report, so I'll leave that one alone for now.
Cheers,
Graham
PS: There is an investor event coming up on March 28th in London, featuring the CEOs of Cloudcall (LON:CALL), Xpediator (LON:XPD) and Realm Therapeutics (LON:RLM). You can get your free tickets at this link.
Focusrite (LON:TUNE)
- Share price: 380p (+7%)
- No. of shares: 58 million
- Market cap: £221 million
This company makes hardware and software products for the music industry, under its own brands. Headquartered in the UK, it distributes its products worldwide.
Rather than making or distributing musical instruments, the company makes the tools used by producers - microphone preamplifiers, audio interfaces, synthesisers and apps.
This is a nice update, which has been warmly received. First-half revenue, profits and cash are up year-on-year.
As a result, revenue for the half year ending 28 February 2018, is expected to be over £38 million, up from £32.0 million in the same period last year. This represents an increase of over 25% on a constant currency basis.
Conversion to cash has also remained positive and, as at 28 February 2018, net cash was £19.7 million, up from £14.2 million on 31 August 2017 and £9.4 million on 28 February 2017.
For a company which sells internationally, such as this one, constant-currency measures are what I focus on. Needless to say, 25% is a fantastic gain.
The CEO comments that the recent Christmas holiday period gave the company a big boost, stating that the outlook remains "confident" for the future:
We keep a close and cautious eye on some of the headwinds being experienced by the music retail industry, particularly in the US, but overall believe we remain well positioned to continue to grow as our strategy of "making music easier to make" resonates with consumers throughout the world.
Some have expressed dissatisfaction that there is no reference to market expectations in the statement.
For what it's worth, I can see revenue forecasts for the current year of £72.6 million, up 10%, i.e. much lower than the growth actually reported for H1. If you include the negative currency effect (beyond Focusrite's control), the revenue growth reported is 19%.
Full-year revenue growth may be difficult to sustain at 19%, as the CEO's comments regarding Christmas suggest that buying might be more weighted to Christmas than it was before. In doing so, he has helped to manage expectations at a lower level.
Because of this cautious approach, commissioned researchers (linked to in the comments below) have increased their EBITDA/PBT expectations for this year and next by only around 4-5%.
As Paul has noted before, Focusrite has a track record of beating expectations. Today's statement and the response by analysts give the company plenty of room to beat expectations again in the rest of FY 2018 and in FY 2019, I think:
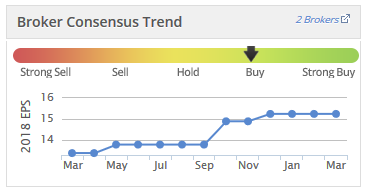
My opinion: so far, I like what I see. The company's products are high-tech and potentially best-in-class, although I would need to perform more research to confirm this. Even though it's in roughly the same industry as Gear4Music (G4M), it's a completely different animal. And while Gear4Music is a good company in it's own right, I would personally attach a much higher multiple to Focusrite.
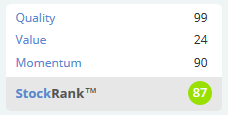
So I agree with Focusrite's StockRank - it looks attractive, even if it is more expensive than average.
£RM2
- Share price: 4p (+260%)
- No. of shares: 407 million
- Market cap: £16 million
Financial Position and Product Update
This next-generation pallet manufacturer comes storming back above our minimum market cap threshold with a positive update.
I've written very bearishly about it in the past, and expressed the view that it wouldn't be refinanced, so it's only fair that I mention it when the situation is less gloomy.
To recap, RM2 previously warned that it would run out of funds in February, and then later said that it would run out in March. Today, it announces that it has found the funds to survive into April:
The Company is now pleased to report that, following the sale of a non-core office building in Switzerland and repayment of the related mortgage, it received net proceeds of approximately $2 million and is therefore able to extend its cash resources to continue operating through mid-April based on information available to it today.
Great news, but I do have to wonder why the building hadn't been sold already, given how close the company has been to going bust? Furthermore, RM2 has its head office in Luxembourg, and its headcount had already been reduced to 44 by the end of 2016. So I wonder what the purpose of owning a "non-core" office in Switzerland, valued in excess of $2 million, could have been?
All that having been said, it's a good thing the company will survive a bit longer. And it's still trying to raise equity:
The Company is in advanced stages of financing discussions with the support of its existing shareholders and will announce developments to the market at the earliest possible opportunity.
Last September, at the interim results, RM2 said:
"The Company confirms that it is in an advanced discussions with one particular party, which has conducted extensive due diligence on the Company over the past few weeks, and hopes to be able to conclude negotiations in the coming weeks.
So the refinancing has been a long time coming, especially considering how close it was to happening six months ago.
There is a well-known fund manager who might be involved in the refinancing, should he not wish to be diluted. I previously assumed that he would let the company find some other resolution to its financial difficulties, even if that meant shutting down.
As the company continues to claim that it's in advanced stages of discussions, I'm beginning to doubt myself. Maybe I was wrong, and there really is another tranche of fresh funds coming RM2's way?
Tantalisingly, the company promises that it will be EBITDA-positive, next year, if it can only convert and execute some sales:
Significant opportunities with Fortune 500 companies are in final trial phases. The conversion of a subset of these opportunities, deployed and financed on schedule, is expected to result in the Company generating positive EBITDA in 2019.
My opinion
My view is a simple one: there is no point in getting involved with these shares in the secondary market, before the refinancing has occurred. Of course, anybody who does that might get lucky (e.g. someone who bought yesterday and sold today).
But there is no getting away from the fact that the company is running out of money, and that existing shareholders are going to be diluted, perhaps very heavily. If I believed in the story, I would seek to take part in the refinancing, or buy shares afterwards.
Buying the shares before the refinancing means risking the loss of your capital if a) the refinancing fails to proceed, or b) existing shares are diluted to negligible value by the deal. That level of risk is ok for gambling money, but not ok for investing money.
The company's products are in "final trial phase". They've been in trials for a long time, and sales/rental income has remained very low.
TT electronics (LON:TTG)
- Share price: 227p (+1%)
- No. of shares: 162 million
- Market cap: £369 million
This is an electronics business we occasionally cover in these reports. It was reorganised last year into three divisions: Sensors and Specialist Components, Power Electronics and Global Manufacturing Solutions. It engineers and delivers electronic products to a wide range of end-markets: industrial, aerospace, defense, medical.
I had a positive impression of the company and thought that the shares looked reasonable value last August, at the half-year results (share price at the time: 214p). It had great cash conversion, modest underlying growth, and an admirable focus by management on ROIC.
Also, its balance sheet was transformed by a big disposal, so that it now had substantial net cash rather than net debt.
Here are the financial highlights, with the yellow marker added by me:
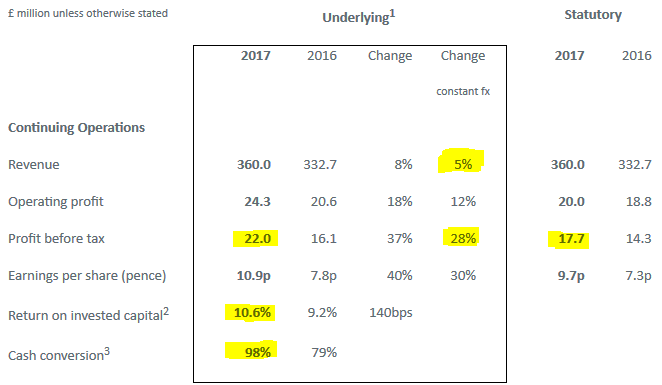
So there was 5% revenue growth at constant exchange rates - not bad. This is the organic growth rate.
Underlying profit increases 28% at constant exchange rates to £22 million - excellent. The high growth rates in operating profit and PBT show the benefits of operational leverage.
Return on invested capital breaks through 10% - great news. I mentioned before that 10% was not a particularly high rate, but that management's focus on it was a green flag for investors.
Finally, cash conversion is close to perfect, using underlying numbers. Another good sign.
Alternative performance measures
Let's try to make sense of the adjustments used to get the underlying profit measures. There were £4.3 million of favourable adjustments to get underlying operating, as follows:
- Negative £3.7 million in site restructuring costs
- Negative £2.3 million of amortisation of acquired intangible assets
- Negative £0.4 million of acquisition related costs
- Plus £1.9 million in unusual pension gains
- Plus £0.2 million in profit on sale of properties
If I scroll back to 2016, there were £3.7 million in favourable adjustments, and in 2015 there were £5.4 million in favourable adjustments.
While I can understand the rationale to make all of the adjustments, and the company has made a strong case for their inclusion, I still have the impression that unusual expenses are a fact of life for the company. I would therefore be inclined to emphasise the reported numbers, rather than the adjusted numbers, for the purpose of valuation.
I could possibly make an exception for the amortisation of intangible assets - maybe compromise by adding back half of them instead of all of them? Their presence is one of the reasons why the company generated fantastic underlying cash flow (pre-tax) of £38.6 million.
Profit on Disposal
Note that there was a big profit on the disposal of its transportation division, including both the profits generated by this division before it was sold, and the gains made in the sale itself.
Profit for TT electronics (LON:TTG) including discontinued operations, i.e. including the benefits of the transportation division, is £32 million, and basic EPS including discontinued operations is 29.5p. Be careful not to use any figures which include these numbers, as the disposal-related profit is not repeatable.
Net cash - the company's pile of cash is set to be used up for the purchase of Stadium (LON:SDM), which will cost £45.8 million plus £11.8 million in net debt.
With the cash being used up in this acquisition, TT declares a somewhat modest 4% increase in the final dividend, to 4.05p.
The outlook statement is confident:
We enter 2018 benefiting from the increasing proliferation of electronics in our markets. We are focusing our resources where we have strong and differentiated capabilities and are again increasing our investment in R&D and business development to maximise this opportunity. Momentum in our operational performance and our improved order book give us confidence, despite current foreign exchange headwinds, of making strong progress in 2018.
My opinion
I still have a positive impression of this company, indeed even more positive after browsing these results.
Customers sound very keen, making their orders earlier in the year than usual and giving the company a stronger order book. Organic revenue growth is not huge, but should hopefully hold up around the current level. Brokers have been forecasting revenue to grow another 2-4% in FY 2018.
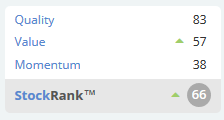
The StockRanks also view it as better-than-average.
Volvere (LON:VLE)
- Share price: 1000p (+2%)
- No. of shares: 3.7 million
- Market cap: £37 million
Trading Update and Notice of Final Results
(Please note that I own shares in Volvere)
This is my largest personal holding by some distance, currently almost 20% of my portfolio (excluding cash). I wrote about it last year in this report: in May and in September.
Please note that I didn't intend for it to be such a large percentage of my portfolio, and wouldn't put 20% of my portfolio into it today! The share price increase is what has created this situation for me.
Also worth noting is that its bid-ask spread can be vicious, perhaps a by-product of the small free float. The directors own 38.5% of the company.
On Wednesday, the share price gained about 11% on the back of this trading update for the full-year ending December 2017.
Headline numbers are excellent: revenue of £43.2 million (2016: £33 million) and PBT of £3.2 million (2016: £1.9 million).
As discussed before, Volvere is an investment company with effectively just two investees (there is a third, but it remains tiny for now). It is extremely patient in acquiring new businesses, and typically only holds a few at a time. It searches for opportunities to buy companies when they are in need of some kind of restructuring, and can be bought at a favourable price.
Impetus Automotive (link), for example, provides support services to the automotive industry. Clients have included VW, Jaguar Land Rover, Audi, and many others. It helps these companies to optimise their sales and aftersales strategies.
Impetus was bought by Volvere for just £1.25 million in March 2015. That figure includes the funds which were needed to pay off some outstanding bank debt. Further funds were needed for working capital, so that Volvere put about £2 million in total into the business. It turned a small profit in 2015, and then trading really took off.
Revenues grew to £17 million in 2016, and £27 million in 2017. Pre-tax profits grew to £1.5 million in 2016 and now £3.4 million in 2017. These figure are stated before the interest and management charges which Volvere Plc charges to Impetus.
How did they do it? One of the things which they seem get right is supporting the existing management - they don't try to tear everything down and start again. Instead, they listen to company management and help them to implement positive change. They incentivise management too, with an equity stake in their businesses. Because of this, Volvere Plc only owns 83% of Impetus (and is thus entitled to 83% of the profit figures mentioned above).
Support services businesses have had some notable calamities recently, but Impetus is bucking the trend and performing extraordinarily well, if these figures can be believed.
The other major investee, Warwickshire-based Shire Foods (link) produced a modest profit of £0.6 million for 2017, after a one-off impairment charge of £0.2 million. Conditions have been tough for makers of pies and pastries.
If you're wondering how all of this can add up to a market cap of £37 million, bear in mind that Volvere has cash of £18.4 million.
So even after all of the share price gains so far, the investees are only being valued at about £18 million. You could argue that this is quite a generous valuation, given how much was paid for them (not much - only about £2.5 million was put into Shire).
On the other hand, it's not very much compared to trailing pre-tax earnings (before impairment charges) of £4.2 million (£3.4 million from Impetus and £0.8 million from Shire), of which Volvere Plc's share is worth about £3.4 million. I make this a pre-tax earnings multiple of about 5.4x.
Not bad, especially when you consider the growth trajectory that Impetus is on. And the £2.4 million of freehold property owned outright by Shire Foods. Any disposal would trigger large bonus payments to the directors, but the multiple is arguably still too low.
Conclusion - I am happy to continue holding.
When the results arrive, it will be interesting to see what are the £6.3 million in marketable securities which Volvere has purchased over the last year. The boost from rising short-term interest rates could have a lovely effect on the cash pile's profitability.
Innovaderma (LON:IDP)
- Share price: 122.8p (-2%)
- No. of shares: 14.4 million
- Market cap: £18 million
This profit warning was published after the market opened yesterday, and we are catching up on it today.
Innovaderma is a small house of brands in the personal care space. You can see the portfolio here (external link). Skinny Tan has been the most exciting element so far.
As was pointed out in the comments, it hasn't been long since publication of the interim results - only three weeks, in fact. The outlook printed then didn't point to any problems.
Times have changed:
"...revenue growth for the year will now be less than anticipated at the time of the interim results. This has been mainly driven by lower than expected orders placed by Superdrug for Skinny Tan despite the brand's continued growth."
That is a surprise. Skinny Tan was previously reported to be best-selling product in its category at Superdrug. Perhaps the company simply got too optimistic about how fast the progress would be?
Indeed, the company reports today that Skinny Tan sales more than trebled in the year ending on Feb 24, 2018. This year-on-year growth had slowed to 60% for the last 12 weeks of that period.
As a consequence of growing pains, there won't be any profit growth this year:
The Group expects revenues to be substantially higher than last year. The profit before tax is now expected to be similar to FY17 due to the significant investment made across the business over the last six months.
Company-funded research points out that Superdrug's exclusive Skinny Tan license is due to expire later this year, which might explain the retailer's reluctance to continue stocking large quantities of the product.
The company has a June year-end, and has been heavily weighted to the second-half. Let's figure out what is likely to happen in H2 2018:
- In FY 2017, Innovaderma made a pre-tax profit of £1 million, with H2 profit of £1.2 million.
- In H1 2018, it was close to breakeven.
Therefore, to match the FY 2017 result this year, pre-tax profits in H2 2018 should be around £1 million. That's about a 15-20% deterioration compared to H2 2017, and the full-year result is even more disappointing when you consider that FY 2017 results were affected by about £0.3 million of one-off listing and set-up costs.
My opinion - I am sympathetic to the company. Rapid growth is hard to manage, and doesn't happen in a straight line. The huge order growth from SuperDrug was inevitably going to be difficult to predict.
Having said that, this is a serious blow to investors. Pre-tax profit this year was supposed to be £2.3 million, according to previous forecasts, and now it is going to be less than half of that. It's a dramatic worsening.
At least we are told that every other part of the business is performing as planned, in particular the Direct to Consumer platform for Skinny Tan and the very promising Roots haircare range.
My major concerns around the stock over the past year have been
- I thought the company had expanded too much, too soon, distracting itself with acquisitions and eventually causing itself to run out of working capital (it raised £4.4 million at 276p in October).
- The valuation become very racy, as the share price at one point exceeded 400p (not long before the company ran out of working capital).
I am a bit more interested now, with the share price back down to 120p. After-tax net income is going to be a disappointment this year, and EPS will be negatively affected by the increased share count. But I'll keep this on my watchlist, looking for evidence that FY 2019 will be a return to form.
That's all for today and for the week. Cheers!
Graham
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

44 comments
I am a voice artist. I think that Scarlett is close to being the industry standard for home studios.
Re Focusrite (LON:TUNE) there's a nice interview with 'socialist capitalist' Phil Dudderidge here https://www.psneurope.com/business/focusrite-chairman-phil-dudderidge-interview He doesn't sound the sort of guy to over-ramp projections, but presumably there's a risk that he will further reduce his holding towards retirement. There are several genuine-sounding testimonials/ case studies on their news page https://uk.focusrite.com/news I've no industry knowledge but it looks as though a typical studio will buy quite a lot of gear if they decide to adopt Focusrite. A chap on advfn also reckons that in time Thunderbolt may replace USB connectivity for high-end studio equipment, giving a further sales boost. None of this is at all quantitative, I'm afraid!
Millen - Thanks for the Focusrite (LON:TUNE) trade mag link. The most interesting part for me is :
Its move to become a public company in 2014 has allowed Dudderidge to offer his staff a direct stake in the firm. As he puts it, people join Focusrite “not just because they are looking for a job but because they are looking for a career”, such is the high percentage of staff that remain with the company on a long-term basis.
I checked Glassdoor and Focusrite score a very creditable 4.5/5. Comments below are typical...
Amazing people who love what they do. There is always a desire for improvement. Free canteen for breakfast and lunch.
https://www.glassdoor.co.uk/Re...
So another aspect of their Moat is their committed staff and a free canteen to keep the troops fed. Not rocket science and helps to explain how they have got where they are.
Another example of investing benefiting from being a team sport. Thanks again. Ian
Can anybody identify why there has been a sell off in the Insurance sector Preference Shares over the past 2 days. In particular Aviva and RSA????
Yes see this this post: https://www.stockopedia.com/content/aviva-and-the-current-price-collapse-of-irredeemable-preference-shares-336348/
Hi, Aviva suggested yesterday that they may be able to repay their prefs at par. All were trading well in excess of par. Market sold off significantly this morning, but had bounced by about 10 points by lunchtime.
Looks like the Volvere (LON:VLE) share issue above doesn't take account of the share buy back, should be about 10% lower
Thanks, re: Volvere (LON:VLE). Fixed it.
great report on volvere, Graham. Many thanks
I see Renold (LON:RNO) has put out a profit warning today due to increased costs and with US$ falling affecting their US business. It does not that bad but shares are down 21%.
Graham - just a heads up for later this month.
A year ago you wrote positively about Robinson (LON:RBN), saying that its market cap of £20m looked reasonably attractive in view of its freehold assets. It hasn't sold its surplus land yet, but put out an inline trading update in December and nothing since then. It reports around 23 March. The market cap is now £15m
I don't hold, but there could be value here, despite the spread. The dividend is 6% and they have never reduced it - perhaps because it's family held.
Thanks FREng, acknowledged re: Robinson (LON:RBN).
Just like to record my appreciation of the continued high quality analysis from Paul and Graham every day.
Easily worth the subscription to Stocko by itself. It has changed my investment approach and I have profited hugely.
Yes , I know we have been through a Bull market, but we have had them before and I have not profited to anything like the same extent.
Thanks, gentlemen.
BB
Graham,
Thanks for the Focusrite (LON:TUNE) write up, that I think sums it up nicely. I re-brought an initial position 1st thing, having believed it to be expensive. I had previously noted the company sales to be H2 weighted, so the smashing H1 and the CEO's Xmas phasing comments are particularly apposite.
Looking at the company's impressive return numbers and sales increase it must have a wide Moat and a dominant position in its niche. I would be interested to hear from others if they know of more specific Moat like Focusrite characteristics? Ian
Hi Ian, you're welcome re: Focusrite (LON:TUNE). I am also interested to learn more about the company's positioning vs. competitors. G
Ex Studio engineer here, FWIW
Focusrite (LON:TUNE) was a very well respected brand for premium studio equipment when I was sweating over hot mixing desks. They have successfully used that premium brand to offer more 'prosumer' kit, but still with the audiophile quality at the forefront, no doubt helped by the ubiquitous USB interface. There is a fair amount of competition from other names in that field (Lexicon, Behringer) but with a mid price point (they are not the cheapest) they appear to be defending their position well.
Their Novation brand of synths and controllers was never my bag of chips (call me a snob) but a quick look at their current range could make me change my mind as they seem to have come a long way. Probably helped by Chris Huggett, a man who invented 2 classic British synths (OSCar and WASP) and co-developed the ground breaking Akai S1000 sampler.
My 16-bits worth!
(I hold)
voda, Thanks for your 16 Bits.
So are we saying about Focusrite (LON:TUNE) : Strong Brand , Quality Products, Innovative Design? Are you aware of any Patents, or Cost advantage?
My pleasure, Ian and yes that sums it up.
Focusrite (LON:TUNE) I've done a very basic patent search and can only find 4, none of which appear to cover the mic pre-amp/audio interfaces that constitutes a big part of their range. Pricewise they are definitely at the higher end of the spectrum, although they do sell units for £100 (equivalent Behrniger is c£50). Can't imagine they are selling many of the £2500 RedNet interfaces, so it's all about the hobbyist buying into the X-factor dream.
Anecdotal evidence alert: I was in a coffee bar last week and overheard an aspiring singer comparing notes with a random passer-by and they had both bought Focusrite Scarlet.
Excellent, thank you for that re: £TUNE!
I wondered if anybody has any views on how long low ratings of smallcap consumer stocks are likely to last. Surely these example forward P/Es are not normal:
Conviviality (LON:CVR) - under 6 (based on 25% EPS drop)
UP Global Sourcing Holdings (LON:UPGS) - 5.7
United Carpets (LON:UCG) - 5.2
Bonmarche Holdings (LON:BON) - 6.4
Connect (LON:CNCT) - 4.4
Some of these are carrying a fair bit of debt, but none look stressed (yet) to me. Most have recent updates reflected in estimates (I have adjusted CVR). The two companies in this space that do look genuinely stressed to me (Debenhams (LON:DEB) and Greene King (LON:GNK) ) are rated higher at around 7 so I think perhaps this is a smallcap thing.
On United Carpets (LON:UCG), I was initially attracted to them but then realised that they hold the master leases for the properties they then franchise out. This is a typical franchise model, but it made me uncomfortable because if franchisees hand back their franchises, then UCG has all these lease obligations.
Bonmarche Holdings (LON:BON) has been a serial disappointer over the last 1-2 years. But maybe turning around under new leadership and maybe their revamped online site is going to start seeing good growth?
Conviviality (LON:CVR) discussed to death in yesterday's comments. Very polarising in terms of how you can view the prospects.
Debenhams (LON:DEB) a restructuring is definitely on the way, especially with Sports Direct almost at 30%. But small shareholders likely to be shafted in any restructuring, so I'm staying away for the time being as the big boys battle it out and secure their spoils.
Sentiment about United Carpets (LON:UCG) is likely to be affected by the last Carpetright (LON:CPR) update which didn't look very promising. It's also very illiquid which means it will likely never be on a normal PER. I hold but I would probably sell once it reached a p/e of say 7.5-8.
Brewers often have high debt, presume much is tied up in their pubs, Marston's (LON:MARS) looks even more stretched both pay out about 7% dividend.
RM2 up over 300%. This is the pallet company which sticks trackers on their pallets so they don't get lost or nicked. They've sold their office in Switzerland for a couple of million which should keep them afloat until mid April, however the main point of interest which has really excited the market is the fact they're looking for positive EBITDA in 2019. Can we believe them? is this a dead cat bounce? do we want to invest in a company Woodford is so bullish on? Will they even have any cash left in May? This is one of those stocks where you lose you entire investment or make it back 10 fold.
On £RM2 even in the best case scenario where they secure some order contracts and get refinanced in the next month or two, why buy now?
The best outcome still requires an equity raising, and this will be on whatever terms the new investors want, given the financial position of the company. So might as well buy shares post-equity raising, when there will be concrete evidence of the following:
1) How much new cash and how much runway the company has
2) What contractual order commitments the company has with all those S&P500 companies who are trialling the product
Sure, you'll have to pay more for the company valuation at that time, but if you truly believe their new IoT product will revolutionise shipping, then there's still lots of SP appreciation to come.
Hello Graham,
Could you please have a look at Frontier Smart Technologies Frontier Smart Technologies (LON:FST) if you have time.
The FY 2017 results look good/ok to me, but a 'modest' statement about future growth probably pulled them down. Like many small caps they seem to be drifting down over the last 3months. They have smart speaker technology which is the potential growth area and a fairly solid business elsewhere. I had a small holding and was stopped out today.
Thanks
John
Yes TT electronics (LON:TTG) does seem interesting, not a company I have looked at before, figures on Stockopedia seem incorrect.
Another vote for discussion of Volvere (VLE) please. Thanks Graham.
I third Innovaderma (LON:IDP) (I hold with the desperation of a man holding his trousers up when the elastic has just snapped in them as he was innocently walking through a park full of children in a rough area in the middle of a paedophile scare).
Hi Graham. I'd also like to read any comments about Innovaderma (LON:IDP). It seems updates from this company regularly lack sufficient detail for the market to value - maybe why it got knocked so badly yesterday? Also would appreciate your views on the trading update from Focusrite (LON:TUNE). Very positive sounding update, although no comment about how performance is stacking up against market expectations... I think Paul has previously written positively about this company.
Hi ppdrs, writing about both of them today, thanks for the suggestions. G
This mornings update from Edison on Focusrite (LON:TUNE)
http://www.edisoninvestmentresearch.com/research/report/focusrite506015/full
I used to hold but maybe the current price of 360-368p is about right?
Another request for Focusrite (LON:TUNE) please. I have held for some time. They seem like a solid well run company, a leader in their field, but (as stated above) their trading updates are a bit on the vague side.
And, if time permits, a look at Microgen (LON:MCGN) (audited preliminary results were out on Wednesday) would be much appreciated. These results look like a clear beat on revenue and EPS with some optimism for 2018.
Hi Graham - Paul didn't quite have time to cover Innovaderma (LON:IDP) yesterday. I haven't properly read the results but it looks like the share price has taken a big beating and I wonder if it's overdone given the revenue growth. Would welcome your view.
Good morning Graham
Given that it seems a fairly quiet morning on news front, I wonder whether you might have time to circle back and look at TT electronics (LON:TTG) prelim results from yesterday. Paul had intended to do so but ran out of time. Also given that you have covered the company previously your views would be appreciated.
Cheers
Jonno
I'd also like your view Graham on TT electronics (LON:TTG), please, as Paul had meant to cover it...
I know it's not small cap territory in the slightest, but Bodycote (LON:BOY) HAS been mentioned here before and so if you're able to do even a brief comment please that'd be fab!
Andrea
Focusrite (LON:TUNE) trading update for H1 2018. I've held for a while and believe it's a high-quality company, however I feel the content of their updates leaves much to be desired.
In January they simply stated 'our revenue and cash had both grown further since the year end'. Today they say 'in the first half of the current financial year ending 31 August 2018, revenue, profits and cash have grown compared with the first half of the last financial year.'
They then let us know revenue is up 25% y-o-y, and cash balances increased, but they once again don't say anything about margins or the actual level of profitability. Stockopedia shows revenue was only forecast to rise 10% for the full-year, so this appears to be a very encouraging update, but if they don't say anything about profitability we can't really make an informed judgement, and are simply left to assume and second-guess.
I couldn't disagree more strongly with those complaining about the lack of detail in the Focusrite (LON:TUNE) trading statement.
This statement covers the first half year ending 28 February and was issued at 07:00 on 9 March. It has thus been delivered to the market in just six working days. I think this is extremely commendable.
The downside of such an extraordinarily fast turnaround is that it limits the detail that can be given. Focusrite is a relatively simple business, so revenue and cash basically come from a process of adding up. They would be setting themselves up as a hostage to fortune by attempting precise statements about profitability so soon after the period-end. However, the fact that they make no mention of it indicates to me that they anticipate margins to be broadly in line with expectations.
I also sympathise with the omission of any comment regarding performance against market expectations, with half a year still to go. There are no market expectations for the half year and, with six months remaining, plenty could still go awry.
Nonetheless, I viewed this morning's update as superb - certainly better than my expectations. The revenue increase was well above the FX-adjusted trend and the high cash balance indicates that the reduction in inventory seen last period was sustained and that payables have reverted back to the higher levels seen prior to 2017. I anticipate broker upgrades of at least 10%.
I took the opportunity to add another 4,000 shares at the bell this morning.
I also bought in this morning - £TUNE
Morning Graham.
Not much small cap specific news today .... apart from Trump steel and aluminium tariffs, the non-nuclear(?) Korean Peninsula and upcoming US non-Farm Payroll this afternoon. If you have time, wondered if you’d like to circle back on the Volvere (LON:VLE) update from Wednesday? Some interesting comments on the discussion thread about the putative sum of the parts valuation although it wasn’t covered in the main reports.
Gus.
Sure, I'll talk about Volvere (LON:VLE) today. Cheers Gus. G
Trading update for Alpha Real Trust (LON:ARTL) today :-
Highlights
· NAV per ordinary and A share 168.4p: 31 December 2017 (167.3p: 30 September 2017)
· Basic earnings for the nine month period ended 31 December 2017 of 14.4p per ordinary share and of 18.9p per A share (13.3p per ordinary share and of 17.7p per A share for the six months ended 30 September 2017)
· Adjusted earnings for the nine month period ended 31 December 2017 of 3.4p per ordinary and A share (3.0p per ordinary and A share for the six months ended 30 September 2017)
· Declaration of a quarterly dividend of 0.6p per share, expected to be paid on 6 April 2018
· Balanced portfolio: continued capital allocation to a mix of investments which balance income returns while creating potential for capital value growth, including a growing build-to-rent exposure
· Mezzanine loan investment: four loans totalling £3.8 million were completed in the quarter ending 31 December 2017 with a further three loans totalling £5.2 million funded post period end
· Data centre Frankfurt: following planning consent being secured, tendering for pre-development works is underway with a view to having a development-ready site
· H2O shopping centre Madrid: record visitor numbers recorded in 2017, increasing 3.9% over 2016, with like for like tenant sales increasing 6.4% over the year.
My morning smallcap tweet:
Renold (LON:RNO), £RM2, Clear Leisure (LON:CLP)
Renold (RNO) warns FY adj operating profit expected to be below previous expectations and slightly down YoY. Blames weak $, slow pace of passing on higher raw material costs in chain division.
RM2 International (RM2) sells building in Switzerland, gives enough cash to continue operating through [to?] mid-April. Still seeking funds from shareholders.
Clear Leisure (CLP) is sending miners to slave in Serbia: its blockchain mining JV's first data mining computers are ready to be shipped to Serbia. "A DCF valuation over a period of five years, assuming mining profitability, mining difficulty, Bitcoin price, projected hash power and miners typology, estimated cost of energy and an 8% discount rate, generates a current valuation of €389k." So they are forecasting the world's most volatile curency five year out AND the total number of Bitcoins existing (to get hash power). Truly modern day Nostradamuses.
Focusrite (LON:TUNE) have issued an interesting trading update stating revenue profits and cash are all up relative to the first half. This may be an on-going trend and a weighting to H2. It is good that it's based on actual data rather than forecasting results will be H2 weighted. However, there is no mention of how the results compare to market expectations and what those are.