Small Cap Value Report (Tue 9 Jan 2018) - EHG, TPT, JOUL, NEXS, TAST, GAW, CARR, BQE, WINE, FOUR

Hello, it's Paul here.
It's busy for updates today. Please see the header above for the stocks that I shall be reviewing today.
Elegant Hotels (LON:EHG)
Share price: 85.5p (down 10.9% at 08:32 today)
No. shares: 88.8m
Market cap: £75.9m
(at the time of writing, I hold a long position in this share)
Results - for year ended 30 Sep 2017. This company is;
...the owner and operator of seven upscale freehold hotels and a beachfront restaurant on the island of Barbados.
It listed on AIM in May 2015. This is a rare exception to my usual (personal) blanket rule not to invest in overseas companies on AIM. The reasons being that it's profitable, has freehold property assets, pays divis, seems to have sensible management, and operates in a country which seems to be politically & economically stable.
Its major shareholders list is pretty impressive too;
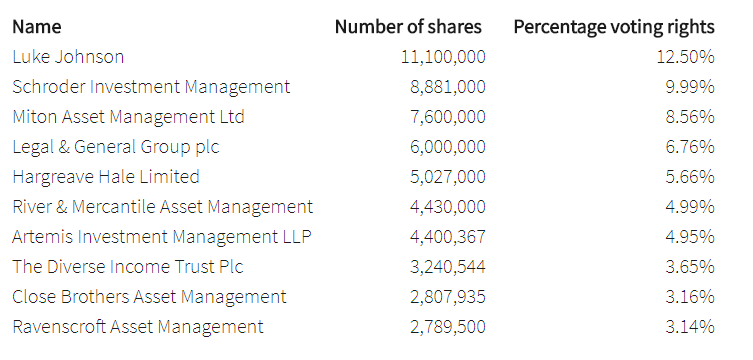
Results today have clearly underwhelmed some people, as the share price down 10.9%.
Dividends have been reduced today, which could have upset some shareholders. Although as I flagged here on 12 Oct 2017, the company was clearly over-paying, so a cut in the divi was to be expected. The final divi this year will be 1.75p (PY 3.5p). The 2018 divi will be 4.0p, split one third: two thirds between interim & final. That will still give a pleasing yield of 4.7%, and looks a much more sensible level of payout. So personally, I'm absolutely fine with this. I'd much rather the company sensibly balances its divis and capex, rather than paying out too much in divis and starving its hotels of capex.
Some key numbers for 09/2017;
- Revenue up 5.1% to $59.9m - with one additional site.
- Adjusted EBITDA down 7.6% to $18.1m - so nicely cash generative, but we do need to take into account maintenance capex, which is heavy for hotels.
- Adjusted profit before tax is down 22% to $11.1m
- Adjusted basic EPS is down from 13.1c last year, to 10.1c this year (converts to sterling of 7.5p). Note that there doesn't seem to be any potential dilution from share options, since the basic & diluted EPS figures are the same.
- At 85.5p share price, the 7.5p EPS results in a PER of 11.4
- EPS seems to have come in below the $0.11 consensus shown on Stockopedia. However, Zeus Capital says in an update this morning that the result is slightly above its expectations.
Forex - this is the key issue for the company, which we already knew about. Something like 70% of the company's revenue comes from British tourists, but its costs are in US dollars. So the devaluation of sterling has been a headwind.
The company gives refreshingly clear guidance about this issue;
This was the first full year of a rebased Sterling/USD exchange rate. As a result, given Elegant Hotels' rates are priced in USD while the majority of its customers are from the UK, it has been necessary for the Group to discount rates at certain of its properties on a targeted and tactical basis. This has inevitably affected the profit margins of the business, but the Group believes that the pricing environment is now much more stable.
As such, these market conditions should be seen as the new normal.
Balance sheet - as you would expect, since it owns freehold properties, the balance sheet is dominated with PPE (property, plant & equipment), of $183.7m. Hotels don't tend to have much working capital, so the only other big item is borrowings, with net debt being $73.1m. That seems a fairly conservative level of gearing, on a loan to value basis of 39.8% - assuming that properties are actually worth book value.
Zeus Capital say that the freehold properties were valued at more than book value in 2016, and quote a NAV of 163p. I'm a bit sceptical about valuations on hotels, as they often don't seem realistic.
Looking at book values on the balance sheet, net tangible assets of $109.7m converts to £81m, which is higher than the market cap of £75.9m. So providing you're happy with the book value of the freeholds, then this share appears very solidly underpinned.
It would be worth checking out the terms of the loans, although I won't bother now, because I'm happy with the relatively modest level of gearing.
Overall, this balance sheet looks OK to me, I don't have any concerns.
Outlook - sounds fine to me;
Trading since the start of the new financial year has remained in line with market expectations, and our bookings are currently tracking ahead of the same period last year. As a result, the Group remains confident in its prospects for 2018 and beyond.
Broker forecasts - Zeus has reduced its profit forecasts by about 16% today, which is rather surprising, since the forex issue was already known about. Therefore it's probably safest to not expect much in the way of earnings growth, assuming forex rates remain unchanged.
My opinion - I haven't read through the narrative yet, as there's lots of other stuff to get through today. However, based on the figures, I'm happy to continue holding this share. There's a reduced, but still good dividend yield. Plus there's strong asset backing, and potential bid activity - note that here on 4 Dec 2017 the company announced a failed bid approach from Melia Hotels International. It's not clear from the announcement why those talks did not progress to a cash bid.
Overall, I think this share looks a reasonable each-way bet - I can continue to hold for the dividend income, and at some point there might be the bonus of a takeover bid. I'm not inclined to buy any more though, because the earnings outlook seems rather lacklustre, with limited growth potential in the short term anyway.
Topps Tiles (LON:TPT)
Share price: 86.2p (up 7.8% today)
No. shares: 193.1m
Market cap: £166.5m
(at the time of writing, I hold a long position in this share)
Topps Tiles Plc (the "Group"), the UK's largest tile specialist, announces a trading update for the 13 week period ended 30 December 2017.
This looks a pretty solid performance, hence why the share price has risen nearly 8% today;
Like-for-like revenues for the first 13 weeks of the current financial year increased by 3.4% (2017: +0.3%)
Outlook - the company sounds cautious, but it's now up against some nice soft prior year comparisons, so I wouldn't be surprised to see it continue to report decent LFL sales growth throughout 2018.
While we are pleased with the like-for-like sales growth achieved in Q1, we are retaining our prudent view of market conditions for the year ahead."
New division - this bit caught my eye, and I like the sound of this;
In parallel with our growth strategy for our core domestic business, we are progressing the development of a new division targeting the commercial tile market. Building on the acquisition of Parkside Ceramics in September 2017, we are investing in the capabilities necessary for future growth. The Parkside commercial offer was launched at the 100% Design trade show in October and our first commercial showroom opened in Chelsea in December.
That sounds as if there might be some up-front costs incurred, but the aim being to drive future growth. This sounds interesting, as it could perhaps be the trigger for a re-rating of this share onto a higher PER multiple?
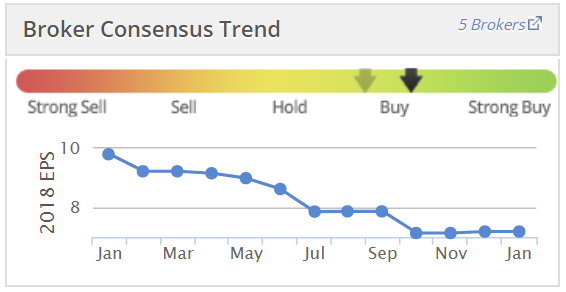
Valuation - Stockopedia shows broker consensus of 7.19p EPS for 09/2018. However, broker commentary today suggests that forecasts could be moving upwards, which is a potential change of trend from the reductions in the last 12 months;
My opinion - as mentioned in my last report here on 4 Oct 2017, I'm warming towards this company. Consumer spending seems to be pretty solid, based on surprisingly good reports so far from retailers. Hence why I think this could possibly be quite a good entry point for modestly valued retailers which are reporting positive trading now.
There's an attractive dividend yield with this share too, still over 4%, even after today's rise. I don't expect this share to shoot the lights out, but it looks to me as if it's possibly set up for a better performance in 2018 than in 2017. Overall then, I'm moderately positive about this share, hence why it's now in my personal portfolio.
Joules (LON:JOUL)
Share price: 309p (unchanged today, at 10:54)
No. shares: 87.5m
Market cap: £270.4m
Joules, the British premium lifestyle brand, today updates on the Christmas trading performance of its retail business for the seven-week period to 7 January 2018.
This company issued a totally unsatisfactory trading update which I criticised here on 12 Dec 2017, which failed to inform investors properly. Anyway, they've done exactly the same thing again today - giving inadequate information, saying only;
Joules delivered a strong performance over the Christmas period with total retail sales* up 19.2% against the comparable period last year. This was driven by continued growth across both the Store and E-commerce channels.
Retail gross margin, over the same period, is expected to be in line with the prior year as we maintained our disciplined and selective approach to promotional activity.
Plus there's another short paragraph of complete waffle, which I haven't copied here.
Where is the key information on like-for-like sales? It's not given. Total sales is too vague, because the number of shops has increased from 107 to 117, therefore costs will have also increased, and we don't know by how much. The timing of those new store openings will have obviously determined the total sales increase, plus the (undisclosed) key figure of LFL sales growth. Very unsatisfactory reporting.
Nothing is said about profitability versus market expectations either - again a glaring omission. A trading update which omits this key information is not a trading update at all.
Broker updates - the company clearly has briefed the analysts with the numbers, because broker updates are coming out this morning with increased profit forecasts for this year. I understand obviously that analysts are going to get more detailed information than the rest of us. However, to withhold the key performance indicators of LFL sales, and profitability versus market expectations, from a trading update, whilst simultaneously briefing analysts with information that results in them upgrading their forecasts, seems to me very wrong indeed.
This is a two-tier reporting process, where only privileged individuals who can get access to broker notes, are told the true picture. Whilst the rest of the hoi polloi are left mostly in the dark, and have to wait until the interim figures are reported on 31 Jan 2018. That gives a privileged few in the City almost 4 weeks to buy the shares, knowing that the results are going to be good, whilst everyone else is largely left in the dark.
My opinion - this share looks expensive on a forward PER basis, but that's partly because the company seems to be trading well, and profit forecasts are likely to continue trending upwards. The current format of its trading updates is appalling, and needs to be revised so that all market participants are made aware simultaneously of key performance metrics. That's what is supposed to happen, but unfortunately with this company, the rules are not being adhered to. Just announcing a total sales figure, with no indication of LFL sales, nor performance against market expectations, results in trading updates that are so vague they're almost useless.
Maybe it's time to get rid of the PR people, and bring in more investor-friendly advisers?
Good company, lousy reporting.
Nexus Infrastructure (LON:NEXS)
Share price: 235p (unchanged today, at 11:40)
No. shares: 38.1m
Market cap: £89.5m
(at the time of writing, I hold a long position in this share)
Preliminary results - for the year ended 30 Sep 2017.
Nexus, the leading provider of essential infrastructure services to the UK housebuilding and commercial sectors...
For anyone not familiar with this company, which floated on AIM in Jul 2017, I wrote an initial review of it here on 25 Oct 2017.
To save me typing, here is a picture of the financial highlights. As usual, I'll double-check to make sure they're not cherry-picking the nice things, and glossing over the not so nice, as lots of companies do!

Whilst the company says that operating profit is ahead of expectations (confirmed in a broker note I've seen today), note that operating profit is actually down on last year.
Order book growth is encouraging, although we don't have any information over what period these orders stretch. It could be multi-year stuff, we don't know.
EPS - the accounts state that diluted EPS was 15.0p, however this is including exceptional costs (relating to the IPO). Underlying basic EPS was 19.1p (down from 22.3p last year).
Valuation - at 235p per share, the (now historic) PER is 12.3.
Forecast EPS for 09/2018 is 21.7p
Forecast EPS for 09/2019 is 25.3p
So if those forecasts are achieved, then the PER would be 10.8 and 9.3 - fairly attractive, although contracting businesses don't tend to command high PERs.
Balance sheet - the company has a good cash position, with £27.1m cash, less £8.4m bank borrowings, which nets off to £18.7m net cash.
Overall though, working capital isn't as strong as you might think - the current ratio is 1.27, which is OK, but not particularly strong. I suspect the £49.9m in trade payables probably includes some deferred income - i.e. the opposite side of the double-entry for cash paid up-front by customers.
Overall NAV is £17.0m, less £2.4m goodwill, gives NTAV of £14.6m. I would say that is adequate, but not particularly strong for a company capitalised at £89.5m - therefore this share should be seen as relying on earnings, rather than assets, for its valuation.
Cashflow - a possible concern is that debtors rose significantly in both years. There was a similar increase in creditors in 2016, offsetting this rise. It's something to keep an eye on - I'll be looking to see the £37.8m debtors come down at the next set of interim results. If it doesn't reduce, then that might indicate a problem turning invoices to customers into cash in the bank.
Outlook - sounds positive;
Trading in the first few months of the new financial year has been in line with the Board's expectations. Demand from customers is robust, and the Group's order book continuing to increase with the balance as at 31 December 2017 of 213m, which provides the Board with confidence for the year ahead.
My opinion - I need to do more research on this company, as it was a bit of an impulse purchase a few weeks ago, after several people recommended it to me.
The group seems to operate in a buoyant niche, and with reasonable profit margins. The PER is modest, and it pays an OK dividend. The balance sheet look reasonable. Overall I'd say that I'm mildly positive on it, pending more research. I'd like to see debtors reduce in future, to be sure that profits will turn into cash.
Stockopedia computers like it, with a high StockRank;

Tasty (LON:TAST)
Share price: 30.0p (down 3.2% today at 13:23)
No. shares: 59.8m
Market cap: £17.9m
Trading update - this is a restaurant chain, mostly branded as "Wildwood" - which in my view is a dull, tired, me-too, pizza/pasta format. The Kaye family are behind it, so it's similar to all their other pizza/pasta formats.
Today it updates us for the 52 weeks ended 31 Dec 2017.
This provoked a sharp sell-off this morning, but it has since mostly recovered;
Trading for the period has been in line with expectations.
The Board has previously highlighted the difficult trading environment faced by the restaurant sector and expects a further deterioration in 2018.
This whole sector is indeed suffering badly at the moment. The big issue is over-capacity. There's been a huge increase in the number of restaurants in the last 12 years - up about 30% apparently. So there are too many operators chasing not enough customers. Contrast that with pubs & nightclubs, where many have closed down, meaning that there's now more business to go round fewer players - hence why we're seeing positive updates from pub groups currently, and profit warnings from restaurants.
So it's fairly easy for investors - I'm just avoiding all the restaurants, and instead have made Revolution Bars (LON:RBG) my biggest long position. Hopefully that might pay off, but I'll have to wait and see.
Forecasts for Tasty are for little more than breakeven in 2017, so could 2018 turn into a loss? I cannot see any reason to want to get involved here. I think the next few years are likely to be all about struggling to survive, not creating shareholder value.
Disposals - good news that it has managed to dispose of 4 under-performing sites, with 2 more pending.
FD resignation - announced today, but it sounds harmonious, as he's apparently going to be serving his 3 months notice. A replacement has been lined up.
My opinion - there's nothing here which interests me.
The only restaurant chain I'm interested in buying more of (to add to a tiny scrap I currently hold) is Fulham Shore (LON:FUL) . However, having seen how empty several of its new sites are (taking space from Debenhams), I think FUL could have another profit warning in it. Also I'm a little nervous about its bank debt. So I don't think there is any rush at all to go back into this very difficult sector. There are likely to be many casualties, particularly of independent operators, in my view.
Games Workshop (LON:GAW)
Share price: 2575p (down 2.8% today, at 13:53)
No. shares: 32.3m
Market cap: £831.7m
Interim results - for the 6 months to 26 Nov 2017. This is a retailer of figurines for fantasy gaming.
These numbers can only be described as spectacular! Pre-tax profit for the 6 months is up from £13.8m last time to £38.8m this time. Wow!!!
The reason seems to be that a game called Warhammer has been a big hit. The big issue now is trying to predict how high, and for how long, demand is likely to remain at elevated levels. I haven't got a clue on that, so there's not really a lot more that I can add, other than to congratulate investors who spotted the opportunity here.
At some point profits are likely to go backwards. Do readers have any views on how this might pan out? It's important not to over-pay, by paying a high multiple of peak earnings. That's the main risk here.
I've run out of time now, so just a couple of brief mentions now;
Carr's (LON:CARR) - this share is up 13% today on a trading update which is only in line with expectations. The commentary sounds upbeat though, e.g.
"We are pleased with how FY18 has commenced. We are seeing the continued recovery across both divisions and the investments we have made in acquisitions and research will continue to act as a solid foundation for ongoing growth."
Might be worth a closer look, as the valuation seems fairly modest.
I'm not keen on this share, as it's just traded sideways for the last 4 years. Is there much upside on this type of share, in a bull market that is seeking growth companies?
Bioquell (LON:BQE) - not one I follow, which is a pity, as it's been rising strongly over the last year. A decent update today says that pre-exceptional PBT is expected to be "significantly ahead of market expectations". Very good. It had net cash of £14.5m at the year end.
Majestic Wine (LON:WINE) - this share is flat today, on an OK trading update - "on track to meet full year expectations". The retail division delivered +1.3% LFL sales over the crucial Xmas period. That was against tough prior year comps. Gross margin "broadly flat" against last year.
Personally, I remain to be convinced that the Naked Wines operation is any good, but time will tell. The share has had a terrific run, up about 50% in a few months, so personally I'd be banking the gains if I held, as the forward PER of 22.7 looks racy to me.
4imprint (LON:FOUR) - shares are up 10.4% on a statement that US tax reform will be very beneficial. This was a known factor, so I'm flummoxed as to why the market did not anticipate this. Seems very odd. I wonder if there are other shares where an opportunity exists to buy now, ahead of US earnings shooting up due to tax reform? I see that Somero Enterprises Inc (LON:SOM) (which I hold) has been rising nicely of late, probably due to the same reason.
All done! See you tomorrow.
Best wishes, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

67 comments
Below is an article from Directors Talk speaking to the Chief Executive Officer, Sunil Chatrani, of Elegant Hotels (LON:EHG).
Question 6 and Chatrani’s answer shows they are actively on the look out for opportunities to expand the business in the region and further afield.
https://www.directorstalkinterviews.com/elegant-hotels-group-plc-qa-preliminary-results-lonehg/412743435
Thanks for your reply paul
The new season will start next November and December so bookings for then is unlikely this early.
Elegant hotels are a well run company especially for the Caribbean and I think treasure beach their latest acquisition is a good move although I think they paid top dollar for waves the year before.
their group has all inclusive hotels as well as top of the range who are affected by costs and Many people have commented at the increased costs of coming to barbados .
I hope I’m wrong as I have a business supplying these guys but I do fear for 2018/2019 unless the new government introduce new policies to help the tourist industry which we all rely on
Sorry it mashed my previous post - i know its a midcap but as a former head bod of a fashion co i thought you might be interested
Hi are you going to cover Superdry (just changed to sdry) in the AM? I think this internationalized, differentiated and compellingly valued fashion retailer is fundamentally undervalued. Look forward to your thoughts.
Hi Booboo,
Probably, yes. Superdry (LON:SDRY) is one of my favourite growth companies, and I hold it personally & in BMUS.
Then it's Boohoo.Com (LON:BOO) (my 2nd largest long position currently) trading update on Thursday. So a tense few days!
Regards, Paul.
Hi paul
ELEGANT HOTELS
Last year barbados government added a ten percent levy on every product imported into barbados.
This has significantly increased the cost of living or indeed the cost of coming on vacation to Barbados.
This season has not been affected as holidays had already been booked but my worry is this coming season could be another story .
The Hilton owned by government has just been sold at a figure of 80 million USA dollars , well below the 200 million it was valued at .
Election soon and difficult to see how the incoming government are going to avoid IMF intervention.
Hi Andrew,
Re Elegant Hotels (LON:EHG) - interesting background re Barbados, thanks. As mentioned in the main article, I'm also sceptical about the valuation of the hotels. Although as regards bookings, the company today said;
So your fears don't appear to be borne out in practice.
Given the big forex impact, I'm actually quite surprised that bookings & profit margins haven't fallen considerably. We discussed this here before though, and other readers suggested that UK tourists who go to Barbados regularly are not that price-sensitive. I've never been there myself.
Regards, Paul.
Games Workshop (LON:GAW) should do ok this year imo, they've yet to release the rulebooks for several popular factions (armies) in the 40k game. They've also recently released a game called "Shadespire" which is a faster format game that requires less time and less kit to lug around which should compete well against the Fantasy Flight Star Wars offerings and perennial competition like Malifaux and this has fantastic traction in my local shop, lots of people are buying into it.
I'm impressed with how they have turned things around recently but they won't win back my loyalty (and around 2-3k per year spent on gaming products) for 2 reasons. 1. I won't forgive them what they did to Warhammer, wrecking the whole format to create "Age of Sigmar" (I've never seen anyone in my local games shop play AoS). 2 They bring out a game every year that they expect you to invest heavily into, then it just suddenly disappears for years with no ongoing support. No announcements, no warning, just gone. I give you Heroquest, Battlefleet Gothic, Bloodbowl, Space Marine, Space Hulk as evidence. Hopefully the new CEO will change this, but it's going to take a long time for me, and several of my gamer buddies, to forgive and forget the amount of wasted cash and hours spent painting now useless models..
Games Workshop (LON:GAW)
Great user comment IGotPoesJacket.
You'll understand better than me I'm sure but the GeekDad link I posted seems to suggest 2018 could be the year of deepening the understanding of the Realms in AoS.
I thought sales were approx 50/50 40k to AoS?
Are you refering to the original release of Bloodbowl? It's been re-released in the last year or so hasn't it? Chatting to my local store manager I thought armies from Necromundo could also be used in the main games, is this not the case with the older standalone games?
I'd be surprised if AoS to 40k was 50/50. I don't go in the GAW stores any more though. My local independent game store sees very little AoS demand, I've never seen anyone play it there in 2 years. It could well be why they created Shadespire though, to get people back into the Fantasy Universe, as that game has already got a lot of fans and GAW are doing a lot to create a regular in-store play experience to generate loyalty (Fantasy Flight games give away a lot of product as prize support and have generated a huge following for their Star Wars games, particularly X-Wing). This might hit margin but should be relatively small, they're not giving away gold trophies :)
Yes the older sets do have models that can potentially be used in other games but the business model of making old sets obsolete and forcing customers to buy new (the reason I don't buy GAW anymore) means this doesn't happen much.
Yes Bloodbowl did got its once a decade re-release. It's one of their most loved games but is back to being pretty much unsupported already.
The whole business model has traditionally targeted lots of short term sales. Hopefully the new management team has a more long term focus but I remain to be convinced.
As one of the other posters says, go to the AGM if you can, their HQ is something you'll never have experienced before - enter the world of the uber nerd/geek!
Games Workshop (LON:GAW)
I was the other poster, the AGM was certainly not like any other I'd attended.
Games Workshop (LON:GAW) current period trading comment - "Our sales for the month of December have also shown good growth trends". 2017 comparatives are strong for Dec 2016 per last year's update on 17/1/17 - "Games Workshop is pleased to announce a significant increase in sales and profits for the period from 28 November 2016 to 15 January 2017". H2 FY17 sales were £87.2m so the current consensus of £86.7m for H2 FY18 looks conservative as the the new 40,000 launch was in H1 FY18.
Mammyoko,
Excellent point about H1 into H2 2018 sales phasing, which others may have missed. Here's hoping. Ian
PP,
Games Workshop (LON:GAW)
I've held the shares since the amazing TS in December 2016 - so approximately 13 months. I attended the Agm in Sept 17 which I would recommend any shareholder to do! Fascinating day out in Nottingham. My son had enjoyed a brief dalliance with the hobby a few years ago so I was vaguely aware of the in and outs of WarHammer.
In answer to your question regarding peak earnings there are in my opinion several moving parts in play.
Kevin Rountree became CEO 3 years ago and has changed the company culture, previously GAW seems to do ok almost despite themselves. Kevin has brought in better marketing, invested in social media content and overseen a very successful re-launch of the Warhammer 40k in June17. The previous launch of Age of Sigma in 2015 was considered to be somewhat of a flop. Customers appear much happier nowadays and the social media (Facebook, Youtube, Twitch.tv) is keeping them engaged and buying.
Online is growing more quickly than the other channels which is great as it's higher margin business. The vast IP held is also being exploited to greater effect with substantial increases in royalty income. Oversea territoriesare growing quicker than the UK.
As GAW enjoys complete vertical integration it has no real competition on price, no need to do sales etc
So 1 side of the argument is that GAW has produced a step change in customer engagement with more players, buying more of the hobby. This level of sales is the new normal or even we are only starting on the path to the new normal.
The counter argument is that last year revenue was inflated by currency effects and this year the Warhammer 40k release in June along with a major video game releases in March & September have caused a spike in earnings which may fall back to the old normal.
I'm clearly biased as I hold quite a few shares in GAW but all my research visiting shops, the agm and viewing online gamers comments suggest GAW is back to being a force in the gaming world after losing it's way somewhat.
If anyone can find me a share on a fwd PE of 12-13, Yielding 5%, massively cash generative and with a return on capital of over 100%, i'm all ears?
Games Workshop (LON:GAW)
I don't think they keep Peel Hunt in the dark. I just think they are since KR took over very conservative in their outlook.
2018 looks to me as the year where they'll look to develop Age of Sigma to keep sales momentum going.
https://geekdad.com/2018/01/games-workshop-announces-malign-portents/
Re Games Workshop (LON:GAW), I find it very difficult to give any weight whatsoever to broker predictions. They have just reported 97p EPS in H1, where traditionally weighting is heavily towards H2 (see last year where H2 EPS was close to double that of H1). The current EPS estimate for this year is 161p which is clearly going to be smashed unless business begins to swiftly unravel, of which there is no current evidence to support. To the contrary, the half year report states December has shown good growth.
I suspect we will see another trading update within the next few weeks, perhaps next week if last year is mirrored, with an above expectations forecast. While I know it is imperative to not be too confident in a stock, I struggle to see many more attractive propositions on the UK market.
I used to play warhammer (40,000 and fantasy) about 12 years ago. I stopped when I reached 16 and discovered computer and console games, and the realisation of how expensive the products were.
I considered buying Games Workshop (LON:GAW) last year when I saw it had a good stock rank, however was put off as they had replaced fantasy warhammer with a "new easy to play" version in 2015 which I thought would alienate a lot of existing players.
I would certainly be interested in how much revenue is from the the tie in with the Total War computer game series (which I understand to be a big success), how much is from existing games and how much is from this newer warhammer variant.
With regards to the growth in revenue, I would guess a lot is to do with a new version of 40,0000 being released in July 17 and Warhammer Total War 2 being released in September 2017. A new version results in people haveing to buy new rule books and lots of new models will be released. From what I remember new editions of each game system are released every 2-3 years (e.g 7th edition 40,000 released in 2014, 1st edition Age of Sigmar (Fantasy) released in 2015, 8th edition 40,000 released in 2017) A third and supposedly final Total War game is supposed to be released late 2018/early 2019
I also understand that they are expanding in the US
On a side note I walked past a shop in maidenhead at lunch, it was closed. Not sure if this was a one off as it was open before Christmas
Shame i missed the boat last year
#GAW I exited these yesterday after 2 bagging in a year. These are spectacular results from a Fab company. The only reason I sold is that the results are generated by the Warhammer game and this has a finite life. Consensus PBT is £65m for 2018 dropping to £55m 2019. (Digitallook).
Games Workshop (LON:GAW)
MtB,
Whilst it's impossible to predict the future I would point out that at this stage last year 2018 results were forecast to be below 2017's (53.2p v 57.9p) and have clearly been blown out of the water with 97p in H1! So not necessarily a good guide.
Agreed - Seems Games Workshop (LON:GAW) delight in keeping their house broker in the dark - All part of the GW mystique!
#GAW Can't argue with that Cockerhoop. Hopefully, (for me) there will be a dip in which case I may well buy back in. All the best!
GAW- Ive been a holder for about 18 months and have top sliced as the price has improved I am happy to say. Of concern was a recent visit to Kingston where they have a physical store. On the 23rd of Dec when I passed by, there wasn't a soul in the shop. I assume their online gaming stuff ( Warhammer ? ) is saving things but the lack of shop visitors was a worry.
Interesting observation there grout123 regarding Games Workshop (LON:GAW) stores. Recently I passed stores in Wakefield and Bristol and both were very busy. Maybe just by chance your timing caught a quiet time?
Well done on your report today Paul, that is a lot of companies covered!
I am slightly surprised Topps Tiles (LON:TPT) is up 7% today. The 3.4% increase in LfL sales in the first 13 weeks is clearly good news but it had already reported 3.2% LfL growth in the first 8 weeks - so this trading update is only giving us an extra 5 weeks of information. (i hold).
Hi wimbledonsprinter,
I have a theory on this. Some investors may not have noticed the 28 Nov 2017 results announcement from Topps Tiles (LON:TPT) because the RNS is entitled "Annual Financial Report". I always ignore RNSs with that title, because they are nearly always just confirming that previously released results are being posted to shareholders.
So it's entirely possible that other investors may also have not realised that the 28 Nov 2017 announcement contained the actual results published for the first time, together with the news on current trading.
In a nutshell then, I missed the current trading figures in Nov 2017, and only spotted the figures in today's update. That could explain why there was a decent rise in share price today.
Also, there has been bullish broker coverage out today, saying that they foresee the need to raise their forecasts later this year.
Regards, Paul.
I have a theory on this. Some investors may not have noticed the 28 Nov 2017 results announcement from Topps Tiles (LON:TPT) because the RNS is entitled "Annual Financial Report". I always ignore RNSs with that title, because they are nearly always just confirming that previously released results are being posted to shareholders.
I'm not sure this is correct. The closing price was 60.75p on 27th Nov and 75p on the 29th, which tells me the LFL numbers in the Nov update had been fully digested by the market.
I would suggest that the new 13 week number today is not as humdrum as wimbledonsprinter has suggested if you "do the math". If the first 8 weeks of a 13 week period sees LFL at 3.2% and the outcome for the full period is 3.4%, then this means the LFL sales for the last 5 weeks must have increased at a lot more than 3.4 %! I think this more recent increasing trend is what the market is reacting to.
All the best, Si
Si. Correct re Topps Tiles (LON:TPT). If all weeks are equally weighted (simplifying assumption), then implied growth in the last 5 weeks is 3.7%. Interestingly, comparatives soon get easier, so if (big if) underlying numbers remaining resilient, you could see even better LfL numbers going forward. FY 2017 LfL numbers were: Q1: +0.3%; Q2: -4.1%; Q3: -4.7%; Q4: -3.0%.
I wonder if Games Workshop (LON:GAW) would be a nice little bolt on for $ATVI ? I'm sure this will have been suggested before. £ATVI could perhaps look to extend into boardgames themselves, gradually, using Games Workshop (LON:GAW) expertise? Similarly, $ATVI could look to change / extend & develop Games Workshop (LON:GAW) offer in the online space, God knows they're the experts. Could Games Workshop (LON:GAW) IP tempt $ATVI?
EDIT - No idea why £ATVI won't link to Activision Blizzard :/ Tried both £ & $ before the ticker
Paul,
Well done for your typically trenchant comments on Joules' (LON:JOUL) lamentable IR standards.
I don't hold, and we have reached the stage in the consumer spending cycle when retailers have to spell out the case for investing in their shares rather clearly....
Impax Asset Management (LON:IPX) had another AUM update today showing strong new funds and capital growth. I have put together a spreadsheet of recent growth:
https://docs.google.com/spreadsheets/d/1CE_VOXpMXunhnX0aDqeDFeTJY022X7HjUjWljZifxeY/edit?usp=sharing
In the context of recent figures the last quarter also looks strong, but as you can see it hasn't always and won't always be like this.
I will try to write some more this evening.
That's interesting Leoleo. The metrics for Impax Asset Management (LON:IPX) look fantastic but then again it looks to have had an excellent 2017. Whether they can remain flavour of the month I don't know but so much depends on them maintaining good performance - without that inflows will quickly turn into outflows!
Stick to the Joules (LON:JOUL) directors, Paul. Totally unacceptable
Elegant Hotels I was in early at above the current price but added considerably when it fell so I came out first thing today at a reasonable profit. I sold because I am not sure that the forward dividend of 4.4% at 90p will not come under pressure and I think it only reflects the fact that the share price is not likely to be going anywhere for a couple of years. Longer term this could be a good business but I think there are better shares to be in for now.
Re GAW.
Having a long position I’m trying very hard to find something negative in the news today. Just can’t see it ? I always try to put myself off if I can, which can prompt a sensible sell, but I can’t see it. There must be something somewhere hidden, but every time I walk passed our town centre shop, it’s full of youngsters having fun. I look around from there, and the rest of the town centre shops are empty, the rows of charity shops, and bookies.
Hi Paul
Could you take a look at ILIKA(IKA). Their results are out today. Do you think the will need refinancing in the next 18 months?
Hi boothbym,
Could you take a look at ILIKA(IKA). Their results are out today. Do you think the will need refinancing in the next 18 months?
I've had a quick look. In terms of liquid assets, Ilika has;
Bank deposits £3.27m
Cash £0.60m
Tax receivable £0.53m (I'm assuming this is R&D tax credits, so should be a cash receipt)
Total £4.4m
It looks to be burning around £3m-ish per year. So my guess is that, yes it would need to raise more equity maybe late in 2018, or early 2019. That wouldn't necessarily be a problem, as the company has some sexy-sounding technology, and we are in a bull market.
I remember going on a site visit to their facility in Southampton a few years ago. It all looked very exciting & space-agey, but there's not been anything commercially viable appear as yet. But you never know! Could be worth a fun money punt, I've punted on it before (unsuccessfully).
Regards, Paul.
Thanks Paul
1.4m shares traded today. Last placing raised 6m at 50p per share.
Elegant Hotels - The dividend cut is disappointing and in reality the company appeared to have floated with a dividend yield that was designed to "get the IPO away." The last sales pitch for a poor IPO it seems is management/IPO brokers hyping up the dividend yield. Elegant Hotels also has a growth strategy so the high dividend payout was incongruous with that. Two hotels have been bought since the IPO.
Results - This is for the year from October 2016 to September 2017. It should be remembered that Elegant gets most of its business in the winter months when people travel to Barbados to escape the gloomy weather. The bulk of Elegant's visitors are also from the UK. So this financial year included the post-Brexit vote impact and the slump in sterling against the US dollar. Sterling is currently higher than the US dollar than it was in winter 2016/2017.
In other words the financial year just gone was an annus horribilis for Elegant Hotels. Things should get better from here. This winter's trading 2017/2018 should be better given the recovery in sterling against the US dollar. However, while luxury travel is a growth area it is also cyclical.
A previous poster highlighted the fall in revenue per available room over the last two years. The group has had to cut prices to stay full. The opportunity is that at some point this should stabilize. I don't see Elegant as a fantastic investment but you do get a reasonable dividend yield, even after the cut, just for holding on. If the company rejected a cash takeover offer they must be confident that the shares undervalue the potential.
Hi,
Another reminder - please can people remember to always put the company name or ticker into every comment here There are a couple of stray comments above, where I don't know which company you're talking about. The way the comments are listed, it's not threaded, so not always clear. Remember that each report will cover multiple companies, so it makes life much easier if people specifically state which company you are referring to in every comment.
Thanks, Paul.
A suggestion for the boffins at Stockopedia - is there a way to embed a drop down list at the top of each message so that people can select or list the companies they are going to be talking about? Then each message will have the company ticker and name(s) at the top.
Bit of an unusual request.
Today is the start of the housebuilder's update season - Persimmon's Persimmon (LON:PSN) out this morning looked good - but the market seems to be unimpressed. (I don't hold)
Do you think the market is totally down on this sector?
Phil
Carr's (LON:CARR) and Ilika (LON:IKA) have updates today. CARR looks good and the market thinks so too, but I can't see how IKA can make it through to break even without raising more funds.
Re Games Workshop (LON:GAW) there is quite a lot of commentary in today's H1 results about how the company is interacting with its customers. One thing I hadn't realised until very recently was how dreadful GAW have been over the last twenty years on this front with improvement only having started in the last year or so.
This is described in great detail, by a member of the GAW user community, in a 14 minute video posted on YouTube:
https://www.youtube.com/watch?v=QbepSuA0aYo
Clearly this improved interaction is not doing and will not do GAW any harm in terms of improving sales and revenue.
Cheers, Martin
P.S.This link was provided by martinthebrave in a post on ADVFN on 01-Jan-18
Stock Spirits (LON:STCK) please. slightly ahead of expectations.
Given the seemingly excellent results from Games Workshop (LON:GAW) the market (non) reaction seems surprising - does anyone have any thoughts?
dgold - Games Workshop (LON:GAW) There was a trading update on 1 Dec not that long ago when the excellent headline numbers were posted.
Since then the sp has gone up some 30%. So I would say that the sp had already factored in today's results.
Anyway, that's my story.
I think you're absolutely right - my mistake for not spotting that and thus buying at the opening - I think I wasn't the only one to make that mistake. I (would like to) think there is probably still a bit of upside though as given the growth in profits the shares are still not too expensive (2019 pe of 19).
Yes I agree with RAM that the results are already in the Games Workshop (LON:GAW) price. I did go though the H1 announcement today looking for any sign of negative sentiment and the closest I could find was this rather apposite comment:
"The greatest risk is the same one that we repeat each year, namely, management. So long as we have great people we will be fine. Problems will arise if the board allows egos and private agendas to rule. I will do my utmost to ensure that this does not happen".
GW is a classic PEAD (Post Earnings Announcement Drift) type share where the market takes a while to come to terms with good news, so I have little doubt (at least short term) that further upward drift is yet to come. Ian
Hi Ian - re. Games Workshop (LON:GAW)
That's an interesting comment to make in a half-year financial report. It is almost as if he is firing a broad salvo against certain managers who are not toeing the company line.
Ram,
Games Workshop (LON:GAW) has made this type of ego comment before, but he is a CEO who is bringing in new external senior managers, so you may be right about sending out another veiled warning to those who do not fit.
Kevin Rountree the CEO is reported to have said, "Games Workshop is in the business of fixing itself from the piece of s..t Tom Kirby (his predecessor) left me with. I mean, have you seen our stocks lately?"
Games Workshop (LON:GAW)
iwight7
Do you have a reference for your Kevin Rountree quote? I've met Kevin and it doesn't to me sound like something he'd come out with.
I do believe though he has transformed the business from the Tom Kirby days by positively engaging with the customer and giving them what they want from the hobby rather than the 'buy it or f*** off' attitude that was perceived to exist in the past.
Re Games Workshop (LON:GAW)
Comment is from this "source" https://1d4chan.org/wiki/Games_Workshop
P.S. I have just looked at it again and the comment appears to be the writers "thought" rather than comment.
Re Games Workshop (LON:GAW)
Comment is from this "source" https://1d4chan.org/wiki/Games_Workshop
P.S. I have just looked at it again and the comment appears to be the writers "thought" rather than comment.
So a complete fiction then! Kevin Rountree has and is doing great work at Games Workshop (LON:GAW) no need to unfairly trash his predecessor.
RE Games Workshop (LON:GAW).
Yes Cockerhoop that source is is virtually hearsay. Seems like someone who had a grudge against GAW started the page way back. However it is an interesting read and the overall narrative does seem to be backed by many different comments from other places. That being that GAW in the past didn't really care what their customers thought or the experience they had but that now that is a major focus. I found most interesting the comments regards GAW branching out into everyday merchandise, which is hinted that they previously didn't do. Maybe like movies GAW will finds these bring in as much revenue as the core product?
Re: Games Workshop (LON:GAW), it is an interesting comment, but has been used before, so nothing specific of note. I suspect he's just keeping people in line.
I'm imagining this scene from Star Wars: https://www.youtube.com/watch?v=YnNSnJbjdws
"I find your lack of faith disturbing!"
IG
Ref GAW
I wouldn't read too much into it.........it's repeated every year!
From the 2017 finals from Tom Kirby ex CEO/Ch
'In my opinion the greatest risk is the same one that we repeat each year, namely, management. So long as we have the right people in the right jobs we will be fine. Problems will arise if the board allows egos and private agendas to rule. I will do my utmost to ensure that this does not happen, especially in the year when Tom steps down from the board. Thanks Tom.'
Games Workshop (LON:GAW) shares are now down over 5% which does seem an odd reaction, so I have topped my holding. Often they is a delayed reaction to good results but I did not expect a 5% fall.
Perhaps part of the reason for the drop in the price is the omission of an outlook statement or trading after the period end. However, I believe Games Workshop (LON:GAW) have done this in previous results announcements.
There still appears to be value in the shares: taking the difference in EPS between full year 2017 and 1H2017 and applying that to 1H2018 EPS results in 2018 EPS of 158p. This results in a PE of 16 which is reasonable. The big question is whether the popularity in its products continues.
Yes you are probably right, but I find a bit bizarre that on good news the shares were up 7% this morning and now down about 12% from that peak, it's as if there is something nasty hidden in the detail. Apart from the missing outlook I can't see any problem in today's announcement and that's what I'm going on. I have seen this before good results and the shares fall on the day but then usually pick up in the following days as the figures are digested.
Well the price has performed pretty strongly in advance of these results? So I imagine that a breather is in order for people to digest the results.
On a different note Robert Walters (LON:RWA) put out a solid trading statement this morning. There's very positive momentum in all of their markets and fee income is really growing with a stack of cash on the balance sheet. They're my pick of the recruiters at the moment but I'd be interested in hearing Paul's thoughts given his past history of investing in this sector.
Elegant hotels ...a bit of a curates egg. There is no denying that business has been challenging, in particular foreign exchange issues and the severe hurricane season. The latter although not affecting Barbados will I suspect have deterred visitors to the Caribbean. The dividend cut and rebalancing going forward is in my view the right thing to do. The business strategy seems sensible and the rebased dividend gives a yield in excess of 4%. Also the discount to NAV is attractive as evidenced by the recent bid approach. Finally Luke Johnson, although not infallible is a smart operator and continues to hold more than 12% of the equity. I continue to hold.
Good luck to All
For a sense of the Games Workshop (LON:GAW) community development see https://www.stockopedia.com/content/games-workshop-164440/?comment=17#17
My morning smallcap tweet:
Totally smug.
Topps Tiles (LON:TPT), Games Workshop (LON:GAW), Bioquell (LON:BQE), John Lewis of Hungerford (LON:JLH), Totally (LON:TLY), 1Spatial (LON:SPA), Carillion (LON:CLLN)
Topps Tiles (TPT) Q1 LFL +3.4%. 'Pleased' but retaining prudent view of FY.
Games Workshop Group (GAW) H1 rev up 54%, EPS 97.6p up 187%. December sales "have also shown good growth trends."
Bioquell (BQE) Guides FY rev beat £29.3m. Pre-exceptional pretax expected to be significantly ahead of market expectations.
John Lewis of Hungerford (JLH) FY to end Aug. Who knew that kitchen supply was such a complicated business? Rev up 1%, EPS 0.06p (-0.21p). Trading: Q1 despatched sales and forward orders £2.3m (£1.8m) - reflects "a higher level of building projects completing in early Autumn months than we would normally expect. For this reason, we caution that it is unlikely to be an appropriate basis from which to extrapolate a full year forecast." 18w sales and order book £3.7m (£3.3m). Moves FY end from August to June "in order to address unintended, and unnecessary, challenges presented by the current reporting cycle."
Totally (TLY) Business Update. Wins £3m PA GP Out of Hours contract for a number of prisons Staffordshire. "Totally is pleased to report that 15 of the 21 sites inspected by the Care Quality Commission (CQC) have been rated Good demonstrating Vocare's continued commitment and focus on providing a high standard of care and quality." And the other 6? I found that Paddington was rated Inadequate overall and placed into Special Measures in Oct. Somerset Doctors Urgent Care was placed into special measures in April, must make further improvements to its NHS 111 service and its GP Out of Hours service following a recent re-inspection in Nov. Nothing to be smug about IMO.
1Spatial (SPA) wins $766k contact over 5 years in USA.
Carillion (CLLN) on share price movement - not aware of any material developments that support this share price increase.
Another great set of results from Games Workshop (LON:GAW) driven by a +54% increase in sales and fantastic operational gearing. GW customers may be a niche market, but those that play their games are very committed. A key growth driver seems to be the GW on-line support activity:
We've supported these customers with daily content for Warhammer: Age of Sigmar and Warhammer 40,000, and increased our video output to more than one video every day, reaching over 100,000 people per day. We've also continued to develop warhammer-community.com and created new brand content sites. In the last 6 months alone, our content has had 16.3 million views from 2.5 million users, and this increase shows no sign of stopping.
Astonishing! Ian
Hi Paul,
Games Workshop (LON:GAW) results look very good.
Elegant Hotels (LON:EHG) seem a little tricker to gague - revenue up 5% but other key metrics dropping. Also dividend has been trimmed. Welcome your views.
I hold both.
Trends for Elegant Hotels (LON:EHG) below that may be of interest to readers.
Note the decreasing Average Daily Rates (ADR) & Revenue per Available Room (RevPAR).
Though it's not listed below, the high levels of debt will not, in my opinion, allow the dividend to be maintained going forward.
Further to yesterday's announcement by Deltic of 8.2% like-for-like sales increase and some comments yesterday about how other pub companies had also reported good trading and potential read-across to Revolution Bars (LON:RBG) the FT now report further confirmation of the trend:
"Based on purchases made using their cards, Barclaycard says nominal spending was 4 per cent higher between November 19 and December 23 last year than over the same period in 2016 — a span that included Black Friday and Cyber Monday at the end of November. This was faster than price growth over the year to November, which was 3.1 per cent, according the Office for National Statistics. Spending in pubs and restaurants grew particularly rapidly, rising more than 8 per cent against a year earlier."