Small Cap Value Report (Wed 25 Oct 2017) - LRM, DFX, NEXS

Good morning! It's Paul here.
Drat, I've just realised that I forgot to put up a placeholder article last night - apologies. There's no way I'll remember reliably in future, so I've just set up a reminder system on my phone.
Today is a very quiet day for small cap results & trading updates. We have 2 profit warnings though, so I'll start with those.
Here is the link to yesterday's report. I updated it in the evening, adding sections on Bloomsbury Publishing (LON:BMY) , Shoe Zone (LON:SHOE) , and Gear4Music results.
Lombard Risk Management (LON:LRM)
Share price: 7p (down 34.9% today)
No. shares: 400.6m
Market cap: £28.0m
Lombard Risk Management plc (AIM: LRM), the leading dedicated global provider of collateral management and regulatory reporting solutions, announces its interim results for the six months ended 30 September 2017.
I'm impressed with the prompt reporting (just 25 days after the half year end). The figures themselves though, can only be described as diabolical. I won't spend much time on this, as I've long been a bear on this share. Looking at the figures today, I'm seriously wondering whether the company might go bust.
A few key numbers;
First-half revenue of 12.7m (H1 2016: 15.2m), down 16.4% largely due to a temporary fall in services revenues and some delays in contract signings.
Negative EBITDA of £3.5m. Bear in mind that the company capitalises a ton of internal costs onto the balance sheet, so the cash loss is much worse than EBITDA.
Capitalised development spend of £2.7m.
Loss before tax of -£5.9m - remember this is just for H1 trading. This is a massive deterioration, from a loss of -£0.1m in H1 2016.
Cash - amazingly, the company has burned through pretty much all the c.£8m in fresh equity raised last summer. There's only £0.4m left. Although it also has (currently undrawn) borrowing facilities of £4.5m. Although if it continues burning cash so quickly, will the lender allow them to draw on those facilities? I'd be rather surprised if they do.
Outlook comments sound upbeat, but they always do. This company is a perennial jam tomorrow - always optimistic, but usually falling short. This is what they say today;
We recognise that this has been a challenging first half for Lombard Risk. A number of opportunities we had hoped to secure in the period remain in the pipeline as market distractions such as MiFID II caused companies to delay on committing to new projects.
This leaves us much to do in the second half, and converting our strong visible pipeline will be crucial in us meeting market forecasts.
However, with the size and quality of our pipeline at an all-time high, we remain confident this can be achieved.
During the period strong foundations have been put in place, with an improved salesforce, a new development centre in Birmingham, and a renewed effort to target new business as well as extant cross-selling opportunities. We believe this positions Lombard Risk well for the future and delivery of a strong second half will enable the Company to meet its stated objectives of being cash generative. We look forward to updating the market on progress during the second half of the financial year.
Balance sheet - looks terrible to me. I don't see how the company can survive much longer, without yet another equity fundraising. Will shareholders stump up more cash, yet again?
My opinion - these figures suggest to me that this company is in serious trouble. I think another equity fundraising is almost certain now. There are several big name institutions with discloseable stakes, who might be prepared to provide more cash, but on what terms?
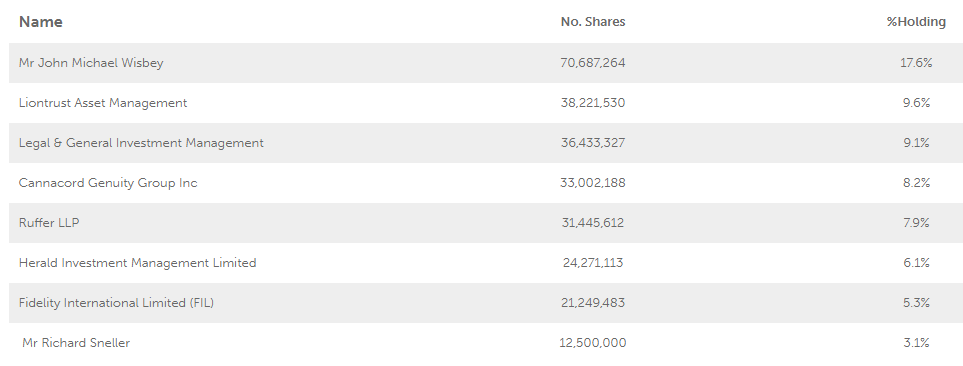
Note that there was an open offer with the last fundraising, so one hopes that this is also included with any future fundraisings, to avoid diluting small shareholders.
Overall, I think anyone holding this share, after seeing today's numbers, needs their head examining. Although of course, the problem with small caps, is that the market price is artificial - because big holders can't sell - there isn't enough market liquidity. So those guys in the list above don't have the option of selling. Smaller private investors can sell, which is a great advantage we have over small cap institutional investors. So to my mind, selling would be the only sensible option, given the scale of how bad today's interim results are.
There's a real risk of a 100% loss here, in my view. Is this a viable business? Based on today's figures, I would say no. Incidentally, I've tried to get a short position on this share today, but my broker can't find a borrow. Pity.
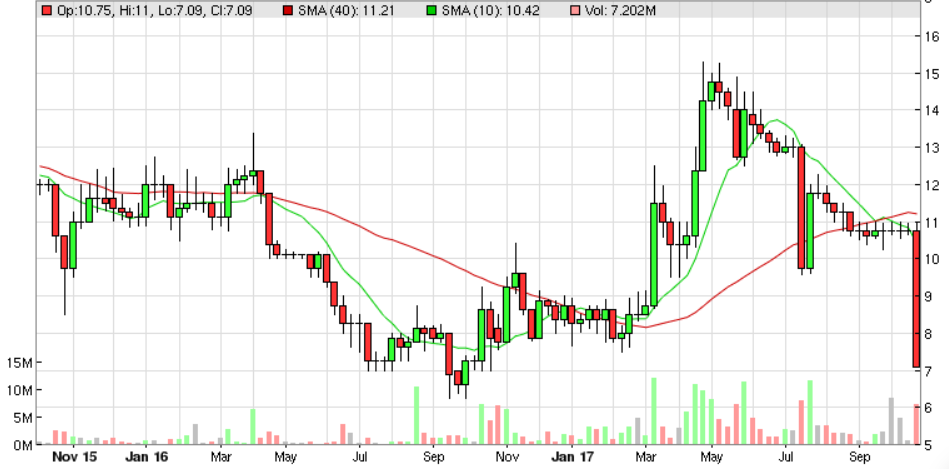
Defenx (LON:DFX)
Share price: 59p (down 39.5% today)
No. shares: 13.0m
Market cap: £7.7m
Trading update - this is a cyber-security company. I've not looked at it before, but will just have a quick look, as the market cap is now below our usual £10m size cutoff.
As you can see from the Stockopedia graphical history (always my first port of call when reviewing a new company), up until recently it looked like a nice little growth company;
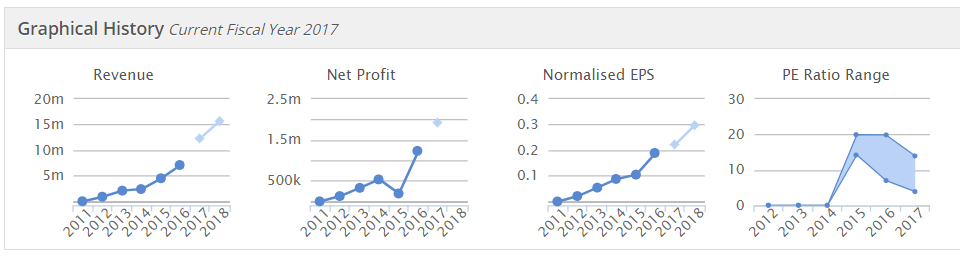
I missed off the 5th chart, which is dividend history, as this company doesn't pay divis.
Profits were building nicely, but it's gone rather badly wrong recently, with the company today saying;
...These factors combined are expected to result in the financial results for the year to 31 December 2017 being materially below market forecasts and the Board currently expects to report a loss for the full year.
The Board is satisfied that Group's cash and available facilities in the region of 2.2 million are sufficient for its current requirements.
I don't like the use of the phrase "current requirements" when talking about cash. That possibly implies that more cash might be needed in the longer term, maybe?
My opinion - this is only based on a very quick skim of the figures. Today's profit warning seems to contain lots of things that have gone wrong, which might take some time to fix. For that reason I'm not tempted to catch this falling knife. I like profit warnings where something untoward has gone wrong, but can be swiftly rectified. Those situations can make nice buying opportunities. This looks a bit more complex, so I'll steer clear. Also something this small won't be liquid enough, so the danger is that you get stuck in the share, unable to exit. Why take that risk?
There are so many companies active in the cyber security field, that picking a winner would be very difficult. Also, I think the danger is that investors chase prices too high, just because it's a sexy sector at the moment.
Nexus Infrastructure (LON:NEXS)
Share price: 193p (up 0.8% today)
No. shares: 38.1m
Market cap: £73.5m
Trading update - this company's trading update was flagged up by andrea34l, in the comments section below. Gus1065 responded with a nice summary of the company, in comment no.9 below.
Nexus Infrastructure plc (AIM:NEXS), a leading provider of essential infrastructure services to the UK housebuilding and commercial sectors, announces a trading update ahead of its annual results for the financial year ended 30 September 2017 which will be announced on 9 January 2018.
I've not looked at this company before. It listed on AIM in Jul 2017. So the usual caution for new floats is probably a good idea.
Trading update - it's an in line update;
The Board expects the results for the Group for the year ended 30 September 2017 to be in line with its expectations.
The Board is encouraged by the level of growth in the Group's order book, which ended the year at 202.7m, a 25% year-on-year increase. This provides Nexus with good visibility for the year ahead.
The Stockopedia graphs show a nice progression in revenue & profitability;
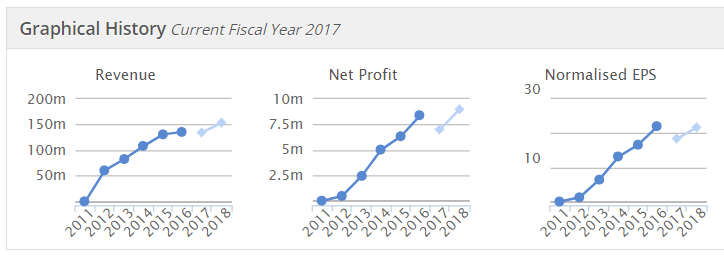
Looking at the usual Stockopedia growth & value graphics, the stand out numbers are the low PER, reasonable dividend yield, making this look apparently good value (although contractor type businesses don't usually command high valuation ratings);
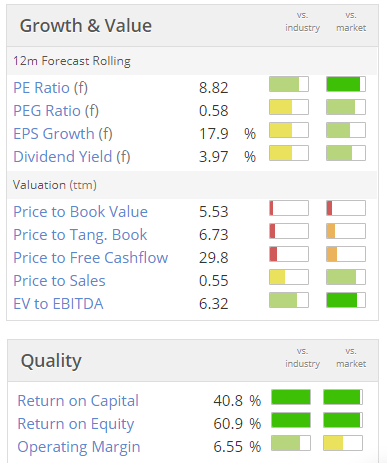
Its AIM Admission document is here. I might review that later.
My opinion - at first glance, it seems quite good value.
I'll wait until the 09/2017 numbers are published, in Jan 2018, before taking the stock idea any further. It hasn't yet published any results post-IPO.
Generally I tend to avoid any contractor type businesses, as so many of them seem to go wrong. However, the attraction here is that the company seems to make decent profit margins - suggesting that it has some particular niche, and/or expertise. Also, I like its exposure to housebuilding, as there is such a clear need for more housing and Government seem to finally be waking up to this need, after decades of neglect. Also, I like that the order book is up 25%.
So it's going on to my watch list.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

26 comments
Lombard Risk Management (LON:LRM) cash bid at 13p offered by Vermeer N.V. this morning. 90%+ premium to last night’s close. Decent result for anyone still holding a recent long position. One of the perils of shorting for anyone on the other side .....
https://www.stockopedia.com/share-prices/lombard-risk-management-LON:LRM/news/vermeg-group-nv-lombard-risk-mngment-offer-by-vermeg-group-nv-urn:newsml:reuters.com:20180111:nRSK5515Ba/
Gus.
Borrow in Lombard Risk Management (LON:LRM) getting tight, and now being rationed, one major provider was only able to offer me 50k shares on Thursday due to the number of existing clients already short and of course that could be recalled at any time.
Paul,
With regard to Bloomsbury Publishing (LON:BMY) which you covered yesterday I think we should give serious consideration to the digital platform they are developing. This did not grow in H1 but as the platform is mainly targeted at academia we should not expect an upswing until H2, which covers the start of the academic year.
I have never invested in a publisher before Bloomsbury Publishing (LON:BMY) which I took a position in a couple of weeks ago. Although their main avenue to profit over recent years has no doubt been Harry Potter I believe they are well regarded for the quality of their publications and the digital platform will grow not only organically but also with the addition of more "themes" such as the latest on China. This will be a digital offer in the English language on Chinese literature, with input from Chinese and non Chinese authors.
I think their current slate of authors will enable them to continue around the current profit levels whilst subsidising the development of the digital offer. They are conservative by nature and I feel their estimate of £5M profits from digital in 3-4 years time may well be exceeded.
Dave
Re Nexus Infrastructure, I notice that after several years of operating cash flow outstripping operating profit, operating cash flow has suddenly dropped to half of operating profit over the last 12 months.
Can anyone shed any light on why that might be?
Distil (LON:DIS) reported interims yesterday, with a muted "in line" outlook and what seem to be slightly lower growth rates. Graham was cautiously positive about DIS on 7 July, so it may be worth an update.
Hi FREng,
I gave this some thought, but decided against writing a section on Distil (LON:DIS) - it's been a listed company for about 18 years now, and has still only managed to get to about £2m p.a. revenues, flogging Blavod Black Vodka (which has never taken off), and various other drinks.
It beats me why such a tiny company has wasted so much money by maintaining a stock market listing for so long?
If some stellar growth started to come through, then it might be worth a fresh look.
Regards, Paul.
Anyone any thoughts on the drop over last days in Best Of The Best (LON:BOTB). No RNS.
Is there a read across from somewhere?
BOTB
Highly rated but illiquid share. I'm afraid it doesn't take much to move it in either direction.
It could well be as simple as someone taking profits.
Pretty huge spread of c10% as well between the bid and the offer.
If you want to see how illiquid a share is put in varying amounts to buy or sell.
Often your broking platform e.g. Hargreaves Lansdown will offer to fill say £10k of shares but if you go to say £15k they say there is no liquidity. You have to be careful with these types of shares, they can be roller coasters! Having said that, illiquid shares are epic on the way up - they gap up if a buyer is around. You are a hero and make loadsamoney. Unfortunately the reverse occurs if there is a seller around.
I first tried to buy these at 30p about 6 years ago...I was working as a fund manager and had my in house dealer hunt a few out. This guy was seriously good at finding shares, but even he couldn't find me a single share to buy. Well done those who did manage to find some to buy, you have done well!
Defenx (LON:DFX) look rather light in directors with technology backgrounds, so their software development problems come as no surprise. You may be able to sell cybersecurity with marketing skills, but you need strong software and project management skills to actually deliver it. I'm not buying.
I'd also be interested in any view on the interims from DIS yesterday... though I realise perhaps the market cap is too small. They seem to be making reasonable progress, and I presume the results are very seasonal buoyed by Xmas/New Year.
Operational review:
· Increased investment in marketing activity at the point of sale and events.
· Development of Blackwoods new vintage for launch in early Q4
· Investment in proprietary bottle and new packaging for Blackwoods Gin and Vodka.
· Continued growth in on-trade distribution for RedLeg Spiced Rum and Blackwoods Gin.
Financial Review - versus same period last year:
· Revenue increased by 22.8% to £0.818m (2016: £0.666m)
· Gross profit increased by 22.1% to £459k (2016: £376k)
· Volume (litres) increased by 41.3
· Investment in brand marketing and promotion increased by 36.3% to £199k (2016: £146k)
· Other administration costs were flat
· Reduction in operating loss of 68.1% to £21k (2016: £66k)
· Cash reserves of £690k (2016: £883k)
Don Goulding Executive Chairman, commenting on these results said:
"We continued to deliver strong year-on-year growth across our brand portfolio in the six months to 30th September 2017 despite lapping prior year pipeline fill in major retailers.
During this period we increased our brand marketing investment to extend our reach directly with consumers at festivals and at the point of sale. Importantly we increased marketing funds to cover development costs of our new Blackwood's vintage and new packaging across the Blackwoods Gin and Vodka range for launch in Q4 of our fiscal year.
A comment on this announcement from NEXS was noted on another discussion thread Paul:
The Board expects the results for the Group for the year ended 30 September 2017 to be in line with its expectations. The Board is encouraged by the level of growth in the Group's order book, which ended the year at £202.7m, a 25% year-on-year increase. This provides Nexus with good visibility for the year ahead.
Commenting on the Group's performance, Mike Morris, Chief Executive Officer said:
"This is the first trading update since our successful Initial Public Offering on AIM in July 2017. We are pleased to report that the full year results will be in line with our expectations and the significant improvement in the order book provides us with confidence for our future growth plans."
Any views? I have no idea what "their expectations" are, or market forecasts, and thus whether they could be considered good value.
Regards,
Andrea
Hi Andrea34l,
Prompted by Matylda's earlier note, I had a closer look at Nexus Infrastructure (LON:NEXS) following this morning's results announcement. It's a recent IPO from July this year - the shares have barely moved since then. I'm usually shy of IPOs (especially out of private equity firms) until they have at least a couple of years' decent trading behind them but in this case it's a partial exit by the founders (from 1976) who have retained a 43% stake in the firm which makes me more comfortable. Reasonable spread of institutions bought in to the IPO.
http://tools.morningstar.co.uk/uk/stockreport/default.aspx?tab=5&vw=own&SecurityToken=0P0001B9HQ%5D3%5D0%5DE0WWE%24%24ALL&Id=0P0001B9HQ&ClientFund=0&CurrencyId=BAS
The company provides utility infrastructure to new build estates, predominantly in the South UK, and counts 9 of the 10 largest builders among its clients. Makes it a derivative of a cyclical industry but my initial thinking is they appear to have a decent moat and as an essential but relatively small part of any development they're likely to have decent control over margins etc.. Financials look pretty good and the Stocko rankings are excellent. Debt profile looks a bit odd as they carry a lot of cash but also have a fair bit of debt (also very high payables/receivables) - may be a function of front end developer deposit payments; need to look further into this. Due to pay a decent dividend too.
On the whole I quite like it. Seems pretty illiquid (EMS of only 1,000 shares/£1,900) but spread this morning was a reasonable 2.5%. I've had a nibble and taken an opening position.
Gus.
Thanks Gus
Hi Andrea,
Thanks for the prompt on Nexus Infrastructure (LON:NEXS) - I've not come across this company before, with it being a recent (Jul 2017) float. It looks potentially interesting, so I'll add a section on it to today's report.
Regards, Paul.
Hi Paul/Andrea,
I've had a bit of a look into the Nexus Infrastructure (LON:NEXS) IPO document and the business.
First things first, it's not quite the typical construction contracting company. As Paul points out, it does operate (although not entirely) in a niche part of the construction industry. It has two operating companies, Tamdown and TriConnex. In the 2016 financial year, Tamdown accounted for c.83% of group revenue and 77% of adjusted operating profit. TriConnex accounted for 17% and 23%. Adjusted operating margin seems to be c.6-12% across the business, which is quite a bit higher than a run-of-the-mill construction company.
Tamdown does infrastructure groundworks, civil engineering, and concrete frame construction, but acts as a sub-contractor to either a housebuilder or a main contractor. This is pretty dull stuff but it appears to have good relationships with major housebuilders nationwide, and doesn't take on main contractor risk.
TriConnex is the potentially more exciting part of the business, and provides the material growth prospects. It is part of a small number of companies providing planning/design/installation services for utilities (gas, water, electricity and fibre) to residential developments. This is a niche part of the industry and has a much, much smaller pool of competitors than your average construction contractor; the main ones being GTC, SSE (listed), and Fulcrum. There don't appear to be many others.
They credibly explain how they intend to leverage the relationships they have established with housebuilders through Tamdown since 1976, in order to win more of the available market share for TriConnex. This type of work generally attracts a premium price and much more lenient contracting terms than normal construction (I have negotiated terms with a rival company and they generally get much more favourable terms than a typical contractor).
TriConnex is generally paid in advance, so working capital is much less of a problem. The difference between TriConnex and GTC, SSE (not sure about Fulcrum) is that GTC/SSE own and manage the utilities on a development post-installation. That has some degree of risk in it and you are responsible for maintenance etc. It appears that TriConnex does not do this, and before commencing work on a development, enters into an asset purchase agreement with the company who will own and manage it (could be a competitor) which pays a lump sum to TriConnex on or before installation is complete.
So generally, I feel this is all positive stuff, and is against the background of a demand for housebuilding. I think there is enough here to distinguish it as an investment from other construction companies. However, I feel there are some bear points worth mentioning:
1. Despite strong growth in the last 5-10 years, H1 2017 revenues are slightly down on H1 2016 (£60.6m vs £63.7m). Mgt say this was caused by the EU referendum. They also say that activity has since increased, and the order book is up 25%, which could mitigate the reduction.
2. If growth is likely to be so good, and they don't need cash to fund it particularly, then why list now? Is it because (in tandem with 1 above) they foresee a market downturn coming, or at least a slowdown of previous growth rates? Maybe, but it could be that the founders and friends just want some cash in their pockets, which is fair enough. The list of selling shareholders doesn't have any evil private equity, and it seems as though the founders would still have plenty of equity.
3. As Tamdown is a more 'normal' contracting business, one or more problem contracts could have a serious impact on financial results, regardless of TriConnex growth. Not much investors can do to prepare for this, but Tamdown doesn't have main contractor risk, and there doesn't appear to be any abnormally high value contracts, although it's all relative to the size of the business.
Overall, it looks good actually. There's not enough excitement to get involved right now. I think I will do as Paul suggested, and wait for the full year results.
Ta
Chris
Hi Chris.
Thanks for the review of the Nexus Infrastructure (LON:NEXS) IPO document. I had a long train journey yesterday which gave me a chance to go through it. As you say, an interesting business which although quite closely linked to the fortunes of the house building sector is quite different in some important aspects.
On your "bear 2" point about the motives for the listing, I agree cashing out by the original shareholders is the most likely (notwithstanding the fact they are retaining about 43%) although they also state that a listing gives them a useful mechanism to provide LTIP and other share incentives to management and employees (I noted everyone received a 100 share "thank you" in the IPO which was a nice touch.). Longer term, it could also be used as currency for a possible future acquisition/merger. They seem to be quite regionally focused and in an industry where there are presumably some decent economies of scale there may well be ambition to grow through acquisition at some point down the road.
Gus.
Thanks for that Gus. Yes, they certainly intimate that acquisitions may be sought, quite right - I also liked the 100 share thank you! Nice to see.
I'm slightly concerned that an LTIP is towards the front of their thoughts, so I'll watch for news of that.
In terms of regions, they're currently only really operating in the South East. They say they have a small operation for TriConnex in the South West, but only about 3% of that available market, and are considering branching out to the Midlands. As TriConnex seems to be quite a capital light business, partly due to up front payments and relatively long lead-in times for a project, it could prove fruitful.
Thanks
Chris
Zoo Digital (LON:ZOO) up 16% today on no news?
You asked about the ZOO share price rise. It could be:
1. ZOO are hosting a capital markets day today. This might be buying by people institutions learning more about ZOO and liking what they see
2. Momentum has been very strongly positive since the AGM statement on 25 September. Mark Minervini calls this share price drift - the tendency for surprisingly good results to be reflected in continued share price growth over several weeks or months.
3. Momentum investors piling in in response to the positive momentum
4. Just the normal random walk of relatively illiquid small cap shares responding to strongly to good news
I bought ZOO after the AGM statement. It seems to have a lot of the characteristics of a Minervini super-performer:
* good catalysts for growth - new products received well
* good share price momentum
* good earnings and revenue momentum
Down sides:
* Stockopedia shows very high gearing. I have not yet worked out whether this high gearing had been cleared by the recent placing. Does anyone know?
* reducing margins (new products have lower margins) which means hat profits may not increase at all this year or at least not as fast as revenues
I am up 89% in less than four weeks. Happy with the purchase but regretting not having bought more.
Small cap momentum has been treating me well so far... :)
Julianh - Re. Zoo Digital (LON:ZOO) Firstly well done for spotting this opportunity in time.
I had a look at this share a few months back and was put off by the balance sheet debt and the fact that broker forecasts for 2017 eps growth was ( and still is?) -44.5%.
I think the balance sheet is now a lot healthier after the placing which raised net £2.6m and further converted 1.1m of debt into equity.
By my calculations, the net effect is to make the old net debt of $5.6m come down to $1.2m. That reduces the multiple of EBITDA from 3.1 (red flag) to 0.6. A lot healthier.
However I am still puzzled by the forecast negative eps growth. Maybe someone else can enlighten me.
Hi Ramridge
Re: Zoo Digital EPS growth, I have no answers but a few guesses:
1. ZOO doesn't get much analyst cover. I have only found one analysts report since the AGM statement (FinnCap) which shows EPS for year ended March 2018 unchanged (not a 44% drop). This seems to be more in line with the AGM statement which suggested higher revenues but lower margins on the new services
2. The Stockopedia forecast fall in EPS may be out of date. The Stock report broker consensus trend shows no change in forecast for the whole year. So it looks as if the Thompsons databases are out of date or don't include the FinnCap analysts report.
For now I am going to trust the market (as demonstrated by the share price) rather than the analysts forecasts. We will see.
I agree that Zoo Digital (LON:ZOO) has characteristics of a Minervini supserstock. However, as Paul mentioned before on here, one client provides 44% of total revenue. Having been burned by high revenue concentration stocks in the past, that alone puts me off. Well done and good luck with it though!
Hi Ricky
Thanks for that. I have had a second look at the AGM statement and it says "The increasing proportion of subtitling work has reduced seasonality, reduced client concentration and improved visibility". What isn't clear is how much client concentration has been reduced. And of course you are right, 44% with one client puts the business severely at risk.
All the best to you.
Julian
Zoo Digital (LON:ZOO) still going
My morning smallcap tweet:
Defenx (LON:DFX), Seeing Machines (LON:SEE), Lombard Risk Management (LON:LRM)
Defenx (DFX) is late with product product updates, new product dev. FY will be materially below market forecasts, making a loss. Looking to employ a Group COO and a Group CTO.
Seeing Machines (SEE) will present research conducted with Emirates airline on how pilots interact and monitor instruments during procedures that could pose potential safety risks. I don't know if there's any sales potential from this.
Lombard Risk Managment (LRM) Has poor H1. Pretax -£5.9m (-£0.1m). "A number of opportunities we had hoped to secure in the period remain in the pipeline as market distractions such as MiFID II caused companies to delay on committing to new projects...This leaves us much to do in the second half, and converting our strong visible pipeline will be crucial to us meeting market forecasts...we are confident this can be achieved...We expect delivery of a strong second half will enable the Company to meet its stated objectives of being cash generative."