Small Cap Value Report (Wed 4 Oct 2017) - FUTR, TPT, IGE

Good morning, it's Paul here!
I don't have a lot of time available today, so apologies but won't be able to do any reader requests today.
3 companies have caught my eye, so here goes;
Future (LON:FUTR)
Share price: 346.3p (up 8.9% today)
No. shares: 45.4m
Market cap: £157.2m
Trading update - for the year ended 30 Sep 2017.
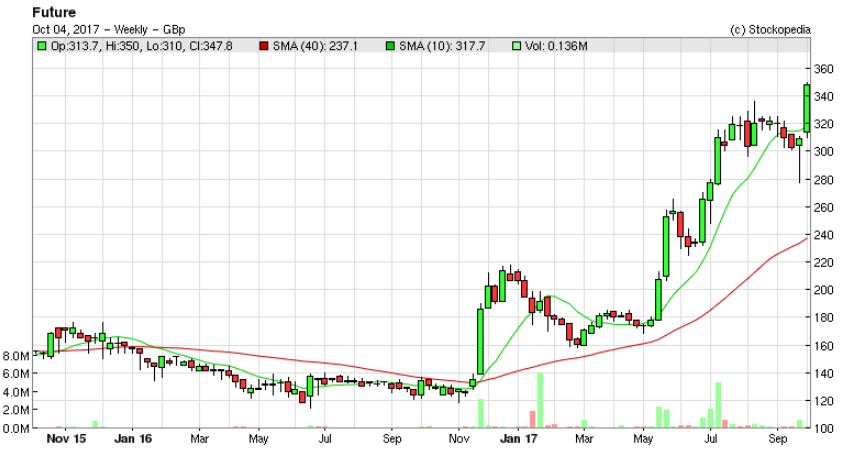
I'm not terribly familiar with this company, not having looked at it personally for over 3 years. Graham did a nice review of the latest interim results here on 19 May 2017, flagging potential value if growth continues. Well growth has continued, and the share price has risen by 68% in less than 5 months - so well done to shareholders here!
The activities of this group are publication of special interest consumer magazines, Apps, and websites. That sounds a little bit like what XLMedia (LON:XLM) do - although XLM seems focused mainly on feeding new customers to gambling websites, in return for a revenue share. I know XLM are diversifying into other areas too.
Anyway, things seem to be going well;
Overall trading for the year has been positive and it is anticipated that results for the full year will be ahead of the Board's expectations.
The Group has achieved good growth in operating profitability and has benefitted from strong cash conversion in the period, with year-end leverage less than 1x adjusted EBITDA.
The Group's Media division is performing well with fast revenue growth, particularly in eCommerce and events.
I like the sound of that - particularly the strong eCommerce revenue growth, which could drive the PE ratio higher - as we're in a market which loves online growth companies. Although I note from the last interim results that eCommerce was only 10.5% of total revenues.
Various other details are given.
Note that some growth has come from acquisitions.
Forecasts - I haven't seen any new broker updates today yet. So working on the existing Stockopedia broker consensus EPS figures, which are 15.2p for 09/2017 (which we now know will be exceeded). For 09/2018 the existing consensus is 20.5p.
Valuation - at 346p per share currently, I make the forward PER 16.9, which sounds reasonable for a growing company.
Balance sheet - as last reported this looks very weak to me. Although I see that a £22m placing at 250p per share was done in Jul 2017, to fund the bulk of a large £32m acquisition. That would still leave the balance sheet in a significantly negative NTAV position, which is a concern.
As always, the problem with acquisitive groups, is that the balance sheet usually ends up lop-sided, with massive intangibles (which are often ultimately written down to zero, when acquisitions go wrong at a later date). So there are risks associated with this type of acquisitive growth.
My opinion - this looks potentially interesting in my view, and is possibly worth a closer look. Have any readers looked into this one? I note that shrewd investor Richard Crow flagged this company as interesting recently, on Twitter. He has a good knack of spotting decent turnarounds.
I would want to get a better understanding of what went wrong in the past too, as there were a couple of years of heavy losses. It seems to have been a successful turnaround since then - so again it would be good to focus on what was wrong, and how it was fixed.
A lovely chart - but has the good news now been priced-in?
Topps Tiles (LON:TPT)
Share price: 73p (down 2.3% today)
No. shares: 192.4m
Market cap: £140.5m
Trading update - the company calls itself the UK's largest tile specialist (i.e. retailer).
This update covers the 52 weeks to 30 Sep 2017.
Like-for-likes down 2.9% for the year, but these are reported quarterly, so the trend was already known. Q4 was -3.0% LFL, which was a sequential improvement on Q3 being -4.7% LFL. Also note that the FY2016 comparatives were quite strong - making them hard to beat.
Whilst we have seen a moderate improvement in trading in our final quarter, market conditions remain challenging and the Group expects adjusted pre-tax profits for the 52 week period ended 30 September 2017 will be at the lower end of the current range of market expectations.
We already know that the consumer is being cautious at the moment, particularly on bigger ticket/household items, and that retailers are facing numerous cost headwinds. So this seems a reasonable outcome to me - it's not a disaster by any means.
Valuation - I see that one broker has trimmed its forecast for FY 9/2017 from 7.9p to 7.6p EPS. That puts the share on a PER of 9.6 - seemingly good value.
The trouble is, there is no earnings growth forecast for FY 9/2018 or FY 9/2019. So a mature business, which is struggling to stand still in terms of earnings, probably should be on a low PER.
Dividends - well worth having. The well-covered 3.5p divis are yielding 4.8% - so this share could be worth considering for an income portfolio, perhaps? I don't see any reason why that level of divi payout would not be sustainable, providing we don't encounter a more serious economic downturn.
Balance sheet - not the strongest, but a great deal improved from the very poor shape it was in a few years ago. I feel that gross debt of £40m is still a bit too high for comfort. Although deducting cash, reduces net debt to £26.6m - which looks OK.
My opinion - I have a generally favourable view of this business, as it is the sector leader in its niche, and seems to be well-managed.
The StockRank sums things up nicely;
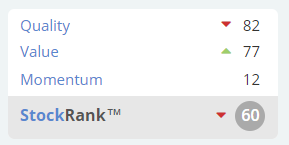
The quality ranking is very good, and I'm impressed with the decent operating profit margin, and strong ROCE and ROE.
Value is also ranking fairly strongly, which makes sense, given a low PER and decent dividend yield.
The big missing link at the moment is momentum - remember this score includes earnings forecast momentum, not just share price momentum (although the two often move in tandem, for obvious reasons).
I'm struggling to find any reasons why the company might begin out-performing forecasts any time soon. It seems to me that good companies in this sector are struggling to stand still whilst weaker companies are seeing profits go backwards.
Therefore, it's probably one I'll put on my watchlist, but I'm not ready to buy any yet. Ultimately though, it is a share I would like to own, once consumer confidence shows signs of returning, because it's a quality business.
We have to consider the political cycle here too. I think it's looking increasing inevitable that politicians of all sides are likely to be forced into having a splurge in public spending. Probably unwise long-term, but that would certainly be helpful in boosting demand for companies like TPT in the shorter term.
Image Scan Holdings (LON:IGE)
Share price: 10.2p (up 13.2% today)
No. shares: 135.7m
Market cap: £13.8m
(at the time of writing, I hold a long position in this share)
Trading update - this tiny company is a specialist in x-ray screening systems for security and industrial applications. It was brought to my attention after a series of recent positive trading updates. Well there's another one today! The numbers are still very small, but sales and earnings momentum really seem to be gathering pace.
It's now upped guidance for profits for y/e 30 Sep 2017 from £250k to £450k. This seems to be due delivering more orders before the year end cut-off than anticipated. There's also a strong order book, so hopefully the good momentum might continue.
Directorspeak sounds good;
Bill Mawer, Chairman and CEO of Image Scan, said: "September has been an exceptionally busy month for the Company and the response of our staff to new opportunities has been very impressive. I am also particularly pleased by the strength of the orderbook with which we start the new financial year. Demand for our new systems remains strong."
(apologies for formatting, I couldn't manage to clear the bolding)
My opinion - I wouldn't normally touch anything this small & iliquid. However, what I like here are;
- Newish management with relevant experience & good track record
- Positive results are now appearing from streamlining & refocusing the business
- Innovation - new products have been successfully developed, which are clearly meeting market demand
- Niche activities with little competition
- Earnings momentum - whilst still quite early days, we've now seen 2 or 3 consecutive earnings upgrades
- Operational gearing - so if demand continues rising, then profits could rise a lot more than people currently expect
- Poor historic track record & results. So the shares are still somewhat off the radar for most investors - possible upside if institutions start to get interested maybe? (probably too small at the moment, but in future that could be a good catalyst)
There's an excellent, recent, comprehensive review of the business from the Chairman, recorded by PIWorld available here.
I think the current share price is probably about right, but it's the long-term potential which interests me, if trading continues to improve.
I have to dash now, see you tomorrow!
Regards, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

15 comments
I thought the trading update from IGE was excellent. Take the point about small and illiquid but that can support eye-watering returns as insti's come onboard and operational gearing improves. Not tradeable in any serious way but well worth a small investment with a 2 to 3 year view. Feels a bit like a young Judges Scientific. I did buy a small stake the day after the recent Mello presentation.
What went wrong with Future (LON:FUTR) is very simple: it was a publisher or paper tech and lifestyle magazines. The internet happened. They're trying to adapt by becoming primarily an online publisher.
The quality ranking is very good, and I'm impressed with the decent operating profit margin, and strong ROCE and ROE.
Value is also ranking fairly strongly, which makes sense, given a low PER and decent dividend yield.
The big missing link at the moment is momentum - remember this score includes earnings forecast momentum, not just share price momentum (although the two often move in tandem, for obvious reasons).
This is a great summary Paul. It's at times such as these that I need to suppress my highly contrarian nature because it attracts me to situations like Topps Tiles (LON:TPT) like a moth to a flame. And with retailers, this years poor LFL numbers are next years much easier comparatives. When you take into account the stockmarket has a memory like a sieve this could make a decent investment on a one year timescale. I'm seriously tempted to start building a position here, because the management seem to be sound and there's a 5% divi for comfort to boot. As Jim Carrey once said "Somebody stop me!"
All the best, Si
Si,
Tiling often forms part of a big ticket item, namely a house move or a complete kitchen or bathroom refit. As such, like the rest of the building materials sector, it is very cyclical. I think we would need to be very confident on the outlook for the UK economy/housing market over the next 12/18 months before investing in Topps Tiles (LON:TPT)
Dave
Tiling often forms part of a big ticket item, namely a house move or a complete kitchen or bathroom refit. As such, like the rest of the building materials sector, it is very cyclical. I think we would need to be very confident on the outlook for the UK economy/housing market over the next 12/18 months before investing in Topps Tiles (LON:TPT)
Dave,
Thanks for helping out on the counselling front in my time of need, it's greatly appreciated! Of course, I understand what the downsides of investing in Topps Tiles (LON:TPT) are i.e. a consumer cyclical share dependent on home improvements which are largely driven by housing transactions. You could add to your list that interest rates are on their way up (it was only last week the Governor of the BoE announced as much) to make matters worse and that you should only buy cyclical companies when they are on high PE's because their earnings have collapsed by the time they hit the bottom.
However, I don't feel things will necessarily get that bad. And there's always the counter argument that people will improve their existing house rather than move if the housing market slows down. I know we did this... we were looking to move last year but instead decided to redo all the bathrooms, put down new wooden flooring etc. A new boiler is coming next week and then we'll replace all the windows but I'm waiting for the replacement window companies to be on their knees before I get any quotes. I'm not sure things will get so bad in terms of unemployment that people will stop doing home improvements, although things will slow and the LFL numbers are likely to keep deteriorating.
I'm still considering it. Like Paul it's an interesting situation and a sound company, so it's on my watchlist but with more cash than I would like on the sidelines earning nothing it's all too easy to be trigger happy.. .
All the best, Si
Any thoughts on the announcement from via net Paul thanks steve
Hi Cleeve,
Any thoughts on the announcement from via net Paul thanks steve
Yes. I didn't think the Vianet (LON:VNET) (in which I hold a long position) acquisition today seemed significant enough to include it in the main report.
From what I can make out though, it seems a sensible deal - a profitable, complementary company, with a decent-sized earn-out, to help adjust the acquisition price to match performance post-acquisition. So it looks good to me, based on very limited information.
Another aspect of this deal that I like, is that they already know the company & work with it. It's far better to buy something you know - less likely for the deal to go sour at a later date.
VNET has an interesting set of skills - it's an internet of things company, with 250k devices already reporting to its servers. If they can find new sectors to expand into, then who knows what could be done with their existing expertise in managing & reporting on customer data?
Regards, Paul.
Thanks Paul very interesting, I had wrongly assumed that you had sold out and got bored with it as I nearly have done on several occassions. The chairman from memory has a lot of skin in the game which I guess is a good thing
Many thanks
Steve
Hi Steve,
I held Vianet (LON:VNET) a few years back, and did indeed sell out as it didn't seem to be going anywhere.
However, I had a fresh look at it earlier this year, and decided to give it another go - as the group has made slow, but steady progress, has sold its fuel division, has net cash, and has paid generous (albeit static) divis for years now.
Plus there's always the possibility that they might develop something new & exciting with their internet of things expertise. Although I'm not holding my breath on that! It's basically a value share, with some potential growth stuff thrown in for free. Mgt has tons of skin in the game, so not likely to go badly wrong IMO.
Regards, Paul.
Vianet (LON:VNET)
I had to check back, but I find I have held a small position in VNET for over 4 years, bought at a shade under £1 after costs.
I was thinking that this was one of those shares that had done nothing during the time I held, but looking back I recall that it fell to around 70p shortly after I bought (due if I remember correctly to concerns over the relationship with tied pubs - it was essentially just a beerflow company then)
So whilst it has not exactly set the world on fire it has made decent progress from that low point.
By August this year I was pretty much break even after 4 1/2 years holding, which is not exactly impressive! (although 29 p/% in dividends over the period somewhat compensates.)
Since then I've made a 25% gain - half of that seemingly being due to the acquisition announced today. This investing game is strange sometimes, this "nothing" stock has now returned me >10% over nearly 5 years which while not overly exciting is not to be sniffed at.
I'm surprised though by today's reaction to the acquisition, like you I thought it was small beer (hoho) and possibly a little expensive. It will increase turnover by about 6% and they have paid a minimum of 7 x operating profit. I think though with the bank loan funding the £2m initial consideration costing on 3% it is instantly earning accretive (and still is I believe if the full earn-out kicks in raising the overall price to £4.25m)
Strategically though it does look a good fit being a complementary business rather than just buying for scale. Vendman, "develops, manages, and supports integrated software and mobile applications for the unattended retailing industry." I presume this means vending machines and that being the case I can certainly think there are some good cross selling opportunities.
Maybe this does begin to give the opportunity for transformational growth, that I recall thinking was possible when I first invested.
I am of the view at the moment that the market has become very frothy - IGE has mushroomed 22% (with about half of that rise occurring only in the last 30 minutes), FUTR is also up 15%... and I did think of buying more FUTR when the buy price was at 349p but with it soon rising to 370 then I am loathed to be chased ever higher by the market makers. I don't know what others think...?
My morning smallcap tweet:
Lightwaverf (LON:LWRF), Image Scan Holdings (LON:IGE), Redhall (LON:RHL), Future (LON:FUTR), Adept Telecom (LON:ADT), Topps Tiles (LON:TPT), Learning Technologies (LON:LTG)
Lightwaverf (LWRF) FY trading. Rev over 2x, pretax loss broadly in line with prior year (£0.84m).
Image Scan Holdings (IGE) FY trading. Extra order boosts rev to £5.0m, 11% up on prev guidance. Pretax £450k up £200k on guidance.
Redhall Group (RHL) FY trading materially below expectations due to contract delays. The H2 weighting curse. "The Directors do not expect these delays to continue and remain confident of a strong performance from Jordan Manufacturing in 2018." Well, you didn't expect the delays at all! Exp next year profit in line.
Future (FUTR) FY will be ahead of the Board's expectations.
Adept Telecom (ADT) AGM stmt. Sets H1 div at 4.25p up 13% even though interims not for a month. XD 16 March. Why announce it now?
Topps Tiles (TPT) FY adj pretax will be at the lower end of market expectations.
Learning Technologies Group (LTG) Financial impact of a major contract will be accelerated in 2017. FY boosted but 2018 negated.
I may have a position in any or all of the shares covered
"I may have a position in any or all of the shares covered".
Don't you know?
Or is it secret?
"I may have a position in any or all of the shares covered" is a boilerplate my report system adds in case I forget to disclose a position. I do have a tiny amount of Adept Telecom (LON:ADT) shares to qualify for a rental-free land line. I thought it might be misleading to say I was long in this case so I left the blanket disclaimer in.
LOL. Only kidding - just seemed unnecessarily enigmatic.
I'm very impressed that you have a "report system", however.