Small Cap Value Report (Wed 7 Mar 2018) - RBG, RTN, BQE

Good morning, Paul here!
Apologies for yesterday's report being late - it's now finished, and covers results from;
A fairly detailed look at Luceco (LON:LUCE) and its latest profit warning. Is it a buying opportunity, or should we follow the excellent conclusion of Stockopedia's brilliant 2016 profit warning analysis, by selling first and asking questions later?
Q3 results from Begbies Traynor (LON:BEG) - (I am long)
LoopUp (LON:LOOP) results
Headlam (LON:HEAD) results.
Anyway, to get you started today, here is the link to yesterday's report.
I'm having insomnia issues at the moment, so got up in the middle of the night to write it. Not ideal, but there we go.
Also, please could readers kindly try to avoid having spats in the comments section? It's rather tiresome when that happens! Many thanks. Although I must admit that one (now former) reader flouncing off yesterday (I couldn't work out why), with his parting shot being to tell us that 99% of us are clueless, which gave me the best laugh of the day!
Revolution Bars (LON:RBG)
Share price: 148p
No. shares: 50.0m
Market cap: £74.0m
(at the time of writing, I hold a long position in this share)
Brief comment
I've been wading through the reader comments for yesterday, and quite a few people want me to comment on recent results from Revolution Bars. I was quite pleased that Graham was working that day, as people already know that I'm bullish on the company, so thought it would be interesting to get Graham's take - which I can probably summarise as being lukewarm, at best!
I'm sure you've already worked out that Stockopedia gives Graham & I complete freedom to write what we believe to be true, at that moment in time, on all companies. We don't confer, or go soft on stocks that the other (or anyone else for that matter) happens to own. In any case, I welcome bearish views on stocks that I hold, as it makes me think more, and question whether I'm right or wrong.
There isn't time at the moment to write anything detailed on RBG, but to give you my current thinking, here's a copy of something I just posted in the comments to yesterday's article, which you might otherwise have missed;
- The accounting issues are pretty irrelevant I think - indeed the onerous lease provision will actually boost future reported profits, so could be seen as positive.
- Roll-out of new branches going well (exceeding initial targets)
- Almost debt-free
- Current trading of -2% LFLs is a bit disappointing
- Food - good to see new CEO & COO being focused (by the Chairman) on improving their food offering. This is key, and a big opportunity in my view. They already have big footfall, but if they could fill the bars with diners during the day, then a lot of upside - high margin sales, with little to no additional fixed costs
- This share is woefully misunderstood by the stock market - we can buy now at under 150p, when a cash bidder was turned away at 203p quite recently. So the valuation clearly doesn't make sense.
I am very confident this is likely to be a big win, but no idea when - patience needed.
Obviously, as always, that's just my personal opinion (on a stock which I hold a big long position) - which is sometimes right, and sometimes wrong!
Restaurant (LON:RTN)
Share price: 255p (up 7.2% today)
No. shares: 201.1m
Market cap: £512.8m
(at the time of writing, I hold a short position in this share)
Here are few bullet points, which I posted as a comment below, in reply to a reader. It seems worth copying here, for people who don't read the comments. Not a small cap, but it's in a sector I take a particular interest in, and has interesting read-across for a sector that is really struggling at the moment, due to over-capacity & cost pressures.
For me, this one is glass half empty, but I can see that if people believe the turnaround strategy will work, then they might see it as glass half full. I would consider buying back here, if the company can start reporting positive LFL sales again, but doubt that is likely to happen any time soon. Time will tell.
My impression is that the figures are not as bad as they could be, but the narrative seems to have been heavily PR'd to create a positive impression, when actually profits are falling, and likely to continue falling.
2017 results;
- LFL sales down 3.0%
- Adjusted profit before tax down from £77.1m in 2016, to £56.7m in 2017
- Dividend held at 17.4p, but that not's well covered any more, by adjusted EPS of 22.3p
Current trading - "broadly in line", so slightly below in reality.
Outlook - this is cleverly worded to sound positive, but actually seems negative to me. "Significant price investments" means cutting prices & discounting. So that's bad for profitability, if volumes don't increase faster than prices have fallen. The way I read this, it's a profits warning for H1, with hopes that H2 will be better;
The trading performance of the business in the first half of 2018 will reflect the significant price investments made in the middle of last year. We expect to benefit from our strategic initiatives gaining further traction as the year progresses.
On the positive side;
- Strong balance sheet, although working capital looks odd, with very large trade & other payables
- Little net debt
- Great cash generation - so if it got into difficulties, it could cut capex to the bone, and ride out a recession, unlike many weaker competitors.
- Management is implementing a turnaround plan, which should help (e.g. closing poorly performing sites, cutting costs)
It's difficult to exaggerate just how bad things are in the casual dining sector, due to big over-capacity & well publicised ongoing cost pressures. So this is probably a sector to avoid altogether, in my view.
I see no reason to close my (small) short position on RTN, based on today's results.
Bioquell (LON:BQE)
Share price: 322.5p (unchanged today, at market close)
No. shares: 22.47m
Market cap: £72.5m
Bioquell PLC (LSE symbol:BQE), the specialist provider of biodecontamination systems and services to the international Life Sciences, Pharmaceutical and Healthcare markets, today announces its preliminary results for the year ending 31st December 2017.
This is not the usual type of stock that I cover. However, it's profitable, and I've written about it before, so no harm in having a quick gander at today's results.
Its defence business is so small, that it's hardly worth looking at. The core business is in the biodecontamination sector.
These figures look good;
- Revenue up 10% to £29.2m, up 6% at constant currency
- Decent gross margin - up from 48% in 2016, to 52% in 2017
- EBITDA up 29% to £5.3m
- Note that the company only capitalised £132k of development spend in 2017. So the gap between EBITDA and operating profit seems to be due to amortisation of historic development spend - i.e. the business is nicely cash generative now.
- Pre-exceptional operating profit up 81% to £2.9m
- Cash-rich, with £14.6m cash on the balance sheet, with no interest-bearing debt.
- Balance sheet overall is very strong indeed, so the group clearly has scope for either special divis/buybacks, or acquisition(s)
- Last year there was a major share buyback, of £41.4m, shown on the cashflow statement
Current trading - looks fine;
The business has started 2018 in line with expectations and the board remains confident in delivering further growth in revenue and profits.
My opinion - I've only had a very quick look, but like what I see.
What's interesting is that, whilst the PER looks high, the price to free cashflow is a lot more attractive.
Also take into account that net cash is 20% of the market cap - and this is genuine cash, it's not smoke & mirrors, in my view.
I don't have time to dig any deeper at the moment, but this one certainly looks worthy of deeper research. Note that Christopher Mills is involved, who has an excellent track record of sniffing our overlooked and undervalued companies. The trouble is, he sometimes grabs the upside for himself with a lowball takeover bid - that happened at Essenden for example, where I was forced out of a nice position at a low premium.
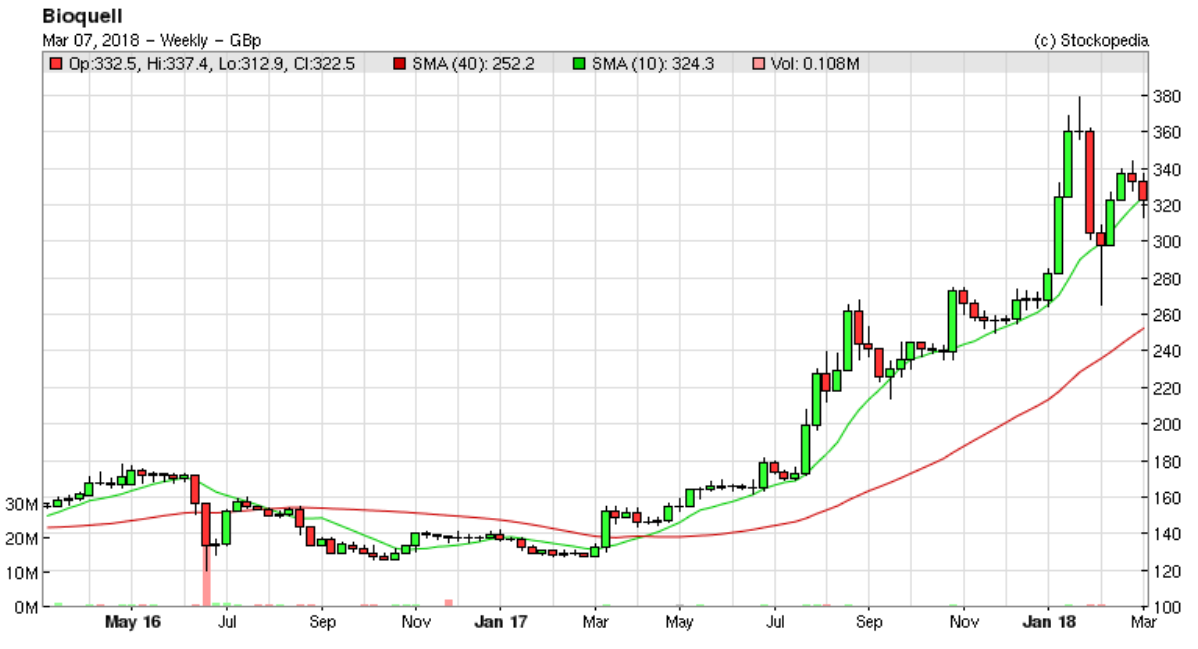
Bioquell has a strong StockRank of 87, which confirms that this one might be worth doing some more work on. Nice chart too;
I'll leave it there for today.
See you in the morning.
Best wishes, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

64 comments
I am very confident this is likely to be a big win, but no idea when - patience needed.
Hi Paul,
Re: Revolution Bars (LON:RBG) I assume you noticed the after hours RNS yesterday:
https://www.investegate.co.uk/...
Another shrewd investor (Keith Ashworth-Lord) has taken the holding up to 10% in his Buffettology Fund. The only collective vehicles I hold are Fundsmith but if I had to choose another it would definitely be this fund.
All the best, Si
Si
You’ll be relieved/not interested to note that none of your red thumbs came from me as an iPad running a Safari browser doesn’t allow me so to do..and if it did I wouldn’t done so as I find your views interesting & thought provoking.
I for one would be delighted if you continued to post but obviously that’s only a decision for you.
PS I still dislike Revolution Bars (LON:RBG) and like Paul & appreciate his views both here and on Twitter..Can’t do a smiley but would put one here if I could
Well done, Si, you're going out in style.
A defeated gladiator condemned to death by the crowd.
Come on Si lighten up, there is no requirement to be a latter day Captain Oates!
Red or blue thumbs do not win an argument or even represent a majority view and who said the majority are always right? You have opinions as do others, don't take it personally, this is not that kind of discussion board.
Thanks for your concern.
When I first joined Stockopedia it was a much more tolerant place to contribute with like-minded investors. You hardly ever saw a post with red thumbs. It was like a village pub with a good community spirit. Nowadays, it's more like a Revolution at 1am on a Sunday morning, inhabited by too many ne'er do wells and "you lookin' at me" types with no bouncers on the doors. Not my kind of place at all. Anyway, this is my last word on the matter, and also my last ever post on Stockopedia.
All the best, Si
Paul, thank you for your helpful analyses, which do much to make Stockopedia a valuable resource.
I have a normal policy of not investing in retail businesses, including retail eateries, because of their fickle and over-extended customers. I have therefore passed over the comments on Revolution Bars etc to look at Bioquell (LON:BQE), which at first glance is attractive to me because its customers in the life science and health sectors give the business defensive qualities.
The company has intellectual property (a quick search revealed 3 granted US patents), and the IP may - or may not - give rise to a real defensive moat. It would be nice to see operating margin rising to validate the defensive moat hypothesis.
In 2014/15, the company sold a significant part of its then business for £33.6 million, and the 2016 annual report says: "Strategic review concluded; management restructured and focus on further development and improvement of bio-decontamination business". The increase in revenue from 2016 to 2017 suggests that the strategy has been successful but, because of the change of business focus, historic trends are not available to be analysed.
Paul says that net cash is 20% of market cap, presumably leading to a cash-adjusted share price of 266.4p and a cash-adjusted trailing PE ratio of 27. (Is that a meaningful calculation to undertake?). Even at this price, the PE ratio is too high for me, especially as the absence of a long comparable track record makes future performance particularly speculative.
One for the watch list.
I don't see how any of the Revolution Bars (LON:RBG) comments can be construed as a comment on Paul's position. He's more than capable of analysing the exceptionals and his comment on the onerous leases was simply that it was all to the good because it would make future profits look better.
I do have a problem with some current accounting standards and some companies use of them because they make it very hard for novice, naive or time-poor investors to really get a grip on what is going on. And in the cases mentioned also seem to make it difficult for the companies' accountants to work out the figures correctly.
I note Paul's slightly adverse comment about Christopher Mills: whilst I hesitate to disagree, I have been an admirer of Christopher Mills for some years and have followed him in to Bioquell (LON:BQE) as well as into North Atlantic Smaller Companies Inv Trust (LON:NAS) MJ Gleeson (LON:GLE) and EKF Diagnostics Holdings (LON:EKF)
These have all been rewarding experiences: at least 100% up on all 4 of the above mentioned (and 350% up on MJ Gleeson (LON:GLE) ). I still hold all of these (although I have a rule to top-slice when a share has doubled).
I would therefore suggest that having Mills on the Board is rather a positive, not a negative.
Best regards to all,
Richard
I am, sort of, with Phil on the Revolution Bars (LON:RBG) issues. The 'sort of' is because I think it is virtually impossible, even going through all the notes to the accounts in detail, to know exactly what was going on. And clearly the company don't either as they chose to restate the accounts for 2015 and 2016 for misapplication of accounting standards (Restaurant (LON:RTN) had to do likewise in their results yesterday, but to a much lesser extent). I go into more depth since it seems to be an active discussion, and quote from the accounts; please ignore if it is too abstruse for you. It is for me which is why I wouldn't hold Revolution Bars (LON:RBG).
Also require estimation and judgement
And quite a few other expenditures are exceptional, even if they occur regularly and aren't treated as exceptional by other companies
And onerous leases are very sensitive to assumptions about budgeted cash flow and about the risk free discount rate
A consequence of this is that it becomes very hard to work out the profit/loss on current trading, the extent of investment in new business, capitalisation of anticipated losses and changes in assumptions not directly related to their own business activity.
It's no wonder that everyone concentrates on cash flow.
Reading with interest the comments re Revolution Bars (LON:RBG) & onerous leases but I think it doesn't have quite the impact some are hinting at.
Let's say that this year we make a provision of £90 for 9 years future rent at £9 per annum. This is an accounting entry only (non-cash) so we debit the exceptional item in P&L account and credit the provision, included in creditors in the balance sheet.
In year 2 though we actually pay the £9 annual rent & this is included as an ordinary expense so a loss of £9 is shown as EBITDA. Beneath the line though we now can release £9 of the provision so this is a credit to P & L. Overall there is no charge to P&L which is correct because the charge was made when the provision was established but actually the provision has not reduced the rent charge that is shown as an ordinary expense in the year.
Therefore, for instance, it has no effect on the profits on which management bonuses are assessed as referred to above or on adjusted EPS in those years.
Does that make sense? Maybe I'm completely wrong though so please say if I am!
Abstruse this stuff may be xcity but I think that the level of discussion shows how easy it is to misunderstand these type of adjustments. As Phil alluded to in his article the real issue behind the impairments/provisions is that some of the Revolution Bars (LON:RBG) bars are trading at a loss and this is a real change to how the group looked a year or two ago. Throw in some confusion around the assumptions and judgements being made and you have a bit of a muddle for investors.
NB the section that you included around bar opening costs makes me feel more than ever that these are far from exceptional. For Revolution Bars (LON:RBG) they are always going to have some bars which aren't open and some staff who have been recruited (and are being trained) and yet aren't bringing in revenue. It's just not possible to have 100% utilisation. Next they'll be excluding costs associated with staff who are on maternity/paternity leave?
As Phil alluded to in his article the real issue behind the impairments/provisions is that some of the Revolution Bars (LON:RBG) bars are trading at a loss and this is a real change to how the group looked a year or two ago. Throw in some confusion around the assumptions and judgements being made and you have a bit of a muddle for investors.
Damian,
I don't really see any muddle. The previous CEO and CFO (both of them!) were useless and you are always going to get a kitchen sink job under new management, particularly with a fresh set of eyes on the accounting side. I'm happy to accept most of the adjustments for now and see how things progress going forward.
I found Phil Oakley's article interesting for the general discussion on statutory vs underlying results, but as others have pointed out, he has plainly got some things wrong or made assumptions with regard to Revolution Bars (LON:RBG) and if you're going to write with such authority on a specific subject and make accusations that the board have massaged the accounts to get their bonuses, then you're verging on libel. I think he's sailing pretty close to the wind myself.
I have no idea why so many people waste so many words on Revolution Bars (LON:RBG) - it's a historically badly managed and mediocre business that's on a mediocre rating that doesn't have much debt - it's not going to go bust. I assume all these words are due to Paul having a well publicised long position and people are just sniping at him using Revolution Bars (LON:RBG) as a cover. I find it all quite pathetic to be honest, let's spend our time discussing more interesting companies.
All the best, Si
Hi Simon
‘I have no idea why so many people waste so many words on Revolution Bars (LON:RBG) - it's a historically badly managed and mediocre business that's on a mediocre rating that doesn't have much debt - it's not going to go bust. I assume all these words are due to Paul having a well publicised long position and people are just sniping at him using Revolution Bars (LON:RBG) as a cover. I find it all quite pathetic to be honest, let's spend our time discussing more interesting companies.’
I’ve never seen you write something that I disagree with more, I like & respect Paul , I dislike & would never invest in Revolution Bars (LON:RBG) I’m quite capable of seperating the two ..and so are a lot of other people
I’ve never seen you write something that I disagree with more, I like & respect Paul
I was merely speculating on why a rather mundane and badly run business gets so many words written about it, that's all. If Paul didn't write about it here so often would anyone else bother? I suspect not. It's popularity as an investment is purely down to Paul as far as I can see. Was it even discussed here before Paul first raised it?
I dislike & would never invest in Revolution Bars (LON:RBG) I’m quite capable of seperating the two ..and so are a lot of other people
I'm not sure why you've taken my comment so personally? It was a general comment as to why there are so many posts about such a mundane business that's trading poorly. It's not a fraud, it's not about to go bust and there are many better (or poorer if that's your want) companies to discuss. And yet here we are discussing it again. It seems from your post you have strong feelings and emotions towards Revolution Bars (LON:RBG) which I find a bit strange tbh, particularly if you have no position. Sorry if I've got your back up, it was not intentional.
All the best, Si
Hi Si
I’ve taken it personally because you made it so..by telling me that my ( & others) negative posts on Revolution Bars (LON:RBG) were a smokescreen for having a pop at Paul!
Anyhow the reason it gets so much comment is that they are an interesting business to dissect, for me it has added interest because Paul likes it ..& I don’t.
cheers
Hi Si
I’ve taken it personally because you made it so..by telling me that my ( & others) negative posts on Revolution Bars (LON:RBG) were a smokescreen for having a pop at Paul!
I'm sorry but I quite clearly addressed my question to Damian (in reply to his post) and I did not mention you or anyone else by name. How can you possibly take it so personally? I think you need to maybe re-read my post and consider why you replied in the way you did. And I didn't specifically refer to negative posts either just the number of posts. It seems for some reason you just took it as an excuse to attack me, so you're the only one personalising things.
Anyway, you can't possibly know that there aren't people out their with agendas, unless you believe everything you read on the internet? It's pretty obvious over the years there are a number of people who like bashing Paul and it's little wonder he wants to take a break. If you don't like what I write, then that's fine, but please play the ball not the man as I always try to do.
All the best, Si
Hi Simoan,
Thanks for the thoughts. Without wanting to over-prolong this thread it's fair to say that I'm only commenting because I used to be invested in Revolution Bars (LON:RBG) (bought before the profit warning, doubled up when trading seemed to have stabilised and sold out just before the bid deadline) and have some interest in the company. I also happen to think that this is an excellent case study which a lot of readers are familiar with - so it's worth going over its accounts presentation.
On the muddle front my point is simply that accounts with adjustments, provisions and impairments are hard for the part-time, non-expert investor to understand. The additional moving parts add complexity and make it hard to pin down the performance of the underlying business. For sure the company can't avoid some of this complexity as the new board clear the decks but it doesn't help.
Anyway who knows what will happen. With luck Stonegate will reappear with a 250p cash offer and everyone will be laughing!
Damian
Hi Damian,
I also happen to think that this is an excellent case study which a lot of readers are familiar with - so it's worth going over its accounts presentation.
On the muddle front my point is simply that accounts with adjustments, provisions and impairments are hard for the part-time, non-expert investor to understand. The additional moving parts add complexity and make it hard to pin down the performance of the underlying business. For sure the company can't avoid some of this complexity as the new board clear the decks but it doesn't help.
I realise there is a level of interest in Revolution Bars (LON:RBG) here (mainly due to Paul) but IMO there are far worse and more egregious examples of the use of adjustments to numbers, and Phil Oakley had a great example with RPC (LON:RPC) who have been doing it for several years as he illustrated which also has a significant amount of debt.
And yet Phil turned his guns on Revolution Bars (LON:RBG) which has just had a change of management and so there is no doubt an element of kitchen sinking and a new CFO with maybe a more conservative approach - that's a good thing, not a bad thing! So what if the new management see things differently from the old who were clearly not very good? So to suggest the new management are trying to ensure they get their bonuses by massaging the numbers is a low blow and verging on libel IMHO. Phil can't possibly know that and as a respected commentator he shouldn't be saying things like that either. Maybe he has a bee in his bonnet on Revolution Bars (LON:RBG) for some reason?
All the best, Si
"suggest the new management are trying to ensure they get their bonuses by massaging the numbers" - shame on anybody who would possibly think such bad bad thoughts!
"just had a change of management and so there is no doubt an element of kitchen sinking"
When does "kitchen sinking" become "massaging" or should I be asking when does "massaging" become "kitchen sinking"?
Bonitabeach
No position.
Yes, exactly, shameful to suggest that any of our fine and upstanding company managements could in any way possibly qualify for the Captain Louis Renault Award:
https://www.youtube.com/watch?v=1H-PS_pr-t0
I see the red thumbs are out which I find really childish. I've never liked the idea of likes, recommendations, thumbs etc. and hope that Stocko drop them as part of the changes. It discourages people from airing dissenting views and gives the upper hand to the crowd. I don't like crowds, never have, and have no interest in communicating in a kindergarten.
However, the crowd wins. I wish you all well. Goodbye.
Si
Come on Si lighten up, there is no requirement to be a latter day Captain Oates!
Red or blue thumbs do not win an argument or even represent a majority view and who said the majority are always right? You have opinions as do others, don't take it personally, this is not that kind of discussion board.
Have a good weekend and see you Monday for more fun and games.
Bonitabeach
Thanks Damian,
Very interesting article. A lot of the issues have been discussed here one way or another. However, one I picked up on, and hadn't previously noticed was this:
This is important as the financial performance targets for 2018 management bonuses are based on adjusted EBITDA and adjusted profit before tax according to the latest annual report:
“For the 52 weeks ending 30 June 2018,the financial targets will be measured based on adjusted EBITDA and adjusted profit before tax (“PBT”).”
I think it’s right for investors in any company to ask whether it is reasonable that over £3m of cash spent on fees and payoffs should be excluded from the calculation of their bonuses?
And
By creating a provision, Revolution Bars is expensing its remaining rent obligations on some bars upfront in full and treating the cost as an exceptional one which many analysts and investors are encouraged to ignore.
The future benefits to profits will not be classified as exceptional and will no doubt count towards management bonus targets
Peter
If you're invested in Revolution Bars (LON:RBG) then this is a "must read" article about how they've massaged profits: https://philoakley.sharescope.co.uk/index.php/2018/03/07/can-you-trust-a-companys-profits/
There's a lot of common sense in that article, particularly this comment with which I wholeheartedly agree:
Any serious investor should be going through the numbers and making their own adjustments to the reported numbers as they see fit, so I don't wholly buy into this narrative about numbers being "massaged" or management "trying to pull the wool over the eyes of investors".
I would take issue with Mr Oakley on a few points:
Firstly this comment on the impact on future periods of Revolution Bars (LON:RBG) 's onerous lease provisions:
I don't think that is right. Look at the last annual report and it's clear that movements on the onerous lease provision in both directions are being included within exceptional items, so the management hasn't been taking credit when those movements serve to boost profits:
Even if they did try to pull that trick in future periods, there is enough information provided in the annual report for investors to be able to make their own adjustments for that movement, if they want to.
Secondly on bar pre-opening costs, I have no problem with treating these as exceptionals. They are costs incurred up front where the related income will be generated in future periods. In days gone by the 'matching' principle would have applied and it would have been possible to defer those costs on the balance sheet as 'prepayments', to be released to the income statement when the bar opened.
Mr Oakley's point seems to be that these costs are recurring due to the roll out strategy and are therefore not exceptional, but I think he glosses over the point that each year's costs will relate to different sites and depending on when sites open, the balance incurred at each period-end may vary considerably from year to year, thereby distorting underlying profitability.
Thirdly:
I don't think that's quite right. If a lease has become onerous, it is not up to management whether or not to create a provision, they are required to do so by the accounting standards. There may be an element of kitchen sinking involved in the case of RBG, but if so that will have arisen from the assumptions and methodology used to calculate the provision, not from a decision to create the provision in the first place. Perhaps that is semantics, but when combined with my first point above, I think this has led to Mr Oakley over-egging the point somewhat.
'movements on the onerous lease provision in both directions are being included within exceptional items'
bidirectional movements in onerous lease provisions gives management a lot of control over how much profit they want to declare.
I do think that some of the more recent changes in accounting standards have made it harder for investors to understand what is really going on. It is important for investors to understand the extent of any pension risks a company carries, but I defy anyone to be able to sensibly quantify that risk from the published figures. Most people seem to deal with this by either believing that its a very big liability and the company should be avoided or its not a large annual payment and so its no problem. They either look at a very big tail or a very big dog and they can have no idea which is more accurate.
Ditto with onerous leases. Expecting to lose money annually on a ten year lease amounts to ten years losses - which can then disappear from the P&L. An improvement in trading, and its all change again. The problem is that these can be large numbers vis a vis the annual P&L and allow management to hide changes in trading. Wouldn't be such a problem if they only affected the balance sheet but they can have a large impact on P&L because of the impact on annual costs. I think Phil is correct to include these as a problem.
Thanks for a superb and detail response bestace - exactly the kind of discussion which I like to see. I know that I was being a little provocative with the word 'massaging' but to some degree that's a core skill for an FD!
Anyway it's interesting that onerous lease provisions are being adjusted both ways as exceptional items. I suppose the risk is that in the future the company can use their discretion regarding these provisions to improve profits somewhat (assuming that the loss-making bars come good).
On the exclusion of pre-opening costs I'm with Phil on seeing these as just a cost of business for Revolution Bars (LON:RBG). Sure these costs will vary over the years but they're in the game of opening new bars and this is an outgoing that will repeat year after year - so it's hardly exceptional. Similarly the costs of closing bars and redundancies shouldn't be adjusted out either as that's part and parcel of running such a business.
Fundamentally where I really agree with Phil is in feeling that companies should make as few adjustments as possible - especially when their bonus payments are based on the adjusted figure. Here they're being incentivised to make the figures look as good as possible within the restrictions set by their auditors.
Also most investors allow themselves to be guided by the company in looking at the reported numbers and, as we know, this can be dangerous. For sure we're all at liberty to dig into the figures and really try to understand them but I only do that for a minority of my investments - the hazard of being a part-time investor.
Damian
This is an excellent spot re Revolution Bars (LON:RBG) - thank you for sharing it. Phil isn't quite correct because as bestace points out, the movement on the onerous lease provision is disclosed as an exceptional item whether it is a credit or a debit
Thanks. The thing that I like about Phil's analysis is the way in which he guides us through his thinking with clear examples. I'd recommend checking out some of his other articles which are written in a similar style.
All the analysis on Revolution Bars (LON:RBG) by me, Phil, and everyone else, is just background noise.
All that matters, is a competitor (Stonegate) bid 203p cash for it recently. That means it's worth at least 30% more than 203p. Otherwise Stonegate would not have bid.
Nothing else matters. This is free money, in my view - just a question of when. I'm up to 300k shares now, and am buying more at 150p. DYOR obviously.
P.
For the record, I apologise for the use of a rude word yesterday. While I think it was a wholly accurate summary of the departed poster, based on content and style of the post, it was inappropriate in the context of this forum.
I was somewhat unhappy at the time because, having reiterated Paul's request for a bit of background on why people want particular shares covered, we had two posts in quick succession just giving Epics, then the "who do you think you are?" message. Instead of getting wound up by it, I should just have laughed at the statement "99% of the people are not or do not hold financial qualifications. "
Won't happen again.
Jon
Welcome back :)
What rude word - at best it was rude punctuation!
I agreed with your sentiments
I think I've made this point about RBG before. It is no easy task to improve the food offering. I expect that the vast majority of the products they offer are ready to reheat foods from the likes of Brake Bros. The only way of dramatically improving this offer is by having chef's capable of preparing and cooking from fresh which neither the culture or equipment is likely to support and would require an increase in menu prices.
This also means increasing the kitchen labour overhead when with all the casual dining chains discounting like crazy there is very little room to manouvre on prices. The other point is that these premises are built to be late night bars first and foremost and being able to convert them to premises which also appeal for all day dining is a very difficult trick to pull off. Weatherspoons do it but only by dint of going for the cheap and cheerful which does not suit the RBG brand.
I would not be expecting any dramatic improvements in margin to come from increased food sales. The money is made from the premium booze.
At the time of the Stonegate bid last year, it was rumoured that they were interested in Revolution Bars (LON:RBG) at an EV/EBITDA of about 5 as this was significantly lower than their internal ration of 9.
Just prior to the bid the Revolution Bars (LON:RBG) ratio at the then price of 125p was 4.5. At the offer price of 203p the ratio was around 7.5 but the expectation was that through stripping out some of the c.£3.6m of Head Office costs and getting procurement synergies this would be reduced to the target ratio of 5.
If Stonegate were to work on a similar premium of 62% this would imply an EV of around £125m requiring an EBITDA after stripping out HO costs and including procurement synergies of £23m to £25m. To get to a projected EBITDA for FY18 of £23m you need to regard all the exceptional costs as exceptional. But assuming this is the case, I would say that the EV/EBITDA ratio still looks favourable for Stonegate.
I have no position but can see why Stonegate could still be interested at a similar premium to their previous approach implying a price closer to the 240p that would likely need to offer to holders to secure acceptance.
The question is whether they feel that both the market and £RBG's prospects have worsened since July 2017. In that case they might want an even greater safety margin than a difference of 4 between their internal EV/EBITDA ratio and the projected ratio of Revolution Bars (LON:RBG) after stripping out costs.
I think that RBG is too good a fit and the commercial justification in a difficult market is too compelling for Stonegate not to have another go at some point. But I think they will conclude that they have plenty of time to see how things pan out.
Thanks mammyoko, on the technical side the trade range 144-172 is still showing some healthy sell vols which is keeping the price subdued. Once the fickle holders are moped up, a break on good volume north of 172 would be positive. However the focus on more food traffic may be admirable but they are rowing against the current eat out headwind.
Exactly zoolook (as regards VLE).
The main subsidiary, Impetus, made £1.83m core PBT in H2 alone (before intra-group interest and charges) with a full 6 month contribution from the large new contract announced in spring 2017.
So Impetus looks as if it can make say a core £4m PBT this year, even without any contribution from the new "opportunities" quoted in today's statement. Call that £3.2m PAT, or £2.7m for VLE's 83%. Then give this a not too demanding multiple of say 13, and that covers the entire current VLE £35.77m m/cap.
Then add on £18.4m of cash - which represents 502p per share - plus £2.3m of freehold property - 62p per share - plus the value of Shire Foods as a nicely profitable business producing £0.83m core PBT, plus something for Sira Defence, and draw your own conclusions as to the potential upside.
Some my recall Paul drawing attention to an extraordinary video interview of Clem Chambers, CEO and founder of Online Blockchain (LON:OBC), a couple of months back. Well, Mr Chambers is offering free pizza to anyone going along to Firezza Pizza in Dean Street W1D 3RY on Wednesday next week to hear his “insights into the blockchain/crypto world”. Someone might be interested to go along and report back. Here’s the link
https://www.eventbrite.co.uk/e...
The SP of On-Line PLC (renamed Online Blockchain in December) shot up in 2½ months from 14p to peak at 152p on 09 January . With extraordinary timing, Mr Chambers raised £1m the next day, but alas, the SP has since steadily dwindled and last night closed 50% off at 72p. Hence, I suppose, an offer of free pizza.
i might go to this, if just for free pizza and free laughs!
I just registered - for the pizza!
Would need to learn a lot about blockchain and cryptos in a short space to really benefit from the event.
I get the feeling that this event might be similar to how pyramid schemes host - uplifting music and promise of amazing lifestyle if only you are brave enough to participate!
Interestingly, the boutique investor relations company Cassi Peia Services (which I personally have never heard of), is also hosting an event for Seeing Machines on 16th March (not one I consider to be a high quality investment).
The founder "Some call her the ‘Lara Croft’ of the small capital investment community." has worked at Proactive Investors and Sound Energy (again, not the best quality imho)
Perhaps others know Lara Croft and her credentials, so maybe the sarcastic tone is utterly unwarranted.
I had a look, it doesn't actually say 'free pizza' so I didn't sign up. Clem will have you paying for it ;)
In response to andrea341
Re Volvere the NAV doesnt reflect the value of their subsidiaries (They are not an investment company). If you look at the performance of the subsidiaries and attribute a sensible value (as opposed to an accounting book value) and add that to their cash pile then the sum of parts is well in excess of the market cap.
Re Revolution Bars (LON:RBG) - leaving aside for the moment whether there is a bid premium in the price and concluding that we can't rely on the P&L, the question arises as to whether this is a self-funding roll-out based on the cashflow statement.
At first glance, it would appear that it is as £6.6m of capex is covered by £7.1m of cashflow from operating activities. However, within that £7.1m are two favourable working capital movements. Debtor days have been squeezed from 19.7 days at the end of H1 2017 to 18.0 days at the end of H1 2018. Creditor days have remained constant at around 58 days. The question is whether these ratios are likely to continue to show improvement in future. I would suggest that neither debtor nor creditor days can be sweated much harder. If you add back in the £5.5m of provisions you get to an adjusted operating cashflow of £4.7m - some £2m short of capex. This does, of course, include the £2.2m of cash sent to money heaven in respect of professional fees. So, if you believe that this was all related to M&A activity, then the capex was funded by operating cashflow excluding working capital movements.
Turning back to the issue of whether the price includes a bid premium, I would say that it probably does to the extent that the instis who bought in at 200p and higher (e.g. BoA) remain as holders. Clearly, if they decided to move on or if Deltic sell the 1.5m of shares that they can ill-afford to continue to hold, the share price would take a knock.
I think this is finely balanced for the moment. Would the instis accept a renewed bid from Stonegate at 225p? I suspect they might be happy to a second time round as they appear to be the only credible bidder. I would think that management would certainly recommend it having previously been happy to sell at 203p.
The trouble is that this has, I think, become a riskier hold. In the absence of a renewed bid it has become harder to value as we don't know if the onerous lease provision is kitchen-sinking or whether it will actually be required. Other liabilities (mainly provisions for onerous leases) now comprise 28% of the net assets excluding liabilities.
If I was Stonegate I would wait to see if the price dribbles down to 125p as they appear to have a clear field and trading and market conditions don't seem likely to push the price higher at the moment. As you say, the factor that could improve trading is developing their food offering but, as many competitors are proving, this is not an easy win.
All of the above assumes rational behaviour on the part of the players and, of course, there may be other factors to consider at Stonegate such as the ease of purchasing growth versus generating it organically. Despite their parting shot that they take a disciplined approach I agree with you that they will be back at some point.
Let's hope that if another bid does appear Revolution Bars (LON:RBG) chooses some cheaper professional advisers.
I'm also very keen on comments on Microgen (LON:MCGN) please - I am a happy holder, and think they are good value considering the growth being made.
As per my comments on Matylda's "I read the market oh boy" page today, I just don't get the staggering valuation of Volvere (LON:VLE) at all, in particular the ridiculous NAV 52% premium and also what I see as a higher risk tiny collection of holdings (of which only one is looking good at present) compared to Draper Esprit (LON:GROW) which is on a relatively more moderate premium of 37% and, IMHO, has a much more promising collection of investments, including some big names.
Finally, I can't imagine you'll please comment on Lookers (LON:LOOK) ... but you have commented quite a bit on the car dealers sector quite a bit in the recent past; overall, these results look better than some in the sector, such as Cambria Automobiles (LON:CAMB) which doesn't look promising.
Looks like the markets as a whole are on the brink of another fall in light of Mr Tweet's latest fiasco... good grief.
A second request please for Microgen (LON:MCGN) . Shauney2 has summarised the results above. Comparing to the Stock Report this looks like a significant beat vs. market expectations.
Water Intelligence (LON:WATR) announced this morning that it is raising £4.2m (18% of its market cap) through a placing/subscription at 195p, representing a 4% discount to yesterday's closing price.
The funds will be used for the following purposes.
- Acquisition of its Louisville, Kentucky franchisee. This is said to be immediately earnings enhancing.
- To provide firepower for three further acquisitions of franchisees.
- To fund development of new products, particularly to support its insurance channel and through its partnership with Flo Technologies.
- To provide working capital to support the rapid growth being achieved throughout the business.
Corporate acquisition of franchisees has been a major driver of growth in this business over recent years, and I view this as a very positive development.
Ref RBG and accounting issues.
I couldn't disagree more that the accounting issues are irrelevant, accounting tends to be about the culture within an organisation and that of RBG was rotten. Hopefully that is in the past but the fact that the adjustments will flatter the future results means we have to wait and see if that Rotten egg is fixed. It should be hard to present simple clean accounts that don't mislead - lets be honest RBG have been misleading by the bucketful. This is a p/e based business investing wise to me and the profits compared to turnover are so small that its easy to hide the true state of play if one has the will.
This may work out in favour of the nimble in that if the culture is no longer rotten and or future trading is ok and many have walked away for good reason due to the fact that they don't trust the presented figures then there may be a temporary depression in price and this may be a buying opportunity. This scenario does appear to be playing out - i was tempted to buy back in at 150 before the most recent results having luckily cashed in near the top but i am happy to wait and see at present.
With regard to the fact they are debt free would one agree that there are significant liabilities on the balance sheet that are potentially an issue if cashflow is tight. There is 31 mill owed out excluding other liabilities over 12 months and they have only 13 mill of receivables/cash. This should be no biggie if they churn out future profits at expected levels but its by far from a rock solid balance sheet - i guess thats the risk with RBG compared to a similar company that may own some decent freehold and have a proper decent NTAV that supports say 50% of the shareprice when buying.
WANdisco (LON:WAND)
Any thoughts on the preliminary results and new partnership agreement from WANdisco (LON:WAND) :
* revenue growth - 73%
* "Adjusted EBITDA3 loss $0.6 million (2016: $7.5 million loss)" - does this mean anything?
* "The loss after tax for the year increased to $13.5 million (2016: $9.3 million), mostly as a result of two non-cash items: an exceptional finance loss of $4.0 million and an increased share-based payment charge which was partially offset by the significant reduction in EBITDA loss for the year. The exceptional finance loss arose from the retranslation of intercompany balances at 31 December 2017, reflecting the appreciation of Sterling against the US dollar."
* the currency translation loss sounds okay to me - not an ongoing cost
* the share based payments don't look so rosy. "WANdisco plc operates share option plans for qualifying employees of the Group. Options in the plans are settled in equity in the Company and are normally subject to a vesting schedule but not conditional on any performance criteria being achieved". So more than £2m is paid out to directors and employees in share based payments with no performance criteria and while the company is still loss making. I guess this would make sense if salaries were low.
Any thoughts Paul?
Not a request for a comment, but simply noting that the Restaurant (LON:RTN) statement today shows massively improved reporting over the previous management. Their troubles had been extensively discussed in these columns.
Hi xcity,
I did read the Restaurant (LON:RTN) results this morning. My impression is that the figures are not as bad as they could be, but the narrative seems to have been heavily PR'd to create a positive impression, when actually profits are falling, and likely to continue falling.
2017 results;
Current trading - "broadly in line", so slightly below in reality.
Outlook - this is cleverly worded to sound positive, but is actually negative. "Significant price investments" means cutting prices & discounting. So that's bad for profitability, if volumes don't increase faster than prices have fallen. The way I read this, it's a profits warning for H1, with hopes that H2 will be better;
On the positive side;
It's difficult to exaggerate just how bad things are in the casual dining sector, due to big over-capacity & well publicised ongoing cost pressures. So this is probably a sector to avoid altogether, in my view.
I see no reason to close my (small) short position on RTN, based on today's results.
Regards, Paul.
Re Restaurant (LON:RTN)
Thank you Paul.
My comment really reflected a degree of surprise in that the results today were clear and well presented and seemed to give an impression of a sensible and competent management getting to grips with the problem in their company and in the industry. A huge contrast to the shambles I remember with the last lot.
The results themselves are better than I had anticipated. They are explicitly saying that they have cut margins, but also indicating that their target market now have a more positive view of their offering, not that it is simply out-of-date, tired menus cheap. That sounds like a big turnround at F&B. Also quite a clear strategy going forward. No longer spending as much on maintenance refurbishment -that always felt like a tactic of throwing money at a problem without actually improving anything that mattered. I think I have a F&B I could check out; though I'm not sure I'll notice the difference even if I do remember going to one 5 or 6 years ago.
The cash flow and balance sheet was always their fundamental strength, and I now believe that they will able to trade successfully and will still be standing when all the blood and gore in the industry has been swept up. And then margins can improve again. AFAICS, there has been far too much over-optimistic expansion in the industry by chains which don't have the financial strength to deal with a little bad patch, let alone one which concatenates increased competition, lower footfall and increasing costs. Restaurant (LON:RTN) always had the financial strength, but seemed to lack management strength and to have lost customer appeal; now I think it looks better. I think it looks as if they can maintain the dividend, though I daresay they would have preferred it to have been lowered a little last year.
I agree about the PR gloss on the report, but impressed by the content too. I don't yet have a view on it as an investment, but I'm always a sucker for management that seems good and competent, and don't tend to be put off by their circumstances being tough. As you say, the first half is going to be down. These results were much better than the market expected, and, if the idea that unexpectedly good results leads to the share price drifting up is correct, the trend is likely to be up rather than down.
Paul Microgen (LON:MCGN) please. Their Aptitude Software division looks to be doing particularly well. Not much price movement this morning, but they are expensive and on a 52 Week High, so am hoping for some latent PEAD. Ian
Good morning Paul
Another request for Volvere (LON:VLE) please.
On another board, someone posted this analysis a while ago. Since then, there has been the £3.4m share-buyback.
It would be good to get your view on their RNS and the above
cheers,
Francis
Simso has kindly updated his SOTP today on Volvere (LON:VLE)
"2018 SOTP Valuation
Impetus
The 2017 PBT number of £3.4m was £1.9m higher than 2016. We will only get a true split of that growth between "Organic growth" and the large new contract which commenced in April 17. For now, I assume £1.5m is 9 months of New Contract, and £0.4m is Organic Growth. This means we have a profit building block of £0.5m for 2018 as we will have the Contact for a full 12 months in 2018 rather than 9 in 2017. I (hopefully!) prudently assume lower Organic growth of only £0.1m..and we get to the £4m Rivaldo mentions above and derived through a different route. Hopefully scope to do better than that, especially with the news in Dec 17 of the new Partnership with Auditex.
If I deduct the 17% minority, a further 10% for Bruvva's Bonus on any sale, and assume 19% Corporation Tax, and then apply a Market Average 14 times multiple to post tax earnings, then Impetus would be worth £34m.
The Multiple of 14 times is debatable, and a bear might argue it as too high because its in the Automotive Industry, but a Bull would point the exceptional growth, and contractual earnings giving certainty. I think 14* is a fair compromise.
Shire
I agree the point that second half underlying of £1.07m (vs £1.02m in 2H 2016) gives validation to the argument that some price increases have now been put through to mitigate cost increases caused by Currency/Brexit etc. On that basis I think it legitimate to assume the FY 2016 of £1.15m is the least we should hope for in 2018. A forecast of £1.15m is basically a roll forward of second half 17 run rate with no further growth assumed, perhaps too prudently discounting their Statement today that VLE " are investing in Shire so that we have the capability to grow. We expect revenues to increase in 2018 and with that, profitability" Given how careful and prudent the Bruvva's usually are, perhaps upside potential on taht number?
I have also been cautious in the Multiple applied of 5*, having deducted the 20% Minority, 10% Bruvva Bonus and 19% Corp Tax to give a value of £5.3m.
I assume Sira has no value in my SOTP. Having made £30k profit it is perhaps worth £200k or so at most.
I would expect net Cash Generation of c£2m (2017 was £1.7m excl the Buy Back), to finish 2018 with £20.4m. Other net Assets of £2.6m is mostly Freehold Property, so will add our 80% share of that in to SOTP Valuation at par.
That gives me a total SOTP of £59.8m. With shares in issue of 3,668k, that gives £16.30 a share."
Be very interesting for Paul's thoughts on volvere Volvere (LON:VLE), given Graham's bullishness on the stock. My largest shareholding by a mile
Hi,
I decided against looking at Volvere (LON:VLE) because time was short today, and also Graham has covered it before. It doesn't look controversial in any way, so doubt I could anything of value to what Graham has previously written.
Regards, Paul.
Good morning Paul
Welcome back. Not sleeping is really tough. I hope you find a good solution soon.
I would be interested in your thoughts (and Graham's - if I remember rightly this is one of his favourite holdings) on Volvere (LON:VLE) . The results look good (already quoted above) and they are well ahead of market expectations on revenue but:
* all the profit increase comes from the automotive consulting business. The other businesses are struggling
* the trading update says "Whilst the decline in new car sales in the UK has affected the scale of some manufacturers programmes, there remain many opportunities for Impetus in what is a very large sector". So definitely a note of caution there (cautious optimism?) for this year
Disclosure - I hold
Microgen (LON:MCGN) )
Preliminary Results. Revenue up 46% to £62.6m 37% excluding the benefit of recent acquisitions. Adjusted Operating Profit up 43% to £13.6m. Adjusted EPS up 39% to 17.1p. Total Dividend 6.25p an increase of 25%. Cash £19.1m.
PER 27 maybe rich but good revenue visibility with strong recurring revenue which should be enhanced by the need for a new accounting standard for insurers IFRS to be implemented by 2021
Distil (LON:DIS) put out an RNS late yesterday (6th). They issued shares to cover their bill to their broker for the last year. I’ve not come across that before. Is it usual? Is this a good sign or a bad sign? Stocko says they are unlikely to go bankrupt so why did they not just pay out the money, does this indicate the broker has super confidence in them?
Share price has been drifting down since autumn of last year (Stockopedia has them as a falling star) and they put out a lackluster update in January but have up ticked quite a bit in the last week.
I have a small holding left after cashing in on gains last August.
ST Ives (LON:SIV): disposal of the marketing print business looks like it has boosted this share. Up 8% today.
Bioquell (LON:BQE) Please Paul, thought they would have made more ground on those results.
My morning smallcap tweet:
Water Intelligence (LON:WATR), Tyman (LON:TYMN), NATURE (LON:NGR), Mysquare (LON:MYSQ), Volvere (LON:VLE), Palace Capital (LON:PCA), WANdisco (LON:WAND), Mirada (LON:MIRA)
Water Intelligence (WATR) placing at 195 (4% discount) for the acquisition of the Louisville, Kentucky franchise and working cap.
Tyman (TYMN) placing by bookbuild to fund the acquisition of Ashland Hardware.
Nature Group (NGR) in advanced discussions with a preferred bidder having reached agreement on indicative terms and pricing on firesale of O&G division to cut debt. Its lender will wait to end of April 2018.
MySQUAR Limited (MYSQ) The Bell of Doom rings as MYSQ turns to death spiral finance of £2.1m ostensibly to fund a potential acquisition or investment into a company that is developing mobile payment services. If it's for an acquisition why do theyneed the cash now?
Volvere (VLE) FY trading. Rev & preax up substatially due to Impetus Automotive. Shire Foods profit down - "we are investing in Shire so that we have the capability to grow. We expect revenues to increase in 2018 and with that, profitability, although this will depend on our ability to contain the effects of higher raw material and labour costs." NAV 656p (end H1 623p). I hold.
Palace Capital (PCA) increased interest rate hedges to 70% of drawn debt. Will inc av cost of debt from 2.9% to 3.4%.
Wandisco (WAND) Fusion will be sold as a standard component on Alibaba Cloud. WANdisco's first OEM agreement in China significantly expanding addressable market.
Mirada (MIRA) takes a secured one-year loan facility from a shareholder for up to £3m at 15%. FIFTEEN PERCENT! "The Directors are confident that as a result of its pipeline of potential new customer contracts and the expected revenues from its recently won contracts now being implemented, the Company's cashflow position will improve and it will be able to satisfy all debts as they fall due."
Trading update for Volvere (LON:VLE) a turnaround specialist today :-
The Group expects to report record revenue of approximately £43.2 million (2016: £33.0 million) and profit before tax of £3.22 million (2016: £1.94 million).
The Group expects to report increased year-end consolidated net assets per share (excluding non-controlling interests) of approximately £6.56 (31 December 2016: £6.17) and Group net assets of approximately £26.0 million (31 December 2016: £26.6 million). Of the Group net assets, cash including marketable securities represented approximately £18.4 million (31 December 2016: £20.1 million), of which marketable securities represented £6.3 million (31 December 2016: £nil million). The level of cash including marketable securities is particularly pleasing given that the Group repurchased £3.46 million of its own shares in the year.
Full year end results on 25th May
Lloyd
Morning Paul, glad to have you back with us. Good luck sorting your sleep hygiene issues out, I used to have insomnia myself and it's so disruptive.
I'm sure we'd love to hear your thoughts on tariffs, Trump, Cohn etc, but I'm also requesting WANdisco this morning, which you briefly held: delivers revenue growth of 73%. up 45% year-on-year to $22.5 million (2016: $15.5 million) Cash overheads contained at $24.5 million (2016: $23.4 million). Still lossmaking: Adjusted EBITDA3 loss $0.6 million (2016: $7.5 million) but probably not for long, as...
No numbers for the deal but there probably doesn't need to be: WANdisco (LON:WAND) - LAUNCHES OEM SALES PARTNERSHIP WITH ALIBABA CLOUD -WANdisco Fusion to be embedded as a standard component in selected Alibaba Cloud solutions, first OEM agreement in China significantly expanding addressable market.
For the uninitiated, Wandisco is a currently-unique solution that enables instantaneous uploading to the cloud through some tech jiggery-pokery.
I hold, but not enough evidently!
Results out for building components supplier Tyman (LON:TYMN) this morning together with an announcement of quite a big acquisition in the US and associated placement of 10% of their shares via an accelerated book build with institutions (presumably leaked as the shares fell 4% yesterday!)
https://www.investegate.co.uk/tyman-plc/rns/final-results/201803070700079091G/
https://www.investegate.co.uk/tyman-plc--tymn-/rns/acquisition-of-ashland-hardware/201803070701019094G/
Decent enough results. Possible concern they’re buying at the top of the market cycle and expanding into the competitive US market further stretching the balance sheet.
Also an update from Volvere (LON:VLE) , one of Graham’s holdings. Record revenues and profitability reported (though not sure what market expectations were).
https://www.investegate.co.uk/volvere-plc--vle-/rns/trading-update-and-notice-of-final-results/201803070700069074G/
Gus.