Small Cap Value Report (Tue 6 Mar 2018) - LUCE, BEG, LOOP, HEAD

Hi, it's Paul here.
Apologies for the delay. Somewhat later than usual, here is Tuesday's SCVR.
Let's start with the biggest percentage faller of the day, which must be a profit warning.
Luceco (LON:LUCE)
Share price: 50p (down 35.7% today, at market close)
No. shares: 160.8m
Market cap: £80.4m
Trading update (profit warning)
Luceco, the manufacturer and distributor of high quality and innovative LED lighting products, wiring accessories and portable power products, is today issuing the following update.
I am not familiar with this company. Thankfully, Graham wrote about it 3 times last year, so I'll get up to speed first by reading his 3 articles. I'll summarise them below;
Oct 2016 - floated by Numis on the full UK stock market, at 130p per share. Selling shareholders cashed out £67.1m-worth of existing shares (before costs). The link to the left is to its prospectus. A further £22m (net of costs) was raised to reduce existing borrowings.
3 Apr 2017 - very strong results for 2016 were announced. Adjusted operating profit up 53% to £17.6m. Strong outlook statement too.
11 Sep 2017 - strong interim results, with operating profit up 25% to £9.0m. Full year outlook in line with market expectations. Net debt £26m.
15 Dec 2017 - this is when things started going wrong - a profit warning. Gross margin weakness is blamed, and the financial controller resigned over the apparent error of not spotting it sooner. Forex & commodity prices are the underlying causes. Profit guidance for 2017 reduced by 21% to £13.2m (profit after tax). CEO sold 2m shares a few weeks before this profit warning!
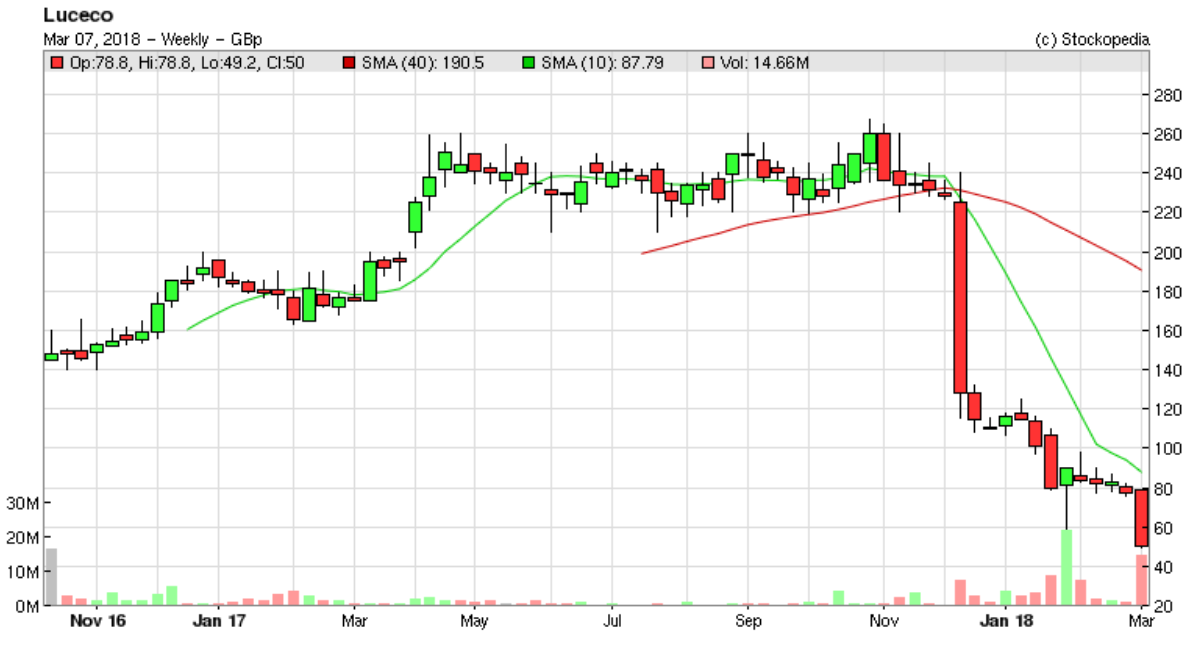
It's interesting to look at the chart, and see that the best strategy in this case, would have been to sell immediately on the first profit warning. We've discussed that a lot in the past, and I am having a quick re-read (highly recommended) of Stockopedia's brilliant 2016 study of 245 small cap profit warnings.
The overwhelming conclusion of this data-driven study, was that selling immediately on a profit warning, has been statistically the right thing to do, on average. This chart says it all;
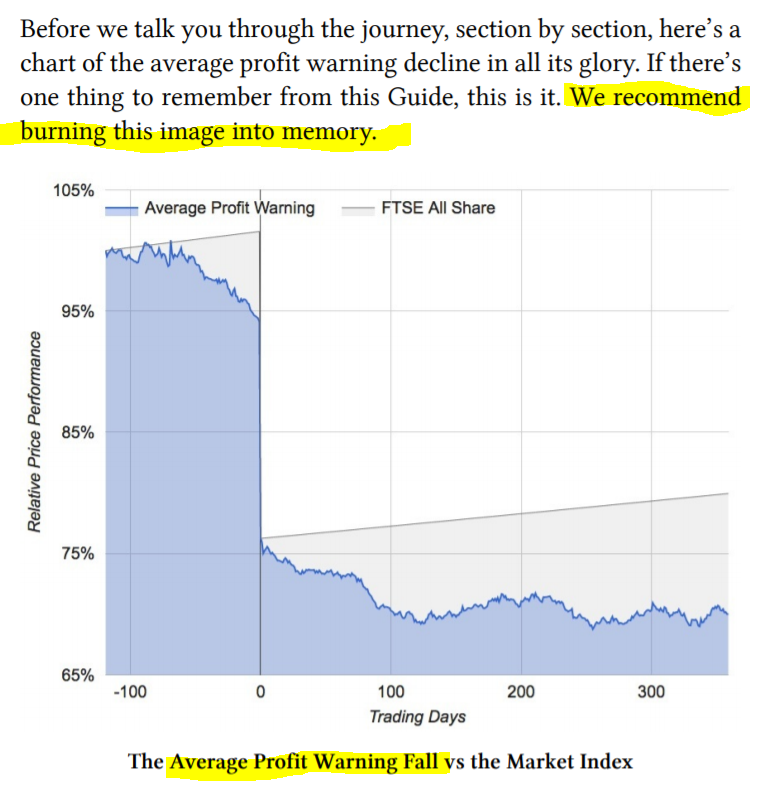
Emotionally, I think we probably all find it quite difficult to embrace this strategy of selling on a profit warning. However, I am warming to the idea. Let's not forget though, that there are some cases, where profit warnings lead to irrational & excessive selling, creating bargains. So every case is unique.
A good recent example of a profit warning creating a bargain opportunity was the crash in share price of Revolution Bars (LON:RBG) (in which I hold a long position) in May 2017. This created a lovely buying opportunity where investors were able to double our money in the next 4 months, when Stonegate launched a 203p cash takeover bid for the company. Shareholders rejected the bid, but the opportunity was there to cash out, in the market, if people wanted to).
The other to consider is liquidity. You might want to sell after a profit warning, but if you hold a large position in an illiquid stock, it can be impossible to get out. So there's the risk that large shareholders might end up drip-feeding shares into the market over a sustained period, after a profit warning. So it's a problematic area, for sure. Sometimes, I find that whatever you do, re a profit warning, the opposite would have been the better course of action!
Anyway, getting back to the latest RNS, what does this say?
Profit warning 6 Mar 2018 - it's a warning on calendar 2018 profits now. I do like the way this company gives us precise guidance in its trading updates. In a MiFID II world, this is very helpful, as otherwise private investors would be left in the dark, due to lack of access to research notes;
Trading conditions since the Group's trading update on 15 December 2017 have remained difficult in our UK consumer facing business, which is approximately 25% of Group revenue, as a result of well publicised weak consumer confidence and a weaker dollar.
These factors have caused us to revise our estimates for the outturn for the year to December 2018.
We now anticipate reporting 2018 profit after tax in the range of 12.0-14.5m, on revenue growth on 2017 of 5-10% at current exchange rates.
I'm not sure why Luceco gives guidance on profit after tax, when profit before tax is the more usual benchmark. Anyway, the fact that the company is using best practice, of providing the market with a clear range of profit outcomes, is fantastic. How long will it take, before so many other companies catch up, and report to us in a similarly helpful style? We need this information direct from companies now, as MiFID II has restricted our access to broker research so badly.
2017 results - the full numbers have not yet been published. Guidance is revised down again. It's great when companies give profit guidance, providing the results fall within the guided range. Unfortunately, the 2017 results are being guided down again today. As mentioned above, on 15 Dec 2017 the company guided to PAT of £13.2m. This has now come down again, to £11.0m. The explanation today is as follows;
The shortfall relates primarily to continued margin pressure and the treatment of certain costs which had been earmarked for capitalisation but are now being taken through the profit and loss account. Revenue is expected to be 168.6m and net debt at 31 December 2017 was 36.9m.
This is seemingly due to the new CFO taking a more prudent view. It reinforces my feeling that the finance function at this company seems to have been very poor in the past. Or, that's perhaps being used as an excuse? It makes me wonder if there are any more skeletons in the cupboard, yet to be revealed?
Other points in today's update;
- UK retailers have de-stocked, after a weaker than expected Christmas
- "Continued strong growth among higher margin trade, projects and international customers"
- "Our previously outlined improvement actions remain on track to return margins to long term expectations during H2 2018"
Balance sheet - I'm a bit concerned that the net debt is reported at having risen to £36.9m at 31 Dec 2017. That's getting close to, or even into dangerous territory in my view. This seems to be due to a debt-funded acquisition, announced here on 18 Sep 2017 of Kingfisher Lighting, for £9.75m.
Aside from its bank debt, the rest of the balance sheet looks OK.
Bank facilities - this is the main issue for further research. Note 11 in the last interim results discloses that most (£20.4m) of the bank debt relates to invoice discounting arrangements. The receivables book was £29.3m at the time. So I imagine the bank is probably reasonably comfortable with borrowings which are supported by receivables, as there shouldn't be any issue with the bank getting its money back, in the worst case scenario.
I've done a search (CTRL+F) on the 2016 Annual Report, on the word "covenant". It's mentioned 8 times, including these bits;
The Group has committed borrowing facilities in place in the UK comprising a £12m revolving credit facility (“RCF”), which was drawn down in full at the year end, and a maximum £30m invoice discounting facility with HSBC.
Bear in mind that this is rather historic now, so might have since changed.
This excerpt below suggests that the company has a net debt: EBITDA bank covenant, which is normal;
Net debt at 31 December 2016 stood at £29.4m, (2015: £46.1m), representing 1.4 x 2016 adjusted EBITDA and the Group continues to enjoy considerable headroom against its covenant requirements.
Given that net debt has now risen considerably, to £36.9m, and EBITDA will have fallen, then I'm not sure the group will still have "considerable headroom"? This is the key issue, where we need more information (as the company does not state in its Annual Report what the bank covenants actually are).
It's not necessarily a problem, but I'm wary that it might be a problem. The smallish divis might need to be cancelled in future, to focus on reducing debt. So I would work on the basis that divis may not necessarily continue.
Cashflow statement - the business looks nicely cash generative. Note that it capitalised £1.2m of internal development costs in H1 2017.
Broker forecasts - I can't find any updates, unfortunately. However, since the company has very helpfully provided us with profit after tax (PAT) estimates, then it's very simple to work out EPS, by dividing the PAT guidance by 160.8m shares in issue. This arrives at;
2017 latest guidance of £11.0m PAT, divided by 160.8m shares = 6.8p EPS
2018 latest guidance of £12.0 - 14.5m PAT, divided by 160.8m shares = 7.5p to 9.0p.
Does the 2018 guidance make sense, or might there be further slippage on these forecasts as the year goes on? Who knows, but given the recent track record, I think it makes sense to treat the company's forecasts with great caution.
Personally, I think I'd be comfortable using a lower range, of maybe 5-7p EPS for 2018, to value this share. Therefore at 50p, it would be on a PER of between 7.1 and 10.0 . Given that net debt of £36.9m is quite considerable, at 46% of the market cap, then the cash neutral PER would be quite a lot higher, and not looking a particular bargain.
My opinion - this looks a can of worms in some ways - e.g. repeated lowering of guidance, accounting problems, bank debt which could now be tipping into problem territory.
On the other hand, even after the latest downgrades to forecasts, this remains a nicely profitable and cash generative business. I'm just worried if anything else might come out of the woodwork?
Looking at the divisional performance, most of the group profits actually come from its wiring accessories division, BG Electrical. The products don't strike me as being high tech, or particularly special. So it's not clear to me what competitive moat the company has? Maybe its high profit margins could be vulnerable to erosion from competitors also sourcing similar products from China, and under-cutting Luceco on price?
Another question is whether the company's owners possibly floated the company at a high valuation, knowing (or maybe suspecting?) that its growth was not sustainable? That question is bound to be raised when strong growth at flotation time turns into a series of profit warnings and accounting problems.
Overall, I think I've talked myself out of wanting to have a punt on this. I shall read its next set of results with interest though, so it's going on the watch list. I think some comfort on the banking situation is necessary, in particular on how much headroom the company now has on its bank covenants?
With the share price depressed now, that makes it harder to raise fresh equity funding, if needed. Management credibility is also bound to be questioned, after the very poor sequence of events in recent months.
Begbies Traynor (LON:BEG)
Share price: 75p (up 2.9% today, at market close)
No. shares: 138.1m
Market cap: £103.6m
(at the time of writing, I hold a long position in this share)
Begbies Traynor Group plc (the "Group"), thebusiness recovery, financial advisory and property services consultancy, today issues a trading update for its third quarter ended 31 January 2018.
Everything seems to be going to plan;
The Group has traded in line with our expectations in the period, with revenue and profit growth for the year to date, reflecting improved year-on-year performance in business recovery and advisory services.
We remain confident that results will meet our expectations for the year as a whole.
It's interesting to note that corporate insolvencies are still historically low, despite a 9% increase in 2017. This is the continued influence of ultra-low interest rates, which has incentivised banks to hold back on forcing zombie companies into administration. How will it all end? Nobody knows for sure, but it seems obvious that with interest rates likely to rise gradually, then insolvencies will probably rise. We're also seeing over-capacity, and financial problems in some sectors, such as hospitality, and retail.
Acquisition - a small, earnings enhancing acquisition has also been announced today. It's a corporate finance firm called Springboard.
My opinion - I remain a holder of BEG, and see it as something counter-cyclical, which helps balance my other portfolio positions a little, given that almost all other holdings of mine would benefit from an improving UK economy. Begbies benefits from corporate insolvencies, so it works the other way.
On a PER basis, Begbies looks rather expensive now. However, when its workload increases, then there's considerable operational gearing. I think the market is pricing in future increased profit margins, hence why the PER looks high at the moment. For this reason, and the divi yield still being pretty good, at 3.3%, I intend to continue holding this share for the foreseeable future.
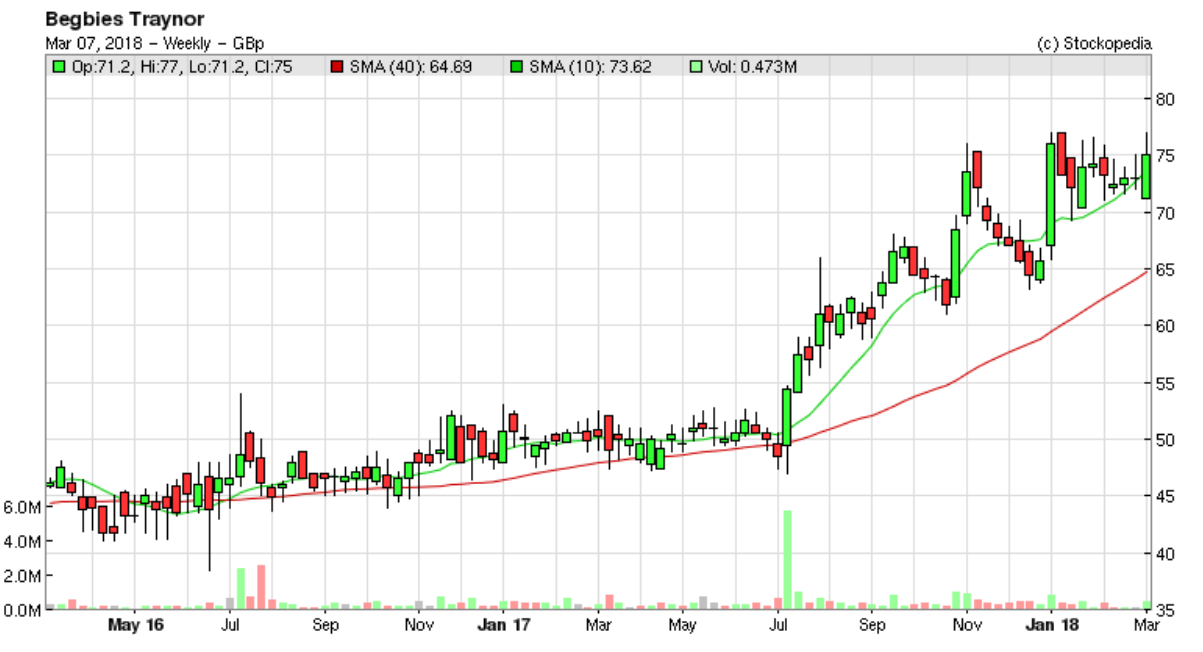
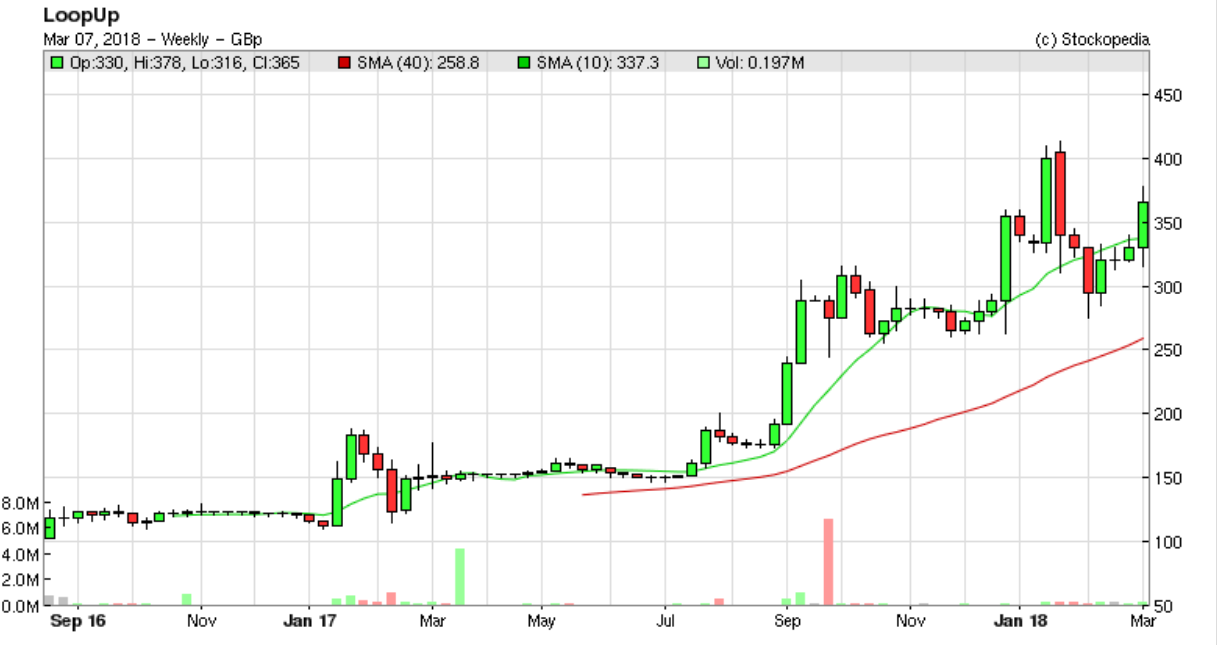
It's interesting to see that the chart is still looking bullish, with none of the profit-taking that has been experienced in many other small caps in the last few months;
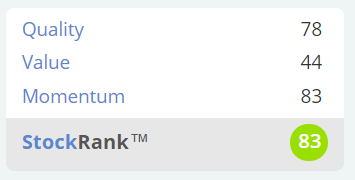
The Stockopedia scores look pretty good at the moment too;
LoopUp (LON:LOOP)
Share price: 365p (up 9% today, at market close)
No. shares: 42.2m
Market cap: £154.0m
LoopUp Group plc (AIM: LOOP), the premium remote meetings company, today announces its unaudited preliminary results for the year ended 31 December 2017.
I've reported on this company several times before. I've tried out the product (which is good), and met management at their HQ (also all good). So lots of positives.
You can read the results announcement if you want all the detail. My take on it is;
- Revenue growth to £17.5m of 36% is clearly excellent.
- High gross margin (76.7%), recurring revenue product, also very good.
- Operating profit is only £0.7m (up from a -£0.3m loss, on a comparable basis, which excludes some other revenue that was winding down). So how on earth can a market cap of £154m be justified?
The answer is that the market is anticipating strong continued growth, and profits soaring due to operational gearing. My problem with that, is that the operational gearing with this type of company often doesn't produce anything like the expected increase in profits - because management usually reinvest profits in increased overheads. There's nothing necessarily wrong with that - in fact, if you have a big market opportunity, then it makes sense to put short-term profits to one side, and "go for it" in terms of growth. The trouble is though, that makes valuation of the shares very difficult, almost impossible really.
Note that LoopUp receives a substantial tax benefit from its R&D activity, which more than doubles operating profit, and results in profit after tax of £2.0m for 2017. The company would obviously be very vulnerable to any negative changes in Government policy over R&D tax credits. So shareholders here should regularly google on that issue, to keep abreast of any potential risks.
Cashflow statement - a quick look at the cashflow statement reinforces just how ridiculous EBITDA is for software companies. In this case, EBITDA of £3.46m compares with £3.76m of capitalised development spend in the year. So on a cash basis, arguably the business is still actually loss-making.
Balance sheet - absolutely fine, no issues here. I don't think the company will need to raise any more cash, so shareholders should be pretty secure from dilution.
My opinion - it's a smashing company, with an excellent niche product. You need to properly research the product, and its specific features, to understand why customers like it. I did that a while ago, and was very impressed. Never mind what I think, the strong organic growth from customers tells us that the product is good, and in demand. What the long-term potential for the product is, who knows? Something better could come along & wipe it out, longer term.
Strong growth in the USA is interesting, and that region is now 51% of revenue. So that could be another reason why investors are prepared to chase the valuation up to such a high level?
Overall, I can't get my head around the market cap being so high. That could be an emotional response to the fact that I panic-sold my decent-sized position here when Amazon launched a competing product. Since then, the share price here has gone through the roof. So I threw away a big potential gain. I can't bring myself to revisit it at this level now, but good luck to the smart people who continued to hold this stock!
I see that the company has also announced that it is appointing Numis alongside Panmures, as joint corporate broker. Could there be a fundraising/acquisition on the cards, I wonder? Also, I have a hunch that LoopUp itself could become an acquisition target for a larger US tech group, who knows?
Headlam (LON:HEAD)
Share price: 476p (down 10.0p today, at market close)
No. shares: 84.85m
Market cap: £403.9m
Headlam Group plc (LSE: HEAD), Europe's largest distributor of floorcoverings, is pleased to announce its final results for the year ended 31 December 2017.
I was a bit surprised at how many readers asked me to look at this company. My initial skim of the numbers, at 7am, was that they looked resilient. So I wonder why the share price fell 10%?
Thank you to the reader who flagged up this link to the company's results presentation. If there's time, I like to read such presentation slides, as they often contain useful additional information. Although care is needed, as such presentation slides will always be painting the most rosy picture possible.
Thinking about its business model, I don't normally like investing in distributors, because there seems to be a long-term trend to cut out the middlemen, using the internet. However, in the case of floorcoverings, which are very bulky, and come in thousands of options, then it's easier to see why a distributor's business model makes sense. As the company presentation says;
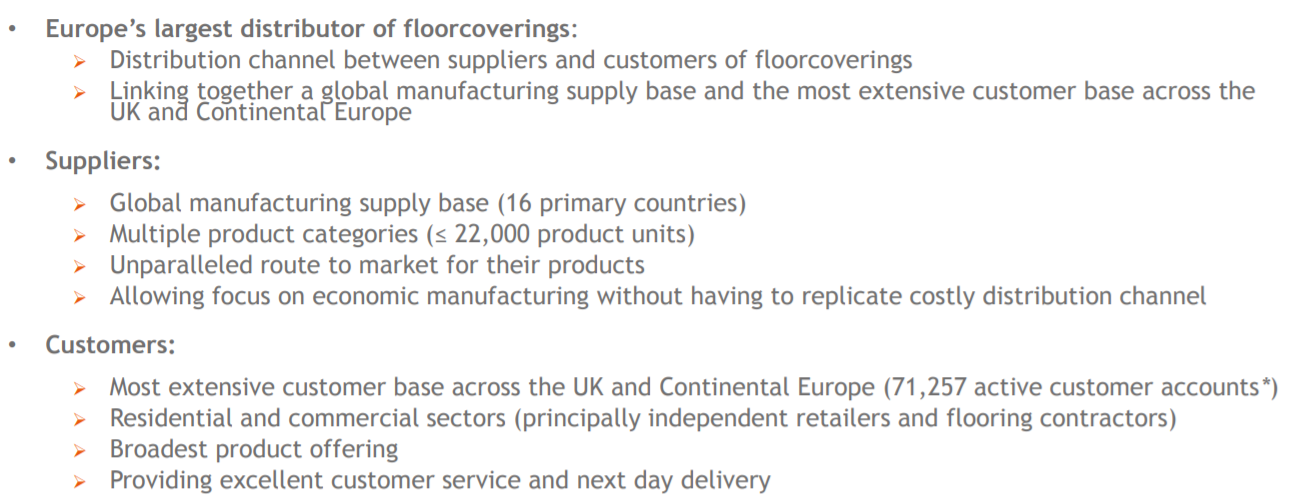
The average customer order value is very small, at only £133. So it seems that independent retailers are using HEAD as their warehouse, and drawing off small orders when required by their own end customers. Price points are low to middle. These factors make me comfortable that this business should be resilient in a downturn, as it's generally not big ticket stuff, but more modest updating of houses, one room at a time, by the end customer.
The financial highlights look resilient, if not madly exciting;
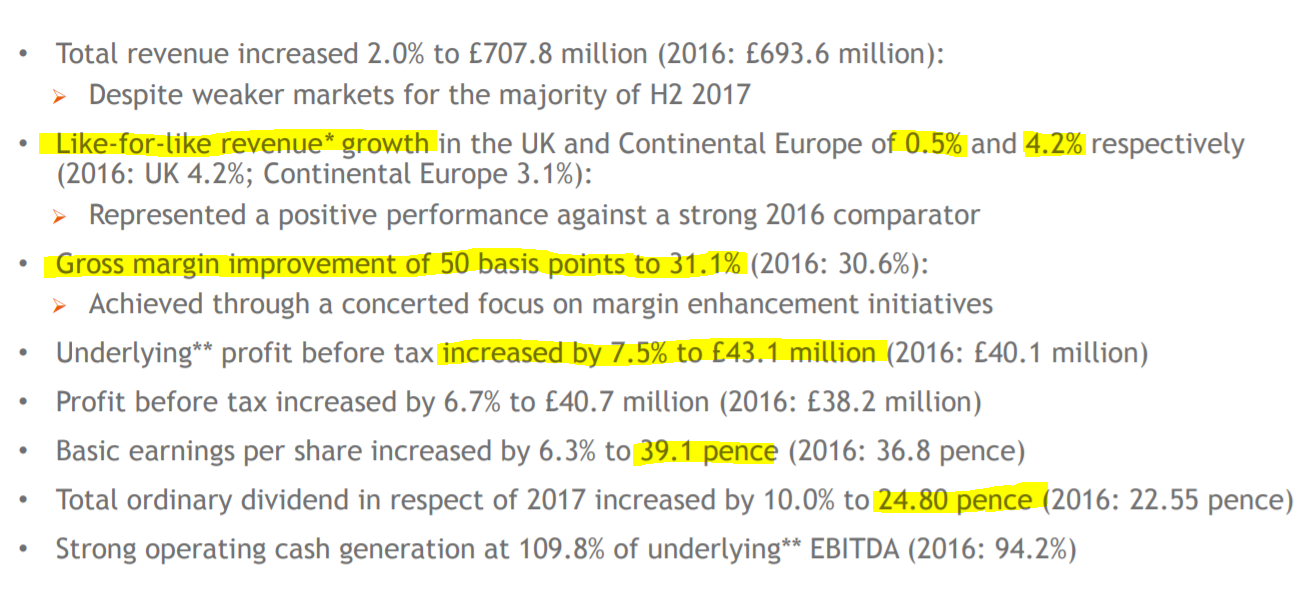
I'm starting to form the impression that this looks a pretty decent business. Gross margin of 31.1% isn't bad for a distributor, and it's risen slightly.
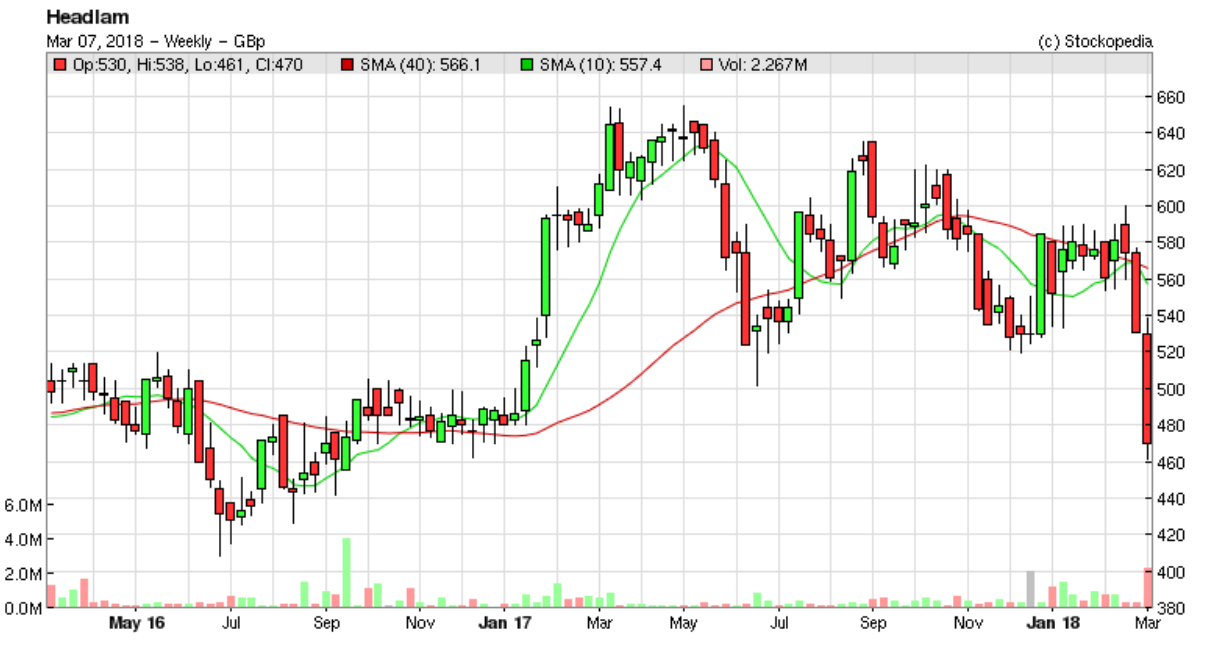
Looking at valuation, the share price has fallen slightly to 470p at the time of writing, so that's a (now historic) PER of 12.0 - which looks about right to me, for a basic business model such as a distributor. It depends on the level of net debt though, so I'll look at that next.
I've just noticed that the company reports a higher EPS of 41.7p, after some underlying adjustments. Using this adjusted figure, PER drops to 11.3.
Dividends look to be the main appeal of owning this share, with a lovely yield of 5.3%, based on the 10% increase to 24.8p divis for 2017 mentioned by the company above.
There's been a decent progression in divis every year from 2012, when the payout was 14.9p. I like shares where the divi can be relied upon to increase each year - providing the balance sheet is strong enough to protect the payouts in a downturn.
Note that the company also paid special divis in 2016 & 2017, but had decided against one in 2018, citing capex on a new distribution centre in Ipswich, and acquisitions.
Balance sheet - note that there is a pension deficit, which has dropped from £23.0m a year ago, to £12.7m at 31 Dec 2017. The cashflow statement shows that £2.16m "pension contributions" in 2017, so this looks to be a bit of a drain on cashflow, but not at a material level, given that cashflow generated from operations was £54.5m. If considering a purchase of this share, I would check the last Annual Report notes on the pension schemes, just to be sure that it's not an "iceberg" type situation.
Looking at my usual balance sheet tests, here are the numbers;
NAV: £218.6m - which looks strong, given that intangibles are only £44.7m
NTAV: £173.9m - this looks very good, given the size of business, and that it has historically been acquisitive, bolting on other similar companies (a process which can often hollow-out a balance sheet, but not in this case)
Current ratio - this measures the working capital position. The result here is 1.51, which is strong, in my view. There's net cash of £41.8m within current assets.
Long-term creditors are relatively modest, at £30.8m, which includes the bulks of the pension deficit, and a bit of additional bank debt, of £6.5m, plus a few other bits & bobs.
Total net cash is £35.3m - which looks a very healthy position. I'm impressed! It's rather surprising that the strong balance sheet, with net cash, is not mentioned in the highlights section at the start of the RNS - maybe something for Buchanan (the PR firm) to think about when the next results come out?!
Does it own any freehold property? The answer seems to be yes, as the word "freehold" appears 3 times in the 2016 Annual Report. However, note 10 shows "Land and buildings" as having a NBV of £93.2m as at 31 Dec 2016. It's therefore not clear whether this is freehold, long leasehold, or short leasehold, or a mixture of the 3. It would be good to find out what the value of the group's freehold properties are. Do any readers have any info on this?
Overall, I'm pleasantly surprised by this balance sheet - it's strong. Hence divis, plus acquisitions can probably be funded without any dilution to shareholders.
Outlook - expectations unchanged;
Full year expectations remain unchanged for 2018, despite continuation of weaker markets
"We are pleased with our performance during 2017, having exhibited further growth against what was qualitatively viewed as an overall flat market, robustness in the face of a weaker second half of the year, and improved profitability as a consequence of our focus on efficiency initiatives.
The acquisitions of Domus and Dersimo illustrate that we have ample opportunities to grow and broaden our overall leading position in the industry while continuing to invest in the business to support organic growth. I personally wish to thank all our people for their contribution to the 2017 result, and look forward to delivering further improvements in 2018."
I've no idea why that text turned blue, but it's rather nice.
Bear in mind that the bulk of HEAD's business is in the UK. So the uncertain UK economic outlook, Brexit/Corbyn worries, etc, are bound to weigh on the share price here.
My opinion - I didn't expect to like this share, but have to say that my impression has gradually become more positive as I dug into the numbers. Let's summarise;
Positives
- Resilient trading, despite tough markets
- Lovely dividend yield - looks sustainable, plus possible future special divis (not in 2018 though)
- Strong balance sheet
- Acquisition opportunities make obvious sense - bolting on more business and improving its margins through group buying power
- StockRank of 88, although the style is "Neutral"
Negatives
- Headlam is a predominantly UK business, that is finding market conditions tough & consumer confidence not great at the moment
- Investor perception might be that this is a boring company, with limited organic growth potential, so what catalyst is there to trigger a re-rating?
- Chart not looking terribly healthy at the moment - so arguably an opportunity cost of holding this stock (which has overall just gone sideways over several years, in a roaring bull market
- One broker has reduced its 2018 & 2019 profit forecasts by about 3%, given the soft start to 2018. I do wonder if further reductions in forecasts might occur as 2018 progresses?
Overall, I'm probably more sanguine about the UK economy than most commentators, so I'm prepared to look at consumer-related stocks. My feeling is that inflation is likely to gradually reduce, and wages are rising. So we could perhaps see confidence improve later this year? Maybe?
As for Headlam, I like it. However, I'm not entirely convinced that I should rush out and buy shares in it now, but it's certainly going on to my watch list. Maybe the company should step up its acquisition programme? It worked rather well for Victoria (LON:VCP) after all - although that is a group of manufacturing companies, rather than distributors. I wonder if HEAD could acquire some manufacturers too, to vertically integrate (is that the right buzz phrase?!)
Apologies again that this report took longer than usual to gestate, but I got there in the end.
Best wishes, Paul.
P.S. If people leave a thumbs down, because a report is late, do you think that makes me more or less likely to want to finish it off? Have a think about that perhaps. I'm not a machine. Sometimes I can write well, other times nothing happens, so I appreciate it when most people cut me a bit of slack on off-days.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

85 comments
Jonathan Ruffer is an astute investor, so the purchase of 5% of Headlam (LON:HEAD) is a positive endorsement of the Company as a long term investment.
Hi Jonno, Ruffer did already have a holding of 4.58% of Headlam (LON:HEAD) according to their website so this latest purchase is a "top up" though still a positive endorsement.
A quick glance at Headlam, a distributor of floor coverings, suggests a pretty good company - a feeling reinforced by the release that Ruffer has just bought 5%. Low margins, I suppose as one would expect with a middleman, but good RoCE and RoE and low valuations. I think I would just like to get to the bottom of the demand profile from the 'independent retailers and flooring contractors' before I made any commitment, though.
For the record, if you see a presentation by the boss of Yu I defy you not to be swept up in his enthusiasm. He is just fabulous. Just a shame one didn't spot it or rather meet him much earlier.
Thanks for the review of Headlam (LON:HEAD) Paul, much appreciated. I agree it is fairly resilient although not punching the lights out in performance. About a year ago I was deciding whether to invest in Headlam (LON:HEAD) or Victoria (LON:VCP), I went for HEAD due to it's balance sheet, dividend and net cash. With the high P/E, borrowing and no dividend I was put off the great growth story of VCP. As you highlight there is an opportunity cost with HEAD and when I see that VCP has rocketed since I first started following it at £3 I really understand that.
Im sure I'm In a minority but I'd appreciate a look at Share plc (LON:SHRE).
With rising interest rates and increasing market share the results look ok to me:
Revenue and revenue market share reached record highs - helped by the emerging benefits of a major new partnership agreement and strong trading volumes
Revenue up by 28% to £18.7m (2016: £14.6m):
commission income rose by 51% to £10.6m (2016: £7.0m)
fee income grew by 7% to £7.2m (2016: £6.8m)
interest income increased by 14% to £0.9m (2016: £0.8m)
Revenue market share excluding interest (*) reached 12.81% (2016: 9.85%)
Assets under administration increased by 27% to £4.7bn (2016: £3.7bn)
Operating losses reduced by 41% to £0.8m (2016: £1.3m)
Profit before tax was £0.4m (2016: £1.0m) including respective one-off items
Underlying (**) earnings increased to £383,000 (2016: £4,000)
The idea is that if a stock issues a profit warning and drops that triggers automated purchase limit orders which counter the drop for a while.
You might perhaps also expect the opposite effect, stops being hit causing an overreaction. Presumably the dominant effect is going the be the least expected one? If people are wary and set stops bad news will cause a large drop. If people are positive and looking for a buying opportunity the fall may be muted.
Peter
Possibly. It looks like a variation on the disposition effect where people preferentially sell winners and keep losers. Quite how that's implemented is probably not that important as long as the post-announcement drift offers an exploitable anomaly.
I'd imagine it's much more likely in small caps where there's less research and institutional interest, and where private investor attention matters more - but I've never done any research into whether there's evidence for that hypothesis.
timarr
I don't understand why people are getting so hung up about what constitutes a small cap, etc.!
Graham & I just write about the day's most interesting trading updates & results statements, with a main focus on small caps. What constitutes a small cap? I would say it's anything under about £400m market cap, but I'll flex that a bit higher, to say £500m if the company reporting is particularly interesting.
Normally if people request me to look at anything above £500m mkt cap, then I just ignore it.
Also if results look boring (in line with expectations) and there's nothing much to say about it, then I'll usually ignore it. The lower limit for market caps here is usually £10m.
Sectors - I don't cover: resources/oil/gas, property, pharmas/biotech, blue sky/story stocks.
My particular sector focus is retail/hospitality, so I'll sometimes write about larger caps within those particular sectors.
NB. The above are not hard & fast rules. They're just guidelines. We like to keep it flexible, so that if Graham or I think something looks interesting on the day, we'll write something about it.
Let's try to keep things a bit more light-hearted, there have been too many snotty comments here lately, which spoils the fun!
Regards, Paul.
Headlam.
I've some skin in this game.
Bought 2 players in EU.
UK profits down 4%...EU up.....is this a (toxic) combination of BREXIT fear effect plus doom and gloom on UK economy & forecasts?
Regarding Luceco (LON:LUCE) and their BG Electrical brand, 2-3 years ago I bought some universal sockets for my flat in Spain so that guests could use EU, UK and suitable US appliances without adapters. Such sockets are necessarily not covered by the BS testing regime, but it should be quite possible to make something as safe as a typical EU socket and safer than using adapters. On fitting I discovered that plugging in a UK plug was extremely hard and pulling it out destroyed the socket. All of the ones I bought were the same due to a design / manufacturing / quality control fault. I find it impossible to believe they had not had enough returns to realise the problem. Naturally I would never risk buying anything marked BG Electrical.
I notice that the BG Electrical brand is currently sold by Kingfisher (B&Q and Screwfix). I don't really understand their positioning - generally more expensive than LAP for products that are inferior on paper (e.g. single pole vs double pole switches) and only 25% cheaper than MK who are better on paper, look nicer and have some kind of reputation to uphold. Their brass / non white sockets look more differentiated.
Another brand Masterplug have long been an expensive but average quality product mostly sold in DIY shops, but with some reputation for RCD plugs.
Overall, I would say their wiring accessories brands may be overly dependent on a structurally declining and cyclical DIY market plus the fashion for brass etc. sockets.
Just to add, I recently bought some Luceco dimmable LED bulbs, they did dim but made a buzzing noise. Returned them and bought Philips dimmable LED bulbs and they work very well, although more expensive.
I'd originally bought much cheaper LED bulbs that were dimmable, but made a louder noise than Luceco. These worked fine in non-dimming locations though.
The Luceco bulbs weren't cheap and it was disappointing that they didn't perform better.
Hi,
Looking at the reader requests, somewhat belatedly,
Yu (LON:YU.) - a spectacular share price rise. I missed this one completely. I don't understand this sector (provision of utilities), so it's not something I can add any insights on, unfortunately.
OptiBiotix Health (LON:OPTI) - there seems an almost constant stream of updates about contract wins. I'll wait for some hard numbers though, as it's too speculative for me at this stage.
Headlam (LON:HEAD) - this seems to have had the most requests, so I'll take a look at this.
Revolution Bars (LON:RBG) - (I'm long) looks OK to me, so I'll circle back to this at some point. The accounting issues are pretty irrelevant I think - indeed the onerous lease provision will actually boost future reported profits, so could be seen as positive. Roll-out of new branches going well (exceeding initial targets), almost debt-free. Current trading of -2% LFLs is a bit disappointing. Good to see new CEO & COO being focused (by the Chairman) on improving their food offering. This is key, and a big opportunity in my view. They already have big footfall, but if they could fill the bars with diners during the day, then a lot of upside - high margin sales, with little to no additional fixed costs. This share is woefully misunderstood by the stock market - we can buy now at under 150p, when a cash bidder was turned away at 203p quite recently. So the valuation clearly doesn't make sense. I am very confident this is likely to be a big win, but no idea when - patience needed.
LoopUp (LON:LOOP) - good results, but crazily expensive now, in my view.
Paul,
Your commments on Ed's excellent analysis of profit warnings prompts me to ask whether you or Ed have ever analysed profit upgrades in the same way? Should one (statistically) always buy immediately on a profit upgrade?
Hi FREng,
Your commments on Ed's excellent analysis of profit warnings prompts me to ask whether you or Ed have ever analysed profit upgrades in the same way? Should one (statistically) always buy immediately on a profit upgrade?
That's a really good point. I think this idea was briefly discussed at Stocko HQ when I was last there, but possibly didn't get pursued. It's a very good idea though. My hunch is that often when companies put out "exceeding expectations" statements, then the initial rise can be the start of a larger, longer term rise. Mark Minervini calls this "post announcement drift", I think. It's certainly worked very well for me, on stocks like Gear4Music (which I still hold, but in reduced size), for example. The initial c.20-30% rise on a sparkling trading update in late 2016, developed into a c.4-5 bagger move. Which was very lucrative for people who spotted it early.
So yes, let's ask Ed if he would consider doing a study on positive trading updates, to mirror the study already done on profit warnings.
A good suggestion, thanks,
Paul.
So yes, let's ask Ed if he would consider doing a study on positive trading updates, to mirror the study already done on profit warnings.
There's research on this which suggests that companies that aren't closely followed experience post announcement drift as the news is only slowly assimilated. The same effect hasn't been found, as far as I know, with high turnover stocks so it looks like an investor (lack of) attention effect.
There are also over and under-reaction effects which it's suggested are due to limit orders. The idea is that if a stock issues a profit warning and drops that triggers automated purchase limit orders which counter the drop for a while. Or if a company issues a upgrade the full impact of that is temporarily mitigated by automated selling as the price rises.
One reason it's always worth trawling through the outer reaches of each morning's RNS's ...
timarr
Your point about more and less followed stocks sounds very logical. The obvious question that arises is how can we know which stocks are less followed than others? Would you say the only way to estimate this is by looking at market cap and/or average volume or are there better ways?
Turnover looks like the best proxy, although it would be interesting if someone could generate a list of the most discussed stocks on UK boards ...
But generally you wouldn't want this information to be easily available, because that would make it easily exploitable, and the opportunity would be arbitraged away. It's the fact that some effort needs to be expended to dig out the opportunities that makes it potentially valuable.
timarr
I think Paul created a rod for his own back inviting requests every day. The pressure on both him and Graham to constantly produce in-depth analysis to demand must be taking its toll. Maybe it's time to consider reverting to them writing about whatever takes their fancy and not be afraid to keep it short and sweet sometimes rather than toiled over.
Further thoughts on Luceco (LON:LUCE)
When they sold the Ross business in China last year, stock had to be independently revalued at approximately half book.
Profit estimate for full year implies a very small profit in the second half.
Unclear whether the problem is across all their divisions or concentrated in one or two. Important to remember it's only about 25% LED.
I get the feeling that this was rushed out when the new CFO realised the scale of the issues and the figures we have been given are those he has worked out so far
.PS I suspect that I would be sending someone out to China to check very carefully on the stock held there. Maybe they have already done it and it is safe to rely on current numbers.
Just a general comment about statements and responses on this board. I had always, and still do, hold it in high regard - generally speaking! I thought that we could avoid the spats and mindless comments found elsewhere. I am sure that Paul etc can clearly define what companies, sectors, company sizes he covers together with very useful general comments about the economy, macro situations like internationalization of companies justifying valuations which under previous circumstances on a conventional basis would have been outrageous. Boohoo.Com (LON:BOO) comes to mind; another is Craneware (LON:CRW) which is topical today here. All in all I feel richer in knowledge and less so in judgement - my fault - for being a receiver from Paul and Co and a sharer of comments by contributors. So lets collect all our toys together, bring them back into the pram and share our very considerable mutual knowledge and insight. Jonthetourist and RedRichmond, shake hands and return to the fold without abuse, disruptive behaviour etc? Please
Who are you, admin or something???
Joking ridavies - trying to help cut the tension.
Clearly, we are all lost without Paul!
I second request for Luceco (LON:LUCE) please - whilst it would be wrong to say I am a happy holder (distinctly unhappy actually!), credit due to management for clarity of the reporting (which is why I am not on the crook side of the fence).
Comments noted re not going after profit warnings or falling knives in general. Even if I think I know better, I think it is worth giving it a couple of days to let the price action resolve.
On the bright side, losing money is a far more effective way of having the learning stick than reading an article (which is why I am not averaging down - lost money doing that already!!)
Paul frequently does remind us exactly what sectors & market cap range he covers.
Also, when he strays outside the market cap range, he also explains why.
Maybe... Paul Scott was the people we met along the way.
Paul
I would also be interested on your view on Revolution Bars
Paul,
I think last week you planned to look at Indigo Vision (LON:IND). Did I miss it? If not, knowing that you used to have an interest and follow this (perhaps you still do), your thoughts if not a full analysis would be much appreciated.
Thanks, and keep up the good work. These reports are priceless
Luceco (LON:LUCE) website put me off. Looks cheap. Amateurs.
It might help followers if they were to read the stockopedia definitions of cap size and following on from Paul's headline statement... Any company with a Market Capitalisation of less than GBP 50 million is classified as a Micro Cap, less than GBP 350 million is a Small Cap, less than GBP 2.5 billion is a Mid Cap and all larger companies are Large Cap.
Perhaps this can be added to the top of each report to help guide suggestions more rigorously. Just a thought.
I thought Paul was focusing on < £500m as small cap?
I'm just quoting from stockopedia where Paul post his thoughtful insights.
Where/when did he say what you state?
I thought I read him saying it in one of his reports in recent weeks. I wasn't 100% sure hence I added the "?".
It'll take me ages to go through all his reports but I did find this where he actually quotes £400m https://www.stockopedia.com/content/small-cap-value-report-thu-15-feb-2018-cnct-sdm-botb-snd-lid-tri-316583/
so we are both out by a little bit :-/
I hope admin will clarify the whole situation and process and perhaps step in to provide clearer guidance and stick to it.
All the best
It's never that rigid. Both Paul and Graham will look at what interests them with an emphasis on small caps. Graham commented on BH yesterday after all. Depends on what they know, what they have thoughts about and what they think might interest readers.
Works for me.
For today, I think that the Luceco (LON:LUCE) and EPE Special Opportunities (LON:ESO) is probably the most interesting situation. No clarity elsewhere, and clearly some readers are, or have been, holders (I've never held). That said, no detailed recent accounts and if Paul has no detailed knowledge, he may not feel that he can add much apart from a general comment about profit warnings. I'm still mulling. Statements aren't really that bad. But Luceco (LON:LUCE) is really just an electrical/building material supplier. Creditors/debtors/stock are a bit high. Can we trust the numbers? What on earth could they have been doing to justify capitalising costs in their industry? What will the new Finance man do when he drills into the full details of the reality behind the numbers?
Cap size category ("Size Group") is already shown on the Stocko's stock reports - it is immediately under the share price in the top left of the screen. To get all the definitions just click on it. (The actual cap size is given right at the top in the middle.) Hope this helps.
Re Headlam (LON:HEAD)
A results presentation is now available on the company's website:
http://www.headlam.com/investor-relations/investor-presentation/final-results-presentation-march-2018
MPAC please.If they have net cash of £29m and the mkt. cap is £37m and the continuing business is making money it seems cheap. It's down 5% today. What am I missing / don't understand?
The pension Yellowdog (message 38). Will cost £1.8m a year at least depending on op profit
what about Yu (LON:YU.)
£JE.
Paul, If you've time could you take a look at the results of LoopUp (LON:LOOP) published today, I know this is one you've had some support for in the past? Given the growth potential the key figures for me are the growth in sales at 36% and the increase in the gross margin proving there are economies of scale, particularly in the purchase of the telephony services which must be the bulk of their cost of sales. The increase in overheads isn't too concerning to me as I guess most of this is an increase in sales staff to continue the growth in the top line.
Good morning Paul
Any thoughts on LoopUp (LON:LOOP)
I saw them present at a Sharesoc seminar in November 2017. I liked their enthusiasm and the novel sales approach (pods of enthusiastic, young and highly incentivised sales staff) but could not see a business moat that would protect them from other competitors including the big boys (Microsoft's Skype, etc.). I have recently been using appear.in for conference calls. It works well and sounds similar to LOOP (except maybe for the marketing approach.
Did I miss something important? The share price has gone up circa 30% since November and today's results are stunningly good:
* Revenue +29%
* Loopup Revenue + 36% (presumably there is another less important part of the business that is not growing at the same rate)
* Diluted EPS + 722%
But:
* my rough calculations put them on a p/e of 77 for this year
* there is not much information on expectations for this year - "We continue to see strong demand for our product from our target market of mid-to-large enterprise and professional services firms. Our highly differentiated market positioning and competitive strategy, combined with our efficient new business unit economics, make for an exciting outlook and we remain confident in our ability to deliver further growth."
Hi julianh,
I also saw LoopUp (LON:LOOP) present at that ShareSoc seminar and my impressions were very much aligned with yours. I also thought it a pretty unusual arrangement to have Joint CEOs, rather than one man/woman/person-of-indeterminate-gender at the helm. I asked them about this over drinks afterwards and the response was as polished and easily forgotten as one might expect given how many times they are probably asked the same question!
Both seemed thoroughly capable and they gave a good presentation but I couldn't see any reason to invest. Which is a shame because had I done so it would have been my star performer since November.
Steve
Hi Paul. You may consider it superfluous after Graham's analysis of Revolution Bars (LON:RBG), and the lively and informative board discussion here, but did you form any personal views on their announcement yesterday?
Hi Paul
Good results from LoopUp (LON:LOOP) today, but still an expensive share (I'll admit I got nervous at the valuation and sold out last year, missing a significant jump up).
I suspect you won't want to go over old results, but wondered if you had any thoughts on Revolution Bars (LON:RBG) from last week - a disappointment?
Thanks
Dave
I'm surprised at the number of people who bought Luceco (LON:LUCE) after the profit warning. Despite the research against buying after a profit warning, most people seem to have a natural tendency to catch falling knives.
My results went from mediocre to stellar when I stopped catching the falling knives!
I totally agree, Ricky, what is the point in throwing good money after bad on a negative trading update from any company? Negative news often comes in multiples, all topping up at a lower price seems to do is make the overall loss of the holding look less bad :-/
Andrea, I agree with everything you said. I want to buy shares with positive trading updates. One of my golden rules is that I never buy more of a losing share (average down). I always think of investor Paul Tudor Jones' “Losers Average Losers” photo. Best wishes with your investing!
CRW£ is an excellent example why you shouldn't base your investment decisions on a PE ratio from Stockopedia.
Stockopedia is a useful resource but PE is not always the best measure and even the best system can't keep up if a company is beating expectations (especially if they don't explicitly say so!)
I too bought into Luceco (LON:LUCE) on the previous profit warning and as of now am down abut 25%. My initial thought - apart from being annoyed that it was released seconds after the opening bell rather than at 7am - is to hold on in the hope that it includes a fair chunk of 'kitchen sinking' by the new CFO.
Hi Paul,
Good Morning!
It would be interested to have your views on Huntsworth plc today.
Thanks!!
£JE please
Good morning Kyoto. Did you mean Just Eat (LON:JE.) (Just Eat)? Definitely an interesting company. And it was a small cap not too long ago. But it has grown a long way past that now. You might need to find some extra interest to encourage Paul to cover it anyway.
Would appreciate your views on whether it is possible to value Luceco (LON:LUCE) after two profit warnings and ample evidence of that management are untrustworthy/incompetent (CEO share sale prior to previous warning, second warning released at 8am this morning, multiple excuses for deterioration in trading, large, undisclosed insti selling). Epic claiming that they are still supportive may provide some base to the share price.
At £11m PAT this year and £12.5m next year the shares are on a 9x historic / 8x prospective earnings. But this includes 22p of debt per share which was foolishly taken on to make an ill-timed acquisition in September.
What do you think the end-game is here? I suppose the risk is a deeply-discounted rights issue to repair the balance sheet but that would dilute both the CEO and Epic who both remain large holders. My feeling is that the CEO is primarily incompetent and only secondarily untrustworthy. This is based on the fact that he only sold a small proportion of his holding before the first profit warning and that they made the acquisition just a few weeks before the first profit warning.
The fundamental problem here is that their supposed 'natural' hedge between USD and CNY has failed and that the price of copper (which accounts for around 40% of costs, also unhedegd) has increased significantly.
Revenue growth rates are now slowing but the EV/EBITDA is starting to look attractive.
I'm also interested in Paul and others views on Luceco (LON:LUCE) Like others I also bought it on the previous profit warning due to what appeared to be a manageable blip in an otherwise strongly growing business. Today's profit warning indicates this was a bad decision. Especially cross with RNS landing just as the market opened....
Luceco (LON:LUCE) - this is what happens when you get a total loss of confidence in management combined with poor communication.
I think that Hornby was as surprised as anyone at both the profit warning and at the extent of the market's reaction. Difficult to see how he would have had the hubris to purchase Kingfisher in September with £10m of cash that they didn't have if he had any idea of the financial situation.
This suggests that he wasn't / isn't in control of the finances. They have a new CFO on whom EPE Special Opportunities (LON:ESO) seem to be placing a great deal of reliance to remedy the situation - https://www.investegate.co.uk/epe-special-opps-plc--eso-/rns/update-regarding-luceco-plc-and-share-buybacks/201803060859168162G/
The trading problems are being compounded by a failure to communicate effectively with the market. This is both in terms of timeliness and precision. Consequently, holders are capitulating and potential shorters can smell blood.
So the question is where does this end up? At the moment there are no buyers. I can see this at 50p or less by the end of the day with further weakness before results are eventually reported (no indication of when that will be in the RNS - another red flag).
I think the most likely outcome here is a heavily-discounted rights issue to repair the balance sheet with dilution for holders. That or an opportunistic offer by EPE Special Opportunities (LON:ESO) although I can't see that they would be able to float this again in a hurry.
Hi mammyoko,
Should holders of LUCECO LON:LUCE draw any comfort from your feeling that the "CEO is primarily incompetent and only secondarily untrustworthy." ?
I would definitey be a seller if he were primarily untrustworthy and only secondarily incompetent.
On a more serious note: I don't see this business as anything other than a supplier of basically commodity products and will not be able to maintain high margins.
Bonitabeach
No position.
Hi Bonitabeach
Re Luceco (LON:LUCE) - I was only trying to make the point that I don't think this is Quindell or Globo. That's purely on the basis that insiders (or ex-insiders) continue to hold around 50% of the shares. If this was a similar fraud this wouldn't be the case.
You appear to be right on the margins as they are forecasting the PBT% to fall to 8.5% in 2018 (£12m x 100/80 / £168.6m x 1.05).
I would also add the further accounting issues which have been noted in today's announcement relating to aggressive capitalisation of costs. In the December 2017 update, there was an incorrect assessment of stock valuation. This negatively impacted gross margins.
In the December update, reference is made to a "strong balance sheet" whereas today they disclose debt of £36.9m.
Whilst revenues are forecast to be growing there are too many references to weak consumer confidence, margin pressures, FX headwinds, and H2 weighting. Is there a more fundamental issue with the quality of the product?
Luceco (LON:LUCE) - I think the fundamental problems with trading is that
a) 40% of the cost of sales is on copper and the copper price went from $2.80 per lb to $3.20 per lb between July and December and
b) the supposed 'natural' hedge between USD and CNY failed to work and the USD fell from CNY 6.75 to CNY 6.25
This explains the pressure on margins. Recently the spot price of copper has fallen to $3.11 per lb and the $ has firmed slightly to 6.35. This may provide some relief.
The question is whether Hornby can be trusted and the market is saying he can't. Incompetence covered up by arrogance is a risky combination when faced with trading issues.
Headlam (LON:HEAD) Good results - the worry is as stated January/Feb 2018. Can't imagine the recent cold spell has helped.
I'm invested here but will wait till adding to my holding as I think the share might go lower.
PE less than 10 which is fantastic long term buy for a well run business and Continental Europe offers the growth. £35M cash in the bank makes it even stronger.
From the report "Against a very strong January 2017 comparator, the Company's overall like-for-like revenue* declined 5.9% in January 2018, with the UK showing a more pronounced reduction, 6.7%, predominantly due to the performance of the residential sector and the adverse impact of a reduction of orders from one of our larger customers. In contrast, Continental Europe delivered a strongly positive result for the residential sector in the month, 6.5% on a like-for-like revenue* basis. The negative UK performance in the month was largely attributable to a very soft first working week following the New Year holiday, with the rest of the month showing some recovery but remaining moderately below our expectations.
The like-for-like revenue* performance in February 2018 was similar to January 2018, with a continued reduction of orders from the larger customer mentioned above and generally softer markets."
Headlam (LON:HEAD) ? Now who would that 'large customer' be do we think? Carpetright? Or do they supply some other sheds? If it's Carpetright I wouldn't expect a significant improvement soon. And the UK consumer is likely to be under pressure for most of this year unless we see wages pick up. Good solid business but the impact of this might take 12 months to work through.
Shall we adjourn and come back for the Interims or take a punt that today's reaction was overdone?
Hi Cisk
Yes somewhat unwarranted I thought, but there you go. Regarding Headlam (LON:HEAD) I share your view that this is a well managed company with good financial metrics operating in a challenging market. To paraphrase Ben Graham, in the short term the Market is a voting machine but in the long term it is a weighing machine.
All the best
Jonno
Headlam (LON:HEAD) please Paul agree with the other posters results look good not sure why its been whacked maybe its a read across from problems in the sector such as Safestlye and Carillion etc ?
Another vote for Begbies Traynor (LON:BEG) As well as the acquisition they put out an 'in line with expectations' statement (neglecting to say what those expectations were) and also state a 9% increase in corporate insolvencies in 2017.
MPAC (LON:MPAC) results today certainly look interesting. This one also covered by Simon Thompson of IC. A possible turnaround after the sale of loss making elements of the business :-
Excellent progress on the Group's strategic initiatives
· Increase in order intake from continuing operations of 21% and order book 35% higher than at the start of 2017
· Sales from continuing activities of £53.4m (2016: £41.5m)
· Underlying profit before tax of £1.1m (2016: £1.5m loss)
· Statutory profit before tax from continuing activities of £4.3m (2016: £3.1m loss)
· Statutory profit after tax of £1.6m (2016: £0.6m loss)
· Underlying earnings per share of 4.2p (2016: loss of 6.0p)
· Basic earnings per share from continuing activities of 12.2p (2016: loss of 12.3p)
· Net cash of £29.4m (2016: £0.8m)
· Sale of the Instrumentation and Tobacco Machinery (I&TM) business
Another profit warning from Luceco (LON:LUCE) down 20% though it insists things are going well internationally profits will be down due to lack of UK confidence. Stupidly I ignored Ed's profit warning advice and bought the 'dip' a while back. Debt up to about 1/3 of revenues. Any opinions?
I also thought that Luceco (LON:LUCE) looked cheap after the December warning, and bought some. Obviously I confused "cheap" and "not worth the asking price". The price seems to have bounced a bit from its 20% low earlier today though. It is still making more profit than last year and 36m of debt versus 11m of PAT for 2017 is just about OK if we can still believe 12-14.5m for 2018. Also, sounds like they have kitchen sinked a bit for 2017 by not capitalising certain costs that they might have done (good for subsequent years). Overall, though, I am probably trying to cheer myself up for a poor purchase and I don't like the unquantified comment about margins. Will need to have another good hard look at this one.
Just for info, my local builder's merchant has stopped stocking Luceco (LON:LUCE) products as they were not selling. Reason not known, but they look a bit 'novelty' to me. I formerly held here.
Morning Paul,
I have a request please before it jumps right off everyones small cap radar.
Craneware ( Craneware (LON:CRW) )
Interim Results For The 6 Months To End December 2017 – Revenue up 16% to $31.1m (H1 2017: $26.8m), PBT up 16% to $8.7m (H1 2017: $7.5m), Adjusted basic EPS up 18% to 25.4c (H1 2017: 21.6c), Cash of $52m (H1 2017: $45m) following dividend payment of $4.1m with the proposed Interim Dividend up 15% to 10p (H1 2017: 8.7p).
My notes this morning...
I have been saying this is expensive on a PER of 30 and 35 and it’s now 43. I am coming to the conclusion I got it wrong here. However, based on these interims I cannot justify paying up on a PER of 43. Rightly or wrongly! What am I missing here?
It was only worth £350m 12 months ago, was worth about £500m this morning (pre-open) and worth even more now.
As always any analysis much appreciated, fully understand it's maybe too large already and that it's a pretty packed day news wise.
All the best for now.
I would also be interested in Headlam
Thanks Dane
Paul, would you be able to take a look at Headlam (LON:HEAD) please?
Underlying PBT is slightly ahead (£43.1 million) of the £42.5 market expectations reported on 18 Jan. Nice to see a company telling us the market expectations!
Europe saw eight times more revenue growth than the UK (4.2% vs 0.5%) and in today’s report under current trading they’re much more bullish about their European markets. Shame these currently make up only 13.2% of revenue. But they did announce today the acquisition of their 63rd company, a 45+ year old Dutch family run business.
Still a good dividend, paid since 1992 as Graham noted when he covered the interims in August.
Specialist US medical service company Craneware (LON:CRW) reporting decent half year results this morning.
https://www.investegate.co.uk/craneware-plc--crw-/rns/half-year-report/201803060700037619G/
Good progress being made but already richly priced after a strong run in the last six months or so. Maybe already fully valued but seems to have a decent moat and possible opportunities to grow internationally. Don’t hold as never quite pressed the buy button waiting for a cheaper entry level .... that so far has never arrived.
Gus.
I agree with You Gus Craneware has everything but the price. My personal view is it will become cheaper as this bear progresses
Regads
Ken
Good morning Paul
I would be interested in your views on Headlam, Headlam (LON:HEAD), time permitting. This morning's prelims look very creditable given the challenging market conditions.
Many thanks
Jonno
Morning Paul,
LSL Property Services (LON:LSL) have release their preliminary results for the year ended 31st December 2017 this morning.
From my untrained eye this looks good with EPS growth of 9.3%, ahead of broker estimates. They are also claiming a strong balance sheet, I know to be one of your pet hates.
All the best,
CD
My morning smallcap tweet:
Havelock Europa (LON:HVE), Zamano (LON:ZMNO)
Havelock Europa (HVE) CFO resigns, leaves April. Sounds amicable.
Zamano (ZMNO) will be suspended on 9 March as it hasn't completed an RTO. Cash return and poss RTO consideration continues. Any RTO will still give cash return option.
Morning Paul & chums, can I please request
Yu (LON:YU.) Independent supplier of electricity to industry which has smashed it out of the park since IPO and whose success I have completely missed - or have I? "Revenue almost trebled to £47 million > FY 2016 with a rapid increase in profitability Achieved an adjusted operating margin of 6.7 per cent, Increase in contracted future revenue adding to the Group's high level of visibility: contracted revenue for the year to 31 December 2018 in excess of £50 million, with FY2019 revenue ahead of previous expectations, revenues FY 2019 also is expected to be significantly ahead of current expectations, Proposed final dividend of 2p per share, making a total dividend for the year of 3p, and expanding into water & gas. This company doesn't lack drive and was one reason I sent old warhorse SSE (LON:SSE) to the knackers. 'High Flyer' BUT Stocko PER is 50. Is it overreaching?
Also ones I know you've covered / hold already: OptiBiotix Health (LON:OPTI) have a new contract - you'd previously been waiting for more before you bought which turned out to be a good call to this point - and Begbies Traynor (LON:BEG) , Acquisition of Springboard Corporate Finance Limited 'a highly regarded, mid-market corporate finance practice, operating from offices in Birmingham, London and Nottingham'. Dilutive, but seems it is casting its net wider to catch more business in the next (current?) slump. I hold both.
Thanks! I know you'll tell me if I'm bring greedy!
Would love to read Paul's view on Yu which was floated two years ago at 185p a share. It is one of those fairy tale stock market stories which is hard to believe. The founder used to run a chain of care homes and found himself being screwed by his energy suppliers. So he researched the energy supply industry to find a better deal and decided that he could do a better job of supplying energy to SMEs. Since then Yu's share price has risen more than six fold.
That's the sort of thing that people should get OBE's for IMO. I missed out on Yu but what a story, and a prime example of how, without the cronyism, capitalism can and should work.
Graham viewed Yu (LON:YU.) on 29th Jan and was generally very positive, although believed it was fully priced.
- Revenue grew 300% and operating costs grew less than 50%, so positive leverage, the impact of own gas transportation has also not had an impact yet. Is an operating margin of 10% possible?
- Current FY18 revenue expectations are £75m, the guidance indicates (ahead market c.+10% ish) £80-85m potentially. Post-it note calculation on EPS would be around 40p (vs. exp. 25p).
- If FY18 EPS is 40p, the fwd PE would be around 32, which seems reasonable.
- much of the PE expansion (doubled from 25 to 50) since Sept has been on barely revised FY18 expectations, this is the issue with just having one broker estimate.
- the H2 for FY saw a basic EPS of 9p, this is a 250% rise from H1 of 3.8p, so we have EPS momentum
I have top sliced today as we're up significantly from the Feb'18 dip. I will add on any consolidations and sell out completely only if EPS momentum decreases
(disclosure i hold)
Just a gentle reminder that Paul asked that requests come up with at least a sentence on what it is about the company that makes it worthy of analysis.
Please?
Jon
Hi Jon and Paul
Regarding Headlam (LON:HEAD), it is the largest floor coverings distributor in Europe and a consolidator in the industry, acquiring small, often family run businesses, which continue to operate independently under the original name and management. Under sound management it has continued to increase revenue, eps and margins over several years and in so doing has broadened the scope of its product offering and geographical coverage. It currently yields around 5%, has very good cash conversion and is ungeared with £35 million cash on the balance sheet. Market cap is about £450m
Management confirms its expectation for earnings for the year to December 2018 to be achieved putting it on a PE of about 12. Given that we are only 2 months into the current year this is a somewhat bold but confident statement.
Jonno
Jonno
Not sure what warranted the thumbs down from someone on your post Jonno, Headlam (LON:HEAD) is now below £500m mkt cap so assume it’s not that.
Anyway, I suspect the mkt has been unduly harsh on Headlam (LON:HEAD) this morning, I know the sector is unfashionable but this is a quality outfit, with a stonking yield and slowly expands its reach and builds new distribution centres etc etc.
I believe that even in the last recession they maintained their dividend but could be wrong on that. I tend to prefer boring companies like this!
Who are you the administrator?
"Just a gentle reminder that Paul asked that requests come up with at least a sentence..."
I,m unsubscribing from this site now.. Its not helpful. 99% of the people are not or do not hold financial qualifications.
I will do my own research in the future..
bye
"Who are you the administrator?
"Just a gentle reminder that Paul asked that requests come up with at least a sentence..."
I,m unsubscribing from this site now.. Its not helpful. 99% of the people are not or do not hold financial qualifications.
I will do my own research in the future..
bye"
(Polite filter on) I greatly regret that a simple reminder of a request for trivial effort from posters has caused a respected member to choose to move on. (Polite filter off)
Bye, D!ckhead.
GMAA gama aviation 117 mil cap
MAYA mayair 49 mil cap
A couple of tiny titans