Small Cap Value Report (Mon 29 Jan 2018) - STHR, UTW, CVR, FISH, SPE, CLLN, ANP, YU., ITM

Good morning!
Thank you for suggestions, which I will prioritise for coverage.
There are a lot of updates today, so I may need to be selective.
Regards,
Graham
SThree (LON:STHR)
- Share price: 368p (-1%)
- No. of shares: 132 million
- Market cap: £485 million
Final Results for the Year ended 30 November 2018
Mentioning this international STEM recruiter only briefly, for two reasons.
1) It doesn't get requested very much, and 2) its market cap is now pushing the limits of what we tend to cover here, after a strong share price performance over the past year.
I covered SThree a few times last year, and my overall stance on it hasn't changed. I think it's a very well-run international business with attractive geographical diversification and an excellent track record of profitable performance.
Today's results show further progress in the strategy to limit Permanent hiring activities, while expanding the more reliable Contract-based activities.
It's more and more international, as 81% of gross profits are now derived from outside the UK.
Some people might be reluctant to invest in this sector due to low margins and its hyper-competitive nature, and I can understand that position. But for an investor who does want to get involved in recruitment, I think this should be one of the first stocks they look at.
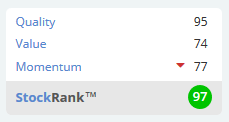
The algorithms are impressed too, giving it a StockRank of 97.
Utilitywise (LON:UTW)
- Share price: 41p (suspended)
- No. of shares: 78.5 million
- Market cap: £32 million
Temporary suspension of share trading
I haven't studied this utilities consultant in any detail before, as my modus operandi is to find things that I might like to buy shares in, and there were more than enough red flags to keep me away from this.
On Jan 17th, Paul highlighted (actually he put it in bold) the risk of the company failing to get its July 2017 accounts published in time to avoid suspension. It was an important warning for anyone holding these shares, as that is indeed what has happened.
Prior to suspension, Utilitywise was trading on an official PE ratio of 5x, but it was no bargain. The algorithms on this website had correctly, I think, identified it as a Value Trap.
The big accounting problem at Utilitywise is one of revenue recognition.
Something which I always reinforce is that revenue should be recognised in accordance with how much work has been done - not how much cash has been paid or will be paid.
At Utilitywise, revenue is recognised on long-term contracts on the basis of an estimate of how much value will be created over the life of the contract. Prior to August 2017, 85% of the total expected value of a contract was recognised on day one.
As admitted by Utilitywise, bigger contracts have under-performed, and the average under-performance (called "under-consumption") for all contracts over FY 2016 and FY 2017 was 18%, i.e. worse than the 15% under-performance which the company priced in.
From August 2017, the company has been using the new IFRS accounting standard for revenue recognition, IFRS 15 (external link), and assuming 20% under-performance.
But an independent accounting firm has reviewed the Utilitywise accounting policies and determined that they were inappropriate both for the old and new accounting standards.
Small contracts need to be treated more conservatively, and big contracts can no longer be treated using a simple percentage estimate of under-performance.
The accounts need to completely redrawn, in other words.
Without good accounting data, it's virtually impossible to understand the value of a potential investment, at least not in any quantitative way.
Maybe when the accounts are cleaned up and the financial situation has been clarified, I will look at this again.
Conviviality (LON:CVR)
- Share price: 316p (-12%)
- No. of shares: 183 million
- Market cap: £579 million
I am a long-time bear of this alcohol wholesaler and retailer, and have generally been on the wrong side of the share price.
Having said that, the last time I covered it, the share price was 386p. Perhaps the tide is turning
Trading is said to be in line with expectations for the full year. But although it isn't explicitly said, there is an implication that H1 did not quite go according to plan, and the shortfall will be made up in H2.
H1 was the period to October 2017:
- Revenue up 9% to £840 million
- Gross margin down to 12.5% from 12.8%
- Adjusted EBITDA up marginally to £23 million
- Adjusted net income down marginally to £12.3 million
- Statutory net income down 10% to £5.2 million
- Net debt of £133 million (had been at £96 million in April).
At lease one broker had been forecasting c. 4% growth in adjusted PBT for H1.
As an aside, for those of you interested in Revolution Bars (LON:RBG), it might be worth noting that Stonegate Pub Company (a previous bidder for Revolution) is one of Conviviality Direct's top customers.
In Conviviality Retail, like-for-like sales growth comes in at just 0.4%, or 2.3% excluding tobacco. For the last six weeks of the year, LFL growth was 0.6%.
As I covered recently, 127 new retail stores were added to its estate from a Palmer & Harvey subsidiary (P&H went into administration).
My opinion - I'll stick to my guns and continue to suggest caution, even though I have usually been wrong by doing this in the past.
The profit figures are said to reflect "the phasing of cost synergies into the second half of the year".
I think today's share price move reflects simple disappointment in the profit miss, and also maybe some fear that the cost over-runs and reduced margins won't be entirely offset by the cost synergies anticipated in H2 and beyond.
My major concerns are the low-margin nature of the work it does and its partially debt-fuelled expansion.
The constant use of "exceptional items" and the focus on adjusted numbers also leave me cold.
Additionally, I have a concern about its possibly excessive use of share-based payments. In the twelve months to October 2017, it generated nearly £18 million in profits, and spent £3 million of this on share-based bonus payments to its managers.
Finally, I think that today's H1 results were a profit miss, which is confirmed by the share price decline.
But with respect to results versus expectations, today's statement has merely expressed confidence that results for the full year will be in line. It doesn't actually say whether or not the H1 results were in line with the company's prior expectations. Would it be much trouble for this to be included?
Brokers are now forecasting that net debt will reach almost £150 million by the end of the current financial year.
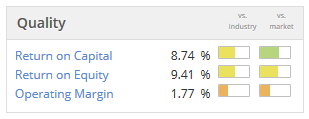
The algorithms give it a high Quality Rank. I'm not sure I agree:
Fishing Republic (LON:FISH)
- Share price: 10.25p (-2%)
- No. of shares: 38 million (before placing)
- Market cap: £4 million
This fishing equipment retailer is now too small for coverage in this report, but I just want to point out that it has raised new money, as was predicted. 13 million new shares raised at 10p.
It has also issued 1,000,000 shares to pay for consultancy services.
It made a loss in 2017 (accounts yet to be published) but has now refreshed its management team and hopefully doesn't need any more cash in the short-term.
Being firmly in the nano-cap space, it's too small for most of us to even consider investing in. All I want to point out is that the smart thing to do, if you were going to invest, was to not hold any shares until the Placing took place.
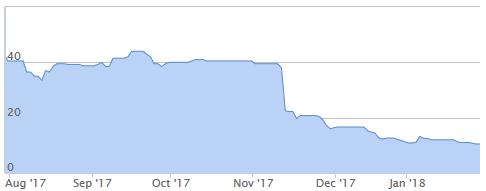
It had become increasingly obvious that more funds were needed (£700k left after a £1.4 million outflow in H1 last year). If you simply held off on buying shares until the Placing occurred, it would have made the world of difference to your entry price:
Coincidentally, Angling Direct (LON:ANG) also put out a little bit of news today.
Sopheon (LON:SPE)
- Share price: 575p (+17%)
- No. of shares: 10 million
- Market cap: £58 million
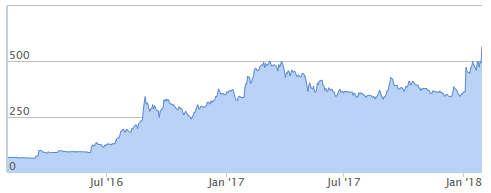
Yet another positive surprise from this software company, which has been on a roll for the past two years. Investors have been handsomely rewarded as the shares have multi-bagged:
We already knew that 2017 performance had been upgraded, but it is further upgraded today. Note the reporting in USD:
The Board expects that reported revenues for the year ended 31 December 2017 will be over $28m, up from $23m in 2016, and comfortably ahead of current market expectations. The Board expects that both EBITDA and pre-tax profits will be significantly ahead of current market expectations. The year-end net cash position is expected to be $9.5m (2016: $4.2m).
The business success in 2017 has a knock-on effect in 2018 due among other things to the recurring revenue it creates.
The company says that its "Accolade" software platform is being used in applications beyond the core "innovation management" it has been traditionally associated with. You can read about this software at Sopheon's website here (external link).
It's still undeniably a medium-sized business, having signed 59 deals with customers in 2017. $18 million of 2018 revenue is now visible as recurring revenue, up from $13 million a year ago.
My opinion - Research paid for by the company suggests that adjusted EBITDA will fall in 2018, due to spending to improve the software platform, but will then recover back to $7.3 million in 2019.
That might disappoint some investors if there is a pause in profit growth, but there are still some very attractive features to this stock.
Firstly, you have the strong cash position as noted above ($9.5 million).
Secondly, you have the company's recent track record of beating expectations. Perhaps its forecasts tend to be on the conservative end of the scale? No bad thing.
Finally, there is the intriguing potential of its software have much wider uses than previously conceived.
Overall, therefore, I retain my positive impression of Sopheon.
Carillion (LON:CLLN) (suspended) - Investigation into the audit of the financial statements of Carillion plc.
A post script on this story, with news that the Financial Reporting Council (the accounting watchdog) will be investigating KPMG's work on Carillion from 2014-2017. I've added the emphasis below:
The investigation will be conducted by the FRC's Enforcement Division, and will consider whether the auditor has breached any relevant requirements, in particular the ethical and technical standards for auditors. Several areas of KPMG's work will be examined including the audit of the company's use and disclosure of the going concern basis of accounting, estimates and recognition of revenue on significant contracts, and accounting for pensions.
It's the old chestnut of revenue recognition on long-term contracts, plus a few other very important questions.
There's a lot to be said for investing in businesses which don't have to worry about estimating the outcome of extremely complicated contracts!
Anpario (LON:ANP)
- Share price: 488p (-1%)
- No. of shares: 23 million
- Market cap: £113 million
This company makes animal feed additives, produced in the UK and exported around the world.
Today's update is in line with expectations. New senior managers have been recruited and the cash balance has grown to £13.6 million.
We haven't covered it very frequently in these reports, but maybe I'll put it on watchlist from now on? I don't know if he is still holding it, but it was previously held by Lord Lee.
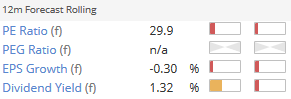
The rating is rather high, reflecting the company's international growth prospects, with international sales said to be taking off very strongly (albeit from a low base). I need to investigate this company in greater depth, so will end my note here for now.
Yu (LON:YU.)
- Share price: 1115p (+9%)
- No. of shares: 14 million
- Market cap: £157 million
Trading Update and Notice of Results
This company provides gas and electricity to SME customers around the UK, with headquarters in Nottingham. It listed about two years ago.
According to its website, it wants to "unseat the big six".
This is an update for the full-year 2017. Revenues will be significantly ahead of market expectations. Overheads (including staff headcount) have been increased too, but operating profits should also be ahead of market expectations.
Based on its success catering for the medium sized corporate sector, Yu reckons that 2018 and 2019 revenues will be "substantially ahead of our previous expectations".
Broker research reckons there is a good chance of more positive surprises over the next few years, on the basis that there are still two million customers who haven't switched from the Big Six.
Trustpilot reviews, which according to the website's best knowledge are not being actively collected from customers, give it a 4-star rating - see here (external link).
My opinion - the high customer service levels promised by Yu are likely to require a substantial and ongoing investment in headcount as the company grows
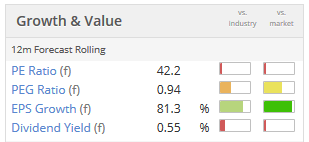
This is borne out in the forecast operating leverage: according to forecasts, adjusted pre-tax profit margin is set to grow from 6.5% in 2017, to 8.3% in 2018, to 8.6% in 2019, during which period revenue is set to double. While there is some operating leverage to be enjoyed, the margins here are unlikely to explode higher.
It does appear to have a substantial growth runway, it pays a small dividend, and it's hard to fault its performance so far. All of these facts are perhaps already priced in now?
ITM Power (LON:ITM)
- Share price: 35.7p (+2%)
- No. of shares: 324 million
- Market cap: £116 million
This hydrogen energy company raised almost £30 million (gross) last year, to shore up its balance sheet.
That fundraising is included in the cash flow statement, published today, for the six months ended October 2017.
The company actively measures its cash burn, using this as a KPI. Cash burn for the six-month period was £5.1 million, significantly worse than the prior period, mostly due to heavy investment in PPE.
The order backlog has thankfully increased by £10 million to £27 million, versus 12 months ago. The "total backlog" (perhaps aggressively including "contracts in the final stages of negotiation"), has more than doubled. There have been some promising deals with Royal Dutch Shell (LON:RDSB).
Actual revenue remains very small for now, at just £1.4 million in these accounts.
The outlook for the second half is "exciting":
The second half of the financial year to end April 2018 looks set to be busier than ever when we will be beginning the process relocating to new manufacturing premises in the South Yorkshire region which will give us the additional capacity necessary to manufacture large scale electrolysers of 10MW and beyond. In addition the ability to operate under one roof is expected to provide important operational and cost synergies.My opinion - I'll reserve judgement on this, as it's too early-stage for me.
Revenues are still so small, they are no basis on which to make an investment.
In terms of the risk factors at play, at least the company should have enough cash to last it for a few years. But I do expect that investment will remain very significant: the CEO commented today that "scale is key", and moving into larger factory premises will doubtless be expensive.
Unsurprisingly, given the very low revenues recorded to date, there are only a few decent-sized paying customers so far. Four customers accounted for >80% of the revenues in this period.
On the positive side of things, there is the growing order backlog.
Hopefully, margins can improve: the gross margin was 9% in these results. Nearly all of the revenue came from construction contracts. Perhaps maintenance and fuel services, when they are material in size, will be higher-margin?
I don't think this is anything resembling a "value investment" but maybe someone with expertise in hydrogen as a source of power would think it was attractive?
Since we had quite a few trading updates and requests today, here's a reminder of the not-very-scientific criteria I use to decide which stocks to write about each day. Failing one or several of these criteria doesn't mean I won't cover it, but it reduces the likelihood. Paul and I may differ, this is just what I do:
- Market cap: £10 - £400 million market caps are the most preferred.
- Industry/Sector: I generally don't cover resources, pharma, investment funds and blue-sky stocks. I like consumer stocks, financials, software, property and industrials.
- Requests: This article is ultimately for the benefit of readers, so the more requests something has, the more likely it is I will cover it. Thumbs up on requests are also taken into account!
- Timeliness: Companies which have issued annual/interim results have priority. After that, companies which have issued interesting updates (results above or below expectations, for example). After that, companies which have issued updates in line with expectations. If there is no news, I am unlikely to write anything about it.
- Familiarity: Stocks which I have previously analysed require less work to analyse their news and write up a reasoned opinion on them. So if I've covered it before, it's more likely I will cover it in the future.
- Is it a good company? If it's not something I would ever invest in, because it's just a "bad" company, then I am less likely to write about it, except as an example of what to avoid.
This is the most scientifically I can describe my selection criteria for now!
A busy day in the market, thanks for dropping by.
Cheers
Graham.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

61 comments
Interesting to see Sopheon (LON:SPE) was able to get away a placement of 3.1% of its shares held by management at 968p - a decent premium to the then market price of about 930p.
https://www.investegate.co.uk/sopheon-plc--spe-/rns/result-of-secondary-placing/201805170801093957O/
Shares have been on a roll since Graham’s piece at the end of January when they were at 575p. Placement at a premium with II’s together with recent strong performance suggests strong demand/shortage of supply.
Gus.
Re Sopheon (LON:SPE)
Which makes the recent precipitous decline very puzzling...
Hi all,
I'd like to hear the collective views on whether it's time to sell Sopheon (LON: SPE) now. The stock has rallied +55% since 29 Jan when Graham wrote his original piece, and Stockopedia shows its Value factor at a low level of 14.
Has it become overpriced now??
Grisha
Sad news about Conviviality (LON:CVR) though I'd have been surprised by a more positive outcome.
I don't understand how it could ever have had a high stockrank because there were a lot of things making it a low quality investment:
Thankfully I never bought any despite all the positive comments on here................surprising how quickly the comments go from buy, buy, buy to sell, sell, sell.............just shows it ain’t easy out there........
Conviviality (LON:CVR)
Lesson is that if people lose faith (rightly) in the numbers, nothing is savable. SR is totally irrelevant here because it relies on those numbers. There is always going to be a certain amount of the story that cannot be captured by quantitative analysis and if the numbers are wrong .......
If this was a company with a good finance function the placing would probably be going ahead and it would be saved.
I feel for the employees, they have been seriously let down, especially those from recent acquisitions. I hope none of the directors are allowed to hold that position again - but suspect they will.
Phil
Happily I was never a holder, but my learning from this sorry saga is that any time an FD leaves without a very good reason being apparent, the small shareholders should just sell and move on. Treat it like a profit warning that hasn't been announced yet.
Happily also I was never a holder and I think you have a good point.
Phil
Sky News reporting that CVR is toast.
https://news.sky.com/story/2600-jobs-at-risk-as-bargain-booze-heads-for-administration-11307294
A stock rank of 92 in January!
Conviviality (LON:CVR) - A stock rank of 92 in January!
Yes, but reduced to 69 by mid Feb with a Z score of 1.15 suggesting financial risk.
It's the old question with a SR portfolio:
Do you hold shares for a year regardless OR
Do you sell if the SR reduces below X
I would love to see an analysis comparing the 2 methods.
Utilitywise (LON:UTW) finally published their re-stated year end accounts for year end July 2017.
https://www.investegate.co.uk/utilitywise-plc--utw-/rns/final-results/201803220700095345I/
In a word, “ugly”. Also a separate Q&A - although quite a few more Q’s I suspect for anyone still holding.
https://www.investegate.co.uk/utilitywise-plc--utw-/rns/questions-and-answers-for-shareholders/201803220701015347I/
I can’t immediately see a reference to the share suspension being lifted but presumably this can now happen. Not sure it will be much cause for celebration to any holders (are you still there Mr. Woodford?).
Nice set of results from Sopheon (LON:SPE) though ......
https://www.investegate.co.uk/sopheon-plc--spe-/rns/final-results/201803220700055201I/
Gus.
Re. Altitude (LON:ALT)
[bestace: I have only just seen your note on this subject. Generally I agree with your view. However I cannot reconcile your $6.6m revenues. I suspect it is based on the target assumption of 210 orders p.a. per distributor rather than the base scenario of 100 orders p.a.]
Altitude is an interesting stock with a high risk profile but also a high reward potential. In my view the potential high reward tips the balance in taking the risk and going long.
The following argument is based on information provided by the company in their 2017 interims presentation (you can download it from their website).
The company shows two scenarios, a base case and a target. Working purely with the base case and the US market only, ALT’s revenues over the medium term are projected to be approx. £43m p.a. So a build-up could be, in the first year £10m ramping up to £43m in year 3.
Considering ALT’s last audited revenues were £4.3m, that’s worth sitting up and take note.
This base scenario assumes capturing 2% – 3% US market share in the medium term.
Here is the second interesting reason. The company is actually building a platform business in the true sense of the expression. A platform business model creates a technology platform with network effects and provides facilities for all parties to transact directly. The platform owner, ALT, does not own the means of production, instead it creates the means of connection, and in the process takes transaction fees based on the completed transactions (viz. ebay, uber, eat, etc)
So as a platform business, we are likely see revenues substantially falling into the bottom line profit and cash flows.
However the risks are not trivial.
- Management have been bullish and optimistic for a number of years. To date they have built the platform but no real revenues from this source to prove the complete business model.
- Take-up by the US is showing promise as yesterday’s RNS shows. But there is still a long way to go before they hit minimum traction.
I have taken a long position but if the company doesn’t show real progress in line with their base case scenario in the near future, then I would likely sell.
Please DYOR
I was trying to combine the figures disclosed in yesterday's RNS with the figures provided in the interims presentation. It's very possible my understanding is deficient so happy to be corrected, DYOR etc. These were my workings:
7 signed up partners doing $11.2m revenue + 57 partners in the process of coming on board doing $44m revenue = $55.2m of partner revenues, which on a gross profit margin of 40% (not 60% as I said in my last post) means $33.1m of supplier revenue (i.e. 60% x $55.2m), which in turn means $6.6m of revenues to Altitude (LON:ALT) (based on a 20% cut of the $33.1m of suppliers' revenue).
re. Altitude (LON:ALT) Thanks, bestace.
Following the presentation data for the base model, for every $100 that a distributed sells, ALT's transacton fee = $100 *60%(gross margin) * 20% (ALT's fee) = $12. Effective 12% of a distributor's revenues.
Taking $55.2m as the total annualised revenues, that gives $6.6m fees for ALT. Which agrees with your computation. Of course this is over a calendar year, and not current financial year.
In reply to Samsgrandad, post 44:
Slightly off topic.
" it's interesting that it is a way of stabilising the supply and demand on the electricity grid, (one of the shortcomings of renewable power)"
This pilot investment by Elon Musk in Australia is very interesting in that respect. It looks like it could be one way of overcoming the aleatory availability of many sources of renewable energy. It may also turn out to be a great investment!
http://www.iflscience.com/technology/looks-like-teslas-giant-battery-in-australia-made-some-serious-cash-this-month/
Fulcrum utilities FCRM a review of this decent company would be hugely appreciated
Those who are interested in ITM POWER, may want to have a look at BLDP, a Canadian company in fuel cell technology. It has quite a few buses being tested in london. It has won so many contracts with China for buses and trams, also with European countries. Their fuel cell technology uses much less precious metals than normal fuel cell, making them much cheaper to produce.
They have a subsidiary called PROTONEX which produces wearable items for USA army, the device scavenges power from different sources to keep the most critical ones active.
The company actually makes a small profit.
I had held in the past but sold last year as I felt the sp had gone ahead of itself. The sp has been drifting down. There was a short seller attack on Friday but the company issued a statement today and the sp is up 30%.
No advice is intended, please dyor
Graham
Any chance of an update on LUCECO, their share price is tanking alarmingly. Is this an over reaction to recent bad news
Hi Graham,
I completely agree with you re taking a negative view of Conviviality (LON:CVR) . My view is that the company is a good example of "busy fools" - i.e. huge turnover, but little profit. The interim figures today look unimpressive to me.
It's the balance sheet that really concerns me though. NTAV is negative, at a whopping -£81.1m! So the whole business is financed by the drinks suppliers & the bank. What happens if either or both lose confidence in CVR? It could easily go bust in an economic downturn, in my view, with it current, precarious, financial structure. Remember that credit gets withdrawn in a downturn. It's madness to be paying out generous divis, in my view. CVR should stop paying divis, and concentrate on debt reduction, in my view.
What about bad debts? The casual dining sector is under severe stress at the moment, and I'm guessing that CVR must be a supplier via its wholesale division, to many restaurants that could go bust. So there's balance sheet risk within that enormous £242m debtor book. I wonder if CVR insures the debtor book? If it does, then fine. If it doesn't then it could prove to be exposed to bad debt risk in the future.
I see today's 15% share price fall will have knocked about £100m off its market cap, but at the resulting c.£550m market cap it still looks far from good value to me. It's just a distribution business, being squeezed from both suppliers & customers, and with no doubt rising costs. There's no attraction to this share at all, in my view. One of my least favourite companies.
Regards, Paul.
One interesting little point on Conviviality (LON:CVR) is in Note 14 of the Annual Report & Accounts:
"As of 30 April 2017, trade receivables of £42,263,000 (2016: £6,813,000) were past due but not impaired. These relate to customers and Franchisees for which there is no recent history of default".
Between FY16 and FY17, the total balance of trade receivables amount increased by c42% from c£132m to £187m.
Therefore, all things been equal, I would have expected a similar increase % wise in the amount past due. However, the amount past due has increased 7 fold.
It is also not impaired - I would have thought that IFRS9 would have something to say about that when it comes into force for them.
Cheers,
0inK
Hi onionking,
How interesting, thanks for posting that info about Conviviality (LON:CVR) (oops, I nearly forgot the ticker then, lol!)
I read the brilliant Langton Capital free email, focussed on the hospitality sector (highly recommended reading) every day, and they are reporting numerous problems in the casual dining sector. Hardly surprising, due to capacity expansion of, from memory, 30-40% in the last 10 years, colliding with (mainly payroll-related) cost increases, and soft consumer demand. Plus consumers are refusing to pay up, instead many are chasing promotions - 50% off food offers are now commonplace.
Byron Burgers is doing a CVA. There are loads of other casual dining operators who are seeing profits collapse, because they expanded too rapidly (often on Private Equity finance), and problems have now caught up with them. Apparently even good operators like Prezzo and Cote have debt problems.
It's the smaller independent restaurants who are also under severe pressure, and often have very weak balance sheets.
So I think Conviviality could end up with lots of bad debts. It would be key to find the breakdown of their wholesale business, and see where the risk lies. But a near-£250m debtor book, at least part of which is exposed to the casual dining sector, looks to me an accident waiting to happen. It wouldn't take much to wipe out profits entirely, if a few medium to large customers went under.
Regards, Paul.
Hi Paul,
Just out of interest, any other daily, weekly reads on your list.
I also skim fullermoney for general market every day and also monthly On Target by Martin Spring (global view).
Cheers (or Cheese if you prefer).
ps - Don't really want to hijack the main discussion, just asking and I guess if any others have a daily/weekly/monthly read list, it's worth sharing perhaps!
I don't agree with you view on Conviviality (LON:CVR) as busy fools. This is obviosuly in vogue as Carillion in on anybody's mind, but the drinks business is far off from construction, as Conviviality basically just applies a mark-up to all their drinks they sell.
Over the last few months, they took on more growth than they could chew and ended up having to hire temporary employees and trucks to deliver on them. So those addition £70m on sales yoy and basically same PBT means they took on those sales at no profit? Hardly. If you dig into drinks wholesale you will realise that rebates from suppliers (the Diageos and Beam / Suntory of the world)
make up 1/3 of earnings, and these come at the end of the year (H2 for Conviviality). With c.8% growth they will be juicy, and this is probably why they are still confident in making their FY numbers while many market participants are scratching their heads around it.
Bad debts could indeed be an issue if the UK goes into a recession, but not an issue at the moment. The receivables are mostly linked to the the large national accounts (Stonegate, Wadworth, JD Wetherspoon...) which represent 60% of Conviviality's sales and are obviously the ones that get to pay with very flexible terms not available to the small accounts. At the moment these guys are posting pretty solid single digit like for like growth so it will be fine. Not that this can't change if the UK goes into a recession, of course. And this is why I agree with you in that the company should ease up on dividend payments until the balance sheet is more solid.
Sorry entered in Error
STREE - HI Graham, you say 81% of the profits are based outside the UK , however in 2016 it fell off a cliff (down from 350 to 175 ish) when the IR35 law for the public sector was introduced by the UK government. With the same law now in Consultation for the private sector it will be interesting. Can you find out in 2016 what percentage of the business profits was UK based?
Yu (LON:YU.) please Graham
The company provides gas and electricity to small and medium-sized businesses throughout the UK, and has gone up over 200% over the last year. Positive trading update this morning “substantially ahead” of previous expectations. The company announced that operating profits will be ahead of market expectations too, despite increased investments in headcount and fixed costs.
analysts currently forecast revenue growth of around 50% for 2018, with the top line expected to hit £60.2m. Earnings are also expected to rise. But the stock isn't cheap, is it worth paying more for this?
Stockopedia sees it as a momentum trap however.
Hey Graham. Would love your views on Yu (LON:YU.) Very bullish trading update today. Thanks!
RNS from Altitude (LON:ALT) today with AIMPro on-boarding update. Any comments from Graham would be appreciated!
Hi ppdrs,
Altitude (LON:ALT) tends to put out quite frequent rampy updates, dangling the prospect of more jam tomorrow. However, the published accounts (so far) show no progress at all in the promised stellar revenue growth.
I tried out their software last year, and thought it was very basic. It didn't seem anything like what was promised.
Today's update is yet more jam tomorrow, about customers signing up to use Altitude's software, and quoting the turnover of the customers. We don't yet know how much of that will actually translate into revenues for Altitude.
This is an interesting company though. If its plans of being an online intermediary between Mom & Pop style promotional goods companies, and their customers, does succeed in the big USA market, then this share could have great potential.
For me though, it's been too much talk, and not enough action so far. Today's update fits that profile - it's not a trading update, so not valid for inclusion in these reports. Although Graham's writing today's report, so he can include anything he wants.
Regards, Paul.
We do have some indications; their investor presentation after the last interims (slide 13) indicated a 20% cut due to Altitude of the supplier's revenue, i.e. a $500 order placed via a distributor's website on the Altitude platform, on a gross profit margin of 60% means $300 due to the supplier, so Altitude's 20% cut would be $60.
Based on the distributor revenue figures quoted in today's RNS that implies $1.3m annual revenue to Altitude from the 7 partners already signed up and $5.3m from the 57 partners currently being onboarded, so that's $6.6m of annual revenues to Altitude.
For context, broker forecasts (per Stockopedia) are for £12m revenues for FY18, which would include revenue from the legacy promotions business, so their forecasts for revenue arising from the new platform are presumably much lower than that (say around £8m based on £4m of legacy revenues, I haven't seen the actual broker note).
In other words they may have already met their 2018 revenue forecasts just based on the partner sign ups announced today, and ignoring the 88 partners in the pipeline.
That's probably unlikely in reality given there are some sweeping assumptions in those numbers - not least of which is the assumption that 100% of those partners' revenues will be flowing through the Altitude platform (most unlikely I would have thought), and that the 60% gross margin for the partner applies across the board (sounds rather high to me given the nature of the product).
Of course you won't see any of that growth in the historic accounts for FY16 or even for FY17 which won't be released for a few more months yet, however the potential upside here is huge relative to forecasts, they just need to get some traction with partner and supplier signups, and in that context I actually found today's update quite encouraging even though I agree there is still a distinct whiff of jam tomorrow. Bear in mind it's not loss making thanks to the legacy business which just about pays the bills, so it's not as blue sky as some stocks out there.
Yu (LON:YU.) trading update please Graham
Hi Mike, I've covered Yu (LON:YU.)
Thanks for the suggestion. G
Would appreciate your views on Anpario (LON:ANP) Graham. Has delivered an inline update this morning, but SP has taken a hit. Seems a bit harsh to me, given its high Stockrank and performance over last two years. Thanks
Good morning Ted
Re. Anpario (LON:ANP)
Today's drop in the share price doesn't look like a big deal. Even after this drop the shares are up 17% year to date. This looks like a standard case of "Buy the rumour, sell the news". The market had already marked the shares up in expectation of (or rumour of) excellent results and now that the results are out there is no more short term upside to be expected. So they take their profits and move on. I don't hold but will look again after these results.
Hi ted/julian,
re: Anpario (LON:ANP)
I agree with the view that these shares had already risen greatly, and therefore may have been vulnerable to profit-taking. Also, they are on a very high earnings multiple, which can increase the volatility surrounding these updates.
It looks like a nice company. I frankly need to learn more about it to understand the products and the growth prospects and how they might justify the current market cap.
Thanks for the suggestion as always.
Graham
Conviviality marked down on what looked to be reasonable results. Any views please Graham?
Hi keith, I'm a long-term bear on Conviviality (LON:CVR) and have updated my views on it here now. Just my $0.02. Cheers.
A look at Seeing Machines (LON:SEE) would be ovely please Graham, also WANdisco (LON:WAND) - neither are trading updates but of interest, a new sales partner deal which makes me wish I hadn't stopped out of 2/3 of my holding last week! :-(
Defenx (LON:DFX) profit warning has led to a savage market reaction despite it being partly a repeat of an earlier warning. Trouble collecting debtors may be the reason. I'd welcome Graham's views .
re: Defenx (LON:DFX)
Hi FREng, the market cap on that is a bit too low for me, apologies! G
Indeed! Yet Defenx (LON:DFX) was well into SCVR territory six months ago. If the business survives it may yet be there again ...
I know it is a bit bluesky but I would be interested in your thoughts on ITM Graham. I happen to think the hydrogen economy is the way to go and they have been working away for a while to establish a position with some success although not necessarily pounds, shillings and pence!! Best wishes
Hi Camtab - I agree that ITM Power (LON:ITM) appears to be doing interesting stuff. But it appears to be static in terms of delivery over the past few years. There is talk in the outlook section of today's 1H results about being busier than ever and hopefully it translates into revenue. However, I would point out that trade & other receivables of £12.8m (which according to the FY2017 financial statements relate to prepayments and accrued income) dwarf the £1.7m of revenue generated in 1H.
Furthermore, there is a table showing cash burn to be £5m in 1H. If this is indicative of average cash burn, then it should have funds in place to operate for 2.5 years which should give it enough time to turn profitable.
Anyhow, I would be interested to know whether it has some unique product and there are high barriers to entry for the competition.
Thanks for your response gajri. I think we are in agreement. They didn't seem to have any problems with the recent cash raise so even with the 2 plus year cash supply I would be surprised if their existence came under pressure given the promise of the sector. However if technology improves upon what they offer there lies the real threat I would have thought. That said I do like their deal with Shell enabling them to use Shell forecourts. When there is a suitable network I believe people will buy hydrogen cars which are already being made and that distribution network should offer some barrier to entry. All the best.
RE ITM Power (LON:ITM) - Sorry for being so stupid but I'm still trying to work out where they make their money. I can see the big advantage of hydrogen over all electric (fill up in 3 minutes vs recharge in 1 hour but there needs to be a lot more outlets across the country so that car buyers feel confidenmt they will be able to fill up wherever they are. Can someone tell me how their deal with Shell works? Do they simply sell their units to Shell and then maintain them or do they rent/lease space on Shell forecourts, install their plants and then make money dependent on how much hydrogen is sold?
RE ITM Power (LON:ITM) (LON:ITM) - Hydrogen will never be a mass market fuel. See http://www.withouthotair.com/
Re ITM Power (LON:ITM)
Thanks for the link, in spite of its title there is a lot of hot air in the book. Where exactly does it mention hydrogen powered cars?
A hydrogen oxygen fuel cell powered electric vehicle seems ideal solution to lack of range of battery power.
The crux of the matter is the huge amount of energy required to create hydrogen for use as a fuel. Far more than direct storage of electricity in batteries. Building the generating capacity for a fleet of electric vehicles will be a challenge, building sufficient generating capacity for creating hydrogen for those same vehicles is totally impractical. The book looks at the fundamental numbers for various strategies of energy generation and use. It is worth reading.
Mentioned in numerous places in the text. One useful page is https://www.withouthotair.com/c20/page_139.shtml which links to references. Also see https://www.withouthotair.com/c20/page_130.shtml which mentions:
"In the CUTE (Clean Urban Transport for Europe) project, which
was intended to demonstrate the feasibility and reliability of fuelcell
buses and hydrogen technology, fuelling the hydrogen buses required
between 80% and 200% more energy than the baseline diesel
bus.
Fuelling the Hydrogen 7, the hydrogen-powered car made by BMW,
requires 254 kWh per 100 km – 220% more energy than an average
European car."
Thanks for the link re ITM Power (LON:ITM) but that document seems to be over 10 years old. Hasn't the science moved on a lot since then? The "book" makes a big play of saying that fuelling a car with hydrogen is no cheaper than diesel and therefore should be discounted. But surely, it's not just the cost that is going to drive the change. It's all about the environment and reducing reliance on fossil fuels.
Maybe I've got it wrong, but a good deal of ITM's pitch seems to be about using solar to power the hydrogen production.
I don't think you are being stupid at all. Although I am thinking I might be a bit stupid for investing in a stock because I believe in what it does. I cannot tell you much about the deal with Shell, but I do know they make some money by supplying the fuel. They have signed various contracts with various companies one example is Toyota. You can find details under the news tab.They have also signed deals with some bus companies. This is one aspect which as you point out doesn't provide much income now but as demand grows (which I hope it will)...... They have also a business incorporating hydrogen systems into companies as an alternative fuel option which has seen an increase in demand. Then there is a scheme they have tested and seems to work well with a German municipality called Thuga where they seem to be able store renewable energy in the gas system via hydrogen. I am no expert but this is my interpretation. DYOR, it is still in the punt section of my portfolio.
Hi Camtab, nice suggestion. I've covered ITM Power (LON:ITM) before. Once again, it appears to be on the verge of significant revenues. As you suggest, it is still a bit "blue-sky" for me. Happy to listen to any arguments for or against it. Thanks. G
To be honest Graham I requested it purely as a left fielder. It is a subject I find interesting and I believe we should do everything we can to help future generations so it fits nicely into the happy clappy part of my portfolio. Backed by a lot of blue sky and hope. Paul would be proud it is only a small part of my portfolio.
I do get a bit fed up though of people poo pooing things with little knowledge. The link attached above is so out of date.....
Re ITM Power (LON:ITM) again - well, I'm with you Camtab. Although I don't own any of these shares I just have a feeling that I should (a) because I like driving but feel we should reduce reliance on fossil fuels and (b) because I feel that this could end up a better bet than pure electric vehicles if for no other reason than the time needed for refueling/recharging.
Here's a more recent link with a more positive outlook - http://www.autoexpress.co.uk/car-news/electric-cars/93180/hydrogen-fuel-cell-do-hydrogen-cars-have-a-future
And another - for those interested - http://www.nextgreencar.com/fuelcellcars/
I wonder if ITM Power (LON:ITM) will be the beneficiary of some of the larger corporates, especially in the traditional fossil fuel sector, seeking to enhance their green credentials by associating with the company either as a customer or in some form of JV? A few crumbs from the rich man's table of the likes of Royal Dutch Shell (LON:RDSA) or BP (LON:BP.) would go a long way to filling up ITM Power (LON:ITM) 's order book even if on a stand alone basis they are uneconomic at the moment.
Gus.
ITM Power (LON:ITM)
Much more to producing hydrogen than at first meets the eye, however, science moves on.
The recent RNS announcing a joint venture with Shell describes a 10 MW industrial implementation of proton exchange membrane electrolysis.
“Shell and ITM Power will build the world's largest hydrogen electrolysis plant at Rhineland refinery, Germany. With a peak capacity of 10 megawatts the hydrogen will be used for the processing and upgrading of products at the refinery's Wesseling site as well as testing the technology and exploring application in other sectors.”
This is to supplement hydrogen produced from steam and which is used in the conversion of heavy oils into lighter refined fuels. I would assume that waste heat from the refining is used to partly power the hydrolysis. The electricity coming from over supply in the grid.
This pilot project falls short of producing vast quantities of hydrogen necessary for replacing fossil fuels in cars although it's interesting that it is a way of stabilising the supply and demand on the electricity grid, (one of the shortcomings of renewable power) and in doing so creates hydrogen using electricity which would not otherwise be used or stored.
https://en.wikipedia.org/wiki/Polymer_electrolyte_membrane_electrolysis
It may not replace all petrol and diesel use but every contribution to fossil fuel consumption will be worthwhile.
Hi Graham
There is a certain irony in that on the day that Inspired Energy (LON:INSE) announces a positive set of numbers and confident outlook for 2018, Utilitywise (LON:UTW) has requested the suspension of its shares whilst it sorts out it revenue recognition policy. 2 companies doing broadly similar work but with historically vastly differing approaches to revenue recognition. The former always recognised the contract over the life of the contract (typically 2-3 years), and thus whilst the sector may not appeal to all, it had excellent earnings visibility. Contract this with Utilitywise (LON:UTW), who used to account for the majority of the revenue on day 1 based on an expectation of future usage.
It feels like a modern day hare and tortoise. I’ve held Inspired Energy (LON:INSE) for a few years and they have performed steadily, though not spectacularly. The revenue recognition at Utilitywise (LON:UTW) always put me off, even when the share was flying.
Hi phoenixnight, thanks for the comment. Bit of a horror show at Utilitywise (LON:UTW), indeed. G
My morning smallcap tweet:
Sopheon (LON:SPE), Immedia (LON:IME), Colefax (LON:CFX), Nasstar (LON:NASA), Yu (LON:YU.), Seeing Machines (LON:SEE), Utilitywise (LON:UTW)
Sopheon (SPE) guides FY rev over $28m ($23m), comfortably ahead of market expectations. Also EBITDA and pre-tax significantly ahead of current market expectations.
Immedia Group (IME) FY trading - order delays and slower than anticipated financial performance of AVC Immedia causes increased loss before tax. Guides -£600k (-£184k).
Colefax Group (CFX) H1 pretax up up 35%. Expects the Decorating Division to exceed its original expectations for FY, but it is only contributing 12% of group profits.
Nasstar (NASA) guides FY adj EBITDA slightly ahead of management expectation.
Yu Group (YU.) guides FY rev significantly ahead of current market forecasts. "The Group has elected to make additional investment in headcount and fixed costs. However, the Board is confident that the Group will report operating profits ahead of current market expectations."
Seeing Machines (SEE) CEO resigns, immed effect (I think). SEE wishes him well so not sacked?
Utilitywise (UTW) suspended - FY accounts not ready "due to the volume of work still required to be completed by the Company and its auditor to cater for the proposed change in the Company's revenue recognition policy...delay is not related to the Company's banking arrangements, nor the trading, cash flows or other underlying economic position of Utilitywise in either FY17 or the current financial year."
Nice trading update on the recent Jan 4 update from specialist software and services provider Sopheon (LON:SPE) .
https://www.investegate.co.uk/sopheon-plc--spe-/rns/trading-update/201801290700041235D/
Not sure if the “ahead of expectations” statement is simply confirming what they said on Jan 4 (which spiked up the share price) or a further increase since then.
Also, as anticipated, Utilitywise (LON:UTW) shares are temporarily suspended having failed to complete their accounts in time for the AIM deadline. RNS seeks to allay any fears its no more than a delay in due process but embarrassing at the very least.
Gus.
Hi gus, I covered Sopheon (LON:SPE). Interesting company. Cheers. G