Small Cap Value Report (Thur 27 Sep 2018) - VLE, BON, MOGP, ZOO, FISH, IGG

Good morning!
A huge pile of news today. The impact on my own portfolio has been a small net positive: Volvere (LON:VLE) shares are up, while IG Group (LON:IGG) shares are down after the CEO stepped down.
Final list:
- Volvere (LON:VLE)
- Bonmarche Holdings (LON:BON)
- Mountfield (LON:MOGP)
- Zoo Digital (LON:ZOO)
- Fishing Republic (LON:FISH)
- IG Group (LON:IGG)
Volvere (LON:VLE)
- Share price: 960p (+8%)
- No. of shares: 3.7 million
- Market cap: £36 million
(Please note that I currently hold VLE shares.)
This is the largest position in my portfolio again.
As a refresher, this is the investment vehicle that finds companies in need of some restructuring. Typically, their bank debt has become too large. Volvere comes in and replaces the bank with a majority equity stake.
It has compounded NAV at a double digit percentage rate for many years. I'm a relative newcomer, only owning it since May 2016 (you can find my original write-up here).
Today's interim results are about as good as I could have reasonably hoped for. The company's key subsidiaries, of which there are only two, have both improved compared to last year.
- Impetus Automotive (website)
These are consultants to the automotive industry - clue in the name!
I wouldn't normally want to own shares in a company like this, as revenues are quite lumpy and contract-driven. However, I don't mind owning it within Volvere's portfolio, as Volvere was able to buy it at a very favourable price. It's also just a small part of the overall NAV.
Impetus revenues are up 21% to £14.8 million and PBT up 31% to £1.9 million (before intra-group charges), after picking up new business.
The statement is cautious about making further growth in the short-term, on the basis of uncertainty in the sector at the moment (including Brexit-related uncertainty).
That's ok - Impetus doesn't owe us anything. Performance has been superb! If it merely carries on at the current rate of profitability, it will be a fine result.
- Shire Foods (website)
Formerly the most profitable part of Volvere, this had been deteriorating for a few years. It makes frozen pies and pasties in Leamington Spa.
Revenues are up 15% to £7.25 million. The H1 loss reduces marginally to £170k.
Volvere attributes the difficulties at Shire to factory wages increasing and Sterling depreciation.
To counteract this, capex of nearly £1 million is planned to improve margins, grow capacity and develop new products.
It would be wonderful to see this return to growth. It's too soon to say whether that's possible but I do trust the Volvere directors to allocate capital in a prudent way (they own about 38% of the company, so they are certainly incentivised!)
For many companies of this size, capex of £1 million would be a matter of routine. For Volvere, on the other hand, £1 million of capex in Shire means £1 million that can't be spent investing in Impetus or acquiring some other more profitable business. I think VLE shareholders have a big advantage merely from the thoughtfulness which the directors bring to their capital allocation decisions.
Volvere's third subsidiary is too small to move the needle.
Future deals - as an opportunistic investor, Volvere stands ready to buy good businesses at the moment when they are most in need of refinancing.
In H1, the managers "did not identify any opportunities which we deemed worthy of investments", but they think there could be deal opportunities if the economy goes through a period of stress:
Volvere may perhaps, on balance, be one of the very few businesses to benefit from Brexit-led distress, provided it does not endure too long. We will of course assess any opportunities as they arise.
Did I mention the cash pile? At period-end, Volvere was sitting on a pile of cash and financial investments worth £20.4 million.
PBT for the Group as a whole in H1 was £1.3 million, or I estimate around £1.6 million if you focus only on Volvere's stake in Impetus (Volvere owns 83% of it).
With the Volvere enterprise value at c. £16 million, we are left with an implied mid-single-digit earnings multiple against Impetus earnings.
So I think that even if we assume Shire is worthless, Volvere's latest market cap is not very ambitious.
I doubt that Shire is worthless, and I also think that value is likely to be created by future deals (the directors have been creating value inside this vehicle since 2002). So I'm holding on!
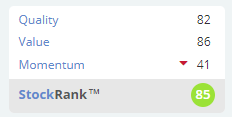
The algorithms can also see some attractive characteristics:
Bonmarche Holdings (LON:BON)
- Share price: 83.5p (-19%)
- No. of shares: 50 million
- Market cap: £42 million
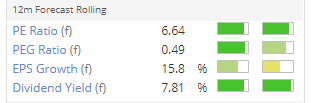
This women's fashion retailer was cheap already, before today's share price fall:
Today we have a sales warning: store sales are below expectations in Q2, after an improved Q1.
The weather is mentioned but only in passing. Bonmarche admits that the main problem is with "underlying consumer demand for the UK high street" and low footfall.
Outlook - underlying PBT for FY 2019 is now expected to be £5.5 million, versus £8 million in FY 2018.
I can see an existing FY 2019 PBT forecast for £9.2 million, so the updated forecast represents a very large percentage reduction.
Balance sheet - strong, with a forecast to have net cash of £4 million at the low point this year.
Dividend - to be maintained. It sounds as if the company will be paying out the majority of earnings this year as dividends. Quite a brave decision! I guess the balance sheet allows it to do that.
CEO comment - this leaves me scratching my head:
"Whilst it is disappointing that FY19's result is expected to be lower than originally planned, despite the challenging market, the health of the business remains strong: excluding the impact of the FX headwind, this year's underlying PBT expectation would be in line with the £8.0m achieved in FY18.
The first part of the update said that lower footfall had resulted in lower sales, and then this sentence says that profitability would have been unchanged without an FX headwind.
I think this needs a bit of clarification, to unpick how much damage can be attributed to each of these factors.
My view
In summary, the company is still profitable, is cheap on conventional metrics, but is suffering from store sales falling too quickly. The hope is that online sales continue to grow well, and at some point could be able to match the weakness in store sales.
I don't feel the need to take the risk with this share, as I already own Next (LON:NXT) and don't think there's anything better out there in terms of getting the combination of a strong online offering and a carefully managed decline in store sales, with a proactive plan to shut down stores as they become unprofitable.
I've just scrolled back to have a look at Bonmarche's most recent full-year results, and I see that the company forecast that its number of stores (325) would stay broadly flat for the foreseeable future.
Perhaps there is more detail which I've missed, but this forecast sounds complacent to me. I'd be a lot more comfortable with an active plan to reduce the portfolio as sites become increasingly unprofitable, due to the shift online. That seems like the obvious thing to do.
In summary, I won't be buying these shares as I don't need or want any more retail exposure. It could be worth a look, as a contrarian play.
Mountfield (LON:MOGP)
- Share price: 1.95p (+2.6%)
- No. of shares: 254 million
- Market cap: £5 million
This is a new one for me. We had a few reader requests so I'm happy to take a look!
It consists of three businesses that provide:
- data centre installation
- building work, employing skilled labour and subcontractors
- flooring installation
The highlights are very encouraging.
- H1 turnover up 56% to £8.9 million
- H1 PBT more than doubles to £700k
- Orders higher compared to those held at the same stage a year ago.
Drilling into the segmental analysis, the big win was in construction which went from breakeven last year to a PBT of about £450k this year, on greatly improved revenues.
The balance sheet has negative tangible net worth and a large build-up of receivables, and is partially funded by borrowings. So not too pretty.
My view - I imagine that these shares could easily re-rate higher when people have digested the earnings that are likely to be achieved in full-year 2018 and possibly in 2019. On current trends, it's probably going to look very cheap in comparison to a £5 million market cap.
While it may have individual merits, it's not for me simply because this is not a sector I want to get involved with.
Incidentally, I wonder what the long-term trend for the number of data centres is likely to be. Will they grow with demand, but then eventually shrink as less space is needed to store the same amount of data?
Zoo Digital (LON:ZOO)
- Share price: 134.5p (-21%)
- No. of shares: 74 million
- Market cap: £100 million
A serious percentage share price fall for an AGM statement. Long-term holders are still sitting on hefty gains:
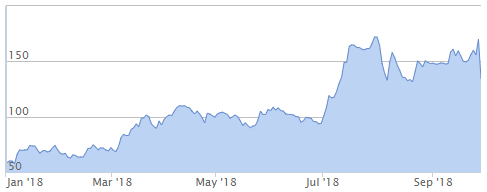
Let's see what it says:
- H1 revenues up 17%
- full year performance in line with expectations
I'm looking for the bit that has provoked the sell-off. Maybe this is it:
Disruption has been experienced by us and other market participants in the subtitling supply chain during the transition of a major OTT operator's partner programmes, but this is easing, and we are seeing normal operations increasingly restored.
An OTT operator would be the likes of Netflix and Apple TV.
According to our report on Zoo's final results, Zoo's top two customers accounted for 59% of sales. Is the market reacting to the danger of some kind of structural shift in how one of its top clients manages its subtitling?
We should also bear in mind that ZOO shareholders have enjoyed massive growth in turnover over the last two years, and the P/E ratio raced up to massive levels:
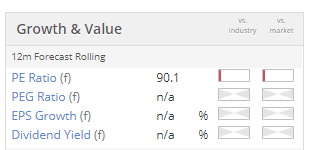
H1 revenue growth of "only" 17%, even if it is technically in line with expectations, might not be what some shareholders were actually expecting. So that could be enough to explain the sell-off, given the high valuation.
I like the company, but it remains far beyond the levels where I would be willing to buy it.
Fishing Republic (LON:FISH)
- Share price: 4.65p (-17%)
- No. of shares: 52 million
- Market cap: £2.4 million
This is a rather sad market cap, given how much attention the company has received.
Lowlights:
- adjusted EBITDA loss of £1.4 million
- statutory loss of £2.5 million
- like-for-like store sales minus 22%, online sales down too
- gross margins down: too much stock and a competitive environment
Outlook - sales affected by competitive pressures, especially online. The new CEO shares the board's vision for the group to be a multi-channel retailer.
My view - the market cap seems about right to me, pricing it at a discount to book value. The business is clearly uncompetitive. Its new e-commerce website offers some hope, but it will be a big achievement if the group can make breakeven.
The stock market listing makes little sense now and I would view this as a delisting risk.
IG Group (LON:IGG)
- Share price: 648.75p (-12%)
- No. of shares: 369 million
- Market cap: £2,393 million
(Please note that I currently hold IGG shares.)
Finally, a quick note on IG. It's not particularly relevant to a small-cap report but I've mentioned the company before and had some requests on it. The CEO has stepped down.
It's an abrupt change, and a disappointing one for shareholders. What makes it worse is the lack of an explanation. All it says is that he is stepping down with immediate effect, without explaining why. So did he jump or was he pushed?
If I had to guess what had happened, I would speculate that there was some kind of boardroom disagreement, maybe a clash over strategy. There is no obvious reason for him to step down after three years in the role. As far as I could tell, he had performed fine.
It has been a difficult period as the company's business model has been threatened by ESMA regulations.
Separately to the impact of regulations, we've also had a couple of weak months of trading, both at IG and at its rival CMC Markets (LON:CMCX), which issued a warning the other day.
So in these difficult times, perhaps there was a falling-out over how to react to the company's challenges.
Today's statement says that the Board is "well advanced with its search for a new CEO", and the CFO will take the job on an interim basis.
The market is rightfully worried that the outgoing CEO might have got his forecasts wrong, that things could turn out to be much worse than he expected, and that is the real reason for his departure. That's certainly a risk.
From my perspective, I like the underlying characteristics of IG (cash generation, return on capital, etc.) to such an extent that I don't mind holding it through a period of reduced revenues.
The main thing I'm worrying about is that ESMA decides at some point that it hasn't regulated the sector enough. Could it make the regulations more onerous? Could it even go for an outright ban on leveraged trading by individuals?
I'm confident (or should I say hopeful) that the UK wouldn't stand for a ban on leveraged trading by individuals, or for more onerous regulations, especially in a post-Brexit scenario where ESMA's views should be less relevant.
So while there is a general risk hanging over the EU business, the UK business should be ok. And there are other international growth opportunities.
Putting it all together, I expect that IG will get through this. But the Board really needs to come into its own now and find a great new CEO who will be in the role for years to come.
Calling it a day there, thanks everyone for your input.
Best,
Graham
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

43 comments
I was out all day today at a training course, so missed the excitement of several of my "holdings" getting a bit frisky.
Like Graham I was up on the day despite one disappointment.
I my case the disappointment was Bonmarche Holdings (LON:BON)
Yes yes , I did say very recently that I could not see the need to hold ANY discretionary retail stocks this side of Christmas! That'll teach me not to allow myself to break the rules in search of contrarian value. Erm, except that it won't as I've decided to compound the error by holding after a profits warning.
I certainly agree that the phraseology of the profits warning is odd.
My interpretation (call it a guess if you wish as they have really done a poor job in communicating this) is that if store sales had not collapsed they could have covered the "forex headwind". So I think the comment that "excluding the impact of the FX headwind, this year's underlying PBT expectation would be in line with the £8.0m achieved in FY18." is meant to convey the message that although our forecasts are much lower than two months ago, it is not a disaster.
They also tell us that "Due to a required change to the established interpretation of IAS36" they have to take a (purely procedural) £1m hit by way of a "provision for impairment of store fixed assets".
(I wanted to have a long rant here about the term "provision for impairment", but instead I'll leave readers to form their own opinions of what that means.)
Either way the reduction in profit forecast is huge based on only 2 months passing, especially given that we/they still have little visibility of the all important Christmas trading period.
By holding here I am essentially taking a bit of a punt (based on some of the supporting commentary) that in this forecast revision they have 'kitchen-sinked' a poor Christmas in advance.
Crazy speculation aside, there were a couple of valid questions raised that maybe I can give some insight into :
Someone asked why they didn't hedge the FX risk. My thought would be that whilst Forex hedges reduce volatility, they cost significant amounts of money - if you have a sound (and liquid) balance sheet as they appear to have, then perhaps the rational position (in the long term) is to let the forex waves wash over you.
Also Graham questioned why the number of stores is forecast to stay broadly flat.
Reading through the strategy ( as outlined in the last FY results) they do regard the stores as an important part of their overall proposition, but they retain flexibility on this point :
"our average store lease had only 3.5 years remaining. This affords flexibility in the event that changing shopping patterns dictate a significant shift in the nature of the store portfolio. It also helps ensure that the rents are at market levels."
In fact : "Overall LFL store rent deflation was 0.3%"
I am tending these days to do less of this in depth digging into individual companies as selectively following "the factors" seems much more fertile ground. But I am convincing myself here that there are hidden positives and that this is a valid contrarian play.
As always though - No advice intended. I offer this up more than anything to hear other views from the collective Stocko mind pool.
Similar performance for me with Bonmarche Holdings (LON:BON) hurting.
I don't intend to sell on this warning - considered adding after today but will see how price plays and the Divi gets reinvested. I would consider adding at better value. At full year 4m they would be 9x ex cash - which I find expensive given the operating trends.
However at the moment some 10% of sales are online, growing 20-30%, about 20m per 2018. We could say that could be 25m this year. Assuming the valuation of other online retailers, say 4x sales (lower Roce), we could end up at 100m valuation. The cost of entirely exiting the store estate as I understand is around 50m (15m / year).
The profit forecast miss was big no doubt. Re the hedging, they do hedge. They also guided in their full year results that they screwed up their hedging strategy and expected higher costs as those unwound.
The return on capital is still healthy although going in the wrong direction. Their reviews on trustpilot are very strong (one which said this should cover everyone from 40-90). And while store numbers are flat overall, they're opening and closing and as noted by Gromley and leo, the stores are used to help the online offering.
Value for me comes from:
Valuation and covered dividend
A growing demographic
Online growing and becoming meaningful to sales
FX impact ought to be a one off
Good ROCE
Think Helen Connolly is strong - like that she does not massage - would expect most CEOs would have struck FX as non-underlying
The reasons I would need better valuation:
Declining retail could mean that this doesn't have time to play out but the balance sheet gives them time
Declining store lfls suggest store refurb / store location strategy is not paying off and costing cash - which could be spent on marketing / investment in online / shareholders!
I'm deluded and waiting for a cheaper price might reveal said delusional tendency!
Thanks for reading - I really can't sleep!
Volvere sounds interesting, sounds like just my cup of tea. I'm currently researching
One quick observation, the Shire Foods website could sure do with some work
Volvere (LON:VLE) is pretty illiquid and the spread is around 6%, if things do go wrong then I would expect the spread to widen. I bought in after the good results but it has been a steady drift down. I'm hoping this report will lift the shares back to £10 and then I can get out.
Herbie47, you need to have a longer time frame and a little patience. This is not a share for traders or short-termers.
Over time VLE's share price has gone from 100p to 930p. At some stage VLE will sell either Shire or Impetus, at which point the share price will likely be catapulted upwards as it has been on all prior disposals.
Either that, or Simon Thompson will once again at some point soon note the huge discount to core NAV which exists, and once again the world will wake up to VLE.
The spread sometimes closes to only 10p-20p and is sometimes larger, as it is today. But already today around £180,000 of shares have been traded. Unless you have a very large holding, trading say £5k-£15k shouldn't now be a problem.
The spread is quite wide even considering the volume traded today. Liquidity is ok today but on a bad day things will be different. Yes it maybe too long time scale for me, I don't want to be in many illiquid stocks over the next 2 years.
I am put off Volvere (LON:VLE) by the fact that they only have three investments made, one of which is minute too. I guess it's great they have that cash sitting there... but is it going to enable them to substantially increase their divestment? I am not convinced. I prefer the likes of Draper Esprit (LON:GROW) and £3IN which have a much bigger spread of investments.
Thanks for the review of Volvere (LON:VLE) Graham. If I may pick up a couple of points.....
Firstly as regards Impetus, I hope you noticed that VLE announced today that "We have been notably successful in winning new business in providing training services and recently won a second contract with another large automotive manufacturer. " So, in their usual prudent fashion, I suspect what VLE are saying is that although Impetus' growth may not be quite as spectacular as to date, it's still likely to continue in pretty decent style.
Secondly as regards Shire Foods, it's incorrect to say that it "has been unprofitable for a few years now". Last year Shire made £0.6m PBT and the previous year £1.2m PBT before intra-group charges.
You may be unaware that H1 is much seasonally weaker for Shire, and that H2 is always much stronger given the cold weather (and demand for pies etc!), which explains the losses which always occur in H1.
Finally, it's worth noting that Shire owns £2.55m of freehold property and £millions more of plant and equipment. Any sale of Shire would take these into account (to whatever extent) in calculating an acquisition price, and of course in the meantime it also acts as a tangible asset base to add to VLE's £20m+ cash pile against the £34m m/cap.
re: Volvere (LON:VLE)
Hi rivaldo. You are correct. Shire has been generally deteriorating since around 2015 and has been unprofitable or around breakeven in H1 since 2016. Yes, it does have a better H2.
Yes, I'm aware of the freehold property, and thank you for mentioning it. One of the reasons I doubt that Shire is worthless is due to the asset base. Hopefully the Lander brothers will find success with this £1 million capex investment and it will prove to be worth quite a lot!
It feels like ages since they had a deal, doesn't it?
Appreciate your contributions on the boards.
G
PS, I edited the wording of the article so it's more accurate. Thanks. G
I have sold out of my position in BON today - agreeing with many of the negative points raised above. In addition, I did not like the repeated emphasis in the statement about the positive trend on online sales. While important, it is still a few years away before his is big enough to really move the needle. It is the decline in physical stores which needs addressing. Helen Connolly seems to be doing a good job but maybe she has run out of low hanging fruit to pick up from correcting previous mistakes.
Another vote for IG Group (LON:IGG) if you have time. It's my largest holding and kicking myself on not taking profits, if only I had a magic ball.
Adept Telecom (LON:ADT) please Graham - AGM looks good and although it's not exactly flush with numbers I find that they are already proposing a 15+% increase in dividend rather reassuring. The Stocko page looks lovely to me, a PEG of only 0.6, and a big rise in broker forecasts after the last results.
I agree that their statement this morning is very positive. It looks as though recent acquisitions are working well and they're confident for the coming year. Not expensive compared to growth forecasts either.
It's all very well clothes retailers blaming the weather for poor sales, but if they actually stocked summer clothes in the summer then maybe they would do more business. In the middle of the heatwave I went shopping for some holiday t-shirts and shorts only to be confronted by a shop full of winter coats, jumpers and hoodies. Needless to say I left empty handed, money in pocket.
We face the same problem every year - with growing children we normally have to buy them new stuff every year, Unless we get it in June or the start of July at the latest then it's a job to get anything. Retailers are always getting the next seasons clothes in far too early.
af20001 - I've always wondered that as well. My wife usually tells me I need to go holiday clothes shopping around May "before they run out" :)
If they all do it there must be a reason for it, fashion changing so fast and not wanting to be left with stuff they can't flog.
The seasonality issue is another advantage for online because the are not space constrained in what they can display.
I made one of my very few visits to a physical clothes shop to Uniqlo on Oxford Street at the end of August looking for a polo shirt. The assistant told me they had none as it was now winter season. They had dozens of them on their website, some at sale prices. So another purchase goes online.
The thing that occurred to me was that it may not be the season anymore in England, but it is somewhere in the world and it's a very international, travelling set of customers on Oxford Street so being parochial in what they stock makes even less sense there.
noted another significant drop in IG Group (LON:IGG) today and the CEO's departure announcement: I used to hold but took profits before the recent double top at 950p
.
Given CMC Markets (LON:CMCX) and Plus500 (LON:PLUS) are all showing similar price action, are these collectively showing a structural change in this sector as tighter regulation and scrutiny are starting to bite?
Is the IG Group (LON:IGG) CEO departure a prescient move?
ESMA regulations on leverage seem to be hitting profits.. is it possible we go the way of the US and ban CFDs?
Interested in your views G as I know it is a conviction holding of yours
Re Bonmarche Holdings (LON:BON) - despite being a positive, contrarian buyer of retail on a case by case basis, and impressed with what the CEO Helen Connolly has tried to do since coming in, I cannot get behind Bonmarche.
A latecomer to the internet, the chain's revenue base is sales in retail stores to poor, old ladies. So it did well in the heatwave of Q1 (when old ladies come out) but not in Q2's normal British summer. Every year, warm, home shopping aka the internet becomes more comfortable for the middle aged and up. I am not ready to be on good British weather defeating that dynamic.
In the current Darwinian retail environment, weak store led-chains and brands like Bonmarche need to and will die. Cash pile and the cleansing re-birth from Peacocks administration will mean it will take time in Bonmarche's case.
But consider this thought experiment : if Bonmarche disappeared who would bring it back (again). What does it sell that's not available more cheaply online (or in Asda if we have to go to a store).
Stockrank value is probably going higher than ever after this fall but Bonmarche is not investable for me.
I agree pretty much with your summary about Bonmarche Holdings (LON:BON)......and am really kicking myself for buying into it. But I have a learning question: I was over-influenced by the good stock ranks. I understand why the value score is so high but I am struggling to see how a business that has been performing poorly for the last two years gets such a high quality score. Can someone explain?
My question too. I'm very much a novice here, and while all the indicators show it as a good bet the share price performance does not!
Re Bonmarche Holdings (LON:BON), the Quality Score is based on multiple components, some of which reflect five-year averages:
Hi Graham, Zoo Digital (LON:ZOO) would be interesting. a 20% drop following an inline update. Obviously expectations are/were very high but dubbing, the big driver going forward, seems to be going well "dubbing service is pleasing and, at approximately three times above our expectation for this stage of the financial year" although there seems to have been a problem with subtitling. The other possible reason might be:
"We expect to report revenues in the first half of the financial year at least 17% higher than the same period last year, and we are confident in the prospects for a strong second half. Accordingly, we anticipate overall full year performance will be in line with expectations." whereas holders were expecting much more.
I hold.
Re: IG Group (LON:IGG)
I think the worry amongst other things is that normally a CEO standing down with 'immediate effect' is a signal of something untoward e.g. a board revolt, a personal calamity etc. but the announcement uses emollient language but doesn't state why the exit is immediate, necessitating an interim Director having to take over, pending appointment of a new exec. It doesn't seem very smooth assuming his departure was on the cards for a while.
Hi Graham. I know you are a holder so would be interested in your view on the IG Group (LON:IGG) CEO stepping down. The market has not reacted well to it and I guess the timing couldn't have been worse with investors already feeling nervous after their recent quarterly update. Would you consider this to be a buying opportunity or is your faith in the firm now being tested?
I also hold this share - it has been a painful few weeks for me. It seems every day one of my stocks has a 4-10% fall!
Bear in mind that IG Group (LON:IGG) went ex-div today by 33p, so the fall is not quite as bad as it first seems.
Bonmarche Holdings (LON:BON)
Don't know what to make of this mornings announcement. In the main body of the text the prime culprit is:-
"During the second quarter of the financial year, online sales have continued to grow strongly, in line with expectations, but sales in the stores have not maintained the momentum gained during Q1, and are below expectations. The continuation of warm weather for an extended period may have delayed demand for early autumn stock, but we believe that the more dominant factor is that underlying consumer demand for the UK high street is weaker which is impacting footfall."
Then in the CEO's comments:-
"Whilst it is disappointing that FY19's result is expected to be lower than originally planned, despite the challenging market, the health of the business remains strong: excluding the impact of the FX headwind, this year's underlying PBT expectation would be in line with the £8.0m achieved in FY18."
So she is suggesting all the profit downturn of £2.5m is due to FX and presumably the remaining reduction against expectations is due to footfall. Could have been explained a lot better + I'd like a explanation of the £2.5m FX - its pretty easy to hedge these days.
I presume this is why the SP is only down about 20% on a major profit warning.
Phil
As I noted, it was 116p at the beginning of the month, so one interpretation is that it is actually down circa 30% on the reduced expectations. Still, that's not as much as the profits miss and not enough to get me adding.
As to the argument that "If it didn't exist, we wouldn't have to invent it", there are two answers. Firstly, it does exist and has significant cash, tangible assets, few liabilities and significant goodwill not shown on the balance sheet. It does have a positive value, it is just a matter of what.
The second argument is that, if the store I braved is any indication, it absolutely does have a niche. The in-store environment I saw was far far superior to a supermarket. It was also superior to the local M&S, Debenhams and Primark plus also had a differentiated smaller "boutique" type feel. I'd be interested in reports from other stores, maybe the Coventry one is atypical?
I would certainly agree that there is little scope for structural growth in store numbers or revenues.
Also Koovs (LON:KOOV) - director buys at 15p from August I believe (current price about 13.2p). Not quite sure how I missed that RNS this morning, but I'm guessing those who got in first thing may be flipping around now, as L2 is evens.
Volvere - look good to me, they have signed Lexus/Toyota and Suzuki ( see Impetus Site), the VW contract would have given them another 10% revenue growth but actually they are 20% ahead. Also, Shire Foods Revenue growth is strong although gross margins are still under pressure. Natural caution re Brexit and Auto but no more cautious than at the finals. Looks like Impetus will make north of £4m, so with cash + investments of £20m Vs market cap of £33m - difficult not to conclude that this is a cheap stock.
Hi Graham
IG’s announcement about Peter Hetherington’s departure; the share has taken a bit of a beating in the last couple of days. Are you still keeping faith and do you see this as a buying opportunity?
There is a broader question here of whether you should view these type of announcements as an opportunity or a threat. It would be interested to hear your thoughts.
Kind Regards
Emmett
Hi Emmett, I've been weighing up the IG Group (LON:IGG) decision this morning. It's not really suitable material for this report, however. I have been thinking about buying more. G
I can't believe other people are also interested in Mountfield (LON:MOGP). Excellent value if results can be maintained. Activity in construction sector seems strong despite brexit fears.
As you're a holder too, I hope you have time to cover the Volvere (LON:VLE) half-year report today.
Highlights:
PBT: £1.28m (£0.76m)
Net Assets per share: £6.75 (£6.23)
Cash: £20.4m (£20.5m) after £3.4m share buyback
Possible positive opportunity due to 'the B word':
"Volvere may perhaps, on balance, be one of the very few businesses to benefit from Brexit-led distress, provided it does not endure too long."
I've held for over 8 years, and looks like a >12% CAGR over that period. Volvere (LON:VLE) is my 2nd largest holding.
Modern Water (LON:MWG) plans a new plant in China to purify landfill runoff. *Homer SImpson voice* 'Mmm, bin juice...'
Beeks Financial Cloud (LON:BKS) loses its CFO who did A-Ok with the IPO. I know Paul holds, I'd just started researching, was this planned, and was that recent pullback this leaking or his shares leaving the building??
Graham's favourite Volere seems to be doing well, profits up about 50% (?) but warns on outlook. I won't be buying automotive with EV sales at 6% and growing.
My morning smallcap tweet: BON turns bad again.
Eservglobal (LON:ESG), Midatech Pharma (LON:MTPH), Bonmarche Holdings (LON:BON), Zinc Media (LON:ZIN), Impellam (LON:IPEL)
eServGlobal (ESG) Placing at 6.25p, a 4% premium but SP was 7.5p 2 weeks ago so crystal balls being rubbed perhaps. Cash needed "to fund the Company's share of an expected capital raise by the HomeSend JV and to help position the core eServGlobal business for sale." The core business is anticipated to return to growth this year...discussions with a small number of interested parties regarding the sale of the core business, with an update expected to the market within eight weeks."
Midatech Pharma (MTPH) Proposed Sale of Midatech Pharma US for $13m and ear out of $6m. Net proceeds will fund key R&D priorities eg MTD201 Q-Octreotide and MTX110 plus repaying the loan to MidCap Financial.
Bonmarche (BON) warns it expects FY underlying pretax only £5.5m (£8m).- blames consumers would you believe.
Zinc Media Group (ZIN) FY rev up 5% but EPS-cont -0.17p (-0.01p). Trading: "very encouraging win rate on significant commissions. This has exceeded the same period in the prior year. The current TV commissioned order book stands at £14.5m, over 50 per cent of budgeted TV revenues for the current financial year. The strength of our order book gives us a basis for confidence in the outlook for the full year..."
Impellam Group (IPEL) Warns FY EBITDA lower YoY. Managed Services businesses in the UK and Australia growing ahead of expectations as is the entire US business, on a like for like currency basis. and accounts for 60% of total EBITDA. NHS market remains challenging due to the continued reduction in agency spend. HNS has reinforced its intention to reduce agency spend by 17% in 2018/19 so the usual seasonal uplift in September has not materialised. Also recent reduced volumes in certain of UK Specialist Staffing brands. FX moves hurting. Nurse!
Bonmarche Holdings (LON:BON) - Profits warning.
https://investegate.co.uk/bonmarche-holdings--bon-/rns/trading-update/201809270700050729C/
After a large (but not unusual for a company of this size) drop in the share price on 4th September and subsequent drifting, they have today announced adjusted PBT for FY ending March 2019 is now expected to be approximately 30% lower than last year, and worse still compared to previous expectations, with statutory figures worser still. They blame lower high street footfall and currency movements. Perhaps because the previous management brought themselves into disrepute by serially blaming the weather they are cautious about putting too much emphasis on the delayed autumn as a factor. They intend to hold the dividend at 7.75 (a likely 10% yield by the time you read this) and therefore forecast cash lower than last year but still healthy.
It seems quite incredible to me (and so perhaps somebody could help me here), how they can possibly predict today to the degree of implied accuracy the shopping patterns (let alone exchange rate) between now and the end of March 2019, a period including Christmas. They have cited a figure of "approximately £5.5m" for PBT and "approximately £4.0m" for cash (rather than, say £5-6m, or £4m respectively) which implies to me a significant degree of certainty. My suspicion is that they will now make short-term decisions to hit these figures regardless of turnover (which they have not forecast), which may affect future profitability.
Note: This is one of my larger holdings. My current inclination is to buy more to maintain exposure, but this may change. Despite its small size, the company is not on AIM, but quoted on the main market.
Bonmarche Holdings (LON:BON)
Well the first two paragraphs didn't exactly exactly fill me with confidence (bold highlight is mine)....
In the update issued on 26 July 2018 in respect of the first quarter of the current financial year, we noted that trading during Q1 had been significantly better than in the final quarter of FY18(1), particularly the store LFL(2) sales performance. Based on this encouraging start, the Board was confident that by continuing to improve Bonmarché's proposition to customers, the Group would achieve further profit growth during FY19(3).
During the second quarter of the financial year, online sales have continued to grow strongly, in line with expectations, but sales in the stores have not maintained the momentum gained during Q1, and are below expectations......
Apart from the mixed messages, they are being weaselly with their words and measures (who isn't these days) - "Q1 better than final quarter" mixed with "store LFL" which is Q1 to Q1.
"modernising the store offer" = discounts and reduced margins or better stock?
Desperate to find a good spin on numbers?
Good luck with your holdings but I see more bad news coming before any turnaround.
How about something a bit different - English Wine. Both Gusbourne and Chapel Down H1 results out. Both showing pretty good progress with significant expansion plans as the appetite for English fizz remains strong.
Seconded for Mountfield (LON:MOGP). The order book is down from H2 last year but there are positive indicators from management "in the process of negotiating or in tenders for substantial new contracts" and "The Board anticipates the Group performing well in the second half of the year and also CAF and MBG securing further business that will ensure a strong platform for 2019".
Thanks for the requests, never looked at Mountfield (LON:MOGP) but will check it out. G
Hi Graham might be a bit of a tiddler for this report but Mountfield (LON:MOGP) reported good H1 results today. If you annualise the results it is on a PE of circa 3.5. Specialist flooring contractor which is in a growth phase thanks to requirements of data centres etc. Recovering after a restructuring several years back and has been showing improved performance over the last 3 halves and positive management statements. Potentially good turn around play. Thanks.